Download

How Health Plans Can Control Pharmacy Risk

Rising specialty drug costs and regulatory pressures are pushing health plans toward marketplace-based pharmacy benefit models.

Expensive Pharmaceuticals

For health plan officers and financial leaders, pharmacy benefits have crossed a threshold. U.S. prescription drug spending surged to $915 billion in 2025 and is projected to exceed $1 trillion in 2026 — one of the fastest growth rates in two decades. Pharmacy benefits is no longer a cost category — it has become a material driver of financial volatility.

The forces driving this exposure are converging. Specialty medications now account for roughly half of total drug spending, with many therapies exceeding $100,000 annually per patient, and some cell and gene therapies reaching into the millions. Overall healthcare spending is projected to grow 10% or more, with pharmacy costs among the primary drivers. At the same time, the passage of the Consolidated Appropriations Act of 2026 (CAA 2026) has expanded transparency, reporting and fiduciary requirements for health plans — adding regulatory and operational complexity on top of financial exposure.

In one-on-one conversations, I am hearing an acute reaction to mounting pressure being felt across the payer ecosystem. Plan sponsors are increasingly focused on how to maintain cost control while also meeting expanding fiduciary and transparency obligations. Health plans and TPAs are actively exploring more proactive approaches to medical and specialty pharmacy management as usage and cost volatility increase. At the same time, PBMs are working to redefine their role as traditional operating models face greater scrutiny and disruption.

The legacy PBM model was not designed to manage challenges at this scale. It was designed to aggregate volume. The result is a system that is increasingly difficult to measure, interpret, and control, precisely when greater visibility, accountability, and agility are most needed.

The Legacy PBM Model Concentrates Risk in the Wrong Places

The legacy PBM structure systematically limits visibility. Opaque pricing methodologies, hidden rebate structures, and aggregate-only reporting make it difficult for health plans to determine true net cost, validate savings claims, or identify the actual drivers of spending early enough to intervene effectively. Addressing this requires a more transparent operating framework built around integrated data visibility, component-level financial reporting, and greater accountability across pharmacy benefit stakeholders.

Flexibility is equally constrained. Bundled PBM arrangements limit a health plan's ability to adjust benefit design, introduce new strategies, or respond quickly when specialty usage shifts unexpectedly. Fragmented vendors and siloed data eliminate the possibility of a single, reliable source of truth, which is essential for effective financial and operational oversight. More adaptable, modular benefit structures allow plans to introduce targeted specialty management strategies, optimize site-of-care programs, and implement new financial controls without overhauling the entire pharmacy benefit model.

Market concentration compounds the challenge further. The top three PBMs control roughly 80% of U.S. prescription claims, limiting competitive alternatives and slowing adoption of models better suited to the current environment. The practical consequence is a widening gap between what health plans are accountable for and what their current structure actually allows them to manage.

To close these gaps, stakeholders are looking for new models that provide access to broader contracting scale, specialty networks, and integrated management capabilities to maintain greater control over benefit strategy, vendor selection, analytics, and member experience.

A Marketplace Model Approach to Pharmacy Benefits Strategy

Managing pharmacy benefit risk requires the same discipline applied to any significant financial exposure: visibility into the drivers, flexibility to respond, and the ability to make decisions based on empirical data rather than aggregated summaries.

A marketplace-based approach to pharmacy benefits addresses each of these directly. Rather than relying on a single bundled arrangement, health plans can evaluate pharmacy benefit components individually — assessing performance, replacing underperforming elements and aligning each component with specific organizational priorities and financial objectives. The result transforms a monolithic, difficult-to-audit arrangement into a set of discrete, measurable risk factors that can be actively managed and adjusted as market conditions evolve.

The implications are real:

Concentration risk is reduced. Dependence on a single PBM relationship — with its inherent opacity and limited leverage — is replaced by a diversified model in which no single vendor controls the full picture of pharmacy economics. A marketplace model broadens choice and competition, enabling organizations to manage risk based on the profile of their covered lives, not that of the masses.

Regulatory and fiduciary exposure are addressed directly. A marketplace model built on transparent, component-level reporting supports the disclosure, audit trail, and accountability requirements that CAA 2026 and ERISA-aligned fiduciary standards now demand. Plans can demonstrate not just what they spent, but why, and what oversight was applied. Furthermore, real-time access to integrated data enhances the power of predictive modeling and the potential for proactive risk mitigation.

Specialty drug volatility becomes more manageable. A small number of high-cost therapies now account for a disproportionate and increasingly unpredictable share of total spending. A marketplace model makes it possible to coordinate key cost savings components — site-of-care optimization, stronger clinical oversight, and more targeted financial management strategies — within a unified framework designed to intervene where costs are most concentrated. For example, plans may redirect eligible specialty infusions from high-cost hospital outpatient settings to lower-cost ambulatory infusion centers, implement enhanced monitoring protocols for emerging high-cost therapies, or better align pharmacy and medical benefit management strategies to more effectively identify, track and control specialty spending across the continuum of care.

Operational risk from rigidity is eliminated. Currently, when the prescription drug market changes — new therapies enter the market, GLP-1 usage accelerates, or a new cell and gene therapy creates an unanticipated claim event — payers can be slow to react, often having to renegotiate a bundled contract or wait for a vendor partner to build a new capability. A marketplace model enables organizations to act in real time, rather than reactively, as these dynamics unfold. This flexibility enables organizations to rapidly deploy targeted utilization management programs, introduce condition-specific clinical management strategies, expand specialty network access, or adjust financial controls in response to changing market conditions.

From Reactive to Proactive: Data as a Strategic Management Tool

Effective pharmacy benefit management is anticipatory, not retrospective. The legacy pharmacy benefits model is built around periodic, aggregated reporting — a structure designed for billing, not strategic decision-making. A marketplace approach changes the information architecture fundamentally.

With integrated, component-level data and real-time reporting, health plans gain the ability to identify cost drivers earlier, compare vendor performance against benchmarks, and make empirically grounded decisions rather than relying on assumptions embedded in aggregate summaries. This shifts pharmacy benefit management from a reactive posture — responding to spending that has already occurred — to a proactive one, where risk is identified and addressed before it becomes a financial event. Unified analytics also help align pharmacy and medical benefit insights, improving visibility into total specialty care costs and supporting more coordinated enterprise-wide decision-making.

This capability is especially critical as the pace of change in the drug market accelerates. Traditional tools — formularies, rebates, utilization controls — remain important, but they are no longer sufficient as standalone management mechanisms. Precise, real-time visibility into cost drivers and direct operational control over how those costs are managed have become baseline requirements for any health plan operating in today's pharmacy environment.

A Sustainable Framework Requires Structural Change

The structure of pharmacy benefits will continue to evolve as drug acquisition costs remain elevated, new high-cost therapies enter the market, and regulatory expectations increase. Health plans that continue to rely on the legacy model are operating within a framework that often limits visibility and flexibility at the exact moment both are most needed.

Organizations with greater expertise, visibility, and flexibility will be better positioned to adapt to ongoing market disruption, manage specialty cost pressures more effectively, and meet rising stakeholder expectations. Those that fail to evolve risk operating within a pharmacy benefit framework that is increasingly misaligned with the financial, regulatory, and operational realities of today's healthcare market.

An adaptable, marketplace-driven pharmacy benefit model enables health plans and payers to adapt to these realities without major structural disruption or service interruption. It replaces opacity with transparency, rigidity with modularity, and assumption-based management with data-driven oversight.

Executing this kind of transition requires more than a vendor swap — it requires a new paradigm and a strategic partner with the clinical, financial, and operational depth to navigate this environment. Collaborating with specialized pharmacy benefit partners — those with proven capabilities across specialty management, analytics, rebate optimization, and benefit design — can help plans build a more responsive and sustainable pharmacy benefit strategy.
AI's Insights Into Customer Sentiment

AI-powered tools now capture real-time behavioral signals from claims interactions, transforming employee experience data into measurable business performance.

AI in the Workplace

Although insurance is a data-first business, it has been traditionally tough to quantify the human side of operations: the quality of a claims adjuster's interaction with a policyholder in crisis, the patterns that predict when a top-performing call center agent is about to disengage, the signals that distinguish a renewal conversation that's going well from one that's creating retention risk.

AI is quickly closing this gap. A new generation of AI-powered tools is giving insurance organizations real-time visibility into behaviors that determine outcomes. The carriers moving fastest on this are redesigning how employee experience data flows through the organization and, in doing so, creating a direct line between workforce intelligence and business performance.

The Data Gap in Insurance Operations

A field adjuster handling catastrophe response may conduct 12 to 15 policyholder visits in a single day, and each one can determine whether a customer walks away feeling supported or abandoned. A call center agent in a high-volume property claims environment may handle 80 inbound contacts in a shift, each requiring rapid judgment calls about coverage, tone, and escalation.

Historically, the data generated by those interactions has been gathered by call recordings, satisfaction surveys, and observation/field rides. However, these are challenging to scale and to measure which behaviors drive impact across the workforce.

The tools available today — AI-powered conversation analysis, real-time behavioral signal detection, field mobility platforms, IoT-enabled workspace intelligence — connect not just data, but patterns, behaviors, and activities that can predict and redirect outcomes.

What the Tools Actually Do

The technology stack for frontline workforce intelligence in insurance has matured significantly. There are four primary capture mechanisms now deployed at scale across financial services and insurance operations.

  1. Real-Time Conversation Analysis

    Ambient voice AI and natural language processing engines transcribe, classify, and analyze spoken interactions as they happen. These systems go beyond transcription by detecting sentiment in both the employee and the customer, flagging compliance-relevant language, identifying missed resolution opportunities, and surfacing coaching prompts — during the call or conversation.

    A system that detects elevated customer distress during a first notice of loss call can prompt the adjuster with an empathetic acknowledgment script, which can enhance the interaction in real time.

  2. Behavioral Signal Detection Beyond Words

    The most advanced conversation AI systems capture language, analyze voice and behavioral signals (think pace, hesitation, tonal shifts, speech rate under stress), and build a real-time picture of both the employee's and customer's emotional trajectory.

    These signals, aggregated across thousands of interactions, also reveal patterns that pure text analyses miss. Which claims generate the most agent stress? Which coverage explanations correlate with downstream complaints? Which interaction profiles predict a renewal at risk? The answers sit in the behavioral data that exist in insurance operations but now can be systematically mined.

  3. Field Intelligence for Road-Based Adjusters

    The data capture challenge for field adjusters is fundamentally different from the call center environment. Their day consists of unscripted property assessments, policyholder conversations, and documentation tasks conducted in varying conditions under time pressure.

    Mobile-first field platforms now give adjusters AI-assisted documentation tools. These include photo capture with damage classification, voice-to-text for on-site notes, and real-time coverage guidance based on policy type and loss description. These can reduce administrative burden and improve documentation quality simultaneously. Importantly, they also generate experience data: how long assessments take, where documentation quality varies, which loss types generate the most adjuster rework, and why.

  4. Workspace and Interaction Pattern Intelligence

    In fixed-location operations like service centers, claims hubs, and regional offices, occupancy sensors, spatial analytics, and interaction pattern data provide a layer of intelligence that traditional workforce management tools cannot. They identify whether certain workspace configurations are creating service bottlenecks, whether team placement is affecting collaboration patterns, and whether high-performing agents cluster in specific environmental conditions that could be replicated broadly.

    For a carrier managing a large claims service center, this kind of environmental intelligence can surface insights like which team with the highest attrition sits in a zone with the highest ambient noise and the lowest natural light, and which agents who access shared knowledge bases most frequently produce the fewest coverage disputes.

What Better Looks Like For Employee and Customer Experiences

Claims Quality and Cycle Time

When adjusters receive real-time documentation guidance and coverage support in the field, documentation quality improves and rework decreases. With in-the-moment coaching on empathy and resolution framing, first-call resolution rates increase, and post-interaction complaint rates fall.

Agent Development and Retention

The traditional model for developing insurance frontline talent is episodic — via classroom training, annual reviews, and occasional supervisor observation. An agent receiving specific, behavioral, in-context feedback across hundreds of interactions develops faster and retains more than one who receives a quarterly performance review.

Customer Experience Outcomes

The EX-CX link in insurance is not theoretical. Adjusters who are well-supported, well-coached, and experience manageable cognitive load produce different customer interactions than those who are overwhelmed and under-resourced. Employee experience quality is a leading indicator of customer experience quality, not a lagging one.

Reducing Burnout and Retention

The employee experience dimension here is direct. Adjusters consistently report that administrative burden — and not the complexity of the work itself — is the primary driver of burnout. Tools that absorb that burden and do so in a way that improves, rather than complicates, the field workflow produce measurable improvements in adjuster retention and output quality simultaneously.

What Deployment Actually Requires

What determines whether a carrier captures this opportunity is how the implementation is designed.

Three elements separate the deployments that deliver from the ones that stall.

  1. Tools must be introduced with clear communication about their purpose. Define specifically what the AI is optimizing for, how data will be used, and what employees can expect from the experience.
  2. Managers must be equipped to use the data the tools generate in ways that support development. The most valuable output of an AI workforce intelligence platform is the conversation it enables between a team lead and an agent.
  3. Metrics used to evaluate the deployment must include employee experience indicators alongside operational ones. If the only measures of success are call handle time and claims cycle time, the deployment will be optimized for those measures, and the experience improvements that make the gains sustainable will be invisible until attrition numbers force the conversation a year later.
The Window Is Now Open

The tools are available. Technology has been proven in adjacent industries. The workforce data that has been sitting uncaptured in every claims call, every field visit, and every agent interaction for decades is finally capturable at scale — and the infrastructure to turn it into real-time organizational intelligence is no longer experimental.

The question for insurance leaders is not whether this shift is coming. It is whether their organizations will be the ones that shape it.


Tamar Cohen

Profile picture for user TamarCohen

Tamar Cohen

Tamar Cohen is the founder of HaloEffect, a people strategy firm built on the belief that traditional “employee engagement” models no longer work in an AI-driven world. 

She has spent more than two decades leading global EX and CX programs across financial services, healthcare, and technology. She is a frequent keynote speaker and executive facilitator. 

The Emerging Threat to Cybersecurity

Liz Kim, president, US, at BOXX Insurance, says invoice manipulation has developed into a major threat -- and explains how not to fall victim. 

An Interview with Liz Kim

Paul Carroll

To start us off, what is your overall outlook for the cyber insurance industry?

Liz Kim

If only we could predict where it's going to go, right? I've been in the cyber insurance industry for many years and I've worked across a lot of different roles. I've been in it as a lawyer, as head of claims for a major insurer, in underwriting, in product development, and as a broker. We’re in a soft market now, but, as with all insurance, the cyber market is cyclical.

I think cyber is more cyclical than other lines, for a couple of reasons. First, although there are plenty of disaster scenarios that people talk about in the industry — things like a worldwide AWS outage — we haven't yet really had a true disaster, which would tighten capacity and increase prices. Second, we have new entrants coming into cyber all the time. Because of that constant influx, a lot of their value proposition comes down to nothing more than having the lowest prices. That dynamic drives pricing down more than you'd typically see in other lines of business.

That said, companies that maintain underwriting discipline and pair their insurance with meaningful services or technology solutions to reduce digital risks are better positioned to hold pricing than those that are purely insurance plays.

My overall outlook? It's always positive — because if it wasn't, I wouldn't still be in cyber after all these years. With the kinds of innovations we're seeing across the industry, it's always going to be an area that drives the market forward.

Paul Carroll

How has the cyber threat landscape evolved over the past year or so, particularly with the rise of AI capabilities being leveraged by bad actors?

Liz Kim

The biggest concern I'm hearing right now with respect to AI, in particular, is deepfakes. It's not necessarily a claims-oriented concern in the way ransomware or even extortion is — it's more of an existential threat, which is how most people seem to view it. But deepfakes do connect to insurance, in that some cyber insurers have AI-related exclusions that could potentially leave a deepfake-related claim uncovered. I don't think we've landed on a perfect solution there yet.

We're also seeing a rise in invoice fraud, especially through business email compromise and invoice manipulation. Deepfakes and other trickier social engineering techniques that are leveraging AI certainly make those types of scams even easier to pull off.

Paul Carroll

Tell me a bit more about invoice manipulation, if you would. It’s been around for a while, but I find it interesting that it’s picking up.

Liz Kim

What you see is threat actors creating a fake invoice from a vendor that the insured already does business with. They'll know somehow that you work with that vendor — maybe through social engineering, or maybe they've actually gained access to your systems. From there, they'll send you a fraudulent invoice using one of two main methods.

The first is domain spoofing, where the email domain looks very, very similar to the legitimate one — maybe just a misspelling, or .com versus .ca or .co. They're counting on the recipient not noticing.

The second is BEC, or business email compromise, where the hacker has actually compromised the email account of the other party and is sending invoices directly from it to legitimate contacts.

Either way, there's generally a payment redirection involved — like, "Oh, I've changed my banking information." That's a key red flag. There's no tech hack to prevent this; it's really a process issue. Accounting teams need to have protocols around anything involving a change to payment details. Verify it through a phone call to a known contact using confirmed contact information. And you need to be the one calling them, not the other way around.

You can even see cases where someone on the accounts payable team receives a fake email thread or a WhatsApp message from their CEO or CFO saying, "Pay this invoice."

What makes it convincing is that the thieves have done their homework: they know the CEO is connected to that person professionally on LinkedIn, or they've worked together, or they're tagged in a post. The thieves replicate real, believable scenarios to trick employees.

Junior employees often don't want to question something that looks like it's coming from the CEO. But that's exactly the point: You cannot bypass your internal validation protocols at any level, no matter how legitimate something looks. Because threat actors are trying to trick you.

Paul Carroll

I gather AI is also increasing the volume of cyber threats like phishing. What is the industry doing to counter that?

Liz Kim

Yes, the volume is going up. AI is an enhancement to all of the tactics that bad actors are already using.

A phishing email from three, four, or five years ago is not the same as a phishing email today. Before, there were very obvious markers — the spelling mistakes, the type of email. Nowadays, with advanced social engineering, they can make an email seem so much more legitimate. It's hyper-personalized.

At the same time, the prevention aspects are improving, too. The market is providing more education around building digital resilience and awareness of how phishing scams work: Don't click on things from someone you don't know, and don't click on something you weren't expecting — even from someone you do business with every day.

As an industry, we're not seeing the increase in claims volume that you would expect given the sophistication of AI, and that's because there's much more emphasis on education and prevention.

Paul Carroll

I've been tracking hackers since probably the late 1980s, back when friendly Nigerian princes used to offer me a lot of money. Now I'm at the point where I may report emails as phishing scams that turn out to be legitimate — I'm suspicious of everything these days.

Beyond education, what are you and others in the industry doing to prevent cyber threats from succeeding?

Liz Kim

We have our in-house technology experts — the BOXX Hackbusters team — who are on call 24/7. In addition, each commercial policy is bundled with Cyberboxx Assist, a suite of tools and services designed to help individuals and businesses predict, prevent, and respond to cyber threats. We also offer a virtual CISO [chief information security officer]. These services are focused on the SME space, because many of our insureds don't have any in-house technology expertise, and we can help them bridge that gap.

By offering services like our virtual CISO, it does two things. One, it raises awareness among the management team that cyber risk is a real issue that can impact their organization. Two, it allows our insureds to get expert-level cybersecurity advice. Our vCISO will work with them on a plan — and offer them advice and resources on how to execute it.

In terms of insurance offerings, BOXX introduced a tech E&O policy earlier this year. It has a really strong cyber focus and offers something very specific for technology companies: breach of contract coverage. To get a little lawyerly, the liability that tech companies face isn't a breach of industry standard, which is what you normally have for more traditional professionals like accountants, lawyers, doctors, and so on. Breach of industry standard is the coverage traditional professional errors and omissions insurance provides. But in the technology space, liability is driven by what companies put into their contracts. So the importance of having affirmative coverage for contracts really cannot be overstated when it comes to Tech E&O.

Paul Carroll

There seems to be growing emphasis not just on an organization's own cybersecurity, but on the security of all the vendors and business partners they interact with, because those relationships can serve as entry points for attackers. How is that third-party risk being addressed in the insurance market?

Liz Kim

We can't physically address the security of our insureds' vendors or business partners. So we have to essentially push our insureds to address the security of their own vendors and business partners through education and awareness.

That's critical, because as an industry, we're seeing more claims come in through those third-party relationships than through direct attacks on the insureds themselves.

Paul Carroll

Looking ahead two or three years, where do you think the cyber landscape is headed — and does it ever really change, or is it always going to be that back-and-forth battle between attackers and defenders?

Liz Kim

Even though cyber is an area that changes a lot, it also stays the same in a lot of ways. The role of cyber insurers — especially technology-focused ones like BOXX — is to stay ahead of what the bad guys are doing. That's why things like monitoring the dark web, which is still a relatively new practice for the industry, are so important.

The focus will shift, sure. We've seen it move from ransomware to extortion to business email compromise and invoice manipulation. But ultimately what we're doing remains the same: predicting, preventing, and insuring against negative cyber and technology-related events.

Paul Carroll

Are you seeing much change in the geographic origin of cyber threats? For a while, North Korea, China, and Eastern Europe were significant sources — has that landscape shifted?

Liz Kim

The industry is seeing what appears to be a decrease in volume from Russia and Ukraine, simply because their energies are focused on each other rather than on the rest of the world.

That said, I don't think we're seeing any decrease from the other traditional sources, such as China and North Korea.

Paul Carroll

This has been very helpful. I hope people get the message, especially about the vigilance needed to head off invoice manipulation.

Any final message?

Liz Kim

I’ll just note that I’m excited to have joined BOXX. Just in the few weeks I’ve been here, I’ve found the people to be amazing. The other thing that really drew me to BOXX — and that I've come to appreciate even more since joining — is that we have all the excitement and focus of a startup and we’re channeling that energy into growth after officially becoming a part of Zurich Insurance, a 150-year-old, well-established, and well-respected insurance company.

Paul Carroll

Thanks, Liz.


About Liz Kim

Elizabeth (“Liz”) Kim is the President, US at BOXX Insurance, where she leads the company’s U.S. strategy, operations and market expansion. With nearly 30 years of experience in the insurance industry, she brings deep expertise across underwriting, claims, product development, reinsurance and legal analysis. 

Before joining BOXX, Liz served as a Cyber Reinsurance Broker at Gallagher Re, structuring reinsurance solutions for cyber insurers, InsurTechs, and MGAs. She also held senior leadership roles at Hiscox in underwriting and product development after spending more than a decade as a litigator and claims leader managing complex technology, media, cyber, and professional liability matters. Her broad background gives her a practical, well rounded perspective on emerging risks and the operational needs of insurers and insureds. 

Liz holds a J.D. magna cum laude from Seattle University School of Law, an M.S.W. with honors from California State University Sacramento, and a B.A. in Sociology with a Minor in Women’s Studies from the University of California Davis. She is also committed to mentorship and community service and has volunteered with San Francisco’s Volunteer Legal Services Program, the Asian American Bar Association/Asian Pacific Islander Legal Outreach Pro Bono Clinic, and the ACLU of Washington. Liz also served on the Board of Directors of the Korean American Bar Association of Northern California and continues to serve on the Board of its affiliated Foundation, where she has chaired the Scholarship Committee and mentors law students.[


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

What Insurance Leaders Get Wrong About Culture

Insurance leaders often mistake compliance for culture. Here are five crucial steps that will let you build the sort of agile culture that AI requires.

Leaders

When people think about a healthy culture in most insurance organizations, they usually say the same things: People follow the process, leaders avoid trouble, and long-tenured employees are promoted. Leaders track metrics like compliance, regrettable attrition and engagement scores to determine success.

But this definition is incomplete because it hides what's beneath the surface: behavioral norms fragmenting across business units and new hires leaving within 18 months because the operating environment is significantly different from what was described during recruitment. The people who stay do so because of inertia, not because the work feels meaningful.

Behavior design matters now more than ever. Cultures built on adherence and compliance are based on a set of rules that are assumed to stay static. But when disruptions occur, the organization is not prepared, and confusion and bad decisions are made.

Culture Redefined as Adherence

In high-compliance industries, culture and process compliance tend to conflate. When regulatory requirements, audit cycles, and procedural accuracy define how work gets evaluated, organizations start measuring culture through proxies like tenure, compliance rates, and survey scores. These operational measures are important, but they describe stability rather than resiliency.

The result is a culture that performs well on paper and fragments in times of instability. This distinction is becoming costly in ways that are hard to ignore. Gallup's 2026 State of the Global Workplace report found that only 20% of employees worldwide are engaged at work (the lowest scores ever), with disengagement costing the global economy an estimated $8.9 trillion annually in lost productivity.

AI Is Making the Problem Visible

When AI shifts what the work actually requires, carriers that have spent years measuring culture through stability metrics cannot answer basic questions: what does good behavior look like to support and sustain change in the organization and the industry overall? How do we sustain and manage our teams through all the changes? How do we ensure confusion isn't jeopardizing team performance?

We need to start moving away from dependence on easy-to-measure metrics, most of which are lagging, and tell us how people worked in the past, during a moment in time. What companies need to start thinking about is how to ensure their teams can learn and adapt to new technologies, new processes, and new requirements. How will their employees learn, develop, and grow in the new AI world? Answering these questions requires the much harder work of defining culture at the behavioral level, specifically enough that people can act on it even when circumstances shift.

Five Steps to Building a Culture That Is Specific Enough to Work

Behaviors don't just change by mandate. They require deep thought into understanding what outcomes the company is looking to create, and then designing the behaviors required to achieve those outcomes. Getting clear and actionable provides transparency and, finally, building recognition and accountability systems around those specific behaviors guides future alignment. Here is how to do it:

Step 1: Get Clear on the Problem and the Desired Outcome

Before naming behaviors, leaders need to name the gap. Is the issue that collaboration is breaking down at the team level? Does accountability diffuse when decisions cross business units? Are new hires not connecting to the real operating and cultural norms fast enough? The behavior work only holds if it is designed to close a specific gap that is clearly articulated. This is where value statements can't hold up.

Step 2: Get Clear on the Dos and Don'ts

Get team members into a room and via digital whiteboard (like Miro or FigJam) or sticky notes, ask them to independently write down:

  • Green Behaviors (Dos): Actions you want to see more of (e.g., "turn on cameras during internal video calls," "respond to messages within 24 hours").
  • Red Behaviors (Don'ts): Actions to avoid (e.g., "canceling 1-on-1s without 24 hours notice," "speaking over colleagues in meetings").

Step 3: Write a One-Sentence Definition

Condense the list into clear, actionable statements and avoid buzzwords as much as possible. If the definition requires interpretation, it is not finished yet. Build a simple test: read it to someone two levels below you and ask them what they would do Monday morning. If the answer matches what you had in mind, the definition works.

Step 4: Apply the Street Test

The street test asks: Would someone off the street be able to easily recognize the stated behaviors in play? Behaviors are exhibited and reflected in the day-to-day actions of employees. It should be in the feedback of customers or vendors. Behaviors that fail the street test are aspirational language that do not change anything.

Step 5: Model It and Reward It

Defined behaviors only become cultural norms when leaders model them visibly and when the recognition system tells the stories of the people doing them. In insurance, where performance management tends to be tightly tied to technical output metrics, this requires a deliberate decision to build behavioral recognition into performance conversations, team meetings, and promotion criteria. What gets recognized gets repeated.

The Real Competitive Risk

Culture defined as adherence will hold together as long as the rules stay stable. The insurance industry is entering a period where the rules, the work, the tools, and the talent expectations are all shifting simultaneously. Carriers that have not done the behavioral definition work have a structural gap that a survey will not capture.

The organizations that will retain the best people and navigate transformation most effectively will be the ones where culture is specific enough to guide behavior when the process is no longer clear. That requires doing the unglamorous work of naming what good actually looks like, one behavior at a time.

Engagement scores will tell you how people feel today. Behavioral culture design determines how they act tomorrow.


Tamar Cohen

Profile picture for user TamarCohen

Tamar Cohen

Tamar Cohen is the founder of HaloEffect, a people strategy firm built on the belief that traditional “employee engagement” models no longer work in an AI-driven world. 

She has spent more than two decades leading global EX and CX programs across financial services, healthcare, and technology. She is a frequent keynote speaker and executive facilitator. 

3 Key Questions for Boards on AI

Boards approving AI deployments often miss critical questions about data foundations, decision documentation, and pipeline positioning.

Questions about AI

In the past two years, I have sat in on more board-level reviews of AI deployment proposals than in the previous 10 combined. The dollar amounts have gone up, as have the strategic stakes. What has not gone up enough is the quality of the questions board members ask before approving these proposals.

Most board reviews follow a predictable script. Management presents a use case, a vendor, a timeline, and an ROI model. Board members ask about the vendor's track record, the integration risk, and the projected savings. The proposal gets approved or sent back for revisions on the basis of those answers.

Those questions are not wrong. They are insufficient.

Across 20 years of building insurance software and watching deployments succeed or fail, I've seen three other questions matter more for the long-term success of an AI decision-making deployment. Most board members are not asking them yet. The ones who do are the ones whose organizations end up with AI in production rather than stuck in pilot.

Question 1: What is the data foundation we are building this on?

Every AI deployment runs on data the organization already has. The proposal will say so. What the proposal usually does not say is whether that data is in the shape the model needs.

In my experience working with carriers, the data foundation question surfaces three different problems depending on the organization. Sometimes the data exists but is fragmented across systems of record that cannot be reconciled to a single customer or transaction. Sometimes the data is reconciled but tagged inconsistently across business units. Sometimes the data is consistent but does not include the variables the model actually needs to make a defensible decision.

Each of these is a deployment-stopping problem. None of them is visible from the vendor demo. All of them surface in the first 60 days of integration when the model starts producing outputs that the business cannot use.

When my team published research from 20 US insurance leaders earlier this month, data quality and fragmented systems came in as the single biggest blocker to AI deployment. ROI uncertainty came second. Internal IT capacity came third. The order surprised some readers. It did not surprise me.

Board members who ask "what is our data foundation" are not slowing the project. They are giving it a chance to succeed.

Question 2: How do we document an adverse decision?

Most AI deployments at the decision-making layer touch outcomes that affect customers. In insurance, that means claim denials, payout reductions, and coverage decisions. In banking, that means lending denials and credit limit reductions.

For each of those, the regulatory environment in 2026 expects you to be able to document why the AI system reached the decision it did, what input features it considered, what model version was active at the time, and what human review was involved. The expectation is not theoretical. The NAIC Model Bulletin on AI in insurance, adopted in 24 U.S. states as of early 2026, makes this explicit. The EU AI Act makes this explicit. Federal regulators in banking and healthcare are moving the same direction.

In recent research, only three of 14 carriers with AI in production were confident they could produce a complete decision audit trail within five business days if a state regulator asked. The other 11 were less confident. Some far less.

The board question is not whether the AI deployment will be regulated. It will be. The board question is whether the deployment as proposed has the documentation discipline built in, or whether it will require an expensive retrofit when a regulator first asks.

Question 3: Does the AI touch the actual decision?

This is the question most likely to change the structure of the deployment itself.

In my experience, AI deployments succeed faster and create more measurable value when they sit on the edges of a decision-making pipeline rather than at the decision itself. The reasons are operational and regulatory. Capabilities that handle structured but tedious work, such as document interpretation, intake triage, and fraud signal generation, scale faster because the data they consume is more structured, the output they produce is easier to measure, and the regulatory scrutiny they attract is lower.

Capabilities that touch the decision itself, such as reserve recommendation in claims, credit decisioning in lending, and care recommendation in healthcare, scale more slowly. The data is messier. The measurement is harder. The regulatory exposure is higher.

This does not mean decision-making AI is wrong. It means decision-making AI should generally not be the first deployment. The board approving a first AI deployment that sits at the decision itself, before the organization has built the data foundation and the documentation discipline on lower-stakes capabilities, is approving the most complex deployment under the worst conditions.

In that same research, of the 20 U.S. insurance leaders surveyed, just three described their organizations as running AI-assisted decision making. Seventeen still relied on humans for every meaningful decision. The 13 with any AI in production had deployed it on the edges of the pipeline, not at the decision.

A different conversation

When boards ask these three questions, the conversation about an AI deployment changes. The vendor selection becomes secondary. The integration timeline becomes secondary. The ROI model becomes secondary, because all three depend on getting the data foundation, the documentation discipline, and the pipeline position right first.

The boards that ask these questions get more AI deployments into production. The boards that do not ,get more pilots that never move beyond pilot.


Piotr Biedacha

Profile picture for user PiotrBiedacha

Piotr Biedacha

Piotr Biedacha is the CEO and head of delivery at Decerto. 

A graduate of software engineering and postgraduate management studies, he has been working in the insurance industry for over 20 years. 


Embedded Insurance Is the Next Big Opportunity

Embedded insurance integrates P&C coverage directly into purchase journeys, creating seamless customer experiences and unlocking new distribution channels for insurers.

Embedded Insurance

The property and casualty (P&C) insurance industry is rapidly evolving as customer expectations shift toward seamless digital experiences. Today's consumers expect convenience, speed, and personalization in every interaction—including insurance. This changing landscape has fueled the rise of embedded insurance, a fast-growing model that integrates insurance products directly into customer purchase journeys.

Instead of buying insurance separately through traditional agents or standalone channels, customers can now purchase protection at the exact moment they buy a product or service. Whether adding auto coverage while purchasing a vehicle, travel insurance during flight booking, or device protection at checkout, embedded insurance simplifies the customer experience while opening new growth opportunities for insurers.

As digital ecosystems continue expanding, embedded insurance is emerging as one of the most promising growth drivers in P&C insurance. But why is it gaining so much momentum, and what should insurers know about its future potential?

1. What is Embedded Insurance in P&C?

Embedded insurance refers to the integration of insurance coverage directly into the purchase process of products or services. Instead of customers searching separately for policies, insurance becomes a built-in or optional part of a transaction.

In P&C insurance, embedded insurance can appear in several ways:

Auto Insurance

Customers purchasing vehicles through dealerships or online automotive platforms can receive insurance offers instantly during checkout.

Travel Insurance

Travel booking websites often provide trip cancellation, baggage protection, or accident coverage at the time of booking.

Home and Renters Insurance

Mortgage lenders, real estate platforms, and rental marketplaces can integrate insurance recommendations into their customer journey.

Consumer Electronics Protection

Retailers can offer device protection plans when customers buy smartphones, laptops, or appliances.

The goal is to make insurance more convenient, contextual, and frictionless by offering relevant coverage at the exact point of need.

For customers, this reduces complexity. For insurers, it creates access to entirely new distribution channels.

2. Why Embedded Insurance Is Becoming a Major Opportunity

Embedded insurance is growing rapidly because it aligns perfectly with changing customer behavior and digital purchasing habits.

Customers Want Convenience

Modern consumers increasingly prefer integrated experiences over fragmented purchasing journeys. Rather than shopping separately for insurance, customers value instant coverage options during existing transactions.

This convenience improves customer engagement and increases policy adoption rates.

Access to New Customer Segments

Embedded insurance allows insurers to reach customers who may not actively seek traditional policies.

For example, younger digital-first consumers may purchase travel or rental insurance when offered contextually, even if they would not independently research insurance products.

Increased Revenue Opportunities

Embedded insurance opens new premium generation channels by integrating insurance into high-volume digital transactions.

Instead of relying solely on brokers, agents, or direct sales, insurers can partner with:

  • E-commerce platforms
  • Automotive marketplaces
  • Travel companies
  • Fintech providers
  • Property technology platforms
  • Mobility service providers

These partnerships can significantly expand market reach.

Better Customer Retention

Offering insurance at the right moment creates stronger customer relationships and improves long-term engagement opportunities.

Embedded experiences also reduce friction, which may increase customer satisfaction and loyalty.

For insurers seeking scalable growth, embedded insurance represents a major opportunity to diversify distribution models.

3. How Technology Is Driving Embedded Insurance in P&C

The growth of embedded insurance would not be possible without advances in insurtech and digital infrastructure.

Several technologies are enabling insurers to scale embedded models more efficiently.

API-Driven Insurance Platforms

Application Programming Interfaces (APIs) allow insurers to connect seamlessly with external platforms.

This enables businesses to integrate insurance offers directly into checkout flows without disrupting the customer experience.

Artificial Intelligence (AI)

AI helps insurers personalize embedded insurance recommendations based on customer behavior, purchase history, and risk profiles.

For example, AI can recommend suitable protection plans depending on product type or customer location.

Real-Time Underwriting

Traditional underwriting processes often involve delays. Embedded insurance requires instant decision-making.

Advanced underwriting technologies now enable insurers to assess risks and issue policies within seconds.

Data Analytics

Embedded insurance ecosystems rely heavily on customer and transaction data to optimize pricing, predict risks, and improve targeting.

These technologies are making embedded insurance more scalable, intelligent, and customer-centric than traditional insurance distribution models.

4. Challenges Insurers Must Overcome

Despite its growth potential, embedded insurance comes with several operational and regulatory challenges.

Regulatory Compliance

Insurance regulations vary by geography and product type. Insurers must ensure compliance while integrating coverage into third-party ecosystems.

Customer Awareness and Transparency

Some customers may not fully understand embedded insurance products.

Insurers must clearly communicate policy terms, exclusions, and coverage details to avoid trust issues.

Integration Complexity

Successfully embedding insurance requires seamless integration between insurers and partner platforms.

Technical challenges around APIs, data exchange, and system interoperability can slow adoption.

Pricing and Profitability

Embedded insurance often relies on smaller premium sizes and high transaction volumes.

Insurers must balance competitive pricing with profitability and risk management.

Data Privacy Concerns

As embedded insurance relies on customer data, insurers must maintain strong cybersecurity and privacy protections.

Addressing these challenges will be critical to scaling embedded insurance successfully.

5. The Future of Embedded Insurance in P&C

The future of embedded insurance in P&C insurance looks highly promising.

As digital ecosystems mature, insurance will increasingly become an invisible yet essential part of everyday purchases.

Emerging trends expected to shape embedded insurance include:

Hyper-Personalized Coverage

AI and predictive analytics will enable insurers to offer highly tailored policies based on customer context and behavior.

Expansion Beyond Traditional Channels

Embedded insurance opportunities will continue growing across industries such as mobility, smart homes, logistics, e-commerce, and subscription services.

Real-Time Risk Prevention

Connected devices and IoT systems may help insurers proactively reduce risks rather than simply covering losses.

Seamless Digital Claims Experiences

Claims processing for embedded products is expected to become faster and more automated.

Ecosystem Partnerships

Insurers will increasingly collaborate with digital platforms, retailers, and technology providers to create integrated customer experiences.

Organizations that embrace embedded insurance early may gain a significant competitive advantage as customer purchasing behavior continues shifting toward digital-first experiences.

Conclusion

Embedded insurance is quickly emerging as one of the biggest growth opportunities in P&C insurance. By integrating protection directly into customer purchase journeys, insurers can deliver seamless experiences, improve accessibility, and unlock entirely new distribution channels.

As customer expectations evolve, convenience and personalization are becoming essential drivers of insurance adoption. However, success in embedded insurance will depend on technology readiness, strategic partnerships, regulatory compliance, and customer trust.

For P&C insurers willing to innovate, embedded insurance offers a powerful opportunity to drive growth, expand market reach, and redefine how insurance is purchased in an increasingly connected world.

Why End-to-End QA Testing Is Essential

As P&C insurers adopt complex digital platforms, comprehensive QA testing prevents costly failures and ensures seamless customer experiences.

Testing

In the highly regulated and customer-driven property and casualty (P&C) insurance industry, system reliability, performance, and accuracy are critical for operational success. From policy administration and underwriting to claims processing and billing, insurers rely heavily on digital platforms to manage core business operations. Even a minor system failure, inaccurate calculation, or integration issue can lead to compliance risks, financial losses, poor customer experiences, and reputational damage.

This is why end-to-end quality assurance (QA) testing has become essential for modern P&C insurers. As insurance companies increasingly adopt digital platforms, cloud technologies, and core systems such as Guidewire, comprehensive QA testing helps ensure business continuity, seamless customer experiences, and operational excellence.

Rather than testing isolated functions, end-to-end QA validates the entire insurance lifecycle—from policy issuance to claims settlement—helping insurers identify defects before they affect customers and business operations.

1. What is End-to-End QA Testing in P&C Insurance?

End-to-end QA testing refers to the process of validating the complete functionality, performance, integrations, and workflows of insurance systems across the entire business ecosystem.

Unlike basic functional testing, end-to-end testing ensures that every system component works together as intended.

For P&C insurers, this often includes testing:

Policy Administration Systems

Ensuring accurate policy creation, endorsements, renewals, cancellations, and premium calculations.

Claims Management Systems

Testing claims registration, approvals, fraud detection workflows, and settlement processing.

Billing and Payment Systems

Verifying invoicing, payment processing, refunds, and reconciliation accuracy.

Third-Party Integrations

Testing integrations with vendors, payment gateways, regulatory systems, CRMs, and external APIs.

Customer Experience Channels

Validating web portals, mobile apps, self-service systems, and customer communication flows.

In complex insurance ecosystems, a defect in one area can affect multiple downstream processes. End-to-end testing helps prevent such failures before production deployment.

2. Why QA Testing is Critical for P&C Insurance Success

Insurance systems handle large volumes of sensitive customer data and business-critical operations. A single defect can disrupt claims payments, affect policyholder trust, or lead to compliance violations.

Preventing Costly System Failures

Errors in underwriting, policy administration, or claims systems can result in incorrect pricing, delayed settlements, or claim disputes.

Comprehensive QA testing helps insurers detect defects early and reduce expensive post-production fixes.

Improving Customer Experience

Today's customers expect seamless digital experiences and faster claims resolutions.

Poor-performing systems, broken portals, or inaccurate policy information can quickly damage customer trust.

QA testing helps ensure:

  • Smooth digital interactions
  • Faster processing times
  • Accurate policy information
  • Reliable claims experiences

Supporting Regulatory Compliance

P&C insurance operates in highly regulated environments where system errors may create compliance risks.

End-to-end testing helps insurers validate regulatory workflows, reporting accuracy, and policy calculations to reduce audit concerns.

Ensuring Business Continuity

Insurance operations cannot afford system downtime.

Performance and reliability testing help ensure systems remain stable during peak claims seasons, catastrophic events, or high-volume transactions.

For insurers, QA is no longer just a technical requirement—it is a business necessity.

3. The Growing Complexity of Insurance Technology

The insurance technology landscape has become increasingly complex.

Many P&C insurers now operate with:

  • Core insurance platforms
  • Cloud-based systems
  • Third-party integrations
  • APIs and digital ecosystems
  • Customer portals and mobile applications
  • AI-driven automation tools

This complexity increases the risk of defects and integration failures.

For example, a change in underwriting rules could unintentionally affect claims workflows or premium calculations if systems are not tested properly.

Similarly, digital transformation projects and cloud migrations often introduce hidden risks if testing is insufficient.

This is especially relevant for insurers implementing or upgrading Guidewire platforms. Specialized testing approaches such as automated regression testing, integration testing, performance validation, and user acceptance testing become critical during implementation or migration initiatives.

Many insurers increasingly invest in specialized Guidewire testing services to ensure seamless system performance, reduce implementation risks, and improve software quality during insurance platform modernization.

4. Key Types of QA Testing Every P&C Insurer Needs

To ensure reliable insurance operations, insurers should adopt a comprehensive QA strategy covering multiple testing approaches.

Functional Testing

Validates whether insurance workflows function correctly, including policy issuance, endorsements, claims processing, and billing.

Integration Testing

Ensures seamless communication between insurance systems, external vendors, APIs, and third-party services.

Regression Testing

Helps insurers verify that new system updates do not break existing functionalities.

Performance Testing

Tests system speed, scalability, and stability under high transaction volumes.

This becomes especially important during catastrophic claim events when system demand spikes.

Security Testing

Insurance systems manage sensitive personal and financial information.

Security testing helps identify vulnerabilities and strengthen data protection.

A strong QA framework reduces operational risks while improving platform reliability and customer confidence.

5. The Future of QA Testing in P&C Insurance

As digital transformation accelerates, QA testing in insurance is evolving rapidly.

Several emerging trends are shaping the future:

AI-Powered Test Automation

Artificial intelligence is helping insurers automate repetitive testing tasks and identify defects faster.

Continuous Testing in DevOps

Insurers adopting agile delivery models increasingly rely on continuous testing to speed up releases without sacrificing quality.

Cloud Testing

As insurers migrate systems to cloud environments, testing strategies are evolving to validate cloud performance, security, and scalability.

Predictive Quality Analytics

Advanced analytics may soon help insurers predict potential failures before they occur.

Customer Experience Testing

Insurers are placing greater emphasis on testing digital experiences across websites, mobile apps, and customer portals.

The future of QA in P&C insurance will be increasingly proactive, automated, and business-focused.

Conclusion

End-to-end QA testing has become a critical success factor for P&C insurers navigating digital transformation, system modernization, and growing customer expectations.

By validating complete insurance workflows, reducing operational risks, ensuring compliance, and improving customer experiences, QA testing helps insurers build reliable and resilient technology ecosystems.

As insurance platforms become more connected and complex, insurers can no longer rely on fragmented or limited testing approaches. A comprehensive end-to-end QA strategy is essential to maintaining system stability, operational efficiency, and long-term business success in an increasingly digital insurance landscape.

AI Won’t Fix the Agency. Re-architecting It Will

The insurance agencies capturing disproportionate value from using AI are restructuring their workflows. Here are some ways that leading agencies operate differently by leveraging AI.

AI for Agencies Graphic

For years, insurance agents and brokerages have pursued growth using a familiar model: Add producers, expand carrier relationships, and absorb the operational load through incremental hiring or outsourced support. When pressure builds, they introduce technology to accelerate individual tasks.

That model is now breaking under the burden of the way agencies actually operate.

Across the industry, agencies are losing significant capacity to operational drag. Anywhere from 30%-40% of their time per week is lost to manual, repetitive work such as rekeying data or manually executing analyses – time that should be allocated to revenue-generating activity.

At the same time, such core processes as policy checking, endorsements and data entry can consume more than 20 hours per week per employee, much of it non-differentiated work. The result: Growth is constrained not by demand, but by how the agency runs.

Industry has moved to AI — but not far enough

Insurance is no longer lagging in AI adoption, it is leading. AI adoption in insurance is outpacing most industries and accelerating rapidly. According to market research firm Zipdo, more than 61% of insurers have embedded AI into workflows or are actively piloting it. Additional research from global consulting firm Deloitte notes that 76% are using AI in some form across their operations.

The impact on the insurance industry of using AI is clear. When AI is applied correctly, insurance organizations have found the following results:

For fast-moving insurance organizations, quoting is where service quality and operational efficiency either scale together or break apart. By implement AI technology, agencies have attained up to 55% faster quoting and 50% faster renewals, improving client satisfaction.

Despite widespread adoption, only a small minority of insurers have scaled AI across their full operating model with most deployments remaining siloed or tactical.

Structural problem: Fragmentation

The majority of agencies have not redesigned workflows. Instead, they have layered AI onto disconnected agency management systems. They continue to use siloed workflows across new business, renewals and servicing. In addition, agencies maintain inconsistent data structures and use manual handoffs from department to department. 

The outcome is predictable: Automation improves isolated tasks, but not end-to-end throughput. Agencies find that they have key data somewhere in their system, but the data is missing context across a policy’s lifecycle. Producers find they continue to be constrained by service dependencies, and the agency’s leadership finds it lacks any visibility into real-time operations.

This is why many agencies experience a paradox: more technology, more automation, and yet limited improvement in growth capacity.

What leading agencies do differently

The agencies capturing disproportionate value are not only adopting AI. They are restructuring the way their agency operates. They are building operating models where:

  • Data flows seamlessly across the policy lifecycle,
  • Work moves across functions with shared context, and
  • AI is embedded into workflows, not added on top. 

This shift is where performance begins to compound. By using AI-driven information, producers can find cross-sell and renewal insights that can increase revenue by 20%-30%. Agencies have found that error rates in operations can drop by up to 90% with integrated validation and data workflows. Most importantly, customer engagement and service response times improve materially, driving retention and growth.  

At an industry level, the upside is significant. According to the well-known consulting firm Bain & Company, AI-enabled transformation represents about $100 billion in value for the insurance industry, driven by productivity, growth, and improvements in operational efficiency. 

The Cogneesol perspective: Extending the agency system

This is the shift Cogneesol is focused on enabling.

The agency management system remains the system of record, but it was never designed to coordinate the full intricacy of modern agency operations.

Cogneesol provides an intelligent operational layer that:

  • Connects data across systems, workflows, and stakeholders,
  • Standardizes and coordinates how work moves across new business, renewals, and servicing,
  • Embeds AI at the points of highest operational leverage, and
  • Creates a unified, real-time view of agency performance.

This is not incremental optimization. It is structural alignment. When agencies move from fragmented operations to a coordinated system many benefits accrue:

  • Producers gain capacity without adding headcount.
  • Service teams operate with greater consistency and scale.
  • Renewal cycles become more predictable and analytics based.
  • Leadership gains actionable visibility across the book. 

Most importantly, the agency transitions from absorbing growth to enabling it.

The bottom line?

The industry has already proven that AI works by reducing costs, accelerating workflows and improving productivity. But those gains plateau quickly when applied to a fragmented operating model.

The next phase of competitive advantage in insurance distribution will not come from deploying more AI tools. It will come from changing the way the agency operates so that intelligence can move across the entire business. That is the difference between simply automating tasks and building an agency that continually improves the way it performs. 

AI is a multiplier, but only if the operating model it sits on is designed to scale it.

About the author

Soumojit Ghosh is Head of Technology Services at Cogneesol.


For more thought leadership from the Cogneesol team, please visit our blog at Cogneesol Blog – For an Ecosystem of Digital Transformation


Sponsored by Cogneesol


Cogneesol

Profile picture for user Cogneesol

Cogneesol

Cogneesol's mission is to help client organizations re-imagine and re-invent every aspect of their business processes.  We seek to achieve this through exceptional, ethical, transparent, and sustainable business services and practices. 

Is the 53-Year Oil Crisis Over?

Even as negotiations on Iran remain muddled, the war shows the world has become resilient to oil shocks. The implications could be profound.

Image
Oil

While oil prices crested at a bit over $110 a barrel In April, some 65% higher than when President Trump began his second term in January 2025, they came nowhere close to economists' forecasts when it became clear that Iran would close the Strait of Hormuz. They expected prices of $150 to $200 a barrel. Some economists feared we might hit $250. 

That oil prices didn't cause a global economic crisis shows that the world has become more resilient in the face of oil shocks. I remember, as a kid, seeing lines around the corner at gas stations after OPEC imposed an oil embargo in 1973, but we came nowhere close to that this time.

The world will now move to become even more resilient, especially to possible events in the Middle East, given that we've seen that supplies can be curtailed just with some mines, speedboats and drones in the world's major oil thoroughfare. The shift toward a global economy no longer dominated by oil considerations will take many years to play out and won't be complete for decades, if ever, but the change will put the world on a new trajectory with profound changes for every industry, including insurance. 

So it's a good idea to start shifting to a new mindset as soon as possible.

My thinking about a post-oil world traces back to 2010, when I was part of a sort of SWAT team at the Department of Energy distributing tens of billions of dollars to drive innovation and help stimulate the economy as part of the Recovery Act following the Great Recession of 2008-9. The leader of the project, Matt Rogers, was the leader of the oil and gas practice at McKinsey, and he had developed a thesis that was radical, especially for the time. While the conversation among economists was about "peak oil" (when global oil supplies would max out and start to diminish), he calculated that the issue was peak demand (when demand, not supply, would crest).

Matt and Stefan Heck, also a senior partner at McKinsey, developed the peak demand idea much more broadly in their 2013 book "Resource Revolution," which I helped them write. So I was intrigued when a columnist in the Washington Post declared yesterday that: "The 53-year-long oil crisis is now over, leaving the world in a better place.... The black, sticky stuff just doesn’t matter as much as it used to."

The soaring output from fracking in the U.S. over the past two decades did a lot to cushion the oil shock this time around. So did impressive flexibility by China, which reduced its imports by some 4 million barrels a day, to less than 8 million, while barely tapping its oil reserves. In coming years, Venezuela may become a major oil exporter again, and the growth of power from renewable sources will keep surging. The Post column notes: "Renewables account for 47 percent of electricity generation across the European Union and 26 percent in the U.S. The share in America is rising fast, with solar last month overtaking coal in power generation."

The columnist says the end of the oil crisis will have three major consequences, and I think he's mostly right:

"First, the Middle East won’t matter so much anymore.... Next, inflation will be subdued. Oil was a crucial enough input in a wide range of products that it helped determine their prices. The U.S. should now expect a decade or more of the cost of living barely changing from one year to the next. Finally, and most significantly, the global economy will be far more stable. Over the last half-century, soaring oil prices accompanied five major recessions or stock market slumps (1973, 1979, 1990, 2008 and 2022).... Chaos was always just around the corner."

I'm not quite as sanguine as the Washington Post writer is, mostly because I've seen too many long-term assurances get derailed. Remember Francis Fukuyama's 1992 book, "The End of History and the Last Man," which assured us that liberal democracy and free market capitalism represented the final stage of human evolution? Look around today and tell me how that worked out.

I can also see plenty of short-term hurdles. The Trump administration is actually paying companies NOT to develop renewable energy, compensating companies for canceling off-shore wind projects. This administration has also recently announced some $700 million to support coal-burning plants, even though coal is on the way out as a source of electricity. In addition, the Trump White House is trying to halt or even reverse the transition to electric vehicles, even though the shift in strategy has caused U.S. car companies to take tens of billions of dollars in write-offs and will help Chinese companies widen their already considerable global lead on the cars of the future.

But I'm still convinced that the half-century-long oil crisis is, in fact, dissipating. 

The geopolitical implications will extend well beyond the Middle East. Other major oil producers, including Russia, Norway, Mexico and, perhaps, Venezuela. will lose huge amounts of revenue and, thus, influence. The world's largest producer, the U.S., won't be immune. Industries, such as chemicals, that rely on cheap energy prices in the U.S. will also lose out. 

Meanwhile, China should gain influence because of its dominance in the rare earth metals that are needed for batteries, in solar panels and in electric vehicles.

The changes should, in fact, reduce global tensions in some areas, though that doesn't mean that peace is at hand. China's increasing influence could, for instance, embolden it to try to retake Taiwan, which could touch off a geopolitical crisis. 

Insurers will have to tack continually as the geopolitical winds shift, and will have to guide clients wisely as they assess their risks. Insurers will likewise have to adapt as industries evolve — probably including shorter, more local supply lines at least for now, in reaction to the Iran war, and to the rise of isolationist politics, including America First. 

Again, there will be lots of twists and turns. Look at how fast Trump reversed U.S. policy in support of electric vehicles. But I think the move toward a post-oil world — at least one far less vulnerable to oil shocks — is accelerating because of the Iran war, and it's never too early to start reshaping our brains to prepare for such a profound change.

Cheers,

Paul

World Cup's First Star — and a Pointer for Insurers

While soccer fans are in a frenzy about the early results from the World Cup, the off-field action offers a suggestion for all businesses, including in the insurance industry. 

Image
Soccer

The World Cup always produces breakout stars. Think of 2018, when the teenaged Kylian Mbappe announced himself to the world by scoring four goals as his French team won the title. So far this year, you might lean toward Folarin Balogun as the possible breakout; he scored twice for the U.S. and looked brilliant as it dominated Paraguay in the opening round. For a team? Perhaps you're partial to Cabo Verde, a country of 500,000 that I confess I did not know existed but that tied mighty Spain, 0-0, on Monday.

For me, the clear breakout star is Freddy. 

The young German has taken social media by storm, growing his follower count on Twitter to 635,000 from the 11,000 he had when he arrived in the U.S. with some friends in early June for a six-week road trip to experience the World Cup. His earnest observations about the U.S. have made him so popular that when he posted that the group was headed to Houston, he arrived to find that former Houston Texas J.J. Watt had paid for a huge room for the group at a posh hotel, and that local businesses had stocked the room with gifts. When Freddy expressed admiration for the music of country music star Ella Langley, she invited the group to meet her backstage after a concert in Oklahoma City. A resort offered to send its plane to pick the group up in Oklahoma City and fly them to Las Vegas for a watch party for a game involving the U.S. men's team. 

There's a reason Freddy has become a sensation, and it suggests something that all businesses, including those in insurance, should do periodically.

An adage attributed to Marshall McLuhan (though with earlier roots) says, "We don't know who discovered water, but it wasn't a fish" — the notion being that anyone immersed in an environment can't understand it the way someone outside that environment can. And Freddy (@FreddyLA7 on Twitter/X) is an outsider providing an unvarnished, unbiased view of America to those of us immersed in it.  

He has shared video of his drive through Alabama and Mississippi and marveled at how beautiful the landscape is — something I certainly missed when I drove through the states on my way from Georgia to Louisiana. Freddy posted a picture of a pile of food at a Taco Bell and called it "the holy land." He wrote: "We were about to walk an hour to the stadium in the rain to save on an Uber, and the receptionist at the hotel we were parked in front of decided to drive us there." Freddy discovered that a Bass Pro Shop had a shooting range inside.

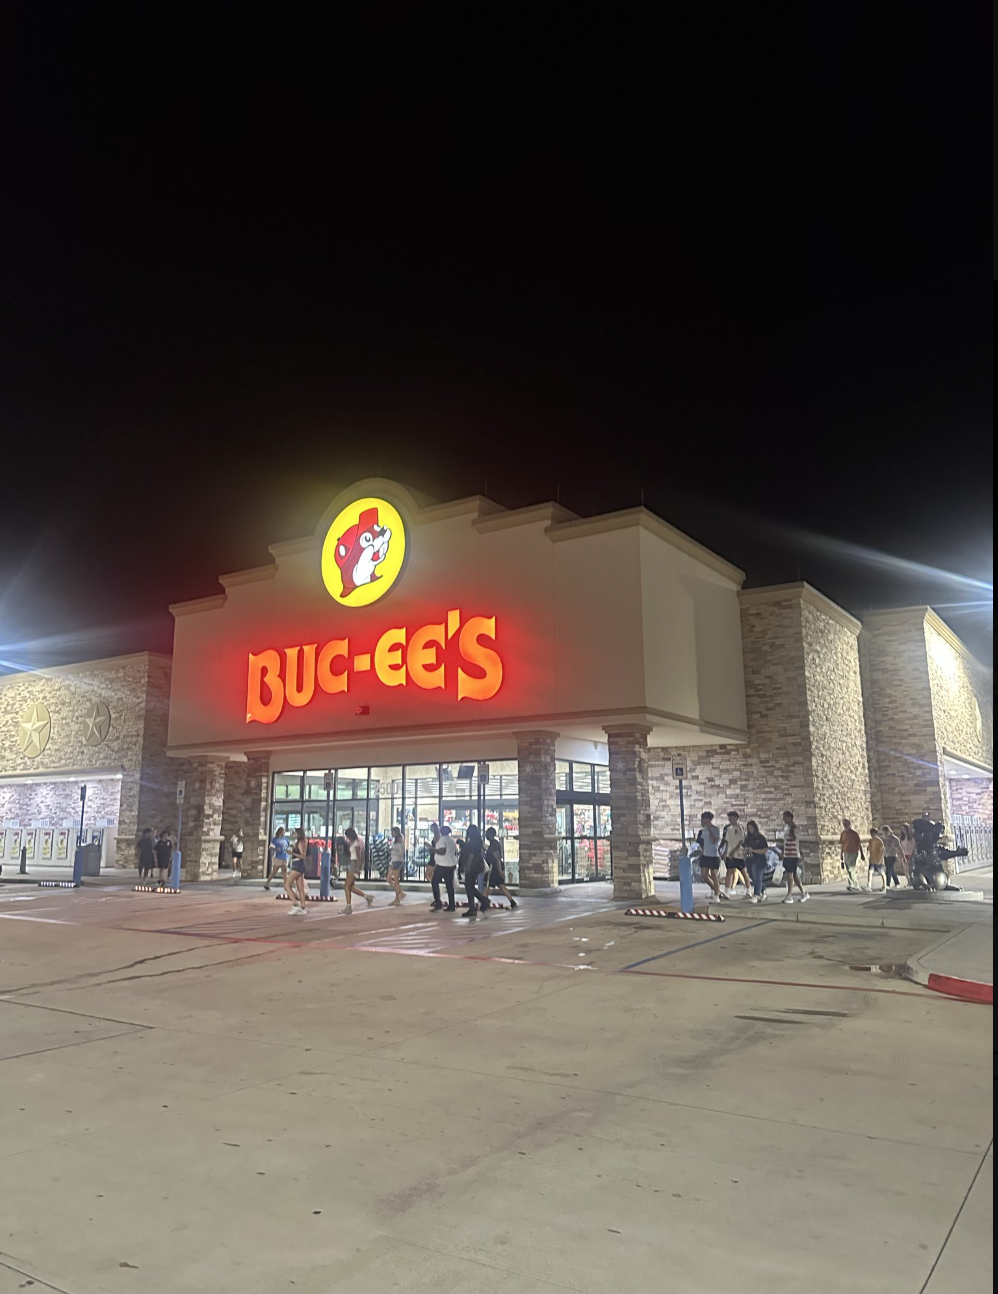
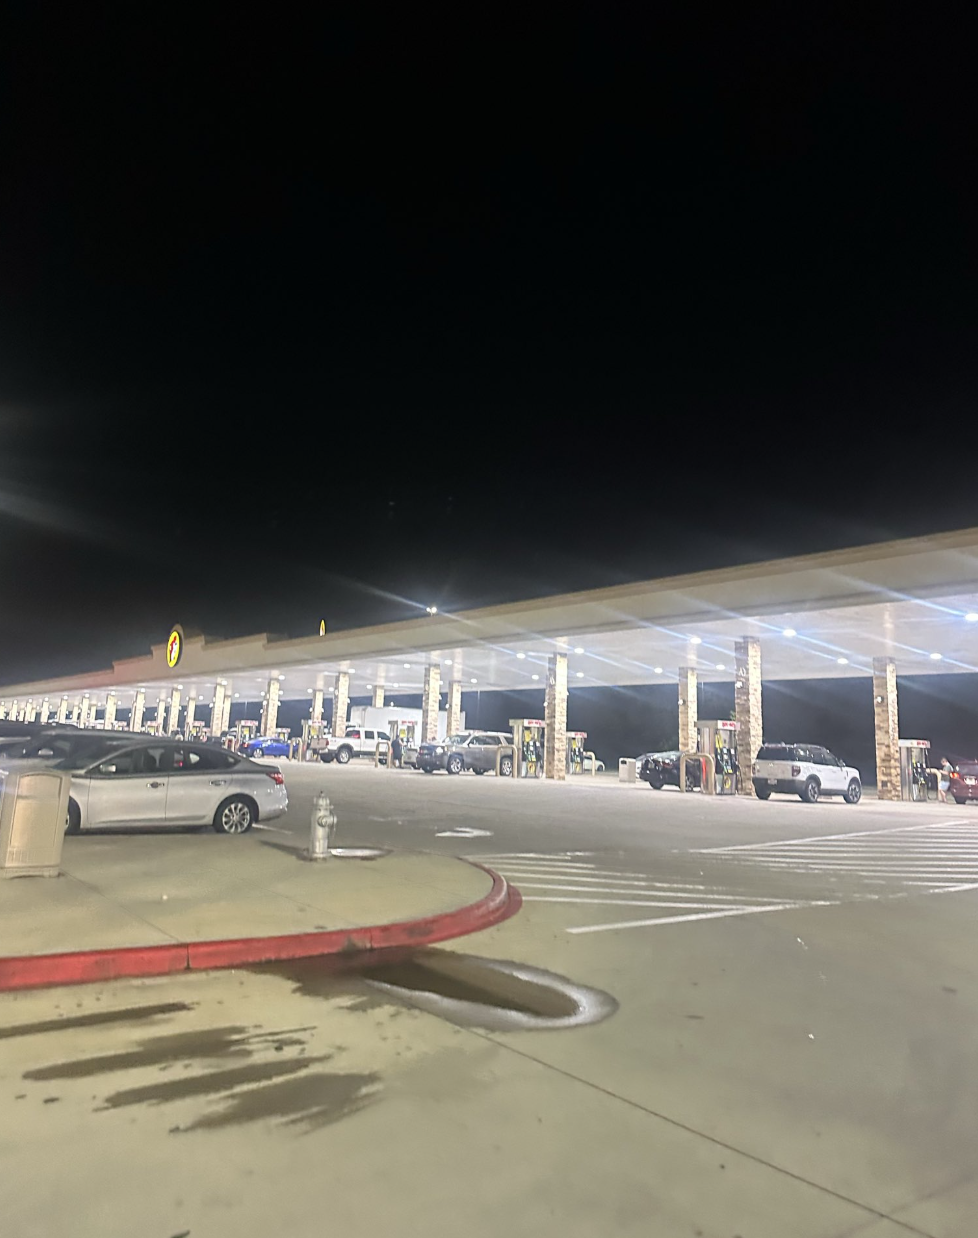
My favorite is a post with two pictures. On the left is a building so big and lit it up it looks like it could be the entrance to an amusement park. On the right is a line of gas pumps stretching way out into the distance. Freddy wrote: "DUDE LMAO THIS IS A GAS STATION." (Someone else said there are 120 pumps and wondered if the travel stop was designed to refuel the U.S. Air Force.)

.           

Freddy then added a photo of the mountain of barbeque he bought inside the Buc-ee's in Texas.

He has surely resonated partly because he's so positive about what he's experiencing in the U.S. Everybody likes to be told they're great. But he still demonstrates the power of outside, objective observation, which is something every company and every individual should solicit as a regular exercise. 

A BCG study I've cited before and will surely cite again found in the early 2000s that 80% of senior executives thought their product was superior to competitors' — and that 8% of customers agreed. Businesses unintentionally erect filters that distort what insiders see, so they have to try extra hard to either remove those filters for themselves or solicit feedback from Freddies who never faced those filters to begin with.

I once interviewed Colin Powell, between his time as the chairman of the Joint Chiefs of Staff and his term as Secretary of State, and he described what I thought was an insightful way to get around the filters. He set up half a dozen phones in his office and gave the number of each phone to a single person whom he trusted to provide a smart, non-DC perspective and reliable, unfiltered information. He told his assistant to never answer any of those phones, to hide the identity of the callers. (I note that the interview was before his time as Secretary of State under President George W. Bush because, after initially resisting the plan to attack Iraq, Powell let himself be sold a bill of goods and made a speech at the United Nations that relied on distorted intelligence to sell the world on the disastrous invasion.)

As I've written before, I think the best way to get unfiltered insight is to experience your company without identifying yourself or to sit with randomly chosen customers as they interact with your company. Make up a persona and call your call center or text it, so you can see what your chatbot actually does. Sit with a relative as they try to decipher the language in the policy you've issued them, without helping. Call people after they've had a claim processed to see just how smoothly your theoretically seamless handoffs from call center and app to adjuster to collision repair shops and rental car companies actually went. And so on.

You surely won't get the sort of joyful feedback Freddy is giving to the U.S., but you'll be able to improve faster than the companies you're up against — and business, like soccer, is a harsh competition.

Cheers, 

Paul

P.S. For those of you who, like me, have been immersed in America so long that the environment feels completely natural, here are a few other observations from visitors for the World Cup:

To start with the negatives, Americans are loud, the U.S. is expensive, and the distances are inconvenient. Traffic is awful. The culture of tipping is baffling. And why are so many items, such as toiletries, locked up in stores?

That said, Ranch dressing seems to be quite a hit. One woman marveled at being able to order a chicken waffle with Ranch dressing and ice cream in an iHOP. Another wrote: "Ranch dressing should be a human right." He added: "The portion sizes are hilarious."

Our grocery store culture has struck a chord, too — the enormity of Walmarts and Costcos, the extraordinary variety of foods offered, and the quality in some of the upscale stores. A Frenchman posted a hilarious screed about how he arrived in the U.S. intending to be a snob but has to admit that the bathrooms in Buc-ee's are nicer than in his apartment. He says, "You could eat the brisket off the floor. It's cleaner than a hospital."

One woman wrote: "I can’t lie… the food in America is ridiculous. Everyone talks about portion sizes, but nobody talks enough about how GOOD everything tastes. Even the ‘quick’ food feels elite compared to what I’m used to in the U.K."

Portion size does come up a lot. One man wrote: "Nobody warned me that American portion sizes are actually a threat to your health. I ordered a medium coffee and received what my country would classify as a bucket."

My favorite, non-Freddy post is a lengthy, almost poetic, one from a Japanese tourist about the biscuits and gravy that a waitress recommended to him at a breakfast counter:

"When the plate arrived, I thought something had gone wrong in the kitchen. I say this with shame. The dish looked like a construction site after rain. Pale mounds. Gray ladle-fall. Speckles I could not identify. In my land, the eye eats first. A meal is arranged like a garden. This meal was arranged like weather.

"I must now formally apologize to the biscuits, the gravy, the waitress, the kitchen and the entire breakfast tradition of the American South. 

"It was magnificent. Warm. Peppered. The biscuit drank the gravy the way a field drinks rain — THAT is why it is shaped like that, you fool — and every mound I had insulted was a soft fold of comfort that my homeland, in 800 years, never once thought to invent."

I'll never look at biscuits and gravy the same way again.