Download

When Insurance Data Can't Be Trusted

In the search for a single source of truth, insurers often force data into one clean gold layer - but make choices that are not always visible or acceptable to every consumer. 

Insurance Data Trust Drives Analytics Adoption Success

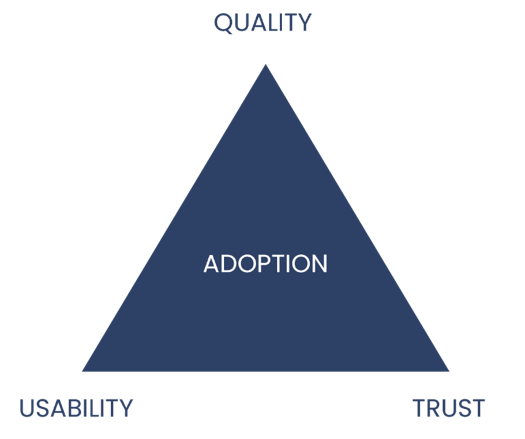
Every insurance company wants a single, trusted source of truth to power analytics, operations, and AI. The common response is to build sophisticated pipelines - often medallion architecture - to cleanse, conform, and enrich data. Quality and usability improve. Yet something unexpected happens: the more we touch the data, the more trust erodes. Key consumers start requesting the original sources instead. They want different grain, different views, or the ability to apply business rules. Traceability becomes more important than curation.

This lack of trust directly slows adoption. When people do not fully believe the curated layer, they route around it. The single source of truth we worked so hard to create ends up underused.

Why the tension is especially sharp in insurance

Insurance data is complex by nature: different systems, grains, effective dating rules, and business meanings of the same concept. When we force everything into one clean gold layer, we make choices that are not always visible or acceptable to every consumer. Actuaries, claims teams, and underwriters often need to reconstruct the original state. Their skepticism is rational.

One size does not fit all

Different consumption use cases demand different types and levels of enrichment and shaping. A dashboard for claims operations needs different treatment than an actuarial model or an AI feature set. Treating all data the same way in a single curated layer creates friction. What is highly usable for one group can feel restrictive or opaque to another.

A pragmatic approach

Instead of chasing one universal table, build shared data foundations, consistent processes, and rich metadata. Then deliver fit-for-purpose data products.

Shared foundations and metadata give everyone a common, well-governed base and clear lineage. Data products package the data in consumer-ready form: the right grain, the right enrichment, the right quality guarantees, and transparent provenance for each major use case. Patterns such as Data Vault help by connecting data early while postponing heavy business harmonization, preserving original history for those who need it.

When consumers can see exactly how the data was shaped and still get a product tailored to their needs, trust rises, and so does adoption. The true goal is a trusted foundation that supports multiple legitimate, well-documented views of the truth. That is how data management moves from a technical exercise to something the business actually uses.

The Easiest Cross-Sell Opportunity

Independent agents can cross-sell commercial coverage to personal lines clients using modern quoting technology and relationship advantages.

The Easiest Commercial Sale Is the One You Already Have

Running an independent agency means constantly triaging what gets your attention. Renewals, service calls, new business, and the next carrier appointment. With all of that in motion, it's easy to lose track of opportunities that could help you grow your business.

If your agency's book is built mainly on home and auto, commercial offers a real chance to diversify while picking up higher premiums along the way. It's an easy opportunity to overlook, though. Commercial quoting has traditionally been complex, and without the right technology, spotting where those opportunities live has been hard to do.

That's starting to change. Here's what's shifted, where the commercial opportunity actually lies, and why independent agents are especially well-suited to act on it.

From Three Workflows to One

Commercial quoting has traditionally meant juggling three separate systems: the application, the rater, and the carrier portal. Each handoff meant re-entering the same client information. Each one added time and room for error. A client would ask about a BOP, and the quote might sometimes take until the following week, once the risk worked its way through submission to quote. 

That's changed. Modern rating and quoting technology has consolidated those steps into a single workflow. Client information is entered once, and carrier quotes surface directly inside the submission workflow. A process that used to take the better part of an afternoon can now take a few minutes. That means commercial opportunities sitting in your book are much easier to act on.

The Cross-Sell Opportunity Already in Your Book

A good number of your personal lines clients probably also own a business. More of them than you'd guess are likely relying on you for their home and auto. For commercial coverage, though, they're going elsewhere, or nowhere at all. That's not a knock on how you've built your book. It's just what happens when there's more relationship there than there's been time to explore.

The upside is that you don't have to go find these clients. You already have them. A good management system can flag commercial cross-sell and upsell opportunities directly inside your existing client records. It connects the dots you might not have time to connect on your own. A client with a general liability policy but no commercial property coverage is a signal worth a second look. 

It's the kind of detail that's easy to miss manually scanning a file, but easy for the right system to surface automatically. Leaning on technology this way is a strong place to start with commercial. The opportunity is already sitting in your book, and the more policies a client holds with your agency, the more likely they are to stay.

Why the Independent Agent Still Closes the Deal

Finding commercial opportunities is only half the equation, though. Technology can surface them, but it won't close them. That part still comes down to relationships, and that's where independent agents have an advantage no software or national carrier can replicate. You know your clients deeply: not just their premium history, but their business, their plans, what keeps them up at night. You know the local market they operate in and the pressures specific to it. That kind of trust is exactly what turns a flagged opportunity into a signed policy.

The benefits of commercial go far beyond any individual sale. Expanding into commercial helps you build a diversified business. Personal lines and commercial lines don't always move in sync. Rate cycles, carrier appetite, and underwriting conditions in one don't necessarily track the other, so agencies with a foot in both aren't relying on a single market's conditions to carry the whole book. Writing more commercial accounts also gives you room to build real depth in a niche — restaurants, contractors, professional services, whatever fits your market. That kind of specialized knowledge makes your agency an obvious call for local business owners.

From Opportunity to Action

Taking advantage of the commercial opportunity doesn't require a big shift in how you run your agency. The friction that used to make commercial too much work to chase down has largely disappeared. Software built to spot these opportunities is now doing more of that work for you. What's left is simpler: the accounts, the trust, and the expertise you've already built are finally easy to put to work.


Rob Bourne

Profile picture for user RobBourne

Rob Bourne

Rob Bourne is the senior vice president and general manager of EZLynx. 

He previously served as SVP at Applied Systems, overseeing inside sales, account management, business development, and alliance partnerships. Before that, he held senior roles at Athelas and Podium. 

He has an MBA from Cornell University.

Reducing Non-Weather Water Loss with IoT

LeakBot's 65,000 years of US underwriting data proves actuarially relevant loss mitigation: mature programs cut non-weather mains-related water claims ~60%, and the $5/month all-in model delivers positive ROI across market segments.

Insurance
The Problem

Most IoT loss-prevention studies don’t survive actuarial scrutiny — underpowered samples, uncorrected selection bias, and hidden program costs have left carriers unable to trust the ROI case for smart-home safety programs, or to justify scaling one past a pilot.

Why It Happens

Proving a sensor prevented a claim runs into three structural problems: there’s no dated invoice for a loss that never happened, early results are skewed by anti-selection bias and poor test design, and the real benefit only emerges once a program has matured well beyond its first few months. Most vendor studies are sized and timed to miss all three.

The Solution

Back solutions that have already cleared the actuarial bar — tens of thousands of device-exposure years, cohort-level (not anecdotal) evidence, and documented, auditable repair records — rather than programs still running on pilot-stage promises.

Results

The synthesized results from four home insurance partners with mature deployments and statistically relevant underwriting years of data are as follows:

  • 60% of non-weather water losses occur on the pressurized side of the water system (Mains water)
  • 40% of non-weather water losses occur on the drain side of the water system
  • 60% reduction in the frequency of non-weather water losses coming from the pressurized side of the water system
  • ROI of 40% in mass market homes, 163% in mass affluent homes, and 980% in high-net-worth homes

--

Download the 2026 Leakbot White Paper 
 

Sponsored by LeakBot


LeakBot

Profile picture for user LeakBot

LeakBot

LeakBot is the only end-to-end IoT solution protecting homes from water damage—one that begins with leak detection and can end with a free repair. Backed by more than 10 years in business and 29 patents, a single self-installed device clips onto the home's main water supply line, monitoring water usage and detecting micro-leaks as small as one teaspoon per minute. When a leak is detected, the homeowner can book an appointment for LeakBot's trained employee plumbers to visit, locate, and repair it using specialty equipment — at no additional cost to carrier or homeowner. Homeowners consistently recognize LeakBot's value, reflected in a Net Promoter Score of 82/100 and Customer Satisfaction Rating of 4.9/5. That impact is especially powerful when a hidden micro-leak is found and fixed before it becomes a claim—or a costly plumber bill. That's #PredictAndPrevent in action.

Please connect with us: 


Breaking Down Silos in Insurance

Insurers can dismantle organizational silos by shifting from project-based work to product teams built around shared capabilities like underwriting and claims.

Breaking Down Silos in Insurance

It's easy to assume insurance silos stem from communication problems. When teams don't share enough information, systems become disconnected, and business units operate in disparate ways.

But silos begin with organizational structure. Teams prioritize work according to the operating model around them. If organized vertically, technology follows the same pattern. Each business unit may build its own systems and data practices to address its immediate needs, creating fragmentation that's difficult to unwind.

Breaking down silos in insurance requires an operating model that connects people, data, systems, and accountability. You can accomplish this by preserving each business unit's deep expertise while building a shared infrastructure that helps them work more effectively across your organization.

Insurance Needs Depth and Connection

Each line of business has its own risk appetite, customer needs, broker relationships, underwriting considerations, and claims complexity. That depth is one of the reasons clients and brokers turn to specialty carriers in the first place.

However, specialization can create the perception that every business unit is entirely unique, making it harder to identify common threads across the entire organization. Teams may assume there's little opportunity to share processes or insights because their work feels highly specific to their line of business.

Many of the core processes behind each segment are similar across the entire organization. You need experts who understand their markets in detail, but you also need the infrastructure to help those experts share their insights and serve customers with greater consistency.

Disconnection Creates Real Costs

When teams and systems aren't connected, you can miss opportunities that should be visible across your organization. A single customer may have relationships across multiple business units, but your organization may not have a unified view of that customer. Even when you know that connection, the customer or broker experience may vary.

Disconnected systems can also create operational inefficiencies. If each business unit builds its own technological solution for a similar issue, your organization may end up solving the same problem several times. That creates higher implementation and long-term maintenance costs. It also limits the ability to cross-skill employees or create business continuity across related functions.

From a technology perspective, the better model is to build once and deploy many times. You can identify what's common and manage the differences intentionally.

The more connected your organization becomes, the easier it is to create consistent workflows and more predictable delivery. But reaching that point requires you to think differently about the operating model behind your technology.

Prioritize Product Over Project

Many insurers still approach technology through a project-based model. A team is assembled to complete a specific project. Once they deliver the project, that team disbands and moves on to the next initiative. This approach can create inconsistency. Each new project may require a new team and a new understanding of the business problem.

However, a product-based model offers a different approach. Instead of bringing teams to the work, you bring the work to your teams. Those teams own a product, platform, or business capability over time. They understand the business context, the technology environment, the backlog, the capacity of the team, and the outcomes they're responsible for delivering.

This model can be especially valuable when teams are built around shared capabilities, such as underwriting or claims, that support multiple business units rather than a single line of business.

Underwriting offers a clear example. While each specialty line is unique, many parts of the underwriting process are similar across the business. Rather than having each business unit build its own separate underwriting tools or workflows, you can create a shared team focused on underwriting as an organizational capability. That team can include experts from different specialty lines, allowing them to build common solutions while still accounting for the unique needs of each business unit.

This approach enhances specialization. Business unit experts contribute to a broader capability that benefits from shared knowledge and accountability. It also creates the foundation for stronger data practices, because connected teams are better positioned to collect and use that data consistently.

Shared Data Is the Foundation for Scalable Technology

Data plays a central role in how you prepare for automation and more advanced digital capabilities.

For these technologies to create value, you need strong data foundations. If data is fragmented across business units or disconnected from the teams building technology, something like AI can become another siloed tool rather than a source of your organization's value. A common data set across business units can help you build technology that supports multiple parts of the organization.

Data engineering should be embedded into the teams responsible for business capabilities. When data and business expertise come together within a product team, you're better positioned to build tools that solve real problems and can be scaled across similar use cases.

But you still need human judgment to harness that data and technology.

Keep Humans in the Loop

Brokers and clients need people who understand the risks and the context behind every decision. Don't believe efficiency means removing the human element from your business.

Technology should help teams focus more time on the work where human judgment matters most. For underwriters, that may mean using automation tools to reduce more routine tasks so they can spend more time on risk selection and pricing sophistication. For business development teams, it may mean using data to identify trends that warrant outreach, such as a change in business flow from a particular broker or market segment.

But a human still needs to understand what's happening and determine the best next step. The human decision then creates feedback that can improve the model over time.

Use technology to make your experts more focused and informed. To do that well, avoid some common modernization traps.

Tie Modernization to Your Business Value

One of the most common risks in technology modernization is chasing solutions before clearly defining the business problem. New tools can be appealing, but technology should never be a solution looking for a problem.

Be selective about what you build versus what you buy from vendors. If a capability helps differentiate your business, building it provides more control and long-term value. If it supports a standard business function, buying an existing solution may be the more efficient choice.

Avoid creating new silos through disconnected tools or over-customized solutions. Make sure technology teams have the structure and visibility required to deliver consistently. That's what turns modernization from a series of projects into a sustainable operating capability.

Building Your Connected Insurance Enterprise

As the insurance industry continues to modernize, treat technology as part of a broader evolution of how work gets done. Brokers and clients are looking for insurers who can combine their expertise and insights with the infrastructure of the future. Balance efficiency with delivering the clarity and confidence they need in an ever-changing, complex market.

Climate Risk Doesn't Begin with a Hurricane

Insurers increasingly rely on AI-driven property condition data to assess climate-related deterioration between catastrophic events, not just during them.

Climate

Insurers have become very good at preparing for the big moments. Hurricanes, hailstorms, wildfires, floods and tornadoes are analyzed in remarkable detail, helping carriers estimate losses and prepare for large-scale events.

But some of the biggest drivers of property risk develop in silence, long before a named storm appears on the forecast.

Properties are constantly responding to the environments around them. Day after day, ordinary weather conditions gradually change the condition of roofs and exterior materials. Over time, they change the condition of a property in ways that aren't always visible until the next severe weather event turns gradual deterioration into a claim.

Catastrophe models are essential to helping us understand what could happen. What's becoming just as important is understanding what's already happened to the property before that event occurs.

Property condition tells part of the story

Rarely does a single storm cause a roof to fail; catastrophic damage is almost always the culmination of long-term environmental stress. Years of exposure to thermal fluctuations, moisture penetration, UV radiation and heavy rainfall systematically degrade roofing systems. By the time severe weather arrives, the property may already be more vulnerable than anyone realizes. The storm gets the blame, but the conditions leading up to it often tell an equally important part of the story.

These gradual changes have historically been difficult to observe consistently across large portfolios. That's beginning to change. Better property-level data is giving insurers a much clearer picture of how long-term climate exposure affects the condition of homes over time.

A recent analysis of more than 2.8 billion AI-derived roof observations across nearly 2,100 U.S. counties pointed to consistent relationships between chronic climate exposure and roof longevity. Counties experiencing the largest daily temperature swings showed roof aging about 23% faster than those with more stable climates. Homes in hotter, more humid regions tended to have shorter roof lifespans than comparable homes in cooler, drier environments.

None of those findings should be viewed in isolation. Combined, they suggest that long-term environmental exposure can influence property condition in ways that deserve greater consideration in underwriting.

A better question for underwriters

Property underwriting has traditionally focused on hazards surrounding a home. Is it exposed to hail? Flood? Wildfire? Wind? Those questions still matter.

The question that is becoming just as important is, what condition is this property actually in today?

Two homes built in the same year with similar construction can age very differently depending on the conditions they've experienced over time. One may have spent years exposed to repeated temperature swings. Another may have seen persistent humidity or heavier rainfall. Looking only at a property's age or location doesn't always explain those differences.

The industry has spent years getting better at predicting what a storm might do to a property. We're now much better positioned to understand what's happened to that property before the storm ever arrives.

Current aerial imagery and AI analysis make it possible to observe how properties change between quote, renewal, and claim. It doesn't replace traditional underwriting, but it provides another layer of context and data when evaluating current risk.

What this means for carriers

Catastrophe models are still essential. They're strongest when paired with a current understanding of how the insured property is changing between major weather events.

Hazard models explain the environment around a property. Current observations help explain how that environment may already be affecting the property itself. Looking at both together gives insurers a more complete view of risk than either can provide on its own.

That has practical implications across the business. Property condition can become part of renewal decisions instead of something evaluated only after a loss. Portfolio-level trends can help identify neighborhoods where homes appear to be aging faster than expected, even outside traditional catastrophe zones. Claims teams gain additional context about pre-loss conditions, while policyholders have more opportunities to address maintenance issues before relatively small problems become larger claims.

These aren't new objectives. Insurers have always wanted better information. What's changed is the ability to observe property condition consistently across large portfolios instead of relying solely on snapshots captured months or years earlier.

Looking ahead

One of the more interesting findings from the roof analysis wasn't simply that roofs age differently across the country. It was that the geography of climate exposure itself is changing.

The report found that U.S. land area in the highest rainfall-intensity band expanded from roughly 35,000 square miles during 1980 to 1984 to about 300,000 square miles during 2020 to 2024, an increase of approximately 750%. That doesn't mean every community faces the same level of risk. It does suggest that millions of properties are now experiencing environmental conditions that differ from what they were originally built to withstand. This reinforces the value of pairing historical experience with a current understanding of property condition.

Property insurance has always been about understanding uncertainty. Catastrophe models will continue to play a central role in that work. As the industry gains better visibility into property condition over time, insurers also have an opportunity to make more informed decisions between the next major weather event, not just after it.

Climate risk doesn't begin when a hurricane makes landfall. In many cases, it starts years earlier, one season, one temperature swing and one roof at a time.

The carriers that recognize those changes sooner will be better positioned to price risk, strengthen portfolios, and help policyholders address vulnerabilities before they become costly claims.


David Tobias

Profile picture for user DavidTobias

David Tobias

David Tobias serves as the general manager of insurance at Nearmap.

Previously, he co-founded Betterview, a property intelligence platform for P&C insurers that Nearmap acquired in December 2023. Before founding Betterview, Tobias was instrumental in scaling Research Specialist, an insurance loss control company.

When Sports and Insurance Mix (Badly)

The rushed sale of the Lakers and impending unwinding of a sports empire that includes the Dodgers will bring scrutiny to insurers and, perhaps, rating agencies. 

Image
Sports Commentary

Sometimes, when a headline hits, you just know the story is going to drag on for months, even years. The rushed sale of the Los Angeles Lakers for $12.5 billion is one of those headlines. 

It has all the elements. There are big names -- the buyers are Bob Iger, the former CEO of Disney, and Josh Kushner... yes, the brother of Jared and, thus, by extension, tied to the president. The Lakers franchise is iconic. The price is the highest for any team in the history of sports. And the sale looks like just the beginning. Mark Walter, who is selling the Lakers, may have to unwind his whole sports empire, and we'll see a new wave of stories any time he sells one of the other iconic names in his portfolio: the Los Angeles Dodgers, the Premier League's Chelsea, the F1 Cadillac team, the WNBA's LA Sparks, and more.

This headline also, I'm sorry to say, includes the insurance industry. That's because the impetus for Walter's yard sale is a federal investigation into the at least $20 billion that he pulled secretly from insurance companies he controls so he could finance his sports empire. He hasn't been charged with any crimes, and the investigation could, of course, lead nowhere. There's also no indication at this point that others in the insurance industry are using their companies as banks, beyond what's allowed by law and routinely reported. But you can be sure that there will be lots of scrutiny both for insurers and, perhaps, for rating agencies.

Let's have a look.

The Wall Street Journal does its usual, thorough job of reporting all the complexities of the investigation into Walter and his financial services firm, Guggenheim Partners, so I won't recount them in detail here. I'll just note that the WSJ says there is about $1 trillion in private credit that insurers have disclosed they are providing to related entities, as Walter did, without disclosing the extent of those loans until recently. That's a lot of money.

As far as I know at this point, much of that stems from an open and seemingly smart approach that private equity firms are taking in life insurance. PE firms are buying life insurers and using their vast investment portfolios both to increase the PE firms' assets under management and to increase the yield that the insurers get on their investments. If PE firms produce better returns than the firms had been generating, then everybody wins.

Walter may, in fact, be able to offer that sort of defense -- what basketball players would describe as, "No harm, no foul." He led a group that bought the Lakers for $10 billion in June 2025 and sold the team just 14 months later for 25% more. He led the group that bought the Dodgers in 2012 for $2.15 billion, and the team is now valued at perhaps $8 billion. But not all the investments were winners. The WSJ says Walter used funds from his insurance companies to, for instance, make an early investment in Beyond Meat, whose stock price has fallen from $4,700 to $11. Walter also leveraged his sports empire to buy personal properties, including mansions.

We'll have to see what happens when Walter unwinds the $20 billion of loans that his firm now acknowledges it didn't disclose.. and any additional ones that come to light now that the Feds are investigating his businesses. 

But don't expect the scrutiny of him, or the insurance industry's investment practices, to go away any time soon.

Cheers,

Paul 

As Iran War Drags on, Concern for P&C Grows

In our quarterly interview, Dr. Michel Léonard, chief economist at the Insurance Information Institute, explains how to use stress testing to protect against what may be unpleasant surprises.

Interview
Paul Carroll

Your latest economic outlook struck me as reasonably optimistic, despite the U.S. tariffs and our war against Iran, but the environment changes awfully fast these days. Where do you stand now?  


Michel Léonard

I'm sorry to disappoint. We put out our Outlook a few weeks ago, and I've already turned more pessimistic. You know me — I lean optimistic by default. But here's what happened, and it all comes down to the Iran conflict:

When we put out our last quarterly estimates, everyone was talking ceasefire — and what it would mean for the P&C industry, replacement costs especially, and for the broader U.S. economy, inflation especially. Then the ceasefire evaporated, and the consensus swung back to the war grinding on. So we started repricing growth and inflation across the board — systemic, structural, economy-wide.

I say more pessimistic because I'm not ready to call a trend yet. You've heard me say it takes two quarters to make a trend — and we're not there. We won't have two clean quarters of data until late this year or early next, on what the Iran conflict has done to the economy, or is still doing by then. But we've clearly shifted from worrying mostly about GDP growth to worrying about price stability and jobs, too.

Paul Carroll

Oil prices haven’t risen as much as many of us expected, because various countries, especially China, have cut way back on consumption or dipped into strategic petroleum reserves. As a result, the oil shock hasn’t spread throughout the economy as much as it might have. But with the resumption of at least occasional fighting in Iran and the depletion of petroleum reserves and stockpiles for fertilizer and other oil-dependent products, are we reaching a breaking point where contagion can no longer be contained?


Michel Léonard

Yes, absolutely. We've been measuring how oil-price contagion spreads into the wider economy two ways: first, the damage already done, through existing PPI [produce price index] data; second, how it could unfold from here, through stress tests.

On what's already happening: higher oil prices have jumped the fence from energy into everything else — the contagion is real. Aluminum and petrochemicals, machinery and equipment, electronics and accessories, fertilizer manufacturing, plastic resins and materials — all up an average of 34% year-over-year over the last six months.

Paul Carroll

As the conflict drags on without a clear path to negotiations or a long-term solution, what do your stress tests say might happen to replacement costs in P&C insurance?


Michel Léonard

Our P/C replacement-cost stress tests ran three conflict durations — through end-2026, into 2027, into 2028 — and zeroed in on the three lines the Iran conflict is already hitting hardest on replacement costs: farm owners, commercial property, and personal and commercial auto. For those lines, we estimate replacement costs climb an average of 13% year-over-year if the war runs into 2027, and another 20% if it drags into 2028.

Paul Carroll

How should people use scenarios like this to plan?

Michel Léonard

In our last outlook, we said the whole point of stress tests is to build consensus around managing the severity of tail events — not their likelihood. Scenarios have to be credible, but not the most likely — and almost never are. 

Let a stress-test conversation slide into political debate about how likely each scenario is, and it's dead on arrival. Pick credible scenarios, skip the likelihood argument, and go straight to impact severity — that's how you actually get people to consensus on a risk-mitigation strategy.

For P/C, that brings us to actuarial analysis — backward-looking by definition. Here, that's a feature, not a bug. You anchor to the data in the rearview mirror, then work with regulators on where reserving and rates should go. The stress tests are the headlights — you use them after, mostly to set reserving or policyholder surplus above what regulators require.

Now, if you ask which of the three is most likely, I'll say this may be the most impossible conflict to forecast I've seen in decades. Put a crystal ball in my hand instead of structured analysis, and I'd still bet on the one-year scenario — into 2027.

But I'll say it again: each scenario's exact probability is beside the point, as long as it's credible. What matters for our audience is that nobody can argue the war couldn't drag on another year or two. So my advice: reserve adequately for all three scenarios — in a way that's economically viable for your own book and how it actually behaves.

Paul Carroll

No matter what happens in terms of costs, the outlook for growth seems fairly positive. Is that correct?


Michel Léonard

The pressure point is what the Fed does. Real tell: the new chairman's very first communiqué ended with a standalone line — "The Committee will deliver price stability." That's just not how these things are written. I've never seen anything like it. It signals rate hikes for an inflationary environment, it locks the Fed in. And markets didn't like that line one bit when there was no rate increase at the next meeting.

I won't get into the dynamics between the new chairman and the president who appointed him — or what the president wants, which everyone knows. But if the Fed hikes based on today's inflation drivers, that's a basic policy mistake. Rate hikes work best on demand-driven inflation; this is supply-side, so raising rates buys you almost nothing.

As Greenspan used to say, rate hikes would be the wrong medicine for the disease. here This inflation is the White House's to cure — not the Fed's.

In my view, a 25 basis point hike in this geopolitical climate would land with several times the force it would in normal times. It would slam the brakes on growth — tipping GDP toward a contraction and pushing unemployment toward 5%.

Paul Carroll

A fair amount could change on tariff policy and other issues based on what happens in the November midterm elections. How do you see these political dynamics affecting the situation?


Michel Léonard

I'm so glad you brought that up, because the tariffs are back. It's August, and out of nowhere a few weeks ago we've got tariffs on Canada and others again. I didn't see that coming — I thought we'd closed that chapter. The only way they make sense right now is to change the subject, from Iran-conflict inflation to protectionism. But it's not all performative — tariffs are increasing government revenues, real money coming in, more than expected back in 2022. 

Tariffs are inflationary by design. They won't do affordability any favors — and insurance affordability least of all.

The midterms and the rest of the DC noise you're pointing to — that's what tips the one- or two-year scenario.

The one-year scenario gets more likely if Democrats lead the polls into the midterms and take at least one chamber of Congress — this could cause a replay of 1980, when Reagan was already offering a better deal to the Iranians before he'd even won the presidency.

The two-year scenario gets more likely if the Democrats don't win back a chamber. You'd have a lame-duck president who'd probably want to end the war he started on his own watch —  or, again, we could have a rerun of 1980.

Paul Carroll


What happens if the Iranians show for the long term that they can keep the Strait of Hormuz mostly closed and that the U.S. can’t protect our longtime allies in the Middle East as much as we and they thought we could?

Michel Léonard

That changes the whole ballgame — the repercussions would run in every direction. But now I'd be trading structured analysis for the crystal ball again, so I'll stop there.

Paul Carroll

We’ve covered a lot. How would you summarize?


Michel Léonard


First, prices are already spiking — and not evenly; some costs aren't behaving the way you'd expect. Check the actual BLS and BEA data. That part matters. Second, P/C replacement costs are climbing, too, hardest in farm owners, homeowners, and commercial property.

Finally — and I'll end on optimism, like I promised — I think this slowdown is short-lived. As long as the Fed keeps its hands off rates.

And if you’re a Triple-I member, don’t forget that you can reach out to us directly. Membership has its privileges. 

Paul Carroll

Thanks, Michel. As insightful as always.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

Insurance Data Accountability Can't Be Outsourced

Insurers outsource processes to third-party vendors, but when data fails or breaches occur, customers still hold the carrier accountable.

Carriers

Insurance carriers rely on third-party providers for nearly every part of their operations, from underwriting and vehicle verification to claims processing and fraud detection. These partnerships can help insurers move faster, access specialized technology and improve the customer experience. However, they also create more opportunities for sensitive information to be accessed, transferred and stored outside the carrier's direct environment.

While an insurer can outsource a process, it cannot outsource accountability for the customer data involved. If that information is exposed, mishandled or used to support an inaccurate decision, policyholders are unlikely to distinguish between the carrier and the provider working behind the scenes. They simply see a failure by the company they trusted with their information.

That shift comes as recent research from The State of Incident Response Readiness 2026, found that 73% of organizations say they are not fully prepared for a major cyberattack, despite having incident response plans and security tools in place. The findings highlight that readiness depends not only on technology, but on governance, coordination, and operational discipline. That is why vendor security can no longer be treated as a narrow IT concern or a compliance requirement that is addressed once during procurement. It has become a core operational risk that can directly affect claims outcomes, fraud exposure, regulatory scrutiny, and customer trust.

Third-Party Risk Is Embedded in Insurance Operations

Outside providers are often deeply involved in the workflows that shape important insurance decisions. In auto insurance, for example, carriers may rely on third parties to verify title status, registration, ownership, vehicle identity, and lien information. These records can determine whether a claim moves forward, whether a payment reaches the correct party or whether a file should receive additional review.

Consider a total-loss claim. Before settlement, an adjuster may need to confirm that the claimant owns the vehicle, identify any active lienholders, and verify that the title record supports the proposed payment. When that information comes from an outside provider, the carrier is relying on more than the accuracy of the record itself. It is also relying on the provider's ability to collect, store, and deliver the information securely.

If the provider lacks strong access controls, reliable audit trails, or clear data-governance practices, the carrier may have difficulty determining who viewed the information, whether it was altered, or how it was used. Those gaps can create delays during the claim, weaken fraud investigations, and make it harder to explain or defend a decision later.

Although the relationship may be managed through a vendor agreement, the consequences of a failure ultimately belong to the carrier, not the contract.

Vendor Reviews Must Go Beyond the Checklist

Most carriers already have a process for evaluating third-party providers. That process may include security questionnaires, contractual requirements, insurance documentation, and annual compliance reviews. These steps are important, but they are not enough on their own.

A vendor can meet a basic procurement requirement while still creating risk in its everyday operations. A written policy does not necessarily show that employees follow it consistently, that access is properly restricted, or that vulnerabilities are addressed before they affect customers.

Carriers should look closely at how a provider's controls work in practice. Who can access sensitive information, and why? How is that access monitored? Is the underlying data pulled directly from the authoritative source, or aggregated and refreshed on a batch cycle? Can the provider show when a record was retrieved or changed? How does it respond when a vulnerability, outage or data discrepancy is identified?

Independent assessments and certifications can help carriers evaluate whether a provider has established repeatable security practices and whether those practices have been tested over time. Their real value is in helping an insurer gauge whether a vendor has the discipline and maturity required to support an important business process.

Security Also Includes Data Integrity

Security also means making sure the information behind underwriting and claims decisions is accurate, current, and traceable to an authoritative source. A record may be securely stored and transmitted but still create real risk if it is incomplete, outdated, or disconnected from the authoritative source. That matters in claims and fraud workflows, where a title discrepancy, undisclosed lien, or ownership inconsistency can change how a file should be handled.

Take a vehicle that was re-registered in a new state last month. If a vendor's registration feed lags behind the state's actual record, an adjuster pulling ownership data may still see the previous owner attached, delay payment to the current policyholder, or route a routine claim into manual review for no real reason. Nothing was breached. The record was just behind, and being behind creates the same downstream cost as a security failure.

According to Point Predictive's 2026 Auto Lending Fraud Trends Report, fraud exposure reached $10.4 billion in 2025, driven in part by synthetic identities, AI-generated documents, and title-related fraud. Fraudulent title documents, fake lien releases, and manipulated ownership records may appear legitimate during a routine review. As more underwriting and claims workflows lean on AI, the quality of the data feeding those systems matters even more. A governance gap at one vendor can now surface as errors across far more decisions, and much faster, than it would have a few years ago. Claims and fraud teams need to understand where the information came from, when it was last updated, and whether there have been changes that require further investigation.

This traceability gives adjusters greater confidence in their decisions and allows fraud teams to identify potential issues earlier in the process. It also creates a clearer record if a payment, settlement, or verification decision is questioned after the claim has closed.

For insurers, secure data needs to do more than resist outside access. It has to be reliable enough to support the decisions being made with it.

Operational Maturity Becomes Clear During a Disruption

The quality of a vendor relationship is often most visible when something goes wrong. A system outage, data discrepancy or security incident can interrupt claims processing and delay communication with policyholders. What matters most at that point is whether the provider can identify the problem fast, explain which systems and records are affected and communicate clearly through the response. A provider that can't answer basic questions about the scope of an incident becomes part of the disruption instead of the fix.

Carriers should settle escalation procedures before a problem occurs: who contacts the vendor, what information the provider has to produce and how affected workflows keep running while the issue gets resolved. That oversight shouldn't stop once the vendor is onboarded. A provider that starts out supporting one verification task can end up embedded in several claims, underwriting and fraud workflows within a year, and oversight needs to grow with the relationship instead of lagging behind it.

Customers Still Hold the Carrier Responsible

Most policyholders will never know which third-party systems are used to support their claim, but they will notice when those systems create a problem. A delayed verification turns a routine claim into a frustrating wait. A security failure exposes exactly the information a customer trusted the carrier to protect.

From the customer's perspective, it's all part of the same insurance experience.

That is what puts a stalled claim or an exposed record on the carrier's reputation, not the vendor's. The controls operating behind the scenes shape how quickly a claim moves, how confidently an adjuster communicates, and whether a policyholder keeps trusting the carrier once the process is done.

Insurers should evaluate vendors with the same seriousness they apply to speed, accuracy, and service. Strong providers build security and governance into how they modernize, so carriers keep control of the data behind their decisions instead of trading it away for speed.

In practice, that starts with two questions worth asking before the next disruption: what happens to a file when a vendor's system goes down, and how fast does a stale or disputed record get flagged before it reaches a customer? If those answers aren't clear today, that's the gap to close first.

Third-party partnerships will continue to play an important role in insurance. As that reliance grows, the real competitive advantage lies in choosing partners that can be trusted with the data behind every underwriting decision, claim, and customer interaction. Processes can be outsourced. Accountability cannot.


Lee Perine

Profile picture for user LeePerine

Lee Perine

Lee Perine is co-founder of YASSI.

He works with insurance and automotive organizations to improve vehicle-data workflows, verification processes, and operational efficiency within auto claims environments.

Claim Preparedness Starts Long Before the Loss

Insurers must build policyholder trust through consistent communication strategies long before disaster strikes, not just during claims processing.

How Insurers Can Build Trust Ahead of El Niño

Customers do not judge their insurer solely by how quickly a claim is settled. They also remember whether they felt informed, supported and confident throughout the experience, and those perceptions often begin to form long before the first claim is ever filed. Every policy renewal, coverage update and customer communication contributes to the expectations policyholders carry with them into one of the most stressful moments of their lives.

The 2026 Atlantic Hurricane Season began June 1 – and as of this point, has not been particularly active. But severe weather events have become more frequent, more destructive, and more unpredictable.

As a result, insurers continue to invest heavily in disaster response capabilities. While those investments are essential, preparedness cannot be measured only by claims capacity or operational readiness. It also depends on having a customer communications strategy that helps policyholders understand their coverages, prepare for potential risks, and know what actions to take before, during, and after a catastrophic event.

By delivering clear, timely, and relevant information through the channels customers prefer, insurers can set expectations, reduce uncertainty, strengthen trust, and empower policyholders to make informed decisions when it matters most. In this way, effective communication becomes just as critical to disaster preparedness as the systems and processes supporting claims themselves.

Preparedness Begins With Better Customer Communication

For many policyholders, a natural disaster may be the first time they have to navigate the terms, conditions, and coverages of their insurance policy. Questions about deductibles, exclusions, replacement costs and coverage limits often come up only after damage has already occurred, adding uncertainty to an already overwhelming situation.

Insurers have numerous opportunities to close that knowledge gap well before disaster strikes. New policy and renewal summaries and communications can explain policy coverages – and any changes – in plain language rather than legal terminology, while seasonal outreach can encourage customers to document their property, review coverage limits, update contact information and understand what to expect if they need to file a claim. These conversations are more than education, they are enablement. This level of transparency helps customers make informed decisions before an event occurs and ultimately makes the claims process smoother for both policyholders and insurers.

Preparedness is not simply about ensuring claims teams are ready to respond. It is also about ensuring customers know what to expect before they ever need to pick up the phone. When policyholders understand their coverage and the claims process ahead of time, they are better equipped to navigate an already stressful situation with greater confidence.

Every Interaction Shapes Customer Confidence

When disaster strikes, policyholders aren't looking for lengthy explanations or technical policy language, they want straightforward answers to questions like:

What happens next?

What is covered?

How do I file a claim?

When will I hear from someone again?

Delivering those answers consistently across every touchpoint has become just as important as delivering them quickly. Whether a policyholder opens an email, logs into a customer portal, receives a text message or speaks with a claims representative, they should receive the same accurate information and the same clear guidance. When communication becomes fragmented through conflicting updates, duplicate requests for information or inconsistent messaging across channels; uncertainty grows precisely the moment insurers are trying to build confidence.

When disaster strikes, consistent communication isn't just great customer service, it's a necessity. Because when customers need confidence most, a seamless communication strategy not only reduces confusion, but reassures policyholders that their insurer is in control.

Communication Infrastructure Resilience

Major weather events place enormous strain on insurance operations. Claims volumes surge, contact centers become overwhelmed, and customers expect frequent updates throughout the process, often across multiple channels. Meeting those expectations requires more than simply adding resources after an event occurs. It requires communication systems that can scale alongside claims operations while maintaining accuracy, consistency, and personalization.

Automated workflows, centralized customer data, and coordinated communications ensure insurers can proactively acknowledge claims, request documentation, provide status updates, and keep policyholders informed throughout the entire claims journey. They can deliver a better experience while reducing the operational burden on employees, rather than relying on manual processes during periods of peak demand.

Just as insurers routinely stress test disaster models and business continuity plans, they must also test their customer communication strategies for resilience. Including asking questions like:

Can communications be updated quickly when necessary?

Are messages consistent across every channel?

Can teams personalize outreach at scale without delays or confusion?

These check-ins are just as central to disaster preparedness as the operational plans themselves.

Trust Is Built Before the Storm

Natural disasters will continue to test insurers in new ways, and while no organization can control when or where the next disaster will occur, every insurer can influence how prepared and supported their customers feel. The organizations that stand apart will not simply be those that process claims efficiently, but those that have already built trust through clear, timely and consistent communication long before a policyholder ever needs to file a claim.


Eileen Potter

Profile picture for user EileenPotter

Eileen Potter

Eileen Potter is vice president of marketing for insurance at Smart Communications. 

She has more than 25 years of insurance experience with both P&C and life. She has worked in independent agencies and MGA operations in various roles, including commercial marketing and underwriting. Her software background includes work with organizations such as ABBYY, Appian, One and Duck Creek Technologies.

Catastrophe Models Lack Key Data

Catastrophe models excel at mapping where disasters strike but lack critical data on when and how events unfold over time.

Catastrophe Models

Catastrophe modeling has spent the last 20 years getting more precise about where a catastrophe happened and what was affected. Parcel-level geocoding, building-level vulnerability, more accurate secondary modifiers and high-resolution terrain data are examples of this focus. Yet almost no progress has been about when events occurred during the catastrophe. Data resolution is no longer the binding constraint on understanding risk, cadence is.

In my years working with insurance buyers of remote sensing data, one refrain came up constantly, "this is great," they would say about high-resolution aerial or satellite imagery, "but I also need to know what is happening before, during, and after an event to fully understand my risk."

There is no clearer example of that temporal gap than wildfire. Wildfire conditions can be forecast, but unlike an impending hurricane there are no days of notice for when they start, just the standing risk that one could begin at any moment. And unlike most other perils, wildfires can be slowed or contained. We can do more than build better and warn people – with the right data at the right time, we can change the outcome of an event.

Unfortunately, there are data gaps in our existing systems that limit our ability to do that today. Geostationary weather satellites provide a snapshot every 20 minutes at two-kilometer infrared resolution, and the published detection floor for the GOES-R fire product is a large 60 x 60 meters. Low Earth Orbit sensors give far finer pixels but only have a couple of looks a day. Aerial sensors are even less frequent and are limited by weather. In situ sensors have limited geographic range and rarely see the fire itself. These systems provide excellent snapshots but are poor at telling the entire story of a wildfire from ignition to extinction.

Commercial GEO remote sensing systems are designed to close that gap. They are deployed farther out in orbit from the Earth, thereby matching the speed of the Earth's rotation, "holding still" over a large geographic region to provide continuous data.

There are obvious upsides to a livestream of data over a large geographical area, event response being the biggest. However, the most impactful are less about what is happening right now and more about a better temporal record of what happened over the life of the event. These include model validation, hours clauses, parametric triggers and mitigation credits.

Every catastrophe model is calibrated against outcomes: final footprint, depth and damage state. The process is inferred from the outcome rather than from observing the progression of the event, and inference is where model divergence lives. This is akin to skipping pages while reading a book. You know how the story ends, but you don't understand how you got there, which in the case of a catastrophe modeling methodology is critical.

Wildfire is the extreme version. We know where fires ended up; we know far less about ignition timestamp, first-hour spread rate, the hours when suppression held and the hour it stopped. A continuous infrared record turns each fire into a time series rather than a handful of perimeter snapshots. Two models can produce the same 40,000-acre burn for entirely different and entirely wrong reasons.

Hours clauses are the clearest case of our market pricing something it cannot measure well. The apparatus assumes we can say when an occurrence began, when it ended, and which losses belong inside it. In practice, it is reconstructed from incident reports, agency data, and argument.

With wildfire, separate ignitions become one event. A continuous, timestamped record of ignition, merge, and progression gives the cedant and reinsurer one clock to read from. That matters for aggregation disputes, retention attachment, and live Cat trading, where the market prices off news coverage and helicopter footage.

Wildfire triggers today lean on a burned area mapped from optical imagery, typically days after the event. Practitioners admit that trigger precision is the whole game, and that the underlying data determines how well a settlement tracks the loss.

Continuous observation moves the trigger off the residue and onto the event, which is why sensors work well. It timestamps onset, which makes duration triggers writable. A geosynchronous satellite does that across a huge geographic area, not just that covered by sensors.

Wind shows what a defensible credit requires. After Hurricane Sally, Alabama's regulator ran a claims data call and commissioned a peer-reviewed study. FORTIFIED construction reduced loss frequency by at least 55% to 74%. Which is why wind mitigation discounts survive a rate hearing.

That method works when the hazard leaves a readable aftermath. Wildfire does not. A destroyed structure tells you almost nothing about what the fire was doing when it arrived. Meanwhile, the regulatory clock is running. California introduced the first mandatory wildfire safety discounts in 2022 and now requires catastrophe models to reflect mitigation. Billions are going into defensible space, home hardening, and vegetation management, credited on engineering judgment and good intentions.

Continuous observation, matched against parcel-level mitigation records and claims outcomes, provides an observed distribution of results for hardened versus unhardened exposures under comparable fire behavior. Mitigation credit stops being an educated guess and becomes a defensible rating variable.

Closing the temporal gap changes what is knowable, giving us a record of a catastrophe as it happened, rather than a reconstruction. We need to start creating a record now for improved peril modeling that will become the standard for the coming decades.