Download

Have We Turned the Corner on Distracted Driving?

We seem to finally be waking up to the dangers, and we're getting an assist from an emerging technology. 

Image
driving while on phone

For a book project in 2013, I looked up trends in traffic fatalities in the U.S. and was startled by the progress. In the quarter-century since 1988, fatalities had fallen steadily from more than 47,000 in a year to less than 33,000 even as the U.S. population increased by a third. Fatalities per 100 million vehicle miles traveled had fallen by more than half, from 2.32 to 1.1. 

We were doing something right. 

Then progress stalled... and then the trend reversed. By 2021, nearly 43,000 people died on U.S. roads, and the number was almost that high in 2022. 

Why? Mostly because of distracted driving--all those smartphones we'd been buying since Apple introduced the iPhone in 2007 and were paying attention to rather than keeping our eyes and minds on the road. 

So I was delighted to see the recent report from Cambridge Mobile Telematics, which said distracted driving had declined 4.5% in 2023. CMT calculated that the improvement "helped prevent over 55,000 crashes, 31,000 injuries, 250 fatalities and close to $2.2 billion in economic damages in the U.S. in 2023."

Calling a turn in a trend is always tricky, but I've followed a lot of trends for a lot of years, and I'm ready to call this one. I think distracted driving will only decline from here, for two reasons. 

I'll explain. 

Insurers can take a lot of credit for one of my reasons: the publicity about distracted driving that has created such awareness and pushback for years now. 

Public pressure almost always builds slowly -- far too slowly, in this case -- but it has now built to the point that you have to be pretty young or pretty reckless not to have had the dangers of distracted driving beaten into your brain. Insurers are reinforcing the PR effort through telematics and usage-based insurance, which dings drivers for distractions and rewards them for improving driving habits. 

The surge in auto insurance rates in the past couple of years has also caught everybody's attention and made them look for ways to lower premiums. That surge relates primarily to supply chain issues that made cars, parts and labor far more expensive and to reckless driving habits that developed when the pandemic emptied roads. Still, sensitivity about rates reinforces awareness about the need to avoid accidents.

I've been watching for some time to see a weakening of the curse of distracted driving. Most of us have had a smartphone for 15 years now. The technology has matured, and so has our understanding of it and our use of it. 

Even if I'm right in calling the turn, we still have a long way to go. The CMT report estimates that 29% of all crashes are due to distraction, which would mean it caused 12,405 fatalities in 2021 (almost the same number that were due to impaired driving that year). 

But trends end. Trees don't grow to the sky. And I think we've passed the peak of distracted driving.

My other reason for optimism is a sort of "tweener" technology that is gaining momentum. It won't eliminate crashes as effectively as I believe driverless cars eventually will, but it can already do a lot to snap drivers to attention at moments of imminent danger, both for themselves and for others on the road. 

The technology is basically two cameras and a whole lot of AI. One camera looks at the road to watch for obstacles such as other cars, cyclists and pedestrians. The other looks at the driver to see if they're paying attention to the road or need to be alerted about what's ahead, about tailgating or excessive speeding, about drowsiness or about anything else. The AI surveys the situation and, when necessary, alerts the driver -- by voice if the driver is just being coached but by alarm if the driver needs to instantly size up what's happening in front of them. 

I've read about various flavors of this approach over the years, but the one I'm most familiar with is from Nauto, because I've known the founder, Stefan Heck, for a dozen years, reaching back to his days as a senior partner at McKinsey and then a professor at Stanford. I did an interview with Stefan for our Future of Risk series last November, which raised the prospect of reducing vehicle accidents by 60%, 

At the end of May, Pete Miller, the CEO of The Institutes, released a podcast he did with Stefan as part of Pete's Predict & Prevent series,  and I encourage you to listen or to read the transcript, which is full of enlightening and encouraging detail. For instance, Stefan says that, when you can actually see what's happening in the car, you learn that 70% of accidents are caused by distraction. He also says that just among his customers, which are mostly commercial fleets, Nauto's technology has prevented 30,000 accidents in the past 18 months; based on government statistics, preventing those accidents means that some 30 people are walking this Earth who otherwise would not be. 

Stefan says the camera looking at the road can give a distracted driver three to four seconds of warning before a collision would occur. It takes the driver maybe two-thirds of a second to focus on the problem, giving them two or three seconds to hit the brakes or swerve out of the way.

Driverless cars will react much faster and will be much more careful in the first place, avoiding many situations that require instant reaction... but they aren't here yet and won't be in meaningful numbers for many years yet. The technology still needs work, and the turnover of the U.S. car fleet typically takes some 15 years. 

Prompts for distracted drivers can do a lot of good in the meantime. 

Cheers

Paul

P.S. I encourage you to not only check out Pete's podcast with Stefan but to use that link to sign up for the Predict & Prevent podcast. which explores how the industry can move beyond the traditional repair-and-replace model and perform the service that people really want: helping them never have that claim in the first place. The first season of the podcast was terrific, and the interview with Stefan launches the second.  

U.S. Annuity Business Must Be Digitized

The future of the annuity business lies in leveraging digital technologies to enhance regulatory compliance, streamline operations and deliver superior customer experiences. 

A Person Holding a Black Pen

The annuity business in the U.S. is a multifaceted segment of the insurance industry, providing a critical financial product that helps individuals secure a steady income stream for retirement. However, managing annuities presents numerous challenges for insurance carriers. These challenges stem from regulatory complexities, market volatility, operational inefficiencies and evolving customer expectations. As the industry grapples with these issues, digitization emerges as a promising solution, offering the potential to streamline operations, enhance customer experience and improve overall efficiency.

Regulatory Compliance and Risk Management

One of the most significant challenges in managing annuities is navigating the intricate web of regulatory requirements. Annuities are subject to federal and state regulations that govern product design, marketing, sales practices and financial reporting. Insurance carriers must ensure compliance with these regulations, which can vary widely across jurisdictions.

Moreover, annuities are long-term products, often extending over several decades. This longevity introduces considerable risk management complexities, including interest rate risk, longevity risk and market risk. Carriers must maintain sufficient reserves and capital to meet future obligations, which requires sophisticated actuarial models and financial projections. Ensuring compliance while managing these risks necessitates substantial administrative effort and expertise.

Operational Inefficiencies

Operational inefficiencies are another major hurdle. Traditional processes are often paper-intensive and require manual handling, leading to delays and errors. Policy issuance, premium collections, claims processing and customer service can be cumbersome and time-consuming, detracting from the overall customer experience.

Legacy systems compound these inefficiencies. Many insurance companies rely on outdated technology infrastructures that are not equipped to handle the complexities of modern annuity products. These systems often lack integration capabilities, resulting in siloed data and fragmented operations. The inability to quickly access and analyze data impedes decision-making and hampers the ability to respond to market changes and customer needs effectively.

See also: Where Next for Insurance Ecosystems?

Evolving Customer Expectations

Today's consumers are more informed and tech-savvy than ever. They demand personalized products and services, seamless digital experiences and real-time access to information. For insurance carriers, meeting these expectations is a significant challenge. Traditional models of customer engagement, which rely heavily on face-to-face interactions and paper-based communication, are increasingly out of step with consumer preferences.

Furthermore, the complexity of annuity products can be a barrier for customers. Understanding the various options, fees and potential returns requires considerable financial literacy. Insurance carriers must find ways to simplify this complexity and provide clear, transparent information to help customers make informed decisions.

The Promise of Digitization

Amid these challenges, digitization offers a transformative solution. By leveraging digital technologies, insurance carriers can address many of the pain points associated with managing annuities and create a more efficient, customer-centric business model.

1. Enhanced Regulatory Compliance and Risk Management

Digitization can significantly enhance regulatory compliance and risk management. Advanced analytics and artificial intelligence (AI) can be employed to continuously monitor and analyze regulatory changes, ensuring that carriers remain compliant with the latest requirements. These technologies can also improve risk management by providing more accurate and timely data for actuarial models and financial projections.

For instance, predictive analytics can help carriers anticipate market trends and adjust their portfolios accordingly. AI-driven tools can analyze large volumes of data to identify potential compliance issues before they become problematic, allowing carriers to address them.

2. Streamlined Operations

Automation is a key benefit of digitization. Robotic process automation (RPA) can handle routine administrative tasks, such as policy issuance, premium collection, and claims processing, with greater speed and accuracy than manual methods. This reduces operational inefficiencies and frees human resources to focus on more complex, value-added activities.

Moreover, modernizing legacy systems with cloud-based solutions can enhance data integration and accessibility. Cloud technology enables real-time data sharing and collaboration across departments, breaking down silos and fostering a more agile and responsive organization. Integrating advanced digital platforms can also facilitate better data management, enabling carriers to quickly access and analyze critical information for decision-making.

3. Improved Customer Experience

Digital technologies can revolutionize the customer experience in the annuity business. Online portals and mobile apps provide customers with convenient access to their accounts, allowing them to view policy details, make transactions, and track their annuity's performance in real time. These platforms can also offer personalized recommendations based on individual financial goals and preferences, helping customers make more informed decisions.

Interactive tools and educational resources, such as calculators and tutorials, can demystify annuity products and enhance financial literacy. AI-powered chatbots and virtual assistants can provide instant, round-the-clock customer support, addressing queries and resolving issues without the need for human intervention.

Furthermore, data analytics can be used to gain deeper insights into customer behavior and preferences. This information can inform the development of more tailored products and services, ensuring that carriers meet the unique needs of their customers.

See also: AI Bias in Life & Annuities Insurance

Embracing the Digital Future

The annuity business in the U.S. insurance industry is fraught with challenges, from regulatory compliance and risk management to operational inefficiencies and shifting customer expectations. However, the advent of digital technologies presents a unique opportunity to overcome these obstacles and build a more resilient, efficient and customer-focused business model.

Embracing digitization is not without its challenges, including the need for significant investment, change management and cybersecurity concerns. Nonetheless, the potential benefits far outweigh the risks. By investing in digital transformation, insurance carriers can not only address current pain points but also position themselves for long-term success in an increasingly digital world.

Conclusion

While the journey toward digitization may be complex, it is an essential step for U.S. insurance carriers managing annuities. The future of the annuity business lies in leveraging digital technologies to enhance regulatory compliance, streamline operations and deliver superior customer experiences. By doing so, carriers can thrive in a dynamic and competitive landscape.


Neeraj Kaushik

Profile picture for user NeerajKaushik

Neeraj Kaushik

Neeraj Kaushik, principal consultant, is a product manager for the NGIN platform initiative at Infosys McCamish Systems. 

He is a published author and Top Insurtech voice on LinkedIn. Kaushik has driven large-scale technology projects based out of the U.S., U.K., India and China for the last 18-plus years. He has led strategic consulting and transformation initiatives across life, annuities and property & casualty.

He was previously part of Big 4 consulting firms such as PwC & Deloitte.

Looking at the 2024 Atlantic Hurricane Season

Most forecasts are for 20 to 25 named storms, 10 to 12 hurricanes and four to six major hurricanes--all well above recent averages.

Palm Trees During a Hurricane

The spring before each hurricane season brings with it calls for preparation throughout those who live on or near coastal areas, as well as throughout the (re)insurance industry. To aid in anticipating such preparations, professional forecasters in academia and industry have been releasing their preseason forecasts for the coming Atlantic hurricane season for decades. These forecasts are based on statistical and climatological models built up from past seasons’ activity and accompanying large-scale climatological patterns. As the science behind these models has improved, these forecasts have become more skilled. With the Atlantic hurricane season just starting, let's examine these preseason predictions for the 2024 season and the science behind them.

See also: Preparing for a Rough Hurricane Season

Hurricane Forecast Graphs

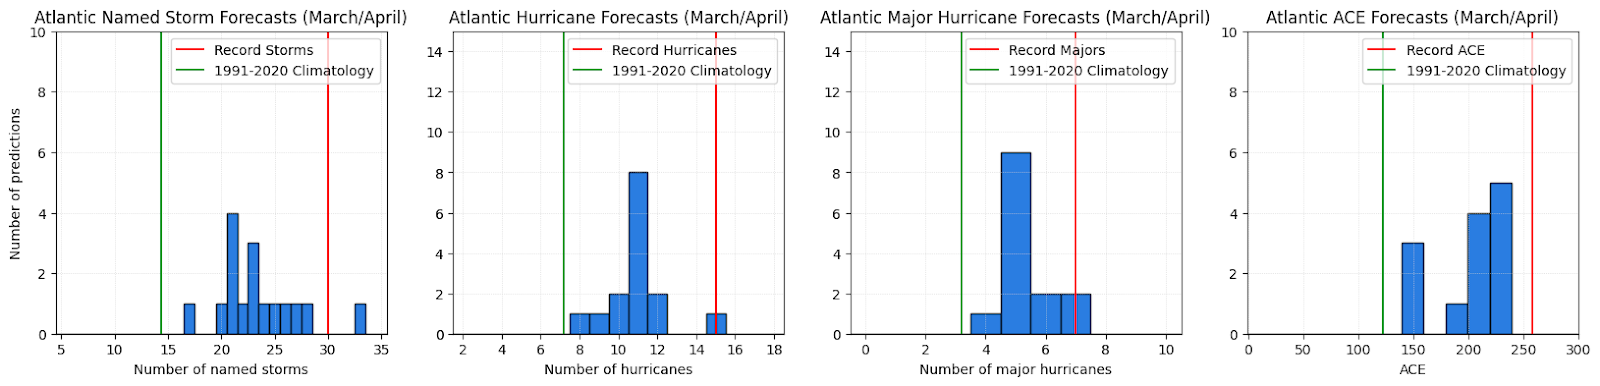
Figure 1- Histograms of the 18 preseason (March/April) forecasts for named storms, hurricanes, major hurricanes and accumulated cyclone energy (left to right) compiled by the Barcelona Supercomputer Center and Colorado State University forecasters. The green line represents the recent average for that category; the red is the historical record for that category.

This season’s forecasts for Atlantic hurricane activity from 18 preseason forecasters are noted in Figure 1’s histograms. From these, we see that the forecasters are predicting that the Atlantic will be busy this year, with most forecasts lying between 20 and 25 named storms, 10 to 12 hurricanes, four to six major hurricanes and an accumulated cyclone energy (ACE; an integrated measure of the activity in a season) between 150 and 240 units. These forecasts are all above the recent averages of 14 named storms, seven hurricanes, three major hurricanes and 120 units of ACE.

See also: The Hurricane Forecast Keeps Getting Darker

These forecasters all use a variety of climatological patterns to guide their forecasts, though many are built around some combination of the same two primary factors: how warm the Atlantic sea surface temperatures will be and the state of the El Niño Southern Oscillation (ENSO). These two factors have been found to be the strongest statistical predictors of Atlantic hurricane activity.

Sea surface temperatures are the simplest effects to understand. Hurricanes form due to strong thunderstorms organizing and forcing a warm-core vortex. This is best accomplished with vigorous, persistent and upright thunderstorms. Warmer sea surface temperatures mean more energy and more moisture being pulled upward through these thunderstorms. So, in general, warmer sea surface temperatures mean that more tropical storms will likely form throughout the course of a season.

ENSO is a bit more complex. ENSO is a coupled ocean-atmosphere climatological mode, measured by the variations from the climatological averages for the waters in the tropical central Pacific Ocean. If these waters are warm/cold, ENSO is in an El Niño/La Niña phase. The phase of ENSO is reflected in the atmosphere by the changes in the overturning tropical circulation worldwide, known as the Walker circulation. For the Atlantic, when El Niño is active, the wind shear in the Caribbean Sea and central Atlantic tends to be increased. When La Niña is active, shear is typically decreased. As mentioned previously, vertically upright thunderstorms best form a tropical storm vortex, so less shear means that more storms will tend to form and intensify.

Navigating the Rise in Terrorism Threats

Terrorism is a multifaceted issue that requires comprehensive strategies to address effectively. 

American Flag on 9/11 Memorial

The events of Sept. 11, 2001, shattered our sense of security and left an indelible mark on our history. Even now, 23 years later, many of us can vividly recall where we were and what we were doing when we heard the devastating news.

Today, the threat of terrorism on U.S. soil remains a stark reality. FBI Director Christopher Wray has expressed growing concerns about the potential for a coordinated terror attack, particularly as conflicts like the Israel-Hamas dispute continue to escalate. 

The safety and well-being of our loved ones and fellow citizens are paramount. However, for businesses—whether large corporations or small enterprises—the impact of a terrorist attack can also be devastating, both directly and indirectly. Employees depend on these businesses for their livelihoods, making preparedness essential for maintaining stability and resilience.

In this article, we will delve into the prominent threat posed by terrorism, explore its ripple effects on the economy and various aspects of business operations and finances and provide insights for risk managers to bolster their protection strategies.

See also: Super Election Year Boosts Risks of Political Violence

The U.S. is facing an increasing threat from terrorism, and it's crucial that we understand the severity of this issue. Recent reports, such as the 2024 National Terrorism Financing Risk Assessment (NTFRA), highlight the growing risks. It concludes that the international security landscape has become more complex, with countries such as Russia and China seeking to challenge the U.S.-led global order. 

The increased numbers of "gotaways" at the border could potentially pose a security threat. In December, the chairman of the House Committee on Homeland Security, Republican Mark Green, said the number of individuals apprehended illegally crossing the Southwest border and found to be on the terrorist watch list has increased 2,500% from fiscal years 2017-2020 to fiscal year 2023. The Democrats for Border Security task force was developed earlier this year to emphasize enforcement. 

Global challenges, such as humanitarian crises and health concerns, further complicate the terrorism landscape, which is why 2024 Homeland Threat Assessment deemed them “a top threat to the homeland.” Terrorism is a multifaceted issue that requires comprehensive strategies to address effectively. 

Terrorism’s Impact on the U.S. Economy and Businesses

Let’s go back to the topic of 9/11. The attacks were a human tragedy, but they also had economic implications that reverberated throughout the U.S. business landscape. The immediate aftermath saw stock markets plunge and economic sectors strained. Insurance companies initially hesitated to cover damages from terrorist acts, introducing uncertainty and escalating financial risks for businesses.

Small businesses, particularly those near the World Trade Center, suffered major losses, with nearly 18,000 shut down or destroyed, according to Investopedia’s The Impact of 9/11 on Businesses. The devastation caused the Consumer Confidence Index to plummet. 

See also: CBRN Terrorism Insurance: A Risk Too Far?

Specific Ways Terrorism Affects Businesses

  • Economic Disruption: Terrorist attacks can disrupt the normal functioning of businesses by damaging infrastructure, disrupting supply chains and causing closures. This disruption can lead to financial losses due to reduced productivity and increased costs for security and recovery.
  • Investment Climate: Terrorism creates an unstable investment climate, making businesses less willing to invest in new projects or expand operations. Foreign investors may also be hesitant to invest in countries perceived as high-risk due to terrorism.
  • Increased Security Costs: In response to the threat of terrorism, businesses may need to increase spending on security measures, such as surveillance systems, security personnel and cybersecurity. These additional costs can strain a company's finances.
  • Insurance Costs: Following terrorist attacks, insurance premiums for businesses may rise, reflecting the increased risk associated with operating in areas prone to terrorism.
  • Reputation and Brand Image: Businesses located in areas affected by terrorism may suffer damage to their reputation and brand image, which can affect consumer perception and loyalty. This can have long-term consequences for a company's profitability and market share.
  • Regulatory Changes: Governments may introduce regulations and compliance requirements in response to terrorist threats, increasing operational costs and administrative burdens for businesses.
  • Supply Chain Vulnerability: Terrorism can disrupt global supply chains, particularly for businesses that rely on international suppliers or operate in regions prone to terrorist activity. This can lead to delays, increased costs and supply shortages.

Measures to Safeguard Business Operations Amid Terrorism Threats

In response to the persistent challenges posed by terrorism, risk managers must advise their clients on fortifying operations and mitigating potential risks through robust strategies and contingency plans. Other tactics worth considering include:

Terrorism Insurance

Investing in terrorism insurance is a prudent move for businesses seeking to shield themselves from the financial fallout of terrorist attacks. This specialized insurance covers losses from property damage, business interruption and liability claims, providing a crucial safety net against both direct and indirect costs.

Consider Terrorism During Risk Assessments

Incorporating terrorism into your risk assessments enables businesses to identify and evaluate potential vulnerabilities. Risk managers can then develop targeted strategies to bolster security measures, enhance preparedness and reduce exposure.

Security Measures

Investing in robust security measures, such as physical security enhancements, surveillance systems, access controls and cybersecurity protocols, can deter terrorist attacks and minimize the impact of security breaches. Collaboration with law enforcement agencies and security experts can provide valuable insights and support in implementing effective security measures tailored to specific business needs.

Supply Chain Diversification

Diversifying supply chains by sourcing from multiple suppliers and geographic locations can help businesses reduce dependence on vulnerable regions and minimize the impact of supply chain disruptions caused by terrorism. This strategic approach ensures continuity of operations.

Legal and Regulatory Compliance

Staying informed about relevant laws, regulations and compliance requirements can help businesses ensure adherence to legal obligations and mitigate potential legal risks. Consulting with legal experts and compliance professionals can provide guidance on navigating regulatory complexities.

Captive Insurance

Captive insurance offers an alternative risk management strategy. By establishing an insurance subsidiary to underwrite the risks of the parent company and its affiliates, businesses can tailor insurance policies to meet their specific needs and risk profiles, including coverage for terrorism-related risks. Careful planning, regulatory compliance and continuing management are, however, essential.

By embracing these strategies and collaborating closely with insurance providers, security experts and other relevant stakeholders, risk managers can enhance their clients’ or business’s resilience to terrorism-related risks and safeguard their operations, assets and reputation. Managing terrorism-related risks is crucial for navigating the complex and evolving landscape, ensuring business continuity and safeguarding long-term success.


Randy Sadler

Profile picture for user RandySadler

Randy Sadler

Randy Sadler is a  principal with CIC Services, which manages more than 100 captives.

He started his career in risk management as an officer in the U.S. Army, where he was responsible for the training and safety of hundreds of soldiers and over 150 wheeled and tracked vehicles. He graduated from the U.S. Military Academy at West Point with a B.S. degree in international and strategic history, with a focus on U.S.–China relations in the 20th century. 

How Insurance Brokers Can Stay Competitive

Here are five strategies for insurance brokers aiming to thrive in the age of AI and digital transformation.

A 3D Abstract Art

In the rapidly evolving insurance industry, brokers are finding themselves at the crossroads of tradition and innovation. As digital transformation reshapes the landscape, insurance companies and brokers alike must adapt to stay competitive and meet the changing needs of both clients and employees. Here are five strategies for insurance brokers aiming to thrive in the age of AI and digital transformation.

  1. Adapt to Changing Demographics and Client Expectations

The insurance industry is witnessing a significant shift in its client base, with Millennials and Gen Z becoming predominant forces. These younger generations demand real-time data, digital platforms and sustainable business practices. For example, insurance brokers specializing in commercial insurance must now offer digital-first experiences and 24/7 support to cater to the expectations of these tech-savvy entrepreneurs.

On the employee side, attracting and retaining talent from these younger generations requires aligning with their values. Insurance brokers can implement programs such as reverse mentorship, where younger employees share insights on technology and trends, while experienced mentors guide them in developing business acumen.

  1. Leverage AI and Digital Tools

AI adoption is no longer optional but a necessity for insurance brokers. Like many other industries, insurance is trying to integrate AI into the way it does business. That can involve using AI to process claims, identify risk, set prices and enhance operational efficiency, among other tasks. AI is adept at quickly processing a lot of disparate information to produce results almost instantaneously. For an industry that sits on top of mounds of data that it needs to analyze, insurance is well positioned to take advantage of AI.

Clients expect seamless digital experiences, from automated claims processing to personalized policy recommendations. Digital transformation enables brokers to provide mobile-optimized websites and apps for customers to access insurance information. 

However, the human aspect of empathy, experience and authenticity remains crucial. Brokers must find the right balance between leveraging AI for efficiency and maintaining the personal touch that builds trust and loyalty. 

In addition to becoming a part of the daily operations of an insurance business, AI could become a line of insurance itself. For instance, AI could be used to exploit vulnerabilities in security systems and, through a deep fake, execute a funds-transfer fraud. Companies will have to protect themselves against that risk.

See also: 'Digital Twins': The Race Is On

  1. Navigate the Era of Dark Social

The landscape of social media and customer engagement has evolved, with a significant portion of interactions now happening in private, also known as dark social. For insurance brokers, this means traditional metrics like likes and shares are no longer reliable indicators of engagement. Instead, focusing on content consumption as a form of engagement can help brokers understand what resonates with their audience. 

By targeting the 95% of the audience that isn't ready to buy, brokers can position themselves on the "day-zero list," capturing attention before prospects start looking for insurance solutions.

See also: The Need for 'Digital Fluency' in Insurance

  1. Use Earned Media to Build Authority

Earned media, such as mentions in reputable publications, plays a critical role in establishing an insurance broker's expertise, authority and trustworthiness. High-quality content that scores well on Google's E-E-A-T criteria can significantly enhance visibility and credibility. For insurance brokers, being featured in industry-specific publications or mainstream media can help move buyers down the funnel by increasing the firm's authority in the field.

  1. Cultivate a Culture of Urgency

In the fast-paced world of insurance, speed is often mistaken for urgency. However, a culture of urgency—prioritizing important tasks and acting—is more beneficial. This approach enables insurance brokers to be agile, innovative and highly engaged. For example, embracing digital transformation with urgency allows brokers to quickly adapt to new technologies and market trends, ensuring they remain competitive and responsive to client needs.

Insurance brokers must navigate the challenges and opportunities presented by digital transformation and changing demographics. By adapting to client expectations, leveraging AI and digital tools, navigating dark social, using earned media and cultivating a culture of urgency, insurance brokers can future-proof their businesses and continue to thrive in an increasingly digital world. 

While AI will play a significant role in the industry, it will augment rather than replace brokers, enabling them to provide better service to their clients.


Shama Hyder

Profile picture for user ShamaHyder

Shama Hyder

Shama Hyder is the founder and CEO of Zen Media, an international keynote speaker and a bestselling author. 

Fast Company calls her a "millennial master of the universe" and a "Zen Master of Marketing.” She is a Forbes and Inc. 30 under 30 alum, and LinkedIn has named her a Top Voice in Marketing four years in a row. 

How and Why to Tap Into Global Talent

Here are four key strategies insurance companies should consider when expanding into international markets.

Laughing businesswoman working in office with laptop

While insurance companies react to evolving consumer expectations and emerging technologies like AI, they are also facing major workforce issues. 

During the pandemic, it wasn’t uncommon for many senior executives to leave the job market entirely, and, according to Workday, 50% of the current insurance workforce is expected to retire by 2036. This leaves insurance companies with a major talent gap, but, also, an opportunity to diversify the workforce to meet the needs of the evolving industry.

Access to diverse global talent can significantly enhance their business operations, while creating opportunities to expand into new markets. Forward-thinking insurance companies recognize these dual benefits. 

Here are four key strategies insurance companies should consider when expanding into international markets:  

Collaborate with local agencies 

The insurance industry is complex, so collaborating with local agencies is a crucial step in selecting a new location. Many countries have incentives for companies that are looking to grow and develop their workforce. Partnering with a foreign direct investment agency can provide access to talent development programs that foster skills critical to new technology objectives. 

For example, Ireland’s foreign direct investment agency has partnered with Skillnet, Ireland’s national talent development agency, to develop a strategic talent development program, accredited by the Graduate Business School at Technological University Dublin, that companies can leverage when establishing local operations. Many countries also provide significant funding to local universities and research centers to provide new businesses with access to research and development capabilities. 

Partnership opportunities are critical to successful foreign direct investment. These agencies are experts in industry, local government and business. Working with them will help insurance companies understand how pre-existing programs can support their businesses’ long-term goals. 

See also: The Next Generation of Talent

Evaluate the local technology community

Insurance companies ready to seize the opportunities that digitalization presents need access to two types of talent: one group with traditional industry experience and, a second with advanced technology expertise. Together, they can develop the insurance products and processes that consumers are looking for. 

Companies looking to grow their technology expertise should look for locations with a heavy technology presence. Ireland, for example, is home to 16 of the top global tech companies and the top three enterprise software providers. In collaboration with local universities, these companies have created one of the strongest talent pipelines for software development, AI, engineering and cloud computing in Europe. 

Tapping into this pool of talent can look different for every company. For example, Marsh McLennan, one of whose businesses is Marsh, a leading global insurance broker, created an innovation center in Dublin in 2015 to leverage the Irish tech talent ecosystem. Now, the center is conducting large-scale generative AI research to inform new products and solutions.

It may seem unconventional to invest in new locations that are heavily occupied by technology enterprises, but those companies create unparalleled access to talent.  Every industry is looking to grow their technology expertise, so to compete, insurance companies and brokers need to have a presence in the community. 

Consider national business objectives

Geopolitical conflict, disruptions to trade and the evolving regulatory environment have made the global business landscape more complex. When evaluating locations for investment, insurance companies should prioritize opportunities that support both talent and business needs. Many cities around the world have large talent pools ripe for the insurance industry, but only some provide the financial benefits that will be significant once operations are established. 

Tax agreements, regulatory commitments and investment opportunities are just a few examples of how countries are providing incentives to new business. Understanding which incentives align with business objectives will be key for insurance companies to find the right fit. 

For insurance companies prioritizing R&D, look for locations that are investing in education programs and research facilities. For those interested in access to new markets, consider locations that have strong business relationships with other neighboring countries. The EU, for example, requires companies to have physical operations within one of their member countries to gain access to the market. Understanding these market complexities will help insurance companies make the right choice, not only for their talent objectives but also for their bottom line. 

See also: How to Captivate the Next Wave of Underwriters

Think holistically

The insurance industry is at a turning point, and accessing diverse, skilled technological expertise will be key to staying ahead of the competition. Investing in new markets can be risky, especially for historically conservative insurance companies, but by partnering with local agencies to strategically evaluate local talent, partnership and financial opportunities, they can make a confident, data-driven decision.

Realistically, talent alone may never be enough to sell many companies on foreign investment. But those that forgo the talent and financial incentives that new markets provide will fall behind as their competitors modernize. 

Why A New Market for Small Businesses Is Needed

Current insurance types don't protect small businesses from trolls abusing the Americans with Disabilities Act. A new endorsement could address the problem. 

An International Access Symbol on Asphalt Road

The Americans with Disabilities Act (ADA) was signed into law by President George H. W. Bush on July 26, 1990 with the good intentions of helping people with disabilities. It is a federal civil rights law that prohibits discrimination against people with disabilities in everyday activities. The ADA guarantees that people with disabilities have the same opportunities as everyone else to enjoy employment opportunities, purchase goods and services, and participate in state and local government programs. 

The stated goal of the ADA was to eliminate discrimination against individuals with disabilities. A major source of discrimination suffered by disabled individuals is the inability to gain access to public accommodations such as restaurants, hotels, movie theaters, gas stations, and the facilities of other small businesses. 

The intent of the statute was to ascertain that businesses that want to comply with the law should be able to do so without undue cost, delay, or uncertainty. But the law of unintended consequences took hold, and those good intentions were taken advantage of by unscrupulous people and their lawyers. Lawsuits proliferated by persons who claimed to be disabled or simply took the position that they were advocates for the disabled. 

In truth, the ADA advocates and their lawyers litigated under the ADA with the sole purpose of making money. Most had no intention or concern about the needs of those with disabilities. They took advantage of the provisions of the statute that allow individuals to enforce the accessibility requirements to bring a private right of action against individual businesses and property owners. 

This important reform in advancing equal access for the disabled has been used by some bad actors for monetary gain more than disability advocacy and threatens the small business economy in some states. The people abused by these bad actors are the owners of small businesses and owners and tenants of small retail establishments like the owners of bodegas, liquor stores, chiropractors, health care providers, and lessors. 

Under the private right of action allowed by the ADA, an aggrieved party can seek injunctive relief remedying the violation and attorney’s fees and costs. Monetary damages are not available to private parties seeking to enforce the requirements of the ADA. 

Providing differing remedies for private and public enforcement revealed to abusers a method to profit from the underlying intent of Congress to prevent private plaintiffs from recovering monetary relief under the ADA. Although the ADA sets its intent clearly, small business owners have found they are added to the growing evidence of abuse of the private remedies provided by the ADA where, as a small business and small property owner, he or she either must litigate with the ADA advocates or succumb to the abusive lawsuit with a settlement. If they contact a lawyer, they will be advised that they will lose the litigation if there are even small technical errors of compliance and be required to pay fines and attorney’s fees to the advocates and their lawyers. The litigants and their lawyers know this and will offer to settle for a sum close to reasonable so that they can negotiate down to a reasonable amount. 

The complaints and discovery are all computer-generated by the advocate’s lawyers, with only the names of the plaintiff, defendants, and non-compliant part of the property changed. The litigation expense for the plaintiff and counsel is minimal, and for the defendant it is excessive. Small business people don’t have the funds necessary to protect themselves from an action legally filed under the ADA and concurrently pay to bring the property into compliance. Agreeing to an offer of settlement is the only choice available to a small business owner because no liability policy provides coverage for the defense or indemnity of the suit brought under the ADA. 

In a case with which I am familiar, a law firm specializing in filing ADA lawsuits, and nothing else, sued a small business owner allegedly on behalf of a person claiming disabilities who met with the receptionist and made an appointment to which she never appeared. Shortly after her scheduled appointment, the plaintiff filed and served an ADA lawsuit claiming that the doorbell to the business was mounted about 60 inches above the ground rather than the 40 inches required for the use of a person in a wheelchair, a technical violation of the ADA. 

In the 30 years since the building was acquired by its owner and leased by its tenant, there were no complaints about an inability to use the doorbell. Regardless, the suit was filed and served, and defense counsel was required to be retained to avoid default at the expense of the owner and the tenant from their limited private funds. 

The abuse of the ADA is well known to federal district court and state judges, who see the same plaintiffs over and over again. There is nothing the judges can do, because of the clear language of the ADA statutes. 

See also: Is 2024 the Year of Digital Health?

Attempts have been made to curb the abuse. For example, in 2006, the Hastings Women's Law Journal, 17 Hastings Women’s L.J. 93 2006 published an article titled "Private Enforcement of the Americans with Disabilities Act via Serial Litigation: Abusive or Commendable?" by Carri Becker, then a JD candidate. The cases Becker described were identical to the suit I became aware of and whose defendant found itself to be one of a multitude of ADA lawsuits filed across the country and that the minor abuses claimed would cost thousands of dollars to cure plus the fees of the lawyers who brought the suit and the fees of counsel retained to defend the small business owner. 

Since 2006, ADA lawsuit abuse continued to be prolific. Profitability of ADA litigation has given rise to what courts have described as “a cottage industry” that has little or nothing to do with assisting people with disabilities. Becker noted that, for example, “a single law firm in Philadelphia has filed hundreds of lawsuits on behalf of two disabled men, reaping thousands in attorney’s fees.” 

Adding to the burden, small businesses are forced to comply not only with the federal standards outlined in the ADA, but also with any state, county, or city-specific regulations. With so many different regulations to follow, it is not surprising that many, if not most, buildings constructed before 1990 are out of compliance. 

Compounding the problem is the fact that the regulations differ substantially. For example, California’s Title 24 regulations require that curb ramps have a one-half-inch lip at the bottom, beveled at a 45-degree angle, whereas the ADA requires a flush transition at the bottom of the ramp. Total compliance with both state and federal regulations becomes impossible. It becomes obvious that the intent of almost all the parties filing suits on behalf of people with disabilities is to bring about a cash settlement. For example, although the property owner cured the deficiency with the placement of a new $5 doorbell, the demand to settle the lawsuit before discovery and adding lawyers fees was $15,000. In addition, a check of court records indicated that the plaintiff who sued the small business had filed multiple ADA lawsuits. 

One explanation for many people’s distaste for the enforcement of the ADA via serial litigation is that the plaintiffs and their attorneys stand to financially gain from each of the suits they file and often fail to make the property ADA-compliant. 

EXAMPLES OF ADA LAWSUITS 

Common examples of ADA lawsuits may include when individuals visit several business establishments with the intent to identify ADA violations, which may include the lack of handicapped parking spaces or the lack of wheelchair ramps, and then sue that business for the violation although the plaintiff was not injured. In certain instances, the individual may drive by the establishment and search for violations in the parking lot or outside of the business and never actually enter the establishment or attempt to conduct any business there. These individuals can target several businesses at once.

As the Los Angeles Times reported in November 2018, about 10,000 ADA lawsuits were filed in the first six months of that year. According to the Orange County Register, one Orange County firm filed 335 ADA cases in the past year, including three dozen for a visually impaired Montana woman. The Register concluded that: “This isn’t about access — it’s simple extortion.” And the “extortion” is perfectly legal. 

In some cases, the lawsuits are collected from the comfort of the attorney’s car or even couch, driving by handicapped parking spots to assess violations or using Google Earth to find motels without accessible pool lifts for the disabled. 

Lawsuits aiming to bring about compliance with an important equal rights law like the ADA are important in advancing the cause. Some of the serial litigators are doing more to rake in damages than increase accessibility. As many states have statutes that go beyond the federal bill and offer individual lawsuit filers cash payments as well as attorney expenses, the incentives to file a lawsuit shift from accessibility to cash recovery. 

See also: Best Antidote to Medical Overbilling

THE COSTS IMPOSED 

In California, in addition to having both sides’ legal fees covered by the defendant, a plaintiff may recover a fine of a minimum of $4,000 per ADA violation, and the plaintiff is not required to offer a grace period for the violation to be rectified. 

ADA regulations are poorly dealt with by the nearly 30 million small businesses in the U.S. Small businesses often lack the expertise, capital, and legal support to understand and adhere to the regulations. If a business owner’s first notice of non-compliance with the law is a lawsuit, the system is askew, and the small businessperson is not equipped nor able to fund defense of the suit. 

Sadly, a few attorneys – the ADA “trolls” — realized that ADA can be a profit center by simply filing cases that, on the surface, have merit. But instead of pursuing those cases to a conclusion, the “trolls” offer to go away in exchange for a financial payoff. The “trolls” are especially active in California and New York, where state laws permit private individuals to recover money damages. For years, most of the ADA “troll” cases involved people in wheelchairs suing over physical or architectural accessibility. Suits would be filed, and the attorneys would then demand a certain amount of money to simply go away. These are not “frivolous” suits in the sense that they have no merit. What sets these lawsuits apart is that they are filed with such enormous volume that the attorneys involved could not possibly represent the plaintiffs properly in any one of them. 

The critical element of the “troll” lawyers’ business plan is volume. The attorneys have to file a lot of cases. And they do. One “pioneer” in this area was a wheelchair-bound California plaintiff whose attorney filed some 400 lawsuits claiming that he confronted virtually identical barriers to access at different businesses, mostly restaurants. These became referred to as “drive-by” cases because there was little or no proof that the named plaintiff had ever actually visited the businesses in question. Although only one of those cases ever actually went to trial, his attorney made an estimated $10 million, and it was not clear how many of the businesses actually fixed the supposed problem. 

A website, adaabuse.com, reports mega-ADA-suit-filers, one of whom was so egregious he was disbarred. Although there have been attempts to modify the ADA to avoid these abuses, the statute remains unchanged. 

LIABILITY INSURANCE UNAVAILABLE 

No insurance policy provides coverage for an ADA suit, because there is no claim of bodily injury, property damage, or personal injury. Liability insurance, like that provided by a commercial general liability (CGL) policy or a business owners policy (BOP) will never provide a defense or indemnity to an insured for lack of covered claimed injuries. 

A PROPOSAL FOR THE INSURANCE INDUSTRY

It seems to me that ADA will not be changed to protect against abuse. Every small business in a facility built before 1990 or without concern for ADA requirements, like most, is a potential defendant in an ADA suit and can be held to uninsured ransom. 

No current liability insurance policy, CGL, BOP, or common liability insurance policy provides coverage for the ADA suit. As a result, a small business owner, lessor, or lessee that protects with insurance will find their assets naked to the ADA trolls. The small business owner will need to retain counsel, defend the suit, pay the legal extortion, or face a major judgment. 

The ADA has created a large market for the liability insurance industry that, by use of a simple endorsement to a CGL or BOP, can create coverage to protect the small business owner and work to defeat the ADA trolls' ability to profit from the scheme. 

PROPOSED ENDORSEMENT 

The endorsement wording I propose follows: 

THIS ENDORSEMENT CHANGES THE POLICY. PLEASE READ IT CAREFULLY. 

It is hereby understood and agreed that the policy is revised to read as follows from the date of inception to the date of expiration stated in the Declarations: 

Americans With Disabilities Act Endorsement 

Special Limits of Liability Applying to this endorsement: 

$25,000 for the cost to make your property comply with the requirements of the ADA to conform to the accessibility required by the ADA and alleged to be in violation of the ADA by a civil suit naming you as a defendant. 

Insuring Agreement: 

We agree to pay whatever is required by counsel of our choice to defend and indemnify you if you are sued for violation of the Americans With Disabilities Act (ADA) that are claimed to have prevented a person with a disability or disabilities that the plaintiff or plaintiffs claim prevented the plaintiff(s), and/or others similarly situated, to access and use your premises because they were not in compliance with ADA standards as it relates to users with disabilities like the person suing as plaintiff. 

We also agree to indemnify you of the cost to bring your property in compliance with the ADA and correct the errors or deficiencies alleged in the suit brought against you, up to the limits of liability. 

All other terms and conditions remain the same. 

Every owner of a small commercial building, apartment house, rental property, or operating a small business that invites the public should or will rush to buy insurance to protect against the risk. The prudent insurer, with a staff of lawyers, adjusters, and contractors will rush to issue an endorsement that, for a reasonable additional premium, will find thousands of small business, small property owners, and everyone who is open to the public, eager to pay extra to add the coverage to their liability insurance policies. 


Barry Zalma

Profile picture for user BarryZalma

Barry Zalma

Barry Zalma has dedicated his life to insurance, insurance claims and the need to defeat insurance fraud over the last 55 years. 

The Need for Excellence in Claims Handling

Insurers that decide they can handle claims with young, inexpensive, inexperienced and untrained claims handlers should be accosted by angry stockholders.

People having a Meeting

In search of profit, insurers have decimated their professional claims staff. They laid off experienced personnel and replaced them with young, untrained, unprepared people. A virtual clerk replaced the old professional claims handler. Process and computers replaced hands-on human skill, empathy and judgment. Money was saved by paying lower salaries. Within three months of firing the experienced claims people, gross profit increased. 

Insurance is a business. Corporate insurers must show their shareholders a profit that pays dividends and increases the share price of the insurer. For centuries insurers understood that catastrophes, firestorms, windstorms, hurricanes and tornados could not be predicted. Some years, the insurer will make profits, and some years it will incur a loss. The prudent insurer recognizes, because of the impossibility of predicting all possible losses, that they should measure profitability over a decade or several decades. No insurer can measure its profitability for periods of a quarter of a year. 

Insurance is a service business. The insurance contract is a collection of promises made by the insurer to those persons or entities that face risks of loss pay for an insurance contract that promises to protect the insured against the risks of loss the insured faces. The person or entity insured relies on the professionalism of the employees of the insurer who are called on to resolve the claims of the insured and provide the protection promised by the policy. 

The Development of the Insurance Claims Professional 

Insurers have created over the last few centuries professional claims personnel whom they trained to interpret the terms and conditions of the policy of insurance, how to thoroughly investigate every claim, how to assist the insured in the presentation and how to resolve claims made by or against the insured. The promises made by the policy to defend or indemnify the insured are kept by the professional claims person: the adjuster or claims representative. 

The prudent insurer understands that keeping a professional staff dedicated to excellence in claims handling is cost-effective over long periods. A professional and experienced adjuster will save the insurer millions by resolving disputes, paying claims owed promptly and fairly, and, by so doing, avoiding litigation. 

The professional claims person exists to resolve claims to the satisfaction of the insured and the insurer. When the claims person does so promptly, effectively and in good faith, the person insured will be satisfied that the promises made by the insurance policy were kept. When the insured and insurer are satisfied by the claims process, the insured will continue to renew his or her or its policy with the insurer and will tell friends and colleagues about how professional the insurer’s staff is. Those friends and colleagues will move their insurance to the insurer with the professional claims staff. The insurer’s business will grow, it will profit from the business of insurance and its shareholders will enjoy the fruits of their investments. 

Satisfying an insured that the promises made by the policy were fairly and completely kept is the key to the insurer’s desire to provide the services promised by the policy and avoid the expense and bad publicity of litigation. The satisfied insured will never decide to sue the insurer for breach of contract or the tort of bad faith. Neither party will need to involve counsel. A happy insured or claimant, satisfied with the results of his or her claim, will never find a need to sue the insurer. 

On the other hand, barely competent, incompetent or inadequate claims personnel will seldom resolve claims fairly and to the satisfaction of the insured or claimant. Inadequate claims personnel will often force insureds and claimants to public insurance adjusters and lawyers. 

It is axiomatic that every study performed on the cost of resolving claims establishes that claims with an insured or claimant represented by counsel or a public insurance adjuster cost more to resolve than those where counsel or a public adjuster is not involved. Prompt, effective, professional claims handling is cost-effective for the insured, the claimant and the insurer. Professional claims handling saves money because there is no need to pay the fees of a lawyer or public adjuster. When the insurer fulfills the promises made by the policy to the satisfaction of the insured when the insured acquired the policy the claim is resolved by the insured and the adjuster. 

Insurers that decide they can handle first- or third-party claims with young, inexpensive, inexperienced and untrained claims handlers should be accosted by angry stockholders whose dividends have plummeted or will plummet as a result. When an insurer compromises on staff, profits, thin as they may have been previously, will move rapidly into negative territory. Breach of contract suits and claims of violation of the tort of bad faith seeking tort and punitive damages will deplete the capital reserves of the insurer. Insurers will quickly question why they are writing insurance. Those that stay in the business of insurance will either adopt a program requiring excellence in claims handling from every member of their claims staff or they will fail. 

The Need for Change 

The insurance business must change — this time for the better — if it is to survive. Insurers must rethink the firing of experienced claims staff and reduction in training to save “expenses.” Insurers must recognize that the expense to train, educate and maintain a staff of professional claims handlers is a small part of the money that flows out of an insurer’s coffers. The major dollar expenditure is the money paid to insureds or claimants to pay claims. When inadequate or inexperienced adjusters pay claims the insurer did not owe, refuse to pay claims it did owe, or pay more than is appropriate, the potential for an insurer to make a profit is reduced much more than is saved by reducing the expense incurred paying a professional claims staff. 

Insurers should, if they wish to succeed, adopt a program to promote excellence in claims handling. Only with a staff of claims handlers dedicated to excellence in claims handling can insurers promptly, fairly and in good faith keep the promises made by the insurance policy and avoid charges of breach of contract and the tort of bad faith in both first and third party claims. 

Insurers must understand that they cannot adequately fulfill the promises they make to their insureds and their obligations under fair claims practices acts without a professional, well trained and experienced claims staff. An insurer must work vigorously and intelligently to create a professional claims department or recognize it will lose its market and any hope of profit. 

The Insurance claims professional is a person who: 

  • can read and understand the insurance policies issued by the insurer. 

  • understands the promises made by the policy and their obligation, as an insurer’s claims staff, to fulfill the promises made. 

  • are competent investigators. 

  • have empathy and recognize the difference between empathy and sympathy. 

  • understand medicine relating to traumatic injuries and are sufficiently versed in tort law to deal with lawyers as equals. 

  • understand how to repair damage to real and personal property and the value of the repairs or the property. 

See also: 5 Ways Generative AI Will Transform Claims

A Proposal to Create Claims Professionals 

To avoid claims of breach of contract, bad faith, punitive damages, unresolved losses, and to make a profit, insurers must, in my opinion, maintain a claims staff dedicated to excellence in claims handling. They must recognize that they, as representatives of the insurer, are obligated to assist the policyholder and the insurer to fulfill all the promises made by the insurer in the wording of the policy. An insurer can create a claims staff dedicated to excellence in claims handling by, at least: 

  • Hiring well trained, educated and empathetic insurance claims professionals. 

  • If professionals are not available, train all members of the existing claims staff to be insurance claims professionals. 

  • Train each member of the claims staff annually on the local fair claims settlement practices regulations.

  • Supervise each claims handler closely to confirm all claims are handled professionally and in good faith.

  • Explain to each member of the claims staff the meaning of the covenant of good faith and fair dealing from its inception in the 18th Century to the present. 

  • Require that staff treat every insured with good faith and fair dealing. 

  • Demand excellence in claims handling from the claims staff on every claim whether small or major, whether an individual or a corporate insured. 

  • Explain to the claims staff that the insurer is ready to immediately dismiss any claims handler who fails to treat every insured with good faith and fair dealing. 

  • If any experienced claims professionals exist on the insurer’s staff, the insurer must cherish and nurture them and use their experience and professionalism to train new claims people. 

  • If none are available, the insurer has no option but to train its people from scratch using available materials produced by the National Association of Insurance Commissioners, the state’s Department of Insurance, insurance associations and professionals who have – for a reasonable fee – the ability to train claims personnel properly and effectively. 

When the claims staff is made up of claims people who treat all insureds and claimants with good faith and fair dealing and who provide excellence in claims handling, litigation between the insurer and its insureds will be reduced exponentially. 

To keep the professional claims staff operating efficiently and in good faith they must be honored with increases in earnings and perquisites. 

Conversely, those who do not treat all insureds and claimants with good faith and fair dealing should be counseled and given detailed training if they are willing to learn. If they are not willing or able to learn they must be dismissed and sent off to a different career. 

If a claims person provides less than professional claims services and excellence in claims handling, they must be fired. 

Claims management must insist on excellence. There is no reason to accept less than excellence in claims handling. The insurer must make clear to all employees that it is committed to immediately eliminating staff members who do not provide excellence in claims handling and are ready to fire publicly and quickly those who cannot or do not provide excellence in claims handling. 

HOW TO CREATE AN EXCELLENCE IN CLAIMS HANDLING PROGRAM 

An excellence in claims handling program begins with a statement in the insurer’s claims manual or statement of professionalism, that it is dedicated to provide excellence in claims handling to every insured who presents a claim. To create an excellence in claims handling program should include, at a minimum: 

  1. A series of lectures supported by text materials explaining: 
    1. A definition of insurance. 
    2.  How to read and understand an insurance policy. 
    3.  How to interview an insured, witness, or claimant. 
    4.  How to assist an insured in the insured’s obligation to prove a claim. 
    5.  How to repair or replace damaged real or personal property. 
    6.  How to repair or replace damaged vehicles. 
    7.  How to identify causes of loss. 
    8.  How to recognize the red flags of fraud. 
    9.  The duty of the claims person who suspects attempted fraud. 
    10.  How to negotiate with an insured, claimant, public adjuster or lawyer to resolve a claim. k. How to recognize when retaining counsel to represent the insurer is necessary. 
    11.  How to retain counsel to represent the insured. 
      1.  How to read and understand the contract that is the basis of every adjustment, including but not limited to: 
      2.  The formation of the insurance policy. 
    12.  The rules of contract interpretation. 
    13.  Tort law: including negligence, strict liability in tort, and intentional torts. 
    14.  Contract law including: 
      1.  the insurance contract, 
      2.  the commercial or residential lease agreement, 
      3.  the bill of lading, nonwaiver agreements, 
      4.  proofs of loss, 
      5.  releases of claims, 
      6.  non-waiver agreements, and 
      7.  other claims related contracts or documents. 
    15.  The duties and obligations of the insured in a personal injury claim. 
    16.  The duties and obligations of the insurer in a personal injury claim. 
    17.  The duties and obligations of the insured in a first party property claim. 
    18.  The duties and obligations of the insurer in a first party property claim. 
    19.  The Fair Claims Practices Act and the regulations that enforce it. 
    20.  The thorough investigation, including: 
      1.  Basic investigation of an auto accident claim. 
      2.  Investigation of a construction defect claim. 
    21.  Investigation of a nonauto negligence claim. 
    22.  Investigation of a strict liability claim. 
      1.  Investigation of the first party property claim. 
    23.  The recorded statement of the first party property claimant. 
    24.  The recorded statement or interview of a third party claimant. 
    25.  The recorded statement of the insured. 
    26.  The red flags of fraud. 
      1. The SIU and the obligation of the claims representative when fraud is suspected. v. Claims report writing. 
    27.  The evaluation and settlement of the personal injury claim. 
    28.  How to retain coverage counsel to aid when a coverage issue is detected. 
    29.  How to control coverage counsel. 
    30.  How to instruct coverage counsel on the issue to be resolved. 
  2.  Instruction, by lecture, documents, webinars on: 
    1.  Dealing with a plaintiff’s lawyer. 
    2.  Dealing with personal injury defense counsel. 
    3.  The evaluation and settlement of the property damage claim. 
    4.  The appraisal process. 
    5.  Arbitration and mediation and the claims representative. 

See also: How to Optimize Insurance Claims Management

Claims handling without excellence is both dangerous and expensive. Insurers must develop a professional claims staff and provide excellence in claims handling because by so doing they will profit more than if they keep an inadequate and unprofessional claims staff. 

The training lectures must be supplemented by meetings between knowledgeable and experienced supervisors and claims staff on a regular basis to reinforce the information learned in the lectures. 

To guarantee that the training and requirement for excellence in claims handling is effective, the insurer must also institute a regular program of auditing claims files to establish compliance with the requirement to deal fairly and in good faith to the insured. 

The insurer’s management must support the training and repeat it regularly because people have short-term memory loss and need to reinforce what they have learned and what is required of them when dealing with an insurance claim. The professional claims handler never sees the identical claim every time. Claims, factual background and the people involved are invariably different, and the professional claims handler must be capable of adapting to the people and facts involved. 

The insurer’s management must, therefore, audit claims files to determine whether the training has taken and is being applied to each claim and whether there is a need to refresh the memory of the claims personnel and add new information and claims processes. 

There is no quick and easy solution. Training takes time; learning takes longer and must be repeated and modified to changed situations and new and modified appellate decisions changing the interpretation of a policy wording. If the insurer does not have personnel with the ability to train its staff, it should use outside vendors who can do so effectively. Many such sources are available from professional associations, independent claims adjuster firms, independent counsel, insurance related publications, insurance related podcasts and continuing education providers. 

I have created, to assist those who wish to create a professional claims staff dedicated to provide excellence in claims handling, a series of publications at my Locals community and at Substack.com. In addition, at Illumeo.com, I produced a short Excellence in Claims Handling program available at 

https://www.illumeo.com/courses/introduction-excellence-claims-handling and multiple insurance claims related programs. 

I also published at Rumble.com more than 660 videos dealing with insurance, insurance coverage, insurance claims handling, insurance law and investigation of claims with similar videos at YouTube.com. I have also published more than 4,450 blog posts digesting appellate decisions modified from the actual language of the court decisions, condensed for ease of reading, and convey the opinions of the author regarding each case on insurance, insurance coverage, insurance claims handling, insurance law, and investigation of claims available for no cost to anyone who watches. At the Insurance Claims Library, I have published more than 30 books on insurance law, insurance claims and insurance claims handling, available at low cost from Amazon.com. 


Barry Zalma

Profile picture for user BarryZalma

Barry Zalma

Barry Zalma has dedicated his life to insurance, insurance claims and the need to defeat insurance fraud over the last 55 years. 

How Algorithms Can Make Life Insurance Offers Fast

Due to advances in AI, properly built algorithms using approved data sources can produce accurate life insurance quotes in only five minutes.

Happy woman sitting at table with laptop

Today’s consumers expect fast, efficient buying experiences for most products and services. According to Forbes, two out of every three respondents to a recent survey said speed is just as important to them as an item’s price, and over half said they would hire the first business that responded to them, regardless of whether its product or service was more expensive than alternatives. Similarly, about half reported being less likely to spend money at a business that takes longer to get back to them than they expect.

Customers for life insurance are no different. The good news, however, is that due to advances in AI technology, properly built algorithms using approved data sources can produce fast and accurate life insurance quotes. For instance, our online tool underwrites and prices insurance applications in only five minutes.

By speeding up the underwriting process, life insurance providers can convert prospects into policyholders. Whether working through agents or directly with consumers, producing an offer quickly, efficiently, fairly and accurately is essential both to the growth of the insurance business and to help cover the uninsured.

See also: Insurance Underwriting Will Never Be the Same

The problem of lengthy vetting processes

Traditionally, life insurance companies have required prospective customers to endure a lengthy vetting process. For instance, many consumers had to endure multiple interviews with carriers’ representatives and get an exam with a blood draw or urine specimen.

In recent years, the industry has evolved, and many companies have started offering accelerated underwriting solutions. In my experience, however, the many restrictions put on applicants mean that only a select few qualify for these programs. Most are still required to answer lengthy questionnaires.

Imagine answering a question about your medical history only to find yourself confronted by five to 15 (or more) additional questions about that condition alone. Now imagine you are confused about how to respond to some of those questions. For others, you don’t even know the answer.

It would make sense for you to feel frustrated and annoyed, yet this is the life insurance industry’s usual approach. Companies design their onboarding surveys with reflexive questions that bog people down instead of ushering them through the sales funnel.

Expecting prospects to tolerate such a negative customer experience leads to decreased conversion rates because many people will elect to abandon the process altogether. Meanwhile, those applications that achieve completion tend to be less reliable because the intensive questioning encourages the consumer not to disclose further medical conditions. If you feared triggering a seemingly endless series of still more new questions, wouldn’t you think twice, too?

How next-generation life insurance algorithms work

The science of polling and survey research allows for a fast, non-reflexive method of interviewing people such as we use in QUITM. This approach gets the key information it needs to make accurate decisions without needing to ask follow-up questions. This cuts down on the amount of time the disclosure process takes.

Essentially, when a consumer discloses a condition, a multiple-choice question is presented that is tailored to that specific issue. The consumer will choose the answer that best describes the severity of their condition.

The system uses the consumers’ answers to derive an instant decision in the form of a provisional quote. Algorithms can rate and price consumers in a matter of minutes, offering a product that fits a budget and risk profile. Providing the most accurate quote as quickly as possible is essential to limit surprises when the final offer is presented to the consumer. This ensures a positive customer experience.

If the customer chooses to move forward after receiving their instant offer, they consent to order third-party data, which includes verifying their identity, conducting a criminal background check and obtaining their driving record and their prescription history. To produce offers that avoid bias, AI-based algorithms should only use standard, industry-accepted data sources and purposefully exclude information from social media or data that would base decisions on the consumers’ race, religion, employment, location or buying habits.

Layering on this industry-standard third-party data is essential to mitigate insurance providers’ risk. It serves as a check against the consumer disclosure because the accuracy of the provisional quote depends on how honest the consumer was when disclosing their medical history.

Algorithms can analyze this data and quantify its degree of confidence in the provisional quote. If the confidence level is high, the system can make a final offer. If it’s lower, the system can order additional data, such as medical claims and digital health records

In our experience, approximately 80% of the time the final offer will be the same as the instant quote.

See also: The Underwriter 2.0, in the Era of AI

Pleasing customers boosts business

According to Zendesk, “73% of customers now say CX [customer experience] is the number one thing they consider when deciding whether to purchase from a company.”

In my experience, consumer drop-off increases as they are asked more and more questions and forced to spend more time answering them. That’s why we designed a life insurance platform that delivers the consumer’s desired outcome in a minimally invasive, five-minute experience. 

By eliminating reflexive questions, assessing and pricing every application and delivering instant offers, life insurers can develop a customer-friendly buying experience while reducing abandonment rates.

Improving CX While Reducing Costs

By adopting automation and sustainability, insurance carriers can enhance the customer experience while driving down operating costs. 

A Smiling Agent Talking to a Client

Faced with rising automation and security risks, the insurance industry is in a constant push and pull between digital transformation and the customer experience. However, amid economic uncertainty, many carriers do not have the expendable capital to pour into the customer experience and instead have chosen to focus on their primary business functions to drive revenue. In fact, however, carriers can find ways to improve the customer experience while reducing operating costs, with a little strategic guidance. 

See also: 10 Reasons to Stress Customer Retention

Automating Processes for Efficiency

Automation presents a unique cost challenge. Initially, investing in AI, chatbots and other automation tools can strain budgets, especially for first-time adopters. However, the long-term benefits can significantly enhance efficiency and reduce operating costs.

Take auto claims processing. Insurance carriers can responsibly adopt technology in two key ways. 

  • They can invest in AI-powered software, albeit with upfront expenses covering software acquisition, employee training, and integration into existing workflows.
  • Or companies can outsource operations to firms equipped with the necessary technology and expertise. This approach minimizes initial investment, offering a cost-effective means of tech adoption. Moreover, it streamlines implementation, freeing time to focus on core revenue-generating activities. Outsourcing also helps maintain low overhead costs.

Either way, machine learning algorithms can analyze vast amounts of data, accurately assessing the extent of damage and estimating repair costs with few to no errors. This drastically improves efficiency, paying for itself with the time saved and the avoidance of overpayments. 

Not only does automation expedite the claims process, passing time savings on to the customer, it also leads to faster settlements, further improving the overall experience. While automation can be a big upfront cost, it’s well worth adopting in the name of improved customer experience and accuracy. 

Adopting Technology Responsibly

When adopting technology, one size does not fit all. Insurance carriers should tailor technology solutions to align with their unique business needs and customer expectations. This approach ensures a seamless integration of technology into existing workflows, fostering a culture of innovation without disrupting operational continuity. Implementing technology like AI in manageable ways will also ensure no resources are spent on anything unnecessary. 

If your company does choose to outsource automation, look for a company that has a customer-first approach. Implementation can be daunting but with the right team, level of expertise, and flexibility, the result can save more than just money. It can also improve customer experiences and better align with customer values such as eco-friendliness and emission reductions, while improving your bottom line. 

See also: How Cloud Tech Improves Customer Experiences

Aligning Business Values With Customer Values

In today's era of heightened consumer consciousness, aligning business values with customer values can strengthen customer loyalty. For instance, a recent Solera survey found 75% of drivers would switch insurers for a more eco-conscious policy. And, lucky for insurers, sustainability can be adopted on a spectrum. For example, 

  • Adopting energy saving practices in your physical locations can help bring down utility bills and operating costs. Measuring carbon emissions and creating goals to reduce your footprint will sit well with eco-friendly consumers. Estimatics solutions can help achieve carbon reduction goals by measuring and minimizing emissions within a supply chain. A car repair shop, for example, can determine if they should complete their repair with a used part, based on potential emissions data. 
  • Prioritizing durability and longevity in repairs and vehicle maintenance can also be a sustainable practice that lowers costs in the long term. By investing in high-quality, long-lasting materials and repair techniques and green parts, insurers can reduce the frequency of auto repairs and replacements. 

The Future of CX Is Efficient

Adopting automation and sustainability are just two ways insurance carriers can enhance the customer experience while driving down operating costs. There are a multitude of options out there, but by prioritizing automation, responsible technology adoption and values alignment, carriers can position themselves for long-term success in an increasingly competitive landscape. Embracing these tactics not only strengthens customer relationships but also fosters operational excellence, paving the way for sustainable growth and profitability in an ever-evolving industry.