Download

The Evolving Claims Professional

With short staffing and less experienced adjusters, organizations must equip claims professionals with better, data-driven tools.

 Woman Using Laptop

One of the biggest issues affecting the P&C industry is the changing labor market. In the wake of the pandemic, hybrid and remote work has persisted. This “new normal” has created challenges for employers. The problem is compounded as older professionals retire, leaving claims organizations to bridge the knowledge gap as younger professionals enter the market.

A report by the National Association of Mutual Insurance Companies indicates 50% of the current insurance workforce will retire over the next 15 years. In addition, a 2022 survey found nearly a quarter of claims adjusters plan to retire by 2027. These stats portend a talent chasm. 

For now, most claims operations have stabilized their staffs by backfilling the notable headcount deficits of the early 2020s. But the cumulative effect is a scarcity of deep claims technical expertise as compared with pre-pandemic levels.  

See also: Overcoming the Talent Crisis in Underwriting

Where to Start?

Once new-but-inexperienced, adjusters are onboarded, the primary objective is to quickly ramp them into productive claims handlers. Prior to the pandemic, formal adjuster training was augmented by “in-office osmosis” – knowledge absorption from experienced adjusters as they talk on the phone with claimants, medical providers and lawyers. A shortage of highly technical adjusters coupled with remote and hybrid work has altered that workplace dynamic, creating hurdles for adjuster training and knowledge transfer. Even as claims organizations find their equilibrium, accelerating talent development will remain an operational obstacle.

The challenge of shifting to a claims staff with less tenure and expertise is magnified by several factors. First, high turnover put pressure on claims organizations as caseloads became bloated while vacancies were backfilled. Empty seats also precipitated claims reassignments, requiring busy adjusters to get up to speed on older, often complex, claim files. Most claims departments are well equipped to handle this; however, a dearth of experienced technicians adds stress.

A more troublesome issue is the menacing profile of claims now populating an adjuster’s inventory. The surge of social inflation — a trend of rising claims costs due to increased litigation settlements, jury awards, anti-corporate bias and aggressive plaintiff attorney tactics — is creating a high degree of difficulty, especially on third-party bodily injury claims. In fact, research by Verisk shows the average size of verdicts over $1 million exploded from $2.3 million in 2010 to more than $22 million in 2018. In 2019, there was a 300% jump in verdicts of $20 million or higher.

As organizations continue to deal with short staffing and less experienced adjusters, it is more important than ever to equip claims professionals with tools to recognize and manage combustible, but often camouflaged, claims.

Tech to the Rescue?

To help retain the knowledge and decision-making experience lost as seasoned professionals leave the industry, more claims organizations are employing technology to guide the new adjusters. The solutions hinge on better tools and decision support, especially for unsuspecting junior adjusters who encounter potentially explosive claims. That’s where decision support can act as an “early warning system” that helps bridge the knowledge and experience gaps.

Embedding intuitive analytic tools into the claim process lifts the technical expertise of low-tenured adjusters and provides the guidance and insight to effectively identify and handle more complex claims. For instance, functionality integrated into platforms can provide the following insights or support:

  • Delays and gaps in treatment or treatment extending beyond guidelines
  • High-frequency plaintiff attorneys – medical provider combinations driving abnormal treatment activity and charges
  • Tools that can organize and synthesize hundreds of medical bills and reports into a concise clinical summary view of a patient’s treatment and condition

High data volumes in a usable format are key. At Enlyte, for instance, we have billions of medical records that allow us to deploy analytic insights to adjusters. For workers’ compensation, connecting medical data (injury type, treatment patterns, etc.) with claimant data, such as age and comorbidities, can help flag cases with high severity relative to disability guidelines. We are armed with a vast database that includes over 1 million medical providers, early analysis of which suggests certain attorney–provider combinations produce significantly higher medical usage and costs than comparable claims with similar injuries. 

See also: The Next Generation of Talent

New Adjusters, New Opportunities

The evolving workforce creates an interesting opportunity to rebrand claims management. We have been grappling with an erosion of deep claims expertise for several years, and the pandemic and "great resignation" have exacerbated it.

So while claims organizations are struggling to fill vacated positions, there is a much-needed youth movement underway. And though these new professionals are green relative to claims handling, they’re seasoned veterans in their affinity for digital capabilities. This makes them well suited to quickly adopt and implement technology tools.

For an industry traditionally sluggish about innovation, this change is refreshing. A budding youth movement will help motivate our industry to the next level of innovation and advanced claims capabilities, reinventing how claims organizations serve injured parties and policyholders in their time of need. 


Steve Laudermilch

Profile picture for user SteveLaudermilch

Steve Laudermilch

Steve Laudermilch is executive vice president and general manager of Enlyte’s Casualty Solutions Group (CSG), where he guides strategy and business operations of Enlyte’s claims technology, analytics and workflow solutions for auto casualty and workers’ compensation industries.
 

Preparing for a Rough Hurricane Season

Forecasts of a "well above-average" 2024 Atlantic are a timely warning for insurers and companies with portfolios and assets at risk. 

Crashing Waves

It's been a century since the Great Miami Hurricane barreled into Florida in 1926, killing 372 people, injuring 6,000 and transforming the up-and-coming tourist destination around Miami into a wasteland of shredded palm trees and wrecked buildings. 

This destructive storm helped drive Swiss Re's U.S. business to a loss that year, according to our corporate archives. Based on more recent exposure data, Swiss Re Institute simulations indicate losses from the Great Miami Hurricane would have eclipsed those of Hurricane Katrina, which hit New Orleans 20 years ago, and Harvey, Irma and Maria in 2017.  

Understanding and preparing for hurricane season

As risk modelers at Swiss Re, we have a natural interest in historic catastrophes like the Miami hurricane. They provide a glimpse of what Mother Nature can unleash, then and now, and why those living in exposed geographies should incorporate risk awareness into their decision-making.  

But hurricane forecasters suggested recently there's another reason this year to consider the hurricane season of 1926: When Colorado State University (CSU) experts released their early forecast for the coming Atlantic hurricane season, they wrote that it exhibits characteristics similar to those that prevailed when the Great Miami Hurricane came ashore.

Warm sea surface temperatures and a predicted transition from El Niño to La Niña conditions at the peak of the June-through-November season favor hurricane formation and intensification. In fact, CSU forecasters conclude that the 2024 hurricane season's characteristics roughly align with not only those of 1926 but also 1878, 1998, 2010 and 2020, all of which were active. 

See also: Lessons From Florida's Hurricane 'Mean Season'

Forecasting the fury

Of course, forecasts can change considerably. 

CSU acknowledges their April forecasts have the lowest level of "skill" ,or predictive power, compared with those issued later in the season. Additionally, we know annual hurricane losses are driven by individual hurricanes, not overall activity. 

However, more recent assessments, such as the one released by the National Oceanic and Atmospheric Administration in late May, also predict an above-normal hurricane season, with activity levels similar to those of CSU's April forecast.

All else being equal, CSU experts' "higher-than-normal confidence" in their early forecast for a very active season is at minimum a timely reminder that insurers and companies should be focused on what coming months may bring, and the importance of being ready for whatever materializes.     

Powered by AI 

This pursuit – helping insurers and corporate clients prepare for the worst, even as we hope for the best – has driven development of Swiss Re's Rapid Damage Assessment platform. The tool lets clients develop a catastrophe response strategy for hurricanes and other perils by automatically monitoring probable impacts of an event with help from proprietary Swiss Re models. 

After a storm's landfall, our platform delivers high-definition satellite and aerial images of affected properties. Aided by artificial intelligence to gauge damage severity, individual inspections can be prioritized quickly and triaged remotely to reduce expense and claims leakage and create loss reports for faster, more accurate settlements. 

Accelerating the claims process reduces costs by helping speed repairs before resources become stretched or affected by construction inflation. Faster claims handling spares customers long waits, boosting brand loyalty.

When any catastrophe unfolds, moving quickly is critical to serve those facing a potentially difficult recovery, while simultaneously containing adjustment expenses and minimizing the claims cycle time to keep customers satisfied and fulfill strict regulatory requirements. 

See also: The Hurricane Forecast Keeps Getting Darker

What matters: Being ready

Hurricanes remain a larger-than-life, difficult-to-forecast phenomenon that test our understanding of weather, much like fast-forming Hurricane Otis did a year ago before slamming into Acapulco. Sometimes, they seem calculated to cause maximum damage. Other times, they swirl around almost harmlessly before heading back out to sea. 

With climate change, Atlantic hurricanes may decrease in number while the proportion of storms that reach Category 4 or 5 intensity may increase, scientists say, though there's uncertainty over these projections. Studies do project tropical cyclones will produce more rainfall, with coastal inundation seen increasing as sea levels rise. 

What's important to remember is fierce individual storms can always cause record losses if they strike valuable assets concentrated in harm's way. In 2022, when Hurricane Ian ploughed through densely populated Fort Myers on Florida's Gulf Coast to become one of history's costliest natural catastrophes, hurricane activity for the year was only about average.

Forecasts aside, insurers and companies active in vulnerable regions need the right tools and technology to prepare for and respond to nearly every eventuality. Whether natural catastrophes conform to experts' expectations or defy them, what matters most is being ready, wherever and whenever they come.

How Agents Can Tackle California's Challenges

With rates soaring and insurers pulling out of California, agents must double down on outreach, empathetic communication and client education.

Golden Gate Bridge

By now, professionals across our industry are well aware of the instability of the California insurance market. California is a high-risk area to insure, as both personal and commercial line insurers have reported frequent, costly losses from wildfires, landslides and earthquakes. Now, insurers are forced to navigate higher replacement costs due to inflation and supply chain challenges and, of course, new underwriting guidelines mandated by the California FAIR Plan. 

Many insurers have pulled out of the market. Those that remain have had to implement strict underwriting guidelines that leave certain ZIP codes very difficult to insure, and sometimes the California FAIR Plan is the only option agents have. The FAIR plan has had an influx of business, which means it can even take 30 days before the agent can get the quote back. And sometimes the FAIR plan comes back with additional questions after the review period, which could lead to a lapse in coverage. This, in tandem with concerns about the long term viability of the FAIR plan, have created a difficult set of circumstances for agents to work through.

So, what can an agent in the California market do to support insureds and maintain or grow customer satisfaction while navigating these challenges?

Outreach, empathetic communication and client education are key. 

See also: Seizing Opportunities in CA State Insurance Crisis

Understanding client needs

Outreach is essential in a difficult market. Our insureds are hearing all over the news that insurers are leaving the market and that rates are skyrocketing. This only damages our reputation. Early, transparent client education can help mitigate this issue.

As a trusted partner of our clients, we must keep them apprised of market conditions. For those in disaster-prone areas, we should offer easy-to-understand explanations as to why these areas are more difficult to insure. If premiums are rising, we should share why that is and provide an outlook. Often, during these difficult conversations, we also have the opportunity to share educational materials with our clients. For example, agents might consider sending over trade articles explaining the market challenges so insureds can learn more about the issues in their own time. 

When premiums rise, agents also have an obligation to consider alternative solutions to keep costs manageable for clients. For example, offering a higher deductible is an option. Encouraging the client to implement risk mitigation practices such as leak detection technology for homes can also help reduce costs. 

Of course, there are only so many solutions an insurer can offer in the current California market. Clients will still find frustration with rising costs and difficulties securing adequate coverage to protect their homes and businesses. When a frustrated client calls, we need to be empathetic. Let them say what they want to say and offer support and reassurance that we are here to support them. In some cases, it may even be wise to recommend the client shop for other insurance policies. Provide them with contact information for other major insurers, such as Costco, AAA or Geico, and encourage them to shop around. This experience can showcase just how difficult it is to find coverage today for the frustrated policyholder.  

Increasing touchpoints

Reconsidering communication touchpoints is also crucial. While a boots-on-the-ground approach may have been the go-to tactic prior to the pandemic, there are a few methods for agents and brokers to consider in 2024.

In the past, we often stressed regular client in-person visits to remind them of our value and develop the relationship. In-person visits remain important and should be done at least annually, or even quarterly with larger clients. Renewal is an ideal time for agents to meet with clients to review their policies. This review should examine whether they have adequate coverage to protect their home or business, whether any new risk measures could help keep costs down and whether there are any trends or pending legislative updates that could affect their policy.

Today, clients want to know their insurers are available to them at all times. And with the rise of Zoom and other video conferencing platforms, our industry now has plenty of additional resources to schedule more frequent client communication. Make sure clients know you are accessible and can easily book a video or phone meeting at any time they may have an issue. Live chat solutions are also valuable. Insureds should be able to visit your website and connect to a live agent quickly. Today’s agent musts be able to mold their business model to these new systems and new means of connection. Both existing and potential clients want an insurer that can provide quick and easy answers to any questions they may have. 

See also: Parametric Insurance Can Tackle Climate Risks

Recommending risk mitigation

Lastly, agents should dedicate resources to risk mitigation., which remains a critical practice for keeping policy costs down. For example, on the personal lines side, agents should ensure clients have the latest leak detection technology. They should also have alarm systems onsite. With wildfires continuing to threaten insureds, agents should recommend common fire mitigation practices such as tree and bush trimming and creating defensible space.

On the auto front, teenage drivers continue to be a frequent source of losses. Agents should encourage parents to stress driver safety, following speed limits and avoiding distracted driving with their teen drivers. In some cases, we also recommend agents encourage policyholders to implement driver monitoring technology on teenagers’ phones. 

For both businesses and homes, agents should be talking to clients about smoke and carbon monoxide detectors. They should also encourage employers to pay close attention to employee training to ensure staff is adequately prepared to work safely, whether operating dangerous equipment or simply walking around the facility. Regular equipment maintenance and inspections should be considered safety practices, as well. And as always, clients should have an emergency response plan in place in case of any disaster.

Recognizing the silver lining

The California insurance market may be at a challenging time for agents, but there is a silver lining. We are starting to see faster approvals for rate increase requests by insurers, so the industry can keep up with the rising cost of claims. This is an important first step toward normalizing the market. We have also started seeing quicker quote approvals from the FAIR plan, which is a good sign for the future.

While our agencies wait for the market to stabilize, agents will want to prioritize customer communication. Those who focus on empathetic and more frequent client communication to ensure client satisfaction can continue to thrive despite the market challenges.

How AI Can Lead to Personalized Medicine

Personalized medicine and targeted therapies are becoming a reality, thanks to AI's ability to analyze vast amounts of genetic and molecular data.

Green and Blue text that reads "AI in Healthcare"

Artificial intelligence (AI) is transforming the healthcare landscape, offering unprecedented opportunities for improvement and innovation. From streamlining clinical workflows to enhancing patient care, AI is revolutionizing the way healthcare professionals work and patients receive treatment. AI-powered chatbots and virtual assistants are enabling 24/7 patient support, while predictive analytics and machine learning algorithms are identifying high-risk patients and preventing costly readmissions. AI-driven medical imaging and diagnostics are improving accuracy and speed, enabling earlier detection and treatment of diseases. 

Personalized medicine and targeted therapies are becoming a reality, thanks to AI's ability to analyze vast amounts of genetic and molecular data. Moreover, AI is helping to address healthcare's most pressing challenges, such as access, affordability and disparities, by enabling remote monitoring, telemedicine and population health management. As healthcare organizations seek to harness the full potential of AI, partnering with an experienced AI software development company can help them navigate the complexities of AI implementation and customization, ensuring seamless integration and maximum impact. As AI continues to evolve and improve, we can expect even more groundbreaking innovations that will transform the healthcare industry and improve patient lives.

Unlocking the Potential of Predictive Analytics and Personalized Medicine

Predictive analytics and personalized medicine are two crucial aspects of AI in healthcare, enabling healthcare providers to make data-driven decisions and tailor treatment plans to individual patients' needs. 

By leveraging predictive analytics, healthcare professionals can identify high-risk patients, anticipate potential health issues and develop targeted interventions. Personalized medicine, on the other hand, allows for tailored treatment approaches, taking into account a patient's unique genetic profile, medical history and lifestyle factors. For instance, AI-powered genomics can help identify genetic mutations responsible for certain diseases, enabling targeted therapies and precision medicine. Additionally, predictive analytics can help identify patients at risk of developing chronic conditions, such as diabetes or heart disease, allowing for early interventions and preventative measures. 

Furthermore, AI-driven personalized medicine can help optimize drug development, dosing and delivery, reducing adverse reactions and improving patient outcomes. By combining predictive analytics and personalized medicine, healthcare providers can deliver patient-centered care, ultimately improving health outcomes and reducing healthcare costs.

See also: How AI Could Set Premiums in Real Time

Key applications of AI include:

1. Disease Risk Assessment and Prevention:

Predictive analytics helps identify high-risk patients, enabling healthcare providers to develop targeted interventions and preventive measures. By analyzing patient data, predictive models can detect early warning signs of chronic diseases, such as diabetes, cardiovascular disease and cancer. For instance, predictive analytics can help identify patients at risk of developing diabetes by analyzing factors such as blood pressure, weight and family history. This enables healthcare providers to develop personalized prevention plans, including lifestyle changes and medication, to prevent or delay the onset of diabetes. 

Similarly, predictive analytics can help identify patients at risk of cardiovascular disease, allowing healthcare providers to develop targeted interventions to reduce the risk of heart attack or stroke. Additionally, predictive analytics can help detect early signs of cancer, enabling healthcare providers to develop personalized treatment plans and improve patient outcomes. By leveraging predictive analytics, healthcare providers can deliver patient-centered care, reducing the burden of chronic diseases and improving overall health outcomes.

2. Patient Outcome Prediction:

Predictive analytics helps healthcare professionals anticipate patient outcomes, enabling them to develop personalized treatment plans and improve patient care. By analyzing patient data, predictive models can forecast patient responses to different treatments, reducing the risk of adverse events and improving health outcomes. For example, predictive analytics can help healthcare professionals identify patients at high risk of readmission to hospital, enabling them to develop targeted interventions and reduce readmission rates. Additionally, predictive analytics can help healthcare professionals optimize medication dosing and reduce the risk of adverse drug reactions. 

Furthermore, natural language generation technology can be used to create clear and concise patient reports, enabling healthcare professionals to quickly and easily communicate complex patient data to patients and their families, improving patient understanding and engagement. By leveraging predictive analytics and natural language generation, healthcare professionals can deliver more effective, efficient and patient-centered care, ultimately improving patient outcomes and reducing healthcare costs.

3. Resource Allocation and Optimization:

Predictive analytics helps healthcare organizations optimize resource allocation, reducing costs and improving efficiency. By analyzing patient flow, staff workload, and resource utilization, predictive models can identify areas of improvement, enabling healthcare professionals to make data-driven decisions. For instance, predictive analytics can help hospitals optimize bed capacity, reducing wait times and improving patient satisfaction. Additionally, predictive analytics can help healthcare organizations identify high-risk patients, enabling early intervention and reducing readmission rates. 

4. Drug Discovery and Development:

Predictive analytics plays a crucial role in drug discovery and development, enabling researchers to identify potential drug targets, predict drug efficacy and optimize drug development processes. By analyzing large datasets, predictive models can identify patterns and correlations, accelerating the development of new treatments and therapies. For instance, predictive analytics can help researchers:

  • Identify potential drug targets by analyzing gene expression data and protein structures.
  • Predict drug efficacy by simulating drug interactions and pharmacokinetics.
  • Optimize drug development processes by identifying potential bottlenecks and areas for improvement.
  • Develop personalized medicine approaches by analyzing patient data and genetic profiles.
  • Improve drug safety by predicting potential side effects and toxicities.
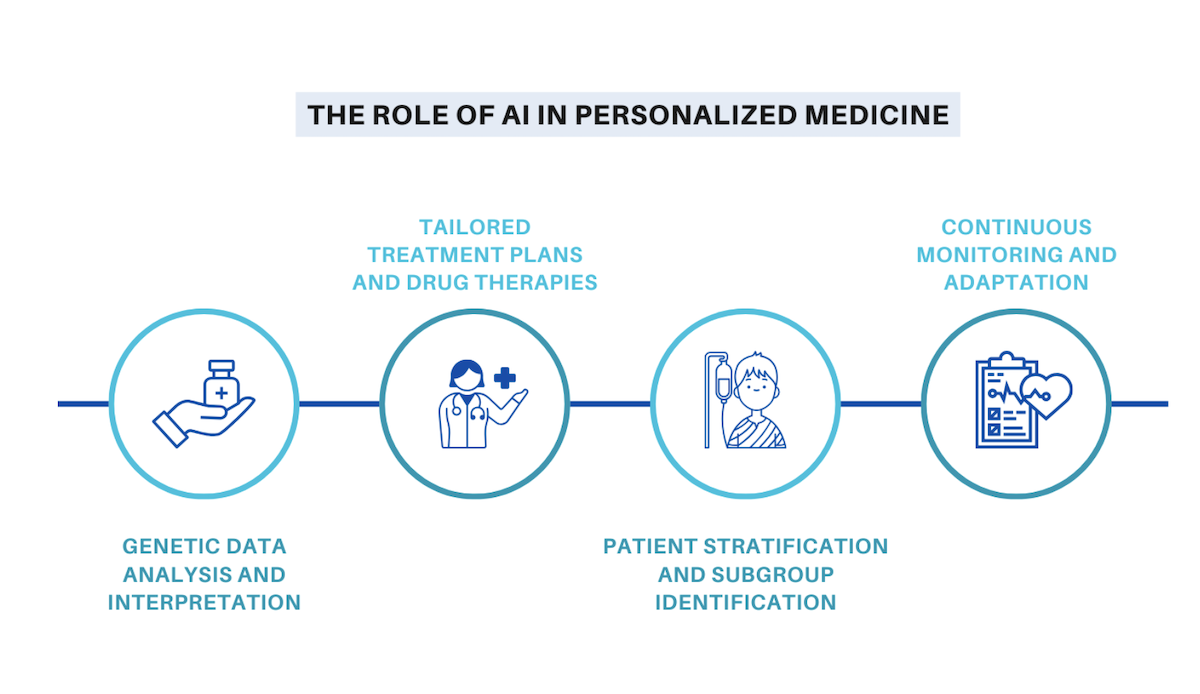
Role of AI in Personalized Medicine

Personalized Medicine and AI: Revolutionizing Healthcare With Tailored Treatments:

Artificial intelligence (AI) plays a crucial role in personalized medicine, enabling healthcare professionals to analyze vast amounts of data, identify patterns and make informed decisions. AI's applications in personalized medicine include:

1. Genetic Data Analysis and Interpretation:

AI helps analyze genetic data, identifying genetic variations and correlations with specific diseases or conditions. This information enables healthcare professionals to develop targeted treatments and therapies.

2. Tailored Treatment Plans and Drug Therapies:

AI helps develop personalized treatment plans and drug therapies based on individual patient characteristics, medical history, and genetic profiles.

3. Patient Stratification and Subgroup Identification:

AI helps identify patient subgroups with similar characteristics, enabling healthcare professionals to develop targeted interventions and treatments.

4. Continuous Monitoring and Adaptation:

AI enables continuous monitoring of patient data, allowing healthcare professionals to adapt treatment plans and therapies as needed.
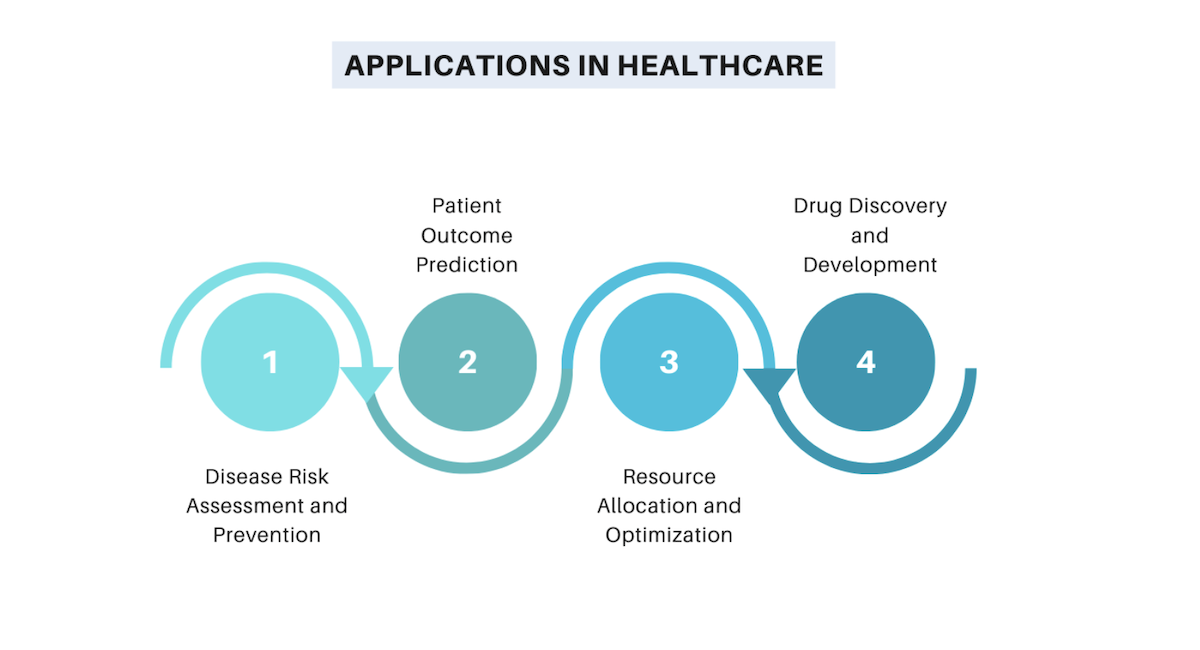
Applications in Healthcare

Examples of AI-Driven Personalized Medicine in Practice:

Cancer treatment: AI helps identify genetic mutations and develop targeted therapies, improving treatment outcomes and reducing side effects.

Pharmacogenomics: AI helps predict patient responses to medications, enabling healthcare professionals to prescribe personalized drug therapies.

Rare disease diagnosis: AI helps identify rare genetic disorders, enabling healthcare professionals to develop targeted treatments and therapies.

See also: Insurance: An Industry Embracing AI

The Double-Edged Sword of AI in Healthcare: Benefits and Challenges

AI has the potential to revolutionize healthcare, offering numerous benefits, including:

1. Improved Accuracy and Efficiency:

AI can analyze vast amounts of data quickly and accurately, reducing errors and improving diagnosis and treatment.

2. Enhanced Patient Experience and Engagement:

AI-powered chatbots and virtual assistants can provide personalized support and engagement, improving patient satisfaction and outcomes.

3. Increased Accessibility and Reduced Costs:

AI can help expand healthcare access to remote and underserved areas, reducing costs and improving health equity.

While AI holds great promise, it also presents several challenges and limitations, including:

1. Data Quality and Privacy Concerns:

AI relies on high-quality data, which can be scarce or compromised by privacy concerns and data breaches.

2. Regulatory and Ethical Considerations:

AI raises ethical concerns, such as bias and transparency, and requires regulatory frameworks to ensure responsible use.

3. Integration With Existing Healthcare Systems:

AI must be integrated with existing healthcare systems, requiring significant investment and infrastructure upgrades.

By acknowledging both the benefits and challenges of AI in healthcare, we can harness its potential while addressing the complexities and limitations. By recognizing the benefits of AI, such as improved diagnosis accuracy and enhanced patient experience, we can leverage these advantages to drive innovation and progress. At the same time, by acknowledging the challenges, such as data privacy concerns and potential biases, we can address these issues and ensure that AI is used responsibly and ethically.

Through this balanced approach, we can ensure that AI is used to augment and support healthcare professionals, rather than replace them. We can also prioritize transparency and accountability in AI decision-making, ensuring that patients and healthcare providers alike understand how AI-driven insights are generated and used. By working together to address the complexities and limitations of AI in healthcare, we can create a more sustainable and equitable healthcare system that prioritizes patient well-being and dignity. Ultimately, this balanced approach will enable us to harness the full potential of AI to improve healthcare outcomes and transform the lives of patients and healthcare professionals alike.

See also: Streamlining Medical Record Reviews Via AI

Real-World Impact: AI-Driven Predictive Analytics and Personalized Medicine in Action:

Case Study 1: Predicting Patient Outcomes in ICU:

Setting: Intensive Care Unit (ICU) in a tertiary care hospital

Challenge: High mortality rates and prolonged ICU stays

Solution: AI-driven predictive analytics to identify high-risk patients and optimize treatment

Impact: 30% reduction in ICU mortality rates and 25% reduction in ICU length of stay

Case Study 2: Personalized Cancer Treatment:

Setting: Oncology department in a cancer center

Challenge: Limited treatment options and high toxicity rates

Solution: AI-driven personalized medicine to identify optimal treatment plans based on genetic profiles

Impact: 40% increase in treatment response rates and 30% reduction in toxicity rates

Case Study 3: Early Detection of Chronic Diseases:

Setting: Primary care clinic in a rural area

Challenge: Limited access to specialized care and high prevalence of chronic diseases

Solution: AI-driven predictive analytics to identify high-risk patients and enable early intervention

Impact: 25% reduction in chronic disease incidence and 30% improvement in patient engagement

These real-world examples demonstrate the potential of AI-driven predictive analytics and personalized medicine to transform healthcare outcomes. By leveraging AI, healthcare professionals can make data-driven decisions, improve patient care and reduce costs. These success stories showcase the value of AI in healthcare, providing inspiration and guidance for future implementations. For instance, AI-powered predictive analytics can help identify high-risk patients and prevent hospital readmissions, reducing healthcare costs and improving patient outcomes. Additionally, AI-driven personalized medicine can help tailor treatment plans to individual patients' needs, leading to more effective treatments and better health outcomes.

Moreover, AI can help healthcare professionals stay up-to-date with the latest medical research and guidelines, ensuring that patients receive the best possible care. AI-powered chatbots and virtual assistants can also help patients manage their health and communicate with healthcare professionals more effectively, improving patient engagement and experience. Embracing AI and predictive analytics ultimately leads to better health and well-being for individuals and communities worldwide. By learning from these success stories and exploring new applications of AI in healthcare, we can continue to drive innovation and improvement in patient care.

Unlocking the Future of Healthcare: Emerging Trends and Possibilities

Advancements in AI and Healthcare:

Explainable AI: Developing transparent and interpretable AI models to build trust and understanding in healthcare decision-making

Edge AI: Enabling real-time AI processing at the edge of healthcare systems, reducing latency and improving response times

Federated Learning: Collaborative AI training across healthcare organizations, enhancing data privacy and security

Potential Applications and Areas of Growth:

Personalized Medicine 2.0: Integrating AI-driven genomics, precision medicine and targeted therapies for tailored patient care

AI-Assisted Clinical Trials: Streamlining trial design, patient recruitment and data analysis for faster and more efficient drug development

Virtual Healthcare Assistants: AI-powered chatbots and virtual assistants for patient engagement, education and support

Future Possibilities and Implications:

Transforming Healthcare Workforce: AI augmenting human capabilities, enabling healthcare professionals to focus on high-value tasks and patient care

Health Equity and Access: AI-driven healthcare expanding access to underserved populations, reducing health disparities and improving global health outcomes

Ethical Considerations: Addressing AI-driven healthcare's ethical implications, ensuring responsible innovation and prioritizing patient well-being

By embracing emerging trends and advancements in AI and healthcare, we can unlock new possibilities for patient care, healthcare workforce transformation and global health equity. This future-focused approach will enable us to harness AI's potential, creating a more compassionate healthcare system for all. By leveraging AI, we can develop personalized treatment plans tailored to individual patients' needs, improving health outcomes and reducing costs. AI-powered chatbots and virtual assistants can also enhance patient engagement and experience, providing 24/7 support and empowering individuals to take charge of their health.

Furthermore, AI can help address healthcare workforce challenges, such as burnout and shortages, by streamlining administrative tasks and freeing clinicians to focus on high-value care. AI-driven analytics can also identify trends and patterns, enabling healthcare professionals to make data-driven decisions and create quality improvement initiatives. Additionally, AI can help bridge the gap in global health equity, expanding access to healthcare services and improving health outcomes in underserved populations.

By prioritizing responsible AI development and deployment, we can ensure that these benefits are equitably distributed and that AI works for everyone. This requires collaboration from healthcare providers, tech innovators, policymakers and patients themselves, working together to shape a future where AI enhances human care, rather than replacing it. 

Conclusion: Harnessing AI's Potential in Healthcare

Recap of Key Points:

  • AI is revolutionizing healthcare through predictive analytics and personalized medicine
  • Emerging trends and advancements in AI and healthcare offer vast potential for growth and improvement
  • Ethical considerations and responsible innovation are crucial for AI-driven healthcare

The future of AI in healthcare holds immense promise but requires collaboration and further research to fully realize its potential. 


Shoaib Karim

Profile picture for user ShoaibKarim

Shoaib Karim

Shoaib Karim is an associate SEO at Kodexo Labs, where he spearheads innovation and technology initiatives. 

He has a strong background in AI and machine learning and has contributed to numerous projects and publications in the insurance industry for six years. 

Reversals of Pandemic Migration Patterns

State rainy-day funds have remained at near-record levels, offering a cushion against inflation and increased costs.

Flock of Birds Flying Under Blue Sky

Influenced by the ability to work remotely during the pandemic, Americans migrated away from the East Coast and California. However, this year, there is evidence of reverse migration patterns due to a variety of developments resulting from rising costs where Americans relocated and the relative lower cost in areas abandoned during the pandemic.

For example, Texas, Florida, South Dakota, Tennessee and Idaho were top-ranked last year in Conning's annual State of the States Report, which analyzes municipal credit across all 50 states based on 13 metrics indicating relative state credit health. This year, states in the Northeast performed well, suggesting affordability may have become a concern for states like Utah and Idaho that previously experienced the most significant home price appreciation, driving state and local government spending and costs higher.

Three New England states (Rhode Island, New Hampshire and Vermont) rose notably in rank this year while Delaware plummeted 21 spots and Hawaii fell 11 spots into the bottom five, alongside perennially low-ranking states Illinois, Louisiana and Mississippi.

Florida fell to third place from last year as Nebraska and Wyoming claimed the top two spots. Last year's #1 ranked Texas dropped five spots to sixth place, as a result of subpar tax revenue growth and the most substantive drop in the housing price index (HPI) despite significant sales tax revenue. Rhode Island advanced the most, climbing 27 spots to #21, driven by robust population growth resulting in a higher tax revenue, employment and HPI. New Hampshire saw a nearly 12% increase in tax revenues when compared with 2022; Alaska witnessed a staggering 50% decline.

Overall, Conning’s outlook on state credit quality for 2024 is revised to “Stable” from 2023’s “Declining” outlook in anticipation of a return to pre-pandemic fiscal conditions. State rainy-day funds have remained at near-record levels, offering a cushion against inflation and increased costs as well as potential revenue declines after a period of surging federal funds, economic growth and stock market gains. 

See also: The Crisis in Long-Term Care

Here are examples that illustrate some of the trends this year:

Population 

South Carolina, Florida and Texas had the greatest increases in population. In South Carolina, additional residents provided a larger workforce, whereas strong population gains in Nevada resulted in high unemployment rates due to insufficient opportunities for work. New Jersey, Rhode Island and Massachusetts attracted more residents after losing population during the pandemic.

It takes a large change in population or economic activity to move the needle in terms of GDP per capita. New York, Massachusetts, Washington, California and Connecticut remain among the top states, and Hawaii bounced back six spots after standing out as a laggard in 2022, while Texas did the opposite, dropping seven spots.

The population in Arizona and Idaho slowed after attracting residents. States such as Georgia, Tennessee, Arkansas, North Dakota and Wyoming are cause for concern, because their population growth outpaces employment growth, potentially indicating a shortage of job opportunities for residents.

Housing 

The Northeast did well, with Rhode Island, Vermont, Connecticut, New Jersey and New York in the top 10 for greatest improvement in the Housing Price Index. States in the West and South likely fell due to rising home prices and the affordability issues arising from those who moved there as people left he East Coast and California during the pandemic.

Employment

All 50 states except Oregon recorded employment growth. Nevada, Alaska and South Carolina had the largest percentage increases in employment growth. Colorado surged 39 spots to 10th place thanks to employment growth in government, education, health services, professional and business services. New York, West Virginia, Alaska, Rhode Island and Missouri had robust employment growth despite modest populations.

GDP 

Natural resources such as oil, natural gas, coal and agriculture helped top-performing states such as North Dakota, Texas, Wyoming, Alaska, Oklahoma and Nebraska in terms of real GDP growth.  Retail trade GDP, a leading contributor to growth in 23 states, was up in all 50 states.., ability to attract new business).?The findings in the 2024 edition are measured in real GDP to remove the effect of inflation and focus solely on the output of a state's economy, a change from last year's report.

For the full report, click here. 


Karel Citroen

Profile picture for user KarelCitroen

Karel Citroen

Karel Citroen is a managing director of municipal research at Conning and currently serves on the Governmental Accounting Standards Advisory Council (GASAC), where he represents the insurance investment community. 

Prior to joining Conning in 2015, he was in municipal portfolio surveillance with MBIA and previously was a banking and securities lawyer for financial institutions in the Netherlands. 

Citroen earned a law degree from the University of Amsterdam, an MBA from Yale University, and an LL.M. in governance, compliance and risk management from the University of Connecticut. He is a member of the National Federation of Municipal Analysts.

How Insurtechs and Incumbents Fared in Q1

There were explosive stock price increases at insurtechs that demonstrated higher-quality growth. 

businesswoman explaining documents in office

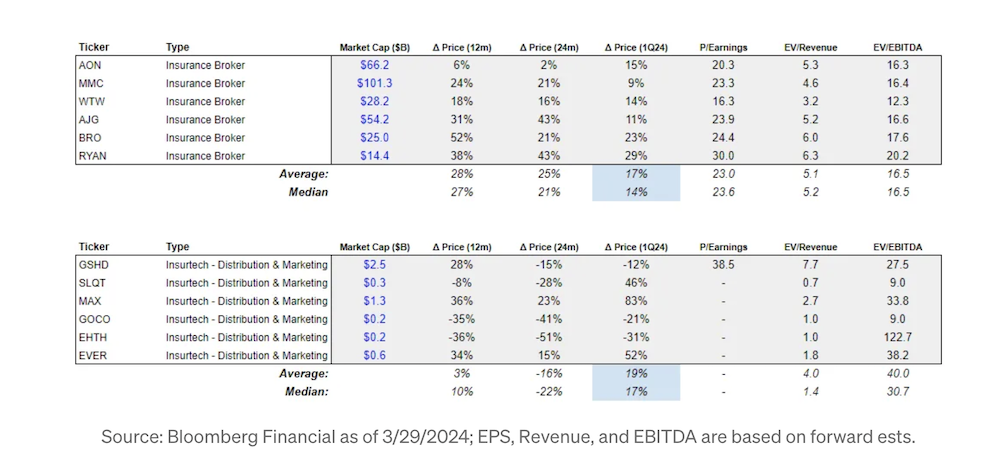
The Equal Ventures Insurance Index is a quarterly summary of public equity performance in the P&C insurance industry. This post summarizes performance of our insurtech/legacy indices in Q1 2024, highlighting key themes and trends in valuations.

Q1 was a strong quarter for stocks, and particularly so for the P&C insurance industry. 10Ks that hit during the quarter confirmed that the industry appears to be turning a corner on profitability. Capital is flowing again toward the hardest risks (Chubb called property the “best-priced business in the world”), and there were explosive stock price increases at insurtechs that demonstrated higher-quality growth. 

Q1 2024 Summary Stats:

  • Insurance equities broadly performed well in Q1: All four of our indices outperformed the broader market (SPX + 10%; Nasdaq + 9%)
  • Insurtechs outperformed legacy peer groups in both distribution and carrier indices, consistent with the trend we saw in Q4 and in FY 2023.
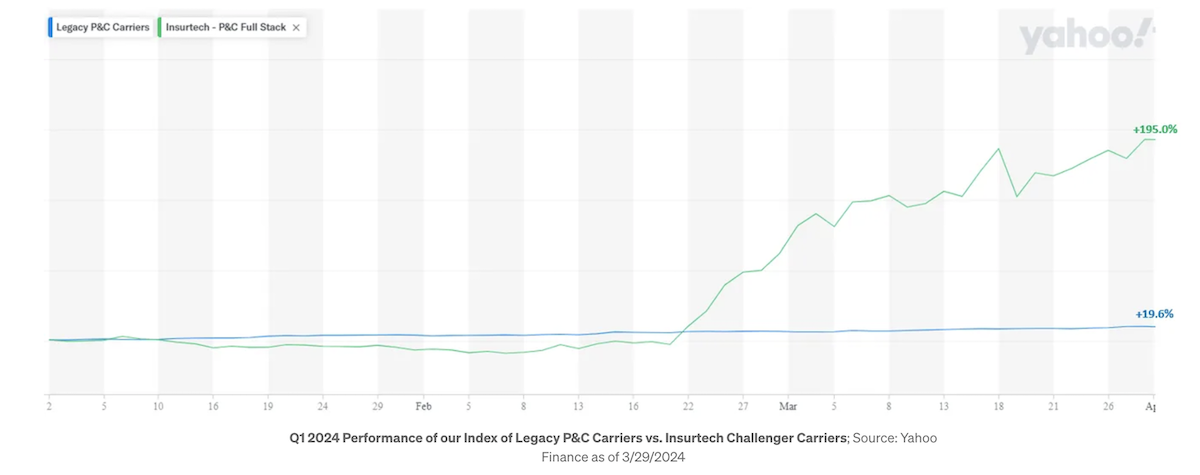
  • Carriers generally outperformed as higher rates and lower losses led to stronger results and improved guidance. The Insurtech Carrier Index, in particular, nearly tripled over the quarter, as investors anticipate and try to get ahead of a turnaround in fundamentals.
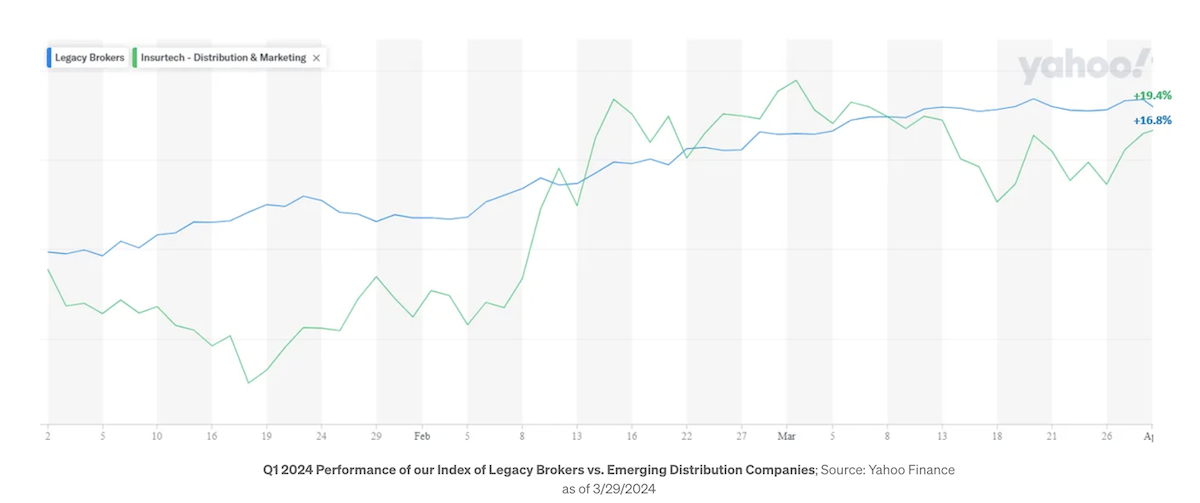
  • figure 1
  • figure 2

Takeaways From Q1 Performance:

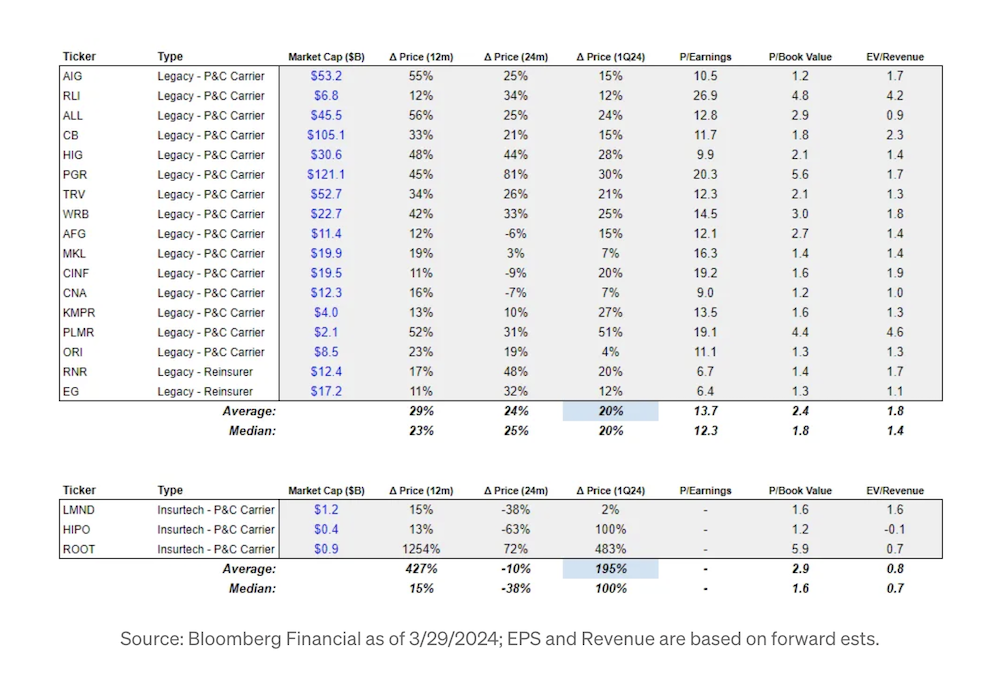
Improving trends in performance helped P&C carriers outperform throughout Q1 and continue the strong trend we wrote about last quarter. As we’ve talked about before, after facing a string of tough quarters in 2023, carriers have been focused on improving their combined ratios (from a terrible ~104% in 2023) by culling their books and taking higher rates. As premiums inch higher and property losses subside (at least for now), the strategy is paying off as profitability expectations rise. Every stock in both of our carrier indices was up in Q1, and the ACORD NA P&C Insurance Index posted a total return >40%. These are the sorts of numbers that look more like high-beta tech than insurance carriers.

figure 3

PGR (+30% in Q1), for example, in January reported a beat on combined ratio and net income in its fourth quarter results. FY combined ratio of 94.9 was ahead of its 96.0 forecast, and premiums rose by >20% y/y. The company pointed to an “unusually low frequency” of losses in the month of December 2023, driven by business mix and mild weather. The trend continued in Q1 results (albeit reported in Q2), with the combined ratio improving further to 86.1, a close to 13ppt improvement y/y and 250bps improvement sequentially over Q4’s strong result.

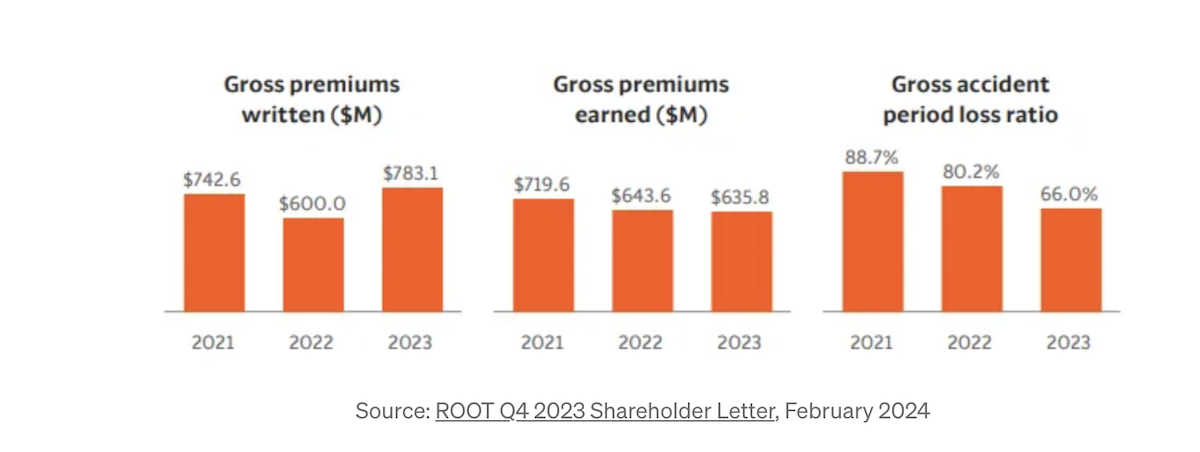
But it’s the insurtech carriers, led by ROOT (+483%!!), that benefited most from the perceived inflection point in growth and operating loss. Combined ratio (though still >100%) improved by a staggering 68 points y/y, and GWP more than doubled. Premiums from new business were up close to five-fold, and share of premiums from renewals ~halved compared with Q4 2022 (as the company churns its higher-risk insureds and builds a seemingly higher-quality book).

figure 4

In this backdrop of material business improvement, ROOT (which had negative EV just a few quarters ago when we launched the index), was up 13x over a year and >5x in Q1. The bet here is that strong growth will continue in an environment with higher rates, more underwriting discipline and tighter opex compared with 2021. On an EV/revenue basis, for example, ROOT and its insurtech peers still closed the quarter at lower multiples compared with legacy carriers. Our Insurtech Carrier Index traded at 27.5x EV/earned premium in 2021– with EV ~$400 million and given 2023 earned premium at $635 million, ROOT’s valuation is still nowhere near that peak stratosphere. But with its price/book value (arguably the most important metric for a typical P&C carrier) approaching 6x, >3x the median of the legacy group, the market is signaling ROOT can sustain its turnaround in growth and gross profit. Yet even PGR, with a long-term track record of underwriting outperformance in PL auto, trades at a lower multiple. This has led some industry commentators, including our friend Ian, to suggest that issuing equity at this multiple would be accretive to earnings (though the stock is already off its highs from early April).

See also: Social Inflation and Reserve Development

The brokerage and distribution universe was a bit less exciting (as it tends to be), though it still significantly outperformed the market across both indices.

figure 5

Brokers have benefited from the rapid growth in premiums (and corresponding revenues) over the last year, and Q4 results (reported in Q1) continue to tell that story. GSHD (-12% but still trading at high earnings and revenue multiples relative to incumbents) reported 29% y/y growth in written premium in its February report and anticipates 25% to 30% organic growth in premiums throughout 2024. RYAN (+29%) posted organic revenue growth of 16% in Q4 and 15% for FY 2023 on a revenue and net income base ~8x the size of GSHD’s, showcasing the continued strength of E&S premiums through Q4. As we wrote last quarter, sustained and accelerating pricing growth across the toughest categories (PL auto; property) is constructive to insurance equity performance, and further evidence of this trend in brokers’ earnings reports that hit in Q1 pushed the sector higher.

See also: Digitization and Enablement of Agents

P&C insurance performance in Q1 was impressive — particularly for an industry typically regarded as low-beta or boring. Q1 stock appreciation was standout (even focusing on the legacy players and ignoring the outsized moves of ROOT/HIPO). We remain excited about the growth in profitability as the industry turns a corner toward cyclically higher growth and earnings. But even as rates trend higher and organic growth remains strong, there are already initial signs of rate growth deceleration in Q1, and tougher comps loom (particularly for brokers). Whereas a year ago reinsurance supply was low and rates were skyrocketing, today the multiple of cat bond yields to expected losses suggests that hard market is history. This is sure to keep index performance interesting, and worth commenting upon, in coming quarters.

Top E&O Claims for IT Consultants

Here are five risk management solutions to deploy today to help reduce your risk of IT lawsuits.

Woman in Blue Suit Jacket on Computer

If you are an IT professional, you protect data and your clients. But despite your best efforts, inevitably there are issues that may arise and result in an errors and omissions (E&O) lawsuit. For example, a client gets upset and points the finger at you for their IT issues.

Let's take a quick look at potential causes for an E&O claim and a few methods you can use to reduce your potential risk.

Who is at risk for technology errors and omissions claims?

Technology companies are -- rightly or wrongly -- at constant risk of lawsuits and disputes over their work. In an increasingly litigious, technology -advanced and cyber-connected world, an IT business could find itself facing an expensive lawsuit for a number of reasons, everything from data breaches to not up-to-date business protocols. For example, you might be blamed for cyberattacks, even if an attack is the result of your client's negligence.

Whether you're involved in technology products, technology services, telecommunications, e-commerce,or any other professional services in the tech sector, there are many potential scenarios that could put your company at risk.

What kind of lawsuits are covered by tech E&O insurance?

Errors and omissions policies, also known as professional liability insurance, vary in terms of liability and omissions coverage. Policies that now include cyber insurance are called technology errors and omissions insurance, or tech E&O. You might also see this coverage called tech professional liability insurance.

Below are some of the more common E&O claims that your technology errors and omissions policy may cover:

1. Clients' data breaches

Security incidents and data breaches may cause your clients to file a lawsuit. Clients may cite improper network configuration, a bad software recommendation or other issues.

2. Breach of contract (missed deadline)

Breach of contract most likely happens when you miss a deadline, e.g., as a result of an unreliable contractor, a computer virus, a supply chain disruption, or any other issue.

3. Breach of warranty

If a client accuses you of making false claims about your product or services, you could be facing a breach of warranty claim. This can happen whether your promise was included as part of a written contract, or even just orally stated.

4. Misrepresentation

If your company makes a false statement to secure a contract, the client could sue you for a claim of misrepresentation. For example, if you offered a quote for IT services but failed to disclose any additional fees that you might charge during the contract, the client could sue.

5. Negligence

Lawsuits involving negligence are typically caused by poor planning or management that results in errors. If you fail to use reasonable care and make a mistake, a client could sue you if it damages their business.

See also: How to Avoid Major E&O Claims

6. Scope creep

Disputes over the scope of a project are common. A client might think the agreed-upon quote includes X, Y and Z, while you think it's only supposed to deliver X. Clients might also add requirements during the course of a project that affect the overall scope and expectations. Make sure your contract clearly outlines what your work does and does not include to avoid larger issues down the line.

7. Employee mistakes

It might seem unfair, but even if you don't have any employees, one of your client's employees could make a mistake, such as clicking on a phishing email or changing a security setting that exposes them to hackers. A client might sue you over any problems that result from this situation, even if you're not at fault.

8. Copyright infringement

If a software company accuses you of stealing some of the code from one of its products, you and your clients could face a lawsuit -- even if you included the code by accident.

Many errors and omissions issues can be avoided by improving client communication and employee training. Here are five risk management solutions to deploy today to help reduce your risk of IT lawsuits:

See also: Does Generative AI Kill Process Outsourcing?

1. Improve email communication

Be timely, responsive and to the point in client communication. Avoid overuse of jargon or technical terms.

2. Test for security

Ensure that security testing for your work is standard practice and be able to track your testing efforts.

3. Overcommunicate and educate

You are the tech expert, not your clients. Clearly convey the scope of your work, what it includes and what it does not, to avoid any gray areas.

4. Use client contracts

Handshake and oral agreements are not sufficient. Use client contracts and amend in writing, with client approval, if changes arise.

5. Explore a formal training program

Knowledge transfers to new employees are not foolproof. Consider a documented, formal training program that includes standard practices related to data security, work expectations and client communication.

In today's technology-advanced and overly litigious world, it's critical to routinely check with your insurance company about your E&O coverage to make sure you're aware of the exclusions and limitations within your policy. Continuous coverage is crucial, because E&O is a claims-made policy that must be active when you file a claim.

Achieving Effective Claims Payments

Digital solutions can make the high-stakes claims experience seamless, but industry data indicates a chasm between customer preferences and reality.

People Discuss Strategy Documents on Paper

Insurance exists to mitigate the fallout from some of life’s most disruptive events. As such, claims are one of the most critical touchpoints for insurance companies. In moments of distress, it’s often easier for claimants to have a memorably negative experience with their insurance provider than a positive one, and waiting for a claims check in the mail or contending with complicated technology only exacerbates customer frustration. 

Flexibility and accessibility are increasingly crucial when it comes to effective claim payments. Digital solutions have the power to make this high-stakes experience seamless for both insurers and policyholders, but industry data indicates a chasm between customer preferences and reality. Recent research conducted by InvoiceCloud, in partnership with Datos Insights, finds that while both claimants and insurers stand to benefit from a paperless shift, there are still stumbling blocks along the path that our industry must work to remove.

See also: Digital Underwriting Now a No-Brainer

Paper still reigns supreme

Most claims payments are still paid via check, even though this process is slower, less transparent, less secure and more expensive to manage than digital disbursement. Not to mention that this manual method ignores policyholder preferences.

Seventy-three percent of those surveyed in InvoiceCloud’s State of Online Payments report prefer to receive claims payments electronically. Not only does this streamline the payment experience, but electronic disbursement also reduces the time and cost associated with printing and mailing paper checks, alleviating employee workloads. Paper claims are slower and less transparent, putting urgently anticipated payments at the mercy of everything from postal service disruptions to lengthy wait times for manual lienholder endorsements. The rates of fraud when it comes to paper checks are also twice that of any other payment method, with JPMorgan Chase reporting that $1.3 billion was lost to check fraud in 2022.

Moving away from paper checks improves the claims experience for all involved. Yet, despite clear benefits to customers and insurers, most claims payments are still made via check. 

This lag in the insurance industry is a disservice to claimants. Customers should be offered self-service resources long before they need them, so they can navigate the process for setting up paperless payment disbursement on their own timeline, not during times of loss. The switch will also reduce stress and workloads for agents and the insurer’s customer service team.

The challenge of multiparty and lienholder disbursements 

A seamless transition to digital claim payments is even more important for multiparty and lienholder disbursements. Outbound payments split between two or more recipients are one of the most significant challenges facing the insurance industry, especially when it comes to facilitating the paperless transition.

Fortunately, there are solutions that address this challenge head on. When the payment process is digitized, claimants, lienholders, vendors and partners can receive payments effortlessly in whichever way they choose.

When claimants receive traditional multiparty checks, they can face a host of issues. They may have to track down other claimants themselves or find a bank that can endorse this specific kind of check – and if there isn’t a local branch that can, the claimant may have to send the check to a larger bank, opening themselves up to theft or mail delays.

Modern solutions simplify this process with digitization. Following the claim, digital solutions will send payment to all the correct parties via their preferred payment method (direct deposit, check, gift card, etc.). This streamlined, digital process gets money to claimants faster, reduces the opportunity for fraud and saves time for everyone involved.

All of this is rapidly becoming the new normal. Carriers are beginning to appreciate the importance of claims interactions and are adopting tech to improve the touchpoint – keeping themselves competitive in the process. Customers want to engage digitally. To keep policyholders satisfied and safeguard retention, it’s critical that insurers implement solutions that offer what customers want: digital options like real-time payments, mobile wallets and more. This is an easy way for companies to fulfill their commitment as an insurance provider and make their policyholders whole. At the same time, digitization helps insurers preserve costs, reduce calls to their office and get vendors paid quickly. 

See also: The Need for 'Digital Fluency' in Insurance

An eye toward the claimant

Stressful and frustrating experiences while attempting to access disbursements, either individually or as part of a multiparty claim, damage policyholder satisfaction. This, in turn, threatens retention. What’s more, the lack of paperless disbursement options could affect an insurance company’s ability to attract new policyholders, perpetuating a vicious cycle.

High customer churn can also add stress for already overwhelmed employees in an industry facing a workforce shortage. When the severity and frequency of claims increase, they impair insurers’ ability to retain talent, leading to smaller teams with more work. Switching to digital outbound payments delivers claimants their ideal payment experience and thus improves their satisfaction. At the same time, it improves expense ratios. These solutions can also make it easier to meet security compliance requirements.

The gap between customer preferences and the current outbound payments market represents a significant opportunity for insurance innovation. Luckily, next-generation solutions are available in the market to bridge this gap. Facilitating a transition to paperless disbursements creates a positive experience for policyholders, which is especially crucial in an industry with so few customer interactions. While it’s true that most people hope not to use their insurance policies, providing flexible digital options can go a long way toward improving the experience of those who do. 


Julie Schieni

Profile picture for user JulieSchieni

Julie Schieni

Julie Schieni is VP, financial services, at InvoiceCloud.

She has over 25 years of experience in insurance and information technology. She has held leadership positions in software companies and property and casualty insurance carriers.

Dialogue as the Departure Point to Action

A recent session shows how convening leaders of at-risk communities can help provide them the tools they need to tackle climate change. 

Group of People on a Conference Room

Convening. It’s not a word I generally like; probably because too often the convening seems more important than the convened. Turns out there’s a discipline to convening, and if done with forethought and rigor it can create the atmosphere and context for meaningful dialogue.

That was the case a few weeks back when I was part of convening a dialogue with at-risk/in-need communities – and those who support them – about the types of climate risk data and analytics they could access and deploy. Sponsored by the North Carolina Office of Resilience and Recovery and the Nicholas Institute for Energy, Environment and Sustainability, the workshop included about 40 state and local leaders, all of whom shared a passion for protecting communities exposed to climate risks. They also shared a healthy skepticism of the insurance sector’s role in supporting those efforts.

That skepticism is justified, as insurers struggle to elevate individual-level risk behavior incentives to the community level and rarely engage communities directly to discuss the complexities of these issues or explore joint solutions. It’s just not what we typically do.

This gap between what communities have and what they need became evident when a veteran risk engineer explained the suite of offerings for a large corporate client, including detailed engineering reports, insightful benchmarking, sophisticated scenario mapping and creative risk transfer solutions. As you can imagine, the community representatives were impressed – and perhaps a little envious – of the breadth of analytics available to large corporate firms. 

See also: Biggest Business Trends for 2024

But these communities have their own needs, like understanding if and how certain risk-reduction efforts meet ever-shifting social justice, fiscal and economic expectations. Communities need a tool that can credibly run countless scenarios and help leaders make risk-informed decisions: seawall or nature-based solution; five-year time scale versus 20; prioritize protection for lower-income dwellings or the commercial district; go it alone or align regionally. In other words, what they need is a crash-test dummy for climate risks. 

Fortunately, several tools are emerging that could serve as climate risk versions of IIHS’s auto-safety crash test dummies. One, called IN-CORE, has been 10 years in the making through a NIST-sponsored research center led by Colorado State University. The computational model builds on many local data sets and peril-specific algorithms to provide a snapshot of how a particular risk will evolve under a chosen IPCC scenario, with or without particular mitigation interventions. The model also generates economic impact assessments of the event and a socio-economic breakdown of affected residents. 

Such a tool could easily become the basis for grant-writing, bond issuances and other adaptation efforts. Its greatest value, though, is ensuring risk-aware decision-making. 

See also: Win in the Small and Medium-Sized Business Market

In our particular case, the convening was not the end of the story. It was literally the beginning.  From here, we plan to tap into an existing Duke program where PhD students lead small teams that pursue impact-oriented data and analytical projects to explore how we could make IN-CORE or something like it relevant and accessible to at-risk communities. As the fall semester begins, we’ll progress to another Duke program and unleash a diverse cohort of 10 students to investigate how these tools can best help individual communities, and to test the feasibility of innovative models like Community-Based Catastrophe Insurance and Nature-based risk solutions.

The pilot aims to support a few North Carolinian communities in using the new tools and then to scale the approaches that create the most value.

All this started with a convening. Not among insurers, but among local leaders and technical assistance providers who ultimately will make the decisions that will shape the property cat market for decades to come. In fact, the entire event occurred in collaboration with the Southeast Navigators Network, a Walmart Foundation-funded campaign run by the GEOS Institute to provide meaningful support to low-income communities recently designated as Community Disaster Resilience Zones. 

Is all this unique to the academic world? Of course not. But unlike many of us in the corporate world, those in the academic world are good, active listeners who are trained in pursuing insights without bias. That objectivity and subject matter expertise make a difference, particularly in dialogues where trust may be an issue.  

So next time you’re convened, make sure you start with a foundation of discipline and rigor – and be ready to make progress through difficult conversations. Otherwise, you’re just in another meeting. 

Climate and Catastrophe Risk Strategies

In the face of what the U.N. calls a "code red," here are three strategies that property and casualty insurers should immediately undertake. 

White Clouds above water

A recent Wall Street Journal headline declared, "Climate Change Is Breaking Insurance." Earlier this year, in congressional testimony, the president of Aon said climate change is inducing "destabilization" within the insurance industry.

Total insured losses from weather-related natural catastrophes surpassed $122 billion last year, as reported by Swiss Re—markedly exceeding the historical average. In the 1980s, the U.S. witnessed severe weather events that caused over $1 billion in losses every four months. According to the U.S. National Climate Assessment report, this frequency has escalated to once every three weeks.

The U.N. Environment Program called severe weather events a "code red" emergency for the world.

Amid these mounting concerns about the repercussions of climate risks, the question arises: How can insurers fortify themselves against this challenge? How can they develop strategies to identify and mitigate climate and extreme weather risks?

While insurance inherently deals with risk, the escalating perils of climate change underscore the industry's imperative to embrace technological innovation for effective risk mitigation. Here, we offer three immediate actions that property and casualty insurers can undertake. The encouraging news is that, in doing so, insurers have the potential to not only mitigate their own risks but also to contribute to the greater challenge of mitigating climate risks for communities, consumers and the world.

See also: How AI Can Help Insurers on Climate

Action Item #1: Rethink Risk Assessment

Insurers can start this journey by rethinking their risk assessment processes. A report by McKinsey recommends that insurers use their annual policy cycle and their understanding of evolving risks to reprice and rearrange portfolios to avoid long-term exposure to climate events. 

There is just one problem: Insurers typically rely on historical data to calculate that future risk. But the climate system the industry has operated within over the past century is now gone. Traditional models and loss experience just will not cut it any more.

Today, insurers need a far more current and accurate understanding of risk to price it profitably or avoid it altogether. Geospatial analytics is one technology that can help. When integrated with an insurance platform, for instance, solutions from companies like Betterview (recently acquired by Nearmap) and Cape Analytics leverage aerial imagery, computer vision and predictive analytics to assess property risk instantly and on-demand.

HazardHub also analyzes and distills data from national sources to catalog risks that may damage or destroy property. It returns a risk score that insurers can use to determine whether they have an appetite for a risk and under what conditions.

To price and fund risk accurately, McKinsey says the industry will also need to invest in technologies that help them understand the cascading effects of specific climate hazards on different sectors and geographic areas. Even when insurers decline to cover a specific property or facility, natural catastrophes that cause damage to infrastructures and supply chains can still affect those they do. According to Swiss Re, these knock-on effects could sap $23 trillion from the world economy by 2050.

Action Item #2: Deliver Innovative Products

McKinsey says climate change also offers insurers an opportunity to create innovative insurance products to cover newer and more frequent hazards, both acute (such as wildfires) and chronic (such as reduced crop yields).

Case in point: parametric insurance. Unlike traditional insurance, parametric coverage provides payment based on a triggering event (hurricane, earthquake, wildfire, drought) of a set magnitude, instead of the value of physical assets. Technologies like those from Plover Parametrics and Demex enable insurers to manage parametric insurance while helping corporations identify and transfer risks to pre-certified carriers that act as “shock absorbers” for the threats emerging from climate change.

According to consultancy Marsh McLennan, parametric cover is particularly useful when there’s a lack of capacity or appetite from traditional insurance markets—especially where business interruption losses from a weather-related event are greater than the value of physical assets. For insurers, it’s an efficient way to not only mitigate risk but streamline CAT response by automating payments at the exact time when the volume of claims being filed could overwhelm capacity.

See also: Property Underwriting for Extreme Weather

Action Item #3: Help Businesses Mitigate the Risk to Us All

The U.N. report is dire, concluding that there’s virtually nothing that can be done to avert the climate-related disasters caused by the 1.5° C increase in average global temperature expected over the next 20 years. But it’s not too late for nations and industries to drastically curb carbon emissions to stop temperatures from climbing even higher. The insurance industry can play a pivotal role.

New forms of pay-as-you-drive and usage-based insurance (UBI) policies, for instance, leverage smartphone-based telematics to reward consumers for driving less. According to Allied Market Research, the usage-based insurance market is expected to reach almost $150 billion by 2027, with 25% yearly growth. This kind of coverage can be used to encourage the deployment of autonomous electric buses and trucking fleets that platoon to make transit safer and more efficient.

In fact, insurers can encourage companies through more than just underwriting. According to Insure Our Future, the insurance industry is the second-largest institutional investor in the world. Allianz, Aon, AXA, Munich RE, Zurich and other major insurers are making strides in environmental, social and governance (ESG) commitments to carbon neutrality in their own operations, as well as the companies and funds in which they invest. Other insurers should follow suit.

From Risk to Resilience

The "code red" emergency necessitates immediate action from insurers, not only to fortify themselves against escalating risks but also to contribute altruistically to the broader goal of mitigating climate change risks for communities and the world.

In navigating this ever-evolving landscape, insurers must initiate a fundamental reevaluation of their risk assessment processes, acknowledging the inadequacy of relying solely on historical data in the face of rapidly changing climate dynamics. Adopting technological innovations, including geospatial and predictive analytics, becomes paramount in acquiring a more current and accurate understanding of risk. These strategic measures are essential in addressing the mounting threats posed by climate change and extreme weather events, marking a significant step toward industry resilience and global risk mitigation efforts.

However, it is crucial to recognize that, while urgently necessary, the trio of action items outlined here cannot single-handedly resolve the multifaceted threat posed. A collaborative approach involving national governments, public awareness campaigns, regulatory mandates and more is imperative. Only through concerted efforts can we mitigate a situation already destined to be challenging. The insurance industry's commitment to technological innovation and risk mitigation serves as a vital component of a collective endeavor aimed at addressing the complex challenges presented by climate change.