Download

How CRM Can Personalize Insurance

Today's insurance CRM solutions capture customer data, likes, dislikes, preferences and more so insurers can finally realize their personalization goals.

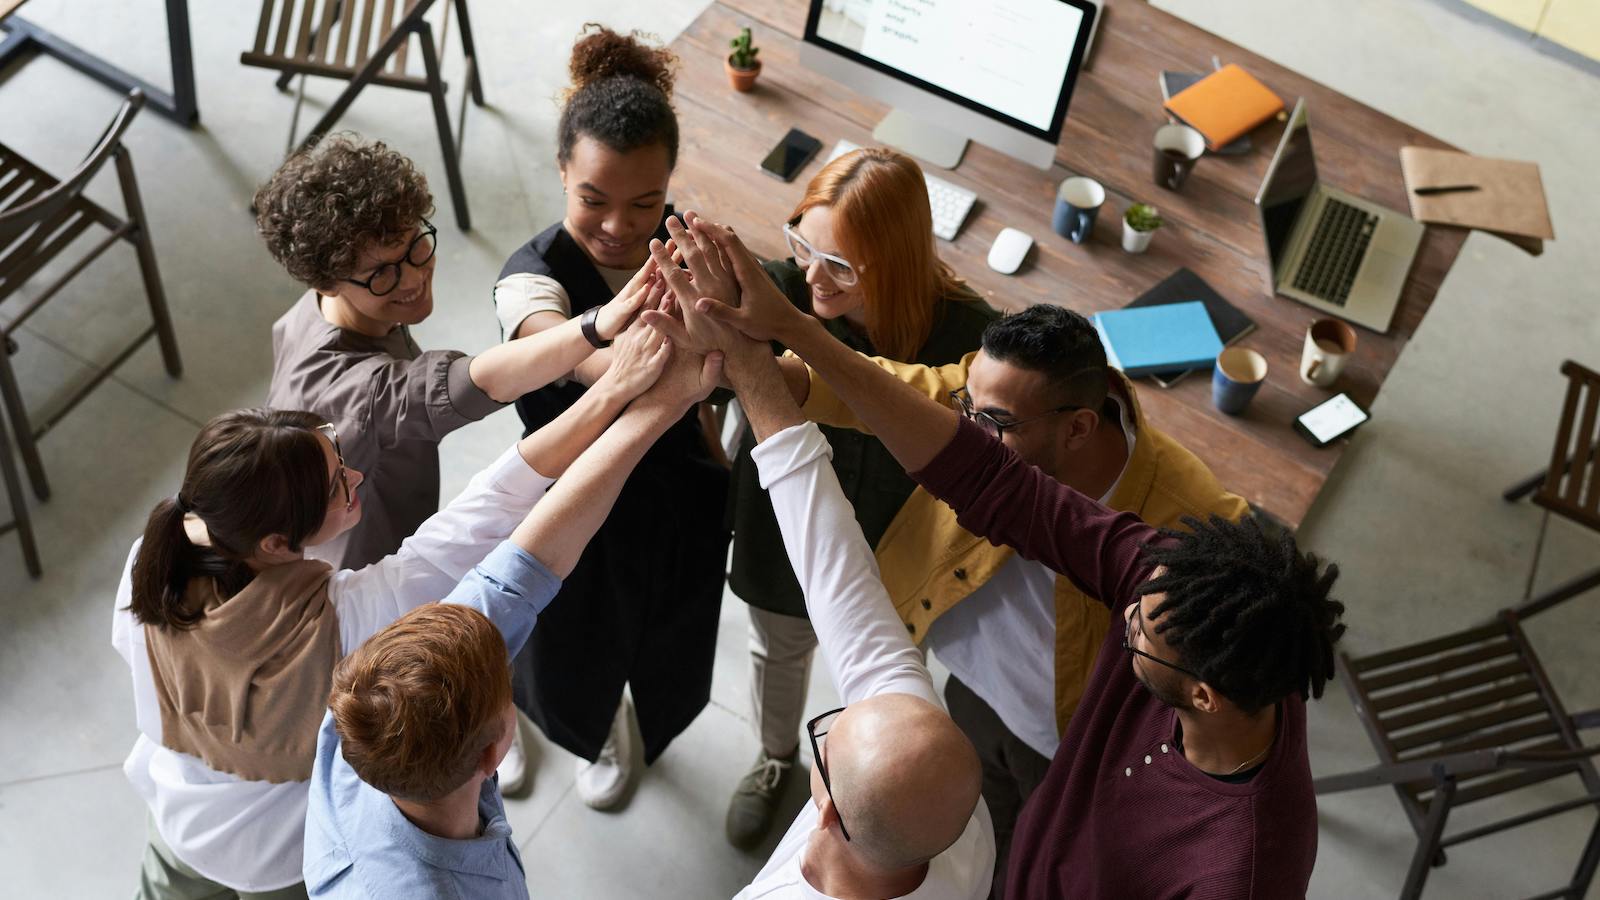
Photo Of People Holding Each Other's Hands

About seven out of 10 customers expect personalization from businesses they transact with. Delivering on this front promises higher customer loyalty, increased revenue, greater trust and ramped-up customer satisfaction. However, when dealing with a data-intensive industry such as insurance, organizing customer data is a major challenge. Insurers have to collect a wealth of structured and unstructured data, organize it and process it to offer personalized policies.

This is where customer relationship management (CRM) platforms can help. While they have been around for a long time, their role in the insurance industry continues to evolve. Today, insurance CRM solutions are the backbone of personalization. They capture customer data, likes, dislikes, preferences and more so insurers can finally realize their personalization goals.

Here’s a look at the role of CRM insurance services in closing the personalization gap.

See also: How to Customize Insurance for Gen Z

Deliver Seamless Omnichannel Experience

An omnichannel presence powered by CRM in insurance is a shortcut to personalizing customer interactions.

How?

Different customers have different preferences when contacting their insurers. For instance, 28% of seniors and 67% of millennials prefer online modes. Even within the realm of online interactions, the mode varies. The older generation would prefer emails and ticketing systems, while the younger ones would demand to be serviced via live chat or even social media.

Establishing an omnichannel presence ensures that your insurance business can cater to your clientele’s communication preferences. Even if the customer were to switch platforms, the experience would remain seamless, continuous and personalized. At the same time, with CRM acting as a hub of all omnichannel communications, all the data gets collected at a centralized location, allowing for a 360-degree view of the customer.

Targeted Personalized Messaging

Insurance CRM integration not only allows businesses to reach out or be accessible over the policyholder’s preferred channels, but it also provides for targeted messaging.

Here, the focus lies on embedding increased value into the business outreach messages by personalizing the message. Insurance CRM solutions capture information related to the customer’s demographics, lifestyle, behavioral data and more. Moreover, they allow businesses to categorize customers into segments for targeted messaging. As a result, it becomes easier to deliver personalization at a granular level that goes beyond addressing them by name.

Insurance businesses can leverage customer insights derived from personalized CRM platforms to send highly relevant and timely messages that resonate deeply with the recipients. Such a strategy drives engagement and satisfaction by making the customer experience highly relevant and contextual.

Driving Personalization With Predictive Analytics Using AI

Delivering personalized customer experiences relies on two factors.

One, understanding the customer’s present needs. Two, anticipating the customer’s future needs.

The former lays the foundation for service and product personalization while the latter stretches it over time. Today, most CRM solutions for insurance come equipped with the capabilities of artificial intelligence (AI), which churns out predictive insights into changing market conditions, customer behavior and preferences. The predictive analytics framework is fueled by the data collected onto the CRM, allowing the AI algorithm to forecast customer requirements and customize solutions dynamically.

Moreover, the combination of the two technologies sets the stage for a continuous improvement and continuous learning setup where AI-driven insights enrich CRM data and vice versa.

See also: How AI Can Humanize Insurance

Enhanced Collaboration to Deliver Consistent Service Quality 

Collaboration is often an understated element in delivering personalized experiences across the customer's journey. However, CRM insurance services highlight collaboration's untapped potential by weaving together the different departments and teams in insurance and laying the groundwork for cross-functional collaboration.

To facilitate this, insurance CRM solutions populate a centralized repository for customer information and interaction history. Such a system brings all the teams onto the same page about their understanding of the client. Additionally, it sets up integrated channels for internal communication, such as through team chats and document sharing, to allow teams to work together. This destroys organizational silos or knowledge gaps, allowing teams to make concerted efforts while addressing customer inquiries and resolving their issues promptly and accurately.

In short, customers can expect a universally consistent and personalized experience regardless of the department they interact with.

Automation-Driven Efficiency to Reduce Turnaround Time

Insurance CRM consulting providers often perform a comprehensive assessment of the business model before recommending the best implementation plan. While evaluating your insurance business for operational efficiency, they might discover routine, repetitive or mundane tasks that can be easily automated using CRM.

Insurance CRM solutions can autonomously handle tasks like policy updates, claims processing and customer onboarding, allowing insurers to focus on more complex and value-enriching tasks. At the same time, they offload human resources, allowing for greater scalability, sustainability and productivity.

Having digital process automation (DPA) tools in CRM solutions for insurance expands the applicability of the system, allowing insurers to deliver a rich, branded and automated experience.

Closing Thoughts

Insurance CRM solutions play a vital role in delivering service and product personalization across various facets of the customer journey. Whether it is marketing and outreach, policy underwriting, claims settlement or customer support, every segment of the customer lifecycle will benefit immensely through insurance CRM integration.

Insurers must explore the possibility of using advanced CRM solutions for insurance to make communication omnichannel, personalize messages, predict customer requirements, collaborate internally and harness the power of automation. 

Such an approach will not only help them meet their current customer expectations but exceed them not just now but also in the future. Such tangible benefits will pave the way for a profitable and sustainable insurance business in a highly competitive landscape.
It’s Time to Revitalize Auto Insurance

Telematics is the key, but four obstacles have to be overcome for it to achieve its full potential. 

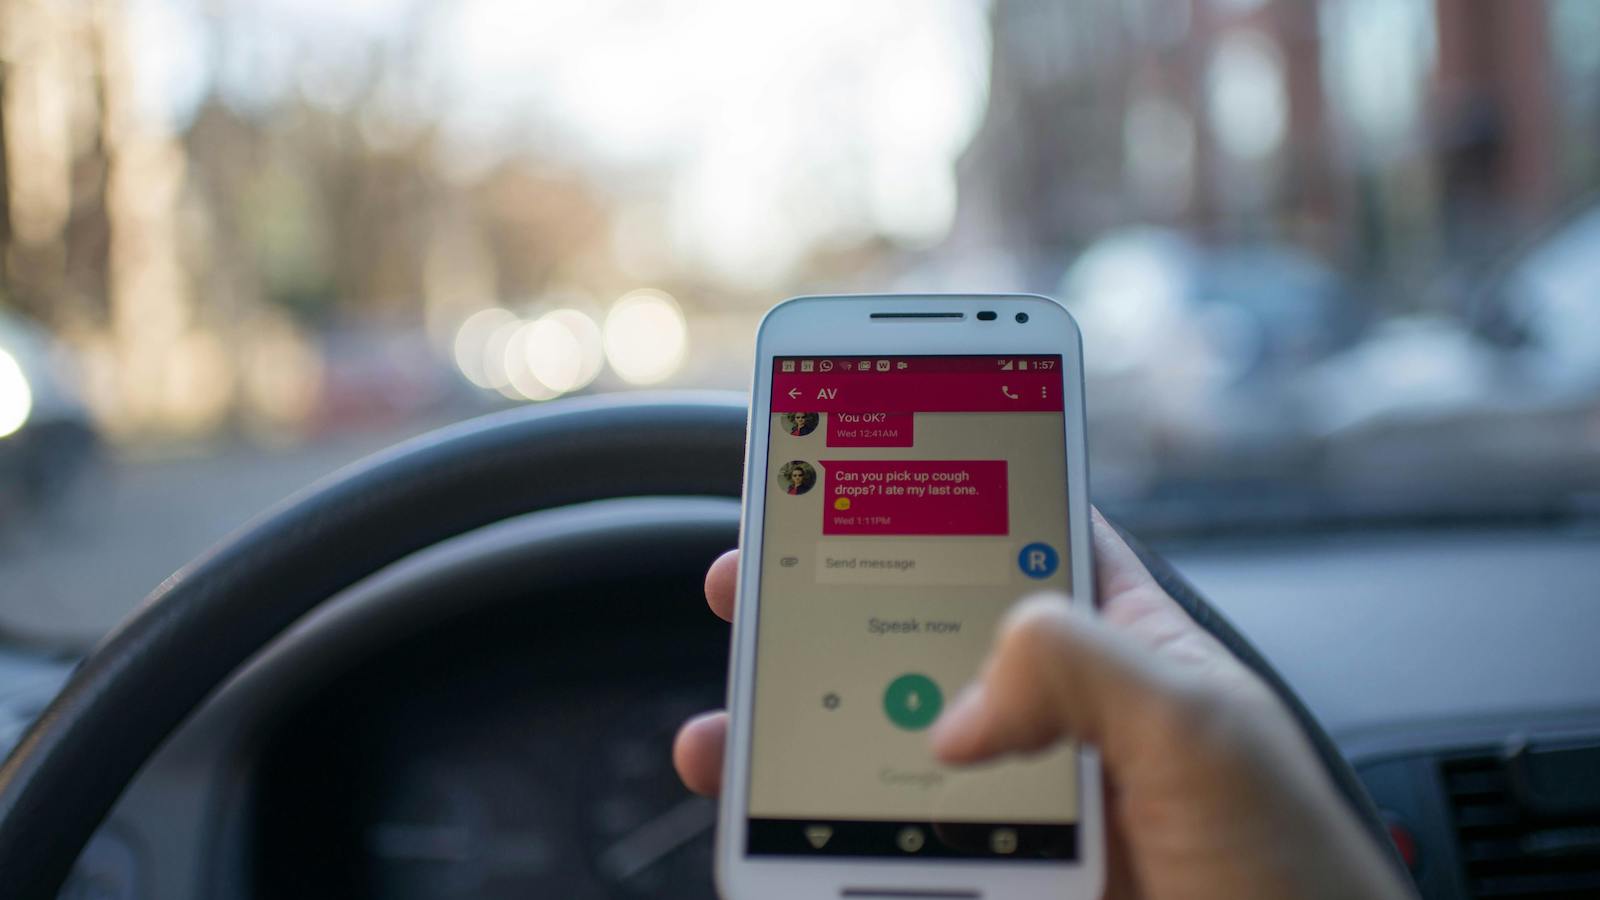
Person Holding White Smartphone Inside Vehicle

Carriers are admitting that this has been the hardest market some have ever worked through, and there’s been a lot of volatility over the last three to four years. Between drivers’ behaviors shifting in a post-COVID world, to higher spikes in frequency, elevated loss cost severity and a sustained increase of inflation, there’s extreme pressure on the sector’s technical sustainability even with a net combined ratio improvement to 105% in the third quarter of 2023 from 112.1% a year earlier.

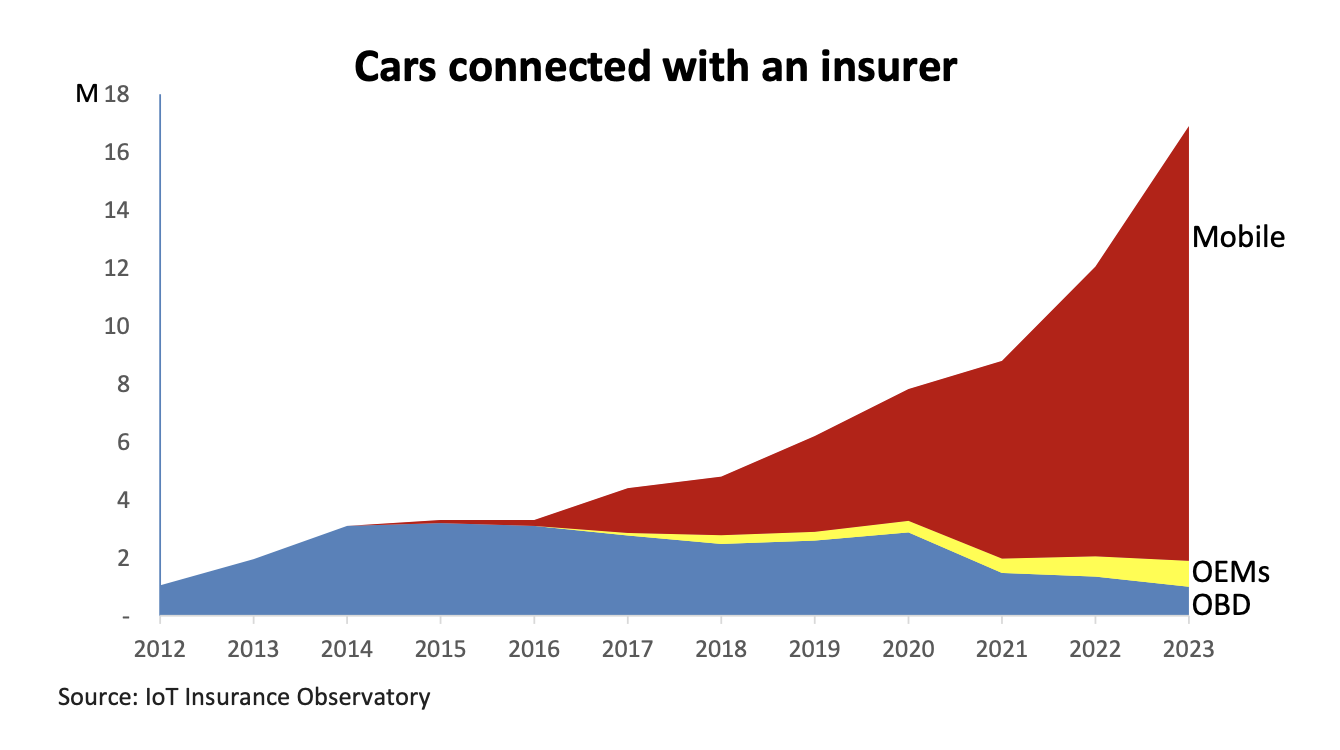
Cars connected with an insurer

Telematics has grown significantly over the past three years, and there is broad consensus among U.S. insurance carriers that the use of telematics is a necessary capability for auto insurers to succeed. However, telematics hasn't made a dent in mitigating these sector issues because it has not yet been used in the right ways. 

See also: Have We Turned the Corner on Distracted Driving?

There are at least four major issues to solve to unlock the full potential of telematics:

  1. Agents aren’t UBI promoters. Their income is a commission on premium: Would you be excited as an agent to sell a product where the only communicated benefit is the potential to reduce insurance premium - and also agent income - by 30% or even more? At the same time, there are many friction points around “selling” a telematics program to new policyholders.
  2. Accurate match between risks and rates only happens at policy renewal after a monitoring period.
  3. Data is mostly used to evaluate risks instead of also helping to reduce them.
  4. Telematics has been used only for new policyholders, versus also offered to a carrier’s existing book of business (limiting by design the number of risks that can be addressed with this innovation). 

In relation to the first point, mastering the usage of telematics data allows the opportunity to unlock a significant amount of value. Carriers should optimize the sharing of this value with both customers and their agents. 

Moreover, carriers need to do a better job at articulating the benefits of telematics to their agents. Insurers should design and execute a structured approach for sharing their vision with their agents about the adoption of telematics and benefits to the agent’s business. Those include the ability to satisfy and retain more policyholders, the ability to offer competitive rates and close more deals for the agency portfolio and the possibility of up-selling many policyholders receiving a discount. 

Insurers should also design processes where agents have visibility into the evolution of the usage of telematics and its related services by their clients. This will allow agents to enhance their relationship with their clients and more effectively do their job. 

Friction points associated with enrolling clients in a telematics program can be addressed through agent training, sales support and straightforward processes for program activation. 

Regarding the second point, the industry has progressively understood the predictive value of telematics. It can have a positive impact on loss ratios, retention and customer lifetime value.

Monitoring the behavior of drivers with a promise of potentially greater savings at renewal, based on how the person drives, is an approach that goes all the way back to the early telematic days that leveraged OBDII dongles in cars. All these years have taught us that telematics represents a significant advancement in the evolution of pricing sophistication. 

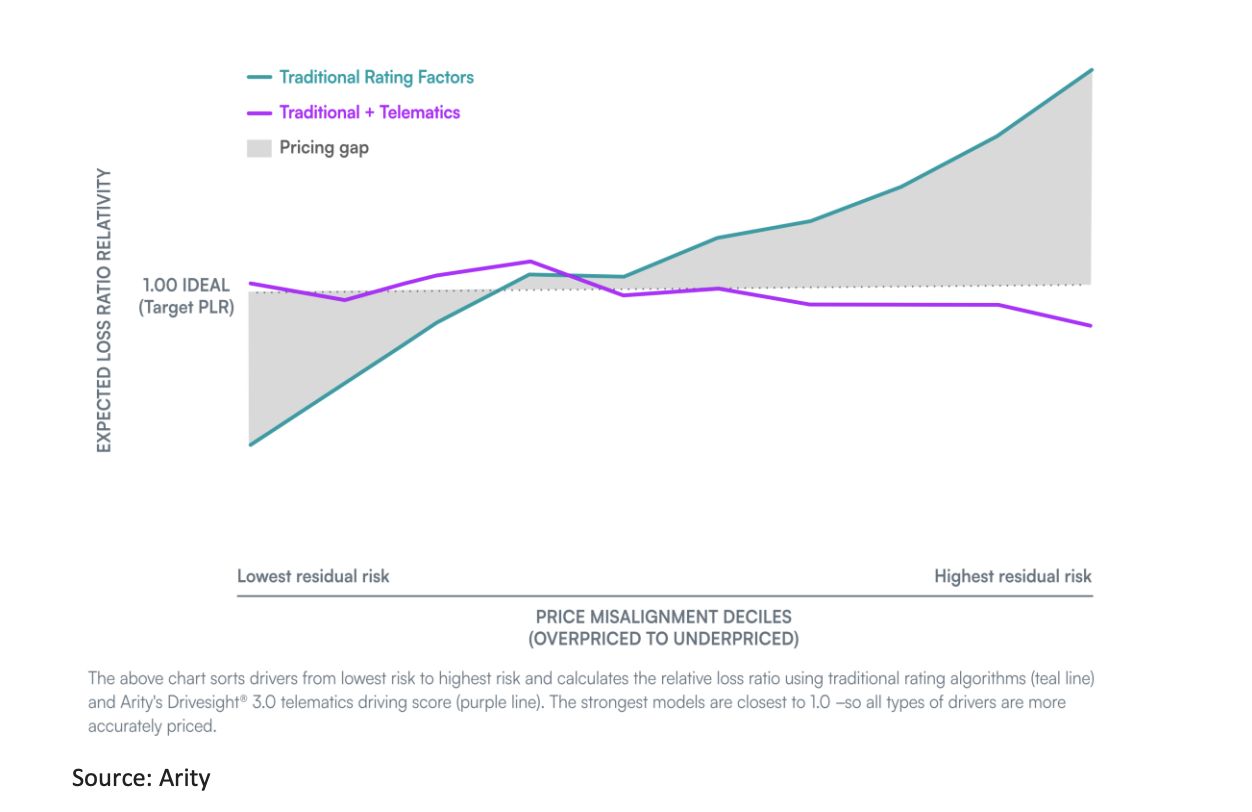
Price misalignment deciles

Telematics enables auto insurance policyholders to receive the best rates based on their driving patterns and vehicle operations (pricing equity). Implementing more precise pricing at each renewal stage across each risk pool defined by traditional variables is enabled by telematics. This strategy entails charging lower premiums for the safest risks and higher premiums for the riskiest ones in each pool. 

The outcome is enhanced customer retention among the best risks and reduction in premium leakage from the riskier pool (if they stay with a carrier). This economic value is necessary to finance both the premium reduction for safe drivers and the telematics program costs.

However, this approach requires monitoring the driver for a coverage period before achieving any benefit from this pricing sophistication. Instead, if the driving score is already available at the point of sale, the insurer is able to better match risks and rates at the time of quote and can attract better risks in each risk pool. 

The evolution of technology facilitates the ability to meet customers where they already are. Consumers already have many apps on their mobile phones that share, with consent, their location data and driving behaviors in exchange for valuable app features and experiences, like crash detection or fuel efficiency. Insurers now have the ability to tap into these consumers and their existing driving behavior history before they even show interest in participating in a telematics program. 

For instance, Arity IQSM network allows insurers to call on existing telematics driving history on tens of millions of drivers to more accurately price customers at time of quote. Much like the way insurers currently request credit information, insurers can obtain near-real-time insights into a customer’s driving behavior at new business. Participation in data sharing for insurance purposes is contingent on consumer consent.

By integrating actual driving data history into the quoting process, insurers can significantly enhance pricing accuracy. This translates into competitive pricing for many drivers and more precise evaluation of higher-risk drivers in each segment; increases customer retention, especially for top-tier drivers; and ultimately improves overall profitability by ensuring that policyholders pay the right premium based on their actual driving risk.

Roads aren’t getting safer - data insights from Arity

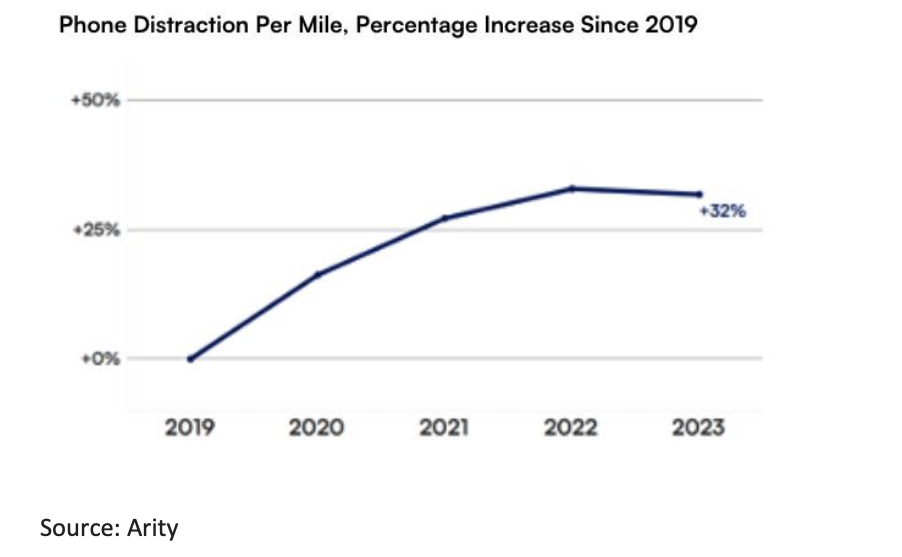
Phone Distraction per mile

Related to the third issue, U.S. roads aren’t getting any safer. Drivers are more distracted, more reckless and more aggressive. More than 40,000 people die on U.S. roads each year, and a lot of the deaths can be attributed to an increase in risky driving behaviors.

We all know that smartphones are contributing to a rise in traffic deaths – it’s the biggest shift in drivers’ behavior over the last few decades. In fact, distracted driving continues to increase year over year. From 2019 through the end of 2023, Arity observed a more than 32% increase in the amount of distracted driving per mile, and recent data shows that it is only continuing to increase. 

Insurance programs that constantly monitor drivers have all the necessary information for improving risks. Instead of using data only to evaluate the risk level of policyholders, insurers can use the driving insights to also promote less risky driving behaviors.

Insurers need to add structured behavioral change mechanisms to their telematics programs to significantly influence behaviors and make roads safer. A 2022 FHWA study empirically demonstrated how frequent and tangible rewards are the most effective elements to nudge drivers in reducing their distraction behind the wheel. 

Finally, in relation to the fourth point, carriers need to move beyond the limits imposed back in the days by OBDII dongles in cars, only making telematics benefits available to new business customers and at renewal. This approach persists today with smartphone-based programs. The societal need to mitigate distraction by introducing structured behavioral change programs would realize its full potential if the usage of a telematics SDK were extended to all policyholders in the portfolio, instead of only making it available to new customers. As Matteo articulated in a recent article, this approach is likely to bring as much as a five-percentage-point reduction of the combined ratio on any auto insurance portfolio.

More broadly, telematics can be strategically leveraged across all insurance core processes – from marketing, to underwriting and point-of-sale pricing, to promoting engagement and loyalty with newly onboarded policyholders and even to supporting customers through crash and claims. 

Arity's multi-year experience has shown that to truly take advantage of the value can have across the entire organization, three things have to be true about telematics data:

  • It has to be available on everyone
    • If a carrier doesn’t have telematics data at scale, they’re leaving valuable opportunities on the table. With the largest telematics dataset tied to actual insurance claims, Arity is working toward connecting to every driver in the U.S. and currently has 3X more driving data than the combined total number of users who are opted-in to a U.S. based telematics insurance program today. 
  • It has to be integrated across the enterprise 
    • This can be measured in two ways. One, penetration – how many drivers an insurer has telematics data on. And two, usage – whether an insurer is using telematics at each stage of the customer journey. Both of these are important key performance indicators (KPIs_ that all insurers should focus on to improve profitability with telematics. 
  • It needs continuous innovation 

Telematics isn’t a one-and-done initiative. Arity has been in the business of collecting and understanding driving behaviors and risks (1.5 trillion miles of driving data and counting) since 2016 – we’ve seen it change. What used to be data collected through plug-in devices has transformed into a lot more data collected through mobile apps and connected cars. And innovation isn’t going to stop there.

Telematics is also about putting the data in context to understand risks more deeply, such as having insight into the types of roadways traveled, the posted speed limit of road segments and the interaction between driving events such as distracted driving and hard braking. Arity’s data shows that if a driver is talking on their phone while driving and immediately follows that with a hard braking event, the potential insurance cost of such an incident is typically 60% higher. That’s powerful insight. And the ability to deliver such insights at scale is critical. Solutions like Arity IQ are enabling insurers to continue to trailblaze telematics. 

Better pricing sophistication to match rate with risks and behavioral change approaches to reduce risk level (especially distraction) are extraordinary opportunities for the future of auto insurance. The insurer of the future, by mastering the usage of telematics data across the insurance value chain, will be able to write profitable business while offering the lowest possible premiums to each policyholder. This will allow many policyholders to pay a lower premium, which will directly improve the availability and affordability of insurance coverage.


Henry Kowal

Profile picture for user HenryKowal

Henry Kowal

Henry Kowal is director, outbound product management, insurance solutions, at Arity, an Allstate subsidiary that tackles underwriting uncertainty with data, data and more data about driving behavior gathered via telematics.

Don’t Get Caught Up in the Buzzwords

In other words, don't "invest in a modern data integration platform that transforms processes and enhances the company’s solution stack."

Thoughtful guy writing in notebook leaning on fence against bridge

Someone entering the industry in a first job capacity could easily be overwhelmed by the “alphabet soup” that is the jargon of insurance. Seriously, what does it mean for a business to “invest in a modern data integration platform that transforms processes and enhances the company’s solution stack”? 

Buzzwords and abbreviations aside, the baseline translation must have real, tangible value. In this instance, the meaning behind the buzzwords is about investing in a solution that speeds digital transformation by operationalizing big data and automating processes for a competitive edge. 

So, yes, even the explanation can sound like a collection of acronyms and abbreviations that explain very little. And insurance companies, agents, brokers, managing general agencies (MGAs), service providers, vendor partners and policyholders alike must be able to make sense of the most commonly used buzzwords and provide a translation that will help even a novice navigate the data integration space. 

Here are some translations:

01: Distributed Cloud

Having come into vogue several years ago, “distributed cloud” is still trending today. This term defines the ability of applications, programs and devices to extract information from images and allows for the organization to unpack and analyze huge quantities of data at speed. It means users get more visibility into data, faster, and the information is both relevant and dynamic. Distributed cloud allows for the deployment of solutions in a variety of environments including private cloud, public cloud or a combination of environments. An investment in distributed cloud can help speed innovation by making data accessible to the right people in the right place at the right time.  

See also: 10 Innovations Transforming Claims

02: API Management

Another term that is dominating headlines and conversations is API (Application Programming Interfaces) Management. It’s a term that has not really come with a detailed explanation as to what it is, how it works or why it’s important. To understand this term, it is important to first understand what an API is. Simply put, APIs are the software translators that ensure two applications can talk to one another seamlessly. Data integration hubs that offer API management capabilities are designed to assist in creating, publishing, documenting and analyzing APIs in a secure environment. Today, APIs are everywhere, in every device, platform, service and solution. This prevalence alone makes API management absolutely critical for insurance organizations. 

Using a data integration hub for API management allows for the connection of multiple moving pieces within a business and ensures that every touch point is managed properly and seamlessly. This can be anything from authentication to logging on to authorization to monitoring alerts and beyond. Working with a hub that’s designed to handle specific, unique requirements will ensure rapid issue resolution and manage systems far more efficiently. 

03: Data Automation and Modernization

Business processes are complicated and often manual due to an underlying technology landscape that is not connected, constantly changing and increasingly complex. Automation is the process of unlocking data to create business processes that optimize workflows. Automation is not the final fix of all things broken in a business. Automating bad processes enables organizations to do things poorly, only quicker, which is not exactly a recipe for success. This is why the terms “automation” and “modernization” must work hand in hand. 

Modernization is, quintessentially, moving siloed data from legacy databases to modern cloud-based databases or data lakes. Data modernization allows organizations to be agile, eliminating inefficiencies, bottlenecks and unnecessary data complexities, making business processes easier to improve and automate. As a result, the business can innovate faster, improve customer satisfaction and transform into an analytics- and data-driven organization. 

04: Big Data

A few years ago, big data took the buzzword world by storm, and it is not going anywhere, any time soon. Put simply, big data is larger, more complex data sets, usually from new data sources. This type of data is so voluminous that traditional data processing software is unable to manage it. It’s also complicated and comes with its own fair share of pitfalls and problems. Big data can get old, it can stagnate, it can take up essential space on systems and cost unnecessary money. The right hybrid data integration platform will allow you to gain valuable insights from big data that can be used to address business problems the business wouldn’t have been able to tackle without it.  

See also: Achieving Effective Claims Payments

A True Solution With Tangible Value

A data integration hub fills the data-related needs of insurance organizations, even those fighting to get value from buzzwords. What sets a data integration hub apart from a traditional integration platform is that it provides a variety of data structures, sources and strategies businesses need to manage all data access, movement and storage issues, all in a single unified platform. A hub can drastically reduce the amount of time a development team spends on trying to get a solution stack to integrate successfully. It also offers pre-defined connectors that allow for the quick configuration of integration points instead of complex coding, which frees time to focus on more important work. 

Don’t get too caught up in the acronyms and buzzwords. While it is easy to move from shiny object to shiny object based on what’s hot at any given moment, a technology solution must have tangible value to deliver to an insurance organization to be truly effective. 

Decoding the Talent Exodus in Insurance

Here’s why I believe the insurance industry should look at the exodus of underwriting talent as an opportunity instead of a crisis. 

People In White Suits Standing Near Black Wall

“I’d rather stick needles in my eyes than be in something as boring as insurance.”

Veteran insurance adviser Tony Tarquini was startled when his teenage son recently dismissed a career in insurance. With as many as 400,000 employees expected to retire from the insurance industry in 2026, the talent crisis seems apparent but also presents a tremendous opportunity.

During the third session of Send’s webinar series ‘INFUSE - Finding, and Keeping, the Best Underwriting Talent,”  industry experts joined me to discuss what we believe is a transformative era for underwriters.

My fellow panelists Georgi Munger, global head of MidCorp Casualty & Underwriting Practices at Allianz, and Caroline Bedford, chief executive at EDII, discussed talent acquisition, retention and succession strategies that could define the underwriting landscape for the next decade.

Here’s why I believe the insurance industry should look at the talent exodus as an opportunity instead of a crisis. 

See also: Overcoming the Talent Crisis in Underwriting

We’re not alone

Today, every industry is facing a massive loss of talent due to an aging workforce. Sectors in education, healthcare and construction are on the brink of a talent exit, as well. This attrition cycle leaves us all with an opportunity to partner with each other to develop alternate strategies. Whether that means early careers programs, career change programs or succession pathways, there are solutions that we can share to learn from each other. 

Companies that evolve traditional human resource policies, augment hiring strategies and develop succession pathways with their existing workforce are the ones that will become a talent acquisition or retention case study for the decade.

Attract talent with purpose and pay

Today, underwriters are seeking a more holistic approach to complement their career paths. To support this, underwriters must be offered growth and professional development opportunities in addition to simply financial compensation. During Send’s INFUSE webinar, Munger said Allianz went a step further and paid their new underwriters to learn everything about underwriting for a year while not presenting conflicting expectations. This gives fresh talent the confidence to explore their skills and develop faith in the organization. These innovative offers for work-life balance and skills development are resulting in a steady inflow of fresh talent looking to join the industry.

Nurturing underwriters

Attracting talent is easy. Retaining and nurturing talent into specialist roles is the challenge. Whether it’s technical training or soft skills, it can take years before underwriters gain the right business acumen for what is a complicated and complex industry. It’s important we involve the retiring workforce in the organization’s talent succession strategy. Veteran underwriters can have a huge influence by transferring years of underwriting knowledge and skills such as risk assessment, negotiation and data literacy. Several carriers have started to include "talent onboarding" as a part of the job duties for senior underwriters. This will certainly help inspire and retain underwriting talent.

See also: The Next Generation of Talent

AI is empowering talent transition

AI-driven large language models are changing how underwriters perform their roles, with the ability to reduce manual data entry underwriters would have previously had to sort through. AI can also help facilitate faster information and knowledge transfer about policy coverages, underwriting rules and industry terminology during the onboarding of new talent. For newer policy models, AI also can help retrieve the latest data and expedite their education during the onboarding process by giving them almost immediate access to the information a new hire needs to come up to speed quickly and efficiently.

This helps new hires improve their skill sets, increase their data fluency and elevate their data literacy. 

We’re confident that underwriters can anticipate a paradigm shift in employer expectations as more insurers work to instill a future-centric approach, with a stronger emphasis on upskilling and sustained adoption of AI.

At Send, we believe AI and technology are there to enable, not eliminate, the underwriter of the future. We’re here to support the important work of the future underwriters already in the industry, and those not here yet.


Pat Caldwell

Profile picture for user PatCaldwell

Pat Caldwell

Pat Caldwell is the first chief people officer at Send. 

Previously, Caldwell held a number of senior executive, board and advisory roles helping technology startups build and scale their people functions in the U.S., U.K. and Australia. He is formerly the COO and head of people at FundApps and is currently on the board at ImpactEd.

How Agents Should Respond to Embedded Insurance

While embedded insurance may offer a quick solution, it lacks the personalized service and tailored coverage that independent agents can provide. 

Black Pen Placed on White Paper

The year is 1925, and in a lobbying campaign so bold that it would make modern players blush, lawyers for Chrysler and Palmetto Fire Insurance are attempting to force their new partnership past a slate of skeptical state insurance commissioners and over the threshold of legality. 

The partnership was a first of its kind. Fire and theft insurance, provided by Palmetto, was embedded in the sale of new Chrysler cars. This historic example laid the foundation for a new insurance distribution model that is still with us today. 

Fast-forward 100 years and embedded insurance has evolved from a controversial new concept into a multibillion-dollar source of premium. It has infiltrated, or is predicted to infiltrate, nearly all facets of the insurance industry. While embedded insurance offers much when it comes to convenience, many within the industry view the phenomenon with a healthy level of skepticism, aware of its pitfalls and the threat it poses to their livelihoods. 

For example, when one of us was fresh out of college and interviewing for an insurance internship, the seasoned, slightly grizzled interviewer threw a curveball: “Do you buy insurance or prepaid gas from rental car companies?” Being too young to rent a car, I dodged the question. After an awkward pause, the interviewer revealed a nugget of wisdom — no self-respecting insurance professional would ever purchase embedded insurance products. 

Did he know something we didn’t? As it turns out, the answer was an emphatic yes. 

In this article, we explain what embedded insurance is, how it works and why its convenience can never measure up to the value provided by independent agents. While embedded insurance may offer a quick and easy solution, it often lacks the personalized service and tailored coverage that independent agents can provide. This is a key advantage that agents can leverage in the face of this growing trend. 

First Things First 

Before we discuss how agents can compete in an environment saturated with embedded insurance, we must first define it. 

Embedded insurance, also known as bundled insurance, is a type of insurance coverage packaged with a separate product or service. We’re all familiar with this concept, such as rental car insurance or gap insurance from the car dealer. But now, the scope of embedded insurance is expanding rapidly, with disruptive partnerships like Carvana and Root Insurance shaking up the auto insurance market. Industry leaders like Chubb are even predicting over $700 billion in gross written premium (GWP) for P&C lines by 2030.

Other products combine features of embedded insurance with data analytics to offer discounted rates to insurance buyers. For example, Tesla’s partnership with Liberty Mutual offers “Real-Time Insurance,” a product that uses real-time driving behavior to rate policies. Tesla’s ability to collect and disseminate data to its insurance partners provides a competitive advantage. 

Uber’s foray into embedded insurance threatens commercial lines, a product most of us thought was protected from disruption. Uber drivers, whether they like it or not, automatically receive rideshare insurance provided by Uber. Of course, the coverage is not free, and Uber passes on the costs via reduced rates paid to Uber drivers and increased rates to riders. 

The potential expansion of embedded insurance into other products, like homeowners insurance paired with mortgage loans or even certain commercial lines, poses significant risks to the traditional insurance market. However, it also presents opportunities for those who can adapt to this changing landscape. This is a crucial point for insurance professionals to consider as they navigate the industry's future. 

What It Means for You 

In nearly all cases, embedded insurance removes agents from the purchasing process. The insurance company providing the coverage partners with the business providing a good or service, which offers coverage as an ancillary product. Think about when your apartment building offers you rental insurance. The building owners are soliciting you to obtain the insurance coverage and have incentives to do so because of the protections offered by rental insurance for liability and negligence caused by the tenant. The problem is that the building owners are not licensed agents and cannot properly or legally advise the buyer on what coverage is right for them or even explain the provisions of the policy. 

Is this really what is best for the consumer? Some would argue yes -- the convenience of instantly obtaining coverage related to a product or service outweighs the pitfalls of a one-size-fits-all insurance product. Regardless of our opinions on the merits of embedded insurance, the market is embracing the concept, and the segment is growing. 

Don’t Worry, It’s Not All Doom and Gloom 

Right now, you are probably envisioning a future in which all of your core lines are sold as embedded products and the traditional agent is squeezed out entirely. However, you can set your mind at ease, as customer data still indicates that a large majority of consumers insist on consulting with an agent before purchasing “high stakes” coverage such as home and auto. 

The primary selling point of embedded insurance is convenience. While some consumers may be enticed by the simplicity of a point-and-click purchase, the consequences of inadequate coverage can be disastrous. Hence, the reticence most consumers show in obtaining P&C lines without first consulting with an agent. 

See also: What's Next for Embedded Insurance?

“One Size Fits All” Meets Reality 

In the world of surety, virtually all coverage is the same because the obligee, the entity requiring the insurance, sets the terms of the bond. A $50,000 auto dealer bond is a $50,000 auto dealer bond, no matter where or how you obtain it. 

This is why bond providers' competitive advantages primarily come down to price, ease of issuance, customer service and claims handling. You never see bond companies advertise based on the provisions contained within the policies they issue. Instead, surety companies center their pitches on their capabilities to issue and service your bond book. 

The same cannot be said for other, more traditional lines of insurance. Each policy is unique, and each insured has different risks that need safeguarding against. While product lines such as renters insurance are one thing, adopting the “one size fits all” model of embedded insurance for core lines does a disservice to the millions of consumers who need policies tailor-made to fit their needs. This is a key distinction that insurance professionals need to understand as they navigate the changing industry landscape. 

For the industry veterans reading this article, we're sure you could write entire novels filled with horror stories you’ve encountered throughout your careers of consumers who inadvertently purchased inadequate coverage and had their claims denied when tragedy struck. Unfortunately, purchasers of embedded insurance greatly increase their risk of becoming just another cautionary tale on the importance of doing due diligence when obtaining insurance. While embedded products may be convenient at the point of sale, that convenience quickly flies out the window when insureds realize they purchased coverage that 1) is inadequate and 2) contains clauses and fine print they would have never agreed to had they been advised on the policy specifics beforehand. 

Competing With Convenience 

Will embedded insurance make independent agents a thing of the past? We don’t think so, and you shouldn’t, either. While embedded products are gaining traction and we expect the growth to continue, agents can take steps now to protect their business. 

What can you do? In short, by highlighting the value you provide to insureds, you can draw a stark contrast between the surface-level convenience offered by embedded insurance and the peace of mind of knowing that when the rubber meets the road, your customers will have the coverage needed to recoup their losses.

Focus on Value-added Services 

Offering personalized advice, risk management services and comprehensive coverage options that embedded insurance might not provide helps differentiate you from the one-size-fits-all approach. Emphasizing the value you bring beyond just selling insurance policies will help you retain existing customers and attract new ones. 

Educate Customers 

Many insureds may not fully understand the limitations or coverage gaps in embedded insurance products. As an agent, you educate your clients about the importance of tailored coverage, policy terms and potential risks, helping them make informed decisions. 

Customize Solutions 

Agents can leverage their expertise to craft customized insurance solutions tailored to the specific needs and risk profiles of their clients. This personalized approach can address gaps in coverage that may exist with embedded insurance products. 

Integrate Technology 

Embrace technology to streamline processes, enhance customer experience and offer competitive pricing. Using digital tools for customer relationship management, online quoting and policy management can help agents remain agile and efficient. 

Collaborate 

Collaborate with companies offering embedded insurance to create complementary offerings or bundled packages that provide added value to customers. By forming strategic partnerships, agents can expand their reach and provide comprehensive solutions while maintaining their role as trusted advisers. 

Emphasize Customer Service 

Providing exceptional customer service and support can set agents apart from embedded insurance providers. Being accessible, responsive and proactive in addressing client needs can strengthen relationships and foster loyalty. 

Adapt and Innovate

Stay abreast of industry trends and adapt business models to meet evolving consumer preferences. Agents can explore innovative ways to package and deliver insurance products, such as usage-based or on-demand coverage, to stay competitive. 

See also: Is Embedded Insurance the Wrong Idea?

An Irreplaceable Level of Value 

At the end of the day, no level of convenience can replace the value that agents provide to their customers. While embedded insurance offers much when it comes to simplicity, obtaining the correct coverage demands careful consideration and consultation with a trusted adviser. The consequences of obtaining improper coverage can be catastrophic, and, as we all know, a one-size-fits-all approach simply doesn’t cut it with core lines. 

While trends come and go, the true staying power within the industry lies with the agents and the irreplaceable value they provide to their customers.


David Gonsalves

Profile picture for user DavidGonsalves

David Gonsalves

David Gonsalves is the CEO of BondExchange. 

Before joining BX, he held various management, underwriting and sales positions with both private and public companies in the financial services and insurance industries.

Be Your Own Magic Bullet for Pain Relief

The mantra "there's a pill for every ill" is being replaced by an emphasis on preventative care, fostered through health insurance. 

Close-up Photo of Medicinal Drugs

In 2023, prescription drug use reached unprecedented levels in the U.S. This alarming trend is linked to the "medicalization" of health issues, institutional factors within the healthcare and pharmaceutical industries, an aging population and the increasing burden of chronic diseases. According to the Centers for Disease Control and Prevention (CDC), a staggering 71% of doctor visits and 76% of emergency room visits are related to drug or medication therapy, with analgesics being a primary focus. 

This reliance on medication is rooted in the American healthcare culture, where people are conditioned to view medications as integral to their daily routines. Many are entrenched in a reactive healthcare regime, heavily influenced by media that promotes the idea of taking a pill to cure or treat every ailment. According to the Lowen Institute, this idea has fostered a culture of overprescribing, driven by the fast-paced nature of healthcare, reimbursement models for patient visits and the pervasive social and medical expectation that there is a "pill for every ill." 

This phenomenon is particularly evident in the management of musculoskeletal (MSK) conditions. In the U.S. alone, MSK conditions incur costs amounting to $380.9 billion annually, a figure that continues to rise steadily as the population ages. 

With a growing emphasis on preventive care and holistic wellness, there emerges an urgent opportunity to transform the management of these conditions. . 

See also: How AI Can Lead to Personalized Medicine

To truly become pain-free, we must change the face of healthcare from a reactive to a preventative approach.  

Why is this necessary? Conditions such as arthritis, back pain, neck pain, cancer and muscle and neurogenic pain are the leading causes of chronic pain. These conditions often stem from musculoskeletal issues and can severely disrupt sleep, hinder mobility and diminish quality of life. Muscle pain, a common complaint across all age groups, can range from mild discomfort to debilitating agony, affecting individuals' ability to engage in physical activities and enjoy life to the fullest. 

By focusing on prevention and holistic wellness, individuals can take steps to manage and alleviate pain. This involves embracing lifestyle changes, such as regular physical activity, proper nutrition and stress management techniques. Additionally, incorporating physical therapy and other non-pharmacological interventions can significantly improve outcomes and enhance overall well-being. 

The journey to becoming your own magic bullet starts with recognizing the power of preventative care.

The first steps to becoming your own magic bullet are: 

  • Be Proactive, Not Reactive by taking charge of your health by getting to know your body intimately, especially when it comes to MSK issues. 

  • Take Responsibility for Your Heath and embrace the notion that true wellness starts from within. Resist the temptation to rely solely on quick-fix solutions like pills or supplements. 

  • Stay Active and Stay Heathy regardless of age, gender or physical ability. Everyone has the capacity to engage in some form of physical activity. 

  • Track Your Progress by setting achievable goals and monitoring how you're moving toward them. 

  • Let Your Physician Become Your Partner.

See also: Data Science Is Transforming Public Health

According to Andrew Naber, an industrial and organizational psychologist, the average person spends one-third of their life at work, equating to about 90,000 hours. It is no wonder that health management is gaining traction in the workplace. 

Both self-funded companies and those that are not self-funded are beginning to provide their employees with Wellness Dollars—insurance-provided funds designated for health and wellness initiatives within organizations, often offered at reduced costs or even for free. Interestingly, Wellness Dollars can be allocated for a variety of wellness activities and tools, including gym memberships, wearable devices, live virtual fitness classes and mindfulness and nutritional classes. 

By leveraging these resources, employees can foster a culture of health management in the workplace and continue at home. 

Transformative healthcare is here to stay. We are witnessing an increasing number of companies entering the digital health and wellness space, offering a wide range of services from mindfulness and AI-assisted technology to fitness apps and biometric monitoring. This marks the beginning of a revolution to stay active and stay fit, starting with each and every one of us.

People are becoming empowered to take control of their health. Let's hope that the mantra "there is a pill for every ill" will soon be forgotten, replaced by a holistic approach to well-being.

3 Steps to Weather the Coming Labor Crunch

The time is now for insurance companies to change how they think about hiring, retention and technology.to ensure a strong pipeline of talent.

Ligtning Striking at Nighttime

A three-step plan could help insurance companies fend off the labor shortage bearing down on the industry. 

I was able to share those three steps and some examples of how they are playing out right now at RGA during a recent online event sponsored by the International Insurance Society (IIS).

Watch the event

The U.S. Bureau of Labor Statistics projects that the insurance industry could lose roughly 400,000 workers through attrition by 2026 in the U.S. alone. Most of those departures will come through retirement, the data suggests.

This is a global trend. By 2031, roughly one in three Japanese and Italian workers will be 55 or older, while around a quarter of workers in Canada, Germany, the U.K. and France will hit that mark. Projections show that Asia will account for 62% of the aged population globally by 2050. 

The time is now for insurance companies to change how they think about hiring, retention and technology. Following three basic steps can be effective for insurance companies no matter their size or global footprint. 

As head of RGA Asia Pacific, I'm always thinking about this topic  — to make sure we are building for the next generation and building the organization in a way to attract talent, generate growth and provide opportunities for individuals to flourish. It is something leaders should always have top-of-mind to ensure a strong pipeline of talent for the future.

See also: The Hurricane Forecast Keeps Getting Darker

Step 1: Hire Smart

The first key for insurance companies to thrive in a tight labor market is to seek out the right combination of people to bring into the business. This means seeing diversity in a different light. 

The insurance industry is based on properly assessing risk, and that cannot be done by a homogeneous workforce. 

When we think about how we consider risk, diversity of thought, diversity of experience, diversity in backgrounds and the way that people actually see things through different lenses are all critical. Having people with varying backgrounds is extremely important to ensure we have a robust view toward how we operate our business.

A diverse workforce empowers insurance companies to make better decisions, which is a foundation for financial success. Top talent will go where the success is, lessening the impact of a labor crunch on the companies able to attract them.  

Paul Carroll, editor-in-chief at Insurance Thought Leadership and moderator for the IIS event, echoed these thoughts. He said it is not just a matter of finding bodies to fill seats but rather that we should be finding the right sort of talent to do the necessary jobs.

Step 2: Train Smarter

Hiring the right talent is a great start, but it is far from enough for insurance companies to thrive amid a labor shortage. Successful insurance companies will retain top talent by demonstrating their commitment to individual employee growth.

The best situations are those in which the company benefits from its employees’ talents while employees benefit from new and varied opportunities within the organization. The more we really appreciate that longer-term prospect, the more we generate a mutual degree of value.

RGA offers several programs that enable employees to grow while experiencing different parts of the company and insurance industry. One is an international rotation program that gives employees exposure to RGA’s global footprint. Another is a short-term program in which employees can try out different roles in the organization to see what doing another job is like and if it is the right fit for their career plans. 

These allow people to try new opportunities and understand different perspectives and cultures. The programs are meant to enhance their current role as much as perhaps provide them with a future career path.

RGA also has a talent marketplace in which employees can enter areas of professional interest into a software system that alerts them when related job opportunities pop up within the company. This is a great way for RGA to identify different skill sets and desires while enabling employees to better control their futures. 

Beyond that, there is a reason I list this plan as three sequential steps. The first step of hiring to create a diverse workplace often helps with this second step of retaining top talent. 

When someone enters an organization, they are looking around, and when they see a diverse organization, they realize, “Alright, I'm going to be treated with respect here. I'm going to be valued here. It's safe for me to really go out on a limb and try and make a real contribution to solving this organization's problems.” That gives them the ability to achieve their full potential.

See also: Preparing for a Rough Hurricane Season

Step 3: Embrace Technology

Generative artificial intelligence (AI) is the first tech topic on most business leaders’ minds these days –— and for good reason. AI has the power to transform the industry and make operations more efficient. 

But there is another reason for insurance companies to embrace advanced technology.

The hunger and desire for technology could attract another generation and set of individuals into the industry. We are clearly relying on that to address this labor crunch.

The exact jobs lost to retirement will not necessarily be filled. Rather, new jobs with new skill sets might be more in demand – data analytics, cybersecurity and digital marketing, chief among them. 

Embracing greater work/life balance and work-location flexibility also will be key. The COVID-19 pandemic created a temporary all-remote workforce for many insurance companies. Businesses have learned there is value in in-person collaboration, but to attract new workers the industry needs to adopt a hybrid culture where appropriate. 

The need is to find that balance between how we use technologies and how we continue to develop and maintain that expertise through collaboration. Some of the retention programs and training programs at RGA rely on Zoom or Teams, but at the same time we also realize the importance of that personal interaction of people coming together.

The Path Forward

The way to bridge the anticipated talent gap is to see it as a human challenge, not one of mere numbers. It is not just about filling seats. It is about hiring and retaining the right people and combining them with the right technology to drive growth for both the company and its employees.

That all starts with publicly touting the feeling people get by having the right insurance and leveraging that to attract those looking for a higher calling for their careers. This can serve as a call to action for a new generation of people to join our industry. 

Our purpose statement at RGA is to make financial protection accessible to all. The way we do that is by partnering with clients to create products that deliver that protection – and the peace of mind that comes with it. 

Our message to those we wish to attract to our industry is that they can find a higher purpose working on our team.


Arthur Ozeki

Profile picture for user ArthurOzeki

Arthur Ozeki

Arthur Ozeki is executive vice president, head of Asia Pacific, for RGA. 

Prior to his current role, he served as senior vice president, China and Japan markets, for RGA and for RGAX Asia Pacific. Before RGA, he had more than 25 years of experience in international financial services, having worked in New York, Tokyo and Singapore at major investment banks, including J.P. Morgan, UBS and Macquarie, specializing in mergers and acquisitions. He is a member of RGA’s executive committee.

Ozeki received a bachelor of science (B.S.) in computer science and engineering from the Massachusetts Institute of Technology and an MBA from the University of Chicago’s Graduate School of Business.

7 Key Strategies to Safeguard Property

Risk mitigation is no longer just a nice bonus but instead a critical aspect of a strong insurance application, and crucial to limiting premium increases.

Aerial View Photography of Houses

Weather-related disasters are happening more often and with greater intensity, driving up the costs of insurance claims and property valuations, often leaving real estate owners with insufficient coverage.

This year, homeowners should anticipate a 6% increase in insurance rates during the 2024 renewal period. This boost comes after a significant 20% average annual increase from 2021 to 2023, caused by inflation and the rising frequency of severe weather events. By year-end, the rise will push the national premium rate average to $2,522 a year. Given climate experts’ anticipation of a severe hurricane season, projections indicate that home insurance expenses will climb even further in 2025.

For this reason, property owners are also facing higher deductibles and lower coverage limits, and some insurance providers are pulling out altogether from high-risk markets such as Florida and California, where weather related losses are highest.

What can individuals do?  

In the past, risk mitigation measures such as smoke detectors and security systems could earn property owners modest discounts. Today, these measures are often mandatory for eligibility. Risk mitigation is no longer just a nice bonus but instead a critical aspect of a strong insurance application, and the costs of insuring individuals who don’t properly mitigate risks will be substantially higher.

A sharp increase in nuclear verdicts — large settlements awarded to plaintiffs in liability lawsuits — has led insurance providers to reassess their risk exposure across different policies, including auto insurance. Now, insurers are giving more importance to risk management strategies they want policyholders to implement, like taking defensive driving courses, using vehicle safety technologies such as automatic emergency braking systems and implementing best practices within and around a property. It’s important for insurers to inform property owners that, in addition to being financially responsible for damage that occurs to their home or vehicle, they may be responsible if a guest gets hurt within their property, as well.

Relying solely on insurance for risk protection is no longer adequate for individuals or businesses. It’s essential to address and mitigate asset vulnerabilities through a combination of risk strategies and technology. This approach positions the property owner as a desirable, low-risk entity, with insurance serving as an additional layer of protection rather than the sole safeguard.

See also: Property Underwriting for Extreme Weather

Here are some ways agents and brokers can help clients better manage and navigate premium increases:

  1. Evaluate the property’s risk profile. This entails a comprehensive cost-benefit analysis of various factors to determine the level of risk associated with insuring a property adequately and consideration of alternative options. This assessment typically includes reviewing the property’s location and susceptibility to natural disasters, such as floods, earthquakes and wildfires. An open discussion surrounding the home or vehicle owner’s lifestyle and habits, such as regular maintenance of the property, previous insurance claims and adherence to safety guidelines, also plays a crucial role in evaluating their risk profile. By examining these factors in detail, insurers can tailor insurance coverage and premiums to accurately reflect the property owner’s risk exposure, ensuring comprehensive protection against potential hazards.
  2. Encourage owners to maintain property perimeters. Each state and insurance provider maintains a list of recommended property maintenance tasks that can yield substantial benefits for property owners. Brokers and agents have an obligation to share that information with property owners so they can contend with potential risks. Tasks such as clearing vegetation around the property can reduce fire risks, while upgrades such as better-quality windows and roofs increase safety and qualify owners for premium discounts. Routine inspections inside and outside the property — including vehicular property — can catch issues such as damaged roofing shingles or a nail stuck in a tire before they escalate.
  3. Implement and use surveillance technology. Clients should be encouraged to invest in smart home technology systems. Today’s systems can monitor more than water, providing real-time data on security, environmental conditions and utility consumption. That information can help carriers assess a property’s risk and demonstrate the owner’s vigilance. Modern technology surpasses standard monitoring by identifying hazardous situations such as electrical arcing within walls, which can lead to fires. Staying informed and ensuring up-to-date electrical wiring is the most effective method to prevent such incidents.
  4. Beef up the property’s security measures. Over a third of burglaries in the U.S. occur without forced entry, emphasizing the importance of securing entryways. Neglecting to lock doors, whether for a vehicle or a home, can lead to significant and unnecessary losses, especially when valuables such as watches, electronics and jewelry are left in plain sight. Insurers should tell their clients to prioritize the security of their properties and vehicles, taking into account the ease of unauthorized access, assessing not only basic door locks but also the type of locks on doors and windows for added security. Property owners also should be encouraged to consider using impact glass for protection against both severe weather and intruders and investing in heavy-duty, indestructible safes for valuables.
  5. Address cybersecurity risks. The increase in cyber threats, such as compromised social media profiles and hacked bank accounts, requires strong cybersecurity measures such as monitoring applications, parental controls and cyber insurance to help prevent reputational damage and financial losses. In addition, encouraging the practice of good cyber hygiene by being vigilant about passwords, logins, cookies, viruses, suspicious links, phishing attempts and more, and double-checking suspicious online requests can reduce an insured’s risk.
  6. Prevent water damage before a leak turns into a flood. Water-related incidents and freezing claims account for nearly 20% of home insurance claims. Water damage typically starts with leaky pipes, appliance malfunctions, roof leaks or foundation cracks. Encourage your clients to use water monitoring apps with smart technology to help detect abnormal water flows and alert homeowners promptly to help avoid claims. Installing leak detection systems and strengthening plumbing infrastructure can significantly reduce water-related damage, but stressing the importance of paying attention to early warning signs like a leaking hot water heater is also crucial.
  7. Assess driving records. Despite advancements in vehicle safety features, human error remains a significant factor in auto incidents. Help insureds reduce accident risks by prioritizing driver education, which can help establish responsible driving habits, such as using turn signals, avoiding distractions and preventing DUIs. Encourage client use of route optimization apps to avoid traffic (and construction) and minimize distractions. Clients need to be aware of their own driving habits as well as those they share the road with.

See also: Rethinking Property Insurance

Navigating the evolving risk landscape requires a strategic approach to asset protection — and an insurer that knows how to guide and help clients. Helping insureds establish smart risk mitigation practices can optimize their risk profile to secure what matters most — their homes, cars and the people who enjoy life in them.

Global Shipping Losses Hit All-time Low

However, vigilance is required because the speed and extent of the way the industry’s risk profile is changing is unprecedented in modern times.

Boat in Body of Water

Given that as much as 90% of international trade is transported across oceans, maritime safety is critical. Thirty years ago, the global shipping fleet lost around 200 large vessels a year. This total fell to a record low of 26 in 2023, a decline of more than one third year-on-year and by 70% over the past decade. However, the fact that shipping is increasingly subject to growing volatility and uncertainties from war and geopolitical events and the consequences of climate change, as well as risks resulting from the trend for larger vessels, means the sector will have its work cut out to maintain this status quo in future, according to marine insurer Allianz Commercial’s Safety and Shipping Review 2024.

The speed and extent of the way the industry’s risk profile is changing is unprecedented in modern times. Conflicts such as in Gaza and Ukraine are reshaping global shipping, affecting crew and vessel safety, supply chains and infrastructure, and even the environment. Piracy is on the rise, with a worrying re-emergence off the Horn of Africa. The disruption caused by drought in the Panama Canal shows how the changing climate is affecting shipping, all at a time when it is having to undertake its most significant challenge: decarbonization. 

Southeast Asia emerges as maritime region with highest total losses

During 2023, 26 total losses were reported globally compared with 41 a year earlier. There have been more than 700 total losses reported over the past decade (729). The South China, Indochina, Indonesia and the Philippines maritime region is the global loss hotspot, both over the past year and decade (184). It accounted for almost a third of vessels lost last year (eight). The East Mediterranean and Black Sea ranks second (six), with activity up year-on-year. Cargo ships accounted for over 60% of vessels lost globally in 2023. Foundered (sunk) was the main cause of all total losses, accounting for 50%. Extreme weather was reported as being a factor in at least eight vessel losses around the world in 2023, with the final total likely higher.

The number of shipping incidents reported globally declined slightly last year (2,951 compared with 3,036 in 2022), with the British Isles seeing the highest number (695). Fires onboard vessels – a perennial concern – also declined. However, there have still been 55 total losses in the past five years and over 200 fire incidents reported during 2023 alone (205). Fires remain a key safety issue on larger vessels given the potential threat to life, scale of the damage and the fact that associated costs can be severe, a factor contributing to the long-term increase in the cost of large marine insurance claims.

Consequences of geopolitical conflicts

Recent incidents, such as in the wake of the conflict in Gaza, have demonstrated the increasing vulnerability of global shipping to proxy wars, disputes and geopolitical events, with more than 100 ships targeted in the Red Sea alone by Houthi militants in response to the conflict. Disruption to shipping in and around the region has persisted and is likely to remain for the foreseeable future. The re-emergence of Somali pirates, following their first successful hijacking since 2017, is an additional cause for concern.

Both the war in Ukraine and the Red Sea attacks have also revealed the increasing threat to commercial shipping posed by new technology such as drones, which are relatively cheap and easy to make, and difficult to defend against without a large naval presence. Looking to the future, more technologically driven attacks against shipping and ports are also a distinct possibility. Reports of vessels experiencing GPS interference are increasing, particularly in the Strait of Hormuz, the Mediterranean and the Black Sea.

The report also notes that in the two-plus years since Russia invaded Ukraine the gradual tightening of international sanctions on Russian oil and gas exports has contributed to the growth of a sizable "shadow fleet" of tankers, somewhere between 600 and 1,400 vessels. These are mostly older, often poorly maintained vessels that operate outside international regulation, often without proper insurance. Vessels have been involved in at least 50 incidents to date, including fires, engine failures, collisions, loss of steerage and oil spills. 

See also: Emerging Risks for Shipping Industry

Rerouting brings risks and environmental challenges

Attacks against shipping in Middle East waters have also severely affected Suez Canal transits – down more than 40% at the beginning of 2024 – and trade. Coming so soon after the disruption caused by drought in the Panama Canal, this amounts to a double strike on shipping, causing yet more issues for global supply chains. Whichever alternative routes vessels take, they face lengthy diversions and increased costs, also affecting their customers. Avoiding the Suez Canal adds at least 3,000 nautical miles (over 5,500km) and 10 days sailing time, rerouting via the Cape of Good Hope.

Rerouting also affects the risk landscape and the environment. Storms and rough seas can be more challenging for smaller vessels used to sailing coastal waters, while infrastructure to support an incident involving the largest vessels, such as a suitable port of refuge or a sophisticated salvage operation, may not be available. Environmental gains may be lost as rerouted vessels increase speeds to cover longer distances. Red Sea diversions are already cited as being a primary contributor to a 14% surge in emissions in the EU shipping sector this year.

See also: The End of Globalization?

Green shipping challenges

Shipping contributes around 3% of global emissions caused by human activities, and the industry is committed to tough targets to cut these. Reaching these targets will require a mix of strategies, including measures to improve energy efficiency, the adoption of alternative fuels and innovative ship design and methods of propulsion. 

Decarbonization presents various challenges for an industry juggling new technologies alongside existing ways of working. For example, the industry will need to develop infrastructure to support vessels using alternative fuels, such as bunkering and maintenance, while at the same time phasing out fossil fuels. There are also potential safety issues with terminal operators and vessels’ crew handling alternative fuels that can be toxic or highly explosive.

Increasing shipyard capacity will also be key as the demand for green ships accelerates. Such capacity is currently constrained, with long waiting times and high building prices. Over 3,500 ships must be built or refitted annually until 2050, yet the number of shipyards more than halved between 2007 and 2022. Capacity constraints on shipyards could have a knock-on effect for repairs and maintenance, with damaged vessels or those with machinery issues potentially facing long delays. Machinery damage or failure is the most frequent cause of shipping incidents, accounting for over half of these globally in 2023 (1,587).

To read the full Allianz Commercial Safety and Shipping Review 2024, please visit: Commercial-Safety-Shipping-Review-2024.pdf (allianz.com)


Rahul Khanna

Profile picture for user RahulKhanna

Rahul Khanna

Capt. Rahul Khanna is global head of marine risk consulting at global insurer Allianz Commercial. 

A marine professional with 27 years of experience within the shipping and maritime industry, Capt. Khanna served more than 14 years on board merchant ships in all ranks, including master of large oil tankers trading worldwide.

Navigating Inflation in the Insurance Industry

Dr. Michel Léonard of the Insurance Information Institute discusses the current economic landscape and its impact on the insurance industry for the rest of 2024 and beyond. 

Michele Leonard interview

In their most recently quarterly discussion, Paul Carroll, editor-in-chief of Insurance Thought Leadership, caught up with Dr. Michel Léonard, the chief economist and data scientist at Triple-I, to review how the economy is affecting insurers’ results and prospects for growth.

What follows is a transcript of that conversation, edited for length and clarity.


Paul Carroll: 

What is your perspective on the current state of the insurance industry and the broader economy?

Dr. Michel Léonard: 

The insurance industry is navigating a complex economic landscape. Inflation remains a significant concern, with the Consumer Price Index (CPI) at elevated levels. This affects insurers in various ways, from increasing claims costs to improving investment returns. 

Despite these challenges, the industry has demonstrated resilience. Insurers are adapting to the changing environment by closely monitoring their underwriting practices and adjusting pricing as needed. They are also leveraging technology and data analytics to enhance operational efficiency and better understand and manage risks.

Looking at the broader economy, there are signs of a slowdown. GDP growth has moderated, and consumer confidence has been affected by the inflationary pressures. However, the labor market has shown strength, with low unemployment rates. 

The insurance industry is closely watching these economic indicators. While the industry is well-capitalized and prepared to weather economic fluctuations, sustained inflationary pressures and a potential recession could pose challenges. Insurers will need to remain vigilant, adaptable and focused on maintaining financial stability while serving the needs of policyholders.

Carroll: 

What is the current narrative around the economy and financial markets, given the recent shifts in expectations around interest rates and inflation?

Léonard:

The narrative has shifted. For the past six months, there was clarity on the direction of bond yields and equity markets, with the old normal prevailing: Bond yields were decreasing, and equity markets were improving. 

This was largely driven by expectations of Federal Reserve rate cuts. However, a couple of months ago, I began to question whether this narrative was still primarily about rate cuts and what was actually driving those rate cuts.

Previously, the focus was squarely on inflation measures like CPI, but now I believe the story is evolving. A few years ago, the consensus was that inflation would not return to normal, and the Fed's long-term 2% target seemed to fade from discussion. We then saw inflation drop significantly by several percentage points in just a few months, which many thought impossible.

The most recent numbers for March came in at 3.5% inflation, up from 3.1%. While that’s still in the 3% range, plus or minus, the question is whether this is where we will remain for the time being. Personally, I'm not sure that's necessarily a bad thing, but the narrative is clearly shifting.

Carroll: 

Some recent articles suggest that high interest rates may be driving the economy rather than being a drag on it. What factors lead you to conclude that interest rates will settle around 3.4% to 3.6% for an extended period?

Léonard:

I still believe there will be a cliff this year, and if the Fed doesn't lower rates it would send tremors through the markets. Looking at the Fed's own forecasts over the past two years, they keep pushing back the 2% inflation target to the long term, indicating that we're unlikely to reach that goal.

If we don't hit that trigger, the Fed can't lower rates, and we'll be stuck at that 3% or so rate. The Fed is unlikely to be comfortable with anemic growth for a year or two, especially with uncertainty about when inflation will return to 2%.

Carroll: 

What implications does this have for individual investors and the insurance industry?

Léonard:

For individual investors, high-quality four-year bonds are now offering returns of around 4% per year, which compounds to nearly 20% over four years without the uncertainty of equity markets and political or geopolitical risks. This is particularly attractive for retirees and those later in their careers who have bonds.

However, while these individuals may spend more, they are unlikely to spend on big-ticket items like homes and cars, as they likely already have these and will use them for longer. For the insurance industry, this means a slight correction in equity markets, probably for a quarter, until there is more clarity about Fed interest rate cuts.

If rate cuts don't materialize, the correction in equity markets could deepen in the second half of the year, especially with political risks. Depending on their outlook, individual investors may choose to cash out of equity markets and move into fixed income for 12 months or ride out the volatility for three months.

Carroll:

What are some highlights from your recent quarterly insurance forecast?

Léonard:

Our forecast looks at both overall GDP and what we call underlying growth, which refers to things like home rebuilding costs and auto usage rather than market prices. We've been predicting that following the pandemic-related recession, underlying growth for P&C insurance would outpace the rest of the economy. 

This trend started to emerge in Q4 of last year. Over the next three years, we project underlying growth to increase from 3.4% to 4.0% and reach 4.8% by 2026. While the 4.0% and 4.8% figures might be slightly optimistic, the upward trajectory is clear.

This growth is driven by anticipated consumer spending on big-ticket items like homes, not just disposable goods. On the GDP front, our outlook is more optimistic than the Fed's, with projections of 2.6% this year, 2.9% next year and 3.1% in 2026. The Fed's projections on GDP show a declining trend of 2.2%, 2.1% and 2.0%. 

Even if the Fed's long-term forecast of 2.0% interest rates and 2.0% real growth materializes, it's still not where we want to be.

From an insurance industry standpoint, the current economic situation is promising, but it largely depends on the Federal Reserve's actions. If the Fed's scenario plays out, we could be in a challenging position, as they control interest rates.

The key question is no longer about when the Fed will cut rates, but rather why they will do so and whether they will allow a 3% interest rate and inflation environment with rates above current levels. The Fed's decisions will have significant implications for the insurance industry and the broader economy.

Carroll: 

What impact do you think persistently high interest rates could have on home purchases, particularly for the younger generation entering the housing market?

Léonard:

While high interest rates can certainly be an impediment to home purchases, especially for the younger generation, it's important to consider the broader policy decisions at play. As an economist, I believe that a moderate increase in inflation from 2% to 3% is reasonable, although this view may differ from the Federal Reserve's stance.

When it comes to generational wealth transfer and housing affordability, interest rates are just one piece of the puzzle. The availability of housing also plays a crucial role. Housing economists point to policies such as rent control, construction regulations and the promotion of multi-use buildings in big cities as key factors in addressing the supply side of the equation.

While I'm not a housing economist myself, I agree with the experts who emphasize the importance of these supply-side policies. Focusing solely on the demand side through interest rates may not be sufficient to tackle the affordability issues faced by younger generations seeking to enter the housing market.

Carroll: 

What are your thoughts on the current state and future outlook of commercial real estate, particularly in terms of its impact on the insurance industry?

Léonard:

The insurance industry's investment in commercial real estate has decreased over time, from owning 60% to 70% to now around 30%. However, it remains an important asset class for insurers.

In terms of commercial property insurance, we estimate 3.5% growth this year, which is above the average of 3.4% for all underlying growth. This growth is only surpassed by personal auto insurance.

Recent conversations with trade economists have revealed early signs of recovery in the commercial real estate market. The ability of Class A buildings to become high-end apartment buildings and adopt a multi-use format is a positive indicator. This transition is crucial for the revival of urban areas, as it allows for the emergence of small businesses and mom-and-pop stores on the first floors of these buildings.

The recovery is particularly evident in the Sunbelt region, which continues to boom, especially in Class A properties. This trend aligns with the general principle that during a correction, lower-quality assets are the first to decline, while higher-quality assets are the first to recover. These signs of hope in the commercial real estate market are expected to support the growth of commercial property insurance, as well.

Carroll: 

What is your perception of how the public discussion and understanding of economics has evolved over the past few decades? It seems there is now a more sophisticated and shared understanding compared with the past, when information was more siloed within individual companies.

Léonard:

You're absolutely right. There is a much more sophisticated audience today, whether it's consumers, corporations or financial firms. The accessibility of economic data has greatly improved, with people closely following key indicators like unemployment, inflation and GDP growth.

The Federal Reserve has also played a role in enhancing public understanding by communicating more openly and providing explanations. However, translating economic insights for specific individuals and companies remains a challenge for economists.

While there are shared resources and a degree of consensus among industry economists, relying on a small group of 10-12 economists for a consensus view may not be representative of a true national consensus.

Economists need to find a middle ground in providing specific, actionable insights while effectively communicating the inherent uncertainties and limitations of economic forecasting. In our own work, we focus on conveying the overall direction of economic trends, as this is more relatable and easier to implement than fixating on specific numerical targets.

Carroll: 

What insights can we gain by looking beyond the surface-level numbers and considering the underlying factors driving the current situation in the insurance industry?

Léonard:

While there have been some short-term changes and volatility in the equity markets over the past few weeks, the bigger picture remains largely unchanged. The key difference is that we now face more uncertainty about where the industry is heading in the long term.

Previously, we had a clearer sense of our long-term trajectory, even if there was some uncertainty in the short term. Now, the situation has reversed: We're in a relatively stable position on a day-to-day basis, but the future direction is less certain.

Ultimately, it's crucial to look beyond the immediate numbers and consider the broader context and trends shaping the insurance industry's path forward.

Carroll:

What is your outlook on the underlying growth for the property and casualty insurance industry?

Léonard:

The property and casualty insurance industry is currently in a good place in terms of underlying growth. However, it's important to remember that the industry experienced a few challenging years, performing worse than the overall economy. 

It will take some time for the industry to fully recover from those setbacks. Many companies still have combined ratios above 100, which makes it difficult to achieve profitability. Despite the positive growth trends, the industry continues to face significant challenges in maintaining profitable operations.


To listen to the audio of the full conversation between Paul Carroll and Michel Léonard, please go to Episode 9 of  Triple I’s All Eyes on Economics podcast. 


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.