Download

Biggest Business Trends for 2024

It's not too early to begin planning strategic initiatives for 2024, so here is a list of 10 trends that will likely dominate next year. 

Image
World Business Trending

When I ventured into the garden section at my local Wal-mart last week, I saw they hadn't just been preparing for Halloween by setting up alluring candy displays throughout the store. They were already getting ready for Christmas, setting up displays for decorations, lights and even fake trees. 

Those displays reminded me that we are, in fact, in the fourth quarter of 2023 and that, while I'll still probably start my Christmas shopping on roughly Dec. 23, it's not too early to begin planning initiatives for 2024. And it happens that a smart analyst I follow on LinkedIn posted a list last week of what he sees as the 10 trends that will dominate next year. 

They are: generative AI, the human touch, the solution to the skills shortage, sustainability, personalization at scale, the data economy, the customer service revolution, remote and distributed work, diversity and inclusion and resilience.

I think some of those are more important than others and have a suggestion or two of my own, but that list is a good place to start. Let's dig in.

The article by Bernard Marr opens with generative AI, which I agree should be a major focus but which I won't go into here, because I wrote about it last week and have gotten into it extensively in other pieces, including in this interview with a longtime friend and colleague, John Sviokla, who said generative AI will be bigger than the internet.

#2 on Marr's list is "Soft Skills and the Human Touch." He writes: 

"As it becomes increasingly feasible to automate technical aspects of work - coding, research or data management, for example - the ability to leverage soft skills for tasks that still require a human touch becomes critical. For this reason, in 2024, we will see organizations increasing their investment in developing and nurturing skills and attributes such as emotional intelligence, communication, interpersonal problem solving, high-level strategy and thought leadership."

I agree and, in fact, have for many years been pushing the idea of "bionic" processes and employees, who take advantage of the efficiencies of digitization, including AI, while maintaining that human touch. Here is a recent piece on how to combine digital efficiency with human empathy.

#3 is the "Skills Solution." Marr writes: 

"We’ve been hearing about the skills shortage for several years now. Changes in hiring practices that emphasize selecting candidates with the specific experiences and skills needed for a role, rather than qualities such as educational attainment or age, are a part of the industry's response and will continue to be a strong trend."

Again, I agree. While universities increasingly offer risk management and insurance programs, we can't expect them to produce such a steady stream of graduates that they will fill all the industry's needs. Instead, the insurance industry will need to get creative in finding talent, as explained in this piece on winning the war for talent.

#4 is "Sustainable Business." I'd say insurance is still finding its way on how to support sustainability. If you're interested in a more detailed analysis of where we stand and how we can progress, I'd suggest you listen to this webinar I recently conducted with Sean Kevelighan, president and CEO of the Insurance Information Institute, and Francis Bouchard, managing director, climate, at Marsh McLellan. I found the discussion exceptionally informative and think you will, too. I'd also recommend the interview I did recently with Alex Wittenberg, a partner at Oliver Wyman, on resilience. 

#5 is "Personalization-at-Scale." I've long identified with this approach. Part of what attracted me to Diamond Management & Technology Consultants after a long career at the Wall Street Journal was the startup's alliance with Joe Pine, who pioneered the idea of mass customization. That was in 1996. The possibilities have only expanded since then. But insurance starts at the opposite end of the spectrum, focusing on pooling of risks, so I suspect the personalization emphasis will lag in the insurance world.

#6 is "The Data Economy," which is a massive opportunity for insurers. Marr writes:

"Data is an increasingly valuable business asset. By 2024, more companies will have streamlined their operations and improved their customer offerings by taking a strategic approach to their data. As a result, they will be ready to take the next step - monetizing data itself to drive new business opportunities. Leading the way are companies like John Deere, which has pioneered the model of selling data from its sensor-laden farm equipment back to farmers as insights to improve productivity. As access to large-scale data collection and AI-driven analytics becomes increasingly democratized, we'll see this trend adopted by smaller companies in niche and diversified sectors."

Insurance is the ultimate data business, and companies have a huge opportunity to turn data into revenue. Some of that opportunity will arise because insurers will go beyond "insure and pay" and shift to a "predict and prevent" business model, as described in this recent piece. Some will come because companies find creative ways to gather and process data, then sell it to others -- a la Allstate's Arity.

#7 is "The Customer Experience Revolution," which is desperately needed in insurance and which we've published about extensively. 

#8 is "Remote and Distributed Work," which seems to be here to stay and which insurance seemingly could benefit from as much as almost any industry. 

#9 is "Diversity and Inclusivity." This is another topic that feels like it's especially important in insurance. We serve a diverse population. Shouldn't we have a diverse work force, including leaders, who empathize with the needs of those diverse customers? 

#10 is "Resilience." Marr writes:

"[That means] ensuring an organization is protected from whatever threat is around the corner. That could mean cyber attacks, economic downturns, environmental events, war, global pandemics or the emergence of a disruptive new competitor."

We've certainly had plenty of recent lessons about the need to plan for resilience, including the attack by Hamas on Israel over the weekend and, just a year and a half ago, the Russian invasion of Ukraine. Both are having massive, unpredictable effects not only on geopolitics but on business. Just imagine what will happen if China follows through on threats to invade Taiwan.

To Marr's list, I'd add two sorts of skills that I think many businesses will want to develop. 

First are partnership skills. We talk a lot about ecosystems and about using technological capabilities such as application programming interfaces (APIs) to plug into what partners are doing, but being a good partner takes practice. Companies shouldn't assume they'll be great at partnerships, or even adequate, in the first go-'round. Companies should engage in a number of low-level partnerships, to understand what they do well and what they do poorly, before attempting any partnership that could be game-changing. Develop those partnership muscles before trying to use them.

Second are M&A skills. These aren't necessary for many in the insurance industry but are required by many others, especially agents and brokers, lots of whom are aggressively expanding. Historically, the rule of thumb was that only about one in three acquisitions succeeded. More recent research suggests a higher success rate, but only because acquirers are making a steady stream of smaller purchases and developing M&A skills rather than swinging for the fences with a massive takeover by a first-time buyer. 

So I'd suggest you start planning for 2024, even as you accept that geopolitical events such as the Hamas attack on Israel could derail some of those plans.

Cheers,

Paul

‘Predict & Prevent’ Can Rescue Insurance

Soaring combined ratios demonstrate P&C insurance is due for fundamental, structural reform. Innovative solutions are available. 

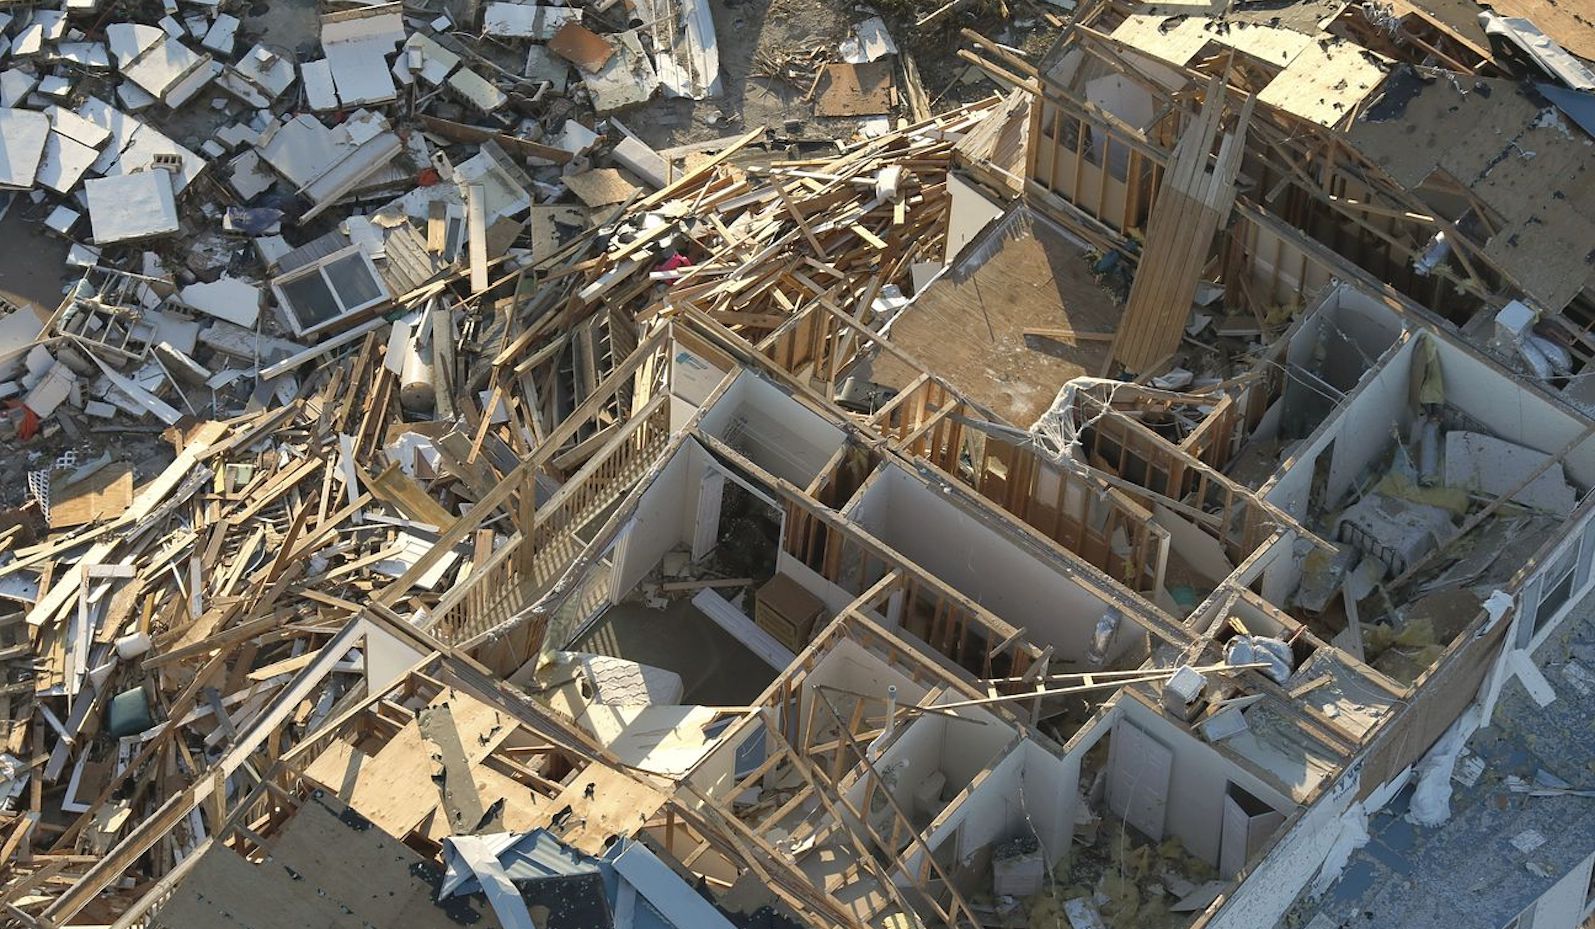
Overhead photo of a damaged and torn apart home

KEY TAKEAWAYS:

--Premiums are soaring, and there is no relief in sight, as people keep moving into areas where homes are at higher risk to natural catastrophes, as electric vehicles and other new technologies raise repair costs, etc. 

--But improved construction and greater building resilience standards can help, as can major preventive measures such as building a sea wall for Manhattan. There are also numerous insurtech solutions emerging that use sensors, AI and other technologies and that can switch the traditional insurance model from "insurance and pay" to "predict and prevent."

----------

In 1735, Benjamin Franklin wrote that “an ounce of prevention is worth a pound of cure.” He was referring not to medicine but to fire safety, because central Philadelphia, where he lived, consisted of connected wooden row houses. In fact, he was a founding member of the Philadelphia Contributorship, the first fire insurance company in America. Today, prevention may very well be the cure for the ailing insurance industry.

Throughout the history of risk and insurance, there have been periods of crisis and reform. In 1971, no-fault auto insurance was adopted in Massachusetts and spread to 19 states by 1974 with promises of lowering high auto premiums. In the mid-1980s, liability insurance rates soared, leading to tort reform. Most recently, Florida, California and Louisiana are enacting reforms in the face of threats from weather, inflation and legal system abuses. 

As the property & casualty insurance industry struggles with the severe impact of extreme weather events, rapidly shifting market conditions, growing social and economic inflation and a rapidly transforming automotive and alternative transportation landscape, it has become obvious that fundamental, structural change is necessary and inevitable. Each of these single pressure points is striking. Collectively, they may represent the “new normal.” In any case, cost of insurance is on the rise while availability has become problematic, with both consumers and businesses absorbing the impact.

How Did We Get Here?

Catastrophic weather trends receive the most attention for good reasons but are not exactly new. According to a study by the Insurance Information Institute, average insured CAT losses were up 700% from the 1980s through 2020, spiking throughout each decade with noteworthy hurricanes: Andrew, Katrina, Wilma, Rita, Harvey, Irma and Maria. There’s little argument that events are more frequent and causing more costly damage, but these trends have been moving upward for some time.

Since the adoption of special, all-risk homeowner policies from previously limited or named peril policies in the 1980s, courts have further broadened insurance coverage. There is a residual tension between coverage for fortuitous loss and what some say are - or should be - uncovered maintenance costs, with much debate over exclusionary language. Meanwhile, U.S. homes have grown in size, averaging 2,522 square feet, doubling from 1975 to 2022, according to Statista. Likewise, home building materials, amenities and construction design have added to rebuilding costs, with increased construction in more disaster-prone regions as population shifts to the Southeast and Southwest, in particular. Between 2018 and 2021, the average annual homeowner rate change was 3%, and through the first three quarters of 2023 averaged 8.8%, according to S&P.

Just prior to the pandemic, auto insurers were engaged in a race to the bottom. Switch and save marketing flooded the market. Fast-forward, and inflation on auto parts, building materials and labor rates are perpetual “sticker shock” realities, despite some leveling-off. Auto repair technician shortages, social inflation and distracted driving behavior are newer and growing influences with no signs of alleviating in sight. Meanwhile, though less obvious, global reinsurance premiums are also driving up rates.

On the commercial lines side, business auto has struggled, with combined ratios for 11 of the last 12 years over 100, amounting to underwriting losses, per Fitch Ratings. Miles driven, demand for commercial trucking and driver shortages are among the causes, again with no clear change in sight.

See also: The Promise of Predictive Models

Just the Beginning

P&C insurers are pulling all the levers. Rate increases are across the board in auto, home and commercial lines. Tighter underwriting rules, restrictions on new writings, pullbacks in select states or product lines are reverberating throughout the industry. Some insurers are scheduling roof limits based on roof age or only offering ACV protection. Higher deductibles or percentage of limit deductibles are emerging or instantly become the only option in coastal areas when homeowners have little to no choice and are pushed into state wind pools or non-admitted E&S insurers. The result is more cost and less coverage, serving as a shift to greater self-insurance.

Allstate told its captive agents in August that it will effectively be reducing their commissions, and other insurers are trying to reduce their administrative costs, but the costs of insuring risks are projected to increase and remain high for the next few years – double-digit rate increases are just the beginning.

High Premiums Here to Stay

There’s lots of evidence to forecast that high premiums are here to stay. Thus far, loss costs have outpaced rate increases, and once they do catch up there is no reason to believe premiums will decline. Insurance to value (ITV) is emerging as an issue as property values and rebuilding costs have soared. The population shift to disaster-prone areas is not slowing. Auto technology, EV repair and parts costs on top of more expensive original equipment car manufacturer repair procedures are all on the rise. Social inflation fueled by juror attitudes, nuclear verdicts of $10 million or higher and litigation funding are gaining more attention (even though the term was coined by Warren Buffett as long ago as 1977 in a shareholder letter, according to the NAIC/CIPR Research Library). In many cases, consumers choose to reduce coverage or drive uninsured. Bankrate says there are an estimated 32 million uninsured drivers in the U.S., a number that is likely to grow.

The implications can be distilled to a greater proportion of self-funded risks for consumers and businesses.

Predict and Prevent

A new paradigm of predict and prevent is gaining traction. The Insurance Institute for Building and Home Safety (IBHS) has encouraged the insurance industry to influence improved construction and greater building resilience standards. Sensor technology combined with preventative measures, such as moving assets from harm’s way, show promise but have a long way to go, balancing efficacy with pragmatic actions. Distracted driving avoidance and driver coaching is making a difference in larger fleets, with much room to improve smaller fleets and personal auto. However, predicting and prevention is also being applied more broadly, such as shoring up storm walls in places like Manhattan and Miami. Meanwhile the devastating Maui fires illuminate major gaps in prevention and how controversial measures to clear vegetation get in the way of progress.

The Role of Insurtech in Risk Transformation

Enabled by new and emerging technologies and funded by professional investors with the highest amount of available capital in history, numerous insurtechs have introduced first-generation solutions to insurance risk management. These solutions have primarily focused on a small number of high-visibility applications, including quoting, underwriting and distribution and claims. But few if any of these products have materially affected combined ratios and thus profitability, leaving insurers with no good response to current conditions other than talking rate.

See also: Convergence and the Insurance Ecosystem

Enabling Insurtech Solutions

  • Sensors are a relatively low-cost, easy-to-deploy technology with large numbers of applications across homes and businesses and “wearables.” The sensors can alert users and carriers of impending risks, providing time to respond and avoid a loss, or at least limit the damage. 
  • Telematics widen the uses of sensors to include the integration of large volumes of contextual data to more accurately predict and prevent accident frequency, severity and injury. Crash detection, automated first notice of loss (FNOL), accident response and emergency services are powerful applications emerging from smartphone enables telematics.  
  • Artificial Intelligence (AI), while it has been used for many years in information and data management, has grown to include other more powerful iterations, including natural language processing (NLP), robotic process automation (RPA), machine learning (ML), computer vison CV) and the latest and most fascinating, generative AI. While not all of these AI solutions support risk prevention, many enable material cost savings. Computer vision has already been adopted for almost 40% of auto physical damage claims, enabling early total loss identification, automated repair estimate generation and parts procurement with limited human interaction.
  • Geospatial data and analytics have high potential to identify, limit and avoid property risks from extreme weather and catastrophes. On the front end of the insurance process, pricing and underwriting, this data can ensure higher accuracy as well as risk avoidance. Insurtech geospatial platforms are expanding through partnerships and integrations, making it faster, easier and less expensive for insurers to consume and use multiple applications.
  • Parametrics is a form of risk prevention in that it limits a carrier's exposure to a specific, narrowly defined “micro-event,” which vastly simplifies the pricing and underwriting of each covered event, eliminates most traditional claim costs and provides greater predictability of total exposure.

Many of these young companies, and their existing and emerging solutions, have the potential to enable the insurance industry to shift its paradigm from “insure and pay" to "predict and prevent.”

Of course, none of these solutions can have real impact until insurers decide to aggressively embrace and comprehensively implement them. Otherwise, the industry will continue to react ineffectively to elements of the current crisis, which will then be followed by reform that could well lead to greater customer self-funded risk management -- defying the founding insurance principle of risk transfer. 

We trust that the industry will recognize that Benjamin Franklin was right about prevention and cure and will embrace innovative solutions, sooner than later.


Alan Demers

Profile picture for user AlanDemers

Alan Demers

Alan Demers is founder of InsurTech Consulting, with 30 years of P&C insurance claims experience, providing consultative services focused on innovating claims.


Stephen Applebaum

Profile picture for user StephenApplebaum

Stephen Applebaum

Stephen Applebaum, managing partner, Insurance Solutions Group, is a subject matter expert and thought leader providing consulting, advisory, research and strategic M&A services to participants across the entire North American property/casualty insurance ecosystem.

Revolutionizing Life Insurance Uptake in Younger Markets

LIMRA found that interest in life insurance products is at an all-time high for younger adults. There is an enormous opportunity.

Five young people in their late teens or early twenties walking side by side on a concrete path among treets on a college campus

KEY TAKEAWAY:

--the life insurance industry must innovate to appeal to the next generation of consumers' appetite for fast, personalized and digital-first experiences.

----------

The COVID-19 pandemic threat led to a surge in life insurance sales: In 2021, the life insurance industry saw its greatest nine-month sales growth in 25 years. However, a LIMRA study shows this trend is reversing, especially for younger markets. In 2023, only 40% of Gen Z adults and 48% of millennials say they own life insurance, and nearly half say they don't have sufficient life insurance coverage. That figure represents 53 million adults.

Still, the same report finds interest in life insurance products is at an all-time high for younger adults, as 44% of Gen Zs and 50% of millennials intend to purchase life insurance this year.

Therefore, life insurers have an opportunity to grow their life insurance sales in untapped younger markets by leveraging technology and digital sales techniques.

Here's how carriers can close the gap with these younger markets:

AI Digital Assistants and Education

Lack of knowledge about life insurance is the greatest obstacle preventing younger adults from purchasing coverage. 40% of Gen Z and 29% of millennial parents say they haven't purchased coverage because they don't know how much coverage they need or what type to buy.

How life insurers educate and engage with younger adults will be critical. While Gen Z and millennials value personalized advice and education from human financial advisers, it's impossible to provide human assistance to each policyholder with different needs and levels of knowledge.

As a result, insurers are using chatbots powered by artificial intelligence (AI) to drastically speed up and simplify the purchasing process and provide an always-on, contextual, educational experience.

For example, digital assistants and generative AI-powered chatbots can answer questions about coverage, simplify complex insurance jargon, coach users through the insurance purchasing process, articulate why each step is necessary or connect prospects and policyholders with human advisers.

Omnichannel Customer Experiences

Today's younger generations of customers aren't just expecting online experiences; they want Amazon-like levels of efficiency and convenience. Despite the demand, a McKinsey study finds that only 11% of life insurers facilitate multichannel online product sales.

An omnichannel customer experience occurs when multiple marketing and service channels work independently but provide an integrated and seamless customer experience across all online and offline channels. This means designing customer journeys that allow for seamless channel-switching and ensuring the customer receives the same experience whether they are interacting through email, text, telephone, website, social media or customer portal.

While the life insurance sector has yet to reach a standard for omnichannel outreach, insurers have an opportunity to differentiate their offering by providing a cross-channel experience that meets the next generation of consumers on their preferred platform.

See also: Balancing Innovation, Compassion in Life Insurance

Personalized Pricing, Products and Customer Experiences

LIMRA says high premium costs and inflation are critical reasons why younger people do not purchase life insurance. The problem is lowering premium prices is easier said than done. Instead, insurers can capitalize on personalizing pricing, products and customer experiences.

Personalization enables prospects and clients to get the exact information and policy they want, allowing them to understand their policies and pricing better. Of course, life insurers will have to obtain large sums of customer data to provide personalized experiences and products. The good news is that many Gen Zs and millennials are comfortable exchanging personal health data (i.e., step counts, sleep data, etc.) from their Fitbits or Apple watches for discounts and personalized policies.

This opens up a massive opportunity for insurers to maximize customer engagement and attract more millennial and Gen Z customers with personalized experiences, discounts and rewards for healthy behavior.

Relevant Marketing and Creative Policies

Life insurers must find unique ways to make their products relevant to younger generations. Life insurance marketing often focuses on financial protection for a traditional family structure. Because a childless 25-year-old would likely have different priorities than a 45-year-old with a family, younger individuals usually skip life insurance. However, if life insurers allowed customers to customize their policies to support a particular cause, customers may be more open to purchasing coverage.

For example, some innovative life carriers position life insurance as a way to buy a tattoo for a friend, activate a charitable donation, care for a beloved pet or send a friend or family member on a trip to Europe. Life insurance is positioned as an act of love. The customer feels in control.

Through relevant marketing and creative policies, personalized life insurance can appeal to younger demographics by making it easier to understand and helping them protect and pay for things they care about. Personalization is critical to filling generational gaps in coverage.

Social Media as a Channel for Education and Digital Distribution

Younger people are likelier to use social media platforms like YouTube, TikTok, Twitter and Instagram rather than financial company websites to get financial advice and information and buy coverage.

According to a LIMRA study, 81% of Gen Z and 75% of millennials turn to social media for discussion, advice and information regarding financial topics. Over three-fourths of millennials use their smartphones for financial transactions.

Almost every insurance organization uses social media primarily to promote its brand and market products. While this will remain important, leveraging social media channels to engage, educate and provide self-service policy options to younger customers will play a significant role in the distribution and marketing strategies of life insurers wanting to capture the next generation.

Accelerated Underwriting

The traditional process of getting insured, which includes paperwork, in-person medical testing (i.e., blood work and urine tests), and a reputation for complexity, are key reasons younger generations don't bother purchasing coverage.

Younger customers want to buy life insurance the same way they buy anything else online: quickly and easily. As a result, many leading life insurers are embracing accelerated underwriting. According to a LIMRA study, three out of four life insurance companies in the U.S. and Canada have automated or accelerated underwriting programs.

Accelerated underwriting enables life insurers to make quick decisions on an application. Accelerated underwriting processes use predictive analytics, machine learning algorithms and various data sources, such as medical records, claims history and credit history, to evaluate the applicant's risk.

This lets customers skip tedious underwriting processes. Accelerated underwriting programs can reduce policy wait times for life insurance from 27 days to just 24 hours.

It is essential to position the speed and ease of accelerated underwriting in campaigns targeted to Gen Z consumers.

See also: Life Insurance Digitalized

Attracting the Next Generation of Life Insurance Customers

Owning life insurance can be life-changing for younger generations and their families. While 71% of insured younger parents would feel financially secure if a primary wage earner were to pass away, only 48% of uninsured parents would feel the same.

With so many uninsured and underinsured young adults, the life insurance industry must continue to innovate to appeal to the next generation of consumers' appetite for fast, personalized and digital-first customer experiences.

Let's get creative and think of new ways to reach these younger markets and close generational coverage gaps.

'Post-Quantum' Agility Is Critical

Insurers must keep up with the ever-changing nature of cyber threats -- and a new form of computing is causing concern.

Blue balls joined together to form a neutron surrounded in orbit by other balls representing electrons along with many bright colors and other rings all representing quantum physics

KEY TAKEAWAYS:

--Due to quantum computers' ability to solve problems like prime number factoring, which is used to protect internet communications, this technology poses a significant threat to the security of traditional cryptographic systems.

--Insurers must not only switch as quickly as possible to encryption algorithms that are impervious to quantum computing but must develop cryptographic agility, which allows them to switch encryption methods and algorithms as needed.

----------

As the world becomes increasingly reliant on connected technology, the threat of cyberattacks and data breaches continues to grow. These breaches can have significant financial and reputational impacts on businesses and organizations, and insurance companies have stepped in to offer protection against these risks.

The impact of security breaches can be severe, not only for the affected company and its customers but also for their insurers, investors and shareholders. The Firewall Times report on data breaches shows several high-profile data breaches at Discord, T-Mobile, Yum Brands and Uber, among others, just in recent months. The T-Mobile breach exposed personal information of 37 million customers. Past historic breaches where hackers gained access to sensitive information such as Social Security numbers, birth dates and addresses of over 100 million Americans had a significant impact on the insurance industry, with insurers facing payouts in the range of half a billion dollars.

These examples highlight the critical role insurance companies play in covering the costs of cyberattacks. The examples also underscore the need for insurance companies to keep up with the ever-changing nature of cyber threats and invest in new technologies to protect their customers. And a new form of computing is causing concern.

Quantum computers are a new breed with the capability to break the current public key encryption we all use. Insurance companies must evaluate this technology and its risks to continue providing effective cybersecurity protection coverage for themselves and their customers.

Quantum computing is a revolutionary technology that promises to solve certain complex problems that are impossible for classical computers. However, due to the ability to solve problems like prime number factoring, which is used to protect internet communications, this technology poses a significant threat to the security of traditional cryptographic systems. As quantum computing continues to advance, businesses and governments must protect against potential security threats.

The National Institute of Standards and Technology (NIST) is leading the charge in protecting against quantum computing threats. NIST is responsible for setting standards and guidelines for cryptographic systems used by the federal government and businesses. In 2016, NIST launched a competition to develop quantum-resistant cryptographic algorithms, known as post-quantum cryptography (PQC). In 2019, NIST announced the finalists for its PQC competition, which included 17 algorithms. These algorithms underwent further testing and analysis to determine their effectiveness and suitability for widespread adoption. In 2022, NIST announced four finalists, with four more being researched. As of December 2022, U.S. federal agencies are now required to shift to post-quantum security, with their private-sector vendors likely following suit.

PQC algorithms are designed to resist attacks by quantum computers. These algorithms use mathematical problems that are believed to be computationally difficult for both classical and quantum computers to solve, providing an extra layer of protection for sensitive data.

A critical component for post-quantum cybersecurity solutions is cryptographic agility, which involves the ability to switch encryption methods and PQC algorithms as needed. By adopting a framework for post-quantum cryptography and cryptographic agility for themselves and their customers, insurance companies can stay ahead of the curve and quickly adopt new encryption methods as they are developed. This approach can help to mitigate the risks of quantum computing and ensure that customer data remains secure.

See also: Quantum Technologies, Cybersecurity and the Change Ahead

Insurance companies have not developed products that provide risk protection against cyber security attacks specifically from quantum computing. With "steal now, decrypt later" (where cyber thieves hack into systems and steal data that they can't decrypt now but will decrypt later once they have a powerful enough classical or quantum computer) businesses might already be vulnerable, and the loss might not be adequately factored into the lifetime revenue of cyber products. However, some insurance companies are taking the lead by getting involved in quantum computing through quantum accelerators and innovative startups. This method has let many industry leaders dip their toe into quantum computing technology and understand the future opportunities and risks of this new technology.

Startups that have graduated from these accelerators have already developed post-quantum crypto-agile products that can be easily integrated into existing systems. One example is QuSecure. Their Post-Quantum agile products are already being evaluated in government agencies. These products provide secure communications and data protection resistant to attacks by quantum computers. By following the direction NIST and U.S. government agencies are taking and bringing these necessary risk management products and technology solutions to their customers, insurance companies can improve their own future bottom line and their customers' reputations by reducing quantum cyberattacks that happen down the road.

Insurance companies have a critical role to play in protecting businesses and organizations against the financial and reputational damage caused by cyberattacks and data breaches. However, as the threat landscape evolves, insurance companies must stay ahead of the curve by adopting new technologies and solutions. They can go a step further by connecting with existing companies providing post-quantum cryptography and cryptographic agility. By embracing these technologies, insurance companies can improve their bottom line by setting security policies and standards for their customers and ensure the security of their customers' data even if it gets in the hands of a nation state-sponsored quantum hacker today.


Alex Khan

Profile picture for user AlexKhan

Alex Khan

Alex Khan is an adviser to QuSecure and is the CEO of ZebraKet, a quantum startup in supply chain optimization.

Khan has been working in quantum computing since 2018 and was the CPO at Chicago Quantum, where he was a co-author on papers on portfolio optimization using D-Wave. As a corporate faculty, he teaches undergraduate to graduate level courses in quantum computing at Harrisburg University.

Khan has an engineering/physics dual major and received his BSME from Purdue University, MSME from KSU, MBA with health sector management from Duke University and a certificate in quantum computing from MITxPro.

A Guide to Wildfire Safety

As cities expand, they often sprawl into previously undeveloped, rural territories, placing communities close to wildlands and forests.

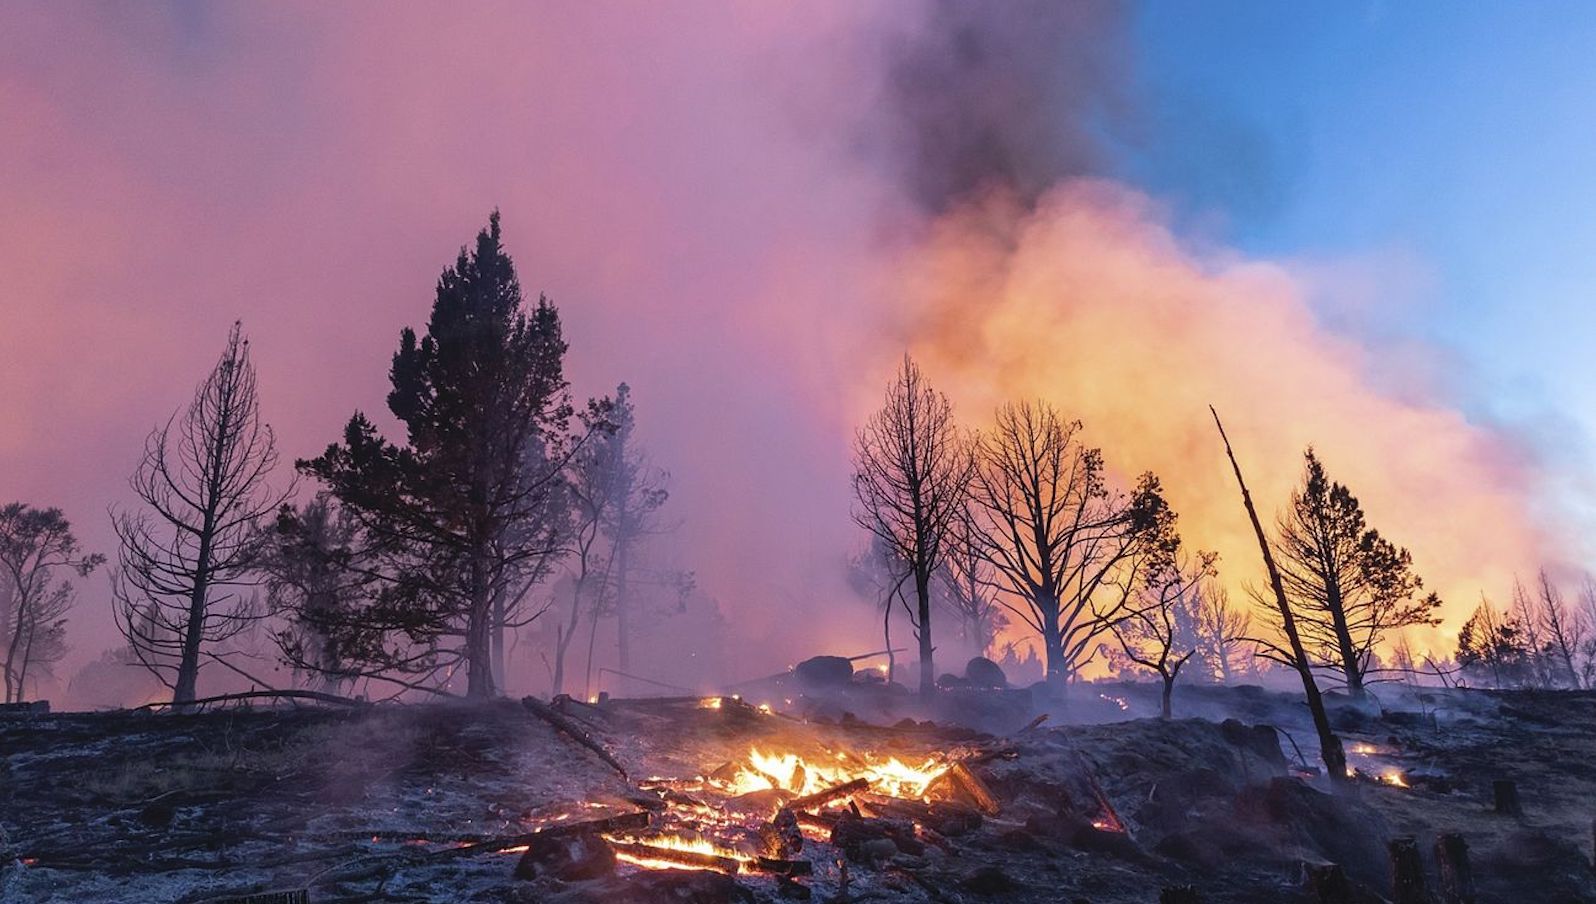
A wildfire among trees and with ash on the ground in front. Sky looks pink and orange from the fire and smoke

As wildfires continue to escalate in number and intensity, businesses across the U.S. face unprecedented challenges in safeguarding their assets and ensuring business continuity. The urban encroachment into once-rural areas, combined with overgrown forests and changing landscapes, has made wildfire preparedness a year-round necessity. Exploring the key challenges businesses encounter as well as the practical steps they can take to protect themselves is vital, especially now during National Fire Prevention Week. 

Understanding the Wildland Urban Interface (WUI)

The term "Wildland Urban Interface," or WUI, refers to areas where human development and natural landscapes intersect. These regions are particularly susceptible to wildfires due to their combination of urban and wildland characteristics. According to the National Association of State Foresters, more than 60,000 communities throughout the U.S. are at risk for WUI fires. 

As our cities expand, they often sprawl into previously undeveloped, rural territories. This expansion places more communities in closer proximity to wildlands and forests.

Additionally, mature forests with an accumulation of undergrowth and deadwood have become significant risks. These areas are more prone to intense wildfires that spread rapidly and emit scorching heat.

Businesses must maintain awareness of the landscape and environmental conditions around their locations year-round. Regular assessments of the risk factors, such as dry vegetation, deadwood and proximity to forests, should be conducted.

Businesses may implement defensible space practices, including using fire-resistant building materials, maintaining fire-resistant landscaping, clearing deadwood and vegetation and creating controlled pathways. Businesses can seek guidance from organizations such as the National Fire Protection Association (NFPA), which assesses vulnerability and provides valuable recommendations.

See also: Here Come the Wildfires

Businesses must also collaborate. A prime example is the Falls Creek area in Durango, Colorado, where a community approach, combined with defensible space strategies, helped protect homes during the 416 Fire in 2018. The mitigation work done by residents, such as clearing brush and cutting dead trees, was noticed and appreciated by firefighters. This collaborative effort saved homes and demonstrated the power of community-based resilience.

Leveraging Innovative Approaches

In the quest to mitigate wildfire risks, businesses should also turn to innovative approaches and technologies. Organizations like the NFPA, the Insurance Institute for Business & Home Safety (IBHS) and the Federal Emergency Management Agency (FEMA) offer valuable resources and guidance.

Here are some innovative strategies and technologies that businesses can consider:

  1. Advanced Building Materials and Designs: Invest in fire-resistant building materials and designs that can withstand wildfire heat and embers. These innovations include fire-resistant roofing materials, ember-resistant vents and non-combustible siding. Embracing these construction techniques can significantly reduce the vulnerability of structures to wildfires.
  2. Ember-Resistant Landscaping: Implement landscaping practices that minimize the risk of embers igniting vegetation around your business. This includes using fire-resistant plants, creating defensible space and replacing flammable mulch with non-combustible alternatives such as gravel or stone.
  3. Firebreaks and Controlled Burns: Collaborate with local authorities and fire management agencies to create firebreaks and engage in controlled burns. These practices can help reduce the buildup of flammable vegetation and create fire-resistant zones around your business.
  4. Smart Sensors and IoT: Deploy smart sensors and Internet of Things (IoT) devices to monitor environmental conditions, such as temperature, humidity, wind speed and direction. These sensors can trigger automated responses, like activating exterior sprinkler systems or closing fire-resistant shutters, when fire-related conditions are detected.
  5. Community-Based Initiatives: Participate in community-based wildfire mitigation programs such as Firewise USA. These initiatives encourage collaboration among homeowners and businesses to create fire-resistant communities. They often provide resources, training and recognition for wildfire safety efforts.
  6. Regulatory Compliance: Stay informed about local building codes and regulations related to wildfire resilience. Ensure that your business complies with wildfire safety requirements and incorporates them into construction and renovation projects.
  7. Insurance Solutions: Work with insurers experienced in wildfire risk to tailor insurance solutions that cover the unique risks faced by your business. These solutions can include business interruption coverage, wildfire-specific endorsements and risk assessments.

Innovative approaches to wildfire mitigation should be tailored to the specific risks and challenges faced by your business and its location within wildfire-prone areas. By embracing these innovations, businesses can enhance their resilience and reduce the impact of wildfires on their operations and communities.

Balancing Cost-Effectiveness

Balancing wildfire preparedness with cost-effectiveness involves creating a comprehensive business continuity plan. This plan identifies key operations, personnel and potential shutdowns, enabling organizations to save money in the long run. 

These plans should often include performing a cost-benefit analysis of different preparedness measures, outlining the critical operations, key personnel and assets that need protection during a wildfire event, prioritizing proactive measures over reactive ones, reviewing your insurance policies, investing in wildfire safety training for employees and exploring government grants and incentives for wildfire mitigation. 

Remember that cost-effective wildfire preparedness is a continuing process that requires careful planning, regular assessments and a commitment to adapt to changing circumstances. By finding the right balance between cost and protection, businesses can mitigate wildfire risks without compromising their financial stability.

See also: A Breakthrough in Wildfire Safety

Insurance Considerations

Businesses operating in wildfire-prone areas should prioritize insurance considerations to ensure they are adequately protected. Key considerations include reviewing property insurance policies for coverage of wildfire-related damage, evaluating business interruption insurance to cover lost income and expenses during shutdowns and exploring wildfire-specific endorsements for enhanced protection. It's important to regularly update coverage limits, understand deductibles and maintain thorough records for claims purposes. Additionally, consider preventive measures for potential premium discounts and be aware of policy exclusions. Consult with insurance experts and incorporate insurance considerations into your business continuity planning.

In wildfire-prone regions, businesses should also assess post-wildfire risks such as flooding and evaluate the need for separate flood insurance. Periodic policy reviews and collaboration with experienced insurers can help align coverage with evolving business needs and risk profiles. By addressing these insurance considerations, businesses can better prepare for the financial impact of wildfires, ensuring a smoother recovery process and the protection of their assets and operations.

Closing Advice

Drawing from years of experience as a safety officer and former deputy fire chief, I encourage business owners and decision-makers to prioritize wildfire resilience. Wildfire prevention and protection can be summed up into five p’s: stay proactive, plan, practice, perform perpetual maintenance and partner with your local community.

Additionally, the FireWise community initiative, led by the NFPA, enhances community awareness and preparedness. It can help businesses stay informed, collaborate with neighbors and embrace wildfire safety as a continuing effort.

In the face of evolving wildfire challenges, together, we can build resilient communities that stand strong against the wildfire threat.


Bob Tull

Profile picture for user BobTull

Bob Tull

Bob Tull is an AVP, lead property consultant, Global Risk Solutions, at QBE North America.

He has over 40 years of experience in the insurance, construction and fire protection industries. He holds a B.S. in management from Widener University and is a Certified Safety Professional, LEED Green Associate and an active member of the National Fire Protection Association and American Association of Safety Professionals.

In addition to building his own home, Tull has been a first responder for 50 years and held rank as deputy chief. He currently serves as his fire department safety officer.

Risk of Underinsurance as Inflation Soars

Balancing inflation and claims payouts shows the importance of updating policy coverage.

Close-up image from behind of a hand holding a green gas pump up to a blue car

KEY TAKEAWAY:

--Outside experts play a vital role in accurately valuing the insured's belongings and providing like, kind and quality (LKQ) replacement products at best pricing.

----------

Inflation can have a significant impact on both policyholders and insurance companies. Failure to account for inflationary costs can result in underinsurance, where the insured value of the policy may fail to cover the actual costs of replacing or repairing damaged goods. This can leave policyholders facing financial burdens and disputes with insurance companies over coverage limits.

Let’s explore the importance of updated policy coverage and how insurance carriers and adjusters can help insureds recover under existing coverages.

Rising Costs of Goods Quickly Eats up Policy Coverage

As inflation drives up the prices of products and services, the existing coverage value may no longer support actual product replacement costs. This can leave policyholders bearing most of the replacement costs for structure and contents. 

Labor Shortages and Delays Affect Replacement Costs

Labor shortages and manufacturing or shipping delays can complicate the inflation and insurance coverage dilemma. With supply chain disruptions, certain items may become unavailable or difficult to replace. Even if replacement options are available, they will likely come at a higher cost. This can complicate the claims process and result in delays or unsatisfactory compensation for claimants. 

See also: What to Do About Rising Inflation?

How Carriers and Adjusters Can Help the Insured Recover More

Insurance carriers may try to save costs by avoiding hiring outside experts to perform contents valuations. However, this cost-saving measure can have long-term consequences, affecting the policyholder-carrier relationship. Outside experts play a vital role in accurately valuing the insured's belongings and providing like, kind and quality (LKQ) replacement products at best pricing.

Contents valuations enable the insured to recover more under the policy parameters. Without the help of contents valuators, carriers may appear to underpay policyholders and be seen as failing to provide adequate coverage.

Carriers should also offer additional help to the insured by allowing complete valuation of all loss items. Continuing the pricing past the policy limit allows the insured to use that data to possibly recoup their losses through deductions on their taxes.

Communicating the Importance of Updating Policies to Compensate for Inflationary Impact

Policyholders need to be aware of the importance of updating their policies to compensate for the inflationary impact of rising costs. This awareness gives them the opportunity of whole recovery during the claim process.

Similarly, insurance carriers must recognize the value of expertise and avoid short-term cost-cutting measures that can result in low policyholder confidence. By recognizing the negative impact of inflated goods, carriers can support policyholders by allowing for expert valuations of products to recover more under the policy parameters.

Awareness on the part of policyholders and insurance companies is crucial to account for the inflationary impact of rising costs, thus avoiding inadequate coverage and underpayment.


Beth Nelson

Profile picture for user BethNelson

Beth Nelson

Beth Nelson is CEO of Claimplus, of Irving TX, North America’s longest-established property insurance contents valuation firm since 1976. Contact her at claims@claimplusonline.com.

An Interview with Mark Breading

In this interview, Paul Carroll, Editor-in-Chief of Insurance Thought Leadership, talks with Mark Breading, Senior Partner at ReSource Pro Consulting, about the latest trends in the insurance industry.

interview with mark breading

Insurance Thought Leadership:

Mark, it’s great to have a chance to catch up a bit.

I saw that Hub International recently took a minority investment that put its valuation at $23 billion. It, Acrisure and some others have been so acquisitive that I’m reminded of a cartoon I saw back in the early 1990s when all of corporate America was in the middle of a takeover binge. The cartoon showed a table of stock prices from the New York Stock Exchange, but there was only one name listed: IBMGEAT&TMicrosoftIntel etc. There were probably 20 more names tacked on.

With that as prelude, what are you seeing in terms of agency consolidation?

Mark Breading:

It's a really dynamic environment and has been for the last number of years, but it's kind of interesting because the number of retail agencies in the U.S. remains relatively constant. There has been all kinds of acquisition activity in the last two years, with about 1,000 agencies acquired each year. Yet, if I look back in history, in 2000, there were 42,000 retail agencies in the U.S. By 2010, the number dipped to 38,000. But by 2022, it's back to 40,000. So, while there were 1,000 agencies acquired every year in the last number of years, more than 1,000 agencies are being launched every year.

Now, to your point about all the aggregators out there, I’ve been blown away by how fast some of them have grown. Some came out of nowhere. There are many stories where, five years ago, a company was valued at $50 million, and now they are valued at $400 million.

On the one hand, these aggregators are snapping up agencies left and right. On the other hand, there's still lots of new activity going on with small agencies. And if you look at the 40,000 to 42,000 that are out there now, most of them are still small. A third of them are still less than $150,000 in revenue – literally a mom and pop around the kitchen table, and that's their living. I think around 60% are less than $500,000 in agency revenue.

There are still lots of small, independent agencies out there, and that makes for an interesting environment.

Insurance Thought Leadership:

I hadn't really thought about all the new agencies sort of filling in for the others that have disappeared because they were acquired.

Does the aggregator model work? In theory, it does, but I certainly have covered some rollups over the years that have not done well.

Mark Breading:

I think we're going to have the answer to that question in the next two or three years. Over the last, say, five years, the aggregators have been very active in acquisitions. In many cases, they let those agencies continue to run independently. But if the aggregators are going to be successful going forward, they have to start to think enterprise, right? How do we optimize our technology, our people management, our partnerships and our relationships?

I can't imagine how they could continue to grow and be successful running hundreds of little agencies.

The aggregators are right at that stage where they need to think about broader platforms and enterprise strategies. Some of them have started to roll up the little brands into the mother brand, but others have left those companies to still just do their own thing.

Insurance Thought Leadership:

That's always the tension. I don't know if I ever sent you a copy, but Chunka Mui and I wrote a book called “Billion Dollar Lessons” that we published in 2008, based on extensive research into 2,500 business failures, and one of the seven major patterns of failure we identified was rollups. They look great for a while, and then, as you say, there comes that point where you either have to start doing something differently or you aren't going to get the value out of the acquisitions. But once you start doing things differently, you can screw up the secret sauce that was making these businesses successful in the first place.

Mark Breading:

There are certainly acquisitions where the aggregators are acquiring agencies of reasonable size, and they're more corporate, so they fit better into the enterprise. But if you're buying a local agency that has 10 employees or 20 employees, and they just serve that local community, it's hard to all of a sudden make that agency part of this big corporate enterprise. If you start telling them, Here's how you have to do business, and we're going to change your brand, it's hard to keep people. They liked working local and for that local agency.

A big challenge for a lot of these aggregators is, How do you retain the talent, keeping not just the producers but the customer service reps and others who are involved in that agency?

Insurance Thought Leadership:

What do you think interest rates will do? It's one thing to be buying up agencies when money is essentially free, but when money is now costing you 6%, or whatever the right number is, that theoretically changes the dynamics some.

Mark Breading:

Yes, it does. We’ve seen that play out a little bit in the insurtech space, but there were still almost 1,000 agency acquisitions last year, and interest rates were higher toward the end of last year than they are now. The pace of acquisitions may slow a little bit, but it seems they’ll continue because the business model requires aggregators to keep buying, at least for a while.

Insurance Thought Leadership:

What other trends are you seeing?

Mark Breading:

I’m seeing a couple of other big trends. One is that the MGA [managing general agency] model is expanding rapidly. There are over 1,000 MGAs in the U.S. now, and we've tracked something like 125 startup insurtech MGAs. In the last few years, we’ve looked at their business models, and about 60% start out as what we have called line-focused or segment-focused. Some might focus only on cyber or

perhaps flood or some other specific peril or say we're just going after the Hispanic segment in the Southwest. As these MGAs grow, of course, they'll either sell or expand.

All these new MGAs are digital natives, so they're investing in tech. If you go back 10 to 20 years, MGAs never wanted to spend a nickel on technology. They relied on their risk expertise in specific areas and on their relationships downstream with independent agencies as well as upstream with underwriting companies. Now they have to be very sophisticated digitally.

The other trend is that there's a lot of activity in new partnerships. Every distributor is trying to figure out how to reach their preferred market segment, so they’re trying to find carriers that want to write the kind of business they want to sell and to leverage the relationships they have with businesses and individuals.

Maybe an agency never worked with an MGA or a wholesaler before, but now they're partnering. Or maybe the agency is expanding their panel of carriers to whom they submit business to add the same capability from the carrier side.

Should they launch their own MGA or work with the wholesalers? Should they do embedded insurance to reach affinity groups?

I see a lot of really interesting activity going on with partnership strategies and new partnerships.

Insurance Thought Leadership:

Have you seen a particularly good example of a partnership?

Mark Breading:

Some are really interesting to watch to see how they develop, such as what Amazon has done with their Marketplace. They are connected with millions of small businesses and are offering professional liability insurance or workers’ comp or whatever via a partnership with Marsh, which is then connected into Hiscox and a number of others. The jury is still out on whether they’ll succeed.

In the workers’ comp space, many are starting to partner with payroll providers, because payroll providers tend to already have a portal into businesses.

Embedded insurance is a whole other dimension, as well.

Insurance Thought Leadership:

The Amazon deal will be fascinating to watch. The potential is huge, just given the reach of Amazon, but, yes, they have to get it right. Operating at their sort of scale, you can go wrong in a big way pretty quickly.

You mention embedded insurance. I have been a big fan but have recently cooled a bit on it because I haven't seen much exciting. What are you seeing?

Mark Breading:

Yeah, I think it's an important trend, but it has been overhyped, for sure.

Part of the issue is that people have different definitions of what they consider embedded insurance Root announced a partnership with NASCAR as an embedded insurance proposition. But it's not. It's just an affinity relationship.

In my view. If you're really talking about embedded insurance, you're talking about the insurance as being almost invisible at the point of service. It's a quick “yes,” “click this” or make a couple of choices and you’ve got insurance, just like travel insurance has always been.

That's starting to happen in personal auto. Obviously, the Teslas of the world are leading, but other OEMs are also doing it. There is still not a huge take up, though. Most personal auto insurance is still sold through agents, despite all the digital options.

There are areas like warranty and travel, where it's always been. Perhaps embedded insurance makes sense for gig workers and on-demand insurance. But I don't think there's going to be much at all in the whole commercial space, outside of maybe for micro businesses. With business with employees and property and vehicles and liability and so on, I just don't see how you're going to make insurance more invisible. You need advice.

McKinsey had a report a couple of years ago that said that, by 2030, 30% of all insurance is going to be embedded. Perhaps they'll prove me wrong, but I don't think we're going to be there.

Insurance Thought Leadership:

Yeah, 30% sounds like one of those made-up numbers.

Mark Breading:

I'm with you.

Insurance Thought Leadership:

That's really it. That's the sort of overview I was hoping for. Are there any things you're seeing that you think are relevant that I didn't ask you about?

Mark Breading:

The only other thing is that there's a lot of technology activity going on to improve the whole transaction flow between agents and carriers. Everybody is upping their game digitally. A lot of the research we've done has been trying to help people understand: What do agencies want? What are carriers building? And how do we bring them together better so they can everybody’s whole game for the entire ecosystem?

Insurance Thought Leadership:

A worthy goal.

Mark, thanks so much for your time and expertise.


About Mark Breading, Senior Partner, ReSource Pro Consulting

Mark Breading Headshot

Mark Breading is known for his insights on the future of the insurance industry and innovative uses of technology. Mark leverages his background in strategy, marketing, and technology to consult with insurers and technology companies on forward thinking strategies for success in the digital age, where his inventive methodologies, fresh ideas, creative conceptualizations, and ability to incorporate InsurTech and transformational tech in business strategies is unparalleled. His thought leadership in the areas of distribution strategies, InsurTech, transformational technologies, and digital strategies has earned him a ranking as a "Top Global Influencer in InsurTech" by InsurTech News.

Mark spent 25 years with IBM, where he co-developed IBM’s Account Based Marketing program and led the global project office to implement ABM across all industry verticals worldwide. Mark was instrumental in the success of Strategy Meets Action from the early startup phase through its acquisition by ReSource Pro in 2020.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

Role of Ransomware in Cyber Insurance

Fewer than half of firms have policies that cover "critical risks," including ransomware, ransom negotiations and ransom payments.

Green and blue lit up digital elements -- a computer and code and artificial intelligence

Ransomware accounts for a staggering 75% of all cyber insurance claims, a significant jump from 55% in 2016. However, new research from Delinea finds that fewer than half of respondents reported having policies that cover "critical risks," including ransomware, ransom negotiations and ransom payments.

The Ransomware Surge and Its Connection to Cyber Insurance 

With ransomware attacks on the rise, and no signs of slowing, cyber insurance companies have had to evolve quickly. Cyber insurance companies have started considering their own risks and exposure and have raised premiums and increased their cybersecurity requirements before granting coverage. Carriers are looking more closely at how well organizations follow security best practices, such as access control, multi-factor authentication (MFA) and the principle of least privilege. 

Some insurance companies have started pulling back and insuring less or putting more limitations on their policies. For example, many cyber insurers may deny claims due to lack of security controls, acts of war or terrorism, not following compliance procedures and even simple human error – if an incident or ransomware attack is caused or worsened by misconfigurations, insurance companies can argue that it could have been prevented and deny incident claims.

It is extremely important to follow cybersecurity best practices and fully understand your cyber insurance policy to ensure you get the coverage you expect in the event of an attack.  

Understanding Your Cyber Insurance Policy 

It is clear that cyber insurance won’t cover all security incident costs. Many insurance companies will not pay ransomware costs or even help cover all of the costs involved. Oftentimes, organizations must accept the consequences of an attack and, even with insurance, will have to cover the costs to get back on track.

According to Delinea’s research, insurance companies are least likely to cover lost revenue, regulatory fines, legal fees and ransomware payments. Instead, the expenses most often repaid by insurance were the costs associated with data recovery and incident response costs. As ransom attacks become more and more common, insurers will continue to modify their ransomware protection to reduce the level of coverage they offer.

Every insurance policy is different, so it is important to review yours carefully, and often to know exactly what your cyber insurance will and will not pay for and ensure that you are meeting their requirements. 

See also: Does Cyber Insurance Add to Ransomware?

Navigating the Complex Cyber Insurance Landscape 

The evolving landscape of cyber insurance requires careful consideration and preparation, especially when it comes to protecting against prospective ransomware attacks. To secure comprehensive cyber insurance coverage while managing costs, organizations must address the following aspects: 

  1. Security Controls: Organizations should implement robust security controls to reduce exposure to ransomware risks. Identity and access controls, password vaults and MFA are must-haves for any organization seeking insurance. These controls can also help minimize potential insurance payouts. 
  2. Budget Planning: It is important to allocate a budget for purchasing necessary technical solutions and for hiring skilled workers to meet the higher security standards required by insurance providers. 
  3. Risk Assessment: The insurance industry evaluates cyber risk using various models and metrics. Organizations must ensure they understand these metrics and are prepared to demonstrate commitment to cybersecurity risk controls. 
  4. Insurance Checklists: Businesses should look into various cyber insurance checklists to ensure they meet the minimum requirements set by insurers. There are also numerous cyber insurance questionnaires available that help businesses have well-informed responses ready for any question insurance companies may ask. 

Cyber insurance should complement a comprehensive cybersecurity program that includes employee training, robust security protocols, regular vulnerability assessments and well-defined incident response plans. With the cyber insurance landscape rapidly changing, and ransomware continuing to rise, it's important to stay informed about evolving insurance policies and industry best practices.

By taking steps to improve your cybersecurity posture and meet your insurance requirements, you can ensure that your organization is well protected and prepared for any adversaries.


Joseph Carson

Profile picture for user JosephCarson

Joseph Carson

Joseph Carson is the chief security scientist and advisory CISO at Delinea.

He has more than 25 years of experience in enterprise security and infrastructure. Carson is an active member of the cybersecurity community and a certified information systems security professional (CISSP). He is also a cybersecurity adviser to several governments, critical infrastructure organizations and financial and transportation industries, He speaks at conferences globally.

Supply Chain 4.0: The Digital Transformation

Blockchain and artificial intelligence are redefining the dynamics of supply chain operations and reshaping the future of industry. 

Geometric rainbow shapes against a black background

The advent of Supply Chain 4.0 marks a transformative shift in the landscape of logistics.

As we stand at the threshold of the Fourth Industrial Revolution, two key technologies - blockchain and artificial intelligence (AI) - are poised to redefine the dynamics of supply chain operations. These digital tools harbor the potential not only to revolutionize the efficiency and transparency of supply chains but also to propel organizations toward unprecedented levels of growth and competitive advantage.

In this article, we delve into the impact of these game-changing technologies on supply chain digitization and how they will shape the future of industry.

What Is Supply Chain 4.0?

Supply Chain 4.0 is the term for the modern, digital era of supply chain management, powered by innovative technologies like blockchain and AI. The "4.0" denotes its place in the “Fourth Industrial Revolution,” following the internet-based advancements of Supply Chain 3.0.

In this new paradigm, supply chains are becoming more efficient, transparent and agile. With the integration of digital technologies, traditional linear supply chains are evolving into dynamic, connected systems. These systems leverage data analytics, automation and machine learning to optimize operations, predict market changes and make strategic decisions. The ultimate goal of Supply Chain 4.0 is to create a fully integrated, automated and transparent supply chain that is resilient to disruptions and capable of self-regulation.

How Are AI and Blockchain Used in Supply Chains?

Artificial intelligence and blockchain have distinctive applications in the realm of supply chain management, each contributing unique capabilities that enhance operational efficiency and transparency.

AI's role in supply chains is predominantly centered on data analysis and prediction. Advanced machine learning algorithms can process vast quantities of data, deriving insights about market trends, consumer behavior and potential disruptions. This information enables organizations to anticipate demand, optimize inventory and streamline logistics, resulting in improved efficiency and customer satisfaction. Additionally, AI-powered automation can handle repetitive tasks, freeing human resources for more strategic roles.

Blockchain, on the other hand, brings transparency and traceability to supply chains. It creates a decentralized, immutable ledger of all transactions, ensuring that every step in the supply chain is documented and verifiable. This transparency mitigates risks associated with fraud or counterfeiting and enhances accountability among all stakeholders. Furthermore, smart contracts - self-executing contracts with the terms of the agreement directly written into code - can automate transactions, further increasing efficiency and reducing the potential for disputes.

The synergy of AI and blockchain technologies in Supply Chain 4.0 creates a robust, transparent and agile system capable of adapting to the rapidly evolving demands of the digital age.

See also: Growing Risks From Quantum Computing

How Will Supply Chains Benefit From the 4.0 Revolution?

The benefits of Supply Chain 4.0 are manifold and far-reaching. At the core of these advantages is improved efficiency. By leveraging AI and blockchain, organizations can automate manual tasks, reducing human error and streamlining processes. This leads to significant time and cost savings. 

Secondly, these technologies enhance transparency across the supply chain. Blockchain, for instance, offers a secure, immutable ledger of transactions, enabling real-time tracking of goods and ensuring accountability at every step. 

Another key benefit is agility. AI's predictive capabilities allow for timely detection and handling of potential disruptions. It empowers organizations to adapt quickly to market changes and customer demands. Moreover, the integration of digital technologies within the supply chain fosters innovation. It provides a platform for continuously testing, learning and improving strategies, thus driving competitiveness. 

Lastly, Supply Chain 4.0 promotes sustainability by enabling smarter resource allocation, reducing waste and facilitating the implementation of green supply chain practices. For instance, AI can play a pivotal role in improving sustainability by optimizing logistics and distribution routes. Using predictive analytics and machine learning algorithms, AI can analyze complex patterns and trends, taking into account factors such as weather, traffic and fuel consumption. By suggesting the most efficient routes, it helps reduce fuel usage and, consequently, carbon emissions.

Conclusion: Moving Toward a Supply Chain Revolution

In conclusion, Supply Chain 4.0, underpinned by revolutionary technologies like AI and blockchain, holds the promise of a more efficient, transparent and sustainable future. It offers businesses a competitive edge, enabling them to navigate the complexities of the digital era with agility and innovation. As we move forward, businesses need to embrace these digital transformations, harnessing their potential to drive growth, enhance customer satisfaction and contribute to a sustainable future. The revolution is here, and it is reshaping the way we think about and manage supply chains.


David Evans

Profile picture for user DavidEvans

David Evans

David Evans is a freelance writer covering sustainability challenges and solutions. He writes to help companies and consumers understand the environmental and ethical challenges in products and their supply chains so we can find viable solutions for both. See more of his writing at: Plastic.Education.

An Interview With Pat Schmid

ITL's Paul Carroll interviewed blockchain expert Pat Schmid, highlighting advancements in enterprise blockchain, particularly the transformative potential of "Rapid X" in streamlining claims processing.

Pat Schmid
Pat Schmid Headshot

Patrick Schmid, PhD, MA, is president of The Institutes RiskStream Collaborative. He previously headed The Institutes’ Enterprise Research Department; served as director of research for the Insurance Research Council (IRC), a division of The Institutes; and worked as an economist for Moody’s Analytics. Schmid has taught economics and finance at Philadelphia colleges and universities.


Paul Carroll

The last time we talked, you had a couple of use cases, in particular, that were moving along well. To set the stage, would you tell us what the state of play is now.

Pat Schmid

It's been interesting. The consortium has done a very good job of developing an efficient platform, which we call Canopy. This was critical to ensure that costs are reasonable to build and adopt various solutions, which would be done on top of Canopy. Over the past couple of years, we’ve developed the platform to the point where we can build and move forward with a variety of different use cases and a variety of different use case types.

In the past, when we've chatted, we've primarily focused on network-based use cases like Rapid X, the loss data exchange solution for auto insurers. With that application, for small or medium-sized organizations to get the large benefits associated with it, the largest carriers would likely need to be on the network. This, at times, created a kind of chicken-and-egg problem for the consortium, because a similar notion also affects the large players. The benefit of being on the network is based on others joining in, too.

To obtain strategic advice and tackle that challenge, we formed an auto insurance advisory committee that consists of representatives from eight out of the top 10 auto insurance companies. Many of these companies have signed a letter of intent to adopt RAPID X and were, therefore, committed to expanding the network. We are now planning to pilot the Rapid X solution with three companies in the fall; all three are top-15 auto insurance companies. We're keeping the pilot, which will leverage production data, small to move more quickly. We’re very excited because this advisory group has helped us understand that the value of RAPID X may be leveraged in other ways, like displacing various companies’ third-party claims portals. This may make the value to a carrier less dependent on the network adoption of other carriers, which could overcome the chicken-or-egg problem.

We've also been recognizing that what we’re calling linear use cases or partnership use cases can emerge and take off quickly. We recently started a working group that was looking into whether there might be a use case for a parametric trigger using smart contracts on a blockchain for homeowners’ parametric reinsurance. Basically, could the cedant-to-reinsurer parametric contract be automated with blockchain-enabled smart contracts?

As we did that, we were introduced to a technology company called Arbol, which had a contract they were working on with a Florida-based insurance company called Centauri, and they actually leveraged a parametric product during Hurricane Ian and had a $10 million payout. They were looking to automate and put the product on a blockchain platform, so we talked to them about Canopy, and within months this application was built and moved to production. This app is live on Canopy. It actually just won the Insurer Insider Honours “Underwriting Innovation of the Year” award, and RiskStream/Arbol held a summit to start to think about other uses of the application.

Whether it’s the network-based apps or linear/partnership apps, I think we're beginning to see a lot of light at the end of the tunnel within enterprise blockchain use cases in insurance. I think there will be

applications here over the next year or so that will be live and will provide significant operational efficiencies to the industry.

Paul Carroll

For those who aren’t familiar with Rapid X, could you say a bit about how it works and what its benefits are?

Pat Schmid

Sure. It's an auto insurance data exchange solution that allows a carrier’s claims system to exchange information and data, automatically and securely, with another carrier’s claims system. This is done today in less secure ways. To give an example: Let’s say a policyholder with Liberty Mutual calls in with a loss. Liberty will record the first notice of loss within their (let’s say Guidewire) claim system. That Guidewire system can integrate Liberty’s claims system to their Canopy node on our decentralized network of nodes for insurance carriers. Let's say the Liberty Mutual policyholder was in an accident with someone from Allstate. The data from Liberty Mutual’s claims system can be sent from the Liberty node over to the Allstate node in a permissioned and private manner. This node can integrate into Allstate’s claims system, which could be Guidewire, Duck Creek or some other, homegrown claim system. So, by the time the Allstate policyholder calls in, Allstate may already have information on the claim, which will expedite the process on the phone and make for a better customer experience. Our solution also lets their nodes exchange information as they fill in data in their individual claims systems, reducing the back-and-forth between the two companies as they determine liability and so on.

We’re not recording the data on the blockchain itself, by design. The blockchain is simply a state machine for network participants. It’s allowing the system’s state to update and providing access between those two parties to exchange information privately and much more securely than they do today.

On top of this foundation, we’ve started to add capabilities. One that's really interesting was brought to us independently by two top-five personal auto insurers. Most of the top insurance companies in personal auto have third-party portals that can provide data to other companies, so employees don’t have to handle lots of calls. The challenge is advertising to their competitors whether they have a third-party claims portal and where to go. There’s really no benefit for a company maintaining their own third-party portal. So these two companies suggested creating an industry “universal portal” so even small companies that don’t have a third-party portal and that aren’t on the Rapid X network can use it and help make the whole industry more efficient. This will likely leverage RAPID X as a back end and allow RAPID X participants to engage (with a much smaller data set) with those not yet on the network.

We’re also looking into adding an auto insurance fraud detection solution. While RiskStream is known for blockchain, our sweet spot is where multiple parties are involved in an issue. We can use any appropriate technology to solve those multiparty business process challenges. For detecting fraud from double-dipping, enterprise blockchain may not be the best tool because generally you need to pool the data to detect it. The industry is, for good reason, concerned about pooling data because of security and privacy issues. But technology can let the industry pool data confidentially (using what’s known as confidential computing).

Imagine this confidential computing platform to be a black box that no one owns, including RiskStream. No one can get the data from within it. But it's part of the RAPID X network, and Rapid X can start to feed it (with tiny bits of private, secure information) after each exchange between two RAPID X users. To continue with the example I used before, when Liberty Mutual and Allstate resolve that claim using Rapid X, it feeds a little bit of data into this confidential computing platform. Then, imagine CSAA comes to the table with a claim with Nationwide later. They can query the confidential computing platform to see, for instance, if that exact VIN has been involved in another incident with another insurer on the network recently. None of the parties will have access to the data, but they can query it to obtain a warning of double-dipping fraud.

Paul Carroll

I can imagine all kinds of benefits. Is there any way to quantify them in terms of time saved? Money saved? Something else?

Pat Schmid

We conducted a study on this, but at that time it was based on various assumptions. With the pilot, we’ll be using production data, so we’ll have real information on the ROI in a couple of months.

Paul Carroll

What did you find in the earlier analysis? I know it's not as complete as the pilot will be.

Pat Schmid

Our previous report on Rapid X ranged between $62 million and $173 million in savings industrywide.

In the Liberty Mutual/Allstate example I was sharing before, the first benefit would be that Allstate would reduce the amount of time needed to transmit information from the policyholder to their system of record. The second benefit is that the effort exerted in data exchange would be reduced. In our working group, among a large number of carriers, we were shocked to learn that the average claim requires five points of contact back and forth. These are all manual, normally conducted by phone or electronic communication, then often keyed into the respective claims system. That’s very inefficient and may not be maximizing privacy and security. The third benefit is the reduced reliance on external vendors that charge carriers for the data used in claims prefill. The fourth benefit is that Rapid X has a simple liability feature that allows carriers to notify one another when liability is determined in certain cases. Finally, there is a reduction in overall cycle time, which will lead to a better customer experience on both sides.

Our members think there's vast potential here and see possibilities for extension to a suite of surrounding products, including fraud detection, broader liability determination, subrogation and salvage. The big question is: Can The Institutes and RiskStream get the industry participants to work together? We're showing through our advisory groups, our pilots and our working groups that we can, and that has been a challenge for other enterprise blockchain initiatives. That's the big step. Once companies start to move to production, we think we will cross the chasm, so to speak. This will lead to a snowball effect. So we're close, but we have a little more work to do.

Paul Carroll

You have an awful lot of the big players, and the small players tend to follow the big players. And correct me if I’m wrong, but I don’t see any competitive reason for companies not to work together on Rapid X. There might be logistical issues, but I don’t see a business reason not to do it.

Pat Schmid

I agree. And the nice thing for a lot of these larger insurers is that they're operating across different lines of insurance, and we have other solutions that can be beneficial to them in other areas. We have use cases in surety bonds, for example. We're also going to be starting up a working group in commercial property and recently launched a lab in inland marine. We have several use cases in the life and annuities market. So, industry players like Nationwide or Cincinnati Financial, for example, that operate in all of the above, have benefits in supporting our initiative because theoretically they're going to want these efficiency gains for surety bonds, but they’re also going to want it for commercial property, and they're going to want it for life and annuities.

On that note, surety is actually our largest initiative, by far. It's global in scope. We've been working with five international surety associations: the International Credit Insurance & Surety Association (ICISA), the Canadian Surety Association, the National Association of Surety Bond Producers, the Surety & Fidelity Association of America and the Panamerican Surety Association. At the outset, these entities supported the effort to create a surety network. Since then, we’ve worked with the industry on two use cases. The surety industry is riddled with complexity and paper because of all the disparate parties: You have the obligee, the surety, the agent, the principal, all involved in verification. So there’s a variety of parties involved in a manual, paper-based process that could be digitized. Thus far, we’ve created an application for a power of attorney document that is created as an NFT [non-fungible token] and digitally verified across the various parties. Since then, we've more moved to the bond itself, again creating an NFT to track delivery and verification.

Now we’re working with large core system providers such as BondPro, Surety2000, Tinubu and Xenex to integrate various systems to the nodes. This will help as we’re now moving to engage obligees. The work has received a lot of attention in the surety space. I wouldn’t have predicted that sector would be so supportive of technology solutions, but enterprise blockchain has been of deep interest to them. I think the key reason is multiparty business process challenges. That’s the sweet spot for enterprise blockchain.

Paul Carroll

If we talk in a year or two, what do you think will be the headlines for blockchain? It sounds like Rapid X is a big one. Surety bonds would be a big one. What else?

Pat Schmid

I see Rapid X moving to production and starting to provide business benefit. Those additional features will likely start to be leveraged, as well – the fraud detection and universal portal, for example. Others may, too, such as assistance with subrogation and increased efficiency in the title transfer process in salvage.

I do think the surety bonds initiative will move to production here over the next year to year and a half in power of attorney verification and bond delivery/verification and probably start to move forward in some other areas, as well.

We'll start to see progress in other sectors, especially life and annuities. The lead there is what we are calling the Mortality Monitor, which allows network participants to securely and privately share certain data on a deceased party in a permissioned manner, provided another network participant also has the deceased as a policyholder. If the industry can find ways for the carrier to learn of the death quicker, the beneficiary reward process is also going to be expedited, which is going to benefit everyone.

I think payments is also ripe for change. As you’ve seen with the use cases I’ve mentioned, a lot of focus has been on data exchange and verification within claims and underwriting, but it’s likely payments use cases will come to light in the next few years. I think these will move very quickly when the time is right.

Finally, I anticipate that insurtechs with innovative solutions will get involved and that partnership use cases can move very quickly, as Arbol did. We have the technology platform today, and we have the business network of all these large carriers, brokers and reinsurers, so if you bring a good idea to the table it can move really quickly to production and provide business benefit.

Paul Carroll

The whole effort sounds so much more robust than when we talked last. Is there anything else you want to highlight that I haven't thought to ask about?

Pat Schmid

The only other thing I’d mention is RiskStream is here to help the industry on multiparty business processes. While enterprise blockchain has been and will remain our focus, a lot of attention has recently been on AI, and our members have asked about multiparty usages of this technology and whether RiskStream could potentially work on related solutions. Again, our focus is enterprise blockchain, but if the industry has an example where there’s a multiparty use of AI, there may be an opportunity RiskStream could look into. To better understand this, RiskStream is preparing an educational series on multiparty AI usage in insurance in the winter. Stay tuned for more on that.

Paul Carroll

This was great, Pat, as always. Thanks.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.