Download

Why Can't People Think Straight?

Analysis of the 49ers' loss to the Browns on Sunday provides a perfect example of a cognitive blind spot that hinders innovation.  

Image
Football laying on field

I come from a long line of people who scream at the TV when our Steelers are playing. My Dad taught my siblings and me well, and I've done my fatherly duty by passing the passion along to my two daughters. When the younger one was watching a Steelers game in college, a fellow student knocked on her door, said he'd heard a lot of yelling and wanted to be sure "you guys are all okay." My daughter was watching the game by herself.

I'm proud of you, Clare.

As you might imagine, I can be a tad critical of what the announcers say. But I was especially struck by the analysis by the TV pundits following the Cleveland Browns' upset of the San Francisco 49ers on Sunday. 

The pundits praised the Browns and denigrated the 49ers as though the outcome had never been in doubt. But, but, but... the 49ers had a 41-yard field goal attempt with six seconds to go that would have won the game, and NFL kickers are about 85% successful from that distance. The Browns didn't just need a coin flip to win the game; they needed the equivalent of calling a coin flip right three times in a row. 

Yet, given how the human mind works, everything about the game was viewed by the pundits based on the fact that the 49ers' kick leaked slightly outside the right goalpost. Had that kick been a yard or so to the left, the pundits would have had a completely different interpretation -- those gritty 49ers, etc.

I don't mean to trash TV football pundits -- well, maybe a few of them... but not more than half... two-thirds at the most -- but wanted to point to the faulty analysis of the game because it demonstrates a serious cognitive bias that's baked into us humans. 

It's called survivor bias, and it's a real threat to innovation. 

As much as it hurts me to be kind to the Browns (Pittsburghers call them "the Brownies"), their defense was awesome, and they mostly outplayed the 49ers. The win also makes for a great story. The Browns were without their injured $230 million quarterback Deshaun Watson and instead started a journeyman who had been in the XFL four years ago. Yet the Browns beat a team that was generally considered to be the best in the league.

After the game, the TV pundits could only sing the praises of the Browns. For instance, former Dallas head coach Jason Garrett said on "Football Night in America": “The guys on the defensive line for Cleveland were owning the line of scrimmage.... [49er quarterback Brock Purdy] certainly came down to Earth today. Struggled with the conditions, a lot of balls were slipping out of his hands, he wasn’t accurate…he just didn’t play as we’ve seen him play to this point.”

Everything he said is true, but neither he nor any of the other analysts said anything about how lucky the Browns had to be to win the game. Even before the field goal attempt by the 49ers that gave them an 85% chance of winning, the Browns benefited from a phantom unnecessary roughness penalty on what would be their final drive of the game (a clear error demonstrated by exhaustive replay analysis). Rather than face fourth-and-10 against a ferocious defense, the Browns picked up 15 yards and a first down, on their way to the field goal that provided the 19-17 margin of victory.

Just imagine how the take on Purdy would have differed if the 49ers had made the field goal. All his struggles would have been noted, but the narrative would have been about how the second-year quarterback, the last pick in the 2022 draft, had survived a brutal challenge from the Cleveland defense. He had marched the 49ers 52 yards down the field with time running out and had set up a field goal that kept his team undefeated. Why, he might be the new Tom Brady.

Purdy for MVP! Purdy for President!

There is certainly some smart analysis in football. (Looking at you, Ryan Clark and Bill Barnwell.) And that kind of analysis needs to be brought to insurance and innovation.

Barnwell actually accomplishes a lot based on just a single, simple adjustment to win-loss records. Rather than decide that some teams have a talent for winning close games, he believes that games decided by seven points or less are essentially coin flips. So, all a team's close wins become half-wins for analytical purposes, as do close losses. Based on that adjustment, he predicted, for instance, that the Minnesota Vikings would tumble from their 13-4 record last season, because they were 9-0 in close games. Sure enough, the Vikings began this season 1-4. (Barnwell also predicted that my Steelers will have their first losing season in Mike Tomlin's 17 years as head coach, but he can be wrong sometimes... I hope.)

The problem for corporate innovation efforts is that they are typically evaluated based simply on a win-loss record, without a Bill Barnwell on ESPN explaining the sorts of other issues that should be incorporated into the analysis.

Venture capital firms are built on the idea that nine out of 10 startups fail. You just have to be sure that the one success is so big that it covers for the others. In corporations, though, the people who keep moving up the corporate ladder are the ones with the unbroken string of wins, so the strivers don't want a one-in-10 chance of major success. They want a 10-in-10 chance of success, even if that success is small.

That's why, I believe, telematics adoption in cars is still so low even though its potential has been apparent for decades -- I, personally, first wrote about the technology almost 25 years ago -- and even though Progressive introduced its Snapshot capability 15 years ago. This need for guaranteed success is why take-up of the IoT has been so cautious, why companies are being so careful about the switch from the traditional "repair and replace" approach in insurance to a "predict & prevent" model, why so many companies are talking about the potential for generative AI but so few in insurance are actually exploring it in any significant way. 

Guarantees of small successes don't lead to breakthroughs.

The survivor bias is hard to shake, though. The first time I encountered it was in a great book on risk that talked about a ship full of Romans who were caught in a storm that was about to sink them but who prayed to the gods and survived. No one ever heard from the Romans who prayed to the gods and drowned, so how could anyone dispute the claims that the gods saved that one ship?

A very smart friend of mine once wrote a book about self-made billionaires and reported that they tended to be single-minded and made big bets. Great, but what about all the folks who were single-minded, made big bets and lost those bets? You could do a book about the benefits of buying lottery tickets if you just interview the winners.

We all fall victim to the sense that rich people must be smart. How else did they become so successful? But I've interviewed more billionaires than I can count and... hmmm. Lots are very impressive, but plenty just aren't. And I've interviewed loads of people who didn't make it big who struck me as much smarter than most of the billionaires -- such as the fellow who invented the iPad (but before the technology was quite ready) and launched an early form of eBay (but took ownership of the goods being auctioned, rather than just facilitating the exchange between private parties).

The survivor bias has even reared its head in academic research and has required corrective action. Papers on, say, the potential for new drugs get published when they find a statistically significant benefit, which generally means at least 95% likelihood. But research that doesn't find the desired result tends to not be published. Non-results are boring. So those reading the academic research see the survivors -- the studies that are 19 out of 20 certain of a positive link -- but not the potentially many other studies that found no link.

Government sponsors are increasingly requiring that all research be published, whether or not it produced an exciting result. And that sort of discipline needs to be brought to business.

Yes, those who have a sterling record of success might well be CEO material. But how big were their successes? Did they take any actual risks? What about the noble failures, the people who did take big risks and failed through no fault of their own? 

If we can get away from the survivor bias that people who succeed must be winners and can focus on rewarding noble efforts, we'll be much less cautious and more innovative as an industry.

Go, Steelers.

Paul

P.S. If you must know, my pet peeve with TV football analysts is their years-long claim that a receiver catching a 50-yard pass by outleaping a defender grabbed the ball "at its highest point." Paying even the slightest attention to physics, it's obvious that the ball reached its highest point when it was halfway to the receiver -- 25 yards or so upfield. At that point, the ball was 40 feet or more above the ground. While NFL players are exceptionally impressive athletes, no, it isn't possible for someone to catch a ball at its highest point, 40 feet or more in the air.

After years of my yelling at the TV, most announcers have changed their terminology and say a receiver "high-pointed" the ball when he makes a leaping catch on a long pass over a defender. That terminology doesn't make a lot of sense, but at least it's an improvement over grabbing "at the highest point."

Next, we'll get announcers to stop talking about "negative yardage" when they mean a loss and "positive yardage" when they mean a gain.

Here's hoping.

Go, Steelers. 
Redefining Insurance: Embracing AI, Data, and Innovation Beyond Policies

In this Future of Risk Forecast, Jim Jones shares his view of how technology is transforming insurance, and how he prepares students to succeed in this new landscape.

Jim Jones The Future of Risk Forecast


James R. Jones Headshot

Jim Jones is the Executive Director of the Katie School of Insurance and Risk Management at Illinois State University. The Katie School supports over 500 students majoring in risk management and insurance, actuarial science, and other majors who are interested in careers in insurance. He works with Katie School staff, the Dean of the College of Business, industry executives, departments chairs, and faculty in helping to develop talent for industry. Jones is Chair of the CPCU Society Ethics Committee.


Insurance Thought Leadership:

What technology now in the market do you believe will have the biggest transformative impact on insurance and risk management in the next 5 years?

Jim Jones:

All of the technologies that are helpful in predicting and preventing losses. The industry will need to distinguish itself by providing value for customers in doing more than just providing insurance policies. This could be smart IoT for homes, wearables to reduce worker injuries, or AI to help insureds better identify loss trends.

Insurance Thought Leadership:

What do you see as the biggest obstacles to insurance innovation, and how would you recommend overcoming them?

Jones:

Status quo bias is always the biggest obstacle. Past success has always been the greatest impediment to future innovation. Regulatory rigidity also is a real challenge to innovation, but can be overcome to some extent through regulatory sandboxes and the use of synthetic data to predict how innovations will impact customers.

Insurance Thought Leadership:

What is an area (or areas) that you believe remains untapped/unfulfilled/overlooked for the promise of innovation in insurance?

Jones:

The creation of a database of curated data that can be used by AI. Industry and regulators will be more comfortable with the AI recommendations if they know the data is accurate and valid.

Insurance Thought Leadership:

How do you believe AI will transform insurance and/or risk management?

Jones:

AI will transform every aspect of insurance, claims, underwriting, and distribution. I think professionals in the future will have limited careers if they do not understand how to leverage AI in their jobs.

Insurance Thought Leadership:

Have your programs changed or expanded to prepare tomorrow’s insurance and risk management professionals for working in new ways with technology and data?

Jones:

Yes, we have workshops and student research with real world clients in order for them to keep up to speed with changing technology and risk landscape.

Insurance Thought Leadership:

Has the wider application of technology in insurance changed how students view opportunities in the insurance industry?

Jones:

Once they see the opportunities, we have a much more diverse pool of talent interested in insurance. Insurance already has so much data and that is appealing to students who want to work with and analyze data. Other technology oriented students see the opportunity for technology in insurance related to AI and to cybersecurity.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

Cybersecurity Turns Attention to IoT

While the focus has been on IT infrastructure, insurers and clients are realizing the IoT creates the biggest attack surface for hackers.

Key in lock on a door

The nature of business risk has changed dramatically as cybersecurity attacks increase in volume, velocity and effectiveness. Data breaches have emerged as a new category of threat that can have catastrophic effects on a business of any size, and the growth of massive botnet armies controlled by threat actors signals that the attackers are becoming more powerful.

Cyber defenses have evolved in tandem, producing increasingly sophisticated solutions for the vast scale of threats organizations encounter as an inevitable result of leveraging the networking and computing infrastructure they need to compete in the modern business environment. Naturally, insurers began to develop processes and structure to serve their traditional role in guarding against this risk, but that development hasn’t proceeded smoothly. 

In recent years, to comprehend the scale of their liability compared with the policyholders’ ability to protect themselves, insurers implemented standards and policy exclusions that require organizations to do far more to secure their attack surface than ever before. If they can’t, these organizations face severe threats on two fronts: the inability to effectively guard against first-order threats to their system as well as the inability to take advantage of the appropriate financial tools to limit the resulting damage.

While these threats present a short-term challenge for many companies, they also reveal an opportunity for the medium and long term. Organizations that build a safe and insurable cybersecurity posture will be better positioned for growth than companies that choose not to invest in those tools and processes. Even if the organization chooses to self-insure, having insurance-worthy cyber hygiene measures in place can reduce potential damage.

Many organizations recognize the need to improve their security: According to market research firm Market.US, the global cloud security market is valued at $20.54 billion in 2023 and is projected to grow to nearly $150 billion by 2032.

Most of the focus is on IT infrastructure. But for many organizations today, the most efficient way to build a safe and insurable cybersecurity posture is to focus on IoT (internet of things) security.

See also: A New Approach to Cyber ​​Resilience

Why IoT?

IoT devices function differently than traditional IT computer systems. IoT devices have agents placed on them (the typical way IT systems are patched) and, until recently, could only be updated manually. Most organizations with IoT systems benefit by using them at scale – think of factory systems, transportation and logistics and automation systems that can physically exist anywhere (not just in datacenters). The devices must work as a team.

Naturally, this volume and sprawl makes manual updates prohibitively burdensome. As a result, more organizations than not are left with vulnerable, unpatched, out-of-date firmware on thousands of network-connected devices. This dynamic also produces a suboptimal organizational dynamic: Because devices need to be maintained manually on-site, they often fall under the authority of on-site teams rather than IT security experts. As a result, IoT networks generate the largest unsecured attack surface for most organizations. Any responsible approach to business risk will involve securing it. 

Why now?

In recent years, there have been high-profile disputes between insurers and their policyholders who filed claims on data breaches and other cybersecurity incidents, and it’s clear that insurers are recalibrating their approach to cyber risk. They are implementing far stricter requirements to qualify for coverage, and an organization effectively must accept the insurer's security requirements as mandates.

The best way for organizations to approach this shifting climate is to work with their insurer so there is a two-way flow of information and the terms of the policy can be customized to the specific business. This helps the insurer understand both the technical and business realities, and through that collaboration, organizations will gain insight into how regulations will develop over time. At the same time, organizations themselves must evolve and take a leadership role when securing their own systems to minimize their cyber insurance premiums.

See also: Cyber Insurance at Inflection Point

How to build a safe and insurable cybersecurity posture

An efficient ecosystem of asset and application discovery tools that leverage automation has delivered IT security teams the capacity to find threats faster than ever. However, because of their distinct technical properties, IoT networks have remained largely untouched by these advancements. At best, teams have been able to mitigate threats (e.g. through port blocking), but to move to true remediation requires a focus on both automation and scale.   

Organizations, first of all, must take advantage of the latest technology to secure their most vulnerable attack surfaces. For most organizations, this is IoT networks. Specifically, this means deploying agentless solutions that can support all types of IoT devices while managing the relationship among all devices and apps, along with their interaction with the broader network. IoT systems must be visible, operational and secure – no longer simply functional.  

Organizations must also change how they approach resolving potential threats, which for IoT are increasing in both volume and velocity. Until now, the focus for most security teams has been on mitigation, or limiting the damage after an attack. In the best case, teams limit the potential for an attacker to use a particular vulnerability. In other words, security limits the potential damage but does not eliminate the threat.

This approach, while eminently understandable considering the scale of modern threat environments, is outdated. Organizations now have the tools to remediate the threat and bring systems back to full operational status. 

Pairing discovery solutions with remediation solutions is an indispensable step toward establishing the cybersecurity posture necessary to do business efficiently and profitably in the modern threat environment. Naturally, companies should prioritize their most vulnerable attack surfaces – in many cases, IoT systems.

As recent CISA directives have shown, along with high-profile breaches from IoT entry points, visibility and security of IoT devices in tandem with all cloud assets must be a top priority for all businesses.

Organizations should develop collaborative relationships with their insurers to ensure that their underwriters have the appropriate level of knowledge and understanding of the landscape as well as how it evolves in real time. At the same time, they must accelerate investments in automation to bring all potential weak points, especially IoT, up to a standard of capability and resiliency that all stakeholders from the boardroom to insurers to the security team itself can feel confident about.

In this way, organizations that take advantage of the latest security technologies, especially as they relate to IoT, will be poised to grow unencumbered by the weight of unsecure, invisible networks accumulating risk as time goes on. 


Bud Broomhead

Profile picture for user BudBroomhead

Bud Broomhead

Bud Broomhead is the CEO of Viakoo, a leader in IoT device remediation.

He is a serial entrepreneur who has led successful software and storage companies for more than two decades. He has experience delivering computational and storage platforms to the physical security space for over seven years, with an emphasis on infrastructure solutions for video surveillance.

Unlocking the Power of Digital Payments

Agencies can take the fear out of digitizing payments through C.A.R.D., which stands for Collect, Apply, Reconcile and Disburse.

Two hands hold a credit card

Paper checks are a thing of the past. This was a shift many industries were starting to see prior to 2020, but the switch to digital payments really picked up speed during the pandemic when many consumers saw exchanging cash and checks as an unsafe option. According to McKinsey, nine in 10 people have begun using a form of digital payment since the start of the pandemic. 

Businesses have been forced to adapt. Insurance, unfortunately, was slow to join the digital payment revolution. Despite the high operational overhead that comes with collecting check payments, the pain of change and lack of core functionality and integration with accounting systems inhibit many agencies. Sometimes, the roadblock to adoption is simply not understanding how the technology works.

Fortunately, there’s an easy way to take the fear out of digital payments: C.A.R.D., which stands for Collect, Apply, Reconcile and Disburse. Using this framework to break down the collection process can help agents better understand what happens at each stage of the payment journey and feel more comfortable going digital.

Collect: Improve customer experience with more choices

The “Collect” phase covers the invoicing and billing portion of the payment process, focusing on the channel, payment choice and communication notifications. This part of the payment cycle delivers a better customer experience by offering choices and simple experiences, something consumers have come to expect in today’s online world. 

For example, insureds can pay their premiums through various channels, such as custom payment links, portals or unique payment pages, all of which allow insureds to pay much more quickly than they could when writing and mailing a paper check. Using these types of payment channels also cuts back on data input, reducing the risk of errors that come with manual entry while also keeping the data secure and only visible to those with permission to see it. Additionally, insureds are given a choice of payment methods that include ACH and major credit cards, many of which offer next-day funding – a win for both agents and customers! 

A digital payments solution also provides multiple communication channels between an agent and their insureds. Payment prompts and copies of receipts can be sent through emails or SMS text messages, creating a digital paper trail. 

See also: First Steps to Digital Payments Processes

Apply: Reduce errors with automatic credits to debits

After a client makes a payment, it must be credited appropriately. It can either be left on the client’s account or added to a specific policy or invoice. This is where “Apply” comes in. When using a digital payments solution, agents still have the option to manually apply these credits, or the solution can auto-apply those credits to debits.

Not only does automating the crediting process save agency staff time, but it significantly reduces the risk of errors, while improving security and compliance. Handling paper checks risks exposing client payment details such as bank account numbers and personal identification information. Using a digital payments solution allows the agency to create unique security and user permissions for its staff, ensuring they only have visibility to the accounts and payments pertinent to their role. Agencies and customers alike can take comfort in knowing sensitive information is safe and secure. 

An additional benefit of automating the “Apply” stage of the payment process is digitizing account activity. When payments are made online, account activities can be synced and tracked, making it easier to complete the audits needed to meet compliance requirements. 

Reconcile: Improve accuracy and reduce costs with auto-matching transactions

Once a payment is applied, the “Reconcile” stage begins. This is where an agency trues up the cash balances, payment deposits and management system receipts. Automating the reconciliation process creates an opportunity to auto-match and highlight payment transactions with general ledger receipts.

Automating this step is often the highest-value part of adopting digital payments for most agencies. It reduces the operational overhead needed to manually match transactions, eliminating low-value tasks and allowing staff to focus on new and renewal business servicing. It also improves accuracy because manual reconciliation allows for a large margin of human error that is removed when using a digital payments solution.

Disburse: Solve administrative hurdles when sending to carriers

The last stage in the digital payments journey is “Disburse,” which is where the payments are sent to the appropriate parties – typically carriers. This step may seem simple enough, but there are often obstacles when it comes to handling this step manually. Using a digital payments solution can solve administrative challenges such as storing carrier payment details more easily on files, initiating payments to appropriate entities and automating direct bill sweeps.

See also: Enhancing Claims Via Digital Payouts

A Few Things to Keep in Mind

Once an agency decides to take the plunge into digital payments, there are a few things to consider when choosing which solution is best, including:

  • Product Integration: Make sure the solution integrates natively with any existing management systems, customer portals and websites. This allows data to flow between the systems to automate the payments process.
  • Payment Choice: Agents should look into factors such as transaction volume limits, whether ACH and major credit cards are accepted, if next-day funding is allowed and if checkout pages allow insureds to choose partial payments and which invoices to pay.
  • Security and Compliance: For any payments solution to be valuable, it needs to be secure and comply with all PCI and NACHA regulatory guidelines. It should also have tokenized data, configurable security settings and capabilities to manage multi-branch/region security differences.
  • Reporting: To increase staff efficiency, agencies should consider a solution that provides real-time visibility on all payment transactions, sends real-time notifications to multiple designees, allows you to create customizable reports for actionable data and can intuitively offer insights and analytics into digital payments trends.

Starting the Digital Payments Journey
Collecting premiums shouldn’t be the hardest thing an agent does. But as with any technology update, moving to digital payments may feel overwhelming. Understanding how they work, the benefits of implementing and what to look for when choosing a solution will help agents move forward with confidence.


Chase Petrey

Profile picture for user ChasePetrey

Chase Petrey

Chase Petrey is the president of applied pay at Applied Systems.

He has a diverse career in the enterprise software industry, bringing with him fintech, software as a service (SaaS), and analytics skills.

Petrey also serves as president of the Salt Lake City Chapter at Silicon Slopes, a nonprofit organization that exists to empower Utah's tech community to learn, connect and serve to make entrepreneurship open and accessible to all.

The Future of Insurance Fraud

Three innovations will shape the future of insurance fraud detection and prevention: holograms, the metaverse and synthetic identities. 

Twenty dollar bills in a wallet placed on other bills

KEY TAKEAWAYS:

--Taking depositions remotely via hologram can allow for body language to be inspected as closely as it can be in person, allowing credibility to be assessed more accurately.

--Insuring metaverse property will require new, tailored insurance policies and legal frameworks.

--Synthetic IDs -- which combine real information such as Social Security numbers and addresses with fake information to create identities for nonexistent people -- are a whole new level of threat.

----------

In a rapidly evolving era defined by technological advancements and digital innovation, the landscape of insurance fraud is undergoing unprecedented transformation. Insurers and investigators find themselves at the forefront of a battle against fraudsters armed with new tactics. To maintain a competitive edge, we as industry experts must foresee the trajectory of insurance fraud and comprehend the indicators that can help us distinguish authentic claims from fraudulent ones.

In particular, there are three critical innovations that will shape the future of insurance fraud detection and prevention: holograms, the metaverse and synthetic identities. 

While these three might sound like far-off technologies that we might expect to have a real impact on our industry in a few years – maybe even a few decades – many are actually in use today or will be very soon. To stay one step ahead of fraudsters, insurance professionals need to be informed about how these innovations can change the way fraud is conducted and about how we can use them to our own advantage in catching malicious activity.

See also: Using AI to Prevent Insurance Fraud

Remote Depositions: Analyzing Body Language With Holograms

Elevating the Digital Courtroom Experience

Picture a deposition conducted in a digital courtroom where holographic technology is used to view body language with the same precision as an in-person session. This technology holds tremendous potential in the context of insurance fraud detection. By scrutinizing subtle and non-verbal cues, insurers can gain profound insights into the credibility of claims. Remote depositions via hologram offer a streamlined and cost-effective approach for legal proceedings, making them especially valuable in insurance fraud investigations. They provide geographic flexibility, reduce costs, save time, enhance safety and health compliance, employ advanced technology for better observation, simplify recording and archiving and increase accessibility, making the legal process more efficient and inclusive. We can examine how remote depositions, driven by holographic technology, are positioned to revolutionize our approach to evaluate claimants' authenticity.

Insuring the Metaverse: Safeguarding Virtual Property Transactions

Protecting Digital Property Ownership

As the metaverse continues to gain momentum and individuals participate in the purchase and sale of virtual properties, a new frontier of insurance emerges. Insurers must adapt to this shifting landscape by forming innovative strategies to safeguard policyholders engaged in metaverse transactions. We must investigate the challenges and opportunities associated with insuring metaverse properties and how insurers can offer comprehensive coverage in this digital world. Insurance plans for metaverse property are still emerging, and they represent a unique and evolving area of coverage. Existing property insurance laws and policies are primarily designed for physical assets and may not directly apply to metaverse property. As a result, it's likely that new, tailored insurance policies and legal frameworks will be necessary to address the distinct challenges of insuring digital assets and transactions within the metaverse.

See also: Coping With Insider and Outsider Fraud

Synthetic Identities: Identifying the Fraudsters of Tomorrow

Addressing the Emergence of Synthetic IDs

In an era where identity theft knows no boundaries, synthetic IDs have surfaced as powerful tools for fraudsters. Synthetic IDs are fabricated identities created by combining real and fake information, often using real Social Security numbers, names and addresses. These false identities appear legitimate but don't correspond to any real individuals. They are frequently used in fraudulent activities, including insurance scams. These fabricated identities pose a substantial threat to insurers. We can shed light on how criminals employ synthetic IDs to perpetrate insurance fraud and explore tactics to recognize and combat this issue. With a synthetic ID, individuals can commit various fraudulent activities, including insurance fraud, identity theft, credit card fraud and tax evasion. To combat this issue, we need improved identity verification methods, stricter data protection and more effective fraud detection technologies. By remaining one step ahead, insurers can protect their customers and the industry from the growing presence of synthetic identity fraud.

The future of insurance fraud presents both promise and peril. As we navigate the intricate intersection of technology and deception, insurers must equip themselves with foresight and knowledge to confront emerging challenges. Remote depositions using holographic technology, insuring metaverse properties and countering synthetic identities provide a glimpse into the forthcoming landscape. By addressing these issues, the insurance industry can maintain the trust and confidence of policyholders in an ever-evolving world.

Insurers must seize the opportunity to reassess their fraud detection strategies, embrace innovation and remain vigilant against those who seek to exploit the insurance system. The future may be uncertain, but with foresight and preparation we can ensure a safer and more secure insurance landscape for all.

Insurers Can Promote Healthier Lifestyles

A behavioral change model has proved successful in promoting healthier behaviors among a broad range of policyholders.

Graph showing weekly physical activity engagement of Vitality members

About 30 years ago, Adrian Gore and Barry Swartzberg harbored an intuition that introduced a different perspective on people's well-being. This approach, known as Vitality, has since matured into a methodology primed to serve as a fundamental competency for any insurer in the future.

The insurance sector has wholeheartedly embraced the notion of incorporating preventive measures, as aptly expounded in the Geneva Association's publication titled "From Risk Transfer to Risk Prevention." Cultivating less risky behaviors among policyholders in personal lines and among frontline employees in commercial domains is the indispensable path toward realizing this aspiration.

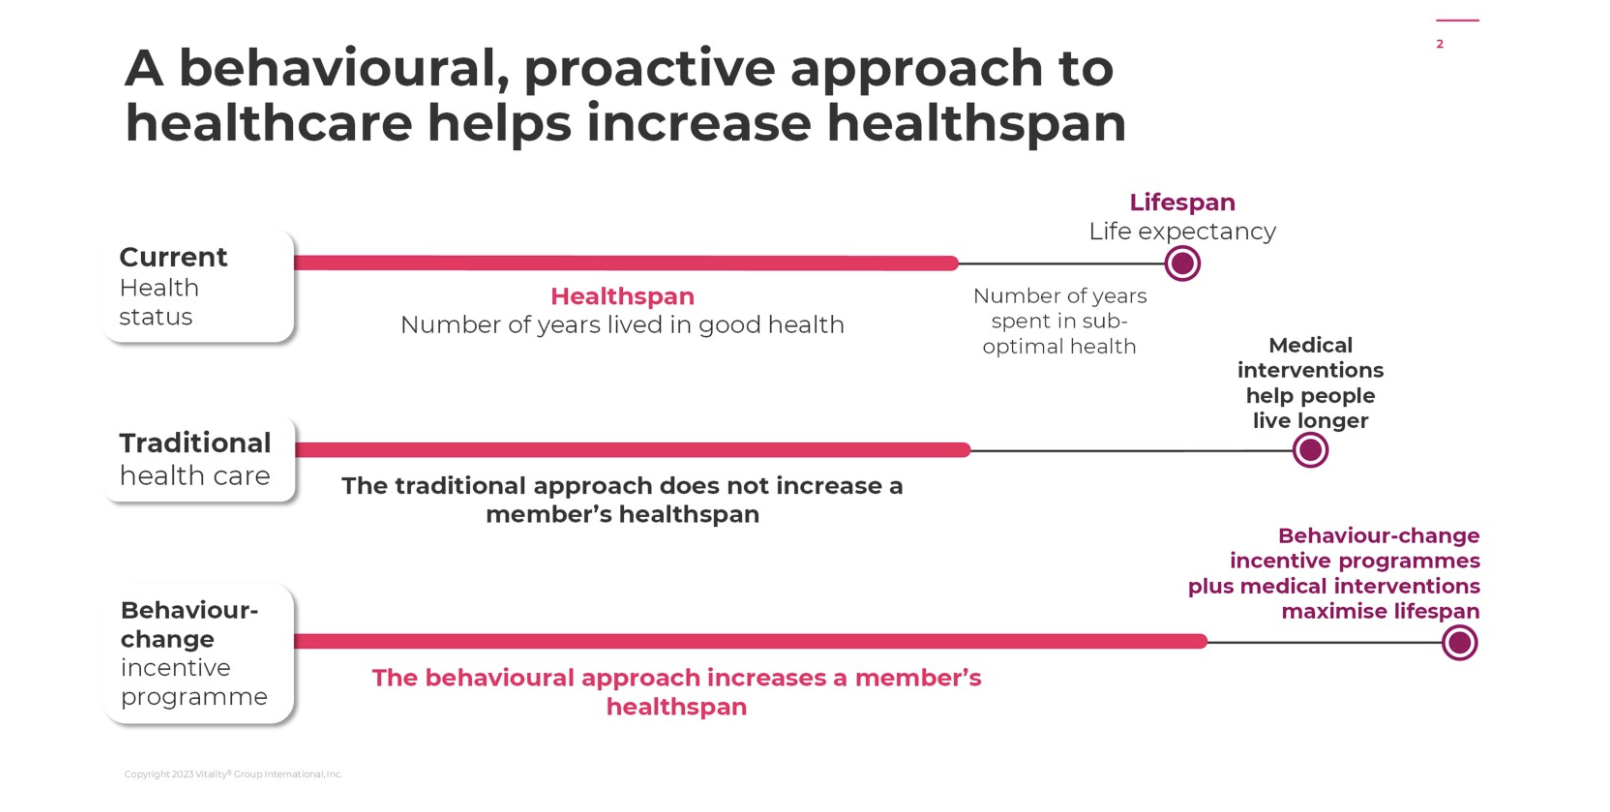
The conventional medical approach centers on employing medical interventions once a disease has manifested. This approach entails prolonging life by extending the period spent in somewhat suboptimal health, albeit with variations contingent on the nature of the disease. Conversely, Vitality's behavioral paradigm concentrates on promoting healthier lifestyle choices capable of elongating the duration of the policyholder's time spent in a state of optimal well-being, thus further extending their lifespan.

A behavioural, proactive approach to healthcare helps increase healthspan

Source: Discovery

See also: Are Health Engagement Programs Worth It?

The frequency and severity of claims will diminish for the insurer. This savings are then partially channeled toward funding the expenses of the behavioral change program: At its core, the Vitality program involves promising rewards to individuals exhibiting enhancements in their conduct. 

Over the past decade, this approach has been replicated in different markets, with different nuances program by program. One international partner has even used Vitality as a stand-alone, fee-based offer open to customers without a policy with any insurer. Vitality has already attracted more than 30 million individuals globally.

This journey has showcased an astonishing capacity to engage policyholders. Across numerous Vitality portfolios, more than two-thirds of the members have engaged in both physical and non-physical activities that provide verified information. Nowadays, more than 100,000 new devices a month are connected by members to the Vitality program.

Discovery has accomplished an enrollment rate ranging from 50% to 80% in their Vitality program among their South African policyholders. This remarkable achievement has been realized even with a monthly fee exceeding $17 charged to the insured for enrollment.

The international partnerships are yielding consistent evidence, as well, demonstrating penetration rates of up to 70% for Vitality in partners' new business programs deployed in mature nations – even with a fee for joining the program -- and up to 80% in emerging economies. Analogous outcomes have been replicated in corporate wellness initiatives, where as many as two-thirds of eligible employees have participated, in contrast to the industry's average of 30% participation.

Policyholders crave to share their healthy behaviors with their insurers and enjoy substantial advantages, with benefits that can be higher than the premium paid. Simultaneously, this shared-value model allows the carrier to achieve superior results, while generating benefits for society at large.

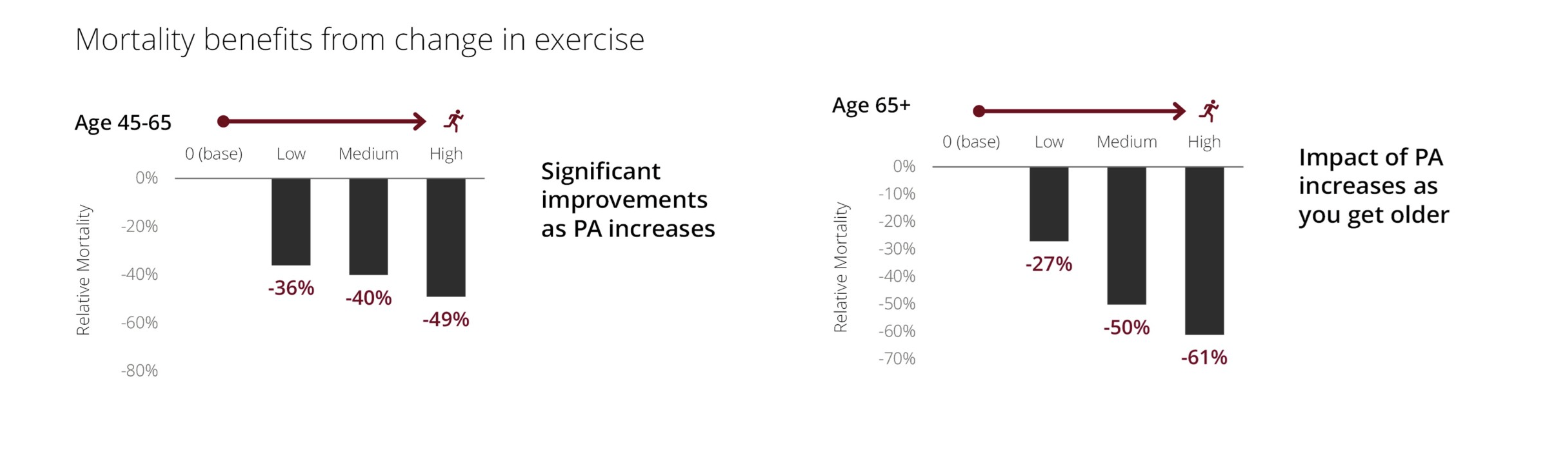
The foundation of the Vitality approach resides in promoting behaviors directly contributing to delaying diseases. Discovery's three-decade journey provides robust evidence that a significant increase in the level of physical activity reduces by 49% the mortality for individuals aged 45 to 65, and a remarkable 61% reduction for those older.  Positive impacts have further manifested within annual medical expenditures, where the most engaged participants have 15% lower claim costs than the less engaged, risk-adjusted by age and medical conditions. A longitudinal study on the people who showed a low level of physical activity during the initial six-month period showed a subsequent 14% reduction in hospital medical costs for the subgroup that notably elevated their engagement levels over the ensuing four and a half years.

Mortality benefits from change in exercise

Source: Discovery

See also: Data-Driven Transformation

As you would expect, a program as successful as Vitality attracts and retains customers. Discovery's latest data pertaining to their South African health portfolio showed that 31% of the economic value the insurer garners through the Vitality approach comes from the attraction and retention of younger members and that 20% stems from the attraction of individuals more likely to exercise. 

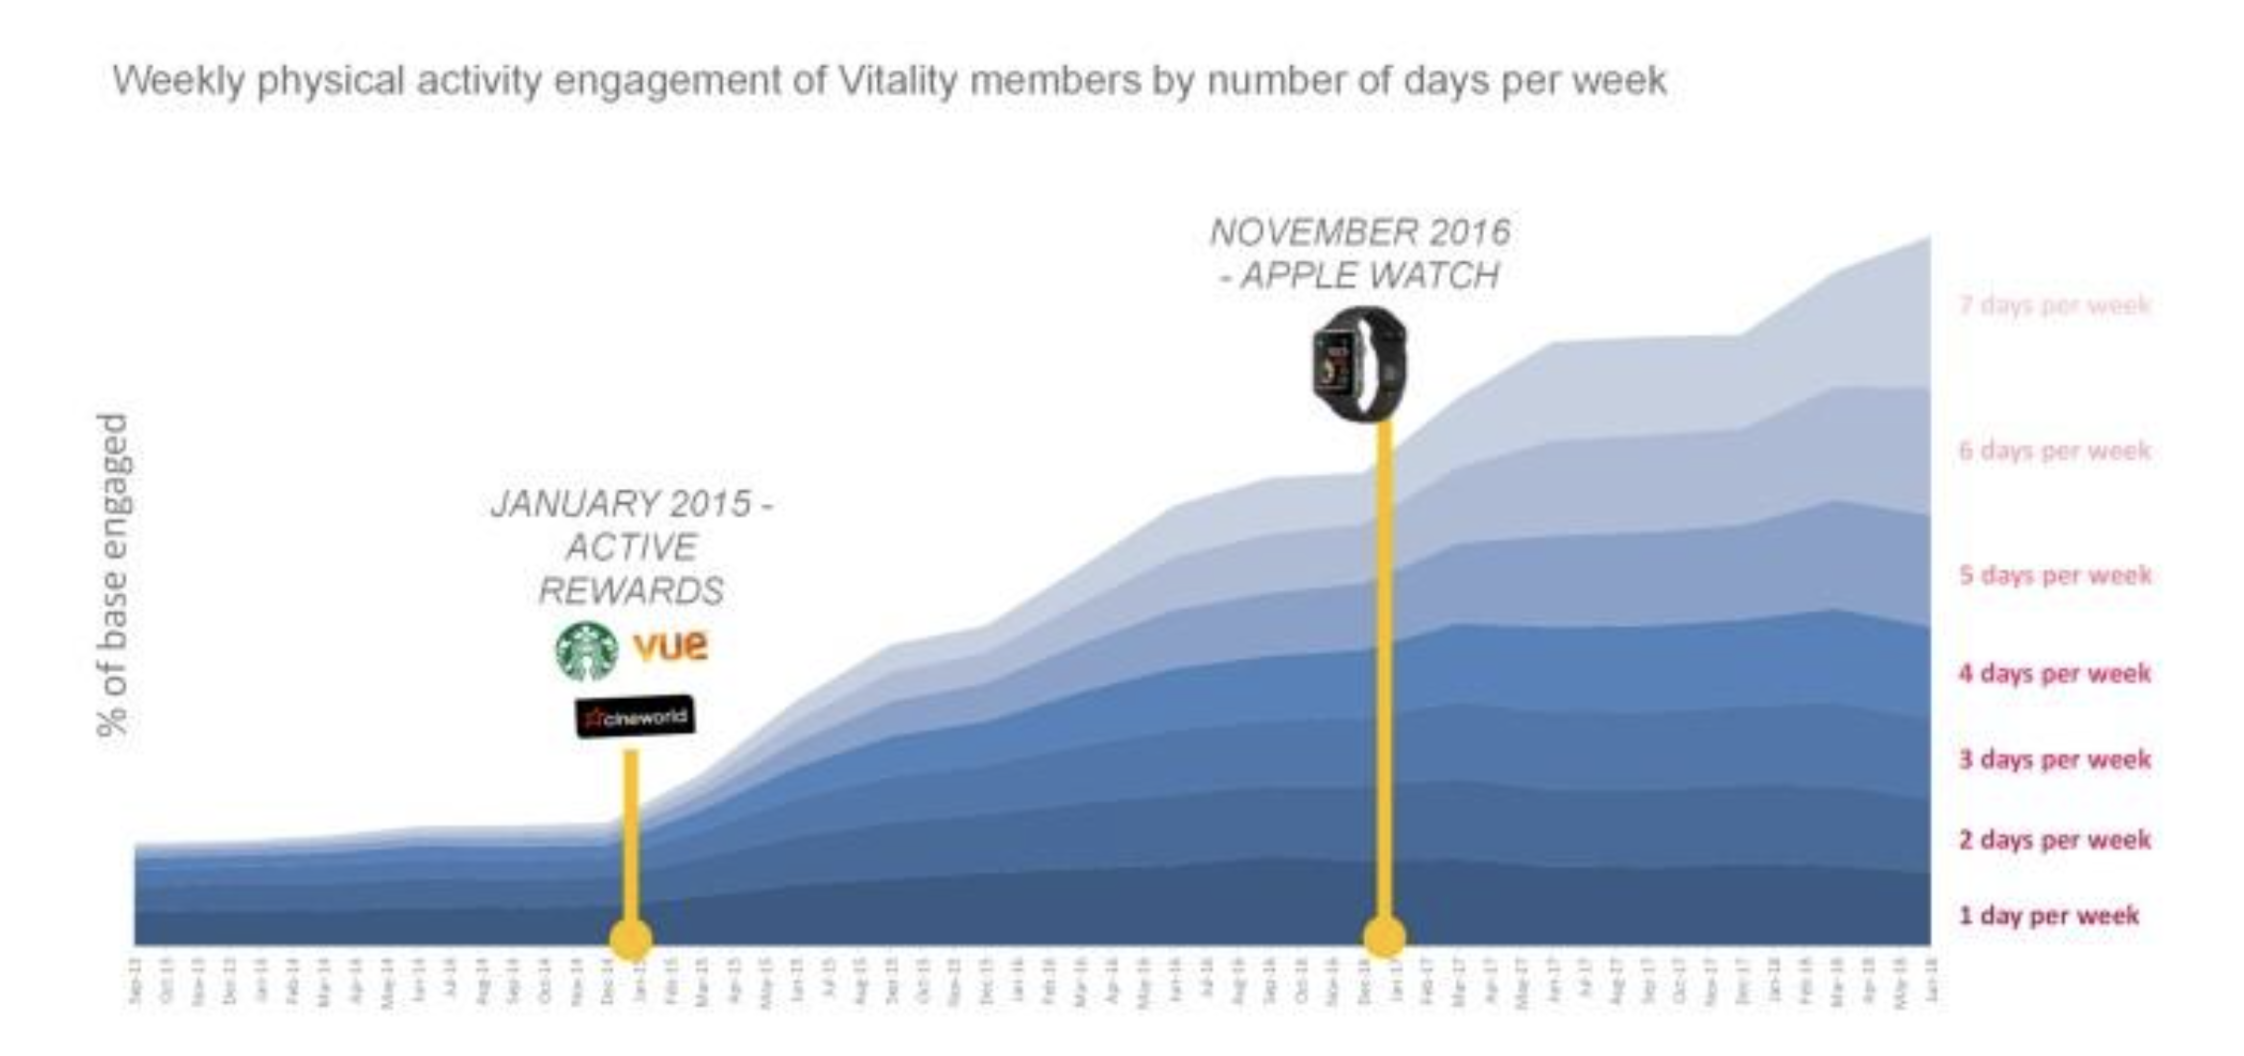
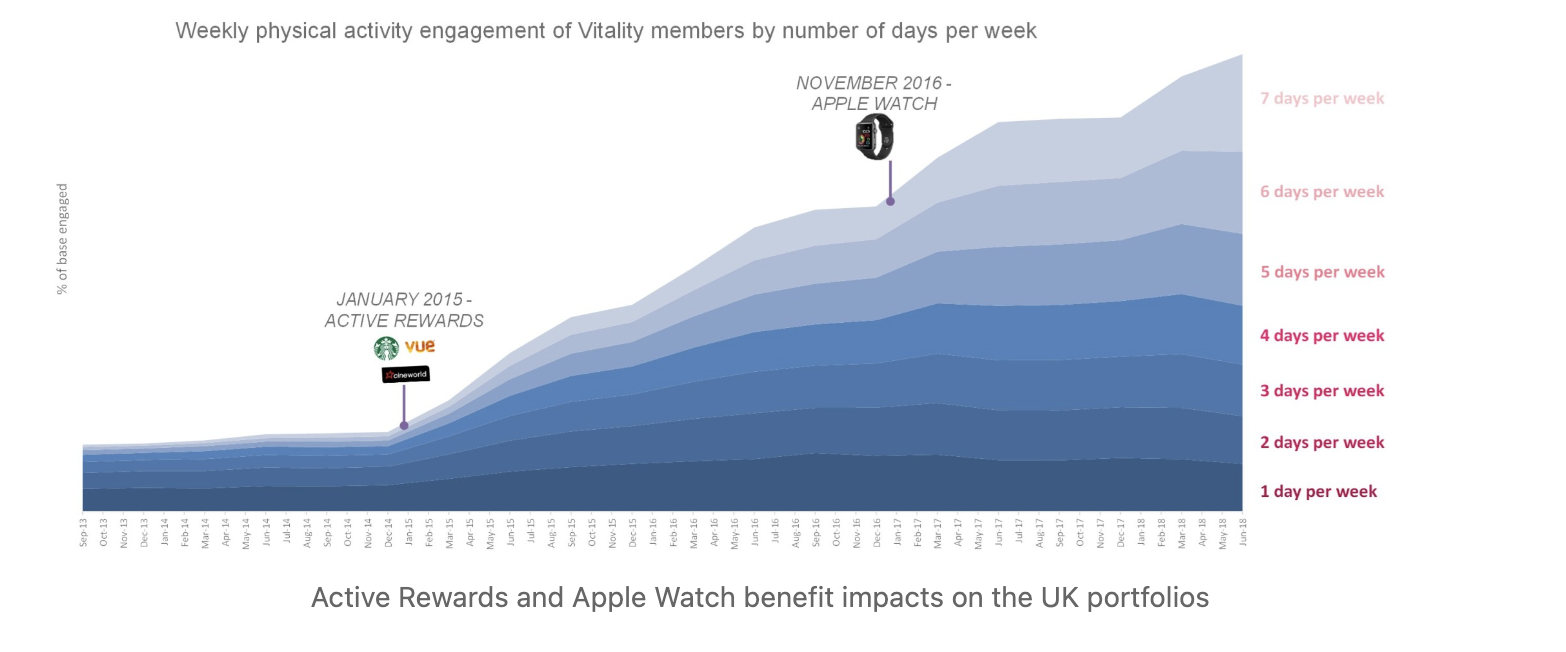
The benefits are a direct outcome of Discovery's continuous innovation effort, which has honed their mastery in behavioral modification, seamlessly applying it across various geographical regions and lines of business. As illustrated by the figure below, the dynamic use of active rewards and loss aversion mechanisms (such as the mechanism to reimburse the Apple watch —methodologies systematically tested and incrementally implemented across all programs over recent years—has showcased extraordinary efficacy in engaging members. This, in turn, directly leads to the embrace of the desired healthy behaviors among Vitality's members.

Active Rewards and Apple Watch benefit impacts on the UK portfolios   

Active reward and Apple Watch benefit impacts

Source: Discovery

Members who participated in active rewards saw more than a 20% increase in physical activity days regardless of their health status. This increase is observable across the entire spectrum of well-being, encompassing individuals categorized as "healthy," "with stable chronic condition," "with significant chronic condition" and "with complex chronic condition."

Following exposure to active rewards, the average activity level exhibited a commendable upswing of 18%. Moreover, with the added incorporation of Apple Watch benefits, this average activity escalation escalated to an impressive 35%. This enhancement is consistently observed across diverse generational segments, with all age brackets showcasing increments surpassing 20%. Individuals aged 50 and above displayed a particularly substantial uptick of 51%. Similar outcomes have been measured in South African, U.K., U.S. and Australian portfolios.

The greater the proportion of engaged members, the higher the impact created on the insurer's technical results. A Swiss Re "Health and Wellness Engagement Impacts" study examining a life insurance behavior change program estimated a threshold of 25% engagement as requisite to ensure a positive ROI for the insurer. More than 90% of Vitality's markets with more than one year of maturity have already achieved engagement levels surpassing this specified threshold among members. One of the most effective international programs – a mature market – has reached a remarkable 64% engagement rate among its members. 

The evidence underscores the effectiveness of this approach—founded on technology and data shared by policyholders—in enhancing the profitability of the insurance portfolio. The approach also provides benefits satisfying the other three requirements in my 4P framework for evaluating insurtech initiatives. Vitality increases persistency (boosting retention), proximity (producing more frequent interactions with customers) and productivity (improving the top line).

All Vitality portfolios have consistently demonstrated superior retention rates when contrasted with the broader market. Furthermore, the churn levels observed within the most engaged members typically range between one-third and half of those observed in clusters exhibiting less healthy behaviors. This phenomenon exerts an exceptional influence on the lifetime value of a policyholder cohort—what actuaries quantify as new business value—resulting in a shift in the quality of the insurance book.

Several of the Vitality life portfolios have encountered an average above 20 touchpoints per month (app usage, push notifications, emails, …) with policyholders, a marked departure from the traditionally minimal touchpoints associated with life portfolios. In one Vitality portfolio, the usage of the insurer's digital channels among members has surged more than fourfold after the introduction of active rewards. 

See also: Lemonade's 'Synthetic Agent' Nonsense

One of Discovery's international partners has disclosed the effect on cross-selling: The count of policies per customer is fivefold greater among Vitality members compared with the conventional portfolio. Among those members with over five years of engagement, the most engaged maintain an average of 50% more policies in contrast to their less engaged counterparts.

Sales are influenced by a multitude of factors, encompassing the insurer's strategy and initiatives, contingent market conditions and competitive dynamics, so achieving an exact quantification of the impact of the Vitality approach is difficult. Nevertheless, there is a plethora of anecdotal evidence:

  • A life portfolio growth four times the market, with market share rank rising from 11th to 7th in four years (mature country);
  • Health carriers with 33% top-line growth over six years compared with a shrinking market (mature country);
  • Life bancassurance player that increased market share from 2% to 7% in four years (emerging economy).

This detailed overview demonstrates the effectiveness of the Vitality model – achieving adoption and engagement among the entire spectrum of well-being and being replicated in all the geographies. 

This approach effectively rewards policyholders to disclose verified behavioral information. This shared-value mechanism optimizes policyholder engagement while yielding superior outcomes for the insurance enterprise, a portion of which is shared back to the policyholders. 

Discovery has meticulously cultivated a suite of specialized competencies, encompassing the adept guidance of behavioral change, adroit engagement with policyholders, the skillful orchestration of an ecosystem of retail partners to sustainably deliver appealing rewards and a comprehensive array of supplementary aptitudes required to ensure the seamless integration and alignment of the Vitality approach across actuarial, marketing and distribution functions. This prowess has been perpetually honed through collaboration with international partners and an unwavering commitment to continuous innovation.

This methodology applied to health and life transcends the scope of a conventional wellness program. It signifies an emergent insurance paradigm that holds the potential for extension across diverse insurance business lines. (In South Africa, Discovery has successfully applied it to auto insurance.) This extension aims to foster less risky behaviors among policyholders and, when deployed within commercial lines, extends its influence to encompass front-line employees.

Navigating the Latest CMS Regulations

Compliance is critical for ensuring transparency and protecting participants but also for avoiding potentially costly penalties. 

Doctor in a white coat holding a clipboard with a stethoscope and writing something

Recently, the Centers for Medicare and Medicaid Services (CMS) released an update to its rules that has significant implications for insurance agents and Medicare agencies that market Medicare plans. These changes aim to enhance transparency, protect participants and ensure that any information provided is accurate. They take effect Sept. 30, 2023.

Let’s look at some of the changes: 

Direct Submission of Marketing Material by TPMOs 

One of the most significant changes is the requirement for third-party marketing organizations (TPMOs) to submit their marketing materials directly to CMS for approval. In previous guidelines, TPMOs were responsible for submitting material to the respective Medicare Advantage (MA) organizations or Part D sponsors. The new rule mandates that TPMOs obtain prior approval from each organization or sponsor and submit the material directly to CMS for review. This ensures that marketing collateral meets CMS guidelines and receives the necessary approvals before participants see it. 

This change means TPMOs must streamline their internal processes to accommodate the direct submission to CMS and ensure compliance with the approval requirements of individual organizations and sponsors. Partners, such as Total Expert, can help TPMOs streamline marketing collateral development and approval workflows while remaining compliant at every step with automated workflows and pre-built content templates.

Disclaimer Changes for TPMOs

TPMOs must also include standardized disclaimers in their marketing material. These disclaimers will inform participants about the TPMO’s representation of MA organizations or Part D sponsors and the range of plans available. The disclaimers differ based on whether TPMOs represent all MA organizations or Part D sponsors in a service area or only a select number. Insurance agents and Medicare agencies must incorporate the required disclaimers accurately in their marketing collateral and provide participants with clear information about available plan options. 

See also: Navigating Confusing Insurance Regulations

Guidance on Misleading Use of Medicare or CMS Name and Logo 

To protect participants from misleading information, the new CMS rule strictly prohibits the use of the Medicare name, CMS logo and products or information issued by the federal government in a misleading way. However, a slight modification to the rule now permits the use of the Medicare card image with authorization from CMS. This change aims to strike a balance between accurate representation and preventing deceptive practices.

For insurance agents and Medicare agencies involved in marketing Medicare plans, this rule demands that you adhere to the guidelines and obtain proper authorization from CMS when incorporating Medicare-related branding elements like the Medicare card image in marketing collateral. Ensuring accurate and transparent representation builds trust of participants and avoids potential compliance issues that could lead to significant fines for each violation. 

Clear Identification of MA Organizations and Part D Sponsors 

To provide participants with clear and accurate information about the entities behind the marketing material, the new CMS rules require marketing materials to clearly identify the MA organization or Part D sponsor offering the products or plans. If the MA organization or Part D sponsors involved are clearly identified, participants can make informed decisions about their Medicare plan choices. 

For insurance agents and Medicare agencies, transparency is not optional. Participants must have clear and easy access to further information about the plans and services being advertised.

Restrictions on Unsubstantiated Superlatives 

The new CMS rule introduces limitations on the use of superlatives such as “lowest premium” or “largest network” in marketing collateral. Such superlatives must be supported by documentation, which should reflect the current or prior year and be easily accessible to participants. 

For insurance agents and Medicare agencies, many of today’s common marketing communication approaches will no longer be allowed. Any claims about service quality, price, etc. must be backed by reliable data and documentation. Incorporating such supporting information not only complies with CMS guidelines but also earns trust with participants who seek reliable information to make informed decisions about their Medicare plans.

Penalties for Violating CMS Rules

CMS exists to protect Medicare and Medicaid participants, a group that has often been targeted by misleading and predatory marketing practices. As a result, CMS will not hesitate to levy fines of up to $5,000 for each violation of their policies.

See also: Balancing Innovation, Compassion in Life Insurance

Compliance with the new CMS rules is critical for ensuring transparency and protecting participants but also for avoiding potentially costly financial penalties. 

Outdated technology and internal processes will make it difficult to comply with the new CMS rules. By embracing a modern technology platform like Total Expert, agents can feel empowered to deliver compliant communications and marketing collateral.

Has Work-From-Home Run Its Course?

How do you know if work-from-home is right for your company. It’s all about productivity, cost and culture.

Woman on computer sitting in bed, sipping coffee

KEY TAKEAWAYS:

--Companies can measure productivity on key metrics and compare work-from-home employees against those in the office, whether now or in the pre-COVID days. Those comparisons will allow a deep look into relative costs.

--Companies also need to explore cultural issues, which can be key to attracting and retaining talent. While values can be shared in written format, discussed in Zoom meetings and reinforced with remotely observed behavior, companies will still find it a challenge to develop a strong culture if team members don’t see each other in person frequently.  

----------

Like many others, I’ve written extensively about work-from-home issues in the last few years. At this point, most articles seem redundant. Rather than write another of those, I’d like to look at how work from home is evolving – both developing opportunities and creating pitfalls.  

The advantages of remote work for both employers and employees are now well known. They include geographic and time zone flexibility and work flexibility for part-time employees, as well as the ability to reduce costs of physical locations for both parties. 

At the same time, we also have come to see that disadvantages for work-from-home include increased difficulty in employee development due to less frequent supervisory contact, challenges with team building and other social benefits of in-person work and a decreased commitment of employer and employee to each other. The problems have shown up in “quiet quitting” and increased employee resignation rates.

While employers currently bear the brunt of the problem, I think that is likely to change with an economic downturn, not to mention technology improvements. I suspect employers will find they have more distant relationships with remote workers and will find it easier to let them go when times get tough.

How do you know if work-from-home is right for your business? It’s all about productivity, cost and culture.

Taking a Look at Productivity

As we think about pitfalls in the work-from-home evolution, we have to acknowledge that the utopian descriptions of its potential for a permanently new way to work may not be bearing the abundant harvest predicted by its earliest advocates. This, I think, is why many larger organizations like X, formerly Twitter, and the U.S. government are calling for or requiring a return to the office.  

The principal reason large employers (and many smaller ones) are calling for a return to office work is a measured decrease in productivity. Despite workforce challenges, those employers that can carefully measure productivity, and have adequate talent recruiting capabilities, are compelling workers to put their pants back on and come to the office. Does this imply that all employers will do the same eventually? I do not know, but the question does point to the importance of measuring productivity. In a professional services businesses like insurance, employee cost measured against business revenue and profit is the key driver of success.   

Whether you are a remote work advocate or not, work from home raises the useful issue of productivity.  

See also: Has the Remote-Work Trend Peaked?

Diving Deeper Into Costs

A key challenge for every business in a relentlessly competitive industry is lowering costs. While technological innovations like artificial intelligence hold exciting promise, they aren’t fully realizable yet. Even when they are, how many activities each employee performs per hour or week still holds the most promise for affecting cost control. If a business doesn’t have a robust set of key performance indicators or isn’t comparing results over time (particularly between in-the-office and remote workers) an opportunity for improvement is being missed.  

As a starting place for developing key performance indicators (KPIs), I suggest you look backward from the end of your process. For many in the insurance industry, this would be a sale. Then, ask what the milestones are. For example, in an insurance agency, an issued quote is a milestone, as is a completed submission. Indicators to measure, in addition to those two items, might include the number of closing attempts or number of lines of coverage sold. Then, with the KPIs established, look back into your business records for a year or two before the business moved to remote work to establish a baseline benchmark. You can then measure your results against a period of remote work and see how productivity was affected and what improvements might need to be made.

Obviously, businesses that started after the COVID era began have no pre-pandemic in-office benchmark. As a result, they have had to focus on creating processes that work regardless of where an employee is located. This is an excellent exercise for hybridized existing businesses to complete, as well. As you examine each process in the business, ask if changes need to be made to maintain or improve from your baseline benchmark. You may find that teamwork involving different time zones may allow you to improve some time-critical tasks like submission to quote to bind, for example.  

Fostering Workplace Culture

Even with improved processes and reduced costs developed from the learning created by increased experience, companies still have to solve culture issues.

“Culture eats strategy for lunch” is often attributed to management guru Peter Drucker. But whether he first said it or not, culture is critical to business. Culture founded on a set of shared and constantly reinforced values is not just a key contributor to business success but is also a key contributor to attracting and retaining the best talent. While values can be shared in written format, discussed in Zoom meetings and reinforced with remotely observed behavior, companies will still find it a challenge to develop a strong company culture if team members don’t see each other in person frequently.  

See also: Opportunity Now and in 2024

Looking Toward the Future

As the trauma created by the business disruption of COVID fades, businesses must increasingly ask the questions of whether remote work improves or impedes productivity and business results. As we enter, inevitably, into an economic slowdown and perhaps begin to see the productivity improvements of a generation of iterative artificial intelligence, business owners might no longer be held hostage to work-from-home demands. They could be in more of a position to call for a return to office. But ultimately whether remote work makes sense for both the business and the employee depends on progress and results related to productivity, cost and culture. The jury is out on those.


Tony Caldwell

Profile picture for user TonyCaldwell

Tony Caldwell

Tony Caldwell is an author, speaker and mentor who has helped independent agents create over 250 independent insurance agencies.

The Promise of Continuous Underwriting

Typically, a risk is underwritten, bound... and forgotten. But new streams of data and automation allow for continuous underwriting.

A long bridge in front of a large body of water on a foggy day

KEY TAKEAWAY:

--Usage-based insurance for drivers shows the potential of continuous underwriting. Based on telematics and automated analysis, drivers' risks are continually being evaluated based on their driving behavior and miles driven.

--That capability is now spreading to numerous other types of insurance, providing ways for insurers to keep tabs on their portfolios in real time. 

----------

Much is said about the need to modernize insurance, an industry rife with legacy carriers tethered to outmoded systems. In spite of the apparent opportunities, insurtech has had a hard time displacing large incumbent organizations and their traditional approach to underwriting. The plodding carriers, driven by their risk-averse cultures and bureaucratic inertia, survive without being on the forefront of tech advancements. Meanwhile, some insurtechs are here today and gone tomorrow, due in part to approaches that produce unsustainable loss ratios. A focus on growth over everything else has rarely been a winning strategy.

The other part of the challenge is that insurtech has been slow to effectively harness the data needed to build better rating models. Setting aside regulatory obstacles, new data acquisition strategies were heralded as the path to more accurately and efficiently pricing risk and modernizing the industry. Several prominent insurtechs, with pressure to grow rapidly in a short time, have since back-pedaled on their data-centric prophecies when it became clear they had not achieved the levels of underwriting profitability they had forecasted. The incumbents consistently outperformed the newcomers by remaining diligent in prioritizing underwriting basics and enjoying the luxury of years of proprietary, historical experience data.

So can growth and the pursuit of a healthy loss ratio co-exist?

It may seem the insurtech innovators have waved the white flag in their battle to conquer the traditional insurance mechanism, but we are in fact seeing a new commitment to enhanced technologies being deployed in insurance. Insurtech VC funding exceeded $2.3 billion in the first half of 2023, a robust sum even if significantly down from peaks experienced during the pandemic. While early insurtechs attempted to disrupt an industry that is built on a resilience to disruption, the next wave of insurtechs has conceded that certain fundamentals are non-negotiable if they are to foster a reliable insurance ecosystem promoting financial stability.

In this vein, an insurtech concept that is innovating the industry is continuous underwriting.  

Continuous underwriting is the process of leveraging data and technology to apply underwriting strategies throughout the policy life cycle. Those of us who have spent time in the traditional small commercial underwriting space have experienced first-hand how a risk gets bound and then essentially forgotten. How many times have you seen a risk and thought “that carrier doesn’t even know what they’re on!”? 

Underwriters have also been taught that the most profitable business is that which is already on the books. While this can be true, a failure to remain sensitive to the portfolio’s evolving risk can lead to detrimental results. Companies have long made this trade for the savings on expenses associated with detailed underwriting processes (but, let’s be honest, the situation usually ends with the book being re-underwritten anyway).

Instead of limiting the use of data to the initial submission, we can now monitor risk throughout the policy life cycle. The tools and systems are available for carriers to continuously underwrite more efficiently than ever, providing opportunities to proactively control the loss ratio while reducing disruptive and costly re-underwriting processes.

One form of continuous underwriting, in which technology promotes safe behaviors, is usage-based insurance (UBI). UBI strategies have been successfully implemented in large sets of homogenous risks, such as telematics devices/apps that measure driving behaviors. Now, a consumer’s auto insurance rates can be reduced based on safe driving and fewer miles driven. Beyond auto, UBI is manifested in areas such as cargo and handyman insurance, where the purchaser can only pay for the amount of coverage they actually need, and only when they need it.

See also: The Next Era of Underwriting

As consumer expectations evolve, more dynamic strategies and tactics will continue to progress into larger, more complex risk evaluation processes. Vertical software solutions (software built for specific industries and use cases) — such as bookkeeping software and point-of-sale (POS) systems — are increasingly critical for small businesses. The software contains vast stores of rich exposure information in real time, allowing the automation of continuing eligibility and pricing decisions by using another UBI concept called pay-as-you-go (PAYG). PAYG allows the accurate tracking of risks after the policy is bound, reduces premium leakage, provides cash flow benefits to the insured and can even help up-sell new cover when additional exposures are identified.

The use of always-current payroll data in workers' compensation started to take off decades ago and has evolved to become a default standard. Other small commercial coverages have evaded the adoption of this common sense approach to underwriting — until now. With the explosion of digital systems centrally managing the business data that underpins many classes of small business, we believe the same benefits can be passed on to small business insurance, such as a business owner’s policy (BOP) or liquor liability, that have exposure bases measured by sales.

Sustainability deserves consideration here. For a concept such as continuous underwriting to achieve commercial scale, carriers must be able to deploy the solution without correspondingly more onerous overhead and manual process. An automated continuous underwriting process will help insurers avoid unanticipated claims by identifying new hazards before the loss occurs — but where does the automation come from? 

The simple answer is that automation from thoughtfully developed software has been built specifically to monitor risk factors and data. It doesn’t happen overnight, and legacy carriers will struggle to shoehorn another piece of software into their antiquated IT infrastructure. This industry dilemma requires a clean start approach to practical innovations.

Facilitating the adoption of continuous underwriting is a shift in insurance buying habits and general comfort in digital privacy controls. Younger generations are more amenable to sharing their data in exchange for products and services that fit their lifestyles. The expectation for immediate digital experiences is on the rise, and consumers are showing increased preferences toward mobile apps and AI-based virtual assistants. Further, underwriting investigations are now streamlined through integrations with external data providers that instantly address advanced considerations -- geospatial imagery can show deteriorated roof conditions in hail-prone areas, and AI-powered machine learning models can identify policies most expected to generate losses.

Automation that continuously brings current data into the underwriting process will allow insurers to more efficiently expand their operations. The human bias inherent in the traditional underwriting process will be reduced, generating greater confidence in the result and forging a path to sustainability. 

The insurance industry readily admits that it must continue to innovate to remain effective. Insurance consumers have demonstrated willingness to adopt technological advancements, as they already have with UBI and PAYG. Underwriters unwilling to commit to continuous underwriting risk being left behind.

Up next: In Part 2, we explore practical examples for unlocking the potential of continuous underwriting for small business and address the impacts and benefits to key stakeholders.


Bill Deemer

Profile picture for user BillDeemer

Bill Deemer

Bill Deemer, CRM, CIC, AU, AAI, is head of underwriting at Rainbow.

Deemer is a 20-year-plus commercial insurance veteran, focused on using his well-rounded perspective to improve the insurance transaction by blending underwriting fundamentals with progressive strategies.


Bobby Touran

Profile picture for user BobbyTouran

Bobby Touran

Bobby Touran is CEO of Rainbow.

He is a founder, CEO and operator with over 15 years of experience in insurance and software development, having previously founded Pathpoint, a digital insurance brokerage focused on retail agents and their E&S risk.

A Moment of Truth for Agency Roll-Ups?

Agent and Brokers Commentary: October 2023

Person smiling at houses

When Chunka Mui and I researched 2,500 corporate disasters to look for the patterns that led to failure, we found that one of the seven strategies most commonly associated with major write-offs or bankruptcy was the roll-up. 

While we conducted our research more than 15 years ago, for our 2008 book "Billion Dollar Lessons," the work springs to mind because insurance agencies have been rolled up for years now by Acrisure, Hub and others. The make-or-break point likely isn't far off. 

The basic problem with roll-ups is that acquirers are tempted to overstate the potential cost savings while underestimating the costs, including those that come from managing the complexity of a sprawling empire that began as a host of idiosyncratic little businesses. 

The main example we explored in "Billion Dollar Lessons" was the Loewen Group, which went from a single funeral home in Canada to more than 1,100 throughout North America in a little more than a decade and employed more than 15,000 people -- then collapsed and filed for bankruptcy. 

Loewen projected major savings from having funeral homes in a metropolitan area share undertakers and hearses, as well as from the efficiencies that were supposed to come from standardizing back-office systems, but few of those savings materialized. Sharing undertakers, hearses and drivers was complicated, and those in charge of business operations resisted change or even quit. Funeral homes were typically operated by families (not unlike many small insurance agencies), and there was no incentive for an older generation to stick around after they cashed out through a sale, especially given that the giant corporate acquirer would have no loyalty to the next generation of the family. Loewen often found itself scrambling just to keep an acquired funeral home operating.

Meanwhile, the funeral homes lost much of the hometown appeal that had made many of them mainstays in a community for decades. The small businesses earned goodwill by sponsoring kids' sports teams and participating in local events. Often, the owners had kids who went to school with the children of clients. But nobody thrilled to the sight of a Loewen corporate logo on a funeral home's front lawn, so business sometimes drifted away.

For good measure, roll-ups typically happen so quickly that the growing pains can be frightful. Scale is the whole rationale for a roll-up, and a growth-at-all-costs mentality can lead to ignoring little problems with acquisitions and integration that become major problems after they've accumulated and festered. Management can become overwhelming, and some management may not be up to the task -- Raymond Loewen did great with one funeral home in one town in Canada, but operating 1,100 in a whole variety of towns and cities throughout North America was far more than he could handle. 

Now, there is reason to think that the insurance agency roll-ups can dodge many of the problems that we documented for Loewen and others in "Billion Dollar Lessons." In particular, the source of the funding for the insurance roll-ups makes a lot more sense. 

Loewen and the others in our research typically were publicly traded. As they grew, investors got excited about the growth prospects, and the stock price soared. That gave the acquirer a currency it could use to buy lots more companies -- but only as long as exponential growth continued. As soon as growth slowed even a bit, the stock crashed. Investors began focusing on the bottom line, not the top line, and management suddenly had to seamlessly integrate all the purchases. Disaster almost always awaited. 

By contrast, the insurance agency roll-ups are largely happening via private equity, which is much more patient money than stock market money is. The pressure to expand too rapidly is more muted. Private equity money is also smarter money, so it insists on more professional management than, say, Bernie Ebbers, who started his career operating a motel, could provide after he bought 60 telecommunications companies, eventually including MCI, and presided over a scandal and then the collapse of WorldCom. 

The insurance agency roll-ups will still face many of the integration problems that other roll-ups must confront, including how to introduce a corporate brand without losing the appeal of a boutique, local one. And the roll-ups are big enough now that I'd say we're getting to a point where we'll going to see, one way or the other, just how successful they can be. 

That question serves as the starting point for this month's interview, with an old friend, Mark Breading, a partner with Strategy Meets Action, who has been tracking the world of agents and brokers for decades. I hope you'll dig in.

Cheers,
Paul


AUTOMATING INSURANCE WORKFLOWS

An MGA is saving $65 million a year by reducing from 25 to two the number of clicks required to issue each policy.

OPPORTUNITY NOW AND IN 2024

The chance to grow or sell an agency can present itself quickly. Here are five steps to take to be ready when opportunity comes knocking.

THE POWER OF EFFICIENT CONTENT MANAGEMENT

Drawing on AI and machine learning, modern content management systems drive intelligence into processes and decision-making. 

CONTINUOUS IMPROVEMENT COMES TO INSURANCE

Process intelligence tools let operations leaders “see” digital products being built, enabling use of statistical process control techniques.

OPERATIONAL EFFICIENCIES IN LEAD ALLOCATION FOR AGENTS

ML-based lead allocation revolutionizes insurance lead distribution, ensuring optimal matches for agents and boosting conversion rates.

THE NEXT PHASE OF GROWTH FOR INSURANCE BROKERS

Value creation through tighter integration.


Paul Carroll

Profile picture for user PaulCarroll

Paul Carroll

Paul Carroll is the editor-in-chief of Insurance Thought Leadership.

He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.

Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.