Download

New Frontiers for Generative AI

AI is beginning to be incorporated into products and may take on much more sophisticated operational tasks, acting as a semi-autonomous agent for a user. 

Image
ai

While generative AI has been a phenomenon over the past couple of years, most uses have stayed pretty close to home — gathering information to make underwriters, adjusters, and agents more efficient, producing first drafts of reports or communications to clients, that sort of thing. 

But some recent articles suggest that AI may be getting ready to break out into much more sophisticated uses, including showing up as part of insurance products.

The article that most caught my eye was one in Fortune about how the CEO of Honeywell intends to use AI for competitive advantage. I had just finished another article in Fortune about a long list of impressive things that Honeywell was doing with generative AI at the operational level and was startled that the CEO belittled the effort. He said the work had to be done, because all his competitors were doing it, but said all the gains in efficiency would be competed away. To gain a sustainable advantage, he said, Honeywell needed to be bolder.

The CEO, Vimal Kapur, mentioned three areas where Honeywell is focusing, all of which strike me as being opportunities for the insurance industry, as well.

First, he talked about using AI to address his industry's talent gap. That issue sound familiar to anyone in insurance?

Kapur said, "If historically somebody said, ‘This job requires 12 years or 15 years experience,’ well, maybe you’re going to be able to have someone do it with seven years experience, and a supplementer [based on generative AI].... What’s a Plan B? There is no Plan B. There’s no humans to replace the humans who have left the workforce.”

He's talking mostly about engineers, so a different pool of talent than the insurance industry requires, but the issues strike me as very similar. AI can provide tremendous aid to help newer employees operate at more sophisticated levels.

Second, he talked about the area that intrigues me the most: actually adding AI to products, not just using it in the background. 

The article says: 

"He gives examples of supermarket checkout scanners, of which Honeywell is a major producer. Today, these scanners work well for bar-coded products. But if you get to the counter with an individual piece of fruit or vegetables where the bar-coded sticker hasn’t been applied or has fallen off, then the cashier must manually look up the price, or the customer is forced to go and weigh the product individually on a separate digital scale, often holding up the line. Kapur says that integrating cameras and computer vision directly into Honeywell’s checkout scanners would enable the scanner to recognize the item and charge the customer appropriately, without delaying the process."

Again, not an insurance example, but it illustrates the kind of thing that's possible for insurers, especially as more companies adopt a Predict & Prevent business model.

AI is already getting built into insurance offerings: the computer vision that monitors the road and the driver and offers warnings in real-time that can prevent accidents; the sensors that detect water leaks and alert homeowners before major damage can occur; Whisker Labs' Ting, which plugs into a wall socket and detects electrical anomalies and warns policyholders before a fire can start. 

But I can imagine a host of other opportunities, particularly in risk management. Who wouldn't like to have a smart adviser whispering in their ear that a risk is developing. Generative AI can be that adviser on issues as complex as cyber or as mundane as the approach of a hail storm, some crime trend, the need for a roof inspection, or certain home maintenance. 

You don't just sell a policy. You provide some continuing intelligence based on AI that is constantly learning.

If you do this right — delivering insights that are truly smart, that are useful, and that are delivered in the way that policyholders want to receive them — then you open up the sort of line of communication with customers that insurers have long craved. Insurance companies complain that they only interact infrequently and in cursory ways with most customers, when they make their monthly, semi-annual, or annual payments. Adding an AI channel would change all that. 

Finally, the article says another area where Kapur will use AI to Honeywell's advantage "is in providing engineering solutions to customers. In many cases, Honeywell doesn’t just sell an off-the-shelf product. It sells a system incorporating several of its products. These are usually built to a customer’s specifications, a task that requires a significant amount of time from the 5,000 engineers Honeywell employs for this work. 'We write the solution or spec for the project every time and we do tens of thousands of projects in our business every year,' he says.

"Kapur says Honeywell wants to build a large language model that can streamline this spec writing process, so that what currently takes as long as a month could be completed in just minutes—with engineers checking the output for perhaps a few additional days to guard against the risk of AI 'hallucinations.'” 

What he's describing sure sounds like it could be applied to the writing of complex insurance policies.

Another recent article tees up the possibilities of what's sometimes called agentic AI. which I think is a bit further out than the sorts of things Honeywell is pursuing but which could certainly be a profound advance for generative AI. The basic idea is that the AI wouldn't just have the authority to gather and work with information. The AI would also have the ability and authority to work with apps and have them execute tasks on behalf of the user. 

In other words, you wouldn't just tell the AI to gather tips on how to build a website. You'd tell the AI to build a website, and it would. 

The article's author, Bernard Marr, offers a range of areas where agentic AI could make a big difference. For instance:

"Business Operations: Agentic AI could revolutionize how businesses handle day-to-day operations. These AI agents could autonomously manage supply chains, optimize inventory levels, forecast demand, and even handle complex logistics planning. By processing vast amounts of data and making real-time decisions, they could significantly improve operational efficiency and reduce costs."

Or:

"Healthcare: Agentic AI could revolutionize patient care by serving as round-the-clock health assistants. These AI agents could engage with patients daily, monitoring their mental and physical health, adjusting treatment plans in real-time, and even providing personalized therapy support. By analyzing vast amounts of medical data, they could also predict potential health issues before they become serious, enabling truly proactive healthcare.

He also describes opportunities in software development, cybersecurity, human resources, scientific research, and finance. 

Again, I think agentic AI will take a while to take hold, just because a hallucination could lead to such big problems if the AI has the authority to act on its own. But the premise is certainly provocative and should be watched.

We're still in the very early innings in terms of what generative AI will do.

Cheers,

Paul
Beyond Activity Monitoring

COVID-era tools designed to track worker activity have evolved into sophisticated metrics foundries and valuable AI data generators.

Silver Security Camera

Let’s consider the $300 billion U.S. auto insurance industry. 

Driven by severe technician shortages, rising labor costs, repair complexities related to in-car technologies, and parts delays, the average cost of repair has more than doubled since 2019. 

Independent body shops are declining in number as VC-backed multi-shop operators (MSOs) proliferate. MSOs are raising rates and limiting their participation in insurer direct-repair networks. 

Capital formation in legal services and changing public sentiment on justice and fair settlement have increased the number of insurance claims going to litigation by 47% over the last three years. 

Medical costs show no signs of slowing, and new Medicare Secondary Payer rules will shift more costs to auto insurers moving forward.

These developments feel more structural than cyclical. The same can be said for the homeowners and broader commercial markets, where climate perils loom and new species of cyber losses (e.g., CrowdStrike) evolve as fast as technology itself.   

Insurance leaders are asking themselves the same questions they always have:

  • Are our people working on the right things?
  • Are our people working to the quality standard that’s needed?
  • How fast are we cycling, operating, executing?
  • How fast are we innovating? Moving with the market?
  • What are our real costs related to all this?

What feels different these days is the urgency to find answers--concrete, quantifiable answers, in real time. Everyone has an opinion depending on their department, their patch. The goal is to generate a single source of operational truth based on how people are really working. 

A new crop of software has emerged generating valuable operational intelligence without having to master query languages, statistical modeling, or the command line. Offerings from the likes of Skan, Mimica, Fortress IQ, Soroco, Automat, and Arkifi require minimal involvement from the IT department to install and create zero technology dependencies.  

Installing this software on worker machines is way more philosophical and cultural than it is technical. The point to make is that it seems increasingly essential. As a baseball leadership team shunning player and positioning analytics operates at a disadvantage, so, too, an insurance leadership team.  

There are three modes of implementation with this stuff. The first is load, don’t tell. Most employment agreements permit this. The second mode is load and tell--that is, let workers know it’s there, period. The third mode is load and share. Again, the baseball comparison is apt. Real metrics ranking team members published in real time can be a powerful motivator.    

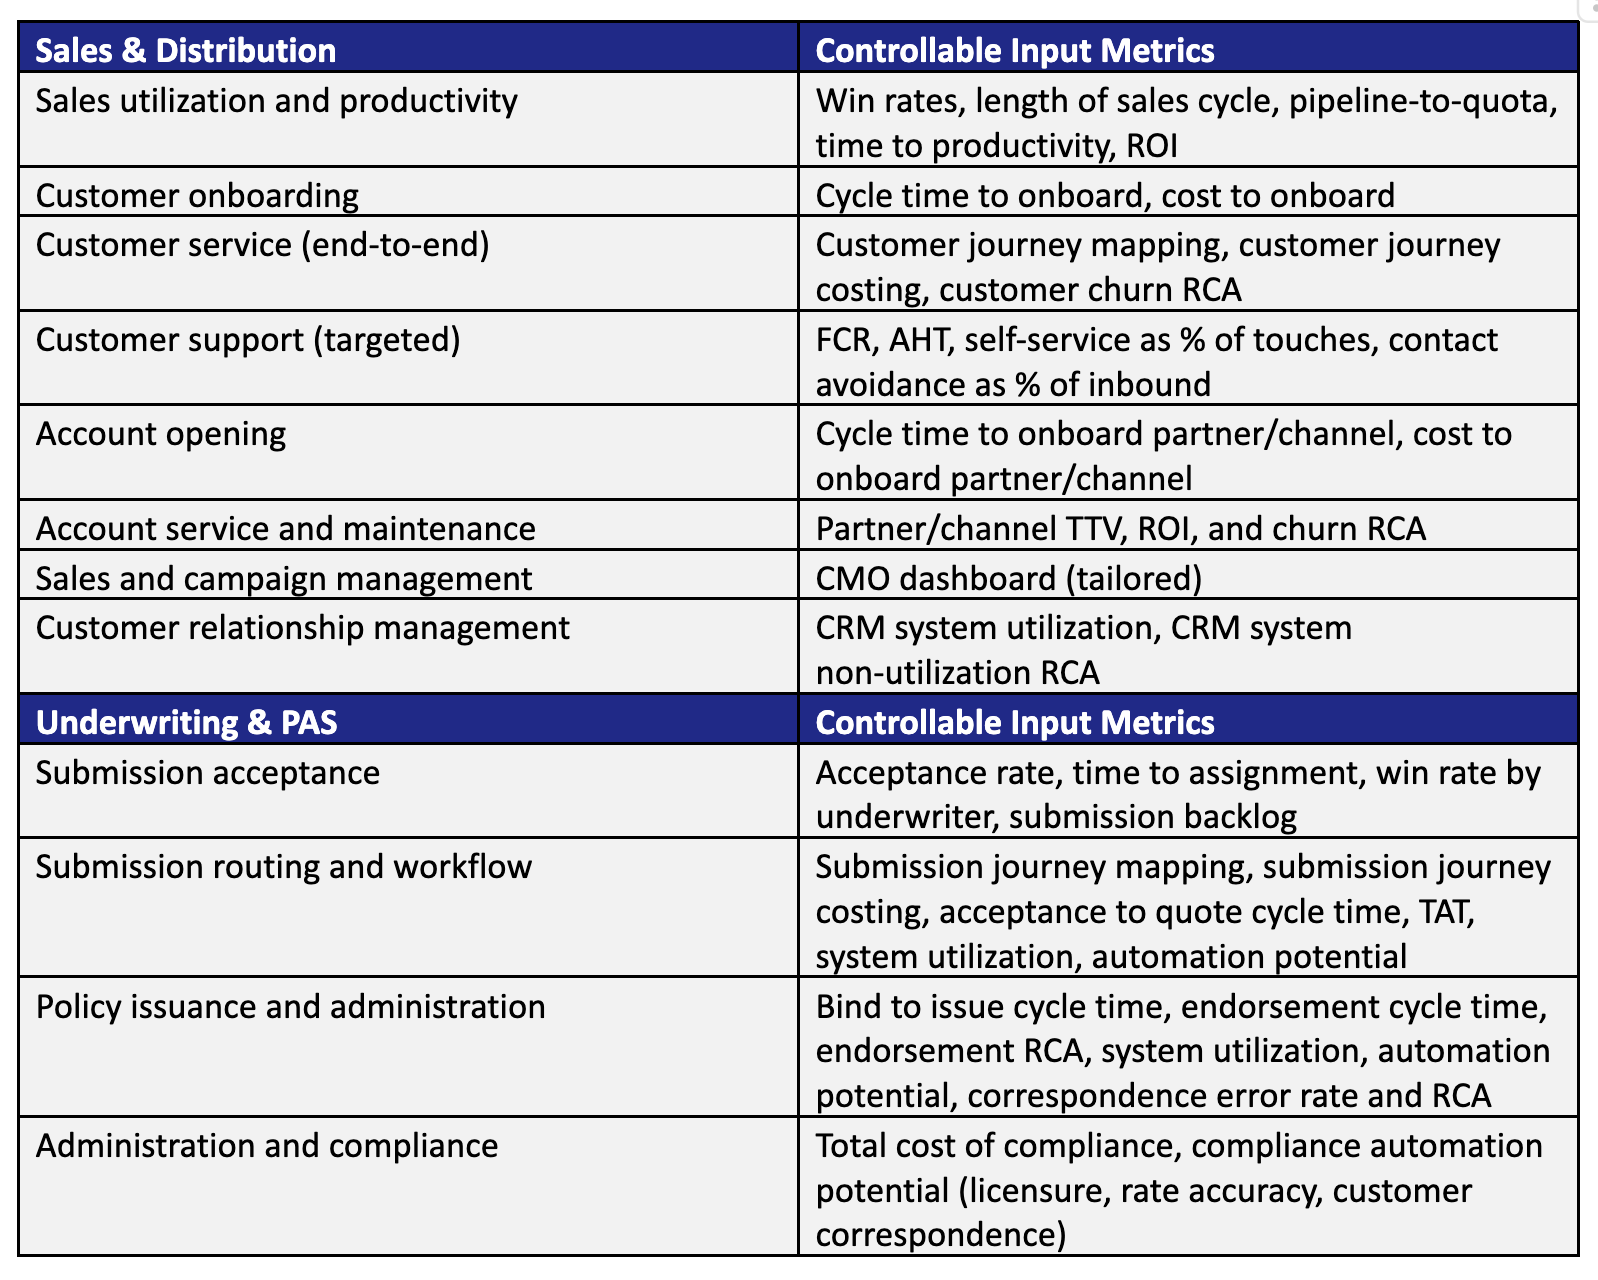
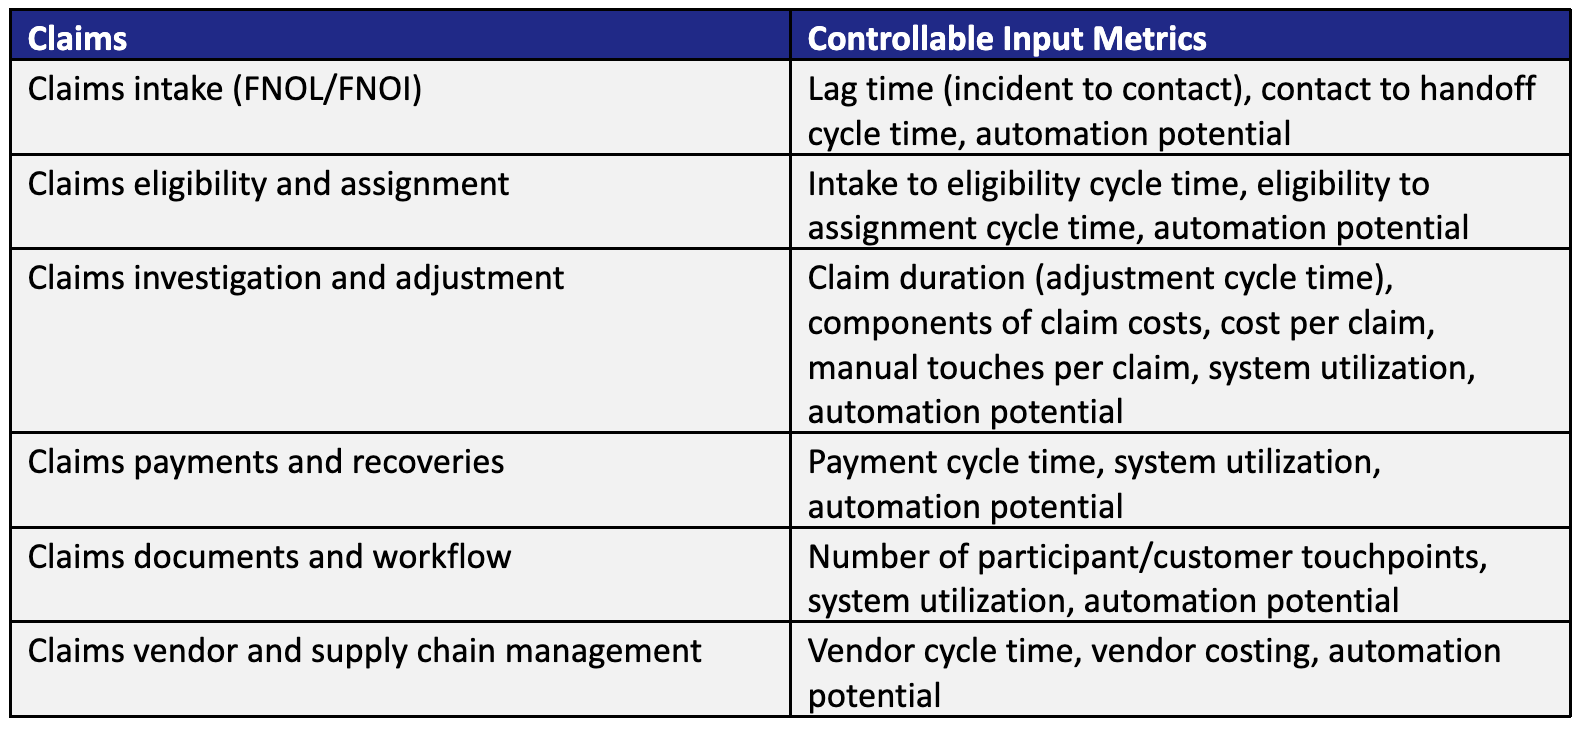
In the now, meaning the current quarter, the controllable input metrics generated by these tools are incredibly helpful driving efficiency and optimizing for, typically, cost. Here are examples in three key areas, working customer-back:

And then there’s enterprise AI. Most insurers are rightly reluctant to use open frontier models like ChatGPT and Anthropic’s Claude to do real work. Many carriers are moving in the direction of building custom models trained on their own data. Operational intelligence tools build a “digital twin” of the humans and systems they’re observing, useful for model training whenever it comes. Scaling laws state: the more data, the better the AI. 

When the board asks, “What are we doing in AI?”, “building a digital twin of our operation for eventual in-house proprietary AI training” is never a bad answer. Especially when that same data drives operational gains paying for its creation.  


Riv Arthur

Profile picture for user RivArthur

Riv Arthur

Riv Arthur is a business leader and technologist working in insurance, healthcare, and private equity.

AI’s Impact on Emerging Risk Management Trends

Risk management has been slow to adopt generative AI. Fortunately, that is starting to change.

An artist’s illustration of artificial intelligence

Even as large language models (LLMs) have made their way into almost every new mainstream product, some industry sectors have been slow to adopt AI. Risk management is one of them. Fortunately, that is starting to change.

According to a 2023 Deloitte study, only 1.3% of insurance companies had invested in AI. But data from this year indicates a shift is underway. In Conning’s 2024 survey, 77% of respondents indicated that they are in some stage of adopting AI somewhere within their value chain. This may sound a bit nebulous — some stage, somewhere — but it represents a sizable jump from the 61% of respondents the prior year. Additionally, 67% of insurance companies disclosed they are piloting LLMs.

We also found evidence of change with our own survey, one specifically tailored to risk management. We polled 1,000 risk managers and almost half indicated that they expect to adopt generative AI (GenAI) tools within the next three years. These increases collectively speak to the potential for AI to affect our industry.

Before we look at where we could go with AI, let’s look at the challenges that have slowed adoption in risk management.

See also: Providing Coverage for AI May Be Huge Opportunity

What’s Holding Us Back?

Based on our years of work developing AI systems for insurance and researching the needs within organizations, we’ve identified a few key issues:

  • At the organizational level: Change is hard, and many companies struggle with integrating AI technologies into their existing infrastructure. Risk management systems often involve complex legacy systems that are not easily compatible with outside tools. They also may not have a clear line of sight into exactly what they want AI to accomplish or how to measure it. Seamless integration requires a lot of forethought and the right partner to ease the transition and ensure that the system is doing what an organization wants or needs.
  • At the IT level: The technical complexity of AI tools requires specialized knowledge and skills. In risk management, as with many sectors, there can be a shortage of in-house expertise to manage and leverage new technologies effectively. Companies need to carefully consider their hiring strategies to account for this or perhaps look into outsourcing options to achieve the best results.
  • At the adjuster or claims rep level: One of the big impediments has been that many people still don’t know exactly what AI does, how it works, or what its limitations are. Couple this lack of knowledge with mainstream messages about privacy concerns or AI taking people’s jobs, and hesitancy is understandable. Comprehensive education and training programs would help overcome the hurdle in terms of grasping AI’s potential to make their work easier and more efficient while staying within regulatory guidelines. Workers will also become more comfortable as they increasingly use models like ChatGPT and Gemini in their personal lives. They will see that AI is not intended to replace humans but rather augment their capabilities, arming them with unprecedented insights they can use alongside their own experience and judgment for the best outcomes.

Why Do We Want AI?

With so many considerations, it raises the question: What exactly can AI do for risk management that is so great? A lot! So much, in fact, that the technology can no longer be ignored. Here are some of the biggest and most successful active use cases we see:

  • Claims processing: AI is being used to automate tasks like reviewing medical records and legal documents, streamlining the claims process, and reducing errors. Not only is it making claims adjusters more efficient, but it is also removing the drudgery and manual processes of their work so they can concentrate on what matters most.
  • Fraud detection: We all know fraud is a big problem in claims. AI algorithms can analyze historical data to identify patterns that spot potentially fraudulent items, alerting adjusters and triggering a human review. Identifying and eliminating fraud, especially early in the claims process, can save organizations millions of dollars each year.
  • Reserving: On the flip side, some claims simply require more. AI systems can predict potential cost overruns for these complex cases. This allows risk managers to adjust reserves and prioritize cases accordingly so claims don’t run up any more or last any longer than necessary.
  • Underwriting: AI can also be leveraged to analyze vast amounts of patient data — far more than a human could possibly consume — to create more accurate risk profiles almost instantly. With better risk profiles, costs go down. This leads to fairer and more competitive pricing for healthcare policies, which is, in turn, an enormous benefit to patients.
  • Knowledge transfer: It’s no secret that risk managers and adjusters are aging out. There will be a massive talent drain when they retire, taking institutional knowledge with them. AI-powered tools can capture their expertise, preserving that invaluable knowledge for future generations.

See also: Cautionary Tales on AI

The Road Ahead

Embracing AI presents an opportunity to advance our industry through improved efficiency, reduced costs, and ultimately, better patient care. These outcomes are worth the effort spent to overcome challenges. The time is right to move the industry forward and to usher in a modern era of risk management.


Heather Wilson

Profile picture for user HeatherWilson

Heather Wilson

Heather H. Wilson is chief executive officer of CLARA Analytics. 

She has more than a decade of executive experience in data, analytics and artificial intelligence, including as global head of innovation and advanced technology at Kaiser Permanente and chief data officer of AIG.


Patrick O’Neill

Profile picture for user PatrickO’Neill

Patrick O’Neill

Patrick O’Neill founded Redhand in 2015 to help organizations maximize their investment in risk technology.

He previously was president and chief operating officer of a risktech startup focused on workers’ compensation and disability management technology solutions. Earlier, at Marsh, he was managing firector and founding member of the broker’s RMIS business and held a series of leadership roles in that unit.

How AI and Automation Are Revolutionizing Claims

As the insurance sector looks for ways to fast-track claims processing, adopting AI is not just a trend but a must.

An artist’s illustration of artificial intelligence

The insurance sector has been looking for ways to fast-track claims processing to foster better customer experience and maintain revenues. Adopting technology like AI is not just a trend but a must.

See also: Insurance: An Industry Embracing AI

Let’s understand how AI streamlines each step-in claims processing:

1.  Empowering Decision Makers

With AI entering claim processing, the ability to evaluate claims has leveled up. AI can make judgments based on large historical datasets and flag fraudulent activities missed in manual investigations.

2.  Speeding Processing

AI-powered systems drastically speed up processes by automating most of the manual tasks. AI can tackle claims at initial levels and categorize them based on urgency. It can further escalate the conversations to the right authorities in real time. 

Let’s now explore some of the top advantages of claims automation:

1.  Smooth Data Analysis

Replacing manual processes with automation leads to higher employee morale. Automation addresses challenges like miscommunications between departments and other delays in claim resolutions. Automation reduces manual data entry, while processing and analyzing unstructured data.

2.  Customer Satisfaction  

Customer satisfaction and loyalty are closely tied to the speed and accuracy of claims processing. Automated workflows enable insurers to deliver faster resolutions, which translates to happier customers. 

For example, with automation, customers can access the real-time status of their claims via chatbots, while freeing agents to spend time on developing meaningful relationship. McKinsey has found that using the right technology can increase customer satisfaction by 20%. 

3. Compliance

AI can be used to spot potential problems that escape human scrutiny and enhance regulatory compliance.

See also: Cautionary Tales on AI

A Real World Example

A national healthcare insurance provider faced challenges in handling claim errors and corrections. Their system required human intervention for a few items. Subject matter experts (SMEs) reviewed emails, created correct copies, and resubmitted, requiring significant time and resources while adding complexity.

A claims automation solution saved over 1,300 monthly work hours for local claims and reduced processing time to 2.5 minutes per claim. For ITS claims, the system saved over 1,600 monthly work hours, with processing time cut to just one minute.

The robotic process automation (RPA) solution also enhanced accuracy by automating the error correction process.. It deployed bots to read and validate claim data, identify errors, and automatically correct them based on predefined business rules. The solution integrated seamlessly with the company’s existing claims management system.

Future Expansion 

As AI and automation evolve, their impact on the insurance industry is expected to grow.

1.  Advanced AI Models  

AI will likely lead to even more sophisticated models. These models will be capable of understanding nuanced contexts and handling complex claims, such as assessing damage from natural disasters or predicting long-term healthcare costs. 

2.  Integration With IoT and Telematics 

Insurers can gain insights into risk factors with real-time data collection. This allows for more accurate assessments and personalized policies.

3. Ethical AI and Transparency  

There will be a growing emphasis on ethical AI and transparency. Insurers must ensure their AI systems are fair, unbiased, and explainable. This will maintain trust with customers and regulators as AI becomes more integral.

4. Expansion of Automation Across Insurance Functions  

Beyond claims processing, automation will expand into underwriting, customer service, and policy administration. This holistic approach will enable insurers to create more efficient and customer-centric operations. 

AI technology is set to create endless opportunities in insurance.

Two Warnings About AI

Customers are making clear that they hold AI to higher standards than they do humans — and hate when AI makes decisions for or about them.

Image
blue glowing lock

If you've watched "The Good Place" — and you should, if you haven't already — you saw an enactment of a deep philosophical question known as "the trolley problem." The notion is that you're on a trolley heading down a hill, and the brakes fail. If you keep going straight, you're going to kill five people. You can throw a switch and head off onto a siding, but then you're going to kill one person. 

Do you save the five people and accept the responsibility of killing someone? Does your thinking change if that one person is a friend of yours?

The trolley problem may seem like an odd one to include in a comedy, but the handling is extremely funny, and, of course, no character stays dead. 

And the problem neatly exemplifies one of the issues that companies will face as they roll out AI that touches customers directly. If, like Chidi, the moral philosopher in "The Good Place," you make a spur-of-the-moment decision, you are given some grace because you're only human and can only process so fast. But AI doesn't get that grace. Someone sat down ahead of time and programmed or at least developed the AI, so whatever decision is made is treated as well-thought-out — and has to be defended.

AI is held to a much higher standard than we humans are. You can't just decide your AI is good to go once it outperforms your current approach when dealing with customers. You have to account for what people expect out of AI. 

The higher standards for AI have shown up recently in a spate of articles complaining about drones that use computer vision to inspect roofs. The technology sometimes says there is moss or some other problem that warrants denial of coverage when there is, in fact, no problem. 

The systems already do a better job than could be accomplished by having a host of inspectors climb ladders and tromp around on roofs, but homeowners aren't using the current system as their benchmark. They've been led to believe that computers are nearly infallible and that AI is close to magic, so they don't tolerate errors — and often complain to reporters, who share many of those attitudes and are happy to ding AI when it messes up. 

Phil Koopman, a professor at Carnegie Mellon who has a popular newsletter on driverless cars, writes: "It’s simple: people over-trust too soon, and backlash too hard just as quickly after adverse news."

While nearly 41,000 people died in accidents on U.S. roads last year, I'd bet that none got as much attention as the non-fatal accident involving a Cruise autonomous vehicle. The accident was gruesome: Although the AV was initially blameless, hitting a jaywalking pedestrian who was tossed into its path when another car hit her, the AV then pulled off to the side of the road, unaware that the pedestrian was underneath the car and was being dragged 20 feet. But the involvement of the AI greatly heightened the industry and the willingness to find blame — among other repercussions, the CEO of Cruise lost his job, and Cruise lost its license to operate autonomous robotaxis in San Francisco.

My second caution about AI is that, as an article in The Byte expresses it: 

"So-called 'automated decision-making' is being heralded as the next big thing  — but it turns out that many consumers are disgusted by the idea of AI making choices for them."

The article cites a survey that isn't specifically about insurance; it's about job hiring, banking, renting, medical diagnoses, and surveillance. But it's pretty easy to extend the survey results apply to insurance. 

Just as customers want a human making decisions on their loan or job applications, I'd bet that customers don't want to be told that they were denied coverage by AI or had a claim lowered or denied by AI.

AI will increasingly be used to make decisions that touch clients — as it should be — but, at least for now, I'd suggest having humans make the final call and communicate those decisions.

You'll still be required to defend the AI's role in decisions, and people won't give you the benefit of the doubt that they might give to a human acting under time and other pressures.

But at least you won't have to deal with the theatrics that the Ted Danson character summoned for poor Chidi.

Cheers,

Paul

P.S. Here is the trolley scene from "The Good Place." Watching it will be the best three minutes of your day.


Why the P&C Market Needs AI Driven Behavioral Insights

The U.S. P&C insurance industry faces challenges. AI-based behavioral insights improve risk prediction, helping insurers stay competitive and profitable.

ai

The US P&C insurance industry faces many challenges as it struggles to get a handle on a changing economic, social and climate landscape. The list of perils seem to grow every year from the increasing frequency and severity of catastrophic and other weather related events to social inflation, population shifts and regulatory rate hurdles to expanding competitive pressures.

Carriers have little control over these external forces. Typically, they resort to using the conventional levers including extensive rate increases, dramatic changes to eligibility requirements and product changes that eliminate coverage. While these approaches can alleviate some carrier issues, the new truth is that they are not enough to make a positive impact for the business.

The industry is rife with stories of carriers going insolvent, soaring reinsurance costs and entire sections of the US having unprecedented struggles accessing basic insurance products. US insurers are in need of forward-thinking, data-driven solutions to help them grow profitably all while achieving adequate, fair underwriting practices and increasing accessibility. 

One potential solution to the problem is advancing our knowledge of individual insureds and their needs. 

Understanding customer behavior and risk tendencies enables insurers to better predict outcomes and make targeted decisions that support profitable growth. Today, most carriers rely on predictive modeling to stay competitive. The industry recognizes the power of analytics in categorizing insureds into broad groups based on factors like credit scores, claim-free periods, and residential zip codes. However, advancements in technology have confirmed that the traditional variables are too broad, too bulky and do not provide the stratification we need to fairly and accurately assign risk.   

Person-level behavioral insights involve a big data approach to evaluating an individual's propensity for some target variable based on their behaviors and actions. By using a vast amount of information including but not limited to a specific insured's interests, purchasing behaviors, media consumption, and associated brands, these newer and powerful AI models are able to more accurately predict frequency, severity, loss and other insurance related outcomes. Insurers will be better equipped with these insights to navigate market volatility, more accurately assign risk, avoid adverse selection, and achieve underwriting profitability and growth.

Of course, there are important questions pertaining to bias when assessing this level of information on an individual. With modern statistical techniques, these models must be built with stopgaps and intense scrutiny on their potentially disparate impacts to protected groups.  Luckily, these techniques exist within the behavioral insight industry and have even been proven to improve the biases the insurance industry sees in its existing underwriting processes. 

Overall the goal of integrating behavioral insights into modern insurance is to create a more targeted, profitable, available and less-biased product. As the industry evolves, carriers that embrace behavioral intelligence will be better equipped to face uncertainty, proactively respond to challenges, and secure their position in the market. In an era where the stakes are higher than ever, the ability to accurately assess and manage risk will distinguish the leaders from the laggards in the insurance industry.


About Devyn McNicoll, Pinpoint’s Head of Actuarial

devynDevyn McNicoll a traditionally trained actuary with over 10 years of experience helping companies grow profitability in the P&C insurance space. She is an Associate of the Casualty Actuarial Society (ACAS), a Certified Specialist in Predictive Analytics (CSPA) and holds her Master’s degree in Statistics from North Carolina State University. She deeply values the role of data analytics and mathematics in the industry. Prior to Pinpoint, she was in an executive leadership role at an MGA offering Homeowners and Commercial Property products. She has extensive experience in actuarial pricing, reserving, filing, modeling and leadership at several large national insurance carriers. In 2023, she was one of two actuaries who represented the US in the Young Actuaries World Cup as a semi-finalist in the competition.

Sponsored by ITL Partner: Pinpoint Predictive


ITL Partner: Pinpoint Predictive

Profile picture for user PinpointPredictivePartner

ITL Partner: Pinpoint Predictive

Pinpoint Predictive provides P&C insurers the earliest and most accurate loss predictions and risk scores to fast-track profitable growth and improve loss ratios. Unlike traditional methods, Pinpoint’s platform leverages deep learning, proprietary behavioral economics data, and trillions of individual behavioral predictors to help insurers identify the risk costs associated with customers and prospects.

Insurtech 100 Awards 2022 | Insurtech Vanguard | AI Breakthrough Awards 2023 | Global Tech Awards 2023 - Category Winner for AI, AnalyticsTech and Insurtech | Insurance Awards 2023 - Category winner for Insurtech in World Finance Magazine 

Cybersecurity Essentials for Insurance Agents

Cybersecurity is crucial for insurance agents to protect sensitive client data from rising cyber threats.

cybersecurity for agents

Insurance agents are at the forefront of handling sensitive health-related, personal, and financial data. They are thus prime targets for cybercriminals at a time when cybercrime is expected to cost the global economy more than $10.5 trillion by 2026 and when the global cyber insurance market is expected to soar by nearly a factor of six by 2032, to $120.47 billion. 

Agents must remain attentive; recognizing the scope of their risks strengthens security.

Types of Cybercrimes and Their Prevention

Cyber risks are growing more complex. Here are typical forms of cybercrime and how you can safeguard your agency.

1. Malware

Malware, or malicious software, intends to penetrate and destroy systems while frequently stealing important data. It can take many forms, including viruses, worms, and trojans. Email attachments or USB devices can spread it.

Prevention Tips:

  • Install and update antivirus software: Do not forget to renew your antivirus software because it is always the first step to detecting new malware.
  • Educate your team: Teach your employees to recognize unwanted emails or connections and avoid downloading unauthentic software files. In addition, ensure spreading awareness about emails with attached files received from an unknown source.
  • Regularly back up data: Always back up your data to prevent data loss due to malware infecting your computer.

2. Phishing

Phishing attacks are socially engineered techniques in which an attacker spoofs as a trusted entity. Phishing aims to deceive people into disclosing sensitive information, tempting them with convincing calls to action or offers to click on dangerous websites. These URLs are often distributed via email, SMS, or calendar invitations.

Prevention Tips:

  • Check whether the sources of the email are verified: Always check if the sender's address is correct and watch out for odd requests.
  • Get multifactor authentication (MFA): Extra security measures prevent unauthorized access, even if the login credentials are exposed.
  • Use spam filters: Use enhanced spam filters to block phishing emails before they reach your inbox.

3. Ransomware

Ransomware is software that encrypts files and demands money for their release. Ransomware potentially causes irreversible data loss as well as financial and operational destruction.

Prevention Tips:

  • Make regular backups of your data: This creates a safe copy of your data that you can retrieve after ransomware breaches.
  • Always keep your software up to date: Secure your operating systems and applications by keeping them up to date. Ensure you fix all the vulnerabilities that ransomware can use.
  • Set administrative permissions to the least level: Another best way to keep ransomware from spreading through your network is limiting user privileges.

4. Insider Threats

Insider threats emerge from within an organization. They can be deliberate or unintentional. Any current or former employee, contractor, or business partner can misuse their rights. They can steal data or fall for a phishing scheme, resulting in a cyberattack.

Prevention Tips:

  • Set access controls: Enforce policies so employees only access the information necessary for their job. Also, update the roles that people currently hold.
  • Administer employee activity: With the monitoring tool, you can discover unusual actions that suggest an imminent insider threat.
  • Positive work environment: Having many dissatisfied employees may lead to the likelihood of insiders committing fraudulent activities.

Implement preventive steps and stay current on prevalent cybercrimes to considerably lower insurance agency breaches. Staying up to date on cybersecurity defenses can secure your business and clients from online threats.

Best Cybersecurity Practices for Insurance Agents

Insurance agents must prioritize their clients' information with robust cybersecurity practices:

1. Comprehensive Security Training

Ensure that your employees are frequently trained in how to identify forms of cyber threats and how to handle them. This will provide the first level of protection against attacks and makes most tasks within your agency secure.

2. Using Digital Certificates

Insurance agents should use SSL certificates to keep clients' sensitive data secure. These data include names, addresses, emails, and Social Security numbers. SSL certificates create a secure layer to share data between the user and server.

Using HTTPS maintains your business reputation. When an insurance company or website does not use an SSL certificate, Google flags that as a non-secure site, which can affect your brand identity.

There are various types of security certificates based on the needs of businesses. Companies can choose from multiple certificates like domain validation, wildcard SSL certificate, and extended validation.

3. Multifactor Authentication (MFA)

Implementations relying on or only using passwords for the authorization of the systems are not solid enough. Integrating MFA takes security to the next level and can be done simply:

  • Login Verification: Ask your employees and clients to enter a secondary code sent to their mobile devices after they enter their passwords, or have them unlock their devices with a fingerprint. 
  • Hardware Tokens: High-level employees who might have to deal with sensitive data can use hardware tokens that generate time-sensitive codes that allow access.

4. Regular Data Backups

Backing up should be considered in the same way as an insurance policy for your data. Backing up relevant data often enough means that you can get back into operation in a short time after a cyberattack or failure of IT systems. When it comes to backups, go for several tiers of backup, such as local, offsite and cloud-based.

Types of Backups:

  • Local Backups: Use external hard drives or NAS devices.
  • Offsite Backups: Consider tape or remote server backups.
  • Cloud Backups: Use AWS, Google Cloud, or Microsoft Azure for scalable, automated solutions.

5. Controlled Access to Data

Not every employee working in your agency requires access to all the data available with the organization. It is necessary to enforce information security policies that would limit the accessibility of specific data to a few individuals. This helps reduce the harm coming from internal threats and minimizes the possibilities of a leak of the firm's information.

6. Secure Communication Channels

Security will always recommend the use of encryption when it comes to communications. Make sure that all data are encrypted, while they are being transferred, as well as during storage. This helps to eliminate instances where third parties may be intercepting and decoding your information.

7. Engage Security Professionals

It could also be wise to seek help from professionals as a viable strategy. Whether you hire your security team or consult cybersecurity specialists, it is always beneficial to have someone knowledgeable guide you when assessing and addressing risks.

8. Network Traffic Monitoring

Surveillance of the network must be done keenly. Network monitoring lets you identify suspicious activities likely associated with a cyberattack. It is also important for organizations to learn to prevent a breach from happening in the first place or at least provide early alerts.

9. Incident Response Planning

Even with the best efforts, you can still find yourself facing a breach. In the event of a security incident, your team must have a clear copy of the response plan. This can greatly reduce the time it takes to recover from an attack and minimize data loss.

These security measures effectively safeguard sensitive data and protect your agency.


Liam Allen

Profile picture for user LiamAllen

Liam Allen

Liam Allen is a freelance writer who focuses on the latest trends in insurance and digital marketing. 

AI Enables Advances in Fraud Detection

Cohort analysis and AI detect insurance fraud by identifying subtle anomalies, emerging trends, and contextual insights.

fraud detection

In the ever-evolving landscape of insurance, detecting fraudulent claims is critical yet challenging. Traditional methods have often fallen short, leaving insurers vulnerable to sophisticated fraud schemes. However, advanced artificial intelligence (AI) and machine learning (ML) techniques are revolutionizing this space, notably by using cohort analysis to identify and mitigate fraud.

The Power of Cohort Analysis and AI to Detect Fraud

Within fraud detection, cohort analysis emerges as a powerful technique that revolutionizes the way we identify suspicious patterns and behaviors. By grouping claims with similar characteristics, this approach unveils subtle anomalies that might elude even the most seasoned claims adjusters. Its multifaceted benefits collectively enhance the efficacy of fraud detection models.

One of the primary advantages of this method is its ability to detect emerging fraud trends. Through the continuous comparison of cohorts over time, AI systems can swiftly identify and address new and evolving suspicious claim activities, ensuring that fraudsters cannot stay ahead of detection mechanisms. This dynamic monitoring capability is complemented by the opportunity to tailor detection algorithms to specific patterns and behaviors unique to particular groups. Such refinement significantly boosts the accuracy and effectiveness of fraud detection, allowing for a more nuanced approach to identifying potentially fraudulent activities.

Perhaps most crucially, cohort analysis provides invaluable contextual insights. By understanding a claim within the framework of its cohort, outliers and unusual activities become more apparent, warranting further investigation. This contextual understanding is the key to uncovering fraudulent behavior that might otherwise slip through the cracks, making cohort analysis an indispensable tool in the arsenal of modern fraud detection strategies.

Key Capabilities of Effective Fraud Detection Systems

Effective detection systems have become essential for safeguarding the integrity of claims processes. Here are the core features of advanced fraud detection:

  • Cutting-Edge AI and Machine Learning: Advanced fraud detection systems use state-of-the-art AI and machine learning technologies. These models are trained on industry-specific claims data, ensuring that the system is tailored to the unique challenges of insurance fraud detection.
  • Continuous Learning Framework: Such systems employ a continuous learning framework, keeping models up to date with new data and adapting to emerging patterns of outlir claims. This ensures that insurers stay ahead of potential threats.
  • Network Analysis: A standout feature of this approach is advanced network analysis, which uncovers connections among attorneys and providers and creates a heat map that highlights potential fraud networks. This method reveals hidden relationships that contribute to various fraudulent schemes, enabling claims leaders and adjusters to identify which providers and attorneys to avoid.
  • Integrated and Interactive Fraud Detection Platforms: Modern fraud detection systems are not standalone tools but integrated components of broader platforms. This ensures seamless data sharing and dynamic updates across the system, enhancing the insights derived from fraud detection. Integration with other products deepens the connections discovered, unlocking additional insights on provider and attorney scoring. Adjusters receive not only information on suspicious activities but also suggestions for alternative options in the same area.
  • Seamless System Integration: Fraud detection systems are most effective when they integrate smoothly with existing claims workflows, ensuring easy adoption without overhauling current systems. An API-driven architecture allows for customization and scalability, catering to each insurer's unique needs and accelerating time to value.

The Real Value of AI-Driven Fraud Detection

The true value of AI-driven fraud detection in insurance lies in its synergy with human expertise. These systems augment fraud investigators' skills with sophisticated tools and insights, creating a collaborative environment where human intuition and machine precision work together. This empowers claims adjusters to make more accurate referrals to special investigations units (SIUs) with clear rationales, streamlining the investigative process.

AI's advanced capabilities, especially in network analysis, allow for early identification of potential fraud that might elude even experienced adjusters. By uncovering hidden connections and patterns, these systems capture suspicious activities that traditional methods might miss, enhancing overall fraud mitigation efforts.

Ultimately, AI-driven fraud detection elevates the entire fraud detection ecosystem. In a sector where fraud can have significant financial implications, advanced fraud detection systems offer cutting-edge solutions that go beyond traditional methods. By leveraging cohort analysis, network analysis and advanced AI technologies, these systems provide a proactive and integrated approach to fraud detection. This not only enhances the accuracy and efficiency of identifying fraudulent claims but also supports a collaborative environment where human expertise and AI work together to protect insurers from sophisticated fraud schemes.

As first seen in Global Fintech Series.


Mubbin Rabbani

Profile picture for user MubbinRabbani

Mubbin Rabbani

Mubbin Rabbani is vice president of product at CLARA Analytics.

He has over 15 years of product management experience focusing on commercial insurance claims. Prior to joining CLARA, he served in senior product leadership positions at Liberty Mutual, Agero and Deloitte. At CLARA, he is responsible for delivering innovative solutions that address critical operational and financial levers in the claims value chain.


Realignment in Insurance: Business Models, Product, Value-Added Services

Learn more about the immense pressure the insurance industry is facing, forcing insurers to rethink operational models and update outdated technology to stay competitive and relevant.

looking glass


majesco

New research from Majesco shines a light on the challenges the insurance industry is facing, and the necessary strategic initiatives and investment priorities insurers must prioritize to succeed in the future.

Read Now


Sponsored by ITL Partner: Majesco


ITL Partner: Majesco

Profile picture for user majescopartner

ITL Partner: Majesco

Majesco isn’t just riding the AI wave — we’re leading it across the P&C, L&AH, and Pension & Retirement markets. Born in the cloud and built with an AI-native vision, we’ve reimagined the insurance and pension core as an intelligent platform that enables insurers and retirement providers to move faster, see farther, and operate smarter. As leaders in intelligent SaaS, we embed AI and Agentic AI across our portfolio of core, underwriting, loss control, distribution, digital, and pension & retirement administration solutions — empowering customers with real-time insights, optimized operations, and measurable business outcomes.


Everything we build is designed to strip away complexity so our clients can focus on what matters most: delivering exceptional products, experiences, and long-term financial security for policyholders and plan participants. In a world of constant change, our native-cloud SaaS platform gives insurers, MGAs, and pension & retirement providers the agility to adapt to evolving risk, regulation, and market expectations, modernize operating models, and accelerate innovation at scale. With 1,400+ implementations and more than 375 customers worldwide, Majesco is the AI-native solution trusted to power the future of insurance and pension & retirement. Break free from the past and build what’s next at www.majesco.com


Additional Resources

Modernize or Fall Behind: 2025 Retirement & Pension Top Industry Trends

Read More

Closing the Insurance Customer Protection Gap: How Generational Differences in Risk, Readiness, and Coverage Are Redefining Insurance Value

Read More

Bridging the Customer Protection Gap

Read More

Transforming Specialty Insurance with AI

Read More

Leaders Reinventing Insurance: Strategic Focus on Business Operating Model and Technology Foundation

Read More

And the Finalists Are....

We've picked the nine finalists for this year's Global Innovation Awards, presented with the International Insurance Society, and they're an impressive lot. 

Image
awards

This past year was a good one for innovation, as demonstrated by the large number of stellar nominations we received for our second year of the Global Innovation Awards, which we collaborate on with the International Insurance Society. 

The nine finalists chosen by our panel of distinguished judges show, in particular, how AI is moving from theory to practice, how insurance is stepping up to some of the biggest societal problems, and how the industry is finding opportunities in the Predict & Prevent business model, moving beyond the traditional repair-and-replace approach. 

Let's have a look.

We'll start with the three finalists in the Predict & Prevent faculty because that's my favorite category and, after all, I'm the one writing this. In no particular order, they are:

Praedicat's CoMeta, which takes the analysis used in predictive models for natural catastrophes and applies it to the problems that liability underwriters face to help them spot major issues before they become major. 

Wouldn't you like to know what will become the next asbestos? Praedicat was founded to address that question and says they can help you with the answer.

Roadzen, which uses computer vision and AI to monitor driver behavior, provide real-time feedback, and prevent accidents. 

I've seen a number of approaches like this, and I'm in favor of all of them. This one seems especially sophisticated. 

Far too many accidents still occur, and far too many people die.

Whisker Labs, whose Ting device plugs into wall sockets and detects electrical malfunctions that can be addressed before they can start a fire. Insurers have offered Ting free to more than 2 million policyholders because of the potential for preventing fires, and the devices are deployed in more than 700,000 homes. The devices can also report to utilities on malfunctions in the electric grid. 

We're big fans of Whisker Labs at ITL — for instance, here is a Future of Risk interview we did with the CEO late last year. Our parent organization, The Institutes, has been spreading the word, too, through a newsletter and podcast on Predict & Prevent (which you can sign up for here). Here is a podcast with the CEO of Whisker Labs from May 2023. 

They're worth a look.

Now for the three finalists in the Life, Health and Retirement category:

Aon "combines machine learning, terabytes of market claim data and expertise from Aon’s analytics, actuarial, clinical and reinsurance teams to predict over 50% of future high-cost [healthcare] claimant exposures ahead of time," their nomination says. 

I've become a big believer in triage as a way to become more efficient and solve a lot of problems, even if we can't solve all of them, and healthcare claims can run so high that getting some warning can make a huge difference.

Hannover Re has partnered with healthOme to use genomics to screen for cancers, laying the foundation for an array of sophisticated diagnostic tests and then for an approach to treatment that helps patients make informed decisions.

It's still early days for genomics, but it's incredibly powerful stuff, and offerings like Hannover Re's hold the promise of breakthroughs.

RGA has begun offering "simplified issue" policies for health and life insurance in South Korea, where many struggle with the traditional, full underwriting process, which requires a medical checkup. RGA merely requires answers to three yes/no questions.

Assuming those questions paint an accurate enough picture, "simplified issue" could make a big difference in a nation that is historically underinsured.

Now for Property/Casualty (likely the favorite for many of you):

Gallagher Bassett uses AI to screen workers' comp cases for those that are likely to need extra care and then provides a concierge service for those injured workers. 

Again, I'm a fan of this sort of triage approach, and AI is perfect for identifying the patterns that lead to complications. The Gallagher Bassett approach could be a great way to head off expensive cases while getting workers the help they need — and quickly.

Liberty Mutual is moving beyond offering maintenance advice to its homeowner customers and is tapping into "insights from our own internal operations, compelling offerings from our strategic partners and even novel capabilities from portfolio companies in the Liberty Mutual Strategic Ventures fund [to provide] new digital tools and experiences to help customers effectively manage and mitigate risks in their homes," according to the nomination.

I've always felt that maintenance reminders might really be a way to generate business for some contractor — I'm cynical that way — but reminders about the pool, the trampoline, the gutters, and so on could benefit a lot of people, especially if everything is in one place.

The Insurance Development Forum's Tripartite Programme tackles a truly worthwhile cause on behalf of the industry: "developing a series of meaningful and effective climate risk financing and insurance programs to help the populations of countries in need," as the nomination puts it. 

The program has rolled out projects in more than 23 countries, with 64 million beneficiaries, backed by offered risk capacity of $5 billion from insurance industry partners.

I told you these finalists were impressive.

The winners will be announced at the IIS' Global Insurance Forum, being held Nov. 17-19 in Miami. I hope to see you there.

Cheers,

Paul