Download

The Growing Need for Real-Time Data

Historical data offers outdated information. Real-time data keeps you informed of changes to a policyholder’s risk profile, letting you adjust premiums. 

Person Writing on White Paper

Insurance policy structures thrive on data. Traditional models collect information about past events to guide risk assessment procedures.

However, there are instances when historical data does not apply to the current landscape. New intelligence could drastically influence policy structures. Real-time data collection provides a continuous stream of data to keep information current, revolutionizing the world of insurance. 

Traditional data collection methods — such as email questionnaires, oral conservations, and web forms — have been sufficient, especially at providing personal information about customers. However, this same set of tools creates several pain points for insurance companies:

  • Organization: There is a variety of information scattered throughout different collection methods, and collating the files requires a lot of resources. 
  • Viewing data: You may also struggle to access and view that data. Traditional intelligence piles up, requiring you to sort through files. Thus, viewing fresh information would still take time due to the backlog. 
  • Deriving value from data: Only 18% of insurance organizations have the tools and technologies to derive full value from the growing volume of files. Additionally, six in 10 collaborate with insurance technology companies, despite the fact that many insurance data masters view insurtechs as a threat. 

Real-time data collection offers a chance to enhance insurance systems. Introducing it may improve several processes:

  • Speeding up accessibility: Insurance professionals can pick out a recent file in a few clicks rather than sifting through multiple documents and scanning multiple texts. 
  • Verifying data reliability: Automating data collection verifies information to make it as reliable as possible. 
  • Accessing more accurate trends: You can also train predictive models to notice recent customer trends regarding their chosen insurance plans and claims. 
  • Forecasting outcomes: With more accurate data, companies could forecast outcomes and mitigate high-cost cases. They can also speed up adjustments. 
  • Enjoying more confidence: Insurance systems can also feel more confident in their numbers with real-time reporting. They can make more informed decisions and more accurately define patterns and trends. 

See also: The True Cost of Big (Bad) Data

Risk Assessment Accuracy

Historical data offers outdated information, and inaccuracy may result in financial losses. With real-time data, you remain informed of changes to a policyholder’s risk profile and can make adjustments to their premiums. Here are a few examples:

  • Driving and auto insurance: If you have real-time insight into a policyholder’s driving behaviors — such as speed and acceleration — you can adjust your assessments. If you notice any concerning behaviors, you can offer incentives for safe driving behaviors and assess whether they are effective.
  • Weather and homeowners insurance: If a policyholder lives in an area that has experienced an uptick in extreme wildfires, hurricanes, floods, or other weather phenomena, real-time data can determine their present risk and indicate whether it would be beneficial to update coverage. 
  • Theft and homeowners insurance: Real-time data can reveal high-risk areas where higher premiums may be necessary. 
  • Policyholder health and health insurance: Monitoring an individual’s health history, demographic factors, and lifestyle in real time can guide insurance companies to update health insurance premiums. 

Personalized Service

Real-time data collection allows insurance companies to offer personalized services to current and potential policyholders. Predictive models showcase more recent trends to see what people in different segments want in their insurance plans. You can match coverage limits, premiums, deductibles, exclusions, and other terms and conditions to the specific individual. 

Updated information can also speed the claims process. With automation, there’s no need to review paperwork and find the relevant data for a case. Automated systems can compile everything you need so that the recent data is at your fingertips.

With real-time data, you’ll understand how policyholders wish to be contacted and can communicate with them effectively. You also get a better basis for your decisions and inevitably create better insurance policies. 

Dynamic Pricing

Real-time data collection is also ideal for creating more dynamic pricing strategies.

Machine learning models that use historical data to guide pricing only improve profits by 1% or less. Replacing historical data with a continuous stream of information tailored to the individual policyholder can lure away potential policyholders from competitors.

Dynamic pricing allows you to act on real-time market changes and meet customer expectations. 

In addition to gathering market data about competitor pricing and demand, you can offer premiums that reflect the individual policyholder, essentially offering lower premiums for low-risk customers and higher premiums for high-risk customers. 

See also: Unauthorized Use of Auto Claims Data

Advanced Fraud Detection

In the U.S., more than $300 billion is lost to insurance fraud annually. Fraud results in higher premiums for all policyholders and costs each consumer approximately $900 per year.

Real-time data plays a critical role in detecting and preventing fraud. Policyholders may make illegitimate claims, whether deliberately or accidentally. With current information, insurance companies can detect anomalies and discrepancies in documents and evidence.

Whether a policyholder deliberately fakes an accident to fabricate an insurance claim, misrepresents an accident to receive a bigger payout, or accidentally omits important information when making a claim, real-time detection can help.  

Machine learning (ML) models are especially useful because they can calculate large datasets. One study published in 2024 found that effective ML models could drastically reduce health care fraud and minimize the resources needed to investigate probable fraud. 

When integrating real-time data collection and fraud detection technology, a human set of eyes must still assess those activities and make the final decision. Predictive analytics and models are only meant to display information and are still not perfect in their structure. 

Privacy and Compliance Considerations

Insurers must, of course, comply with privacy laws. A significant example is the European Union’s General Data Protection Regulation (GDPR), which extends its protection beyond its borders. 

A U.S. company may only receive personal data from an EU resident in accordance with GDPR guidelines. Insurers that provide services to individuals in the EU must comply with GDPR regulations, regardless of where the insurance company is registered. 

Select U.S. data protection laws also exist and prioritize the protection of policyholders. For instance, the Insurance Information and Privacy Protection Act (IIPPA) covers California residents, while the Health Insurance Portability and Accountability Act (HIPAA) protects an individual’s medical records and personal health information. Another important law is the Gramm-Leach-Bliley Act, which requires companies that offer financial services to explain their information-sharing policies to customers. 

Technological advancements like blockchain can provide data privacy advantages to insurance policymakers and holders. It’s designed to protect confidential and sensitive information by decentralizing control and using encryption to ensure data is inaccessible to unauthorized users.

Blockchain technology maintains the system's integrity and gives users peace of mind that their data is protected. Insurance companies also implement traditional cybersecurity protocols to mitigate cyberattacks.  

Revamped Policy Structures

Effective insurance policies protect policyholders. The best insurance policies are tailored to the individual and take market conditions into account. These policies help foster the relationship between companies and people. However, policies created using outdated information benefit neither party. In fact, they may diminish policyholder trust and lead to adverse financial outcomes. 

Real-time data collection is a key asset for insurance professionals. They can gain more updated information about their current and potential policyholders and resolve some of the issues associated with using historical data. With real-time data, your company can better assess risks and create a better relationship with customers. 

Jack Shaw

Profile picture for user JackShaw

Jack Shaw

Jack Shaw serves as the editor of Modded.

His insights on innovation have been published on Safeopedia, Packaging Digest, Plastics Today and USCCG, among others.


Harnessing Data to Improve Decision-Making

Here are five ways to use insurance data to gain insights on claims, underwriting, marketing, and operations and gain a competitive advantage.

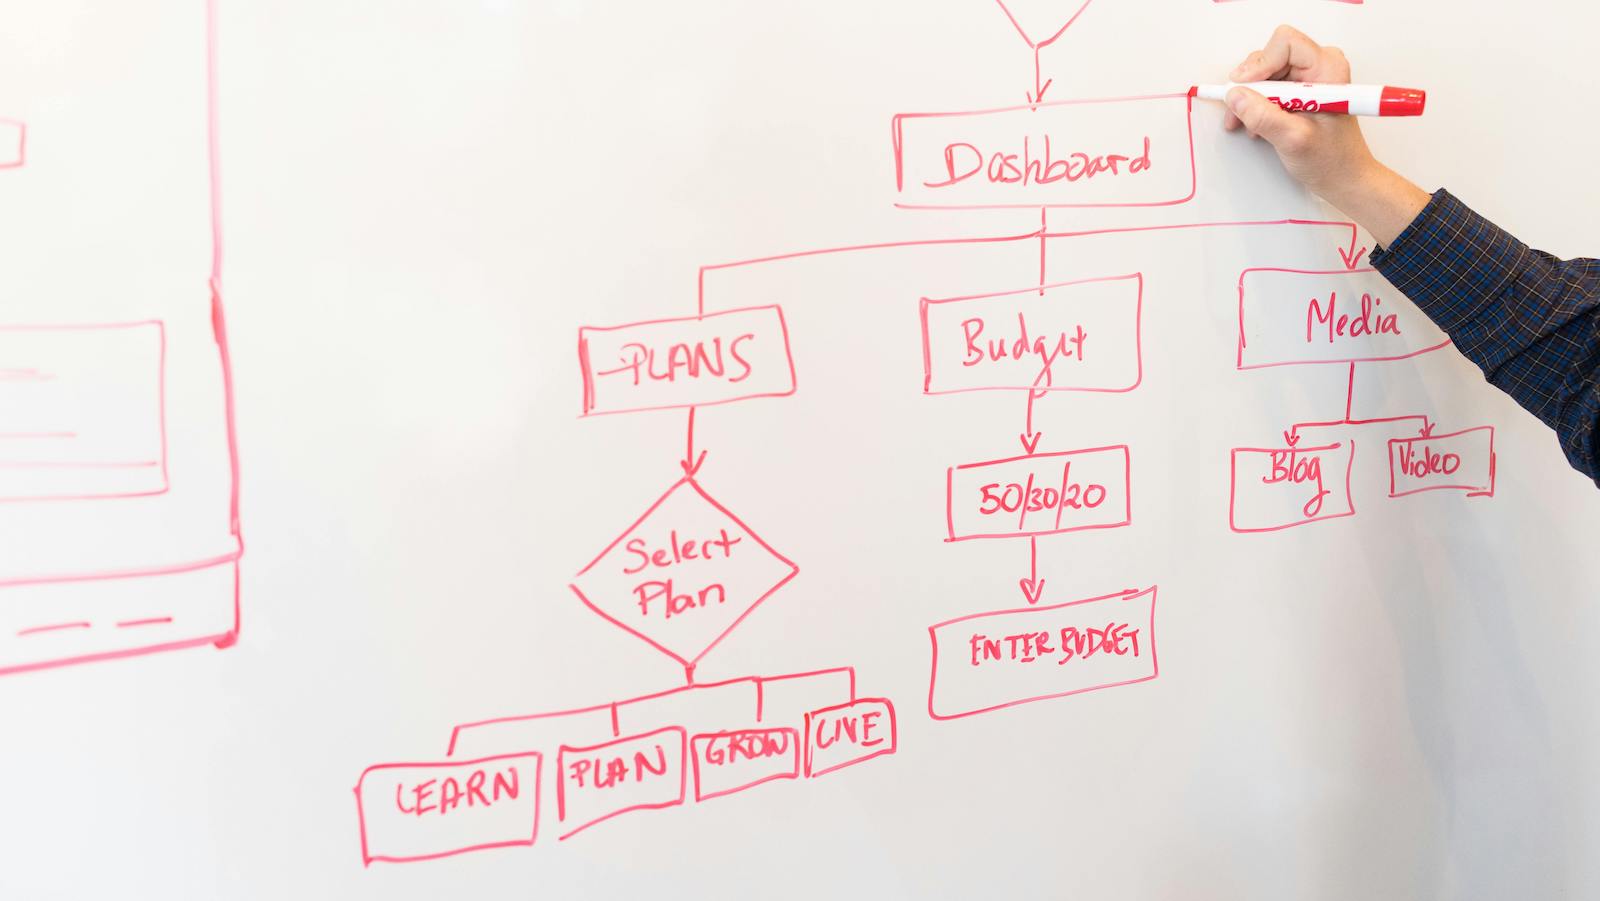
Flowchart on whiteboard

From historical claims data to hazard or policy data, insurance companies are sitting on an untapped goldmine of information, and only those that can convert this data into useful insights unleash its real value.

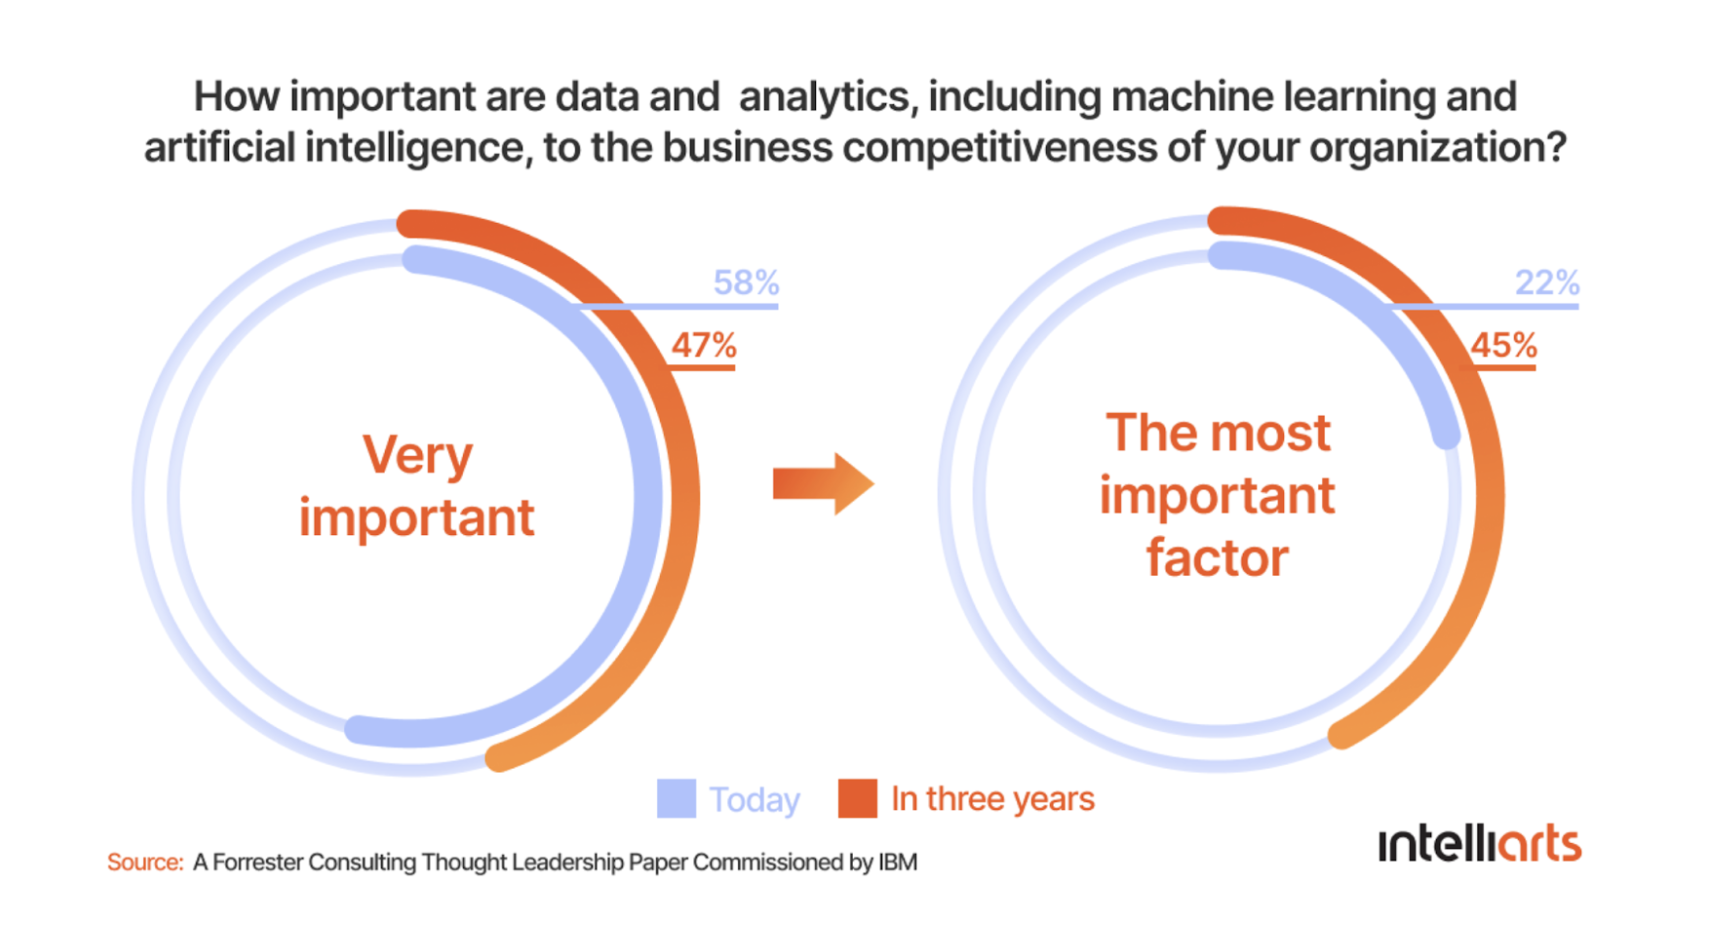
According to IBM, 47% of insurance businesses consider data and analytics a key to their competitive advantage. This percentage is projected to grow to 58% in a few years. This isn’t surprising, if we consider that data can help insurers enhance decision-making, contribute to innovation, and increase customer satisfaction and operational efficiency.

Let’s explore how to unlock the potential of big data with the help of analytics and machine learning technology.

Infographic: How important are data and analytics to business competitiveness?

Five ways to get the advantage of insurance data

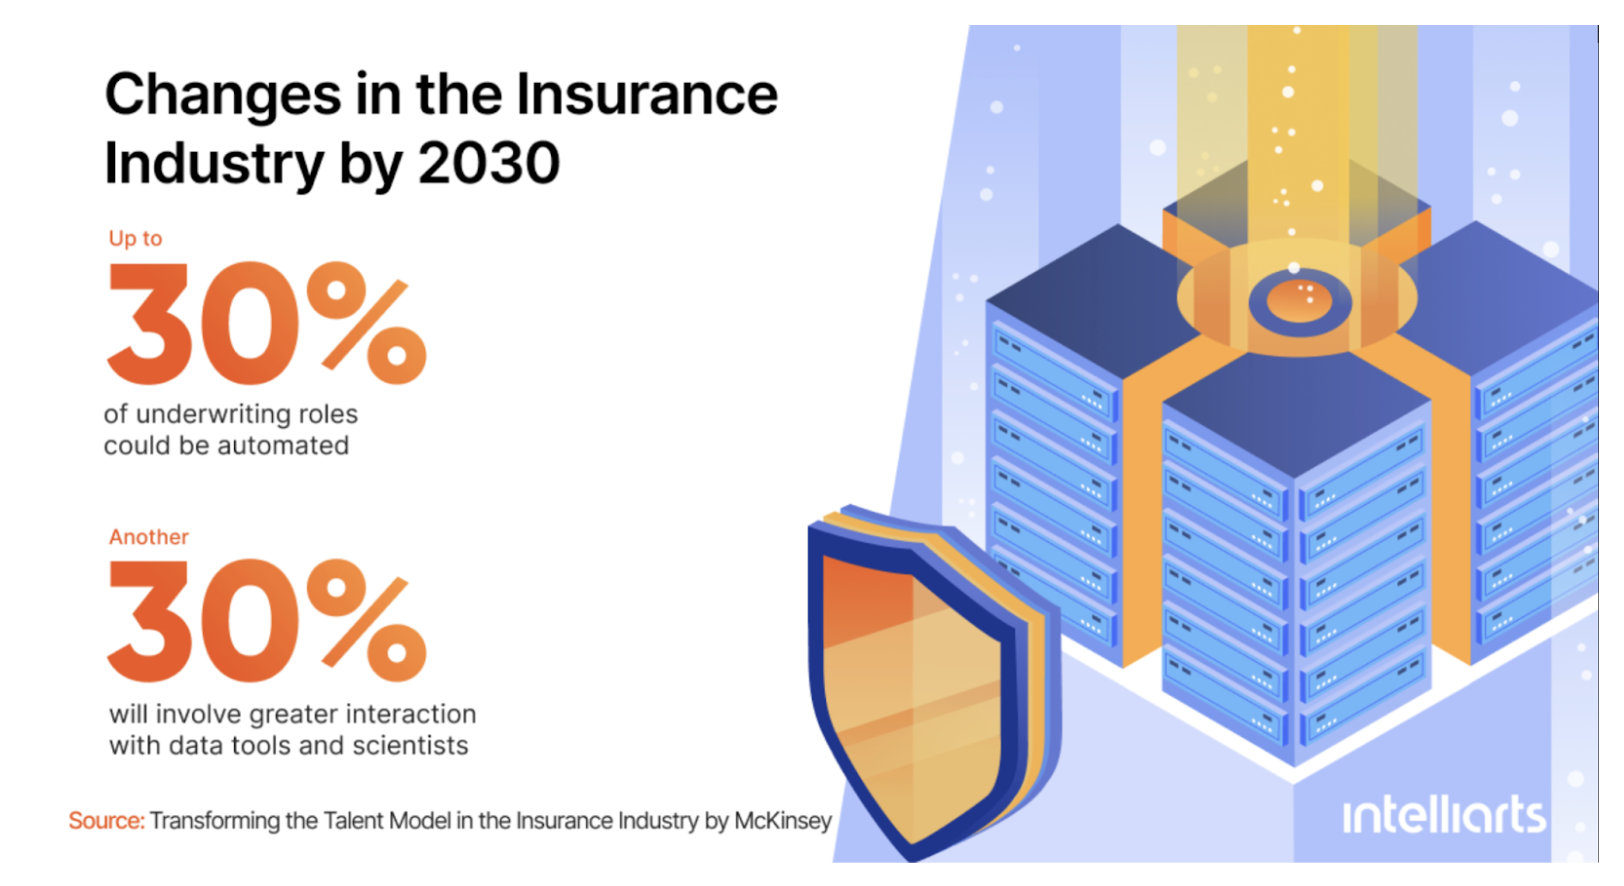
Research finds that from 10% to 55% of the tasks performed by insurers could and will be automated over the next decade, including claims, underwriting, marketing, and operations. We’ve already been witnessing a prominent shift in how insurers approach their business strategy, making an emphasis on data-driven insurance. The major values that data analytics and data science in insurance bring include the following:

Improved lead generation

Data and analytics, including unstructured data, offer valuable insights about customer behavior and market opportunities. Insurers can use this information to get a fuller picture of their ideal customer and their journey. As a result, an insurance company can personalize interactions with leads, provide in-context offers, and choose a marketing tactic depending on the value of the customer.

In particular, marketing insights received from insurance data could be used in:

  • Building innovative products and services that would target specific customer segments.
  • Choosing the best channels and touchpoints to contact the leads.
  • Providing more personalized communication to attract leads, for example, by writing customized warm-up messages.

Here are some real-life examples:

  • Paired with machine learning, data science has empowered a U.S.- based digital insurance agency to improve lead quality by 5% and insurance agent efficiency by 3%.
  • French multinational insurer AXA relies on data analytics and predictive modeling to identify future product and service priorities for different customer segments. This big data strategy has allowed the company to increase its sales.

See also: 'Data as a Product' Strategy

Higher customer satisfaction and loyalty

No doubt, the secret weapon for business success is to keep customers happy. McKinsey says satisfied policyholders are 80% more likely to go for policy renewals. And there are lots of ways to increase customer satisfaction in insurance, from delivering services faster and more efficiently to making them more personalized.

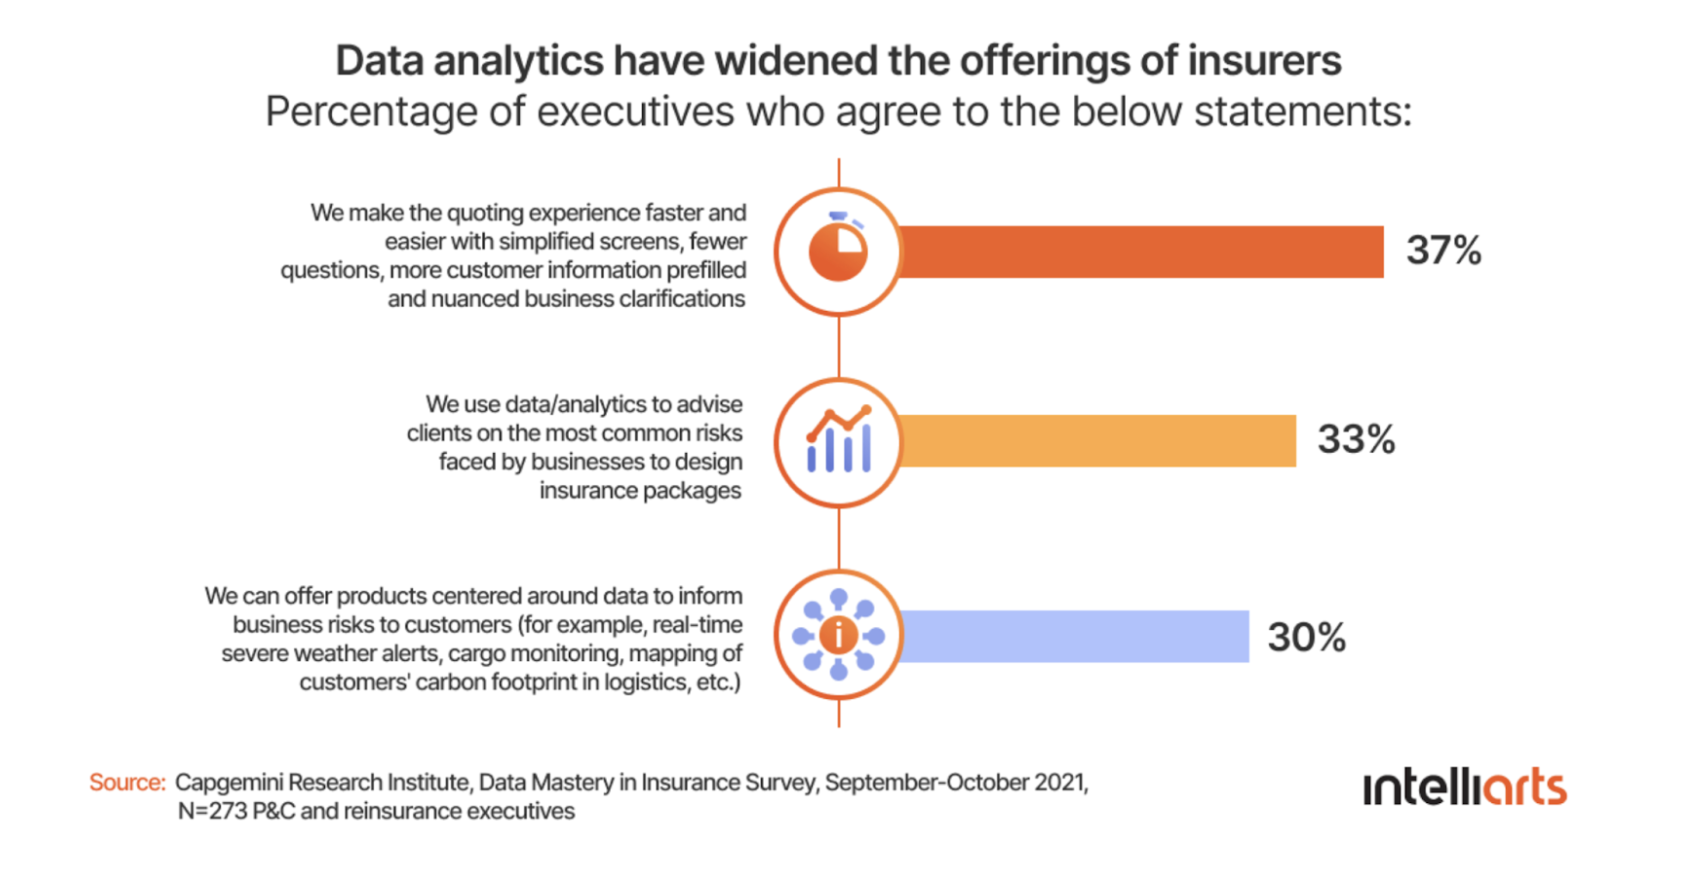
Data analytics have widened the offerings of insurers

By looking through data trends and patterns, insurance companies can predict customer needs and discover opportunities to improve service. Data can also be used to predict customer churn. This way, an insurer could provide a timely, appropriate action to prevent customers from leaving.

Real-life examples:

  • A U.S.-based insurance company, Prudential Finance, has started offering life insurance policies to HIV-positive customers after extensive data analysis found that they have a longer life span than previously known
  • AIA's life insurance business in China uses data analytics to personalize insurance coverage for their customers. Out of thousands of possible coverage combinations, customers receive an insurance offer that is the closest to their needs
  • A large U.S. insurer has analyzed available customer data, transaction data, and call-center interactions to develop new product offers. As a result, the company experienced a 40% increase in its retention rate.

New cross- and up-selling opportunities

Insurance data is also a substantial source of insights if the company seeks cross-selling and up-selling opportunities. With the aid of data science, an insurer can analyze customer behavior and track critical life events to target the customer with new types of policies and coverages that match the customer’s needs better.

The most illustrative example is the discount on bundled auto insurance when the company discovers that a policyholder’s child is near the driving age. Or the customer could receive an individual life insurance policy offer after the company discovers they have been exploring different options online. More advanced analytics, powered by machine learning, can even predict the likelihood of whether the customer accepts the offer.

Real-life examples:

  • AEGON Hungary had access to tons of raw customer data, which the company planned to use for cross-selling. The insurer used statistical analysis and modeling solutions to connect customer life events to their insurance needs. As soon as it started to send personalized offerings to customers, the insurer improved its response rate by 78% and sales by 3%.
  • John Hancock Financial, a life insurance company, has used an unusual data-driven approach to cross- and up-sell. The insurer offers a discount on new premiums based on how their customers are reducing their unhealthy and risky behaviors.

Claims optimization and fraud prevention

Combined with a machine learning model, data analytics allows insurers to handle claims faster and more accurately. Most importantly, it can help categorize risks and predict fraud likelihood in real time.

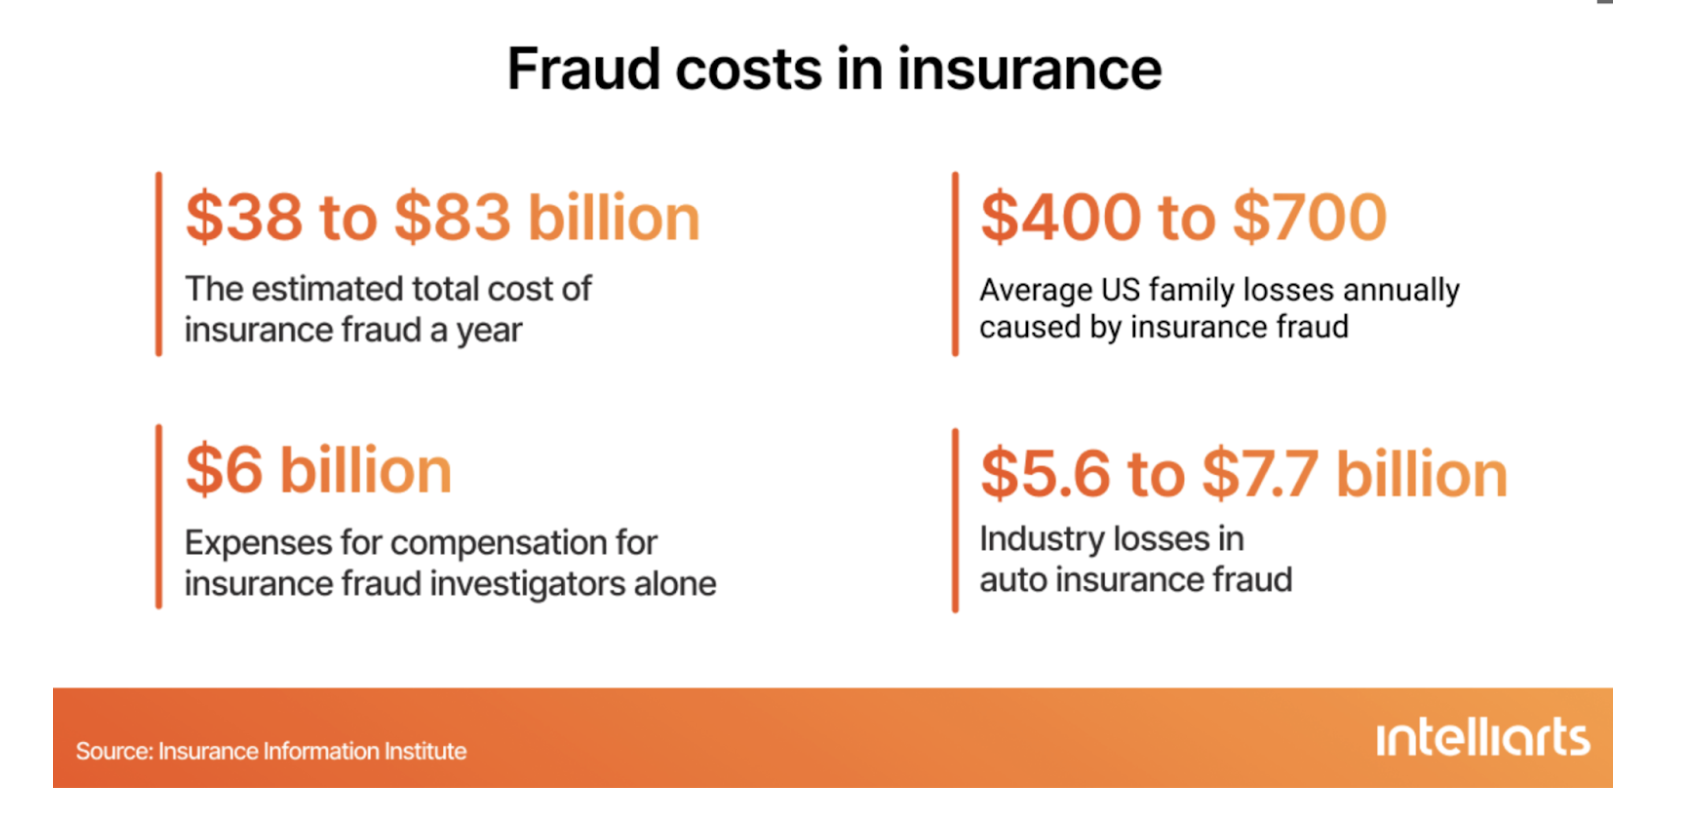
Fraud costs in insurance

Built based on historical data, an ML-powered model can analyze data patterns to seek these trends in new claims. If any suspicious trend is noticed, the company will know immediately and inform investigators. The insurer can also use alternative data sources, such as geospatial data or social media. For example, geospatial data could be useful to check whether the policyholder is honest about accident details.

Real-life examples:

  • After Santam Insurance deployed a predictive analytics solution for fraud detection, the company managed to save $2.5 million in payouts to fraudsters and almost $5 million in total repudiation.
  • ZhongAn Technology, a Chinese insurance company, uses image recognition to mitigate claims fraud. Users are asked to upload a photo of their cracked phone screen, for example. ML-driven technology then helps the company decide whether the actual damage took place and allows automated claim processing.
  • Allianz Insurance reports saving up to $4.5 million a year thanks to reducing fraud via data analytics.
  • Poste Assicura, an Italian insurance company, estimates savings of 5% to 10% of claims since it introduced insurance data analytics to its fraud detection.
  • Insurtech company Lemonade is using machine learning to compare claims against each other and detect fraud. More complex cases are transferred to an insurance investigator. The simpler ones are solved in a few seconds.

See also: Data-Driven Transformation

Improvements in insurance underwriting

Historically, underwriting was associated with a document-rich assessment process, which undermined any effort at automation. However, data and analytics have changed this approach, bringing automated data extraction, business intelligence, and predictive modeling to insurance underwriting.

In intelligent underwriting, insurers are able to prioritize submissions for quoting and start from the most valuable ones. In those sectors where the workload is the highest, such as in life insurance, carriers can decline the least profitable submissions at once and improve turnaround times.

Insurance industry forecast by 2030

Insurance data can increase the accuracy of risk assessments. An insurance company would have access to more data sources to analyze the customer’s risk profile, such as credit agencies, social media, and third-party vendors. If, for example, it’s learned that the customer was involved in rough driving, they will receive a higher premium.

Real-life examples:

  • A Scandinavian insurance company, Tryg A/S, used data analytics to check the effectiveness of its risk parameters. In 2021, the company discovered that 0.6% of its quotes needed reassessment because of risky behavior by those customers. Tryg A/S increased renewal prices for them.

  • AIA Life Malaysia reduced its underwriting submission process to less than an hour by introducing a set of specific, profile-based questions on the digital platform.
  • U.S.-based Allstate insurance company relies on telematics to collect and analyze mobility and driver data. The insurer then derives behavioral insights and optimizes premiums for auto insurance.

See also: 6 Steps for Cultivating a Data Culture

What should I do to unleash the power of my insurance data?

If you agree it’s the right time to use the data for the benefit of your organization, here are some recommendations on where to start:

  • Invest in data analytics and big data: You won’t be able to get the advantage of your insurance data unless you put in order your data sources, data collection process, data preparation, and so on.
  • Use machine learning: There are many use cases for ML in insurance, but the main idea is to build algorithms that will automatically process your insurance data, find patterns behind them, and help you improve decision-making.
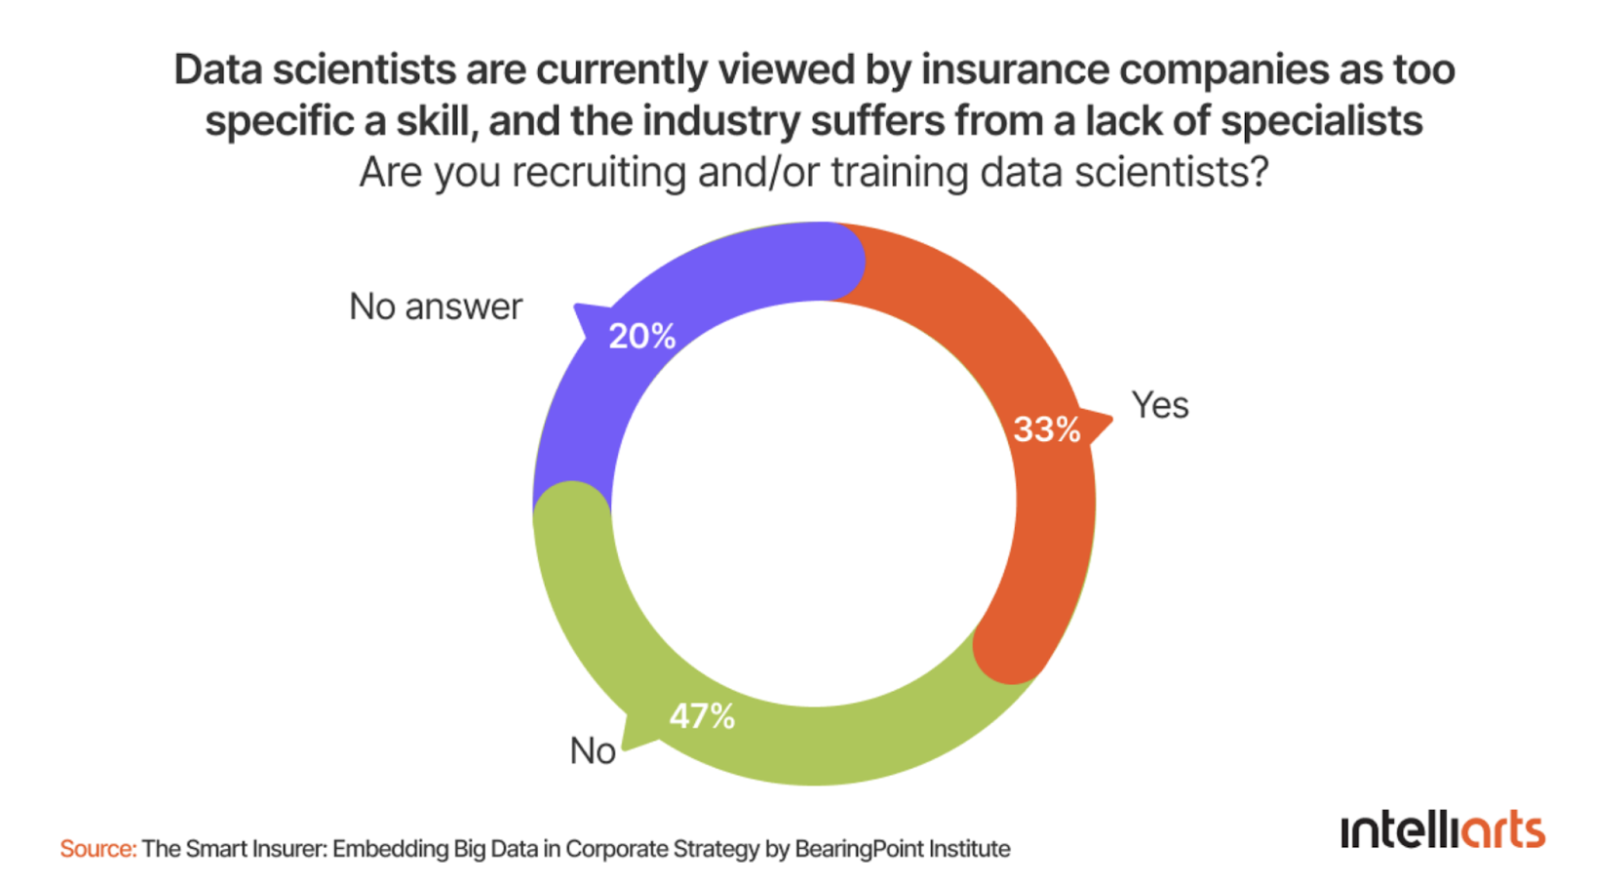
  • Build data expertise: At least half of insurance companies report the lack of data specialists in their organization, even though creating value from data is hardly possible without having one on your team. A good data scientist is worth their weight in gold; they don’t only have important technical skills but domain knowledge, too. A talented data scientist will see the broader picture of your business strategy and advise on how to solve your challenge with the help of data.
Embedding big data in corporate strategy
  • Go paperless with OCR: Automatic data extraction is the first thing you should think of when improving your business processes in insurance. ML-based optical character recognition (OCR) reduces any manual entry and searches for sources and accelerates the insurer’s work.
  • Pay attention to ethics and governance: Whenever data is involved, the issue of data governance, including data leakage and data privacy, becomes urgent. That’s why you should think about your company’s reputation and build customer trust and loyalty. Aside from committing to the principles of ethics and governance, try to walk the talk on ethics and be transparent with your customers when it comes to the use of data.

Wrap up

Having access to a large volume of insurance data is one thing. Being able to unlock the power of this data is something entirely different. 

In the process of unlocking, the insurer can meet a range of challenges: from more global ones, such as how to introduce data analytics into your business strategy, to trivial ones, such as building data pipelines and machine learning models.

As a result of these efforts, the insurance businesses might get valuable insights: from powering up the company’s decision-making to handling claims most efficiently, optimizing premium rates, and much more.

Insurtech Profits? Maybe Next Year

Let's take a look at the latest financials of the full-tech insurtechs, the (not too) new kids on the block.

 Person Holding Paper with White and Blue charts

As full-stack insurtechs keep aiming at profitability, let’s take a look at the latest financials of the (not too) new kids on the block.

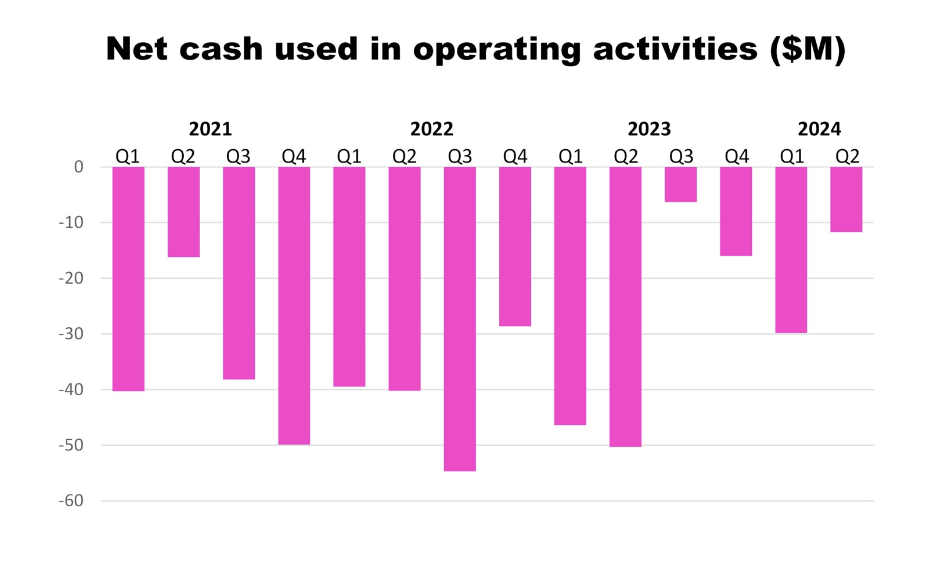
Lemonade – our undefeated master of storytelling – opened their shareholder letter with a triumphalist, “we were net cash flow (“NCF”) positive,” while their operations are still burning millions of dollars each quarter.

Net cash used in operating activities

They have definitely improved - as noted in the December edition of this newsletter - but they are still burning a lot of cash.

See also: Auto Insurance: Perennially Predictably Profitable

We are talking about a grown company (nine years old) with almost 2.2 million customers and expected in-force premiums at almost $1 billion by the end of this year. In their shareholder letters, the reference to “improvement” is everywhere:

  • 14 times related to Q2 ’23,
  • 23 on Q4 ’23,
  • 12 on Q1 ’24,
  • 18 on Q2 ’24.

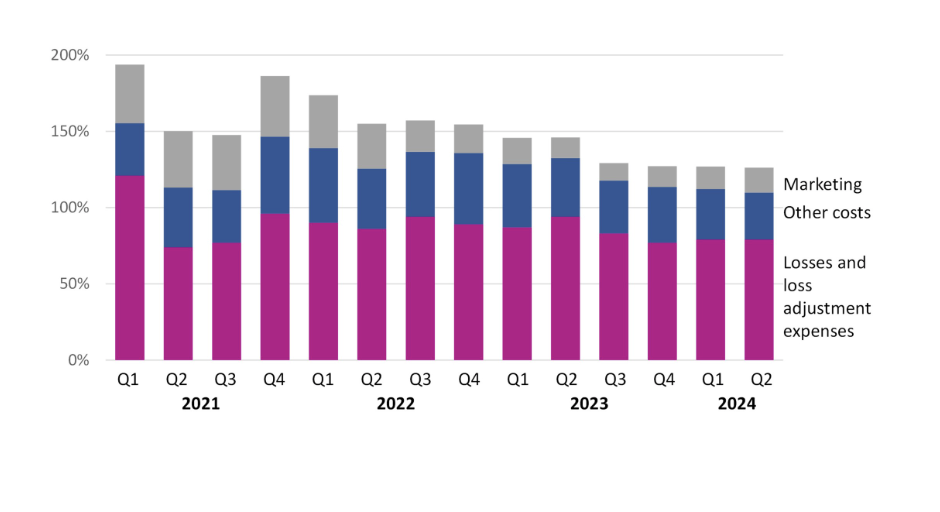
Yet their gross combined ratio has stayed just a few points below 130% for these past four quarters. They have lost $104.5 million in this first half of '24 (compared with the $133 million loss in H1 '23), bringing the cumulated losses to $1.2 billion.
 

chart #2

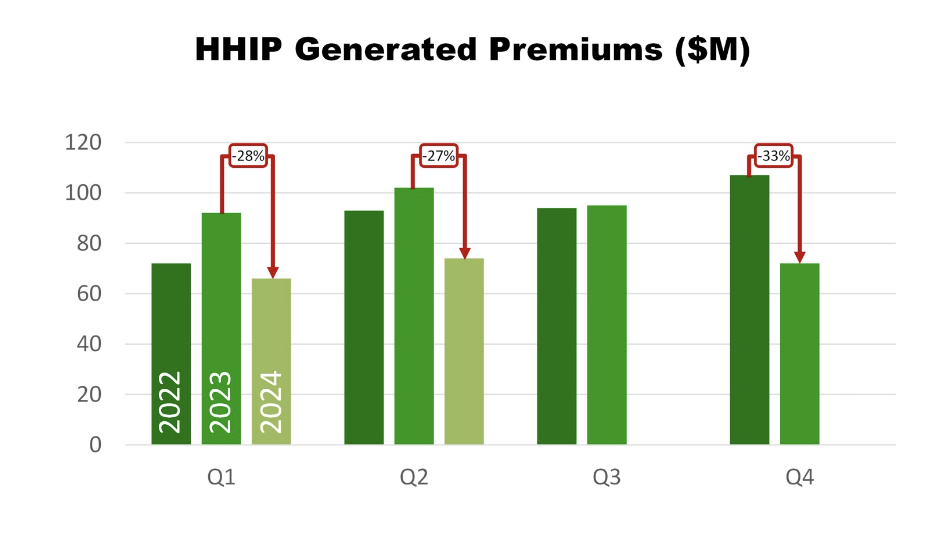
Hippo lost $70 million in the first half of ‘24 (compared with $173 million in H1 ‘23), and the operating activities generated $7 million (compared with -$45 million in H1 ’23). Hippo has continued its turnaround by pruning its original homeowner business in this first half of the year. This segment of the business ("Hippo Home Insurance Program - HHIP" in their letters) has shrunk its top line by almost 30% compared with the same quarter of the previous year, while starting to reduce its loss ratio. The original Hippo homeowner portfolio is still a loss-making business.

HHIP Generated Premiums

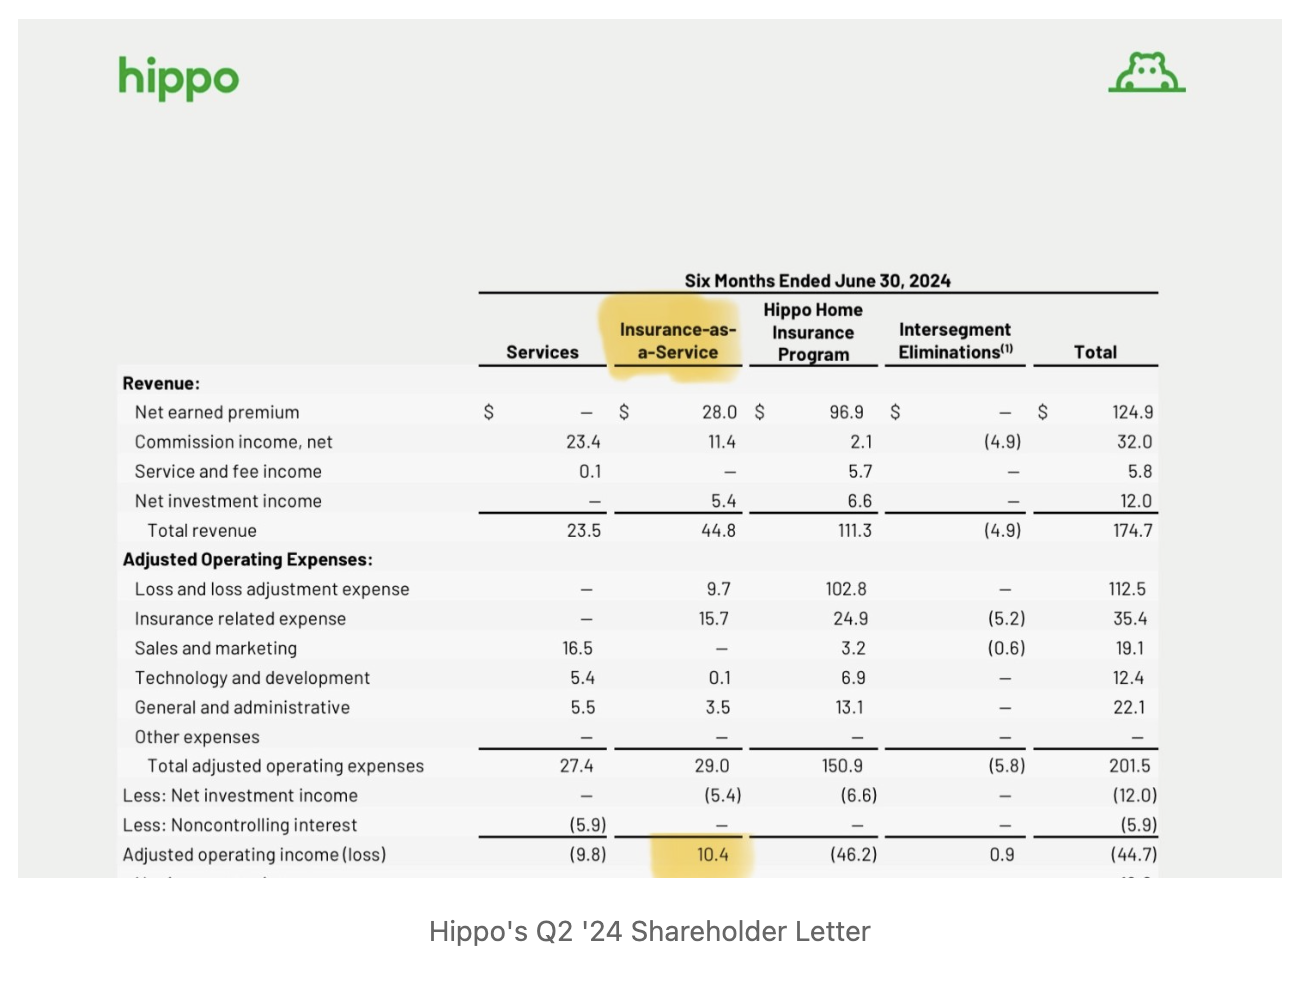
The only segment consistently generating profits is the business of giving underwriting capacity to MGAs (presented as “insurance-as-a-service” in their shareholder letter). This further confirms that the acquisition of Spinnaker in 2020 has been the best management decision in the history of this venture.

Hippo's Q2 '24 Shareholder Letter

Root lost $14 million in the first six months of 2024 (compared with $78 million lost in H1 ‘23), bringing their accumulated losses to $1.73 billion over the life of this venture. Their operations generated $77 million of cash (compared with -94 million in H1 ’23).

See also: How AI Can Keep P&C Insurers Profitable

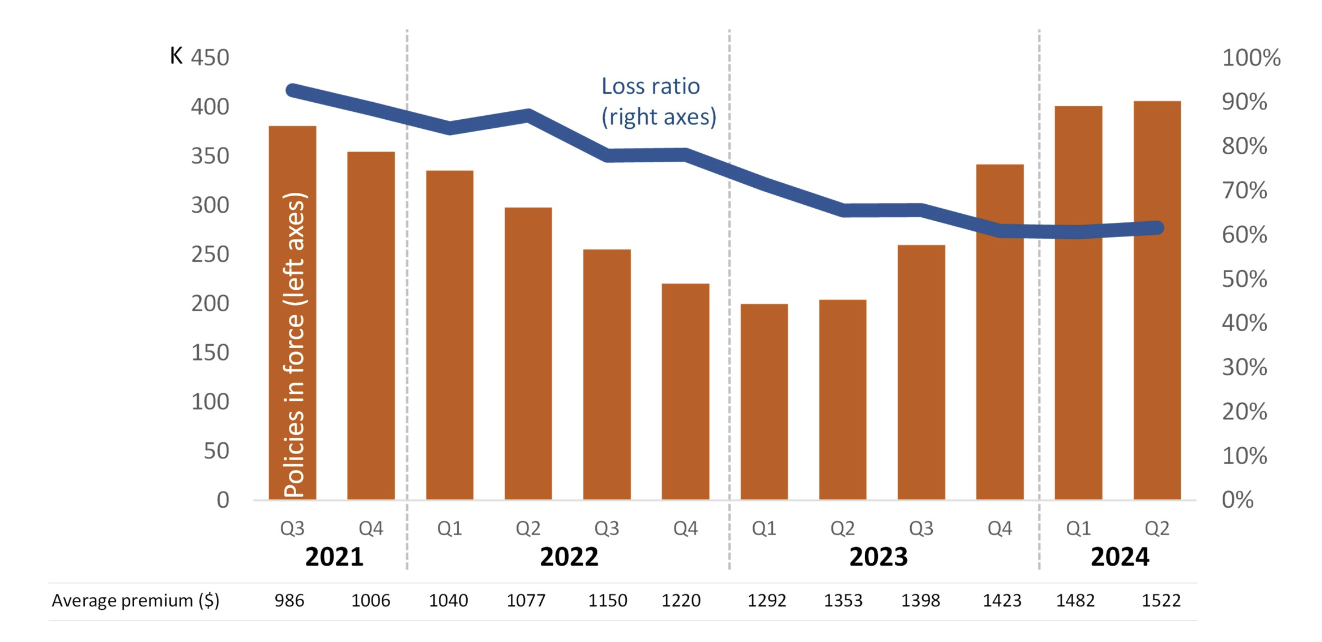
Root had a strong focus and excellent results in U-turning their auto portfolio since the end of 2021:

chart #4

In the last quarter, Root showed only a 1% growth of the customer base and an increase of 3% of the average premiums, with a slight increase of 100 basis points in the loss ratio. The next six to 12 months will tell us more about the “superiority in matching price to risk” claimed in their last shareholder letter.

Maybe next year.

Removing Pain Points for Life Insurance Actuaries

New product technology are addressing the traditional pain points of data analysis, model development, and risk assessment for life insurance actuaries.

White and Blue Butterflies Illustration with text: AI

For decades, life insurance companies have relied on the expertise of actuaries—professionals who analyze risk and uncertainty using mathematical and statistical methods—to design and price their products. However, the traditional methods used by actuaries are being transformed by advancements in product technology and artificial intelligence (AI). These innovations are not only alleviating long-standing pain points for actuaries but also driving product innovation in the U.S. life insurance industry.

The Traditional Role of Actuaries and Their Pain Points

One of the primary pain points for actuaries is the complexity of data analysis. Actuaries must sift through enormous datasets, often using outdated tools and methodologies. This process can be time-consuming and prone to errors, leading to inefficiencies and potential inaccuracies in risk assessment.

Actuaries also must continually update their models to reflect new data, regulatory changes, and emerging risks. This requires a deep understanding of both the technical aspects of actuarial science and the broader economic and social factors that affect the life insurance industry.

Moreover, actuaries face pressure to innovate and create products that meet the evolving needs of consumers. Traditional life insurance products, such as term and whole life policies, are increasingly being supplemented by more complex offerings, such as universal life insurance and annuities. Designing these products requires actuaries to balance the need for innovation with the demands of rigorous risk management.

See also: How Life Insurers Can Leverage Generative AI

How Product Technology Alleviates Actuarial Pain Points

Advancements in product technology are playing a crucial role in addressing the challenges faced by actuaries. These technologies are helping to streamline data analysis, improve the accuracy of risk assessments, and enable the creation of more innovative insurance products. 

One of the most significant developments in product technology is the use of advanced data analytics platforms. These platforms allow actuaries to process and analyze large datasets more efficiently and accurately than ever before. By leveraging cloud computing and big data technologies, actuaries can access real-time data and perform complex analyses in a fraction of the time it would take using traditional methods. This not only reduces the risk of errors but also frees actuaries to focus on higher-value tasks, such as product innovation and strategic decision-making.

Another critical innovation is the development of sophisticated modeling tools. These tools enable actuaries to create more accurate and dynamic models that can better reflect the complexities of modern life insurance products. For example, scenario-based modeling allows actuaries to simulate a wide range of potential outcomes, helping them to better understand the risks associated with different product designs and pricing strategies. This leads to more informed decision-making and ultimately results in more competitive and consumer-friendly insurance products.

Product technology is also facilitating greater collaboration between actuaries and other stakeholders within life insurance companies. With the advent of integrated software platforms, actuaries can now work more closely with underwriters, product managers, claims examiners and data scientists to develop and refine insurance products. This collaborative approach not only enhances the quality of the products being offered but also accelerates the product development process, allowing insurers to bring new products to market more quickly.

The Impact of Artificial Intelligence on Actuarial Work

While product technology is helping to address many of the traditional pain points faced by actuaries, AI has the potential to fundamentally change how actuaries approach their work, offering new opportunities for innovation and efficiency.

One of the most significant impacts of AI on actuarial work is the ability to automate routine tasks. Machine learning algorithms can be trained to perform many of the repetitive tasks that actuaries currently spend much of their time on, such as data cleaning, preliminary analysis, and report generation. By automating these tasks, AI allows actuaries to focus on more strategic and creative aspects of their work, such as developing product ideas and exploring innovative risk management strategies.

AI is also enhancing the accuracy and predictive power of actuarial models. Traditional actuarial models are often based on a relatively small set of variables and assumptions, which can limit their ability to accurately predict outcomes. AI-driven models, on the other hand, can incorporate a much larger and more diverse set of data inputs, including non-traditional data sources such as social media activity, wearable device data, and even genomic information. This allows for more precise risk assessments and better-informed pricing decisions, ultimately leading to more tailored and competitive insurance products.

Furthermore, AI is enabling actuaries to develop more personalized insurance products. By analyzing vast amounts of data on individual policyholders, AI can help actuaries to identify patterns and trends that might not be apparent using traditional methods. This allows insurers to offer products that are better suited to the specific needs and preferences of individual customers, leading to higher customer satisfaction and loyalty.

See also: Using AI to Better Manage Closed Blocks 

Driving Product Innovation in Life Insurance

The combination of product technology and AI is not only resolving pain points for actuaries but also driving significant innovation in the life insurance industry. As actuaries become more adept at using these tools, they are able to design and price a new generation of insurance products that are more flexible, personalized, and responsive to the needs of consumers.

For example, the rise of insurtech companies—startups that leverage technology to disrupt the traditional insurance industry—has led to the development of product offerings such as on-demand life insurance, usage-based insurance, and microinsurance. These products are often powered by AI-driven underwriting processes, which allow for faster and more accurate assessments of risk. This, in turn, enables insurers to offer more competitive pricing and more convenient customer experiences.

In addition to new product types, AI and product technology are also enabling insurers to offer more dynamic and adaptable policies. For instance, some life insurance companies are now offering policies that can be adjusted based on changes in a policyholder's health, lifestyle, or financial situation. These "living policies" are made possible by continuous data monitoring and AI-driven analysis, allowing for real-time adjustments to coverage and pricing.

Conclusion

The integration of product technology and AI into the life insurance industry is transforming the role of actuaries and driving significant product innovation. By addressing the traditional pain points of data analysis, model development, and risk assessment, these technologies are enabling actuaries to work more efficiently and effectively. Moreover, the power of AI is opening up possibilities for personalized and dynamic insurance products that better meet the needs of modern consumers. 

As the life insurance industry continues to evolve, the role of actuaries will undoubtedly continue to change. However, one thing is clear: The combination of product technology and AI will be at the forefront, helping actuaries to not only solve the challenges of today but also to shape the future of life insurance for generations to come.


Neeraj Kaushik

Profile picture for user NeerajKaushik

Neeraj Kaushik

Neeraj Kaushik, principal consultant, is a product manager for the NGIN platform initiative at Infosys McCamish Systems. 

He is a published author and Top Insurtech voice on LinkedIn. Kaushik has driven large-scale technology projects based out of the U.S., U.K., India and China for the last 18-plus years. He has led strategic consulting and transformation initiatives across life, annuities and property & casualty.

He was previously part of Big 4 consulting firms such as PwC & Deloitte.

Leveraging Cloud Technology in Telehealth

Operating in the cloud, data engineering and analytics drive efficient, personalized services while enhancing patient outcomes.

Down Angle Photography of Red Clouds and Blue Sky

By enabling remote patient monitoring and virtual consultations, telehealth has brought healthcare to the doorsteps of patients. Underpinning this revolution are data engineering and analytics, playing a pivotal role in driving efficient, personalized services while enhancing patient outcomes.

Role of Data Engineering in Telehealth

Data engineering is the backbone of telehealth services. It involves collecting, validating, storing, protecting, and processing required data to be accessible and informative. Data engineers develop and maintain systems to ensure that the massive amounts of data generated in healthcare are systematically processed and ready for analysis. Telehealth involves various data types like electronic health records, real-time physique data, and even video consultations data. A robust data engineering framework ensures smooth management and processing of these diverse datasets.

Analytics: Empowering Decision Making in Telehealth

Once data engineering lays the groundwork, analytics steps in to drive insights from the data. It involves the discovery, interpretation, and communication of meaningful patterns in data. Descriptive analytics help with understanding the current healthcare conditions, while predictive analytics anticipate healthcare outcomes based on patterns gleaned from historical and real-time data. Prescriptive analytics goes a step further to provide recommended actions to achieve desired health outcomes.

Through the use of sophisticated techniques and algorithms, healthcare providers can leverage these insights for patient diagnosis, treatment planning, risk prediction, and cost-effectiveness. For instance, predictive analytics can forecast trends and outcomes, such as risks of specific diseases, aiding in preventive care.

Impact of Data Engineering and Analytics on Telehealth

  1. Personalized Care: With the insights provided by data analytics, healthcare providers can offer tailor-made treatment plans to their patients, enhancing patient satisfaction and outcomes.
  2. Improving Access: Telehealth, powered by robust data engineering and analytics, extends the reach of healthcare services, allowing providers to reach underserved communities and cater to the aging population in the comfort of their homes.
  3. Cost Savings: Optimized prediction models and analytical reports can guide effective resource allocation, reducing operational costs and helping providers deliver quality care economically.
  4. Efficient Service Delivery: Real-time analytics can help in the immediate detection of critical health conditions, enabling immediate intervention and thereby improving treatment results. Also, analytics helps healthcare providers promptly respond to changes in patient condition or behavior.

Data Sharing: Provider Enablement

Data sharing enhances the potential of telehealth, allowing for an improved healthcare experience for both the providers and the members. Here's how:

Enhanced Care Continuity: If providers within a network have access to the shared data, they can understand the medical history, current medications, and other crucial health-related information about a member. This ensures care continuity even when the member switches between different providers or needs to consult multiple specialists in person or through telehealth.

Improved Decision Making: Data sharing arms healthcare providers with the necessary insights to make evidence-based clinical decisions. Comprehensive knowledge of a member's medical history allows providers to accurately diagnose conditions, devise effective treatment plans, and predict potential health risks. This helps providers to prescribe the precise medicine even over telephone.

Coordination and Collaboration: Data sharing enables multi-disciplinary team collaboration in managing a member's health. Various providers caring for the same member, such as primary care physicians, specialists, nurses, and pharmacists, can access shared data to coordinate care effectively.

Efficiency and Convenience: In telehealth, providers can access shared data from anywhere, reducing the need for repetitive tests and, hence, enhancing administrative efficiency. For members, telehealth eliminates the inconvenience of repeated information sharing or undertaking the same tests.

Preventative Care: Predictive analytics can use shared data to identify early signs or risk factors of diseases, allowing for timely intervention and preventative care. Early prevention leads to better health outcomes for members and potentially reduces healthcare costs.

Trust and Transparency: When members know that their health data is being shared securely but with a purpose, the knowledge can promote a sense of trust between providers and members, leading to better engagement and adherence to treatment plans.

In essence, data sharing in telehealth signifies a move toward integrated, coordinated care, yielding improved health outcomes, cost efficiency, and member satisfaction. As we navigate the digital age, secure and effective data sharing protocols will be paramount to the evolution of telehealth services.

See also: How Cloud Tech Improves Customer Experiences

Role of Cloud Technology

The use of cloud technology has enabled greater capacities for data storage, processing, and analytics, making it crucial for the effective management of healthcare data. Here's how the cloud plays a significant role in data engineering in telehealth:

Scalable Storage: With the massive amounts of data being generated in telehealth, cloud technology offers scalable and cost-effective data storage solutions. Cloud storage can easily scale up or down based on the data volume, thereby efficiently managing storage needs.

Data Integration: Cloud platforms facilitate seamless integration of diverse health data from multiple sources, such as electronic health records (EHRs), wearable devices, and images. All relevant patient information can be consolidated in a single, accessible platform.

Real-Time Access and Collaboration: Cloud enables real-time access to data for healthcare providers, regardless of their location. This fosters collaboration among a patient's healthcare team, allowing them to provide coordinated care based on comprehensive, up-to-date information.

Data Security and Compliance: While data security is paramount in healthcare, cloud service providers offer advanced security features to protect sensitive health data. They also help ensure regulatory compliance, including adherence to rules set by the Health Insurance Portability and Accountability Act (HIPAA).

Advanced Analytics and AI: The cloud supports sophisticated data analytics tools and AI capabilities. These tools can process and analyze large sets of data, yielding insights that can guide clinical decisions and health predictions. They also support machine learning models that can identify critical health patterns and predict outcomes, enhancing telehealth services.

Speed and Efficiency: Cloud computing allows quick processing of large volumes of data, minimizing latency. This efficiency is critical in telehealth settings, where swift data access can affect health outcomes.

Reduced Costs: By using cloud-based solutions, telehealth services can avoid the high costs associated with maintaining physical servers and data centers.

Cloud technology plays an essential role in data engineering within telehealth, providing the infrastructure needed to collect, store, integrate, analyze, and securely access health data. As healthcare continues its digital transformation, the cloud will continue to deliver innovative, flexible, and secure solutions.

See also: Moving From Legacy Systems to the Cloud

Conclusion

Data engineering and analytics play an integral part in telehealth, turning vast amounts of data into actionable insights. They allow the efficient delivery of healthcare services, increase patient satisfaction, and cut costs. As telehealth continues to grow, advancements in data engineering and analytics will usher in a new era, promising improved outcomes for both healthcare providers and patients.


Mandhir

Profile picture for user Mandhir

Mandhir

Mandhir is a software development, senior engineering lead at Elevance Health.

He has two decades of experience specializing in software product development for healthcare, focusing on data science and analytics solution engineering, architectural design, data integration and reporting technologies.

The Challenges of Embedded Insurance

While merchants are excited about the possibilities of embedded insurance, insurers are feeling the pressure. 

Agent talking to elderly couple

In the never-ending pursuit of customer satisfaction, more merchants are finding they can delight customers by offering insurance right alongside products.

But while businesses are excited over the growth potential of embedded insurance, one industry is feeling the pressure: insurance. 

There are huge opportunities for insurers and insurtechs, but they must face these hurdles head-on:

HURDLES

1. Outdated UI/CX 

While the world is busy building modern apps, many insurers are still stuck with complex systems due to lack of resources and complicated regulations. Consumers will have a smooth user interface (UI) until they are redirected to the insurance part. Jargon-filled insurance policies and complex claim processes often turn off customers. 

Although insurers have started to improve, there’s still a lot to be done. Until then, you can use these strategies to improve the customer experience (CX):

  • Minimal Integration: Use the merchant’s platform to show basic policy information and claim status, but anything complex? Redirect to the insurer website.  
  • Dedicated Customer Support: Support customers to navigate the complex platform through email and chat. 
  • Third-Party Integration: Until you fully modernize, integration with third-party digital tools can help cross the UI/CX hurdle.

For example, consider a customer renting a car online. The process is quick and seamless, but when the insurance part hits, the experience often becomes fragmented. Your company can make a difference here by letting the rental company offer only basic insurance details online while you assist customers with complex claim processes. 

Insurers such as Geico and Lemonade have already started to improve their customer service with advanced support systems and third-party AI chatbots. You can use similar solutions to help your customers navigate through complex processes and enhance their experience.

2. Poor Communication With Merchants

When insurance products get bundled with the merchant's, ensuring a seamless customer experience is on insurers. You need to establish clear communication with the merchant to avoid misalignment while framing the terms and conditions for the product.

  • Merchant Support: For instance, Tesla is supporting its insurance provider State National Insurance by handling most of the insurance queries on Tesla’s platform.
  • Co-Branded Marketing: Market jointly to build brand awareness and trust.
  • Data-Sharing Agreements: Maintain customer insights by creating data-sharing agreements with the merchants. 

If you are a travel insurer, you can partner better with merchants like online booking platforms. Imagine a customer booking a flight and being presented with a personalized insurance offer that covers everything from trip cancellations to lost luggage, all without leaving the booking site. This not only enhances the customer experience but also increases the likelihood of a purchase.

You and the booking platform can also promote your products together. This makes the insurance offering an extension of the travel booking process, which can drive sales.

3. Data Privacy and Customer Knowledge

As embedded insurance involves data-sharing between merchant and insurer, it's the insurer’s responsibility to safeguard customer data and educate customers about the terms and conditions. Here’s how you can do it:

  • Regulatory Compliance: Adhere to data privacy regulations such as GDPR and CCPA.
  • Standard Privacy Policy: Provide clear privacy policies that outline data collection and usage practices.
  • Customer Education: Offer all the must-know information about the insurance products on the merchant’s platform.

As an insurer, you know that transparency and trust are crucial to customer satisfaction. Imagine the impact of a seamless integrated experience where a customer is provided with all the necessary data about the privacy policies and the risks associated with it while booking a flight ticket or getting employee-provided health insurance. 

This level of transparency not only builds customer loyalty but also strengthens your brand's reputation in an increasingly competitive market. You can enhance the customer experience by keeping them informed, protected, and engaged about how their data is being used by the insurer.

See also: Is Embedded Insurance the Wrong Idea?

NEW INSURANCE MODELS

The advent of connected devices such as wearable devices, IoT, and smart home devices opened a new era of possibilities for the insurance industry. New insurance models can attract users to move from the old way of paying annual premiums. Data generated through the connected devices further helps insurers cater to more specific and personalized products. 

1. On-Demand Insurance

This model will give the convenience of using insurance for your immediate needs and help avoid unnecessary costs for coverage you don't use. 

Uber, a ride-sharing service, offers its customers and drivers the option to purchase insurance coverage on-demand. This means that both parties can use insurance protection only during the ride. Uber leverages connected devices like GPS and telematics to accurately track their vehicles, ensuring that both riders and drivers are protected precisely when they need it.

2. Contextual Insurance

Ever thought about insurance that adapts to your real-time needs? Contextual insurance makes this a reality by providing coverage based on the context of the user’s activities. 

Imagine you’ve just installed a smart home system that can analyze data like occupancy patterns, appliance use, and even environmental conditions. This data offers a clearer picture of potential risks in your home, allowing your insurance coverage to adjust.

This approach ensures that you’re not paying for unnecessary coverage but are instead getting precisely it when you are in need.

Google Nest’s extended warranty is a prime example of contextual insurance. At the time of purchase, you’re offered a plan that not only covers accidental damage but also uses data from your thermostat to offer protection to your home. 

3. Pay-Per-Use Model

Why should consumers pay heavy premiums for products they use occasionally? The pay-per-use model offers the convenience of integrating insurance into existing services or products and the flexibility to use it only when it is needed.

Consider purchases of high-tech products. Merchants offer a standard warranty period for that product. If customers wish, they can opt for an extension only to some specific parts of the product, like extending the warranty period only for the motor of a washing machine.

See also: Beyond the Hype on Embedded Insurance

THE FIRST STEP

Customer experience is not just about keeping customers happy—it’s about acquiring and retaining them with minimal costs. 

That’s why many businesses are shifting toward embedded insurance. To stay in line, insurers are relentlessly working to overcome challenges and deliver personalized customer experiences. The emergence of new insurance models is a clear sign they are on the right track.

The future of insurance is undoubtedly embedded, and your current progress will benefit insurers, merchants, and, most importantly, your customers. 

Life Insurance Has a Social Problem

Six in 10 people now use social media when looking for information on insurance products. Here are suggestions on how to adapt.

Clear Drinking Glass Filled With Water

Half of Americans have life insurance; half do not. Is this a glass half full? Or a glass half empty?

The truth is: It doesn’t matter. We are here to help everyone who needs life insurance get coverage. But how do we move the needle? The answer is social media. But let me back up a bit. 

First, we have to be laser-focused on addressing the reasons people tell us they are not buying life insurance, or more of it. That seems logical, but many companies bypass that step for marketing strategies rooted in complex internal politics. 

Why People Don’t Buy

So, why are people not buying coverage? The 2024 Insurance Barometer Study, which the nonprofit Life Happens does in conjunction with LIMRA, delves into just this. I’ve worked on the study since its inception 14 years ago, and the reasons people have for not buying life insurance have stayed consistent.

  • People think it’s too expensive. 
  • They say they have other financial priorities.
  • They are not sure how much or what type to buy. 

Let’s take the top reason.  People think life insurance is too expensive. But, according to the study, 72% overestimate the true cost. In fact, half the population think it’s two-and-a-half times as expensive than it is. How are they estimating what it would cost? More than half (54%) say they use either “gut instinct” or “a wild guess,” according to the study. 

Many admit they are not knowledgeable about life insurance (44%), and half of women say they are not (51%). Income is not a huge predictor of people being more confident about what they know: 41% of the middle market ($50K-$149K) and 39% of top income earners ($200K+) say they are not knowledgeable about life insurance.

Whatever their income level, people are not going to buy what they don’t understand and what they think they can’t afford. 

There is a key step that can’t be missed, and that’s to educate them about what life insurance does, about why it is important for them, and that there is a policy (or policies) that fits their needs—and budget. 

See also: Insurance Is Not a Commodity

The Importance of Social Media

The “how” of reaching people and educating them is becoming a very interesting subject. Increasingly, the focus is social media. We just released a supplement to the Barometer Study called “Reaching New Insurance Buyers,” which delves into social media usage in our industry.

This year, six in 10 people say they use social media sites when seeking information on financial or insurance products. In 2019, that figure was just two in 10.

I’ll let you sit with that information from a minute. 

Now, ask yourself: What is my company doing on social media to provide this educational information about the products we sell and then turn people into customers?

I can probably guess the answer: not enough.  

What’s happening with social media and our industry is a seismic shift. Over the years I’ve been doing the Barometer Study, I don’t remember any shift of this magnitude in such a short time.

To stay relevant, we need to pay attention to this shift whether we want to or not. Whether compliance wants us to do it or not. Whether our blinged-out traditional advertising campaign wants us to or not. Being set up for success means being on social media to educate and help consumers feel confident purchasing the solutions your company has.

There are a number of companies that are 100% homed in on social media, have advanced strategies, are working with influencers, and are advertising on social as well as growing their organic following. These are the folks that are going to eat your lunch. 

See also: Revolutionizing Life Insurance Uptake in Younger Markets

How can you start or make some significant steps to enhance your social media? Here are some suggestions:

Make internal changes—even if they are incremental. Educate compliance. Having to follow compliance rules is no longer an excuse. How do we know? Just look at your peer companies that are doing social media well. They are working within the same legal framework you are.

Don’t keep social siloed. One of the most perplexing things I see is huge companies with one, maybe two people working on social media, but off in a dank, dark corner. I exaggerate, but not by much. The social team should be 100% integrated into your marketing strategy and team—it should be so enmeshed that you don’t make a move without questioning: How do we integrate social with this? 

Just start and then be consistent. Making mistakes is fine—we all do. The beauty of social media is that it is fast-moving, and you can course-correct easily. It may take time to build a following, but as you can see from the Barometer numbers, things can also move with lightning speed. 

Stop doing what doesn’t work. One of the biggest mistakes I see is using corporate social media for “vanity” postings. We all know what this is. Stop it. 

Know that great educational content wins the day. At Life Happens, we’ve been doing social media for more than 15 years and know what works (and what doesn’t). We rely heavily on statistics to inform our content strategy. For example, stats showed that we had 153 times more organic engagement on Life Happens’ Facebook than the average of the biggest life insurers. Our Instagram also outpaces what companies are doing. 

Celebrate success and communicate it. Remember that you have internal audiences that you will have to convert. Be the champion of your social media, articulate your wins well internally, and win ever-increasing budget to support that success.

Honestly, we as an industry make social media more complicated than it is. 

Educate consumers about the products that can help them build a strong financial foundation, and then show them solutions they can afford. Do this where consumers spend time—on social media—and in a way that is engaging (think the opposite of what compliance would have you do or say). The key is to effectuate change internally to help you reach that goal. Good luck!

Sorry, but I Don’t Know Who You Are

Four lessons for a better life in a world of confusing communications.

Silhouette of Electric Posts Under Red Sky

Fifteen years ago, I was working for a company with offices in California, New York, and London. I was at a conference in the U.S. My wife was back in London, with our three young children while overseeing the renovations of our 300-year-old house.  

While I was away, the kitchen ceiling collapsed, bringing down with it an old water tank and soaking everything in dirty water. The au pair quit the same day. I hadn’t been in touch for 48 hours. My wife didn’t even know where I was staying. 

So she sent an email to Matthew Grant – expressing some frustration that I hadn’t called and needing sympathy for the troubles at home. An hour or so later, she received a response:

“I’m sorry but I don’t know who you are.”

She saw red. 

How dare I pretend not to know her because I was at work and she was having a hard time? She shot back a response:

“You B@st@rd, how dare you ignore me just because I’m having bad day. Who do you think you are?” 

A few minutes later, she got a reply

“No, I really don’t know who you are. I am not your husband. But I do hope you sort out your troubles.”

She looked at the email address she had used. She had indeed sent her original email to Matthew Grant at Hotmail. Just not to the right Hotmail address. 

We laugh about it now, but we both learned something about communication that day.

See also: Life Insurers' Communication Problem

Don’t be a stranger…

I was reminded of the comment, “I don’t know who you are,” when looking this week at the backlog of all the people who have asked to connect to me on LinkedIn. 

I have a something of a love/hate relationship with LinkedIn. 

We use it a lot at InsTech for sharing information about what we are doing and what our clients and members are up to. It’s a great way to share longer-form articles, event information, and links to our podcast episodes.

But none of us can control what the LinkedIn algorithm does with its content. Despite being selective about whom I open up my network to, I still get too much irrelevant information in my feed. And I get a lot of strangers asking to connect. 

LinkedIn favors people from our connections when it shows us content, so one way to manage the quality of what we see is being thoughtful about whom we agree to connect with. 

I also still believe in the original concept of LinkedIn, that connections are people in your network whom you know and whom you have a connection with in the real world outside of the platform. 

I realize this may be more of a personal pet peeve, but I suspect I am not alone. Some people value the quantity of their connections on LinkedIn in the same way others value the size of their bank accounts. I’m not judging that approach if it works for you. For me, personally, I have a bias toward the quality of my connections.  

I tend to get four types of people asking to connect. You probably do, too:

Type One – People I know. A pleasure to be connected, thank you.  

Type Two – People I don’t know but who send a message explaining why they want to connect. I almost always respond to those and accept. 

Type Three – People from companies that are already clients or who are likely to be buyers or users of our services, or the services of  our clients and members. If you work for an insurer or a large technology company, or are an existing client, or perspective client, we need more people like you in our network. Thank you. 

Type Four – People I don’t know and whose employers I don’t know. These people offer no message or explanation about why they want to contact. If I don’t know you, how do I know how I can I help you, or what I have I done that brought you to me? Sorry, but that will be a “decline.”

See also: 3 Steps for Insurers to Keep the Human Touch

Managing the communication overload

We are overwhelmed with the need to communicate today. Sometimes we spend too much time in “receive” mode and neglect the effort we spend in “transmit” mode. We respond to what is present, not what is important. We can write quickly, but we suffer regret slowly. 

Can I offer some advice that might help make sure you are not the stranger and may reduce the likelihood of a small communication catastrophe?

Lesson One: Double check the email address before you send. 

It’s too easy to send an email to the wrong person. I suspect you have done it more than once. I have. Most email tools use text prediction to complete the email address you start with. There are lots of Matthews out there. Are you sure you have the right one?

Lesson Two: Never say anything in an email you write that you wouldn’t want the person you are writing about to read. 

Assume that any email you write about someone will be sent to that person. Because that will happen one day. It’s Murphy’s Law. If something can go wrong, it will. Harsh words said in haste can’t be taken back, and they are really hard to recover from.

Lesson Three: Who are you? Introduce yourself when requesting a connection on LinkedIn. 

If you want to get someone’s attention on LinkedIn, take the time to say hello and introduce yourself. Tell them what they have done that has caught your attention. Don’t make the first contact be a pitch to sell something. 

Lesson Four:  If you travel and have someone waiting at home, check in every single day. 

A phone call is best. Otherwise a text, WhatsApp, or email at least shows you remember them. It’s not every day something troubling happens, but each day does have something worth sharing, the good and the bad. These are the small parts of our day that may be forgotten or seem not important 24 hours later but which form the broader tapestry of how we experience our lives. That daily contact is part of the vital glue that holds us together. 

I am still married to Mrs Grant. Occasionally, the other Matthew Grant does still get emails. I’m assured the offer to book flights to go on holiday in Bermuda that he received was entirely accidental.

Four suggestions. Take them or leave them. If you have read this far, then this is one communication that has succeeded. That’s good enough for me.


Matthew Grant

Profile picture for user MatthewGrant

Matthew Grant

Matthew Grant is the CEO of Instech, which publishes reports, newsletters, podcasts and articles and hosts weekly events to support leading providers of innovative technology in and around insurance. 

Building Trust in Insurance with Technology

Learn how automated trust solutions improve customer loyalty and make insurance companies work better.

Technology and human hand touching

How Digital Trust Strengthens Customer Loyalty

In today’s fast-paced world, insurance companies face the challenge of balancing customer trust with quick service. Technology allows quick decisions and real-time service but also makes customers more impatient and demanding. Insurance carriers must meet these needs while being careful, especially to prevent fraud.

Good processes help maintain customer trust. But trust can also slow down services. This blog looks at whether customer interest and care can work together. 

The Shift from Distrust to Trust Automation

In the past, carriers unfortunately had little options than to operate based on distrust, focusing on controlling damage. There are many rules to manage risks and avoid losses. Now, the industry is moving towards each customer’s experience. Modern carriers want to build personal relationships. They use technology to meet each customer's needs. The market is less about groups and statistics and more about serving one unique person well.

Trust. Automated. A Solution for Modern Challenges

Automating trust processes helps carriers manage lots of interactions smoothly. If you can automate who to trust based on real-time data, carriers can act quickly and focus on high-risk cases, while speeding up low-risk ones. By using advanced analytics and machine learning, the platform spots patterns and odd behaviors. 

Key Parts of Trust Automation

  1. Primary Verification: Checking personal details, income, and more to ensure accuracy. This step ensures that the information provided by customers is correct, which builds a foundation of trust.
  2. Text Mining and Anomaly Detection: Analyzing large amounts of data to find unusual patterns and potential fraud. This helps in identifying risks early and avoiding potential losses.
  3. Social Network and Voice Analysis: Mapping social links and analyzing voice signals to judge trustworthiness. Understanding relationships and how people communicate helps in assessing risk more accurately.

Benefits of Trust Automation

Automating trust brings significant benefits for both customers and carriers. 

Customers value quick and efficient service. With trust automation, carriers can offer expedited claims processing for trustworthy clients. This reduces wait times and improves customer satisfaction. Happy customers are more likely to remain loyal, refer others, and even purchase additional policies.

For carriers, the benefits extend beyond customer satisfaction. Trust automation streamlines operations by handling large volumes of data and interactions consistently. Carriers can standardize verification processes, ensuring that all customers are treated fairly. This consistency builds trust and helps in maintaining a positive reputation.

Detecting and Preventing Fraud

As data grows, systems get more complex. This affects decision-making speed and makes fraud harder to spot. Trust automation helps normalize and standardize many processes. It lets skilled staff check exceptions when needed. Examples include:

  • Text Mining: Analyzing large amounts of text for patterns and tendencies. This involves scanning through documents, emails, and other text data to find inconsistencies or red flags.
  • Anomaly Detection: Identifying items or events that don’t fit expected patterns. This could be unusual claim amounts or irregular policyholder behavior.
  • Social Network Analysis: Mapping social structures to find hidden connections. This technique helps in identifying relationships that may not be apparent but could indicate collusion or fraud.
  • Voice Analysis: Using voice analysis to catch signals of someone’s state of mind. Voice patterns can reveal stress or dishonesty, providing additional clues during claims processing.
  • Financial Risk Analysis: Charting the financial risk of a company or person using public info. This step helps in assessing the overall risk profile based on financial stability and history.

Conclusion

Fraud prevention and customer trust can work together. By using technology to automate trust, carriers meet modern customer needs while maintaining care. Trust automation boosts customer loyalty and makes operations efficient. It is a valuable tool for the insurance industry. As the insurance world changes, carriers must use new solutions like trust automation to stay competitive. Building trust through technology helps carriers create lasting customer relationships and ensure long-term success. 

In summary, trust automation is not just about preventing fraud; it's about creating a more efficient and customer-centric insurance experience. Technology is reshaping the industry, and those who embrace these changes will lead the way in customer satisfaction and operational excellence.


Sponsored by ITL Partner: FRISS


ITL Partner: FRISS

Profile picture for user FRISSpartner

ITL Partner: FRISS

FRISS is the leading provider of Trust Automation for P&C insurers. Real-time, data-driven scores and insights prevent fraud and give instant confidence and understanding of the inherent risks of all customers and interactions.   

Based on next generation technology, the Trust Automation Platform allows you to confidently manage trust throughout the insurance value chain – from the first quote all the way through claims and investigations when needed.   

Thanks to FRISS, trust is normalized throughout the organization, enabling consistent processes to flag high risks in real time.

A Paradigm Shift for Agents and Brokers

"Automation has taken such a big leap forward that it’s freeing agents to focus on their clients and provide more thoughtful, more personalized interactions and focus on higher-value activities."

chase interview

Paul Carroll

From your perspective, how is the role of agents changing?

Chase Tarkenton

We're seeing a paradigm shift with the onset of AI. Automation has taken such a big leap forward that it’s freeing agents to focus on their clients and provide more thoughtful, more personalized interactions and focus on higher-value activities. The agent can provide a better experience, which is ultimately what the consumer is looking for.

For years, technology has been integral to supporting agents, but a lot of new use cases are coming up every month, where you can trust that the technology will execute and do so at scale and in a compliant fashion. It's really exciting to see.

Paul Carroll

If I'm an agent, how might my day look different now?

Chase Tarkenton

Automation is a big topic, so it can touch lots of different areas of the agent workflow.

With the onset of self-service, more and more customers are coming in already educated on different insurance policies. Now, when an agent is interacting with those clients, some of those conversations have already started, and maybe the agent has been provided a summary of how the customer has been interacting with the organization and what their situation is. By the time the agent speaks with someone, whether it's over the phone, over email, or through digital channels, the agent already has context, and they can pick up the discussion midstream.

At the end of the interactions, the paperwork that the agent has to fill out can be automated. Or a survey can be automatically sent to capture the client’s feedback.

Ultimately, customers can self-serve, and if they don't want to automate, there's that human in the loop. That human is the agent, who can have higher-quality interactions and more interactions on a daily basis than they could previously.

Paul Carroll

I’ve been an advocate for self-service for decades, but in my experience the handoffs to humans from the AI can sometimes be messy. How do you tackle those problems?

Chase Tarkenton

Obviously, the quality of the AI matters. So does the quality of the partner providing the AI to the agents and brokers. Unfortunately, there are a lot of technologies out there today that cannot deliver on some of the promises that are made.

Anyone considering a chatbot system should talk to reference customers and do a pilot to spot where problems might arise and to figure out in advance how to handle any issues.

Paul Carroll

I assume that this sort of technology, like most I've covered over the decades, has a progression to it. What are the sorts of interactions you started using AI with? And where are you now?

Chase Tarkenton

Twenty years or more ago, chat and voice virtual agents, as we call them, just handled basic FAQs [frequently asked questions]. What’s your phone number? How do I find a branch location? The agents were useful, but I wouldn’t say they were high value.

Fast forward from there, with the emergence of natural language understanding and the incorporation of machine learning and AI, many of these technologies can now handle more sophisticated use cases. Customers can fully resolve requests without having to call and speak to a human—though it’s an important design consideration to make sure they can reach a human if they want.

For example, look at first notice of loss. If your car breaks down on the side of the road, you could pick up your phone, call your insurance provider, and fully authenticate yourself through voice automation. They could leverage geo tracking to know where you are on the side of a busy highway and call a tow truck to come get you. They could capture information automatically and complete first notice of loss without any need to escalate or require a call center or an agent to support them.

That's a great use case that we're seeing come up again and again, and insurance organizations are executing on it. Their NPS [net promoter score] stays consistent with the NPS of a human interaction, which is what we want.

Paul Carroll

Where do you think you can get in two or three years?

Chase Tarkenton

Things are moving so fast that it’s hard to say what’s two or three years out in the AI space, but we’re clearly going to see generative capabilities produce some very exciting outcomes.

We're seeing models produced by some of the bigger generative providers that can reason and handle complex interactions. Open AI’s latest model does complex reasoning in a scientific setting. Those are breakthroughs that will allow for more intense use cases within insurance.

While we can all get excited about technology, though, what matters most is: What does the customer want, and are we doing everything we can to help them be successful? A close second is: How do we make the agent as successful as possible in their role? How do we make them efficient? How do we make them effective? How do we help them to scale?

I think using pre-trained models that are then trained on the data of the insurance organization, with generative capabilities blended in, can drive hyper personalization, which is what the industry is asking for.

Paul Carroll

Where do you see the breakdowns at this point? Where are people most likely to say, "Okay, I’m done with the chatbot. I want to speak to a human?"

Chase Tarkenton

In the design of an automated experience, there are a couple of things that are just a hard stop for consumers.

Number one, if the bot doesn't understand what you're saying, we have very low patience and will immediately drop out of those channels and want to speak to a human.

Number two: Sometimes a partial experience is not what consumers want. They're looking for full resolution. If I want to check what my premium is and can only do part of that before I’m escalated to a human, where I have to repeat myself, that's a non-starter, right?

Any time an interaction is being escalated to a human, it’s critical that the context and information already gathered is transferred to that agent in advance, so it's not being repeated.

Paul Carroll

Are there any issues that I should have gotten into that I didn't?

Chase Tarkenton

AI and automation are a huge topic. The only other areas that might be worth getting into are security and compliance.

Paul Carroll

Great question. Glad I thought of it. How do you handle security and compliance?

Chase Tarkenton

The good news is that the tools exist to mitigate hallucinations and to make sure that any AI-based agent will speak in a fully compliant fashion. If an agent or a customer asks the bot a question, it can quickly recognize whether responding would violate compliance.

Those tools are being used today. At Boost.ai, we’ve got hundreds of financial institutions, many in insurance, that are leveraging those tools to get the results they’re looking for: a better customer experience that they know is ironclad, protecting their reputation and their brand from a security standpoint.

Paul Carroll

Thanks, Chase.


Succession Planning for Agencies

Severe Weather Needs Innovative Insurance


About Chase Tarkenton

chase headshotChase Tarkenton is the SVP and general manager of boost.ai, North America. He’s focused on partnership growth, helping insurance firms leverage AI technology in personalized customer experiences.

Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.