Download

Choreographing a Successful Insurance Career

Leveraging transferable skills and diverse backgrounds are key to bridging the industry's talent gap.

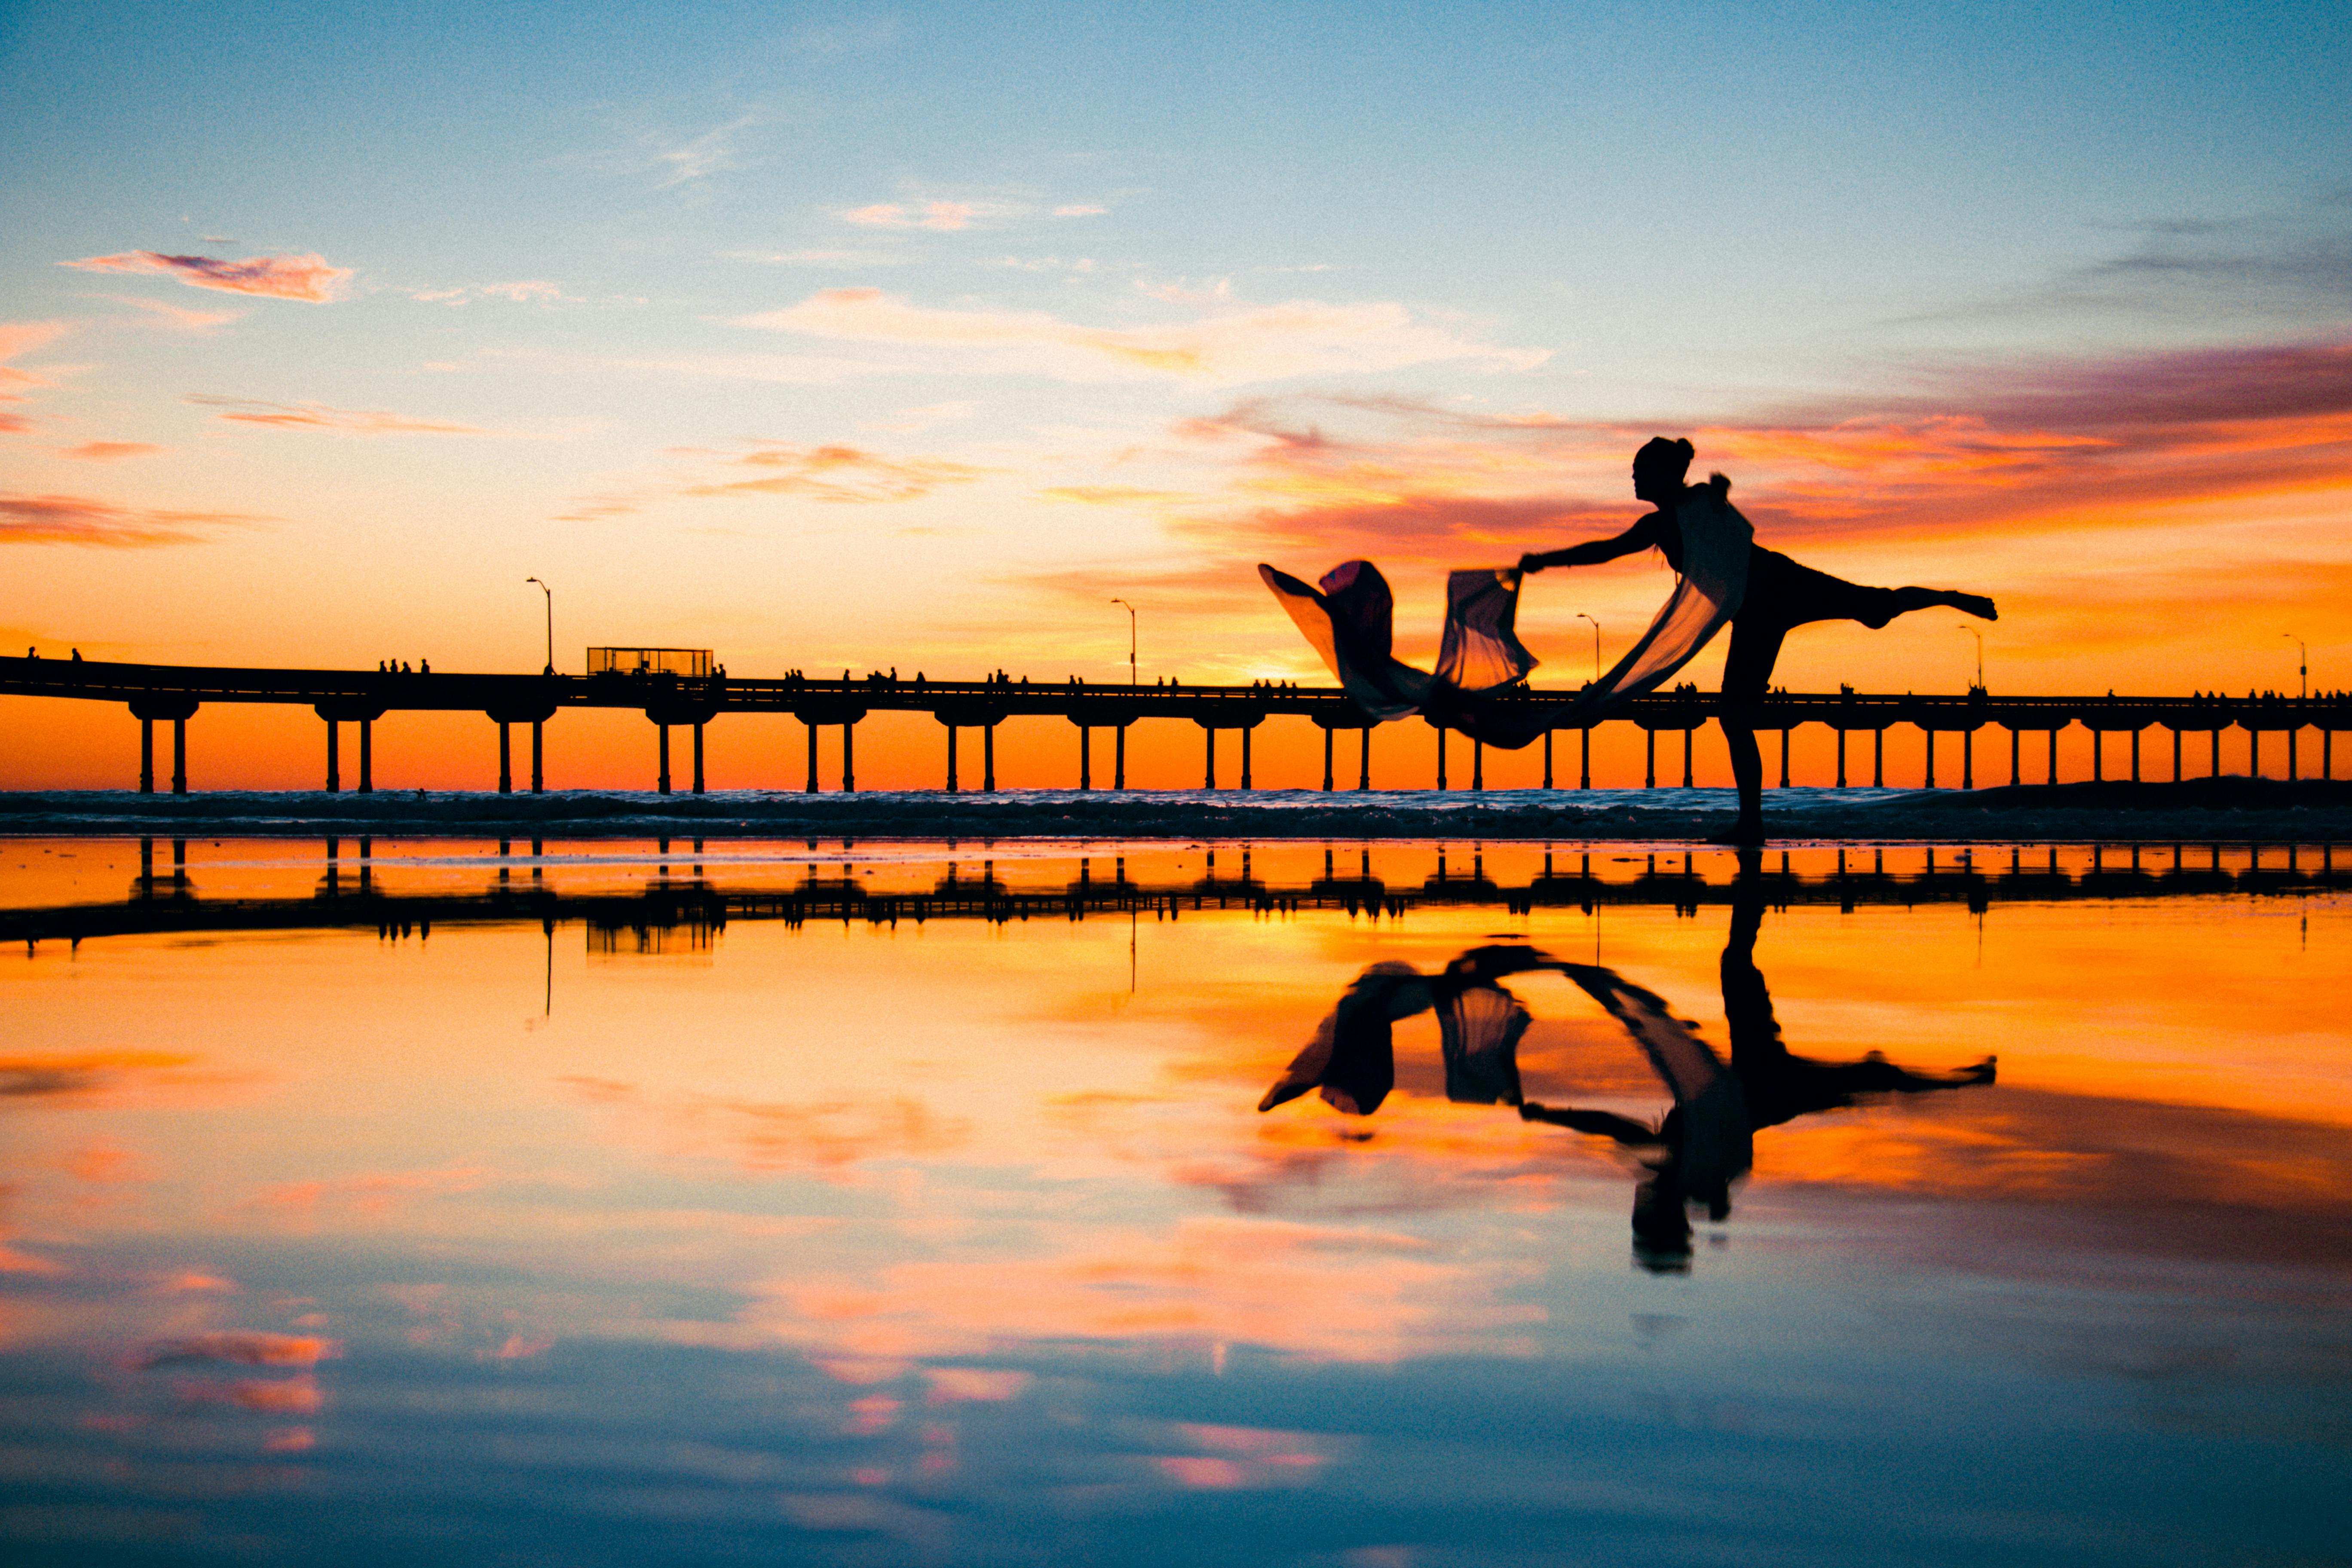
dancing

In 1966, Ronald Reagan shifted from actor to politician as California’s 33rd governor, later becoming known as the Great Communicator. Reagan leveraged transferable skills to change careers.

While I’m no movie star or politician, dramatic career moves are something I appreciate. I have worn many professional hats in fields like engineering, tax management, and, now, insurance. I’ve also worn a few pairs of dancing shoes that helped, as well, and continue to teach dance and run a successful studio while working in the insurance sector. With President Reagan’s experience as something of a guide, I also brought forward talents and abilities learned in my other professional incarnations to help launch and sustain a successful insurance career.

After several years of growing my career and helping develop Across America’s talent profile, I have found looking outside the industry for those with varied backgrounds like my own can bring talented, multifaceted individuals with fresh perspectives into insurance. As the industry struggles to fill a continually growing talent gap, thinking outside the box may be an answer.

See also: What's Causing the Insurance Talent Shortage

Dancing My Way Into Insurance

We often hear insurance is a relationship business. For those of us who find – or are recruited to – the industry after careers elsewhere, there is no truer statement.

I was discovered on the dance floor. I had been teaching dance classes for years. One of my students, a lovely and graceful young woman, was the daughter of insurance entrepreneur Harish Kapur. During her time as one of my students, our families became friends. A few years after, in a casual conversation, Harish mentioned he was looking to hire someone with executive potential. He had built a successful model by bringing in non-insurance professionals with an acumen for business and then training them on the nuances of the industry. While I did – and still do – love dancing, I felt I had been searching for my professional home for years. With a background in engineering and tax management, I wondered if he would consider taking a chance on me. What could I bring to the table?

Transferable Skills

Insurance is an industry where many skills can translate and prove useful. Math, proficiency with technology, administrative talent, actuarial science, sales ability, management experience and other skills all feed into a range of roles within insurance, not just as nice-to-haves but rather as critical, backbone requirements. As the industry continues to experience a talent drain as Baby Boomers retire, candidates with nontraditional experiences outside of insurance can provide a bountiful well of potential talent.

Working in different industries, I was an example of that nontraditional, potential insurance professional with transferable skills highly sought by the industry. With a degree in engineering, I am hard-wired to solve problems. When faced with any task, I need to understand the root of the assignment and create my own workflow rather than just following a predetermined process.

Working at my family’s powder metallurgy unit in India, I managed the accounting and led the company’s quality control over both our products and the company’s workflow processes. That experience taught me the value of communicating clearly in different languages and dialects because our workforce and vendor partners were made up of diverse talent pools, including individuals of varied education and experiences. I learned the importance of making my interactions personal and meeting people where they want to be met.

Having supplemental degrees in industrial and tax management gave me an appreciation for and an ability to implement actuarial science practices, which helped me further develop an aptitude for solving problems.

And, of course, there was dancing. I have taught traditional Indian dance for decades, concurrent with my various day jobs. My experience as a dance teacher has helped me refine my appreciation for entrepreneurship, as well as the importance of time management, patience, flexibility, empathy and nonverbal communication.

A New Routine

Once Harish understood my skills were not restricted to dance, he saw how my experiences would serve as a foundation for a role in insurance. I had transferable skills critical to the industry. If I could be taught well and diligently strive to learn the ins and outs of insurance, it could work. He took a chance and hired me.

The hours worked well for me back then, as they do now, and afforded me the opportunity to continue to pursue my first love – dance – while also balancing my family responsibilities. Also, I’d come to know Harish and his family well. They valued hard work and intelligence and prioritized family while also bringing a little fun to everything they did. It was the right move for me.

My first official role with Across America Insurance was as an executive assistant, later becoming an executive manager, where I worked on tax management and operational tasks for the company. As I continued to prove myself, I earned additional responsibilities that provided a crash course in the more technical side of the industry. I learned the fundamentals of insurance, thanks to company leaders who allowed me to gain a thorough understanding of industry definitions and the technical processes.

I also learned processes and procedures on various action items such as filing taxes. I learned the claims workflow, learned to understand how to identify and implement technology to cut down on redundancies, and more. My background, the training and support of our leadership team, and old-fashioned, real-world experience helped me grow my insurance career from executive assistant to my current role as vice president of captive operations for Across America.

I remember one of my first big projects with the company was to manage a coverholder program with Lloyds of London. That work taught me a great deal about the industry. It can be both straightforward and complicated, which for me offers the kind of challenge I enjoy. I appreciated that kind of environment as a dance instructor and dance studio owner. Even back in my family’s business, marrying complexity and clear process always captured my imagination. But it was insurance that brought it all together for me.

To this day, I regularly tap into the skills I learned in my former careers to train others, interact with clients, streamline operations, and more. Working for an organization that values outside perspectives and sees the benefit these skills can bring to a business and the people it serves makes the work even more rewarding.

See also: 7 Ways to Innovate With Purpose

Finding My Stride

Today, I work with captives, existing and potential reinsurers and other servicing partners. Among other things, this work demands careful application of the communication skills I honed while leading the quality management certification and overall quality control of products and process flows at my family’s powder metallurgy business. The ability to translate complex products and services into human terms has been key to my success and in building the relationships. Building and maintaining those relationships as the market tightens, something I learned to do when I opened my dance studio, is paramount to ensuring you don’t just secure a transaction but rather continuing business, even in challenging times.

My additional degree in tax management helped train me to think as a problem solver and has allowed me to develop procedures and systems that not only helped me in my earlier days at Across America for filing state taxes but continues to serve as important training for newer team members.

Of course, my teaching skills also remain invaluable as we continue to welcome new talent. Across America has made it a priority to hire beyond the insurance industry. While that practice has brought a wealth of perspectives, it can also require training customized to meet everyone on their level, understanding their perspectives and finding the right fit within the organization. Identifying and training the next generation of talent for Across America and the insurance industry has been a learning experience of its own that continues to help me grow professionally.

Building the Future

Companies across our industry can follow this model to success, as well, particularly as insurers struggle to attract qualified candidates. Consider thinking outside the traditional realm of insurance for your next hire. While a prospect’s job title may not appear relevant, certain core competencies should be apparent, including:

  • Patience: As a newcomer to insurance, your new employee may have years of existing experience in a different industry. Keep an open mind. You would be surprised to see what skills end up being relevant to insurance.
  • Asking Questions: When adapting to a new industry, there will be knowledge gaps. As your employees identify what they don’t know, it is important to find talent that can put pride aside and ask questions. Keep doors open. Questions from all employees should be welcomed. This philosophy helps eliminate misunderstandings.
  • Research Capabilities: Independent research will not mirror the in-depth insights of a colleague with years of experience; however, it will help your employees enter the conversation armed with some foundational information. Finding employees who take the time to learn what they can on their own is important. It showcases a willingness to take initiative and adapt quickly.

Job seekers today face the dual challenge of presenting the right characteristics to employers while seeking organizations with core values that match their own. Characteristics that new employees have found enticing at Across America include curiosity and an interest in helping employees grow, an openness to learning and acceptance of honest feedback from all levels, as well as strong market knowledge of the entire insurance industry and market overall. I’m grateful for the opportunity to have found insurance, and more so for the work culture that helped me become a skilled insurance professional.

Recruiting the next generation of talent is a challenge with solutions in reach. Recruiting individuals for their unique characteristics and willingness to learn rather than strictly insurance-specific experience can foster fresh ideas and perspectives to help insurance innovate and move into the future. We simply need to think on our feet about going beyond the usual practices
Ragini Chandrasekar

Profile picture for user RaginiChandrasekar

Ragini Chandrasekar

Ragini Chandrasekar is vice president of captive operations for Across America Insurance Services.

Ragini has worked in electronics engineering, tax management, and teaching Indian classical dancing.

Risks Facing Small Businesses Are Evolving

Emerging trends in cyber, flood, and excess and surplus lines insurance highlight the changing risk landscape for small businesses.
small business

As the business world continues to evolve, so do the risks faced by small enterprises. Recent research highlights six key areas of insurance coverage that are becoming increasingly relevant for small business owners. This overview explores emerging trends in cyber, flood, and excess and surplus lines insurance, offering insights into why these protections are gaining importance in the current business climate.

Cyber insurance

The prevalence of cyber risks is rising as businesses become increasingly digital. However, small business owners may be unaware of this risk or of the financial and reputational consequences of an attack until it's too late. According to the Hiscox Cyber Readiness Report, "41% of small businesses experienced at least one cyber attack during the last year. The median cost of cyber attacks for one small business in a year is $8,300."

Madison Williamson, senior insurance product manager at At-Bay ,stated, “As all businesses are forced into the digital world, it is no surprise that small businesses are sometimes ill-equipped to recognize the risks or react with the necessary speed to rectify errors or attacks. While it can be tempting for small businesses to [ignore] the risk of cyber attacks, it is vital for business owners to carefully consider not just the financial impact of lost sales and profits but also the reputational impact of being considered not secure by customers.”

The types of cyber attacks and the associated technologies that cyber pirates use are quickly evolving and dynamic. For this reason, small businesses can be an easy target for cyber hackers, sometimes with devastating effects.

Small businesses usually don't have the luxury of dedicated, trained resources to address cybersecurity weaknesses or rebuild systems. Hackers target smaller businesses because they typically focus less on cyber risk management and have weaker security than enterprise corporations.

According to Mathew Probolus, chief underwriting officer at Berkley Management Protection, "Small businesses are frequent targets of cyber attacks. A recent Datto report found that in the last year 32% of small businesses reported that they dealt with a phishing email or attack. 30% of small businesses reported that they also dealt with a computer virus."

Risk can be mitigated, though not eliminated, by "implementing strong internal controls and procedures, maintaining security controls, and proactive action," according to Chris Hojnowski, vice president, technology and cyber practice leader with Hiscox USA. "Where there are humans, there's vulnerability to cyber attacks. And where there is any kind of sensitive or valuable data, such as customer information, there's a target for bad actors."

See also: Top Global Business Risks in 2024

Flood insurance

According to a recent article by the Insurance Information Institute, "Flooding is the most common and costly natural disaster in the United States, causing billions in economic losses each year. According to the National Flood Insurance Program (NFIP), 90 percent of all natural disasters in the United States involve flooding."

The Federal Emergency Management Agency (FEMA) has shared some eye-opening statistics:

  • Just a few inches of flooding can cause thousands of dollars of damage. The deeper the flood water, the higher the repair cost.
  • From a 2018 press release: "About 25 percent of businesses do not reopen after [natural] disasters. Having an emergency disaster plan and a continuity operations plan in place can reduce that risk and help the business recover faster."
  • From a 2023 FEMA fact sheet: "Ninety-nine percent of U.S. counties have experienced a flood since 1998, and over 40% of flood insurance claims come from outside high-risk flood areas."

There's reason to hope innovations in the parametric flood insurance space will help fill some flood coverage gaps in the U.S. in coming years. Flood risk is difficult to price for carriers, so what follows oftentimes is a coverage gap. New tech tools are being developed to improve the accuracy of underwriting data for conventional insurers, which could ultimately help expand access to parametric flood insurance to even the smallest businesses.

See also: "Micromorts": A New Way to Talk About Risks

Excess and surplus (E&S)

According to the International Risk Management Institute, "Excess and surplus lines insurance is any type of coverage that cannot be placed with an insurer admitted to do business in a certain jurisdiction."

In a recent interview, Mark Schauss, executive underwriting officer, small commercial, for Markel, summarized, "The most significant trend in the E&S insurance landscape is the continued growth of the E&S marketplace itself."

According to a recent McKinsey report, "Between 2016 and 2021, the E&S industry has grown by three times as much as the admitted market."

E&S submissions have increased by double digits in the past year, propelled by independent agents and wholesale brokers. Agents have become increasingly reliant on this high-risk insurance coverage tool to ensure their customers' investments are properly protected.

Within the commercial category of E&S, commercial liability and commercial property have made up the bulk of the market. As summarized in a recent Insurance Journal article, "Premiums in [commercial liability and commercial property] lines increased nearly 10% and 32% to about $26.8 billion and $24.2 billion, respectively, in 2023."

We expect this growth in high-risk insurance for commercial markets to continue, at least for the short term.

What factors contribute to the increased demand for E&S coverage?

  • Non-admitted markets for high-risk insurance have stepped in for admitted markets

Admitted carriers are not renewing business and are reducing their industry and coverage offerings. Additionally, the increasing cost of claims is leading to the need for admitted carriers to increase premiums. And because of regulatory requirements, it can be difficult to raise those premiums quickly, leading insurers to exit certain markets altogether. Because E&S carriers can offer more flexible premiums where admitted markets can't budge, they have been able to fill the coverage gaps where there are no, or only prohibitively expensive, coverage options.

  • Catastrophic events have increased the demand for high-risk insurance

Regions that tend to experience more natural disasters can drive demand for high-risk insurance options like E&S.

  • Nuclear verdicts have exceeded expectations

Nuclear verdicts are jury awards or settlements in a liability lawsuit that significantly exceed expectations. Because E&S carriers usually have higher limits, they can be a valuable option in these high-risk insurance situations.

  • Flexibility and agility when remarketing

The industry has demanded creative solutions to an ever-changing variety of high-risk insurance exposures, like cyber risk. Those solutions aren't readily available, or have become very expensive, on admitted markets. E&S carriers, buoyed by their financial strength and agile underwriting, have quickly responded with solutions when remarketing was needed, allowing them to capture new business due to their flexibility.

Are We Asking the Wrong Question on the Talent Gap?

While the emphasis has been on how to replace hundreds of thousands of people retiring in the next few years, the issue may be less about finding new talent in the insurance industry and more about retaining it.

talent gap

Paul Carroll

I’d like to get into some of the ideas you laid out in your latest book, on the power of collaboration, but let me start by asking for your general sense of where the industry is in terms of addressing the talent gap that’s being created by the wave of retirement as well as the need for new types of talent.

Bryan Falchuk

I think we've made a lot of strides from a recruitment standpoint, but the overwhelming theme that I hear, certainly from people in claims leadership I interact with, is that we're bringing them in but not keeping them. To be fair, I don't get enough exposure to underwriting and some other areas to know what they’re facing, but claims is very difficult because you really get beaten up. You're there to help someone, and everything they've been told is you're there to screw them over. It's one thing to be treated adversarially. It's another to be treated that way when you're genuinely trying to be helpful. It hurts twice as much for someone who's new.

I don't think we've done enough to make new people feel connected and bring them up to speed, partially because of more remote work, partially because the folks who would do that are retiring or have retired. We're not getting people to the point where they could feel expert in their work, and then they're getting pummeled.

So we bring people in, and then, after a year or two or three, they're very disillusioned, and they go elsewhere. That's especially true when the recruitment story is around money. People decide there are other things they can do that make similar money, where they're not being kicked in the face while trying to help people.

Paul Carroll

Do you have a particular tip on how to do better?

Bryan Falchuk

We need to get the older, more experienced people involved with the newer folks, to bring them along. We can’t just throw in the towel and resign ourselves to the current reality.

Remote work, especially in claims, is not a new story, because we have field adjusters. We’ve had people spread across the country, or at least focused on different geographies from the person sitting next to them. We just have to be much more creative about how we bring that knowledge together.

That might mean a bit more travel budget. That's something I've seen in the past year. On the back of 2023 underwriting results, a lot of carriers froze travel, even for training and for continuing ed, but if you aren’t bringing your folks together and giving them the proper training, you don't have the right to complain about how they're not feeling like a part of the organization and aren’t getting trained up.

Historically, you would pop your head up over the cubicle wall or look right or left and ask a question. We haven't really figured out how to duplicate that mechanism now that we don't have the cubicle wall to stick our head over. And when we look right or left, we don’t see a person. (We might see our cat or our dog.)

But a lot of new tools are coming online, a lot of AI type tools, such as generative AI. These technologies provide more of a human interaction. When someone poses a question, the responses are more flexible and situational, instead of rote and hard to understand. The tools have evolved from the more traditional kind of knowledge management tools. They respond more as if I popped my head up and asked a question. Maybe the answer is that we need to get a lot more aggressive in deploying tools like these.

Paul Carroll

What you’re describing certainly matches what’s been happening in the world of journalism. When I joined the Wall Street Journal copy desk as a 22-year-old, way back when, there was a sort of apprenticeship. I’d ask questions of the copy editors who’d been on the desk for 20 or 30 years. For obscure questions about style, the answers had been collated in a light blue binder known as “the recipe book.” Today, all the institutional knowledge has been collected in digital form, and copy editors can ask questions or even get prompted when they misunderstand a rule.

My theory has been that this new generation of AI can take a lot of drudgery out of the document gathering and reading that happens in insurance, especially in claims, underwriting, and in agencies, which should help both in attracting and retaining talent. Does that track?

Bryant Falchuk

I come from primarily an E&O background, so professional liability, where every claim could have a lawsuit lurking in it. Every claim has an 80- or 90-page PDF that's probably a scan, so the information isn’t digital. It’s exhausting to have to go through that as part of the 800 emails, literally, that you're going to have over the course of a claim, and stay on top of it while you have 120 other pending claims on your desk. That's impossible.

So to have something that can parse through the PDFs and emails and keep a sense of what's going on, summarize things for you, help you get up to speed faster, understand when something is popping that might be out of your periphery: That's valuable.

I’ve seen one carrier in particular use Gen AI to go through all their past coverage letters. If the adjuster decides to deny a claim, the AI goes to that knowledge base to look at similar situations and draft the denial letter. Same thing on acceptance of coverage—and they started with acceptance because it's less contentious. That's not an earth-shattering application, but it does save some time. You still have to check for accuracy, but at least you have a draft to start with.

There’s another aspect to what AI can do that occurred to me after I got a new car recently. It's a General Motors product, with its SuperCruise autonomous driving. When people drive, we’re more focused on what’s right in front of us. But the AI is focused on that plus what is well out ahead, perhaps some car that is merging awkwardly that we never would have spotted otherwise. In insurance, AI can look out ahead, see the bigger picture, and perhaps spot issues that will become more important than the specifics of this one letter that's going to drain you for the next hour.

Paul Carroll

I like that analogy.

Tell me a bit about the importance of collaboration, which is the big theme in your latest book.

Bryan Falchuk

That’s key on a few fronts. For one thing, younger generations are more interested in the impact they have, and being part of something. That's collaboration.

Having a more interactive, collaborative, enriching work environment is absolutely appealing to them, and if that helps counteract some of the negative aspects of the work when it gets really tough, fantastic. Collaboration also creates new opportunities in the sense that you may get to work on something that would never have been possible otherwise. And collaboration inherently brings new thinking into the mix. All that makes the industry more attractive.

That can even be as simple as claims and underwriting working together. You've seen enough carriers where they hate each other. Claims will blame underwriting for what they did that's now on claims’ plate, and underwriting will blame claims for spending all the money that underwriting works so hard to bring in.

Actually, they’re both wrong. If underwriting isn't hearing from claims, and claims isn't seeing what's going to be coming down the pike from underwriting, you're missing something.

I see progress in specialty lines carriers, where they are much more integrated and collaborative.

At lots of companies, other departments are referred to like enemies. You will hear things like, “IT did this wrong,” or, “IT didn’t do what we needed.” I'll always ask, “Who is IT? You're talking about them like they're some singular, terrible person.” We can get past those sorts of characterizations if we collaborate.

Paul Carroll

Do you have a favorite example or two of collaboration?

Bryan Falchuk

I have lots of frustrations where it's clearly lacking, but I’ll stick to the positive.

I remember meeting with claims folks at two carriers, where you couldn't keep track of who was in claims and who was in IT. My first reaction was, “Why is IT involved and asking all these seemingly irrelevant questions?” But then I realized that the IT people were thinking through all the system enhancements they were planning to make down the road. They were excited to learn what claims was going to need and were thinking about how they could provide the right tools and connections. The interaction was very symbiotic and supportive.

Paul Carroll

That’s great. Anything else that’s top of mind before we wind up?

Bryan Falchuk

I just go back to where we started. We've been having the same conversation for over a decade, and it's really easy to just keep having it and then get frustrated with the new generation of people. If they don’t stick around, that’s not on them, that's on us. We can’t just bemoan them. We have to understand what makes them tick and solve for that.

If you don’t do that, you’re not going to have any employees left. And we don’t have a lot of time to get this right.

Paul Carroll

Thanks, Bryan.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

September ITL Focus: Talent Gap

ITL FOCUS is a monthly initiative featuring topics related to innovation in risk management and insurance.

talent gap


FROM THE EDITOR 

A nephew of mine neatly embodies the talent issue facing the insurance industry.

After he earned an economics degree at William & Mary, his first job five years ago was at an insurtech, but he got bored, so he quit and became a professional gambler focused on sports. He earned more in his first year than the combined annual salaries of my younger brother (a longtime editor at the Wall Street Journal) and his mother (an adjuster with a major insurance company). In the first week of this year’s college football season, he earned more in a single day than he had in his first year with the insurtech. But the major books are shutting him down, because they can see how much money he’s taking from them, so he’s thinking he may look for a real job in the spring, after college football and basketball – his two favorite seasons – conclude.

I think a Wall Street firm is the logical landing spot for him, because he’s not only super-bright in a mathematical way and is a cold-blooded gambler but is a nearly scratch golfer and is very funny, so he’d be great with clients, but he’s certainly open to returning to insurance. My question: Let’s say some company in our insurance ecosystem is fortunate enough to land my nephew; how do you keep him interested after a year or two?

That’s the question that came up in this month’s interview with Bryan Falchuk, the CEO of the Property & Liability Resource Bureau and one of my gurus on all things insurance.

Bryan says many companies are actually doing better at recruiting talent—but are losing people after a year or two. He lays out a number of ideas on how to improve retention, including ponying up some money to bring people together so the old hands can nurture the new hires and using AI tools far more aggressively, to answer the sorts of questions that a newbie used to be able to address just by popping their head up over a cubicle wall and asking an experienced colleague. He also talks up the importance of collaboration, the subject of  his most recent book.

I hope you find the interview as enlightening as I did.

Cheers,

Paul


"Having a more interactive, collaborative, enriching work environment is absolutely appealing to them, and if that helps counteract some of the negative aspects of the work when it gets really tough, fantastic. Collaboration also creates new opportunities in the sense that you may get to work on something that would never have been possible otherwise. And collaboration inherently brings new thinking into the mix. All that makes the industry more attractive."

Read the Full Interview

"So we bring people in, and then, after a year or two or three years, they're very disillusioned, and they go elsewhere. That's especially true when the recruitment story is around money. People decide there are other things they can do that make similar money, where they're not being kicked in the face while trying to help people.”


— Bryan Falchuk

Read the Full Interview
 

READ MORE


3 Steps to Weather the Coming Labor Crunch

The time is now for insurance companies to change how they think about hiring, retention and technology.to ensure a strong pipeline of talent.

Read More

What Does Gen Z Want?

Leaders need to come to grips with this generation. Already 22% of the workforce, they will represent one out of every three employees by 2030.

Read More

AI and Skills-Based Hiring

Skills-based hiring and skills-based salary levels can mean better results and access to a wider pool of talent at a time when AI is increasing the pace of change.

Read More

Decoding the Talent Exodus in Insurance

Here’s why I believe the insurance industry should look at the exodus of underwriting talent as an opportunity instead of a crisis.

Read More

How and Why to Tap Into Global Talent

Here are four key strategies insurance companies should consider when expanding into international markets.

Read More

Why Take a Job in Insurance?

Here are five reasons! We'll start with the fact that employees have the privilege of helping people at key moments in their lives.

Read More


FEATURED THOUGHT LEADERS


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

How AI, Tech Reduce Friction in Insurance

Insurers must embrace innovative technologies to meet elevated customer expectations and remain competitive in the digital age.

choices

When we contemplate the term “innovation,” we typically envision disruptive innovation—technologies that significantly change the landscape of a service or product. But it is really sustaining innovation, or continual improvements in product suites, that typify most industries. In recent years, sustaining innovation has given rise to powerful tools that insurance companies can use to minimize the “friction” that frustrates consumers and create new and more seamless customer experiences.

For insurers, the proliferation of friction-reduction technologies has become a double-edged sword. New solutions have the potential to eliminate or minimize service and performance issues that have caused headaches for customers for decades. At the same time, adjacent industries have already adopted new technologies that have resulted in elevated customer expectations. The result? Customers are likely to have less patience with insurers that are slow to address pain points in their customer experience, forms processes, and claims handling, among other processes.

Across all industries, 45% of consumers say they’ve stopped doing business with a company due to a poor experience, and 47% say they are willing to spend more money to receive a better experience or service. As the rise of artificial intelligence allows first-movers to rapidly elevate the quality of service they provide, insurance companies of all sizes should embrace technology to reduce friction and enhance experiences for customers as a core strategic priority.

A potent mix of technologies

Companies have always used technology to make both internal and customer-facing processes more efficient. What’s different now is that next-gen technology is allowing companies to eliminate friction to an extent never before possible.

This progress is not being driven by any single new solution. The industry has historically seen different waves of innovation that gradually displaced manual processes. Early on, tech stacks involving optical character recognition (OCR) and robotic process automation (RPA) were game-changers for automating repetitive processes. Later, cloud computing and API development allowed for increased interoperability and automation at scale. Now, companies are layering the next evolution of AI into this mix. It is now easier than ever for a disruptive innovation in one market to be applied to an adjacent industry. The interaction among all these solutions will hopefully propel the industry to a new era of frictionless processes.

Eliminating pain points for short-term gains

Removing friction from the customer experience will require both short-term and long-term strategies. In the short term, insurers should target the most prominent and persistent pain points that have plagued insurance company customers. For example, one of the biggest complaints from customers is that they are required to fill out the same information repeatedly in different forms.

Until recently, pre-populating forms with data already provided by the customer was a complicated task. Data is often stored in different formats in separate systems. Over the last few years, however, most large insurance companies have undertaken comprehensive data management overhauls designed to normalize and centralize data across the organization. Once companies have this “single source of truth,” they can tap into usable, reliable data for any and all uses—including pre-populating forms.

Today, companies are also harvesting data by feeding images of paper documents into natural language processing solutions and other AI applications that can parse non-harmonized data to identify and understand specific information, like pinpointing first, last, and middle names from various documents, and determining if a phone number is a cell phone or a home landline. Using these techniques to reduce the friction associated with duplicate paperwork can have a positive and immediate impact on the customer experience.

Long-term transformation

Insurers must also consider how AI and other technologies are transforming customer experiences over a longer horizon and set IT budgets and strategies to keep pace.

In general terms, companies should constantly be looking for ways to apply AI internally to reduce friction and make workflows more effective. For example, think of something as simple as a forgotten password. Most of us have had the experience of clicking a “Forgot Password” link and waiting for a reset email that never arrives. I, myself, often abandon a site when that happens in utter frustration, as I suspect others do as well. A function as basic as this can be rearchitected leveraging AI. 

Pattern detection algorithms on a user’s expected versus actual behavior, in addition to downtime detection, should result in a better experience. Did the user abandon their journey in frustration? Platforms should be able to course-correct by detecting these behaviors and triggering the next-best action. Correcting these issues is just one example of how removing friction from back-end systems can improve both customer experiences and business results. By preserving customer satisfaction and minimizing client attrition, such operational IT investments can deliver big ROI in the long term.

These initiatives will become even more important over time as insurance companies build out the omnichannel models needed to meet the expectations of today’s customer base. According to the results of Broadridge’s 2024 CX & Communication Consumer Insights, 90% of consumers want companies to honor their channel preferences, but only 31% think companies do a good job at that task. Allowing customers to interact with the company through their preferred channel of print or digital will require effective integration of all the company’s internal platforms.

The landscape of competing for customer attention is more competitive than ever. Consider the nouveau consumer; within two seconds, consumers make a decision whether or not to engage with a 15-second TikTok or Instagram video. In this world of microsecond decision processing, if content fails to hold a user’s attention, they immediately move on to other content. In such a setting, traditional long-form financial statements or insurance forms will not cut it. Going forward, borrowing from the social media industry, insurers will have to deliver content that is personalized, easily digestible, and engaging. Examples may include personalized videos explaining benefits or streamlined account statements that highlight the most important information.

Next-gen customer experience

Beyond these new types of content, the interaction of cloud computing, APIs, AI, and other innovations are unlocking new opportunities for insurers to revolutionize the way they interact with customers. These emergent technologies support what’s known in the industry as “data federation,” or the ability to pull data from separate providers, harmonize it, and integrate it for use. Going forward, insurance companies will use this capability to access both internal data warehouses and external companies and data sources for functions across the organization and business lines—from confirming data on a claims form to verifying physical addresses and driver licenses from policy applicants and even double-checking the certification and credentials of doctors and other providers.

As technology has evolved, the lines between hardware and software are becoming more blurred, resulting in truly seamless experiences for customers. It is typical for a user to replace their physical wallet with their phone; we now live in a world of digital identity cards, mobile wallets, and keyless entry for vehicles. Adjacent industries have been able to greatly improve due to the ubiquitous nature of new features in mobile devices. Extended to the automobile insurance industry, imagine a world in which your phone detects you’ve been in an automobile accident, automatically contacts your insurance company, and provides back data on where the crash occurred, which vehicle and driver were involved, and other pertinent information. Such a harrowing experience shouldn’t be further exacerbated by a painful insurance process. A future is near where most of these interactions will be completely automated.

Thoughtful deployment of AI

As companies use these technologies to upgrade to a next-gen customer experience, they must avoid creating new next-gen pain points. Chatbots are a prime example. Chatbots were one of the first AI applications employed by companies and used by consumers. The experience for customers has not been great. When asked to define the things that make up a great customer experience, 48% of consumers cite “making it easy to talk to a real person.”

In fact, the replacement of humans by chatbots and other voice and online AI-powered customer service applications is probably one of the reasons ratings for customer experience and service satisfaction have been falling recently, as opposed to increasing due to innovation. Across all industries, the percentage of consumers who believe the companies they do business with need to improve their CX has doubled, hitting 70% this year.

Theoretically, however, chatbots should be a win-win for both companies and customers. The applications can reduce costs, cut down on wait times, and deliver instant answers to customers. But the failure of the earliest version of this technology provides a valuable lesson: As you implement new technology, use the concept of friction reduction as your north star.

In the case of chatbots, a new solution aimed at making customer service more efficient and easier for users actually resulted in more friction and a lower CX for customers. Looking ahead, however, I’m confident that the integration of solutions and systems will eventually result in highly effective, AI-driven self-help solutions that will significantly reduce friction and usher in an era of vastly improved service for customers.

That level of friction reduction will be replicated in scores of places throughout the customer journey, resulting in increased efficiency and lower costs for insurers, and an elevated experience for customers.


Aman Mundra

Profile picture for user AmanMundra

Aman Mundra

Aman Mundra is vice president and head of composition for Broadridge's Customer Communications business.

He focuses on delivering next-gen capabilities and investing in scalable, omni-channel solutions, as well as dual-sided network effect platforms, Web 3 enablement and blockchain.

Mundra is pursuing his MBA at Columbia business school.

Embrace Automation to Eliminate 'Gen-AI-nxiety'

Embracing automation is key for underwriters to keep pace with the industry's growing demands for advanced risk assessment solutions.
business underwriting

“Brokers are constantly evaluating underwriters," insurance veteran Tony Tarquini said in a recent webinar that I participated in. As a digital transformation expert, I’ve increasingly witnessed the broker-underwriter partnership being tested.

In the market these days, underwriters are pressed for higher quote volumes while needing to stay focused on quality risk selection, and brokers are pushing for faster turnaround times. With the staggering amount of data available to analyze, is it fair to expect underwriters to produce fast and accurate quotes using legacy systems?

In a fiercely competitive market, both underwriting delays and inaccuracies are unacceptable. While data is essential to gain real insights to assess risk accurately, sifting through large volumes in multiple documents and screens results in a massive slowdown. Hence, there is a sincere need for insight-driven data orchestration and enhanced efficiencies through automation across the risk life cycle. But are underwriters ready for the big shift?

In the recent webinar, “The Underwriting Maturity Framework,” my colleague Lloyd Peters and I discussed the current maturity level of underwriters, exchanged ideas on how to inspire change in the community, and discussed the value of having a road map to go from process-centric to data-centric underwriting at their own pace.

Here’s how underwriters can embrace automation and eliminate "Gen-AI-nxiety":

The change is inevitable

Today, insurers are looking to stay ahead and are seeking advanced risk assessment solutions. The focus has shifted from cost and efficiency to risk selection, pricing, customer-centricity, and AI enablement. Hence, underwriters must embrace technology to keep pace with the growing demands of the industry. The great news is underwriters now have access to emerging technologies and AI to support this transition.

See also: What to Understand About Gen Z

The first step: Breathe

The good news is underwriters don’t need to attempt transformation overnight. To acknowledge the need for change, one must be convinced it’s the right thing to do. A great place to start is to use an underwriting maturity model to benchmark where you’re starting from. This model provides a powerful visual of an underwriter’s current capabilities, allows them to identify both independent and interdependent business priorities, and accordingly identifies their level of maturity so they know where they’re starting from.

The next step: Self-assessment

The underwriting maturity framework is a practical, easy-to-embrace mechanism to make the necessary shift from manual to smart underwriting. There are five stages to this model, and each stage signifies the current capabilities of the underwriter.

  • Stage 0: Manual Underwriting - Traditional manual, off-system underwriting with information sorted within documents and isolated Excel files. Work is allocated through email between teams.
  • Stage 1: Digital Underwriting - Enable existing underwriting flow with a structured workflow engine and document/data storage where teams can collaborate.
  • Stage 2: Connected Underwriting - Optimize the underwriting flow by leveraging technology to accelerate and automate key steps, allow data transfers, and replace manual steps across the submission-to-bind journey.
  • Stage 3: Augmented Underwriting - Harness the power of the business and operational data captured through digital underwriting to provide targeted insights to underwriters on portfolio position, market, and risk characteristics.
  • Stage 4: Smart Underwriting - Enable the system to make automatic, algorithmic underwriting decisions in certain scenarios and provide recommendations to underwriters in others.

The maturity framework allows underwriters to identify capabilities that are key to executing their underwriting strategy, which will be specific to the line of business, geography, and complexity of risk that they write. What’s meaningful for one carrier may be less important for another, so having clarity in that strategy (growth, new products, efficiency, etc.) will help determine where you go first. This model highlights how connected all the components through the value chain are, and why it is important to get your underwriting data needs understood, work with operations, data, and IT to craft the right roadmap together.

The final step: Outline goals

Once you have clarity on your current state, plot your deliverables around each phase that will support identified goals. Start putting the building blocks around the desired underwriting capabilities across the next six, 12, or 18 months. The aim is to move the current operating state into a more data-driven state that advances the strategy and where the collective teams see immediate benefit—dramatically improved quote turnaround times, better clarity, and consistency on risk selection with more accurate pricing.

See also: What Does Gen Z Want?

Remember

It is important to keep in mind that technology is only a part of the solution. Engagement from operations, data teams, application and infrastructure architects, etc. must be fully aligned to see success in smart underwriting. The way the insurance industry works is changing. The underwriting evolution is here. The tools are available. The potential is significant. Now is the time. Embracing automation is one of the best decisions in an underwriter’s career.


William Harnett

Profile picture for user WilliamHarnett

William Harnett

William Harnett is the head of business strategy and customer success at Send.

He spent 20 years at AXIS Capital where he was the deputy chief operating officer and digital COO, working with AXIS’ underwriters to spearhead the business’s digital transformation.

Legacy Systems: Modernize or Overhaul?

There may be an alternative approach worth exploring: leveraging our current core systems while integrating modern technologies effectively. 

computer servers

In today’s fast-paced insurance landscape, the allure of shiny new technology can be tempting. The promise of modernization often leads organizations to consider a complete overhaul of their core systems—claims, policy administration, and underwriting alike. 

But before diving headfirst into multimillion-dollar implementations that could take years to bear fruit, it’s worth pausing for thought. Are we sure that throwing out our existing systems is the best route? With digitalization on the rise and innovative solutions like robotic process automation and microservices making waves, there may be an alternative approach worth exploring: leveraging our current core systems while integrating modern technologies effectively. 

Let’s rethink this narrative together as we navigate through sales and distribution, claims management, policy workflows, and underwriting processes in a way that maximizes efficiency without sacrificing investment or time.

See also: 2-Speed Strategy: Optimize and Innovate

Resisting the urge to throw out your core claims, policy admin, underwriting systems

The instinct to replace legacy systems can be strong, especially when faced with the latest tech trends. However, core claims and policy administration systems often carry valuable data and institutional knowledge that shouldn’t be discarded lightly.

According to research conducted by Celent and reported in their "Dimensions: P&C Insurance IT Pressures & Priorities 2024: North American Edition," 91% of the carriers interviewed stated that growth and distribution are significant (56%) or moderate (35%) for 2023, with 85% stating process optimization/operational efficiencies are significant. Celent stated, “Growth is the clear top priority for insurers in 2024, potentially indicating they are optimistic about the current climate and are taking an offensive tack. Operating cost reduction and process optimization remained top of mind for carriers. Notably, operating cost reduction is a much higher priority than IT cost reduction, indicating businesses are seeing the value of IT.”

Instead of a complete overhaul, consider an assessment of your existing infrastructure. Many organizations find that their current systems can integrate with new technologies, such as microservices or digital distribution channels. This approach allows for modernization without the full disruption of a re-implementation.

For example, an international insurer faced multiple business challenges, including creating products and not having a digital way to sell and distribute their products. They had siloed systems and an on-premises core. By enabling the products, sales, and marketing teams to create insurance products and deliver them in weeks rather than months or even years, they were able to provide API integration with their affinity partners and launch new B2B and B2C web portals. They leveraged their on-premises, legacy claims, underwriting, and policy administration systems and modernized by adding orchestration and integration layers.

By keeping what works while introducing enhancements through automation and embedded insurance solutions, you can create a more agile environment. Small adjustments might yield significant improvements in efficiency and customer satisfaction without the costs associated with starting from scratch.

Reinvesting in your core doesn’t have to mean tearing everything down; it could simply mean building upon a solid foundation that's already in place.

Do you really want to reinvest in a multimillion-dollar implementation?

When determining whether to "rip and replace" your legacy systems or enhance them with a modernization layer, it's crucial to evaluate several factors related to customer experience, system capabilities, and future growth potential.

Instead of immediately opting for a complete overhaul, consider whether a modernization layer on top of your existing systems might be more effective. This approach can extend the life of your legacy systems while introducing new capabilities through microservices, digital distribution, and APIs.

To decide which path to take, ask yourself the following questions:

  1. Customer Experience: Are your external portals and internal systems user-friendly? Are customers and employees expecting more digital interactions and services? If your current systems fall short in delivering seamless digital experiences akin to those of leading e-commerce platforms, modernization may be necessary.
  2. Digital Capabilities: Can your current systems support "Amazon-like" digital experiences, such as online ordering, real-time inventory tracking, and customer self-service? If not, it might be time to consider either enhancing your systems with APIs and microservices or replacing them.
  3. Integration: Does your current process integrate seamlessly with other digital platforms (e.g., Insurtech leaders, e-commerce, ERP, CRM)? If your team is bogged down by manual workflows, a modernization approach that leverages microservices and APIs could streamline these processes.
  4. Scalability and Growth: Can your existing systems handle future growth and increased demand? If your current infrastructure lacks scalability, a complete system replacement or significant modernization might be necessary to support long-term business objectives.
  5. Digital Presence: How important is a strong digital presence for your long-term goals? If digital interactions and services are becoming more critical for your customers, modernizing your systems to improve these areas is essential.

See also: Time to Modernize Your Mainframe

By answering these questions, you can determine whether a "rip and replace" is necessary or if enhancing your current systems with modern tools is the better approach. The toolkit available—comprising microservices, digital distribution, and APIs—offers flexibility in modernizing your infrastructure without necessarily discarding legacy systems. This balanced approach ensures you meet both current operational needs and future business objectives.

Before embarking on a multimillion-dollar implementation, it’s also crucial to consider the resources required—not just financial investment, but also the time and personnel needed to manage such a project. The process of aligning stakeholders, engaging teams, and training on new systems is a massive undertaking that can disrupt daily operations and divert focus from other critical business activities.

The insurance industry is relentless, and every day counts. In a market where companies are continuously vying for customer attention and market share, can you afford to pause operations for another three to five years to implement a new system? During this time, your competitors won’t be standing still. They’ll be leveraging their core systems while innovating with digital solutions, potentially gaining an edge in the market.

Instead of committing to lengthy and resource-intensive re-implementations, consider modernizing what you already have. Think about integrating middle-layer solutions or microservices that enhance current capabilities, allowing you to retain the agility needed to adapt. Embracing digitalization today means focusing on efficiency while minimizing risk—a much smarter path forward in an ever-evolving market landscape.

How Telematics Can Keep Fleets Safe, Insurers Happy

Unified fleet management platforms with AI dash cams provide critical insights to improve safety, satisfy insurers, and optimize operations.

windshield view in rain

Juggling multiple software systems to manage a fleet is like trying to assemble a puzzle with missing pieces. You're constantly switching between platforms, searching for data, and hoping everything fits together. It's a time-consuming process that often leaves you with an incomplete picture of your fleet's health.

But the real problem with these data silos? They put your fleet at risk. Without a unified view of everything that’s happening, how can you identify trends or make data-driven decisions? Imagine guessing if a driver is speeding or if a truck is about to have a breakdown. Not exactly a recipe for safety or peace of mind.

Here’s a concern I recently heard from other fleet managers: Insurance companies are getting tougher. Without strong driver safety tech stacks that include telematics and AI-powered dash cameras, there’s talk about nonrenewal of policies or increased rates. Distracted driving accidents are on the rise, and insurers are starting to require proactive fleet safety programs.

A unified fleet management platform can serve as a command center for your entire fleet operation. Everything—GPS location, engine data, driver behavior captured by AI dash cams, maintenance schedules—is all in one place, accessible with a single click. No more switching between systems, no more piecing together reports. Just a clear picture of your fleet’s health, right at your fingertips.

See also: How to Reduce Distracted Driving

So, how can a unified platform with AI dash cams help you keep your fleet safe and your insurer satisfied? Consider the following:

  • Safer drivers: AI dash cams and telematics catch risky driver behavior events in real time and provide trending data to help prevent accidents. This lets you identify problem drivers and implement targeted coaching programs. Safer drivers mean fewer accidents, which translates to satisfied insurance companies.
  • Fewer breakdowns: Real-time engine diagnostics keep you ahead of the curve. Imagine catching a potential issue before it leaves your truck stranded on the side of the road. Maintenance not only reduces downtime but also minimizes the risk of accidents caused by mechanical failures. Less risk means insurers are more likely to see you as a safe bet.
  • Data-driven decisions: Finally, you have the data you need to make smart choices. Analyze trends, identify areas for improvement, and make informed decisions about everything from driver training to route optimization. Demonstrating a commitment to safety through data could potentially lead to better insurance rates.

See also: AI and a Vision for Safer Roads

Managing a fleet is tough. Don’t let data silos make it even harder. By implementing a unified fleet management platform with AI dash cams, you can gain the insights you need to prove your commitment to safety to your insurers, improve driver behavior, and create a safer, more efficient, and cost-effective fleet.


Erin Gilchrist

Profile picture for user ErinGilchrist

Erin Gilchrist

Erin Gilchrist is vice president of fleet evangelism at IntelliShift.

She brings 15 years of experience from Safelite AutoGlass, where she managed a fleet of more than 8,500 vehicles. A long-term member of the Automotive Fleet Leasing Association, she advocates for fleet leaders through her podcast, "Straight Talk on Fleet." 

The Growing Toll of Secondary Perils

Parametric reinsurance offers a new approach to managing the increasing threat of secondary perils, providing much-needed financial protection for insurers.

stormy weather

Property insurers have always needed to watch out for large losses that shock their balance sheets. Historically, the insurance industry has considered catastrophes the largest threats. Today, however, property insurers face an existential threat from another source: skyrocketing losses caused by secondary perils. In fact, secondary perils—led by severe convective storms—have surpassed catastrophes as the leading cause of insured loss.

Severe convective storms (SCS) are localized events accompanied by lightning, thunder, strong wind gusts, intense rainfall, and, in some instances, hail. An analysis by Aon found that from 1990 to 2022, U.S. SCS losses increased at an annual rate of 8.9%.

A problem for insurers and policyholders

In 2023, severe convective storms caused $64 billion in insured losses, 85% of those originating in the U.S., according to Swiss Re. This volume of loss in the U.S. alone resulted in ratings downgrades for dozens of insurers, and four companies became insolvent. Swiss Re notes that the fastest-growing category of disaster is medium-severity events, or those causing $1 billion to $5 billion in insured losses. More SCS events are falling into this category.

Options for insurers facing large losses from secondary perils are few but consequential for policyholders. Those options are:

  • Raise rates or deductibles, making coverage unaffordable for policyholders
  • Exclude coverage, reducing protection for secondary perils
  • Withdraw from markets where losses from secondary perils are heaviest

When secondary perils cause company insolvencies, policyholders can lose access to insurance coverage. That leads to serious economic consequences for individuals, businesses, and communities.

See also: Blind Spots in Catastrophe Modeling

Traditional reinsurance isn’t solving this problem

For catastrophe losses, insurers have a ready source of financial protection in reinsurance. Insurers already buy catastrophe reinsurance because they’re required to have it—but catastrophe reinsurance doesn’t cover the effects of the accumulation of losses associated with much more frequent secondary perils.

Traditional reinsurance is not solving the problem of secondary perils because it is generally not available for the aggregation of such losses. At one time, reinsurers offered aggregate cover but could not write it affordably within their risk appetite.

Another reason reinsurers have avoided covering secondary perils at scale is the limitation of catastrophe models. Cat models have evolved significantly since the early 1990s, and they work well for low-frequency, high-severity events—such as one-in-250-year and one-in-500-year events. These models have proven unsuitable for high-frequency, lower-severity events. Many secondary perils are one-in-five-year or one-in-10-year events.

Without reinsurance to spread the risk of secondary perils, insurers have had no real financial option, until now.

See also: Litigation Risks in 2024 and Beyond

A path forward to keeping property coverage available

The high loss frequency of sub-catastrophic events—that is, lower- to medium-severity secondary perils—makes traditional risk transfer solutions untenable. At the same time, paying steady volumes of high-frequency, lower-severity losses is unsustainable. For these reasons, a new approach to reinsuring secondary perils is needed.

One such solution is parametric reinsurance. Parametric risk transfer is a useful tool that is becoming more common for primary insurance risks, from personal travel to crop damage. The mechanics of parametric coverage are relatively simple: Based on defined parameters that can be reliably measured (examples include flight delays or cancellations, or a certain level of rainfall or hail in a defined period), an agreed amount of coverage is triggered when those parameters are met. There is no need for loss adjustment and the additional costs that process entails. Parametric insurance benefits the buyer as well as the capital provider by providing certainty and efficiency in transferring risk.

Until recently, however, parametric solutions have not been used in the context of reinsurance. Parametric reinsurance uses sophisticated modeling to assess secondary peril risks, but not in the same way that catastrophe models do. Its model does not predict specific events. Instead, it uses firsthand claims data from an insurer and verified historical weather data to estimate the likelihood of aggregate losses in a given year for that insurer.

The parametric reinsurance solution’s trigger, therefore, is not a single event but an aggregate dollar amount of modeled losses. Parametric insurance models secondary peril losses on the specific weather ingredients that generated historical claims on covered properties. In this way, the parametric solution resembles excess-of-loss reinsurance. This scalable solution is available at different attachment points, subject to the protection needs and budget of the insurer. For example, if a property insurer has an expected aggregate SCS loss of $100 million, it can buy parametric coverage that attaches at a point that makes economic sense for the insurer. 

This innovative solution fills a need that can keep insurance available for high-frequency, high-severity types of losses, on a portfolio basis.


Bill Clark

Profile picture for user BillClark

Bill Clark

Bill Clark is the CEO of Demex, a risk analytics and intelligence company offering reinsurance solutions for severe convective storms. 

He previously held executive roles at several technology companies, including Silicon Valley start-ups and firms backed by private equity. Clark also spent time with industry heavyweights JP Morgan and IBM. 

He was a professional tennis player before embarking on his corporate career.

Balancing AI Innovation With Consumer Protection

Regulators in the EU and U.K. want insurers to balance AI's potential with protecting consumers from potential bias and harm.

finding balance

The regulatory challenge around artificial intelligence (AI) is as broad as its potential applications. In response to the scale of the task ahead, the U.K. government’s white paper "A Pro-Innovation Approach to AI Regulation," published last year, emphasizes fostering and encouraging innovation. The ambition is clear: to create an environment that enables businesses to develop and invest in AI while protecting businesses and consumers from potential harms and some of the worst excesses of the technology.

Regulation today

Currently, AI is indirectly regulated in the U.K., meaning there are no specific U.K. laws designed to address AI. Instead, a range of legal frameworks are indirectly relevant to the development and use of AI.

AI systems fundamentally rely on large amounts of data to train the models that underpin these systems. Personal data is often used to develop and operate AI systems, and individuals whose personal data is used have all the normal rights under existing laws such as the General Data Protection Regulation (GDPR). These typically include rights of transparency, rights to data access, and, perhaps most importantly, existing rights under GDPR not to be subject to automated decision-making in relation to significant decisions, except under special circumstances.

Impact on insurance

The current approach to AI regulation in the U.K., as outlined in the government's white paper, relies heavily on existing regulatory frameworks. Particularly relevant for the insurance industry is financial services regulation and the role of the Financial Conduct Authority (FCA) and Prudential Regulation Authority (PRA).

The FCA and PRA will use their existing powers to monitor and enforce against the misuse of AI, applying existing principles such as consumer protection and treating customers fairly. These principles might be affected if an insurer relies on an AI system and predictive models to make pricing decisions.

Because there is a risk that some customers might be discriminated against or priced out of insurance markets through the increased use of AI, the FCA is carefully considering how to translate existing principles when regulating firms in the use and misuse of AI.

See also: Balancing AI and the Future of Insurance

Embracing the future

Most companies accept that it won’t be possible to hold back the tide of AI. As such, many leading businesses are already focusing on how to integrate AI into their operations and apply it to their existing business models, recognizing the need to embrace rather than resist change.

In the insurance industry, not all of this is new. For many years, insurers have used algorithms and machine learning principles for risk assessment and pricing purposes. However, new developments in AI make these technologies increasingly powerful, coupled with the explosion in other forms of AI, such as generative AI, that are more novel for insurance businesses. Consequently, a key challenge for the industry is adapting and upgrading existing practices and processes to account for advancements in existing technology while also embracing certain innovations.
Regulation tomorrow

The EU AI Act is one of the world's first comprehensive horizontal laws designed specifically to focus on the regulation of AI systems, and the first to command widespread global attention. It is an EU law, but importantly, it also has extraterritorial effect. U.K. businesses selling into the EU or using AI systems where the outputs affect individuals in the EU are potentially caught by the law.

The EU AI Act applies to all parts and sectors of the economy. Crucially, it is also a risk-based law that does not try to regulate all AI systems and distinguishes among different tiers of risk in relation to the systems it does regulate. The most important category of AI system under the act is high-risk AI systems, where the vast majority of obligations lie.

Most of these obligations will apply to the provider or developer of the AI system, but there are also obligations that apply to the system’s user or deployer. The insurance industry is specifically flagged in the EU AI Act as an area of concern for high-risk AI systems. The act explicitly identifies AI systems used in health and life insurance for pricing, underwriting, and claims decision-making due to the potential significant impact on individuals’ livelihoods.

Because the majority of the obligations will sit with the system’s provider, businesses building their own AI tools—even if those tools depend on existing models such as a large language model to develop an in-house AI system—will be classified as a provider of that AI system under the act.

As a result, businesses will need to understand the new law, first determining in which areas they are caught as a provider or deployer, before planning and building the required compliance framework to address their relevant obligations.

The regulation of AI had one brief mention in July’s King’s Speech, specifically in relation to the establishment of requirements around the most powerful AI models. This means the EU AI Act is the most pressing law on AI likely to be applicable to insurers in the coming years. Other relevant parties, such as the Association of British Insurers (ABI), have provided guidance to their members on the use of AI.

See also: Two Warnings About AI

Navigating AI

For the insurance industry and other sectors to make the most out of AI, businesses will first need to map out where they are already using AI systems. You can only control what you understand. Similar to when businesses first began their GDPR compliance programs, the starting point is often to identify where within the organization they are using personal data and, in particular, where they are using AI systems that are higher risk because of the sensitivity of the data they're processing or the criticality of the decisions for which they are being used.

Once the mapping stage is complete, organizations should then begin the process of building a governance and risk management framework for AI. The purpose is to ensure clearly defined leadership for AI is in place within the business, such as a steering or oversight group that has representation from different functions, articulating the business's overall approach to AI adoption.

Organizations will also need to decide how aggressive or risk-averse they want their business to be regarding the use of AI. This includes drafting key policy statements that will help clarify what the business is prepared to do and not do, as well as defining some of the most fundamental controls that will need to be in place.

Following this, more granular risk assessment tools will be needed for specific use cases proposed by the business that can be assessed, including a deeper dive into the associated legal risks, combined with controls on how to build the AI system in a compliant way that can then be audited and monitored in practice.

The approach a business takes will also depend significantly on whether they buy their AI systems from a technology vendor or instead buy the data they need for their own in-house AI system, as well as potentially selling AI to their own customers at the other end of the pipeline. An insurance broker, for example, might sell certain services to an insurer that depends on the use of AI and will therefore need to consider how they manage their risk at both ends of that pipeline in terms of the contracts, the assurances they get from their vendors, and whether they are prepared to give the same assurances to their customers.

The challenge with AI at present is that use cases are continuously emerging, so demand is increasing. Therefore, the creation of governance frameworks and processes needs to be designed alongside the business processes to assess and prioritize the highest-value AI activities and investments. Governance, business, and AI teams need to work side-by-side to embed appropriate processes within the emerging use cases, which can often save significant work later.

The EU AI Act is a complex piece of legislation and will be a significant challenge to construct the frameworks needed. Success will not only rely on the quality of data and models used and good governance but also on adopting an approach to the new law that is proportionate and builds confidence to enable businesses to make the most of future AI opportunities.


Chris Halliday

Profile picture for user ChrisHalliday

Chris Halliday

Chris Halliday is global proposition leader for personal lines pricing, product, claims and underwriting at WTW's Insurance Consulting & Technology business.