Download

How Business Rules Engines Can Slash Time to Market

The systems streamline the management of business rules, letting insurers adapt swiftly and efficiently without the need for intervention by IT. 

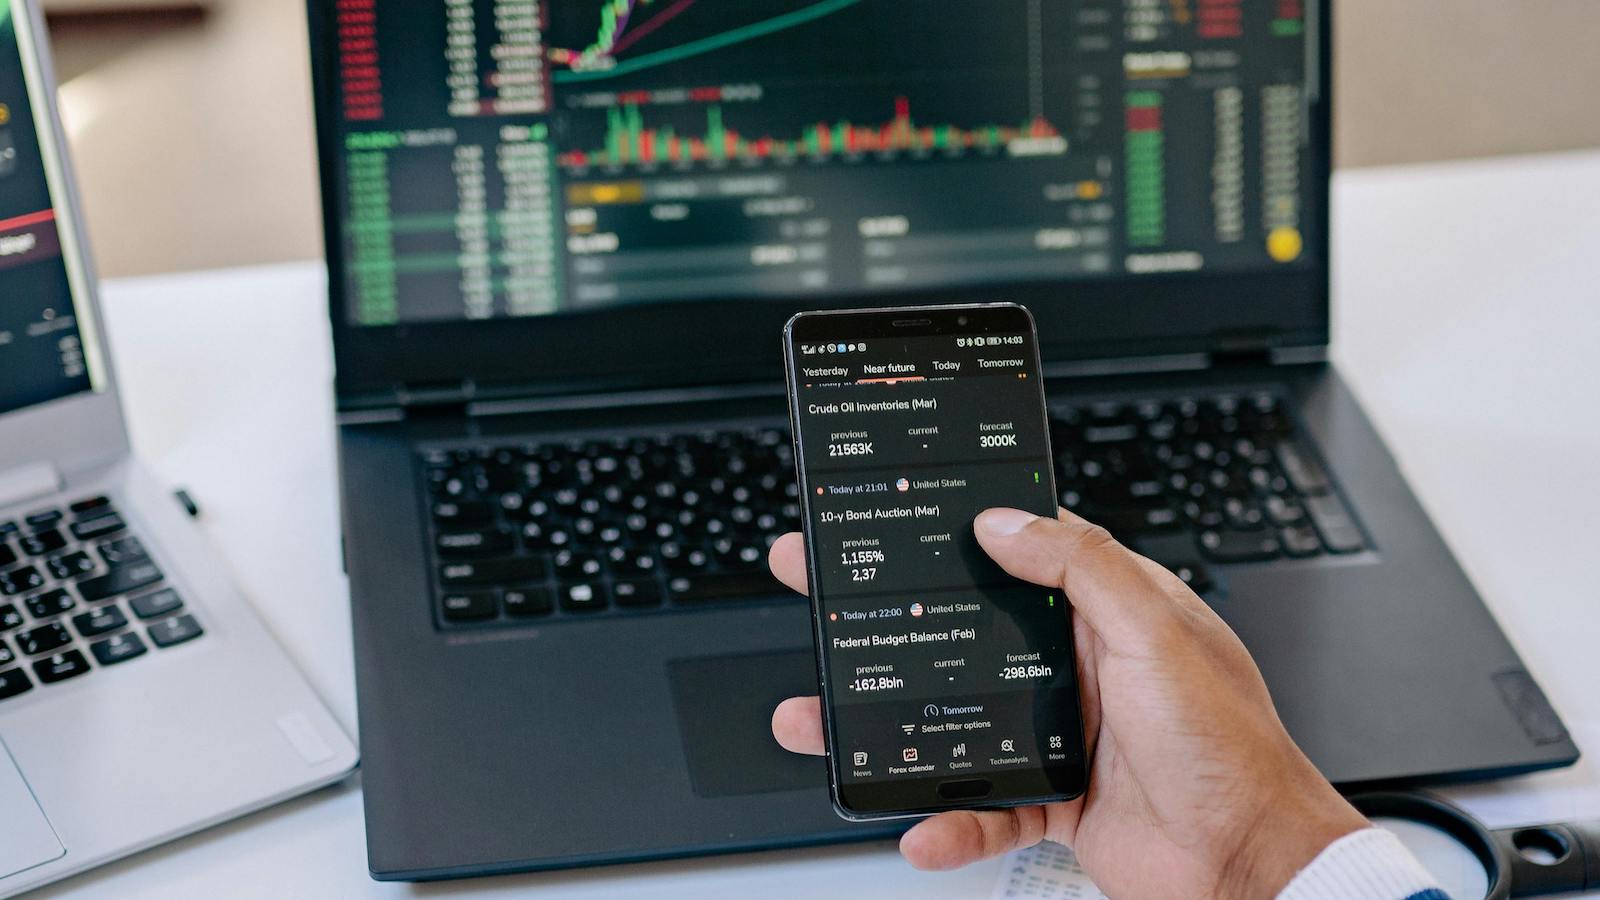
Person Using Smartphone and Laptop

Business rules are the backbone of decision-making in the insurance industry, guiding everything from claims processing to policy pricing and compliance. However, updating and managing these rules is often cumbersome and time-consuming, leaving many insurers struggling to keep up with market demands and regulatory changes.

This is where business rules engines (BREs) come into play. These systems streamline the management and execution of business rules, enabling insurance companies to adapt swiftly and efficiently. By introducing automation and flexibility into their core operations, insurers can respond to market shifts, regulatory changes, and customer needs with unprecedented speed and accuracy.

Let’s dive deeper into what a business rules engine is, how it works, and why it's becoming an indispensable tool for insurance companies. 

See also: Automated Underwriting: A New Era of Work

Traditional Approach to Business Rules Updates

The traditional approach to managing business rules relies on embedding the logic directly within the application code. This means that even the simplest change requires the IT department to locate the relevant section of code to implement updates. This method comes with significant risks:

  • Dependency on IT – Every change requires IT intervention, slowing the process and leading to potential bottlenecks.
  • Lack of Centralization – Business rules are scattered across the codebase, making it difficult to maintain a single source of truth.
  • High Risk of Errors – The absence of a centralized rule repository means different versions of the same rule can exist, raising the likelihood of mistakes.
  • Time-Consuming Updates – Implementing changes is a lengthy process, which hampers a company’s ability to respond quickly to market.

The Benefits of a Business Rules Engines

A BRE can be thought of as a product configurator, allowing non-technical users to manage and modify business logic without needing to know how to code. This makes it especially valuable for insurance companies, where business rules must be updated regularly due to changes in regulatory policies, market conditions, or customer needs. By using a BRE, insurers can respond quickly and efficiently to these changes without depending on IT.

There are many different BREs on the market, including our Higson solution, which provides an intuitive, modern studio interface and reflects the client's business structure, giving nontechnical users easy access to the rules they need to manage.

Using a business rules engine drastically reduces the time to market. Instead of waiting weeks or even months for IT to locate, update, and test rules embedded in application code, business users can make necessary adjustments directly in the BRE.

Use Cases for Insurance 

Tariff Adjustments

Traditionally, updating insurance tariffs involves multiple teams and IT intervention and can take weeks. With a BRE, business users can update premiums in hours. 

Underwriting Automation

A BRE can partially automate underwriting decisions for standard policies, leaving underwriters to focus on more complex cases. For instance, rules engines can automatically approve life insurance applications that meet predefined risk criteria, while flagging higher-risk cases for manual review. 

Product Offer Adjustments

For one of the major insurance companies in Poland, managing the introduction and adjustment of complex insurance products across various channels was a challenge. The process involved manual updates to product configurations and pricing models and regulatory compliance checks, making it slow and prone to errors.

By leveraging a BRE, the insurer was able to automate and centralize product offer management. The BRE enabled business users to quickly configure new insurance products, adjust existing offers, and ensure regulatory compliance without IT intervention.

See also: Business Models, Product, Value-Added Services

Conclusion

BREs provide a highly efficient solution for insurance companies, offering a way to significantly reduce the time required to introduce products. They empower business users by allowing them to manage and adjust business logic. Moreover, the flexibility of a modern BRE means it can seamlessly integrate with existing systems. 

BREs shift the approach managers and analysts take when dealing with complex business logic. Instead of relying on rigid, generalized rules, BREs allow companies to experiment with different scenarios and implement changes in real time without high costs or  dependencies on IT teams. Developing new tariffs or product updates need no longer be a lengthy, IT-heavy process. With a rules engine, you can quickly adjust and test market behavior, pulling back changes that don’t work and moving forward with those that do.

What Agencies Miss About the Power of Design

Cake & Arrow CEO Josh Levine says it's crucial for agencies to design experiences for agents, not just for customers, by simplifying the web of systems they must use. 

Josh Levine

Paul Carroll

I’ve long been a big believer in the power of design. My history with writing about technological innovation goes back far enough that I interviewed some of the original designers of the Macintosh computer, then watched as its ease and elegance let it outclass the computers built based on the standard set by the then-all-powerful IBM. Over the years, people have been learning that design considerations are powerful far beyond branding and individual products, which is why I wanted to talk to you about the design work you’re doing with insurance agencies.

Josh Levine

In insurance, people tend to think about design in terms of the user experience with consumer-facing apps and websites. Very rarely do people think of the agent experience or the broker experience or the employee experience. Most internal systems are overlooked, or at least are not top of mind. So agents wind up working with various carriers and being stuck learning and navigating these cumbersome systems.

We've been around for quite a while, and a lot of the original work, particularly 10 or 12 years ago, was with carriers. The work was mostly related to direct-to-consumer, claims tools, and all that. But over the last five or six years we’ve seen that start to shift. Now, about half of our work is focused on what I call the agent experience or the broker experience. 

And that’s a big shift. It shows that the industry is starting to recognize something pretty important: When agents and brokers and other internal users have good tools, it doesn’t just make their lives easier. It makes them more efficient, keeps them loyal, and ultimately leads to better outcomes for the end customer.

The question is: How do you leverage design to make it easier for them to do business, plain and simple? How does one use design like Apple did, to make these systems kind of filter into their lives and feel natural? How do you design the stuff that people do on a daily basis?

This new emphasis on design for internal tools is refreshing. It’s a healthy shift because, while every agent and broker is familiar with well-designed consumer products—like their Apple Watch—they’re not necessarily clamoring for better interfaces at work. They’re not out there demanding, "We need better design!" But it’s encouraging to see more agencies and brokerages recognizing the value of better-designed tools and starting to focus on this need.

Carriers are finally starting to see that design and user experience are ways for them to differentiate themselves with agents and brokers, to be the carrier of choice. 

Paul Carroll

I published an article not long ago about the talent gap that has so many people worried, with so many senior people retiring and with seemingly too little enthusiasm among younger people about taking their spots. The article said the best way to find new talent is to stop scaring it off through the sort of profusion of complex systems you’re talking about. 

Josh Levine

We do a lot of research. We spend a lot of time researching and observing agents at work, watching the challenges they go through to get a policy issued or to process a claim. It almost feels like the complexity is intentional. Obviously, it’s not. It's no one's fault. It's the nature of a non-design-driven industry. You end up with these clunky, disconnected systems that don’t talk to each other—basically, the opposite of the seamless experience we’ve come to expect from well-designed products. It’s what happens when systems get built in silos over the years.

And you can’t expect the younger generation to use these old tools. They simply won't. Modern design is table stakes. Tools don't need to be game-breaking, but they need to make people’s jobs easier. The intersection of design and the business of insurance, how things get sold and how things get serviced, is so, so critical for recruiting and retaining younger talent.

Paul Carroll

Beyond the haphazard nature of the development of the systems agents and brokers use, are there other impediments to a design focus? 

Josh Levine

The big, obvious misconception is that these tools are only about data entry—like all agents and brokers need to do is plug in information as fast as possible. But the reality is, these tools need to support more consultative work. You’re dealing with agents and brokers with a huge range of experience: Some have been in the industry for decades, while others are just starting out. Then you have assistants, junior agents, specialists—each with their own role and level of expertise. Good design needs to accommodate all of them, making it easy for anyone to find what they need, work efficiently, and provide value to their clients. It’s not just about speed; it’s about designing tools that adapt to different workflows, experience levels, and needs.

That's where digital can play an incredible role. Some of this is just common sense, like giving a broker or an agent immediate feedback rather than asking them to answer 75 underwriting questions only to then say, “Oh, nope, not eligible.” 

So the big question is, how do you create a real dialog with agents and brokers? How can you use digital and design to give them insights? And for those newer to the industry, how do we layer in coaching and training to help them understand the nuances of the products they’re working with? The goal is to guide agents and brokers at every stage, whether they're seasoned pros or just starting out, making sure they’re equipped not just to enter data but to provide value to their clients in ways that feel natural and informed.

There are a lot of best practices for how to go about this. And there is a lot you can do to facilitate more collaboration—not just in the sense of multiple people working on the same job, but in creating tools that let agents ask questions and get feedback within their organization. You want to create the sort of environment you have when you’re sitting with someone and having a dialog, and you're saying, “No, no, stop right there. We can't write this. This won't be a good fit,” or, “Talk to Johnny over there.” Digital tools can mimic this experience by building in components that let people interact, ask questions, and share insights naturally. It’s about designing systems that encourage the same kind of helpful, real-time exchanges agents would have in person.

But the core systems out there are missing that layer of user experience, of agent experience, of customer experience. Humanizing the agent/broker experience is such a huge opportunity to move the industry forward. We obviously talk a lot about customer experience. But the customer experience and employee experience are connected. You can’t have a great customer experience without a great employee experience, right?

The CSRs [customer service representatives] need to know the right things to say and have the right tools. The agents need the right tools. They need to have the right education, they need to be equipped, or you're not going to be able to deliver on this great customer experience everyone's talking about.

Paul Carroll

You remind me of my early days on the copy desk at the Wall Street Journal. I was all of 22 years old, but I was surrounded by institutional knowledge. “Hey, George, how do we handle this?” “Hey, Joe….”

Josh Levine

You have to engage with the realities of the day-to-day work of agents and brokers. If they prefer using email or other digital apps and tools, you have to factor that into the digital experience you are designing, or they won't adopt it. 

At the end of the day, they have to be able to do business and sell. They’ll either use your tool as intended, or they’ll find workarounds to bypass it. Getting the design right is challenging, but it’s essential if you want them to fully engage with the tools you provide. 

Our first client was MetLife, and they actually flew us out to Japan to meet with folks who were just so passionate about helping the next generation of agents. These senior people had been agents at one time, but that was 10 or 15, or even 20 or 30 years ago. Being such an expert in this very complex, nuanced industry is an amazing thing, but the knowledge can also be a curse. The senior people make assumptions about the tools the younger people need and the features they’ll want, and how they use them. And the reality is that it's just a different world.

Our goal is to dismantle these assumptions by considering the “why” before the “what.” Through direct research with agents, we can avoid spending two years investing in a platform only to discover that agents won’t use it.

Paul Carroll

This is great, Josh. Thanks so much.


Embedded Insurance: A Major Disruptor

About Josh Levine

josh levine headshot

Josh Levine is the founder and CEO of Cake & Arrow, an experience design and product innovation company that works exclusively with insurance companies to create digital products and services that transform how insurance is bought, sold, and serviced.

With a career spanning over 25 years, Josh is a seasoned practitioner of human-centered design, digital product strategy, and design thinking. Since founding Cake & Arrow in 2002, Josh has led innovation and design initiatives for more than 40 of the most prominent carriers, distributors, and insurtechs—including MetLife, Travelers, Aflac, Chubb, Amwins, American Family, and Unqork.

A designer by trade, Josh inspires insurance companies to embrace design-driven mindsets and build meaningful relationships with the customers and employees they serve. He’s motivated to help traditional organizations unleash the humanity in their business and explore new ways of solving old problems.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

Beware the Algorithm!

Lawyers and consumer advocates are demonizing algorithms any time a decision goes against a policy holder. Let's talk about them less. 

Image
algorithm

When I write the Great American Novel about today's political dysfunction, I'm going to call it "They." Because some mysterious, evil "they" sure are causing lots of problems — pick just about any complaint about anything you don't like in the U.S. these days, and "they" are causing the problem. "They" will make a great villain for my book. 

When I write the sequel, about the insurance industry, I'll call it "The Algorithm." Because, to look at how consumer advocates are using the term to villainize any decision they don't like, we may have another "they" on our hands.

In the meantime, I suggest that, even amid all the excitement about generative AI, we talk far less about the great algorithms we're creating and put a human face on everything we do. 

The thought about how algorithms are being used to demonize insurers crystallized for me when I saw this headline on a recent press release: 

"Insurance Commissioner Finalizes Plan Allowing Secret Algorithms to Raise Home Insurance Rates; Lies About Making Insurers Sell More Coverage in Return, Says Consumer Watchdog."

Now, I'm not sure that the California insurance commissioner isn't using some spin when he describes how insurers will have to commit to offering coverage for a certain number of vulnerable homes, in return for the right to use predictive modeling and not just historical data in their underwriting.

But the notion of 'secret algorithms" is a straight-up scare tactic. We're basically supposed to imagine that the Terminator has traveled back through time and just landed among us. 

The use of predictive models is thoroughly standard these days, across industries, but I suspect that consumer advocates, lawyers, and anyone else with a beef with an insurance company will lean into the specter of evil algorithms for some time. 

AI advocates talk a lot these days about going even beyond generative AI to what's known as artificial general intelligence, or AGI — AI that isn't just relegated to a specific task but has truly human intelligence. The advocates talk glowingly about the prospect, but some experts think humanity could be innovating its way out of existence — and we all remember how HAL turned out in "2001: A Space Odyssey."

Insurers are doing all the responsible things, thinking about biases that can creep into AI and providing as much insight as possible into how machine learning makes decisions, so they don't just come from a black box. 

Still, I'd suggest not talking about algorithms, AI, or machine learning except in a situation where there is a clear benefit to the consumer. 

"We're using AI so we can automatically approve your policy submission." 

"We're paying your claim super-fast because of our algorithms." 

"We're using machine learning so our chatbots are so smart they can answer all your questions at any hour of the day or night." 

But I'd make clear that any decision to turn down a policy submission or claim or to raise a rate was made by a human, based on all sorts of traditional, explainable criteria. And I'd make sure customers know that any confusion with a chatbot means a query is immediately kicked to a living, breathing person. 

Because if we were to link adverse outcomes to algorithms, "they" could have a field day. 

Cheers,

Paul

P.S. My favorite Dad joke goes like this:

Q. How do we know that Al Gore invented the internet?

A. Because it relies on Al-Gore-ithms.

Ba-dum-bum.

What AI Means for Compliance

In this Future of Risk interview, RGA's Casey Beckman explains how AI can drastically improve monitoring -- but brings with it a new set of risks. 

Casey Beckman Future of RIsk


casey rga headshot

Casey Beckman is Vice President, Global Compliance and Fraud, for RGA. She is a highly skilled financial services compliance professional with over 20 years of experience in building and transforming compliance and risk programs for global companies. Casey joined RGA in 2016 and leads the vision, strategy, and execution of the compliance operating model for RGA’s global operations. Before joining RGA, Casey held various compliance roles for Aegon/Transamerica, a leading provider of life insurance, retirement, and investment solutions. Casey earned a bachelor’s degree in business administration and management from Mount Mercy University, and an MBA from the University of Phoenix.


Paul Carroll

Casey, thank you for joining me today. Would you share a bit about your role at RGA and your overall industry experience?

Casey Beckman

I’ve been with RGA for eight years, and I’m currently RGA’s global chief compliance officer. I have been in the compliance field within the insurance industry for over 20 years. Prior to RGA, I worked at Aegon/Transamerica for 17 years and held various compliance roles both on the insurance side as well as the asset management side. I have experience in leading all aspects of a global compliance program, including artificial intelligence governance, financial crimes monitoring, economic sanctions compliance, code of conduct policy compliance, regulatory change management, compliance assurance testing, and directing investigations.

Paul Carroll

Based on your experience, what do you see as a major risk trend for the insurance industry?

Casey Beckman

The use of artificial intelligence comes to mind. This emerging risk has been impossible to ignore as we continue to use AI in both our personal and work lives. Along with this use comes an increase in compliance and ethical concerns such as data protection, AI transparency, and explainability, and mitigating biases that AI could create. It's important to remember that AI was built by humans and is susceptible to flaws and errors. 

RGA currently has an AI governance strategy project underway to ensure we have appropriate controls and governance over the use of AI to mitigate risks posed by AI. The project team includes various business leaders, data scientists, experts in AI technology, risk management, compliance, and legal. I can’t stress enough how important it is that organizations acknowledge that AI risk is owned by everyone, and everyone has an obligation to use AI responsibly. 

Paul Carroll 

What role can AI, data analytics, and emerging technologies play in mitigating compliance risks related to fraud, cybersecurity, and other areas?

Casey Beckman

I think AI will significantly impact how compliance teams monitor risks. 

AI has the ability to analyze a large amount of data and can quickly identify patterns and anomalies that can help with suspicious activity detection, whether it be financial transaction patterns or monitoring for cyber threats.

AI can also help with:

  • Sanctions screening that could help reduce and clear false positives.
  • Knowing your customer, to help determine if there are high-risk clients that would require additional due diligence or monitoring. 
  • Overall compliance program health, such as metrics and reporting on key performance indicators (KPIs).
  • Streamlining compliance processes, such as policy creation and maintenance, policy monitoring and adherence, and control development and assurance.
  • Assisting with investigations, including performing data analytics.
  • Gathering information, including from unstructured sources such as notes on paper or in PDFs and from audio and video, whose review has historically been extremely time-consuming. 
  • Crafting reports, at least by providing a rough draft that provides a substantial starting point for the compliance officer.

Paul Carroll

How is the evolving AI regulatory landscape across global markets affecting risk management practices and compliance requirements?

Casey Beckman

We are beginning to see more momentum from regulators in this space, however, there are still many regulators that have yet to propose or enact regulations. Risk and compliance professionals need to ensure that any AI governance framework being developed is agile enough that as new regulations come out, the governance framework can adapt quickly to new requirements. 

Paul Carroll

What skills and mindsets will risk and compliance professionals need to develop to stay ahead of rapidly evolving AI risk facing the insurance industry?

Casey Beckman

Knowledge is power! There are obvious things like attending conferences, obtaining AI governance certifications, and building your network, which can help you stay ahead, but it’s also important to not lose sight of the fact AI governance is a team effort. It’s important to stay connected to your business leaders, research and development teams, data scientists, IT teams, etc. to align with your organization’s AI strategy to ensure the governance continues to mitigate the risks as AI evolves. Just like being agile with the regulations, the governance also must be agile and align with your organization’s AI strategy goals.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

How to Navigate Social Inflation

Facing increasingly complex claims, insurers must modernize, shift their cultures to prioritize efficiency and empathy, and seek legal reforms. 

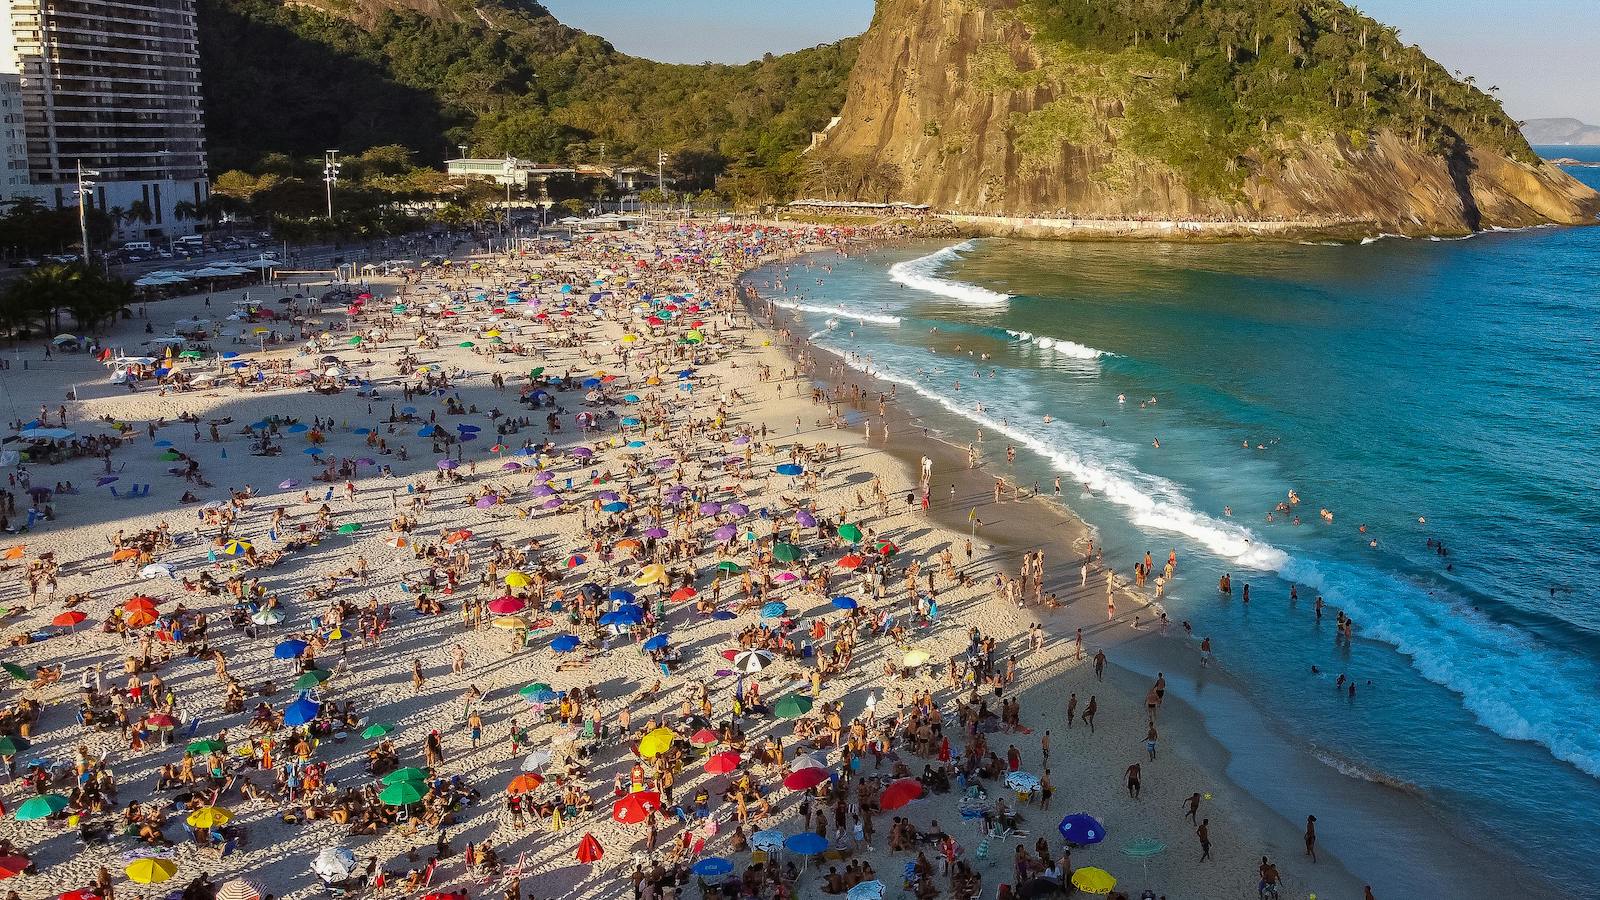
Crowd on Beach

As social inflation continues to exert pressure on the insurance industry, this is not only a financial issue, but one with far-reaching impacts on insurers, beneficiaries, and society at large. 

Rising litigation costs, evolving societal expectations, and increasingly complex claims are not isolated challenges — they are part of a larger wave of change. To meet these challenges, insurers must explore changes across the board, from modernization efforts  to reforms within the legal system itself, to cultural shifts that prioritize efficiency and empathy. 

Social inflation refers to the upward trend in insurance claim costs driven by a combination of legal and societal factors, distinct from traditional economic inflation. Unlike economic inflation, which reflects changes in the cost of goods and services, social inflation stems from a broader set of influences, including increased litigation frequency, escalating jury awards, evolving societal expectations of corporate responsibility, and changes in legal practices. 

This phenomenon has become particularly pronounced in sectors such as life and liability insurance, where claim valuations have seen a significant rise. Legal frameworks that permit extended litigation and large punitive damage awards are key reasons. 

Additionally, the growing influence of litigation funding and the public’s increased scrutiny of corporate practices have intensified the financial pressures faced by insurers. 

The rise in costs associated with social inflation is not merely a result of higher claim values but reflects a fundamental shift in how claims are processed and contested. 

See also: Social Inflation and Reserve Development

According to a recent report from the Swiss Re Institute, the surge in large court verdicts has driven a 57% increase in liability claims in the U.S. over the past decade, with social inflation peaking at 7% annually in 2023. Jurors and courts are increasingly awarding higher compensation as a reflection of societal demands for fairness, justice, and accountability in corporate behavior. This shift has led to more frequent and higher cost claims, particularly in cases where punitive damages are involved. According to Swiss Re, legal expenses in the U.S. are rising at a rate that surpasses economic inflation, signaling an urgent need for the insurance industry to adapt. 

Addressing social inflation requires a multidimensional strategy that goes beyond cost control and delves into structural reform. This includes revisiting legal frameworks that contribute to protracted litigation and higher settlement costs. The existing system often delays claim resolutions, leading to elevated legal expenses that ultimately increase premiums for policyholders.

Implementing legal reforms, such as caps on damages or streamlined litigation processes, could help mitigate the financial pressures on insurers and improve the overall efficiency and fairness of the claims process. 

In addition to necessary legal reforms, a fundamental shift in corporate culture is imperative. Insurers must adopt a framework of enhanced transparency and prioritize the customer. This entails not only optimizing the claims process but also improving communication channels and transparency with policyholders and beneficiaries. 

Gianfranco Lot, Swiss Re’s chief underwriting officer, P&C Re, highlighted the severity of the issue, noting that U.S. liability lines exposed to bodily injury claims have incurred cumulative underwriting losses of $43 billion over the past five years. This has led to a significant decline in available capacity for global businesses, with rate increases failing to keep pace with escalating loss trends. 

See also: Social Inflation: Decades of Insurance Litigation Abuse

The integration of automation and data analytics can significantly enhance both efficiency and transparency. These technologies allow carriers to better leverage data, improving the prediction of claim trends, risk assessments, and process optimizations. As a result, claims can be handled more quickly, with fewer errors, and beneficiaries can receive real-time updates. 

Given the escalating underwriting losses and increasing litigation costs faced by insurers, technology must be leveraged as a crucial component of a broader strategy to address these challenges. While technology alone cannot resolve systemic issues, its role in reducing operational costs and enhancing data accuracy is vital. 

As social inflation intensifies, the industry is faced with implementing a multifaceted strategy encompassing both internal and systemic reforms. Legal changes, corporate transparency, and technological advancements must collectively contribute to a more  equitable and efficient claims process. Insurers adept at integrating these elements will be better positioned to manage the complexities of rising claim costs while upholding their obligations to beneficiaries. 

To learn more, you can download this white paper from Benekiva.

Managing Loss Control With Location Intelligence

By combining historical aerial imagery, property condition data, and AI, insurers can optimize underwriting, inspections, and fraud reduction.

Wrecked Home Furnitures Interior

Managing loss control has never been more critical for maintaining property risk. Insurers face rising claim frequency, escalating weather events, and the need for more effective loss control measures. Traditional methods, like in-person inspections, often fall short, leaving insurers vulnerable to unnecessary losses and inflated payouts.

The good news? More insurers are adopting technology to change these outcomes. Enter location intelligence. 

By combining historical aerial imagery, property condition data, and AI, insurers gain the insights they need to optimize underwriting, inspections, and fraud reduction—and ultimately improve loss ratios.

A Common Challenge: Roof Condition Visibility

Inaccurate or outdated property condition data can cripple insurers' ability to accurately assess and price risk and manage claims. Consider Frederick Mutual Insurance Co. (FMIC). Initially, FMIC struggled with roof claims due to a lack of clear visibility into property conditions across its portfolio. Without property intelligence based on current imagery or reliable property data, the company relied heavily on inspection teams to verify roof conditions—an approach that was time-consuming, costly, and resource-intensive while not providing visibility on roof condition.

This challenge isn’t unique to FMIC; roof claims continue to be a pain point for the industry. Without a source of truth to determine if a roof was previously damaged—especially after severe weather events—insurers can’t effectively identify fraudulent claims, leaving them exposed. Location intelligence directly tackles this by delivering clearer, data-backed insights into risk.

Seeing Risk Clearly

The combination of new and historical aerial imagery, AI, and property condition data offers a comprehensive understanding of a given property—long before a physical inspection. With these tools, insurers can detect aging roofs, faulty designs, and materials exposed to weather risks, all before these conditions lead to expensive losses and claims. AI-derived detections from imagery and risk scores allow for more detailed damage assessments, enabling insurers to pinpoint hazardous or high-priority areas. This targeted approach not only enhances underwriting accuracy but also strengthens loss control efforts.

Location intelligence also sharpens claims accuracy. By comparing claimed damage against historical imagery and property data, insurers can swiftly identify discrepancies and potential fraud. Inspection processes are streamlined, helping insurers allocate resources to properties that need immediate attention.

FMIC, a Nearmap customer, found success leveraging this approach. The company improved its direct loss ratio by 57% and maintained a 36% average loss and loss adjustment expense ratio over five years. The insights not only helped FMIC reduce losses but also boosted operational efficiency, allowing for straight-through processing of low-risk properties and reallocating resources to complex cases. In essence, FMIC was empowered to write business with greater confidence. 

See also: Crucial Role of Geocoding in Insurance

The Future of Location Intelligence in Insurance

Location intelligence, powered by AI and advanced analytics, will become even more essential for insurers aiming to manage losses and verify claims. It’s also paving the way for improved risk management and better relationships between insurers and insureds. Here’s why:

  1. Risk Mitigation
    Traditional risk assessment methods fall short, especially amid rising construction costs and increasing weather severity. Location intelligence allows insurers to overcome these limitations by identifying properties at higher risk for damage from hailstorms, hurricanes, tornadoes, and floods. Insurers can:
    • Offer more competitive coverage options in high-risk areas by accurately assessing and pricing risks.
    • Implement risk mitigation strategies, such as encouraging property improvements that increase resilience, protect assets, and reduce potential losses, all while making insureds partners in risk management.
  2. Building Trust and Resilience With Policyholders
    No one wants to deal with a major property loss, so when a crisis hits, a fast claims response can strengthen trust between insurers and policyholders. Location intelligence enables this by:
    • Capturing imagery 24-48 hours after a severe weather event and leveraging AI to classify the damage, which accelerates claims verification and can reduce the need for physical inspections.
    • Allowing for quick communication about property damage and streamlined claims payout processes. These are practical, vital ways to help people who may be displaced and need rapid access to resources. 

See also: 'Data as a Product' Strategy

Adopting location intelligence can help insurers make more informed decisions, better manage risks, and deliver a more responsive, customer-focused experience. As the industry grapples with evolving risks, accurate AI, aerial imagery, and property condition data will remain central to building a more resilient future for insurers and their customers.


Dave Tobias

Profile picture for user DaveTobias

Dave Tobias

David Tobias serves as the general manager of insurance at Nearmap.

Previously, he co-founded Betterview, a property intelligence platform for P&C insurers that Nearmap acquired in 2023. Before founding Betterview, Tobias was instrumental in scaling Research Specialist, an insurance loss control company.

10 Most Expensive States for Car Insurance

Rising repair costs and climate disasters force insurers to push auto premiums to historic height, especially in Maryland, South Carolina, New York and seven other states.

map software on smartphone inside vehicle

Car insurance rates have soared in post-COVID years, and despite many insurance industry experts predicting slower rate increases in 2024, data from the first half of the year shows a 15% increase in full-coverage premiums. Industry analysts project a total 22% increase in 2024.

Rate increases in 2024 are largely a continuation from 2023, a year that saw full-coverage premiums rise by 24% in response to insurers' record underwriting losses ($33.1 billion) in 2022. Underwriting losses decreased in 2023 but were still $17 billion.

Additionally, legislative changes in states such as South Carolina and Maryland have increased insurers' financial responsibility, leading them to charge higher premiums. In California, which froze insurance rates during the COVID-19 pandemic, some insurers are requesting double-digit increases as they struggle to return to profitability, while others are exiting the state entirely.

Other Key Findings:

  • The average annual full-coverage premium now costs $2,329.
  • California, Missouri and Minnesota could see car insurance costs increase by more than 50% in 2024. 
  • Maryland has the highest car insurance costs in the U.S., with an average full-coverage rate of $3,400 annually. New Hampshire drivers pay the least, at an average of $1,000 annually.
  • Vehicle maintenance and repair costs have increased by nearly 38% over the past five years, according to the Bureau of Labor Statistics Consumer Price Index. 
  • Increasingly severe and frequent weather events are driving up auto insurance premiums. Hail-related auto claims represented 12% of all comprehensive claims in 2023, up from 9% in 2020, according to CCC Intelligent Solutions.
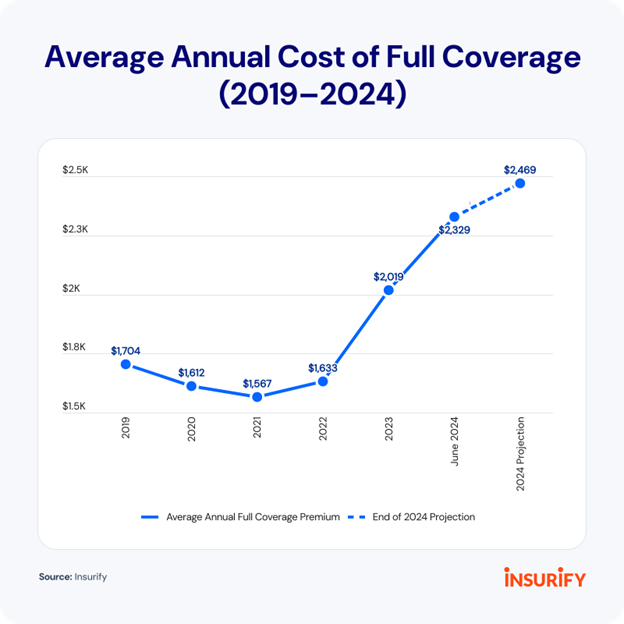
Chart of average annual cost of full coverage

See also: It's Time to Revitalize Auto Insurance

The 10 most expensive states for car insurance

Three of the 10 most expensive states for car insurance — Florida, Michigan and New York — have no-fault systems. In these states, drivers file claims with their own insurance companies to receive compensation for their injuries, no matter which party caused the accident. No-fault systems are supposed to speed claims but have also provided opportunities for insurance fraud.

Other states with sky-high insurance rates, like Florida, Louisiana and Nevada, face weather-related damages from hurricanes and wildfires. While climate risk has historically affected homeowners insurance more than auto insurance, insurers factor in the risk of car damage from hail, wind and falling objects.

Vehicle theft rates, traffic congestion from high population density and an increase in car accidents contribute to higher rates, too. Recent analysis of the 10 most expensive states for car insurance identified the hidden factors affecting policyholders.

Maryland
  • Average annual cost of full coverage: $3,400
  • Percentage higher than the U.S. average: 46%
  • Projected average rate increase in 2024: 41%

Maryland saw an 8.2% rise in motor vehicle crash deaths in 2023, while on average the U.S. saw a 3.6% decline, according to the National Highway Traffic Safety Administration.

New Maryland legislation, effective July 1, requires auto insurers to provide enhanced uninsured motorist coverage. 

South Carolina 
  • Average annual cost of full coverage: $3,336
  • Percent higher than U.S. average: 43% 
  • Projected average rate increase in 2024: 38%

South Carolina ranks 13th in the U.S. for questionable vehicle-related insurance claims, according to the National Insurance Crime Bureau (NICB).

A 2023 South Carolina Supreme Court decision increased financial responsibility for insurance companies, ruling that auto insurers cannot limit property damage claims to just covered vehicles under UM/UIM coverage. Under the new law, insurers must effectively cover all properties registered to the policyholder and their family.

New York 
  • Average annual cost of full coverage: $3,325
  • Percent higher than U.S. average: 43% 
  • Projected average rate increase in 2024: 4%

New York drivers had the most expensive full coverage in the country at the end of 2023 but saw a 1% decrease in the first half of 2024 while rates in other states increased significantly. New York is the ninth most densely populated state in the U.S., which increases the risk of claims. New York also has the highest number of stolen cars, with 32,715 thefts in 2023, NICB data shows. 

Nevada
  • Average annual cost of full coverage: $3,271
  • Percent higher than U.S. average: 40%
  • Projected average rate increase in 2024: 20%

The state had the third-highest vehicle theft rate in 2023, with 572.7 car thefts per 100,000 residents, according to the NICB.

Nevada's rising climate risk could play a large role in future rate setting. Wildfires burn an average of 450,000 acres in Nevada annually, and the state also sees some damage from major storms. .

Florida
  • Average annual cost of full coverage: $3,201
  • Percentage higher than U.S. average: 37%
  • Projected average rate increase in 2024: 18%  

The state's continuing insurance crisis, influenced by severe weather events, has pushed some insurers out of the state entirely, while others have declared insolvency. In 2023, Farmers Insurance stopped offering coverage in Florida, and AAA didn't renew certain home and auto insurance policies. 

Over the past two years, Florida has seen a flurry of legislative activity aimed at reducing frivolous lawsuits against insurers, lowering consumers' insurance rates and mitigating auto insurance fraud. But the no-fault state accounts for 74% of questionable auto glass claims in the U.S., according to the National Insurance Crime Bureau. 

Louisiana
  • Average annual cost of full coverage: $3,182
  • Percentage higher than U.S. average: 37%
  • Projected average rate increase in 2024: 23%  

The state's growing insurance crisis, tied to Louisiana's high hurricane and tornado risks, has mostly affected home insurance. However, the state's climate risk is also beginning to affect car insurance rates, as comprehensive coverage — one part of a full-coverage policy — protects against damages sustained in a weather event. 

Louisiana also saw a 10% surge in vehicle thefts in 2023, according to NICB data.  

Louisiana lawmakers passed a series of auto insurance reforms in 2024. The laws target excessive medical billing in personal injury lawsuits and limit policyholders' time to file an immovable property claim to two years after the policyholder knows (or should know) about the damage. These reforms, aimed at lowering rates, reduce some insurer responsibility. 

Delaware
  • Average annual cost of full coverage: $2,982
  • Percentage higher than U.S. average: 28%
  • Projected average rate increase in 2024: 13% 

The state has the seventh-highest population density in the country, according to U.S. Census Bureau data. 

In one bright spot for policyholders, the Delaware Department of Insurance adopted a regulation in January 2024 requiring insurers to promptly refund any unearned auto insurance premiums (meaning payment for the unused days of coverage after a driver cancels their policy). 

Washington, D.C.
  • Average annual cost of full coverage: $2,977
  • Percentage higher than U.S. average: 28%
  • Projected average rate increase in 2024: 17% 

Washington, D.C., has the highest population density in the nation. The district also saw traffic fatalities increase by more than 40% between 2022 and 2023, according to National Highway Traffic Safety Administration data. 

Premium increases may soon slow in D.C. The D.C. legislature passed a law requiring home and auto insurers to file for prior approval to raise rates. Excessive increases require notice and an opportunity for a hearing. Previously, D.C. had a file-and-use system, meaning insurers could raise rates immediately after filing with the Department of Insurance.

Michigan
  • Average annual cost of full coverage: $2,719
  • Percent higher than U.S. average: 17%
  • Projected average rate increase in 2024: 8%

Michigan adopted a no-fault insurance system in 2019 in an attempt to lessen rate increases. The state saw a 4% increase in full-coverage premiums between June 2023 and June 2024, compared with a 28% rise nationwide, but Michigan still has some of the highest rates in the country.

The Michigan Department of Insurance and Financial Services Fraud Investigation Unit received 3,789 fraud reports between July 1, 2023, and June 30, 2024. 99% were insurance-related, and 50% involved auto and no-fault claims.

Georgia
  • Average annual cost of full coverage: $2,688
  • Percent higher than U.S. average: 15%
  • Projected average rate increase in 2024: 24%

On July 1, 2023, House Bill 221 went into effect, ending the state's file-and-use provision and giving Georgia's insurance commissioner 60 days to review rate filings before insurers can implement increases. Despite the new legislation, Georgia drivers saw a 21% increase in full-coverage costs between June 2023 and June 2024.

See also: Unprofitable Insurance: Tail Effect Hits Auto Lines

States where car insurance is rising fastest

The cost of full coverage across the U.S. increased by 28% between June 2023 and June 2024 — but drivers in some states are seeing year-over-year rate increases of more than 50%.

Minnesota, which saw a 55% increase in rates, experienced $1.8 billion in damage following a series of storms that dropped hail up to baseball size across the Twin Cities in August 2023.

Severe storms also hit Missouri and northwest Illinois in 2023. A supercell produced large hail and heavy rains, forming a tornado as it moved across the states.

North Carolina faces a different weather risk — hurricanes. In 2023, Hurricane Idalia hit the state. While the hurricane weakened to a tropical storm, it still brought damaging high winds, heavy rainfall and local flash flooding. Storms like this cause water damage to cars.

Missouri and California are among the 10 states with the highest auto theft rates per capita. 

California is playing catch-up

The state froze rate increases during COVID, but drivers saw a 45% full-coverage rate surge in the last year.

California is increasing its minimum car insurance requirements. Gov. Gavin Newsom signed Senate Bill 1107 into law in late 2022, doubling and, in some cases, tripling the liability limits for auto insurance policies. The change takes effect Jan. 1, 2025. This means California residents will see higher premiums next year, albeit with higher protection limits. 

California's consumer protection laws keep insurance costs down for policyholders, but it's difficult for insurers to operate profitably. The state's Department of Insurance is slow to approve rate boosts, and insurers have pulled back on writing policies. GEICO has closed all its California offices, State Farm has stopped quoting via phone, and Progressive has halted advertising in the state.

As more insurers leave the state, the department may approve additional rate increases to keep companies in the market.

See also: Modernizing Commercial Auto Insurance

What consumers can do

Consumers can take several steps to manage insurance costs, including comparing rates among multiple insurance companies and asking about available discounts for safe driving, military service, vehicle safety features and multi-vehicle policies. Adjusting deductibles and participating in usage-based insurance programs may also help reduce costs.


A Step-by-Step Guide to Using AI in Insurance

Focus on understanding processes, stakeholder engagement, and controlled testing for meaningful improvements.

stair case ascending to the right

Artificial intelligence can benefit the insurance industry by accelerating work processes, improving customer service and enhancing efficiency. However, many insurance companies struggle with implementation. This guide offers a step-by-step approach to identify and implement AI opportunities effectively.

Understand Company Operations

The first step is understanding organizational workflows. Start by consulting with enterprise architects to review process maps or blueprints of core operations across departments like underwriting, claims and customer service. These visual diagrams show how different units interact and where their workflows connect.

After gaining this overview, examine processes more closely. Look for pain points, especially in areas with repetitive, time-consuming or error-prone tasks. Focus on operations that, if improved, could save time or enhance customer satisfaction.

Select one value chain, department or team as a starting point. Choose a unit with clear challenges or one receptive to innovation. Working with supportive teams often yields better initial results than targeting resistant groups with larger issues.

Engage Front-Line Staff

Consult employees directly involved in identified processes. Hold workshops to review workflows, discuss challenges and identify bottlenecks. This collaboration validates initial assessments and may reveal overlooked issues.

These discussions can highlight quick wins where simple AI tools could help with minimal process changes. Focus first on high-impact pain points that are relatively easy to address.

Start Simple

When evaluating AI solutions, break down each challenge into components. Look for tools that integrate with existing systems. Prioritize solutions that don't require significant IT changes or cross-departmental coordination.

Begin with a pilot project targeting one specific issue. Test the solution with a small group before wider deployment. This approach allows for feedback and adjustments while minimizing risk.

Measure Results

Track performance metrics before and after AI implementation. Monitor processing speed, case handling volume and error rates. Gather user feedback about workflow improvements and efficiency gains.

See also: How AI is Redefining Insurance Pricing Strategies

Scale Successful Projects

For effective pilots, consider broader implementation. Present results to IT, finance and leadership teams to build support for expansion. Maintain the principles that drove initial success: keep projects focused, set clear goals and ensure user engagement.

Avoid major legacy system modifications when possible. Use APIs to connect new AI solutions with existing infrastructure. This flexibility enables rapid adjustments during implementation.

Document outcomes to guide future decisions and demonstrate value to stakeholders. Consistent measurement helps justify continued AI investment.

Implementation Guidelines

Success factors include starting small, delivering measurable benefits and involving end users. Flexible integration methods allow for easier adjustments. Performance tracking helps validate investments and build momentum.

See also: Cautionary Tales on AI

Moving Forward

AI implementation in insurance need not be overwhelming. A methodical approach focusing on process understanding, stakeholder engagement and controlled testing can yield meaningful improvements. This practical strategy helps organizations build capability and prepare for more advanced AI applications while delivering immediate operational benefits.

A Practical Approach to AI in Insurance

Insurers can use AI to solve specific problems without causing major disruptions.
arrangement of tools

Artificial intelligence is often talked about as the future of the insurance industry. It's described as a game-changer that could transform how things are done. With all this excitement, insurers might feel like they need to jump into big AI projects, expecting fast results. But it's important to see AI not as a magic solution, but as a useful tool. If used strategically, AI can solve specific problems and improve current processes without depleting resources or causing major disruptions.

AI as a Tool, Not a Revolution

Many people think AI will change insurance overnight. This kind of thinking can lead to unrealistic expectations and poor strategies. Instead, AI should be seen as a powerful tool that can enhance different parts of the insurance business. By thinking of AI this way, insurers can focus on using it in specific areas instead of pursuing sweeping changes that might not meet their real needs.

To use AI effectively, organizations need to understand the whole business—from product development and underwriting to claims, customer service, and IT. This means identifying inefficiencies or repetitive tasks that AI can help solve. For example, customer service agents often struggle to provide quick and accurate information because they must search through numerous documents. Also, manual work in claims can slow processes and lead to errors. By identifying these specific issues, insurers can evaluate how AI tools might improve operations.

How to Decide on AI Solutions

When evaluating AI solutions, it's important to be practical. Cost is an obvious factor—tools should be affordable and scalable, whether that means handling more users or more data or adding features over time. Integration is also important—the less an AI tool needs to connect with existing systems, the better. Solutions that require minimal changes to current workflows and are easy to use are ideal because they cause less disruption and are more likely to be accepted by staff.

Two examples are chatbots for customer service agents and AI tools for handling documents in claims. These are effective first steps for AI because they address common problems, are relatively easy to implement, and provide quick, visible benefits without major disruptions. A chatbot can help agents find information faster, leading to better customer service. AI document tools can sort and extract information, reducing manual work and accelerating claims processing.

A practical approach to AI means starting with small projects. Choose simple initiatives that can show quick wins, like fixing a specific customer service issue or automating a repetitive task in claims. Small projects can be completed quickly, often in just a few weeks, which helps build momentum. These quick wins are important for gaining organizational support for AI and encouraging wider acceptance.

Initially, it's best to involve only the people directly affected by the issue. This keeps projects simple and avoids unnecessary complications. For early AI projects, integration with existing IT systems may not even be necessary. Once a small project succeeds, it can serve as a model for other projects and help build support across the company.

Building Toward a Larger AI Plan

After success with small projects, insurers can work on a broader AI strategy. This means scaling AI tools across the company and involving key departments like IT, finance, and leadership. Having a clear plan helps ensure AI is used in a way that meets business goals. Growing AI gradually also helps the company develop the internal skills needed for more advanced projects.

The biggest mistake is starting with projects that are too large and complicated. Signs of this include unclear goals, needing to connect with too many systems, or involving too many departments immediately, which increases complexity. Big, ambitious projects are tempting, but without experience, they can consume too many resources and disrupt workflows. A better approach is to start small, with simple, easy-to-use tools. This helps insurers get real benefits without losing control over adoption pace and scope.

Setting Up for Future Growth

By taking a practical approach, insurers can use AI to work more efficiently, improve customer service and stay competitive. The key is to avoid trying to do too much at once and instead focus on practical uses that fit into current operations. Starting with small projects not only brings quick results but also prepares the company for bigger AI opportunities in the future. A practical approach helps insurers succeed now and set the stage for long-term growth as AI technologies continue to improve.

AI has significant potential for the insurance industry, but using it successfully requires a careful, step-by-step approach. By seeing AI as a set of tools for solving specific problems, insurers can implement solutions that are cost-effective, easy to integrate and compatible with current processes. This approach allows companies to build skills over time and create a strong foundation for more advanced AI use in the future.

AI in Insurance: Balancing Innovation and Caution

AI's potential to transform insurance clashes with the industry's risk-averse nature, creating a complex landscape for insurers to navigate.

caution cone on computer keyboard

Artificial intelligence promises to revolutionize the insurance sector with streamlined operations, enhanced customer experiences and improved risk predictions. However, this cutting-edge technology often clashes with the industry's risk-averse nature. Insurers' cautious approach, essential for managing risk, can hinder the agility and innovation required to adopt AI. This tension has led many insurers to take a measured, "wait-and-see" approach, delaying the integration of transformative technologies.

The insurance industry, historically, has been relatively resistant to disruptions. Infrequent customer interactions and complex, long-term policies create customer "stickiness" that reduces pressure for technological improvements. Stringent regulations, designed to protect consumers and ensure financial stability, pose significant barriers to disruptors.

Natural barriers to entry into the insurance industry are expected to persist short-term, but the rapid pace of AI development presents a challenge. Insurers that don't adapt will miss opportunities to enhance efficiency, lose their edge in risk prediction and fail to meet evolving customer expectations.

See also: Cautionary Tales on AI

AI in the Insurance Industry

Imagine a world where policy administration and claims processing – tasks that once consumed countless work hours – are autonomously coordinated by AI. These intelligent systems can route tasks, automate routine decisions and escalate complex cases to human experts. This improvement will significantly cut down on the maintenance costs of large insurance companies.

These benefits extend to customer experience, as well. AI-powered chatbots and virtual assistants are already transforming this part of the value chain, offering instant, 24/7 support. Consider a scenario where an employee has just experienced a work injury. An AI-powered claims assistant guides them through the process, analyzing photos of the injury, cross-referencing policy details and even scheduling a medical appointment – all within minutes. By handling these routine tasks, AI frees human agents to build meaningful relationships.

Risk assessment, the cornerstone of the industry, also stands to be transformed. Machine learning algorithms can analyze vast datasets, uncovering patterns and insights that might elude the most experienced actuaries. Generative AI will further harness unstructured data, including as much as 80% of all available information in insurance companies. By leveraging these underused insights, insurers can create comprehensive, 360-degree views of the insured. This deeper understanding leads to more accurate and personalized risk profiles, significantly enhancing the quality of underwriting decisions and claims assessment.

'It all sounds promising, but ...'

That's the common refrain from insurance colleagues. While AI holds immense promise, there's a notable gap between its potential and the reality of implementation.

One hurdle that affects all industries is the disconnect between AI expectations and current real-world applications. This gap frequently leads to overly ambitious implementation plans and subsequent disappointment when results do not materialize as quickly as anticipated.

There are also unique hurdles that the insurance industry faces. One significant obstacle is the sector's reliance on legacy systems. These systems, developed over decades to handle complex insurance processes, aren't easily compatible with modern AI tools. Integrating AI often requires a substantial overhaul, including redesigning data pipelines, creating new interfaces and establishing processes to effectively leverage AI outputs. These overhauls are costly and time-consuming, especially to an industry with limited IT resources.

Moreover, the data within these legacy systems, historically treated as a byproduct of the process, often lacks the quality, organization and accessibility required for effective AI applications. In the age of AI, high-quality data that accurately represents the insured risks and customer behaviors is a critical asset, as it significantly affects the ability and accuracy of AI solutions.

Given the critical role of AI in insurance operations, it's essential to implement robust safeguards to ensure reliability, accuracy and security, including measures like output verification, anomaly detection and human oversight. Additionally, AI introduces security vulnerabilities, requiring expertise to defend against risks such as adversarial attacks on underwriting models and privacy breaches in customer service chatbots.

Strategic Considerations

An important step for insurers is investing in the quality and availability of current and future data. This paves the way for future AI success and is challenging to rectify retroactively, making it a high priority for those seeking to leverage AI to its fullest. Without high-quality, accessible data, even the most sophisticated AI models will fall short of their potential.

Another key factor is governance. Establishing effective AI governance requires insurers to develop frameworks that address the unique challenges posed by this technology. This entails creating clear policies and guidelines for AI use, incorporating ethical considerations and defining transparent decision-making processes.

There is also a need to invest in human capital. Insurance companies require specialists with in-depth understanding of AI applications, including data scientists, AI engineers and AI security experts. However, these skills are in high demand and short supply, with big tech companies fiercely competing for this talent. To address this challenge, insurers should pursue a dual strategy: actively recruiting specialized talent while simultaneously developing these capabilities in-house by training existing staff.

Equally important is bringing the rest of the organization on board with AI. This includes employees across operations, risk and HR departments that will interact with AI tools in their daily work. One strategy is to identify a core group of enthusiastic users. By providing additional training to these key users, companies can create internal champions for AI adoption. This investment in skills development not only empowers employees to collaborate effectively with AI but also lays the groundwork for broader understanding and acceptance throughout the organization.

Transparent communication about the company's AI strategy and its potential benefits is essential. Company-wide discussion should highlight opportunities AI creates for employees, such as the ability to focus on higher-value tasks. As AI advances, many employees will grow apprehensive about their future roles. By building trust and clearly articulating AI's goals and future, companies can address these concerns effectively. This proactive approach to communication will pay dividends, fostering a workforce that is both prepared for and enthusiastic about AI integration.

See also: Insurance: An Industry Embracing AI

Start Small, Think Big

How can insurers move forward without getting bogged down in complex implementations with limited IT resources?

A practical approach is to begin with pilot projects in low-risk, high-impact areas where AI can deliver tangible value. Employee-targeted service chatbots or document verification are ideal starting points.

Chatbots can quickly retrieve policy coverage details or explain common claim procedures. AI-powered document verification could streamline claim payouts by automatically extracting and validating information from submitted receipts or medical reports. These projects allow insurers to gain practical experience with AI implementations while building confidence in its capabilities. Such initial projects serve as stepping stones, facilitating broader AI implementation while minimizing risks.

Collaborating with insurtech firms helps insurers explore AI's potential. These partners, unburdened by legacy systems, can speed up AI integration. This collaboration strengthens AI foundations while maintaining governance and workforce awareness.

Insurers should also modernize core systems alongside AI implementation, ensuring long-term data-driven solutions. Key steps include improving data quality, updating infrastructure and ensuring cross-platform compatibility. A solid data foundation is crucial before advancing AI integrations as technology evolves.

Conclusion

AI's potential in insurance lies more in its future possibilities than in its present reality. The industry's inherent conservatism, while essential for managing risk, creates a unique tension with the rapid pace of AI development. This presents both a challenge and an opportunity for insurers willing to navigate this complex landscape.

A strategic approach that balances the industry's need for caution with the growing necessity to innovate is ideal. By embracing this approach, insurers can bridge the gap between AI's promise and the pragmatic realities of the insurance business. This strategy enables them to navigate the hype, address the real challenges of legacy systems and data quality, and pave the way for meaningful AI integration.


Tyler Kennedy

Profile picture for user TylerKennedy

Tyler Kennedy

Tyler Kennedy serves as the vice president of engineering at Gain Life. 

Previously he's held senior engineering roles building software across a multitude of domains from industrial controls to cloud software.