Download

'Every Carrier Is a CAT Carrier Now'

With seemingly nowhere immune to natural disasters these days, carriers must communicate the risks better and spur policyholders toward resilience.

Dave Tobias interview

Insurance Thought Leadership

Let’s start with the Southern California wildfires, as long as Nearmap was so involved in helping carriers respond and as long as the disaster is so on point for our Predict & Prevent focus this month. What did you see?

Dave Tobias

Interestingly, we had flown over the LA area, including the Palisades, on Jan. 1, just before the fires started on the seventh. This is part of our normal cadence, as we capture new imagery three to four times a year depending on the region.

We had planes in the air within five hours of the fire starting. We maintain a nearly 24/7 operations team outside Washington DC that monitors events, weather, and plane locations, and we were able to start streaming this imagery to insurance companies within hours after these flights.

We run AI analysis on every flight, and in catastrophes we conduct damage detection via AI. For wildfires, we're assessing total versus partial losses, though these fires typically resulted in total losses. While a hurricane typically moves through an area and is done, this fire kept spreading, and areas that were initially safe were later destroyed.

I happened to be in Hartford during the fires, meeting with some of our largest insurance customers. I witnessed firsthand how they were using our data. One top-five carrier had integrated our imagery and AI analysis into their mapping system, using it to guide their call center in contacting insureds who were evacuated. The reps were often the first to inform people about whether their homes had survived. These insurers went to great lengths to locate their customers, even searching social media platforms like Facebook and TikTok to reach them.

The human element really stood out to me. Insurance executives were reaching out after seeing my LinkedIn posts, asking me to check on their childhood homes or family members' properties. I found myself delivering news to about 20 people personally. It reinforced that, during a crisis, whether you're an insurer or insured, people want certainty. They need to know what's happening so they can start planning, regardless of the outcome. That's really one of the fundamental elements of insurance – providing certainty for people moving forward.

And in a catastrophe like this, resources become very constrained. Whether it's apartments, contractors to clear debris, or other services -- there's only so much available in the area. The sooner insured homeowners can start taking action, the better position they'll be in.

I heard this sentiment echoed by many insurers we work with. In cases of total loss, they could immediately process claims for policy limits because everything was gone. Seeing them use AI and aerial imagery to facilitate this process was remarkable -- it's the first time I've witnessed that kind of straight-through processing.

Insurance Thought Leadership

Based on your aerial imagery from January and earlier, what insights are insurance companies gathering to help homeowners and communities better protect themselves against fire damage?

Dave Tobias

Everyone has seen that one home that survived on the block because it had more robust building materials. But really, the easiest thing everybody can do, and the data makes it very clear, is have good defensible space around their buildings.

When you have hundred-mile-an-hour-plus winds and embers in the air, sometimes there's nothing that can be done. But you definitely see the homes that had good defensible space around them versus the ones that didn't -- their survivability went up quite a bit.

The nice thing about defensible space is it's something a homeowner can do as step one without a lot of investment. That's what I would call the base-level mitigation: Clear the shrubs, cut down some trees, use nonflammable plants.

Another issue I see, even in my neighborhood in Burlingame -- where wildfire isn't really a threat, except in the hills -- is what people put right next to their building. They put wood mulch literally touching the building because it looks nice. But it's kindling. Wood mulch is kindling. You might as well put a bunch of matchsticks up against your home.

We've all done it. My old home had it. But you're putting very flammable material right up against the structure.

These are things people can act on now as preventative measures. The Palisades, specifically, everybody knew was a wildfire danger zone. There's a lot of negative press about insurers canceling policies ahead of the fire, like they knew the fire was coming. The reality is the insurers and everybody else knew this was a wildfire zone for a long time.

Insurance is just math at the end of the day. If you can charge enough premium, you can insure anything, but the regulatory environment in California makes it difficult to charge the right rate, so insuring properties in a highly dangerous wildfire zone is really expensive.

I think it's going to be interesting to see how the rebuild happens in some of these areas, and if some of these risk-mitigating factors change. There are plenty of great materials and building guides from IBHS (the Insurance Institute for Business and Home Safety) and others on fortified homes for wildfire. I'm hopeful, but it's not going to change the fact that these areas will continue to be arid and have high winds.

Insurance Thought Leadership

How can insurance companies better encourage homeowners to maintain proper brush clearance year after year, especially given the mixed success of community efforts like those in the Palisades?

Dave Tobias

When you have houses in close proximity to each other, if some homeowners maintain their property while others don't, it diminishes the value of community protection. We need to create better incentives for people to maintain their properties.

There's the inherent carrot-and-stick approach. Doing certain things might bring down your insurance rates. We see some states implementing programs, like with fortified homes and fortified roofs. In areas that experience massive hail events annually, where people need new roofs every year, some states provide rebates or funding to insurers or homeowners to install more sustainable roofs that meet specific fortified standards.

But we need to start implementing these sorts of programs now. These events aren't going to stop happening, and people are going to continue living in these areas.

While some homeowners will take initiative on their own, my hope is that we'll develop a more cohesive strategy around prediction and prevention at the state level, and maybe someday even at the federal level. That's really the only way some of these areas will remain insurable.

Insurance Thought Leadership

What if you used your aerial images to show homeowners how their properties compare with their neighbors’, similar to how utility companies share data on how my energy usage compares with similar homes in my neighborhood?

Dave Tobias

Absolutely. The technology and data exists today. Insurers have a lot of this data -- they're buying from companies like us and others. When you log in to pay your insurance bill, you don't see this data that insurers have, at least I don't with my insurer. That's a big opportunity.

I think there's huge potential for sharing downstream preventative measures. Take defensible space. The AI can show your current defensible space profile and indicate that if you clear out specific zones, it will reduce your risk by a certain amount. The same applies to roof condition. We can monitor your roof and share that information with you as an insured, pointing out problems like missing shingles or staining that might need attention.

You can track issues over time, which is valuable because most people don't regularly inspect their roofs -- out of sight, out of mind. I think sharing more information downstream with agents and insureds would benefit everyone. That's a last-mile problem we hope to solve.

The concept of Predict & Prevent isn't new -- I and others have been talking about it for years. What's new is the technology to assist in it, like the information we can get from aerial imagery and how we've been able to unlock it with AI. But we're not doing anything to act yet. We need to add some level of action to that prevent step.

Insurance Thought Leadership

How do your hurricane monitoring and tracking methods differ from your wildfire surveillance?

Dave Tobias

With hurricanes, we typically know they're coming and can plan accordingly. Even before the hurricane hits, we can identify which properties will be most susceptible to damage.

The Predict & Prevent aspect is crucial. With hurricanes, you can see fascinating examples where two neighboring properties experience the same storm conditions -- identical wind speeds and everything -- yet one roof survives without a scratch while the other gets completely ripped off. This demonstrates how taking preventative action, like installing fortified roofs, can prevent hurricane disaster damage.

Insurance Thought Leadership

What is your approach to areas that aren't obviously at risk? How do you handle coverage in places like Kansas or Minnesota that may not seem like immediate priority zones?

Dave Tobias

For our impact response, we'll fly anywhere. Milton and Helene hit some areas that weren't as populous, but we flew them. We flew 118 flights. We analyzed over 5 million buildings.
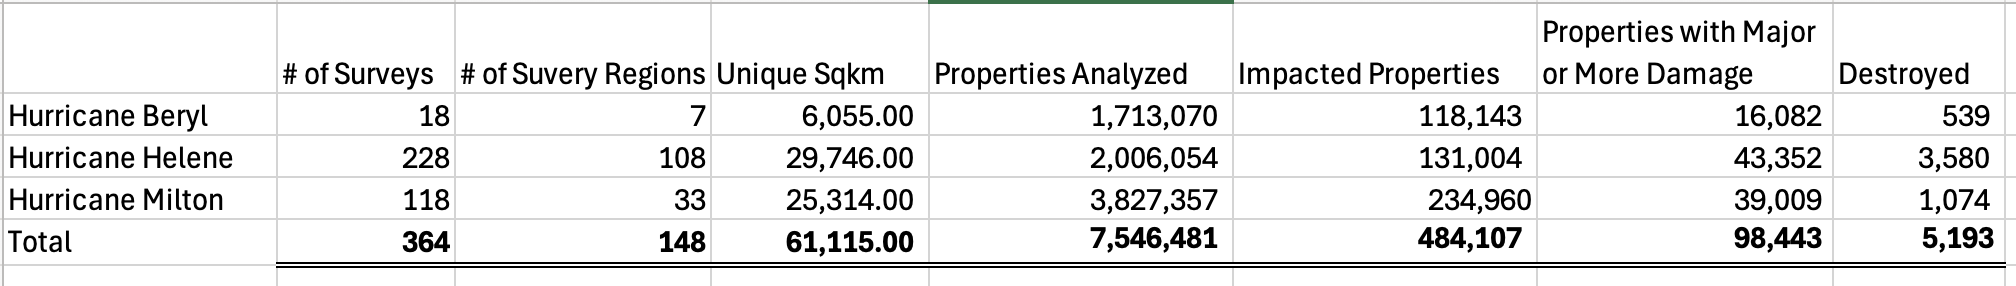
data

We can fly areas we've never flown before, and that still provides tremendous value to insurance companies. They're trying to triage and decide where to send their claims adjusters and get everything moving in the right direction. The sooner they can do that, the better for everybody.

I like to say that every carrier is a CAT carrier now, because every state has had at least one catastrophic-level peril that's starting to hit it. When I started in insurance, you would talk about certain carriers just dealing with catastrophic stuff in Florida and Louisiana, while others would say "we're in Colorado, we're not really a CAT carrier." But that's definitely changed because of the severity of these events, the frequency of these events, and where populations have moved to.

Insurance Thought Leadership

Looking ahead two to five years, where do you see your technology evolving in terms of predicting risk factors?

Dave Tobias

I think we're going to have to evolve, because otherwise too much of the country will become uninsurable. We're going to have to change the mindset and have insurance companies, insureds, and agents all partner together to maintain properties at an insurable level.

To achieve this, insurance companies need to share more information with the insureds. We need tools from companies like Nearmap to make that sharing easy and interactive, so insurers can easily assess the condition of their roof and defensible space profile and improve them. That's the only way to get closer to an equilibrium of rate to risk. Right now, in certain areas of the country -- Florida and California being extreme examples -- we don't have that equilibrium or anything close to it.

Five years from now, I think Predict & Prevent is going to be a cornerstone of insurance policy and framework.

Insurance Thought Leadership

Is there anything we haven't covered or any final thoughts you'd like to share?

Dave Tobias

Obviously, I'm biased, but I think not enough gets told about how proactive insurers were during the fires and how they were really trying to help people. They weren't just canceling policies and doing the things that the news has described. I think we need to tell the story of carriers who were tracking people down on TikTok just so they could be there to help.

I was talking to one carrier whose claims adjusters were sometimes spending three or four hours on the phone with insureds because they were being counselors. They were helping people figure out how to replace their pictures and other personal items. These companies were really going above and beyond.

Insurance Thought Leadership

That seems like a great note to end on. I’ll certainly try to do my part to spread the word.

Thank you for taking the time.

Dave Tobias

We love talking about this stuff, and there's so much to discuss.



Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

AI Takes Insurance BPO to the Next Level

Organizations that successfully combine AI's processing power with experienced professionals' judgment will gain significant advantages. 

Hand of a Person and a Bionic Hand

After decades of manual and low-tech document processing, business process outsourcing (BPO) is due for an AI transformation. 

The scale of document processing in insurance is staggering. A typical mid-sized retail agency processes thousands of policies annually, with each policy requiring multiple reviews and comparisons. With staff spending an average of 70% of their time on manual document processing, the industry faces a critical efficiency challenge. 

The Next Wave of Insurance Operations Efficiency

The BPO model today delivers significant cost savings, and insurers and agents are counting on artificial intelligence (AI) technology to deliver further efficiencies throughout the insurance value chain. The automation of policy and agency document processing alone will prove to be transformative to carriers, retailers, wholesalers, MGAs, and customers. Manual tasks of policy checking, quote comparisons, policy data extraction and analysis, and dozens of other use cases can now be automated thanks to AI. 

The evolution of AI technology has been particularly meaningful for insurance operations. Early automation attempts often struggled with the complexity of insurance documents and the need for contextual understanding. Modern AI capabilities, enhanced by advances in machine learning and natural language processing, can now effectively handle intricate insurance documentation while maintaining accuracy. This technological maturity, combined with established BPO processes, creates new possibilities for operational efficiency.

Consider policy checking, a traditionally labor-intensive process. Where previous automation attempts could only handle basic data matching, today's AI can analyze complex coverage forms, identify potential gaps, and flag discrepancies while reducing processing time by 75%. Similar advances in quote comparison and data extraction capabilities are transforming how insurance organizations handle routine but critical tasks.

See also: Balancing AI Innovation With Consumer Protection

The Importance of Human Oversight

The insurance industry's reliance on judgment and expertise means that technology alone isn't the answer. Experience across the industry shows that maintaining quality standards while achieving efficiency gains requires finding the right balance between artificial intelligence and human insight. This "human-in-the-loop" approach ensures that AI outputs align with industry standards and business objectives.

Even with the most advanced AI systems, it’s critical these tools are supported by experienced professionals who understand:

  • Complex risk assessment nuances that require human judgment
  • Program business dynamics across multiple carriers
  • Authority compliance requirements and monitoring
  • Market relationship management and development
  • Strategic growth opportunities identification

The impact extends beyond operational efficiency. Insurance providers implementing this balanced approach report improved customer service through faster, more streamlined processes and fewer errors. They gain deeper insights into customer needs and can provide better risk advisory services. Financial benefits emerge through improved forecasting, better carrier relationship management, and more effective tracking of performance metrics.

Maximizing AI's Value Through Professional Insight

Insurance professionals provide the critical thinking and industry expertise needed to transform AI outputs into strategic advantages. Most importantly, for the foreseeable future, they will be key to providing the strategic insight and analysis necessary to holistically achieve elevated customer service and business optimization. 

The results of this balanced approach are evident in several key areas. Organizations implementing AI-enhanced BPO typically see dramatic improvements in processing efficiency while maintaining or improving accuracy. Quote comparison times drop from hours to minutes, leading to faster client response times and improved close rates. Policy data extraction becomes more thorough and consistent, enabling better carrier negotiations and risk assessment.

With the right AI and BPO partner, Insurance providers can dramatically improve customer service. This means faster and more streamlined purchase and renewal processes; a deeper understanding of customer profiles and needs; an ability to provide risk advisory services using loss runs data; and far fewer errors and mistakes. 

With the right balance of technology and human capital, agencies can run more profitably. Areas for immediate gains include improved forecasting and management of revenue and margin by customer vertical or geography; analysis of retail brokers’ relationships with carriers – and carriers’ relationships with retail brokers; better management of the placement of policies with the best carriers; and the tracking of performance toward earning carrier contingent payments, to cite just a few.

See also: Blending AI With Human Interaction

Conclusion

The future of insurance operations lies in finding the right balance between AI technology and human expertise. While AI provides unprecedented efficiency and accuracy in processing insurance documents, the industry's complexity demands that we maintain human oversight to ensure quality and strategic insight. Organizations that successfully combine AI's processing power with experienced professionals' judgment will gain significant competitive advantages. The key to success isn't just implementing AI technology but creating an integrated approach that leverages both technological capabilities and human expertise to deliver superior results for clients and stakeholders.


John Simpson

Profile picture for user JohnSimpson

John Simpson

John Simpson is the founder and CEO of Patra, which has grown to more than 6,000 employees worldwide. 

He has spent more than 20 years leading tech-focused companies and previously founded CyberBills, a web banking technology company.

P&C Insurance: Mind The Gap(s)

The last three years are arguably the most challenging the P&C insurance model has faced, and a worrisome series of gaps has taken shape. 

Grey and white staircase ascending against a solid white background

The expression, "Mind the Gap," dates to the 1960s, when it was first announced on the London Underground. The purpose was to warn passengers of the potentially dangerous gap between the train door and platform, which are not perfectly aligned. The expression has since evolved to become a general warning about the danger of open space or gap between two points. 

It applies especially well to the many risks and headwinds faced by the insurance industry today. If unattended, the gap may be irreversible or much harder to close.

The P&C industry is, by design, resilient, with layers of financial insulation. Reinsurance, surplus capital and low-risk and liquid investment portfolios are just some of these layers, with individual state oversight to monitor financial stability. The insurance model has been tested during high inflationary periods and catastrophes and alternating hard and soft market cycles. However, the last three years are arguably the most challenging, because of fluctuating inflation and worsening climate risks. Meanwhile, there are emerging and widening gaps that both threaten and are reshaping massive segments, such as real estate and homeownership.

Climate Resilience Gap

As made painfully obvious by the recent series of extreme weather catastrophes, government and public agencies’ collective ability to respond to these new and greater risks has proven inadequate, while the insurance industry is more vulnerable than ever. Each event seems to outpace the last, taxing FEMA, illuminating dated infrastructure and financially straining insurers. 

Protection Gap

It is estimated that 50% of insurable global risks are actually insured – in some countries and socio-economic groups, the gap is much larger. The impact of this lack of coverage is the high, and in some cases unexpected, cost of covering losses and replacing property. Frequently, insurance companies take the brunt of the blame for not properly advising policyholders at the front end. Affordability is driving the gap further as trade-off decisions are made to partially or fully self-insure. Most are ill-prepared for this new paradigm.

Trust Gap

Consumer trust and policyholder loyalty is at an all-time low within the insurance industry, including in health and P&C. The reasons include; years of double-digit premium increases, well beyond inflation; protracted and frustrating claims payment experience in the face of losses from increasingly extreme catastrophes; unexpected coverage denials; and a trust deficit as policyholder driving data and personal information is being collected and commercialized without explicit permission. All of this is exacerbated by the stark differences between insurance industry customer service levels in comparison with other modern digital experiences. Finally, insurer profits, whether in reality or just perception, are widely considered excessive.

See also: Embedded Insurance: A Major Disruptor

Transparency/Information Gap

The process by which premiums are calculated and claims are adjudicated remains opaque. Policy language is lengthy, technical and in parts vague and open to debate. Most policyholders are unaware of what information is collected and calculated or disagree that factors such as credit scores somehow accurately predict risk. Either way, there is a missing link between premiums and perception of risks, such as one’s self-evaluated driving skills. Most believe they are good, safe drivers, for instance.

Legal System Abuse Gap

While the plaintiff bar systematically optimizes the tort system, there are widespread abuses that enrich them with oversized fees resulting from astronomical jury verdicts, fueled by litigation funding and mass marketing. Conversely, the insurance industry has basically failed to exert its influence to reform the legal system and has been unable to keep pace. The industry needs to organize itself and fund a concerted effort to address this problem. Consumers are aware that these sky-high verdicts ultimately translate to higher premiums and expect insurers to do more to protect them.    

Talent Gap

The "silver tsunami" is a term used to describe the aging of the baby boomer population. It refers to the potential impact of this demographic shift on the workforce. Many baby boomers are retiring at an accelerated rate. The aging workforce is leading to a “brain drain” as older workers leave their jobs, taking their rich insurance knowledge to the pickle ball courts.

The recent shift from analog to digital business processes requires that the workforce receive appropriate upskilling or retraining, but the insurance industry continues to lag in these initiatives.

Finally, attracting the best and brightest young adults – most of whom are “digital natives”– to insurance careers has proven elusive. It is incumbent on the industry to work together to address the gap, starting with image and purpose. 

Empathy Gap

As insurers work to leverage new technology, there is a loss of human empathy across the enterprise. Claims is especially vulnerable because policyholders are suffering anxiety and stress. Efforts to automate often lead to fewer people resources, to meet ROI objectives, or are disjointed and yet to be perfected, resulting in a bumpy claim process.  

Insurers will need to do more to deploy, integrate and orchestrate new technology and coordinated provider services, especially AI, while improving and not degrading customer service and satisfaction. Loyalty and retention are at stake.  

Marketing Gap

The P&C insurance industry – specifically personal auto and home carriers – continue to offer essentially the same products they have been selling for decades. However, today’s consumers bear no resemblance to those in the past. Needs, expectations and preferences have changed dramatically, and legacy insurance institutions are quickly becoming irrelevant when making purchasing choices.

Product Gap

One prominent characteristic of the “new consumer” is their expectation of personalization in goods and services. This is the opposite of the “one size fits all” approach that the legacy insurance industry still pursues.

Consumers want dynamic, real-time, fit-for-purpose, bespoke insurance products, and if one carrier cannot provide it, there are others that will. Record-high insurance shopping rates are a reflection of these preferences.    

Consumers have embraced connected devices (cars, smartphones, watches, sensors) and the associated products and services, but insurers are badly lagging other segments in leveraging these from a product perspective, exposing themselves to competitive risk from technology providers. 

See also: Does the P&C Insurance Cycle No Longer Exist?

Distribution Gap

Independent insurance agents and brokers place about 62% of all P&C insurance premiums in the U.S. (including commercial lines and personal lines), yet they are not as effective as they could be. 

Brokers do a fair job of marketing new prospects but are generally much less effective at customizing coverage to personal needs and even less so at staying in touch with relevant communications and basically go silent until policy renewal approaches.  

Although the vast majority of auto insurers offer telematics-based insurance products, market penetration stands at only 16% of policies. Agents typically do not promote these products because they are not proficient at explaining them and fear alienating their prospects.

Embedded insurance (insurance bundled at point of sale of a product or service) is seeing rapid growth outside of insurance, but carriers are behind the curve. This deficiency not only represents lost revenue and the loss of new customer acquisition opportunities but allows non-traditional providers to take market share.   

Innovation Gap

Insurance C-Suite executives talk up innovation and transformation, but very few invest sufficient effort and resources beyond catching up with technology, and even fewer have strategic plans to close this gap. Yet technology is making a difference in numerous areas and is expected to do so well into the future.

It is incumbent on insurance CEOs to regularly communicate and clearly articulate their support of innovation and to ensure that adequate resources are being allocated and applied. It requires nothing less than a cultural makeover, addressing outdated constructs that impede breakthrough progress. 

Closing the Gaps

The role of innovation and insurtech cannot be overstated for an industry that historically is people- and labor-intensive. Closing these gaps is vital for the insurance industry and its contributions to the economy and consumer livelihoods. Long-term insurance stability is in the best interests of investors, financiers and risk takers of all types, including businesses and consumers. 

Minding the gap is foundational for industry success in 2025 and beyond. 


Alan Demers

Profile picture for user AlanDemers

Alan Demers

Alan Demers is founder of InsurTech Consulting, with 30 years of P&C insurance claims experience, providing consultative services focused on innovating claims.


Stephen Applebaum

Profile picture for user StephenApplebaum

Stephen Applebaum

Stephen Applebaum, managing partner, Insurance Solutions Group, is a subject matter expert and thought leader providing consulting, advisory, research and strategic M&A services to participants across the entire North American property/casualty insurance ecosystem.

Rising Climate Risks Demand New Strategies

"Smart" hazard scores of each asset, combined with historical data and predictive insights, can provide comprehensive risk assessments.

Scenic View of Dramatic Sky over Beach during Sunset

Climate change is amplifying property damage and business interruption exposures by increasing the frequency and severity of natural catastrophe events such as floods, wildfires and storms.

Understanding amplified physical risk exposures

Last year, natural catastrophes caused more than $350 billion in economic losses globally, with insurance covering less than a third of these losses, at just over $100 billion.

Between January and June 2024, the U.S. experienced more than $30 billion in insurance claims due to an above-average number of tornadoes, hailstorms and straight-line wind events. Texas, meanwhile, recorded its largest wildfire, which burnt 426,600 hectares. The damages involved in these events often far exceeded businesses’ risk scenario planning considerations.

What can companies do to better identify, quantify and mitigate potential damage and ensure both effective insurance protection and more resilient operations in the face of escalating physical climate challenges?

Organizations need smarter, more dynamic and comprehensive approaches to understand and respond to the risks. 

See also: What Trump 2.0 Means for Climate Initiatives

A smarter way to address physical climate risks

By evaluating the aggregate hazard scores of each of a company’s assets – the metric to evaluate the likelihood and potential impact of a specific hazard occurring – companies can understand their exposure to various natural catastrophes. Smart hazard scores can also combine historical data and predictive insights with expert judgment, providing the comprehensive risk assessments organizations need to address property damage and business interruption risks in today’s context.

More sophisticated risk evaluations will help to identify high-risk assets and prioritize actions to mitigate potential damage. Organizations can better detect vulnerabilities, such as the presence of basements with critical equipment in buildings or plants in flood-prone regions, or identify with more precision secondary peril risks such as landslides following heavy rainfall.

A combination of traditional insurance, captives and alternative risk transfer (such as parametric solutions), as well as cost-effective and sustainable adaptation on site level, can help business operations or value chains recover more quickly.

Using a combination of "what-if" types of stress testing, risk engineering and numerical or theoretical modeling can put companies on the front foot to manage the landscape of increasingly complex risks. The same is true of looking beyond an organization’s boundaries to better assess the potential vulnerabilities across their value and supply chain in light of more frequent, more severe disruption.

See also: Insurers Must Evolve to Survive Climate Crisis

How to avoid under-insurance using analytics and valuations

Many businesses could be under- or overestimating their property and business interruption risk in the context of heightened climate-related exposures. Some insurers, meanwhile, are potentially mispricing property risk, in part because their models don’t capture what used to be "black swan" events – those events that are almost impossible to predict yet seemingly inevitable, after the fact. Once rare, such events are now much more common due to climate change.

Because many models call on claims experiences, they effectively play back what’s already known, rather than forecast future likelihoods and impacts. This can lead to underestimating the value of assets and subsequent underinsurance, leaving businesses vulnerable to significant financial losses in the event of a claim.

A Day in the Life of an L&A Insurance Super Agent

Here is a snapshot of a typical day for a service staff with  SUPERPOWERS (i.e., good data, automation, and an AI assistant).

Woman Holding Black Flag

A life and annuity (L&A) insurance service staff (policy administration or claims) serves as a critical intermediary between policyholders and insurance companies. Their role involves policy maintenance, investigating claims, assessing impact, and ensuring that settlements are processed fairly and promptly. 

To transform an L&A service staff into a “superpowered” professional, disruptive technologies would enhance efficiency and accuracy, empower staff with the ability to get the job done, and ultimately improve customer satisfaction. 

Below is a snapshot of a typical day for a service staff with SUPERPOWERS (i.e., good data, automation, and an AI assistant):

See also: A Season of Change for Life Insurance and Annuities

Human in the Loop Work Orchestration: 

  • Review personalized dashboard on critical items needing attention.
  • Respond to overnight emails and messages from policyholders, internal departments, or other external stakeholders in your enterprise workflow solution. Update any notes or set any reminders.
  • Review and start working on pending/new cases that are automatically prioritized and routed based on deadlines, severity, or complexity.
  • Analyze insurance policy information and document summaries to understand eligibility, request type compared with policy information such as coverage limits and exclusions for new requests in one user interface. Contact policyholders via their communication choice if additional information is required.
  • Handle urgent requests or disputes that may require immediate attention.
  • Update policyholders/stakeholders on progress and resolve questions or concerns per communication choice of their choosing. Handle disputes or escalations when stakeholders disagree with assessments or coverage decisions, using facts and empathy as data surrounding the decision is in one interface.
  • Submit for approvals/denials based on authority limits
  • Review and adjust ad hoc letters for any complaint/denials/complex workflows. The correspondence engine automatically provides a recommended language based on the action.
  • Review payout calculations that need oversight due to the size and nature of the request. The calculation logic is presented for review and approval.

Agentic Workflows (Superpowers) in Action

  • Natural Language Processing (NLP): Real-time, multilingual customer interaction and document interpretation. NLP tools like chatbots and voice assistants handle policyholder queries, extract key data from documents such as medical records or death certificates, and summarize complex documents, ensuring faster resolution.
  • AI-Enabled Workflow Automation: Lightning-fast processing aimed to un-fragment various solutions into one experience. With agentic flows, repetitive tasks such as checking eligibility, retrieving and summarizing required documents, and initiating payouts are automatically done, which reduces human error and processing time.
  • AI-Driven Triage: Instantaneous work categorization, prioritization, and routing of work. AI models analyze request details, policyholder history, policy information, and third-party data to recommend next steps, flagging fraudulent activity and urgent payouts.
  • Third-Party Data Integration: Access to real-time data from various sources to retrieve meta data or specific info such as death data. Service staff leverage data from these data sources to validate events (e.g., accidents or health conditions) and expedite processing.
  • Quantum Computing Insights: Instant risk assessment and fraud detection. Quantum computing processes complex datasets to identify fraud patterns or optimize payout models faster than traditional systems.
  • Hyper-Personalization With AI: Tailored customer experiences and communication. AI analyzes policyholder demographics, behavior, and preferences to customize communication and processes, enhancing satisfaction.
  • Sentimental Analysis for Empathetic Support: Detecting emotional states for tailored communication. AI models evaluate a stakeholder’s tone, language, and sentiment during interactions, helping staff respond empathetically while managing expectations.
  • Advanced Analytics and Insights: Data-driven decision-making. Predictive analytics tools identify trends in requests, uncover potential risks, and suggest ways to enhance underwriting or streamline future processing.

See also: AI Bias in Life & Annuities Insurance

By blending these technologies, the L&A service staff becomes not just a processor but a proactive problem solver, delivering exceptional service while minimizing inefficiencies and errors.

At carriers that adopt these technologies, operations staff can focus on more complex, human-centered aspects of their roles while ensuring accuracy, consistency, and efficiency in handling work, providing a personalized customer experience.


Bobbie Shrivastav

Profile picture for user BobbieShrivastav

Bobbie Shrivastav

Bobbie Shrivastav is founder and managing principal of Solvrays.

Previously, she was co-founder and CEO of Docsmore, where she introduced an interactive, workflow-driven document management solution to optimize operations. She then co-founded Benekiva, where, as COO, she spearheaded initiatives to improve efficiency and customer engagement in life insurance.

She co-hosts the Insurance Sync podcast with Laurel Jordan, where they explore industry trends and innovations. She is co-author of the book series "Momentum: Makers and Builders" with Renu Ann Joseph.


Lawrence Krasner

Profile picture for user LawrenceKrasner

Lawrence Krasner

Lawrence Krasner is an associate partner, financial services: insurance strategy and transformation, at IBM.

He has over two decades of business, IT strategy and transformation experience in the insurance industry, with a focus on life insurance. He has led efforts at different organizations to define and manage large business change programs and technology portfolios.

Mining Brokerage Data to Find Pots of Gold

Insurance brokers can unlock significant opportunities by leveraging placement data to accelerate growth and profitability.

Glittering gold dust

When British mathematician Clive Humby said in 2006, "Data is the new oil," he might not have realized just how applicable that statement would be to the insurance industry's growth and profitability 19 years later.

Humby's quote has been interpreted to mean data will surpass oil as the driver of the global economy. Whether that ultimately proves to be the case is unimportant; comparing data and oil is apt. The value and usefulness of both depend on how they are processed and applied.

Insurance agents and brokers have a complex array of data at their fingertips, and maximizing the value of it all is challenging. There is, however, an area where they can tap significant revenue opportunities with minimal effort: placement data.

Insurance intermediaries collect vast quantities of data every day related to placing coverage, not only on their customers' risks but also from the insurance companies that accept those risks. This data can serve as a roadmap to consistent financial outperformance, if brokers can unlock it.

Even though placement data reflects potential revenue, brokers can't realize those earnings until they connect the dots between client need and carrier appetite and they complete coverage placements. What's needed is a reliable way to speed that process.

See also: 4 Challenges in Adopting Broker Technology

Accelerating placements

Accelerating the placement process and making it more efficient is an opportunity for every agent and broker. Beyond speed, maximizing the value of placement data means gaining clear visibility into opportunities that drive growth.

Identifying growth opportunities in placement data is a bit like matchmaking. Brokers must consider: What coverages do insureds need? What are underwriters looking for? Where do insurers have an appetite to write more business? By bringing both sides together with agreeable terms, the intermediary fulfills its mission and forges relationships that can deliver long-term benefit to all parties.

Imagine how much faster a broker could achieve revenue goals by analyzing placement data and finding opportunities it didn't see before. What could happen when a broker sees the possibility of offering additional coverage to an existing customer, or consolidating multiple lines with an insurer that is paying more commission for that business? Growth and profitability could increase for the brokerage, while the client gets more protection for its risks.

Consider the following hypothetical – though common – scenario:

ABC Insurance Brokers serves a wide range of midsize and large clients by procuring property and liability insurance policies. Even though ABC has placed its clients' risks with more than 50 different insurance companies, 80% of its book of business is placed with just 10 carriers. A great deal of time and effort is expended maintaining relationships with 40 insurers that account for a fraction of ABC's clients. In addition, of the 10 core insurers, five generate more than 60% of ABC's commission income. Seeing this, it becomes clear to ABC that the brokerage can generate more income by consolidating placements with fewer insurers, where doing so makes sense for the clients.

Moving up the ranks

A MarshBerry analysis of U.S. brokers shows the largest 50 firms account for 96% of the revenue of the top 100, while the bottom 50 have only a 4% share. With mergers and acquisitions forming a key building block of growth for most brokers, achieving organic growth through better use of placement data is a highly cost-efficient alternative – or supplement - to M&A.

The five-year compound annual growth rates (CAGR) for brokers in the top 100 varies by revenue size, MarshBerry found. Average five-year CAGR for brokers ranked 11-50 in 2023 was 18%, while it dropped to 9.5% for those ranked 51-75. The brokers ranked 76-100 had the lowest average CAGR, at 4.7%. This shows how smaller brokers struggle to consistently achieve growth.

Privately held brokers pursue growth to meet different objectives. Some prefer to remain independent, while others look to maximize their appeal for sale to a larger firm or private equity buyer. In either case, better use of placement data is a key to achieving sustainable, consistent growth.

See also: How Insurance Brokers Can Stay Competitive

Sharpening the line of sight

Gaining insight into the revenue opportunities within placement data is difficult with existing agency management systems. Those platforms excel at supporting agents' and brokers' workflows, but they fall short in providing strategic insights about placement. Innovative technology now exists that works hand-in-glove with brokers' existing core systems to analyze placement data and bring growth opportunities to the fore.


Travis Shank

Profile picture for user TravisShank

Travis Shank

Travis Shank is head of U.S. operations at Broker Insights USA, a division of Scotland-based Broker Insights Ltd., a provider of data analytics and market insight for the commercial insurance industry. 

Shank has more than 15 years of experience in insurtech, IT Services, healthcare and consulting. He has held various senior executive roles, including chief revenue officer at Quility Insurance.

Iterative Tops Waterfall in Project Management

Modern software development demands iterative approaches over traditional Waterfall methods for greater flexibility and project success.

Oberwart, Burgenland, Austria  Water Falls

The traditional Waterfall method, a linear and sequential process for software development, was for a long time a cornerstone of project management. However, in the dynamic and ever-changing world of modern software development, this approach often proves inefficient and unsuitable for contemporary needs.

Its place is frequently taken by iterative approaches, such as Scrum or smaller Waterfall cycles, which offer more dynamic and effective alternatives for achieving success in IT projects.

See also: Multi-Agent Systems Reshape Human-Machine Collaboration

The Other Side of the Coin

The fundamental flaws of the Waterfall methodology stem from its tendency toward excessive upfront planning. Teams often overcompensate, trying to address every possible requirement early in the project, which leads to an overly expanded project scope. Fear of future budget constraints results in the inclusion of unnecessary and low-priority features, increasing the complexity of the project and hindering its execution. Consequently, projects often become inefficient and prone to failure.

Another critical problem of the Waterfall method is the delayed response to user needs and product delivery. Users and stakeholders typically cannot evaluate the product until the later stages of development. By this point, resolving issues becomes costly and time-consuming. This delayed feedback loop limits the ability to effectively align the product with user needs and expectations.

Moreover, the rigidity of the Waterfall method assumes that requirements remain constant, which is rarely true in today's dynamic business environments. This lack of flexibility makes it difficult to adapt to changing market conditions, customer preferences, or technological advancements, often leading to wasted resources and diminished project value.

The Iterative Approach as a Key Solution

The iterative approach offers an appealing alternative. By building systems step by step in smaller cycles or mini-Waterfall projects, this approach allows teams to focus on delivering the most critical features first. This strategy enables faster delivery, earlier user feedback, and quicker issue resolution. The iterative model better aligns development efforts with business goals and ensures the product remains relevant and valuable throughout its lifecycle.

A key principle underpinning the success of the iterative approach is the Pareto Principle, also known as the 80/20 rule. In IT projects, this principle suggests that 80% of a product's value often stems from just 20% of its features. By prioritizing high-impact features and deferring or eliminating low-value ones, teams can optimize resource usage and shorten development timelines. This approach avoids excessive costs and complexities associated with rarely used edge cases, ensuring a more efficient use of time and resources.

The iterative approach also accelerates time-to-value by enabling users to access functional elements of the system earlier than traditional methods. Early delivery increases user satisfaction and provides tangible evidence of progress to stakeholders. Continuous delivery builds trust and fosters collaboration between development teams and business stakeholders, creating a positive cycle of improvement and adaptation.

See also: The Need for Agility in Insurance

Factors Building Success

For iterative approaches to succeed, decisive leadership is crucial. Managers must effectively prioritize, having the courage to defer or discard unnecessary features when necessary. Strong collaboration between business and development teams ensures alignment of priorities and makes the iterative process deliver meaningful results.

Equally important is the support and understanding from executive leadership, which should approve budgets in phases. This staged approach to financing allows for flexibility, enabling teams to respond to emerging challenges and opportunities without being constrained by rigid upfront planning.

Adopting the iterative approach also requires a cultural shift within the organization. Teams must move away from the mindset of achieving perfection from the start and instead focus on experimentation and learning from early iterations. Promoting agility and flexibility empowers teams to innovate and adapt to changing circumstances, supporting a more resilient and effective development process.

In Summary

While historically significant, the Waterfall methodology is increasingly unsuitable for modern, complex projects. Its inefficiencies, lack of flexibility, and delayed responsiveness make it ill-suited for today's dynamic environments. Iterative approaches provide a powerful alternative, delivering flexibility, faster delivery, and cost efficiency. By adopting iterative strategies and fostering the right organizational mindset, companies can unlock greater value and achieve sustained success in their software development processes.

Insurers Face Complex Risk Environment in 2025

Insurance leaders must navigate emerging risks while building resilience through data analytics and strategic risk management.

3D Render Graphics

Despite a positive overall sentiment about 2025, business leaders must navigate significant challenges to profitability, employee productivity and organizational resilience.

This complexity arises from an ever-changing risk environment. Key risks include climate change, natural disasters, cyber threats like deepfakes, the growing adoption of AI, and geopolitical uncertainties. Organizations must adapt swiftly to remain competitive and resilient.

Building resilience through comprehensive risk management

Integrating risk management into corporate culture is critical for turning disruptions into opportunities in 2025. Businesses must plan for climate-related risks, as climate change has escalated the frequency and intensity of natural disasters, leading to average annual global losses of $151 billion.

Organizations should conduct a business impact analysis to understand risks and recovery strategies. Extending business interruption policies to 24 to 36 months to accommodate long-term recovery needs and updating replacement costs in property insurance policies annually are essential steps.

Moreover, creating a "people plan" is vital, as disasters affect employees as much as operations. Establishing robust communication systems for employee support and providing essential resources such as food and medical benefits during crises ensure both operational continuity and workforce stability. Organizations that prioritize resilience are better equipped to maintain operations and recover quickly, gaining a competitive edge.

See also: Cyber Incidents Top Global Business Risks in 2025

Leveraging data and analytics for strategic decision-making

One of the essential actions businesses need to take in 2025 is leveraging data for strategic decision-making. The shift from cautious experimentation to widespread adoption of analytics is accelerating. Businesses that harness advanced analytics gain crucial insights into risk exposures and can "see around the corner."

Leading organizations are using data-driven strategies to optimize insurance costs, enhance employee benefits and improve decision-making alignment across the organization. By embracing analytics, companies can improve resilience and employee engagement, positioning themselves as leaders in navigating emerging risks.

Addressing cyber and geopolitical risks

Addressing emerging cyber and geopolitical risks is also a significant focus in 2025. The digital and geopolitical landscape presents challenges that businesses must address to secure profitability. Cyber threats, including ransomware, deepfakes and social engineering, are growing in sophistication. Projected global costs from deepfake fraud alone are estimated to have reached $1 trillion in 2024.

However, not all companies currently hold cyber insurance policies. To enhance cybersecurity preparedness, businesses should evaluate exposure to cyber risks, consider data retention policies and employee training, and offer employees cyber protection tools to safeguard both personal and corporate information. Securing comprehensive cyber insurance coverage tailored to evolving threats is crucial.

Geopolitical risks, often perceived as distant issues, have direct impacts, such as supply chain disruptions and regulatory changes. To mitigate these risks, companies should invest in political risk insurance to manage potential losses from political violence or government actions and use trade credit insurance to protect against payment defaults by foreign entities. Collaborating with vetted insurance partners in target regions ensures compliance with local policies and strengthens international operations.

Enhancing employee productivity and well-being

Employee productivity remains a top priority for 2025, as businesses face rising costs for medical benefits, pharmacy drugs and compensation. Companies are increasingly aligning total rewards with productivity metrics, emphasizing efficiency and innovation.

To enhance workforce vitality, more businesses are adopting a human-centric approach, building workplaces that prioritize well-being, flexibility, social connection and continuous learning. Leveraging data analytics helps identify cost-saving opportunities, especially in healthcare and pharmaceutical expenses. Additionally, reducing financial stress by offering solutions such as personal insurance coverage and financial coaching supports employees' financial health and improves productivity.

See also: Rising Climate Risks Demand New Strategies

Treating insurance as a strategic asset

Insurance should be a strategic tool for mitigating complex risks, protecting reputation and safeguarding the bottom line in 2025 and beyond.

Companies must conduct annual reviews with their broker to ensure policy limits and replacement costs are up to date. Additionally, they should explore alternative risk transfer solutions, such as captives and parametric insurance, to address gaps in traditional coverage.

By guiding organizations in adopting advanced analytics to better understand risks and employee needs and offering tailored solutions for employee well-being and financial security, brokers enable companies to achieve growth, resilience and operational excellence.

Thriving amid uncertainty

Insurance in 2025 requires integrating data analytics with strategic risk management. Organizations can navigate challenges by treating insurance as a strategic asset while building resilience against emerging risks. Expert partnerships and employee wellness programs help companies adapt to uncertainty.


Tim DeSett

Profile picture for user TimDeSett

Tim DeSett

Tim DeSett is the North American commercial lines president for HUB International. 

With more than 30 years of experience in the insurance industry, DeSett came to HUB from a leading P&C broker, where he served as executive vice president of P&C. Prior to that, DeSett was the head of North America field operations and distribution for AIG. 

AI Transforms P&C Insurance Data Governance

Generative AI enhances P&C insurance data governance, automating processes while strengthening regulatory compliance and data quality.

People Discuss About Graphs and Rates

Accurate and well-governed data is critical for success in today's data-driven P&C insurance industry. But the sheer volume and complexity of data presents significant challenges to insurers, which must manage complex regulatory requirements while ensuring accuracy for underwriting and claims processing.

Conventional data governance methods often struggle to keep pace, leading to data quality issues, compliance risks, and missed opportunities for insights. Generative AI offers the opportunity to automate processes, improve data quality, and gain competitive advantage through well-informed decisions and streamlined operations.

At its core, Generative AI uses deep learning architectures to create models that learn complex statistical representations of the data they have been trained on and generate new data that conforms to the learned distributions. Unlike discriminative AI/ML models, which are designed for tasks like classification and prediction based on existing data, Generative AI models focus on generating new data. This capability enables a wide range of applications, from synthesizing text and images to generating synthetic data for testing and training other models and creating metadata or data quality rules for an analytical pipeline.

See also: How AI Can Maximize Unstructured Data

Here are some of the ways P&C insurance companies are leveraging Generative AI to address key data governance challenges and unlock opportunities:

  • Improving data quality through automated metadata generation and data quality rule creation
  • Streamlining data stewardship and metadata management processes
  • Strengthening compliance with evolving regulatory requirements

Generative AI helps insurers automate the generation of metadata for business attributes, tailored to their specific terminology and standards. This not only standardizes existing metadata but also generates information for missing metadata, which is particularly helpful with legacy systems that may not have good metadata definitions in place. Effective implementation of AI models and integration with data quality and data observability platforms enables continuous monitoring and improvement of data quality. This approach helps generate comprehensive data quality rules, consistently identify critical data elements for operational reporting and apply company-specific language for business glossary definitions.

Data stewards play a vital role in data governance, ensuring quality, integrity, and security of the company's data assets. Generative AI significantly reduces the workload for the data stewards by enhancing metadata management and keeping data catalogs current and comprehensive. Strategic integration of AI into data governance workflows can deliver time savings ranging from 50% to 90% for data stewards on tasks such as generating business definitions, identifying critical business attributes, and creating data quality rules, helping data stewards focus on strategic, human-in-the-loop activities that maximize the value of their subject matter expertise.

See also: A Data Strategy for Successful AI Adoption

AI-driven data classification can significantly strengthen regulatory compliance and enhance the protection of sensitive information. By analyzing both sensitivity (e.g., PII, PHI) and contextual attributes (e.g., document type, ownership), AI models, including those leveraging computer vision and natural language processing, extend discovery and classification to documents, images, and other unstructured data. This contextual understanding enables far more effective classification than traditional methods based on text patterns.

Data protection and governance platforms now provide pre-trained models and the flexibility to incorporate custom-trained models to accomplish this. Language models can also automate the monitoring and analysis of regulatory changes published by state insurance departments, the NAIC, and other relevant authorities, assessing their impact on existing policies and processes.

The convergence of AI and data governance presents a significant opportunity for P&C insurance companies to transform their operations and gain competitive advantage. However, successful implementation requires deep expertise across all these domains.

AI Shapes Insurance Industry's Digital Shift

AI transforms insurance operations, promising faster claims, personalized products and enhanced fraud detection capabilities.

AI

Artificial Intelligence (AI) is disrupting the insurance space at a remarkable rate, building a new ecosystem based on accuracy, efficiency, and customer-centricity. It is changing the way we look at all the legacy insurance functions, like claims processing, personalized customer experience, and fraud detection.

As the adoption of AI expands, more tailored products can be delivered, claims can be responded to faster, and risks can be mitigated. Progress never comes without hurdles, though, and new challenges in the form of regulatory compliance and data security make it imperative for insurance enterprises to have a strategic approach while implementing AI. 

In this article, we will explore how AI can deliver impact across different touchpoints of the insurance value chain.

Disrupting Underwriting and Claims Processing

Underwriting is one of the highest-value activities across the policy lifecycle, performed by highly skilled and highly paid resources. Most insurance carriers follow a first in, first out (FIFO) system with no consideration for the criticality of a claim, which places undue pressure on underwriters and leads to a sub-optimal experience for customers. AI's intervention at this touchpoint of the insurance value chain can be transformative as it can enable automated screening of proposals and ensure that they are assigned to the right resources based on priority.

Generally, settling a claim has taken a few weeks or even months due to issues with potential fraud detection and the efficiency of verification processes. However, AI can accelerate this process by up to 40%, satisfying customers while reducing operational costs. AI also makes it possible to identify patterns in claims data along with easy verification of records, including visual evidence, mainly due to the advent of image recognition technology. Early warning and fraud detection using AI help in identifying certain patterns that can help define rules to better identify potential fraud based on data accumulated over time. Furthermore, the use of AI in claims digitalization can better enable straight-through processing, first notice of loss (FNOL), ease of registration and faster settlements.

See also: How AI Will Transform Insurance in 2025

Maximum Impact on Tailored Customer Experience

Traditional insurance players haven't had access to precise information like customer behavior, lifestyle factors, or past interactions. With AI, insurance companies can deeply analyze the vast amount of customer data available to them and develop highly personalized insurance products and experiences. Customer-oriented data is fed into an AI-enabled chatbot that provides automated recommendations of the best-fit insurance products. Such personalization of the insurance products can directly boost customer loyalty and satisfaction.

Insurance GPT: the New Norm

Insurance companies are looking to develop a custom-built AI GPT tool that is focused on the specific needs and workflows of their industries to significantly enhance customer experience, boost operational efficiencies, and ensure data engineering readiness.

Here are some of the areas where insurance GPT can have the biggest impact:

  • Policy Distribution: Insurance agents or websites typically specialize in selling targeted policies. However, this specialization limits their ability to identify and capitalize on cross-selling and upselling opportunities. With the advent of insurance GPT, agents can go beyond their area of specialization and effectively position other complementary policies or offerings that may be of use to a customer. Agents can also look up queries in real time, handle objections effectively and better articulate the combined value proposition of different offerings.
  • Service Management: Effective service management entails handling structured and unstructured data that might be found in various form such as web forms, Excel sheets and PDFs. AI can greatly simplify the process of converting unstructured data to structured data with a pre-built context to increase operational efficiencies.
  • Integration: As in every industry, insurance companies are also mired in legacy investments in technology that may not be compatible with modern AI journeys. Hence, it is important for an insurance GPT to be compatible with third-party applications and ensure seamless integration by serving as an AI and user experience (UX) wrapper.
  • Reporting: Data that is often found in silos within legacy systems across different form factors isn't very usable. An insurance GPT can facilitate greater visibility and transparency by leveraging AI for dashboards, management information systems (MIS) and reporting, thereby keeping businesses ready for the data and AI revolution.
  • Customer Engagement: With the sheer amount of data that is generated in the insurance industry, account managers or agents find it difficult to have the necessary insights needed to ensure a great customer experience. Insurance GPT can streamline all customer conversations and provide a 360-degree view of a customer, which can help an insurance provider drive better customer engagement while improving policy renewal rates.

See also: How AI Is Changing Insurance

Conclusion

As the use of AI expands, it is bound to leave a huge footprint on the current regulatory environment, which includes data privacy laws and ethical usage standards for AI. Making sure that modern AI tools comply with rules and regulations around data security and consent is essential to gaining public confidence and building accountability and transparency.

In 2025 and beyond, AI is set to drive significant transformation across the insurance industry, delivering substantial benefits in areas like risk management, claims processing, fraud detection, and underwriting. Insurers must be ready to fully leverage AI's potential by making strategic investments in technology and developing a well-structured roadmap to tackle emerging challenges as the industry's AI adoption accelerates.

By making this technology shift responsibly, insurance companies can unlock immense value for customers, offering unprecedented agility and predictive capabilities. As insurers evolve to meet shifting customer expectations and regulatory requirements, AI emerges as both a transformative tool and a catalyst for a more resilient, customer-focused future.


Subhasis Bandyopadhyay

Profile picture for user SubhasisBandyopadhyay

Subhasis Bandyopadhyay

Subhasis Bandyopadhyay is the head of the Banking, Financial Services & Insurance (BFSI) Industry Group at Happiest Minds. 

In his 30 years of professional experience, he has worked across a spectrum of marquee organizations, such as Oracle Financial Services, Birlasoft, and Mindtree, where he led their BFSI practices. 

He holds an MBA in finance and marketing from the University of Calcutta.