Download

Insurers Stay Optimistic on Investment Returns

U.S. insurers remain optimistic for 2025 despite political concerns, showing increased appetite for private assets and risk-taking.

Commercial Lines

U.S. insurers appear to remain generally optimistic about investment conditions for 2025 and expect to continue to take on more investment risk, according to a recent survey of 310 investment decision makers in the U.S. insurance industry commissioned by Conning.

The recently completed election season also seems to be weighing on insurers' minds as the domestic political environment was the top portfolio concern of 10 choices listed, even though the survey was conducted after the November 2024 elections. Portfolio yields and market volatility were tied as the second greatest concern. Inflation, which had ranked as the top concern in the previous three investment risk surveys, fell to seventh among respondents.

Insurers continue to express interest in private assets and expect their current exposures to grow. The bulk of respondents (71%) currently have between 5% and 20% in private assets. In two years, a majority (63%) expect to have between 10% and 25% in private assets.

The majority of respondents also said they expect to maintain or increase duration in 2025 as well as exposure to floating-rate assets, and almost all are confident they can meet the liquidity demands of their business.

See also: 20 Issues to Watch in 2025

Optimism, Less Inflation Concern, Comfort With Liquidity

Overall, the respondent group remained optimistic regarding the investment environment in 2025, although the optimism has slipped a few points since the last survey and pessimism has risen slightly.

For the third year in a row, the majority of respondents also said they expect to increase their investment risk in the year ahead, although their inclination has been easing over the past three surveys. Respondents with the largest firms were the least likely to increase risk and the most likely to decrease it. Those outsourcing asset management were also more likely to decrease investment risk than those managing assets internally.

A major change in the leading portfolio concerns during the next two to three years among respondents was the significant decline in inflation worries, which had been the top concern among respondents the past three surveys (and remained the primary worry for the smallest firms). Of a list of 10 portfolio concerns, the domestic political environment was first, followed by investment yields and market volatility (tied), geopolitical events and the impact of artificial intelligence/model risk.

The political environment category was added in the prior year's survey and proved to be a major worry again in this survey, although it was not a leading concern for the largest insurers, which identified yields and market volatility as their top threats. Monetary policy rated among the lowest in the list of concerns (except for insurers with between $5 billion and $10 billion in assets).

Liquidity was the lowest concern (it was slightly higher for property-casualty firms than life), a point to note given the increasing interest in adding less liquid private assets to portfolios. In separate questions, respondents voiced confidence in having the necessary portfolio liquidity to meet business needs. Nearly half (48%) said their portfolios had an appropriate amount of liquidity, and 30% said they had too much. Only 12% said they had too little. And the vast majority (92%) agreed or strongly agreed that their companies are well positioned to address liquidity needs for their operations.

Cost control and the need for expertise in analytical capabilities in risk management and asset allocation remained the top reasons for insurers to outsource asset management. The next greatest reason to consider outsourcing was accessing different investment strategies.

Patience With Asset Allocation, Seeking More Private Assets

Respondents also indicated they do not anticipate a rush into particular asset classes, another sign of restraint compared with the prior year's survey. For example, 63% of respondents to the 2023 survey expected to increase exposure to investment-grade fixed income, not surprising given the opportunities apparent from rising yields in late 2023. Six other categories saw at least 50% of respondents expect to increase exposures. In our most recent survey however, none of the 12 asset classes listed saw more than 47% of insurers expecting to add exposure; responses generally were higher in the "no change" or "decrease" options in comparison with the prior year results.

However, momentum appears to remain for moves into private assets.

The exposures to private assets from our most recent survey respondents almost matched the prior year's survey, with 71% currently holding between 5% and 20%. While respondents expect moderate growth in their exposures, there was some tempering at the higher end: 17% expect to have 25% or more in the asset class, down from the 25% who projected this level of exposure in the prior year's survey.

Private assets are not without their own risks, as insurers know, and tops among them for respondents was the impact on liquidity; 31% said they were "very concerned" about it, clearly an area of focus for insurers given their stated comfort with current portfolio liquidity overall. Concern about sourcing private assets, having data/analytics to support them, and management/board approval, were less of a concern.

Floating Rate Strategies and Duration

Responding to a separate question, the large majority of those surveyed said U.S. Federal Reserve policy affects their investment strategy "moderately" or "significantly," and Fed policy has a significant impact on floating-rate strategies. In the year ahead, 53% said they expect to increase exposure to floating-rate strategies, and a further 25% said their exposure will remain the same.

While insurers expect to increase exposure to shorter-duration floating-rate assets, overall duration is expected to increase, suggesting the duration barbell will be popular this year. A number of insurers in 2024 sought to extend duration in the portfolio, a strategy that appears popular for 2025: Nearly two thirds of insurers (64%) said they expect to increase duration this year, and only 14% expect to decrease.

Market conditions in 2024 seemed to suggest that portfolio turnover might be on the rise, and half of all respondents confirmed that they had more turnover in 2024 than the prior year; only 22% said it was lower, with 28% saying it was the same. Of those who had more turnover, the leading reason (62%) was a tactical decision given market opportunities. Of those who had lower turnover, their leading reason (53%) was a limited ability to reposition. In both groups, change in risk preference was the least-chosen reason.

See also: What Trump 2.0 Means for Insurance

Investment Managers' Role in Market Navigation

The survey finds that insurers remain a generally optimistic group but do see challenges in the year ahead. While the scourge of inflation appears to have eased, at least for the time being, and interest rates have declined, uncertainty remains over the future direction of rates and the potential for volatility, both in markets and the political environment. Insurers continue to broaden and diversify their portfolios and are expressing clear interest that they expect to add more private assets, and they will likely be careful to assure that they can maintain their confidence in meeting their companies' needs for liquidity.

The circumstances of each insurer's business goals, risk tolerance, and book of business help reinforce the view that insurers often require customized solutions to address their unique needs. They may be best served by investment managers with a deep understanding of insurance asset management to help them develop valued investment strategies and navigate any volatility that may arise.


Matt Reilly

Profile picture for user MattReilly

Matt Reilly

Matt Reilly, CFA, is a managing director and head of Conning’s Insurance Solutions group.

He is responsible for the creation of investment strategies and solutions for insurance companies. Prior to joining Conning, he was with New England Asset Management.

Reilly earned a degree in economics from Colby College.

Digital Benefits Tools Drive Employee Wellness

Digital tools are transforming how employees access and use workplace benefits, creating opportunities for brokers to enhance engagement.

Woman in Blue Shirt Sitting Beside Woman in Red Shirt

Many employees today may find themselves in the beginning months of a new benefits period. Yet whether they re-enrolled in the same policies they had previously or elected new ones, they might not make full use of their non-medical workplace benefits throughout 2025 without fully understanding the coverage and services available to them.

To help change this trajectory and empower consumers to take advantage of their benefits, carriers today are investing in digital tools more than ever before to provide members with resources that meet their well-being needs. These solutions are focused on making learning about and accessing both insurance and non-insurance coverages as simple and intuitive as possible. This presents a unique opportunity for brokers to connect the dots for employers and their workforces. By advising their clients on how to make the most of digital tools and resources across benefit offerings, brokers can help support employee well-being in the year ahead.

See also: How Wearables Can Improve Worker Safety

Showcasing the richness of available support

To encourage engagement and offer comprehensive coverage, some carriers have begun to include wellness resources directly within traditional insurance products. If employees don't know about these benefits, they can't use them—and the implications can be significant.

Take the millions of full-time working Americans who have non-work-related caregiving responsibilities. A recent Guardian study found that these caregivers are two times more likely than non-caregivers to need to take a leave of absence from work. Employer-provided disability insurance may offer curated caregiver support solutions, including digital planning tools, a caregiving concierge, and a peer support network. These resources can help to minimize the need for an employee to take a leave of absence for caregiving duties. Given this approach remains innovative today, supporting awareness and access through digital self-service channels is critical.

Tobacco cessation is another example. While smoking rates are down overall, there is an alarming increase in teenage vaping rates, and almost a third of working Americans continue to use tobacco products, according to Guardian research. Yet two-thirds of workers say they would be very interested in using a tobacco cessation program through their dental insurance plan if it was complimentary.

Ultimately, embedded wellness offerings that leverage digital touchpoints to offer frictionless access to services can help make a difference when it comes to fostering employees' mental, physical, and financial well-being. As workers look to make the most of their benefits this year, brokers can help their employer clients educate their workforce about any wellness offerings included in their benefits package to ensure they use all available digital features and, in turn, tap the full scope of these resources.

Leveraging digital platforms to streamline information

Digital features are key to enhancing wellness offerings, but they're not the only way that tech-enabled solutions can encourage benefits usage and support well-being. There is also an opportunity to make important benefits information and related resources easier to access.

What does that look like in practice? Our research shows that more than 51% of employers would be interested in a single platform through which all wellness-related benefits could be made available. Further, employees who have access to a more digital benefits experience self-report better well-being than workers who don't.

In response, carriers are working to bring this digital experience to life through various digital hubs designed to help ease access to wellness benefits for members. These platforms typically include educational content on mental, physical, and financial well-being, as well as family and community support topics. Additional resources often include third-party fitness classes led by virtual instructors for people of all fitness levels, as well as wellness articles that are regularly refreshed and focus on the connection between mental and physical health.

For employers looking to offer a more comprehensive digital benefits experience for employees, brokers can use the opportunity to highlight the resources carriers are making available to streamline information and drive engagement.

See also: 'Bleisure' Travel Is on the Rise--and It's Complicated

Now is the time to get started

At a time when technology is integral to so many aspects of our everyday lives and carriers are embracing digital tools like never before, brokers can play a key role, supporting employers in helping their workforce to make the most of digital offerings.

When employees understand how to leverage the benefits available to them, including through embedded digital offerings or streamlined digital platforms, they're more likely to use them. It's a crucial way that brokers and employers can support employee well-being across mind, body, and wallet.

Is Extreme Weather in Middle East a Trend?

Climate change intensifies extreme weather risks in the Middle East, challenging traditional insurance models and renewable energy projects.

Dubai, United Arab Emirates, Cityscape

The climate in the Middle East has seen an increase in the frequency of both hailstorms and heavy rains.

Oman has been experiencing cyclones on an almost annual basis, with the latest being Cyclone Asna in August/September 2024. One of the most damaging to date was Cyclone Gonu, which hit Oman and the east coast of the UAE in 2007, resulting in 70 deaths in Oman and 10 in Fujairah, as well as significant damage to property (estimated $4 billion of damage in Oman).

Saudi Arabia is no stranger to extreme weather, with flash floods hitting the country on several occasions in the 1970s, 1990s and more recently in 2009 and 2011 when flooding hit Jeddah, causing average damages of around $3 billion per event.

The UAE has seen irregular extreme weather events over the last 70 years, mostly in the form of flash floods due to intense rains, and it is possible that future events will increase in magnitude as the climate changes.

Interestingly, none of the major natural catastrophe tools used by the insurance industry today show any sort of major (extreme) natural catastrophe risks in the Arab Gulf region (other than one-in-50-year return storm surges in coastal areas). The renewables industry, and solar farms in particular, have been severely affected by severe convective storms in other parts of the world, most notably in North America. Hail damage is a rare but not impossible phenomenon in the Middle East, and the UAE has recently seen hail damage to infrastructure and vehicles, even though the size of the hail has so far been modest. 

Will that change with changes to the climate? Although unlikely to have the same impact as on the North American renewable industry, some negative future effects are possible.

See also: Insurers Must Evolve to Survive Climate Crisis

Predictions

The confidence in the forecasts of cyclones and flash floods remains low due to their relative rarity and the scale of the event. While cyclones are large events that can be captured by weather forecast models, the direction of the cyclone and its impact is much harder to forecast. The intensity of a cyclone depends on a large number of factors, including the track the cyclone takes, which itself is influenced by several factors that are difficult to predict, e.g., sea surface temperatures and other weather patterns.

Flash floods are much harder to forecast, as the processes that lead to them are typically only a few kilometers in size, smaller than the resolution of most forecast models. Flash floods are typically caused by sub-daily rainfall extremes, caused by localized heating, resulting in an unstable atmosphere and leading to a convective storm (which can also cause hail). However, whether the rainfall is absorbed by the ground or overflows resulting in flash flooding depends on the preceding conditions – too wet a ground means it cannot absorb any more rain, too dry a ground reduces its ability to absorb rain.

Climate change projections for the Arabian Peninsula show an increased risk from extreme rainfall that most typically leads to flash flooding. A warmer atmosphere can hold more moisture, thus when the conditions that favor extreme rainfall, and thus flash flooding, occur there will be more moisture in the atmosphere, leading to more extreme rainfall.

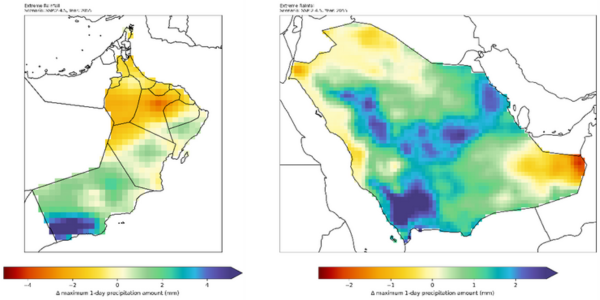
Figure 1 shows changes in extreme rainfall by 2055 under the SSP2-4.5 warming scenario (the current most likely warming scenario) using data from climate risk models. It shows that there is a large variation within both Oman and Saudi Arabia to changes in the rainfall pattern. Southern Oman shows a large increase in rainfall, directly leading to an increased risk of flash flooding. While northern Oman shows a decrease in extreme rainfall, this does not necessarily result in a decreased risk of flash floods. A drier soil could result in less rain being absorbed by the ground, increasing the risk of flash floods when extreme rainfall does occur.

Saudi Arabia (at right) has a much larger region showing an increase in extreme rainfall, where the majority of Saudi Arabia sees an increase in extreme rainfall occurrence. This suggests that the risk of flash flooding across the country will increase.

Figure 1
Figure 1: Data from Aon’s Climate Risk Monitor showing increases in extreme rainfall in southern Oman (left) and central Saudi Arabia (right).

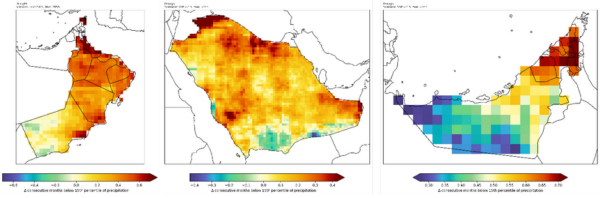
Figure 2 also shows an increase in drought risk across Oman, Saudi Arabia and the UAE for the SSP2-4.5 scenario. This will lead to drier soil conditions, particularly in the summer, increasing the risk of flash flooding from extreme rainfall. The data is not able to capture the processes that lead to sub-daily rainfall events; however, it does show that the conditions favor an increase in flash flooding risk.

Figure 2
Figure 2: Data from Aon’s Climate Risk Monitor showing increases in drought risk across Oman (left), Saudia Arabia (middle) and north-east UAE (right), although decreases in drought risk in UAE can be seen in the south-west.

There are other perils that may become worse due to climate change and thus potentially start causing significant losses in the region, in particular hail. The impact of climate change on hail remains very uncertain, due to the scale at which the processes that lead to hail occur. However, most projections for hail are for an increase in size and occurrence. This could have a big impact on the renewable energy sector, specifically solar panels, which remain vulnerable to hail and haven't seen that kind of damage in this part of the world yet. We also need to consider the changing nature of perils; with cyclones holding more moisture, we could see a greater impact from the rainfall/flooding from a cyclone, and not the wind, as traditionally seen.

Impact of Mitigation Aids

Improved forecasts of cyclones can reduce the impact through mitigation measures, e.g., increasing the resiliency of buildings, boarding up windows, and removing potential debris. Examples of this can be seen most recently in Florida in preparation for Hurricanes Helene and Milton. While losses were still experienced, they were smaller due to the warning and preparation. Florida also requires that when greater than 25% of the roof is damaged, the whole roof is to be repaired to new building codes. This has resulted in an increased resilience of buildings to hurricane winds.

A similar approach can be taken to flash flooding, even if it is more difficult to forecast. Improved drainage, identifying potential blockages and flood resiliency schemes that absorb water for short periods can significantly reduce the impact from flash flooding. It is also possible to increase the resiliency of assets to flash flooding by identifying potential water ingress locations and adapting them to prevent the ingress of water.

See also: Severe Weather's Effects on Auto Claims

Conclusions

An analysis of Oman and Saudi Arabia shows localized increased risk of extreme rainfall and subsequent flash floods if the SSP2-4.5 scenario becomes reality. Analysis data can be used to reduce long-term risk to a project by applying mitigation measures for future scenarios at the design stage of the project.

Will we eventually see weather events having an impact on premiums given the rapid deployment of renewables in the region? Although unlikely in the near future, a single damaging event (even if isolated) could have a massive impact on the market. The recent flash floods in the UAE caused severe damage to the Noor 1 Concentrated Solar Plant, possibly reaching a staggering $500 million of insured damage.

Insurers have until recently been relatively happy ensuring that an asset is adequately protected for a one-in-100 or one-in-200-year flood. We are now starting to see instances where insurers move toward requesting the one-in-500-year flood to be the governing condition for flood protection. This trend is likely to continue and might also come with requirements for predictive models to be used for large market assets to determine present and future natural catastrophe risks. The key is how these risks are managed and resiliency is embedded.


Adrian Champion

Profile picture for user AdrianChampion

Adrian Champion

Dr. Adrian Champion leads climate analytics for UK & EMEA across Aon's Risk Capital. 

He has a PhD in meteorology and spent 10 years in academia and at the U.K. Met Office.


Zaid Laftah

Profile picture for user ZaidLaftah

Zaid Laftah

Zaid Laftah is the head of AGRC and natural resources for the MENA region at Aon. 

He has over 17 years of experience from the refining and petrochemicals industry.

Gen AI: The Game Changer Insurance Has Been Waiting for

Generative AI promises to revolutionize customer engagement, yet only 10% of companies fully embrace its transformative potential.

businessman giving contract to woman to sign

The way consumers experience insurance is on the brink of change, as digital innovations revolutionize the user experience. Yet while many insurers are keen to embrace artificial intelligence (AI), few are using it to drive profound impact.

KPMG observed that the primary driver for digital adoption was to simplify existing processes. This tunnel-vision approach is all too common and misses the powerful potential of generative AI (Gen AI) to transform business models and the way modern insurers operate.

The insurance sector is ripe for reinvention, and the case for Gen AI adoption is compelling, so why does research by Boston Consulting Group indicate that just 10% of companies are applying Gen AI at scale?

Many will agree that the insurance industry is risk-averse, and this "digital reluctance" is likely to be a major stumbling block. Standing still in an ever-changing world is not an option.

Thankfully, a small, growing number of forward-thinking insurers are carrying the torch of innovation. They truly understand that Gen AI is key to transforming the entire value chain, redefining customer interactions, improving operational efficiencies and, ultimately, setting a new bar for industry standards in the digital age. Most importantly, they recognize that Gen AI cannot simply be an afterthought but requires a commitment to companywide integration and a desire to evolve continually.

See also: AI in Insurance: 2025 Predictions

Embedding Gen AI Across the Value Chain

When fully integrated into an organization, at the heart of corporate strategy, Gen AI can achieve new heights in insurance distribution, operations and customer excellence.

Gen AI can enhance agent recruitment and retention strategies, streamlining the hiring process by efficiently sifting through vast amounts of applicant data to identify top-quality candidates. These tools increase the number of high-caliber recruits and ensure a better fit for the organization's specific needs. Furthermore, Gen AI can identify high-potential agents early in their careers, facilitating their growth through targeted and personalized coaching, upskilling and reskilling and development programs, ultimately improving retention.

Productivity gains are plentiful, with Gen AI empowering agents through an optimized sales journey, providing real-time assistance by analyzing customer needs, identifying gaps and prompting agents with product recommendations tailored to customers' specific needs.

Through Gen AI, agents will receive leads enriched with customer insights and product recommendations that are best aligned to their preferences and needs. Draft emails and suggested marketing content will be ready to go at the push of a button, saving agents valuable time while ensuring engagement with customers remains personal and tailored. The nurturing of leads through to conversion will also be enhanced with automated and timely communications. Gen AI can also help manage agents' performance more intelligently by simulating agent and team performance and recommending action plans to achieve targets.

From an operational perspective, Gen AI can provide medical and financial document summarization for underwriters and claims assessors, resulting in scalable operations, increased staff productivity and unit cost reductions. Customer queries are addressed more effectively, with contextual responses based on previous customer conversations, knowledge bases and policy-specific information. Contact centers are better equipped to provide personalized responses based on customer history and product information, enabling staff to focus on resolving more complex cases. Moreover, Gen AI can inject highly sophisticated social media marketing capabilities into agency apps to create compelling ways for agents to attract and engage with an entirely new customer base.

See also: Blending AI With Human Interaction

Safeguarding the Use of Gen AI

Gen AI is more than just an operational add-on for insurers; it must be embedded into the organization's very culture to maximize operational efficiencies, enhance the user experience and build trust.

Transformational projects require innovative leadership, significant investment, companywide buy-in and rigorous safeguarding to ensure the use of Gen AI remains ethical, accountable and transparent. That's why it is essential to establish a robust framework to assess existing AI risks, including reliability, fraud, impersonation risks, privacy and data governance, and new-gen AI risks, such as the generation of false, misleading or biased information.

Embracing Gen AI is a substantial undertaking for the modern insurer, but with a robust action plan, sustained budget and dedicated project team driving it forward, companywide integration can be achieved in just a few short years.


Biswa Misra

Profile picture for user BiswaMisra

Biswa Misra

Biswa Misra is group chief technology and life operations officer at AIA Group. He is also responsible for the group’s business operating in New Zealand and Sri Lanka. 

Previously, Misra served as the regional chief technology officer for ING Insurance Asia Pacific. He also spent six years with information technology consulting firm Capgemini.

Misra holds a degree in electrical engineering from the National Institute of Technology, Surat, India.

Why Tesla Insurance Will Flop

Even as the decision to bring underwriting in-house is generating enthusiasm, a host of issues means Tesla Insurance will flounder. 

Image
tesla tire

Tesla's recent announcement that it is bringing underwriting in-house for its car insurance unit generated enthusiasm about the prospect of taking data-driven auto insurance to the next level. But I have a different take.

I agree that what Tesla is doing is the next logical step in having sensors in cars feed data about driver behavior directly to underwriters to improve their understanding of the risks. In time, that path could take us to a world where behavior is being monitored in real time and feedback provided to drivers in the form of higher or lower premiums. Encouraged to be careful, those drivers could make the roads safer for all of us. 

But I don't think Tesla is the right, well, vehicle for that next step, for a host of reasons.

I'll explain.  

Tesla CEO Elon Musk has frequently overpromised and underdelivered over the past decade, primarily on the prospect for fully autonomous driving but also on insurance. After he launched Tesla Insurance in 2019, he said it could soon account for 30% to 40% of Tesla's value. Based on Tesla's market cap today, that would imply a value of $330 billion to $440 billion. For comparison's sake, Allstate has a market value of about $50 billion. Anyone think Tesla Insurance, with a $42 million net underwriting loss for the first nine months of 2024, is worth six to nine times Allstate? 

Musk has said Tesla owners should get discounts on insurance because Tesla Autopilot is so much safer than human drivers, but analysts say he fudges the numbers on accidents, and a recent study found that Teslas actually had more accidents per vehicle than any other make in the U.S. last year, as they did in 2023. Starting with bad assumptions doesn't exactly lend itself to good underwriting. 

If your publicly stated starting position is that you should offer discounts, and your drivers are no safer or perhaps even less safe than those insured by others, you're in for a rough ride. Perhaps Musk has hired great people and perhaps they'll be very careful as they bring the underwriting in-house, but caution isn't part of Musk's personality or the company's. And we've seen how hard it can be to get the formula right even at seemingly prudent startups such as Root and Metromile. 

Musk has been known to power his way through problems before, including at Tesla, but he's CEO of five companies at the moment... and has a day job in Washington, DC that appears to be all-consuming. So he's unlikely to wade into Tesla Insurance any time soon.

Besides, Tesla has bigger problems these days than its insurance operation. Sales fell for the first time last year, even though the market for electric vehicles is growing rapidly and even though Tesla had posted sales gains of 38% and 40% in the two prior years. 

Tesla's stock has soared more than 40% since the U.S. presidential election on investor hopes that Musk's $278 million of contributions to the Trump campaign and vocal support via Musk's social media platform, X (formerly Twitter), will translate into success for the business. But the tenor of the Trump administration is, in fact, very much opposed to electric vehicles. Last week, Senate Republicans introduced bills that would not only repeal the $7,500 tax credit for electric vehicles that was Tesla's lifeblood in years past but would charge a $1,000 fee on every new EV sold.  

Musk may have other political problems, too. Suspicion is growing that the sales slump partly stems from Musk's hard-right turn politically, which has angered lots of people in what was considered to be Tesla's sweet spot: well-off consumers worried about climate change. An article in Wired says the potential trouble extends to Europe, where Musk has waded into politics in support of right-wing parties in England and Germany. Wired says Tesla sales dropped 13% in the European Union in 2024, and the decline may be accelerating. 

"Last month, Norway—where EVs overtook internal combustion vehicles in total market share in 2024—recorded a biting 38 percent slump. At the same time, Tesla sales in France fell by a thumping 64 percent. And it gets even worse: In Spain, Tesla sales plummeted by 75 percent.... Tesla registered only 1,277 new cars in Germany in January, a year-on-year drop of 60 percent.," Wired says.

I also think he's going to have a major problem come June, by which time he's promised to roll out a fleet of robotaxis. Based on the lofty stock price, I may be in the minority. But I've been following autonomous vehicles closely since starting on a book on driverless cars that Chunka Mui and I published a dozen years ago, and I can't believe the technology is ready. 

Waymo has been cautiously rolling out its robotaxis for years, based on technology that includes radar, lidar and cameras. It's only operating in geofenced areas that it's mapped in excruciating detail. Yet Musk says he'll be able to put out a fleet that uses only cameras and that can go anywhere. 

I just don't see it. 

Now, he's plenty good at distracting people with promises that he'll colonize Mars or whatever if we just give him some time. And he does have X/Twitter to broadcast his messages, as well as a supporter in the Oval Office. But I still believe he'll have to do major damage control. If history is any guide, he'll make some small gesture and promise that the robotaxi fleet is imminent -- he's been making such promises about Tesla Full Self-Driving since 2015.

I still believe in the basic vision behind what Tesla is trying to do with its insurance arm, including the move to bring underwriting in-house. Actual data on driving behavior is obviously far more helpful than something like a credit score when evaluating risk, and other recent attempts to supply insurers with more data face pushback. GM's OnStar has been banned from selling driver data to insurers for five years, and Arity has been sued for allegedly collecting data via cellphone apps without warning drivers that they were being monitored. 

Insurers such as Progressive will obviously still have access to driver data that they obtain directly from customers. But the hoped-for breakthrough in integration between car makers and insurers will have to wait, and I suspect Tesla won't be the first to get there. 

Cheers,

Paul

P.S. Here's how not to sell extended warranties on cars.

'Agentic AI' Rewrites the Rules (Again)

For insurance agents and brokers, "agentic AI" can function as a sales assistant or even a sales agent and carry much of the load for customer service.

Abby Hosseini Interview

Insurance Thought Leadership

I'm interested in what you’ve written about using agentic AI in distribution. Could you explain the framework for how you're thinking about the use of AI agents in the agent and broker space?  

Abby Hosseini

AI has been part of the insurance industry for 25 to 30 years. We’ve been using different disciplines, such as natural language processing [NLP], deep learning, machine vision, and robotics, in the front office, back office, and middle office. A few years ago, we saw the rise of robotic process automation (RPA), and chatbots have been around for 20 to 25 years in the form of FAQs, NLP, and search engines. The latest trend involves generative AI, which produces content or knowledge, while agentic AI takes it a step further by doing something with that knowledge.

Agentic AI orchestrates processes or uses machine learning to achieve specific outcomes. There's a distinct difference between generative AI, which focuses on knowledge creation, and agentic AI, which can make processes happen. 

Companies are trying to understand the new technology, deciding which large language model to use, and considering security, governance, and risks. There's been a lot of focus on choosing among Google, OpenAI, Anthropic, and Microsoft, but less on actually implementing the technology. A significant challenge is that, without good data, there is no AI. Many process owners in insurance and banking struggle with poor data quality or lack confidence in the data used for decision-making.  

Insurance Thought Leadership

Why is the data not clean enough, and what can be done about it?

Abby Hosseini

Good question. That's a good segue into the distribution side of the house, because data is created by agents, mostly independent agents, as well as by customer service and claims adjusters. If you're lucky, you have good data entry tools and core systems with some governance or control around what to input into the system. However, poor data entry is causing data quality issues. A lack of governance around the definition of the data or the ability to understand what a field means is another issue. For example, if a field is called "premium earned," what's the exact definition of it? Because there's a lack of common definition and people have taken liberties with how they input data, you end up having challenges with creating a single view of the customer.

For instance, if I say "Jane Doe" versus "Doe, Jane," or spell the word "senior" versus typing "Sr.," the computer doesn't understand these differences and can't tell that the entries are the same. When machines operate on the data, they need some normalization or cleaning. 

In insurance, we expect agents to cross-sell, and for them to do that they need a good understanding of the household and knowledge of what products the person or household is using. A lot of that is missing.

If you have four or five different underwriting systems, as most large carriers do, there is no connection between them. For example, when I was at Mercury, if you were a homeowner customer, you were instantiated in the home system. If you were an auto customer, you were instantiated in the auto system. But there was no linkage or index that says this person here is the same as that person there.

There are a lot of these kinds of problems, but there's also the fact that there's a new age of abundance when it comes to the availability of data, particularly from the internet. Being able to wrangle that data, purchase it, bring it in, and integrate it with your own data has been a challenge.

Insurance Thought Leadership

What’s the solution to the data cleansing issues?

Abby Hosseini

As far as data entry is concerned, you need a robust user interface with good business rules for every field. For example, when the pandemic happened, the company I was at realized we didn't have email addresses for about 45% of our customers. We asked ourselves why and discovered that the email address was an optional field in the agent portal. Someone, 10 or 15 years ago, decided emails were just nice to have. Then the pandemic hits, and you need to go digital, send notices and information, and you realize you can't quite do that.

We had to go back to our agent portal and make it clear that this field is not optional. But even then, people still mistype things. You need to have email address validation in place to catch these mistakes. Software can handle these issues, but there also needs to be human commitment to ensure the data entered isn't just lazy typing or missing critical information.

In insurance, particularly in personal lines, there's still a debate about who owns the customer—the agent or the carrier. This can lead to issues where the agent might not want to share too much information.

Insurance Thought Leadership

You've talked about three specific areas where agentic AI could be applied. Let's start with the sales assistant. What does the current landscape look like, and how might it evolve with AI?  

Abby Hosseini

The concept of AI copilots is already coming to fruition in many respects. These assistants aid salespeople with next best actions, offering contextual products or help, while providing a lifeline for policy, procedure, or product knowledge that the salesperson might be missing.

In complex product sales, like insurance, it's impossible for a human to remember all the specific rules across different locations. For example, knowing the garaging rules in Wisconsin versus Arizona. AI solutions can provide this information contextually, in line with the sales process. Anything related to guidelines, policies, procedures, cross-selling, or next best actions can be facilitated through these Gen AI solutions.

The level of intrusiveness for these copilots is customizable. They can function as a sidekick that the salesperson consults when needed, or as a more supervisory presence overseeing the human's actions.

We're not even considering the direct-to-consumer model yet. In online quote-and-buy scenarios, customers often get confused about certain terms or need product education. They may have questions about what they're buying. In this context of self-service for complex sales, the AI copilot can play a crucial role in educating the customer and helping them navigate the buying process.

Insurance Thought Leadership

I have to say, I always find it funny when I hear the term “next best action.” The first time I heard that, I thought, well, why wouldn't you tell me the best action?  Why just the next-best? I quickly figured out that the term refers to the best action to take next, but I still chuckle in my head.

Abby Hosseini

I think of it as an "if-then-else" scenario. When a customer calls and presents situation X, Y, or Z, there's a fork in the road based on that dialogue -- you either go this way or that way.

While you're solving the initial problem, you might identify an opportunity. That becomes what we call an "aspect section." For example, if you're talking to a homeowner, maybe they don't have an umbrella policy or a car policy. Or if you hear a dog barking in the background, you might ask if they have pet insurance. These opportunities become what we call the next best action, primarily in the context of cost.

Insurance Thought Leadership

Turning to the second of your points about how agentic AI can be used in sales: Beyond acting as a copilot, what would a sales agent in AI look like?

Abby Hosseini

Well, there can be instances where the AI isn’t just providing knowledge or product information but is managing a process. For example, in underwriting, if you have an expensive novelty car or a Monet painting in your house, you can't just write the policy; you have to have some proof. In the old days, pre-pandemic, we would tell the Porsche or Lamborghini owner to drive over to the agent and show them the car. The agent would go out, take pictures, and send them to the carrier. Then the pandemic hit, and nobody could visit anyone else.

So, how do you support that sales process? It needs to be a self-service process where the customer can take pictures and upload them on their own. The customer could call the carrier, and the carrier sends a text message back that says, "Click here." The agent then takes over, guides the customer through taking the picture, uploads it, and brings it back into the underwriting world. This process, which could take days or be very cumbersome before, is now much faster with a good digital experience powered by some sort of orchestration or AI. That's an example of assisting the sales process.

Insurance Thought Leadership

Pardon me while I go take a picture of my Lamborghini and send it to you.

Abby Hosseini

The other thing I wanted to mention, which I'm pretty excited about, is the potential of interactive AI in customer education. When you buy a new product, like a Cadillac EV or a Samsung TV, you own it and bring it home, but you might not know exactly how to operate it or have questions about it.

The ability to use interactive AI to educate the customer about the product is exciting. It's not just one-way communication but interactive. Today, we might Google questions like, "Why doesn't my TV turn on?" or "How do I turn off the child lock in the car?" If you're lucky, you might find the answer after some searching. But imagine if this process was more intuitive, where you could talk to an avatar and ask, "Tell me more about the child safety lock," and then immediately follow up with, "How long does it take to charge my car?"

That thick manual we used to get in the glove compartment could become an avatar you can talk to for contextual help. This isn't just about the sales process but also about post-sales product loyalty and experience, which can be really helpful.

Insurance Thought Leadership

I can imagine that sort of thing certainly applying to insurance. Instead of having to go through your big thick policy, you could ask, "Am I covered for fire?" or "How am I covered for fire?" and get specific answers.

Abby Hosseini

Yes, there are already some vendors out there that do this. They have systems where you upload your deck page, and they will interpret it and come back to you, telling you what your coverage is and what your exposure is.

Insurance Thought Leadership

To get to your third point on agentic AI: How do you see AI fitting into customer service?

Abby Hosseini

In customer service, there's traditionally been a two-pronged approach. There are about 1,800 chatbot vendors in the market, and chatbots have been around since the early 2000s. So, there's nothing new in terms of providing customer-facing FAQs. The focus has been less on customer service representatives having an FAQ system and more on self-help options for customers, which have been hit or miss. Some younger people often prefer not to talk to anyone and want to engage with bots to get what they need. However, the nature of insurance is such that you can't really sell anything with a chatbot. Eventually, you have to talk to a licensed agent. Sometimes, you don't have the digital processes to provide everything because you have to go through the agent. For example, with some carriers, if I buy a car and want to add it to my policy, I have to call my agent, who then has to call the carrier. It can take a day or two to get that done. If I want to add a name to my policy or drop a driver, all of that takes a long time.

With AI or some chatbot capabilities, I can now have a guided experience that asks about the new driver and then processes the backend changes to add that information. More and more digital policy support can be done with bots to a certain degree. You don't want to disintermediate the agent, and there are complex scenarios where you can't quite get it done without one. But if you look at your call center and analyze how many calls you're getting and why, there's probably a chance that 20% of those calls could be automated and avoided with self-help.

However, you have to promote the capability, as well. For example, in my previous company, we implemented what we called EFNOL, or electronic first notice of loss, for clients. Once we rolled it out, we had roughly about 10% to 11% adoption. I asked the head of claims why adoption wasn't picking up, and he didn't know. So, I went on Google and searched, "How do I file a claim with company XYZ," and the system came back with a phone number. It didn't mention that you could do EFNOL.

There you go. We didn't nudge the customer. We were still using old methods to advise the customer on how to engage. You can't expect that, just because you rolled out some digital experience, it will get adopted. You have to force it, nudge people, promote it, and make it a better experience than waiting on the phone. Those are parts of the strategy for promoting digital solutions. It's not enough to just build these agents and put them out there.  

Insurance Thought Leadership

I love the theory of chatbots but often find myself yelling at them. Have you ever dealt with a chatbot you like?

Abby Hosseini

Quite a few. They help with the mundane things. Has my payment been received, or what's my bill? When is my policy going to be canceled?

But you have to give the customer a choice. I can start in chatbot, elevate to a click to call, or elevate to a screen-sharing experience or a video sharing experience. Sometimes you start in one channel and then you go to the other channel because things get more complex. But it gets very frustrating when the chatbot doesn't answer your question and doesn't offer you any other way to engage.

Insurance Thought Leadership

If you give me five options, none of them are what I want, and there's nothing that says "talk to an agent," I get very unhappy very quickly.

Do you have any final words of wisdom?

Abby Hosseini

When I was a CIO and CTO, we had 10,000 agencies and 40,000 agents. We provided some level of delegated management of the users and the organizational hierarchy of these large agencies. However, onboarding was a struggle. Compliance with NAIC and other licensing adherence was a struggle. Commission distribution, commission calculation, and analytics around agents' performance were always a struggle.

When you look at where good analytics and AI can come in, I think it's across the whole spectrum: onboarding, agent education, compliance, commission and incentive management, and then reporting and analytics from a productivity perspective. In every aspect, some form of machine learning, analytics, or AI can be applied to really modernize that space.

There's risk involved with not having properly licensed agents. There's always an appetite or a need for just-in-time appointments. There are all kinds of human errors with commissions, and there's third-party reporting to regulators that has to happen. When you look at the whole value chain of distribution management, it's antiquated at best because most carriers have legacy custom commission systems and clunky onboarding.

That got us thinking about how, with some of these newer technologies that have come to the market, we can automate and streamline that experience.  

Insurance Thought Leadership

OK, this is super. I really appreciate your taking the time.

About Abby Hosseini

abby headshot

As principal and chief digital officer, Abby Hosseini leads the strategic development and evolution of Exavalu industry solutions and practice areas. His strategic consultation and assistance to client CIOs/CTOs during digital and operational transformation ensures organizational growth for clients.

He has over 33 years of experience as a senior technology executive, including 22 years as CIO/CTO, driving large and complex IT transformations for some major organizations like Mercury Insurance Group. At Mercury, Hosseini also managed the company’s core insurance platforms, including custom software and Guidewire InsuranceSuite and InsuranceNow (SaaS) platforms implementation over 14 years.

Hosseini holds a bachelor’s degree in mathematics/CS from UCLA and completed his MBA from Pepperdine University.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

Multi-Agent Systems Reshape Human-Machine Collaboration

Multi-agent systems and human-machine collaboration reshape how we work, pushing boundaries between human expertise and AI capabilities.

A Robot Holding a Wine Glass

This article delves into the application of systems using multiple AI "agents" and into human-machine collaboration in industry, aiming to reveal to readers without a technical background how they can lead us to a tech-driven, AI-powered work world.

Think about the writing process, typically divided according to people's work habits into: gathering information, drafting, revising and finalizing. What would happen if artificial intelligence were introduced?

The seemingly linear and unidirectional writing task could be entirely generated by AI, although the content generated by AI might not meet our expectations or standards. Alternatively, we could have AI assist us in analyzing and handling complex topics, collecting, filtering and summarizing useful information from multiple sources, embodying human-machine collaboration. Further, if the content of an article is rich, covering profound discussions and extensive knowledge, assigning each step of the writing process to agents with different expertise and requiring them to cooperate with each other would undoubtedly produce superior outcomes. That is the approach of multi-agent systems.

Early AI capabilities were limited, and it was more of a "human-centered" auxiliary tool. As machine capabilities improve, the nature of human work changes, and the "machine-centered" human-machine collaboration model becomes possible, continually evolving the boundaries between humans and machines.

In this new work model, AI is not just a tool or service; it has become a collaborative partner for humans, facing challenges and solving problems together. 

For example, in the healthcare field, AI is assisting doctors in analyzing cases and developing treatment plans, and playing a role in personalized medical services. In the creative and design industry, AI's involvement provides new sources of inspiration and creative tools for artists and designers, pushing innovation while challenging traditional creative processes.

Everyone is a participant and beneficiary of this transformation. Multi-agent systems and human-machine collaboration are changing our ways of working, reshaping our behaviors and habits. In the relationship between humans and AI, we can act as observers overseeing AI's work from a god's-eye view, or actively participate in the multi-agent system, cooperating with AI as part of the process. As consumers, understanding how AI affects the provision of products and services can help us make more informed choices. As AI technology spreads, many jobs will evolve, and understanding these technologies helps us adapt to future work environments and seize new career opportunities.

I. The Future of Human-Machine Collaboration and Multi-Agent Systems

As AI technology rapidly advances, we are entering a new era assisted by intelligent systems and robots. Multi-agent systems and human-machine collaboration not only showcase technological innovation but also directly affect our work and lifestyle, signaling that cooperation between humans and machines will become the norm.

1.1 What is an Agent?

Computer scientists and AI researchers Stuart Russell and Peter Norvig in their book "Artificial Intelligence: A Modern Approach" define an agent as "anything that can be considered to perceive its environment through sensors and acts upon that environment through effectors." This definition applies to humans, robots, software programs and artificial intelligence.

With the rollout of large language models like GPT-4, agent scenarios have seen explosive growth. Below is an illustration by Yohei Nakajima showing the interaction between agents and a large model (GPT-4):
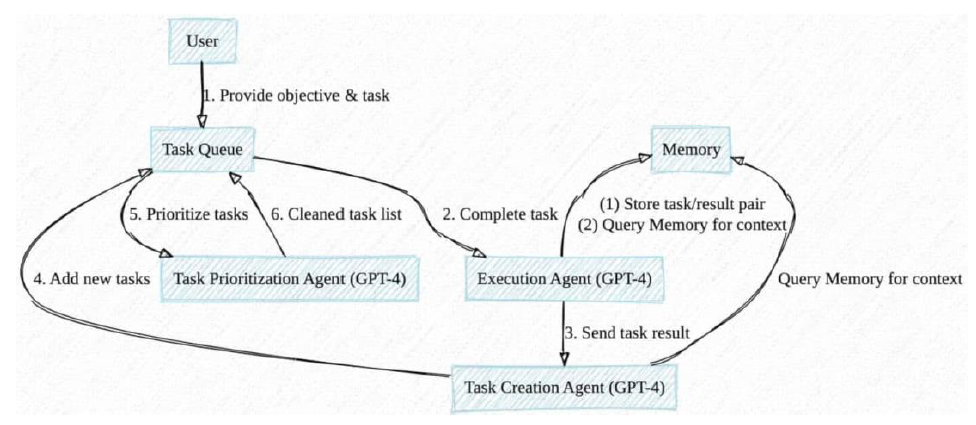
Task-Driven Autonomous Agent

Agents act like the "decision engines" for large models, communicating with GPT-4 to complete high-difficulty tasks such as data analysis, brainstorming, resource management, language translation and task organization, prioritizing tasks needed to achieve user-defined goals.

1.2 Defining a New Work Paradigm Through Human-Machine Collaboration

Under the human-machine collaboration model, AI is no longer just a tool for executing commands but a working partner for humans, together solving problems and completing tasks. This cooperation significantly enhances work efficiency and frees humans from repetitive or high-risk tasks, allowing more involvement in creativity and emotional intelligence tasks. Subsequent demands for new skills, including AI technology knowledge, data analysis capabilities and communication coordination skills for cooperating with AI, will be key to future workplace success.

In the past, most people only needed to understand the surface functions of the tools or technologies they used enough to apply them in daily life and work, without delving into how they work. For instance, when using the Windows operating system, users are more concerned with how it can help them complete tasks or enjoy entertainment, rather than understanding its internal mechanisms. However, this traditional approach to technology understanding, particularly in the field of artificial intelligence and in the context of multi-agent systems, may prove insufficient because in future human-machine collaborations, everyone's role might resemble those of agents in a multi-agent system, necessitating a deeper understanding of technology.

When the nature and organizational form of work shift toward models similar to multi-agent systems, where previously human-centered processes are deconstructed and reconstructed according to machine capabilities, each person plays a role similar to that in a multi-agent system, focusing on their expertise and tasks while collaborating with others or AI assistants to achieve larger tasks and goals.

McKinsey's report "Insurance 2030: The Impact of AI on the Future of Insurance" predicts that by 2030, AI and related technologies will have a significant impact on distribution, underwriting, pricing and claims. However, these changes are not just imaginary stories, nor do they have to wait six years; they are realities happening today.

These transformations indicate that AI is reshaping every aspect of insurance sales at an unprecedented speed, making it smarter, more efficient and user-friendly. As technology continues to advance and its applications deepen, we expect AI to play an increasingly important role in the development of various sectors of the insurance industry, creating more value for businesses and customers.

1.3 AI-Driven Work Environments and Changes in Human Performance

People's attitudes towards artificial intelligence are at two extremes: One end is denial (believing AI cannot replace my job), and the other is panic (believing AI will definitely replace my job).

In AI-driven work environments, human performance will undergo multiple changes:

  • Enhancing Specialization and Efficiency

In work models centered on human-machine collaboration and multi-agent systems, the repetitive, simple parts are replaced by AI, allowing individuals more opportunity to focus on their areas of expertise. The efficient collaboration between humans and machines not only accelerates the process of resolving user issues but also optimizes the efficiency and effectiveness of task completion. This cooperation symbolizes the future trend of work—achieving higher productivity through technological power.

  • Stimulating the Desire to Learn and Develop

Whether with telesales or planning consultants, when individuals realize that they are playing a role similar to that in a multi-agent system in their work, their motivation to learn relevant technological knowledge also increases. This realization pushes individuals to understand their roles in the team, how to collaborate with AI more effectively and thus enhance personal skills and the overall work effect of the team.

  • Developing Cross-Domain Skills

Future work requires not only deep professional knowledge but also cross-domain skills, including technological knowledge, human-machine communication and coordination abilities, and an acceptance of innovative thinking. The enhancement of personal cognition and awareness, in turn, helps the iterative progress of AI capabilities, which is key to successful collaboration in a multi-agent system and is also the foundation for individuals to adapt to future work changes.

  • Promoting Personalized Career Paths

As standardization and digitalization progress, everyone's job becomes more personalized and modularized. Those who cannot adapt choose to leave, while those who accept the challenge have more opportunities to tailor their career paths based on their interests, expertise and goals. This change not only enhances individual job satisfaction but also provides a broad space for personal long-term development.

  • Improving Understanding and Application of AI Technology

For most people with non-technical backgrounds, a basic understanding of AI technology becomes particularly important in the new AI-driven work environment. Inquiry into "why" gradually becomes a norm in the workplace. This is not only about individual career development but also about how to effectively position oneself and maximize value in the future work world.

II. Multi-Agent Systems (MAS)

Large language models (LLMs) provide AI agents that excel in different fields, and multi-agent systems bring them together to cooperatively accomplish set goals. Below, we introduce what multi-agents are and how they differ from single agents, role specialization and content generation.

2.1 What is Multi-Agent?

Imagine a scenario where a team composed of members with different expertise works together to complete a complex project. In a multi-agent system, the team members are replaced by AI agents, each playing a specific role and responsible for specific tasks. This type of collaborative mechanism allows multi-agent systems to effectively solve complex problems that are difficult for a single intelligent entity to handle.

Multi-agent systems excel at handling complex, dynamic tasks that require coordination of multiple participants' actions, relying on their expertise, flexibility and creativity to gain an advantage. For applications of multi-agent systems in smart home management, supply chain optimization and personalized services, see the last section.

However, the construction of multi-agent systems faces many challenges, such as effective coordination between agents, managing system complexity and the illusions of AI and inadequate understanding of vertical professional fields. Only when these issues are effectively addressed can multi-agent systems function properly.

2.2 Differences From Single-Agent Systems

The comparison between single-agent systems and multi-agent systems goes beyond their distinct technological architectures; they also differ in complexity, interaction modes and the strategies for completing tasks through cooperation or competition:

  • Simplicity and Focus of Single-Agent Systems

Single-agent systems are characterized by their straightforward nature, making them ideal for executing clear, relatively fixed tasks within a controlled environment. In these systems, a single intelligent entity can make decisions and perform tasks independently. For example, a chatbot providing responses based on user inputs, or a personal assistant software managing schedules and reminders, are typical applications of single-agent systems.

  • Complex Interactions and Cooperation in Multi-Agent Systems

In contrast, multi-agent systems consist of multiple intelligent entities that can be functionally similar homogenous bodies or functionally different heterogeneous bodies. They operate in parallel within the same environment, achieving common or individual goals through cooperation, competition or independent actions. The core is the coordinated actions between agents, involving complex communication, negotiation and learning other agents' behaviors.

  • Collective Intelligence of Multi-Agent Systems

Multi-agent systems are not merely about stringing together single agents with different functions. Their complexity mainly arises from the dynamic interaction rules and cooperative strategies between agents, and how they adjust themselves and make decisions based on external environments and the statuses of other agents. Similar to human collective decision-making, multi-agents exhibit characteristics of swarm intelligence, where the system's overall performance exceeds the simple sum of individual agents' capabilities.

Designing and implementing multi-agent systems require consideration of complex factors such as communication protocols, decision mechanisms, and cooperation and competition strategies, all of which go far beyond what is involved in single-agent systems. The application of multi-agent systems has driven deep development in AI technology and provided new perspectives and methods for solving real-world complex problems.

2.3 Differences with Role Specialization

Agents can possess unique skills and "personalities"; we can define their capabilities through online resources or uploaded document knowledge. Building an efficient, scalable and stable multi-agent system is not easy—it requires clearly defining each agent's role and responsibilities during the system design phase, which is crucial for ensuring the system works collaboratively to achieve the intended goals.

Suppose we are launching a product. At this point, a multi-agent system can be employed, assigning a role and function to each agent:
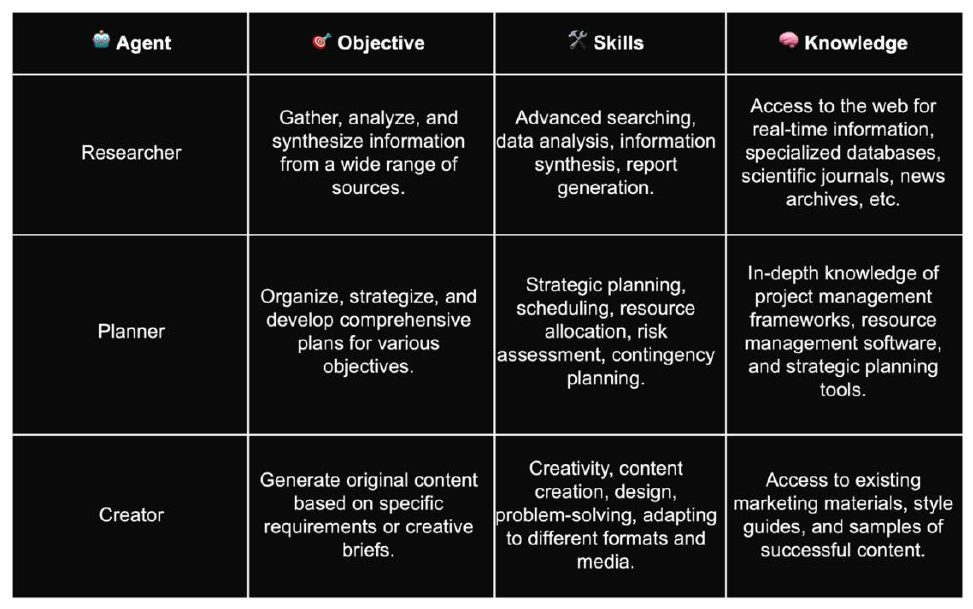
Multi-Agent System matrix
  • The Importance of Role Specialization

In a multi-agent system, clearly defining role specialization helps delineate the scope of responsibilities within the system, allowing each agent to perform optimally in its area of expertise. This specialization not only prevents redundant work but also enhances overall work efficiency. The clear demarcation of roles and responsibilities among agents facilitates their smooth collaboration, efficient information exchange and decision-making negotiation, thereby optimizing the overall system performance.

  • Collaborative Efficiency and System Scalability

Clear role definition not only enhances collaborative efficiency but also increases system scalability. When faced with new demands or functional adjustments, the system can adapt flexibly to changes without needing a complete system overhaul, by introducing new agent roles or modifying the responsibilities of existing agents. Although this flexibility is crucial for coping with the ever-changing environment and demands, without effective interaction and coordination among agents, simply having roles and responsibilities will not enable a multi-agent system to function effectively. In the next section, we will discuss how agents can interact effectively.

  • Implementing a Multi-Agent System

Defining roles provides the basic framework for the system, but implementing a well-functioning multi-agent system requires additional steps:

  • Specific Implementation of Agents: Each role must be realized through an AI agent, involving the programming, training and configuring of agents' behaviors and response strategies.
  • Interaction and Coordination Mechanisms: Effective interaction and coordination mechanisms among agents are key to a multi-agent system's capabilities, ensuring agents can share information, make collective decisions and cooperate on tasks.
  • Environment and Context: Multi-agent systems typically operate in a specific environment. Defining the environment and how agents perceive and affect it is an essential part of system design.
  • Integration and Testing: The success of the system depends on the effective integration and comprehensive testing of all parts, ensuring that agents can work together and operate as expected.

    Building a multi-agent system capable of solving complex tasks involves in-depth planning and technical implementation, and a profound understanding of the system's goals and the modes of cooperation among agents is necessary.

2.4 Differences With Content Generation

ChatGPT interacts with users primarily based on a word-by-word generation mode. As a large language model (such as the GPT series), it generates responses based on the information provided by users, the context of the question and the training data of the large model. This means that in the process, there are not multiple independent agents responsible for different parts of the answer or different stages of processing, but a unified model is responsible for understanding the question and generating the entire answer.

Regardless of whether the user uses a conversational prompt or a structured prompt, the large model, due to its ability to coherently understand the input question and generate corresponding answers, performs well in handling single interactions. However, this method's limitation lies in its heavy reliance on the capabilities of a single model and the breadth of its training data, unlike the specialization and flexibility of multi-agent systems in specific tasks.

In the introduction of this article, we used the writing process to illustrate the concept of multi-agent systems. Below, we continue this analogy to further explain the differences between a single word-by-word generation model and a multi-agent system. Multi-agent systems assign different tasks to specialized agents, not only improving the professionalism and efficiency of writing but also enhancing flexibility, adaptability and creativity, ultimately achieving high-quality writing outcomes.

  • Specialized Processing

In a multi-agent system, each agent is responsible for a specific task within the writing process. For instance, some agents focus on gathering information from specific fields, while others are responsible for structuring the draft or refining the style and language. This clear division of labor ensures that each part of the writing process meets higher professional standards and depth.

  • Parallel Processing

One of the major advantages of multi-agent systems over single models is their capability for parallel processing. Multiple agents work simultaneously, much like having several assistants who help the author collect information from various sources or edit different parts of the article at the same time, significantly speeding up the overall writing process.

  • Flexibility and Adaptability

Another highlight of multi-agent systems is their outstanding flexibility and adaptability. The real-time collaboration between agents can quickly respond to changes in the article's needs, whether adjusting strategies based on initial feedback or optimizing information collection and editing methods during the writing process.

  • Enhanced Creativity

Different agents bring a diversity of perspectives and backgrounds to the article, enriching the content and creativity. This input from various intelligent entities not only expands the boundaries of thought but also makes the content more innovative and appealing.

  • Quality Control

While generative AI sometimes produces hallucinations, we can establish specialized agents within a multi-agent system responsible for quality control of the article, including fact-checking, grammar and spelling checks, and ensuring the coherence of the content. This collaborative mechanism can effectively enhance the overall quality of the article.

Thus, compared with single word-by-word generation models, multi-agent systems offer comprehensive advantages—specialized processing, high efficiency, flexibility, enhanced creativity and quality control—providing robust support for complex writing tasks and offering a more refined and high-quality solution. This not only marks the progress in writing technology but also opens up possibilities for future content creation.

2.5 Effective Interaction and Coordination Between Agents

In a multi-agent system, ensuring effective interaction and coordination between agents is crucial. The latest paper, "AIOS: LLM Agent Operating System," proposes that in the AIOS framework, agent communication is achieved through a shared memory and storage system. Other methods such as tool invocation and context management are also explored, and interested readers may refer to the paper for more details.

Let's focus on several core technologies and concepts, such as communication protocols, negotiation mechanisms and learning algorithms.

  • Communication Protocols

Imagine if each agent were a country; communication protocols would be like the language and etiquette between diplomats. They specify the format, timing and manner in which agents exchange information, ensuring that messages are sent and received correctly. Just as people need translations to communicate in different languages, communication protocols help different agents understand each other's "languages."

  • Negotiation Mechanisms

Negotiation mechanisms are methods used in multi-agent systems to resolve conflicts and reach consensus. Like in a team project where members need to discuss and decide on the best course of action, agents also need some way to "discuss" and decide which action fits best with the current goals. This can be implemented through various algorithms such as voting, auctions or rule-based decision processes.

  • Learning Algorithms

Learning algorithms allow agents to improve their behavior based on experience. This functionality is similar to how humans learn to ride a bicycle: we might fall initially, but through repeated attempts and adjustments, we eventually learn to balance. In a multi-agent system, agents can "learn" the best ways to interact by observing feedback from the environment and the behavior of other agents, thus improving the system's overall performance over time.

  • Simple Application Scenarios

Imagine we are organizing a large party and need to coordinate multiple teams (agents): catering, music, venue setup, etc. Each team has its specific tasks, but they must communicate and coordinate with other teams to ensure the party goes smoothly. This requires a good "communication protocol" to ensure accurate information transmission; a "negotiation mechanism" to resolve any situations where, for example, the venue setup team needs more time, affecting the catering team's preparations; and a "learning algorithm" that allows each team to learn from each event how to cooperate more effectively.

III. Case Studies of Human-Machine Collaboration and Multi-Agent Systems

Below are some examples of applications of human-machine collaboration:

Medical Diagnostic Collaboration

IBM Watson Health, in partnership with several global hospitals such as the Memorial Sloan Kettering Cancer Center in New York, uses its cognitive computing capabilities to analyze clinical data and provide precise diagnostic suggestions and personalized cancer treatment plans. This showcases the tremendous potential of artificial intelligence in enhancing the quality of medical services and accelerating the diagnostic process.

Creative Design Assistance

Adobe Sensei, Adobe's AI and machine learning platform, is integrated into software such as Photoshop and Illustrator, providing intelligent editing features like automatic image cropping and facial recognition adjustments. This helps designers work more efficiently, demonstrating AI's role in advancing the creative industry.

Here are some examples of multi-agent systems applications:

Intelligent Traffic Management

Singapore's smart management of urban traffic through its Intelligent Transport System (ITS) allows the city to monitor and adjust traffic flow in real time, effectively reducing congestion and enhancing road usage efficiency. This demonstrates the capacity of multi-agent systems to improve public service efficiency.

Supply Chain Automation

Walmart, one of the world's largest retailers, uses AI and machine learning algorithms to optimize its supply chain management. Through the Retail Link system, Walmart automatically tracks inventory levels, predicts demand and ensures timely product restocking, showcasing the application value of multi-agent systems in commercial operations.

Smart Home Systems

Google's Nest smart home product line, including the Nest Learning Thermostat and Nest Protect smoke alarm, learns users' living habits to automatically adjust home temperatures and monitor safety, creating an efficient and comfortable home environment. This highlights the potential of multi-agent systems to enhance the quality of life.

Through these specific examples, whether in the fields of healthcare, creative design, city management, retail logistics or home living, we observe that both human-machine collaboration and multi-agent systems are playing an increasingly important role. These technologies not only enhance the efficiency of work and life but also provide higher quality and more personalized services. As technology continues to evolve, we anticipate even more innovative applications to emerge in the future.

IV. Conclusion

As we step into a new era shaped by AI technology, multi-agent systems and human-machine collaboration are not only hot topics in the field of technology but are also beginning to influence our ways of working, living habits and even our thinking. Steve Jobs once said, "Technology is nothing. What's important is that you have faith in people, that they're basically good and smart, and if you give them tools, they'll do wonderful things with them." Multi-agent systems and human-machine collaboration are precisely such tools, giving us unprecedented capabilities to solve complex problems, enhance efficiency and stimulate innovation.

Through this article, we have witnessed the application of these technologies across various sectors. They have made services more personalized, decisions more intelligent and creativity unleashed. However, facing the new challenges brought by artificial intelligence, we need new perspectives, new ways of thinking and interdisciplinary collaboration to fully harness the potential of multi-agent systems and human-machine collaboration.

As technology continues to evolve and its applications expand, we have good reason to believe that multi-agent systems and human-machine collaboration will open doors to innovation in more fields. In this process, every one of us is a participant, and our curiosity, creativity and desire for knowledge will be the driving forces that propel this intelligent revolution forward.

This article is not only a description of current technological trends but also an expression of hope for the boundless possibilities of the future. Let us join hands with AI, dance on the edge of intelligence, explore the yet-to-be-discovered wonders and together create a world that is smarter, more efficient and harmonious.


David Lien

Profile picture for user DavidLien

David Lien

David Lien is a partner at Lingxi (Beijing) Technology. 

He wrote “Decoding New Insurance” (2020), which ranked among JD.com’s top books. Lien has held leadership roles at Sino-US MetLife, Sunshine Insurance and Prudential Taiwan, leading digital transformations and multi-channel marketing. A 2018 e27 Asia New Startup Taiwan Top 100 nominee, he holds a patent for the "Intelligent Insurance Financial Management System." 

The 3 Big Trends for Insurance in 2025

Yes, AI is one of them. In this Future of Risk conversation, Capgemini's Adam Denninger lays out a road map to a wholly new policy lifecycle.

Adam Denninger future of risk


adam headshotAdam Denninger leads Capgemini’s global strategy and product management for the insurance industry and manages its relationships with the insurance technology ecosystem. He has 20-plus years of experience creating and delivering solutions at the intersection of business and technology.

Insurance Thought Leadership

As you look ahead to 2025, what are the key trends we should expect to see play out? 

Adam Denninger

Common themes emerge across all insurance sectors. One of the biggest trends we're seeing is that customers are no longer tolerating complex, convoluted experiences in either sales or service. This applies to policy owners, members, agents, and distribution partners alike. Insurance companies are responding with significant investments to address these pain points, particularly through experience improvements, service enhancements, and contact center optimization – all powered by gen AI and new tools to increase efficiency.

Another major trend, particularly in the P&C space, focuses on better understanding and pricing risk. For instance, how do you differentiate between two 18-year-old male drivers – one excellent and one poor – using available insurance data? The same applies to property insurance, where two houses near each other on Florida's coast might represent vastly different risk profiles. This trend has led to substantial investment in underwriting workbenches, especially in traditionally tech-resistant markets like London.

Similar developments are occurring in life insurance, where there's a push toward fluidless underwriting. After a decade of discussion, companies are finally implementing better, faster, and less expensive underwriting processes while maintaining or improving accuracy.

The third major pillar of investment centers on cost optimization. Companies are exploring various approaches to reduce operational costs, whether through legacy system replacement, cloud platform migration, Gen AI implementation, or enhanced self-service capabilities.

Looking ahead, I expect to see step changes in the industry's overall technology capabilities. While the benefits of current investments may take one to three years to materialize, the scale and scope of approved projects suggest meaningful transformation is on the horizon.

Insurance Thought Leadership

How is generative AI currently improving insurance operations, and what developments do you see beyond basic efficiency gains?

Adam Denninger

I see several key developments happening with generative AI in insurance. One of its most powerful capabilities is synthesizing disparate sources of unstructured data – including reports, police documents, and news articles – into concise, fact-based summaries. This functionality is being integrated into both sales and claims processes. 

Working with Google, I've seen this in action through their new claims handling tool that some companies are implementing. While a human claims handler remains involved, the AI handles the analysis of backend documents, synthesis, and initial recommendations. This is truly game-changing, though companies still need to get comfortable with the accuracy and keep human oversight during these early stages. 

The efficiency gains in claims handling will be astounding, especially considering the cost of claims handlers. We're seeing similar developments on the underwriting side. For example, at Capgemini, we've developed a tool that can analyze unstructured public data from financial reports and news articles to create actuarially viable and defensible rating factors for D&O insurance – something previously unheard of. 

On the customer experience front, generative AI is transforming contact centers. The technology enables natural conversations where AI agents can gather information organically to populate quote information. Instead of dealing with structured IVR systems with rigid questions, customers can have fluid conversations. For instance, a customer might casually mention needing auto insurance for their 18-year-old son's first car, and the AI can extract and process that information while maintaining a natural dialogue.

What's revolutionary is that the computer can have human-like conversations and extract relevant information without requiring exact scripts or button pushing. This capability allows insurance companies to completely reimagine their contact center operating model. While these solutions are still being developed and tested, I believe they represent a significant advancement.

Insurance Thought Leadership

What companies are successfully implementing chatbot technology using large language models, and how close are we to seeing widespread practical applications?

Adam Denninger

Currently, no company has successfully implemented this technology in production at a high level. The main challenge, particularly for insurance companies, lies in integrating these new capabilities into existing legacy systems. This integration is incredibly complex and requires years of investment to implement in a production environment. While I can't name specific companies due to NDAs, I know several tier-one organizations are actively investing in these solutions. 

The technology is definitely coming. Initial iterations of these solutions will likely begin appearing in the market within the next six months, allowing people to start experiencing the technology firsthand. I anticipate widespread adoption and implementation from major carriers in production environments within two years.

The transformation from traditional scripted chatbots to these more sophisticated, conversational AI systems represents a leap forward.

Insurance Thought Leadership

And reducing customer service expenses through automation actually improves customer satisfaction.

Adam Denninger

It's definitely a win-win situation. While people are great, they do make mistakes, and not every customer service representative can know everything about the company. In contrast, a chatbot can be programmed with comprehensive knowledge about the company and provide consistent, accurate answers within its designated scope. 

Let me use Google as an example. Their claims-driven capabilities, which are part of an ecosystem of claims tools they're developing with our customers, deliver more accurate upfront answers in a fraction of the time compared with traditional methods. This isn't just a chatbot – it's a comprehensive claims management solution. 

The end result is faster, more accurate service that benefits everyone involved. Who wouldn't prefer getting their claims settled more quickly and accurately?

Insurance Thought Leadership

How far can we get with incremental innovation, and when do we need to think about complete system redesign?

Adam Denninger

When carriers come to us wanting to leverage new technology and transform their business operations, I typically recommend a specific strategy: Keep their existing legacy ecosystem and processes intact while building a completely new greenfield solution.

This approach allows companies to retain all their valuable assets – their product expertise, operational knowledge, regulatory understanding, industry experience, and distribution networks – while running them on legacy systems. They can then selectively transfer what they need to a new platform, creating a best-in-class solution. 

In my experience, this is unquestionably the most effective and efficient approach. However, it's highly customer-specific whether organizations choose to pursue this path. The hesitation is understandable – building an entirely new operating model and platform represents one of the highest-risk IT and operational programs possible. You're essentially betting the company that this new platform will be superior going forward. 

While this approach carries higher risk, it's demonstrably the most efficient and effective way to achieve transformation. The companies that do choose this path tend to be true market leaders who are willing to take that calculated risk for potentially greater rewards.

Insurance Thought Leadership

Do you know the origin story of Target? It fits that model. Back in the 1980s, when I was in the Wall Street Journal’s Chicago bureau, we covered a relatively quiet company called Dayton Hudson. Like many department stores at the time, they had experimented with a heavy-discount approach, but they did it as a greenfield, largely because of the dynamics among the five brothers who had inherited leadership of Dayton Hudson from their grandfather, who founded it. The four oldest brothers didn’t think discount retailing would work. The youngest did and set up Target in 1962, with the condition that his brothers would stay out of the way. Target grew so fast that it eventually subsumed the rest of the business, which was renamed Target in 2000.

Adam Denninger

From my perspective, a greenfield is always the right way to go. But I also fully understand people's hesitancy given sort of the risk of doing that. You need the right leadership to pull that off. So probably that brother was a fantastic corporate leader, is what I would say!

Insurance Thought Leadership

What might a successful greenfield operation look like for a top five P&C insurer in five years?

Adam Denninger

The operation will fundamentally transform the entire policy lifecycle by drastically reducing operating costs and improving response speed across sales, service, and claims processes. Everything will be faster, better, and easier, with significantly lower costs due to AI support. The system will enable maximum self-service capabilities, available anytime, anywhere, through any channel, benefiting both distribution partners and insurers. 

The real beauty lies in the data integration. All interactions, policy sales, servicing, quotes, and third-party data will feed into a single core system for the insurance company. This creates incredible power for cross-selling, underwriting outcomes, pricing optimization, marketing effectiveness, and claims handling. It enables a virtuous circle of continuous improvement that's impossible with current systems. 

The reason insurance companies can't achieve this today isn't due to lack of desire or knowledge – it's because their existing systems literally can't communicate with each other. The current infrastructure is an incredibly complex morass that prevents meaningful progress. While you might achieve incremental improvements like a 5% reduction in claims handling time, true step-change transformation isn't possible with legacy systems. 

What we're going to see is carriers finally operating the way we all want them to – efficiently, responsively, and driven by data. It will start with a few pioneering companies, and their success will force others to follow suit. This transformation isn't just a possibility – it's an inevitability. The only question is when companies will make the leap.

Insurance Thought Leadership

How significant is the potential for insurance companies to shift toward a Predict & Prevent model, particularly in using data to help prevent accidents and losses?

Adam Denninger

The model has enormous potential, with the main limitation being our ability to deliver data to the right place at the right time. We already have access to extensive data about traffic accidents, risky roads, and dangerous drivers. On the property side, we know which types of houses carry more risk based on building code history. The challenge lies in creating effective mechanisms to share this information with individuals who need it most. The technology already exists -- our phones can alert us to traffic jams, for instance. The next step is getting this valuable data out of its current silos and into public-facing systems. 

Currently, insurance companies are still focused on more fundamental challenges, like updating their pricing models more efficiently. Many companies are struggling with the fact that it takes up to five years to roll out new pricing models, which is unsustainable in today's market. 

However, the Predict & Prevent approach is universally recognized as valuable. The key is developing systems that can make data usable and accessible, such as mobile apps that can provide real-time location-based alerts and warnings. Once we overcome these implementation challenges, this model will only continue to improve and expand.

Within the next five to 10 years, I expect consumers will regularly receive location-based notifications from major tech companies like Apple and Google through their mapping services. These notifications will likely alert you to available hybrid parking spots and other location-specific information. Insurance companies will also leverage this technology advancement. Once they have the capability to effectively analyze policyholder data, they'll be able to provide customized notifications about specific risks and maintenance requirements based on the type of property being insured.

Insurance Thought Leadership

Thanks, Adam. I really appreciate your taking the time.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

P&C Insurance Claims: The Time Has Come

For too long, progress in the insurance claims process has been slow and incremental. The time is now ripe for reinvention. 

Magnifying Glass and a Document

For those of us who have worked in this industry for a decade and longer, when you honestly assess how claims handling has evolved, you would fairly conclude that while certain aspects have improved – some even impressively – the fundamental model, process, service and financial outcomes have essentially remained unchanged or marginally improved. 

When comparing insurance claim modernization with other financial and consumer services, the shortcomings become even more obvious. Yet the environment in which claims occur and are resolved has changed significantly.

The reasons for this lack of breakthrough are many and complex, and playing catch up in real time has not been easy – but it is possible, and mandatory.

Evolution vs. Transformation

Claims evolved from paper in the 1980s to computerization in the 1990s, followed by mobile technology by the late 1990s and into the new millennium. So-called transformation from legacy, often home-grown, core CMS (claim management systems) to modernized systems was the most recent, costly and arduous of undertakings. 

While many large carriers began tackling policy management and CMS upgrades 10 or more years ago, some are now just finishing or making those changes. Carriers find themselves “upgraded” but now need to bridge integration and digitization gaps to fully realize massive system investments often encumbered by budget and technology prioritization fatigue. Disappointment is expressed throughout as gains in system maintenance and ease of modification fall short of high expectations. In other words, transformational change is not yet completed despite time and tremendous capital expenditures. 

This is not a vote for turning back, as such legacy system upgrades were overdue by decades.

The core process of claims intake, assignment and the remaining linear claim steps is unchanged throughout the industry. Claims handling is considered part art, part science, difficult to untangle and requiring apprenticeship learning and development that takes years. Litigation risks and fiduciary responsibilities are real but often amplified as barriers to change. Visions of STP (straight-through-processing) have been muted because of loss cost containment priorities, and cloud migration no longer appears to be the next silver bullet, as the landscape is changing.

Interdependency among vendors, providers and other ecosystem friends and foes has grown and become more sophisticated. Many are sizeable, global companies making their own technology investments and are constantly vying for a larger piece of the pie. The reliance on such entities has never been higher when it comes to repairing, restoring and managing a multitude of moving parts in today’s claim response whether individual or catastrophic scenarios. The insurtech wave over the last 10 years has only added to these players that are now posturing with AI in the forefront, regardless of depth and validation. 

The stakes are high as premiums become unaffordable and both claim operational productivity and indemnity control are leaned on to offer relief. Either way, the horizon is a next frontier of incomplete digitization, limited integration and a fragmented provider/vendor space while AI is unfolding rapidly. 

See also: The Need for Excellence in Claims Handling

Claims Needs More Attention, Respect and Resources

It is counter-intuitive that the claims operation, which consumes the majority of a carrier’s total income, receives the minority of investment in dollars and technology. And much of that is for maintenance, not development. Because claims is (wrongly) perceived as little more than a major cost center, it can be underappreciated in C-suites and in other operating areas. In tough times, it is the first to incur layoffs. 

While we often hear about how the claim is “the moment of truth” in insurance, it has until recently been mostly lip service emphasizing indemnification control while requiring intensive people resources to overcome numerous process workarounds. Carriers have recognized that the critical importance of customer retention is heavily tied to claims satisfaction and must rely on people assets to fill various process holes. Yet what is really needed to make true progress is real transformation in philosophy and operating models.

Tinkering vs. Transformation

The industry has embraced numerous third-party information technology solutions, but they have almost all been “point solutions” that address only single functions within the broader end-to-end claim process. True transformation will require a bold, holistic mindset, not just modifications and “band aids.” Integrations, AI and marketplace models are part of the solution. Solution providers have a similar responsibility to help unlock inefficiencies among repair, replacement and restoration following a loss and remain uncoordinated or lack incentives to partner.

True Transformation: Predict and Prevent vs. Respond and Mitigate

Underpinning true claims transformation will be a new paradigm built around a new “predict and prevent” operating model vs. the legacy approach of “respond and mitigate.” Connected sensor and data-enabling technologies and business models are widely available and should be pursued aggressively. This transformation will unlock innovative insurance product models. Increasing cyber, data and climate risks are just a few that call for greater loss detection and avoidance.

The New and Different Automotive, Repair and Consumer Landscape

The insurance industry needs to stop operating in ways that worked in yesterday’s automotive and consumer environment. Driver assistance and electric vehicles have forever changed the auto physical damage and collision repair landscape. Consolidation of the collision repair industry, backed by well-funded private equity investors, has shifted the balance of power between them and auto insurers. Auto manufacturers have begun disrupting the auto insurance and collision repair process through branded insurance and certified repair programs requiring the use of their parts. Consumers are shopping and switching auto insurance at record rates in the face of relentless premium increases. The insurance industry’s image is at an all-time low, including a highly negative view of their claims adjudication practices.  

The Silver Tsunami

The insurance claims adjuster workforce has been shrinking and now tops the list of vanishing industry jobs. Several factors are driving this shrinkage, including fewer auto claims, cost cutting, and aging out, all of which is expected to continue. This reality makes it incumbent on carriers to transform the claims process by leveraging technology and implement effective upskilling programs for the surviving workforce.  

Too Many Solutions – Too Few Integrations

The insurance information technology landscape is proliferated with numerous startups as well as legacy providers, most of which offer closed, proprietary solutions and only a fraction of which are integrated with carrier claims systems. And almost all of these solutions address only a small subset of the claim process. 

Shiny Things Distraction

The insurance industry has suffered from the same irrational attraction to “shiny objects” that consumers display, and the costs have been high. Research, testing, meetings, IT resources, pilots, staff time have all contributed, and unwarranted opportunity costs too frequently result in abandonment. Carriers need to identify their challenges and then review potential solutions rather than the other way around. 

New Technology Potential

It is surprising to consider how much new claims technology has been developed, tested and effectively validated by a small number of carriers but has not been more widely explored or adopted by the wider industry. Consolidation and attrition among this segment may be expected and could address this gap in time. 

Critical Leadership

Real transformation by large, complex companies is not possible without the clearly articulated encouragement from leadership including CEOs and the rest of the C-suite. These leaders will need to convince their stakeholders of the existential need for transformation and be cheerleaders for the required innovation.    

See also: Why Do Insurance Claims Take So Long? 

Legislative/Legal Refocus 

The insurance industry has historically been quick to point to regulators as impeding their ability to innovate. While sometimes true, this claim is exaggerated, and carriers need to learn how to navigate these challenges. Confronting the threats of legal system abuse, social inflation and consumer dissatisfaction can become a common cause for these constituents.

The time is now, conditions are ripe, the solutions are at hand and the future of the industry awaits.


Alan Demers

Profile picture for user AlanDemers

Alan Demers

Alan Demers is founder of InsurTech Consulting, with 30 years of P&C insurance claims experience, providing consultative services focused on innovating claims.


Stephen Applebaum

Profile picture for user StephenApplebaum

Stephen Applebaum

Stephen Applebaum, managing partner, Insurance Solutions Group, is a subject matter expert and thought leader providing consulting, advisory, research and strategic M&A services to participants across the entire North American property/casualty insurance ecosystem.

What Trump's Tariffs Mean for Insurance

Also, why didn't Flo, Mayhem and their animal equivalents show up during the Super Bowl? And the arrival of "digital workers."

Image
tarrifs

After the chaotic first three weeks of the new Trump administration, it's impossible to know what the long-term effects will be of the tariffs, the rescinded tariffs, the threatened tariffs and the president's broad endorsement of "tariff" as "the most beautiful word in the English language." But some of the effects on the insurance industry are becoming clear, especially on auto insurance — and they aren't good. 

This week, I'll tell you what I can about what happens next. I'll also take a look at the absence of insurance ads on the Super Bowl broadcast, which probably changes nothing but which I choose to take as a possible sign of a new seriousness by insurers to educate consumers on their needs for coverage and as a shift away from just pounding brand names into people's heads. Finally, I'll dig into a smart piece that provides a way to think about implementing generative AI, as "digital workers."

Let's start with the tariffs.

Auto insurance premiums have pretty much caught up with the surge in prices for new and used cars and for replacement costs that came out of COVID. It disrupted supply chains and made many parts scarce. The lack of cars on the roads led to increasingly reckless driving, which has been slow to wane even though driving has for years been back to pre-pandemic levels. Distracted driving seems to keep getting worse, too. The spread of technologies such as driver-assist has made repairs more expensive, as has the increasing market share of electric vehicles. 

But just when you thought it was safe to get back in the water, here come the tariffs. Even the scaled-back version of Trump's tariffs, which cover only aluminum and steel, could add $1,500 to the price of a new car, according to this MSN article. The reason: The average car contains about 1,000 pounds of steel, at a cost of $6,000 to $7,000. Add a 25% tariff, and that steel costs $1,500 or so more. 

As the article notes, car makers could shift suppliers to avoid the tariffs, but the higher cost of imports creates a pricing umbrella, and other suppliers will surely take the opportunity to raise prices. 

If Trump follows through on the 25% tariffs he's threatened to apply to all goods from Canada and Mexico — before backing off in the face of a 600-point drop in the Dow Jones Industrial Average — the costs of cars and replacement parts would soar even more. The Wall Street Journal says the boost could be $3,000 per car. MSN goes further, putting the price increase at $6,250 for a $25,000 car. 

Even if Trump never follows through on the tariff threats, "The damage has been done," according to a Georgetown University professor quoted in the WSJ. “We are going to have tremendous uncertainty looming over the industry for the foreseeable future…If I’m an insurance company, I’m pretty dour at the moment, and certainly highly motivated to pass on my risk in the form of higher premiums to consumers.”

That sounds right to me. I think we've reentered an inflationary phase for cars because of the tariffs and threatened tariffs. The only question is how bad it will be and how long it will last. 

Now to the Super Bowl ads.

I suspect the reason for the absence of Mayhem, Flo, the GEICO gecko, etc. was the (smart) decision not to get caught up in a wave of ads by startups you'd never heard of and by established brands that somehow decided that having facial hair take on a life of its own would sell chips and pizza bites. (My younger daughter thinks both companies must have made the same sort of ill-advised prompt with a generative AI in a search for a novel idea.)

But I hold out hope for a more meaningful reason. I keep thinking the insurance industry will take seriously its complaints about a protection gap and will focus on educating consumers about the need for life insurance, flood insurance, etc. I keep thinking the industry will move toward the future of insurance — the Predict & Prevent model — and will help people think about how to harden their properties and communities against wildfire and other threats. 

I've been thinking this for a long time. Here are articles I published as far back as 2016 and 2014 that complain about the reliance on ads vs. substance. 

I won't even try to claim that the bang-your-name-into-people's-heads approach isn't effective marketing. I'm sure it is. But I'll keep hoping that the insurance industry will find a way to focus consumer attention on the really important long-term issues.

On to "digital workers."

You've read a lot recently about AI agents — including articles I've published at ITL — but I still commend to your attention a recent piece by my old friend and colleague John Sviokla, because it provides a useful way to think about agents, as well as a great example.

While AI often seems esoteric and vaguely threatening, John describes how AI personas can be created and simply put into the staffing pool, as any human would be. Hire the AI or don't; the choice is yours. 

His great example is OneDigital, which helps meet work-life needs for more than 100,000 employers and which has created 10 digital workers, with about a dozen in the pipeline. 

“'Frank' is an expert in sales effectiveness and strategizing on growing the services that OneDigital provides to existing clients," John writes. “'Yesper' was recently added to help managers mentor and support their team members while maintaining OneDigital’s innovation and client-first culture, as OneDigital has grown significantly over the last few years. There are many others, including 'Ben,' an expert at everything to do with lowering healthcare costs for OneDigital’s clients."

I remain cautious about AI agents, because I'm not ready to let them act on my behalf, but I can imagine having digital workers who report to me and who I supervise, perhaps rather closely, at least until they prove themselves. And the AIs available to us are improving so fast that we should be planning for the next round, and the one after that.

Cheers,

Paul