Download

AI Expands Life Insurance Industry Value

AI presents life insurers with transformative opportunities while challenging traditional approaches to customer trust and operations.

An artist’s illustration of artificial intelligence (AI).

Life insurers play an essential role in protecting the financial well-being of people by providing products that mitigate financial risks and aid in retirement planning. Traditionally, insurance companies have been "second movers," slower in adopting technology due to their long-term focus and desire to clearly understand the risks and rewards of change.

New capital investments in technology must meet internal benchmarks for opportunity cost and overcome the high barriers to adopting unproven innovations. Many insurers interact with customers through third parties or digital platforms, providing another barrier to decisiveness. This cautious approach has led some to view the life insurance industry as ripe for disruption, especially with the rise of fintech and insurtech in the late 2000s. 

There have been numerous historical examples of insurers whose early adoption of transformative technologies — such as advances in computing (MetLife, Franklin Life, and PacLife's UNIVAC mainframes, 1954), the internet (Progressive's auto-insurance.com, 1995), and development of derivative financial instruments (Keyport Life Insurance's KeyIndex FIA, 1995) — gave them a competitive edge.

Artificial intelligence (AI), and in particular generative AI, is just such a new technology that will drive growth in embedded value for those companies that can harness it.

While all the flavors of AI are interesting, we believe the value of machine learning to insurers is already well-understood. Instead, we plan to focus on how insurers will create value from generative AI, such as large language models (LLMs) and similar models and capabilities. For simplicity, we refer to this as "AI" throughout.

See also: AI Bias in Life & Annuities Insurance

Generative AI capabilities for insurers

The following features and uses of generative AI are key to insurers:

Generalist capabilities: AI has broad capabilities and potential reasoning abilities across a diverse array of tasks, with the ability to become further specialized in particular domains or task areas through additional fine-tuning. This flexibility allows insurers to deploy AI across multiple functions, reducing the need for multiple specialized systems.

Human-computer interface: AI provides a new way to interact with computers. Spoken or written colloquial language can "prompt" a unique response from a machine. This more stochastic approach is a departure from the traditional interface humans have with computers: entering commands to receive outputs determined through deterministic algorithms. These more intuitive and natural interactions can lead to improved experience, efficiency and satisfaction.

Multimodal content generation: AI can produce substantial written, programmatic, pictographic, video and audio responses based on simple requests. This core capability drives higher productivity for knowledge workers and can allow insurers to scale this generation with fewer resources.

Personalization and customer experience: AI can correlate general information (from its training data) with specific information from end-user input and customer data to create personalized writing and responses. This stands to elevate the customer experience when compared with deterministic chatbots or static knowledge bases, as people typically respond better to more personal interactions.

Automation and improving efficiency: AI can automate routine and repetitive tasks, which reduces the scope for human error and increases efficiency. Even in instances where the accuracy is not high enough to completely entrust to AI, it can expedite tasks by performing a first pass that a human can improve upon.

Facilitating innovation and creative thinking: AI can accelerate innovation in companies by assisting with scenario analysis, suggesting solutions to complex problems, and providing predictions and challenges for the feasibility of new ventures.

Optimizing and expanding AI in insurance 

We examine the role that AI will have in the insurance space across the following dimensions:

Optimizing and improving current capabilities

Generative AI stands to provide widespread efficiencies across current operations. The mechanisms for these improvements rely on taking tasks that are currently done by people (usually working with computers) and inserting generative AI into the workflow. One example of this is using generative AI to summarize existing documents, or to take notes on a call. Microsoft has incorporated this feature ("Copilot") into the Office Suite already. Insurers can leverage these capabilities by creating generative AI chatbots (for example, through a "CompanyGPT" interface) and search assistants that reference company document repositories to support querying of complex documents such as contracts, policy forms and product specifications. Envision a new company employee in the marketing division asking an AI bot detailed questions about a specific annuity policy. While this may not fully replace detailed reading of the source documents and conversations with knowledgeable colleagues, using an AI chatbot can reduce the amount of human time spent searching for the right document or chunk of text embedded within a document.

By improving the efficiency of current capabilities, AI assistants will lower the cost for activities such as searching for information or providing additional teaching or training to employees. As the costs for these activities drop, we expect to see insurers develop employees who are functionally more knowledgeable because they have access to more information through efficient search assistants.

Expanding abilities available from generative AI

We recognize that generative AI will also expand the opportunities available to insurers. The mechanism of this expansion is using new AI capabilities that did not exist before LLMs and generative AI: machines producing content, collating ideas and concepts with less time and effort than people do. AI will serve as an assistant to the marketer (Holloway, 2024), to produce copy and images in the company's own style, at first as a way for marketers to deliver their visual ideas to professional artists, but eventually producing content that is ready for publication.

Specific to insurer operations, generative AI may help the insurer fraud division detect signs of fraud activities in real-time. Currently, call center employees need to balance providing good customer service while also watching for red flags but, with an AI assistant, these duties could be bifurcated between the human and the machine. For example, an AI assistant could listen to voice calls between customers and administrators and be on the lookout for social engineering tactics, unusual requests or suspicious communication, while the person on the line focuses on the customer's needs. With access to a repository of call transcripts, the AI could also detect repeated scripts used in organized fraud attempts or similar schemes. The AI could keep the service representative in the loop regarding any potential fraud issues and suggest countermeasures, including alerting an organization's fraud specialists for intervention. Of course, fraudsters already employ generative AI in creative ways, such as voice cloning (Bethea, 2024), in this "arms race."

See also: AI in Insurance: 2025 Predictions

Challenges to AI adoption in insurance

Insurers must be strategic in deploying AI in their organizations: adopting these technologies comes at a financial and resource cost. Despite that, we believe that failing to adopt AI in various ways produces an opportunity cost that will eventually put most insurers at a strategic and competitive disadvantage, as widespread adoption of AI will lead to, for example, better customer service, higher worker productivity and lower fraud.

Envision learning of the first spreadsheet technology (say in the late '70s or early '80s) and believing: this will put company actuaries and accountants out of a job, it will cost a ton of money, and the company puts itself at risk by relying too much on machines to do the work we have done successfully as humans thus far.

Business—and insurers—are at the next major technology inflection point, and (despite what actuaries say) it's bigger than the spreadsheet.

Insurers must devise a clear strategy for AI, considering opportunities that make sense for their core business, and consider taking calculated risks on others.

Building and buying

Innovating at the cutting edge of any new technology is a high-risk, high-reward gambit. Early innovators that succeed can reap outsized returns and durable advantages. However, the unpredictable nature of technological innovation also means that many early bets will be misplaced and thus result in wasted resources.

The prospect of building new AI tools and processes within an insurance company will be tempting. One approach is to build the new technologies in-house: to hire new experts and integrate new workflows. After all, if there are major new opportunities available, then why not invest and earn the returns of that investment?

Another strategy is to be a more passive fast follower. Let other companies take the early bets and risk their capital and only be reactive, seeing which bets pay off and only implementing those proven ideas, but necessarily with a time lag. With this approach there is less overall risk of overinvesting in unproven technology, but it will reduce the value of any competitive advantage and, indeed, if the first movers are truly successful, it could put your company at a significant disadvantage playing catch-up.

Another uncertainty looming over both options is that it is still unclear to what degree in-house customized solutions will be more useful than off-the-shelf third-party tools, if at all. It is possible that the products of generalist providers such as ChatGPT will suffice, or that successful specialist vendors will emerge in the insurance space. Going back to the spreadsheet example, no insurance companies would have benefited by creating their own customized spreadsheet software, as major software developers such as Apple, IBM and Microsoft offered superior, general solutions. Moreover, few companies were significantly harmed by adopting spreadsheets at a slower pace than their competitors. Yet while both those things are true, any insurer that resisted the technology entirely would have found itself eventually defunct. Similarly, as major business technology players continue to pour billions of dollars into developing AI solutions, keeping an in-house solution current with external developments may prove to be a Sisyphean task.

The decision will likely come down to company culture. Those companies for which such disruption is more welcome, and that are willing to test "tried-and-true" methods against new models, will find themselves faster adopters of this new technology. They will be the companies most willing to hire external guides for their AI build, and to hire a new team themselves. If the company or CEO has been rewarded in the past for quick adoption of new technology, they will be ready for this next paradigm shift.

Regulation and compliance

In addition to our focus on key strategic areas, this series will also dedicate an installment to compliance and regulatory considerations. The National Association of Insurance Commissioners (NAIC) has issued the 2023 model bulletin "The Use of Artificial Intelligence Systems in Insurance" (NAIC, 2023). Insurers, primarily through their legal and compliance teams, have adopted internal policies on the use of AI at work, and have begun to articulate their positions regarding the use of AI for business operations. This area of practice is constantly evolving with the new tools and techniques that generative AI brings us and it will continue to evolve as the cost of new intelligence continues to decline.

Overreliance on AI

Even the most techno-optimistic insurance companies will realize that placing too much reliance on AI presents new risks:

  • Relying too heavily on machines for tasks traditionally done by people will atrophy our human connections to the business. The more we cede tasks and decisions to models, machines and electronic agents, the less we are in control of the core operations of the business, and we risk losing culture and the raison d'etre of the venture. Employees might not take kindly to the prospect of AI-generated performance reviews, for example.
  • There is value to the institutional memory that we generate through our daily interactions, tied together over decades to produce quality products and experiences for our customers. Allowing machines to do more tasks may bring efficiencies to our customers—through better experiences and lower prices—but this could come at the cost of not developing sufficient human intelligence about the customer experience.

In the end, the balance between reliance on people and machines will be a company decision, dependent on culture and economics and leadership, as well as external factors such as competition and larger business trends.

Reliability

Knowing when and how to rely on the output of AI will become a harder task as AI becomes more prevalent. AI in its current form is prone to hallucination. However, though often less discussed in the same terms, humans also are prone to such "hallucinations"—our own human frailty can manifest in diverse ways such as misunderstandings and overconfidence.

Underwriters will try to override decisions where the AI suggests accepting profitable business. Claims might get flagged as fraudulent when the model is noticing rare but unconcerning behavior.

The future of work will involve the complementary hybridization of work between people and AI. The employees best able to navigate this future will have the openness to let the technology automate things when it can, and then further use it augment their judgment when it can't. We must retain the healthy skepticism to understand that, just because AI determined an answer, it is not automatically correct.

Work force transformation

Any adoption of AI to perform tasks currently done by people will transform the way a company thinks about doing work. To start with, we envision AI completing or assisting with certain tasks done by managers in much less time. These tasks include rudimentary work, such as taking notes and writing memos, but also include more cerebral tasks such as assigning work (or suggesting assignments), brainstorming ideas on new ventures and outlining project workflows.

This requires an "upskilling" for current employees to adopt AI in their own roles—in a compliant manner—to improve their own efficiency. A large adoption of AI will no doubt lead to additional business gains: with extra time, skilled and thoughtful employees have more opportunity to contribute to other business ventures.

Most roles will be transformed not only by "upskilling" to incorporate AI into their current processes, but also by changing the nature of those roles altogether. We envision actuarial and underwriting roles, for instance, being rewritten over time to incorporate new parameters of risk from new data sources and newly available analyses. Just as the advent of spreadsheets within analytical professions revolutionized what could be done in those positions (leading to new positions, new products and more consumer choice), the new AI capabilities could produce new roles that were previously unfathomable.

See also: 4 Golden Opportunities With AI

The imperative of trust in the age of AI

The insurance industry's greatest asset is trust: consumer trust that the company will be there to pay claims when it promised it would, to alleviate financial distress in a time of need. With lifetime contracts, this trust must be held "forever," for as long as customers live. However we move forward with adopting AI, we must ensure that we retain and enhance consumers' trust.

In noninsurance settings we already see the online landscape muddied with "AI slop," or the vast array of AI-created content that proliferates on social media and in email and more.

In insurance, we must present the case for AI use to our customers: how we reach comfort with "black box" algorithms, or models that seem to lack explainability. We must be vigilant to recognize the potential for biased outcomes to emerge from our models, which are inevitably based on data and methods that can never be completely free of bias. Finally, customers will rightly have concerns about the use of their personal data in our AI models. We must address these concerns with transparency and understanding as an industry.

But in addition to defensive trust fortification, insurers should consider the variety of ways that AI allows for a better customer experience, thereby expanding trust. As an example, insurers that use AI to successfully anticipate their customer needs and behaviors may create a bond that is hard to generate when seeing every policyholder as simply "part of a pool" of risks. Insurance companies can foster longer-term relationships with consumers through proactive engagement, sending personal, relevant communications when people will most welcome them (e.g., at the time of life events like purchase of a new house).

In that regard, some companies will use AI to their competitive advantage, to strengthen trust among their customers.


This paper is the first in a series that will explore strategic areas where life insurers may deploy artificial intelligence (AI): in underwriting, customer experience, risk assessment, fraud detection, and operational efficiency. We will also publish an installment dedicated to regulation and compliance considerations in the use of AI.
Robert Eaton

Profile picture for user RobertEaton

Robert Eaton

Robert Eaton, FSA, MAAA, is a principal with Milliman specializing in long-term care insurance in its many forms: traditional LTCI, hybrid life and LTC (or chronic illness) policies, annuities with LTC benefits, short-term care, Lifeplan communities (CCRCs), and more. 


Corey Grigg

Profile picture for user CoreyGrigg

Corey Grigg

Corey Grigg, FSA, MAA, CERA spearheads the design, implementation, and maintenance of sophisticated automated actuarial data management, valuation, and reporting processes using Milliman’s technology solutions, including Integrate. He also advises clients on building technology-centered target operating models and addresses complex corporate modeling challenges.


Michael Niemerg

Profile picture for user MichaelNiemerg

Michael Niemerg

Michael Niemerg, FSA, MAAA is principal and director, data science and analytics at Milliman IntelliScript. He specializes in data science and AI in the life and health insurance industries.


Michael Regan

Profile picture for user MichaelRegan

Michael Regan

Michael Regan is director of business and technical solutions with Milliman. He leads teams focused on AI, cloud solutions, and software development, driving innovative technology strategies to support Milliman's global operations.

Insurers Must Evolve to Survive Climate Crisis

As climate risks intensify, insurers must evolve from damage compensation to prevention or face industry-wide collapse.

Stunning Night Sky Over Mountain Fire Line

The world today is burning, drowning and crumbling in ways that no one can ignore. The tragic scenes in Los Angeles in January were just the latest proof. As temperatures rise and weather patterns grow more violent, the question is no longer whether disaster will strike but when – and how hard. 

Economic losses from natural catastrophes reached $350 billion last year. And in this new age of climate uncertainty, insurers find themselves at a crossroads: adapt or collapse. The storms will come, but human and financial losses need not rise with the seas.

In California, wildfires now rage with such frequency and ferocity that several major insurance companies have simply quit. In less than a year, from summer 2023 to early 2024, eight insurers stopped writing new home policies in the state, claiming that wildfire risks made business untenable. 

Flood-prone areas are facing the same grim exodus of insurers, leaving thousands uninsured and vulnerable. This is the so-called "protection gap" – an inoffensive term that in reality means homes left unprotected, lives potentially left in ruins.

To close this gap, insurers must shift from paying compensation for damage to actively predicting and preventing it from happening. The existing model must ascend to the next level. The climate crisis has made nature too fierce, predictable only in its unpredictability. "Acts of God" have become commonplace. Now, the cost of reaction and response are just too high. Hence the need to predict and prevent.

Consider this: Every euro spent on disaster prevention saves between five and seven euros in recovery costs. This was a finding of the European Investment Bank; it describes a sound investment by any standard you choose. The question is why more insurers are not doing it. 

One answer lies in the sheer complexity of modern risks. Unlike hurricanes or earthquakes, so-called "peak perils," which tend to devastate large areas, wildfires and floods often strike with pinpoint precision. One house burns while its neighbor remains untouched. This confounds traditional risk models, which rely on broad statistical averages.

Technology presents a path through the fog. Geospatial technology, in particular – mainly satellite data, made intelligible with artificial intelligence and geoanalytics – can now monitor the planet in astonishing detail. Insurers can track weather patterns in real time, pinpointing the precise location of emerging risks. They can find out not just that a fire is coming, but exactly which valley it will sweep through and which homes lie in its path.

This is no longer science fiction. Some forward-thinking insurers are already using such tools. If a wildfire looms, they alert clients to take defensive action – clearing brush, installing fire-resistant materials or even hiring private firefighting teams. The same principle applies to global commerce. "Moving assets" – ships carrying vital goods – can be tracked minute by minute. If political unrest, piracy or a typhoon threatens a key shipping lane, insurers can warn businesses to reroute their cargo, avoiding catastrophe before it strikes.

Yet, for all its promise, this predictive approach to insurance faces resistance. It demands that insurers rise to the height of a major challenge, becoming highly active, data-driven risk analysts and managers, working closely alongside clients to reduce exposure before disaster hits. It means investing in historical datasets, sophisticated geospatial technology and human expertise. It means rethinking what insurance is or, if you prefer, "completing" insurance, realizing more of its potential to make human settlements robust.

Critics will say that such efforts are costly, that they will cut into profits. Or they'll say that the technology isn't there yet, that it can't possibly face up to the task we're facing. This is too pessimistic. 

Insurance emerged as a means to manage the uncertainties of a dangerous world, to save people from having to lean on neighbors and loved ones to pick up the pieces after catastrophe. It has evolved and evolved and evolved again as the world has changed. History, after all, is ruthless to those who won't adapt. 

Today, the dangers facing us have multiplied and intensified. So must the industry's capabilities. It isn't easy, but it is simple. That evolution, a genuine leap forward for this essential, even vital sector, can help to keep people safe.

We don't need to overstate the point, but the stakes are high. If insurers retreat from the riskiest places, the protection gap will widen into a chasm. Whole regions could become uninsurable, their economies shattered. The alternative is a world where insurers, equipped with expertise and the most advanced available technology, serve not just as financial backstops, as essential as those are, but as frontline defenders against the crises of the future.

The climate crisis is no longer a far-off threat to our communities. It is here, reshaping lives and landscapes with brutal indifference. Insurers have a choice: predict and prevent, rise to the occasion, enlarge its important social role as a guarantor of community resilience, or retreat. The storms will rage regardless. But how much we lose – both in lives and livelihoods – depends on what we do now.


Pierre du Rostu

Profile picture for user PierreduRostu

Pierre du Rostu

Pierre du Rostu has been CEO of the AXA Digital Commercial Platform since June 2022.

He started his career in consulting in 2011 before joining the AXA Group in 2015, where he first held several senior positions in commercial P&C. He was chief operating officer - international P&C at AXA XL, then global head of innovation and business architecture.

What Does AI Say About AI in Insurance?

"Generative AI isn’t just regurgitating pre-programmed responses anymore; it’s starting to think. Sort of....It’s not perfect, but it’s getting there—fast."

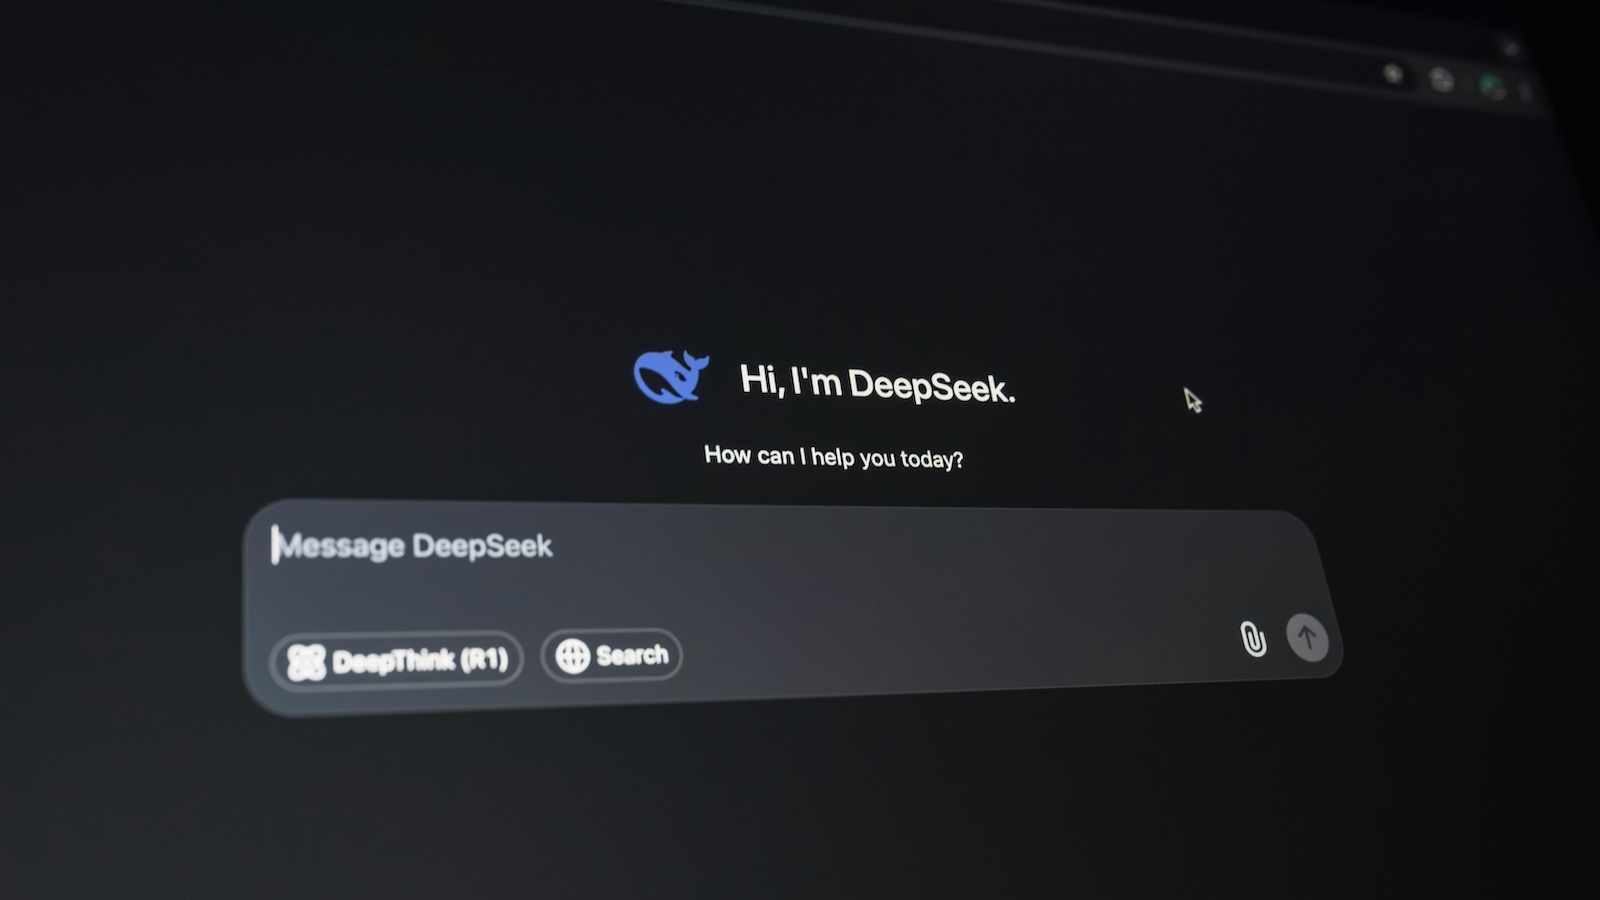
AI Interface on Dark Screen Display

My DeepSeek prompt: 

You're a management consultant who writes in the clean, edgy style of Hunter S. Thompson. Write a 500-word essay on generative AI in property and casualty insurance. Consider where we are in the context of OpenAI's five phases of AI: chat, reasoning, agent, innovation, organizations. Include specific use cases from insurance companies such as Progressive and Allstate. Consider the $450 billion in AI infrastructure investment made by Big Tech in 2025 alone. Consider the human and corporate reluctance to use AI to replace people, but also consider that humans hate jobs staring at screens all day moving tokens around.

See also: How AI Is Changing Insurance

DeepSeek’s output (unedited):

The Gonzo Frontier of Generative AI in Property and Casualty Insurance: A Wild Ride Through the Five Phases of OpenAI’s Vision

The property and casualty insurance industry is a beast—a bloated, bureaucratic leviathan that thrives on risk assessment, claims processing, and the occasional existential crisis. It’s a world where humans stare at screens all day, moving tokens of data like croupiers in a casino where the house always wins. But now, generative AI has crashed the party, and it’s not here to play nice. It’s here to rewrite the rules, disrupt the flow, and maybe—just maybe—set the whole damn table on fire.

Let’s start with OpenAI’s five phases of AI: chat, reasoning, agent, innovation, and organizations. Right now, the insurance industry is straddling the first three phases like a drunk cowboy on a mechanical bull. Chatbots are already ubiquitous—Progressive’s “Flo” has gone digital, answering customer queries with the kind of relentless cheer that only a machine could muster. Allstate’s “Digital Virtual Assistants” are handling claims inquiries, freeing up human agents to do… well, whatever it is humans do when machines take over the grunt work. But this is just the warm-up act.

The reasoning phase is where things get interesting. Generative AI isn’t just regurgitating pre-programmed responses anymore; it’s starting to think. Sort of. Allstate is using AI to analyze accident photos and estimate repair costs, a task that once required a human adjuster with a keen eye and a tolerance for tedium. Progressive is leveraging AI to predict risk with terrifying accuracy, crunching data on driving habits, weather patterns, and even social media activity to set premiums. It’s not perfect, but it’s getting there—fast.

Then there’s the agent phase, where AI starts to act autonomously. Imagine a world where your insurance policy updates itself in real time based on your behavior. Drive like a maniac? Your premium spikes instantly. Install a smart home security system? Your rates drop before you can say “Big Brother.” This isn’t science fiction; it’s the logical next step in a world where AI is increasingly calling the shots.

See also: How AI Will Transform Insurance in 2025

But let’s not kid ourselves. The real game-changer is the innovation phase, where AI doesn’t just optimize existing processes—it invents new ones. Picture this: generative AI designs entirely new insurance products tailored to niche markets. Pet insurance for crypto bros? Done. Pay-as-you-go coverage for gig economy workers? Easy. The possibilities are endless, limited only by the imagination of the algorithms.

And then there’s the organizations phase, where AI doesn’t just assist humans—it replaces them. This is where the rubber meets the road, and where the industry’s reluctance to fully embrace AI becomes glaringly obvious. Humans hate change, especially when it threatens their livelihoods. But let’s be real: humans also hate jobs that involve staring at screens all day, moving tokens around like digital Sisyphuses. AI can do that faster, cheaper, and without complaining about the coffee.

The $450 billion Big Tech poured into AI infrastructure in 2025 wasn’t just a flex—it was a signal flare. The future is here, and it’s powered by algorithms. The question isn’t whether AI will transform property and casualty insurance; it’s whether the industry will embrace the change or get dragged kicking and screaming into the brave new world. One thing’s for sure: the ride is going to be wild. Buckle up.

Author’s note: I started typing the prompt at 8:01 and submitted the article at 8:09.


Riv Arthur

Profile picture for user RivArthur

Riv Arthur

Riv Arthur is a business leader and technologist working in insurance, healthcare, and private equity.

Managing Divestitures of Entangled Business Assets

Strategic divestiture of entangled assets requires careful planning to minimize disruption and maximize retained value.

tangled brown ropes

The financial services sector currently accounts for about 10% of all deals and is experiencing positive momentum. Throughout 2023, the industry has maintained a consistent level of deal activity and has demonstrated year-over-year growth in both deal value and deal count. There is still a pressing need for organizations to improve their divestiture processes – in both selection and execution.

See also: 3 Key Workplace Challenges Reshaping Business

Complexities of Divesting Entangled Entities

When looking at a business through the lens of a divestiture, an asset can often be thought of in one of two ways: Either it is largely independent from the parent company, or it is dependent on infrastructure owned by the parent. The latter scenario, commonly referred to as "entangled," presents additional complexities regarding how to effectively separate during a divestiture.

"Entangled" is an umbrella term that can describe many relationships between the parent and the division being sold. These two parties might be connected by the labor they employ or by the infrastructure they use. The entanglements that are easiest to manage are relationships with third parties where the master agreement sits with the parent company but the purchase orders or statements of work specific to the entity being divested are straightforward. On the other end, time-intensive and difficult-to-manage entities are tethered to their parent companies by IT applications and infrastructure. In these cases, program management resources that can coordinate between different functions and subject matter experts within each function are crucial.

The degree of entanglement also affects compliance considerations that must be made when selling an asset that has previously been dependent on the parent company. These considerations will hinge on the size of the deal and the degree to which the industry in question is regulated. For insurance specifically, parent companies need to inform numerous regulatory organizations at both federal and state levels, while also completing an approval process for some aspects of the divestiture. Regardless of the industry of the seller, the parent company also must be compliant with employment laws when managing workforce reductions or as employees are moved to the new owner.

Practical Considerations

  1. Planning for the known and the unknown

It is important to establish a structure through which the divestiture will be managed. This management structure can include things like a governance hierarchy, a suggested schedule for when different groups should meet, the responsibilities of different required roles and a framework for making critical decisions. It is also important to ensure this management structure is flexible. The proper governance and meeting cadence that exists six months from the close of the transaction may no longer be appropriate when launch is only one month away. Having this flexibility will allow for the divestiture to maintain momentum throughout the process while also being able to respond to unforeseen complexities.

An effective way to facilitate this flexibility is to employ a program management team. The team will serve as the glue that holds things together, connecting different stakeholders with each other at the appropriate times and planning ahead for critical milestones. This team works within parameters of the governance structure to ensure quality, timelines and efficient decision-making. As the needs of the divestiture change, the program management team will adapt accordingly and keep the plan current. It is important for this team to communicate clearly and to keep the broader team motivated during periods of intense work.

  1. Establishing effective communication

A divestiture represents a time of uncertainty for employees of the company. When a deal is newly announced, employees will question the longevity of their jobs. How a company communicates with its employees during this stressful period will greatly affect employees' trust and engagement. As a successful divestiture is contingent on retaining key talent and continued engagement, communication to assuage employees' fears will go a long way to stabilize the situation and enable the success of the new organization.

There are different ways a company can effectively communicate with its employees. First, a central communications team should be established to own, develop and manage all communication activities and messaging. Key communication milestones such as deal announcements and employee town halls should be set and prepared in advance. Employee messaging should be as transparent and factual as possible and foresee questions that employees may have at the top of their minds. Less formal communication activities may also be deployed – such as smaller meetings hosted by department heads – however, it is important to ensure that the messaging delivered across all these meetings is consistent and vetted by the central communications team.

See also: How Business Rules Engines Can Slash Time to Market

  1. Retaining critical talent to limit business disruptions

Successful separations are predicated on retaining critical talent and staffing key roles with the right personnel. Separations signal times of change and uncertainty for personnel for various reasons, such as cultural misalignment with the acquiring company, changes in leadership and disruption in ways of working (relocations, job function changes, etc.), which often result in a marked increase in attrition rates. High turnover at the outset can affect company operations directly and indirectly – by demoralizing and placing extra burden on remaining employees.

There are, however, ways to limit talent disruption and impact on business operations. One way is the creation of a talent retention program, in which critical personnel are identified in advance and offered incentives to stay with the company. Incentives can be monetary (stock options, bonuses) and non-monetary (developmental opportunities). Incentives can also be set up to align with transition timing as the impact of the divestitures may sometimes be felt for years down the line. Encouraging employee engagement during the transition is another effective way to improve employee satisfaction, which reduces turnover and loss of productivity. Employees want to feel valued and heard in company matters, and engaging employee feedback is one way to achieve that.

  1. Mitigating Stranded Costs

"Stranded cost" is a term commonly used to describe a component of the parent company organizational structure that was previously supporting the divested entity but did not transfer as part of the transaction. Stranded costs can come in the form of people, third-party contracts, IT infrastructure or any other piece of the overall cost structure. These costs differ from other costs incurred by the parent company in that they no longer generate any value. Because of the entangled nature of many divested entities, planning for stranded costs, or even the recognition that they exist, can often be overlooked. This is a misstep that can be mitigated, but it requires the identification of potential problem areas upfront.

As an example, IT is a function that is often difficult to unwind and so creates stranded costs. This is in part driven by the contractual landscape that supports an IT function, as day-to-day activities are typically driven by a consortium of third-party agreements that may include outsourced resource support and hardware and software licenses. These agreements are often not in sync with the timeline of the divestiture, so the parent company may be responsible for paying for goods or services that it no longer uses once the transaction is complete. Timely planning and communication with the respective vendors can help to amend contracts and minimize any residual obligations. This process takes a considerable amount of time and effort, and the involvement required also scales in relation to how entangled the entity is and how many agreements it has.

In sum, companies in the process of divestiture can approach unraveling entangled assets thoughtfully by putting some guardrails in place. Establishing a structure with teams appointed to manage programs and talent retention, ensuring proper timing for all changes and putting existing employees' morale first are some ways companies can retain value and support their business through a transformation.


Jim Kane

Profile picture for user JimKane

Jim Kane

Jim Kane is a senior director at SSA, which advises the world’s largest companies on enhancing business outcomes

New Standard Life Insurance Application Simplifies Process

New ACORD standard life application promises to eliminate redundant questioning and streamline the insurance buying process.

Photo of People Wearing White Crew Neck Shirt

Have you noticed that all life insurance carriers ask the same basic questions on their applications?

"Who is the owner of the policy?"

"Who is the beneficiary of the policy?"

"Do you have a history of cancer?"

"Do you have a history of heart disease?" et cetera.

The problem is, while they all ask the same basic questions, none are identical, and all have enough differences that a producer can't simply ask the questions once and populate the forms. This causes a great deal of redundant keying and rework by the producer, and confusion with the customer. This is particularly true when a client wants multiple policies and must endure multiple instances of carriers' electronic applications.

With this frustration in mind, ACORD pulled together stakeholders from across the life insurance value chain to develop a first-of-its-kind standard life application that could be delivered in a digital format. This new application includes all reflexive questions, is pre-cleared for use in 48 jurisdictions, and will enable improved producer and customer experience.

Many have asked for one standard life application, and due to the various industry factors and trends below, the standardized life application has finally become a reality.

See also: A New Era in Life Insurance Underwriting

Consumer Frustration With Repetitive Online Applications

Historically, there has been a gap between the digital experience expectations of consumers and what the life and annuity (L&A) industry has provided during the life insurance application process.

Imagine a typical agent-assisted sale with today's digital application, requiring an investment of about 30 to 40 minutes of the client's time. The client completes the application online, but a meaningful percentage of cases today are "issued other than applied." The natural inclination is to apply for coverage with another carrier to try for a better risk classification and lower price.

The customer is expected to begin the application again, requiring another 30 to 40 minutes. In the customer's eyes, the questions are the same and have already been answered. Why couldn't the answers be saved and used by the next carrier? This is possible with a standard life application.

NIGO Delays for Producers

Now imagine an agent-assisted sale with today's paper application, which is frequently seen in the large case market, which is known for sophisticated policy ownership (e.g., trust-owned policies, business-owned policies, etc.) and often requires multiple policies.

The producer first typically completes a client intake form (abbreviated medical history) to perform field underwriting to determine the risk class to quote. When the carrier, product type, and amount are determined, the producer needs to complete each paper application, then proofread them before having the client sign them.

Even with rigorous proofreading, there is a significant chance a key question is missed, and the policy is NIGO (Not In Good Order), causing delays in underwriting. This translates into a delay for the carrier earning premium, a delay in coverage for the client, and a delay in payment of the agent's commission.

If carriers adopt the standard life application, both online and paper applications will be dramatically improved. Application/enrollment vendors can configure their platforms to ask the questions once, then populate the carrier's electronic applications when coverage is selected. The redundant field underwriting questions can be merged with the application's medical history questions so they only need to be asked once, and NIGO rates with paper applications will be reduced because the producers won't be forced to familiarize themselves with every detail of every carrier's forms.

Pre-Cleared by the Interstate Insurance Compact

The new standardized life application is pre-cleared for use in 48 jurisdictions by the Interstate Insurance Compact. The compact implemented electronic product filing in 2007 to review and approve carrier submission of product application forms for its member states, bringing uniformity to the industry, and keeping forms maintained and updated across jurisdictions. The compact has been involved with the creation of the ACORD Standard Life Insurance Application since the beginning and strongly supports adoption.

The standardized application was created with bracketed questions that carriers can decide whether to include or exclude. Reflexive questions were also included to reduce the number of supplemental forms. Carriers that choose to use the standard application will automatically be moved to the Compact's Expedited Review Process Queue. Upon compact approval, the carrier can personalize the form to fit their branding and documentation guidelines. This shortens the form's approval time for a carrier's application from weeks to days.

See also: Removing Pain Points for Life Insurance Actuaries

A Competitive Advantage for Carriers

Carriers recognized that the question structure of a standard life application can improve data quality. The standard life application's questions were designed to incorporate behavioral science principles and industry best practices to improve response accuracy and reduce bias. They were also designed to maximize the amount of structured data and minimize free text. This will ensure maximum automation in underwriting and reduce manual interpretation on some carriers' medical and exam forms.

The reflexive questions were designed to ask only information necessary to continue underwriting. The reflexive questions refrain from asking questions the client likely won't know (or may misstate), like tumor stage and grade.

In addition, the standard application forms packet contains a full litany of avocation questions rather than just scuba and aviation. It includes motor sports racing, powerboat racing, rock climbing, back country skiing, and many others, and asks reflexive questions relevant for many of the reinsurance underwriting manuals to determine the appropriate risk classification.

ACORD has already completed the mapping of the initial data structures from the standard life application and reflexive questions to the ACORD Next-Generation Digital Standards (NGDS) JSON formats for easy manipulation and traceability.

The Future of Applying for Life Insurance

The new standardized life application will change how consumers, distributors, and carriers work through the life insurance value chain. The application offers a solution to the convoluted, time-consuming, and frustrating process of applying for life insurance policies and makes it easy to match consumers' digital expectations in 2025.

The benefits of a standardized application are threefold: Consumers avoid confusion and misrepresentation on their applications; distributors reduce NIGO delays and improve efficiency when completing multiple applications; and carriers can reduce form approval times and implementation costs with their enrollment system vendors.

The $1.5 Trillion Opportunity for Home Insurers

A study finds that U.S. homes will lose $1.47 trillion of value by 2055 because of climate change. Therein lies a major challenge — and opportunity. 

Image
Large colorful puzzle pieces being put together by 6 different people

A new study reports that U.S. homes will lost 6% of their value in the next 30 years, or a collective $1.47 trillion (that's trillion, with a "t"), because of climate change and the staggering premiums that insurers will have to charge to cover the growing risks.

The study by First Street, a group that focuses on climate threats to housing, says the home insurance premium amounted to about 8% of the mortgage payment not long ago. Today, the average is closer to 20%. And First Street says premiums will rise an average of 29% by 2055, not counting inflation, to catch up with the risks that aren't currently priced into premiums (partly because of resistance from regulators) and to account for the growing threats from climate change. Some locales may see premiums double or quadruple, soaring so high they become unaffordable.

Unless....

... insurers find a way to work with homeowners, regulators and other government officials to reduce the risks. Saving homeowners some significant portion of $1.47 trillion would be a huge service to humanity, while being immensely profitable for insurers. 

And I'm not sure I've ever seen the media so sympathetic to insurers, on any subject, so now would be a great time to start. 

The report by First Street says insurance currently underprices climate risk for 39 million properties across the continental U.S. That's 27% of the total. 

And First Street projects that as premiums soar to match the growing risks, the decline in housing values will just be the beginning of the disruption. It talks about climate change migrants — people who move to escape its effects. First Street says there will be 5 million such climate migrants this year alone and 55 million by 2055. Among other things, First Street predicts that the migration will slow the growth of the Sun Belt. (It also singles out Sacramento, which I live near, as one of the cities that will be hit hardest by rising insurance premiums. Hmmm.) 

A lot will happen between here and 2055, so the effects are hardly set in stone. But the report lays out in stark detail the opportunities — and challenges — that homeowners insurance presents for aggressive, forward-thinking insurers.

The way the report has been covered, along with recent stories about insurance, also shows remarkable sympathy for insurers, caught between frightening climate scenarios and regulators wanting to protect consumers from too-rapid disruption. We're all used to seeing complaints about heartless insurers canceling policies and not paying claims, so the different tone has been refreshing. 

Here is an essay in the New York Times, described as a joint effort between ProPublica and the Times, that presents the First Street data as requiring price increases by insurers. The same with this piece in USA Today, which sneaks in a little brag about how long and extensively the publication has been writing about First Street, in particular, and climate's effect on home ownership, in general. Here is another piece in the Times, this one laying out the oh-so-very-long timeline for people trying to rebuild after the recent fires in the Los Angeles area, dramatizing the pain of restoration and, thus, the importance of prevention. Here is a piece sympathetic to insurers in the Washington Post. I could go on. 

I wrote just three weeks ago about what I think next steps for insurers should be, as they try to help policy holders harden their properties and prevent damage from future natural disasters, so I'll merely summarize here:

  • Engage with regulators and government officials at all levels and use the shock from the LA fires as a way to get to the tough conversations that need to be had about pricing risk properly and about how to persuade policyholders to change risky behaviors. These conversations must go way beyond the 22% increase in homeowners premiums that State Farm just filed for in California.
  • Educate those who have lost properties on how to build back stronger and encourage them to do so.
  • Try to get information on climate risks to potential buyers or builders of homes long before they're about to sign on the dotted line. Zillow has taken steps in that direction. The First Street study is another example. There must be many more.
  • Help communities develop and stress test plans to better protect themselves.

As much as we all hope the LA fires will mark a turning point in the thinking about climate risks for homeowners, we also know that we have so very far to go. But the First Street report provides some dire forecasts that can serve as sort of anti-targets, as outcomes to avoid. 

Let's keep building momentum.

Cheers,

Paul

Cancer Breakthroughs: Insurance Impact?

Munich Re explores exciting breakthroughs in the diagnosis and treatment of cancer and what they mean for life and living benefits insurance. 

Artistic view of Cells Under a Microscope

Cancer is the leading cause of death among life insurance policyholders. In recent years, we have seen an explosion of groundbreaking advances in cancer research that are changing the way that cancers are defined, prevented, diagnosed, and treated. These advances are expected to drive significant improvements in cancer mortality, even beyond what we have seen in the past few decades. 

The profound and swift evolution of cancer knowledge will have far-reaching implications for various facets of life and living benefits insurance products, underscoring the need for insurers to remain vigilant and adapt to this shifting landscape.

Improving Cancer Outcomes is one of the five critical topics featured in Munich Re’s 2025 Life Science Report, a wide-ranging thought leadership project intended to help life insurers better understand and navigate prevalent emerging medical trends and risks.

Key Insights:

  • Prevention efforts will leverage the power of AI to integrate and analyze vast amounts of biometric, genetic, and imaging data and improve cancer risk prediction. Insurers will need to monitor this to anticipate potential anti-selection behavior.
  • Diagnostic advances will also be fueled by the power of AI and the acceleration of earlier cancer detection by molecular/genetic analysis of bodily fluids (‘liquid biopsy’). Potential changes in how cancers are classified will require the modification of insurance product definitions.
  • Therapies will continue to progress into more and more personalized treatment, further enhanced by tumor genetic analysis with targeted drug development and immunotherapies, such as personalized cancer vaccines. Much of this, however, will come at a high financial price, which could significantly impact health insurance costs and limit access in some markets.

Visit our Life Science Report page for more information and to access additional chapters as they are published, including AI in Healthcare (available now), Prevention (February 18), Obesity (March 4), and Climate Change (March 18). 


ITL Partner: Munich Re

Profile picture for user MunichRepartner

ITL Partner: Munich Re

Munich Re Life US, a subsidiary of Munich Re Group, is a leading US reinsurer with a significant market presence and extensive technical depth in all areas of life and disability reinsurance. Beyond vast reinsurance capacity and unrivaled risk expertise, the company is recognized as an innovator in digital transformation and aims to guide carriers through the changing industry landscape with dynamic solutions insightfully designed to grow and support their business. Munich Re Life US also offers tailored financial reinsurance solutions to help life and disability insurance carriers manage organic growth and capital efficiency as well as M&A support to help achieve transaction success. Established in 1959, Munich Re Life US boasts A+ and AA ratings from A.M. Best Company and Standards & Poors respectively, and serves US clients from its locations in New York and Atlanta.


Additional Resources

Drug deaths a concern for life carriers

A 25% increase in substance abuse death rates in the college-educated population is a particularly worrying trend for the life insurance industry.

Read More

EHRs transform life underwriting

Our extensive study confirms the value of electronic health records (EHRs) across life underwriting use cases.

Read More

Life insurance fraud trends

Munich Re’s survey reveals which types of fraud have been on the rise for U.S. life insurers in recent years.

Read More

Recent patterns in cancer claims

Cancer is the most common cause of death for the life insurance population. Munich Re analyzes recent trends.

Read More

The digital future of life insurance

Leverage emerging technologies to improve operational efficiency, enhance underwriting processes, and expand insurance accessibility.

Read More

February ITL Focus: Cyber

ITL FOCUS is a monthly initiative featuring topics related to innovation in risk management and insurance.

Padlock on the left, and to the right the ITL Focus logo, along with Cyber, February 2025, Sponsored by Boxx Insurance


FROM THE EDITOR 

Watching cyber insurance mature over the past decade has been fascinating, with attacks and counterattacks reminiscent of the old Spy vs. Spy cartoons in Mad magazine – just at high speed, with serious stakes and with a clear delineation between the good guys and the bad guys. 

Cyber insurance began with a stark realization – not just that it was needed but that existing policies might cover a major risk that insurers very much didn’t want to be covering. At the same time that carriers started offering cyber policies, they were rewriting general liability policies to make very clear that cyber attacks weren’t covered.

Early attacks focused on stealing Social Security numbers, credit card information and other data that the bad guys could use to impersonate people. But credit card companies responded with, among other measures, faster response to fraudulent purchases and with secure chips in credit cards. 

So hackers went to a new level, hacking into corporate systems, stealing and encrypting data necessary for running a business and demanding ransom in return for tools that would decrypt the data. But then the good guys responded by not just improving their defenses but by creating backups that they would use if their main systems were compromised. 

Now we’re on to the new battle. Hackers are using AI to quickly sift through corporate systems once they’ve wormed their way in and are being much more strategic about the information they’re after. Once they have it, they may threaten to make it public and extort payment in return for silence. AI also keeps lowering the cost of doing business for hackers. They can, for instance, come up with a general template for an attack, then have AI replicate it and go after orders of magnitude more targets than were reachable in the past. The AI can even translate the attacks into other languages and do custom coding to facilitate the hacking attempts. 

But the amped-up attacks are hardly the end of it. As Vishal Kundi, co-founder and CEO of Boxx, explains in this month’s interview, the good guys can use the same tools that hackers use to scan corporate systems, to spot vulnerabilities and to fix them before hackers can exploit them. Boxx monitors conversations on the dark web to see what information is being offered for sale, so it can warn any clients who’ve been compromised. Boxx is also increasingly providing modules of cyber insurance that merchants or platforms can buy and embed into digital commerce to cover individual transactions and make customers feel safer. 

What comes next? We’ll just have to keep our eyes and ears open. Spy vs. Spy battles are often surprising. 

In the meantime, I think you’ll find the interview with Vishal enlightening – dare I say, even encouraging. 

Cheers, 

Paul

 
Banner Headline reading "An Interview with Vishal Kundi", next to a headshot of Vishal


"Cybercriminals are constantly looking for new ways to extract money, and they’ve realized that the ability to rebuild data no longer holds the same weight. What truly gets a company’s attention now is the threat to its reputation, particularly when it comes to customers. If a hacker can threaten to publicly expose sensitive customer data, that becomes a far more effective tool for extortion. "

Read the Full Interview

"Cybercriminals are constantly looking for new ways to extract money, and they’ve realized that the ability to rebuild data no longer holds the same weight. What truly gets a company’s attention now is the threat to its reputation, particularly when it comes to customers. If a hacker can threaten to publicly expose sensitive customer data, that becomes a far more effective tool for extortion."


— Vishal Kundi

Read the Full Interview
 

READ MORE


Cybersecurity Risks Surge Across All Business Sectors

New cybersecurity data reveals manufacturing and supply chains face unprecedented risks as digital operations expand.  

Read More

Why is the Cyber Insurance Market So Soft?

Insurers are writing adaptive policies, and organizations have improved their defenses.  Underwriters now have a big opportunity to innovate.  

Read More

Insurance Fraud Rises as AI Powers Scams

Insurers must balance sophisticated fraud prevention with seamless customer experiences in an AI-driven landscape. Here's how.  
 

Read More

Man with beard and glasses staring off, images of a computer screen reflecting back on his face

Deepfakes: An Emerging Cyber Threat

As AI evolves and becomes more user-friendly, deepfakes will likely play a bigger role in cyber crime. Insurance companies must stay one step ahead.

Read More

How AI is Reshaping Cyber Insurance

AI emerges as both threat and solution in cyber insurance, reshaping risk assessment and breach response.

Read More

Main Frame Image

The Need for 'Systems Failure' Coverage'

The recent CrowdStrike outage and disruption to businesses of all sizes has refocused attention on the value of cyber insurance for non-malicious losses."

Read More


FEATURED THOUGHT LEADERS

Rajeev Gupta Headshot
Charles Grodecki Headshot
Laura Barrowcliff Hedshot
Gwenn Cujdik Headshot
Anshu Gupta Headshot
Megan Silverman Headshot
Stephanie Snyder Frenier Headshot


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

P&C Insurance Brokers Must Evolve

In today's volatile P&C market, brokers must evolve beyond policy sales to become strategic risk advisres.

Risk

What does it take today to stand out in today's crowded property and casualty insurance landscape? The property and casualty (P&C) insurance landscape is always changing, and rarely do you find a time such as now where changes are happening more rapidly than ever. Recent industry data suggests that global insurance premiums are expected to continue to increase over the next five years. This trend is driven by increasingly severe weather events, economic uncertainty and inflation, creating pressures that brokers must navigate, with clients looking for brokers not only to secure policies but also to provide consultative support in managing risk.

With these dynamics in play, brokers have an opportunity to stand out by taking on a more modern, strategic advisory role — offering solutions that extend beyond traditional carriers. 

Let's look at the challenges P&C brokers encounter, the broad solutions available and how they can meet client needs by building long-term, resilient partnerships.

Managing Volatile Premiums in Hard Markets

In hard markets, clients often face significant premium increases and limited capacity, making it challenging to maintain affordable coverage. In fact, in 2023, the average commercial property insurance premium rose by over 20%, and some sectors — like real estate and manufacturing — saw even sharper spikes. Rising premiums coupled with restricted options can strain clients' budgets, requiring brokers to find alternative ways to stabilize costs. Chasing rates, increasing deductibles and reducing total insured value should not be the only options.

One solution is structured and customized insurance programs, which can help level out premiums over time and smooth the impact of market cycles. Brokers might also suggest exploring alternative risk retention strategies that allow clients to focus on specific, essential coverages tailored to their unique needs. These targeted approaches allow clients to stabilize costs without sacrificing coverage, fostering trust and demonstrating the broker's commitment to client needs and reducing attrition.

See also: Does the P&C Insurance Cycle No Longer Exist?

Meeting Demand for Specialized or Hard-to-Find Coverage

With emerging risks and niche markets on the rise, brokers are increasingly tasked with finding customized coverage solutions. According to a recent survey, 70% of executives report that they need more specialized insurance to address the unique risks of their industry, particularly in areas like cybersecurity, construction and health care.

To meet this growing need, brokers can help clients implement self-insured retention (SIR) programs, where businesses set aside funds for certain types of predictable losses while insuring more catastrophic risks in the traditional market. For industries facing complex or niche risks, bundling multiple specialized coverages into one policy can simplify protection while addressing specific exposures. These solutions allow clients to manage unique risks, helping brokers address specialized demands and enhance client satisfaction.

Improving Client Control Over Claims Management

Claims management can significantly affect the client experience, and a lack of transparency or delayed handling can cause friction. A report from Accenture highlights that dissatisfaction with claims handling can drive policyholders to switch providers, with around 74% of dissatisfied customers indicating they either changed providers or are considering it. For brokers, guiding clients toward more transparent and efficient claims management is essential in maintaining strong relationships.

Brokers can advocate for using third-party administrators (TPAs) that offer more tailored, efficient claims management services. TPAs give clients greater visibility and control over the claims process, creating a more proactive and aligned experience. Furthermore, brokers can encourage clients to implement safety and risk management programs, which can reduce claims frequency and improve outcomes. By helping clients take control of their claims, brokers position themselves as essential advocates in achieving smoother claims handling and better client experiences.

Enhancing Client Risk Management Practices

Effective risk management is not only a strategic priority for clients — it directly affects their insurance costs, claims experience and overall profitability. For example, industries with significant physical risks, like construction and manufacturing, can see substantial benefits from implementing comprehensive safety programs. According to the U.S. Bureau of Labor Statistics, businesses with strong safety programs can significantly reduce workplace injuries, which leads to fewer workers' compensation and liability claims. Over time, this can improve clients' claims histories and lead to more favorable premium rates.

By guiding clients to adopt robust risk management strategies, such as safety training and real-time monitoring technology, brokers help stabilize clients' insurance costs, making them less vulnerable to market fluctuations and claims-driven premium hikes.

Innovative Risk Financing Options: Adding Captive Insurance to the Toolkit

For clients who face unique or complex risks, alternative risk financing options such as captive insurance can offer significant advantages. While not suitable for every client, captives allow businesses to retain and manage risk more effectively, with benefits such as greater premium stability and customized coverage. According to industry data, nearly every Fortune 500 company now uses captive insurance for some portion of their risk management program, with captive formations growing among small and midsize businesses, underscoring its value in stabilizing volatile premiums and addressing niche risks.

A captive can be particularly beneficial for businesses with frequent, high-volume claims or those seeking customized coverage outside traditional markets. For example, a construction firm dealing with regular but predictable liability claims might use a captive to manage these costs more efficiently, while still maintaining traditional coverage for catastrophic events. Brokers who offer captives as one of several advanced risk financing strategies provide clients with greater control and flexibility.

See also: P&C Trends Point to Transformative 2025

Building a Strategic, Long-Term Partnership with Clients

Success in the evolving insurance landscape requires brokers to go beyond one-off policy placements and build enduring relationships with clients. By acting as strategic advisers, brokers can help clients not only manage immediate risks but also achieve long-term stability. Clients who view their brokers as invested partners are more likely to remain engaged and receptive to future recommendations.

In this regard, captives are one of many solutions brokers can suggest as part of a comprehensive, client-centered approach. By emphasizing risk management practices, transparent claims handling and strategic solutions tailored to individual needs, brokers foster trust and loyalty — key components of lasting partnerships.

Future-Proofing With a Diverse Set of Solutions

The challenges and opportunities in the P&C industry continue to grow, and brokers who build a versatile, innovative toolkit will be best positioned to meet evolving client needs. From structured programs and TPAs to specialized coverages and captives, today's brokers have a wide array of strategies at their disposal. By focusing on education, strategic advising and client-specific solutions, brokers can build resilient relationships, creating value and positioning themselves as trusted advisers for the long term.

In a market where client demands and risks are constantly shifting, brokers who prioritize a consultative approach and embrace diverse, customized solutions will be the ones who lead — helping their clients navigate the future of risk with confidence.

Data Orchestration Reshapes Future of Insurance

Data orchestration emerges as the key to transforming insurance from policy-centric to customer-centric operations.

Technology

Capitalizing on a data-driven future is fundamental to reclaiming insurance's rightful place as the backbone of societal resilience and progress.

The future of insurance hinges on relationships. These relationships extend between people, their possessions, health, future, present, companies, families and ability to thrive in the face of losses.

It's a complex web that insurers must navigate. It extends beyond customers to include ecosystems - comprising both in-house innovations and integrated partner solutions - their staff, and adaptive business models and pricing that all interact simultaneously. At the core of this relational network lies data, the foundation upon which insurers must build sustainable, adaptive enterprises.

For example, if insurers hope to adopt AI as a foundational tool for delivering smarter, more adaptive customer experiences, the business and supporting technology model will need to change substantially. Harnessing multi-agent AI and applying it responsibly and securely across operations requires a robust data model. One that centers data on the customer and the dynamic world they inhabit, processes it in a fluid, near real-time manner and then integrates the resulting insights into personalized customer experiences.

Consider this scenario: You're involved in a car accident and press your car's "help" button. Instantly, emergency services and roadside assistance are alerted and dispatched to your location. Your family receives an automated text, reassuring them that you're safe, while your car begins interacting with a network of connected systems. The car initiates your insurance claim, retrieving policy details, assessing damage via integrated sensors and pre-filling forms for you.

As the process unfolds, you receive real-time notifications: repair options tailored to your location, transparent updates on claim progress and reminders about next steps. The system anticipates your needs, suggesting rental car services or alternative transport arrangements, ensuring your journey is minimally disrupted.

This is the power of data orchestration -- an intelligent and connected data ecosystem working together to transform stressful moments into smooth, supportive experiences.

However, disconnected, policy-centric insurers will continue to struggle to participate in this data-driven world. The question is, what does the insurance sector need to do to harness the value of data orchestration and apply it to transform customer experiences for the better?

In short, a fundamental rethinking of how insurance is built.

Insurers must shift from being policy-centric to customer-centric, ensuring their systems can adapt dynamically through the seamless flow of data. Whether that's enabling smooth integrations or rapidly shaping personalized experiences through low-code user interface (UI) capability tools, adaptability must be at the core of their design.

This adaptivity is reinforced by being born into the cloud as opposed to adapted to be hosted by it. This creates significant core resiliency and transferability between cloud platforms.

Such a foundation gives insurers the potential to operate like e-commerce style businesses, offering innovative products that address whole insurance needs. This approach also empowers them to overcome challenges in selling, servicing and partnering across a diverse technological ecosystem.

This is about creating a true adaptive future. One where data is no longer abstracted, stored, analyzed and then painstakingly reintegrated through layers of legacy systems and policy-based architecture. A future where insights don't have to be manually engineered back into the customer experience only to be hard-coded and rendered inflexible over time.

For those in multiple partnerships, the challenges are even greater -- constantly reconfiguring how data interacts with new services or ecosystems.

Principally, businesses need to intelligently orchestrate customers and build relationships and products and services into those relationships -- doing so in ever-widening ecosystems.

Data-driven futures are about treating data as a perishable asset, constantly mining it for insight and acting on it. AI will do much of the analysis and even much of the customer orchestration over the coming years, but even this lower level of use for AI is difficult if you're not built right. This is potentially at the heart of the legacy issue and why it is only now arriving at its crunch point.

Operating more efficiently, keeping up with regulation and competing on price has worked for insurers, but at this stage even doing those things competitively will require a significant shift in enterprise design.

It's time for a change, and intelligently orchestrating data is fundamental to all of it.


Rory Yates

Profile picture for user RoryYates

Rory Yates

Rory Yates is strategic adviser for insurance at Synechron, a digital transformation consulting firm.

He previously was the SVP of corporate strategy at EIS, a core technology platform provider for the insurance sector.