Download

Is Insurance Ready for AI Agents?

In this Future of Risk interview, Gallagher Bassett's chief digital officer, Joe Powell, details how far AI has come in insurance and where it goes next (carefully).

JOe future of risk banner


joe headshot

Joe Powell joined Gallagher Bassett in 2014. He serves as chief digital officer, overseeing data, analytics, and product innovation functions.

His team manages GB's innovation road map, including Luminos RMIS, Waypoint decision support, and GB's suite of AI technologies. The team also provides a wide range of analysis, reporting, and insight services, from basic loss runs to state-of-the-art machine learning-based benchmarking.

Previously, Powell served as a management consultant at Bain, focusing on initiatives involving growth strategy, corporate investment planning, IT strategy, post-merger integration, and cost reduction across numerous industries.

He holds a bachelor of science degree and a master of science degree in management information systems, both from the Kelley School of Business at Indiana University.


Insurance Thought Leadership

How would you describe the transition from basic generative AI to agentic AI?

Joe Powell

I'll start with AI as it existed when ChatGPT was launched in 2022. It was this raw foundation model that you could ask questions of, and it would give you a cogent -- maybe not completely accurate, but at least coherent -- response. It sounded like a human. It was magical.

From there, the progression has been a relatively natural evolution toward better and better accuracy, to the point where eventually that accuracy becomes so good that you can begin to use it to take action. That's the nature of agentic AI -- you're going from something that is error-prone to something that hopefully is highly accurate and is driving action for your organization.

You could imagine the progression: When we first got into AI, having a chatbot like ChatGPT was impressive in itself. Eventually, it evolved to allow handling documents and asking questions about them. The next step was allowing the AI not just to get you the answer from that document but to show you where in that document it found the answer, thus getting a little bit more action-oriented. Eventually, the AI gets to a place where you've implemented this seamlessly in an organization's process, and through that process, it's handling a step or helping with a step and presenting information to a person to make a decision. Finally, you get to a place where the AI is taking that action out of a person's hands, and operating autonomously. That’s when you achieve the true goal of agentic AI.

Insurance Thought Leadership

What are some examples of AI taking actions traditionally performed by humans, either at Gallagher Bassett or in the industry at large?

Joe Powell

In the industry, we're generally not at the point where AI can make major decisions yet. There are two important dimensions to consider when thinking about agentic AI and what actions it should take. First, how critical is the decision? Another way to think about this is: What are the consequences if the decision is wrong? And second, how autonomous do you want the AI to be?

As decisions become more critical, you're less likely to want AI making them. For instance, you're not going to have AI deciding the settlement on a $10 million claim. Instead, you'll start with AI handling relatively routine, day-to-day decisions. As it becomes more sophisticated and accurate, you'll trust it with increasingly critical decisions.

The same principle applies to autonomy. The right approach is to begin with AI providing information to help you make decisions. Then, as it progresses, AI will help make recommendations. Eventually, you'll reach a stage where AI is making decisions with human oversight, and finally, it will make decisions with full autonomy.

Insurance Thought Leadership

What are some current examples of AI applications that meet appropriate risk and reliability standards?

Joe Powell

Around the industry, we're seeing organizations take a cautious approach by starting with low-risk decisions. Much of what we're seeing involves having AI review work that humans have already completed – for example, reviewing completed policy work or double-checking the coding on a claim.

At Gallagher Bassett, we're developing a tool to help flag urgent emails. This addresses a micro-decision that people make every day when reviewing their inboxes -- determining which messages are critical. Having AI serve as a second set of eyes to identify important demand letters and determine what needs immediate escalation is highly valuable.

These are the types of low-risk applications where we're starting to see AI step in -- relatively small day-to-day decisions where having an automated helper or second set of eyes can provide significant value.

Insurance Thought Leadership

It seems AI could be a good verification tool, given the recent story about AI quickly detecting a mathematical error in research about black plastic spatulas that was overlooked by human researchers?

Joe Powell

Absolutely. There are analogs for our industry, as well. You could imagine somebody entering a plan of action on a claim and having AI double check to make sure it aligns with what was prescribed in the prior plan of action -- what was going to be done, what was going to be followed up on, and whether those action items were addressed. 

AI can also be a huge help in ensuring adherence to best practices and consistent product delivery. At Gallagher Bassett, we use both generative AI and machine learning models to help us make more consistent decisions in various ways.

We tend to leave the power in the hands of our claims experts but still have AI offering recommendations or acting as a check. A simple example is determining the right reserve at a given time. We ultimately equip our adjusters to make a decision on the most likely ultimate financial outcome on that claim, but we have AI models running in the background that are constantly checking to say, "Is this what the AI would come up with?" If not, we have a conversation about why, and whether a reserve change is needed.

Insurance Thought Leadership

How do you ensure that AI implementation genuinely helps adjusters and customers rather than becoming technology in search of a problem?

Joe Powell

A few ways. One is getting those people involved early in the decision-making process. We have a team of former adjusters, whom we call AI specialists, that are engaged in our AI design team. These individuals advocate from the very beginning of an AI project in terms of how to make the AI effective in the adjuster’s workflow.

Second, as the product progresses to something usable, you want to begin testing it in multiple ways. There's automated testing for accuracy, which includes head-to-head tests with actual people to see which one's more accurate. You do automated tests to see how consistent the AI is in its decision-making and whether that reveals areas where we might need to improve the model. Finally, you gain feedback early in the process from a pilot group.

As an example, we launched a tool that summarizes claim files. You can imagine, if you're an adjuster handling an insurance claim that's been open for a few years and is highly complex, it can have hundreds of pages of documentation. It can be extremely helpful to have the AI scan through those hundreds of pages and give you a tight summary.

The summary covers what happened with the claim, the medical situation, how legal has progressed, whether we're nearing settlement, and what next steps have been documented. It also provides the ability to drill into any one of those areas to find out more. The user can then dive deeper into specific pieces of information, like all the medical visits that have happened.

We had the AI specialists involved upfront, but we also piloted it and got phenomenal feedback from adjusters in the field. We also asked what more we could provide. The input was key to the tool’s success when we launched this across our entire North America operation.

Insurance Thought Leadership

How do you envision teams of AI agents working together, particularly in claims processing?

Joe Powell

This is an interesting problem because as an organization and industry we're launching more and more AI tools, and they all tend to report back to the human user -- typically the adjuster, in our world. 

I like to use the analogy of a basketball team. If you're playing basketball and you can only talk to the coach, you as a team are not going to communicate well. The players need to be able to communicate with each other, not just with the coach.

I think that's the next stage, especially as we see more agentic AI that's actually taking action. Those actions, just like human decisions, need to be based on information from other agents and what they're seeing. For example, if you have an AI that handles claim intake and asks various questions, being able to distill that information down and perhaps having a back-and-forth between that AI agent and one that's concerned with detecting fraud could equip the fraud agent to do an even better job.

The interplay between these AI agents is something we're just beginning to experiment with, but it's really powerful. In the same way that a human would be much less productive if they could only work by themselves and never ask anybody questions, AI agents will be much more productive when they can begin to interact and share knowledge.

Insurance Thought Leadership

How will you approach integrating AI agents that span different organizations, ones that maybe start with Gallagher Bassett and eventually expand to carriers and brokerages?

Joe Powell

For the foreseeable future, it's much more realistic to do this within a controlled environment. But we're laying the groundwork for broader implementation.

For example, we have that AI that engages with email -- flagging important messages and gleaning critical information from them. We've got an AI that covers claim documentation and another AI that listens to phone calls, creating transcription summaries, checking if we're following best practices, and analyzing the sentiment of the person on the other end of the call.

When you've got these various sources of information available to AI, we can begin to pull relevant pieces from each to make things like litigation predictors or reserve predictors even more powerful. Whatever you could dream up becomes possible when you can access and integrate these various sources of information.

Insurance Thought Leadership

What are your thoughts on the trend of moving from large language models to small language models that are specific to industries and business functions?

Joe Powell

It'll be interesting to see how this develops. There's a lot of experimentation happening around whether to use large language models (like ChatGPT 4o), small language models (smaller, more efficient models), or large language models that have been fine-tuned for specific industries.

Which approach fits best with which use case is something we'll likely gain better insights about in the coming months and years. Right now, there’s a bias toward large language models because they tend to be more accurate and thus are lower risk, but there could theoretically be a place for small language models for very low risk use cases.

Insurance Thought Leadership

AI processing capacity is reportedly doubling every 3.4 months, so there’s certainly a lot of runway in front of us. 

Joe Powell

There are some interesting rumblings about whether AI is hitting a plateau. While I don't have a strong opinion on that, I think this discussion misses a crucial point: There's a tremendous amount of value we can derive from applications of AI even if the underlying technology itself doesn't get dramatically better.

It's similar to what happened with the internet. At a certain point, even if bandwidth doesn't massively increase, there's still so much you can do with it simply by connecting people -- you just have to figure out creative ways of using the technology. That was true 30 years ago, and it's still relevant today.

We've got the foundational AI technology now.

Insurance Thought Leadership

I'm sure some amusing situations will come up as AI agents talk to each other. I remember moderating a panel in the late 1990s, when a senior partner at a major VC firm talked about using early versions of speech recognition in his car and in his phone. At one point, he said, his car said something unprompted. The phone responded, "I don't understand you." The car started talking back, the phone responded, and so on. His car and phone had this long conversation that he couldn't figure out how to stop.

Joe Powell

You do have to tightly prescribe those interactions. I'm probably making it seem like you just put the two together and say, "Have a conversation," but there's going to have to be a lot of forethought in terms of the architecture. You need to consider what information you want them to share and how it will be shared so you don't have these surprises, but instead have the right information flowing from the right agents to the right agents.

Insurance Thought Leadership

What advice would you give readers looking to begin their AI journey?

Joe Powell

There are several ways companies can get started. One is to build your own, which is what big, well-resourced claims organizations are going to want to do. You build a team of AI experts and invest in the infrastructure -- specifically a private and secure in-house AI environment. It's quite an investment, which is why this path is typically for larger organizations.

Smaller organizations can take different approaches. One option is to work with AI startups and organizations that are selling their services on an ad hoc basis. This is a fast way to get to value. However, longer term, this option presents some risks in terms of what I described -- if you eventually want your AIs taking action and working together, you need them to be cohesive. If you've gone with a multi-vendor approach where you're taking very specific skill sets from each of them, the question becomes whether they'll be able to work well together in the future.

The other option, and probably the better option for most organizations that have claims or claim handling needs, is to partner with an organization that offers an end-to-end solution -- one that has a vision that you share. The key then becomes a matter of making sure you do indeed share a vision -- in terms of their adherence to privacy and security, accuracy, where you think the technology will go, and the organization’s capability to improve your outcomes in terms of better claims results, better communication, and better employee experience.

Insurance Thought Leadership

How do you determine which functions to outsource? The case of Borders Bookstores outsourcing their online book sales to Amazon in the 1990s seems like a cautionary tale.

Joe Powell

Yeah, 100%. That's a fantastic point. At Gallagher Bassett, when we think about what we should build, we look at our core competencies.

The claims summarizer is a great example. We're experts at handling claims -- it's a huge part of what we do as an organization. So naturally, when we want an AI to help us digest claims into tight summaries, that's something we feel we're better than anybody else at taking on. But when you look at something like building the foundation model, that's not something we're going to try to do. There are other examples where we might say OpenAI or Google would be better because that's their game.

Insurance Thought Leadership

This is great. Thanks, Joe. 


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

4 Strategic Risk Transformations | Leveling Up as a Risk & Safety Professional

In today's fast-paced risk environment, traditional roles in claims, insurance management, safety, and GRC are evolving into strategic positions crucial for organizational decision-making. Discover the four key ways to elevate your approach to risk by downloading the eBook.

two people working

Today’s complicated, fast-moving risk environment is forcing changes to traditional roles across claims and insurance management, safety, and Governance, Risk and Compliance (GRC). How will you stay ahead?

While these roles may historically have been heavily weighted toward administration and reporting functions, the modern risk professional is increasingly a strategic role looked to for insight and context that factors heavily in the decisions made by organizations’ leadership teams.

The transformation to a more strategic and impactful approach to risk requires a move toward 4 key ways to level up.

Download Now  


Sponsored by: Origami Risk


ITL Partner: Origami Risk

Profile picture for user OrigamiRisk

ITL Partner: Origami Risk

Origami Risk delivers single-platform SaaS solutions that help organizations best navigate the complexities of risk, insurance, compliance, and safety management.

Founded by industry veterans who recognized the need for risk management technology that was more configurable, intuitive, and scalable, Origami continues to add to its innovative product offerings for managing both insurable and uninsurable risk; facilitating compliance; improving safety; and helping insurers, MGAs, TPAs, and brokers provide enhanced services that drive results.

A singular focus on client success underlies Origami’s approach to developing, implementing, and supporting our award-winning software solutions.

For more information, visit origamirisk.com 

Additional Resources

ABM Industries

With over 100,000 employees serving approximately 20,000 clients across more than 15 industries, ABM Industries embarked on an ambitious, long-term transformation initiative, Vision 2020, to unify operations and drive consistent excellence across the organization.  

Read More

Webinar Recap: Leveraging Integrated Risk Management for Strategic Advantage

The roles of risk and safety managers have become increasingly pivotal to their enterprises' success. To address the multifaceted challenges posed by interconnected risks that span traditional departmental boundaries, many organizations are turning to Integrated Risk Management (IRM) as a holistic approach to managing risk, safety, and compliance. 

Read More

The MPL Insurance Talent Crisis: A Race Against Time

Managing Medical Professional Liability (MPL) policies has never been more complex — or more critical. With increasing regulatory demands, growing operational costs, and the ongoing talent drain, your team is expected to do more with less.  

Read More

MGA Market Dominance: How to Get & Stay Ahead in 2025

Discover key insights and actionable strategies to outpace competitors and achieve lasting success in the ever-changing MGA market. The insurance industry is transforming rapidly, and MGAs are at the forefront of this change. Adapting to evolving technologies, shifting customer needs, and complex regulatory demands is essential for staying competitive.

Read More

Insurers Paying Attention to Obesity Drugs

Munich Re examines how new anti-obesity medications can reduce obesity-related mortality and morbidity risks. 

Obesity Drugs

Munich Re’s global medical team recently collaborated on a wide-ranging thought leadership project intended to help life insurers better understand and navigate the most prevalent emerging medical trends and risks across five critical topics: AI in Healthcare, Improving Cancer Outcomes, Prevention, Obesity, and Climate Change. 

The Obesity chapter examines how new anti-obesity medications can reduce obesity-related mortality and morbidity risks. As many adverse medical conditions are associated with obesity, if these medications can stop or reverse the upward obesity prevalence trends, the potential impacts on mortality and morbidity could be significant, with an impact on life, disability, and critical illness portfolios.

Key takeaways
  • Forecasted obesity trends: Obesity prevalence continues to rise, with forecasts predicting that more than half of the global population will be obese by 2035. This trend poses significant risks to health outcomes and insurance portfolios.
  • Impact of new medications: If these medications can stop or reverse the upward obesity prevalence trends, the potential impacts on mortality and morbidity could be huge.
  • Weight loss outcomes: The current literature on newer drugs for adults with obesity supports weight loss outcomes never seen with prior weight loss medications.
  • Impact on insurance portfolios: This chapter provides a plausible estimation of the revolutionary impact weight loss medications may have on life, disability, and critical illness portfolios.

Visit our Life Science Report page for more information and to access additional chapters. 


Sponsored by ITL Partner: Munich Re


ITL Partner: Munich Re

Profile picture for user MunichRepartner

ITL Partner: Munich Re

Munich Re Life US, a subsidiary of Munich Re Group, is a leading US reinsurer with a significant market presence and extensive technical depth in all areas of life and disability reinsurance. Beyond vast reinsurance capacity and unrivaled risk expertise, the company is recognized as an innovator in digital transformation and aims to guide carriers through the changing industry landscape with dynamic solutions insightfully designed to grow and support their business. Munich Re Life US also offers tailored financial reinsurance solutions to help life and disability insurance carriers manage organic growth and capital efficiency as well as M&A support to help achieve transaction success. Established in 1959, Munich Re Life US boasts A+ and AA ratings from A.M. Best Company and Standards & Poors respectively, and serves US clients from its locations in New York and Atlanta.


Additional Resources

Drug deaths a concern for life carriers

A 25% increase in substance abuse death rates in the college-educated population is a particularly worrying trend for the life insurance industry.

Read More

EHRs transform life underwriting

Our extensive study confirms the value of electronic health records (EHRs) across life underwriting use cases.

Read More

Life insurance fraud trends

Munich Re’s survey reveals which types of fraud have been on the rise for U.S. life insurers in recent years.

Read More

Recent patterns in cancer claims

Cancer is the most common cause of death for the life insurance population. Munich Re analyzes recent trends.

Read More

The digital future of life insurance

Leverage emerging technologies to improve operational efficiency, enhance underwriting processes, and expand insurance accessibility.

Read More

Finally, a Break in the Hurricane Forecast?

Early forecasts are for a less active hurricane season than 2024's devastating one — though severe convective storms show no signs of letting up.

Image
hurricane storm on the earth

Two key factors suggest that the 2025 hurricane season won't be as active as the one that caused such heavy damage in the U.S. last year. The water in the tropical Atlantic isn't as warm, meaning less energy to fuel massive hurricanes like Helene and Milton. And this season isn't expected to see a La Niña weather pattern — a cooling in the Pacific Ocean that makes it easier for tropical storms to form in the Atlantic. 

At the same time, a study finds that severe convective storms are becoming a bigger problem, and the Trump administration has announced cuts that could imperil key federal capabilities for weather forecasting.

But let's start with the good news, even if the hurricane forecast is preliminary. 

As this Washington Post article explores in detail, the early indications are that the conditions during the Atlantic hurricane season could be much more benign than in 2024, when there were 18 named storms and five hurricanes that made landfall in the U.S. Conditions might even be close to opposite of what they were a year ago. 

Last year, an El Niño weather pattern held into the early part of the hurricane season, leading to record temperatures in the Atlantic waters where tropical storms form. An El Niño pattern interferes with the winds that coalesce into tropical storms... but a La Niña pattern took over as the summer progressed and removed the obstacles. Hurricane Helene blasted through Florida, Georgia and western North Carolina in late September, and Hurricane Milton slashed across Florida two weeks later.

This year, a La Niña is currently in place, reducing water temperatures and thus the energy that is available to fuel hurricanes. Yet that La Niña is expected to fade as the summer progresses. It's not clear that an El Niño and its hurricane-preventing effects will replace that La Niña, but at least the weather pattern that is conducive to major storms should be absent.

As I say, the hurricane forecast is preliminary. Much more definitive information will be available in about a month, and even better forecasts in May. But I'm really hoping for a break, for everyone's sake.

If only severe convective storms would cooperate....

A recent study finds that the storms continue to pose increased dangers. The season for such storms is starting earlier and ending later, and they are becoming more powerful. A derecho — a long-lasting band of rapidly moving thunderstorms that causes straight-line wind damage that can stretch for hundreds of miles — hit downtown Houston in May and caused more destruction than Hurricane Beryl, which struck the area in July 

Citing a study by CoreLogic, the Triple-I Blog writes:

"The traditional severe convective storm (SCS) season is expanding, with storms appearing earlier in spring and continuing later into fall. Tornado impacts are also shifting much farther east than historical norms, impacting Midwest states such as Illinois, Indiana, Michigan and Ohio."

Triple-I says:  

"Hailstorms pose a threat to 41 million homes at moderate or greater risk, representing a reconstruction cost value (RCV) of $13.4 trillion, according to CoreLogic’s risk score models. For tornadoes, 66 million homes are at risk, valued at $21 trillion RCV. Straight-line winds affect 53 million homes with an RCV of $18.6 trillion....

"[Insurers need] refined risk models and improved infrastructure in emerging high-risk areas. Geographic risk exposure management will become increasingly important as SCS events evolve, according to CoreLogic."

Yet in Washington DC...

The Trump administration has fired some 880 staffers at the National Oceanic and Atmospheric Administration (NOAA). CBS reports that an administration official said critical employees, such as National Weather Service meteorologists, were largely spared. But CBS adds: "A source at the National Weather Service disputed this, however, telling CBS News some meteorologists were impacted, including radar specialists, as well as staff of the Hurricane Hunters crew, which fly airplanes into storms to help forecasters make accurate predications during a hurricane."

Given the chaos that has surrounded the budget cuts by Elon Musk's DOGE team — the claim of an $8 billion cut in spending that turned out to be $8 million, the claims of major savings on contracts that actually ended almost 20 years ago while George W. Bush was president, and so on — I, for one, have become skeptical of any claim DOGE makes. We'll have to wait to see what's really going on. 

(I confess to a bit of a personal stake in the fate of NOAA. The rock-climbing partner and close friend of my younger daughter is a contractor for NOAA, and her boss was among those fired. My daughter's friend, a very bright and impressive woman, says the boss is the best she's ever had, but the boss had the temerity to be promoted a few months ago and thus is officially "probationary" in her new position and easy to fire quickly. I've covered major businesses for a very long time, and I assure you that going after the easy fires is never the right way to go.)

The Trump administration is also reportedly planning to close two key facilities for weather forecasting. According to Axios, "One of the buildings is the nerve center for generating national weather forecasts.... The modeling center runs the computer models used in day-to-day weather forecasting and ensures that weather data correctly goes into these models and that they are operating correctly."

Axios says "another building on the list... is the Radar Operations Center [in Norman, Oklahoma], a centralized hub for technicians and researchers to work on improving and repairing the nation's aging fleet of Doppler weather radars."

The firings and moves to close facilities come amid considerable speculation that Trump wants to eliminate or at least neuter NOAA. The thinking is that he may have it in for NOAA because it talks about and tracks climate change. Trump may also want to privatize weather forecasting, along with many other other parts of the federal government. There's even speculation that he's still fuming because a NOAA official told Alabamans not to worry about a hurricane in Trump's first term, shortly after Trump had said publicly that they were in the line of fire — the NOAA notification that led Trump to use a Sharpie to alter a NOAA map and falsely claim that he'd been right.

Whatever his plans for NOAA, I'm in favor of top-notch forecasting and hope no permanent damage is being done. 

I'm also in favor of fewer hurricanes and severe convective storms, and if these early predictions bear out then we can perhaps all have a more relaxed summer. Here's hoping.

Cheers,

Paul

AI Revolutionizes Long-Term Care Planning

AI emerges as a game-changing solution for the complex challenges of long-term care planning.

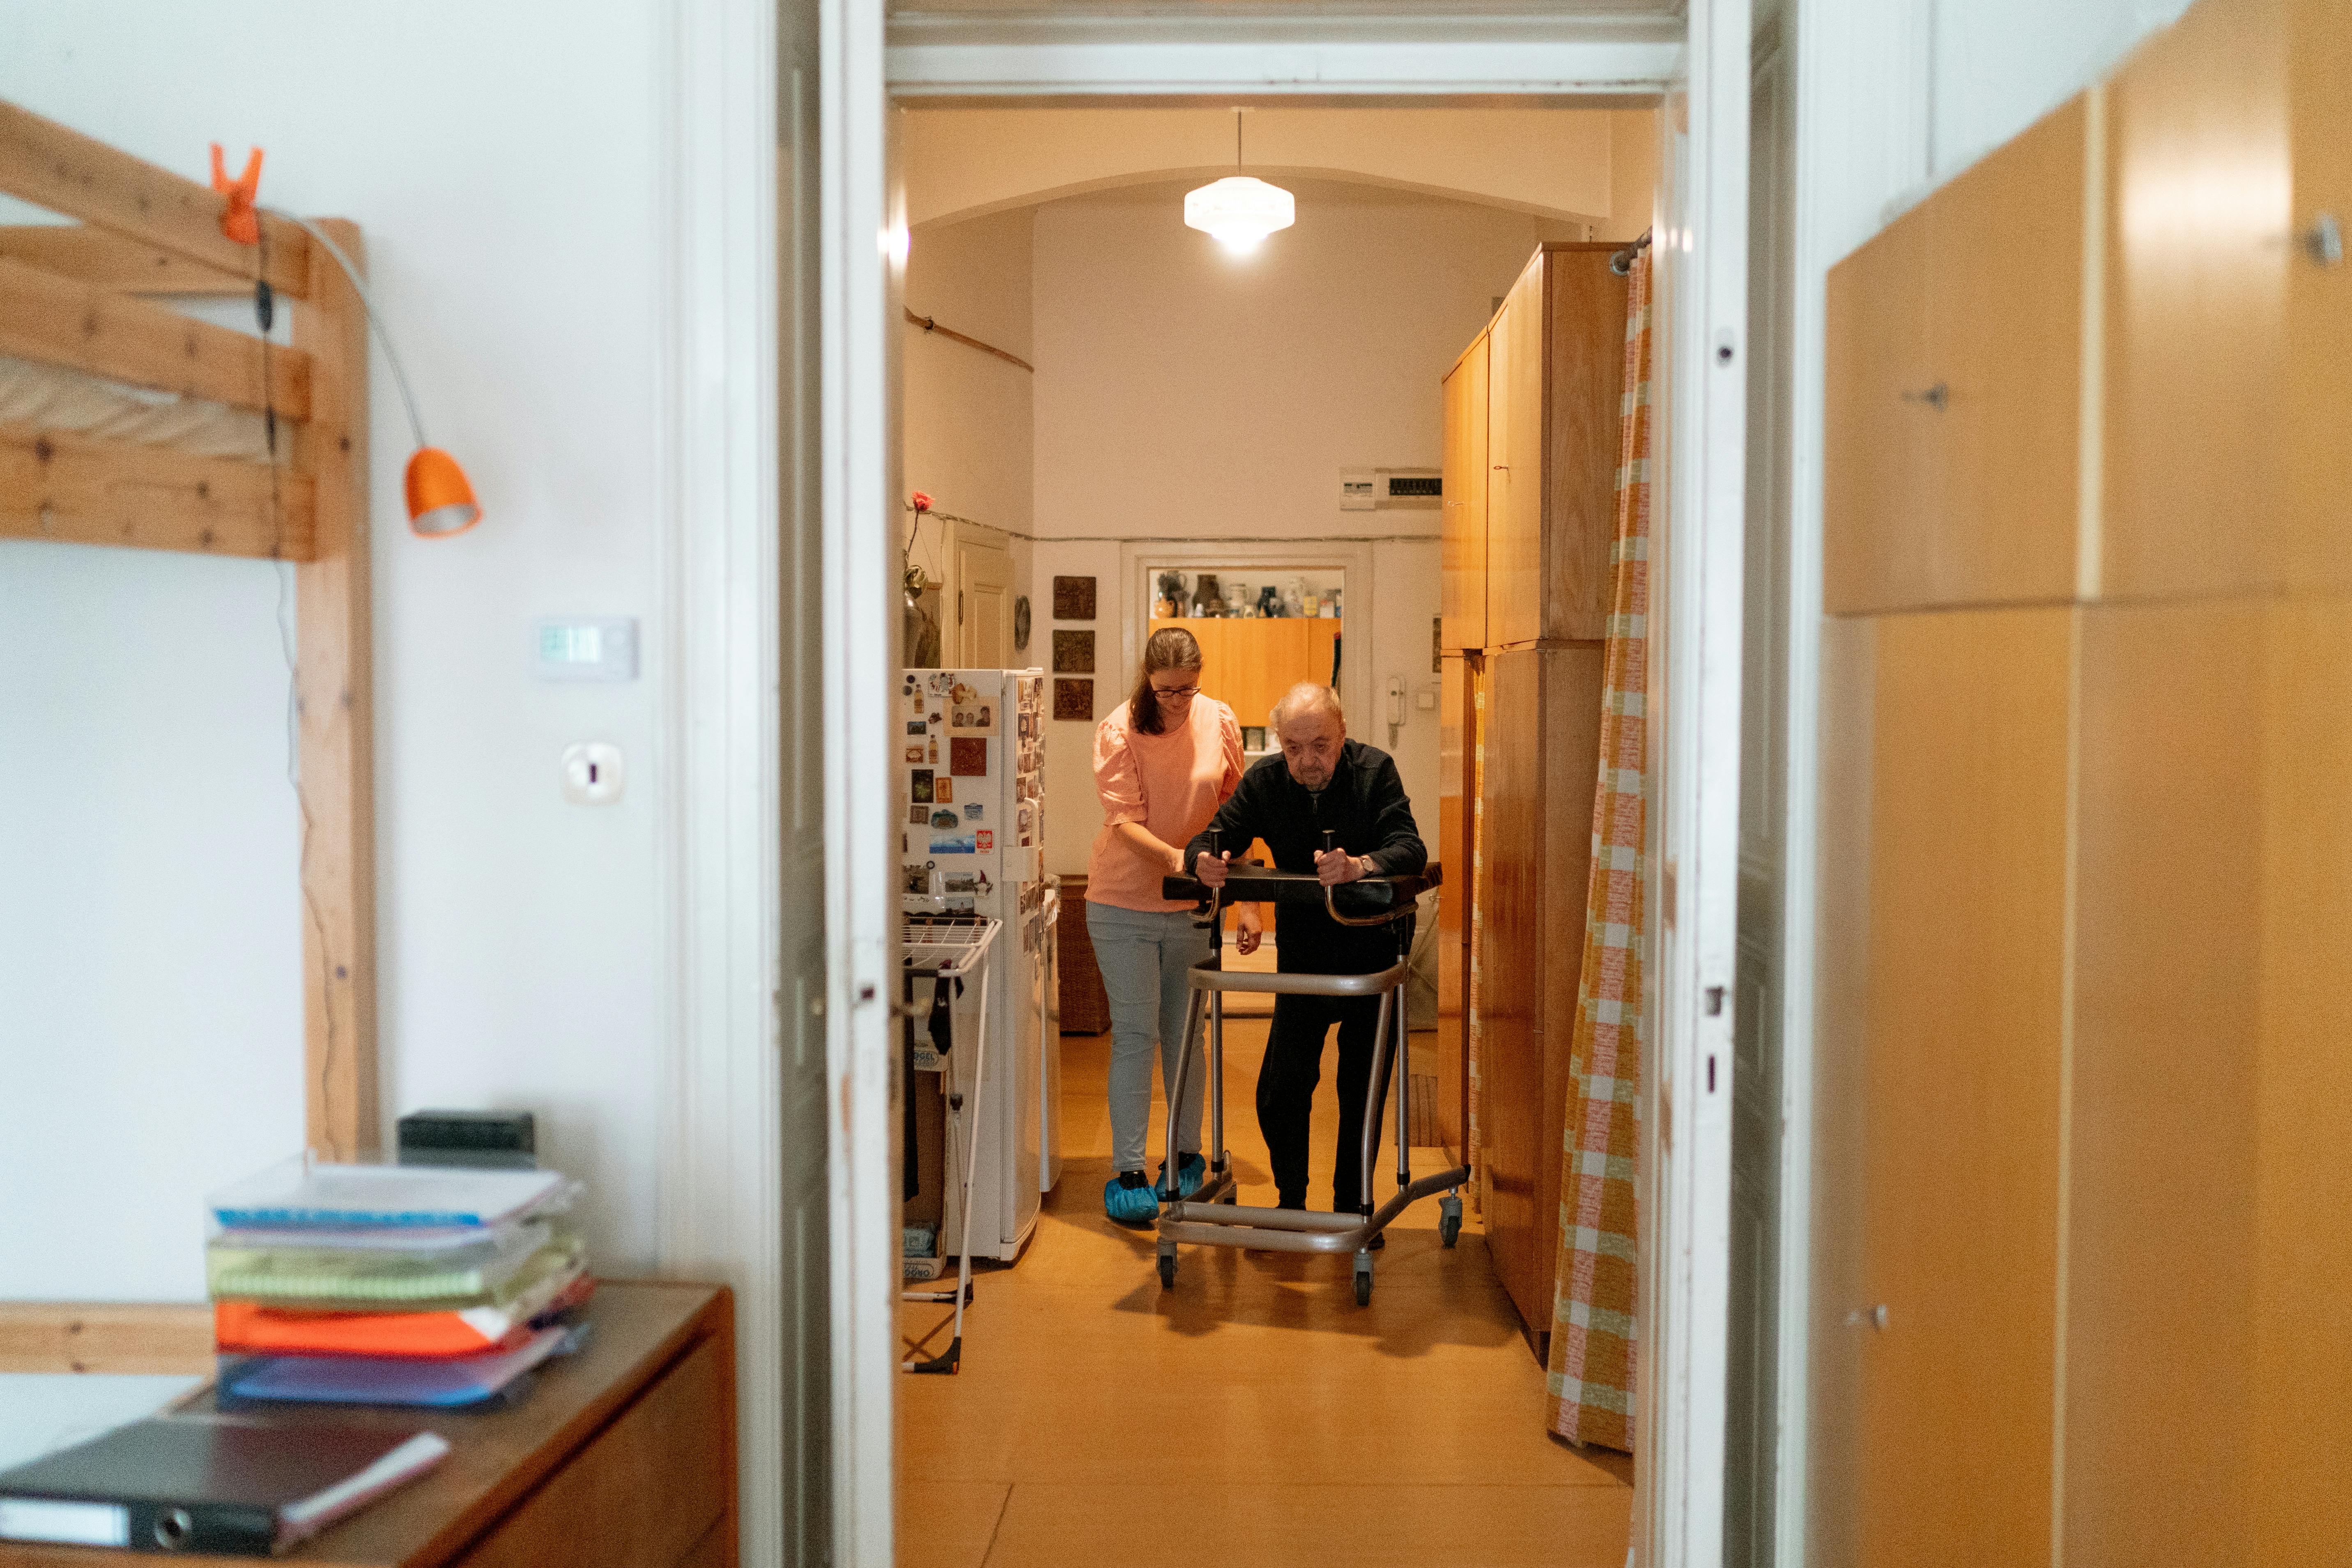
Elderly Care Routine in a Cozy Home Setting

Long-term care (LTC) planning stands as one of the final frontiers in retirement strategy, a true wildcard that continues to challenge retirement planning for both families and advisers. Traditional methods, whether national averages or basic Monte Carlo simulations, have never truly addressed the unpredictable costs and complexities of aging. As lifespans extend and healthcare needs evolve, these outdated tools fall short in preparing families for what's ahead. In this rapidly changing landscape, artificial intelligence (AI) potentially emerges as the solution we've been waiting for.

See also: The Crisis in Long-Term Care

The Persistent Challenges of LTC Planning

Historically, long-term care (LTC) has been the "elephant in the room" for retirement planners. Conventional models tend to paint with broad strokes, leaving critical questions unanswered:

  • Delayed Conversations: Many families wait until a crisis hits before discussing LTC, often scrambling to put a plan together at the last minute and getting rejected by the most favorable LTC protection insurance products.
  • Generic Data: Relying on average statistics and standard simulations rarely reflects the unique circumstances of any given family, causing clients to feel unmotivated in addressing LTC today.
  • Missed Opportunities: Without tailored insights, advisers can struggle to translate preliminary discussions into concrete strategies, causing clients to experience confusion today and frustration when it's too late to plan.

LTC planning is one of the few remaining unsolved challenges in retirement planning. Its inherent unpredictability creates significant risk, but it also presents a prime opportunity for advisers to differentiate themselves by offering bespoke, forward-thinking solutions.

AI: A New Lens on an Old Problem

Unlike outdated traditional approaches that rely on broad averages, AI-driven platforms analyze a vast array of data, ranging from regional cost variations and healthcare inflation to individual health profiles and family dynamics, to generate a truly personalized projection of a client's LTC journey. 

AI platforms for LTC planning can streamline the process with quick intake forms that produce tailored predictions about a client's future care needs. These platforms can deliver detailed projections on the timing and duration of care, anticipated costs, and even estimates of the caregiving hours that family members might need to provide. With such personalized insights, advisers can move well beyond vague "what if" scenarios and instead initiate rich, meaningful conversations that address the specific realities of each client's situation.

  • Initiate Rich Conversations: Rather than relying on generic averages, advisers can discuss specific care projections tailored to each client's circumstances. This not only clarifies the planning process but also helps clients grasp the real implications of their choices.
  • Accelerate Decision-Making: When clients see a clear, actionable plan outlining expected timelines and costs, they're more likely to act, whether that involves purchasing the right policy or adjusting their savings strategy.
  • Unlock Premium Growth: By overcoming the emotional barriers that often stall LTC discussions, personalized planning converts tentative ideas into high-value, concrete action plans, opening up new opportunities for advisers.

AI can transform a complex, often intimidating subject into a clear, relatable narrative that clients can understand and act on. Advisers can now replace vague "what if" discussions with detailed, personalized projections that spark more meaningful conversations.

Beyond Traditional Insurance: A Broader Perspective

Today's LTC planning goes far beyond traditional long-term care insurance. The market now offers a diverse range of products, from indexed universal life (IUL) policies and hybrid solutions to annuities and even short-term care options. By harnessing AI insights, advisers can create holistic strategies that not only forecast future costs with precision but also tailor the ideal mix of insurance products and self-funding plans to meet each client's unique retirement needs.

Despite the sophistication of AI, the human element remains irreplaceable. LTC planning is deeply personal, requiring emotional considerations and family dynamics. While AI provides the hard data needed to forecast costs and timelines, it's the advisor's empathy and insight that translate those numbers into a plan tailored to each family's unique situation. In essence, AI complements the adviser's expertise, offering clarity and precision while leaving room for the nuanced, human guidance that clients rely on.

See also: The Future of Long-Term Care Insurance

A New Era for Retirement Planning

As digital transformation continues to reshape the financial services landscape, integrating AI into LTC planning is quickly becoming standard practice. In a market where long-term care remains one of the last unsolved frontiers in retirement planning, AI tools are not only bridging the gap between uncertainty and clarity but also paving the way for a more secure, confident future.

For families facing the realities of longer lifespans and rising care costs, having a clear, tailored LTC plan is a necessity now more than ever. By combining the precision of AI with the irreplaceable human touch, advisers can ensure that their clients are prepared both financially and emotionally for whatever the future may hold. In doing so, they not only protect their clients' financial well-being but also reinforce their own role as trusted, forward-thinking leaders on one of the most critical aspects of retirement planning: long-term care.


Lily Vittayarukskul

Profile picture for user LilyVittayarukskul

Lily Vittayarukskul

Lily Vittayarukskul is the co-founder and CEO of Waterlily. 

She started college at 14 years old and by 16 was venturing into a career in aerospace engineering as an intern at NASA. She graduated from UC Berkeley with a bachelor's degree in genetics and data science and led product and engineering at multiple startups before founding Waterlily. 

Data Strategy Drives Growth, Operational Efficiency

A robust Master Data Management strategy is no longer optional. It provides an essential, unified, consistent view of key business data. 

white lines representing geometric shapes and stars across a gradient blue and purple background

In today’s fast-paced insurance landscape, where data is abundant but often fragmented, a robust Master Data Management (MDM) strategy is no longer optional—it’s a critical driver of business growth and operational efficiency. MDM capabilities help insurance carriers optimize their operations by creating a unified, consistent view of essential business data. 

Here's how MDM transformation can enable insurers to improve efficiency, compliance, risk management, and more.

1. Single Client View for Risk Pooling

Insurance carriers often deal with multiple clients, brokers, and partners across different regions, lines of business, and systems. By implementing an MDM solution, insurers can create a single, consolidated client view that enables them to:

  • Accurately pool risk profiles across diverse markets and geographies, ensuring that underwriting decisions account for the full risk exposure of a client.
  • Eliminate duplicate or fragmented client records, which reduces the risk of underwriting errors and enhances decision-making.

2. Cross-Sell and Up-Sell Opportunities

A unified view of customer data, facilitated by MDM, can also drive significant revenue growth through targeted cross-selling and up-selling. With accurate, consolidated customer profiles, insurance carriers can:

  • Identify potential cross-sell and up-sell opportunities by gaining a comprehensive understanding of customer needs and behaviors across different lines of business.
  • Personalize offerings based on client profiles and past interactions, improving customer engagement and satisfaction.
  • Enhance sales and marketing effectiveness by providing insights that help agents and brokers offer the right products to the right clients at the right time.

3. Enhanced Partner Relationship Management

Insurance carriers work closely with a wide network of brokers, agents, and reinsurance partners. MDM plays a key role in streamlining partner data management by:

  • Creating a centralized repository for partner profiles, facilitating consistent onboarding, contract management, and performance monitoring across the partner ecosystem.
  • Providing a 360-degree view of partner relationships, enabling insurers to optimize contract terms, pricing, and performance based on accurate, up-to-date data.

See also: A Different Slant on Operational Efficiency

4. Single View of Reinsurance Contracts

Reinsurance contracts are often complex, with terms and conditions spread across multiple systems. With MDM, insurers can:

  • Maintain a centralized repository of treaties that serves as a single source of truth for contract terms, obligations, and renewal dates.
  • Ensure automated synchronization of terms across underwriting and claims departments, minimizing errors and discrepancies in claims settlements.

5. Improved Catastrophic Event Response

During catastrophic events (e.g., natural disasters, pandemics), insurance carriers need to quickly and accurately assess claims. MDM enables:

  • Rapid identification of impacted clients and regions by providing consolidated, accurate policyholder and coverage data.
  • Quicker mobilization of resources by automating claims prioritization based on a unified view of risk exposure and client profiles.

6. Regulatory Reporting Accuracy

Insurance companies are subject to rigorous regulatory requirements across multiple jurisdictions (e.g., Solvency II, IFRS). MDM ensures that insurers can meet these standards by:

  • Unifying risk, policy, claims, and financial data across departments, ensuring consistency in the data used for regulatory reporting.
  • Automating the generation of accurate, real-time reports, reducing the risk of non-compliance and costly penalties.

MDM also enables better management of personally identifiable information (PII), ensuring compliance with global data privacy regulations like GDPR, by applying consistent security and privacy controls across borders.

7. Data Standardization for Global Operations

Insurance companies with global operations face the challenge of managing data from diverse regions, each with its own standards and formats. MDM helps:

  • Standardize data from various countries and lines of business, aligning it with a global data model.
  • Simplify the integration of data from new acquisitions or partners, allowing seamless data consolidation across regions without affecting business decisions.

This standardization enhances global operational efficiency and ensures that data discrepancies do not hinder the decision-making process.

See also: Insurance Faces Growing Natural Disaster Challenges

8. Fraud Detection and Prevention

Fragmented and inconsistent data create vulnerabilities for fraud in the insurance industry. MDM helps mitigate this risk by:

  • Creating a unified view of customers and claims, making it easier to identify and prevent duplicate or fraudulent claims.
  • Cross-referencing claims data across multiple jurisdictions, enabling insurers to detect patterns indicative of fraud, such as repeated claims under different aliases or policy numbers.

Conclusion

MDM transformation is more than just a technology upgrade; it’s a strategic initiative that can drive substantial business growth and operational efficiencies for insurance companies. By creating a single source of truth across data silos, MDM empowers insurers to enhance risk management, regulatory compliance, fraud prevention, and customer service. As insurance companies continue to embrace data-driven decision-making, MDM will play an increasingly pivotal role in ensuring long-term success in an increasingly competitive marketplace.


Ravindra Salavi

Profile picture for user RavindraSalavi

Ravindra Salavi

Ravi Salavi is a financial services technology leader with over 20 years of advisory and consulting experience working with major insurance and financial enterprises.

His key expertise is in digital transformation and the role of data analytics and AI for risk insights, profitable underwriting decisions, cost and fraud optimization for claims, etc. He has led strategic initiatives for leading insurers in North America.

March ITL FOCUS: Predict & Prevent

ITL FOCUS is a monthly initiative featuring topics related to innovation in risk management and insurance.

itl focus predict and prevent
 

FROM THE EDITOR

Maybe a dozen years ago, I spoke on a panel with a founder of Opower, who told me something about motivating customers that could help insurers encourage policyholders to make their properties more resilient in the face of growing threats from wildfires, hurricanes and more.

He had begun his career as a political consultant – he told me ruefully that he turned out to be very good at getting a candidate to finish second… meaning it was time to find a new career. He did learn one key thing, The best way to increase voter turnout was to put a note in a mailbox telling the residents how often they had voted in the past and – this is the genius part – how they stacked up versus their neighbors. People are competitive. They may not feel motivated to vote, but if that couple next door can find the time….

That insight led him and a college friend to start Opower, which took on utilities as clients and told customers how their electricity and gas usage stacked up against comparable homes in their area. Customers responded. Energy efficiency improved. Utilities rolled out Opower’s reports nationwide, and Oracle bought the company in 2016 for more than half a billion dollars.

(I certainly take the reports seriously, and you may, too. I take pride in being at least in the 90th percentile on both gas and electricity. In the unlikely event that I’m not, I double down on efficiency the following month.)

The potential application to insurance of the Opower approach is tantalizing. Insurers know a lot about which homes in an area haven’t fortified their roofs, removed inflammable landscaping from near their homes, etc. They may even communicate that knowledge to consumers via premiums, but that communication is opaque. It takes a lot for a policyholder to see a premium and tie it to the presence of bark right next to a house – a practice that Dave Tobias, general manager, insurance, at Nearmap, says in this month’s interview is akin to setting matchsticks next to the home. But what if Nearmap and others could put their aerial imaging in front of policyholders and let them see how they stack up against their neighbors? Might that not drive some action?

The technology to do that is already here. Nothing has to be invented. The issue is just a matter of insurers rethinking what they do with the troves of information they gather, as the world shifts away from “repair and replace” and toward Predict & Prevent. Do insurers just gather information and use it within their four walls to quantify and price risk, or do they share with customers in ways that reduce risks?

I know how I vote. And Dave underscores the need to communicate better with policyholders to reduce risks, while also describing how quickly insurers were able to respond to the SoCal wildfires because of the kind of aerial imagery Nearmap provided. I hope you find the interview as interesting as I did.

I also encourage you to read the latest on Predict & Prevent from Pete Miller, the CEO of the Institutes. The piece does a lovely job of describing recent progress and the stakes involved for all of us.

Cheers,

Paul   


An Interview with Tobias

'Every Carrier Is a CAT Carrier Now'

Insurance Thought Leadership:

How do your hurricane monitoring and tracking methods differ from your wildfire surveillance?

Dave Tobias:

With hurricanes, we typically know they're coming and can plan accordingly. Even before the hurricane hits, we can identify which properties will be most susceptible to damage.

The Predict & Prevent aspect is crucial. With hurricanes, you can see fascinating examples where two neighboring properties experience the same storm conditions -- identical wind speeds and everything -- yet one roof survives without a scratch while the other gets completely ripped off. This demonstrates how taking preventative action, like installing fortified roofs, can prevent hurricane disaster damage.

read the full interview >
 

MORE ON PREDICT & PREVENT

Insurers Must Evolve to Survive Climate Crisis

As climate risks intensify, insurers must evolve from damage compensation to prevention or face industry-wide collapse.
Read More

Insurers Must Lead Disaster Risk Awareness

Insurance companies must evolve from safety nets to proactive leaders as climate disasters reshape risk management. Here are four ways they can.
Read More


road in forest

Geospatial Technology Helps Combat Wildfire Threat

Earth observation technology emerges as a crucial tool in predicting and fighting wildfires.
Read More
AI power grid

The Path Forward for Workers' Comp

As the industry keeps making progress on reducing injuries, Bill Zachry describes how AI and other technologies can take workers' comp to a whole new level. 
Read More


The Crisis in Homeowners Insurance

In theory, increasing insurance premiums signals rising risk and spurs action that mitigates disasters like California's fires. In practice, climate is changing too fast, and government is being too slow.
Read More

The Next-Gen Risk Readiness Index: P&C Insurance

Sponsored by Nearmap
Nearmap, in partnership with MSL and Reputation Leaders, surveyed senior decision-makers at U.S. P&C insurance companies to uncover their strategies for addressing emerging risks. This report reveals data-driven insights into how insurers are leveraging aerial imagery and AI to optimize the policy lifecycle, mitigate risks, and drive growth.
Read More


FEATURED THOUGHT LEADERS

Laura Barrowcliff

Pierre du Rostu
CEO

AXA Digital Commercial Platform

 
Charles Grodecki

Divya Sangameshwar
Insurance Expert & Spokesperson 

ValuePenguin

Laura Barrowcliff

Antoine Rostand
President and Co-Founder

Kayrros

William Zachry

William Zachry
Executive Director

Safeway

 
white block
 
Paul Carroll

Paul Carroll
Editor-in-Chief

Insurance Thought Leadership


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

Mobile AI Transforms Auto Insurance Underwriting

Mobile-first solutions and visual AI are making processes faster and more accurate for insurers.

 Man in Black Suit Using His Phone While Leaning Beside Black Car

Mobile-first applications and strategies have become the go-to approach for delivering services, and they are making an impact in vehicle underwriting, transforming traditional workflows.

A mobile-first approach enables policyholders and insurers to speed the underwriting process significantly. Policyholders can submit important information directly through their mobile devices, eliminating the need for time-consuming physical inspections or lengthy back-and-forth communication.

But what's truly driving the mobile-first approach even further into the mainstream is the rise of artificial intelligence—particularly computer vision AI, or "visual intelligence." This technology is making it possible for insurers to assess, process, and price vehicle-related risks faster and from anywhere.

According to the Capgemini Research Institute's World Property and Casualty Insurance Report 2024, 42% of policyholders find current underwriting processes too complex and lengthy, highlighting the need for AI-driven improvements.

The combination of mobile and AI-powered technologies has the power to transform underwriting forever by prioritizing speed, accuracy, and customer satisfaction.

Breaking through inconsistencies and delays

Powering a mobile-first underwriting approach with visual intelligence AI can mean serious advantages for insurers as it provides a way to analyze images or videos submitted by users remotely, with high accuracy. Visual intelligence AI can identify a vehicle's make, model, and condition, even spotting minor damage that a human inspector might miss. For insurers, this means faster decision-making and more accurate data, which means fairer and more reliable risk assessments.

Visual intelligence can also help reduce human error and subjectivity, which have long been challenges in vehicle underwriting. This is promising news for the 70% of insurance firms that reported inconsistent underwriting decisions as a prevailing issue in 2024.

See also: AI Revolutionizes Auto Insurance Via Real-Time Data

More data, more insights

As AI and mobile-first technologies continue to advance together, it will only lead to smarter vehicle underwriting. According to Bain, insurers collect only about 60% of the data they need to underwrite a policy, highlighting the potential for more mobile data collection to improve this process.

After users submit vehicle details remotely via mobile devices, insurers can use visual intelligence AI to add a layer of more in-depth insights. This can help reduce manual underwriting processing times quite significantly, and lower overall operational costs.

More efficiency across the underwriting process benefits not only the underwriters but also end consumers, who experience quicker quotes and more transparency throughout the application process. The powerful combination of mobile and AI also means insurers can handle any surges in demand while maintaining accuracy and quality.

See also: AI and a Vision for Safer Roads

Bridging the technology gaps in underwriting

Shifting tedious underwriting processes to mobile-first can improve the customer experience overall. In fact, mobile-first practices aren't really an option any more but the standard for insurers striving to remain competitive.

The future of insurance lies not in replacing humans, but in elevating efficiency, precision, and a customer-first approach – a movement that will only continue as mobile and AI technologies advance.

Shifting From Transactional to Relationship-Driven Insurance

Specialty insurers must evolve beyond transactions to deliver personalized, digital-first coverage that meets modern consumer demands.

Person in Orange and Black Long Sleeve Shirt Holding Holding Hands with Woman in Blue and White Polka Dot Dress

The insurance industry has long been defined by transactional relationships: customers purchase policies, pay their premiums, and file claims when necessary. While this model has sustained the industry for decades, it lacks the engagement and personalization that modern consumers expect.

Today, the rise of digital-first insurance providers and the increasing demand for tailored coverage require a transformation. Specialty insurers, in particular, have an opportunity to move beyond mere transactions and build customer-centric products that provide real value, trust, and engagement throughout the entire policy lifecycle.

Here's how specialty insurers like us at Roamly can shift from a transactional mindset and create products that foster long-term loyalty and enhance customer experiences.

1. Understanding the Customer Beyond the Policy

The first step is to develop a deep understanding of who the customer is and what they truly need. Traditional insurers have historically relied on broad demographic and actuarial data to design policies, but today's consumers expect more than just a one-size-fits-all approach.

By leveraging data analytics, AI-driven insights, and customer feedback, specialty insurers can craft products that align with specific lifestyles. For example, at Roamly, we cater to digital nomads, RV, motorcycle, and boat owners, and travelers who need flexible, on-the-go coverage. Rather than simply offering a generic travel insurance policy, we integrate features that support their unique experiences—such as coverage for remote work setups or short-term rental insurance for RV owners.

2. Seamless Digital Experiences That Build Trust

Consumers today expect fast, intuitive, and digital-first insurance experiences. A customer-centric specialty insurance product should be easy to understand, purchase, and manage. This means moving away from cumbersome paperwork and opaque policy language and instead offering:

  • User-friendly online platforms for policy selection and management
  • Instant quotes and on-demand policy adjustments
  • AI-driven chatbots and virtual assistants for real-time support
  • Simplified claims processing with automated approvals

When customers feel that their insurer is accessible, transparent, and responsive, it generates trust and strengthens the relationship beyond just the moment of purchase.

3. Personalized Coverage Tailored to Evolving Needs

Static, inflexible insurance policies often leave customers feeling underserved. Specialty insurers must design coverage that evolves alongside their customers' lifestyles and risk profiles.

For example, instead of offering a standard adventure travel insurance policy, insurers can provide dynamic coverage options that adjust based on:

  • Destination-based risks (e.g., political instability, natural disasters, or health concerns)
  • Activity-based needs (e.g., extreme sports coverage or equipment protection)
  • Trip duration and frequency (e.g., one-time vs. multi-trip plans)

This level of personalization ensures that customers feel seen and understood, which improves their overall experience.

4. Embedding Insurance in the Customer's Journey

Transformational insurance is about meeting customers where they are, rather than forcing them to seek out policies separately from their activities. Embedded insurance—integrating coverage directly into the purchasing experience of a product or service—has revolutionized the specialty insurance space.

For instance, Roamly partners with travel platforms to offer insurance at the moment of booking, ensuring customers have seamless access to coverage without extra steps. Whether it's integrating short-term rental insurance into an RV marketplace or providing travel medical insurance within a booking platform, embedding policies into existing workflows makes insurance feel like a natural, value-added component rather than an afterthought.

5. Risk Mitigation and Engagement

Beyond just offering financial protection, specialty insurers can help customers minimize risk. By using predictive analytics and AI, insurers can send real-time alerts about travel disruptions, weather hazards, or security threats based on a customer's itinerary.

Additionally, value-added services such as 24/7 concierge support, telemedicine access, or digital safety tools enhance the overall insurance experience. These measures transform the insurer from a reactive claims processor into a trusted partner that looks out for its customers.

Specialty insurers that focus on building long-term relationships, personalizing experiences, and embedding value into their products will not only retain customers but also differentiate themselves in an increasingly competitive market. As the industry continues to evolve, insurers that prioritize customer-centricity will be the ones that thrive.

The question for specialty insurers today isn't whether to evolve, but how quickly they can adapt to meet the changing expectations of modern consumers.

AI Transforms Assessment of Storm Risk

Insurers' current approach to assessing the risk from severe convective storms is fundamentally flawed. AI allows for key, property-specific insights.

Purple Thunder Storm during Nighttime

The current approach to managing severe convective storm risk is fundamentally flawed. Most models in use today rely on stochastic methodologies designed to evaluate probable maximum loss scenarios but lack the precision to accurately assess average annual losses at the individual property level. This approach does not fully account for how hail damage accumulates over time on roofs. Just as a single cavity cannot be attributed solely to one candy bar, hail damage often results from cumulative effects rather than a single large hailstorm.

This leaves many carriers in a reactive posture, responding to events rather than anticipating them. For example, when a large hailstorm devastates a region, the typical response is to reassess rates across broad geographies—regions, territories, or ZIP codes. This reactive approach not only fails to address the underlying risk effectively but also triggers a cascade of negative consequences.

When the next storm inevitably hits, it targets a different set of properties, repeating the cycle. Losses continue to mount, good risks continue to leave, and carriers are left grappling with rising claims and deteriorating risk portfolios.

See also: Property Insurance Must Evolve for Climate Resilience

The Blunt Instruments of the Past

Some carriers have explored alternative measures, such as mandatory actual cash value (ACV) endorsements for roofs older than a certain age (e.g., 10 years) or exclusions for roof coverage on older properties. While these strategies may help curb immediate losses, they often lack the precision needed to differentiate between well-maintained and poorly maintained properties.

By treating all older roofs the same, regardless of their actual condition or risk profile, these blunt-instrument approaches drive away good risks—policyholders who maintain their properties but find themselves penalized nonetheless. Once again, carriers are left with the worst risks: poorly maintained roofs with limited coverage options elsewhere.

A Better Way Forward: Property-Specific Risk Management

Fortunately, there is a more effective approach: Property-specific risk management. Advanced AI-powered models enable carriers to assess the unique risk profile of each structure, moving beyond proxies like roof age, material, and ZIP code. This approach considers critical factors such as:

  • Roof shape and geometry
  • The number of roof penetrations (e.g., skylights, vents)
  • Roof steepness
  • Roof condition
  • Roof material and its aging characteristics

AI-powered models uncover critical insights that traditional methods often overlook. For example, claims frequency for asphalt shingle roofs rises exponentially with age, while for metal roofs, the increase is more gradual before leveling off. Similarly, properties exposed to multiple hailstorms see claims frequency double with each event, up to a point where the effect saturates. These nuanced, non-linear relationships are invisible to traditional methods but can be precisely modeled using AI.

Precision Risk Assessment

AI-powered risk assessment transforms how insurers evaluate hail damage risk by analyzing the interaction between the built environment and regional climatology. This approach moves beyond outdated methods that rely on broad groupings, such as ZIP codes and roof age, to assess risk. Instead, each property is evaluated based on its unique characteristics, enabling more accurate underwriting and pricing decisions.

Traditional models often fail to distinguish between good and bad risks within the same territory. AI-driven models, however, leverage vast amounts of property-level data to unlock a level of granularity that conventional methods simply can't achieve. By moving past broad categorizations, insurers can tailor their decisions to the specific attributes of each property, leading to a more precise, fair, and profitable approach to risk assessment.

The results speak for themselves: Insurers using AI-driven models are outperforming their peers, achieving over 60X lift in risk segmentation. This precision not only improves profitability and reduces loss ratios but also ensures fairer premiums for policyholders—delivering value across the entire insurance ecosystem.

See also: What Trump 2.0 Means for Climate Initiatives

Breaking Free From the Cycle

The traditional methods of managing severe convective storm risk are no longer sufficient in an era of increasing storm frequency and severity. Reactive rate adjustments and blunt exclusions are short-term fixes that exacerbate long-term problems. By adopting property-specific risk models powered by AI, carriers can break free from the cycle of rising losses and adverse selection.

This approach doesn't just mitigate losses; it redefines the relationship between carriers and their policyholders. Policyholders with well-maintained properties are rewarded with fair and transparent rates, fostering loyalty and trust. Carriers can provide tailored recommendations, educating policyholders about property maintenance. This makes for a healthier risk pool while improving the overall customer experience.

The path forward is clear: By embracing property-specific, data-driven models, the insurance industry can break the cycle of severe convective storm losses, ensuring a more sustainable future for both carriers and their policyholders.


Kumar Dhuvur

Profile picture for user KumarDhuvur

Kumar Dhuvur

Kumar Dhuvur is the founder and head of product at ZestyAI, an AI-powered property and climate risk analytics platform. 

He has led credit risk analytics teams at Capital One Bank and advised financial services institutions on risk management strategies while at McKinsey. 

He holds an MBA from the Wharton School, University of Pennsylvania, and a B.S. in electrical engineering from IIT Madras.