To meet customers and prospects in the new virtual world over the past year, independent agencies scrambled to find ways to connect that felt personal and retained the “human touch.” Networks of agencies that care about their members understand how important it is to provide expert guidance and resources throughout this digital journey.
Independent agencies come in all sizes and with different levels of resources, but they all require cost-effective strategies to ensure current clients are happy and attract new prospects. They join networks looking for collective strength and bargaining power and to get support with professional development and technology. Networks can level the playing field for independent agents by equipping them with the kind of advanced marketing tools those at the largest corporations have at their fingertips.
Independent insurance agents are continually researching a multitude of options in service to their clients while managing every aspect of their business. Adding marketing on top of this load can be overwhelming. Access to resources, such as a marketing library with timely content that can be customized, simplifies communication with clients.
A recent independent survey asked insurance professionals their perception of marketing. According to those surveyed, enhanced marketing strategies improved client retention, acquisition and revenue growth. Virtually all the respondents agreed that marketing is a competitive advantage (98%), and 96% reported that more effective marketing would grow their business. The survey also revealed that agents would switch networks to gain better technology platforms.
Networks that support their members’ client-retention initiatives can expect higher member retention and profitability for their own organizations. Because it can cost seven to nine times more for an agency to bring in a new customer than to retain a client, active engagement with the current client base is one of the strongest foundations for sales growth.
Agents look to networks to fill the gaps in their marketing. The past year’s rush to a digital platform, while challenging, gave agents opportunities to strengthen their relationships with clients and prospects. The personal attention that smaller agencies provide is a powerful competitive advantage, in contrast with how clients can feel when dealing with a large, impersonal corporation.
A 2020 IBM survey that found only 56% of consumers are satisfied with their insurance provider’s personal attention. The same survey found that, in response, 84% of insurance organizations adding artificial intelligence (AI) tools are doing so to improve customer satisfaction.
People need insurance policies for every stage of life, and they're an emotional as well as financial investment. Agents who understand this make sure their clients know they are always advocating for them. One way to do this is to take the time to build authentic relationships based on personal details -- providing useful information and offering help when clients need it, identifying pain points, alerting them to renewal deadlines and celebrating milestones like birthdays, graduations, anniversaries and more. But time is a valuable resource. This is where networks can step up and be a true partner in relationship-building by offering technological tools that simplify content development.
A library with insurance-specific, relevant email and social media content, personalized greeting cards, as well as copy for virtual and in-person events makes engagement easy and efficient. AI technologies within a marketing suite can quickly sort and identify content that will resonate with clients by being precisely tailored to their interests, saving agents’ time. With these sophisticated tools added to their marketing arsenal, agents can increase cross- and up-sell opportunities.
Automation in marketing helps agents manage a larger customer base while making the customer interactions more meaningful and relevant. Insurance agents are evolving to be consumer educators and partners in the lifelong journey of buying insurance for protection at every stage. Agents use multiple touchpoints to nurture, inspire and inform their clients, who respond to genuine interactions with trust and loyalty.
Networks can serve as partners and facilitators for these agent-customer journeys, by serving as a resource that supports agents as they manage these relationships. As the industry continues to recover from the past year’s challenges, networks that are responsive to agency members’ technological and professional growth will remain strong for the inevitable changes to come.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
Holly Herron, CEO of Assure Alliance, manages all partner-carrier relationships, recruiting and operations and works with members to optimize their revenue potential within the alliance.
I've waited for years now to see how insurance might fit with Jeff Bezos' quote that "your margin is my opportunity." Amazon's announcement last week that it will help sellers find product liability insurance through a network facilitated by Marsh may provide the answer.
Assuming the product liability offering is popular -- and Amazon is relentless when pursuing new opportunities -- it's easy to imagine the company expanding into other types of insurance for small businesses. For a lot of small businesses.
Amazon currently has 1.9 million active sellers on its site, so offering product liability insurance could quickly give Amazon a massive base of small businesses that could be interested in buying other types of insurance through the company. Not all of those sellers will buy via Amazon, of course. Many don't meet the minimum level of sales ($10,000 a month) at which Amazon requires that they carry product liability insurance. Others will buy their insurance through other channels or are already covered by general liability policies. But what Amazon is calling its Insurance Accelerator could easily become the starting point for hundreds of thousands of small businesses purchasing product liability insurance.
Those customers will find it easy to buy, because the insurance offering will be embedded in the services that Amazon already provides sellers digitally. Those buying the insurance through Amazon will also benefit from the sort of simple, intuitive interface that Amazon provides customers, as opposed to the more complex approach that most insurance companies and brokers employ.
So, why wouldn't those small businesses perk up if Amazon offered them workers' comp insurance for whatever warehousing and shipping operations they have? Perhaps some business interruption coverage, too? Once these small businesses start buying from Amazon, why not go all the way to a general liability policy, property insurance, key man insurance and everything else a small business might need?
Now, it's always possible that the Amazon Insurance Accelerator is just a fancy way of handing off leads to Marsh, in which case the arrangement could turn out to not be that significant. This would just be a way for Marsh to extend its already considerable reach and not the long-anticipated move by Amazon into insurance.
But using product liability as a launching point for a broad push into small business insurance fits the Amazon model of innovation going all the way to its beginnings. Bezos always hoped to build what he called an "everything store" but knew he needed to start small and thus began merely as a bookseller in the mid-1990s. Once he had a foothold in electronic commerce, he expanded as fast as he could in every direction.
Amazon's approach to insurance also lines up with the model it has scaled to enormous success. Amazon is providing an interface but otherwise serving as a platform, using Marsh to pull together outside resources (insurers Chubb, Harborway Insurance, Hiscox, Liberty Mutual Insurance, Markel and Travelers, as well as technology from Bold Penguin and Simply Business to help match insureds to the right coverages).
It's even possible to imagine Amazon moving well beyond small business if this initial push succeeds as broadly as it could. Amazon doesn't shy away from complexity, so it could keep climbing the ladder, developing expertise that would let it serve ever-larger companies. Amazon could also move into personal lines, especially because many owners of small businesses don't see a clear demarcation between their corporate and personal lives.
"Customers are going to have other insurance needs," says Karnina Szymanski, president of insurance at Bold Penguin, which was acquired earlier this year by American Family Insurance. "I'm not in the head of Amazon... but I think the possibilities are endless."
Cheers,
Paul
Get Involved
Our authors are what set Insurance Thought Leadership apart.
Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.
The problems associated with issuing certificates of insurance (COI) are so egregious, it could be argued most insurance professionals have either forgotten their existence or ignored them altogether. Nearly 30 years ago, a court characterized the certificate of insurance as “a worthless document.” Yet little has changed -- until now. With the aid of technology, promising solutions are being developed to solve the problems plaguing the outdated certificate of insurance.
There are an unlimited number of examples where the COI failed an interested party. Whether it is a lapse in coverage, incorrect limits or unknown exclusions, the COI would provide little comfort to anyone who knew the true limitations of these one-page documents. More significantly, it is often the business owner, franchisor or contractor, who have the most to lose, who are the least involved in obtaining and confirming coverage.
It may not entirely be the fault of the industry for the COI’s apparent challenges. The alternative to COIs would require the comprehensive review of hundred-page policies and constant confirmation with carriers of their in-force status. -- a costly replacement that business would prefer to avoid.
Why COIs Are a Cause for Concern
The sheer number of challenges associated with certificates of insurance should make any agent or insured take pause. Deemed nothing more than an informational piece of paper, COIs are consistently issued to businesses that are only looking to tick a box off a checklist. On the other side, organizations that are looking to protect their interests by requesting COIs from their vendors often take minimal steps to ensure they are receiving the protection they desire.
Consider that the COI does not:
List Exclusions — Certificates of insurance do not list the myriad of exclusions that could leave insureds without coverage. Particularly in the construction industry, insurers are keen to restrict coverage of the contractors they insure -- such as the roofing contractor whose liability policy excluded roofing work, or the painter doing work for a major home builder whose policy specifically excludes tract homes.
Confer Any Rights — A COI is “issued as a matter of information only and confers no rights.” The documents are nothing more than a summary of coverage provided by an insurance agent as evidence the insured obtained coverage. Language exists within most COIs explicitly advising that policies must be endorsed to provide additional insured status and again warns rights are not conferred in lieu of such endorsement.
Constitute a Contract — The COI is littered with disclaimers, including language insulating agents, brokers and insurers by specifically stating “this form does not constitute a contract.” Wording continues to remove any ambiguity by stating coverage is not affirmed by the certificate. The specificity of the language is intended to remove all responsibility from the agent and the insurance company represented.
Guarantee Notice of Cancellation — Even if a certificate of insurance has been properly produced, accurately reflecting the terms afforded within the insurance policy it represents, certificate holders are still exposed to the potential the underlying policy gets canceled. Cancellations can occur for a variety of reasons, including failure to pay premiums, unresolved audit disputes or unattended loss control recommendations.
The ubiquitous nature of the certificate of insurance has blinded certificate holders to the glaring and obvious deficiencies they carry. Perhaps there is some reliance by insureds on the insurance producer and their errors and omissions coverage. But, again, while individual circumstances may possibly implicate an agent for inaccuracies, there remain many more reasons a certificate could fail.
While certificates of insurance themselves are unquestionably flawed, we must also look at the industry’s standard practice of how COIs are issued. In doing so, we can begin to grasp how something designed to be quick and efficient has become an exposure even for those being insured.
Cutting costs in any industry commonly relies on reducing tasks to the lowest common denominator. Insurance is no exception. The issuance of certificates has become so procedure-based, their significance has been all but lost.
Take franchisors. They request that franchisees procure insurance and forward proof of coverage in the form of a certificate of insurance. As the first step, franchisors provide very clear instructions regarding the type of coverage required. But from this point forward vulnerabilities in the process are exposed.
Insurance Placement — The franchisee solicits quotations from local insurance agents to obtain the necessary coverage. While franchisees rely on producers to obtain the appropriate limits of coverage, the desire to place coverage at the most competitive premium could lead less experienced agents to place coverage that has unfavorable conditions or exclusions.
CRM Input— Insureds' data, including coverage information, lives inside the insurance agency’s client relationship management program. Commercial lines have not been as fortunate as their personal lines counterparts in that nearly all coverage information must be input manually. When human hands are involved, there lies the possibility of inaccuracies.
COI Issuance — Most of today’s CRM programs can automatically populate and print Acord forms, including the standard certificate of insurance. If the client service manager assumes the CRM information is correct, any errors entered previously will be transposed onto the certificate of insurance.
Receipt of the COI— This last step of the process is where our concern primarily lies. Often there is a clerk on staff with a franchisor (or other interested party) who receives the certificate of insurance and does nothing more than crosscheck the information against a checklist. Rarely are insureds requesting policy copies to identify any potential coverage gaps or exclusions.
The certificate of insurance is a snapshot in time. Even if every step of the process has been followed to produce an accurate COI, the document can only be relied on in that moment. Any reliance on the COI as proof of coverage after its initial insurance can be undermined by midterm endorsements or an unforeseen cancellation.
Who Will Transform the COI Process?
Without the hand of technology involved, the only sure-fire solution to ensure the policy provides coverage as intended remains a painstakingly manual process. It remains incumbent on insureds and other interested parties to review policies in their entirety to confirm coverage. Regrettably, today such reviews can only be tackled by the largest of companies with both the necessary personnel and deep enough pockets.
However, as insurtech begins to penetrate deeper into the commercial lines space, technological developments for the less exciting aspects of insurance, such as the COI, will follow. Because the challenges associated with certificates of insurance are so pervasive, solutions will likely be developed by several different drivers.
Carrier-Centric— Insurance carriers will continue to work on improving the customer experience either directly with the consumer or through agents and brokers. Carrier-centric solutions would offer an additional way to build brand loyalty and increase policy retention. Insureds who have experienced an uninsured claim after collecting a COI may be willing to part with the ability to shop their coverage in exchange for more certainty with their certificates.
Industry-Driven— Industries relying most heavily on COIs to conduct their business may not wait for their insurers to present a solution. Instead, individual industries may take it upon themselves to force carriers to develop solutions under the threat of moving their business elsewhere. Industries or individual businesses with enough weight to broach the issue may also have the capacity to develop insurance pools tailored to their own needs, eliminating the need for COIs for those who participate.
Third Party Insurtech— Technology solutions, independent of a single insurance company and with the ability to serve multiple industries, can offer the flexibility necessary to satisfy the various needs of agents, carriers and insureds. Acting as a bridge, third-party technology companies can bring many insurers together to serve those industries desperately seeking a way to confidently rely on the COI.
There is plenty of room in the marketplace for one or more drivers to profoundly change the COI process. How solutions are designed and implemented will likely set the stage for how certificates are issued in the future, regardless of the innovator.
Technology tends to improve existing processes or services only slightly. Irrespective of who will develop technologies to tackle the COI’s challenges, success will only come once all its related concerns have been addressed. In fact, perfunctory improvements could actually further overstate the already misleading sense of security certificates present.
This problem necessitates a truly comprehensive solution for the COI -- an answer where certificates can be relied upon in real time, any time.
Developing such a complete solution requires the entire COI process be examined through the eyes of all interested parties, from insurer to insured. In between the two, we must also investigate whether brokers are required or should even be involved in facilitating certificates.
Ultimately, we must look through the lens of our named and additional insureds who hold all the risk in this equation. Often naïve to the COI’s deficiencies, they deserve better from the insurance industry. Now is the time for technology initiatives to reimagine the certificate of insurance and the issuance process. The best solution will be so transformative it may be unrecognizable in comparison with today’s practices. The industry will question why COIs were ever handled any other way.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
Wade Millward is founder of RIkor. He has consulted business owners across the country on their insurance and risk management for 14 years, uncovering the suffering of franchisors and franchisees that led him to start Rikor.
Where there is growth, there is opportunity; where there is opportunity for one, there is hope for all. The opportunity to create opportunities for communities in need of growth, the opportunity to create jobs for residents of communities in need of work, the opportunity to create communities for a country in need of hope — these opportunities are true and righteous altogether. By offering these opportunities, insurance entrepreneurs do their part to be true to what our forefathers said on paper: coming together to insure domestic tranquility and form a more perfect union. By creating businesses in Opportunity Zones, insurance entrepreneurs can strengthen communities. Because of the tax incentives Opportunity Zones provide, insurance entrepreneurs must use this tool to help underserved communities nationwide.
A product of the Tax Cuts and Jobs Act of 2017, Opportunity Zones provide a tax incentive for investors to reinvest their unrealized capital gains into dedicated Opportunity Zone Funds. An investor may exclude 100% of long-term or short-term capital gains tax by investing in an Opportunity Fund within 180 days of the realization of that gain.
A long-term commitment on behalf of low-income communities, Opportunity Zones are census tracts in all 50 states as well as American Samoa, Guam, the Northern Mariana Islands, Puerto Rico and the Virgin Islands. The zones allow an investor to defer capital gains taxes for up to five years. After 10 years, all capital gains on the investment in the Opportunity Zones are waived.
To qualify, the Opportunity Fund must invest more than 90% of its assets in a qualified property or business located in an Opportunity Zone. The property must be significantly improved, which means it must be an original use, or the basis of the property must be double the basis of the non-land assets. The business must remain compliant as an Opportunity Zone-qualified company.
States may designate up to 25% of low-income census tracts as Opportunity Zones. To date, there are 8,764 Opportunity Zones in the U.S., many of which have experienced a lack of investment for decades. These tracts are candidates for renewal, not only because of the wrongs of the past but because of the urgency of the present; for the past is present among generations of residents of the same communities, where change is negative, investment nonexistent and existence itself a nightmare of poverty, strife and despair.
Insurance entrepreneurs must bring opportunity to these communities, offering tax-free retirement income strategies and principal-protected insurance contracts, among other more sophisticated risk management solutions.
Insurance entrepreneurs must bring economic freedom to communities in Opportunity Zones, because choice is essential to the survival and success of these communities.
The incentives for everyone, whether insurance entrepreneurs or residents, are several and substantial.
Seizing these opportunities is a way to repair the breach and raise up the foundations of many generations, restoring the lives and dignity of our fellow citizens.
Opportunity Zones are a grant to lift up the world.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
Jason G. Mandel has spent over 25 years at the intersection of Wall Street and the insurance industry. Mandel founded ESG Insurance Solutions (www.esginsurancesolutions.com) in 2020 to help better integrate these two, often conflicting worlds Having a strong belief in ESG concepts (Environmental, Social and Governance), Mandel found a way of incorporating his beliefs in his business.
Representing only insurance carriers and products that he believes offer compelling risk management solutions and maintaining business practices that he can support, Mandel has led the industry in this ESG initiative. ESG Insurance Solutions serves some of the wealthiest families internationally, and their business entities, by providing asset protection, advanced tax minimization vehicles, principal protected tax-free income structures, employee retention strategies, key person coverage and tax-free enhanced retirement plans for their essential employees.
The past 18 months have been interesting (to say the least) for anyone involved in technology strategy, planning or implementation. Ideally, a road map with prioritized projects and defined resource allocations directs the activity, and the company stays relatively true to its path. Unfortunately, the pandemic, with all its implications, has wreaked havoc on tech plans. Project priorities have often shifted, sometimes virtually overnight. Digital gaps have been exposed. Customer expectations have dramatically changed. And executives wonder what the new normal will look like.
SMA has conducted a series of market pulse polls throughout the pandemic, starting in April 2020 as the initial economic lockdowns and work-from-home mandates began to take hold. Our latest survey, conducted this May, assessed how plans are being reshaped as commercial lines insurers move forward in the second half of 2021 and formulate plans for early 2022. Whether we are moving toward a post-pandemic era in the U.S. is debatable, but what seems clear from the plans of commercial lines insurers is that tech-related plans are moving ahead full steam.
So, what does the big picture look like?
The commercial lines insurance industry has gone through three distinct phases over the last year and a half. In the early days of the pandemic, there was a tactical response to the lockdowns that affected employees, customers and partners alike. New virtual, digital capabilities became a priority to enable remote work and remote customer interactions. Then, as 2020 proceeded, phase two began. As it became evident that the pandemic would continue for some time, there was some deceleration of some activities or a pause in projects, and some of the more innovative initiatives were tabled until 2021. The third phase began in 2021 with an explosion of activity. It was almost as if someone flipped a switch on Jan. 1. Commercial lines companies began accelerating plans, launching a frenzy of tech-based strategy and implementation activity in the first half of the year.
SMA’s most recently completed survey shows that hardly any companies plan to retrench or pause project activity in the second half. There is a significant amount of rethinking for road maps and project reprioritizations. One exception to the reshuffling of priorities is in core systems. Any companies that had policy, billing or claims systems modernization projects in flight have continued to push forward. These projects are so foundational and have so much urgency and momentum that it would be unwise to pause or reprioritize them.
So, the stage is set to be very active for the rest of the year as companies double down on technology initiatives. Although 2022 plans have not come into sharp focus just yet, strategy and budget planning are underway at many companies, and the early glimpse indicates that this accelerated digital transformation will not be just a one-year phenomenon. It may just represent the new normal. I personally can’t wait until 2022 to see what is in store for the industry!
Mark Breading is a partner at Strategy Meets Action, a Resource Pro company that helps insurers develop and validate their IT strategies and plans, better understand how their investments measure up in today's highly competitive environment and gain clarity on solution options and vendor selection.
My grandchildren are curious, a trait they definitely inherited from me. Whenever they get a cool new toy or technology gadget (yes, even the 1½-year-old loves these!) and have put it through its paces for a while, their attention inevitably turns to trying to figure out how the thing really works. This can result in the destruction of the item to get a glimpse of its guts, to see how the parts all work together to create the engaging experience they just had.
They are the perfect audience for the book series The Way Things Work by David Macaulay. The simple text and detailed, colorful drawings in these books “pull apart” items “from levers to lasers, from cameras to computers” to show curious kids (and their parents) the inventive thinking and innovation that goes into the things that make life easier, engaging and more enjoyable.
If there was an illustration in this book of traditional insurance distribution, what do you think it would look like? Maybe something like a Rube Goldberg contraption? (For those who don’t know the name, he drew cartoons in which Professor Butts solved a simple task in the most complicated, inefficient and hilarious way possible.) Most people studying the diagram of insurance distribution, especially customers, would agree that the process is complicated, confusing and inefficient -- needing an innovative makeover!
I have previously highlighted the increasing use of ecosystems and partnerships to expand beyond the traditional agent/broker distribution channel. This creates a win-win-win for insurers, their ecosystem partners and most importantly their customers. Insurers and their partners can quickly tap into new markets, and both potential and current customers benefit from more purchase and service options. Distribution ecosystems also help meet customers where and when they want to buy, creating friction-free experiences and evolving insurance from something that had to be sold to something people want to buy.
These ecosystems create a satisfying experience, just like that cool new toy that your kids and grandkids spend time with.
Embedded Insurance: Creating Innovative and Interesting Partnerships
Distribution options fall across a spectrum of channels, including direct to customer, agent/broker, other insurers, marketplace exchange or platform and embedded. Embedded insurance is among the newest options, and numerous interesting examples of partnerships between insurers and other industries are popping up, including with GM, Ford, Tesla, SoFi, Petco, Airbnb, Uber and Intuit.
Insurance can be “soft” embedded, offered as an opt-in option during the purchase of another item; “hard” embedded, included as an opt-out option with the purchase of another item; or “invisible,” included in the purchase of another product without the option to remove it (e.g., bumper-to-bumper warranty with a new car).
I’m convinced that ecosystems will play a big role in the future of the industry. So, until the next The Way Things Work book adds a chapter on them, let's do our own examination of how embedded insurance can produce a better result for all stakeholders customers, insurers and ecosystem partners.
The Customer Is the Critical Core Component
Majesco has long promoted/used a framework of three macro trends to help explain the forces driving change in the industry: people, technology and market boundaries. Multi- and digi-channel ecosystem/partnership strategies embody all these categories. No innovation in insurance would be possible without all three, but people are the most important. The greatest, most innovative technology or business model will only last if individuals and business owners see the value in it.
Why do people see value in ecosystem/partnership and embedded distribution models? Some clues can be found by looking at three different models of how people think and make decisions especially about insurance.
Jobs to Be Done
The famous business professor Theodore Levitt gets cited often as a pioneer of the Jobs to Be Done (JTBD) concept, with his quote, “People don’t want a quarter-inch drill, they want a quarter-inch hole.” The idea is that customers don’t necessarily think about products the way the businesses selling them do. To customers, products are an input to accomplishing a larger task, while the business is narrowly focused on making the sale. In his book, The Jobs to Be Done Playbook, Jim Kalbach says: “JTBD is not about your product, service or brand. Instead of focusing on your own solution, you must first understand what people want and why it’s important to them. Accordingly, JTBD deliberately avoids mention of particular solutions in order to first comprehend the process that people go through to solve a problem.”
In traditional distribution, the insurer takes a narrow, inside-out view, where the policy purchase is viewed as the beginning and end of the “job.” But, while customers do want to complete the purchase, it’s just one task in a series they need to do to complete their “job,” which could range from being able to drive their car or buy a home, to setting up their financial wellness plan, and more.
With embedded distribution, the insurer recognizes that insurance is just one task in the customer’s job and makes it easier for the customer to complete this task by stringing it together with one or more other tasks in the job. This allows the customer to save time and effort by completing several tasks at once instead of dealing with them separately.
System 1 and System 2 Thinking
In his book, Thinking, Fast and Slow, the Nobel Prize-winning behavioral economist Daniel Kahneman described human decision making and thinking as a two-part system. System 1 thinking produces quick (i.e., instantaneous and sub-conscious) reflexive, automatic decisions based on instinct and past learnings… the familiar “gut reaction.” System 2 is slow, deliberate and reason-based and requires cognitive effort.
Good decisions about complex issues like insurance should be based on System 2 thinking. The problem with System 2 is that it’s hard! And our natural preference as humans is to minimize effort. During the traditional research and buying processes, the effort that is needed can lead many customers to seek shortcuts to in-depth research and analysis or delay a decision altogether. Embedded distribution can ease some of the System 2 effort because the insurance offering is viewed in the context of the “job” the customer is currently doing, making it easier to understand how it will be used and what it does (and doesn’t) do.
Fogg Behavior Model
Another very useful framework for understanding people’s decisions and behaviors is the Fogg Behavior Model, developed by BJ Fogg, the director of the Behavior Design Lab at Stanford University that we highlighted in our customer research and that a number of insurtech startups have used in designing their business models. The model translates behavior into a simple formula consisting of just three components: prompts, motivation and ability, all of which must occur in the same moment for a behavior to occur.
This model highlights an inverse relationship between motivation and ability. If someone has low ability for a behavior (i.e., it’s hard to do), a high level of motivation is needed (plus a prompt) to make it happen. Similarly, if someone has low motivation for a behavior, whoever wants them to do it must make it extremely easy (and provide the right prompt). Using this model as a lens for how people make insurance decisions reveals the weaknesses of traditional insurance distribution that ecosystems and embedded insurance can exploit. Let’s take a look at the three components.
Prompts
What triggers people to think about buying insurance?
There are two basic categories of prompting events that align with mandatory and discretionary insurance. Simple examples of mandatory prompts are auto and homeowners insurance in personal lines or workers compensation in commercial – the customer must buy these to own the car or home or to run a business that has employees.
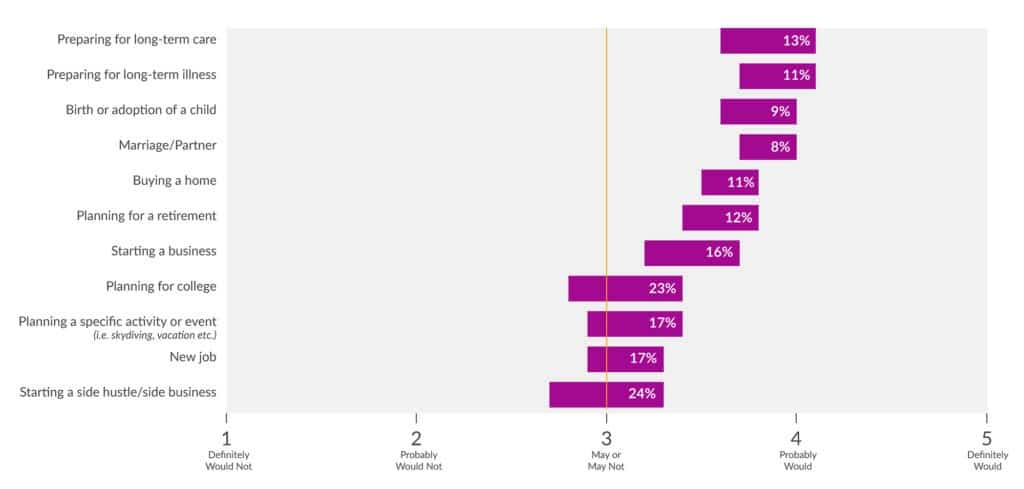
Discretionary prompts align with other events that cause people to think about protection of the things that are important to them. In our 2020 consumer research on life insurance, we actually found that life events had a stronger impact on younger generations in terms of considering life insurance purchases, as seen in Figure 1, which shows the gaps in the ratings between Gen Z / millennials and Gen X / Boomers.
Figure 1: Gaps between generations in impact of life events on L&A insurance purchase consideration
In the traditional distribution model, insurers need to fight for share of mind so people think of them when one of these prompts occurs. Large personal lines insurers like GEICO, Progressive and State Farm spend millions of dollars on advertising – not to cause people to drop what they’re doing and begin the buying process but to stay top of mind for the times when important events cause people to think about the need to buy or update their insurance.
In the embedded approach, the insurer receives in-the-moment top-of-mind awareness because the offering is placed directly in the path of purchase of another product or service… at the right time and in the right place. This is a great strategy for well-known brands and startups alike. A startup insurer won’t have the same brand equity as one of the major advertisers, but it can get some “rub-off” equity as a featured option by a trusted ecosystem partner from whom the customer is purchasing a product or service, or the startup could be white labeled with the partner’s brand.
Motivation
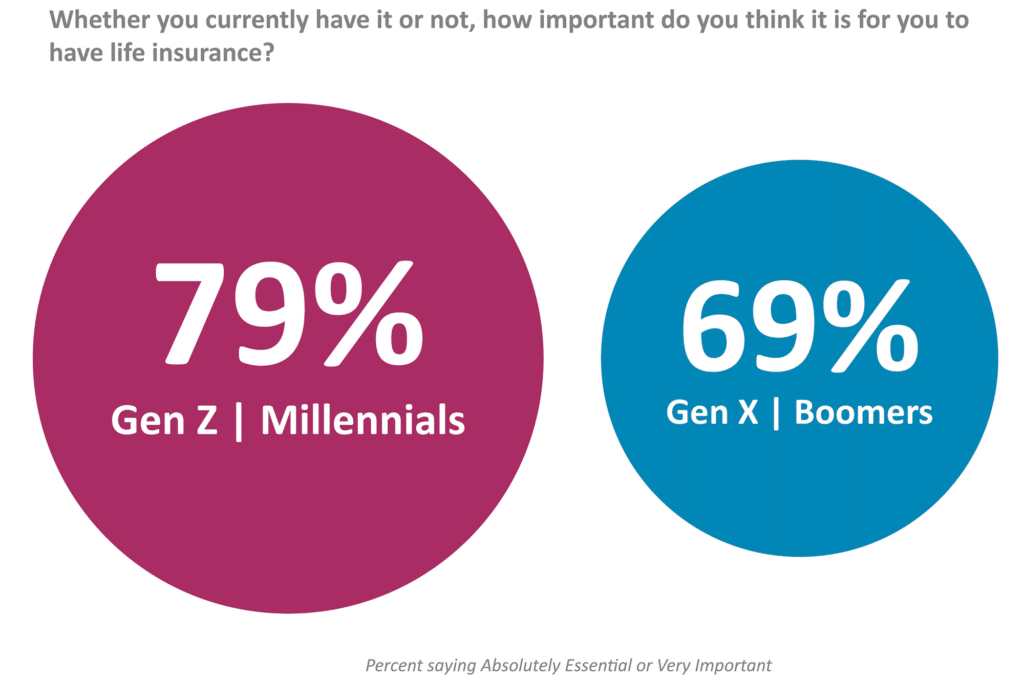
Motivation, with respect to insurance, is closely related to prompts and has two types I like to call “forced” and “fuzzy” that align with the mandatory and discretionary prompt categories. Mandatory coverages can be highly motivating, but to some people they can carry a negative feeling of being “forced” to buy insurance (of course, most people probably would buy these coverages even if not mandatory). “Fuzzy” motivation is a more emotional feeling about the value and importance of insurance… and it’s vitally important to the purchase of discretionary products like life insurance. Fortunately, Gen Z / Millennials place high importance on life insurance, even more so than their older counterparts, as we found in our 2020 consumer research.
Figure 2: Importance of life insurance
In traditional distribution, insurers rely on these two types of motivation to drive customers to their websites, agents or call centers. It’s a strategy based on hope. In embedded insurance, the insurer piggybacks on the motivation that has driven the customer to buy a product or service. This is a strategy based on intimate knowledge of your current and potential customers.
Ability
Most customers do not think of insurance as being “easy to do business with.” In some of our early consumer research, we found that insurance ranked at or near the bottom in terms of being easy to research, buy and service compared with other businesses customers interact with. The life and annuity industry ranked worse than property and casualty. Even cable and mobile phone companies ranked higher in many categories, two industries with traditionally poor customer service.
Since then, many insurers have made great strides in simplifying processes and products with new data sources, digital technologies and cloud-based platforms. However, JD Power’s recent study on customers’ P&C insurance digital experience reveals that insurers are having a hard time keeping up with continually rising expectations for digital capabilities; the study says insurers are “stuck at providing only ‘good enough’ digital user experience.”
In the traditional distribution model, insurers rely on motivated prospects who have been prompted by an important event to reach out to them to research and buy insurance. If the insurer’s processes and products are too complex and exceed the prospect’s abilities (and patience), the insurer loses the business. In the embedded model, motivated customers can add insurance to a product or service during the purchase process, usually with just a few clicks. Easy peasy!
Make Multi- and Digi-Channel Distribution Your Strategy
Traditional distribution channels have served the insurance industry well for hundreds of years. They still work and are vitally important. But people, technology and market boundaries have changed dramatically in just the past few years, and insurance distribution must keep up. The new and growing spectrum of channel options now available, especially the exciting opportunities for embedded insurance, will give innovative insurers and their partners tremendous opportunities for growth, with new markets, new offerings, satisfied and loyal customers…and growing books of business.
What is prompting you to adopt a multi- and digi-channel distribution strategy? Are you motivated to take action? Do you have the ability? These are the components that drive decisions and actions…and innovative insurers are deciding to act!
Get Involved
Our authors are what set Insurance Thought Leadership apart.
Denise Garth is senior vice president, strategic marketing, responsible for leading marketing, industry relations and innovation in support of Majesco's client-centric strategy.
Ratemaking processes using legacy technology and methods are no longer adequate.
A recent McKinsey report, Insurance 2030—The impact of AI on the future of insurance, found that more technologically advanced market entrants have increased pressure on traditional insurance companies to innovate. Furthermore, the pandemic has increased the need for insurers to adopt solutions that enable them to meet consumer expectations for more affordable rates and for products that meet their needs, at the moment of need.
The answer is dynamic ratemaking, an advanced, AI-driven process that creates product offerings that respond to real-time market changes and align with consumers’ expectations as market conditions shift.
Delivering on Consumer Expectations With Agility
Traditionally, gathering data and building new insurance rate structures has taken several months, because traditional systems are slow to adapt and solutions that operate in a siloed manner rely on multiple approval processes.
Waiting six to 12 months to introduce new insurance products and rates is too long. Many insurers currently use real-time automated ratemaking and product deployment, and consumers are likely to go with those insurers that can provide the most personalized and competitive product offerings.
Personalization as a Competitive Advantage
Consider usage-based insurance (UBI). Some insurance customers now prefer to pay a rate based on their driving habits, as opposed to a one-size-fits-all rate, and dynamic solutions can calculate millions of rates and product options each day – in a personalized way.
A dynamic solution enables insurers to provide both traditional and UBI options by managing and automating the entire ratemaking process. Agile and sophisticated solutions propel data through the enterprise-wide ratemaking machine to deploy new rates quickly. Once filed and deployed, real-time quotes are provided to the right customer touchpoint.
A single, end-to-end solution that combines personalization, ratemaking and deployment capabilities doesn’t necessarily require a complex implementation. Capabilities can be implemented iteratively, enabling insurers to realize ROI faster and safeguard operations.
With increased technology adoption in the insurance industry, the market will become more competitive, and consumers' expectations heightened. Alternatives to traditional ratemaking methods can improve consumer retention and enable insurers to offer competitive options regardless of market conditions. With a dynamic rating solution that combines advanced and traditional statistical methods, insurers can create and deploy new rating structures attuned to market conditions and consumer needs.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
Dror Pockard is head of North America Insurance at Earnix. He has over 30 years of experience building and leading start-ups and in senior executive roles in large global companies. His expertise lies in strategy, business development and M&A.
Offering advanced digital capabilities to customers is a top priority for many insurers, which are now re-evaluating the core systems they’ve used for decades and looking for alternatives.
When considering the modern core systems on the market today, carriers need to be aware that not all solutions are created equal. To leverage the full benefits of cloud technology, decision-makers must understand the nuances of cloud-agnostic software models and SaaS platforms.
The 'Run It Anywhere' Model
Traditional enterprise software companies develop systems designed for insurers to deploy and operate on their own infrastructure. In this model, the insurer controls and operates the infrastructure.
But the time and cost to design and implement infrastructure is easy to underestimate. Even if the software is easy to deploy, the design, implementation and required maintenance of infrastructure are high-skill and -cost activities, both up front and on a continuing basis.
Operating the infrastructure also means the insurance carrier is responsible for the security and reliability of the system. This results in even more cost and pulls IT staff attention away from other projects. All security and reliability service-level agreements with the business are underwritten by the carrier’s internal IT team.
The same goes for software support. When the carrier’s employees or customers experience issues with the software, the insurer must investigate to find out whether its own infrastructure is the problem or if blame falls to the software vendor. Overall, this model results in a lot of extra work and cost for the carrier.
Software companies that follow the “run it anywhere” model are easy to spot by the claims they make. If a software vendor claims to be able to “run on any infrastructure” or be “cloud-agnostic,” it follows this model.
Using Cloud Technology Doesn’t Change This Model
In the traditional model for core systems, insurers use on-premises infrastructure. When we hear "on-premises," we think of the insurer having their own server room in their building.
But insurers now tend to outsource the physical aspect of managing their data center. “On-premises” now usually refers to servers housed in a commercial data center. Removing the outsourced data center and replacing it with cloud infrastructure (IaaS) can provide many benefits, but it doesn’t change the essence of the model.
The carrier still takes on all the complexity and cost of designing, implementing, operating and maintaining the infrastructure to run the vendor’s software. If anything, there is even more complexity, because the cloud brings additional security risk compared with the dedicated data center.
Adding Digital Capabilities Further Strains the 'Run It Anywhere' Model
Any modern core system must support digital service channels and collaboration with the insurer’s ecosystem through application programming interfaces (APIs).
These connect the carrier’s digital channels like portals, chatbots, contact centers and voice assistants to their real-time core data store. Having a cloud infrastructure enables these digital capabilities and is key to providing fast self-service that is consistent across channels, as well as integrations with ecosystem partners.
But, again, making a core system available to anyone over the internet, even indirectly through a web-based cloud infrastructure, must be handled with care. This is a moving target as hackers continue to up their game.
Much of the protection insurers need comes from their infrastructure, not from the application. So, with the “run it anywhere” model, a large portion of the complexity, risk and cost is taken on by the insurer.
Insurance carriers have to wonder, is this where they want to focus their IT expertise? Fundamentally, if the carrier can “run it anywhere,” the carrier will be doing the running.
Containers Limit the Benefits of Cloud Technology
One of the enabling technologies of “run it anywhere” is containerization. When software is packaged in containers, it can run almost anywhere – on-premises or in any cloud. Containers are very useful, but they’re not the best for everything. Once an insurer is committed to a cloud provider, other useful technologies like serverless functions and cloud managed services can be leveraged.
Serverless functions are a way of deploying software without managing infrastructure, allowing software to scale from very low to very high usage without any additional effort, and only paying for what is used. The approach is ideal for peaky workloads like the APIs supporting digital service channels.
Clouds also offer managed services, large building blocks of capability that reduce the cost of infrastructure while improving security and reliability. Some replace what would otherwise be self-managed infrastructure, including file storage, backup, database management and network management. Others add leading cloud capabilities like business intelligence, machine learning and voice interfaces.
SaaS Is the True Solution to Reap All the Benefits of Cloud
Leveraging serverless functions and cloud managed services gives SaaS core systems vendors a great opportunity to embed additional value for the carrier. But because these technologies are not standardized to use across different types of infrastructures, they can’t be leveraged by those “run it anywhere” vendors seeking to be cloud-agnostic.
The goal of a SaaS company is to focus its efforts on creating one system that works extremely well, instead of creating many variations for each individual insurer that may not perform as efficiently. This goal allows the SaaS vendor to provide the most cost-effective, secure, scalable and reliable solution possible for clients.
Another advantage of SaaS is the benefit of a strong partnership with a single cloud provider. Cloud-agnostic companies that work with multiple cloud providers spread their skills and commercial influence across multiple providers. The companies weaken their internal expertise and reduce their access to support and to key resources from the cloud infrastructure partner.
When moving to cloud-based core systems to modernize their organization, insurance carriers should keep a few points in mind:
Look for SaaS core systems to get the full benefits of cloud technology.
Choose a vendor that allows the carrier to focus its IT resources on differentiating the business, not building and maintaining infrastructure.
Ask if the SaaS vendor has developed a strong cloud infrastructure partner.
Expect the SaaS vendor to leverage cloud machine learning and digital communications to help the carrier deliver leading-edge digital capabilities.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
Jonathan Boylan is chief technology officer at FINEOS.
Six Things Newsletter | August 10, 2021
In this week's Six Things, Paul Carroll looks at a new breakthrough in blockchain. Plus, building telematics can mitigate risk; how insurance can halt ransomware; breathing life into life insurance; and more.
In this week's Six Things, Paul Carroll looks at a new breakthrough in blockchain. Plus, building telematics can mitigate risk; how insurance can halt ransomware; breathing life into life insurance; and more.
While the enormous potential for blockchain in insurance has been apparent for a while, I’ve been waiting to see a breakout application hit the real world. I think I saw one last week, albeit in a different industry.
An article on Quora reported that Amadeus, a global reservation system, has adopted a blockchain-based system for verifying health clearances, such as COVID-19 vaccination records, for travelers.
The system will have to adapt as the pandemic continues to unfold and, in particular, as policies on eligibility for travel evolve, so success is by no means guaranteed. But I think this rollout is one to watch, because it’s the first I’ve seen that aims at truly massive scale, of the sort that will need to occur in the insurance industry as blockchain tracks certificates of insurance, manages first notice of loss and so on.
Join this webinar to learn how Group and Voluntary Benefits players have the opportunity to extend their reach through new, broader diversified plays that align to a new generation of employees and employers.
Cognitive computing is a funny beast. Every time you hit your target, you find that another pops up off in the distance.
When I first saw a demonstration of speech recognition, some 30 years ago, I was mightily impressed that the computer understood a few words. If I had seen what would be possible today, I’d have been stunned. But now? Oh, that’s just Siri or Alexa. And why didn’t auto-correct guess exactly what I wanted to say?
Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.
We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.
Ransomware cyber insurance policies are perceived as having high deductibles and low ceilings. In other words, costs are seen as misaligned with the risks and coverage needs of insureds.
Many insurance companies have adopted a conservative approach toward ransomware premiums out of fear of a cyber insurance "hurricane" where, due to correlated risks and virtually unlimited liability, insurers could be overwhelmed by claims covering cyber-extortion payments, forensics, recovery and data loss and legal expenses.
Exposure has led to premium increases, and some carriers now sub-limit policies with fixed caps on recompense. Mechanisms such as co-insurance demonstrate a mindset of risk-sharing, but a more efficient cyber insurance marketplace demands a broader understanding of shared risk.
Ransomware attacks are felt beyond the targets, with pain spread across the global economy. Cyber insurance offers financial stability. Brokers, actuaries, auditors and other stakeholders should expect reasonable, documented assurances that insureds are making rational investment decisions concerning risk management.
This requires greater cooperation among insurance companies, policyholders and private industry -- including technology vendors. Disclosure and documentation, internal network and ransomware data resilience controls and information sharing are areas where we can and should work more closely. This is the way to ensure individual pricing suits the size and scale of risk for both insurers and insureds.
Shared responsibility for data resiliency
An aggressive cybersecurity posture must include forward-thinking strategies toward ransomware. It is in the interests of each of us to disrupt the cyber-extortion business model and eliminate its source of profits.
Ransomware variants are not monolithic. A cooperative response requires a joint analysis of both new and emerging threats, as well as the technologies that ensure security controls are in place and effectively applied.
Altogether, technology is shifting the paradigm. It is effective at early ransomware detection, and software can automatically shut down attacks to minimize the damage. However, while historical capital expenditures have been focused on perimeter and endpoint protection, effectiveness has proven incomplete.
Data immutability provides a more complete resiliency model. Maintaining clean datasets that are more readily restored, minimizing loss and preserving data probity, means making data resilient to malicious encryption.
Global file systems, as an example, which in advanced applications offer wider unstructured data management capabilities, in some cases use immutable data architectures.
While immutable repositories resist tampering with data contents, that does not necessarily mean that the host platform cannot be compromised separately. Cybercriminals are adept at finding ways to disable data protection software and systems.
Conducting backups on a daily or weekly basis can help organizations better respond to a ransomware strike, but restoring from a backup almost always involves data loss. Strict data-backup procedures do not ensure that files cannot be encrypted, and moving backups offline results in an operational gap.
Additionally, even where backups are readily available, the time that such restoration will take is frequently underestimated. Because backups are a complete and incrementally produced copy of data, the size of the dataset is substantial, and it may take days or even weeks for clean copies to be restored.
Insurers, policyholders and technology makers should be aware that immutable approaches to data storage are particularly effective even in cases where ransomware can lie dormant in an IT environment, leading to backup of files containing malicious code, because they preserve a pristine data set.
Cloud-based immutable storage repositories, such as Panzura on Amazon AWS S3, which operates with an object-lock feature irrespective of whether the data is accessed, may not necessarily prevent an attack but maintain an unadulterated copy of data for use in a restore scenario.
Best practices say that, should a primary object store be attacked through a security vulnerability, insureds should consider a split-write, or cloud mirror, to a second object store to ensure guaranteed data accessibility.
Collectively documenting data resilience
Research by the University of Kent and the Royal United Services Institute for Defence and Security Studies (RUSI) indicates the insurance sector is struggling to collect and share reliable cyber risk data that can inform underwriting. The report posits that more regulatory intervention may be necessary.
While there is a legitimate role for public agencies in the fight against ransomware, the time is now to take collective steps that will avoid the blunt lattice of regulation. Frameworks of agreement and cooperation among private industry are really the best cure.
The cyber-ecosystem is only as strong as its weakest link, and insurers can more thoroughly underwrite cyber insurance if they better understand the precautions that insureds must take to fend off ransomware attacks and back up their data resources.
Providing brokers and underwriters with better information calls for standardized certifications, enabling all parties to have a holistic view of what constitutes secure data. This should be based on a clear mapping of agreed protocols for defense and acceptable recovery parameters.
The insurance purchasing process itself requires an inward evaluation of security controls, and results in better understanding of the value and nature of data. For example, Panzura works with customers to provide a Statement of Ransomware Resilience, along with other types of documentation, which insurers can consider when determining premium pricing and coverage limits.
Consensus among insurers and technology vendors is necessary to define the form and function of the documentation. Acceptance should be a basis for negotiating rates that appropriately balance risk with the immutability and resilience of insured data and networks.
Sharing risk more equitably, we can build on responsible efforts by insurers to avoid a cyber insurance "hurricane." Collective action will shield all organizations from infection and mitigate the damage of ransomware on the global economic landscape.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
Glen Shok is vice president of strategic alliances at Panzura, a provider of unstructured data management solutions. He has more than 25 years of experience in enterprise technology, including past roles with Oracle, EMC and Cisco.