Download

Resilience Ratings: Triple-I Unveils Way to Measure Communities' Risk Levels

In this webinar, ITL Editor-in-Chief Paul Carroll and the Triple-I’s senior economist, Michel Leonard, discuss what the measures cover, how individuals and communities can use them and where the Triple-I will take them from here.

|||

Peter Drucker once famously said that "what gets measured gets managed," and the Insurance Information Institute is unveiling measures for U.S. communities' resilience against natural disasters. In this webinar, ITL Editor-in-Chief Paul Carroll and the Triple-I's senior economist, Michel Leonard, discuss what the measures cover, how individuals and communities can use them and where the Triple-I will take them from here.

This webinar discusses:

  • How the Triple-I assembled the ratings over the past 18 months based on data from federal authorities, from academic institutions and from its own work.
  • How those considering buying homes can use the ratings to understand the flood risk in the communities they may move into and be assured that insurance will be available at an affordable rate.
  • How the Triple-I will extend the measures to cover additional types of natural disasters, including wildfires and tornados.

Speakers:

Dr. Michel Leonard, PhD, CBE

Senior Economist and Data Scientist, Head of the Economics and Analytics Department
Insurance Information Institute

Dr. Michel Léonard, CBE, leads the Triple-I’s Economics and Analytics Department. He is responsible for providing analysis and insight on industry economics and business performance, as well as other forward-looking, data driven insurance insights.

Michel brings more than twenty years of insurance experience to Triple-I, including senior and leadership positions as Chief Economist for Trade Credit and Political Risk at Aon; Chief Economist at Jardine Lloyd Thompson; Chief Economist and Data Scientist at Alliant; and Chief Data Scientist at MaKro LLC. In these roles, he worked closely with underwriters, brokers and risk managers to model risk exposures for property-casualty and specialty lines such as credit, political risk, business interruption and cyber.

Michel also currently serves as adjunct faculty at New York University’s Economics Department and at Columbia University’s Statistics Department and Data Science Institute. In this capacity, Michel provides a key link between the Triple-I, its Non-Resident Scholars and academia.

Michel holds a Bachelors of Arts from McGill University, a Masters of Theological Studies from Harvard University, and a Masters of Arts and Doctorate of Philosophy in Political Economy from the University of Virginia, focusing on qualitative and quantitative risk modeling. He is a member of the Insurance Research Council Advisory Board.

Paul Carroll

Editor-in-Chief, Insurance Thought Leadership

Paul Carroll is the editor-in-chief of Insurance Thought Leadership. He is also co-author of “Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years” and the author of a best-seller on IBM, published in 1993. Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

When AI Doesn't Work

To keep us from getting carried away, it's good to look from time to time at the failures of AI to live up to the projections -- and COVID is a prime example.

Although I'm a big believer in the prospects for artificial intelligence, and we've certainly published a lot to that effect here at Insurance Thought Leadership, AI has also carried a ton of hype since it emerged as a serious field of study in the mid-20th century. I mean, weren't we supposed to be serving our robot overlords starting a decade or two ago?

To keep us from getting carried away, it's good to look from time to time at the failures of AI to live up to the projections, to see what AI doesn't do, at least not yet. And the attempts to apply AI to the diagnosis of COVID-19 provide a neatly defined study.

I've long believed in learning the lessons from failure, not just from successes. To that end, while Jim Collins had done the work on the patterns of success in Good to Great and Built to Last, I published a book (Billion Dollar Lessons, written with Chunka Mui) a decade-plus ago based on a massive research project into the patterns that appeared in 2,500 major corporate writeoffs and bankruptcies. You can't just look at the handful of people who, say, won millions of dollars at roulette and declare that betting everything on red is a good strategy; you have to look at the people who lost big at roulette, too, to get the full picture.

In the case of AI, a recent article from the MIT Technology Review found that, to try to help hospitals spot or triage COVID faster, "many hundreds of predictive tools were developed. None of them made a real difference, and some were potentially harmful.... None of them were fit for clinical use [out of 232 algorithms evaluated in one study]. Just two have been singled out as being promising enough for future testing."

Another study cited in the article "looked at 415 published tools and... concluded that none were fit for clinical use."

What went wrong? The biggest problem related to the data, which contained hidden problems and biases.

The article said: "Many [AIs} unwittingly used a data set that contained chest scans of children who did not have COVID as their examples of what non-COVID cases looked like. But as a result, the AIs learned to identify kids, not COVID."

One prominent model used "a data set that contained a mix of scans taken when patients were lying down and standing up. Because patients scanned while lying down were more likely to be seriously ill, the AI learned wrongly to predict serious COVID risk from a person’s position.

"In yet other cases, some AIs were found to be picking up on the text font that certain hospitals used to label the scans. As a result, fonts from hospitals with more serious caseloads became predictors of COVID risk."

Some tools also ended up being tested on the same data they were trained on, making them appear more accurate than they are.

Other problems included what's known as "incorporation bias" -- diagnoses or labels provided for the data before it was fed to the AI were treated as truth and "incorporated" into the AI's analysis even though those diagnoses and other labels were subjective.

I'll add based on personal observation from 35 years of tracking AI that it's tricky to manage, meaning that issues should be expected. The vast majority of senior executives don't have a technical background in information technology, let alone in AI, so it's hard for them to evaluate which AI projects will pan out and which should be set aside. Even those proposing the projects can't know with much precision ahead of time. They can identify areas as promising, but nobody can know that they'll hit an insight until that insight appears. Add the fact that AI carries an air of magic, which can give it the benefit of the doubt even when good, old humans might do a better job.

The article's main general recommendation happens to be the same prescription that Chunka and I offered at the end of Billion Dollar Lessons to help head off future disasters: generate some pushback.

In our case, dealing with corporate strategy, we recommended finding a "devil's advocate" who would look for all the reasons a strategy might fail. The person would then present them to the CEO, who otherwise is often fed a diet of affirmation by people trying hard to make the CEO's brainchild look brilliant. Our research found that 46% of corporate disasters could have been averted because the strategies were obviously flawed.

In the case of AI, experts quoted in the MIT Technology Review article recommend finding people who could look for problems in the data and for other biases. That advice should be extended to considerations of whether a project should be attempted in the first place and whether claims made on behalf of an AI should be tempered.

As I said, I firmly believe that AI will play a major role in transforming the insurance industry. There are already scores of examples of successful implementations. I just think we'll all be better off if we keep our eyes wide open and anticipate problems -- because AI is tricky stuff, and problems are out there. The more pitfalls we can avoid, the greater our likelihood of success.

Cheers,

Paul


Paul Carroll

Profile picture for user PaulCarroll

Paul Carroll

Paul Carroll is the editor-in-chief of Insurance Thought Leadership.

He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.

Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.

Underwriting Small Business Post-COVID

Carriers must go beyond traditional data sources to minimize the information gap and transform the underwriting of small businesses.

Despite the impact of COVID-19, the commercial insurance marketplace must provide the proper insurance coverage for small businesses that have survived, morphed, jump-started or stalled. Insurance carriers have needed to assemble a more complete snapshot of each small business’ individualized risks, but now that’s more important than ever. To do so, carriers need to go beyond traditional data sources to minimize the information gap and help to transform the underwriting of small businesses.

Assessing risks more accurately

One of the challenges in underwriting a small business is finding sufficient financial data about the business. According to a 2019 internal study conducted by LexisNexis Risk Solutions, approximately half of small businesses have a credit profile only in a single commercial credit bureau. When insurers exclusively use commercial credit for commercial rating, they are likely missing the true risk profile of the small business in their book. 

To properly protect a small business customer, insurance carriers need to make sure they’re collecting and analyzing available data. Fortunately, there is an abundance of data and analysis available to overcome this problem; it just needs to be aggregated, analyzed and provided in a readily digestible way. 

Gain from a multi-source strategy 

A multiple-source approach can address the gaps, but identifying and evaluating the right data sources is critical for pricing a risk fairly, for both the customer and the insurer. Our internal analysis shows that when insurers use three financial data sets in their underwriting, it results in an average scorable rate of 74% compared with just 52% with only one source.

Leveraging small business credit data also provides insurance carriers with extended visibility and financial data insights on small and micro businesses, and combining small business credit data with other available business data makes it even more powerful. Providing predictive modeling makes it easier for carriers to evaluate a business by its loss propensity at the point of quote, underwriting or renewal. 

With financial data from millions of small businesses, carriers can benchmark a customer against the industry at large and have financial insight that may not be found in commercial credit sources. This approach, with an incremental model of business data and small business credit data, can provide up to an 88% scorable rate coverage on small businesses and can match up to 96% when combined with business owner financial data.

See also: COVID-19 Trio Tops Global Business Risks

Create an inclusive approach

For commercial carriers looking to improve their book of business, begin by understanding your current and future target market. How do these types of businesses compare with similar entities in your book of business, and what financial products do they use?

Next, select the right sources of data for a particular business. Credit bureaus, non-traditional financial sources and personal financial data can all be used to better align to your book of business.

Lastly, create an underwriting program that leverages these data sources to better segment small businesses based on a more precise view of the business’ or business owner’s financial profile. This design, a predictive model, is built specifically to help you more quickly and confidently assess risks. Taking advantage of segmentation can increase the effectiveness of your program and improve your loss ratio contingencies. 

Insurers looking to remain competitive within the small business market need to evaluate the right mix of information on both the business and its owner to price the risks of each small business they insure more accurately. Embracing change and seeking predictive models with industry data can improve risk assessment and support more dependable decision-making.


Jeremy Stafford

Profile picture for user JeremyStafford

Jeremy Stafford

Jeremy Stafford is senior director of commercial insurance for LexisNexis Risk Solutions. He is responsible for establishing the strategic direction of the commercial insurance business at LexisNexis Risk Solutions.

Small Commercial: Digitizing Distribution

Data pre-fill is the top project area for sales capabilities as it is a critical starting point for achieving straight-through processing.

How far along are commercial lines carriers in delivering digital solutions to their agents and other distribution partners? Answering that question depends on whether you are a glass half-empty or glass half-full type of person. The pessimist might say: Despite huge investments in technology over the past few decades, there is still a great deal of manual processing; the time for the rate-quote-bind process is too long; and the goal of truly making it easy for the agent to do business with the carrier is still elusive. The optimist would cite enormous industry progress, as many companies have increased straight-through processing (STP) to a significant percentage of the business; digital self-service capabilities for both sale and service are widespread; and agent-carrier connectivity, in general, enables astounding volumes of electronic business flow.

SMA recently surveyed carriers focused on the small commercial market to assess the state of digital capabilities offered to distribution partners, the barriers to implementation and adoption and the plans for enhancing or delivering new digital capabilities. We discovered that rather. than taking a glass half empty or half full approach, the better analogy is a road trip, with the kid in the back seat regularly asking, “Are we there yet?” It turns out that the question is not easy to answer. Once you get by the lofty goals of STP and ease of doing business (EODB), there are a variety of specific functional capabilities that are important. By the way, STP and EODB are still the top two reasons that carriers invest in tech solutions for distribution, and they do provide a north star for plans in this space.

SMA’s research tracked 14 different digital sales-oriented capabilities and 17 servicing capabilities, starting with a carrier’s satisfaction with the state of the offerings to their distribution partners. Suffice it to say that, while some are satisfied with their offerings, many are not. For example, only about a third are satisfied with their quoting capabilities. Satisfaction levels on the servicing side are higher, but there are still many companies that are dissatisfied or do not offer the digital capability. In terms of plans and projects, there is lots of investment and activity in addressing the areas where companies believe they are weak. For example, data pre-fill is the top project area for sales capabilities as it is a critical starting point for achieving STP.

See also: Agencies Turn to Networks for Growth

There are both business and technology roadblocks to success in distribution technology. For example, few will be surprised to learn that limited IT resources are the #1 barrier on the technology side. In short, this is a very critical but complex area of the insurance business, and the industry as a whole is moving to enhance the digital capability provided to distribution partners. It is a journey, but, like that proverbial kid in the back seat, many executives will continue to ask, “Are we there yet?”

For more information on commercial lines distribution expansion strategies, see our recent research report, “Distribution Technologies for Small Commercial: Carrier Progress and Plans.” SMA is also introducing a research series with perspectives from the distributor viewpoint. A regular series of research reports will be published based on surveys and interviews of agencies, brokers, MGAs and others in the distribution channel, including insights from ReSource Pro’s large footprint of distribution clients. 


Mark Breading

Profile picture for user MarkBreading

Mark Breading

Mark Breading is a partner at Strategy Meets Action, a Resource Pro company that helps insurers develop and validate their IT strategies and plans, better understand how their investments measure up in today's highly competitive environment and gain clarity on solution options and vendor selection.

Adding Transparency to Life Settlements

Transparency prevents relationship-based decisions and gives all stakeholders confidence that the buying process is fair.

The life settlement is a legal, regulated process for liquidating life insurance. Unfortunately, the regulations in place don't fully address the culture of mistrust in the industry. That culture is an outcome of the traditional process: Life settlement cases have historically been managed behind the scenes, with each stakeholder having access to only some of the case details. That veiled environment allows providers, agents, advisers, investors, brokers and policyholders to work at cross purposes.

Complicating matters, the amount of funds available to buy policies has exploded in recent years. As more money circulates in the industry, dishonesty and deception remain key issues that ultimately work against all stakeholders. 

Harbor Life Brokerage set out to move the industry past those issues with technology -- specifically, a life settlement exchange that ensures transparency and ethical business practices.

Underlying mistrust and lack of transparency 

The traditional life settlement auction process has pockets of secrecy. Insureds, agents, advisers, life settlement brokers, life settlement providers and life settlement funds rarely have access to the same set of information. Brokers typically act as gatekeepers, with the freedom to share or withhold details as they see fit. They naturally create a lack of transparency and fosters mistrust. 

Some of that mistrust is warranted. Unethical brokers will award cases based on relationship rather than bid size. That's a clear disservice to the insured, who assumes the broker is working to negotiate the highest selling price possible. In these cases, the broker must intentionally limit the auction information provided back to the insured. The insured certainly won't see the highest bid -- and also may not know how the winning offer was calculated or where it came from.  

Fortunately, these problems are solvable with technology. The Harbor Life online auction platform creates transparency by giving all stakeholders access to the same information. With case details and bids accessible electronically, whoever submits the highest bid wins the case, period. There is simply no room to make a backdoor deal, which ensures a fair process for everyone involved.

Poor communication

Poor communication, whether intentional or by accident, worsens the lack of transparency in the traditional life settlement process. Layers of hidden fees charged by providers or brokers cut into the insured's proceeds -- often without the insured's knowledge. 

As an example, a broker might deliver a net offer to the insured, with no breakdown of the gross selling price and the broker's commission. As well, providers may put in offers net of their fee, essentially hiding those fees from funders.

Policy metrics can be another area of confusion. Actuarial firms, responsible for valuation, may be inconsistent on key metrics, such as life expectancy. That misalignment of data works against providers who are trying to put their best offer forward to win the deal. 

Again, technology can solve for missing or inconsistent data. The Harbor Life Exchange states valuation metrics up-front so all parties are working from the same set of numbers. The exchange also requires families to sign off on commissions for every transaction -- ensuring full transparency into the fees paid out of sale proceeds. 

The exchange also invites providers to specify their fees. That way, life settlement funds know what the provider is making on every deal.

See also: Making Life Insurance Personal

Lack of free market competition

Ultimately, the closed nature of the traditional life settlement process limits free market competition. And any factor limiting open competition will hold the entire industry back from growth. 

Transparency inspires confidence in life settlement transactions. And confidence creates growth. Confident buyers submit higher bids -- because they're more comfortable with policy details and valuation metrics. Confident agents and advisers refer more cases, creating more opportunities for buyers. And confident insureds have a positive, profitable experience they can share with friends and family.

The Harbor Life exchange promotes this confidence dynamic by encouraging as many providers as possible to compete openly on every case. 

Reinventing the life settlement market 

The Harbor Life Brokerage exchange streamlines life settlement transactions for agents and buyers. When agents submit cases, Harbor Life orders current records and compiles the case information. Agents can then list those cases on the exchange with a reserve price -- that is, the minimum bid the insured will consider. 

More than a dozen licensed providers are invited to view all listed policies on the exchange. Those providers can filter listings by policy type and insured demographics, including health status, state of residence, gender and life expectancy. Diving into each listing, providers will see a summary of key metrics for each case that's easy to analyze and compare.

See also: Beware the Grey Swan 

All stakeholders have a transparent view of bids, fees, case details and valuation metrics. It's a form of forced transparency to combat communication shortfalls that have historically plagued the industry. This transparency prevents relationship-based decisions and gives all stakeholders confidence that the buying process is fair. 

Life settlements are growing in popularity, but the industry needs innovation to move into the mainstream. Technology that fosters transparency and competition is a big step in the right direction.


Lucas Siegel

Profile picture for user LucasSiegel

Lucas Siegel

Lucas Siegel is the founder and CEO of Harbor Life Settlements, a life settlement company that is dedicated to helping seniors and the terminally ill sell their life insurance policies, and Harbor Life Brokerage, a life settlement broker.

Challenges Loom for International Shipping

Shippers must master COVID challenges, apply the learnings from the Suez Canal incident and prepare for cyber and climate threats.

|

The international shipping industry continued its long-term positive safety trend over the past year but has to master COVID challenges, apply the learnings from the Ever Given Suez Canal incident and prepare for cyber and climate change threats. The number of large vessels lost remained at record low levels in 2020, while reported incidents declined year-on-year, according to Allianz Global Corporate & Specialty SE’s  latest Safety & Shipping Review 2021. 

The annual AGCS study analyzes reported shipping losses and casualties (incidents) over 100 gross tons. During 2020, 49 total losses of vessels were reported globally, similar to a year earlier (48) and the second lowest total this century. This represents a 50% decline over 10 years (98 in 2011). The number of shipping incidents declined from 2,818 to 2,703 in 2020 (by 4%). There have been more than 870 shipping losses over the past decade. 

The South China, Indochina, Indonesia and Philippines maritime region remains the global loss hotspot, accounting for one in every three losses in 2020 (16) with incidents up year-on-year. Cargo ships (18) account for more than a third of vessels lost in the past year and 40% of total losses over the past decade. Foundered (sunk/submerged) was the main cause of total losses over the past year, accounting for one in two vessels. Machinery damage/failure was the top cause of shipping incidents globally, accounting for 40%.

COVID-19 factors

Despite the devastating economic impact of COVID-19, the effect on maritime trade has been less than first feared. Global seaborne trade volumes are on course to surpass 2019 levels this year after declining slightly in 2020. However, the recovery remains volatile. COVID-19-related delays at ports and shipping capacity management problems have led to congestion at peak times and a shortage of empty containers. In June 2021, it was estimated there was a record 300 freighters waiting to enter overcrowded ports. The time container ships are spending waiting for port berths has more than doubled since 2019.

The crew change situation on vessels is a humanitarian crisis that continues to affect the health and wellbeing of seafarers. In March 2021, it was estimated some 200,000 seafarers remained on board vessels unable to be repatriated due to COVID-19 restrictions. Extended periods at sea can lead to mental fatigue and poor decision-making, which ultimately affect safety. There have already been shipping incidents that have featured crews who have been on board for longer than they should have been. Seafarer training is suffering, while attracting new talent is problematic given working conditions. Future crew shortages could affect the surge in demand for shipping as international trade rebounds.

Larger vessels, larger exposures

The blocking of the Suez Canal by the Ever Given container ship in March 2021 is the latest in a growing list of incidents involving large vessels or mega-ships. Ships have become ever larger as shipping companies seek economies of scale and fuel efficiency. The largest container ships break the 20,000 teu mark, with vessels over 24,000 teu on order – capacity of container ships vessels alone has increased by 1,500% over 50 years and has more than doubled over the past 15 years.

If the Ever Given had not been freed, salvage would have required the lengthy process of unloading some 18,000 containers, using specialist cranes. The wreck removal of the large car carrier, Golden Ray, which capsized in U.S. waters in 2019 with more than 4,000 vehicles on it has taken over a year and a half and cost several hundred million dollars.

See also: A Price Tag on Climate Change

The number of fires on board large vessels has increased significantly in recent years. There was a record 40 cargo-related fires alone in 2019. Across all vessel types, the number of fires/explosions resulting in total losses increased again in 2020, hitting a four-year high of 10. Fires often start in containers, which can be the result of non-/mis-declaration of hazardous cargo, such as chemicals and batteries. When mis-declared, these might be improperly packed and stowed on board, which can result in ignition and complicate detection and firefighting. Major incidents have shown container fires can easily get out of control and result in the crew abandoning the vessel on safety grounds, thus increasing the size of loss.

Loss of containers at sea also spiked last year (over 3,000) and has continued at a high level in 2021, disrupting supply chains and posing a potential pollution and navigation risk. The number lost is the worst in seven years. Larger vessels, more extreme weather, a surge in freight rates and mis-declared cargo weights (leading to container stack collapse), as well as the surge in demand for consumer goods, may all be contributing to this increase. There are growing questions about how containers are secured on board ships.

Delay and supply chain issues

Maritime supply chain resilience is in the spotlight after a series of recent events. The Ever Given incident sent shockwaves through global supply chains dependent on seaborne transport. It compounded delays and disruption already caused by trade disputes, extreme weather, the pandemic and surges in demand for containerized goods and commodities. Such events expose the weak links in supply chains and have magnified them. Developing more robust and diversified supply chains will become increasingly important, as will understanding pinch points and supply chain nodes.

Piracy and cyber concerns

The world’s piracy hotspot, the Gulf of Guinea, accounted for over 95% of crew numbers kidnaped worldwide in 2020. Last year, 130 crew were kidnapped in 22 incidents in the region – the highest number ever – and the problem has continued. Vessels are being targeted farther away from the shore – over 200 nautical miles (nm) in some cases. The COVID-19 pandemic could exacerbate piracy as it is tied to underlying social, political and economic problems, which could deteriorate further. Former hotspots like Somalia could re-emerge.

The report also notes that all four of the world’s largest shipping companies have already been hit by cyberattacks, and, with geopolitical conflict increasingly played out in cyber space, concerns are growing about a potential strike on critical maritime infrastructure, such as a major port or shipping route. Increased awareness of – and regulation around – cyber risk is translating into an uptake of cyber insurance by shipping companies, although mostly for shore-based operations to date. 

The environmental picture

With momentum gathering behind international efforts to tackle climate change, the shipping industry is likely to come under increasing pressure to accelerate its efforts. A huge investment in research and development is required if the industry is to meet the challenging targets being set. Today’s existing fleet and technology will not get the shipping industry to the International Maritime Organization’s target of a 50% cut in emissions by 2050, let alone the more ambitious targets being discussed by national governments.

Last year, the cap on the sulfur content of ships’ fuel was cut. Known as IMO 2020, the cut is expected to reduce emissions of harmful sulfur oxide (SOx) from shipping by 77%. Insurers have seen a number of machinery damage claims related to scrubbers, which remove SOx from exhaust gases for vessels using heavy marine fuel. 

See also: COVID-19 Trio Tops Global Business Risks

Most frequent loss and incident locations 

According to the report, the South China, Indochina, Indonesia and Philippines maritime region is also the major loss location of the past decade (224 vessels), driven by high levels of local and international trade, congested ports and busy shipping lanes, older fleets and extreme weather exposure. Together, the South China, Indochina, Indonesia and Philippines, East Mediterranean and Black Sea and Japan, Korea and North China maritime regions account for half of the 876 shipping losses of the past 10 years (437).

The British Isles, North Sea, English Channel and Bay of Biscay region saw the highest number of reported incidents (579) in 2020, although this was down year-on-year. The most accident-prone vessels of the last year were a Greek Island ferry and a RoRo ferry in Canadian waters, both involved in six different incidents.

To learn more, please visit AGCS: Safety & Shipping Review 2021.


Andrew Kinsey

Profile picture for user AndrewKinsey

Andrew Kinsey

Capt. Andrew Kinsey is senior marine risk consultant at Allianz Global Corporate & Specialty. He spent 23 years in the U.S. Merchant Marine and Naval Reserve. He served in Operations Desert Shield and Desert Storm, Restore Hope, Enduring Freedom and Iraqi Freedom.

How to Improve the Customer Experience

Increasingly, customers don't choose just a risk product but a combination of risk product, customer experience and services.

|||||

Tunnels, once the greatest innovation in transportation, are poised to be the greatest once again through innovation and rethinking of transportation. While Elon Musk has been looking to the sky with SpaceX, he’s also been going underground with the Boring Company, creating test tunnels in California and operational tunnels in Las Vegas. The key to Musk’s tunneling concept is the rapid technological advancement being made in boring machines. Prufrock, the current all-electric boring machine, can dig a 12’ diameter tunnel up to one mile per day. The Boring Company has a goal of producing a machine that would be able to bore up to seven miles per day, a stunningly fast pace that will change the landscape of transportation and create a system that connects people and places more than ever before.

The value of tunneling is also a new level of versatility and looks at the concept of mobility rather than individual types of transportation. It will improve pedestrian traffic, auto traffic and certainly some forms of subway traffic, but it will also facilitate new types of underground travel, such as autonomous vehicle traffic and hyperloop travel. Tunnels can be dug without disruption to the infrastructure, and they could be an excellent way to improve ground-level and atmospheric environments through non-emission subterranean commuting. Who would have thought that digging could lead to a more sustainable future? It is just one more example of how complex problems are often best solved by breaking outside of the boundaries of convention and incorporating new 360-degree thinking with an outside-in perspective.

Recently, we have been looking at Majesco’s latest thought-leadership report, Digital Insurance: The Inflection Point, in an effort to peek into the future of the insurance experience. Increasingly, customers choose insurers not just for the risk product but for the combination of risk product, customer experience and value-added services. Because of this, future insurance leaders will be those who provide smooth, pleasant experiences with the best views into products and value-added services. Can we learn anything by digging deeper?

An Outside-In Mindset

No one will argue that insurance opportunities exist for those who can innovate and adapt. Each insurer has its own mining to do. Not only do they need to think ahead about the impact of new technologies, like the Boring Company, on P&C insurance products, but they need to think about the impact of 360-degree digital views and services that create greater value for customers today and tomorrow. When it comes down to it, the customer is the one who is pushing insurers to innovate. They are looking especially hard at companies that can provide unconventional solutions to difficult insurance puzzles.

Insurers must lay the groundwork of a new digital business model. We are facing a constant flow of disruptive factors at the same time we are witnessing unprecedented opportunities.   

Consider the pressures, threats and opportunities, including:

  • Non-Insurance Providers: Companies like Tesla and GM are offering/embedding insurance and have access to more real-time data to competitively price and underwrite the risk than most insurers will have, potentially cutting off traditional carriers from these opportunities. 
  • Connected Everything: Connected devices, beyond telematics, are enabling underwriting and pricing based on mileage, location, weather and behavior for P&C and L&A products, which would tie premium to usage, risk or more – providing more personalized coverage. 
  • On-Demand and Embedded Insurance: On-demand insurance, expected to increase 30% by 2026, will expand to nearly all lines of business. Furthermore, embedded insurance is poised to automatically include insurance in the purchase of something else -- like a vehicle, home or electronic device.
  • Continuous Underwriting: Rather than pricing once, insurers are shifting to constantly updating the risk profile. This changes policy terms and pricing using the continuous flow of data from different sources like cyber, fitness devices, telematics and other IoT devices and encourages people to manage their risk, which can drive lower prices.

See also: 3 Ways to Improve Customer Experience

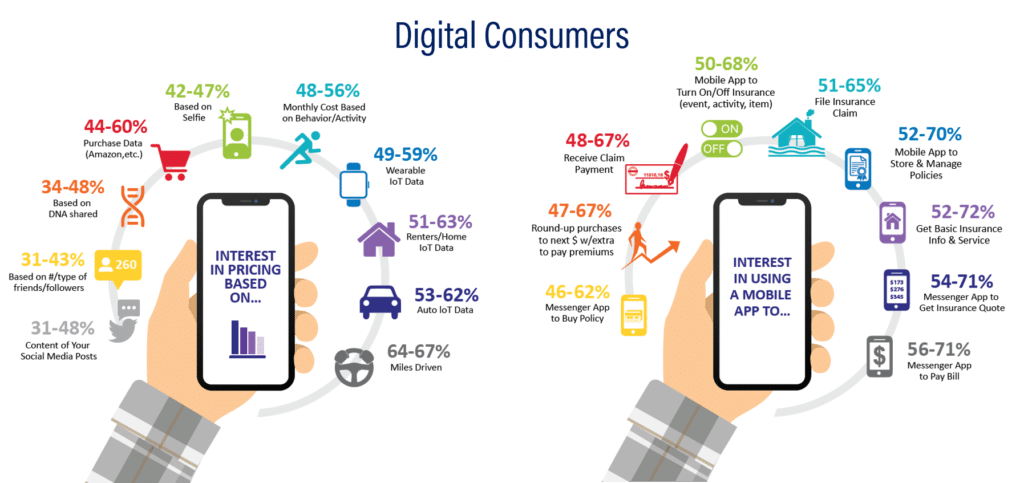
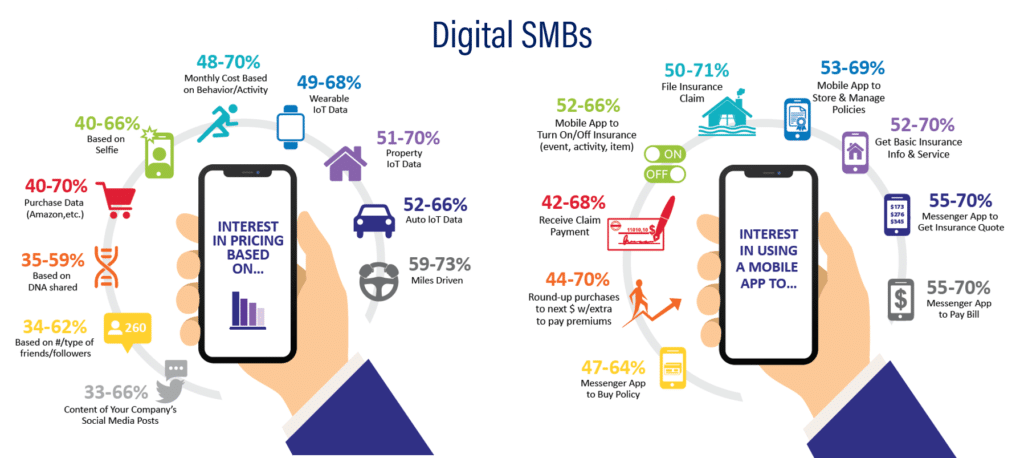
Today’s customers are extremely digitally adept, with higher expectations, different needs and a demand for better experiences that are not met with the “traditional” insurance approach, creating a fault line between customers’ expectations and insurers’ ability to deliver. In our customer research for individuals and businesses (Figures 1 and 2), the digital shift is well underway, reflected in the interest among both the older and younger generations for digital customer engagement and pricing. 

Figure 1: Interest in digital customer engagement and pricing — consumers

Insurers leveraging digital technologies, data and AI/ML are poised to leapfrog the competition by organizing talent, technology and ways of working around a digital-first vision for empowering customers.

In the recently released reports on innovation rating status, AM Best found that while the pandemic forced businesses to cram years’ worth of innovations into one year, most companies still have a long way to go. The report also found that there is a perceptible link between superior ratings and use of cutting-edge processes and technology-leveraged innovation initiatives.

If insurers are willing to dig deeper, they may find that data, analytics and digital technologies can help them create paths to income and value. The costs of cutting-edge technologies are continually going down as their impact rises. For example, the flexible, scalable, volume-based pricing of cloud-based processes that are necessary for digital service create a tremendous cost savings over on-site, server-based systems, but more importantly provide the flexibility to connect with ecosystems and adapt to market changes rapidly.

This is similar to tunnel boring. Prufrock’s boring cost per mile is going down just as the necessity for tunnels is on the rise. The result in both cases (tunnels and insurance) will be an ability to improve traffic flow, improve speed, improve experience and meet demand while reducing the overall use of previous technologies. That’s what makes digital insurance a more sustainable solution in the long run. It is solving multiple formulas at the same time.

The bottom line … a digital-first strategy will position that insurer as a future leader.  

Figure 2: Interest in digital customer engagement and pricing - SMBs

Can a Digital Strategy Meet the Digital Insurance Shift Quickly Enough?

Nothing satisfies an insurance customer more than having a positive personal interaction with any company --- even their insurer. All it takes is to meet their expectations of a personalized, smooth experience for a claim, a purchase or a routine contact such as billing and payments, creating the “Amazon experience” for insurance.

Of course, when interactions are disparate, frustrating, complex or redundant, the opposite is true. Customers become disillusioned and unsatisfied with the insurer.

COVID has tested insurers’ ability to pivot to a digital-first strategy, with an increased focus on customer experience. Years of adding disparate, siloed digital capabilities like functional portals were challenged. It became apparent that real digital transformation required a mindset shift to a new way of thinking, planning and doing. Leaders know this.

Unfortunately, insurance still embraces decades of legacy business assumptions and technologies that are roadblocks on the path to digital maturity. Many insurers were early adopters and innovators in technology but have built up a complex landscape of technical assets over decades, resulting in significant technical debt. The “modern” solutions of 10 years ago no longer meet the demands of a digital era or match the capabilities of insurtechs that are raising the bar.  

Creating compelling experiences for customers that provide transparency, intuitiveness and efficiency require next-generation core, data and digital platform solutions that use cloud, applicating programming interfaces (APIs), microservices, AI/ML and other technologies. This next-generation technology stack allows the exchange and ingestion of valuable data from diverse sources to produce highly personalized customer experiences in near real time. 

Insurers need to do some future-thinking around real-time risk assessment. They need to re-imagine customer journeys to move beyond a “tunnel-vision” portal to a new customer experience, to create new products offer new services and innovate their business models.


Denise Garth

Profile picture for user DeniseGarth

Denise Garth

Denise Garth is senior vice president, strategic marketing, responsible for leading marketing, industry relations and innovation in support of Majesco's client-centric strategy.

The Evolution of Frictionless Payments

The buying process needs to be easier for both the customer and the seller, to avoid all those abandoned shopping carts.

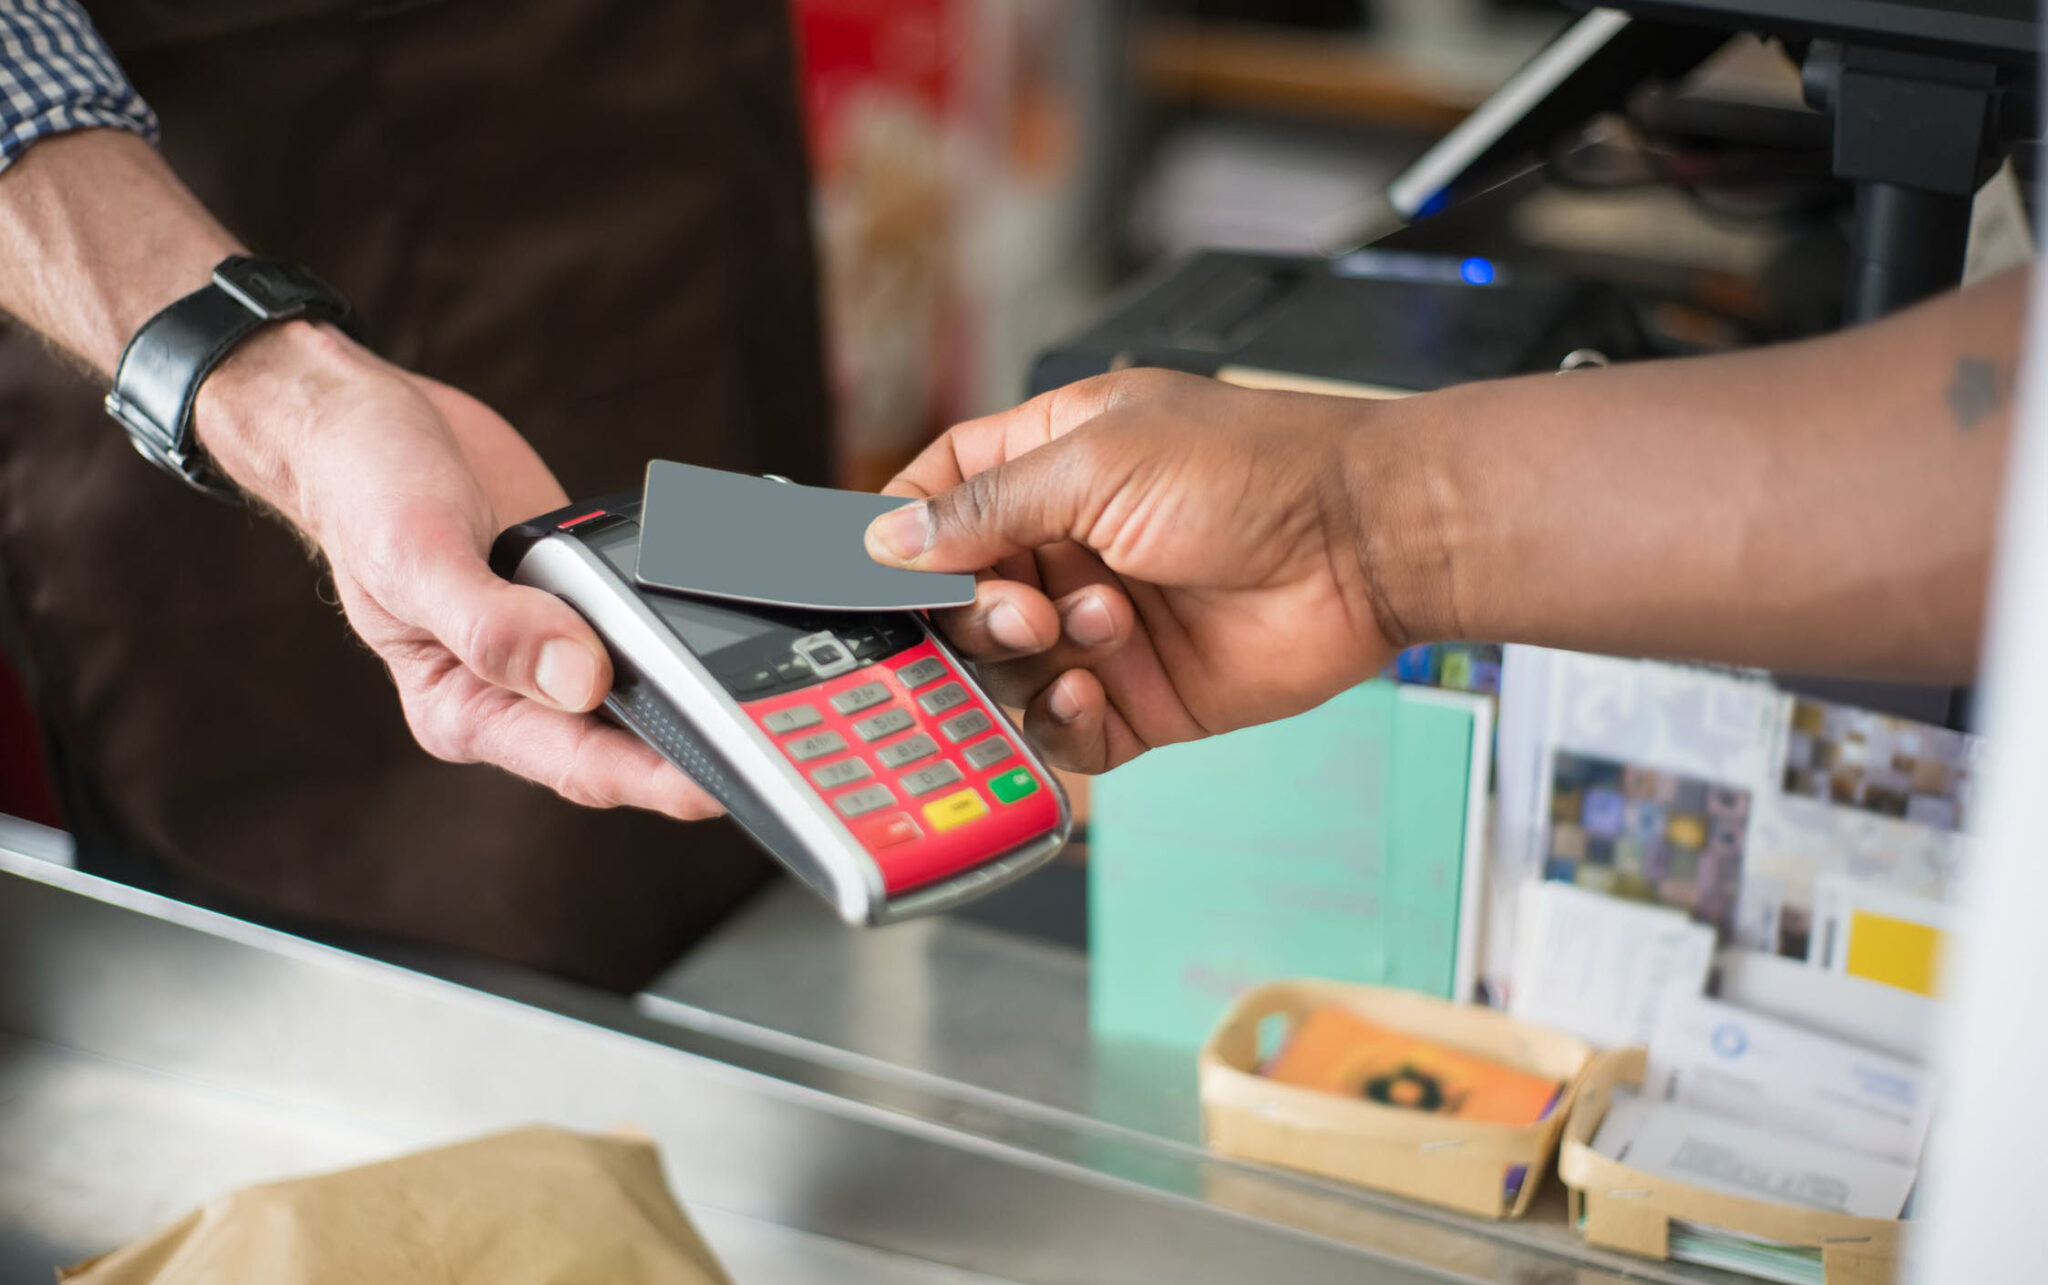
Frictionless payments are essential for e-commerce platforms to reduce the barriers between online shopping and completed checkouts. The buying process needs to be easier for both the customer and the seller, because an enjoyable user experience leads to higher conversion rates and fewer abandoned shopping carts.

When done right, frictionless payments improve the checkout process by eliminating waiting times. It’s all about reducing barriers and the steps toward a completed sale. Ultimately, frictionless payments should feel like a natural part of the experience.

Understanding how frictionless payments have developed and reviewing the history of buying processes will help us understand how businesses will be able to continue their growth in the digital age. So, let’s explore the evolution of frictionless payments and predict how businesses will drive conversion rates and create better customer experiences.

1950: Debit and credit cards

The credit card was developed in the mid-twentieth century, but it wasn’t until 1973 that the card payments system was computerized. This frictionless payment reduced transaction times to just one minute and gave rise to the era of electronic consumer payments. Computerized payments would eventually allow for future online transactions, where e-commerce businesses could contact banks to finalize payments with ease. In 1994, Stanford Federal Credit Union in California was the first financial institution to offer online internet banking, leading the way for online transactions to begin in 1995.

1999: 1-Click

Bookseller-turned-global-conglomerate Amazon patented an online transaction process called "1-Click" in 1999. This allowed customers to buy products with just a click of a button. Items could be purchased at the product level, without adding to a shopping cart, meaning that customers could buy a product in a flash. Voila: no shopping cart abandonment. With 1-Click, personal details and your bank account details are stored online, along with your usual delivery address.

The patent has expired, meaning a flurry of businesses can now use this frictionless checkout method. Given the global average rate for shopping cart abandonment is 70%, skipping over the shopping cart means that e-commerce businesses can maximize their conversion rates through this simple process.

2003: Chip, pin and tap

In 2003, the introduction of chip and PIN in the U.K. allowed cards to store data in a small chip on the face of a card. This data could then be accessed using a four-digit PIN, authorizing the payment. The American conversion to chip and PIN was announced in 2012 and completed in 2015.

Not only did this process increase efficiencies for both customers and businesses by automatically authorizing payments rather than making a customer sign a receipt, but it also curated a secure form of payment. Only those with access to the card and the secret PIN could access the account. The advance demonstrates how frictionless transactions can be made easier, and, importantly, more secure at the checkout.

Contactless payments were introduced in 2007, making the checkout process even easier. Today, one in five card payments is contactless.

2011: The mobile revolution

As mobile phones became smaller, they became as much an essential accessory as a wallet or purse. They’re with us all the time. So it’s not surprising that these handheld devices have become ingrained in the checkout culture. Leading mobile manufacturers Google, Apple, Android and Samsung all launched digital wallets between 2011 and 2015, allowing users to complete transactions with them rather than use their debit or credit cards.

These transactions had the added security benefit of authorizing payments through a fingerprint or facial scan. Furthermore, these digital wallets could be used in-store or online, storing personal data to automatically fill in those arduous forms with personal details, delivery addresses and billing addresses. The innovation helps further speed up online sales and transactions.

See also: The B2B Digital Payment Opportunity

Now and the future…

As online transactions become easier and quicker on the customer side, some obstacles for businesses to achieve a completely frictionless payment remain. Businesses must ensure that they balance the risks and rewards that come with streamlining checkout and ensuring protection from fraud and abuse.

As the popularity of omnichannel sales, digital wallets and one-click buying continues to develop, innovative ways to maximize sales without being affected by fraud and abuse have been developed. Commerce protection platforms, such as Signifyd, drive automated decisions on all transactions, approving more good orders and recovering lost revenue from chargebacks. This streamlines the customer experience, limiting the need for authentication forms and processes. Overall, commerce protection platforms feel like a natural part of the checkout process, going unnoticed by customers, and they can increase conversion rates by 4% to 6%.

Frictionless payments will continue to improve, creating better customer experiences and improving business performance. As more sales move online, and transaction speeds and efficiencies increase, it’s important to tackle attempts at fraud and abuse. At every stage of the evolution of frictionless payment, new processes are helping to make every transaction safer and more worthwhile for customers and businesses.


Ed Whitehead

Profile picture for user EdWhitehead

Ed Whitehead

Ed Whitehead is the managing director of EMEA for Signifyd, where he leads a team dedicated to the expansion and support of Signifyd's client base.

Six Things Newsletter | August 17, 2021

In this week's Six Things, Paul Carroll looks at Amazon's insurance play. Plus, the recipe for embedded insurance; dynamic markets need dynamic rates; collective response to data resiliency; and more.

In this week's Six Things, Paul Carroll looks at Amazon's insurance play. Plus, the recipe for embedded insurance; dynamic markets need dynamic rates; collective response to data resiliency; and more.

What Amazon’s Insurance Play Means

Paul Carroll, Editor-in-Chief of ITL

I’ve waited for years now to see how insurance might fit with Jeff Bezos’ quote that “your margin is my opportunity.” Amazon’s announcement last week that it will help sellers find product liability insurance through a network facilitated by Marsh may provide the answer.

continue reading >

Majesco Webinar

Listen in as industry experts cover the evolving shift in underwriting, keys to the next-gen underwriting workbench, and why insurers need this to stay competitive in the commercial lines market. 

Watch Now

SIX THINGS

The Recipe for Embedded Insurance
by Denise Garth

With embedded distribution, the insurer recognizes that insurance is just one task in the customer’s "job" and makes the buying process easy.

Read More

Dynamic Markets Need Dynamic Rates
by Dror Pockard

Insurers can use dynamic systems to create and deploy new rating structures attuned to market conditions and consumer needs.

Read More

Collective Response to Data Resiliency
by Glen Shok

Collective action will shield all organizations from infection and mitigate the damage of ransomware on the global economic landscape.

Read More

Tech Pulse Quickens for Commercial Lines
by Mark Breading

It was almost as if someone flipped a switch on Jan. 1, and commercial lines insurance companies began accelerating technology plans.

Read More

COI Is a 4-Letter Word; Tech Is the Solution
by Wade Millward

Certificates of insurance are broken. Processes must be transformed to provide the confidence clients deserve in the COIs they need to operate.

Read More

Why SaaS Is Key in Core Systems
by Jonathan Boylan

To fully leverage cloud technology, decision-makers must understand the nuances of cloud-agnostic software models and SaaS platforms.

Read More

Digital Revolution Reaches Underwriting

by Intellect SEEC

Underwriting is evolving toward a service that will help clients prevent losses, rather than merely indemnifying clients afterward.

Read More

MORE FROM ITL

AUGUST FOCUS: Cognitive Technologies
This month sponsored by Intellect SEEC

Cognitive computing is a funny beast. Every time you hit your target, you find that another pops up off in the distance.

When I first saw a demonstration of speech recognition, some 30 years ago, I was mightily impressed that the computer understood a few words. If I had seen what would be possible today, I’d have been stunned. But now? Oh, that’s just Siri or Alexa. And why didn’t auto-correct guess exactly what I wanted to say?

Keep Reading

Partner with ITL to create expert thought leadership content.

Custom Content
Promoted Content
Display Advertising
Custom Webinars
Monthly Topic Sponsorships
ITL Partner Packages and more


Learn more and get the 2021 Media Kit

GET INVOLVED

Write for Us

Our authors are what set Insurance Thought Leadership apart.
Get Started

SPREAD THE WORD

Share Share
Share Share
Tweet Tweet
Forward Forward
SUBSCRIBE TO SIX THINGS

Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

10 Ways Insurers Should Lean on OKRs

Objectives and key results (OKRs), a tool developed by legendary Intel CEO Andy Grove, can guide insurers through digitization.

While the insurance industry has long played it safe, innovation is now accelerating as digitization is gaining ground in more business sectors and the pandemic has forced companies to rapidly adapt to new restrictions. “It’s highly likely that the insurance industry will change more in the next 15 years than it has in the previous 100,” says Mark Anquillare, chief operating officer at Verisk.

The industry would do well to rely more on what are known as OKRs -- objectives and key results, which were developed as a management tool by legendary Intel CEO Andy Grove, championed by Google and explained to a broad business audience in venture capitalist John Doerr's 2018 book, Measure What Matters.

In this article, I'm going to explore 10 ways that the insurance industry will lean on OKRs in the years to come. 

1. Digitization of insurance front-end processes: Digitization of customer-facing processes makes it easier for customers to access information, compare providers and accelerate the closing process. 

The slow progress of customer-centric innovation in the insurance industry is a huge problem. COVID-19 has accelerated the migration of customers to digital channels. In response, insurers will more than likely rely on OKRs to efficiently execute their digitization initiatives before they lose customers to providers that have already digitized their customer-facing processes. Innovative companies like Lemonade, which has prioritized the digital experience of customers, have taken a lead in this charge.

2. Process (specifically speed of process) is becoming critical: Customer onboarding, underwriting, policy administration and claims are key processes in insurance. As customers become accustomed to a digital experience in nearly every vertical – from retail to media and entertainment, and even education and healthcare – their expectations have only grown.

Slow manual processes are not going to cut it for the modern-day customer. A few insurance leaders have already anticipated this necessary change and adopted OKRs to plan for dramatic improvements.

See also: A Quarantine Dispatch on the Insurtech Trio

3. Customers want flexibility and an omnichannel experience: Today, insurers are multichannel — not omnichannel. However, channels must be integrated to provide customers with a single, seamless experience. 

Customers should have information consistency across channels to avoid confusion and grant them flexibility to access their important information in any way that is convenient for them. Customers should have the flexibility to navigate across channels easily. OKRs can be used to execute omnichannel projects and ensure that this important aspect of user experience is provided to customers.

4. Responsiveness will be a differentiator: The top requirements insurance customers have for their providers are to have safe and secure transactions, receive fast responses and claims resolutions and receive guidance on the right policies required to cover their risks.  

Because there are so many touchpoints for an insurance customer, it’s important for insurers to provide highly responsive service that feels personalized and sensitive. When people feel genuinely cared for during an ordeal or in their time of need, they are more likely to be satisfied, repeat customers. OKRs can be used to build and run responsive organizations.

5. Agent-customer interaction has moved digital: The pandemic has made digital engagement between insurance agents and their customers the default. This pandemic-induced shift has actually resulted in more frequent and efficient interactions. Customers still want empathetic personal service as well as accurate information about coverage types and policy options. 

Both potential and current clients need answers about policy restrictions and coverage availability and will seek personal guidance. Agents should be comfortable with digital communication and be able to answer these questions and help clients get the coverage that best meets their needs and budgets. OKRs should be employed to manage this shift to digital as well as the desired outcomes in agent-customer interactions.

6. Enterprise agility will be key: Agile organizations can quickly direct their people and priorities toward value-creating opportunities. With the disruption caused by digitization, changing customer preferences and pandemic-induced disruption, insurers with enterprise agility will be rewarded. OKRs can be a great framework to build enterprise agility and ensure that a company is keeping up with the developing needs and expectations of their customer base.

7. Role of ML/AI in claims: Claims processing can frustrate customers. Because claims involve forms and paperwork, the sense of urgency that customers feel might not be reflected in the process itself. However, insurers that use AI can now respond to customers quickly, ensuring that they get their money fast. Agents can use AI tools to assess coverage, communicate instantly via portal, create follow-up tasks and ultimately process claims in a vastly more efficient process. 

By reducing cycle times, insurers satisfy customers and can process more claims. OKRs are being used to manage this important work done by the team of data scientists and AI/ML developers. A machine learning application can be trained to analyze claims and place them into one of three buckets: pay, don't pay or refer. In ML projects, machine learning tools are given a batch of historic claims to analyze and decide on -- and then compare those results to those already delivered by the human underwriters. By making any changes needed, the algorithm should soon be comparable to the human decision-making process. 

8. COVID-19 will still play an important role: The insurance industry is generally well-prepared for major loss events. Still, a pandemic like COVID-19 can be quite demanding in various ways for insurers, payers, employers and investment managers. COVID-19 mandated insurance companies allow up to 90% of their employees to work from home. 

One of the biggest challenges for insurers during the pandemic has been the spike in customer contacts. Customers are flooding insurers with queries over what they may or may not be covered for, and to submit claims on travel insurance, critical illness, health coverage, business interruption or another issue. 

While service and call centers associated with life, health and retirement products are seeing significant increase in inquiries, other products such as auto have seen a significant drop in claims. This is a low-visibility environment for insurers. OKRs provide the agility for insurers to navigate the effects of COVID-19 in 2021 and beyond.

See also: P&C Insurance Is Losing Importance

9. Fraud detection will be important: COVID-19 has brought in a host of new types of frauds for insurers, including tele-medicine scams, dental provider frauds, disability claims and auto-related frauds. Insurers are using traditional fraud prevention and detection technologies. But they are also looking at advanced analytic techniques to better identify attributes and trends for new and emerging threats so they can develop controls to mitigate the risks. ML is being deployed to detect frauds. OKRs are being used by many insurers to execute these projects and monitor and mitigate fraud incidents.

10. Client referrals and retention rate will be key: Client referrals measure the number of new clients that were referred by existing clients in any given time. This will become a key metric to measure two important factors. First, how satisfied your existing clients are with your products and services. Second, how much of the company’s growth is organic as opposed to advertisement-driven. OKRs can help manage these outcomes by streamlining customer success and related processes.

Insurance is in the middle of a disruption being caused by an industry-wide move to digital processes. This shift has only been accelerated by the pandemic and rising customer expectations. Smart insurers are using OKRs to manage this disruption and emerge stronger with better operational efficiency through great execution and high-performance teams that are prepared to adapt to the changing industry.


Bastin Gerald

Profile picture for user BastinGerald

Bastin Gerald

Bastin Gerald, founder and CEO of Profit.co, has a track record of taking initiatives and turning them into market-leading products.