Download

Mental Health Challenges (Part 2)

Central to the conversation of how best to support the mental health of BIPOC and AAPI communities is to realize one size does not fit all.

Woman with a phone smiling at something off-camera

Potential for improvement of Asian American and Pacific Islander (AAPI) and Black, Indigenous and people of color (BIPOC) mental health support, mental health treatment and mental health recovery abounds. BIPOC and AAPI need more equitable reimbursement rates from insurance companies, less bias in diagnosis and treatment and help overcoming mental health stigma in their communities. The disparity in providers (psychiatrists, social workers, psychologists and nurses) also needs to be addressed.

Acknowledgment and inclusion of all challenges AAPI and BIPOC face are essential. “How can we ‘treat’ individuals and ignore the historical trauma and systemic racism?” asks Pata Suyemoto, feminist scholar, writer, educator, diversity trainer and mental health activist. “How is this even ethical?”

“When it comes to historical trauma, if you lie to people long enough, they’ll begin to believe it’s the truth,” adds Dr. Brenda Wade, clinical psychologist. “This is why it’s a challenge to dislodge the fear and mistrust of ‘The System.’”

Solutions

How can BIPOC and AAPI people receive the most equitable care and sustainable results?

“We don’t exist in a vacuum,” explains Dr. JaNaè Taylor (she/her), licensed psychotherapist, private practice owner, podcaster and emotional wellness consultant, “and to approach our medical care without seeing the whole being is irresponsible and damaging. In our BIPOC communities, we’ve learned that we are our own best asset, and things like peer support, healing circles and mutual aid fill those gaps.”

Brianna Baker, Ph.D. student in counseling psychology at Columbia University, recommends an approach that is adaptable and culturally responsive to provide the most equitable care and sustainable results. Suyemoto recommends enabling AAPI and BIPOC communities “to define for ourselves what is helpful and useful and culturally relevant.”

Central to the conversation of how best to support the mental health of BIPOC and AAPI communities is to realize one size does not fit all. An approach that works for one community does necessarily work for others. Additionally, improvements to mental health treatment and support for BIPOC and AAPI include:

  • Culturally Representative Providers: Mental health systems need more providers that understand BIPOC and AAPI and how to advocate for their needs. We need to train more clinicians to address racial trauma and systemic racism in practice. We need to create stronger opportunities for people of color to serve as mental health providers.
  • Dismantle Systemic Racism in Mental Health Systems: Address the white supremacy culture and a Eurocentric perspective that imbues the mental healthcare system.
  • Understand BIPOC and AAPI Mental Health Through a Trauma-Informed Lens: Improve access to trauma-informed interventions to acknowledge and address the historical racial trauma and current systemic racism all BIPOC and AAPI experience. Stop misdiagnosing and pathologizing trauma.
  • Partner With Organizations of Color and Community Leaders: Assess best mental healthcare practices and supports for particular communities—ASK and LISTEN.

Community Care – An Alternative to Medicalized Mental Health Treatment

Community care is a viable option for more holistic and helpful mental health treatment. “Community care is critical for everyone, but especially for BIPOC and AAPI communities,” Suyemoto says. “Often, what professionals in the mental health field consider as ‘care’ is medicalized and not in alignment with BIPOC needs or cultures.”

“Community care” is a holistic approach to identifying and understanding each individual’s needs in the context of the social and physical landscape. It’s about developing a culture of shared mental wealth in which collective healing and liberation are the priority. In this framework of mental health support, BIPOC and AAPI people are valued as a whole person and as an integral part of the intersecting communities of which they identify. This culturally congruent approach to mental health care which values a person’s culture while validating their experiences as an individual.

There are many benefits to this approach. First, “community care” provides great accessibility and equity. This form of support meets a person where they are physically, emotionally and cognitively and brings traditional cultural practices to the forefront of treatment. These practices include spiritual practices (e.g., meditation, chanting, drumming, dance), oral traditions, kinship systems and the arts.

See also: Why We Don't Say 'Committed Suicide'

Emphasis on Community Resilience, Strength and Hope

AAPI and BIPOC have strong traditions in their cultures that have endured centuries of oppression and efforts to eradicate them. This resilience and tenacity, and the increased recognition and respect these traditions are beginning to garner, offer hope for the future. Africanity, for example—community-supporting beliefs and practices that originated on the African continent—have survived enslavement and modern-day racism. “Please remember that Africanity … has infiltrated America and world culture through dance, music, visual art and Black inventions,” Wade says. “Cultivate Africanity in your life, and celebrate the courage and strength of ancestors who made our lives possible!”

Resources

This blog is based on an #ElevatetheConvo Twitter chat hosted July 8, 2021, by Dr. Sally Spencer-Thomas @sspencerthomas. Advocates and experts unpacked the many ways disparities show up in our BIPOC and AAPI communities and opportunities for change and help. Special thanks to guest panelists:


Sally Spencer-Thomas

Profile picture for user SallySpencerThomas

Sally Spencer-Thomas

Sally Spencer-Thomas is a clinical psychologist, inspirational international speaker and impact entrepreneur. Dr. Spencer-Thomas was moved to work in suicide prevention after her younger brother, a Denver entrepreneur, died of suicide after a battle with bipolar condition.

Union Pacific Leads on Suicide Prevention

As the second-largest railroad company in the U.S., they took the bold leadership move to take the pledge to make suicide prevention a health and safety priority.

peron sitting on top of a hill watching the sunrise

Those in the railroad industry know about the toll suicide takes on employees, customers, families and communities. As an industry ranked in the top 10 for highest suicide rates, railroad corporations lose employees to suicide each year. Additionally, however, trains are also used as a means for suicide, so, tragically, people in the rail industry are often traumatized by witnessing pedestrians ending or trying to end their lives on the tracks.

So, Union Pacific decided to do something about it – as the second-largest railroad company in the U.S., they took the bold leadership move to take the pledge to make suicide prevention a health and safety priority and have been implementing the practices of the National Guidelines for Workplace Suicide Prevention. They started using education and information tools to help remove barriers mental health support and connect their employees with meaningful assistance. The mission? Let people know it’s normal to struggle, it’s okay to reach out for help, you don’t have to go it alone, support is available, and you won’t be penalized.

[Suicide is] the second-leading cause of death for middle-aged men,” says Mark Jones, Ph.D., Union Pacific’s former director of Employee Assistance and Support Services and member of the national Workplace Suicide Prevention and Postvention Committee. “Union Pacific is involved because our employees live and work in thousands of communities across 23 states, and it’s important that we’re part of this solution.”

Further, former Union Pacific Senior Vice President Robert Turner, now private sector chair of the National Action Alliance for Suicide Prevention, offered this personal testimony at the U.S./Canada Forum on Workplace Suicide Prevention.

Each year, Union Pacific supports World Suicide Prevention Day and spreads awareness about the importance of taking action to prevent suicides. After weeks or coordination, Union Pacific mobilizes approximately 200 volunteers to meet their fellow employees as they report to work or leave work and hand them wallet-sized cards about suicide prevention and a key chain imprinted with the inspiring message “Stay Connected.” The volunteers estimate they reach approximately 10,000 of the 50,000 Union Pacific employees through this effort in just one day.

See also: Workplaces Coping With Suicide Trauma

In addition to the World Suicide Prevention Day program, Union Pacific’s suicide prevention efforts go wide and deep. They include Operation RedBlock, a drug and alcohol prevention program; Union Pacific’s Peer Support volunteers, employees trained to help co-workers cope with difficult events; and Union Pacific’s occupational health nurses, who speak with employees system-wide about suicide warning signs and available resources. They even convened an international railroad summit that brought together representatives from most of the major railroad stakeholders to find industry-wide solutions.

For more on Union Pacific’s leadership in suicide prevention, visit: 

https://www.up.com/aboutup/community/inside_track/suicide-prevention-8-31-2016.htm

https://www.up.com/aboutup/community/inside_track/suicide-prevention-awareness-210910.htm.


Sally Spencer-Thomas

Profile picture for user SallySpencerThomas

Sally Spencer-Thomas

Sally Spencer-Thomas is a clinical psychologist, inspirational international speaker and impact entrepreneur. Dr. Spencer-Thomas was moved to work in suicide prevention after her younger brother, a Denver entrepreneur, died of suicide after a battle with bipolar condition.

A Frenzy of Activity in Commercial Lines

Research finds that insurers in small commercial lines are further along in their digital transformation journeys than their peers in mid/large commercial lines.

Abstract blue whirl design

Since 2020, there have been endless discussions around COVID-19’s impact on customers’ needs and how the insurance industry adapted swiftly to unprecedented times. Although the pandemic helped accelerate innovation in some areas, many commercial lines insurers came to realize how unprepared they were for the digital demands resulting from the global crisis. In fact, a recent SMA survey found that fewer insurers consider themselves to be in transformation mode today compared with in the pre-pandemic era. So, it is no surprise that, in 2022, many senior executives across commercial lines see how imperative it is to transform and innovate, and a sense of urgency is driving a frenzy of new activity.

SMA’s newly released research report, “Digital Transformation in Commercial Lines: Project Priorities for 2022 and Beyond,” identifies specific project plans for insurers in small commercial lines and mid/large commercial lines this year. Across all lines in the commercial market, insurers are focusing on operational transformation and the technologies needed to enhance data and analytics capabilities in different business areas. There is also more significant activity in initiatives to improve digital interactions with agents and policyholders. However, unique project priorities emerge when looking separately at insurers in small commercial versus mid/large commercial lines. 

Within small commercial, SMA’s research finds that insurers are further along in their digital transformation journeys than their peers in mid/large commercial lines. Specifically, small commercial insurers are increasing their investments in straight-through processing (STP). For insurers serving the mid/large commercial segment, modernizing core systems and eliminating manual processes are their top two project areas in 2022. Advancements in these areas will be essential for insurers handling complex and specialized risks that involve vast amounts of forms, documents and data.

See also: Emerging Tech in Commercial Lines

Insurers’ plans in 2022 will only continue in the years to come, and it will be become ever-more critical in a competitive industry environment. Upgrading digital capabilities to serve agents, policyholders, employees, members and shareholders will be hallmark traits of future market leaders engaged in their digital transformation journeys today.


Deb Smallwood

Profile picture for user DebSmallwood

Deb Smallwood

Deb Smallwood is the founder and CEO of SelfPowerment.

She spent four decades in corporate leadership across the insurance industry, operating at the intersection of business, technology, and organizational transformation. Her leadership inflection point led her to research the experiences of more than 50 high-achieving women and 10 men leaders. This formed the foundation of her book, SelfPowerment: The Inner Shift for High-Achieving Women Who Want More Than Just Success. The work introduces a research-informed framework that redefines success from within and invites women to shift the question from, “Will they choose me?” to “Do I choose them?”

How Analytics Can Democratize Insurance

Analytics are finally catching up to the vision, letting everyday business users harness the power of data through easy-to-use tools and advanced automation.

graphic showing a chart

One of technology’s best promises is democratization–taking specialized capabilities meant for a few people and then making them cheaper, simpler and more accessible to everyone. We’ve seen many examples in modern consumer products, such as computers, cars or even the internet itself. We’re starting to see examples of this in business, as well, such as in healthcare and logistics, and I believe we are on the cusp of a big change in insurance, too.

Although the insurance industry has always been about serving people, both individuals and groups, I think technology hasn’t always made insurance easier and more accessible for everybody. In fact, sometimes it seems to do the opposite. We are an analytics-driven industry, and analytics tools are still very hard to deploy and often harder for ordinary people to use. Most companies still rely on IT or business intelligence (BI) specialists to make sense of data so others can make smarter decisions.

But I think analytics and BI technology are finally catching up to our vision, allowing us to let everyday business users harness the power of data through easier-to-use tools and advanced automation. This is a huge opportunity for our industry, and I think embracing data analytics for all will pave the way for us to make insurance even more transparent and delightful (well, certainly less painful) for all of our customers.

The dream of democratized data in insurance

We have all dreamt of an insurance agency where every employee uses insights from data to make decisions and C-suite executives have on-demand dashboards with updated key performance indicators (KPIs). Line-of-business leaders use weather data to identify geographies potentially exposed to coming storms. Marketing teams combine U.S. Census Bureau data with internal data to discover business opportunities based on demographics and claims information.

At Hastings Mutual, we have finally been able to make this dream a reality, and I know that we aren’t alone.

For us, the key to making this possible has been to rethink how we use analytics in the first place. Like most organizations, we began using analytics by relying on static mainframe reports that had a refresh cycle of 30 to 45 days. Even when we centralized our data into a data warehouse, only IT specialists had the skills to query it. This led to a constant, growing backlog of requests from business users, which was frustrating for everybody involved. IT was exhausted, business users were using data that was already out of date and, of course, our customers and policyholders suffered as a result. No matter how much we tried to streamline the analytics delivery process, we always struggled with that last mile—actually getting the data insights into the hands of the people who needed them.

The revolution has been to take the opposite approach: Use new technology, such as self-service dashboarding tools, embedding and AI, to put the business users first—let them analyze data on their own, wherever they are, in whatever applications they’re already using, without having to first turn to IT, BI specialists or other experts.

In practice, this looks like employees who build their own dashboards, partners who discover opportunities using visualizations embedded into existing portals and policyholders who receive data-driven alerts via email or phone. In short, we put the end user first and bring the data to them, not the other way around.

See also: Setting Goals for Analytics Leaders

Creating insurance opportunities with analytics

It’s understandable that many people wonder if relying on analytics even more will turn insurance into an automated, robotic industry that simply does whatever the data decides is best, but the truth is precisely the opposite. As with computers or the internet, when we put analytics and insights from data into the hands of everyone, we all benefit.

Take something simple like weather data. By combining weather forecasts with maps and policy data, our internal business teams have been able to understand the effects of damaging weather conditions and, importantly, what to do about it. This combination has led to an improved bottom line through better data reporting and subsequent cost savings, but more importantly lays the foundation for a more positive customer experience through weather-related alerts to policyholders.

I’m excited to see how new technologies will continue to take insurance to the next level. AI can help automate much of the slow, manual processing of policy changes. Machine learning can increase the speed and accuracy of the underwriting process. Deeper app integrations lead to more data for business partners to see a complete financial picture, including premiums, plans and claims.

These are only a few of the possible ideas.  Many more become possible as we democratize data analytics and provide everyone with intuitive access to factual information upon which they can make smart decisions on their own and in their own time.

Elon Musk Is Wrong About AI

In painting a rosy and likely unrealistic picture of what AI can and can't do, Musk has, in our view, misled the public about how far we still have to go.

Binary and technology on a blue background showing AI

Elon Musk has a habit of using Twitter and interviews to make big statements. For instance, Musk told Jack Dorsey via tweet that AGI-artificial general intelligence, or AI with the power and flexibility of human intelligence--would most likely be here by 2029.

And when Elon talks, people listen. But should they?

He has a history of making bold predictions, not always correct; those self-driving taxis he promised still aren't here, for example. In this particular instance, the idea that some quantum jump in AI is imminent might actually cause some people to panic, especially given that Musk himself once famously told a crowd at MIT that, "with artificial intelligence, we are summoning the demon." At the same time, suggesting that humanlike intelligence is not far away might distract from all the current flaws in AI that so desperately need fixing.

The truth is, there is a giant gap between today's AI, which is largely pattern recognition, and the kind of Star Trek-computer-level AI that Musk is dreaming about. Yes, AI can already do some amazing things, such as speech recognition, with the ability to hold surrealistic but entertaining conversations about virtually any topic. But when it comes to reliability, dependability and coherence, current AI is nowhere near what it needs to be. Despite years of promises, AI continues to regularly make bizarre and unexpected errors of "discomprehension." It also perpetuates stereotypes; spreads misinformation; and still fails even at everyday tasks like human-level driving, especially in unexpected circumstances. Recently, a "summoned" Tesla crashed into a $3 million jet that was parked at a mostly empty airport. Inside the field, these kinds of challenges are well-known, but there are no firm fixes at hand.

Remedying AI's current flaws (and using the AI we actually have now wisely) must start with realism. Building an AI that is genuinely trustworthy is one of the most important but also challenging engineering missions of our time. But being glib about it isn't helping. In painting a rosy and likely unrealistic picture, Musk has, in our view, misled the public about how far we still have to go.

With so much at stake, we decided to call BS.

It began when one of us, Gary Marcus, drafted a $100,000 bet. In essence, the bet highlights the disconnection between Musk's latest claims about the future of AI and current reality. In the spirit of serious betting, Marcus laid out five very specific conditions.

To really say that AGI had been achieved, it would have to clear at least three of the following five benchmarks of intelligence, compiled in collaboration with NYU computer scientist Ernest Davis. To be considered artificial general intelligence, AI would need to be able to accomplish some of the following:

  1. Watch movies and tell us accurately what is going on. Who are the characters? What are their conflicts and motivations? Et cetera.
  2. Read novels and reliably answer questions about plot, character, conflicts, motivations, etc. The key is to go beyond the literal text and show a real understanding of the material.
  3. Work as a competent cook in any old random kitchen (a tip of the hat to Steve Wozniak's cup-of-coffee benchmark).
  4. Reliably construct bug-free code of more than 10,000 lines from natural language specification, or by interactions with a nonexpert user. (Gluing together code from existing libraries doesn't count.)
  5. Take arbitrary proofs from the mathematical literature, written in natural language, and convert them into a symbolic form suitable for symbolic verification.

The other of us, Vivek Wadhwa, thought the bet was terrific, fair and provocative, and something that could move the field of AI forward. So Wadhwa decided to match Marcus's wager. Within a couple hours, there was a flurry on Twitter, and Marcus's Substack had close to 10,000 views; soon, other experts in the field also offered their support to $500,000. But not a word from Musk.

See also: The Real Disruption From Robotics, AI

Then writer and futurist Kevin Kelly, who co-founded the Long Now Foundation, offered to host the bet on his website side by side with an earlier and related bet that Ray Kurzweil made with Mitch Kapor. Ben Goertzel, for decades one of the leaders in trying to make AGI into something real, rather than just a fantasy, tweeted that he thought the tests would signify real progress. World Summit AI, the world's leading AI conference, offered to host a debate. Others wondered aloud which benchmarks might fall first, and in what order.

Despite all that excitement in the AI community, there has still been no word from Musk.

Half a million bucks is chump change, of course, for someone who is perhaps the richest person in the world. But it is real money to us, and it symbolizes something important: the value of getting public voices who hype AI's near-term prospects to stand by their claims.

Spreading misinformation about the potential of AI and its likely progress may serve Tesla by diverting attention from the many problems it has with its self-driving software, but it doesn't serve the public. If Musk believes what he says, he should stand up and take the bet; if not, he should own up to the reality that his pronouncements are little more than off-the-cuff hunches that even Musk himself realizes aren't worth the virtual paper he's printed them on.

This article was written by Vivek Wadhwa and Gary Marcus.


Vivek Wadhwa

Profile picture for user VivekWadhwa

Vivek Wadhwa

Vivek Wadhwa is a fellow at Arthur and Toni Rembe Rock Center for Corporate Governance, Stanford University; director of research at the Center for Entrepreneurship and Research Commercialization at the Pratt School of Engineering, Duke University; and distinguished fellow at Singularity University.

What to Do About Rising Inflation?

Property-casualty insurers should stress test their operations and consider ways to counter potential inflation impacts on both sides of their balance sheets.

Man at a table with money, a calculator, a computer, and papers

​​Heading into 2021, projections for U.S. inflation were mixed. At least two economists were on record saying “2021 will be a year plagued by numerous unwarranted inflation scares.” For the first three months of 2021, this outlook seemed reasonable, with consumer price index inflation averaging approximately 1.9%. Then, in April 2021, CPI inflation jumped to 4.2% and climbed steadily for the rest of the year. In December, inflation eventually reached a high for the year of 7%.

The last time CPI inflation exceeded 6% was back in the late 1970s/early 1980s. Inflation during that period was partly due to surges in the price of oil, while measures taken to curtail inflation included wage and price freezes, surcharges on imports and a break with the gold standard. At the time, the Federal Reserve implemented tight monetary policies that raised the federal funds rate from 10% to 20%. While these actions resulted in a recession, the policy proved effective, and in 1982 the trend of high inflation subsided. 

Various reasons are given for the current spike in inflation, including supply bottlenecks, government policy, pent-up consumer demand for goods, imbalances in supply and demand and a lack of competition among corporations. Government stimulus spending since the pandemic has exceeded $5 trillion. Congress and the White House are still discussing additional stimulus spending. Continued availability of disposable income and hampered supply chains are expected to contribute to inflationary pressures well into 2022.

Not All Inflation Is Created Equal

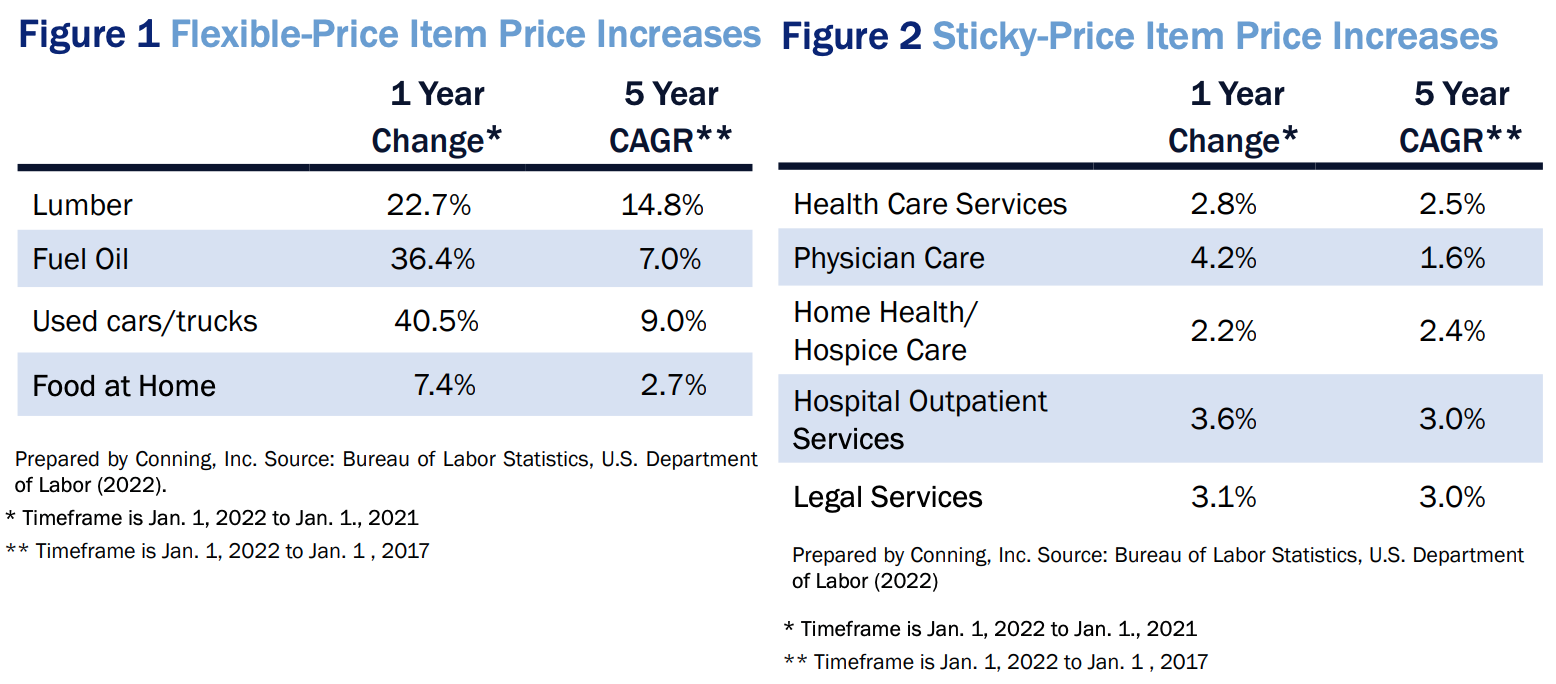
If the price changes for a particular CPI component occur less often, on average, than every 4.3 months, that component is called a “sticky-price” good. Goods that change prices more frequently are labeled “flexible-price” goods. Examples of sticky-price goods are medical care services, education, public transportation and motor vehicle maintenance. Examples of flexible-price goods are lumber, fuel oil, used cars/trucks and food at home. 

As shown in Figures 1 and 2, most of the headline inflation during 2021 has come from price increases for flexible goods. Sticky-price goods—many of which underlie liability claim costs—have seen lower than headline inflation.

Two charts showing inflation

What Does This Mean for the MPL Industry?

As with most financial institutions, higher-than-expected inflation has adverse effects on the operations and results of property-casualty insurers. 

Reserves — Insurers carry liabilities in the form of loss reserves that are intended to pay claims in the future. If inflation is higher than the rate built into the loss reserves, then future payments will be greater than expected. The impact of inflation varies by line of business, but an increase of one percentage point in inflation can raise the P/C industry combined ratio by two to three points. For personal lines of business, where liabilities are short in duration, a one-point increase in inflation may boost the combined ratio by less than one point. For a long-tailed line of business such as medical professional liability, the same one-point rise in inflation may increase the combined ratio by more than five points. 

Rates — Insurers charge prices today that will pay for future claims. For some lines of business such as MPL, claims might not be paid for 10 years or more. If inflation proves to be greater than the inflation rate anticipated in the prices charged, then insurers may not have sufficient funds to pay claims. The dynamics of underestimating the inflation rate built into prices is like that of liabilities—i.e., a one-point increase in inflation will result in overall price inadequacies of 2% to 3%. These increases tend to vary by line of business. 

Small differences between assumptions and actual inflation can have meaningful effects on the adequacy of prices. In a recent filing, a company assumed annual trend in pure premium--the combination of frequency and severity--of 0% and used a discount rate that assumed an annual return of 4% on its funds. If the assumptions were changed so the pure premium trend and the annual return on funds were both set at 2%, the company’s indicated rate change goes from an initial estimate of +34% to a revised +43%.

See also: https://www.insurancethoughtleadership.com/six-things-commentary/how-bad-will-inflation-get

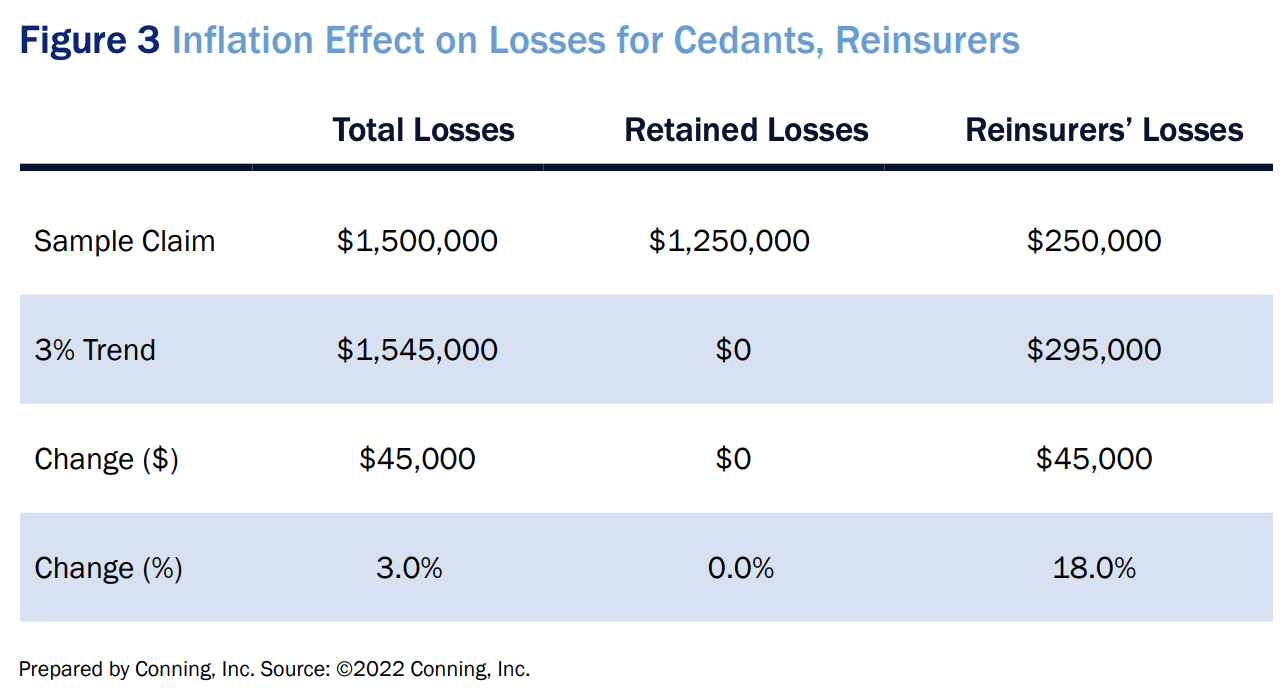
Reinsurance — Inflation affects losses in excess layers differently than losses in primary layers. Figure 3 shows a scenario where 3% inflation has 0% impact on a ceding company’s net losses but has an 18% impact on its reinsurer’s losses. Under the same conditions, an inflation rate of 5% would raise the reinsurer’s losses by 30%. The example helps demonstrate that, even in an environment where inflation is rising by low- to mid-single digits, the effect on losses ceded to reinsurers increases by multiples of the ground-up inflation rate.

Chart showing inflation effect on reinsurers

Investments — Approximately 80% of the assets held by the P/C industry are in fixed income instruments such as Treasury, municipal and other bonds. These assets are structured to match the payments--cash flows--of the loss reserve liabilities they support. If companies sell current bonds so they can invest in newer, higher-yielding bonds, they will have to book losses upon the sale because higher interest rates drive down bond prices. However, if they hold onto current assets while the ultimate values of the underlying loss liabilities are increasing, there will be a mismatch between their assets and liabilities. This mismatch would have to be accounted for by a reduction in the company’s surplus. There is no efficient way for companies to hedge inflation risk, but they can try to dampen the risk through holding assets such as stocks and real estate, which bring their own inherent risks to a balance sheet.

And We Haven’t Even Mentioned Social Inflation

Another item affecting the insurance industry that is not included in any of the indices is potentially the largest inflation factor of all: social inflation. Broadly defined, social inflation refers to all ways in which insurers’ claims costs increase over and above economic inflation. While there is a clear trend in rising claim costs for liability lines of business, the overall increase in costs has been higher than the inflation in underlying costs such as medical care and wages.

Because the factors that drive social inflation are not quantitative, measurement of social inflation is difficult, if not impossible. These factors include anti-corporate sentiment, behaviors of the plaintiff bar, changing societal views and desensitization to large verdicts. However, to the extent social inflation is contributing to claim costs, insurers and reinsurers must attempt to quantify its impact so liabilities and prices are adequate. In an attempt to quantify the impact of social inflation on commercial auto losses, the Insurance Information Institute recently performed a joint study with the Casualty Actuarial Society. The study concluded that, from 2010 to 2019, approximately $21 billion, or 14%, of commercial auto losses could not be explained by regular increases in the CPI. The authors of the study stated that they found evidence of social inflation in other liability (occurrence) and medical professional liability (claims-made), but they did not provide measurements for these lines of business.

See also: Insurers' Social Inflation Problem

Inflation’s Bottom Line 

The CPI and other economic indices such as the Producer Price Index are valuable resources, but arguments have been made that these indices have inherent flaws that can distort their measures of inflation. For example, the CPI is heavily weighted toward urban consumption and may not be an accurate measure of the price of goods for suburban and rural areas, where prices may be higher due to distance from production centers. The CPI is also criticized for not representing the innovation of products that could be years away from inclusion in the calculation of the CPI. 

The 7% increase in inflation in 2021 has captured many headlines, and market expectations suggest inflation rates are likely to remain higher over the near term. January 2022 CPI increase was 7.5% and February 2022 increase was 7.9%. According to the February edition of the Federal Reserve Bank of Philadelphia Survey of Professional Forecasters, headline CPI in 2022 and 2023 will be 3.8% and 2.4%, respectively. While insurers have been raising prices in response to rising costs, it remains to be seen if increases in loss reserves will follow. For the past 15 years, the industry’s carried liabilities for MPL have been above average in terms of redundancies. However, if inflation is greater than anticipated in the reserves, these redundancies can turn into deficiencies. As such, property-casualty insurers should be stress testing their operations and considering strategies to counter concern about inflation and potential impacts on both sides of their balance sheets.

This article previously appeared in Inside Medical Liability magazine.


Bill Burns

Profile picture for user BillBurns

Bill Burns

Bill Burns, ACAS, MAAA, is a director in Conning’s research and consulting group, where he is responsible for producing research and strategic studies related to the property/casualty industry.

Prior to joining Conning in 2017, he was most recently the vice president of reinsurance reserving for Everest Reinsurance. Burns has over 25 years of property/casualty insurance and reinsurance experience, including as a consultant for a Big 4 firm and a reinsurance broker and as the chief actuary for two medical professional liability companies.

Burns is a graduate of Seton Hall University with a B.S. in mathematics. He is an associate of the Casualty Actuarial Society and a member of the American Academy of Actuaries.


Lauryn Kothavale

Profile picture for user LaurynKothavale

Lauryn Kothavale

Lauryn Kothavale is an assistant vice president at Conning, where she is responsible for providing production support, statistical data, research and analysis for the property casualty and life and health research and consulting teams.

Prior to joining Conning in 2020, she worked in finance and operations at Travelers.

Kothavale graduated from the University of Central Florida with a B.S. in business management. She received an advanced business certificate in digital marketing and earned an MBA with concentrations in marketing and management of technology from the University of Connecticut.

Why Everyone Wins With IaaS

Insurers and their distribution partners must evolve and convert new customers where they already choose to spend their money, no matter where that is.

Low angle view of an office building

During a 2017 first quarter earnings call, FedEx founder and CEO Fred Smith famously doubted that we would ever do most of our shopping online, saying of e-commerce’s share of retail sales, “It’s about 10% now. It’s certainly going to grow as a percentage. But will it be half? I doubt it.” It took fewer than two years for the U.S. Department of Commerce to issue a report proving him wrong. 

Smith was hardly the first to underestimate consumers’ voracious appetite for convenience, and he’s unlikely to be the last. But a growing body of empirical evidence across sectors paints a picture that shouldn’t come as much of a surprise: Many of us lead impossibly busy lives, and convenience is not just a “nice to have”; it supersedes brand loyalty -- and even cost -- as a deciding factor for a growing majority of modern consumers. 

This desire for convenience translates into a massive opportunity within the insurance sector, and not just for insurance companies. A study conducted by Bindable in 2021 showed that 65% of consumers would be willing to purchase insurance through a non-insurance brand, and, of those respondents, a large majority would actually prefer to do so if they already trusted the brand in question. Placing a complementary insurance product in front of prospective customers at precisely the time and place they need it, and while they’re interacting with a brand they already trust, is not only how insurers will stay relevant but also how brands can improve customer loyalty and retention in a competitive market.

Get Strategic About Selling

Potential insureds generally want to think about insurance as little as possible, which is one of the reasons why customer acquisition costs (CAC) are disproportionately high. This is also why insurers and their distribution partners must evolve and convert new customers where they already choose to spend their money, no matter where that is. To do so, they must strategically cultivate alternative distribution channels, optimize digital environments and provide superior technology and tools to agents, which is exactly where Insurance-as-a-Service (IaaS) offerings come into play. 

What Is IaaS? 

IaaS combines software, a digital marketplace and a full suite of support services to create flexible, market-ready solutions that connect insurance providers, trusted brands and consumers for the benefit of all. 

It’s a mechanism by which insurers can increase visibility and distribution (and potentially reduce CAC) by enabling partners to leverage an established network of insurance companies and introduce fully branded digital insurance propositions into their existing ecosystem -- all while staying in control of their brand story, expanding their value proposition and driving monetization with minimal to no friction, lead time, infrastructural investment or guesswork. IaaS enables carriers and brands to increase their digital delivery capabilities, streamline sales processes and optimize insurance offerings through sponsored channels.

See also: Why SaaS Is Key in Core Systems

Insurance Distribution, Redefined

With some earnings reports looking ominously grim, corporate budgets could potentially be tightening across the country in response to the anticipated downturn, and marketing budgets are often the first to be slashed. As mentioned, customer conversions within the insurance space are already notoriously expensive, but a product you can’t market, no matter how artfully designed, dies an ignoble death – so how can carriers stretch those dollars and minimize financial risk?

Simple: Partner with brands consumers already trust and embed the offer where they’re already shopping, at the moment of peak relevance. This could mean partnering with an employer, a financial institution, a consumer brand or even another insurance carrier; every industry is trying to improve customer acquisition and retention, so there is opportunity everywhere. 

For example, mortgage companies will find that many customers value homeowners insurance offers incorporated into the preexisting purchase flow, especially during what is likely to be a busy time for the homebuyer. Similarly, how many drivers would welcome the opportunity to drive off the lot by getting auto insurance coverage on the spot without having to start a separate process? Insurance might not be a brand’s main product, but, if it’s an adjacent offering, it’s never bad business to create added value for customers (as long as you keep their convenience in mind). 

What’s in It for Insurers?

As any insurance provider can tell you, one carrier does not want every risk, especially in a hardening market. By having a choice environment, even if the customer usually shops with one provider, when the provider doesn’t have an option for that consumer or doesn’t want to take on the risk they can offer an alternative solution through another provider; this is what we like to call “coopetition.” Such an arrangement also gives carriers the ability to present other relevant ancillary products that they might not currently offer. Instead of always trying to say “yes and…”, a provider can do what’s best for their business yet still provide an elevated experience for their customer by saying “no, but…” and still meet their needs through other options while owning the relationship with the customer. 

Leveraging an IaaS-powered marketplace or implementing an embedded insurance offer also enables a provider to control their customer experience. Contrary to using lead generation partnerships or aggregators (which can often be quite expensive), using an IaaS approach enables a brand to not only provide a better branded experience -- from the front end to agent service experience -- the brand can also gather data on their customers, understanding what they’re buying and when. If there is an opportunity to sell differentiated products, that provider can make an informed decision before committing to the heavy lift that entails.

Through IaaS, you can create a seamless online-to-offline experience that leverages your brand to sell insurance through digital channels (including embedded insurance offers) or via licensed agents over the phone, giving customers the choice of products they need, delivered in the manner they prefer, under a name they trust: yours. Enrich relationships with current customers and convert new ones, all while saving time and money and gathering invaluable data; there are no losers in this story. 

A Win-Win-Win

Today, we know one thing to be unequivocally true: Convenience is king. If providers want to stay relevant, they must adapt quickly and think innovatively, especially when it comes to distribution channels and technology, to meet consumers’ evolving needs. Working with brands that consumers already trust can build brand equity and minimize CAC, creating a mutually beneficial, omni-channel solution for insurers, distribution partners and potential insureds. Everyone wants a win – and, with IaaS, everyone gets one. 


Bill Suneson

Profile picture for user BillSuneson

Bill Suneson

Bill Suneson is the co-founder and CEO of Bindable, a national leader in digital insurance and alternative distribution technology. He also co-founded and serves on the board of Next Generation Insurance Group, which operates GradGuard.

There Is No 'I' in 'TEAM'

But there is an 'i' in 'WIN.' Let’s talk talent. Let’s talk football.

football team in a huddle

My columns for Insurance Thought Leadership share best practices from outside insurance. For example, Amazon in digital customer experience, and AWS in large program management. Sticking with the A's, this piece on talent is from outside tech altogether: Alabama Crimson Tide football. 

For readers unaware, Nick Saban is arguably the most successful college football coach in the history of the sport. Mr. Saban owns a 269-67-1 career record, and his seven national championships--one at LSU and six at Alabama--are the most all-time. 

Winning, Saban would be the first to tell you, requires talent. Alabama has landed the top recruiting class in eight of the past 13 years and was top three in the other five. Success breeding success, today Alabama practically sells itself to top recruits, players interested in practicing against, and playing with, the best, toward winning championships and a lucrative career in the NFL.

But it wasn’t always that way. Saban inherited a Crimson Tide program that went 6-7 in 2006. “We’re going to build a winning culture here,” he said in his introductory press conference. “A culture that winners will want to be a part of.” Saban rightly put the horse before the cart: culture draws talent.

Here are three aspects of Alabama’s winning culture that can help you build and shape yours.

1. Think process, not outcomes.

“We don’t think or talk about winning the SEC Championship. We don’t think or talk about winning the National Championship. We don’t think or talk about the result, but what needs to be done to get the result,” Saban said in a recent speech. “What do you need to do in this workout? This drill? This play? In this moment? Let’s think about what we can do today. The task at hand.” 

Controllable inputs, in other words, over desired outputs. Right action; detachment from result. 

2. Alabama’s process in three steps:

  1. What’s the vision?
  2. What’s the plan to achieve #1
  3. Do we have the discipline to follow #2?

This is where leadership comes in. It’s on you as a CxO, LOB head or Program Owner, to spell out the vision for your players. It’s on you to map the plan for getting there. And it’s on you to define roles and responsibilities and manage to them. Remember, winning culture is formed from high standards, firmly enforced. 

Saban’s vision of football excellence is a lot easier to articulate than yours. It’s for the most part implied. Everyone knows why they’re there. But finding the right “why narrative” is a must for attracting top talent, and in insurance the “why” is not implied. Here’s what we’re doing. Here’s why it matters. Here’s how we’re going to do it. And here’s where you fit in. You must define it, spell it out. 

See also: 3 Keys to Leading a Team in a Crisis

3. After process, people.

Alabama doesn’t recruit every five-star player who can run a 4.3 40-yard dash. Nor do they automatically pass on three-star players. Mac Jones, who led Alabama to a 13-0 record and National Championship in 2020 and is now starting quarterback for the New England Patriots, was a three-star recruit. 

The tangibles matter. In football, speed, height, athletic agility can’t be coached. Likewise, five-star business and especially digital talent just jumps off the page of the CV. Elite developers can do things mortal developers cannot; a ninja coder can often do the work of 10, and in half the time, creating a cleaner, more elegant solution. 

But the intangibles can’t be overlooked, either. On a team level, respect and trust are key--to the organization, the structure, the standard, each other. Beware chemistry wreckers. 

On a personal level, look for players with character, who work to get better and have a proven track record of working through adversity to get the job done. A favorite Sabanism: “It takes no ability to be mentally tough and finish.” Look for players who are mentally tough and finish. Mac Jones, while biding his time, waiting his turn to start, not only mastered the playbook but earned his degree in three years, masters in four, with a 4.0 GPA. 

In the three-step process that Saban drives at a program level, he looks for players to define for themselves on a personal level. What’s your vision for yourself? What’s your plan for getting there? Are you following that plan--or are you just talk? He develops players by holding them accountable to their own words. 

And he develops teams one player at a time. Alabama carries 85 scholarship athletes on their roster. That’s a lot of talent, a lot of egos, to manage. Whatever else is going on, Saban makes it a point to meet one-on-one with at least three players a day. “It’s about them--always. Not you,” he says. “People gotta know you care; that you’re a leader, not a manipulator. That you’re here to help them get what they want--which you know because you talk to them.

“There’s a misconception out there that the culture is somehow going to magically make players better. But that’s wrong. It’s the players and their daily behaviors that make the culture. There is no ‘i’ in 'team,' but there is an ‘i’ in 'win.'”

In 2007, Saban’s first season with Alabama, the Crimson Tide went 7-6. In 2008, they went 12-2. In 2009, they went 14-0, winning their first championship under Saban. Winning championships takes time. Building a championship culture, which attracts championship talent, starts today.


Riv Arthur

Profile picture for user RivArthur

Riv Arthur

Riv Arthur is a business leader and technologist working in insurance, healthcare, and private equity.

Identity Management: the Future of Marketing

Identity management involves reconciling what you know about an individual with real-time behavioral data, specifically actions that signal purchasing intent. 

five people around a computer at a desk

According to Google, 90% of owners of multiple devices switch between screens to complete tasks. So, the importance of being able to accurately identify consumers across devices and marketing channels – or identity resolution – cannot be overstated. This is especially true in industries like insurance, where shopping journeys typically involve extensive research and comparison shopping over time.  

There’s a high cost to unidentified consumers. Failing to invest in identity resolution leads to canned messaging, wasted marketing spending and lost opportunity to cross-sell and up-sell existing customers.

Today’s shoppers demand personalization. The logical next step to identity resolution, then, is using the additional data that comes with it to improve the customer experience in a process called identity management. 

Identity and Experience

Identity management involves reconciling what you know about an individual – static demographic information, such as income, as well as personal attributes like existing vehicle and homeownership – with real-time behavioral data, specifically actions that signal purchasing intent and tell marketers and agents it’s the right time to engage. 

This sort of data is useful for nurturing both prospective and existing customers. Consider an auto policyholder. Are they homeowners? Do they have children in the household who will be driving soon? Do they also own boats, motorcycles or second homes? Does their recent online shopping behavior indicate any of these attributes have recently changed?  

In essence, identity management centers on knowing who a consumer is as well as what they’re in search of and putting that knowledge to work. While this may seem obvious, for every $92 spent on acquiring customers, on average, only $1 is spent on converting them. Investing resources in lead nurturing and personalized messaging can be a significant differentiator. 

See also: 10 (Lame) Excuses for Not Marketing

Identity and Optimization 

Reliable data is the first requirement of effective personalization. Automated identity resolution solutions layer identity markers, or information like an email or IP address, with third-party data to fill in the holes, so to speak, on a given customer profile. Third-party data can include demographic details and personal attributes as well as real-time shopping behavior. In either case, third-party data extends a company’s view of a customer beyond the data it already has. 

Though most insurance providers have mountains of data at their fingertips, that data is often spread out among internal systems and tools, leaving providers without a singular 360-degree view of the contacts in their CRM systems. It can be time- and resource-intensive to disrupt these data silos, but getting your own first-party data in order is essential to making the most of identity resolution tools and leveraging additional data for identity management. 

In addition to lead nurturing, identity management also supports lead scoring. Take property and casualty. Our collective return to work (and thus return to commuting), recent supply chain challenges, even an uptick in catastrophic events due to climate change are all driving up the frequency of and severity associated with P&C claims. In return, P&C insurers are dialing back customer acquisition efforts until they’re able to increase rates to be commensurate with today’s risk. Concerns about risk only strengthen the case for identity management, as it allows marketing and sales teams to dedicate the limited resources they have to identifying and working the most profitable leads, while they pass on targets that do not meet the profile of ideal customers.

Identity and Privacy 

Any discussion on consumer data should also include a note on consumer privacy. Insurers must confirm each and every customer has given their consent to be contacted, to remain compliant with consumer privacy regulation like TCPA (the Telephone Consumer Protection Act). When purchasing lead data from a third party, marketers must verify that their lead partners have also complied on their behalf, as the courts have made it clear both parties are ultimately responsible. Marketers and agents should be prepared to demonstrate compliance in the event of a consumer complaint. 

All that said, compliance is the bare minimum. With great data comes great responsibility. Consumer data must be managed with great care. Not only because it’s good for business but because it’s the right thing to do. Retail giant Target offers us a cautionary tale – years ago, it detected a 16-year-old’s pregnancy based on her shopping behavior and mailed her maternity-related marketing materials before she shared the news with her parents, creating a PR nightmare for the company and an unfortunate breach in privacy for the young woman. 

To be effective, identity management strategies must balance what’s technically possible with what’s feasible and optimal from a business perspective. A thoughtful approach and reliable partners will empower insurers with more accurate, comprehensive customer data and the ability to communicate with the right customers at the right time and with the right message.

How to Help Children Deal With Trauma

It is important for parents and caregivers to restore a sense of safety to their children even when the world does not feel safe.

Two people sitting down with a child

Recent events have highlighted the impact of violent, traumatic events on our daily lives. Trauma refers to an event, series of events or set of circumstances that are experienced by an individual as physically or emotionally harmful or life-threatening and that have lasting effects. Exposure to traumatic experiences creates emotional challenges for children of all ages. 

Parents and caregivers have the added worry of how to support their children in the aftermath of traumatic experiences. It is important for parents and caregivers to restore a sense of safety to their children even when the world does not feel safe. Adults can support the children in their lives by understanding the impact of traumatic events and knowing specific actions that can bring a sense of comfort and safety. 

Children respond to violence and trauma in a variety of ways; however, there are several typical responses. These responses vary, depending on numerous factors, including the following: 

  • the child’s age
  • whether the child knew the individuals involved
  • whether the child directly witnessed or indirectly heard about the incident
  • how “graphic” the violence was
  • how extensively the media covered the event 
  • if the child has previously experienced exposure to trauma. 

Representative Common Responses to Trauma Include: 

  • Concerns about fearing that the affected person or people suffered
  • Repeatedly visualizing the crime or incident in their minds 
  • Constant attempts to tell and retell the story of the crime or incident 
  • Need to reenact the crime or incident through play 
  • Feelings of guilt for not having intervened or prevented the crime
  • A desire to seek revenge [for those who knew the victim(s)] 

Signs of Grief in Children Parents Should Watch for After Traumatic Exposure

For parents and caregivers, it is important to observe children exposed to trauma for signals of grief after a violent crime or incident. For some children, particularly those who knew the victim(s), these grief signals may include:

  • Fear of death 
  • Fear of being left alone or sleeping alone 
  • A need to be with people who have been through the same experience
  • Difficulty concentrating 
  • Drop in grades (during the school year) 
  • Physical complaints, such as headaches or stomachaches
  • Bedwetting 
  • Fear of sleep 
  • Nightmares 
  • Clingy behavior and wanting to be with and around parents more often

How to Support Children When They’ve Experienced a Traumatic Event

Ask what they think happened: Let them tell you in their own words, and answer their questions. Do not assume you know what they are feeling or what their questions will be. The easiest way to have this conversation might be while they are engaged in an activity, such as drawing, sitting on a swing or driving with you in the car. Details that may be obvious to adults may not be apparent to children. Be truthful, but don’t tell them more information than they can handle for their age. 

Focus on their safety: Once you understand their perception of the traumatic event, be clear that you will keep them safe and let them know other adults (school, police, etc.) are working hard to make sure they will stay safe. 

Pay attention to your reactions: Your children will be watching you carefully and taking their cues from you. If you can manage your anxiety about the traumatic event, your children will be more easily reassured. 

Monitor your child’s access to media: It will help if young children do not watch news reports or see the front page of the newspaper. Young children who watch a traumatic event on the TV news may think the event is still going on or happening again. 

Watch for behavior changes: Your children may show you through their behavior that they are still struggling with what they have heard or seen. They may have physical complaints or regressive behaviors, often including nightmares, insomnia or bedwetting. They may feel guilty that they are responsible for the event and need to be reassured that they are not responsible. 

Maintain your routines: Sticking to your daily structure of activities -- mealtimes, bedtime rituals, etc.-- reduces anxiety and helps children feel more in control. 

Keep the door open: Encourage your children to come to you with any questions or concerns and do not assume the questions will stop after a few days or up to several weeks. Let them know their fears and questions are normal and you will always be available for them. Remind them that all questions are welcome. 

Consider this a teachable moment: For older children, this traumatic event may lead to a discussion about ways they can help others who have experienced a tragedy. You can also ask them if they know how to keep themselves safe when they are away from home. Traumatic events make us feel like we have lost control, so any constructive activities we engage in make us feel less vulnerable.

See also: Workplaces Coping With Suicide Trauma

Tips for Talking to Children Witnessing or Hearing About Traumatic Events

For children who have witnessed violence, either directly or through media exposure, talking with them in an informed, age-appropriate manner can help them process what they’ve seen. Below are representative pointers to consider for these conversations: 

  • Allow your child to talk about what he/she experienced or heard about 
  • Know that younger children may prefer to “draw” about their experiences 
  • Ask them what they saw and heard and what they think about the experience 
  • Help them to label feelings and normalize their reactions (“That must have been pretty scary. It wouldn’t surprise me if you keep thinking about it.”) 
  • Keep routines as much the same as possible in the aftermath -- children count on routines and structure
  • Spend extra time with your child: have dinner together, make sure to keep bedtime routines, share playtime or take walks together
  • Remind your child of things he/she likes to do to help feel better when upset (playing, reading, drawing, singing, etc.) 

Steps for Employers to Help Employees Understand the Effects of Trauma on Children

The growing frequency of traumatic incidents has necessitated the expansion of crisis management and emergency response plans for organizations of all sizes. The importance of instituting Critical Incident Response protocols cannot be overstated, including stress debriefing and grief counseling. Often, community-wide services are coordinated in the aftermath of violent, traumatic events. Employers are encouraged to promote these services to their employees and ensure they feel supported to be able to attend these events. 

Employers increasingly are adopting trauma-informed approaches to wellbeing and understand the importance of addressing the harmful effects of trauma on affected stakeholders. Employers are encouraged to share information with workers about how to communicate with children in their lives about traumatic incidents. Parents and caregivers are encouraged to seek professional support from licensed practitioners when children do not respond to their intentional efforts to address the effects of trauma.


Calvin Beyer

Profile picture for user CalBeyer

Calvin Beyer

Cal Beyer is the vice president of Workforce Risk and Worker Wellbeing. He has over 30 years of safety, insurance and risk management experience, including 24 of those years serving the construction industry in various capacities.