Download

An Interview with Jenn Knight

Jenn Knight, co-founder and chief technology officer of AgentSync, lays out an approach that seems like it should be obvious but that somehow isn't. Her approach to attracting and retaining talent? Stop driving it away. 

She explains how companies can use technology to onboard talent faster and more efficiently and remove much of the drudgery from their work that can make them seek greener pastures in other industries. 

An Interview with Jenn Knight

ITL:

In general terms, how would you frame the talent gap that the industry faces?

Jenn Knight:

We really need to be thinking about how we as an industry start to bring people in, in their early 20s, late 20s, early 30s. The way that a digital native operates is different than how I've operated through my life and how generations before us have operated. And figuring out how to be an attractive employer to a group of people that do not look like those currently working for you is a pretty significant challenge. How can you be compelling for them?

ITL:

As a relative latecomer to insurance, it amazes me to see all the people who say they just fell into insurance. I mean, it's a great industry offering great careers. How do you get people to see that?

Knight:

There’s a macro question here. How do you do that for any industry? Right? How is it that we've just decided that tech is cool? Where did that start?

Insurance is a really complicated, fascinating space that supports all of us as consumers in the hardest moments of our lives. If your house catches on fire, the first call is to the fire department, and the next call is to your insurance agent. Like the fire department, insurance is an emergency service that helps you get on with your life. If you frame the industry that way – which nobody did to me until I worked in insurance – it can become something you love and want to do for 10, 20, 30 years.

ITL:

Beyond the framing issue, what are some other challenges to filling the talent gap?

Knight:

There is a technology gap that has to be addressed. People are turned off if they feel they can’t drive enough impact because it's too difficult to go through the onboarding process or to engage with a certain set of carriers, or compliance with regulation is causing most of your day to be administrative.

Before I worked in insurance. I worked primarily in the back office of scaling tech companies and supported sales. The whole job is getting information you need from sales, supporting them with the information they need and getting out of their way so they can be on the phones.

In the insurance space, agents are going to be attracted to things that help them go out and have those personal relationships and really drive their business forward. How do we as an industry laser focus on improvement of administration work? Talented people demand that they are supported and enabled with effective and usable technology, and are not being dragged through all kinds of hoops.

ITL:

People who’ve written for us say that, in the old days, you got onboarded by sitting next to somebody who was 20 years older than you. You said to the person, over and over again, Okay, how do I do this? But talented people today aren’t willing to sit there for two years and learn. You also can’t wait two years for people to become productive. As you speed the onboarding process, are there problems you’re finding easier to solve than others?

Knight:

Everything in the insurance space is somewhat hard to solve. One thing we focused on early is “productizing” institutional knowledge. It's a continuing process because there are so many layers of complexity. But we started with some core aspects, such as, What are the rules you have to follow to get someone licensed? Well, those rules are different by state, by line and by license class, but the issue is something we can tackle.

We thought: Can we build a product that someone who's been doing a job for 20 years can use successfully and appreciate because it speeds them up? Can we take someone who’s new and let them quickly figure out if their five agents are compliant?

There are complex scenarios where you need to sit down and talk with someone or do some deep reading, but even that work can be supported with technology. We've started with situations, such as licenses for adjusters, that are more consistent and are working our way up to more complicated forms of knowledge transfer.

The change can actually be a bit disconcerting for people. They’re used to having to know all this stuff, down to the LOA code numbers, and we’re saying, but you don't have to do that.

ITL:

For a long time, lots of people thinking about innovation in insurance said the solution was to disintermediate the agents. Just get rid of them. Now, people seem to be realizing that the agents aren’t going anywhere.

Knight:

Yeah, we're big believers in the power of the agents. Insurance is super personal. Some of it is more mechanical – I don't get as worried maybe about my car insurance. But agents are here to stay, and that’s a great thing. The question is: How do we make sure they’re doing strategic relationship-building work and not operational, tactical, administrative work?

If you're not actively thinking about yourself as competing for the best talent, then you're probably doing it wrong. You can no longer just be this name and assume people are going to come to you.

It’s getting easier for your competitors to poach your people, too, because LinkedIn makes everyone and their talents so visible now. But the reaction shouldn’t just be fear. If you’re creating an environment where people want to be and you're celebrating their successes, and you're comfortable with them being out there as advocates for your company, they can help you attract that next wave of talent.

More openness, more celebration of people is better for everyone overall, and will help people maybe be more attracted to insurance as an opportunity.

ITL:

In Silicon Valley, there’s a maxim known as Joy’s law, after Bill Joy, one of the founders of Sun Microsystems. It says: “No matter who you are, most of the smart people work for somebody else.” You can fight Joy’s law or learn to live with it.

One last question: While lots of companies are focused on improving the customer experience – as they should be – it seems that the work-from-home experience during the pandemic has created a break point in how people think about the work environment and that smart companies can redesign the employee experience, too, in ways that can address the talent gap. Do you agree?

Knight:

I couldn’t agree more. At the end of the day, the person who is going to make or break your experience with insurance is the person you’re talking to. So, you need to focus on having engaged, happy, supported agents who are getting opportunities to learn more and be better partners who create better experiences for your consumers.

Agent experience empowers customer experience.

ITL:

Thanks so much for taking the time.

About Jenn Knight 

Jenn is the co-founder and CTO of AgentSync. With skill sets that encompass both left- and right-brained thinking, Jenn enjoys tackling the biggest challenges she can find.
Jenn Knight's headshot

Her passion for solving the unsolvable has put her at the forefront of solving the producer license compliance challenges of the insurance industry. After building the basic architecture of what would become AgentSync Manage in her free time on nights and weekends, Jenn's side project grew into a software enterprise that is poised to change the way the insurance industry tackles license compliance and reporting.

Jenn's background leading software development and architecture teams spans many well-known companies, among them Bluewolf, LinkedIn, Dropbox, and Stripe. She focuses on transforming business applications landscapes from disjointed single-point solutions to highly integrated, optimized, and best-in-class platforms. In those roles she learned the importance of building community while tackling difficult business challenges, as trust and humor are essential to navigating the ups and downs of delivery. She is grateful to those who helped her appreciate the journey is just as important as the outcome and works to pay that forward with her team.

Jenn earned a Bachelor of Arts degree in international relations with a minor in French and graduated magna cum laude from Boston University. She learned to code at her first job after college, and rediscovered her knack for logic and problem solving.

Growing up in Petaluma, California, Jenn spent her childhood biking through fields and tinkering with projects. With access to a computer at an early age, Jenn enjoyed deleting files to take apart the operating system before then going and rebuilding it.

As a leading woman in tech, one aspiration Jenn has for AgentSync is to challenge the industry to be better by example when it comes to hiring and maintaining a culture of diversity and inclusion.

When Jenn isn't solving big problems with intuitive solutions, she spends her time with her husband and co-founder, Niji, and their daughter, Inga.



Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

Is Insurtech Over?

Stock prices for marquee names have plunged, and venture capitalists are raising red flags about inflation and possible recession. But don't despair. 

Image
a red and blue computer generated graphic representing the fall of stock prices

With the stock prices of marquee insurtechs such as Lemonade, Hippo and Root down as much as 95% from their peaks, doubt has been growing for some time about the future of the insurtech movement. Concerns have accelerated as Policygenius laid off 25% of its staff, and as venture capitalists talk about how inflation and the threat of recession are putting pressure on startups across all industries. There is even talk of -- perish the thought -- down rounds (in which startups will have to raise money at lower valuations than they previously held).

So, what does the future hold for insurtechs?

I wrote at the end of January that I thought the future was still bright, especially for insurtechs that serve as what Silicon Valley calls "arms suppliers." Even though so much of the valuations of dot-com companies turned out to be air during the internet bubble of the late 1990s, companies that supplied the "arms" -- servers such as those from Sun and IBM -- still thrived. The same should be true for insurtechs, I reason: There will always be a market for technology that makes insurers smarter and more efficient.

Rob Moffat, a partner at Balderton Capital in London, now weighs in with a smart piece I wanted to share on the outlook for "full stack" insurers such as Lemonade. The headline: "Reports of insurtech's death are greatly exaggerated...."

He goes into some detail on the reasons for the plunges in stock price -- high loss ratios, poor unit economics and slowing growth, as the companies try to deal with those loss ratios and unit economics. (For more detail, check out the smart analysis Matteo Carbone has been publishing with us for years.)

Rob is nonetheless optimistic because:

"There are a number of private insurtech businesses reaching real scale: Zego, ManyPets, Next Insurance, Ethos Life, Alan, Atbay, Coalition, etc. Having seen some of their numbers, I can say that their loss ratios are good, their unit economics are sensible and they are growing strongly. They are achieving this through great execution, and some combination of the following:

  • Addressing new markets that didn’t exist before, such as cybersecurity
  • Using telematics and novel data to meaningfully reduce losses and fraud
  • Targeting underserved segments such as SMEs and the self-employed
  • Operating in ‘easier’ lines of business where there is less competition and loss ratios aren’t as tight as in home and motor, such as pet insurance."

He says others can prosper, too, based on the key lessons that we've learned about insurtech, which include:

  • "Underwriting is crucial. As an insurtech, you start with the disadvantage of not having a base of loyal good customers. Where are you using tech to give you a real edge over incumbents? But also do you have enough actuarial talent and data to complement this?
  • Telematics (real time data) works. Whether in motor or health insurance, telematics data has repeatedly demonstrated the ability to reduce loss ratios. As data collection becomes cheaper and universal, expect telematics to become widespread across many insurance lines....
  • Your unit economics have to work. This starts with a good loss ratio, and requires you to have happy clients who stay with you. It also requires you to have a good customer acquisition cost, which in insurance is never easy.
  • Automation will bring down expense ratios dramatically, but only at scale.
  • Brokers are very hard to dislodge. Many startups have tried to bypass brokers without success. Some of the large private insurtechs above have ended up building a successful broker channel.....
  • Disrupting a large sector takes time. Disruptors start off being worse than incumbents in all respects other than one really crucial one. Look at the early days of SaaS or Fintech for examples."

In terms of the Gartner Hype Cycle, insurtech is in the Trough of Disillusionment, having passed the Peak of Inflated Expectations, but we've all seen what happens next in these technology-driven cycles: Real progress happens for those who stay the course. 

Cheers,

Paul 


Auto Insurance in the Hyperconnected World

Telematics is becoming a necessary capability for dealing with the future of insurance, especially in auto, and capabilities will only grow from here. 

Map of Earth lit up

Telematics enables insurance to be done in a smarter way. Telematics data can be made available as a core component of the analytical rating engine, personalizing pricing. The same data can be used to make personalized appeals to customers as a retention tool, when it’s the right time to do so.

Insurance carriers will better understand their customer profiles and risks, improving sales and profitability, thus making the use of telematics data a concrete opportunity in all geographies.

The U.S. market has focused on using telematics data to enable continuous underwriting that personalizes pricing. We believe this approach will help usage-based insurance (UBI) move to the next level of adoption, convincing motor insurers that driving data is more than just longer something to experiment with because some of the competitors have it. Today, it’s truly an element that cannot be disregarded.

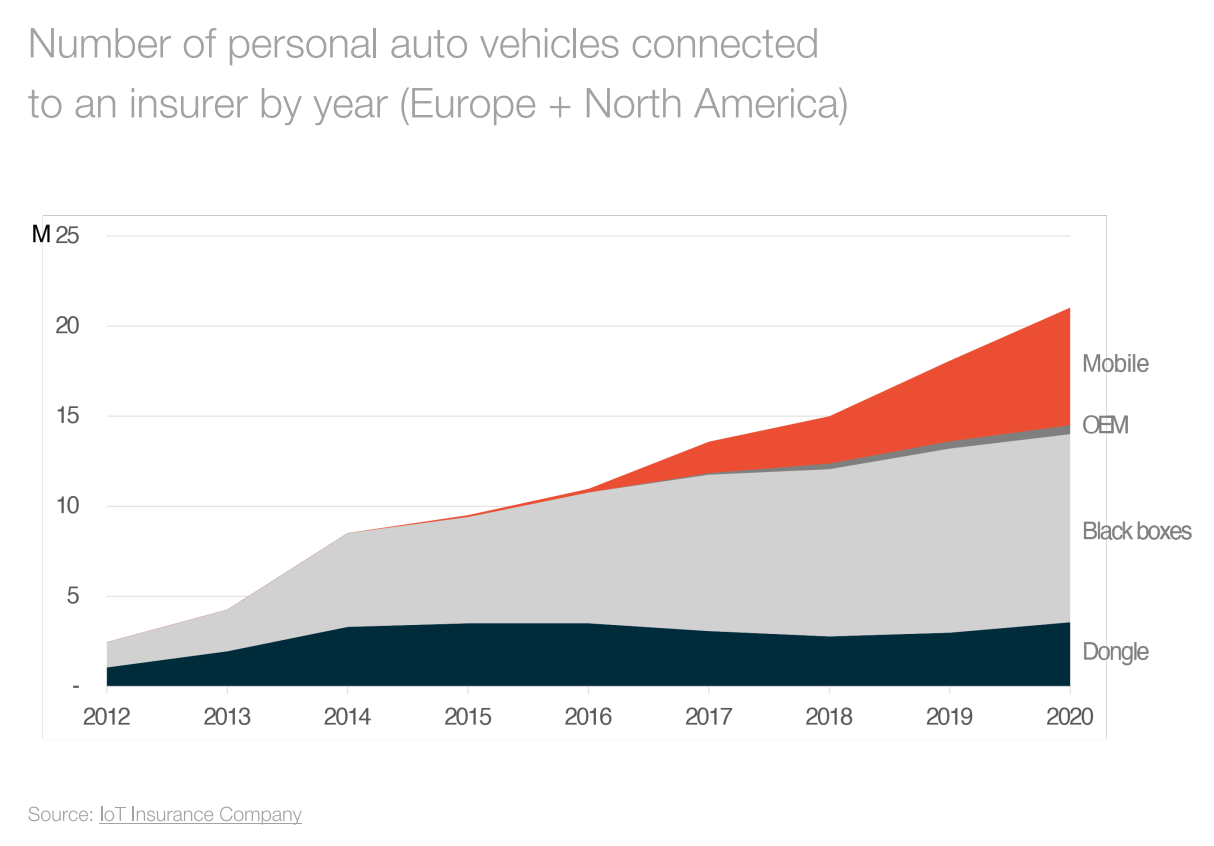
Chart showing personal auto vehicles

Some insurers worldwide have already successfully introduced a wide range of telematics-based applications. However, motor insurance telematics is still at the beginning of the development curve. Based on IoT Insurance Observatory research, there are fewer than 10 insurers globally with a portfolio bigger than one million telematics-based policies.

In Europe, usage of telematics data has not yet scaled to full potential, and still is rarely used to assess driver risks for modeling. UBI is either a small niche or telematics usage is limited to risk selection and claims management, where it has scaled. The two most advanced markets have been Italy and the U.K., with recent developments in Germany.

In the U.K., UBI is still considered a product for young drivers. In the Italian market, telematics was already present in 22% of the personal motor policies at the end of 2021. Italian personal auto insurance is still globally in a leading position regarding telematics portfolio size, value proposition toward its customers and demand for such services. Many insurers have mastered the use of telematics for self-selection of risks, for claim management and for delivering services to policyholders.

European markets can leverage the recent development in the U.S. market, where the transition to the less expensive, mobile phone-based approach has driven penetration and made the business cases more sustainable. 

The opportunity for telematics will only grow. Consumers love to interact with their smartphones, and digital tools and large tech companies are addressing consumers' needs based on the collected data with highly targeted offers, which consumers seem to like. Carriers' experience will mature, and the cost of technology will keep dropping, making it even more accessible. Data sources will increase, too, letting carriers create a powerful mix of elements and better assess driver risks.

We believe that telematics is becoming necessary for dealing with the future of insurance and that there is a concrete opportunity to use it to operationalize any motor book of business!

Want a Brighter Future? Just Write It

How can you prepare for the opportunities of a world going digital while avoiding the pitfalls that kneecapped Kodak? The answer is a tool called a future history.

Image
two hands writing in the notebook on a desk there is also a smartphone, a cup of coffee. two notebooks, a pen and a pair of glasses on the desk.

In last week's Six Things, when I wasn't simply luxuriating in the notion that I had just given a talk in a palace ballroom on an island in Prague, I laid out my basic theory of what happens when an industry goes digital: It gets stripped down to its essential parts, which can then be rearranged in any number of ways that need not have anything to do with the way things had always been done.

The example I used was photography, whose analog form involved a dedicated camera, film, chemicals, special paper and maybe little yellow boxes from a Kodak one-hour lab, but whose digital form just consists of an image and a way to share it. I noted that, while the digital form of photography sucked almost all the value out of Kodak, it allowed images to be incorporated in new ways in Facebook/Meta, TikTok, Pinterest, YouTube, texting and a host of other apps whose value far exceed what Kodak's used to be. 

I then said that insurance, stripped down to its essentials, consists just of a customer, a yes/no mechanism that determines whether a payment is to be made, and capital -- and that, as the industry becomes increasingly digital, those three elements may take on very different forms, whether through embedded insurance, parametric insurance, direct access to capital markets or any number of other possibilities.

But enough with the back story. That was last week. This week's question is: How can you organize your thoughts about the possibilities that will open up to you as the industry keeps digitizing while avoiding being Kodak-ed?

The answer is a tool called a future history.

The concept stems from a book that Chunka Mui and I wrote, Billion Dollar Lessons, on what can be learned from corporate failures. Jim Collins had done books on the lessons to be learned from major success stories, about how to be like those guys, but we reasoned that there was lot to be learned, too, about how NOT to be like THOSE guys. After we had 20 researchers spend two years looking at 2,500 corporate failures, we concluded that 47% of them stemmed from strategies that could have been identified as brain-dead ahead of time -- no, one of the world's biggest cement companies was not, in fact, actually a home products company that should start making and selling lawn mowers. 

Our solution was what we called a devil's advocate -- someone whose job it is just to gather and surface all the potential problems with a strategy. We have found through our research and consulting that executive teams include people who are aware of all the vulnerabilities, but big issues can get swept under the rug as executive teams try to make the CEO's vision work and shy away from challenging him or her. Such challenges can be career-limiting moves. 

Once you have identified the key vulnerabilities, though, how do you best present them? That's where the future history comes in. 

We reasoned that people respond well to stories. They're how we talk to each other. Stories are memorable in ways that individual facts are not. They connect the dots, too. X led to Y, which led to Z.... B didn't happen, so C and D couldn't, either....

So, we suggested that people pick a date well into the future, perhaps five years, and write a story that assumed that their strategy had failed. You set a dateline of, say, June 14, 2027, write a lede about something dramatic -- senior staffs often suggest starting off with the CEO being fired, though CEOs are often less enthusiastic about that idea, for some reason -- and then produce a "history" of the strategy's failure. Customers didn't do what you expected. Competitors were surprisingly aggressive. A key technology didn't work. You didn't, in fact, know anything about making lawn mowers or have the distribution network to sell them (this being the sort of observation that would have saved that major cement company from filing for bankruptcy and being acquired).

With that future history in hand, you see the pitfalls more clearly and can either realize that you have no way to get around them or can navigate your way past the perils.

You should do a more optimistic -- and more fun -- version of a future history, too. You take out a clean sheet of paper and imagine the perfect form of your business five or 10 years out, Then you write a "history" from the future date that describes how you got there from here. That sort of future history lets you start making plans now that are required if you want to hit that future home run -- if I want to be here in year 10, then I need to be here in year 5 and here in year 3, so I'd better invest a few small sums this year to start exploring the space. You can also see when you're getting off track, if some key development in technology or in the market doesn't come to pass as planned. 

I'd suggest using both optimistic and pessimistic future histories from time to time to help make sense of a digital world of insurance in which the core elements -- the customer, the yes/no mechanism and the capital -- are freed from their current forms. What if you could use digital channels to reach any customer, anywhere, any time? But what if competitors, perhaps ones you've never seen before, could reach yours? What if that yes/no mechanism could largely exist without human intervention, greatly increasing your efficiency and letting you serve new customers? But what if that mechanism no longer needs to be in-house and renders your claims operation moribund? Etc.

If you're interested in seeing examples of future histories, you can check out the website for a book Chunka and I wrote recently with a longtime colleague, Tim Andrews. I won't make you buy the book, called "A Brief History of a Perfect Future: Inventing the World We Can Proudly Leave Our Kids by 2050" -- though you're welcome to; it's really good, Instead, you can just click here, enter your name and email and get three free chapters of the book, which include examples of both positive and negative future histories.

Please let me know if you have any questions. I've seen these future histories help major organizations sort through strategic complexity and save them tens of millions -- and perhaps, in one case, even billions -- of dollars. I hope the tool will help you prosper, too.

Cheers,

Paul


How IoT Shifts Insurance's Paradigm

Traditional discussions of react, repair and replace are changing to predict, prevent and protect. Part of this transition has been supported by the IoT.

graphic showing the internet of things

There is a shifting paradigm in the insurance industry, with traditional discussions of react, repair and replace changing to predict, prevent and protect. Part of this transition has been supported by the Internet of Things (IoT). Technology has paved the way for people and devices to interact and instantly exchange data. By 2025, it is estimated that people will own more than 50 billion networked devices, double the amount in 2015, all of which make up IoT. While IoT technology is rooted in our society, the insurance industry is embracing the use of this technology by policyholders to mitigate and attempt to prevent losses. 

One specific area that is advancing quickly within IoT is water damage and leak protection. Businesses are subject to water damage from a multitude of sources. Plumbing system failures, HVAC malfunctions and severe weather events are just some of the many types of incidents that can ultimately lead to water damage. No matter what the source, these events are increasingly expensive and disruptive. A large water damage incident can interrupt normal business operations for days, weeks and even months and can be as damaging and destructive as a fire. Water-sensitive components, sensors and electronics are finding their way into everything, from the production floor to the office and everywhere in between. As a result, insurance carriers are relying on technology - specifically IoT sensors - to help businesses shift from reaction to prevention.  

IoT Impact 

The deployment of IoT technology and the impact it can have on reducing potential loss is significant. For example, a multi-story hotel deployed water leak sensors in their HVAC rooftop unit. The coils within the condenser burst, resulting in a discharge of water down a utility chase to the basement where the main electrical equipment was located. When water was detected in the HVAC system, alerts and notifications were sent following the communication notification protocol established, and maintenance personnel were able to resolve the issue before it caused significant damage. If the IoT sensors were not deployed and prompt action not taken, the hotel likely would have temporarily closed, suffering a major loss and disruption. It is important for companies to keep a rule of thumb in mind - for every six water sensors installed in the commercial business portfolio, one large water damage loss has the potential to be avoided.       

Accidents affect a business owner in a variety of ways, but the first thing that often comes to mind after a water damage incident following clean-up and restoration is the monetary impact. In insurance, both the business owner and the carrier may be affected, subject to the terms and conditions of the policy. In addition to losses that may be covered by insurance, when such an accident takes place the policyholder will likely experience unfavorable developments that are not covered. Some of these impacts may not be quantifiable, but they are all costly to policyholders. Fortunately, IoT can provide another level of protection that has a direct correlation with loss cost aversion.   

IoT technology can also help create a peace of mind for business owners by keeping their businesses operational and thus avoiding a disruption. This growing technology market provides prompt alerts and insights that allow adverse conditions to be addressed quickly, which can reduce losses and minimize business interruption. IoT can result in superior risk management, reduced cost and enhanced bottom line performance for companies that leverage the technology.  

See also:Insurance and the Internet of Things

Looking Ahead

Technology and proper planning are key components in a successful loss mitigation strategy. Tapping into IoT provides real-time data as an alternative to relying only on historical post-loss information. In the future, IoT sensors are expected to use live data to feed, train and test predictive models to forecast losses before they happen. Leveraging this technology can minimize the impact and maximize the effectiveness of loss-prevention programs. Risk control professionals can assist with understanding possible damage sources and provide support when building an effective incident response plan.  

Disclaimer

The purpose of this article is to provide information, rather than advice or opinion. It is accurate to the best of the author’s knowledge as of the date of the article. Accordingly, this article should not be viewed as a substitute for the guidance and recommendations of a retained professional. Any references to non-CNA websites are provided solely for convenience, and CNA disclaims any responsibility with respect to such websites. To the extent this article contains any examples, please note that they are for illustrative purposes only and any similarity to actual individuals, entities, places or situations is unintentional and purely coincidental. In addition, any examples are not intended to establish any standards of care, to serve as legal advice appropriate for any particular factual situations, or to provide an acknowledgement that any given factual situation is covered under any CNA insurance policy. Please remember that only the relevant insurance policy can provide the actual terms, coverages, amounts, conditions and exclusions for an insured. All CNA products and services may not be available in all states and may be subject to change without notice. 

“CNA" is a registered trademark of CNA Financial Corporation. Certain CNA Financial Corporation subsidiaries use the "CNA" trademark in connection with insurance underwriting and claims activities. Copyright © 2022 CNA. All rights reserved.


Steve Hernandez

Profile picture for user SteveHernandez

Steve Hernandez

Steve Hernandez serves as senior vice president, risk control, at CNA.

He is responsible for strategic direction and leadership of risk control for CNA’s $2.8 billion commercial property and casualty business, which is composed of business insurance (smaller commercial accounts) and commercial insurance (middle market and risk management accounts).   

Prior to joining CNA in 2016, Hernandez worked for the Chubb Group of Insurance Companies, where he most recently served as senior vice president of global risk engineering. He also served on the company’s diversity senior manager roundtables, where he was a moderator and presenter for numerous diversity and employee resource group sessions, including: minority development, working parent, Hispanic and LGBT resource groups. 

Hernandez earned a bachelor of science degree in construction management from Bradley University and is a member of the American Society of Safety Engineers, National Fire Protection Association, the International Association of Emergency Managers and the J.D. Power Insurance Advisory Board.


Adopting a New Mindset on Benefits

At the core of group and voluntary benefits is one question that affects all others. Who is the customer — the employer or the employee?

Three lightbulbs in front of a cloudy blue sky

Traditionally, individual life and annuity insurers and voluntary benefit/group insurers were not much alike. Their products were different. Their processes and systems were not alike. Their distribution was different. Their experiences were different. Even those carriers that played in both segments typically conducted their businesses as separate units of the company. It wasn’t hard to see why. Risks were calculated based on individuals, or they were calculated based on the employee group. 

However, one thing was the same … the ultimate customer – the individual or employee.

While there are still many differences in play, there are increasing similarities that create opportunities with a new set of choices and a new set of rules. Sometimes, the answer to these choices is no longer either/or but is both. If voluntary benefit/group insurers are open to this shift in mindset, they will open themselves up to growing market opportunities — and a host of possibilities to create deeper, longer, profitable customer relationships. But it is going to take a lot of “both” thinking to achieve a successful perspective.

At a roundtable organized by Capgemini and Majesco, distinguished leaders from the industry discussed how expectations at the workplace are changing for Gen Z and Millennial workers, especially regarding voluntary benefits at the workplace. Capgemini and Majesco released many of their comments and findings in a special report, Growth Opportunities in the Voluntary Benefits and Group Benefits Market. Today, we’ll take a brief look at some of those conversations for insights on how this might affect group and voluntary business strategies.

Defining the customer

At the core of group and voluntary benefits is one question that affects all others.

Who is the customer — the employer or the employee?

In group and voluntary benefits, the employer has long been considered the customer. But we are undergoing a shift that has created an entirely new employment dynamic, where companies treat their own employees like customers — making sure that the experience looks inviting from the outside and doing their best to keep the employees happy once they’ve joined the organization. With employers needing to meet employee expectations, group/voluntary benefit insurers are now needing to look one layer deeper in the experience.

How can the industry improve the employee experience through the group and voluntary benefits? Of course, they can’t begin to improve the employee experience if they can’t prove to employers that their own experience will improve, as well. Time-strapped HR teams don’t want to spend any extra time in the enrollment and administration of group and benefits products, but they do want to provide an expanding array of products and benefit plan options that meet a growing diverse employee continency. That means that the answer is both. If insurers can expand their definition of customer, they will begin to look at their products from both vantage points.

Enrollment as the first, but not only, area of opportunity.

In our round-table discussions, two words appeared as important and connected: relationship and relevance. It can be difficult for insurers to establish both a relationship and relevance while selling through an employer as part of their benefit plan options. The key is to find or create windows of opportunity.

The first window is typically the annual benefits enrollment period — the short period when an employee selects their benefits for the coming year. The industry is quite efficient at open enrollment. But it only happens once a year, and so much else happens throughout the year that creates new insurance needs. The birth of a child, college, starting a business, marriage, purchase of a home, traded in cars, a new pet or retirement are moments where the employee’s risk needs change and that are often missed.

Instead, could we capture more employee-related data internally and externally to guide them in selecting insurance benefits? Even more importantly, can we change the enrollment process assumptions from once a year to any time throughout the year? And why not offer personal or individual coverages as an option within the benefit plan for needs like pet, auto, home, life insurance, long-term care and more that are increasingly desired?

A workforce in the midst of upheaval and shift

In 2021, the Millennial generation overtook Gen X and Boomers as the dominant 30- to 60-year-old insurance buyer segment in the U.S. Millennials will be joined by members of the Gen Z generation in 2025.

Which employee population best represents the need for an expanded range of benefits and an increased portability in benefits — Gen X and Boomers or Gen Z and Millennials?

Millennials and Gen Z are not bound to a single organization for their career, instead opting to move around and have different experiences, including starting their own business or gig work. Their potential need for coverage now and after they leave their jobs is great. They will be especially interested in benefits that they can take with them.

Gen X and Boomers, on the other hand, are also moving toward retirement and a different kind of financial independence that may include working part time or carrying their benefits with them in ways that are unlike COBRA coverage – because Medicare does not cover all their risks.

The pandemic has created a spike in the number of people who left their jobs from both demographic groups. Many have found they can work from anywhere, creating a new competitive workplace landscape. Termed the Great Resignation, this economic trend, seen across all businesses from small to large and from retail and education to technology workplaces, has put employers on notice to retain existing and attract new talent. 

Insurers that can offer a wider array of group/voluntary benefits with different benefit plan options that meet the broad and different generational needs to meet their unique risk needs can capture a significant market opportunity not seen in decades. Given the nature of the younger generation to change employment and the older generation wanting to retain some coverage, voluntary benefits insurers are staring at a fantastic opportunity.

Products that can be underwritten individually or can be ported to individual insurance so the employee can retain them will offer insurers an opportunity to retain customers and deepen the relationship with other products over time — a far more cost-effective customer acquisition. They gain the short-term advantage of bulk business and the long-term benefits of a broadening relationship that doesn’t have to end with employment.

For insurers, though, it is a clear signal that both groups are candidates for selling through the employee channel, growing a deeper relationship and providing the portability that employees may find appealing as they weigh their future options.

See also: 3 Ways to Develop a Growth Mindset

A new set of rules for a new type of life

As insurers grapple with the possibility of selling to employee groups, they should also consider that generational needs aren’t the same. In fact, possible interests and products are all over the map. The wider the net, the broader the portfolio of offerings and the greater the importance of the experience.

To retain and grow their customer base and revenue, insurers must rethink their scope to a broader lifestyle experience across health, wealth and wellness that includes insurance products, lifestyle needs and value-added services. Providing a broader portfolio of offerings as part of an overall plan benefit package begins to address the broad range of needs across multiple generational groups that will drive employee enrollment, satisfaction and value. To make the process easier, insurers must leverage employee data – both collected as part of the employment process and voluntarily supplied by employees – to personalize and prioritize the products and services that fit with employees’ life stages and personal needs and interests.

For example, there are solutions that provide online portals and apps to help employees with enrollment and benefits questions throughout the year. Using AI, you can capture engagement data to further guide employees and identify future needs. This different level of engagement creates opportunities for consideration. Can group/voluntary benefits insurers find ways to “listen” to structured and unstructured data for signs of new risk needs or product and services trends?

One of our roundtable participants discussed how we use our listening to create new models of business.

“If you [look] at employee life events, does that offer an opportunity to engage that employee differently? They had a child. Maybe they need additional insurance. Maybe they took a loan out of their 401K to be able to put a down payment on a house. Now there's a lot of opportunity to engage to sell new products at that point in time, off-cycle to the annual benefits process. These could be individual products that can create a better overall value proposition and loyalty to the employer and insurer because they're helping them at that time, when their life is changing.”

Embracing innovation as the tool of rapid advancement and growth       

Group and voluntary benefits insurers need to look at broad-stroke changes in engagement, but they may need to also consider a wide array of factors concerning innovation and improvement. Data, for example, will be the key to successfully negotiating group, voluntary benefit and individual underwriting, claims, product development and communication. To rapidly add these capabilities, insurers should be prepared to adopt a next-gen platform approach. Next-gen platforms are providing insurers with out-of-the-box, third-party data integrations and social media sentiment analysis using machine learning and artificial intelligence.

Should we innovate to expand our group channels or innovate to improve individual experiences or innovate by embedding our insurance into someone else’s experience?

It is in the area of innovation that we find so many questions that can be answered, “all of the above.” One level of innovation gives rise to another because innovations have become more dependent upon each other than ever before. Channel growth makes a great case for this. It’s the innovation of ecosystems that enable insurers to think outside of their markets.

One roundtable participant commented that, “I think smart insurance companies are beginning to think about everything as a channel. If I’m an insurer and I want to embed insurance into somebody else’s value chain or experience, I should have the ability to do that.”

By building a partner ecosystem of collaboration, insurers can play to their strengths while the customer gets to enjoy a well-rounded product. For example, a life insurer can partner with a fitness tracker company to offer insurance to their customers, thereby allowing the insurer to target that market without having to set up a separate fitness watch business. But to do so requires next-generation technology using application programming interfaces (APIs) to bring together solutions transcending industry or company boundaries.

Next-gen platforms are the foundations for future group and voluntary product innovation. They must support the customer across their lifecycle – whether for group, voluntary benefits or individual insurance, recognizing the need to move between these as they change employers, gig on or off and have new product needs based on where they are. Optimally, these systems will support group and voluntary benefits with individual policy servicing on a single platform, recognizing that customer retention, regardless of where they originate, is critical to insurers’ growth strategies.

Finding the win-win in the quest for a transformational mindset

Last, there is the question of motivation. Is there any evidence we can point to that will solidify the need for group and benefits insurers to act now, while the employee and technology shift is creating opportunity? The answer might be found in the answer to one more question.

Who wants a wider choice of benefits options that can be provided through insurance innovation — employees or employers?

According to the MetLife U.S. Employee Benefit Trends study, 60% of employees are interested in their employer providing a wider mix of non-medical benefits that they can choose to purchase on their own. According to the same report, 66% of employers are expanding the range of employee-paid benefits or have plans to. This is great news for group and voluntary benefits insurers. The answer is both. Employees want us to expand our mix of benefits. Employers want us to expand our mix of benefits. We want to improve our market reach and deepen our relationships with increasingly-mobile insureds.

The time to win in the group and voluntary market is right now.

For an in-depth look at the Majesco and Capgemini roundtable comments and findings, be sure to download Growth Opportunities in the Voluntary Benefits and Group Benefits Market. This article was written by Denise Garth and Seth Rachlin. To continue this conversation, connect with Seth on LinkedIn and Denise on LinkedIn or Twitter


Denise Garth

Profile picture for user DeniseGarth

Denise Garth

Denise Garth is senior vice president, strategic marketing, responsible for leading marketing, industry relations and innovation in support of Majesco's client-centric strategy.

Why APIs Work Better in the Cloud

While APIs have become commonplace, we are running into the danger of creating too many point-to-point tethered connections and losing the value that we had found.

Sailboat on clear blue water in the mountains

California is a gorgeous state, unfortunately known to the rest of the world for its wildfires, a high cost of living and, in some locations, bad traffic. But bad traffic makes for good analogies, especially when it comes to application programming interfaces (APIs). Both traffic and APIs require a bit of advance planning, so let’s consider road planning for a moment as a model for API gateways.

When the Spanish founded Los Angeles, they probably weren’t planning for a population of 12 million people geographically locked between an ocean and a desert and mountain range. So, they didn’t plan their streets for the future. Traffic, since the 1800s, has always been an issue. Public transportation hasn’t helped much. Freeways are often more gridlocked than ancillary roads. Growth and use has always eclipsed capacity. I’m sure today’s city planners wish they could start from scratch.

With APIs, we have the ability to strategically plan our routes for today and the future — acting right now to plan the digital roads that will allow for smooth sailing and avoid frequent gridlock. Once we uncover some of the crucial issues that APIs present, we can then assess the thoughtful solutions that are available to us to help us tame the traffic. Our goal is to answer the question:

“How does the world of APIs change and get transformed by leveraging the cloud?”

APIs began with the concept of simplicity. One road led to one destination. This is why APIs were developed in the first place. We needed one-to-one, easy plug-and-play connections to relieve the stress of coding issues within monolithic systems. APIs answered the question, “What if we could reduce the number of points of implementation impact by creating one-off pathways?” APIs allowed for microservices. APIs allowed us to talk to outside entities much more easily. APIs opened new doors of data that were previously difficult to ingest and consume. APIs allowed the digital world to work in real time.

The issue is that, while APIs have become commonplace, we are running into the danger of creating too many point-to-point tethered connections and losing the value that we had found in the original point-to-point idea.

Right now, much API development and administration is still point-to-point between one system and another system, multiplied by many systems and hundreds of APIs. What happens to API development and administration when you’re dealing with hundreds or thousands of separate APIs? This is like paving a separate road for every commuter where the rules for the road are all different and yet they all cross at random locations. A growing population of APIs without an effective way to manage the traffic represents an untenable future. The cloud takes this impossible situation and makes it manageable and less strenuous for everyone involved.

The stresses in the system that necessitate an API gateway

The simplest way to understand the value of an API gateway is to understand what could go wrong if APIs aren’t managed properly. Here are just a few issues:

  1. Poor performance and operational inefficiency.
  2. Lack of effective documentation, responsibility, administration and governance.
  3. Lack of adequate security.

See also: How API Hub Can Spark Innovation

API gateways tame the traffic

An API gateway acts as a proxy for each of the APIs that it manages.

Let's assume there are 1,000 APIs. Each API is a point-to-point interface. If there is an API between system A and system B, it is a one-to-one relationship. A gateway is a proxy, exposing the public-facing API endpoints. It then routes the incoming client requests to the relevant services. So, let’s say there is a request coming in from an outside entity that needs to go to two different systems internally. The standard process with no gateway would be that there are two calls made: one from the external system to internal system A and one from the external system to internal system B. That’s two calls. Multiply those two calls for each required function times 1,000. This is what leads to latency and traffic jams.

The API gateway not only routes the incoming client requests to relevant services, but it also aggregates the response data from a variety of different internal APIs and sends back the responses with one request. Less traffic to point A. Less return traffic from point A.

The API gateway also acts as border security for anything entering the organization. But, like a border security post, monitoring isn’t just about finding insecurity, it is about organizing tasks and proper routing. At the border, there are queues, split apart by various destinations. If you’re traveling to/from an international airport, you’ve seen how border security works to process people based upon where they are coming from and where they are going. An API gateway efficiently guards the organization’s systems from overuse and abuse by queuing properly. All of the most important performance metrics that would commonly define the success of an API, such as requests per minute, latency, errors per minute and API uptime — are threatened when APIs are distributed and disorganized outside of the gateway.

We should mention here that if an organization isn’t seeing clogged traffic just yet, they will. Insurance customers are increasingly choosing “data-heavy” products and services that will require more API integration and use, as shown in Majesco’s latest consumer research. APIs aren’t going away, and they aren’t becoming fewer in number. Remember the city planners who should have planned ahead. If you are in a position to save your company from future grief by moving APIs to an API platform in the cloud, now is the time to speak up.

API gateways avoid “chatty” outgoing client requests

With distributed APIs and no coordination mechanism, a single outgoing client request can result in multiple round-trip requests. Being able to make a single request to an API gateway, which then routes calls and collates responses is far more efficient. This also dramatically improves performance.

API performance isn’t just about traffic flow, it’s about reducing API traffic “accidents”

APIs are game-changers, so there’s no doubt that organizations are finding them useful in every respect. In some innovative organizations, there is a charter that stipulates that they need to use APIs as the primary nodes of interaction between various systems, both internally and externally. But if you’re doing that and you aren’t using an API gateway in the cloud, you’re running the risk of having a bunch of connected streets and avenues with no sense of logic or a set of rules constructed among them.

Without an API platform-based approach, you run the risk of a network of connectivity where the systems and functions are too complex to understand the impact of changes. When you end up having to either upgrade a particular API or troubleshoot it, it becomes an exercise in network engineering. Imagine being an electrical engineer, sorting through a host of painted wires that are mixed up with no schematic, and you have to literally take out each wire by itself. Simple APIs lose their simplicity as they multiply with no documentation or governance. As the network slows, the errors will grow.

The API platform-based approach brings order to the chaos. Traffic management is far easier because the system knows and understands the APIs and their relationships to one another. And, it’s smart enough to be able to share its knowledge with us, which is something we’ll discuss in a few weeks when we talk about an API gateway and its ability to automatically document the details of each API.

API gateways are cloud-based because that’s where they are effective

If we step back and look at the pre-cloud-driven services world, to implement an effective API gateway would entail a huge amount of redesign, reworking of existing APIs and then making sure that all of the connections, programming and system protocols are aligned. There are organizations that do this, but the cloud has given us a much more logical option. 

What we have today is not necessarily “drag and drop” programming, but it's closer to drag and drop than to reprogramming. Cloud-based solution providers like Microsoft Azure have made the process workable and efficient. Everything that an organization would have needed to invent on their own in-house is provided as a standard part of the process. Cloud technology choices are so much simpler because of their ease of use, their pre-built functions and their simple configurability. And, of course, cloud gives us the speed that we and our customers crave in our transactions and communication. There is simply no comparison when working with APIs in-house. Those who do still find themselves turning to hybrid solutions or mirroring data on the cloud to stay secure. 

See also: A Cloud Platform's Role in APIs

The “hurdle” of API migration

Of course, one of the biggest hurdles to migrating your APIs to a cloud-based solution is just the decision to do it. The actual migration itself is fairly simple. The API migration playbooks already exist. They are precise, “hands on” directions for making the switch. It’s not neuroscience. The ease of migration is actually one of the greatest motivators to do it.

Cloud providers make it possible to envelop an existing API architecture and a library of existing APIs with cloud-enabled orchestration. They have a toolkit that provides you with everything you need for API discoverability, plus a documentation library, with a system-generated capability of defining new APIs so that you don't have to unlearn and relearn how to define and document your APIs. The process is thoughtful and smart.

Things like security and load balancing are all predefined in these platforms. You simply have to customize the API gateway to your organization's needs. It’s like selecting a new Tesla. You can’t change the primary functions of the car, but you can add the various options that fit your taste. This is what a cloud-based solution does for insurers for organizations that already have APIs. It not only delivers the cloud, but it easily guides IT teams through the process. We’ll discuss this more when we talk about developer and user roles in coming weeks.

In our next cloud blog, we’ll discuss documentation, administration and governance in the new API platform environment. (Spoiler alert: It’s much simpler, highly automated and built for security and consistency.)


Ravi Krishnan

Profile picture for user RaviKrishnan

Ravi Krishnan

Ravi Krishnan, chief technology officer at Majesco, oversees the architectural and technical direction for all Majesco SaaS platforms.

How Billing Models Can Keep, Recover Business

Billing is important enough to the business that it requires a future-focused strategy. Billing innovation and transformation strategy pays for itself.

Back of a football ref

Sheila is shopping online for a new auto policy. Marketing has done its job to get the ball in play. Sheila made a few simple choices. She received a timely quote. Underwriting catches the pass. Like running down the field with the football in hand, the full insurance team has taken the ball to the goal line and is ready to issue a new policy…and then…fumble.

Sheila wants a usage-based policy for her second car, a convertible that doesn’t get driven in the winter. Fortunately, her insurer will allow her to turn on and off her insurance with the click of a button on their website. Unfortunately, she pays semi-annual premiums, which means that she doesn’t actually see her savings “catch up” until months later, creating a massive inconsistency in her billings. When she tries to switch to monthly billing, she realizes that she loses her pay-in-full discount. The modern insurance product and the fantastic UBI capability are of no value because the carrier’s billing system isn’t aligned to its capabilities and her expectations.

Sheila pauses and considers shopping around. This is the point of fumble. Who is going to recover the ball? Whoever can match the customer’s billing needs to the customer’s billing expectations.

There are a hundred different scenarios we can replay in this situation, but many of them end in similar results. Billing is important enough to the business that it requires a future-focused strategy. Billing innovation and transformation with a customer-first strategy pays for itself.

Majesco released a joint thought-leadership paper with Deloitte titled, Insurance Billing and Payments: From Back Office Calculators to Channel Growth Accelerators, based on an executive round table with industry leaders. The paper examines how and why billing’s operating model is changing within the insurance organization — seen through the eyes of insurance executives. It also makes an excellent practical case for a quick, sustainable and valuable ROI.

“Put me in, coach.”

Rapid digital transformation across industries is pulling billing and payments off the bench and into the game. Once considered to be back-office financial functions, billing and payments are now at the center of the digital customer relationship, along with innovative products and services, and they are as adept on offense as they are on defense. Billing is a key component in any growth and innovation strategy. A redesigned billing experience can anchor an insurer’s future success and survival. The reason? Billing sells!

Data from venture capitalist Mary Meeker indicates that over 60% of transactions are digital, ranging from mobile payments, messenger apps and contactless payments through online commerce sites and buy buttons. Yet most billing systems are not prepared to meet the higher challenges of service expectations and customer success. Billing is a universal touch point for insurers. Customers may never deal with claims. They may only deal with underwriting once. Billing, however, will follow them into the future with frequent communication. The time to rethink the billing and payments foundation is now, before billing’s technology and service gap becomes insurmountable.

Billing plays offense. Billing plays defense.

In billing and payments, insurers will find that they need to think in terms of defensive tactics and offensive strategies. Today’s billing is versatile enough to be on both sides of the team.

Making the big plays to outperform the competition is the role of the offense. These are the billing model innovations that will excite the business because they enable the whole organization to think big without billing constraints. 

The defense reacts to market necessities, responding to what is current and holding the ground already gained. This would be akin to maintaining service levels, tracking information for reports and keeping omni-channel service strong during moments of stress, such as internet outages or high call center volumes.

The offense adapts to new business demands and strives to leap ahead of the competition. The defense maintains operational effectiveness, executing today’s business. Front-office opportunities are handled by the offense. Back-office optimization is pure defense. Today’s rapidly changing market requires that both are done with excellence, but, more importantly, that they are executed with balance.

“We are constantly playing defense because of the legacy technical debt that we are burdened with. It generates an enormous amount of friction. There’s significant value when you focus on the offensive side with new things that can be done to drive customer retention, satisfaction and more." — Round Table Participant

See also: Myths on Reference-Based Pricing

Billing on Defense – Optimized Operations and Customer Engagement

Insurance billing sits at the intersection of cashflow and customer engagement, so it can’t be ignored.

The foundational elements of billing and payment solutions are task-oriented:

  • Set up payment plans
  • Calculate payments due by customers (including fees)
  • Produce invoices
  • Create reports for management
  • Record premium payments made to customer accounts

These tasks are important in providing effective billing processes that deliver quality of service, support financial operations and encourage customer and distributor relationships.

But these are just the operations that will keep the insurer on the playing field, not what will catapult them over the competition. More than optimized operations and customer engagement are needed to meet the digital demands of today’s customers.

Billing on Offense — Innovation and Customer Experience

Billing is more than a financial arrangement. It has a significant role to play in the overall customer experience. Billing encompasses significant events, such as renewals and claims. These are trust building opportunities — times when insurers follow through on the brand promise of protection and service.

Experience also encompasses e-commerce, a concept far removed from yesterday’s electronic payments. The payment portion of the transaction is now a component of an integrated digital value chain that includes search features, bundling, recommendations, quotes and complex schedules. It necessitates the free streaming of data in and out with numerous integrations.

Innovation within insurance products and services is causing insurers to offer new transaction types and new payment methods that may be unlike anything they have ever seen or that can be handled by traditional billing processes. Embedded insurance makes a great example. Can an insurer’s billing and payments processes easily communicate with a partner’s transactional channel? What steps does an insurer need to take to prepare for billing innovations that are the trickledown from a new product or service?

One way an insurer can play offense is to integrate only enterprise billing solutions that have been designed with the future-focused, front-office approach in sight, rather than considering a legacy replacement of a back-office transactional process.

The growing demand for new payment methods, billing plans and access to real-time billing information can transform digital capabilities. It can improve communication and fuel growth to leap ahead of the competition and capture new markets while growing existing markets.

The Billing Operating Model — A Strategic Enabler for Growth

A billing operating model shift allows insurers to keep one eye on the customer and another on the company.

Insurance operating models have traditionally been functional (policy, claims, and billing) and product-focused (commercial/personal). This has resulted in distribution and servicing technologies that mirror the priorities and limitations dictated by traditional strategies.

The evolution of traditional operating models has been incremental and directed toward centralization to deliver scope and to scale benefits. Today’s billing models will still need to meet internal demands, but they will also need to account for customer desires and trends in billing and payment capabilities.

Every insurer must undergo an introspective analysis if they hope to maximize value from their functional and technology transformations. They must look at themselves in light of reality and determine what it will take to reach their customer-focused transformational objectives.

“Billing is not just a cost center anymore. There’s significant value in moving to a new, different operating model that opens up possibilities for business growth — scaling to adapt and use new enabling technologies and creating new experiences.” — Round Table Participant

A customer-first approach requires a deep understanding of the carrier’s customer base as well as the various interactions that will make a meaningful difference. Furthermore, "customer first" operating models are not an evolution of the current state and are not limited to customer interactions with insurance carriers. Amazon, Google and Apple experiences are pervasively re-defining CX. The impact delivered by new experiences will accelerate, not only because of these major tech players, but also in response to the smaller tech/fintech/insurtech firms that are seeking a competitive advantage.

Matching the agility and speed of the startup

Startups have a billing advantage. They can engage customers from the outset, unencumbered by technical debt or the need to convert data. This allows them to play offense, developing customer-first operating models powered by tech/data capabilities to deliver insights that will shape interactions. For example, startups can begin with optimized workflows to automatically create best practices in retention. A modern workflow with embedded "next best action" can be crafted to prioritize each customer interaction through the lens of retention analysis.

Startup insurers are often able to sort, rank, rate and predict with efficiency and clarity. Customer effort scoring is a crucial improvement metric that startups would find much easier to implement than a traditional insurer. This is just one example of hundreds, but it makes the case that the world of customer experience is moving quickly, and insurers need to move with it.

Large carriers are still focused on assimilating changes in customer behaviors with limitations imposed by their operations and legacy technology debt. The traditional contact center is a prime example. How adept are carriers at mixing customer service channel methods in the midst of an omnichannel revolution? Insurers are grappling with perfecting service in light of shifting customer expectations.

See also: Integrating Chatbots, Policy-Handling Apps

Billing’s Role in Communication — Making the Touchdowns

Communication with customers is where the whole thread comes together. It’s where the touchdowns are scored. Previously, all of the aspects of billing were more clearly separated from channels of service and communication. Today, however, insurers are giving agents and customers faster and easier access to those portions of the billing system that will assist them to accomplish their goals.

Streamlining communications in an omni-channel age has many hurdles. Billing, because it is so customer-service heavy, has to stay in constant contact with communication management. For example, during the last two years of pandemic, contact center staffing has been a concern. Insurance is the third-largest user of call centers, ahead of even healthcare and telecommunications. Any point of difficulty with this portion of the omni-channel communication strategy needs to be offset by technologies that can help to pick up the slack — integrated with billing.

Carriers need to consider the details (What alternative user support channels can we use for billing and payments?) and the larger concerns (How do we use intelligent routing that balances the optimal customer experience with our staffing and resources?).

A redesigned operating model for billing will consider the impact and future-focus that may include greater agility, reprioritization, replacement of siloed operating models and the leveraging of ecosystem partners. These greater efforts will pay off in many ways, not the least of which will be customers who quote, buy and stay because their carrier allows them to do business in the way they want.

Today’s blog is written with Ajay Radhakrishnan, managing director at Deloitte Insurance.


Denise Garth

Profile picture for user DeniseGarth

Denise Garth

Denise Garth is senior vice president, strategic marketing, responsible for leading marketing, industry relations and innovation in support of Majesco's client-centric strategy.

Coping With Insider and Outsider Fraud

Recent macroeconomic events involving supply chain slowdowns, flexible work arrangements and rising inflation have paved the way for a possible uptick in crime.

person using computer

While fraud has existed for as long as there have been companies, when changes occur in how an organization operates, new doors open for people inside and outside an organization to steal.

Recent macroeconomic events involving supply chain slowdowns, flexible work arrangements and rising inflation have paved the way for a possible uptick in such crimes. Changes in the supervision of an employee coping with financial pressures, for instance, may encourage the person to commit fraud or invite a con artist to deceive the employee in a sophisticated social engineering scam.

Both types of criminal deceptions are widespread and expensive. According to the Association of Certified Fraud Examiners, occupational fraud causes an average 5% revenue loss annually, with the average loss per incident estimated to exceed $1.5 million. Social engineering scams have tripled since 2020, according to the Anti-Phishing Working Group, which tallied 316,747 phishing attacks in December, the highest monthly total since the organization began reporting on the subject in 2004. 

In our annual Midsize Company Risk Report, fraud-related theft was cited as the top concern of financial risk managers. Because fraud involves insider and outsider deceptions tricking people into believing something that is not true, internal controls are the primary means of thwarting the schemes. 

The Insiders

In cases involving an employee committing a fraud against an employer, criminologists have cited three factors at work: financial pressures, opportunity and rationalization. At present, the opportunity to commit fraud may appear greater for employees feeling the pinch of inflation at a 40-year high. 

Under this pressure, some employees may rationalize that they are being unfairly penalized for economic factors beyond their control. If an opportunity presents itself to commit fraud, they may be tempted into thinking they won’t get caught. 

A case in point is the disruption in the supply chain. The difficulties sourcing needed supplies have impelled many manufacturers to contract with new suppliers in unfamiliar locations. Given high demand for the company’s products, time is of the essence, possibly compressing the customary due diligence performed into the new supplier’s controls. 

An employee with financial stress may decide to impersonate an accounts receivables executive at the new supplier to trick the company’s accounts payable into sending a payment into a bank account held by the employee. Or the employee may instead collude with someone working at the new supplier to manipulate the invoice, overcharging the company by 30% and sharing in the illicit proceeds. 

The Outsiders 

Threats from outsiders continue to grow at an alarming rate. FBI statistics show crimes involving phishing/vishing/smishing/pharming nearly tripled from 2019 to 2021. In cases involving social engineering schemes, today’s more prevalent remote work options constitute a greater opportunity for success, because employees are under less physical supervision. 

A different set of factors are at play in committing social engineering frauds. A common scam is for the fraudster to gather information from social media about an employee and a high-ranking executive within the company or at a key customer or supplier. The fraudster perpetrates a cyberattack to penetrate the company’s network and then impersonates the senior executive in a series of emails that appear legitimate. 

If the impersonation is convincing, the employee can be duped into doing something that seems perfectly normal, such as  transferring company or client funds into an illicit bank account held by the fraudster. 

See also: Global Trend Map No. 11: Fraud

Warning Signs and Controls

Against this backdrop, financial risk managers have an array of defensive and offensive tactics at their disposal. 

With regard to insider fraud, warning signs include sloppy record-keeping, accounts that often fail to balance, incomplete or undetailed bookkeeping records and missing documentation in financial reports and statements. Other red flags include a sudden shortage in inventory that is inconsistent with prior practice, frequent cash shortages and baffling adjustments to payable and receivable accounts. 

If any of these warning signs are in place, question the employee, as there may be a plausible reason for the discrepancy. If the stated reasons are insufficient, and evidence suggests the employee is having personal financial problems, conduct an internal investigation to gather the facts. 

During this period, curtail the employee’s access to company funds and other resources, as well as their involvement in supplier and other vendor transactions. If the company is publicly traded, external auditors should be alerted to the internal investigation. 

To reduce the potential for fraud and theft, a strong system of internal controls must be in place. Practices like the segregation of duties ensure that no single employee can simultaneously commit a fraud and conceal it, because other people are required to countersign any transactions. Multiple tiers of review and approval, both with the payment of goods and services and the approvals of electronic fund transfers, are mitigants that work.

With regard to outsider fraud involving remote work by employees, warning signs include repeated non-use of the company’s VPN (virtual private network) by employees. Use of employee home WiFi systems increase the possibility of network penetration, setting the stage for a social engineering scam.

To reduce risk, encourage protections like multi-factor authentication, software updates and regular changing of passwords on employee laptops, routers and modems. 

Alert employees to be extra vigilant about social engineering attempts, pointing out the three “unusual” components of a typical scam—an unusual request by someone in authority at the company, customer or supplier; an unusual sense of urgency in the request; and an unusual appeal to take immediate actions. If anything seems out of the ordinary, the employee should pick up the phone and call a supervisor.  Employees should also use dedicated internal phone directories when confirming requests with other employees and outside vendors rather than relying on the phone contact information provided within the suspected email.

Lastly, in both insider and outsider frauds, there is wisdom in periodically having the above procedures vetted through internal and outside audits. It’s one thing to have a policy in place and another to make sure it is being followed, especially in times of stress.

Risk Transfer

No control system is foolproof, of course, hence the purchase of a fidelity bond absorbing the costs of the aforementioned scams, as well as other financial losses incurred due to theft, forgery and other fraudulent acts. Because fidelity bonds differ, it is prudent to discuss with an insurance broker or agent which type is best suited to the organization’s risk exposure, such as financial institution bonds, first-party bonds, third-party bonds or a commercial crime insurance policy. 

An insurance broker or agent also can help explain each policy’s coverage nuances. Some fidelity bonds, for example, may exclude losses if company anti-fraud/anti-theft control policies and procedures were not followed or the fraud was directed by an outside entity like a supplier or a client.


Kevin Mason

Profile picture for user KevinMason

Kevin Mason

Kevin Mason is lead underwriter, private company management liability, financial lines, QBE North America.

He has four years of experience helping private and not-for-profit companies manage their management and professional liability risks. Before joining QBE in June 2021, Mason served in key underwriting positions at Berkshire Hathaway Specialty Insurance and CNA Insurance.

He holds a bachelor's degree in economics from the University of Wisconsin-Madison and is working on an MBA from the University of Illinois-Chicago. Mason has also earned the RPLU designation.


Antonio Trotta

Profile picture for user AntonioTrotta

Antonio Trotta

Antonio Trotta is vice president, claims practice leader, cyber and professional liability, financial lines, QBE North America.

Trotta has 20 years of experience handling and advising on claims involving management and professional liability insurance coverage. Before joining QBE in August 2021, he led the claims team for cyber/tech E&O/media/ commercial crime at Beazley for three years. Before Beazley, he was the senior claim counsel for CNA's MPL, technology, fidelity, cyber and media claims. Trotta also spent five years as a lawyer.

He holds a JD from New York Law School and is a certified information privacy professional.

Mental Health: Challenges and Opportunities

Discrimination and historical trauma have shaped the mental health of our BIPOC and AAPI communities and the treatment they receive. How can we do better?

Person with a backpack looking at the camera

Racism, discrimination and historical trauma have played major roles in the mental health of our BIPOC (Black Indigenous People Of Color) and Asian American Pacific Islander (AAPI) communities and the treatment they receive. According to Dr. Brenda Wade, clinical psychologist, “Systemic racism permeates every layer of society, education, health and mental health—not just police departments and fire departments.”

Why do these barriers persist, and what can we do to improve AAPI and BIPOC mental health supports?

Part one of this two-part series shares data and observations regarding the current state of mental health challenges and supports for BIPOC and AAPI.

The Current Situation

“Discrimination, race-based stress and trauma, structural oppression all contribute to the genesis and continuation of racial mental health disparities,” explains Brianna A. Baker, second-year doctoral student in counseling psychology. “Exposure to racism is correlated with increased stress levels (Peters, 2006), accelerated aging (Carter et al., 2019; Gee et al., 2019), and a variety of other mental health disparities in BIPOC populations (Jackson et al.,2010; Miranda et al., 2008).”

“Elected officials and all other systems reflect underlying—often unconscious—racism that the research shows creates devastating outcomes for BIPOC,” Wade adds.

Did You Know?

  • Mental Health America, reports that 17% of Black people and 23% of Native Americans live with a mental health condition
  • According to the national Alliance on Mental Illness, Asian Americans and Pacific Islanders (AAPI) have the lowest help-seeking rate of any racial/ethnic group:
    • Only 23% of AAPI adults with a mental health condition receive treatment.
    • Researchers have learned this is often due to:
      • Cultural shame
      • Language/cultural relevance barriers in current mental health services options
  • Suicide was the leading cause of death for AAPIs ages 15 to 24 in 2019. (CDC)
  • Mental health issues are on the rise for AAPI/Native Hawaiian young adults. (SAMHSA’s National Survey on Drug Use and Health)
  • Major depressive episodes increased from 10% to 14% in AAPI youth ages 12 to 17, 8.9% to 10% in young adults 18 to 25, and 3.2% to 5% in the 26-to-49 age range between 2015 and 2018.
  • Research indicates that BIPOC are:
    • Less likely to seek mental health care
    • More likely to experience mental health provider bias
    • Less likely to have access to mental health services
    • More likely to receive poor quality of care
    • More likely to end services early

See also: Five Things Employers Need to Know About Mental Health

The Caveats

Available data tracking of AAPI and BIPOC mental health can be misleading for the following reasons:

  • Due to prejudice and discrimination around mental health conditions and suicide, suicide deaths or mental health challenges are most likely underreported in most BIPOC and AAPI communities.
  • Available data reported does not reflect the great variability that exists within subcultures of BIPOC and AAPI groups.
  • Current statistics do not reflect the rise in anti-Asian hate and its impact on AAPI mental health.

Other Obstacles to Unbiased Treatment and Support

  • Language and cultural barriers
  • Dismissing, denying or neglecting symptoms due to mental health bias in many Asian cultures
  • The erroneous model minority myth that AAPI communities are doing well and don’t need any services or attention
  • BIPOC self-devaluation, one of the saddest byproducts of racism, which causes redirection of anger at the system toward “myself and those who look like me”
  • Coping by repressing emotions such as sadness, grief, shame, and loneliness—a necessary strategy to survive racial trauma
  • Lack of representation in the field
  • Multi-layered bias and discrimination
  • Historical betrayal by the scientific community
  • Disregard for cultural congruence
  • The current medical model, which is neglectful, dismissive and oppressive

Despite current challenges to equitable and meaningful mental health support for AAPI and BIPOC, helpful insights and opportunities for improvement are out there.

Resources

This blog is based on an #ElevatetheConvo Twitter chat hosted July 8, 2021, by Dr. Sally Spencer-Thomas @sspencerthomas. Advocates and experts unpacked the many ways disparities show up in our BIPOC and AAPI communities and opportunities for change and help. Special thanks to guest panelists:


Sally Spencer-Thomas

Profile picture for user SallySpencerThomas

Sally Spencer-Thomas

Sally Spencer-Thomas is a clinical psychologist, inspirational international speaker and impact entrepreneur. Dr. Spencer-Thomas was moved to work in suicide prevention after her younger brother, a Denver entrepreneur, died of suicide after a battle with bipolar condition.