Download

Investment Strategies for Today's Volatility

Many insurance companies have begun to reevaluate their equity investments. Is it time for them to follow John D. Rockefeller’s example and focus on dividend-paying equities?

person at a desk holding a pencil and money and typing into a calculator

“Do you know the only thing that gives me pleasure? It’s to see my dividends come in.” – John D. Rockefeller, 1908

It’s 2022, and inflation, geopolitical instability, rising interest rates and more are driving uncertainty to heights not reached since the late 1970s. Meanwhile, economic growth is falling and market volatility is at its highest since the onset of the pandemic. In the wake of this, many insurance companies have begun to reevaluate their equity investments. Is it time for them to follow John D. Rockefeller’s example and focus on dividend-paying equities?

When compared with an index equity strategy such as the S&P 500 Index commonly found in many insurance company portfolios, a dividend-paying equity strategy may offer insurers lower volatility, income opportunities and potential tax advantages. It may also prove to be a more effective equity strategy during a period of rising interest rates when viewed from a duration perspective.

A History of Lower Downside Risk

Historically, insurance companies have been reluctant to invest in equities, preferring fixed income securities’ typically higher yields and lower volatility. More recently, the need for portfolio growth led companies to take on equity exposure, often via passive index funds. Insurers became more willing to accept the higher volatility and lower income of equities in return for their potential capital appreciation. Unfortunately, insurers also accepted that they would only be able to convert the value of their equities into cash by selling shares, triggering a taxable event.

The Great Financial Crisis (GFC) of 2008-2009 caused many insurance companies and asset managers to again adjust their approach to equity investing. During the GFC, insurance companies experienced the downside of passive investing: When the market falls, passive investments bear the full brunt of the downturn. Lost to many in the chaos of the time was that dividend-paying stocks did not drop nearly as much as the broader market (as Figure 1 illustrates, the decline of dividend-paying stocks was only about 80% of the broader equity market between September 2007 and February 2009).
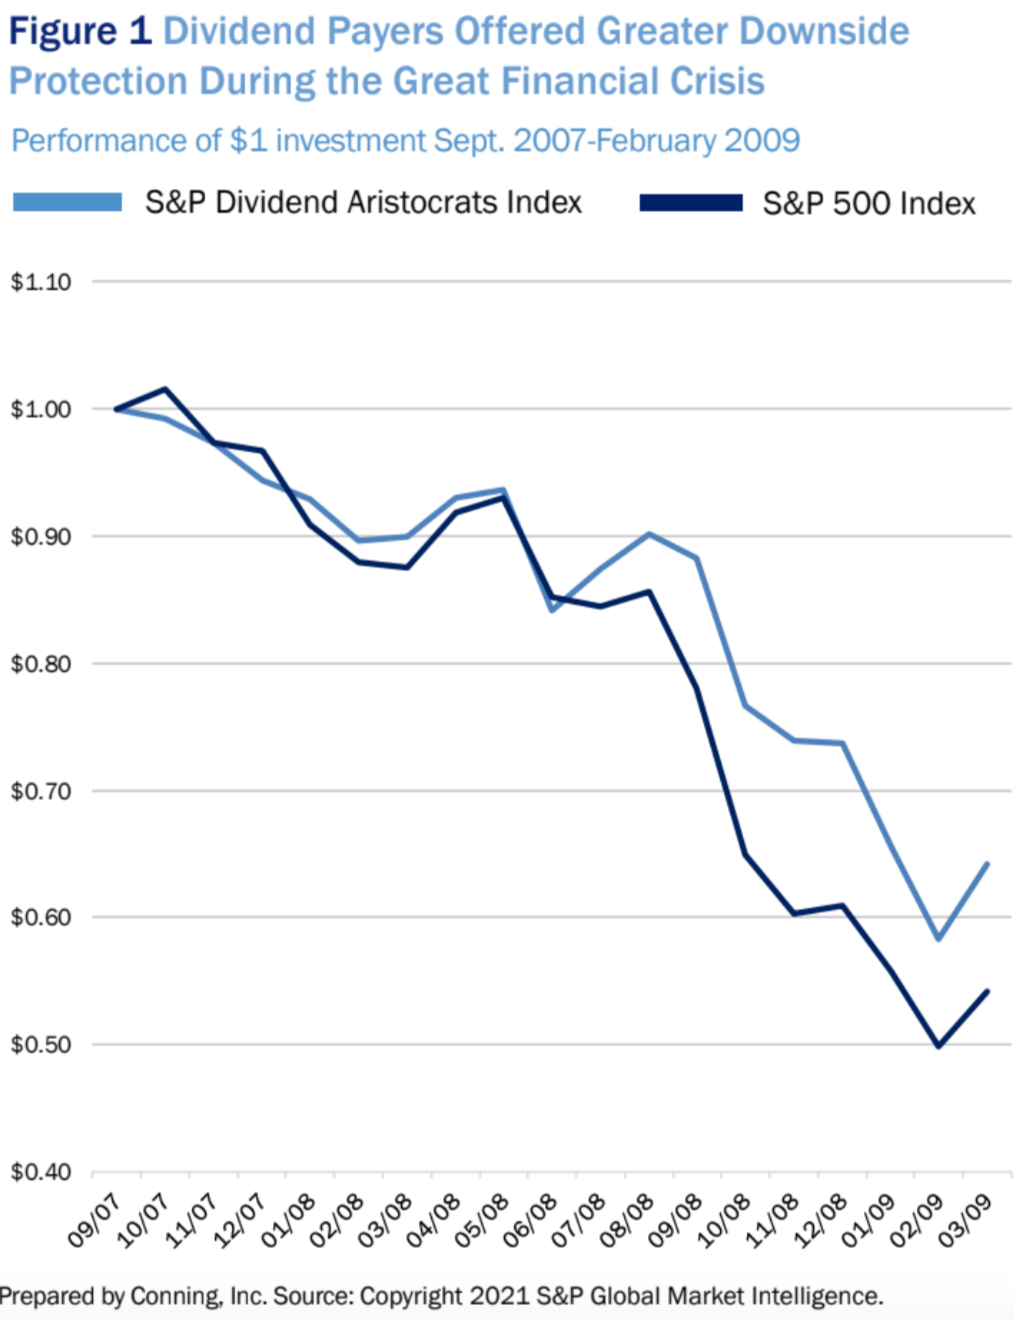
Dividend Payers Offered Greater Downside Protection During the Great Financial Crisis

In fact, dividend-paying stocks have outperformed in other downturns, as well, notably after the tech bubble burst in 2001 (see Figure 2). After the GFC caused interest rates to drop and equity yields to rise, insurance companies began to look for an equity investment solution that combined higher yields with lower volatility. Many turned to dividend-paying stocks.
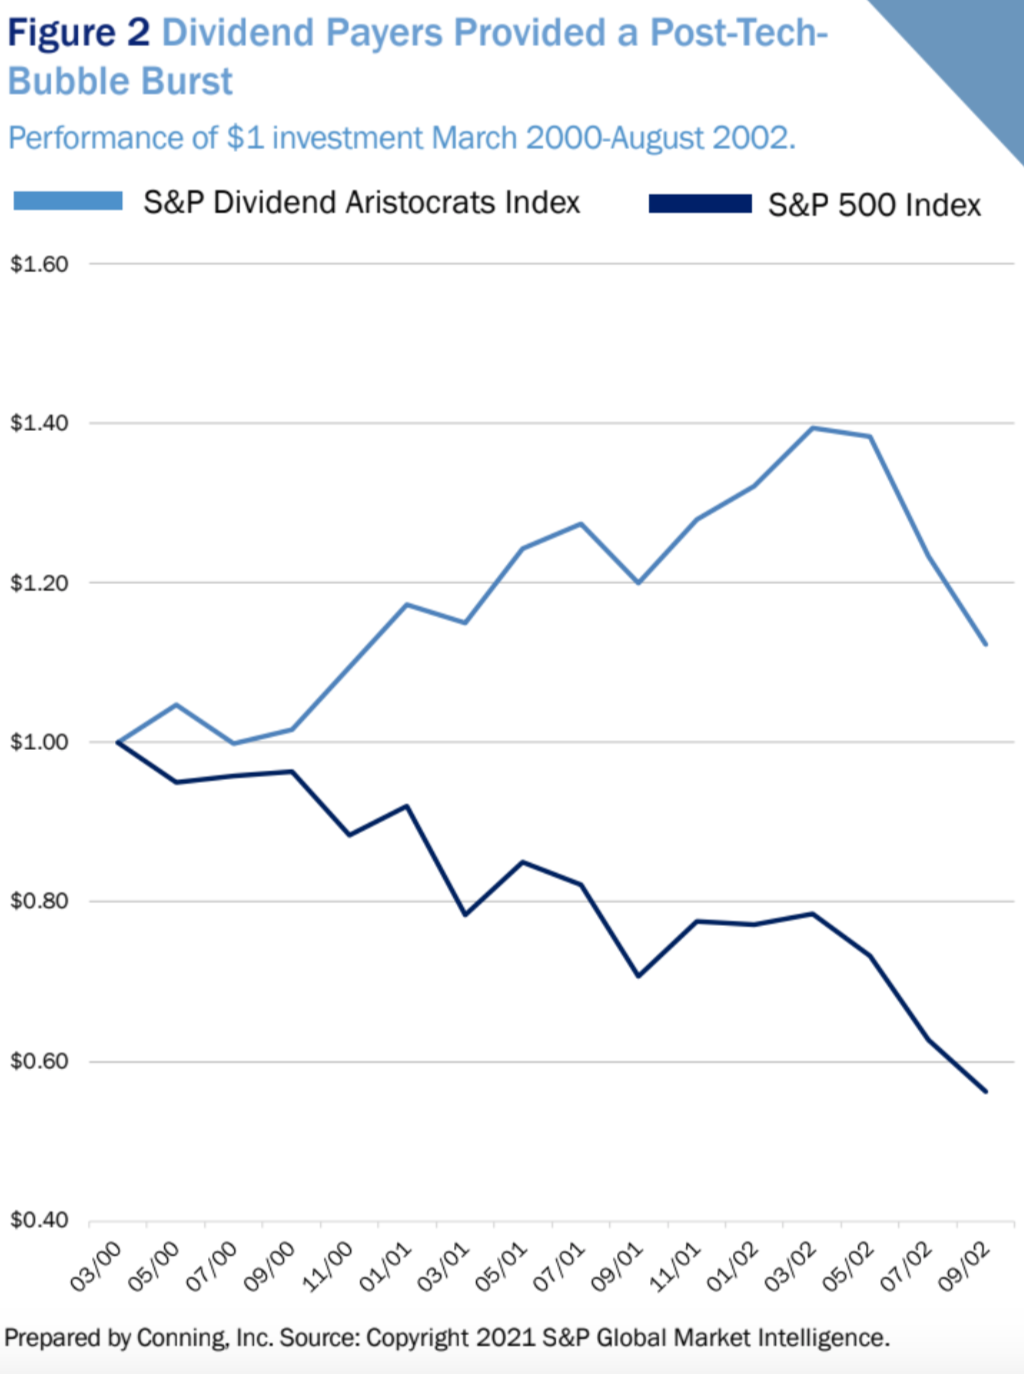
Dividend Payers Provided a Post-Tech- Bubble Burst

See also: Private Equity Drives Agency Change

Benefits of Dividend-Paying Stocks for Insurers 

Dividend-paying stocks can offer insurers several potential benefits, mainly steady income streams, lower volatility and some tax advantages.

Income Stream

Income-producing investments are very important for insurance companies and typically make up most of their assets. Companies often use this income to pay operating costs or increase earnings. Many dividend-paying stocks offer a consistent income stream paid on a quarterly basis. In fact, many dividend payers (unlike most fixed income securities) offer growing payouts by annually raising their dividend, while also offering the potential for capital appreciation if the equity market rises.

Lower Volatility

Equities tend to be riskier than bonds because the equity of a company represents a subordinate claim on the cash flows of a company relative to its bonds. As such, equity markets tend to loathe uncertainty because it calls into question the present value of these future cash flows. Within the cross-section of equities, though, dividend-paying stocks tend to have lower volatility. Because these stocks typically provide a cash payout each quarter, the level of return uncertainty associated with them is lower than for companies whose expected equity return is based solely on price appreciation.

Tax Advantages

Companies that receive dividends from their equity investments can take advantage of a tax rule that the average investor cannot. Known as the Dividends Received Deduction (DRD), this rule allows companies to deduct from their taxable income a portion (between 50% and 65%) of the dividends they receive from other companies. This rule applies to all dividends received except for those paid by real estate investment trusts (REITs) or other companies that are tax-exempt according to the Internal Revenue Code.

Tax-advantaged dividends tend to be a preferred source of funding from equities for these companies because the other source would be the sale of equity investments. Again, a good portion of dividends received can be deducted from taxable income, but equity sales will always generate either a capital gain (which is taxable) or a loss (which will reduce earnings).

Taken together, these three benefits provide a compelling argument for insurers to consider dividend-paying equities rather than an index fund representing the broader equity markets.

A “Shorter Duration” Equity

Insurers always face the risk of inflation, and that is especially true in 2022. Rising interest rates are also a reality now as the U.S. Federal Reserve has begun to aggressively raise rates and promises to continue this practice, with at least several more 50-basis-point increases expected in the near term, in an effort to tamp down inflation rates not seen since the late 1970s. Conning’s view is that most dividend-paying stocks will likely offer better protection in a rising rate environment than stocks that don’t pay a dividend.

Fixed-income investors are familiar with the concept of “duration,” which helps predict the behavior of bond prices as interest rates change. If we compare a 10-year bond that pays a coupon twice a year to a 10-year bond that pays no coupon until maturity (a “zero coupon” bond), we can see that the coupon-paying security will have a lower duration than the zero-coupon bond. As a result, the price of the coupon-paying bond will fall less than the zero-coupon bond as interest rates rise.

A similar case can be made that dividend-paying stocks are lower-duration instruments than non-dividend-paying stocks. In a general sense, any stock will have a higher time to maturity (essentially infinite) than any bond. As in many things, though, what matters is relative. With stocks, the analogy to the principal payment that is received when a bond matures is the price received upon the sale of the stocks. The intrinsic value of the stock is based upon the present value of the sale price and any payments received before the sale.

Because dividend-paying equities typically pay a consistent income stream in the nearer term while non-payers do not, dividend-paying equities effectively have the lower duration of the two groups and should be affected less as rates rise.

The relative relationship between the two groups of stocks (dividend payers versus non-payers) in a rising rate setting tends to hold up well across the economic spectrum, with a couple of exceptions. Stocks that pay very high dividends and also have significant debt on their balance sheets can be hurt more by rising rates than other dividend payers. For example, REITs, telecoms and utilities tend to suffer more as rates rise than less levered industries that pay more modest dividends. This implies that focusing investments on the very highest yielding stocks might not be wise in this environment. A strong argument can be made for investing in a broadly diversified portfolio of dividend-paying stocks to soften some price volatility during rate increases while still providing a competitive income stream (see Figure 3).
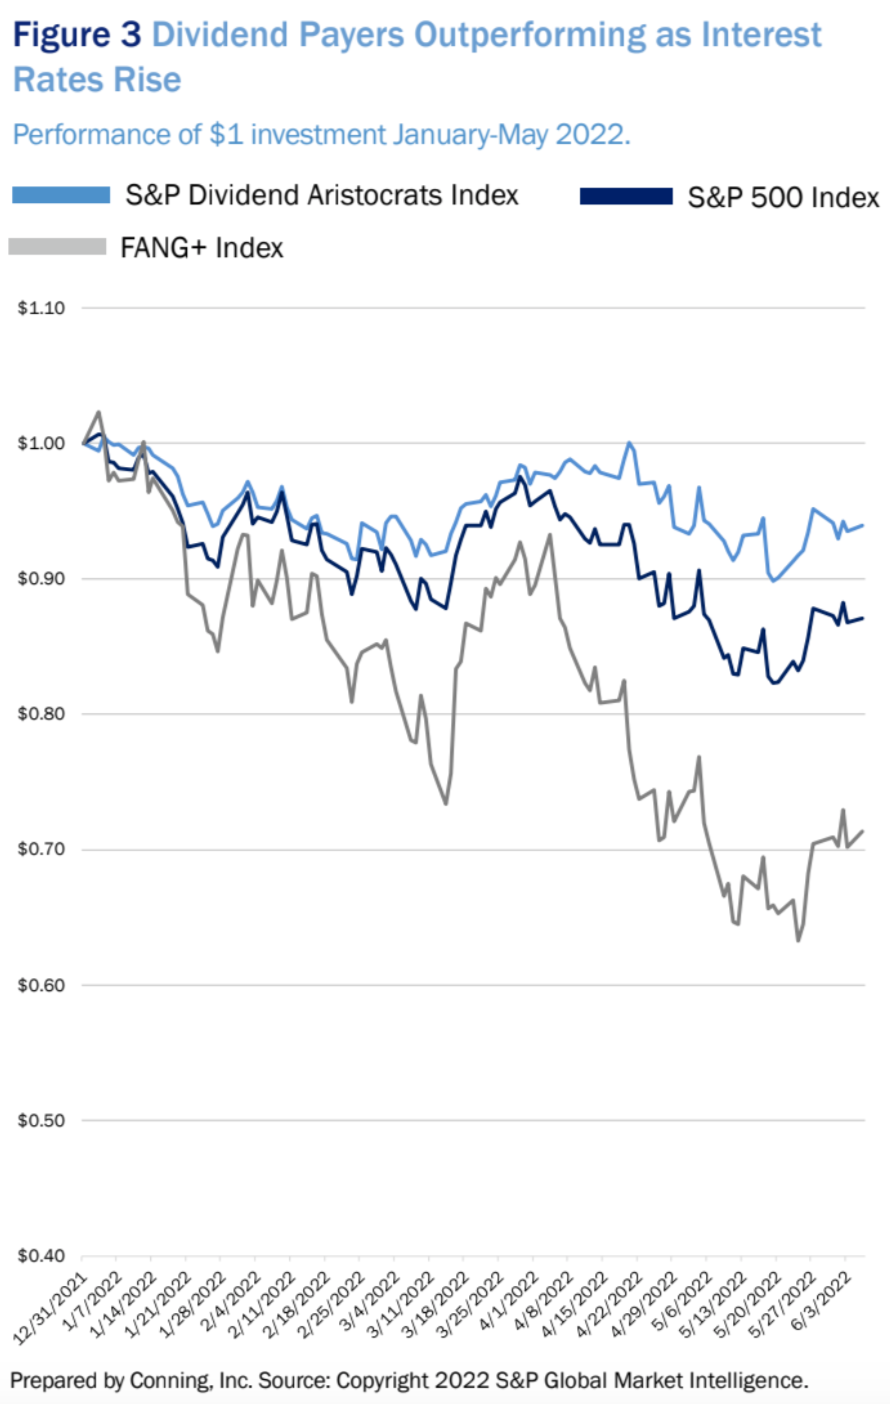
Dividend Payers Outperforming as Interest Rates Rise

Going Forward

History has demonstrated the potential benefits of equity investments for insurance companies. Passive strategies, though, have tended not to provide the income stream, lower volatility or tax advantages of a dividend-paying approach. In addition, many executives and investors have yet to experience a period of rising rates as sharp as is likely in 2022.

Income-producing equity portfolios may be a good fit for insurance companies but should be approached with caution. Not all income portfolios are created equal, and they can differ widely in terms of the consistency of income streams, volatility and tax advantages, not to mention sensitivity to interest-rate increases.

Many small and mid-size insurers may not have the capabilities or desire to manage equities internally and should consider an external manager to provide them the insights into these issues and to help them navigate through an environment that promises to be very volatile for the foreseeable future.

Risks of Dividend-Paying Stocks for Insurers

Equity prices will decline in bear markets. Potential changes in dividend tax rates could lessen demand for the asset class. A sharp increase in interest rates could affect prices of income-oriented equities.
Donald Townswick

Profile picture for user DonaldTownswick

Donald Townswick

Donald Townswick, CFA, is director of equity strategies, responsible for the development and implementation of equity investment strategies and is a member of the team managing Conning’s dividend equity strategies.

Prior to joining Conning in  2015, he was senior portfolio manager for global equity strategies at Golden Capital  Management. Previously, he was director of quantitative research for ING and a U.S. equities portfolio manager with INVESCO and Aetna.

Townswick earned a BS in mechanical engineering from the University of Southern California and an MBA from Vanderbilt University.

How to Reach Those 19 to 34 Years Old

Insurers can use AI and machine learning to offer to anticipate customers' needs as they progress through life events and their risk category changes.

Ball of connected lines signifying artificial intelligence

In recent years, insurers have begun to adopt digital initiatives to improve the customer experience, use data and analytics in key processes, introduce digital products and services and reduce operating costs. Despite the advances in how insurance is offered to the public, many people still do not have insurance. Most uninsured are 19 to 34 years old; can artificial intelligence have an impact with them? 

AI can detect those who do not have sufficient insurance protection. From there, companies can produce policy recommendations that can better fill gaps based on individual needs. Whether it be in the areas of health, auto or home -- the recommendations that are offered are adapted as the life situations of the policyholders change. In essence, the industry can use AI and machine learning to offer to anticipate the customer’s needs as they progress through life events and their risk category changes. 

Another way AI can help is through hyper-personalizing messages to the client. The old line is that insurance isn't bought, it's sold. And carriers struggle to engage the younger generation with relevant messages. AI helps educate individuals about the risk they may face, with the context, messaging and approaches that are meaningful to them. 

What contributes to individuals being uninsured? 

Two of the biggest barriers to getting insurance, for the customer, are cost and accessibility, according to a study conducted by Oregon Health and Science University, Department of Family Medicine. This issue can be mitigated with AI technologies. Rather than wasting everyone's time by wading through insurance policies that are not relevant to a person, the insurer can immediately recommend a package that makes sense to their personal lifestyle and background. By making insurance more approachable for those in the 19-34 age range, insurance companies can begin to narrow the protection gap and keep their customers covered. 

AI technology has already been available to help insurers better anticipate customers' changing needs, including major life events such as having a child, buying a home or achieving a milestone birthday. Over time, a person’s risk category changes just as their needs and priorities do, or the impact of weather patterns change, and they may not be aware of how their insurance policy needs to be updated. If they are uninsured, they may not know where to begin when it comes to choosing the right policy for themselves and their families. The insurance industry owes it to consumers to help them better understand insurance, their risk change, their coverage–it needs to be simpler.

With evolving technology, insurers are getting better at assessing real-time risk category changes. Because the AI teaches itself over time, it can study the needs of those from the uninsured population and target the types of policies they may need. This results in a more accurate representation of this population. There is also a significantly reduced need for human intervention. 

See also: Life Insurance and Millennials

Updating policies once insured with AI 

Previously, a person would have bought an insurance policy, then forgotten about it, only to later realize, when they need it, that their risk category changed years ago. Now, AI helps insurers assess risk changes for that individual, advise clients and prevent loss before it’s too late. This process allows the customer to be at ease, knowing that their policy will be subject to updates as needed. 

AI optimization can also include circumstances such as natural disasters; unfortunately, too many are left realizing that they are no longer covered after a disaster has occurred, such as occurred following recent wildfires in the West.  

Conclusion

If insurers are to reach the uninsured between ages 19 and 34, it is of utmost importance for insurance companies to make sure that their customers receive the services that they need, through an optimized process for connecting with each other. 

Insurers Are Taking Over the World

An insurance brokerage buys naming rights to the Pittsburgh Steelers' iconic stadium; autonomous drones are checking power lines; and more. 

Image
a picture of the earth from space

I thought I'd try something different this week: a series of shorter items rather than a longer exquisition. That's partly because I found a whole series of items worth pointing out but also because I need to note the news that sparked my headline about how insurers are taking over the world:

The stadium where my beloved Pittsburgh Steelers play will, after 21 years, no longer be called Heinz Field, after the local corporate food icon, and will instead be named after Acrisure, an insurance brokerage based in Grand Rapids, Michigan, that bought the naming rights. 

I had held out hope that the stadium would some day be named Hines Field, after longtime Steeler wide receiver Hines Ward, who, in my not-so-humble opinion, needs to be in the Hall of Fame, but I defer to the power of the insurance industry. 

Now, on to some developments on: how drones are being used to inspect power lines; how electric vehicles are reaching a tipping point that could have major implications for auto insurers; the arrival of a new generation of "digital assistants"; why insurance customers may cut spending; and how embedded insurance is providing what Swiss Re calls a "second act to insurtech."

Autonomous Drones Inspecting Power Lines

An article in Wired describes how drones are being used to take a look at pylons in the U.K. electric grid to spot issues that could, among many other things, cause wildfires. Crucially, these drones are autonomous. They don't have to be maneuvered by an operator. And they can be controlled from anywhere -- the operator, who can handle a fleet of drones at the same time, doesn't need to be out in the field. The drones remove the need for workers to climb towers to conduct inspections (time-consuming and dangerous) and allow for photos to be taken much closer up than is possible with helicopters at a small fraction of the cost. 

While the article focuses on the U.K., it also describes early uses in Florida, Norway and Sweden.

As a resident of California, which seems to have become the wildfire capital of the world, I'm all for anything that will reduce that risk.

Electric Vehicles Have Reached a Tipping Point

An analysis by Bloomberg finds that electric cars in the U.S. has passed a tipping point: accounting for more than 5% of new car sales. "If the U.S. follows the trend established by 18 countries that came before it," the article says, "a quarter of new car sales could be electric by the end of 2025. That would be a year or two ahead of most major forecasts."

Such a swift switch would have wide repercussions. Car makers, already retooling to build more electric vehicles, would need to accelerate the changes in their factories, supply chains, work forces, sales forces and more. EVs need less maintenance than cars with internal combustion engines (many fewer moving parts), so those that service cars will see business diminish. 

Insurers will, as usual, have to adapt to the new realities of all those businesses and individuals they insure. They will also have to deal with the fact that EVs are more expensive to repair -- and will likely widen the difference with conventional cars because the massive batteries will be able to power many more (delicate and expensive) sensors and safety devices.

The change will also create uncertainty as the ground shifts in such a major industry. Who knows, all the new EVs flooding the market might even affect a certain individual who made most of his record-breaking fortune with an EV named after a Serbian-American inventor and who may or may not buy Twitter. 

New Generation of "Digital Assistants"

I've been a skeptic about digital assistants ever since tech types started geeking out about them three decades or more ago. No, I don't want my refrigerator ordering milk for me. I can buy milk all on my very own, thank you very much. Now, we're in business if, while I'm in a store, the refrigerator can tell me how much is left in the carton and that I not only have cilantro but that it hasn't melted into mush in my produce drawer. But the vision for "assistants" has really been about devices that would take control, so they missed on two counts: They didn't know enough to actually be able to take control of my whole refrigerator, let alone of more complicated parts of my life, and I didn't want to give up control even if they did know enough.

But a kinder, general, less obtrusive generation of digital assistants may be on its way. A Fortune newsletter quotes one of the AI developers as saying, “If you had another person on your team, what would you shamelessly ask them to do? That’s what we want this software to do.” 

In a demonstration that a developer has posted online, the article says, "software uses a basic SQL database to perform a variety of tasks. A user types 'can you grab the name and population for every country?' and the software goes ahead and pulls that data from the database and assembles it in a simple table. Then a user asks the software to 'make a bar plot of that,' and the software does so. But the plot is hard to read because it contains too many countries. So the user asks it to just 'to show the countries with the six highest populations,' and the software comes right back with a much easier-to-read chart. This time, though, the labels for the six countries are overlapping, which still isn’t great. So the user types, 'Good. But the x axis is still a bit hard to read, can you fix that?' And remarkably, the software does so—by writing the labels on an angle—even though the feedback from the user was not that specific. Later in the demo, the software grabs publicly available U.S. unemployment figures from the internet and charts those."

Don't add a digital assistant to your Christmas list just yet. I've been promised one repeatedly since the late 1980s. But these kinds of digital assistants should be available in some form in a few years -- and I'd actually use one.

Will Customers Cut Spending?

Just a quick data point here for those interested: A Guidewire survey found that:

"With most people (86%) concerned about the cost-of-living crisis, many are considering how to cut back. For almost half of insurance customers (48%), that will be insurance cover that they are not legally obliged to have. Policies likely to get the chop are cover for travel (18%), home contents (17%), and bicycles (16%)."

Embedded Insurance and a "Second Act to Insurtech"

Another pointer for those interested: A rich look at the prospects for embedded insurance, based on a conversation between Sebastien Bert, co-head of strategic partnerships for the Americas at Swiss Re, and Carrier Management.


If you've made it this far and have an opinion on this week's use of short items, whether good or ill, please let me know.

In the meantime, I'll be commiserating with my fellow Yinzers about the loss of an iconic name on the Steelers' stadium while assuring those I know that insurance brokerages are good people, too.

I do worry that Pittsburgh fans will have trouble pronouncing Acrisure while screaming at their TVs in the fourth quarter of a nail-biter, after perhaps one or two too many Iron City beers, but that should be the least of our worries this year, now that we have no idea if our quarterback will be any good. Don't get me started....

Cheers,

Paul 


How to Tailor the Customer Experience

Here are three tips on how to get past a one-size-fits-all approach and take a personalized approach to customer needs and desires. 

Man on his phone while sitting down

Many insurance companies are realizing a one-size-fits-all approach to customer needs is out of date. 

Call it the Amazon effect. Customers need speed, service and selection—all at once. Spurred by the pandemic, consumers are rethinking how they spend their time. Inflation, too, has people scrutinizing their spending. 

Today’s insurance companies must deliver the efficiency of technology and the personalization of human interaction. It’s no secret that many insurers need to improve their customer experiences. But often, they don’t know where to start.

Digital transformation can be the key to keeping customers satisfied. 

Digital Transformation: A Billion-Dollar Opportunity

According to Accenture, the insurance “switching economy” – revenue up for grabs due to consumer spending patterns and switching rates – is booming. Accenture estimates that nearly $500 billion in life insurance and property and casualty insurance premiums are in play “as a result of declining customer loyalty and the perceived commoditization of products.” 

McKinsey found that a large, established insurance company could double its profits in five years by digitizing its business. Companies that fail to embrace digital transformation risk turning their offerings into commodities. 

In an industry where hundreds of billions of dollars are up for grabs, investing in digital innovation is not optional. 

New Table Stakes: What Insurance Customers Expect

Active Digital and Harris Poll found that 88% of customers value an insurance carrier that customizes communications. Eighty-six percent want to interact with their insurance company through all digital channels. Additionally, 79% of customers agree that having a person available to help them online or through an app would make them choose one insurance company over another.  

According to IBM, three key steps that marry technology with personalization can help deepen the company-customer relationship. These include leveraging data to personalize customer experiences, using AI throughout the customer journey and interacting with customers at the right time and place through contextualized content. 

What Today’s Best-In-Class CX Looks Like

More insurance companies are turning to digital-driven, customer-centric models that focus on customer experience (CX). According to IBM, 85% of insurers use CX initiatives throughout the customer journey, and 90% of companies have a C-suite position dedicated to the consumer experience.

Focusing on CX helps insurers compete on more than just price. McKinsey found that better CX can promote sustainable growth and drive profits faster than raising advertising spending or lowering prices. 

Further, McKinsey found that car insurance companies offering best-in-class CX doubled and even quadrupled new signup volume and saw profits 30% higher than those that didn’t. Satisfied customers are 80% more likely to renew their policies than unsatisfied customers. 

Employee Engagement Builds Customer Loyalty 

Employees are a crucial ingredient in your customer-centric digital transformation. Employee enablement and customer experience are two sides of the same coin. 

Insurance Innovation Reporter found a strong inverse relationship between employee turnover and employee satisfaction and productivity. The more stable your talent roster, the better your customer experience. 

The connection between employee engagement and customer experience is more crucial in the insurance industry than any other. Engaged employees deliver better customer experiences. Happier customers have a higher lifetime value due to their willingness to buy more, their tendency to refer more and their generally lower service cost. 

See also: The Rules of Digital Transformation

Meet Employee Needs and Enhance CX with Digital Transformation 

How can digital transformation improve customer experience and promote employee enablement? Here are some tips for approaching digitization with the customer in mind. 

Tip 1: Make Your Company More Available to Customers

Insurance companies must meet customers where they are – even if it’s a new venue for the company. These include social media platforms like Twitter, Instagram and TikTok or messaging platforms like Facebook Messenger, SMS, WhatsApp and Telegram. 

Not sure where to begin? Focus on personal connection and integrating existing channels. Improve transparency with automated updates on processes and payouts via email, SMS or messaging. 

Expanding self-service options can improve customer satisfaction while freeing employee bandwidth. For example, invest in help content or publish resources such as a list of approved vendors to help customers get the answers they need faster. 

Use technology to classify customer needs and requests. Consider implementing "rules" that organize and rank all incoming claims. For instance, customers appreciate it when simple claims are solved quickly. 

Tip 2: Mix Technology With Personal Touch

By combining the efficiency of self-service with the warmth of personalization, insurance companies can increase productivity and cement customer loyalty. 

How? Digitally minded insurance companies must streamline the quote, claims and signup processes. Automation can reduce the cost of the claims journey by 30%. Adding online claims reporting lets you streamline the process by asking fewer questions and leveraging technology that delivers dynamic adjustments. 

But you also must ensure customers have a reliable way to access a human. Maintain a robust online presence but have real, informed agents behind each profile, ready to address questions and complaints.

Tip 3: Seek Feedback, Stay Flexible

Customer-centric digital transformation is dynamic. It’s not something you do once and then stop thinking about. Instead, it is an iterative process that improves with continuous assessment and feedback from employees and customers. 

Insurance companies pursuing digital transformation must provide more touches over the customer lifecycle. When insurance companies initiate contact outside the standard signup and renewal conversations, it signals to customers that their insurance company is active, available and on top of things. 

Insurance companies should provide talent with training and development opportunities. This shows employees that their employer is committed to helping them succeed. 

Technology can do things people can't and vice versa. When insurance companies embrace digital transformation while centering customers, they can unlock unprecedented levels of loyalty and longevity.


David Antoline

Profile picture for user DavidAntoline

David Antoline

At Active Digital, David Antoline drives and oversees the company’s go-to-market motions, client partnership and success motions, solution and delivery capabilities and thought-leadership efforts. He also focuses on ensuring corporate operations and talent teams are well-aligned with the needs and pace of Active’s growth and delivery organizations.

Now Comes 'Retaliatory' Ransomware

A new wave of attacks is being driven by politically motived cyber mercenaries seeking revenge -- and may presage a full-fledged cyber war.

Lock icon on a computer screen showing ransomware

At the beginning of the Ukraine conflict, ransomware gang Conti issued a statement threatening to deliver "retaliatory measures in case the Western warmongers attempt to target critical infrastructure in Russia." A few months later, a separate hacker group launched an attack with the following message for its victim: "You're the most widely used payment application in Russia, so the reason we've selected you for targeting should only be obvious.... Your files have been encrypted, you can thank Conti for that... If you're looking for someone to blame for your current situation, look no further than Vladimir Putin."

In light of the current Ukraine conflict, more and more ransomware gangs are beginning to issue political statements alongside their demands. This may create some issues for both the hackers and their victims, as these messages run an increased risk of triggering the "war exclusion" contained within all cyber insurance policies. A typical war exclusion will read as follows:

"Alleging, based upon, arising out of, directly or indirectly caused by, resulting from, or in connection with war (whether declared or not), invasions, hostilities, civil war, strikes or similar labor actions, acts of foreign enemies, terrorism, hijacking, warlike operations, rebellion, revolution, insurrection...".

Attacks issued with political statements are more likely to be perceived by insurers as hostile or warlike actions indirectly caused by, resulting from or in connection with the war. Remember, often "war" does not need to be declared. If these statements do trigger the war exclusion within the victim's cyber insurance policy, it could make it more difficult for a ransomware gang to collect their ransom, given that their target may be more reluctant to reach into their own corporate pocket to pay any extortion demand.

So why are groups making such statements? While it may be an oversight, or they may not realize the potential insurance implications in doing so, that's unlikely. Hackers are well-versed and have been known to specifically target companies that maintain cyber insurance. It's more likely that these new attacks are simply motivated more by political/ideological interests versus purely economic gain. The statement being made is the primary goal, with the monetary reward secondary. In addition to political retaliation, some of these statements may also be the result of feuding hacker groups, with their victims being caught in the crosshairs.

There may be an even more sinister explanation. It's also possible that the hacker groups understand that such statements have the potential of negating insurance coverage. Launching an attack and attempting to force the targeted organization to personally pay the demand, more effectively strikes at the hearts of their victims.

Regardless of the reason, such statements would appear to indicate this new wave of attacks is being driven by politically motived cyber mercenaries seeking retaliation and revenge. The bigger question is, if this is indicative of more aggressive impending attacks, or a precursor to a full-fledged cyber war.

There may be some hope. Most cyber insurance policies contain carvebacks, excepting (to the policy exclusion) acts of "cyber terrorism." A typical carveback may read as follows: "cyber terrorism means, use or threatened use of disruptive activities against the insured's computer system committed with the intent to further stated social, ideological, religious, economic or political objectives."

See also: Ransomware Grows More Pernicious

Insurers have been fairly reluctant to cite the war exclusion, but a surge of attacks could make them reconsider. The question is, will these statements be enough to justify the attacks as acts of "war" (and excluded by the policy), given that they are hostile and warlike actions in support of the war? Or will they be perceived acts of "cyber terrorism" (and covered by the policy), given that the hackers appear to be using disruptive activities to further their stated political/ideological objectives?

This is something the courts may ultimately have to grapple with, but the decision may come down to the exact phrasing of the statement itself. In the example of the statement issued by Conti, they clearly state "retaliation against attacks by western warmongers." Such phrasing may be more likely to be deemed a retaliatory act of "war." The specific ransomware gang itself may also play a role. Attacks launched by suspected state-sponsored actors with ties to a foreign government (such as Cozy Bear and Lazarus) are more likely to trigger the war exclusion, especially when their attacks are accompanied by political or warlike statements.

In the interest of maximizing insurance coverage for retaliatory ransomware, there are a few steps companies should take. In addition to implementing advanced security measures and implementing comprehensive policies and procedures, the C-suite should also perform a careful assessment of its cyber insurance policy, ensuring its terms and conditions pertaining to cyber extortion are as broad as possible. Additionally policyholders should pay special attention to the "war exclusion," given that all policies contain different versions -- some more problematic than others. In the meantime, hackers can do themselves and their victims a favor by refraining from such statements when making extortion demands.


Evan Bundschuh

Profile picture for user EvanBundschuh

Evan Bundschuh

Evan Bundschuh is a vice president at GB&A. 

It is a full-service commercial and personal independent insurance brokerage with a special focus on professional liability (E&O), cyber and executive/management liability (D&O). 

An Interview with Joel Zwicker

"Many agencies will say, well, we have two policies per client, so we've done a really good job because the industry average is around 1.62. But if my agent only has two policies with me, he's left well over half my business on the table."

a graphic with the words insurance, insurance policy and health insurance written on paper slips. Superimposed on top of the image there is  blue background with white lettering that reads "an interview with Joel Swicker and the insurance thought leadership logo"

ITL:

It has always seemed to me that marketing is a tough thing for agents and brokers. Customers can be told what the products are and what brands the agents are representing, but how can you communicate, believably, what level of service you’ll provide, and how can the customer know whether they’ll click with the agent?

Joel Zwicker:

People choose an independent agency for two reasons: It is your expertise, and it is the relationship. That’s how agencies need to market themselves.

Far too many agencies forget that they have a whole book of business leads right in front of them. You have an acre of diamonds. Many agencies you talk to will say, well, we have two policies per client, so we've done a really good job because the industry average is around 1.62. But think about it: My family and I have five or six policies. If my insurance agent only has two policies with me, he's left well over half my business on the table. If you’re an established agency, you have more than enough opportunity sitting right in front of you.

Agencies need to remember they are in the renewal business. They should have a strategic communication plan to continually share their expertise, building deeper relationships that will maximize their book of business.

You also need to have niches. Too many agencies want to sell to anybody. The sexiest thing in the world is new business. But you’re just not going to wind up with more quotes than you could ever imagine. An agency needs to take a step back and truly understand who their ideal client is, then focus on that type of client.

ITL:

Let’s start with niches. It's fairly easy in commercial to think, Okay, I'm going to be the guy on landscaping businesses or pizza parlors, but it sounded like you were saying that the niche idea goes even beyond commercial. What would some niches in personal lines look like?

Zwicker:

Here’s one from personal experience. When I worked at an agency, we didn’t focus on traditional home and auto. Our niche was toys, things like cruiser motorcycles, classic cars, boats, snow machines and, off-road vehicles. So, we had expertise – and if someone has the disposable income to have a nice boat or a cruiser motorcycle or a classic car, chances are they have some nice properties and other things they want to insure, as well.

Another common one would be to take a private client-type approach, focusing on higher-end neighborhoods in your area or higher-end clientele.

Another niche is not necessarily the product that you're selling but the client experience. I can think of a client of ours whose niche is that the experience is all digital, through email, text and video. Everything is done in multi-step sequences that incorporate video so you can see, say, how to file an auto claim.

ITL:

Once you’ve picked your niche, how do you make sure the world knows you have that expertise?

Zwicker:

Here’s a commercial example, from my friend and our client whose niche is laundromats. If you were making a list of the top 10 niches that you're going to make money on like gangbusters, laundromats wouldn’t be on that list. But he knows them better than anybody. Why? Because he spent 20 years working with them, and that's what he's focused on. When he talks at events, when he writes white papers or posts on his website or blog, when he's doing an email, he demonstrates his expertise and stays focused on his niche.

Some people focus on contractors, but that’s a broad area. Specifically, do you do roofing contractors? Okay, let’s go deeper. Just commercial asphalt, or are we talking about hot tar?

Too many agencies try to be too broad with their expertise. Be specific. Find that area where you're really an expert. Then share stories about claims experiences or coverages you should be leery of, maybe highlight some other vendors that may partner with you.

ITL:

Now that you’ve identified your niche and demonstrated your expertise, how do you build the relationship so you generate more and more business from those clients?

Zwicker:

The vast majority of agencies have an incredible database of leads. It’s just being able to target them. It’s understanding when someone has commercial general liability but no cyber, property but no personalized home or auto, no umbrella… whatever the example is. You also keep in mind that there are other opportunities, too, in life insurance and annuities and financial planning if you nurture the relationship.

Simply remember why these people chose you in the first place: your expertise and your relationship with them. Then continue to share your and your staff’s expertise.

Here’s an obvious one that’s often the toughest thing to do: You ask for the business. Simply ask for the chance to discuss those other lines of business.

A lot of agents are afraid of annoying clients, or assume that everybody knows that you offer all these services. Assume nothing. Agents fear that, if I start asking, I’ll trigger them to maybe shop their insurances or go elsewhere. And I have to say that that is maybe one of the most ridiculous thoughts you should have in your head. If you think for a moment that an email, a text, print or a phone call from you, on a quarterly basis, asking about other business is going to trigger that person to shop elsewhere…. They’re already getting any number of imprints in their mind about what to buy, minute by minute, hour by hour, day by day, just by turning on the TV, listening to the radio or going online. Why would a simple request from you trigger them?

And here’s a powerful, easy way to talk to your clients: Ask them to assign you a Net Promoter Score. You see who really values you, and you know who would be most likely to respond if you ask for additional business. Combine that information with the data points in your management system about

what additional policies those customers might buy from you, and you have an awful lot of low-hanging fruit.

ITL:

Great stuff. Thanks, Joel.


a headshot of Joel Zwicker wearing a black button down shirt Joel Zwicker is insurance evangelist at Agency Revolution Suite and formerly an insurance agent at one of Canada's largest independent insurance agencies. He now works to provide independent insurance agents the best marketing tools for their unique needs.



Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

Gaps Found in Digital Strategies

A recent SMA study shows that 41% of personal lines insurers are revisiting their digital transformation strategies in 2022, a significant jump from 19% in 2021.

Triangle shapes over a light colored backround

The personal lines segment is known for leading the charge with innovations and technologies – a reputation that only strengthened during the pandemic. From digital underwriting submissions and virtual inspections to digital first notice of loss (FNOL) and other capabilities, personal line insurers were poised to meet the new digital needs of customers and employees when other industries struggled to adapt to the virtual era. However, in enhancing processes and workflows to adjust to the pandemic's demands, insurers also uncovered gaps in their digital capabilities, forcing them to reexamine their existing projects and identify new opportunities.

A recent SMA study shows that 41% of personal lines insurers are revisiting their digital transformation strategies in 2022, a significant jump from 19% in 2021. This heightened activity indicates the acceleration of the digital projects identified in SMA's new research report, "Digital Transformation in Personal Lines: Project Priorities for 2022 and Beyond."

Unsurprisingly, personal lines insurers are most focused on expanding policyholders' self-service capabilities. With the pandemic creating the essential need for capabilities such as obtaining a policy, paying a bill or filing a claim online, customers now expect sophisticated systems that allow them to interact with their insurers when and how they want. Half of all insurers focused on personal lines are also implementing digital platforms. Because digital platforms leverage application programming interfaces (APIs) and low- and no-code technologies that allow for connectivity from various channels, SMA is seeing more and more insurers of all sizes shifting from portals to platform technology. Other projects aimed at leveraging emerging technologies are also rising on the priority lists of personal lines insurers as they complete their upgrades of more foundational technologies.

See also: Foundational Tech for Personal Lines

Although signs point to continued digital transformation acceleration across personal lines in the coming years, competition will only grow fiercer as progress gains momentum. Insurers that pause their digital projects for too long risk falling behind peers, losing distribution partners and being dismissed by current or potential customers. To stand out in the saturated personal lines market, insurers must commit to modernizing capabilities to serve agents, policyholders and employees and push forward in their digital transformation journeys.


Deb Smallwood

Profile picture for user DebSmallwood

Deb Smallwood

Deb Smallwood is the founder and CEO of SelfPowerment.

She spent four decades in corporate leadership across the insurance industry, operating at the intersection of business, technology, and organizational transformation. Her leadership inflection point led her to research the experiences of more than 50 high-achieving women and 10 men leaders. This formed the foundation of her book, SelfPowerment: The Inner Shift for High-Achieving Women Who Want More Than Just Success. The work introduces a research-informed framework that redefines success from within and invites women to shift the question from, “Will they choose me?” to “Do I choose them?”

Vendors Up Their Game in Competition for Talent

When jobs are in high demand for both employers and prospective employees, it creates a hyper-competitive job market that requires a strategic approach.

two tall black buildings that show a reflection

Talent has been a front-and-center topic in boardrooms across the U.S. amid the pandemic, widespread resignations, a labor shortage and other trends challenging the recruitment and retention of employees. Yet, through the adversity, companies across the insurance ecosystem have adapted remarkably well, including the vendors that serve the industry.

Recently, SMA surveyed insurance professionals to understand how companies are approaching talent in 2022 and beyond. As a follow-up to SMA's research report focused on insurers' talent objectives, SMA has released a report that offers a fresh view of how technology/software vendors and services solution providers are shaping their talent strategies this year.

The technology sector has long attracted young professionals looking to jumpstart their careers. In fact, a study by Glassdoor found that most Gen Z job seekers are applying for tech-related positions. But when jobs are in high demand for both employers and prospective employees, it creates a hyper-competitive job market that requires a strategic approach. So, it is no surprise that insurance vendors consider attracting new talent as their No. 1 talent objective in 2022.

SMA's study shows that vendors have found new ways to recruit talent since the pandemic's start. Sixty percent of vendors reported recruiting from broader geographic areas as the primary change in their recruitment strategies in the past two years. This is a significant finding when considering that many technology/software vendors were ahead of the remote-worker trend when they employed personnel in various geographic regions pre-pandemic.

Another 40% of vendors stated they are using social media or are partnering with universities and associations to reach talent pools that may have previously gone untapped. But it is not enough to simply set new talent strategies – leaders at vendor companies must ensure their organizations are allocating resources, setting clearly defined goals and holding themselves accountable to be truly successful in their talent acquisition.

See also: In Competition for Top Talent, Innovation Matters

With the current competitive talent market expected to continue into 2023, it is critically important that vendors rethink their recruitment strategies in 2022 and the roles and skills needed to deliver products and services to the industry. There is now an opportunity to reevaluate traditional processes and redefine roles to provide a quicker onboarding experience and improve the organization's technology talent. The key will be achieving balance within teams as the industry is driven to expand its talent search well beyond the boundaries of insurance.

For more information on insurance vendors' talent strategies for 2022 and beyond, read SMA's recently published research report, "How P&C Insurance Vendors are Responding to the Battle for Talent.”  


Karen Furtado

Profile picture for user KarenFurtado

Karen Furtado

Karen Furtado, a partner at SMA, is a recognized industry expert in the core systems space. Given her exceptional knowledge of policy administration, rating, billing and claims, insurers seek her unparalleled knowledge in mapping solutions to business requirements and IT needs.

Why Agents and CPAs Must Collaborate

Insurers and accountants have similar concerns on behalf of clients, so the more agents and CPAs collaborate, the better. 

person at a desk working with a calculator and a laptop

As an accountant looking at the uncertain economy, I can’t help but say, “It’s an accrual world.” Joking aside, certified public accountants (CPAs) and insurers should do more to help clients in this economy, and, as a CPA, I know how insurance can help individuals and families. 

Whether following the loss of a loved one or a financial loss, life insurance is a lifesaver—truly. But if an insurance agent doesn’t have a chance to make this point, if he doesn’t know who needs help, a CPA can fill the gap. 

For example, if I tell a client he should buy life insurance to protect his family or lower his tax burden, I am not selling him anything. I am telling him what he should do, because it is right and because I don’t have a conflict of interest. CPAs who take a similar approach are why 86% of small business owners say their most trusted adviser is their accountant.

If I refer a client to an agent, it’s because of a specific policy an agent offers.

If I don’t know how a policy works, or don’t understand what an agent says about the workings of a policy, I will recommend a different policy or agent. The point is, I want to help my clients, and I know insurance can be a valuable form of help. But I must first communicate with my clients, which is why I read news and books to expand my knowledge.

In turn, insurance agents must communicate with CPAs, too.

Collaboration is everything. That is, if an agent emphasizes the tax benefits of a policy, he should encourage clients to consult with a CPA. If the benefits are clear, let a CPA say the same; if the terms are reasonable, let a CPA come to the same conclusion.

The more agents and CPAs collaborate, the better. 

See also: Ready for New Accounting Standard?

If collaboration improves communication, making it easier for everyone to explain or understand the importance of insurance, society will be better off.

Insurers must take the initiative, however.

As a whole, the insurance industry needs to contact and build relationships with CPAs.

The relationship is mutually beneficial, because it increases a CPA’s network of potential referrals. This network also allows CPAs to call on insurance agents. The result is a network of trust, for the good of clients and agents and CPAs alike.

Creating this network is not expensive, thanks to industry directories, social media, existing contacts and the internet in general.

The only thing necessary to create this network is action.

CPAs and insurers need to act, even if the act is nothing more than a phone call or letter (via email) of introduction. This act alone may be enough to establish a  conversation; and something—something positive—is better than nothing.

This network can help clients prepare for or protect themselves from the uncertainties of the economy.

Whether the economy worsens or inflation rises, no matter how bad things get, CPAs and insurers can plan for—and avoid—the worst.

Working together, both industries can be models of collaboration and communication.

The two can inspire more industries to follow their example, putting CPAs and insurers at the forefront of innovation.


Romeo Razi

Profile picture for user RomeoRazi

Romeo Razi

Romeo Razi, CPA, is the founder of TaxedRight.com.

With degrees in computer science and accounting, he is a former IRS revenue agent. Due to his background in computer science, Razi is well-versed in insurance, startups, funding and the changing landscape of tech.

Inflation and the Auto Insurance Outlook

Auto insurers should expect higher claims costs in the second half and longer wait times for damaged vehicles to be repaired and returned to their owners.

multiple cars on a freeway

2022 has been another roller coaster ride. Inflation hit a 40-year high in February, and, according to the World Bank, global growth in 2022 is expected to decelerate from 5.5% to 4.1%. We can blame continued COVID-19 disruptions, supply chain bottlenecks and anticipated higher food, gasoline and energy prices, combined with worker shortages and recent geopolitical issues related to the Russia/Ukraine conflict. 

But before we talk about what this means for auto insurers in the second half of the year, we need to go a bit deeper into the causes of the current inflation crisis.

First, supply shortages caused by the ripple effect of COVID shutdowns on manufacturing and distribution centers in multiple geographies have affected nearly every industry. For instance, I recently looked into buying furniture and learned that, not only would it take up to four months to arrive, but I’d also have to pay 20% more than I’d have had to pay last year. 

The auto industry is no different. Parts shortages are so severe that Ford had to shut down its Flat Rock assembly plant for more than a week because it could not secure enough chips. If manufacturers can’t get parts, the situation is going to be at least as severe for repair and body shops. For auto insurers, this means they should expect higher claims costs in the second half of the year and longer wait times for damaged vehicles to be repaired and returned to their owners. Prices for auto parts will definitely continue to rise, given manufacturing shortages and distribution delays. 

Auto repair costs 

What’s more, auto body and repair shops are facing the same labor shortages and increasing wage pressures that every other business is experiencing, further increasing costs for repair. In response to the labor shortage and other factors fueling inflation, the Federal Reserve voted to raise rates by half a point in May, the largest increase in more than two decades -- then three-quarter point in June. But the increases will take time to have an effect and are unlikely to temper auto claims costs much in the next six months.

Another factor to consider is how companies entice the last of the pandemic’s workforce dropouts to jump back into the job market. According to JP Morgan Chase, continued strong demand for labor should attract those workers, but demographic trends may still drive a long-term worker shortage. Moreover, even a return to pre-pandemic labor market participation rates and higher wages won’t reverse the aging of the American workforce or the slowing of immigration flows. As a result, businesses will need to invest in technologies that allow smaller teams to be more productive. 

Thankfully, used-car prices have begun to decline from the eye-popping heights they reached last year. Cox Automotive reports that used vehicle prices declined 1% in April over March, marking the third straight month of declines. But prices are still close to twice what they were over the previous decade. So while auto insurers may see a bit of relief in the second half of the year in the cost of replacing a totaled vehicle, costs will still remain historically high.

See also: What to Do About Rising Inflation?

Roadside assistance

But these are not the only costs that insurance carriers should expect to rise. Roadside assistance claims may not be a large share of total claims by amount, but they are by far the most common claims by volume. And inflation is having a large impact on the towing and roadside industry. 

After auto usage and road volume declined to unprecedented lows in 2020 due to the pandemic, motorists have significantly increased how often they drive and even changed their driving behavior now as public health measures have loosened. According to the U.S. Federal Highway Commission, traffic volume in November 2021 was up 11% year over year and is continuing to climb in 2022. 

A recent survey we conducted of tow providers found that 22% have more work than they can handle, which has led to dispatching delays and longer wait times for motorists stranded on the side of the road in some areas. Continued worker shortages, equipment shortages, higher fuel costs, higher maintenance costs, pandemic-related issues and inflation may affect high-performing towing and roadside program performance metrics, service-level agreements (SLAs) and pricing moving forward. As a result, towing and roadside rates in H2 2022 will continue to rise, with rates increasing across the US.

Additionally, conditions have prompted nearly three-quarters (73%) of tow providers to prioritize work. And while one might expect that their top priority would be to jump on the most lucrative jobs or contractual obligations, their No. 1 choice was to do the closest jobs first. In this way, tow providers can spend less on fuel, and each truck can complete more jobs per day, increasing both revenue and profit.

When service providers have more work than they can handle, that results in longer wait times for stranded motorists. Unfortunately, longer customer wait times lead to unhappiness, which has a domino effect by lowering net promoter scores (NPS). Since the return of pre-pandemic driving patterns, traditional motor clubs and other roadside providers have started to struggle to meet the demands of their clients, while those who rely on algorithmic systems that find the nearest provider have been able to protect their NPS ratings and, consequently, the customer satisfaction scores of their insurance partners.

The Outlook for H2 2022

The next six months will prove challenging for auto insurers when it comes to costs. The economy will have to overcome current downside risks, including simultaneous Omicron-driven economic disruptions, further supply bottlenecks, a de-anchoring of inflation expectations, financial stress, climate-related disasters, geopolitical conflicts and a weakening of long-term growth drivers. If this doesn’t happen, unfortunately, inflation will continue to drive up prices for all services.

A few positive signs are on the horizon. The measures taken by the Fed and the trending decline in used car prices point to some possible relief from inflation in 2023.

In the meantime, carriers will need to take measures to control costs and increase efficiencies.


Rochelle Thielen

Profile picture for user RochelleThiele

Rochelle Thielen

Rochelle Thielen is chief revenue officer at HONK, which provides a next-generation roadside assistance platform for motorists, insurers and fleets.

She previously served as CEO of Estify and in senior positions at Mitchell.