Download

HOW MGAS AND E&S CARRIERS CAN THRIVE

MGAs and E&S carriers are thriving, and they have lots of runway in front of them. They can continue to exploit their deep understanding of market niches, can drive efficiencies in the often-cumbersome underwriting process and can increasingly fit into insurers' processes by being at the forefront of APIs.

HOW MGAS AND E&S CARRIERS CAN THRIVE


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.


Intellect AI

Profile picture for user IntellectAI

Intellect AI

IntellectAI is a suite of contemporary artificial intelligence products and data insights triangulated from thousands of sources for commercial underwriting offered through Intellect Design.  The IntellectAI products take a strategic approach to tackling the biggest challenges for the industry. We are a proven leader in Data First Strategy for commercial underwriting.  

Our underlying technology powers sophistication with simplicity ensuring an engaging and insightful user journey. Our AI cloud native products are known to address the most complex business objectives with the highest accuracy of outcome. Our skilled technical experts and data scientists seamlessly augment our customer teams to accelerate their transformation journey easily adapting as business models and technology evolves. www.intellectai.com

Insurtech Must Be Taken Seriously

Many incumbents are doubting their insurtech efforts, but the recent drop in stock-market valuations is not about insurtech, it is about tech.

Abstract photo of what looks like pieces of glass

We have seen the evaluations of the listed insurtech startups falling more and more over the past year. The HSCM Public InsurTech Index (HPIX) presented to the market 14 months ago is down by almost 65% from its maximum.
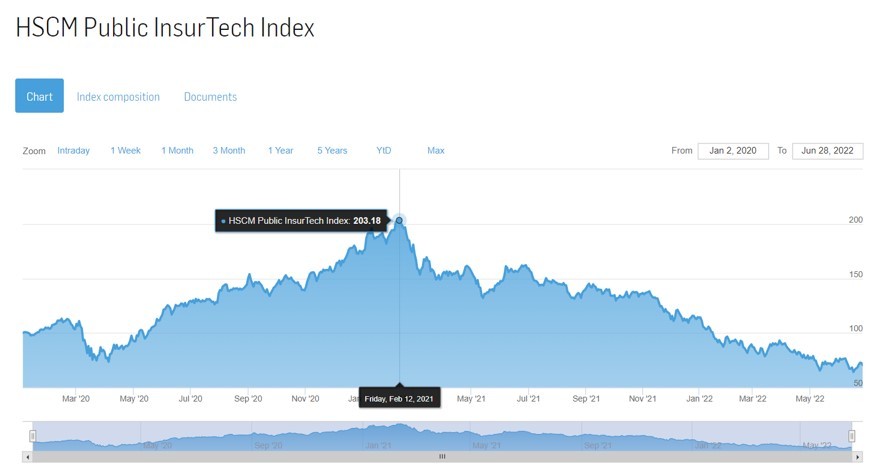
HSCM Public Insurtech Index

This has led some incumbents to doubt their insurtech efforts and the priority (and budget) assigned to the innovation initiatives. I've felt this speaking to insurance executives at conferences, and you can check how the tone has changed on many earning calls and in analyst presentations by insurance incumbents over the past six months.

This is why I take extremely seriously the following statement from venture capitalist Marc Andreessen: "The minute tech stocks get hit, a lot of big companies basically say, “Oh, thank God, we don’t have to take this stuff as seriously”.

Please, my fellow insurers don't make this mistake!

1) The market has NOT turned its back on insurtech. 

The drop in the valuations is not about insurtech, it is about tech.

Let's compare the insurtech index with Global X FinTech ETF (FINX), ARK Innovation ETF (ARKK), and iShares U.S. Technology ETF (IYW). 
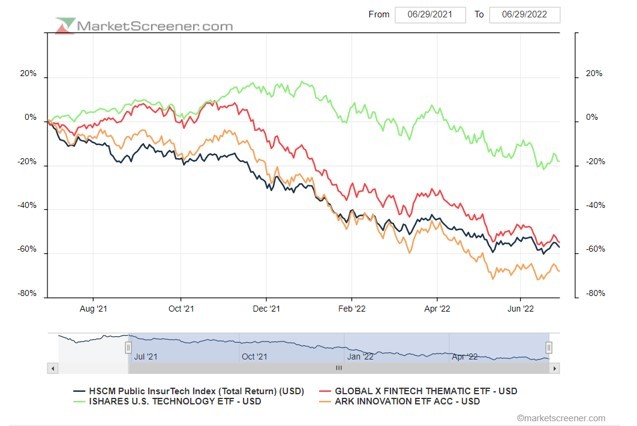
Chart comparison of insurtech indexes

Revenue multiples for tech companies tell the same story. Here is the reference.
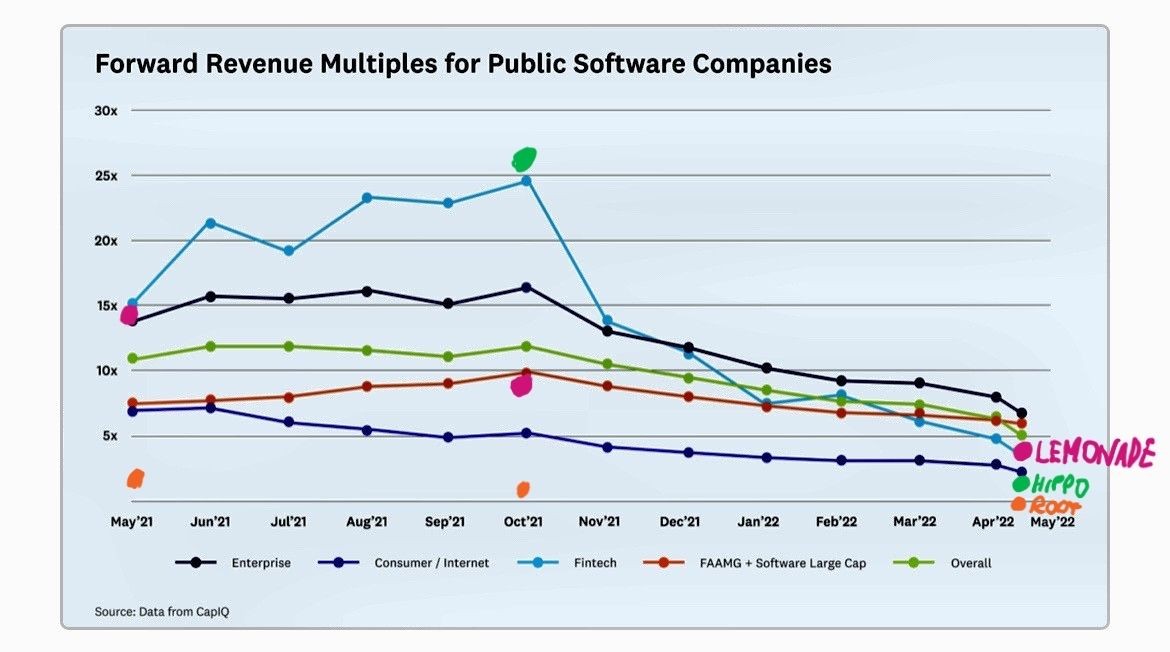
Forward revenue multiples for public software companies chart

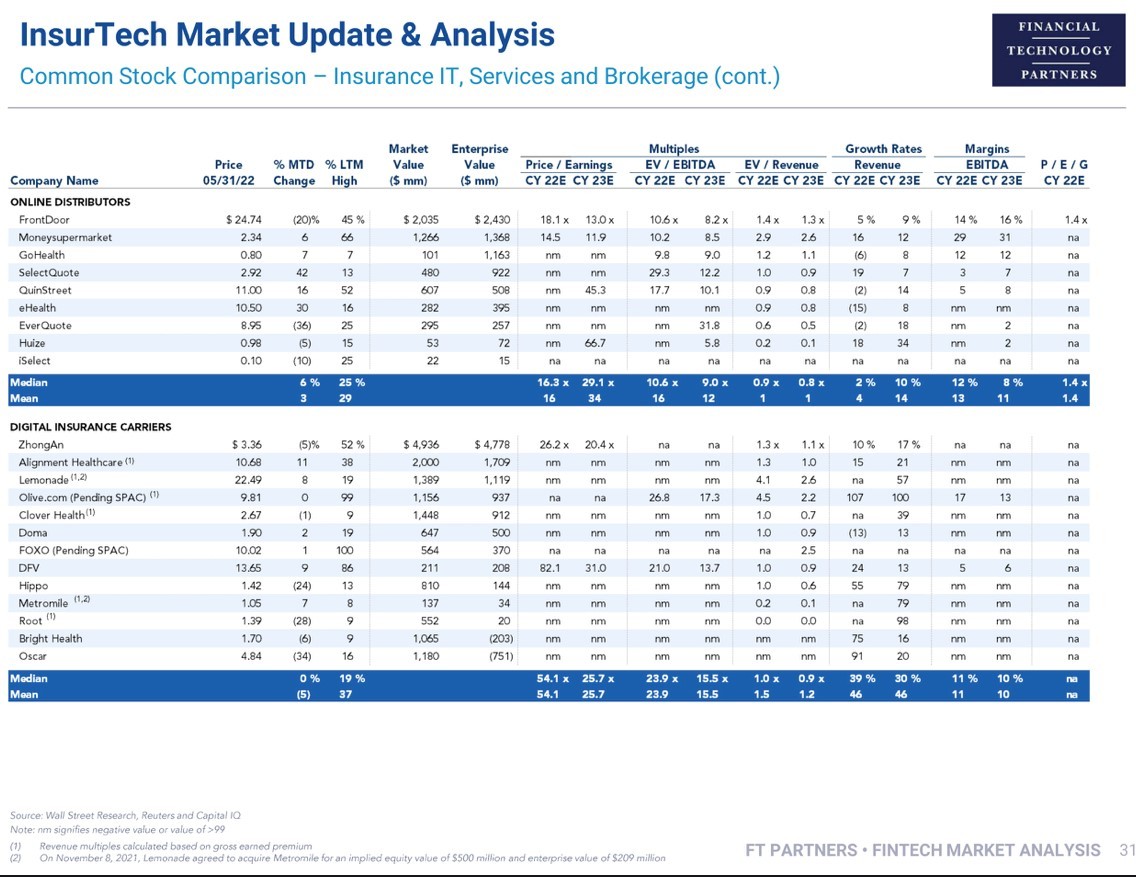
Insurtech market analysis chart

As Rob Moffat says: "Reports of insurtech’s death are greatly exaggerated…"

2) Insurtech investments are paying off.

Incumbent insurers have always been evaluated for their growth and their profitability. Well, there is great news for all my friends working on innovation in their insurance company: Innovation delivers higher growth and better combined ratios!

This has been clearly shown by AM Best's deep and robust analysis of the performance of the best innovators (innovators), the average (moderate) and not innovative (minimal) in the insurance property and casualty sector.
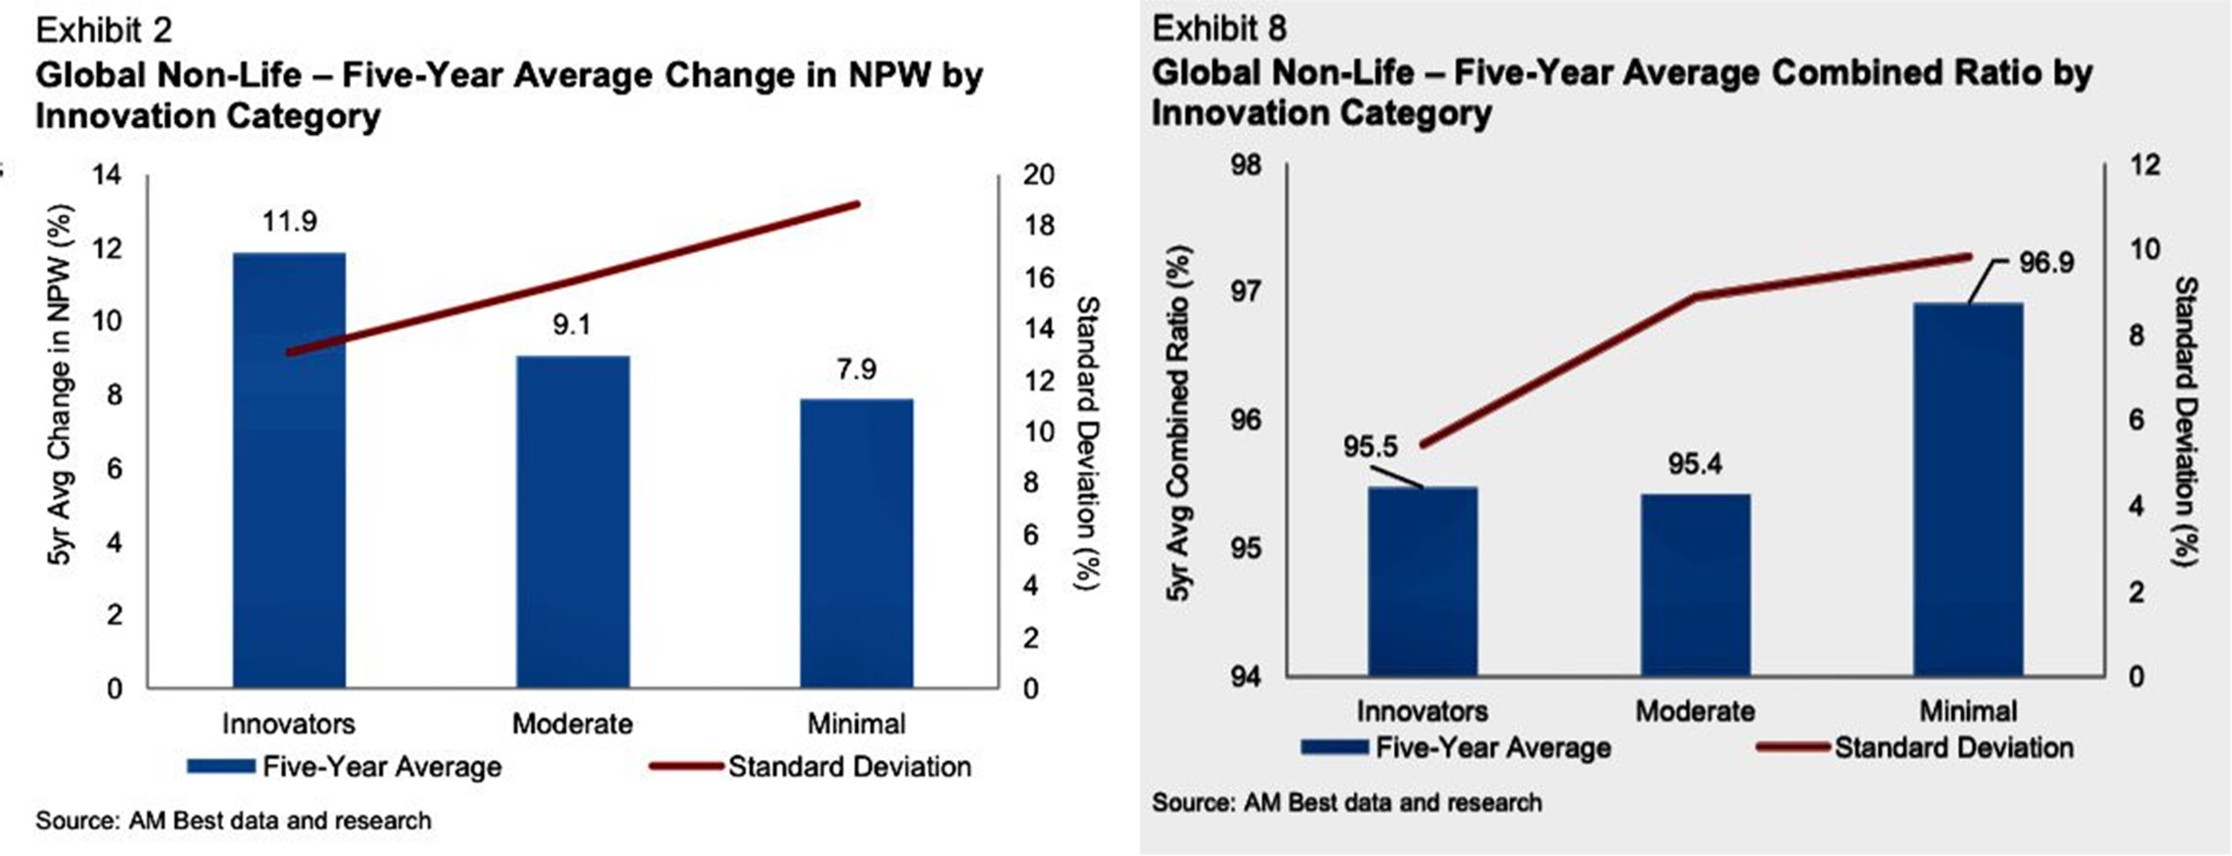
Chart comparison of innovation

These two charts should be hung on the walls of any P&C carrier. Instead, these figures haven't yet had the deserved attention since their publication three months ago. 

3) Some Insurtech initiatives have kept the promise.

  • The Allstate Group had over 2.5 million telematics policies among all programs and companies at of the end of 2021.
  • The Allstate branded telematics programs represent already a penetration above 20% on portfolios in the states where at least one telematics program is offered.
  • In these states, this penetration ranges from 30% in the exclusive agent channel to 40% for business sold through the call center and over 50% for online business. 
  • 30% of Drivewise customers use and engage with the app monthly, and the percentage grows to over 50% for the Milewise portfolio.
  • Customers who connect and sign up for a telematics program tend to have anywhere between five and 15 percentage points higher retention rates relative to those who have chosen to not enroll into a program.
  • Allstate’s Arity found there is a 4X difference in the lifetime value between the top-quartile best drivers and the bottom-quartile worst drivers.
  • Customers who are active within the Allstate rewards program tend to have both retention and loss ratio benefits in the range of one to two percentage points. These customers also have 26% higher likelihood of recommending Allstate.

The Allstate case history described in the article shows the real impact already generated by using telematics data and the progressive development of the foundations for the next steps of this multi-year journey.

See also: 5 Questions for Matteo Carbone on Smart Homes

Let's move to another IoT-based insurance journey, by Kinetic and Nationwide. Below you can find some thoughts I exchanged with Haytham Elhawary and Brian Anderson.

Matteo: Haytham, we discussed your risk mitigation approach in workers' compensation in front of a cup of coffee in Manhattan exactly 12 months ago. This May, you also presented it at the last plenary session of the IoT Insurance Observatory. I would like to ask you to share your IoT approach and something about the collaboration with Nationwide.

Haytham: Workers’ comp is mandatory, and traditionally transactional – you have an injury, we pay your costs. Our offering is different, it doesn’t just pay claims, it also provides safety technology that can help prevent those claims from happening in the first place.

While there’s been a lot of emphasis on worker productivity recently, the emphasis on safety hasn’t kept pace. Workers aren’t properly trained to avoid injury, and safety technology hasn’t changed in decades. So, injury rates are huge, especially among front line and industrial workers. Half are strain- and sprain-related, which have the largest impact on cost ($60 billion annually), time out of work and productivity.

We believe the best and most scalable way to help workers avoid injury is with a tech-based, real-time solution. So we developed a wearable device, with sensors that measure worker biomechanics, that gives real-time feedback when a high-risk movement is performed, like an awkward twist, bend or overreach. And we’re including this safety tech for free in our workers’ comp policies for the industrial workforce.

Our offering reduces injuries among these workers by changing their behavior and by providing managers with actionable data about risk. So, the policyholder can lower injuries, which leads to fewer claims, lower costs and an eventual reduction in premiums. It’s a preventative approach to workers’ comp that leverages state-of-the art tech.

To accomplish this, we’ve formed an MGA, in partnership with Nationwide. Kinetic distributes through agencies and does the underwriting and device deployment. Nationwide does the claims, billing and compliance. By collaborating, we can write policies in all states, on A+-rated paper, while providing proven safety technology at no extra cost.

Matteo: Looking at the different initiatives you supported, can you share some quantitative insight about the results achieved, on one side, directly with real-time risk mitigation (the real-time feedback to front line employees) and, on the other side, indirectly with the behavior-change programs (sharing insights with operational managers or loss control teams, providing incentives to workers, ...)

Haytham: To get a clear picture of the impact of our wearable device, we partnered with an actuarial consulting firm, Perr&Knight. They looked at our operational data from users in various industries and verified the device supports improvement in injury reduction, lost work days and claims costs. Their report found the Kinetic wearable reduces strain and sprain injury frequency by 50% to 60% and lost work days by 72%.

When looking at the high-risk-movement data our tech can collect across an entire workforce, we’ve found that a reduction in high-risk movements is directly correlated to a reduction in injury rates. For example, in a 1,000-unit deployment on a company’s drivers and warehouse workers, data showed that for a 30% reduction in high-risk movements, we saw a 50% reduction in injury rates 12 months later. And when Frito-Lay deployed our wearables on thousands of manufacturing workers, they experienced a 26% reduction in high-risk movements and a 20% reduction in injury rates after six months. We’re providing a leading indicator that correlates strongly to claims reduction.

Policyholders can access all of their workforce’s high-risk-movement data on a web dashboard, where they can see what specifically is driving risk, like a job type or individual, a day of week or hour and more. Then they can make improvements to enhance safety, such as focused trainings and workstation or process redesigns. As an example, at one Frito-Lay plant, management was able to identify times of risk, such as when taking weight samples or during ingredient changeovers. They used this data to drive purchasing decisions, retrofit equipment and modify workspace setups to reduce risk. Another example: A machinist at a construction machinery and equipment company had to regularly bend and twist to place parts from a table into a machine. When data showed he was performing an average of 97 high-risk movements each day, the company modified the work process by adding a raised platform to the table. The redesign reduced the employee’s risky movements by 64%.

Matteo: This approach uses IoT data to prevent a risky situation and avoid a claim. I've always considered these smart actions an extraordinary opportunity for insurers because they affect the core of the portfolio's technical profitability. Brian, what is your perspective as the investor?

Brian: Wearables have always had a lot of promise. The biggest challenge has always been where and how do they fit or, to put a fine point on it, can they seamlessly (i.e. in the background) create behavior change. Kinetic’s real-time machine learning-enabled vibration reminders are the gentle nudge that workers are accepting of because the vast majority of people in the workforce don’t want to be injured when they’re bending, lifting or twisting in a way that may hurt them. Having a short, small vibration make the nudge versus someone’s manager is far more palatable feedback, too. These very nuanced elements culminate in real sustainable profitability improvements, not just at a point in time, but over the long haul, which is a compelling economic moat for both the company and for the investor. 

Ultimately, Kinetic is exactly why MGAs actually should exist:

  1. They differentiated strong distribution strategies that others lack.
  2. The profit profile of the business they generate is better than others and is non-replicable, all things good fintech investors should be keenly tuned into looking for.

Matteo: One of the biggest historical success stories in the past of the P&C U.S. market has been characterized by the strategy to grow as fast as possible at a target (healthy) combined ratio. Instead, we have seen many full-stack insurtech carriers focusing only on the growth and running portfolios with terrible loss ratios. I'm starting to hear founders in the market talking about the ambition to have more modest growth and sustainable portfolios. I'd love to hear the thoughts of both of you?

Brian: The last decade in public and private markets has been about three things - growth, growth and growth. The success of tech sector economics and winner-take-all strategies has rewarded this. But over the last year or so, the public and downstream private markets have shown that prioritizing growth without the context of contribution margin and capital intensity is not going to work with rising interest rates, tighter credit markets and dramatically fewer capital markets willing to fund fully verticalized *anything* models.

Haytham: In the private markets, though, you are serving two masters:

  1. The carrier partner that provides balance sheet capital capacity and lets you write premium and wants slow, profitable and predictable growth.
  2. Investors are often hard-wired to prize growth in premium to substantiate high valuation multiplesm which are still based on revenue.

For example, in commercial lines like workers’ comp, understanding the actual developed losses of a book of business can take years. In the absence of reliable loss data, we’ve seen that the emphasis tends to shift to growth, which can be more easily controlled, and perhaps some proxy of losses. So it's a tricky situation, and finding the more nuanced investors who understand that it can often be better to have more moderate, but profitable growth has not been easy.

We like to think of Kinetic as the next wave of insurtech, or insurtech 2.0. We’re focused on risk reduction, using technology and data to help reduce losses and improve underwriting, which in turn will lead to more profitable policies. In this context, growth and profitability should be more compatible than they have typically been in the first wave of insurtech.


Please, my fellow insurers, don't stop investing in innovation! It’s unthinkable for an insurance company today not to pose the question of how to evolve its own model by thinking of which modules within their value chain should be transformed or reinvented via technology and data usage

I believe all the players in the insurance arena will be insurtech, meaning organizations where technology will prevail as the key enabler of the achievement of their strategic goals.


 

Cyber Insurance Market Hardens

While the cyber market improved significantly in 2021, increases to prior-year reserves may cause a drag on earnings, and the Russian invasion of Ukraine creates uncertainty. 

Cyber security image shaped like a camera lens and with a lock

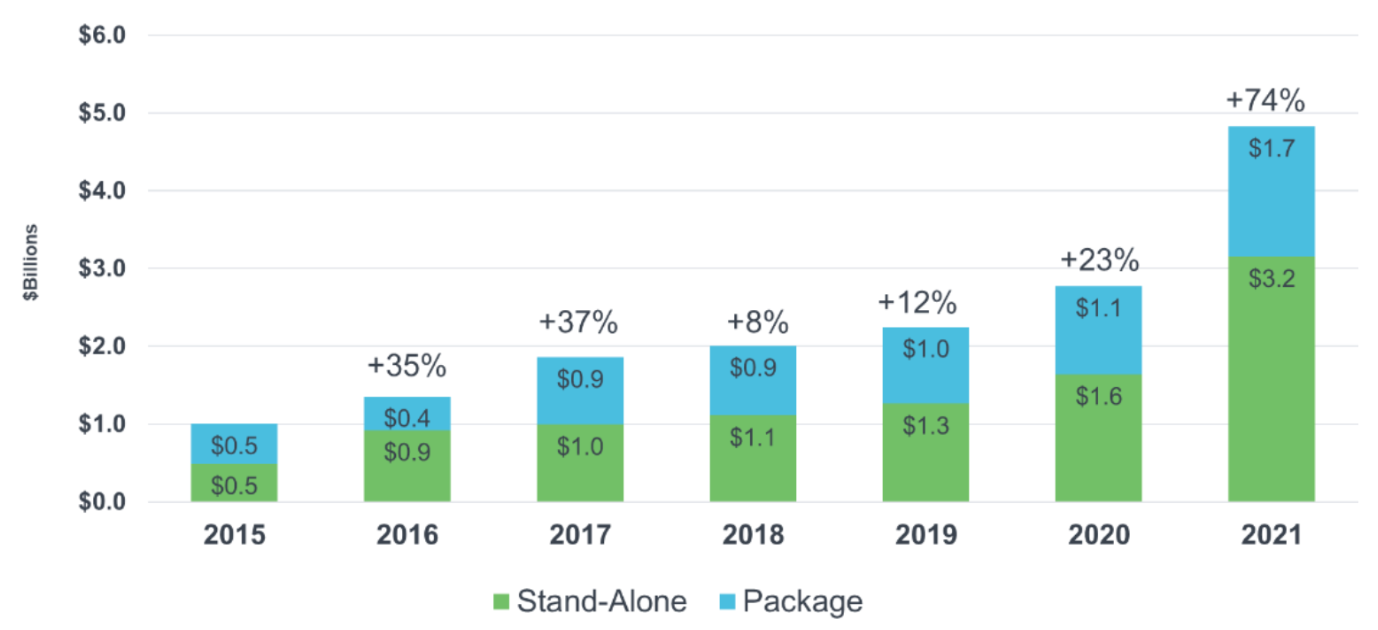
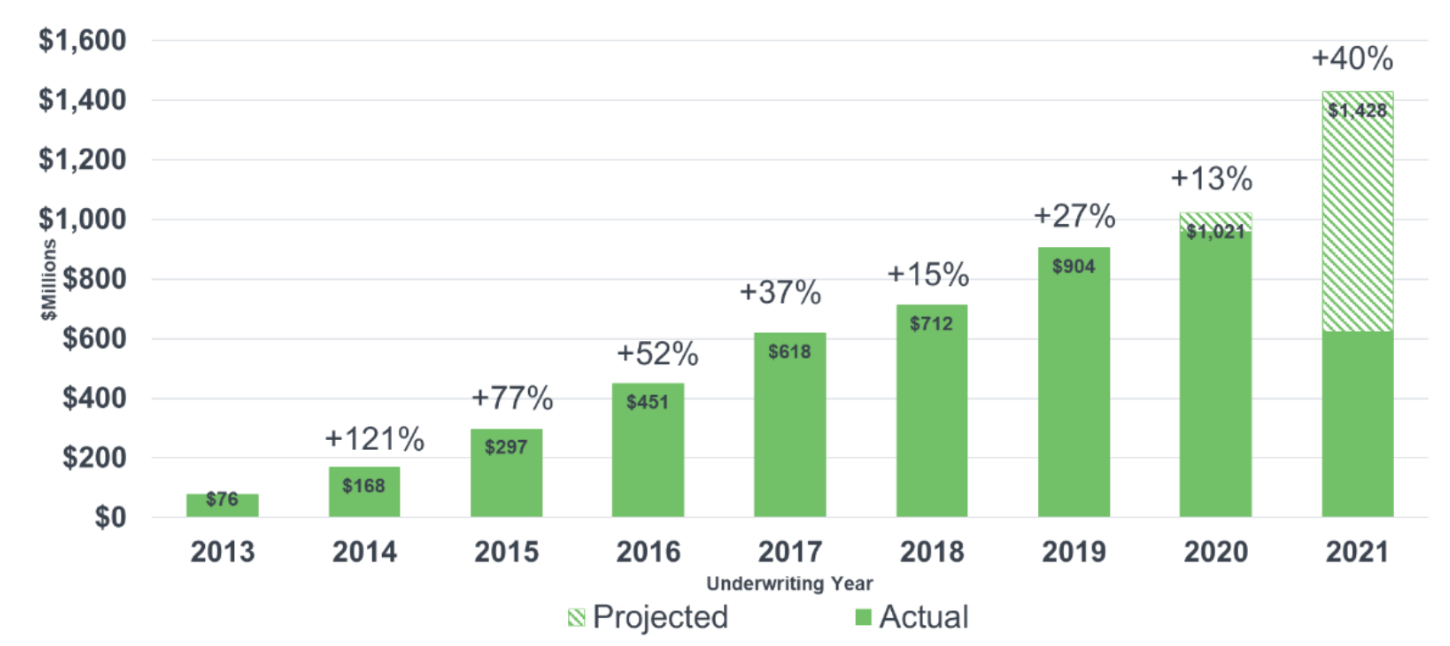
The cybersecurity insurance market (“Cyber Market”) has experienced rapid premium growth in recent years. Our analysis of NAIC Annual Statement data through year-end 2021 suggests the direct written premium (“DWP”) for the NAIC Cyber Market grew to approximately $4.8 billion in 2021, up 74% from $2.8 billion in 2020. The corresponding NAIC Cyber Market growth rates in 2020 and 2019 were 23% and 12%, respectively. Additionally, our analysis of Lloyd’s of London (“Lloyds”) data through year-end 2021 suggests the ultimate signed premium for the Lloyds Cyber Market will grow to $1.4 billion in underwriting year 2021, up 40% from the $1 billion estimated for underwriting year 2020. The corresponding Lloyds Cyber Market growth rates in underwriting years 2020 and 2019 are estimated to be 13% and 27%, respectively.

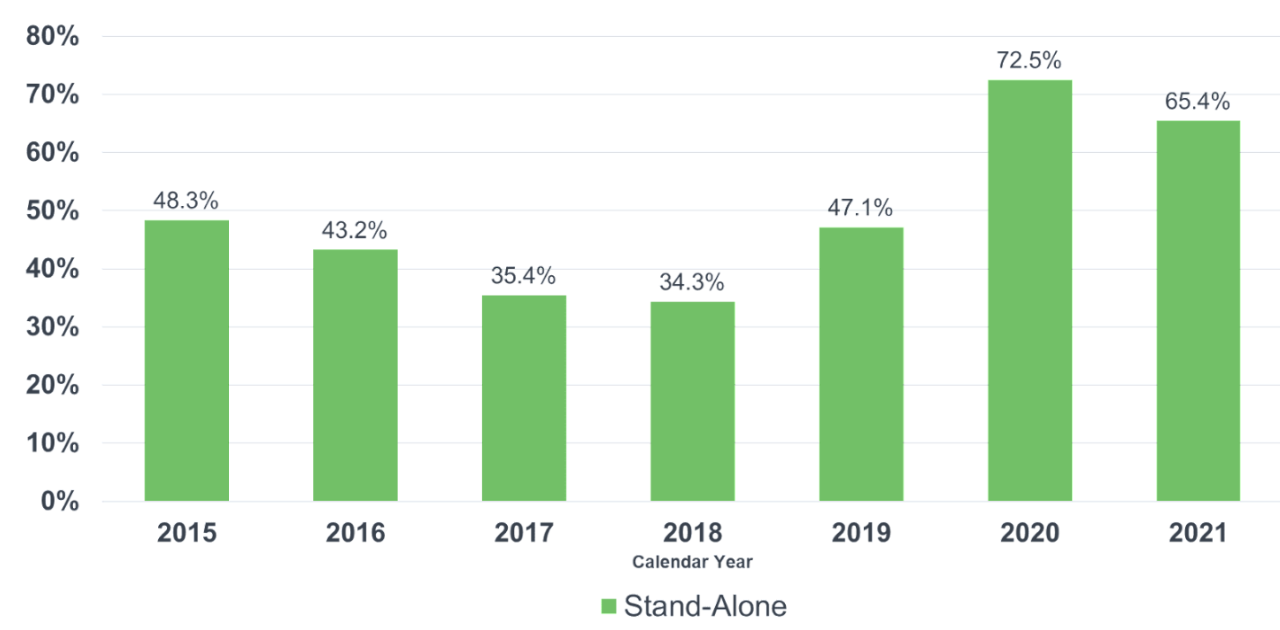
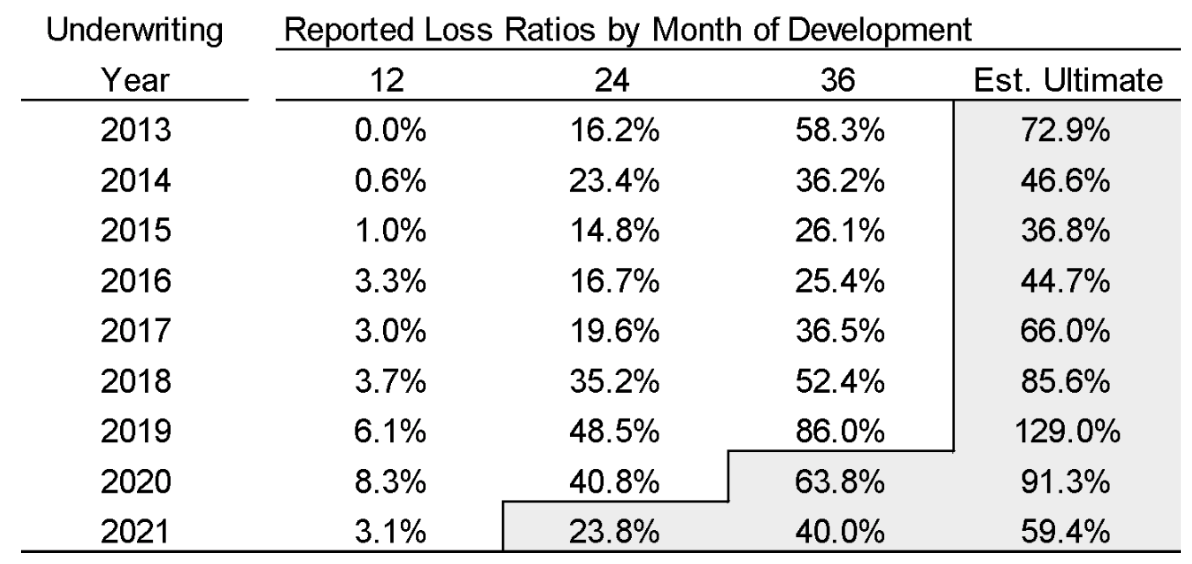
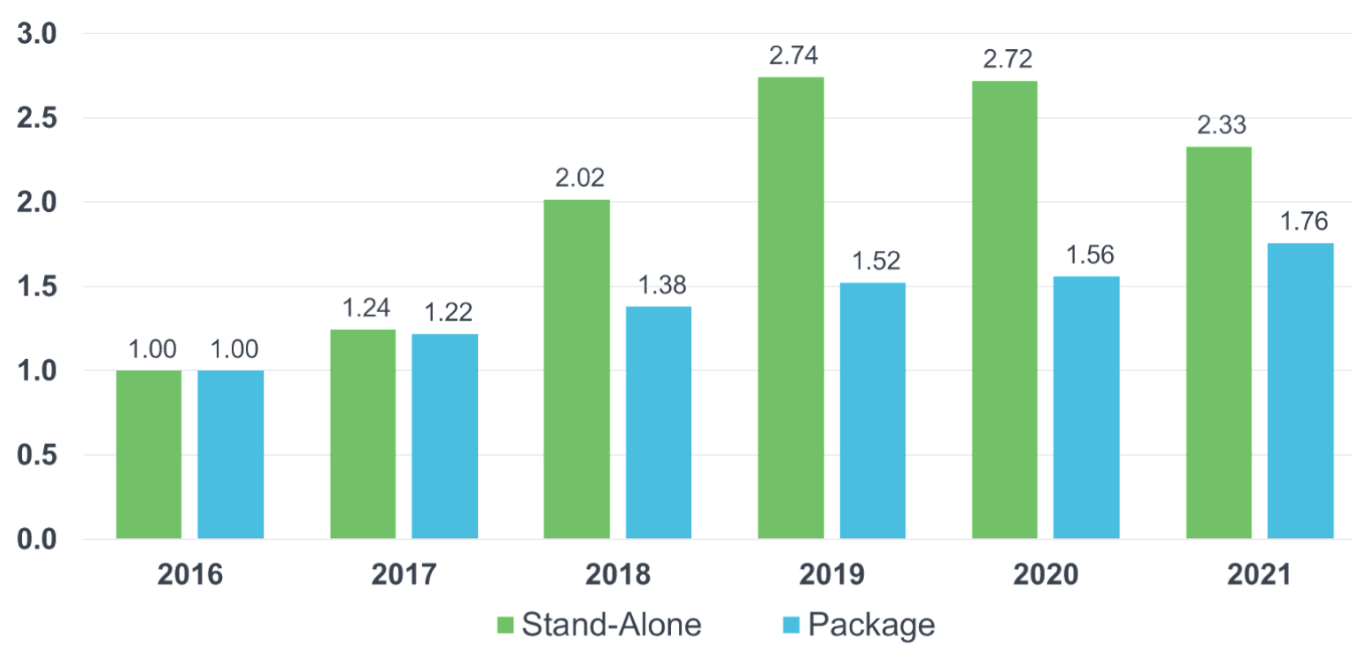
The Cyber Market’s recent growth follows deteriorating insurance results in preceding years. Specifically, the NAIC Cyber Market’s reported calendar year incurred loss and defense and cost containment expense (“DCCE”) ratios on Stand-Alone cyber policies have increased from 43% in 2016 to 73% in 2020. During this time, reported claim frequency increased 172%. Future calendar year results will provide insights as to whether companies have fully reserved for the increased cyber frequency. Further, our projected ultimate loss and DCCE ratio estimates for the Lloyds Cyber Market increased from a low of 37% in underwriting year 2015 to a high of 129% in underwriting year 2019.

Unfortunately, working from home due to COVID has led to increased Cyber incidents. According to Cloudwards, the rate of cyber crime increased by 600% during the COVID pandemic. The number of Cyber complaints reported to the FBI increased from 250,000 a year during the 2008 to 2018 years to over 750,000 a year in 2020 and 2021. 

Despite the increase in Cyber incidents, insurance results improved in 2021. The NAIC Cyber Market’s calendar year 2021 incurred loss and DCCE ratio decreased to 65%, and our projected ultimate loss and DCCE ratios for the Lloyds Cyber Market decreased to 91% and 59% in underwriting years 2020 and 2021, respectively. However, the Lloyds results are highly uncertain due to the immaturity of the underwriting years as of year-end 2021. 

We attribute this recent improvement to the combined effect of decreased frequency, increased rate levels and constrained capacity (e.g., increased deductibles, lower limits, refined policy terms, etc.). Specifically, within the 2021 NAIC Cyber Market, reported claim frequency decreased 14%, while large risks commonly experienced 100% to 150% rate increases, with the middle market often experiencing even larger increases. Considering DWP per policy has grown at a much slower pace than rates alone would suggest, we estimate the effective coverage per policy has decreased significantly.  

All things considered; the results of our analysis suggest an improved Cyber Market in 2021. A significant question relates to the adequacy of prior accident year reserves.

The following sections detail the results of our analysis.

Cyber Market Growth

As illustrated in Chart 1 below, the NAIC Cyber Market has experienced significant growth in DWP since 2015:

Chart 1: NAIC Cyber Market Change in DWP by Calendar Year

NAIC Cyber Market Change in DWP by Calendar Year

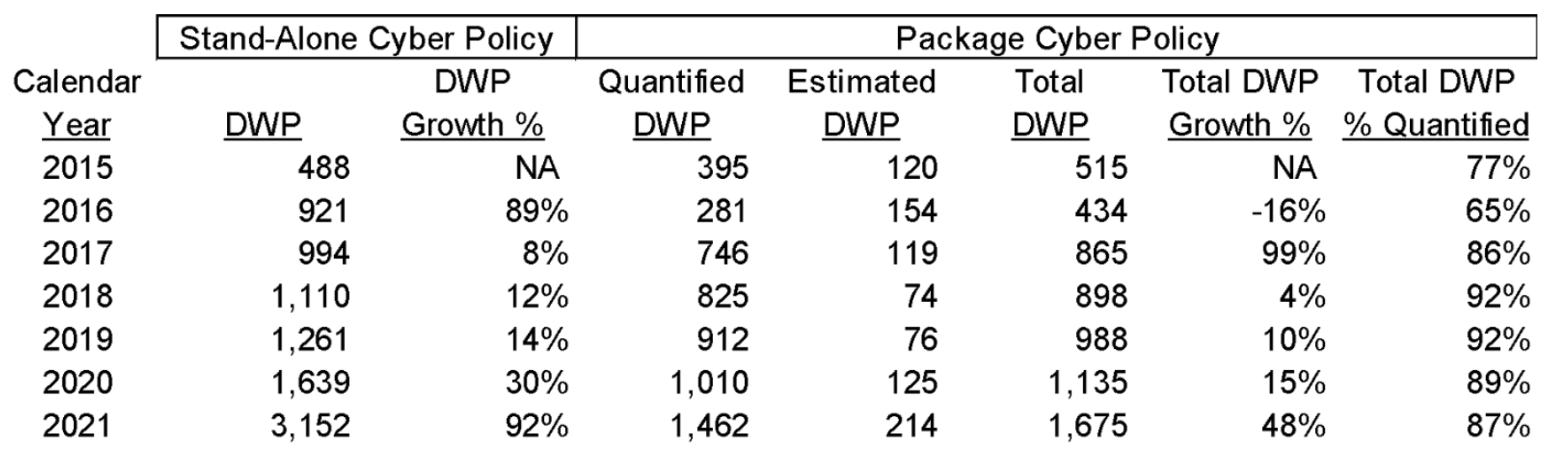
The DWP displayed in Chart 1 is composed of cyber premium stemming from Stand-Alone cyber policies (i.e., those policies designed specifically to cover cyber risks) and Package cyber policies (i.e., those policies where cyber coverage is offered in addition to other coverages). The NAIC Annual Statement requires companies to list cyber premium stemming from Package cyber policies as either “Quantified” or “Estimated.” We display this bifurcation in Table 1 below, along with DWP growth specific to Stand-Alone and Package cyber policies:

Table 1: NAIC Cyber Market Change in DWP by Calendar Year and Policy Type ($Millions)

NAIC Cyber Market Change in DWP by Calendar Year and Policy Type ($Millions)

As Table 1 displays, “Quantified” cyber DWP has generally represented approximately 90% of the displayed DWP stemming from Package cyber policies since 2017. Table 1 also shows the DWP growth for Stand-Alone policies has recently outpaced the growth for Package policies, especially in 2021. We expect the demand for Stand-Alone cyber policies to continue to grow as the need for tailored coverage specific to cyber risks is becoming apparent among insureds, especially in light of war exclusions commonly listed, or generally accepted to apply, to Package policies.

As illustrated in Chart 2 below, the Lloyds Cyber Market has also experienced significant growth in premium in recent years:

Chart 2: Lloyds Cyber Market Ultimate Signed Premium by Underwriting Year ($Millions)

Lloyds Cyber Market Ultimate Signed Premium by Underwriting Year ($Millions)
The DWP displayed in Chart 2 is composed of actual and projected signed premium. Our analysis of the Lloyds data suggests actual signed premium is at an ultimate level for underwriting years 2019 and prior, is near the estimated ultimate level for underwriting year 2020 and is less than half the estimated ultimate level for underwriting year 2021. As such, there is considerable uncertainty around the ultimate growth rate for underwriting year 2021. That being said, the 40% growth estimate does not seem unreasonable considering the $625 million of signed premium for underwriting year 2021, as of Dec. 31, is 43% higher than the corresponding signed premium of $437 million for underwriting year 2020, as of Dec. 31, 2020.

See also: Why Hasn't Cyber Security Advanced?

Cyber Market Insurance Results

As illustrated in Chart 3 below, the NAIC Cyber Market insurance results deteriorated between calendar years 2018 and 2020, but improved in 2021:

Chart 3: US Cyber Market Incurred Loss & DCCE Ratios by Calendar Year – Stand-Alone Policies Only

US Cyber Market Incurred Loss & DCCE Ratios by Calendar Year – Stand-Alone Policies Only

As illustrated in Table 2 below, the Lloyds Cyber Market has also experienced a period of deteriorating insurance results with improved trends recently:

Table 2: Lloyds Cyber Market Reported Loss and DCCE Ratios by Underwriting Year

Lloyds Cyber Market Reported Loss and DCCE Ratios by Underwriting Year

The Table 2 values shaded in grey represent our projected estimates based on our analysis of available information. The results for underwriting year 2021 are particularly uncertain given the year is still in the earning period. That being said, early evidence suggests the results for underwriting year 2021 could be significantly lower than 2019, which follows the apparent momentum of improved results in 2020.

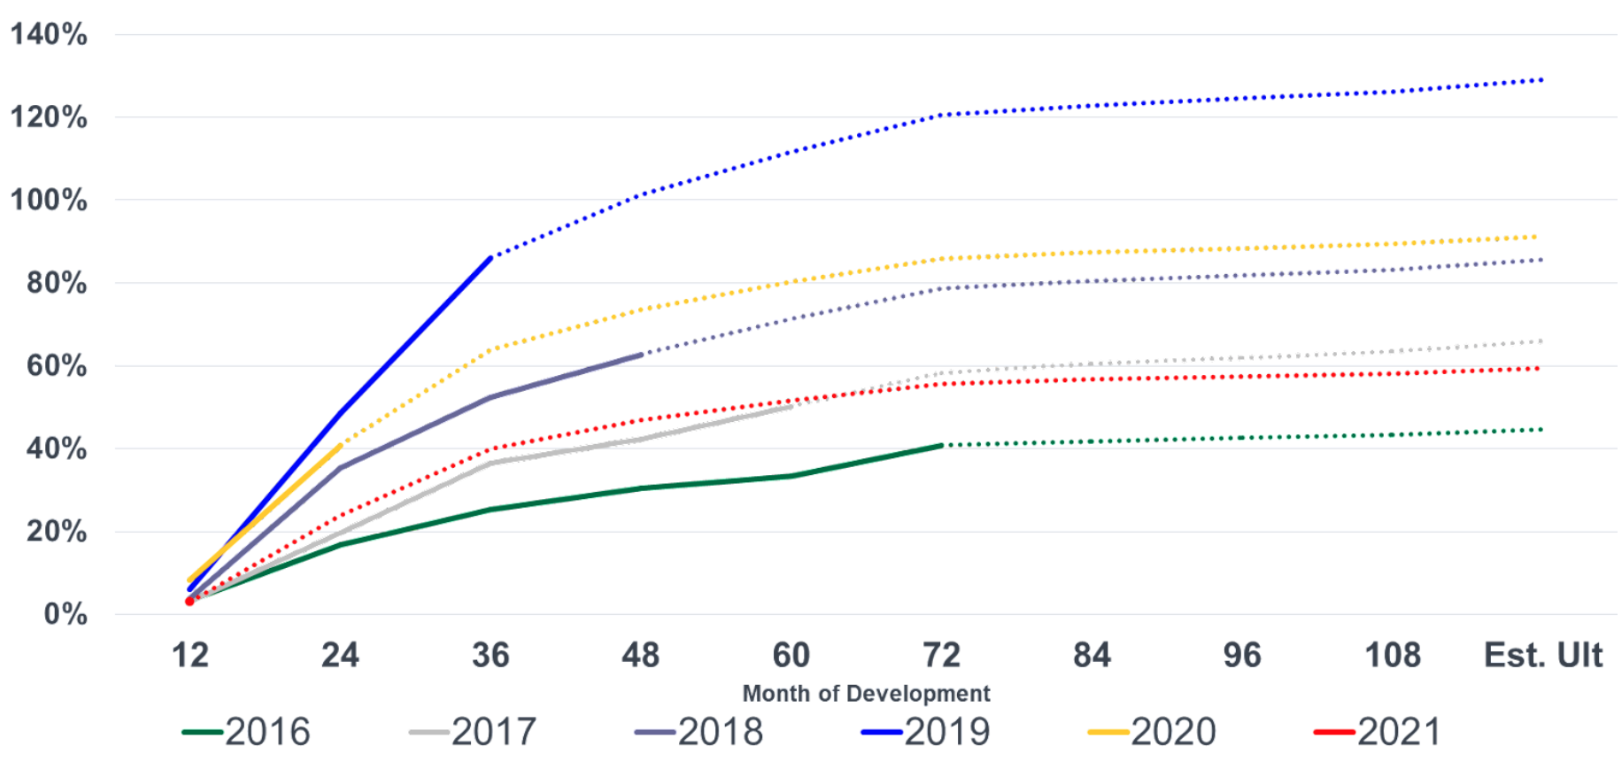
A graphical depiction of the development of the Lloyds Cyber Market reported loss and DCCE ratios by underwriting year is displayed in Chart 4 below:

Chart 4: Lloyds Cyber Market Reported Loss and DCCE Ratios by Underwriting Year*

Lloyds Cyber Market Reported Loss and DCCE Ratios by Underwriting Year*

*Dotted lines represent our estimates of the development of reported loss and DCCE ratios to ultimate value.

Cyber Market Diagnostics / Discussion

The deterioration of NAIC Cyber Market insurance results between calendar years 2018 and 2020 follows a period of increased reported claim frequency between 2016 and 2019, as illustrated in Chart 5 below:

Chart 5: NAIC Relative Reported Claims per Policy – 2016 Base Period

NAIC Relative Reported Claim’s per Policy – 2016 Base Period

There is an apparent lagged relationship between increased reported claim frequency and increased booked loss and DCCE ratios. Specifically, the increased 2018 and 2019 reported claim frequency measures displayed in Chart 5 above don’t appear to manifest as increased incurred loss and DCCE ratios until 2019 and 2020. This lagged relationship suggests initial booked reserves have likely been inadequate. 

Also of concern is that the reported claim trends displayed in Chart 5 above imply the calendar year 2019 through 2021 incurred loss and DCCE ratios would be significantly higher than reported. That is, if the calendar year 2016 incurred loss and DCCE ratio of 43% was trended forward to 2019, 2020 and 2021 using only the reported claim trends displayed in Chart 5 the resulting incurred loss and DCCE ratios would be 118%, 118%, and 101%, respectively. These trended results do not account for recent rate increases, but are nonetheless significantly higher than the corresponding reported ratios of 47%, 73%, and 65%, respectively.

The significant reduction in reported claim frequency in 2021 may be explained by increased awareness of cyber threats among the general population, along with improved security protocols and more robust education on the risk by corporations. The trend toward higher deductibles may also contribute to the lower reported claim frequency recently.

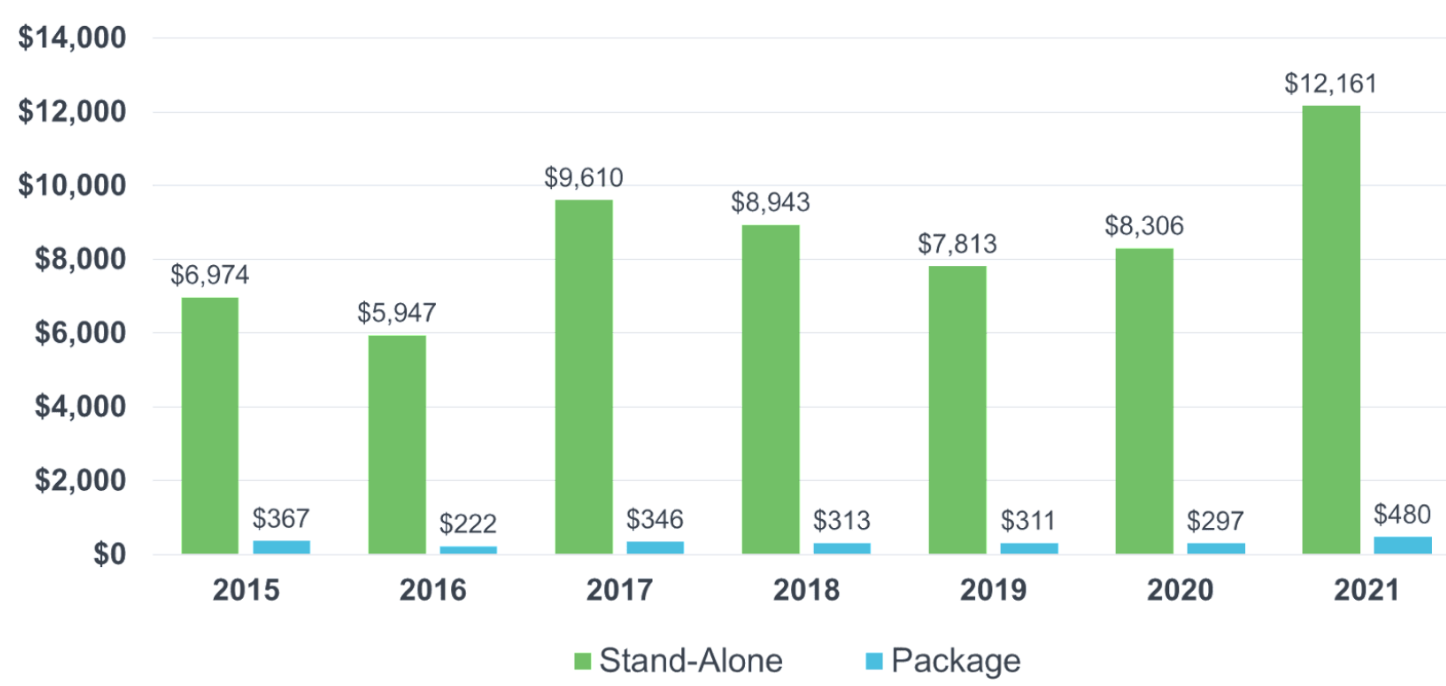
The average NAIC DWP per in force Stand-Alone cyber policy increased to $12,161 in 2021 from $8,306 in 2020, an increase of 46%. Chart 6 below displays these average premiums back to 2015 for both Stand-Alone and Package cyber policies:

Chart 6: Average NAIC DWP per In-Force Policy

Average NAIC DWP per In Force Policy

Considering average U.S. cyber rates were estimated by many parties to increase by 100% in 2021, the implication is coverage was significantly reduced likely due to a combination of increased deductibles and reduced policy limits.

Recent Claim Department Responses

The increase in ransomware and data breach events have led to more changes in claim departments:

  1. Insurers continue to add claims technical staff and reimagine business process and vendor relationships to improve efficiency and reduce loss and DCCE. There is evidence of insurers building incident response technical teams as these costs fluctuate with demand.
  2. Talent shortages have begun to show in claim teams, law firms and vendors.
  3. There is a lack of surge capacity in the vendor marketplace. 
  4. The COVID-19 pandemic exposed the heavy reliance of insurers on third-party professionals to render response services where there are now growing questions of surge capacity. Insurers may be left exposed for lack of timeliness in responding or subject to higher costs.
  5. Brokers are left to assist clients that have recently uninsured or that have significant retentions. Enhanced broker services are being developed to fill the services gap.
  6. The speed of cyber incident response continues to quicken, and the demand and cost for specialized claims services continues to increase.
  7. Data breach class action litigation continues to rise.
  8. Claim handling data gathering and the use of analytics is growing. 
  9. There is more focus on planning for incidence response surges, suggesting that insurers nourish service development and competition. Specifically, law firms specialized in incident response, forensics, e-discovery, call centers and identity theft and fraud monitoring and restoration provider.

Ransomware losses, which began to affect portfolios heavily commencing in 2019, are quicker to settle than data breaches, which are more prominent in prior years’ losses. Despite the purported lower latency, there is an increase in case reserves. 

Brokers likewise are taking a more active role in vendor due diligence and selection for their clients and looking specifically for improved services for identity monitoring that go beyond credit monitoring to include health data, social media profiles and services for minors and high wealth individuals. Expanded services offerings are expected and needed to avoid or mitigate the potential for litigation and maintain goodwill with consumers.   

See also: Excess & Surplus Lines Market Hardens Further

Concluding Remarks

While the Cyber Market has significantly improved in 2021, increases to prior coverage year reserves may create a significant drag on earnings. Also, the instability caused by the Russian invasion of Ukraine and the potential for a cyber catastrophe creates a very uncertain future. 

All NAIC data referenced in this article was provided by S&P Global Market Intelligence, unless otherwise noted. All Lloyds data referenced in this article was provided by Xchanging, unless otherwise noted. 

For further information, please reach out to the authors.


Zach Ballweg

Profile picture for user ZachBallweg

Zach Ballweg

Zach Ballweg is a consulting actuary for Milliman.

His area of expertise is property and casualty insurance, specializing in ratemaking and loss reserve analyses for unique and non-standard exposure. Ballweg serves entities ranging from small self-insured municipalities to large insurers and corporate clients. Ballweg has 14 years of experience with Milliman.


Brian Brown

Profile picture for user BrianBrown

Brian Brown

Brian Brown is a principal and consulting actuary for Milliman.

His areas of expertise are property and casualty insurance, especially ratemaking, loss reserve analysis and actuarial appraisals for mergers and acquisitions. Brown’s clients include many of the largest insurers/reinsurers in the world.

He is a past CAS president and was Milliman’s global casualty practice director.


Paul Miskovich

Profile picture for user PaulMiskovich

Paul Miskovich

Paul Miskovich is the head of global cyber solutions at Pango, an Aura company.

Miskovich has held insurance leadership roles as chief underwriting officer for Evertas, a global underwriter of crypto-related risks, group head of cyber at ARGO and global head of cyber for AXIS Capital. He has a combined 20 years of experience in the cyber insurance industry and 10 years of experience in engineering and IT within the telecommunications and the defense industries.

Miskovich is also a licensed attorney in New York and New Jersey, as well as a licensed P&C broker.

Top Causes of Business Insurance Loss

Despite improvements in risk management and prevention, fire/explosion (excluding wildfires) is the largest single cause of corporate insurance losses (21% of total losses).

Low angle photo of a building tinted blue

In one of the industry’s most comprehensive analyses, Allianz Global Corporate & Specialty (AGCS)  has identified the top causes of loss for companies from more than 530,000 insurance claims in over 200 countries and territories that it has been involved with between 2017 and 2021. (Typically, a number of insurers provide coverage jointlym considering the huge values at stake in the corporate sector.) These claims have an approximate value of €88.7 billion, which means that the insurance companies involved have paid out – on average – over €48 million every day for five years to cover losses.

Top Causes of Loss

The analysis shows that almost 75% of financial losses arise from the top 10 causes of loss, while the top three causes account for close to half (45%) of the value. Despite improvements in risk management and fire prevention, fire/explosion (excluding wildfires) is the largest single identified cause of corporate insurance losses, accounting for 21% of the value of all claims. Fires have resulted in more than €18 billion of insurance claims over five years, according to the analysis. Even the average claim totals around €1.5 million.

Natural catastrophes

Natural catastrophes (15%) rank as the second top cause of loss globally by value of claims. Collectively, the top five causes (based on more than 20,000 claims around the world) are: hurricanes/tornados (29%); storm (19%); flood (14%); frost/ice/snow (9%); and earthquake/tsunami (6%). They account for 77% of the value of all disaster claims. Hurricanes and tornados are the most expensive cause of loss; two of the past five Atlantic hurricane seasons (2017 and 2021) now rank among the three most active and costliest on record, and there has recently been record-breaking tornado activity.

Insurers are also seeing new scenarios. During 2021, the Texas Big Freeze in the U.S. and flooding in Germany stood out because of unexpected claims. The Texas freeze in February caused huge disruption to infrastructure and manufacturing, with many companies forced into shutdowns by widespread power outages, resulting in property damage and in some large contingent business interruption (CBI) losses. This event alone is estimated to have caused economic losses up to $150 billion. 

Faulty workmanship/maintenance incidents are the third top cause of loss overall (accounting for 9% by value) and are also the second most frequent driver of claims (accounting for 7% by number, ranking only behind damaged goods, with 11%). Costly incidents can include collapse of building/structure or subsidence from faulty work, faulty manufacturing of products/components or incorrect design.

The other top 10 causes of loss are: aviation collision/crash (#4; 9%), machinery breakdown (#5; 5%), defective product (#6; 5%), shipping incidents (#7; 3%), damaged goods (#8; 3%),  negligence/bad advice (#9; 2%) and water damage (#10; 2%).  

Inflation’s Impact on Claims

Inflation is bringing pressure on claims costs from multiple angles. Property and construction insurance claims, in particular, are exposed to higher inflation, as rebuilds and repairs are linked to the cost of materials and labor, while shortages and longer delivery times inflate business interruption (BI) values. Other lines of insurance, such as directors and officers, professional indemnity and general liability, are also susceptible to inflationary pressures through rising legal defense costs and higher settlements. 

Replacement costs more, and replacement takes longer, and this means both the property damage and the business interruption loss are likely to be significantly higher. Updating insured values for all new contracts is therefore a pressing concern for insurers, brokers and insureds. The insurance market has already seen a number of claims where there has been a significant gap between the insured’s declared value and the actual replacement value. For example, in a claim for a commercial property destroyed in the 2021 Colorado wildfires, the rebuild value was almost twice the declared value, due to a combination of inflation, demand surge and underinsurance. 

See also: Taking Care of Small-Medium Business

Business Interruption Losses on the Rise

The claims analysis also highlights the growing relevance of BI as a consequence of losses in property insurance, and the fact that CBI claims have reached a new high over the past year. Costs associated with the impact of BI following the aftermath of a loss can significantly add to the final bill. The average BI property insurance claim now totals in excess of €3.8 million compared with €3.1 million five years ago. For large claims (>€5 million), the average property insurance claim that includes a BI component is more than double that of the average property damage claim.

The number of CBI claims has increased year-on-year for the past five years, exemplifying the growing interdependence and complexity of corporate supply chains. The automotive industry alone has seen several CBI events during this period, with the overall growth in CBI claims exacerbated in the last two years by a large loss in the semiconductor manufacturing sector and the Texas freeze. The claims from these two events more than tripled the number of CBI claims in the previous three years. 

The COVID-19 legacy and the Ukraine crisis 

The report also investigates the insurance impact of recent specific claims events such as the pandemic and the Ukraine crisis. Insured losses from COVID-19 are in excess of $40 billion, according to industry estimates, with the bulk of claims coming from event cancellation insurance and BI claims from companies affected by lockdowns. The pandemic has also had knock-on effects, such as stressed supply chains, heightened inflation and financial insolvencies.

Meanwhile, Russia’s invasion of Ukraine is likely to result in a significant, yet manageable, loss for the global insurance industry. Insurers’ exposure to the conflict are limited by war exclusions, which are standard in most property/casualty insurance contracts. Expected insured losses from the war in Ukraine are comparable to a mid-sized natural catastrophe, according to AGCS, but specialist markets such as aviation insurance could yet suffer disproportionately.

To read the full AGCS report, please visit Global Claims Review 2022.


Frank Sapio

Profile picture for user FrankSapio

Frank Sapio

Frank Sapio is senior vice president, North American head of claims for Allianz Global Corporate & Specialty.

SMBs Are Vulnerable on Cyber

Small and medium-sized businesses must improve their risk management protocols while putting in place a cyber insurance safety net. 

Computer code over a blurry blue background

Small and medium-sized businesses (SMBs) have been grappling with an array of economic and cultural forces over the past two years that threatened their viability. Stretched thin by the global pandemic, the Great Resignation and spiking inflation, SMBs have no doubt relegated other important concerns to a lower priority, including cybersecurity and cyber insurance. However, an attack on a small business is often catastrophic, leading to a tarnished reputation, customer dissatisfaction and, even worse, closures. In a National Cybersecurity Alliance study, 25% of small businesses that experienced a data breach filed for bankruptcy, and 10% went out of business. 

A recent survey reports that only 50% of small business owners are fully prepared for a cyberattack. Many SMBs do not view cyber insurance as urgent, because of the cost and the effort required to conduct due diligence on providers. Cyber insurance is a crucial safety net to have in place, but companies must also improve risk management protocols.

Risk management is a neglected piece of the cybersecurity puzzle  

An excellent place to begin is with employee training, especially because 85% of breaches involve the human element. Forty percent of people simply do not see themselves as responsible for looking after their workplace’s sensitive information. Remote workforces have added a level of challenge for companies to control risk factors, such as home network connections. 

Addressing the human factor in risk management

Robust education and awareness programs are essential because a personal cyberattack on one employee creates an enormous burden to the entire company. Training courses should include recognizing privacy risks, preventing phishing attacks and detecting an attack. Multi-factor authentication (MFA) has emerged as a great, inexpensive way for SMBs to combat potential account takeovers or bad password hygiene. If MFA is not in use, then password blacklisting -- a list of words disallowed as user passwords due to their commonplace use -- becomes a must. In addition, like large enterprises, SMBs can take an extra step of protection by imposing a password protection cadence where employees are expected to change their username and passwords regularly.

SMBs need to also remain vigilant when it comes to their vendors. The often-overlooked process of scrutinizing insurance requirements in vendor contracts, confirming where the onus lies in handling a cyberattack and understanding the full spectrum of liability, is necessary.

See also: Tips for SMBs Buying Cyber Insurance

Cyber insurance considerations 

Once these risk management logistics are in good standing, adding a layer of protection by seeking cyber insurance is a must. To execute proper due diligence, SMBs need to fully understand what cyber exposure is, what cyber insurance can do and what it covers. (If an SMB stores any sensitive client data whatsoever on computers and network technology, they have the potential for cyber exposure. Cyber insurance generally covers a business' liability for a data breach involving sensitive customer information. Not all cyber insurance policies cover the same things; most provide breach response services and damage mitigation and ensure the obligatory investigation and notification procedures are implemented. Some insurers may offer an enhanced plan that also helps protect against lawsuits and regulatory actions.)

Before applying for cyber insurance, SMBs should have a sense of the depth of internal information carriers will require. Carriers want to get comfortable with the risk before they're willing to offer decent insurance coverage. There aren't many insurers willing to offer a minimum limit of cyber insurance without extensive supplemental applications. The process may require time, but SMB leaders should not be discouraged, as cyber liability insurance ensures the organization has a concrete response plan.

The proper guardrails in place to succeed 

SMBs have made strides in recent years in recognizing the existential threats that data breaches present, but they must be even more vigilant as remote work models and the digital transformation continues to sweep through virtually all industries. While they have fewer resources than enterprises, SMBs should adopt the same level of caution against cyber criminals through a combination of cyber liability insurance and comprehensive cyber risk management practices.


Richard Clarke

Profile picture for user RichardClarke

Richard Clarke

Richard Clarke is chief insurance officer at Colonial Surety.

With more than three decades of experience, Clarke is a chartered property casualty underwriter (CPCU), certified insurance counselor (CIC) and registered professional liability underwriter (RPLU). He leads insurance strategy and operations for the expansion of Colonial Surety’s SMB-focused product suite, building out the online platform into a one-stop-shop for America’s SMBs.

Anti-Fraud Measures Don't Work as Well as You Think

Fraudsters know "knowledge-based authenticators" 92% of the time, while genuine customers only pass KBAs 46% of the time.

Close-up of a keyboard lit-up

Faced with increasing competition, insurance providers are adding new products and offering better deals to take a slice of the $200 billion in revenue opportunity. Yet, providing an experience that meets the needs of today’s customers can prove challenging, especially when it comes to seamlessly authenticating customers. 

Insurers, like many modern-day service providers, can store sensitive customer account information and even have access to customer banking/payment information, making it essential that they deliver the appropriate account protection and customer experience. To do so, insurers need to know who is accessing accounts from the beginning of the interaction, on mobile, via web and over the phone. However, contact center phone exchanges are increasingly a challenge for insurers, especially as fraudsters leverage new tactics to gain access to customer accounts. 

Fraudsters are better at accessing accounts than genuine customers

Contact center customer interactions usually start with a series of questions that begin the authentication process by asking the user to verify their name, phone number, account number and other knowledge-based authenticators (KBAs), for example. But with data breaches making this information readily available and social engineering attacks tricking users into handing over their information to fraudsters, it’s harder than ever to tell if a caller is genuine. 

Asking questions during the authentication process is no longer a secure method because the answers may no longer be private and can allow fraud to infiltrate the business. In fact, according to a case study covered in Pindrop’s recent Voice Intelligence and Security Report, fraudsters passed KBAs 92% of the time, while genuine customers only passed KBAs 46% of the time. This harsh truth of fraudsters knowing customer information more than actual customers, coupled with information from the same report that call center agents from insurance companies failed to verify customers’ identities as much as 12% of the time, allows fraud to slip through the cracks. 

The report found that a sample of insurers have an average fraud call rate of 1 in 7,390. Although insurers typically see lower fraud rates than a bank, the payoff is often higher in the life insurance space. Additionally, property/casualty companies sampled regularly saw fraud during the automated claim process, with fake credentials being used by fraudsters. 

See also: How to Balance CX and Fraud Detection

Changing the locks 

Insurers have a lot to lose, and, without the proper authentication protocols, disaster may await the company and its customers’ financial information.

To help insurers protect their customers’ accounts and only allow verified callers access, they can leverage new technology tools, such as voice authentication, which analyzes callers’ voice characteristics. Unlike traditional questions that are easily answered due to data breaches and other means, voice characteristics are hard to replicate. Even if an audio deep fake is created, voice authentication tools can still detect a synthetic voice, helping thwart fraud attempts at the source. 

Not only can voice authentication help reduce fraud, but it can also reduce average call handling times in contact centers and increase operational efficiency by creating a frictionless authentication process. 

Customer information is more readily available than ever before, and insurers need to be at the forefront of protecting their business and customers from fraud. If they let fraud infiltrate their contact center, they risk more than losing money; they risk losing their customers’ trust and loyalty to the brand.


Ben Cunningham

Profile picture for user BenCunningham

Ben Cunningham

Ben Cunningham is director of product marketing at Pindrop. Since joining Pindrop in January 2017, Cunningham has helped lead marketing, product management and go-to-market efforts for the company.

Is the 'Heat Apocalypse' an Insurance Apocalypse?

While many debate how high temperatures will rise by 2050, major effects of climate change are happening here and now -- and insurers are on the hook. 

Image
an orange background with a wooden thermometer reading 90 degrees farenheight on the left side

While the "heat apocalypse" that is baking much of Europe may seem like just more of the same extreme weather we've been experiencing globally for years now, it seems to me that we've now reached a new level of disruption, with significant implications for insurers. 

Like prior heat waves, this is one is exacerbating wildfires, destroying homes and other buildings, causing mass evacuations and generally upending millions of lives. The "heat apocalypse," as it's being labeled in France, is causing stress that is killing people -- hundreds just in Spain last week -- and overloading hospitals. But, as awful as all that is, insurers have been adjusting, and the public has become inured. 

The new news here, it seems to me, is all the downstream disruption -- the business closings, the cancellation of flights and trains, etc. that will produce a flurry of claims for insurers and that will only get worse as global warming continues. 

Although most of the climate change debate seems to focus on just how much temperatures will rise by 2035 or 2050 and just how destructive that increase will be, major effects have begun happening here and now -- and insurers are on the hook. 

In England, temperatures of 104 degrees Fahrenheit are expected this week. That may not sound unbearable to Floridians, Texans or those of us who live in California's Central Valley, but the average daytime high in London in July is 70F. When I lived in Brussels, where the climate is very similar to London's, we once went straight from a rainy spring to a rainy fall, with only one clear, reasonably hot day in between -- and that was a Thursday, so I was in the office and missed summer that year. 

English homes are built to retain heat, not cold air. Fewer than 5% of English homes have air-conditioning. The transportation infrastructure is tuned for a mild climate, too, so the heat is hitting hard.

Luton Airport, near London, had to close for repairs because the runways were melting. The Royal Air Force closed two airports for the same reason. Municipalities spread sand on roads because the asphalt was getting sticky and endangering drivers. Rail transit shut down because of fears that the metal rails would buckle -- electrified commuter trains had additional problems because stress on the grid meant that their power lines were unreliable. 

With millions of people unable to get around, businesses closed across the British Isles.

All the other problems associated with extreme weather are, of course, still happening, too. Temperatures in Spain and Portugal hit 117F last week, and there are wildfires in those countries, as well as France, doing massive damage to property and forcing evacuations. 

"In rural areas," the Washington Post reports, "heat waves are expected to have an increasingly serious impact on agricultural production. This year, French farmers faced a mix of frost, a record-hot May accompanied by a spring drought, and intense hailstorms that brought heavy rain, followed by more drought this summer.

“'The drought in much of Europe is critical,' the European Commission’s research branch concluded in a report released Monday, which warned that 'a staggering portion of Europe' — about half of European Union and British territory — is now at risk of drought."

Drought, wildfires, tornadoes, hurricanes, derechos and other forms of extreme weather will continue to generate the vast majority of claims for insurers, but the lesson for me from the "heat apocalypse" in Europe is that lots of claims for travel and business disruption and perhaps for auto accidents are already hitting insurers, too. 

So, even if you don't think of yourself as being in the business of insuring against extreme weather, you may be. 

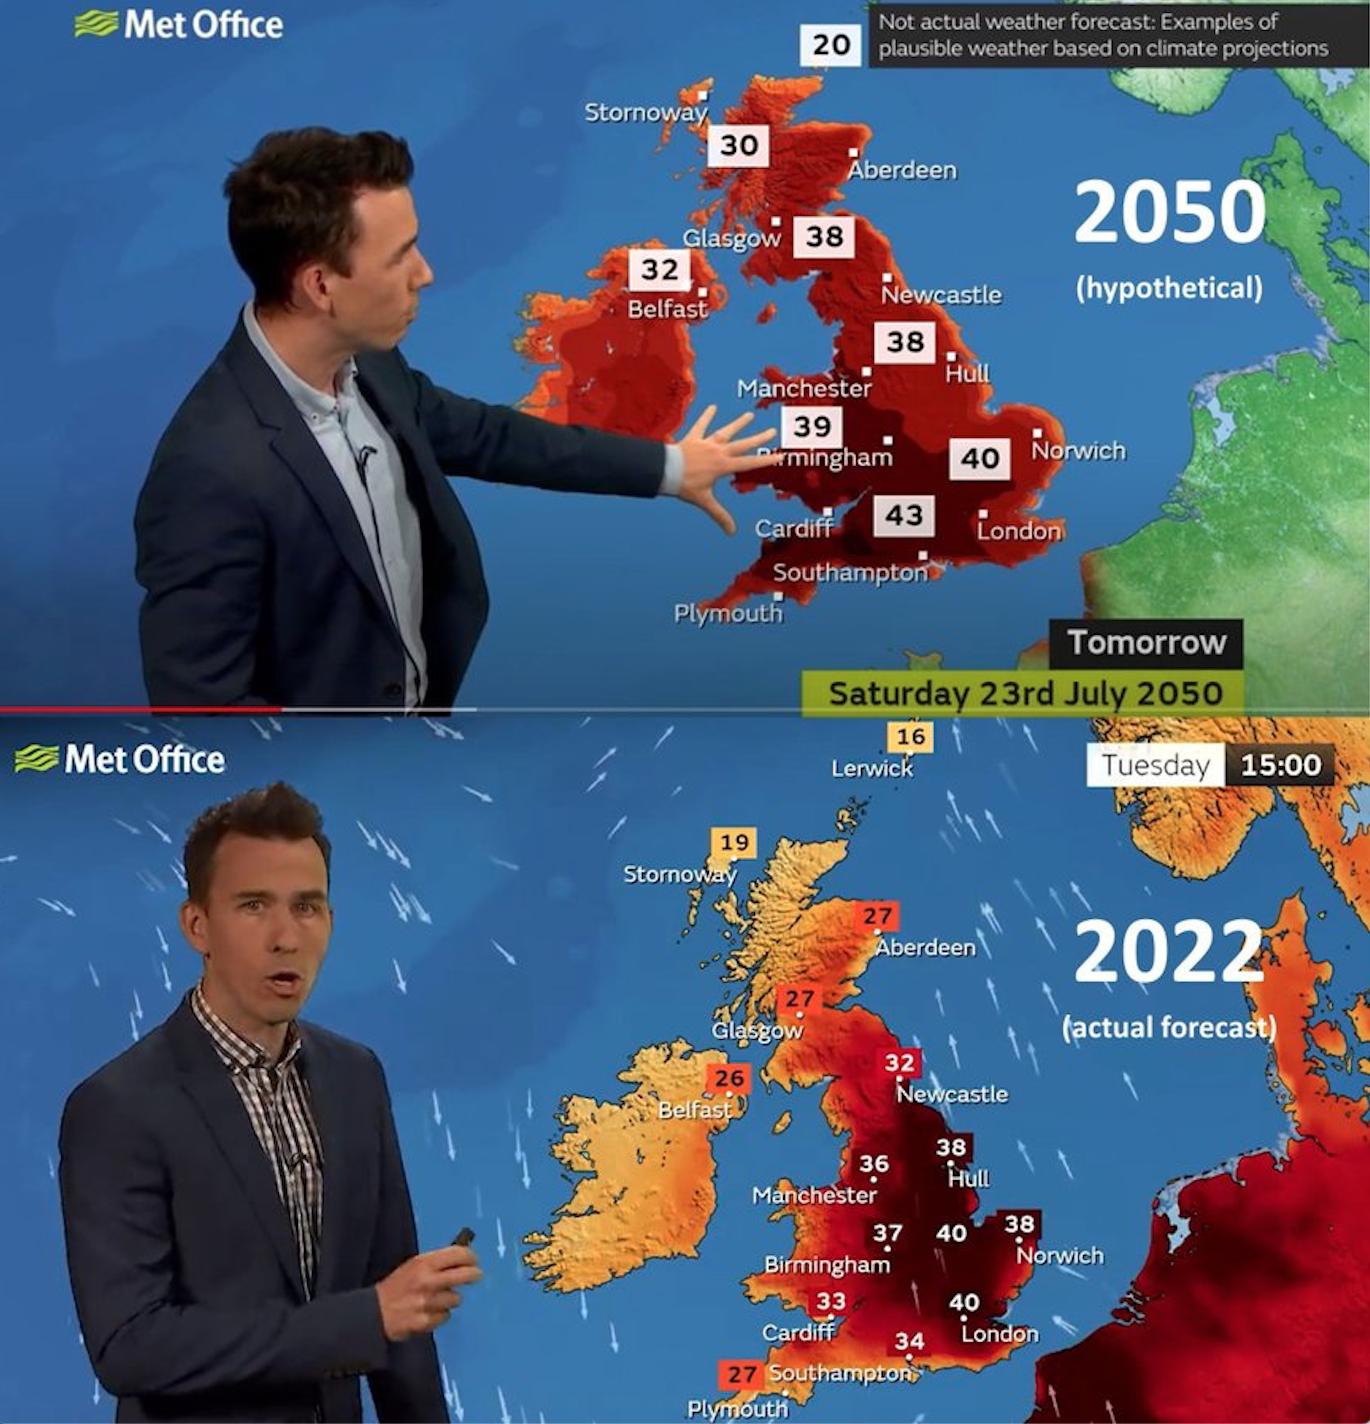
And the exposure will only grow as climate change worsens. Look at the images below. The top image is from two years ago. It was a hypothetical example of a weather forecast from 2050 that would show how extreme the temperatures could get in England. (For those of us not conversant in Celsius, 40C is 104F.) The bottom image is an actual forecast from the past week. They're eerily similar.

Now think how hot 2050 could actually be. Or 2025, for that matter. 

Map showing the weather

Cheers, 

Paul

How to Balance CX and Fraud Detection

With insurance carriers at a pivot point because of the pandemic, here are three ways to attack fraud without messing up the customer experience.

person typing on a computer with green code

The insurance industry has experienced record-breaking fraud attempts since the pandemic’s onset, significantly outpacing other sectors during the same period. Consequently, insurance carriers have reached a pivot point when it comes to fraud detection and prevention.

According to IDology’s Eighth Annual Fraud Report, 75% of insurance companies report increases in fraud attempts, nearly 10 percentage points higher than the next sector. The repercussions have been swift and severe. The Coalition Against Insurance Fraud’s most recent assessment found that insurance fraud costs people $80 billion annually, increasing annual premiums for the average family by up to $700. 

Several factors contributed to this increase, including enhanced phishing attacks, mass work-from-home deployments, decentralized fraud teams and nation-state attacks. While insurance fraud is a crime, the perpetrators are intelligent and well-organized. They know how to exploit the industry’s vulnerabilities for financial gain, and they capitalized on this unique moment to commit fraud at an alarming rate. 

At the same time, broad industry trends, including customer desire for self-service onboarding, extensive personal identifiable information (PII) exposure from data breaches and authentication infrastructure gaps, made it easier for threat actors to commit insurance fraud.  

In response, insurance carriers must enhance fraud detection and prevention measures, ensuring they can protect platforms and customers from constantly shifting fraud trends. Let’s look at three ways every company can strike a balance between fraud prevention and customer experience. 

#1 Verify Customer Identities Without Collecting Excessive Data 

After years of astonishing data breaches and personal information misuse by digital platforms, many consumers are rightly wary of handing over their information. As a result, two-thirds of Americans report they are extremely or very concerned about cybersecurity, data breaches and ransomware attacks. 

Similarly, 70% believe that businesses obtain their personal information without consent, and 90% want new federal laws that protect their data online. 

Of course, this puts insurance carriers in a difficult position. With threat actors opening unauthorized accounts and defrauding insurance providers, implementing identity verification and Know Your Customer (KYC) protocols is a natural solution. 

However, nearly half of Americans will abandon enrollment if the process is overly onerous or companies ask for too much information. Today’s consumers are vigorously guarding their Social Security and driver’s license numbers, dates of birth and home addresses, making it especially challenging to balance fraud deterrence and customer expectations. 

That’s why insurance carriers must develop the capacity to verify customer identities without collecting excessive data by analyzing readily available but less invasive data, such as IP addresses, phone numbers and email addresses. With the right solution in place, insurers can effectively analyze this information to verify identities and reduce fraud without impeding customer experience.

See also: How to Thrive Using Emerging Tech

#2 Implement Customized Identity Verification Protocols 

Today’s consumers are unapologetically self-sufficient and digital-first. For instance, nearly 70% of consumers would rather self-serve than speak with a customer service representative. 

To empower self-enrollment and self-service functionality without compromising identity verification protocols, insurance carriers must implement customized workflows that support customer preferences while continuing to thwart fraud attempts. This includes solutions that minimize data collection but also requires the industry to develop protocols for prequalification that streamline the application process while preventing unauthorized account openings or other fraud efforts. 

This can be achieved with a solution that optimizes identify verification workflows without encroaching on customers' desire to be self-sufficient. 

#3 Adapt to the Latest Trends 

Fraud trends changed significantly during the pandemic, introducing new risks while mitigating others. Threat actors took advantage of the peculiarities of pandemic life to enhance their fraud efforts, and their tactics will continue to change in the days ahead. 

The insurance sector can’t afford to remain stagnant in the face of evolving threat patterns. 

Notably, insurance carriers should pay close attention to fraud attempts targeting mobile technologies. While mobile apps and digital communications are prerequisites for doing business, they also introduce fraud prevention challenges, requiring insurance carriers to implement identity verification and fraud detection solutions across all device types and platforms.  

Deterring Fraud Is Part of the Customer Experience 

Insurance fraud increased significantly in recent years, representing a turning point for insurance carriers and their customers. 

Security and customer satisfaction are inextricably linked. Now is the perfect time to enhance the customer experience with identity verification solutions and processes that keep customers safe and criminals unsuccessful.


Christina Luttrell

Profile picture for user ChristinaLuttrell

Christina Luttrell

Christina Luttrell is the chief executive officer for GBG Americas, composed of Acuant and IDology, the premier identity verification, regulatory compliance and fraud prevention provider for all industries to establish trusted digital identities.

Transforming the Auto Insurer/Shop Partnership

Insurers and body shops need to start thinking differently about claims and repair processes, and how they can be revolutionized through AI and VI – Visual Intelligence. 

Rear tail light of a car

While COVID was life-changing for all of us, the pandemic catapulted customers and businesses alike into the digital world, revamping standards for how we engage to conduct business while also creating a universal demand for digitization for almost every aspect of our lives. Some industries were quick to adopt AI and technology into their business models, while the auto insurance industry was a little slower to adopt despite the fact that 79% of customers would trust automotive claims powered entirely by AI.

Those that did adopt early had remarkable success. In fact, 58% of insurers that are already using AI experienced improved business resilience. The customer demand for AI is strong today, and it is time for all insurers and body shops to start thinking differently about their claims and repair processes and how those processes can be revolutionized through implanting AI and VI – Visual Intelligence. 

Visual Intelligence (VI) is a form of computer vision (a field of AI) that uses image-processing technology and machine learning algorithms to derive insights from photos and videos. At Solera, we have introduced VI at different touchpoints to help the industry make faster and better decisions about a claim. For example, we use VI to pinpoint damage and itemize a line-item estimate within about three minutes by processing photos and vehicle repair data. In this article, I will refer to AI for the photo estimating process but want to note that all AI solutions are not equal, so a close evaluation of AI estimating capabilities is key to success in leveraging this technology to gain greater efficiencies with an elevated level of estimate accuracy and customer satisfaction. 

The current insurance claims processing model is often criticized as being too slow, disconnected and outdated. After experiencing damage or a collision, a customer must call their insurance company to file a claim with a member of the staff, who then sends the claim to the body shop within the insurance company’s network, leaving the administrative work primarily in the hands of the body shop: to contact the vehicle owner, schedule an initial inspection and complete the repair estimate before scheduling the repair. This is the same process that was in place 30 years ago when Direct Repair Programs (DRP) were just getting started.  While technology has improved dramatically, especially over recent years, the DRP process has not changed.  

Over the last two years, customers of all ages began to leverage digital in new and exciting ways to simplify life, from ordering food to having virtual doctor appointments and ordering a wide variety of personal services. Some even used digital options to buy their next vehicle online for a home delivery. I often refer to the pandemic years as the tipping point for digital, as today customers really do “think digital first.” The question for auto insurers and body shops is, how do we leverage these customer digital first preferences to re-imagine the way insurers and body shops interact and assist customers in creating a more seamless claims and repair experience.  

It is clearly time to rethink how auto claims and repairs are processed and ask how the industry can leverage digital tools to improve this process to better service customers and automate many of the manual tasks, which will increase efficiencies and lower operating costs. AI is now an integral part of the customer journey across all industries, and consumers are actively seeking out claims and repair providers that put automation first. 70% of consumers would switch insurers for a faster digital claims experience, while 65% of consumers would choose a repairer using AI to minimize the risk of error in the claims process. In addition to meeting customer demand, AI implementation is also a significant benefit to insurer and body shops as it creates more efficient workflows and requires less employee assistance.

See also: 5 Trends Changing Auto Insurance

From the moment a vehicle sustains damages, the digital journey can begin, with the customer reporting the claim digitally via a customer friendly app or link instead of having to call into an insurance call center where at times hold times can seem long. This can also reduce handoffs in the claims process, simplifying the workflow and reducing the risk of miscommunications. While filing the claim digitally, the customer can also take photos of the vehicle damages and upload them directly through a user-friendly photo app or link to create an AI powered estimate for the body shop that already includes competitively sourced auto parts and AI-generated repair times. Just think, this could allow the body shop to simply review the AI estimate for approval, click a button for parts ordering and call or text the customer with repair date options. The change dramatically reduces the front office admin work while streamlining the process for the customer. 

For insurance call centers, leveraging more self-service digital options for customers who prefer digital would reduce the stress on the call center and provide the photos needed to advance the auto repair quickly, freeing staff to handle the more complex losses. Data capabilities available today can quickly auto-populate claims forms with data, speeding up the processing time and improving accuracy to create a better experience for customers, while AI technology can produce an intelligent estimate of the damages, including the needed parts through the photos provided by the customer. Additionally, transforming the insurer and shop relationship can open greater repair capacity. Not only can insurers work with DRP shops, but with today’s technology customers will have more freedom of choice in selecting a non-DRP body shop as insurers can electronically pre-approve shops outside the DRP that accept the AI repair estimate and have the equipment and skills necessary to complete quality repairs. 

AI leveraging the deep learning of Visual Intelligence is already at work across the industry, and insurers that have chosen to move forward in their digital journeys have already met strong success. 55% of customers surveyed said they have taken digital pictures of their vehicle damages and submitted them to the insurer to speed the claims process, and 100% of insurers were planning to invest in AI insurtech software in the next 12 months. Body shops have also leaned into AI to deliver on digital objectives, and 52% experienced improved profitability after adopting more technological process. With demand for AI on all sides, the insurance industry’s digital journey is already beginning, and it’s clear that the future of claims is an AI-powered touchless or low-touch experience.

While highly automated digital auto claims and repair process will take a lot of thought and planning along with the expertise of a top software provider, the impact will be off the chart with high customer satisfaction, lower body shop administration cost and increased repair capacity, which will lower repair cycle times. The benefits to adopting digital with a well-planned process are truly off the chart, and this is the future for the auto insurance and repair industry. The big question is: Is our auto insurance and repair industry ready to leap into the future and adopt the full benefits of an AI-powered digital claims process?

2 Overlooked Marketing Keys for Agents

Agent and Brokers Commentary: July 2022 

two insurance agents sitting on a couch in an all white office together. There is a white bookshelf in the back containing binders, organizers and plants.

With their massive ad budgets, personal lines insurers can beat their names into our heads -- yes, yes, Flo, I get it. But what are agencies supposed to do? How can they put themselves in front of the right customer at the right time with the right product, in a way that piques the interest of that customer?

I asked Joel Zwicker, industry evangelist at Agency Revolution, which helps agencies with their marketing. Although I'm sure he'd be more than happy to help you spend a massive budget, he had two much simpler and less expensive ideas about how to market more effectively. 

For one, Zwicker says in our interview that agencies don't focus enough on renewal customers. He says there is so much cachet associated with bringing in new customers, that agents don't spend enough time on the massive numbers of leads that they have for additional business with existing customers. He says many agents worry they'll bother those customers by asking for more business but dismisses that worry out of hand and offers an easy way to broach the topic: Ask customers to assign you a Net Promoter Score -- then follow up with the fans.

For another, Zwicker says agencies need to focus more on niches so they can develop and demonstrate the sort of deep expertise that will draw clients. He says agencies often understand the need for a niche but don't go deep enough. For instance, he says, "Some people focus on contractors, but that’s a broad area. Specifically, do you do roofing contractors? Okay, let’s go deeper. Just commercial asphalt, or are we talking about hot tar?"

He says niches don't all need to focus on the product, either. For example, he cites agencies that provide a particular type of experience -- perhaps giving wealthier customers the sort of private-client experience that they get from their financial advisers, or arranging for all touchpoints with the customer to be digital.

Zwicker's approach to marketing won't get you all the attention that Flo does, but you won't have to spend billions of dollars, either. And you won't annoy me the way she does.

Cheers,

Paul


P.S. Here are the six articles I'd like to highlight for agents and brokers:

Agents Must Practice and Prepare

New business opportunities are difficult to come by. So why don't producers properly prepare and practice for those oh-so-valuable prospect meetings?

Inflation and the Auto Insurance Outlook

Auto insurers should expect higher claims costs in the second half and longer wait times for damaged vehicles to be repaired and returned to their owners.

Why Agents and CPAs Must Collaborate

Insurers and accountants have similar concerns on behalf of clients, so the more agents and CPAs collaborate, the better. 

Go All-in With Data Tracking

Agencies are highly motivated to use technology to track data on existing clients, to retain them. We need this same commitment in the pre-sale process for new clients.

Agencies Turn to Networks for Growth

Networks of agencies understand how important it is to provide expert guidance and resources throughout the digital journey.

Digital Is the Assistant We Always Wanted

So why do many companies and advisers in our industry resist digital advances like customer self-service and apps?


Paul Carroll

Profile picture for user PaulCarroll

Paul Carroll

Paul Carroll is the editor-in-chief of Insurance Thought Leadership.

He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.

Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.