Download

Are Claims Leaders Facing a Perfect Storm?

Inflation, tight labor markets and economic volatility create a perfect storm for chief claims officers. The solution is advanced analytics.

Body of water with dark clouds overhead

2022 is off to an exciting start: COVID-19 is waning. But the pandemic's hangover looks to be long and fraught with surprises. Inflation has hit levels not seen since the 1980s. Individuals and businesses saved much of the money given to them during the pandemic, and pent-up demand for goods and services is driving prices for almost everything higher. Actual and perceived shortages of commodities, exacerbated by the war in Ukraine, have contributed, too. Investors reevaluate sky-high equity valuations as interest rates rise, and some markets have corrected more than 25%. Corrections of this magnitude can become self-sustaining as highly leveraged investors sell more to meet margin calls. Time alone will tell how extensive the damage becomes.

Recent inflation, tight labor markets and economic volatility create a perfect storm for chief claims officers. Inflation is detrimental to insurance carrier profits as policy rate increases lag the costs of doing business, especially for settling claims. While some unprofitable commercial lines made progress with rate increases before COVID, combined ratios for commercial auto and general liability are still above 100. Workers' compensation has experienced several years of good profitability, but that has led state regulators to authorize base rate decreases over the last few years. Inflation and a challenging regulatory mindset could be a lethal combination for carriers in this line.

The "Great Resignation" that disrupted the supply of experienced workers across most industries has become the "Great Engagement," adding fuel to the economy's fire. Unemployment rates that pushed above 10% in some demographic groups are now under 3% in others. Employers in all industries are competing for workers by increasing incentives. Many workers have switched industries and perform jobs with little experience. If your server in a restaurant has not done the job before, the result might be poor service. But a truck driver who has never driven an 18-wheeler poses a significant hazard to himself and others. As a result, we will likely see accident frequencies in workers' comp and commercial auto increase beyond expectations over the next few years.

Claims leaders are always looked to for help when anything challenges the combined ratio of an insurance carrier. Pricing and underwriting functions may have contributed to these challenges, but once a policy is written, it's up to claims departments to rein in loss costs and adjustment expenses. Concerning the future performance of claims after the accident year, the NCCI expects that 2021's accident year combined ratio of 102 will fall by 10 points once these claims are settled and closed over the coming years. Experience implies this is feasible, but inflation and economic volatility decrease this outcome's probability.

Where should you turn to pull a fresh rabbit out of the hat when the CFO asks for "your share" of profitability improvement? Claims organizations operate leaner than ever today. Increasing the workload of adjusters who are already stretched thin isn't very feasible. Automation can be an answer, but building and implementing the systems needed to make it work can take years to install and test before they become useful.

See also: How COVID Alters Claims Patterns

A solution to this problem is advanced analytics. Forty to 50 percent of commercial carriers use advanced analytics today, and half of those not using them say they will within two years. Personal lines carriers have shown the way, significantly improving financial performance by leveraging advanced analytics in pricing, underwriting and claims. In claims, assessing severity, triage, finding fraud and determining litigation potential are the leading applications.

Unfortunately, many companies that experimented in these areas failed initially. But cloud computing and improvements in artificial intelligence accuracy significantly improve the odds of success today. Some vendors of claims intelligence can implement their products with very little involvement from the carrier's IT department. Increased cost-effectiveness of massive computing resources has made very advanced artificial intelligence methods feasible and cost-efficient. Some vendors put a great deal of effort into looking at their products and services through the eyes of the claim adjuster, the front-line worker whose engagement with advanced analytics is critical to its successful deployment

Advanced analytics are improving the performance of claims departments in many insurance carriers today. Advancements in cloud technologies and artificial intelligence enhance their performance and make analytics easier and quicker to implement. The future looks challenging for chief claims officers. Now is the time to harness the advanced analytics advantage to survive the perfect storm.

As first published in WorkCompWire.
Insurtech: Still No Sign of Disruption

I hope the next wave of insurtech players will have more robust insurance fundamentals and will not pretend that insurance ignorance is a competitive advantage.

Graphic of a computer with particles coming out

Warren Buffett recently paraphrased the thoughts of an unnamed insurtech: “'We are not an insurance company. We’re a tech company.'" He added: "Well, they’re an insurance company…A dozen people or so have raised a lot of money. They just don’t pay any attention to the fact that [they] sell insurance…. In the end, they wrote insurance and overwhelmingly lost a lot of money.”

Let's see if he's right. Let's look at the Q1 financials of these insurtechs to see how they're doing.

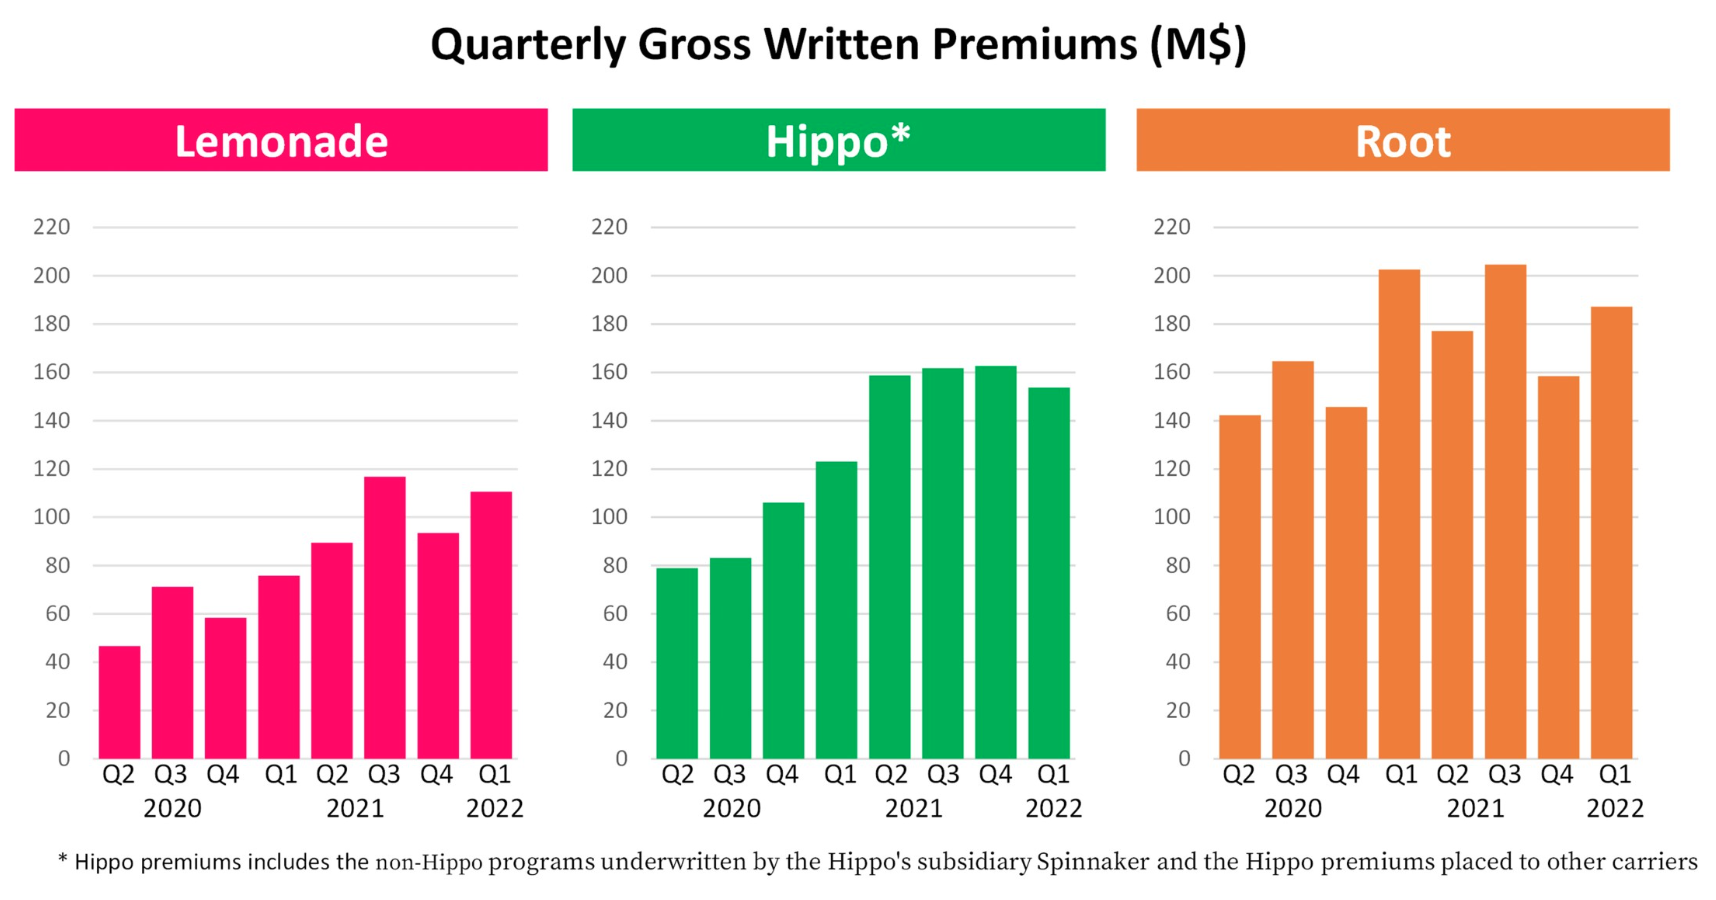
chart comparing insurance companies

Lemonade

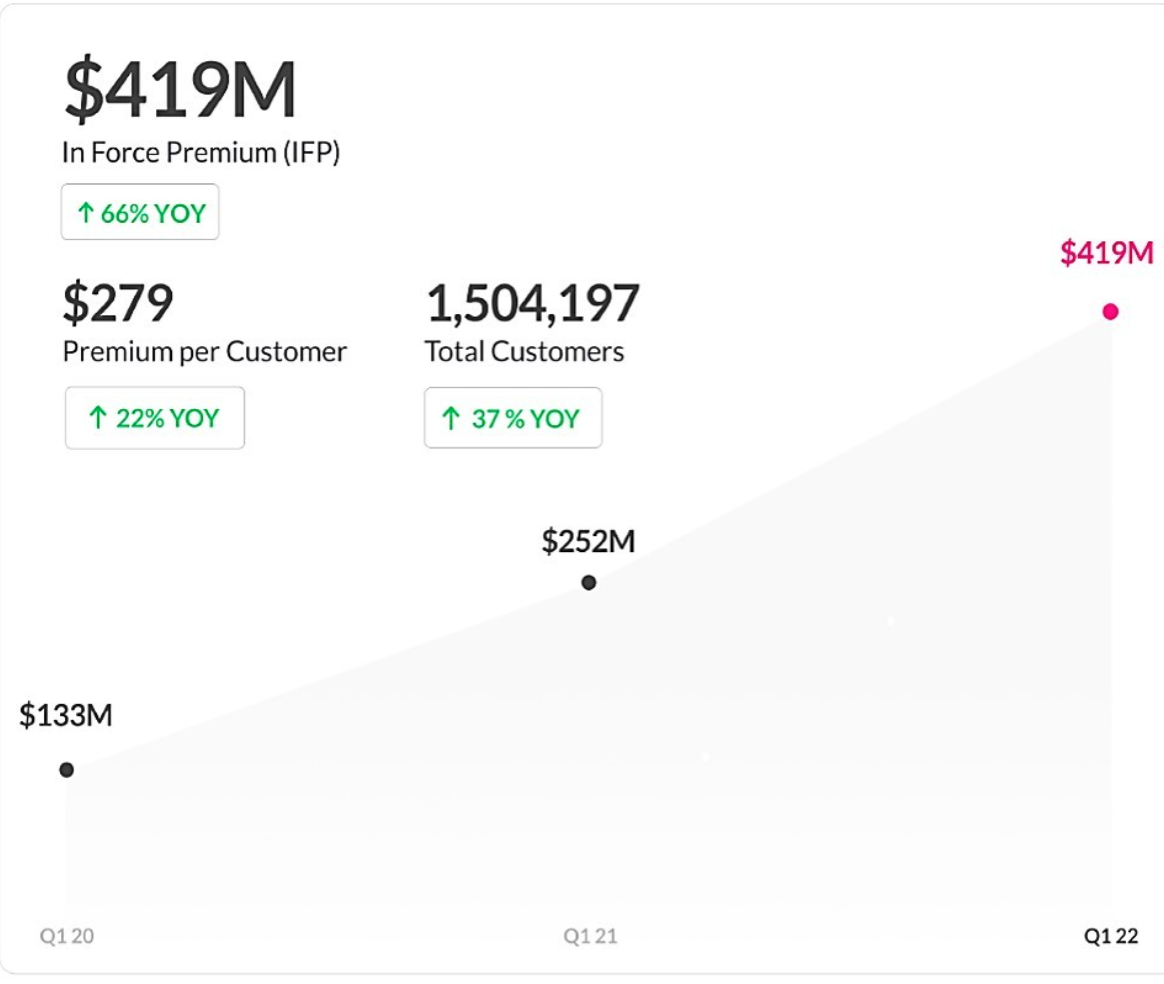
Loss ratio for the company Lemonade

  • Loss ratio: 90% gross loss ratio in Q1 '22 (in line with the 90% loss ratio that led to a 167% COR for 2021)
  • Burned cash: $59 million in Q1 '22
  • Short interest: 34% of float (MarketBeat data at May 15)
  • Market cap: $1.42 billion at May 27 (-46% YTD)

See also: Lemonade: No Sign of Disruption Yet

Hippo

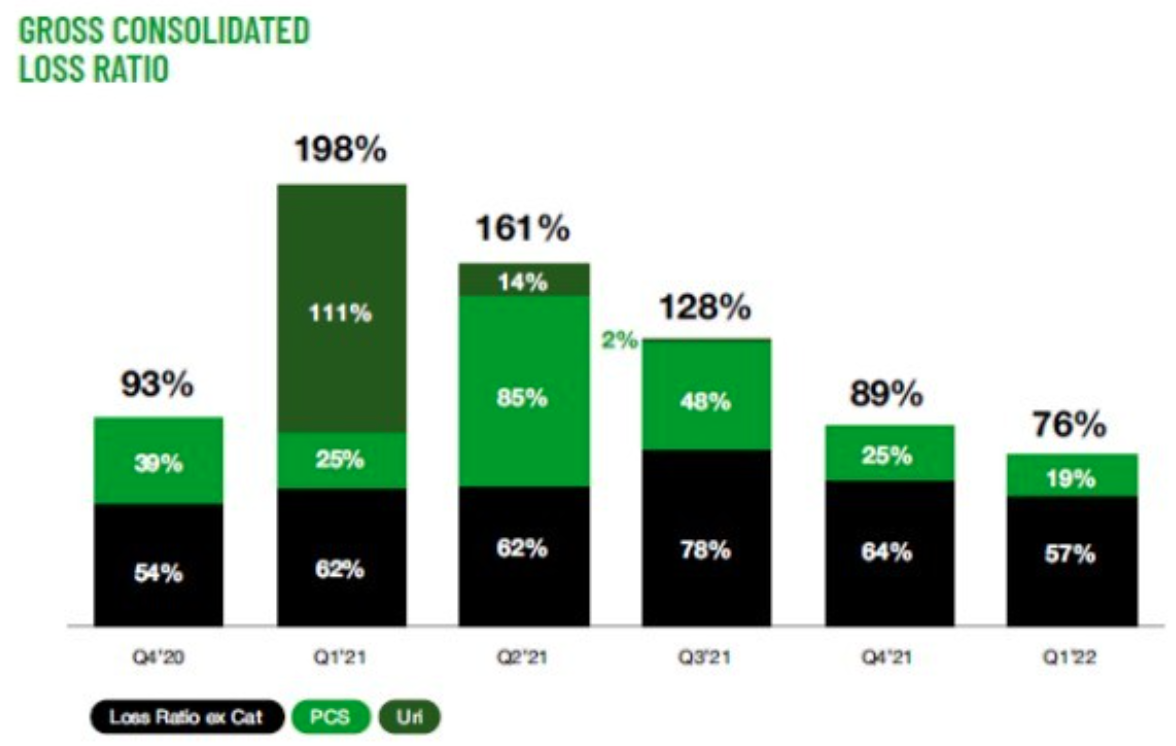
Hippo gross consolidated loss ratio

  • Loss ratio: 76% gross loss ratio in Q1 '22 (significantly improved from 138% loss ratio, which led to 178% COR for 2021)
  • Burned cash: about $59 million in Q1 '22
  • Short interest: 1.6% of float (MarketBeat data at May 15)
  • Market cap: $800 million at May 27 (-50% YTD)

Root

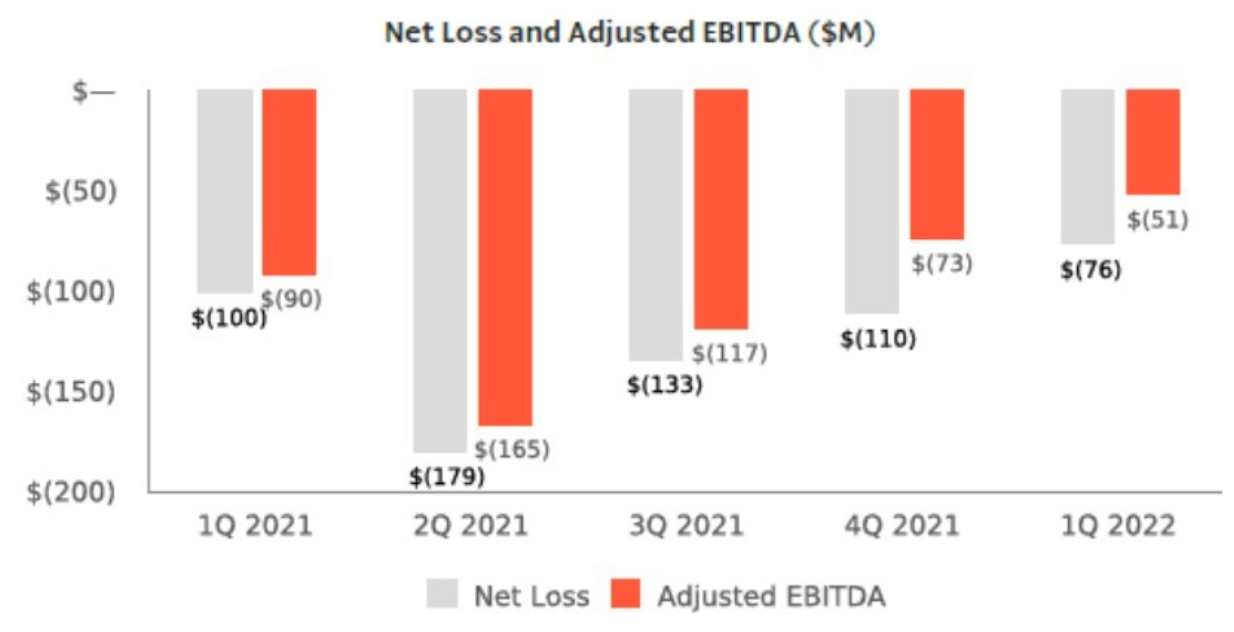
Root net loss and adjusted EBITDA

  • Loss ratio: 93% gross loss ratio in Q1 '22 (slightly improved from the 97% loss ratio, which led to a 157% COR for 2021)
  • Burned cash: about $57 million in Q1 '22
  • Short interest: 4,8% of shares (MarketBeat data at May 15)
  • Market cap: $360 million at May 27 (-57% YTD)

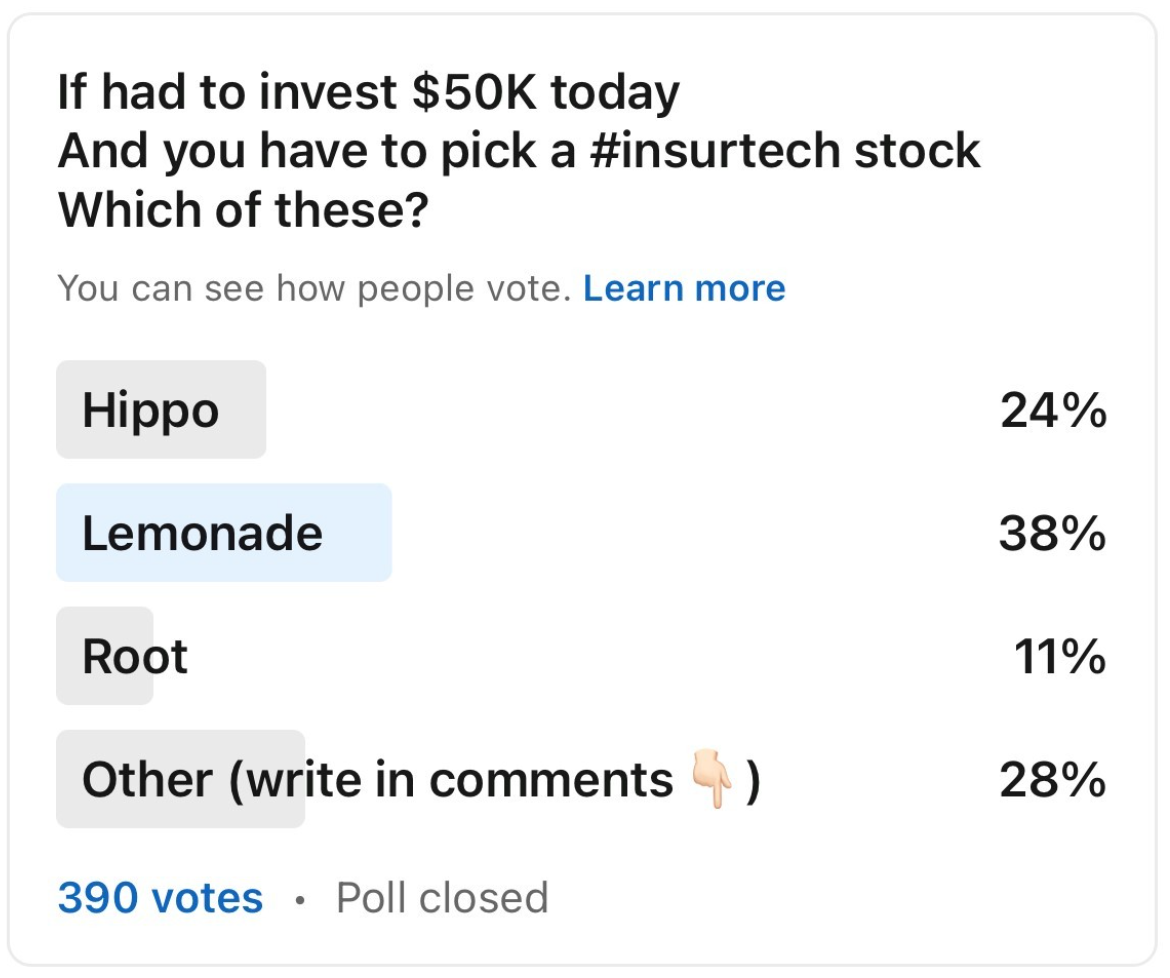
Poll comparing insurtech companies

Despite the facts and figures, fascinating stories show impressive resilience. After the publication of these financials, I did a LinkedIn poll to assess my network's current mood about these stocks.

The poster child of the insurtech passionate stays on top of the ranking!

I'm a firm believer that insurtech solutions will make the insurance sector stronger, therefore more capable of achieving its strategic goal of protecting people's lives. I hope the next wave of insurtech players will have more robust insurance fundamentals than the first wave and will not pretend that insurance ignorance is a competitive advantage.

I've been lucky over the past four years to work with Andrea Battista on Archimede SPAC and -- after the acquisition of Net Insurance -- as a board member of the listed combined entity, which has overperformed the plan we designed initially. This is a concrete experience where insurtech solutions have been integrated into the insurance value chain to perform the insurance job better (to assess, manage and transfer risks). Lessons learned: tech & underwriting discipline!

We have seen hundreds of insurtech articles with click-baiting headlines claiming a coming disruption in the insurance sector for the last seven years. Now they are shifting to the underwriting discipline.

Talking about past disruption expectations and current mood, Bill Harris, chief revenue officer at Insuretech Connect, adds some color.

Matteo: ITC is at its seventh edition; you have observed the entire first insurtech wave. What is your critical review of these seven years? How has the thinking of industry leaders changed?

Bill: When we launched ITC back in 2016, it was all about disruption, and we asked, “Will insurtechs replace traditional carriers?” It’s evolved into a more symbiotic relationship. Now, carriers understand insurtechs can help enhance their offering, and especially how to be more customer-centric. When we began seven years ago, investment was everywhere, the first million was easy to get. We are now seeing a trend where it may be harder to get the early seed/Series A investments, but the investment amounts in later rounds are much bigger. To us, it indicates that the VCs and CVCs know exactly what they are looking for and are not scared to invest massive rounds in companies that can really scale. 

It's been interesting to observe insurtechs that have become carriers and gone public. A few on our team might say that it’s been more interesting to see the likes of Trov, Bold Penguin and SingLife be acquired by carriers. Also, we are delighted to see how insurtechs such as Flock or Zego are evolving and expanding their lines of business. ITC is a platform where you come to see new and emerging insurtechs, plus new product launches from innovators that we’ve seen evolve over the past 7 years. 

See also: Strategies to Combat Barriers to Insurtech

Matteo: What should people expect from ITC 2022?    

Bill: We’ve developed a meaningful formula for ITC, so we will continue with a focus on making connections and showcasing the top thought leaders. We recently announced that McKinsey is joining us as the presenting sponsor at ITCVegas, which is a great honor for us.  

One innovation to our content is that we will host 14 distinct tracks across seven stages to make it easier to plan your time. We look forward to seeing you again, Matteo!

Strategies for Smaller Life Insurers

One option is to focus on being nimble -- too many large carriers still must wade through layers of organizational complexity to get anything done.

People around a table working with tablets

U.S. life insurance carriers have faced significant challenges in recent years, particularly low interest rates and the burden of legacy systems. These issues are compounded for carriers with less scale and more modest budgets, perhaps having less than $50 million of annual new sales or under $2 billion of assets.

Larger carriers have achieved certain economies of scale in operations, information technology and new business processing, which brings pressure on operating expense ratios for smaller carriers. 

In addition, capital requirements are higher for certain lines, such as term and no-lapse guarantee (NLG) – a carrier with a very large in-force block relative to new sales has much larger profits from that book to better absorb the capital strain from new sales. Higher-selling carriers also have more leverage with reinsurers and bankers in developing structures for reserve engineering. Yet because of stringent profitability and capital usage constraints, carriers are exiting these lines (which should improve profit measures for remaining carriers), even though they are the products most in demand from distributors, as measured by policy count. One need only look at the sales of the insurtech startups to see the demand for term and similar products.

Investment management has become more sophisticated with private equity (PE) approaches to asset management generating increasing yields. The question, of course, is what increased risk are carriers taking on with certain asset classes that offer an illiquidity premium but may present specific challenges in a market downturn. This may be an opportunity for carriers’ in-house investment managers to re-assess specific strategies, while noting that regulatory considerations are also surfacing with respect to these approaches. But clearly the annuity carriers are doing well in gathering assets to generate higher investment income.

Distribution channels are demanding more from carriers. Witness the continued aggregation of independent marketing organizations (IMOs), such as the market power of the merger several years ago between LifeMark and BRAMCO, and the rapid-fire purchases of agencies, including very large ones, by entities back by private equity. Such consolidation in life distribution will, in my view, increase pressures on carriers for competitive pricing and compensation, but it is hard for a carrier to be a price leader if it is not a cost leader, or supported by one.       

So, what is a smaller carrier to do to survive and thrive in this environment?

It is difficult for smaller carriers to be a price leader, so they need to focus on other differentiating factors, and look to where they can have a competitive advantage.

See also: A New Boom for Life Insurance?

One option is to look at niche markets – opportunities in specific sectors where relationships and specific expertise matter more than price. This contrasts, for example, with fixed and fixed-indexed annuities that are very competitive, unless you have a unique product or service approach. Getting really good at a specific niche can be a big plus!

A second option is newer takes on traditional products – perhaps upending long-held views on product structures or underwriting approaches. There may be opportunities to have such an approach supported by reinsurance from a capital management perspective. Tied in with this, a carrier might examine product development - being able to listen carefully to distributors and customers, vs. larger companies doing canned surveys that provide little insight. Too often such market research is done by staff lacking the expertise/experience to "connect the dots" and see truly feasible opportunities. This may also involve a much more personal approach with distribution at all levels of the carrier.
    
A smaller carrier may want to focus on being nimble - too many large carriers still must wade through layers of organizational complexity to get anything done, even if they've invested in newer technology platforms promising speed to market for product development. This may involve rethinking your product development approach, particularly internal approval processes and IT considerations. In some cases, smaller carriers with rigorous cost control and fewer layers may be able to justify very competitive pricing. In conjunction with this, you may want to consider proprietary products developed in close conjunction with significant distribution organizations.

Another option is a different approach to customer service, which historically has been focused on transactional efforts on in-force policies, with little focus on emphasizing cross-selling and up-selling opportunities. Some companies have done this well, having implemented the structures and incentives and partnerships with their distribution entities to make this a successful revenue center, but for many large carriers this aspect has been essentially ignored by the policy owner service team. I observed this personally while recently trying to help a friend wade through the process of porting some group life coverage. In essence, carriers may want to look at a lifetime value (LTV) approach to customers and distributors. 

Smaller carriers should also look to unique approaches to analytics and technology. Developing unique expertise in specific aspects of underwriting might be worth considering. Along the same lines, it may make sense to outsource those aspects of the value chain where a smaller carrier may not have the necessary expertise in-house, possibly in asset management and some aspects of operations. You may look to shared approaches for certain functions – at least one smaller carrier with which I’m familiar has become in essence a "virtual insurer," laser-focused on particular markets, products and distributors.

I hope these ideas provide some food for thought in your strategic deliberations and am happy to discuss these in much more detail.


Alan Lurty

Profile picture for user AlanLurty

Alan Lurty

Alan Lurty is practice director for insurance in Korn Ferry’s Interim Executives and Professionals practice.

He is a proven senior executive in the insurance and financial services sector with a passion for building companies into profitable industry leaders through new products, new markets and new distribution. He was most recently at M Financial Group as vice president of insurance solutions during a period of record sales.

Lurty’s career highlights include heading business and product development for nine years at ING/Voya Financial, where he spearheaded the development of products that increased sales from 17,000 paid policies in 2005 to over 200,000 by 2009, building a new distribution channel at ING to $45 million of sales within three years and, with P&L responsibility for Voya’s $100 million affinity markets division, increasing net income within the first year from $800,000 to more than $3 million.

Lurty was also chief marketing officer for SCOR Re and chief operating officer for annuities at CNA Life. His significant experience includes developing the industry’s first modern guaranteed level term plans and the first life product with wellness features. 

He holds an MBA in finance and strategic planning from Ohio State University, graduating first in his class, and a bachelor of music in piano performance, summa cum laude, from Kent State University. He has also participated in executive leadership programs at the Darden School at the University of Virginia and at other universities. 

From Agents First to Agents Last?

Even though agents are thriving, direct distribution will significantly increase, insurtech will play a big role in reshaping distribution and big tech companies will enter the space.

Man at a desk looking at a piece of paper

Let me begin by saying I am a big fan of agents, and I believe they will play a vital role in personal lines distribution for a long time to come. But, clearly, direct distribution models in personal lines, and the prominent companies that feature them, have gained traction and market share over the last two decades. The insurtech movement has now presented new options for digital distribution, such as direct digital via web/mobile. And now, all the talk is of the potential for embedded insurance that incorporates insurance at the point of sale. These new options usually (although not always) bypass the agent.

SMA asked agencies and carriers how they expect personal lines distribution will change in the next five years. Both agencies and carriers cite continued consolidation in the distributor space as the number one way the landscape will change. However, close behind are expectations that direct distribution will significantly increase, that insurtech will play a big role in reshaping distribution and that big tech companies will enter the space.

In the past, when an individual needed insurance for their car, motorcycle, home, apartment or personal property, they would reach out to their local agent. The agent may have been captive or independent, but the point is that the best path to obtaining insurance coverage was to get the advice of an agent. In the case of an independent agent, a customer would get advice on which carrier best met their needs. Thus, historically the approach for personal lines insurance has been “agent first.” Now, in today’s digital world, many digital on-ramps lead a customer to insurance. In some cases, this results in completely digital interactions, from needs analysis to policy issuance. This would be an “agent-none” scenario. However, in many cases, an agent is still involved somewhere in the process. Perhaps “agent last” is too extreme a term, but even when the buying process begins at a comparison site, digital retail site or showroom floor, the buyer may ultimately be connected to an agent to complete the transaction.

An example that brings this idea home is the recent launch of HUB International’s VIU platform. This digital platform enables individuals to compare choices and prices for auto and homeowner’s insurance – as many comparison sites do. However, the transaction is not end-to-end digital. The final purchase always ends with an agent. This approach provides agents with the opportunity to provide additional advice that may lead to cross-sell or up-sell opportunities. It also establishes an agent of record that can be available for policy services, if appropriate.

See also: Foundational Tech for Personal Lines

Many similar examples exist for other comparison sites, insurers’ mobile apps, affinity group sites and other digital on-ramps that connect prospects with insurers. Even in embedded insurance examples where the insurance is purchased as part of the automobile or home sales transaction, there may be an agent of record assigned to follow up and be a human connection point for the customer for future needs and renewals.

Will direct models and digital on-ramps spell the demise of the personal lines agent? Many have been predicting as much since the dawn of the internet and digital communications. Yet agents are surviving and thriving. They are consolidating for scale to support their own digital capabilities and enhancing their relationships and expertise to stay competitive. While there is little doubt that the percentage of personal lines insurance transactions that go completely digital will steadily increase, there will likely still be agents in the picture for the foreseeable future – even if customers don’t come to the agent first.

Agents and brokers, we want to know if your carrier partners are meeting your expectations. SMA’s new survey assesses the current state of P&C distribution, including digital sales and service capabilities, and will reveal the opportunities and strategies of today’s retail agencies. Agents who complete the survey will also be entered to win a $250 Amazon gift card.


Mark Breading

Profile picture for user MarkBreading

Mark Breading

Mark Breading is a partner at Strategy Meets Action, a Resource Pro company that helps insurers develop and validate their IT strategies and plans, better understand how their investments measure up in today's highly competitive environment and gain clarity on solution options and vendor selection.

Is Silicon Valley Passe?

An announcement by a prominent venture firm suggests we have reached peak Silicon Valley and, more broadly, are headed toward a more decentralized model for innovation. 

Image
a road sign that reads Silicon Valley Blvd exit 377A 3/4 mile

Living in six cities in three countries on two continents in my 17 years at the Wall Street Journal, I often heard locals claim they were going to render Silicon Valley obsolete. New Yorkers were developing a Silicon Alley. Chicagoans planned a Silicon Prairie. Scots promised a Silicon Glen. But Silicon Valley barely noticed. 

Now, an announcement by one of the most prominent venture firms suggests we may finally have reached peak Silicon Valley and, more broadly, suggests we are headed toward a more decentralized model for innovation. 

The announcement from Andreessen Horowitz is that it is moving its headquarters from the very heart of Silicon Valley venture capital, on Sand Hill Road in Menlo Park, to "the cloud."

The firm says the past 2 1/2 years of operating remotely because of COVID have shown that startups can innovate and operate very effectively without having everyone in the same place, which has reduced the need for aspiring entrepreneurs around the world to pack up and move to the Bay Area. If the firms don't need to be crammed into Silicon Valley, then the VCs don't, either. 

Now, I was born at night, but not last night. There is some obvious PR behind the announcement. Andreessen Horowitz is one of the biggest backers of what it calls Web3 (known to others as the Metaverse), and it can't very well be evangelizing for a decentralized, largely disembodied universe for interactions if it makes everyone show up in a single office every day. 

Still, the shift to a virtual model for the firm seems justified. The magic of Silicon Valley has always come from its having achieved critical mass -- of entrepreneurs, of money and of engineering talent. With Stanford right there and Cal just across the bay, the talent was always abundant. Then, Hewlett-Packard and Intel hit it big in the '50s and '60s and started a modern-day gold rush of entrepreneurs who thought they could do just as well. Money, of course, followed the successful entrepreneurs. 

But with the shift to remote work, critical mass in a physical location just doesn't matter so much any more. Bloomberg reports that office vacancy rates in San Francisco were 18% in the second quarter and 15% in the larger Silicon Valley area, compared with 11% in Manhattan. Even Ben Horowitz, one of the eponymous cofounders of the firm that calls itself a16z, has moved to Las Vegas. 

That shift suggests that insurers, too, can change how they approach collaboration, in general, and innovation, in particular. Rather than thinking in terms of localized talent and collaboration, insurers can pull in people from across the organization, without the need for them to relocate, or even get on a plane. It is becoming easier, too, to incorporate people from partners, swapping them in and out as needed. With Silicon Valley's state-of-the-art practitioners heading toward a distributed approach to innovation, the rest of us can watch, learn and copy.  

To be clear: I'm not predicting the demise of Silicon Valley. Bloomberg says firms based in Silicon Valley received $52.3 billion in venture capital in the first half, or 36% of the nation's total, while Austin, Texas, seen as a rising star, got only 2.6%. (New York was second behind Silicon Valley, with 27%, while Los Angeles was in third, with 17%). And many will still value the serendipity factor--you never know who you'll see at Il Fornaio for breakfast, Buck's for lunch or the Rosemont bar for late-night drinking sessions. 

Maybe I'm just hoping that we've reached peak Silicon Valley so I can stop watching the Zillow estimate on the house we bought in Atherton in 1996 and sold in 2002, which has climbed (soared?) steadily for years and currently stands at $7.9 million. If only....

Cheers,

Paul


Why Are Food Plants Catching Fire?

Looking at the root causes of the spate of fires -- and the root causes of the root causes -- suggests a lapse in discipline in enterprise risk management. 

Picture of a flame of a fire

Very recently, I heard John Catsimatidis, owner, president, chairman and CEO of Gristedes Foods, say on a news show that someone needs to look into the spate of fires occurring at food manufacturing plants around the U.S. When I looked this subject up on the internet, I found a lot of news and speculation. The news from organizations such as Reuters and the National Fire Prevention Association (NFPA) cited statistics about fires that led them to the conclusion that the number of recent fires was not above the norm; in other words, there was nothing suspicious about them. However, there was also general speculation by other sources that there was something suspicious going on and that nefarious actors might be behind the fires.

Because the NFPA doesn’t specifically track fires at food-processing plants alone, but rather fires at agricultural, grain and livestock and refrigerated storage facilities, which could all include food processing operations, the use of these statistics to benchmark food processing plants does not seem satisfactory. And if the number of fires was not out of the norm, then why is there so much attention being placed on them now? But I will leave the numbers and probability plotting to actuaries.

With over 20 fires at food manufacturing plants or food distribution centers by mid-year, the question becomes one about how well these plants are managing their risks. Fire risk can stem from a variety of causes or hazards. The categories of causes include: 1) poor housekeeping, 2) dangerous/flawed processes, 3) equipment failure, 4) natural catastrophes and 5) human error or malfeasance.   

The role of enterprise risk management is to bring together the disparate functions in an organization to identify risks and mitigate them regardless of root cause. An “all enterprise” solution is needed to manage risks because many root causes have root causes themselves.

Consider a food processor that stores certain preservatives in refrigerated areas and away from operational activity, but when the refrigerated areas become full puts some of this material into a non-refrigerated area temporarily. The preservatives are highly combustible. The non-refrigerated area is subject to high temperatures, overcrowded conditions and high equipment traffic. A small spark sets off from the equipment and alights on the preservatives, starting a fire. 

The root cause of the fire is that these highly combustible preservatives should have been refrigerated and somewhat isolated but were not. Yet, what about the root cause of the root cause? The procurement department wanted to take advantage of good pricing and decided to increase the amount of preservatives it usually ordered without checking to see if warehousing could accommodate the bigger order appropriately. 

This example points to why a holistic approach to risk management is so necessary. Spontaneous combustion would be a high risk area for the company and should have detailed mitigation strategies in place, one of which should be joint planning and communication between procurement and warehousing.

See also: Top 2022 Global Business Risks

This scenario is not taken from any of the recent fires. Rather, it is meant to highlight the need for an enterprise approach to risk management. In determining a mitigation strategy, both engineered solutions and human behavior solutions need to be invoked. 

Engineered solutions include such things as: 1) sprinkler systems, 2 fire retardant building and storage materials, 3) site lay-out and 4) combustible materials handling protocol. Human behavior solutions include such things as: 1) management commitment to enterprise risk management, 2) worker training, 3) strong performance management by supervisory staff through daily observance, periodic inspections or audits and 4) recognition for excellent safety records. 

The protection of our food supply at every stage in the value chain is vital to the strength and security of our nation and our people. Therefore, food manufacturing needs the most robust ERM practices feasible.


Donna Galer

Profile picture for user DonnaGaler

Donna Galer

Donna Galer is a consultant, author and lecturer. 

She has written three books on ERM: Enterprise Risk Management – Straight To The Point, Enterprise Risk Management – Straight To The Value and Enterprise Risk Management – Straight Talk For Nonprofits, with co-author Al Decker. She is an active contributor to the Insurance Thought Leadership website and other industry publications. In addition, she has given presentations at RIMS, CPCU, PCI (now APCIA) and university events.

Currently, she is an independent consultant on ERM, ESG and strategic planning. She was recently a senior adviser at Hanover Stone Solutions. She served as the chairwoman of the Spencer Educational Foundation from 2006-2010. From 1989 to 2006, she was with Zurich Insurance Group, where she held many positions both in the U.S. and in Switzerland, including: EVP corporate development, global head of investor relations, EVP compliance and governance and regional manager for North America. Her last position at Zurich was executive vice president and chief administrative officer for Zurich’s world-wide general insurance business ($36 Billion GWP), with responsibility for strategic planning and other areas. She began her insurance career at Crum & Forster Insurance.  

She has served on numerous industry and academic boards. Among these are: NC State’s Poole School of Business’ Enterprise Risk Management’s Advisory Board, Illinois State University’s Katie School of Insurance, Spencer Educational Foundation. She won “The Editor’s Choice Award” from the Society of Financial Examiners in 2017 for her co-written articles on KRIs/KPIs and related subjects. She was named among the “Top 100 Insurance Women” by Business Insurance in 2000.

How to Simplify Customer Experience

Automation and other digital technology, often unseen by the consumer, continue to improve operations for insurers with the vision to embrace them.

Person pointing at the screen

Today, we can sit on the couch, in the car, or by the pool and buy anything we want online -- including insurance. The evolution of the insurance industry makes it easier than ever to get quotes, choose the right policy, file claims and get updates on claims with very little effort. Whether consumers are shopping for car insurance, supplemental benefits such as accident insurance and critical illness coverage, or medical insurance, the processes are automated. Artificial intelligence (AI), machine learning (ML), optical character recognition (OCR), chatbots, data mining and automated underwriting tools are a few examples of automated technologies that make the processes easier for consumers and insurance carriers.

Integrated and Efficient Underwriting 

Automation has introduced new efficiency to the underwriting process for insurance carriers. Tools such as FINEOS Underwrite, Optum and Workhuman allow for integration with their internal and third-party systems, automate workflow and ensure compliance with standards and requirements. As a result of automation, the carriers no longer must worry about manual, rote tasks and can instead focus on customer service and providing consistent information regardless of who the consumer is talking to within an insurance organization. 

Aids in Choosing the Right Policy

When it comes to the consumer, it can be intimidating to choose the right policy for a specific situation. Automation makes this process easier. Most carriers provide comparison tools to help people choose the right policy in both the retail arena, such as car insurance, and in employee benefits. After answering a few basic questions, they are presented with a comparison of different policy options based on their individual and family needs. Price and coverage are personalized based on the information they entered. The introduction of AI and chatbots allows for answering basic questions instantaneously without talking to an actual person or waiting for a call back after a seemingly endless climb through a phone tree.

Simplifying the Claim Filing Process 

Once coverage has been purchased, a claimant can use a computer or an app on a mobile phone to submit a claim. Filing a claim requires that sensitive information be shared with the carrier in a secure manner. These portals include the ability to upload documentation, eliminating the need to fax the documentation or figure out how to send an encrypted e-mail to try to keep the information secure.

Data mining allows automated decisions on some simple claims within just a few minutes if not a few seconds. Data mining can help insurance carriers configure their systems to identify claims that are approved a certain percentage of the time (e.g. 85%, 95% whatever the carrier is most comfortable with) and approve them based on submitted information and policy terms -- without a person ever looking at the claim.

This is good for consumers because they know immediately that their claim was approved. And it’s good for insurers because their employees don’t have to manually process routine claims, freeing them to assist where their expertise is needed. For claims that are not simple, the claimant will receive instantaneous communication informing them if their filing is complete or if additional information is needed, with the specifics of what is still missing. This gives the claimant comfort in the knowledge that the carrier has received their claim instead of being left to wait and wonder until they receive a letter in the mail days or even weeks later.

See also: Insurers Turn to Automation

Faster Claim Status and Tracking Process

Claims processing is significantly faster because of ML and OCR, and the claimant benefits. ML uses algorithms to learn what processes a human follows to automate those workflows. OCR can remove the need for a claims examiner to review the documentation to also speed up determination of a claim. The claims examiner can devote their expertise to more complex claims that require additional attention and communication with the claimant.

In addition to accelerating the determination process, digital solutions allow claimants to track their claims through a portal in real time. Digital solutions let consumers choose how they want to receive their claim status updates and communications (text message, email, potentially even a paper letter). They can see status updates like, “Your claim is with an examiner but is still pending,” or “Your claim has been approved.” Customers typically receive notifications regarding the status of their cases in near real time through prompts to log on or through an email or text message.

Smart and Fast Decisions 

Although insurance can be intimidating, automation helps take away much of the difficulty in the decision-making and claims processing for consumers. It allows insurance carriers greater speed and efficiency processing simple claims, giving claims advocates more bandwidth to care for their clients. Automation and other digital technology, often unseen by the consumer, continue to improve operations for insurers with the vision to embrace them.

A Guide to Legacy Modernization

78% of digital transformation efforts fail to drive desired results due to poor planning. Here are some steps that will ensure success.

Person typing on a computer with headphones on

Whether you are moving from a paper-based system or upgrading an existing application, you may have already realized the dire need for digital transformation within your organization. Moreover, you might have validated this decision with the requisite proof and convinced the higher-ups to give a green light to the modernization process. However, 78% of digital transformation efforts fail to drive desired results due to poor planning. In other words, insurance agencies have to chalk out a concrete plan for this ambitious venture.

Here are some steps that will ensure legacy system and technology modernization success:

Make Organizational Goals Concrete

By this point, you may have already identified the problems and pressing issues plaguing your current system. With this problem statement in mind, identify the changes that you anticipate with the introduction of modern applications and insurance technologies. The resulting objectives would serve as your organizational goals. For greater efficacy, translate these into SMART goals (specific, measurable, achievable, relevant and time-bound) so you can monitor the progress.

Evaluate the Available Options

Once you have acknowledged the persistent problems and devised possible solutions, it is time to bridge the two by seeking practical options. Here’s a quick summary of some of the most common application modernization techniques:

  • Retain and Expand: Retain the legacy system and make necessary modifications to expand its scope and applicability.
  • Rehost: Rehosting is a lift-and-shift approach, modernizing applications with minimal modifications.
  • Replatform: Replatforming requires shifting the entire code or parts of it to a new ecosystem while retaining the core functionalities.
  • Refactor: Refactoring optimizes the code and code structure to update the legacy software.
  • Redesign: Redesigning involves making significant changes to the code architecture to enhance capabilities.
  • Rebuild: Rebuilding entails redesigning and rewriting the application without changing the scope, specifications or capabilities.
  • Replace: Replacement should be the last resort if insurance agencies can no longer justify the use of legacy systems. If you are still stuck with obsolete paper systems, replacing them with digital-age insurance software solutions would be the first option.

These 7 R's of application modernization will help you prepare a successful road map for your transformation.

See also: 4 Keys to Agency Modernization

Prioritize the Modernization

After you have decided on the technology modernization methodology, you need to weigh out its impact with regard to the workload, resource availability, downtime, risks, cost, etc. Based on these parameters, you can minimize the impact by prioritizing the activities based on their relative importance for maintaining business continuity, resilience, agility, etc.

Once again, the SMART principle can help quantify these goals and ascribe them to a timeline.

Select a Technology Partner

While the need for digital transformation and legacy modernization may stem from pressing issues requiring immediate action, insurance agencies may not be equipped to handle such a mammoth task on their own. In such a situation, it is always wise to partner with a technology enabler for the job as you focus on your core operations. Look for an organization that specializes in the digital transformation of insurance agencies so that they can cater to your specific requirements.

Test, Observe and Optimize

Digital transformation and technology modernization are continuous processes. As such, insurance businesses have to keep an eye on their status and progress during and after implementation. Test, observe and optimize the workflows.

Closing Thoughts

Even though digital transformation and application modernization may seem overwhelming, they do not have to stay that way. A well-planned and -thought-out strategy can overcome any obstacles and help your company get the most out of this process. Legacy system and application modernization will free your insurance business from IT complexities and compatibility issues. By leveraging digital-age insurance technologies, you can adapt and innovate at scale.

Tackling Turnover Amid the Great Resignation

Digital Adoption Platforms can help new employees get up to speed quickly and can upskill existing workers to fill gaps caused by turnover. 

Woman in an office putting items into a box after resigning

There has been a significant shortage of insurance professionals for years, and now the Great Resignation has hit. Jacobson Group’s recent Insurance Labor Market Study found that insurance professionals are exploring their options and taking a hard look at their current jobs.

As more employees move between jobs with greater frequency, companies are compelled to onboard workers quickly to maintain business continuity while upskilling the existing workforce to fill talent gaps and minimize any loss in productivity.

While many applications are deployed to help ease employees’ workload, they do not always make for the right transitions when it comes to learning for both new and experienced employees. There still remains a need for continuous support and feedback-driven change management for the workforce. Digital Adoption Platforms (DAPs) help address those issues and, if deployed correctly, can help employees get up to speed quickly and effectively.

What are Digital Adoption Platforms?

A digital adoption platform (DAP) is software that integrates fully with your enterprise applications. The software can then walk users through the applications step-by-step to complete role-specific tasks and navigate on their own. DAPs also feature a self-help widget with links to articles, videos and guided walkthroughs so users can effectively search and learn every aspect of the application. The software helps prevent user confusion when they are trying to understand specific tasks and lets them focus on the task at hand. 

A DAP can be used to drive digital adoption in a number of ways. One of the most effective ways is to help companies onboard and train employees on new technology. DAPs help keep employees on track and ensure they get the knowledge they need for the most essential features of their job. DAPs also teach employees how to help themselves, ensuring they know how to find the answers to their questions. Another important DAP feature is the ability for users to search for and find all relevant documentation when they need it.

See also: Opportunities Amid the Great Resignation

DAPs' Role in Onboarding

The benefits of DAPs in the insurance industry are numerous. Because insurance is driven by internal and external regulations specific to each business, region and the different types of products offered, there is a steep learning curve. And, especially with younger employees, you may have to be prepared to onboard frequently. The latest Deloitte Global 2022 Gen Z and Millennial survey found that 40% of Gen Z workers would like to leave their jobs within two years. It can take a long time for any employee to become proficient in their area, whether it be underwriting, claims or distribution. A DAP’s ability to flatten that curve is invaluable to insurance companies to onboard new employees quickly and efficiently.

Your onboarding process can be significantly improved by using DAPs to create near-real-life simulated training experiences and custom training content to make underwriters, claims and service representatives more proficient. New employees will be encouraged to lean into the flow of work. The guided walkthroughs engage users nearly every second of the training process and will also help reduce the number of errors new employees make. Leveraging AI, a DAP can identify and rectify mistakes with automated data input. 

Upskilling Experienced Workers

Upskilling is unavoidable and absolutely necessary in the insurance industry. Workers will inevitably receive added responsibilities and tasks to their current roles. This may include overseeing a new region with different regulations, processing more policies each day or working in a new cross-functional role due to staff shortages. In each case, it takes time for employees to gain the desired level of knowledge and proficiency for the applications used to perform those new duties.

Most of the workflows within legacy insurance applications are complex, making it hard for users to understand their current tasks, let alone handle any new responsibilities. DAPs integrate with existing applications to help users learn more about the important features and processes. The same step-by-step walkthroughs that benefit new employees can be used to expand the knowledge base of more experienced employees. If an employee runs into a problem regarding a certain insurance process, they can look to self-help menus and access walkthroughs to get the help they need.

DAPs enable employees to maintain productivity levels while taking on new responsibilities. One of the ways this can be achieved is through just-in-time nudges to reduce errors made in policy or claims processing. A DAP can also pre-fill or validate entries to speed certain processes and ensure data entered adheres to the correct format. Another way a DAP can help is by automating repetitive tasks, allowing employees to focus on judgment-intensive and more crucial tasks. Through the creation of on-demand content and training, insurance companies can leverage a DAP to increase employee productivity and reduce the margin of error. Smooth onboarding and seamless transitions to new roles for experienced employees can be achieved faster as they gain the power to learn more quickly on their own terms, ensuring that your organization can stay on track despite employee turnover.


Vara Kumar

Profile picture for user VaraKumar

Vara Kumar

Vara Kumar is the co-founder and head of R&D and solutions at Whatfix.

Kumar co-founded Whatfix with Khadim Batti in 2014 with the vision of empowering individuals and organizations to work symbiotically with technology to maximize their potential. 

Tomorrow’s FNOL Has Arrived Early

As digitization, mobility and connected vehicle technologies transform auto insurance, a better FNOL solution is now critical – and it's here.

Cyber network showing blockchain

Claims are frequently cited as “the moment of truth,” and FNOL (First Notice of Loss) is where all claims begin. Now, new technology through an innovative industry collaboration on a blockchain platform is being leveraged to enable FNOL data exchange between insurers – and eventually other claim ecosystem partners.

RAPID X is the trade name for RiskStream’s First Notice of Loss Data Sharing application, which has been developed with and for the property and casualty insurance industry by the RiskStream Collaborative, an industry nonprofit affiliated with The Institutes. Rapid X was introduced earlier this year, and the insurtech space has since lit up with numerous efforts to modernize the traditional process of reporting and starting an insurance claim.

The Institutes’ RiskStream Collaborative has a different approach, which focuses on creating an ecosystem within the risk management and insurance industry that leverages a scalable, enterprise-level blockchain/distributed ledger technology framework to streamline the flow and verification of data. The effort lowers operating costs, drives efficiency from improved processes and enhances the customer experience.

This capability is perfectly positioned for the next generation of advancements in claims. As the insurance industry strives to prevent and detect accidents through telematics and crash notification, these features accelerate the tempo of FNOL and claims reporting. Immediate sharing of claim notification via RAPID X will enable all stakeholders to coordinate more immediately, no longer waiting until the end of the claim process to reconcile information vital to subrogation.

Greater efficiency and less redundancy in individual processes are just a couple of benefits. Consider a minor auto accident between two drivers, where both insurance companies have separate loss intake processes, individual claims investigations and duplicated, related process steps. A common customer complaint concerns the number of times they have to describe how the accident happened, not to mention the overall confusion created from interactions with two or more carriers and their various specialized adjusters. RAPID X shares data between insurers to create a universal FNOL among carriers, setting the stage for streamlined data-sharing processes.

FNOL and Claims Process Transformation: Why It Matters

P&C insurance is going through an unparalleled period of change that has attracted exciting, record-setting insurtech investments. One of the most discussed areas is FNOL, the first step in the claims process.

Automation initiatives encompass everything from the use of sensor technology to detect damages to leveraging artificial intelligence to predict and automate intake. Still, the vast majority – some 80% of policyholders and claimants – prefer to speak with a live representative today, generally at an insurer’s contact center. 

Historically, reporting a claim can take 30 minutes or longer, through a series of questions and an iterative conversation. Each carrier has had to create their own individual FNOL record.

RAPID X allows for the creation of a single, universal FNOL record shared by all parties involved in that claim. Data changes can only be made by the information owners, ensuring that things are accurately captured. A carrier can’t change the data on another carrier’s policy holder.

Industry savings from the use of RAPID X have been conservatively estimated to range between $60 million and $120 million annually, depending on the extent of industry adoption. In any  event, the opportunity is significant.

Industry Leaders Join Forces

The Institutes' RiskStream Collaborative is an unprecedented, industry-led consortium collaborating to unlock the potential of blockchain. It is the risk management and insurance industry’s first and largest enterprise-level blockchain consortium, which is developing insurance-specific use cases via Canopy, a custom blockchain architecture. RiskStream is a network-based, nonprofit organization affiliated with The Institutes, which provides professional development, research and educational services to the insurance industry. The Institutes' board includes senior executives of companies that write a significant percentage of the U.S. personal auto market. 

The RiskStream Collaborative offers insurance solutions for personal lines, commercial lines, reinsurance and life and annuities. Members (carriers, brokers or reinsurers) lead all areas of RiskStream’s governance and activity. For example, members work with RiskStream staff to design use cases on behalf of the industry and then work with RiskStream staff and service providers to develop and test the buildout of applications. The Collaborative aims to expand its network of members and connect insurance-oriented organizations in 2022 to create greater efficiencies and achieve growth opportunities through additional blockchain innovations.

See also: How IoT May Revolutionize Claims

How It Works

RAPID X is built on an underlying blockchain technology similar to that which powers Bitcoin and other cryptocurrencies to share, confirm and verify transactions without a centralized authority. The key distinction is that RiskStream’s platform is not public. Instead, it’s a private, permissioned platform called Canopy, which was designed by the industry through RiskStream Collaborative technology governance. The Canopy platform is SOC2-certified and meets industry ISO standards. It provides the ability to safely and securely share information, saving time and effort while maintaining individual control. 

Each company has a node on the private decentralized network, on which it can create, update, reconcile and share loss records. Simple liability determination and agreement can also be input and tracked. FNOL is just the beginning, with a number of other use cases up next; proof of insurance, claim verification, investigation, evaluation, settlement and total loss determination and salvage title processing, to name a few.

The Bigger Picture: Blockchain as Ecosystem Enabler

RAPID X is only the beginning. Integration among carriers and other claims ecosystem partners is the future of efficient claims processing and will significantly benefit all stakeholders, including claimants. 

The future vision and development road map for the Canopy blockchain platform leverages the technology and active carrier support to create a multi-party platform that will support the broader insurance industry ecosystem, including service providers and partners. Essentially, RiskStream is “laying the plumbing” for data exchanges between entities and facilitating network collaboration and coordination, as well. This is neither easy nor simple, but RiskStream CollaboratIve is uniquely qualified to accomplish such a feat both privately and securely.

To learn more, please reach out to RiskstreamCollaborative@theinstitutes.org.


Stephen Applebaum

Profile picture for user StephenApplebaum

Stephen Applebaum

Stephen Applebaum, managing partner, Insurance Solutions Group, is a subject matter expert and thought leader providing consulting, advisory, research and strategic M&A services to participants across the entire North American property/casualty insurance ecosystem.


Alan Demers

Profile picture for user AlanDemers

Alan Demers

Alan Demers is founder of InsurTech Consulting, with 30 years of P&C insurance claims experience, providing consultative services focused on innovating claims.