|


Discover 'The Future of Risk™': Innovation, Tech, & Disruption Insights from Industry Leaders!
ITL FOCUS is a monthly initiative featuring topics related to innovation in risk management and insurance.
This month, we're focusing on Workers Comp
|
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.
We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.
AI can let insurers spot fraudsters faster and more efficiently, while separating otherwise-well-meaning offenders from the the serious thieves.
Between 3% and 10% of total U.S. healthcare spending each year amounts to fraud, according to the National Healthcare Anti-Fraud Association. Facing potential multimillion-dollar losses, insurers invest significant resources into weeding out fraud and protecting their financial interests.
Conducting a healthcare fraud investigation is a laborious process that can take weeks at the minimum. Most of that time is spent sifting through information from multiple sources, piecing it together like a jigsaw puzzle to reveal a complete picture of the provider-member relationship. Only a small proportion is dedicated to actual decision-making.
But it doesn’t have to be that way.
Dynamic problems vs. manual solutions
Healthcare fraud is a dynamic problem, with fraudsters constantly changing their tactics to evade detection. Yet many insurers are tackling this growing issue using only manual tools – multiple databases, pivot tables and Excel spreadsheets – which are difficult to adapt to new scenarios.
Unsurprisingly, this approach leaves insurers constantly playing catch-up with fraudsters, as investigators spend days manually looking into cases. In the current environment, some fraud is missed by insurers, while false positives are too frequent. Plus, when an insurance investigator does spot something fishy, they often lack the data to validate their findings.
Evidence suggests that the pandemic and the rise of telehealth led to an increase in insurance fraud – as stringent telehealth rules were relaxed overnight, enabling providers to bill insurers for an enormous range of medical services provided virtually.
So – in this increasingly digitized healthcare landscape – it’s clear that insurers must modernize their back office to protect against healthcare fraud. That’s where artificial intelligence (AI) and machine learning (ML) tools come in. These technologies enable insurers to create dynamic solutions to a dynamic problem. Here’s how.
How AI Helps
AI enables insurers to optimize employee time. Rather than spending tens of days on research, caseworkers can rely on AI to analyze relevant, contextualized data and generate alerts accordingly. This both increases the efficiency of insurance investigators and improves customer experience.
Consider the telehealth example. Imagine you’re an investigator working with rudimentary manual tools like pivot tables and Excel spreadsheets. You might spend hours assessing providers’ telehealth billing data before finding one that seems to be filing a suspiciously high number of claims. Bingo – you've spotted a fraudster! Not so fast. After embarking on a lengthy investigation, you find that this "discrepancy" can be attributed to the way the provider in question is coding a certain category of services. False alarm.
Though the insurance investigator in this scenario acted completely reasonably, they inadvertently wasted significant resources chasing this dead-end lead. If this investigator had been equipped with AI-powered analytical tools, the same billing data could have been processed and interpreted in minutes – rather than hours. What’s more, AI would’ve produced significantly fewer false alarms, enabling the investigator to dedicate their time to following up on genuine leads – which means even more time saved.
AI’s second superpower is uncovering trends or patterns that simply aren’t easily recognized – thereby revealing hidden fraud.
Let’s take the example of prescribing controlled substances via telehealth consultations. Rules governing this practice were significantly relaxed during COVID-19. As a result, this area of prescribing has become a fraud hotspot. This has both financial implications for insurers and potential public health ramifications – for example, if fraudulently prescribed opioids were to be sold on the streets.
AI is great at uncovering fraudulent prescriptions issued via telehealth. It can quickly spot suspicious prescribing patterns by aggregating all relevant data – including relationship analytics between members and providers. Has there been a spike in prescribing? Have these members been issued this prescription before? If not, why now?
What’s more, AI can analyze huge quantities of publicly available data from the internet – forums, social media, Google reviews and more. For instance, if a physician was at a conference or on vacation during a particular week, how could they possibly have completed several dozen telehealth consultations each day?
See Also: Can AI Solve Health Insurance Fraud?
Striking the right balance
This isn’t about replacing special investigations units with AI. Instead, it’s about enabling employees and AI tools to work together symbiotically.
There’s no doubt that AI can analyze data in a fraction of the time it takes a human analyst – and with a much higher degree of accuracy. However, healthcare is – and will always be – a people business. Complex, life changing decisions made each day by insurers on the behalf of members and providers will always need human input.
Let’s take the example of "fraud" perpetrated by healthcare providers. This falls broadly into two categories. The first category is composed of otherwise-well-meaning providers who might sometimes round up appointment times by 10 or 15 minutes and receive a higher insurance payout. The second category is made up of serious fraudsters, who consciously and consistently set out to defraud insurers.
With AI and human employees working in tandem, insurers can easily uncover both groups. But they can also retain the freedom to handle the issue with compassion – punishing genuine fraudsters, while educating providers who’ve committed minor abuse.
That’s why – without a hint of irony – it seems obvious that AI is exactly what’s needed to bring humanity back into healthcare fraud investigations.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Ricky Sluder is head of healthcare value engineering, North America, at Shift Technology.
He has more than 25 years of experience producing results in high-demand environments. From his days as a special criminal investigator and hostage negotiator, to his work at Shift Technology, Sluder has successfully led many teams with as many as 100 direct reports and has produced more than $600 million in consultative enterprise software sales in 35 states and seven countries.
Insurance must get beyond the hype of the "I" in AI and become more pragmatic in its use of AI/ML technologies for generating business insights.
After almost 15 years of increasingly effective technological developments in the AI/ML arena, we are at a point where the algorithms and the trained models are well-known and the overall architecture of neural nets is well-understood. However, the quest for reasonable ROI from AI/ML projects continues, with data issues impeding wider adoption.
The current and still evolving technologies coined loosely under the term data-centric AI could help many industries tackle issues with data and make help make meaningful progress in reaping benefits of AI/ML sooner than later.
Insurance as an industry should take the lead in adopting data-centric AI technologies in providing better customer experience to the insureds.
Issues with data
Many of the following have been well-documented and are issues for which solutions have been emerging for some time:
Adhering to aspects of data like sovereignty with all the current and emerging regulations requires insurers to essentially train AI/ML models in country or in some cases in the region where the models will be used to predict business insights. Because data is indicative in the context of regional and local market dynamics, AI/ML models should be trained locally for avoiding bias and making them explainable in the local context.
Another issue is that the pandemic caused major disruptions to business data, essentially weakening the efficacy of pre-trained models. This led many insurers to spend time and effort in re-training deployed models, as many of them built bespoke models in-house.
See Also: The Data Journey Into the New Normal
What Is Data-Centric AI?
It is loosely defined as AI/ML that depends on data that is engineered to a) account for domain-specific nuances while also factoring in the regional/local context, b) handle regulatory aspects like the appropriate amount of anonymization, c) remove bias from data that is used for training, d) depend on smaller but relevant data sets when large data sets are not available and e) potentially use synthetic data that is generated by tools that try to maintain statistical similarity to real data.
This engineering of data goes beyond the traditional sourcing, cleaning and basic, algorithm-related tuning that happens today. Increasingly, tools to help visualize and engineer data are appearing in the market.
The data-centric AI and related tools are aimed at enabling business domain experts who can manage AI/ML initiatives without the need for a large team of data scientists and IT experts.
What should the insurance industry do?
The insurance industry should look at data-centric advances in AI/ML and take the opportunity to lead in providing a better experience for insureds. Here are some suggestions for insurers as they embark on and in some cases re-look at their current AI/ML initiatives:
In this context, Insurers should start looking at engineering the small but relevant data sets that are easily available and can help improve accuracy of the models.
Conclusion
It is imperative that insurance as an industry gets beyond the hype of the "I" in AI and becomes more pragmatic in their use of AI/ML technologies for generating business insights. The recent evolution of AutoML technologies helped shift the required skills to the left and reduced dependency on data scientists and IT teams. However, many of the issues with data necessitate the rethinking of the use of AI/ML in a data-centric way, helping business domain experts to engineer data and address many of the macro-issues and in the process, improve efficacy of trained models and keep them relevant in their continued use over a period of time.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Chak Kolli is the global chief technology officer for insurance at DXC Technology.
Kolli is responsible for DXC’s global insurance software product and services strategy and vision. He is also responsible for working with DXC’s insurance software clients as they use new and emerging technologies to transform their business.
Prior to DXC Technology, Kolli led large global initiatives as a senior leader at TCS and AIG.
He has a Ph.D. in computer science from George Washington University.
Integrating a new feature, for example to provide dynamic quoting and pricing, usually takes months. Hyperautomation, such as low-code, provides robust solutions faster.
The insurance industry is exploring ways to adopt technologies to minimize risks, provide personalized solutions, reduce costs and ensure compliance. Leveraging hyperautomation solutions is a game-changer.
With heightened customer expectations, hyperautomation technologies such as low code play a crucial role in delivering the speed and flexibility to resolve diverse customer requirements and provide personalized solutions. Because the technologies can seamlessly integrate legacy systems, they offer solutions at a nominal investment compared with traditional infrastructural upgrades that deliver similar results.
Furthermore, hyperautomation technologies allow various departments to work together to improve processing speed and efficiency. Process improvements and changes can be implemented faster than ever, leading to higher flexibility and enhancing customer experience.
High Levels of Accuracy
Automation in insurance and risk management allows multiple processes to be carried out simultaneously without risking errors while making processes, including onboarding, claims and verifications, error-free and fast-paced. Delivering solutions at speed while being accurate is crucial to elevating the customer experience and reducing operational costs.
Introducing software robots to take over mundane and repetitive tasks enables the department to remain functional around the clock without increasing the workforce. Workflows for intelligent case routing can assign claims to the proper personnel easier. At the same time, carriers can bring efficiency into critical areas, such as document checking and compliance. The system can pull scattered and disparate datasets and store claims into one central repository. Thus, the system enhances reporting and expands access to critical information at the right time for verification.
Further, upgrading the digital workforce could seamlessly implement changes in processes. By harnessing the power of core automation, carriers can reduce fraud losses and cut operating costs while improving underwriting accuracy.
To deliver a connected experience throughout the insurance life cycle, it’s critical to enable teams to work together efficiently and make informed, data-driven decisions while remaining connected with clients. Because of disparate technology and lack of automated workflows, insurers face several preventable issues like gaps in transparency, manual process and poor customer experience.
Hyperautomation brings together multiple technologies and their capabilities, including Robotic Process Automation (RPA), Artificial Intelligence (AI), API Integration, Machine Learning (ML), intelligent business management software (iBPMS) and Process Mining to augment and automate processes in ways more important than traditional automation.
Without hyperautomation, core policy and underwriting systems often require manual, repetitive tasks and result in a lengthy quote-to-bind process. This can hinder growth and result in customer dissatisfaction. With legacy systems, the underwriting process is time-consuming and at risk of human error due to its manual nature, resulting in inefficiencies and more liability.
By bringing data together, integrating systems and automating workflows, you improve connectivity with unified claims, underwriting and agent-customer experience. Your staff has the technology they need to do their jobs more effectively and efficiently, empowering them to deliver the digital, connected and mobile insurance experience that today’s customers expect.
See Also: Insurers Turn to Automation
Seamless Adaptability
Fully optimized claims triage, straight-through processing and fraud management are the hallmarks of process automation. As the insurance industry launches business products and services rapidly, low-code platforms allow businesses to capitalize on the opportunity by empowering people with no previous software experience to build enterprise-grade applications effortlessly. Integrating a new feature, for example, to provide dynamic quoting and pricing usually takes months. Low-code provides feature-rich, pre-built templates and drag-and-drop elements so users can build robust applications and solutions faster.
Enhancing Customer Experience
The fast-growing insurance industry gives rise to ever-increasing amounts of data, and insurers face a considerable challenge in collecting and handling customer data. With automation and advanced data analysis technologies, businesses don't have to spend months on data preparation and model selection. Automation extracts, cleans and processes volumes of data—policy, claims, records—and provides meaningful information.
Whereas legacy processing is fragmented, automation unifies data processing and provides 360-degree customer insights for effective decision-making. Automation empowers carriers to offer more targeted and personalized products. Automated insurance processing provides companies with better contextualization that allows for meeting individual customer needs, which is not possible with an outdated, one-size-fits-all model.
Customers can enjoy dynamic pricing and omnichannel customer experience. Ultimately, it all comes down to customer experience, and automation delivers the promise.
In the highly competitive insurance market, where the importance of convenience and efficiency is increasing, automation facilitates holistic, seamless claims processing. From noticing the loss to final claims settlement, automation platforms make the process easier for everyone. It can deploy rich solutions for claims and renewals triage, risk management, fraud identification and auto-retrieval of policy information. When automation is embedded in the process, instant claims reporting is possible through responsive solutions.
By automating the insurance landscape, carriers can remove high costs across the value chain, striking a balance between retaining customers and maintaining profitability. Embedding automation capabilities can reduce margins and help insurers reinvent their entire business with significant cost savings.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Ravichandran Thiruganasambandham is the director of services at Vuram.
He has over 10 years of experience automating various organizations' business processes. With the help of hyperautomation technologies, he has designed over 100 business processes with on-time delivery.
In numerous cases, such as the tsunami in Sri Lanka, even a bit of warning could have saved lives and protected assets. Texting should be a key tool.
The clouds shifted rapidly as I drove back home after helping my colleagues set up for the Future of Insurance conference in Chicago recently. The sky looked ominous, but I kept on jamming out to XM radio. I thought we'd just have a normal thunderstorm, until I saw an electronic billboard on I-90/94 reading, “Tornado warning in effect, tune into local radio immediately for more information.”
It was hard not to panic. Has the tornado landed near me? Is my family okay? Is there damage to my home? Who else might be injured?
Luckily, I made it home, and everyone I knew and loved was safe. Ultimately, the tornado never appeared, but there was some wind and storm damage sprinkled throughout the city.
The next day, I thought about the lack of clear and accurate communication regarding the storm. And, given that nothing happened, I would probably believe the next warning a little less if I wasn’t in the industry. I also found it odd that I was in a vulnerable state and my insurance carrier had not communicated with me at all.
According to a 2019 paper by Khaled & Mcheick, more than 3,800 natural disasters have affected more than 2 billion people in the past decade, resulting in 780,000-plus deaths and at least $960 billion in damages. The frequency and severity of these natural disasters will continue to increase because of climate change, and insurers have been enlisted as one of the first responders on that chilling front to deal with the aftermath of these devastating events. We must do more, not only for our financial viability as an industry, but also to deliver on our promise to policyholders to protect what they value most.
Warning People Before an Event
We have seen numerous cases, such as the tsunami in Sri Lanka, Hurricane Maria in Puerto Rico and wildfires in the Western U.S., where warning in the days, hours or even minutes beforehand could have saved lives and protected assets. Carriers have invested in advanced weather monitoring services, improved coordination with national agencies to understand the potential trajectory of storms, more efficient identification of affected policyholders and more flexible readiness plans to deploy CAT-related claims employees and third party administrators. But they still rely on antiquated communications channels with numerous friction points, such as sending emails that have low open rates or routing policyholders to glitchy websites to obtain needed information.
Instead, carriers could leverage texting to connect with policyholders faster. Texting is accessible, personal and ubiquitous. Reports show that 97% of adults text daily, and 99% of texts are opened. We also found this to be true for policyholder interactions with insurance carriers. In our study about insureds and texting, we found that 84% of policyholders would save a carrier’s texting number to their contacts and text them about a service or a claim, if offered that option.
Carriers could also offer dedicated short codes (e.g., text “STORM” to 999-999 to receive hurricane-related updates) for policyholders to opt into and save to their contacts during the bind process. Policyholders could automatically receive timely information about catastrophic events if carriers integrate the service into their CRMs and weather monitoring services. The texts could also direct the policyholder to local weather sites for safety information or the carrier’s website for preparedness instructions for loss mitigation and prevention.
Helping People During an Event
Texting is also a highly effective communication tool during an event. According to Khaled & Mcheick, there are many benefits of SMS. It:
Texting also offers a critical way to get information from disaster response agencies at the state and federal levels (e.g., FEMA) to policyholders during an event. Carriers can amplify communication and relay these agencies’ messages to policyholders and provide GPS pins for shelters to get people to safe locations. And carriers can enable these one-way notifications to be two-way communication channels so that they can collect preliminary information on the extent of damages and capacity plan for the post-event claims.
See Also: The Best Tools for Disaster Preparation
Assisting with Post-Event Claims
After an event, speed is critical for dealing with a high volume of claims and reducing fraud. Carriers can deploy texting solutions to capture first notice of loss (FNOLs). The texts can route policyholders to eFNOL channels and also take short-form FNOLs for high-frequency, low-severity claims that are likely to be paid out quickly. Also, texts can prompt policyholders to collect critical data, such as images or videos that can feed the claims model for triaging and payment.
If a policyholder needs to mitigate any damages, carriers can coordinate third parties and the policyholder via group texting. Or, if carriers need to get policyholders to hotels, pay-by-text can provide the first payment. Additionally, when an adjuster is assigned to adjudicate that claim, they can schedule an initial phone call via text instead of leaving endless voicemails and playing phone tag, which is critical for productivity given the large load.
The current catastrophe communication process is not good enough, given what we will likely face in the coming decade. Carriers need to offer a more empathic, simple and convenient communication channel. By transforming and modernizing this process, not only will we protect our financial strength but also what our policyholders love.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Ujjval Patel is the director of consulting and solutions at Hi Marley, the insurance industry’s first intelligent, conversation-driven service platform.
Prior to joining Hi Marley, Patel was site leader and data engineering leader for Synchrony’s emerging technology center. He served as the head of membership and strategy for ACORD and led the business analysis unit at Marsh. Patel started his career with State Farm as a strategic resources analyst, working for the internal consulting team.
Patel graduated from the University of Illinois Urbana-Champaign with a bachelor of science in management science and a minor in T&M and went on to earn his as MBA from Yale.
High-res data sees more than a shipment of glass: It sees a load of Gorilla Glass on clear summer roads or of crystal chandeliers on a pockmarked highway in a winter storm.
High-resolution data is rapidly changing the cargo insurance paradigm—and it’s about time.
While brokers thoughtfully deliver individualized care to each client, the limitations of traditional insurance mean they’re still selling them the same set of insurance products.
With high-res data, however, they are empowered to dynamically create tailor-made products that address the unique needs of each client—all while minimizing pricing fluctuations and delivering stable costs to balance sheets.
In short, the way they do business is changing for the better.
Traditional underwriters are flying blind
Think traditional insurance leverages historical data to underwrite risks? Think again.
For hundreds of years, our industry has operated on the data it can acquire from a few sheets of paper and historical claims data. That’s about as low-resolution as it gets—an unsettling thought when you consider underwriters often quote out coverage with million-dollar price tags. Intuition and personal experience have long influenced pricing, as well.
This approach is ripe for error.
Past performance is not a good indicator of future performance, and human intuition is fallible — experience varies wildly from underwriter to underwriter, after all. Let’s also not forget that underwriters are human; they can and will make mistakes. Perhaps the data they’ve gathered is incorrect or incomplete. Maybe the events of the previous year, such as catastrophic storms or pandemic-driven supply chain disruptions, don’t reflect today’s environment.
With so many unknowns, it’s understandable that underwriters must price insurance conservatively—they have to ensure the sustainability of their business.
In the end, this approach has contributed to the wild peaks and troughs we often see in conventional insurance pricing—extreme swings that leave clients frustrated and price some out of coverage altogether.
See Also: Shipping Industry Safety Keeps Improving
High-resolution data paints a more accurate picture of freight industry risks
While the insurance industry has been slow to digitalize, the freight industry has long embraced big data approaches to optimizing routes, reducing losses and improving driver safety. As a result, the industry is awash in data.
Leveraging embedded insurance to gain visibility into this data, an AI learning engine like Loadsure’s is generating more accurate, sustainable pricing with a more holistic view of the risks. Where traditional insurance priced policies against the quantities and types of shipments and losses in the previous year, it’s so much more useful when premiums are also informed by the shipment-level details of those loads, like routes, reefer temperatures and G-loads on cargo—all while simultaneously synthesizing the claims history to understand the correlations where losses occurred.
This is only the beginning.
Soon, location, weather and national crime database integrations will feed data into our AI learning engine, as well. This data may be meaningless when pricing traditional, annualized policies, but with transactional coverage it becomes both valuable and actionable. Automation and AI allow dynamic pricing models to be refreshed with new shipment and environmental data as often as need be. We can then bring together historical and real-time data and adjust on the fly. By catering to specific instances, brokers are empowered to deliver every customer a bespoke product.
Where traditional insurance could only see a shipment of glass, for example, high-res data can enable one tailored rate for a summer shipment of Gorilla Glass when roads are clear—and another for crystal chandeliers traveling a pockmarked highway during a winter storm.
Pricing granular risk? That’s just the tip of the iceberg.
What’s particularly exciting is that high-res data will also enable active risk management. Delivering actionable reports and real-time alerts, freight SMBs that lack the benefit of in-house risk management teams will get the crucial insights they need to suppress losses. If a police report indicates a high incidence of cargo theft at a truck stop, for example, an automated alert can instruct the driver to bypass that location in favor of a stop that’s less likely to pose a threat.
In time, this actionable information will become even more important than the paper itself—and clients will increasingly come to see brokers as active partners in their risk mitigation.
High-res data is the key to opening up new levels of service to brokers’ customers and delivering products as bespoke as the relationships they have already developed.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Damith Chandrasekara is CTO at Loadsure.
Prior to joining Loadsure, Chandrasekara served as 30dB CTO. He designed and built a highly scalable social sentiment engine that delivered real-time insight into both public opinion and what drives it.
At IAC Applications, Chandrasekara grew from senior engineer to technology executive, with responsibilities that spanned technology strategy and architecture; business plan development; management; reorganization; and funding of teams across business units. As IAC Applications' vice president of data, Chandrasekara took on broad responsibility for everything from shared data and information strategy to the website, search engine and its underlying technologies.
The Great Resignation is walloping insurance--65% of those who resigned from a job in the past two years left the industry entirely.

We've all heard about the Great Resignation that has accompanied the pandemic, as people have reevaluated their priorities and, in millions of cases, decided that their current job doesn't make the cut. Many have quit and moved to a different company or even to a different industry, and many have stepped out of the work force altogether.
It seems that insurance has it worse than just about any other industry. A study by McKinsey finds that 65% of those who resigned from a job in insurance or finance between April 2020 and April 2022 left the industry entirely. That percentage is exceeded only by the 76% in consumer/retail, which has always had a problem retaining people, and the 72% in government/social sector. And the departures from insurance come as the industry is starting to experience a long-anticipated sort of Great Retirement, as an awful lot of talent is aging out of the work force.
What to do?
The McKinsey report warns that "there simply aren’t enough traditional employees to fill all the openings. Even when employers successfully woo these workers from rivals, they are just reshuffling talent and contributing to wage escalation while failing to solve the underlying structural imbalance. To close the gap, employers should try to win back nontraditional workers."
To do so, the report argues, employers need to understand different personas and craft appeals to each.
For instance, the persona that McKinsey labels the "do-it-yourselfer" values autonomy above all else and could be attracted by modularized work that can be done independently and measured by output rather than based on time spent.
The "caregivers" -- which strike me as a particularly rich opportunity -- are what I've seen described as the "sandwich" age group. They're caught in between caring for kids and caring for their parents. They respond to offers of compensation much as traditional employees do but have a whole, complicated set of needs for flexibility. If they can be accommodated, they bring a rich set of skills.
The "idealists," who are students and younger part-timers, have often avoided insurance because they don't find it exciting but, it seems to me, could be attracted much more readily if insurance does a better job of describing its "noble purpose."
The "relaxers" also seem to me to be a rich vein for the insurance industry to tap. A lot of the calculations about the talent drain facing the insurance industry are based on the traditional notion that people retire at age 65. But 65 is no longer such a cut-and-dried number, especially with work-from-home becoming widespread. Sure, people may no longer want to saddle up and head to the office for 40 or more hours a week, but maybe they'd work 20 or 25 on some sort of flexible basis at home, to contribute on projects they find meaningful, to keep their brains engaged and to stay in touch with their friends, while still allowing time for more travel, golf or something else. Some sort of continuation of health benefits could be a powerful sweetener -- and there's an awful lot of institutional knowledge that could be kept from walking out the door.
"Vitally, companies can no longer assume that they can fill empty slots with workers similar to the ones who just left," the report says. Insurers wanting to address the talent problem will need to not only look in nontraditional areas but must be willing to craft more personalized value propositions for employees.
Employers can also help themselves a lot by stopping some behaviors that cause that talent gap to develop in the first place. In particular, McKinsey says, "It cannot be overstated just how influential a bad boss can be in causing people to leave,... along with a lack of career development."
The report provides a full description in the figure below that shows which factors, according to the firm's research, are most likely to drive people away, as well as which factors attract people.
Albert Einstein famously said, "We can't solve problems by using the same kind of thinking we used when we created them." If we're to get out of the talent crisis that is unfolding around us, it's time for some bold, new thinking.
Cheers,
Paul
Mark Walls, vice president, client engagement, at Safety National and long my go-to person on workers' comp, says the industry faces a major issue with staffing -- actually, two major issues.
 |
Mark Walls, vice president, client engagement, at Safety National and long my go-to person on workers' comp, says the industry faces a major issue with staffing -- actually, two major issues. First, clients are having trouble filling positions, so they're having to ask more of current employees and hire and onboard new employees faster, even if the pre-employment physical would ordinarily raise questions. As a result, carriers are likely to see an uptick in claims. Second, carriers and third-party administrators are having their own staffing issues. Amid the Great Resignation, it's hard for them to find enough adjusters, nurse care managers, etc. Even if the companies can find enough, they're having to pay so much more that the economics of many long-term, fixed-price contracts no longer work for TPAs. There's no simple answer, but Mark, as always, has some smart guidance. |
What would you say the biggest issue is that people are wrestling with in the workers’ comp world these days?
The biggest issue is staffing.
So many businesses are challenged with staffing. They're trying to do more with less. So, people are working longer hours and having to do more while they're working. Employers trying to fill shifts are often compromising on the physical requirements of the job – waiving pre-employment physicals or taking candidates who are borderline on those physicals. You're rushing to get people on the job, so training isn’t always what it should be.
Add all of that together, and there's a significant concern that there's going to be an uptick in claim frequency. Some statistics are already starting to show that uptick.
Staffing is also affecting the workers’ comp industry. There's a shortage of adjusters and nurse case managers, as well as physicians, nurses and others who treat people. There's a shortage of risk-control professionals.
So you've got potentially an increase in claims and not as many people handling claims. That is a big problem.
People have positions they haven't been able to fill for months and months. That is a particular challenge for third-party administrators, which are on multi-year contracts that guarantee a certain level of staffing for a certain price. Even if they can find people to staff the work, they’re costing so much that meeting those contractual obligations is darn near impossible.
There have been all sorts of fits and starts as businesses have brought some workers back to the office. How is that playing out in the world of workers’ comp?
Most TPAs and carriers are not bringing people back to the office full-time. They’re finding they can't attract and keep talented people if they're not willing to allow some degree of work from home. You're even seeing that among state regulators. Ultimately, that's going to mean a lesser footprint in offices.
Work at home is also presenting some challenges. There are three or four states that have definitive cases on what constitutes a compensable claim for someone injured at home, but most don't.
Some states are positional risk: If you're at work and you get hurt, it's workers’ comp. In other states, the risk has to be inherent to the job. In a positional risk state, if I'm in the office, bend over and pick up a piece of paper and hurt my back, that's a claim. In a state that requires the risk to be inherent to the employment, I have to be lifting a box or something like that.
Throw this into a home-based environment, and you run into several issues. What constitutes being at work when you're at home? If you trip over your dog, is that a work comp injury? The answer is: It depends.
It’s important to define what the workspace is. You can't just say you can work wherever you want, because that basically opens you up to having people be considered at work when they do anything anywhere. The best practice is to have your employees have a designated workstation and send you a picture. Your risk-control people can review that workspace from an ergonomic standpoint. Having the picture also puts parameters around what is the workspace. You're not considered at work if you’re at the table in your backyard.
One of the interesting twists is that people are now working from different states than they did before. This is especially a problem for people who are self-insured, because self-insurance certificates are state-specific. If you're in California, and all your employees were in California before but now you're allowing them to work from home, some of your employees are now in Nevada or Montana or wherever. Well, your self-insurance certificate doesn't cover those people. That's something that a lot of people just didn't think about.
The one positive is that what’s being affected here are office jobs, which are lower-risk. Work in construction, restaurants, retail and so on, the higher-risk jobs, those really haven't changed.
A point I’ve made repeatedly since getting involved with the insurance industry nine years ago is that the industry can and should move toward preventing losses, rather than just indemnifying clients after something has happened. How far along is workers’ comp in that transition?
The workers’ comp industry has had a huge focus on loss prevention for many, many years. I mean, that's why the trend in workers’ comp has been a steady decline of frequency of claims going back 20 or 30 years. I expect that to continue in the long term.
A lot of work is being done on wearables, which can reduce workplace injury. And one of the solutions to the staffing shortage is more automation. You're starting to see that, from things as simple as ordering kiosks in restaurants to more complex work in a warehouse or manufacturing environment.
But, as I said earlier, in the short term there could be some uptick in claims.
How about triaging, to make sure bigger problems are identified up front and to get injured workers to the right treatment right away?
Having some type of telephonic nurse triage has already been a best practice, to evaluate whether maybe they should just go home and take some ibuprofen and rest for a day, or whether they need to get to a clinic tomorrow or whether they need to go to the emergency room tonight? Those programs have been very successful.
How about social inflation? That’s been a huge issue in many lines of insurance; how about in workers’ comp?
Because workers’ comp is a no-fault system, it’s somewhat insulated from social inflation. The impact is in the continued blurring of the lines between what is workers’ comp and what is not occupational.
The pandemic is the perfect example. Here is a disease that affected billions of people all over the world, yet certain states said, if you work in these occupations, it is presumed that you got this disease in the workplace. That, to me, is an example of just trying to push things into workers’ comp that weren't there before.
You see states increasing compensability around gradual onset injuries, which are part of the normal aging process. There is also the continued expansion of presumptions for first responders, especially for cancers. Again, an ordinary disease of life is being pushed into the workers’ compensation space, where the science is fuzzy on whether the workplace creates a greater risk.
Is there anything else that's top of mind that I didn't ask about?
Workers’ comp has been fairly stable for a number of years. But you can see that costs are ticking up. If we're not already at the end of the soft market cycle, it's right around the corner. Combined ratios had gotten down to 85%, but now they're back up around 100% and are projected to go higher. Something has to give, right?
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.
We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.
How can insurers make themselves more valuable to SMBs that need them more than ever in a rapidly changing risk environment?
A family-owned printing and mailing house is suffering through some daunting challenges. Paper is in short supply. Supply chains have been inconsistent since the start of the pandemic. When the paper is available, the company doesn't have enough people to work at capacity on their folding, binding and packing equipment. They can’t afford to give new employees the common period of supervised training. Most of the equipment is dangerous. They are now at a higher risk for expensive production errors and costly injuries.
Safety is a growing casualty of the current economy and labor shortages. In the next 10 years, 22% of skilled manufacturing personnel will retire. Healthcare workers are already in short supply. There are too few truck drivers, airline pilots, teachers and food service and hospitality workers. The more unstable the talent pool, the less employers can count on adequate staffing and training.
Insurance technology companies like Majesco are currently helping insurers assess, underwrite and manage the growing array of new risks. How can insurers make themselves more valuable to SMBs that need them more than ever in a rapidly changing risk environment?
Understanding the realm of insurance opportunity in the SMB market
In Majesco’s recently released 2022 SMB report, A Rapidly Changing SMB Landscape: Growth Opportunities Grounded in Grit and Resilience, we see a number of areas where SMB insurance buyers are rethinking the role of insurance. Many business owners are just now waking up to the importance and value of insurance. SMBs have been affected by COVID and the economy, supply issues and talent shortages, as well as increasing environmental, societal and technology risks. Many have been pushed into changing their own business models to adapt to a changing market, and, as such, their risk has likely changed.
Business operation is only one area of SMB change. Change isn’t just about running a business; it’s about the experiences businesses encounter as buyers. Majesco found that SMB buyer sentiment is in the midst of rapid change. Business owners and decision makers are shifting from a generation with “traditional” purchase sensibilities to a generation where convenience, ease and digital process are just as important … very similar to what we found in our consumer research.
Product and business needs and channel preferences and value-added services share a blended focus, so it is crucial that insurers consider all of them as they attempt to innovate.
See also: What SMBs Want in Group Insurance
Motivated to move
Insurers that think SMBs are a one-size-fits-all commodity market will struggle to grow, let alone retain their customers. While risks are often classified into various categories, businesses are unique based on their business model, growth plans, products and services, technology, climate, society and other forces of change.
The pandemic raised the importance of insurance in the minds of business owners, as reflected in Figure 1. This offers a unique opportunity to tap into this mindset and offer insurance solutions that will meet their changing needs and expectations. Simply offering the same is not enough.
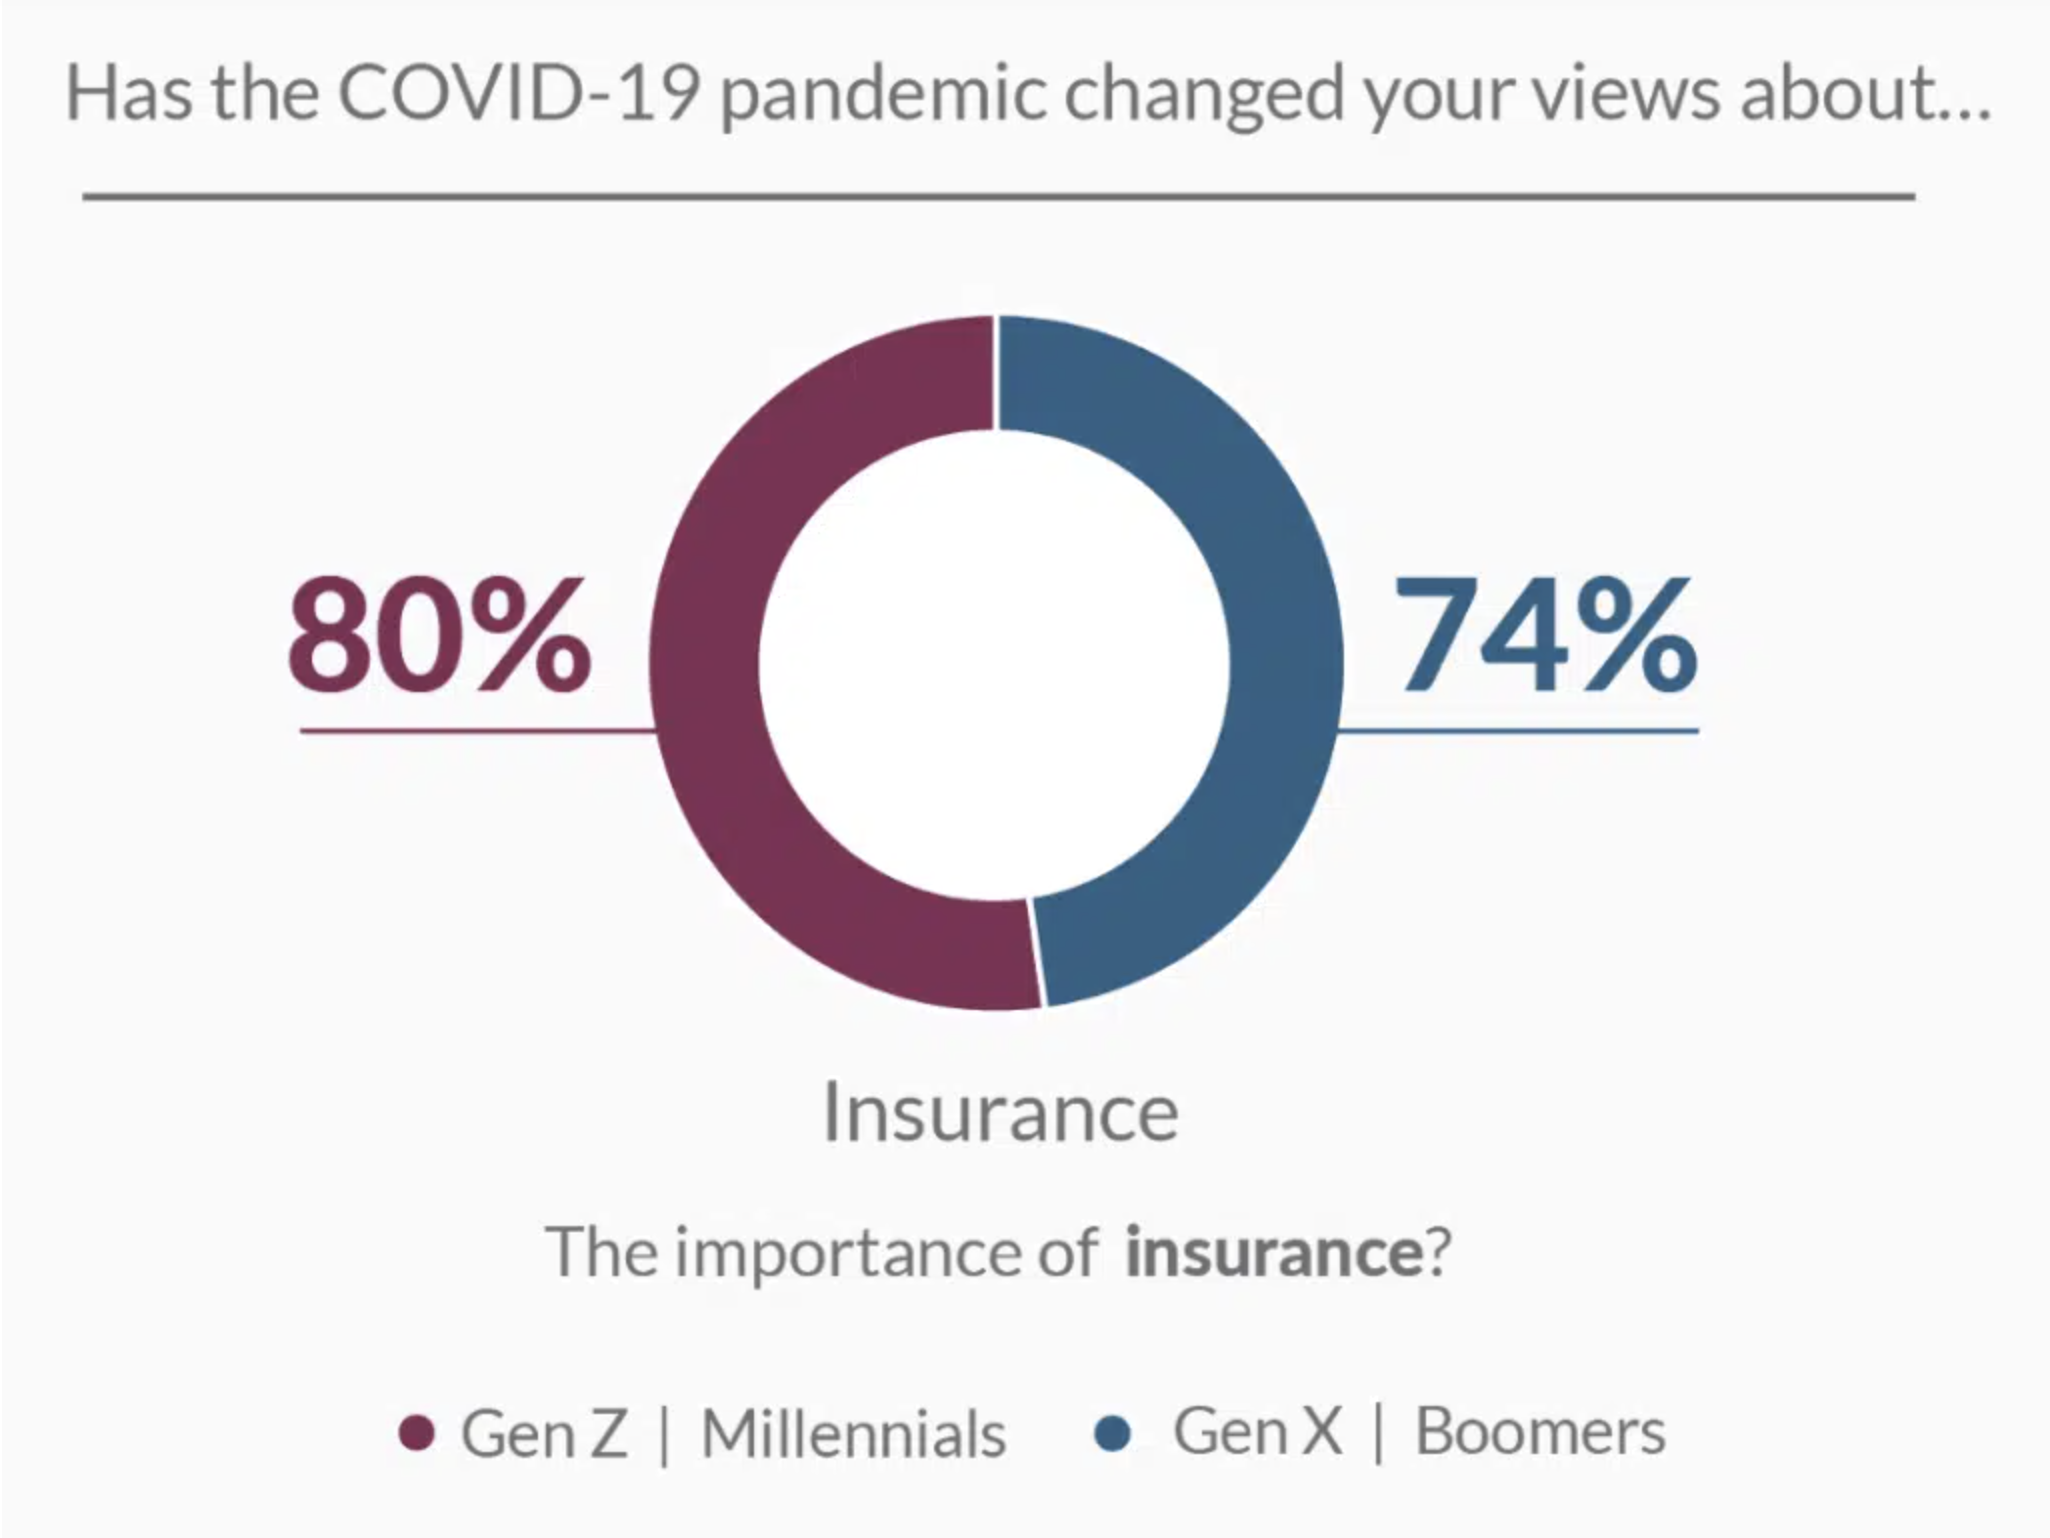
Figure 1: COVID's impact on the importance of insurance
Insurers must vary commercial insurance channels for purchase and engagement
Majesco research assessed the channel, products and value-added services desired and expected by SMBs. Insurers can use this information to test and develop products and services that will best support SMBs with their existing business.
Commercial P&C represents about half of all P&C premium in the U.S. market. BOP, commercial auto, general liability, property, cyber and workers' compensation are key products for SMBs depending on their specific business model. SMBs need new or different combinations of coverages based on changes in their business models due to the pandemic. Insurers now have the opportunity to re-engage with them through expanding distribution channels or by developing new solutions to meet their new risk needs. From offering new products and services to using new distribution channels, to moving to a digitally enabled business, SMBs’ risk profiles have likely dramatically changed during the last two years, requiring a new look at their business risk and insurance needs. Just renewing current coverages is not sufficient to meet their needs.
Today’s insurance purchase process is still difficult. It lacks transparency. It can be complex and often time-consuming. In contrast, many insurance technology companies and insurer innovations are refocusing to a “buying” over “selling” approach – through a multi-channel strategy that meets customers where and when they want to buy.
Commercial Auto Purchase Channels
Traditional channels, including an insurer website/app and agents, continue as the overwhelmingly preferred channels for purchasing Commercial Auto for both generational segments. (See Figure 2) However, there are differences by generation for other traditional purchase channels, including car dealership, car rental agency or other partnership organizations. The younger generations prefer a broader array of channels by 25%.
This trend continues for the “new” channels and significantly widens for the “high tech” channels. With the exception of including insurance with a purchase/lease and through an auto repair shop, the generational differences are 26% - 43% across all other options, including banks, retailers, legal services, tax services and vehicle manufacturer or shopping sites. For “high tech” purchase channels, the gap is massive, at up to 51%.
Consistently, the Gen Z and Millennial segment is broadly open to an expanding array of channels. These trends point to key generational differences. The younger generational groups:
Insurers need to grow their channel and partnership options with other entities to meet customers where and when they want to purchase insurance. Using only traditional agent/insurer website channels no longer works. It will look like an increasingly outdated strategy as Millennial and Gen Z buyers rapidly become the dominant owners and decision-makers. Even more importantly, the lack of establishing partnerships now will keep insurers out of the game and limit their market reach as partnerships become established by other competitors.
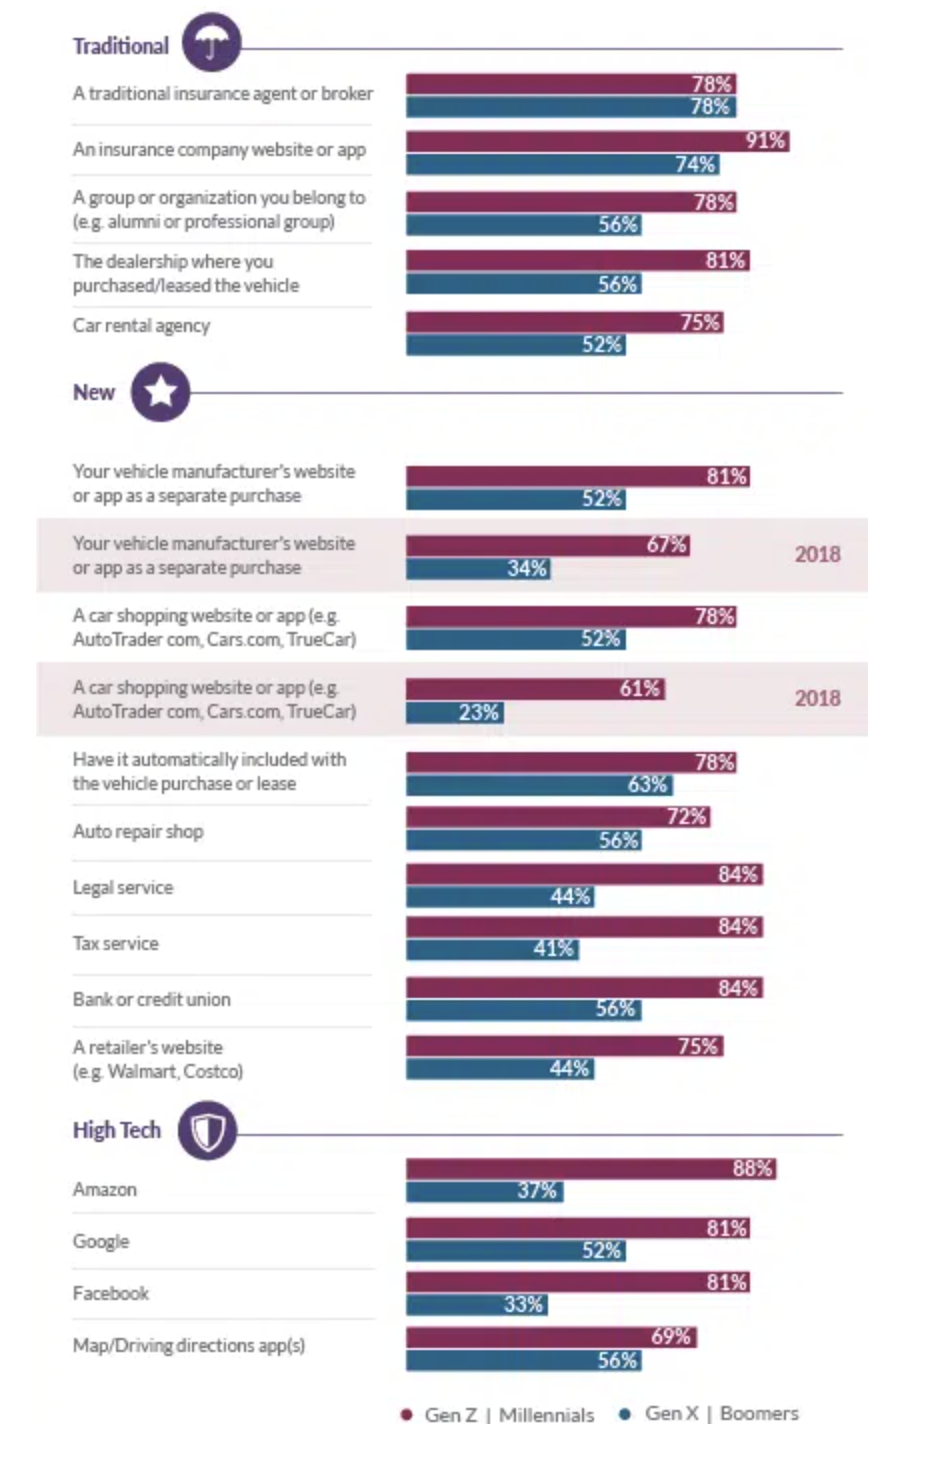
Figure 2: Interest in commercial auto purchase channels
Commercial Auto Engagement Channels
Both generational segments have similar interest in a wide range of commercial auto pricing and claims options, but gaps in the interest for some categories climb to 27% (see Figure 3).
Variable pricing continues to gain strong interest across a number of different options. The strongest interest was adjusting price and coverage based on whether the car is being driven or parked. The great majority (94%) of the younger generation is interested in this approach. The older generation also has a great deal of interest (67%). Both generations express interest in adjusting their pricing based on personal versus business use. Both generations show a remarkable increase in interest in rates based on miles driven, and in rates based on driving behavior, compared to Majesco research from 2018.
For claims, both generational groups reflect very strong interest across all the digital app-assisted claims processes, from 70% - 91%. The nuanced difference for Gen X / Boomers reflects a desire for a process where they are in control. In contrast, the younger generation is very interested in parametric or automated claims processes which once again tie to their desire for digital, real-time convenience.
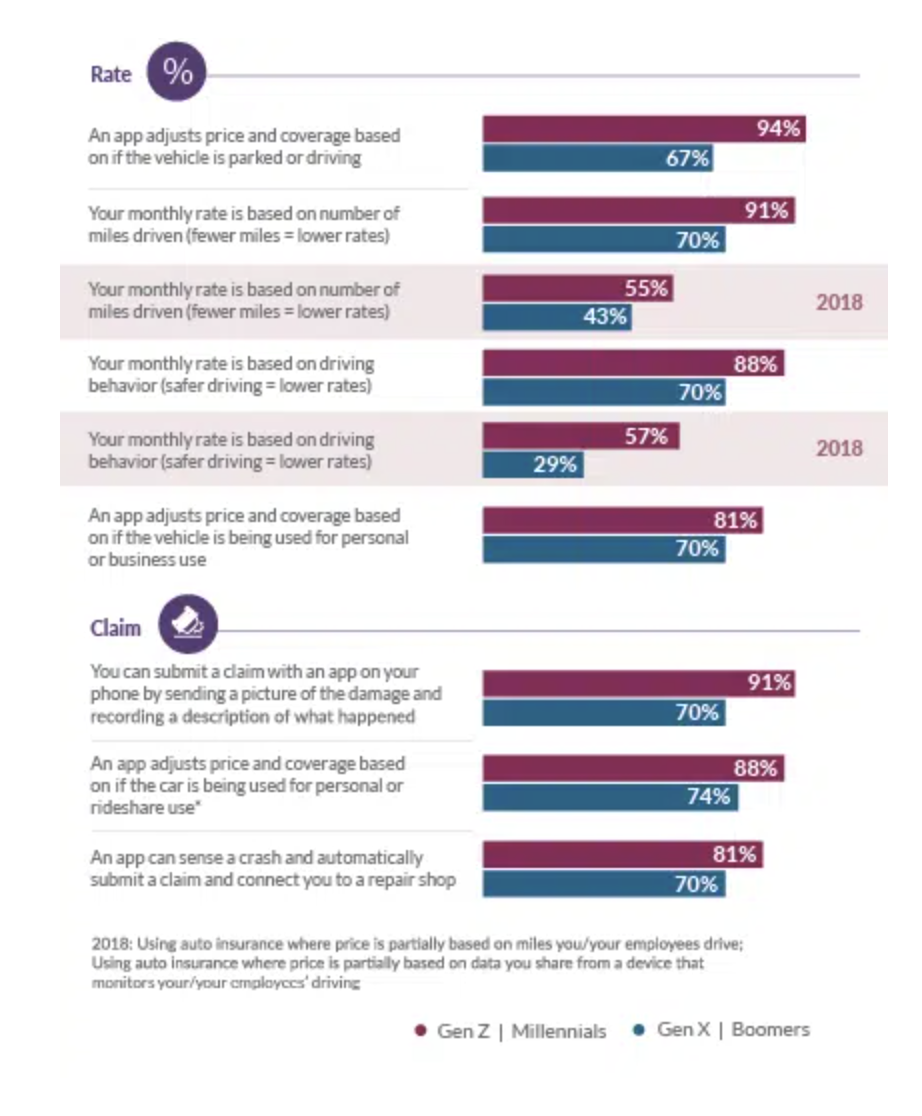
Figure 3: Interest in ways to use/activate and determine the cost of commercial auto insurance
Once again, this shows how insurance technology companies play a role in insurance marketing. Insurers who are not rapidly advancing in new pricing, management and engagement capabilities will fall well behind others who are leading the industry and capturing the growing demand and market share.
See also: How to Engage Better on Auto Insurance
Commercial Auto Value-Added Services
Value-added services represent “low hanging fruit” that can strengthen the value proposition and loyalty of customers. They are increasingly valuable to enhancing SMB stability and ease within business. (See Figure 4.)
Both generational segments are keenly interested in services that provide real-time information on driving/safety, maintenance, and paperwork related to their vehicles (59%-97%). This is an effective method for managing the safety of an employee pool with high turnover. Interestingly, the market value notification service showed strong increases over 2018 for both generational segments (19% for the younger and 17% for the older). Given the increased costs for both new and used vehicles and the limited inventory, these vehicles are increasingly viewed as critical assets on SMB balance sheets.
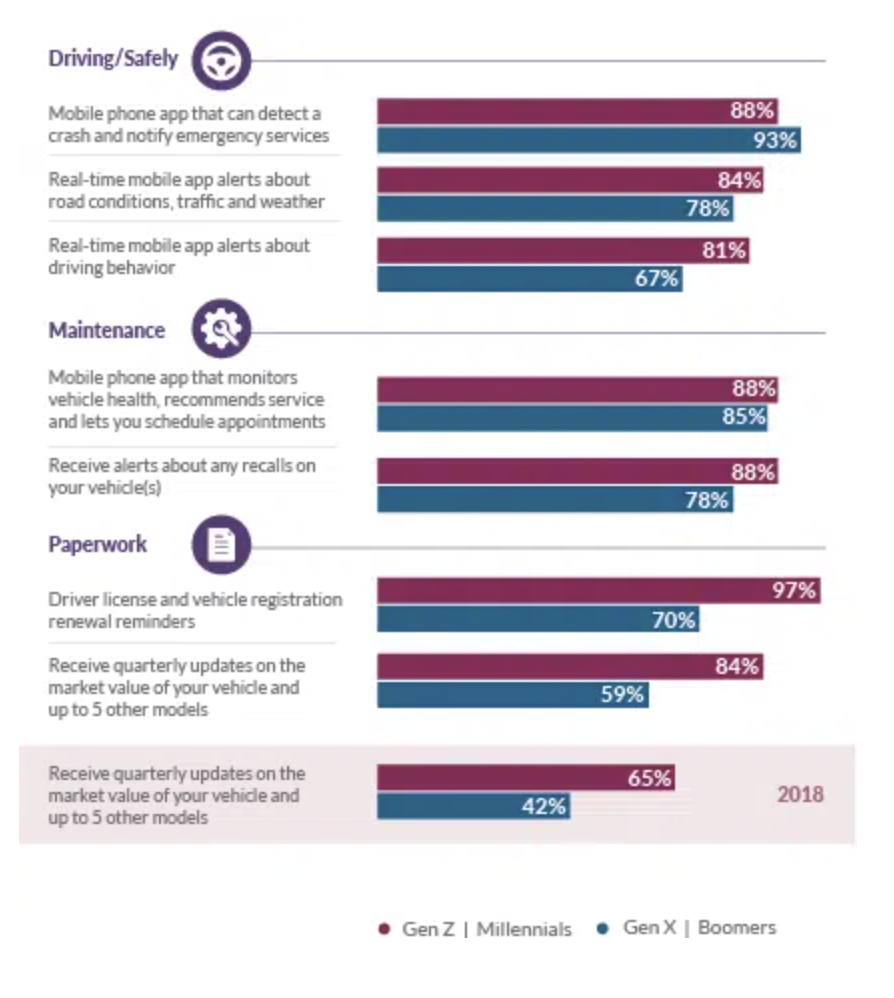
Figure 4: Interest in value-added services for commercial auto insurance
These results reflect a significant opportunity for insurers to shift the value discussion from just pricing to include a range of value-added services that could drive loyalty and retention for relatively little cost. Furthermore, it reinforces a relationship that helps customers reduce or eliminate their risk, helping to drive lower rates in the future.
Commercial Property/BOP Purchase Channels
Both generational segments strongly agree that traditional channels including agents and insurance company website are of top interest. Purchasing through an organization is also of high interest for the younger generation, but less so for the older generation. (See Figure 5.)
The new generation of SMB customers, however, are increasingly interested in other channels to purchase insurance, based on trust and loyalty as well as ease of purchase. They are willing to purchase through a real estate company, legal service, tax service, retailer’s website, Amazon, or Google. This move away from the traditional siloed channels to those that offer or embed it at the time of purchase highlights the need for insurers to re-evaluate their channel strategy and expand their reach through new partnerships and relationships to meet customers on their terms.
There is a hurdle, however. Commercial property insurers understand that the traditional channels are far more effective for information gathering and that the initial collection of property data is the most crucial component to protecting against risk. Even if buyers wish to use new channels (such as at the point of a loan) insurers may not find themselves capable to create a new process that will more easily underwrite the risk.
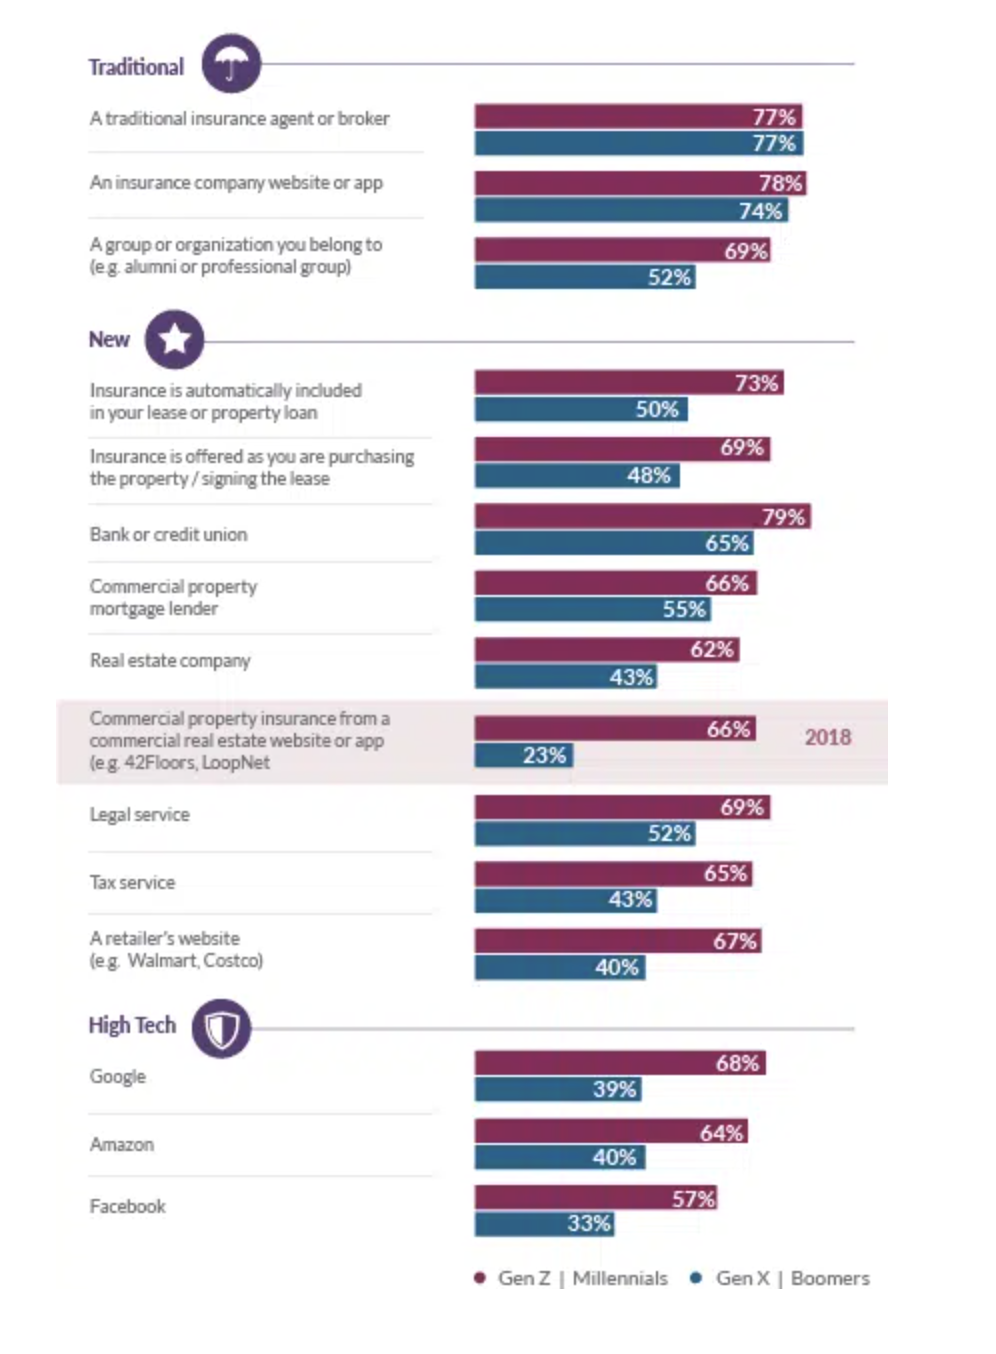
Figure 5: Interest in commercial property/BOP insurance purchase channels
Commercial Property Value-Added Services
Value-added services that help manage prevention of and recovery from perils show strong interest to both generational segments, with Gen Z/Millennials consistently outpacing Gen X/Boomers by 15%. (See Figure 6.)
Both generations are strongly interested (62%-83%) in sensors and alerts for preventing or mitigating losses from fires, carbon monoxide, water leaks, machinery/equipment damage or severe weather, as well as video monitoring and a self-administered risk assessment tool. Concierge services, while slightly lower, still have significant interest of 50% to 66% for both generations. Gen Z and Millennials’ interest reflects a generational shift, where they seek services to help them manage and make their personal and business lives easier.
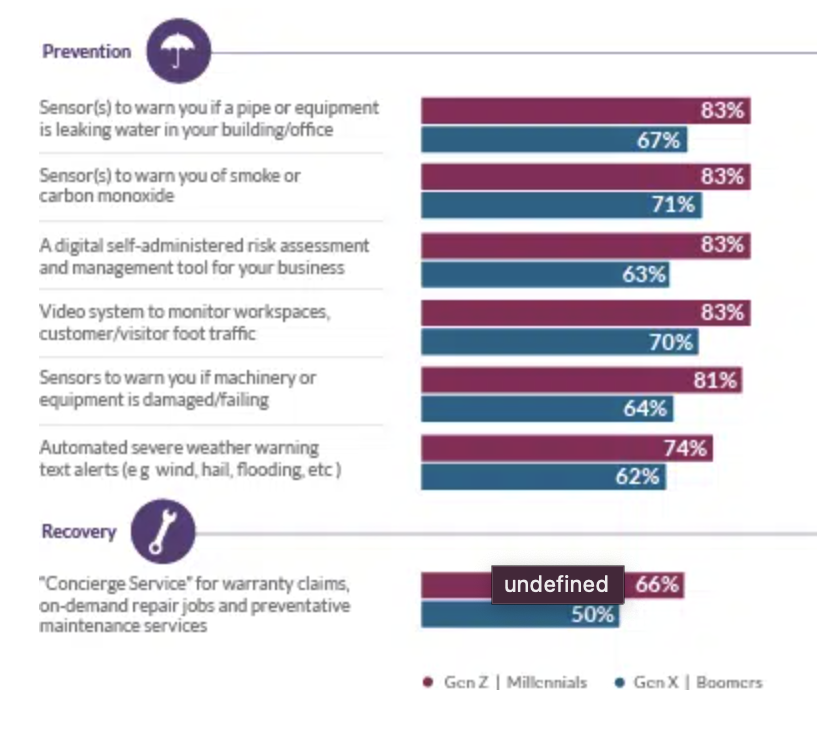
Figure 6: Interest in value-added services for commercial property/BOP insurance
The insights and impact of Majesco’s research highlight a renewed understanding of what it means to be a P&C insurer in a new age of risk. Insurers that think beyond the core risk product and personalize the underwriting and customer experience will have more success in capturing the business of Gen Z/Millennials as they increasingly become business owners and leaders, while at the same time keeping the business of their older, established customers. Value-added services that help customers manage and run their businesses as well as reduce or eliminate risk are a valuable tool for maintaining loyalty. And meeting SMB customers where and when they want to buy insurance through an increasing array of channels is crucial to retain and grow the business. If insurers use this knowledge to grow and cultivate business, they will find likely find that they have improved their ability to manage and reduce risk along the way.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Denise Garth is senior vice president, strategic marketing, responsible for leading marketing, industry relations and innovation in support of Majesco's client-centric strategy.
During the COVID pandemic, especially in the first half of 2020, the pattern of healthcare use across the country changed dramatically.
After more than two years, the global pandemic has brought both challenges and opportunities for health insurers. It has accelerated trends that are now reshaping the way insurance is underwritten, distributed and managed. At the same time, some of the problems that have challenged the industry for years still exist.
To peel back the onion on the insurance industry, we are going to examine previous, current and future assumptions and how they actually played out in the real world. We will also look at using artificial intelligence (AI) to challenge future assumptions as the industry and our world continue to evolve.
Making Assumptions
Actuaries and underwriters make tons of assumptions every day, so much so that we forget that we’re even making them. Three key assumptions make up the backbone of our work in health insurance:
When calculating the renewal of an insurance group or forecasting claims into the next 12 months, we almost always rely on the most recent couple of years’ experience as the basis of our calculations—typically applying more weight to the most recent year. Under normal circumstances, this is the prudent and best practice. But we are not living in normal circumstances (don’t worry, I’m not going to call it a new normal), and the COVID-19 pandemic threw our ability to make assumptions for a loop.
COVID Realities - Medical Care
During the COVID pandemic, especially in the first half of 2020, the pattern of healthcare use across the country changed dramatically. For one, providers rushed to adapt to an influx of COVID cases. In doing so, they diverted people and resources from normal operations and tried to figure out how to charge for the new services and care protocols that didn’t exist just a few weeks prior.
Simultaneously, people abruptly stopped going to the doctor for routine and preventive care, either because their doctors were discouraging it or they wanted to avoid exposing themselves to the virus unless absolutely necessary. Additionally, patients with acute issues thought twice about going to the ER.
In just the first seven weeks following COVID shutdowns, surgical volume dropped 48%, although by July 2020 that volume was only 10% less than we saw in 2019. Overall, millions of non-acute procedures were postponed indefinitely or canceled. And because different regions addressed the pandemic in different ways, insurance agencies lost the ability to make blanket statements about the way their clients would be affected.
To continue providing necessary care to their patients during this time, providers turned to online and virtual tools to help diagnose and treat patients. And while telehealth existed before the pandemic, it wasn’t widely used in the same way it is now, meaning many healthcare facilities had to learn how to bill appropriately for it.
See also: Optimizing Insurance's Role in the Pandemic
COVID Realities - Insurance Industry
Post-pandemic, the insurance industry held its collective breath, waiting to learn about the financial impact. As the claims started rolling in (or not rolling in, as was actually the case), it became clear that something unprecedented was indeed happening.
Claims submitted for March and April 2020 were far below historic or forecasted levels. Payers and insurance company risk managers were happy the pandemic didn’t spell doom for the insurance industry.
As the pandemic continued deeper into 2020, those of us in the industry continued to watch the claims feed, expecting there to be some sort of a correction. We wondered when the claims would just return to “normal” levels or even run high as the market over-corrected for the low claims period. By the time it came to calculate plan renewals and year-end reserves, the overcorrection never came. The assumptions weren’t working as they had in the past.
How to Address
The common practice for actuaries and underwriters was to go ahead and use the prior year’s claims in renewal forecasts but apply a simple adjustment (usually 4%) to account for the dip in utilization based on guidance given by the Society of Actuaries.
On the surface, the experience from March 2020 through the present day has been such a large departure from the past that it appears to be unusable in traditional actuarial models. But is that really the case? And is applying a simple load to the experience really the best we can do to make the data usable?
While the historical data doesn’t quite fit the industry’s current needs, AI can improve actuarial models to help insurance providers make more accurate estimates. Artificial intelligence gives underwriters a more complete picture of risk, separating good risks from bad risks and helping them price policies accordingly. Additionally, AI can make these predictions faster and draw deeper insights from the data, further improving business decisions.
AI Works Where Assumptions Can’t
Traditionally, underwriters have used decades of historical information to develop rules and guidelines to assess risks. However, if the relevance of historical data diminishes over time, it may not accurately predict future trends and exposures, resulting in poor risk assessment and inaccurate pricing. For example, relying on historical loss experience to write natural catastrophe risks used to be considered adequate. But it may be insufficient in the future; changing climate, urbanization and increased asset concentration in climate-exposed areas could significantly alter risk patterns.
The insurance industry relies on accurate underwriting to remain profitable, and underwriters have always relied on data to make decisions. When the normal layers of data aren’t there, underwriters have to be able to turn to artificial intelligence to fill in the gaps. Artificial intelligence can identify trends and outside factors faster than humans, allowing it to provide more accurate predictions when historical data doesn’t fit current patterns.
Get Involved
Our authors are what set Insurance Thought Leadership apart.
|
Partner with us
We’d love to talk to you about how we can improve your marketing ROI.
|
Brett E. Heineman is FSA general manager of health products at Gradient AI.
Heineman is a health actuary with broad experience in the health insurance industry, ranging from provider contracting analysis for carriers to actuarial valuation and actuarial transformation for consulting firms. His professional interests include organizational and personal productivity, actuarial process automation, practical applications of predictive modeling and actuarial modernization/actuarial transformation.


