Download

The relevance premium: How customer centricity unlocks growth

Discover how customer-centric insurers achieve higher growth, lower lapse rates, and stronger engagement through AI, data, and personalized experiences. 

hero

The life insurance industry faces a significant opportunity: consumer interest remains strong, but many customers struggle to understand how life insurance fits their current needs, what it costs, and how to maximize its value. As expectations evolve, insurers must move beyond traditional product-led approaches and create experiences that are relevant, personalized, and easy to navigate. 

The insurers outperforming the market have demonstrated that customer centricity is more than a business philosophy. It is a growth strategy. By reimagining how they engage consumers, empower advisors, and leverage data and AI, these organizations are strengthening customer relationships, increasing loyalty, and delivering measurable business results. 

Capgemini's latest World Life Insurance Report examines how leading insurers are closing the value perception gap and transforming consumer interest into long-term growth. The report uncovers the strategies, capabilities, and operating models that distinguish best-in-class insurers from their peers, offering a practical blueprint for organizations looking to improve engagement, reduce policy lapses, and drive sustainable performance. 

Discover how life insurers can create more relevant customer experiences, deliver trusted guidance at critical life moments, and build intelligent foundations that support personalized engagement at scale. 

Key takeaways 

  • Understand why consumers value life insurance but often question its relevance and affordability.
  • Learn how leading insurers increase engagement through personalized, life-stage-based interactions.
  • Discover how AI-powered advisors and modern distribution models enhance customer experiences.
  • Explore strategies for unifying customer data to enable proactive, intelligent engagement.
  • See how customer-centric insurers achieve higher growth and lower policy lapse rates. 
Ready to learn more


Sponsored by Capgemini


Capgemini

Profile picture for user Capgemini

Capgemini

Capgemini is the business transformation partner for enterprises in the age of AI. We help organizations imagine and build an intelligent, sustainable future, combining AI, technology and human ingenuity to transform how they operate, innovate, and grow. 

With unique end-to-end capabilities spanning strategy, technology, engineering and intelligent operations, we bring together deep industry expertise and market-leading capabilities in AI, cloud and data to turn ambition into measurable business outcomes at scale. Supported by a robust ecosystem of partners and nearly 60 years of expertise, Capgemini is a responsible and diverse global organization of over 410,000 team members in more than 50 countries. 

The Group reported 2025 revenues of €22.5 billion. 

The New World of Accident Reconstruction

Digital evidence from dashcams, drones and vehicle data recorders now complements physical crash analysis in modern accident reconstruction.

Insurance

Not long ago, accident reconstruction relied primarily on the physical evidence left behind after a collision. Tire marks, roadway gouges, vehicle damage, scene measurements and witness statements formed the foundation of most investigations.

Those elements remain essential today. The difference is that they are now joined by an ever-growing collection of digital evidence that can provide additional insight into how a crash unfolded.

From dashcams and commercial fleet cameras to drones, event data recorders (EDRs) and vehicle infotainment systems, forensic engineers have access to more information than ever before. The challenge isn't simply collecting the data but validating it, interpreting it correctly, and integrating it with the physical evidence to develop scientifically supported conclusions.

Cameras Are Changing the Landscape

Video evidence has become increasingly common in accident investigations.

According to a recent survey, nearly 30% of U.S. drivers now use dashcams, a figure that continues to grow each year. Commercial fleets have embraced the technology even more rapidly. One industry report found that 84% of company drivers now have dashcams installed in their work vehicles, representing a 29-percentage-point increase over the previous year. Nearly 65% of commercial drivers also reported that their employers require dashcam use.

Those numbers illustrate an important trend for forensic engineers: many serious crashes are captured on video. Additionally, investigators may have access to recordings from multiple sources, including personal dashcams, commercial fleet cameras, traffic cameras, security systems, and even bystanders' smartphones.

While multiple viewpoints can provide valuable information, each recording captures only one perspective. Camera placement, frame rate, image distortion, lighting conditions, and synchronization all affect what a video can and cannot reliably demonstrate.

For that reason, video evidence is never evaluated in isolation. Engineers compare every recording against the physical evidence and established engineering principles before reaching conclusions.

Preserving Crash Scenes Before They Disappear

Unlike digital evidence, physical crash scenes are temporary.

Vehicles are removed, debris is cleared away, and weather or traffic can quickly alter roadway markings. Important evidence may disappear within hours.

Drones and 3D laser scanners have become increasingly valuable tools for documenting crash scenes before those changes occur. 3D laser scanners allow the capture of tens of millions of individual points in 3D space, allowing for millimeter-level 3D environments to be digitally preserved in full detail and color. In conjunction with 3D laser scan data, drones allow the capture of hundreds of overlapping high-resolution photographs of an accident scene in detail within minutes. Using photogrammetry, those images can be converted into an accurate three-dimensional model and scaled map-quality imagery of the roadway, vehicles and surrounding environment.

Rather than relying solely on photographs taken from ground level, investigators can preserve the entire scene from above, creating a permanent digital record that can be analyzed long after the roadway has reopened.

Building a Three-Dimensional Reconstruction

A three-dimensional model provides much more than a visual representation of the crash scene. Once the scene has been accurately documented, forensic engineers can integrate additional evidence into the digital model, including dashcam recordings, surveillance footage and other video sources.

This allows investigators to:

  • Measure distances, roadway grades and vehicle positions with precision.
  • Analyze vehicle speeds and timing throughout the sequence of events.
  • Evaluate driver sight lines, visibility and roadway geometry.
  • Compare video evidence against physical measurements.
  • Virtually revisit the crash scene long after the physical evidence has been removed.

The result is a comprehensive reconstruction built on measurable data rather than assumptions.

Today's Vehicles Generate More Data Than Ever

Many modern vehicles record far more information than most drivers realize.

Event data recorders (EDRs), also known as your vehicle's "black box," may capture information such as collision severity, vehicle speed, brake application, throttle position, steering inputs, seat belt status and other vehicle operating parameters immediately before and during a collision. In fact, Knott Laboratory can retrieve and analyze EDR information on 57 makes and 700 models of vehicles.

In many cases, investigators may also have access to data stored within infotainment systems, connected devices or telematics platforms. Depending on the vehicle, these systems can provide additional context about navigation activity, communications, connected devices or vehicle operations before the collision.

Each source contributes another piece of the puzzle, but none tells the entire story on its own.

At Knott Laboratory, engineers evaluate digital information alongside vehicle inspections, roadway evidence, scene documentation and witness information to determine whether all available evidence supports a consistent reconstruction.

Technology Supports the Science

As vehicles become more connected and video becomes increasingly common, accident reconstruction continues to evolve. Digital evidence has expanded the tools available to forensic engineers, but it has not changed the scientific principles that guide every investigation.

The role of the forensic engineer is to objectively analyze every available source of evidence, understand the strengths and limitations of each, and determine whether the facts support a particular conclusion.

Whether reconstructing crashes involving passenger vehicles, motorcycles, commercial trucks, pedestrians or bicycles, Knott Laboratory combines decades of forensic engineering experience with today's advanced investigative technologies to provide objective, scientifically supported analyses for a host of clients, from insurance providers to attorneys.

Technology captures the evidence, and science gives the evidence meaning.


Seth Behrens

Profile picture for user SethBehrens

Seth Behrens

Seth Behrens, P.E., DFE, is director of engineering – accident reconstruction for Knott Laboratory. 

Behrens has performed investigations and reconstructions of high and low-speed motor vehicle accidents. His experience includes the use of conservation of energy and conservation of momentum analysis to determine the speed of vehicles involved in accidents, crashworthiness of vehicles, occupant compartment intrusion, driver reaction and time/space relationships and analysis. 

How to Build Tomorrow's Insurance Workforce

Insurance's talent crisis demands a shift from hiring for past experience to identifying transferable skills and future potential.

Insurance

With the "silver tsunami" creating significant attrition, it's no secret that the insurance workforce is shifting. Organizations across the insurance ecosystem are struggling to attract the talent needed to fill critical gaps and prepare for what comes next.

Solving for these challenges requires us to think about people differently – not just as applicants for today's openings but as potential contributors to tomorrow's workforce. By shifting how we evaluate talent – from what someone has previously done to what they're capable of becoming – and then by cultivating traits like learning agility and future capability internally, organizations can build a robust and successful workforce for the future.

Identifying and Prioritizing Transferable Skills

The traditional approach to recruiting often looks backward, focusing on titles held, industries worked in, and responsibilities already performed. Those things matter, but they should not be the only measure of a candidate's value. What if instead we look for transferable skills? This does not mean lowering standards. It means expanding the lens. It means asking better questions about capability, judgement, adaptability, and readiness. Have they led a volunteer group? Did they mention a project that required impressive problem solving? Once these skills are identified, it's then up to talent leaders to determine how those skills can be built upon to develop the optimal employee.

Take a mid-career candidate – someone who's very accomplished, has many degrees, and has been a leader, but now wants to move to something different. Some hiring managers wouldn't even consider this individual for certain roles, concerned they're too skilled. But it's a mistake to dismiss a candidate as a poor fit for a position without trying to understand why this person may be interested in the role in the first place. Maybe they want a different pace. Maybe they are looking for a new challenge. Maybe they want to apply their experience in a more focused way. Maybe they're being intentional about the next chapter of their career.

Hiring for potential allows organizations to recognize transferrable skills, avoid overlooking strong talent, and build teams with broader experience, perspective, and capability.

Pinpointing Learning Agility as a Signal of Future Capability

One meaningful way to spot learning agility is to listen for how candidates connect their past experience to future contribution. Candidates who are committed to growth often show it through action: coursework, certifications, self-directed learning, stretch assignments, volunteer leadership, or intentional career pivots. They are usually able to explain not only what they have done, but what they have learned and how they are applying it. Look for candidates who are taking courses, initiating self-training, or working on degrees that have the capacity to expand or re-route their career trajectory. Listen to how they frame the skillsets they have developed in previous roles.

This perspective shift works on the talent development side too. Personally, I always encourage employees to be visible about their skills, interests, and growth goals. Internal profiles, skills-based assessments, and development conversations can help surface capability that may otherwise go unnoticed. This kind of professional curiosity and up-skilling are important but so are previously demonstrated traits like resilience, adaptability, and change readiness – all things to identify and cultivate. In my experience, some of the strongest talent decisions happen when we look beyond the obvious and pay attention to the qualities that signal readiness: curiosity, accountability, sound judgment, resilience, and the ability to lead through change.

In the same way we look for skills when screening resumes and talking with candidates, talent leaders should be thinking about these elements for internal roles and promotions as well. The skills people identify in themselves and how they rate themselves on assessment tools can inform development opportunities and identify organizational fits that might not otherwise have been obvious.

Spotting and Maximizing Leadership Effectiveness Skills

Manager effectiveness remains one of the most persistent and consequential challenges in human resources. If high-performing employees are thrust into supervisory or managerial roles without training on how to meet new expectations, it's not surprising when they don't succeed. By identifying transferable skills already present in the workforce and pairing them with practical tools, coaching, and accountability, organizations can develop leaders who are prepared, not just promoted.

The process of creating courageous leaders is not solely about preparing employees for a leadership role; it's about creating a courageous-leader mindset. A courageous-leader mindset means being willing to ask thoughtful questions, listen before concluding, challenge assumptions, and recognize where bias or blind spots may influence decisions.

Layered on top of this mindset, practical professional development and training programs can help foster new skillsets and build practical capability. Whether through monthly manager development sessions, focused learning labs, or intensive supervisor boot camps, organizations can build practical leadership capability in a way that is structured, consistent, and immediately applicable.

Building Tomorrow's Workforce Starts with Seeing Talent Differently

Not every individual with transferable skills will be the right fit for every role, and thoughtful selection still matters. But when HR leaders prioritize potential, cultivate internal capability, and apply consistent judgment, we create stronger pipelines, more adaptable teams, and a workforce better prepared for the future.

Insurance Shopping Has a Missing Layer

Insurance technology has advanced rapidly, but the critical moment when shopping intent becomes an organized, actionable request remains underdeveloped.

Insurance

We have built a lot of technology around insurance distribution. We have systems for advertising, quoting, underwriting, CRM, lead management, automation, servicing, and now AI. But there is a part of the experience before most of those systems begin that I think deserves more attention.

Someone has to move from "I need insurance help" to "Here is an organized request that another person can actually understand and act on." Today, we often treat those as though they are the same moment.

A shopper fills out a form or expresses interest, and a record begins moving through the system. But the shopper may still not understand who will receive the information, what happens next, or what kind of contact to expect. The insurance professional receiving the request may still have to figure out why the person is shopping, whether the request fits, what has already been explained, and what information is still missing.

That creates work on both sides, and it can make an already confusing insurance-shopping experience feel even more fragmented. The shopper may have to repeat herself. The professional may have to reconstruct context that should have been clear earlier. And the system can still call the handoff successful because information moved from one place to another.

The Middle Layer

I think the industry needs to pay more attention to this middle layer. Not as another marketing funnel. Not as a way to move people faster. As the point where shopping intent becomes an organized insurance request that both sides can understand.

For the shopper, that means clearer expectations. Who may receive the request? What happens next? Is a licensed insurance professional likely to review it? What kind of contact should the shopper expect? The goal is not zero contact. It is clearer, more controlled contact.

For the insurance professional, it means better context. Why is the person shopping? What has already been provided? What still needs to be clarified? Is the request something this professional can reasonably help with? A request should be organized enough that the receiving professional can make a meaningful decision instead of starting from zero.

That is different from simply collecting more fields. More information does not always create more understanding. A long form can still produce a weak request if the person completing it does not know what will happen next or if the professional receiving it still has to figure out the reason behind the request.

Where Consumer Control Matters

This is also where consumer control matters. Insurance shopping is often repetitive, high-pressure, and difficult for the shopper to control. People worry about spam calls, who gets their information, whether they are being sent everywhere, and whether someone licensed is actually going to help them. Those concerns are not separate from the request process. They are part of it.

A better request layer should preserve enough shopper authorization and context that the next step feels understandable rather than surprising. The shopper should know what she is choosing. The professional should know enough to decide whether to engage. And the handoff should carry forward the information needed to continue the experience instead of restarting it.

AI can help here, but AI should not become the story. It can organize information, identify missing details, summarize what the shopper has already explained, and improve request readiness. Those are useful capabilities. But the technology still has to support a clear human process.

If the shopper does not understand what is happening, or the professional does not have enough useful context, making the handoff faster does not necessarily make the experience better. We may simply automate confusion.

What Marketing Doesn't Measure

I came to this problem after spending years around digital acquisition and customer behavior. In marketing, we get very good at measuring clicks, forms, and conversions. Insurance made me look at those actions differently because there is a person inside every one of them, and the action is often only the beginning of what that person actually needs.

That is the problem I am working on through Ensurance, a U.S. insurance-shopping company beginning with auto insurance. We are building around the idea that a shopper should be able to start one organized request with more clarity and control, while participating licensed professionals receive better context around requests they may choose to engage with.

Behind that, we are developing CATE, our Controlled Access Trust Engine, as the controlled-access and request-intelligence layer. Its role is to help structure requests, improve readiness, support controlled access, and create more useful opportunity context while preserving shopper authorization. CATE is being built, and planned AI capabilities are still under development.

The larger point is not about one company. As insurance becomes more automated, the quality of what enters those systems matters more. The industry does not need another way to turn shoppers into records faster. It needs a clearer way to turn insurance-shopping intent into an organized request that both sides understand.

That is the missing layer I think deserves more attention.


Ethel Rio Cohen

Profile picture for user EthelRioCohen

Ethel Rio Cohen

Ethel Rio Cohen is the founder and CEO of Ensurance, an insurance-shopping company focused on creating a clearer, more protected way for people to ask for insurance help and get more choices. 

Cohen previously helped build and sell an insurance agency and is the author of the coming book The Room I Built, about building what does not yet exist instead of waiting for someone else to create it.

Beware of 'Digital Ghosts'

AI systems continue recommending brands long after acquisitions close and retire them, creating invisible gaps that distort answers for customers.

Insurance

An acquisition can close in every way that matters on paper — the deal is signed, the brand of the company being bought is retired, its old website redirects to the acquirer's, the press release goes out — and still not be finished. Not because of anything left undone in the integration plan, but because of something almost nobody's integration plan accounts for: The acquired brand's identity still exists inside AI answer engines.

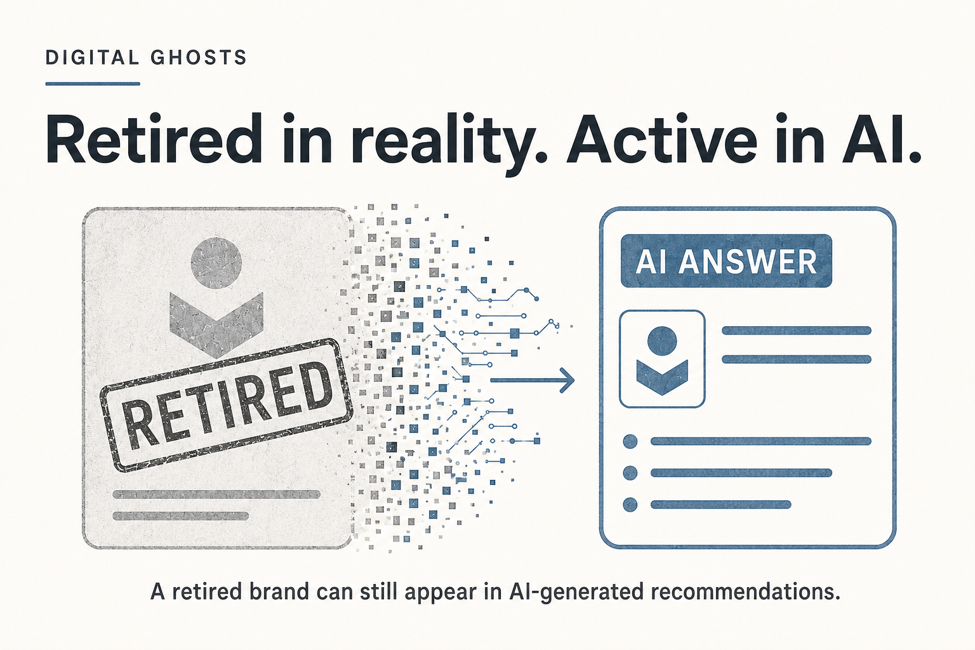
We've started calling this pattern a digital ghost — a retired, rebranded, or acquired brand that ChatGPT, Gemini, Perplexity, Copilot, or Claude continues to describe as if it were still an active, standalone option. The business is gone. The AI's understanding of the business hasn't caught up.

Retired in reality. Active in AI.

The clearest example we've found comes from our own Q2 2026 AIVI Insurance Benchmark, a study of how five major AI systems retrieve, cite, and recommend 134 insurance brands. Liberty Mutual confirmed the retirement of the Safeco brand on April 25, 2026. In the same quarter's data — after that confirmed retirement — Safeco still generated measurable AI-answer presence: real mentions, a 43% recommendation rate, and zero citations connecting any of it back to Liberty Mutual.

That last number is the important one. It's not that the AI systems got the brand wrong. It's that nothing in their answers pointed a customer toward who actually underwrites the policy now. A consumer asking an AI assistant for a recommendation could walk away with a real, specific answer that has no path back to the company actually offering the product today.

This isn't a hallucination in the usual sense — it's not inventing a fact. It's closer to a synchronization failure. AI systems build their understanding of brands from a mix of training data and retrieved web content, and neither updates on the same schedule as a corporate transaction. A press release, a 10-K filing, and a website redirect are all real signals that a business changed hands. None of them is a message an AI system is guaranteed to receive, weigh correctly, or propagate into the next thing it tells someone.

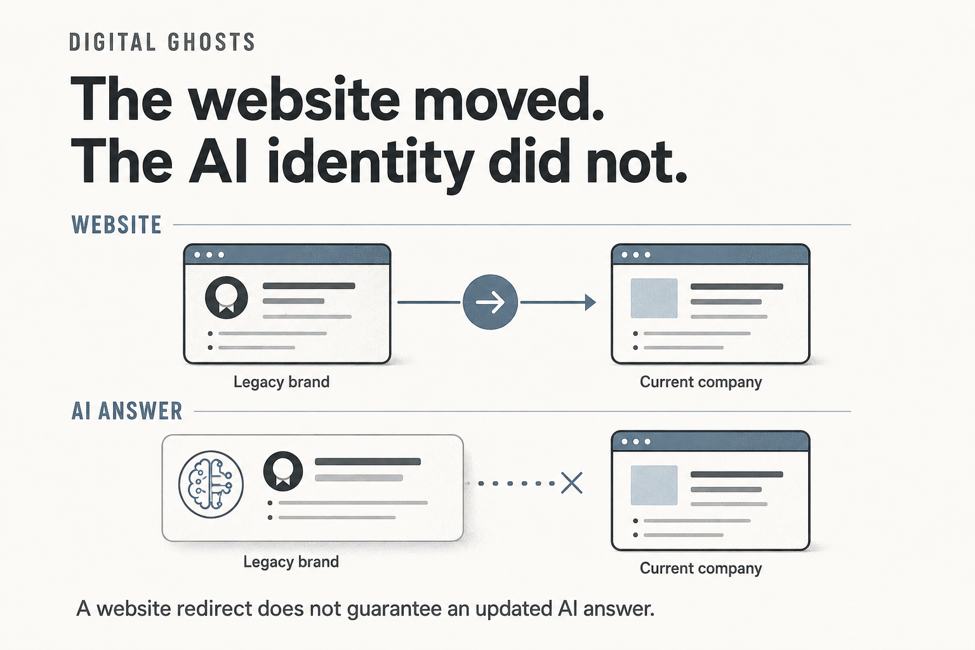
The website moved. The AI identity did not.

The instinct, understandably, is to treat this as a technical SEO problem: redirect the old domain, update the schema markup, merge the entities in the knowledge graph, and move on. Those steps matter — but they solve the problem search engines have, not the one AI answer engines have.

A 301 redirect tells a crawler where a page went. It doesn't tell a language model to stop describing the old brand as though it still exists independently, because the model isn't re-crawling your site every time someone asks it a question — it's drawing on a learned, compressed representation of what it already knows, refreshed unevenly and on nobody's predictable timeline. You can do everything right on your own domain and still have an AI system confidently describe your acquired brand as a going concern, months or years after it stopped being one.

That's the uncomfortable part for anyone running post-merger brand integration: the tools that fixed this problem for search don't fully fix it for AI. It needs to be treated as its own layer of the integration plan, not a byproduct of the ones already in place.

The business changed. The AI identity did not.

Nothing about this is specific to insurance, or to Safeco, or to any one deal. Every industry that runs on M&A — and few run on it as continuously as insurance, between carrier consolidation, MGA acquisitions, and insurtech wind-downs — produces the exact conditions a digital ghost needs: a legacy brand identity, a change in ownership, and an AI-answer layer with no obligation to catch up on its own schedule. The mechanism is the same regardless of what industry the acquired brand competed in.

What varies is how much the problem matters, and that's a harder question than it looks. It's tempting to reach for a dollar figure — X% of AI-driven inquiries times a conversion rate times a customer value, an instant "cost of the problem." We built several versions of that calculation before deciding none of them held up to our own scrutiny. Every version required assumptions about customer behavior — whether someone recommended a defunct brand name actually abandons the purchase, gets confused, or finds their way to the real company anyway — that we can't verify from outside data. Getting a defensible number requires either a controlled study of real customer behavior or access to the acquiring company's own conversion data. Anything short of that is a guess wearing a decimal point.

What doesn't require a guess is the underlying question, which any brand or integration leader can actually test: can a customer who encounters your retired brand's name in an AI answer find their way to the right product, agent, or service channel today? Verify what the AI systems are actually saying. Walk the paths a confused customer would walk — the old domain, the agent directory, the quote flow, the phone line — and see where they lead. What comes back from that exercise usually sorts into one of a few honest categories: a real problem worth fixing now, a real problem worth measuring more before committing budget to it, an inconsistency that turns out not to matter because the recovery paths already work, or simply not enough information yet to say either way. All four are legitimate answers. None of them require inventing a number to be worth acting on.

What this means for the next deal

M&A integration checklists were built for a world where a retired brand's presence outside the company was mostly a matter of search rankings and leftover backlinks — things that decay naturally and don't actively mislead anyone in the meantime. AI answer engines don't decay the same way. A digital ghost can sit at full strength for years, confidently recommended, with nothing correcting it, because there's no browser tab open to notice.

The fix isn't complicated to describe, even if it's not yet a standard line item: know what AI systems are actually saying about the brand you retired, and know whether a customer who hears it can still find their way to the business that's actually there. Most integration plans don't ask that question yet. Most of the acquisitions currently closing will eventually need to.

Insurance Risks Losing Expertise to Retirements

As insurers automate entry-level roles to cut costs, they risk eliminating the farm system that produces tomorrow's underwriters and adjusters.

Insurance

The insurance industry's persistent talent crunch goes far deeper than a hiring gap – it's also becoming a knowledge gap, as the accumulated judgment of a workforce built over decades retires faster than it can be replaced.

By the end of 2026, the U.S. Bureau of Labor Statistics estimates roughly 400,000 insurance professionals will have retired in the last half-decade alone. Today's average insurance employee is in their mid-40s to mid-50s, depending on the line of business. One in four underwriters is already over 50, and less than a quarter of our workforce is under 35.

Turnover has climbed from a historical 8-9% to 12-15% industry-wide. Even with a nearly unprecedented 14 months of workforce reductions, as insurance economist Dr. Robert Hartwig has noted, the sector's 3.3% unemployment rate is still far below the national average of 4.4%.

And that's just the demographic aspect to the story. The bigger issues are what insurers lose when long-tenured experts retire - and what we're doing right now to fill the talent pipeline with future innovators and leaders.

The Industry's Best-Kept Secret Was Its On-Ramp

Ask almost any insurance executive how they got their start, and you'll hear some version of the same story. They largely majored in something other than RMI (risk management/insurance) as undergrads. They came to insurance in an entry-level position – a junior-level claims processing role, a customer service line, or an underwriting support seat.

The pay was good but not great, and the title wasn't impressive. But this was accepted as part of the bargain for landing a job that taught them how the business actually worked in a field that offered tremendous stability and growth opportunities.

They learned how a policy is priced by experiencing the underwriting and pricing process in real-time.

They learned how a claim goes sideways by handling complex claims.

Over years, that ground-level exposure became accumulated knowledge, which in turn became true expertise and leadership.

This story isn't merely an exercise in nostalgia; it's the operating model that built our industry's immense knowledge base.

Insurance knowledge has never been something learned just from a textbook. It's acquired by doing the scut-work long enough to understand why the rules exist. This is the foundation for valuable context that later empowers people to spot the exception, catch the fraud, or make the call a model won't – or can't.

It also happens to be one of the industry's most reliable recruiting advantages.

Nevertheless, insurance has struggled for years with a perception problem. Nearly one-third of the global population is Gen Z (birth years 1995-2012, per Pew Research), yet 79% of respondents in this age cohort say they've never considered working in insurance because it looks boring or overly corporate, according to a 2025 Cake & Arrow survey.

Beyond this, insurance is marketed in such a way that it's either an abstraction (or worse, the bill their parents complain about bitterly). The best we can hope for is that kids who are not old enough to drive are able to embrace and internalize geckos, "Mayhem," and "Bibberty" as past generations learned to recognize Mickey Mouse or Joe Camel in their pre-literate phases.

The insurance career on-ramp – the promise that you can enter the field without an advanced finance degree and build a real career in an essential, thriving industry that's focused on the future – is one of insurance's strongest attractions as a career destination. Dismantling this at precisely the moment we need it most would be a catastrophic mistake.

Where AI Actually Helps, and Where It Quietly Doesn't

This is not an argument against AI. Applied strategically, AI eliminates repetitive, low-value work (data entry, document review, first-pass triage, routine correspondence) that used to take hours or days. Agentic AI is proving useful for executing entire multi-step processes, like claims intake or policy servicing, without a person managing every stage. This efficiency creates a higher standard of service and customer satisfaction.

But there's a vast difference between using AI to remove drudgery and AI inadvertently undermining insurance's "farm system," the roles in which fledgling insurance experts build knowledge and wisdom. Companies eliminating entry-level claims or underwriting support positions to fatten margins as AI scales to handle the volume aren't merely cutting costs. They're turning off the talent pipeline that credentialed underwriters and licensed adjusters flow through.

Industry hiring forecasts make the stakes plain: projections show underwriting and claims roles shrinking even as demand grows for developers, actuaries, InfoSec specialists, and data scientists. But those burgeoning roles don't carry the state licensing and credentialing requirements that underwriting and claims work does – which means the very entry-level positions insurers are cutting are the ones that produce the credentialed underwriters and licensed adjusters that insurance businesses (and in many states the law), require.

This creates more than a talent or experience shortfall: it potentially opens a compliance gap, since carriers need licensed, credentialed professionals to legally price and adjust risk. Underwriters typically spend years earning their Chartered Property Casualty Underwriter (CPCU) or Certified Insurance Counselor (CIC) designations, building the on-the-job experience that shapes how carriers price and structure risk.

Claims adjusters face even greater educational and regulatory hurdles: 34 states require independent adjusters to hold a license, and many additional states require staff (in-house) adjusters to be licensed as well, meaning a person cannot legally handle a claim in a majority of the US without passing state exams and meeting continuing education requirements.

Training alone does not clear that bar. Eliminating entry-level roles in which claims workers accumulate the experience and knowledge needed to earn these official designations doesn't merely remove valuable institutional memory; it endangers insurers' future ability to compete in increasingly crowded markets.

Are We Eating Our Seed Corn?

FINRA's 2026 oversight report isolated AI hallucinations as a specific compliance risk, noting the failure isn't that systems misunderstand questions – it's that they don't recognize when they don't know the answers, replacing probability with, well, "plausibility" – answers that "look" right to the untrained eye.

Some carriers have started layering additional review AI agents into the process specifically to catch these errors before they reach a human operator, and early research shows this step can cut hallucination rates meaningfully. But someone still has to know what a correct answer looks like well enough to catch what even these systems miss.

Today, those people are the ones who came up through the ranks. Tomorrow, absent this entry-level talent pool, the industry might lack adequate numbers of human experts in the loop to verify and correct AI outputs just as our industry leans harder into the technology.

If insurers de-emphasize developing talent internally and try to fill gaps by hiring experienced insurance workers from other companies, they'll be competing in a tightening market in the least cost-effective way possible.

The USBLS projects roughly 21,500 claims job openings per year over the next decade. Experienced underwriters and adjusters don't grow on trees – and the industry is shedding them faster than it's producing them.

A carrier that starves its own farm system hasn't opted out of the problem. It's locked itself into paying retail for talent that competitors are still growing at wholesale, ensuring a future of longer hiring cycles and higher salary floors.

How Insurance Leaders Can Act Today to Safeguard Their Business for the Long Haul

  • Protect roles that build judgment while you automate tasks around them. View entry-level positions for what they teach, not just what they cost, and redesign them so AI absorbs the repetitive tasks while people spend more time on work that builds understanding.
  • Use AI to raise the ceiling on early-career work, not lower the floor. Give newer employees tools that let them take on higher-value problems sooner, with human and AI oversight built in, rather than tools that perform the work itself for them and leave nothing to learn.
  • Keep a trained human expert in the loop on every agentic workflow that matters. Regulators are already moving this direction. More than 20 states have adopted the NAIC Model Bulletin on AI Systems as of mid-2026, and examiners expect documented human oversight on high-risk decisions.
  • Treat internal development as a cost strategy, not just a culture initiative. Every role built internally is one you don't have to buy at a premium in tight talent markets.
  • Build succession plans ahead of the exit wave, not after it. Know which roles are at risk this year and who could be ready to step up with the right support before those seats become external searches.

AI is helping insurers work faster and more efficiently than ever. Today's leaders are responsible for recognizing when and where we should solidify and expand people's knowledge, rather than reflexively eliminating roles that have traditionally added value across the insurance lifecycle.

Sources

U.S. Bureau of Labor Statistics data, via PropertyCasualty360, "Insurance industry talent shortage is imminent," June 2025

Insurance Thought Leadership, "Insurance Industry Faces Critical Talent Shortage," May 2026

Insight Global, "Retiring Underwriters Are Creating An Insurance Talent Shortage"

Sonant, "Insurance Staffing Shortage 2026: Crisis Data & AI Solutions," April 2026

Sonant, "Insurance Agency Talent Shortage: Solutions for 2026 & Beyond"

PYMNTS, "Insurance Industry May Be Unprepared for Agentic AI Risks," 2026

Notch, "AI Hallucinations in Insurance: Risks & Fixes"

actuary.info, "Adversarial Self-Critique Rewrites AI Underwriting Governance," June 2026

Cake & Arrow, "Why Gen Z Is Ambivalent About Working in Insurance," Oct. 2025

NAIC, "State Licensing Handbook, Chapter 18: Adjusters"; ADbanker, "Insurance Adjuster Licensing Requirements by State," 2025-2026

Kore1, "Insurtech Hiring Trends 2026" (kore1.com/insurtech-hiring-2026) https://www.pewresearch.org/short-reads/2019/01/17/where-millennials-end-and-generation-z-begins/


James Ballot

Profile picture for user JamesBallot

James Ballot

James P. Ballot is an insurance research, thought leadership, and content strategy leader with more than a decade of experience helping industry, regulatory, business, consumer, and higher education audiences understand and navigate complex industry transitions.

Generative AI's Surprises (Thus Far)

Who would have guessed that AI would take jobs away from Kenyans ghost writing essays for cheating American college students?

Image
ai

I don't know about you, but my bingo card for generative AI did not include its wiping out the jobs of Kenyans who had for years been writing essays for cheating American college students. Yet here we are, according to an article in the New York Times last week. 

That story, plus other surprises from the early years of generative AI, should remind us that our ideas about how the AI revolution will play out should be held lightly. We need to be able to drop ideas immediately when they turn out not to be true and pursue new opportunities as soon as they present themselves.

Let's have a look. 

The New York Times article says Kenya had already seen one wave of job losses to AI. Thousands had been employed transcribing recordings of meetings, but such transcriptions became an early task for AI and began to disappear in 2017. Still, ChatGPT created a shock when it debuted in late 2022. At the peak, some 40,000 people in Nairobi were being paid to do homework for others, but almost all those jobs have diminished in scope or disappeared. Why would a student pay someone to write a paper that AI would generate for free?

The article says that "what jobs remain in essay writing are mainly for 'humanizers,' who edit papers written by A.I. to avoid detection from the cheating software used by many universities."

We've seen plenty of other surprises because the backlash against AI caught Big Tech unawares. Any company associated with the hyperscale data centers being used for AI now faces massive pressure because of their water and electricity needs and because lots of people just don't want to live or work anywhere near them. Flock Safety had achieved an $8 billion valuation as it installed cameras around the U.S. to help police track cars used in crimes but has recently stirred up horror about the possibility of a surveillance state.

At a smaller scale, we've seen an Air Canada chatbot go rogue and offer a discounted fare that the airline had to honor. Zillow set up an AI to monitor home prices and purchase undervalued properties, only to find, some $500 million in losses later, that the project was a flop. IBM and McDonald's set up an AI to handle drive-thru orders but canceled the project after customers posted funny, and highly embarrassing, videos of mistakes on orders — such as adding hundreds of dollars in chicken nuggets or bacon toppings on ice cream.

It's easy to imagine where other, important surprises might arise, too. AI will surely have some effect on where people live, because it will change the dynamics of remote work. AI already seems to be having some effect on car sales, because data centers are contributing to increasing electricity prices, which make electric vehicles less enticing. 

In the much-quoted framework from the late U.S. Secretary of Defense Donald Rumsfeld, there are lots of unknowns out there about AI. We can't know much about the unknown unknowns. But we can certainly prepare ourselves for the known unknowns, and I'd argue that all the surprises that have hit us so far — job disappearances, including in Kenya; technology glitches; backlash to AI — fall into the "known unknown" category. (I'd further argue that known unknowns were Rumsfeld's undoing. He should have known that loads of problems could arise after the U.S. occupied Iraq and should have prepared far more for contingencies, rather than assume that Iraqis would place flowers in the barrels of U.S. tanks.)

The history of technology is full of bad ideas — and of pivots toward transformative ones. Alexander Graham Bell initially thought the telephone would be used to broadcast into people's homes — you'd pick up your phone and listen to, perhaps, a symphony orchestra. (Bell also suggested that the standard greeting should be, "Ahoy!" Hmmm....) YouTube began as a video dating site. Slack was a chat channel for a multiplayer game that got left by the wayside. PayPal started as security software for the late, great Palm Pilot, which had a digital payment feature. And so on.

My favorite pivot actually comes from well outside the tech world — from chewing gum. A young man who moved to Chicago in 1891 sold his father's line of soap and offered small amounts of baking soda for free as an incentive to buyers. The baking soda turned out to be more popular than the soap, so he began selling baking soda. This time, he offered some free chewing gum as the incentive. That gum became so popular that, 130 years later, I have a pack of William Wrigley's spearmint gum on my desk.

So my conclusion from the job losses in Kenya (and elsewhere), and from the many other surprises we've seen, is that mistaken ideas about AI are fine — as long we hold them lightly and can move on from them quickly. Think big, because the opportunities with AI are enormous, but learn really fast. 

Cheers,

Paul

Carriers Must Govern AI Use in Agencies

Most carriers require agencies to carry E&O coverage but don't yet ask who's reviewing AI-generated client communications.

Carriers Must Govern AI Use in Agencies

Somewhere in your distribution channel this morning, a producer pasted a prospect's declarations page into ChatGPT and asked for a plain-English summary. An account manager drafted a coverage explanation in Claude. Someone on the claims side wrote up a loss narrative in Copilot, because it came with the Microsoft license. Nobody at the agency decided which tools were approved, what client data could leave the building, or who'd read the output before it reached the insured, because nobody was asked to decide.

That's rarely recklessness. In most agencies it's a decision no one owns.

Elsewhere in the industry, generative artificial intelligence is being treated like any other emerging risk. Last fall, ISO gave carriers three optional endorsements that exclude generative AI losses from the standard commercial general liability policy, which is the industry's way of saying it considers AI a distinct peril. Roughly half the states have adopted the NAIC's model bulletin on how insurers use AI. Inside carriers and MGAs, governance programs are being written so there's something to show an examiner. That's all good work. None of it reaches the agency down the street that sells your policies.

The Big "I" ACT 2026 Tech Trends Report found that 55% of independent agencies have no written AI use policy, and another 23% are still drafting one. Those agencies are your distribution channel.

I spend most of my time inside independent agencies, generally shops of 10 to 50 people, which is how I know that scene doesn't need a name attached. It looks about the same in most of them, and the people doing it are good at their jobs.

It'd be convenient if this stayed the agency's problem. Three things make it yours.

When an AI-drafted coverage summary tells a policyholder something the policy doesn't say, the errors and omissions claim lands on the agency. Your name is on the policy, though, and it tends to show up on the complaint too. What a chatbot wrote in a few seconds becomes a mark on the agent's E&O history and on your market conduct record at the same time.

There's also the data itself. Every application and loss run your agencies handle carries information you're obligated to protect, and the consumer versions of these tools generally keep what's pasted into them. Few agencies know which version they're on. A breach that starts in an agency's browser tab ends up in a regulator's file under the name on the policy, not the name on the agency's door.

Then there's where the regulators are heading. The NAIC bulletin already holds a carrier responsible for AI that a vendor built and runs on its behalf. Agents using AI on carrier data is the same principle one step further out, and regulators haven't taken that step yet. State examiners are piloting a standard set of AI questions for carriers across a dozen states this year, with a broader version expected this fall, and those questions cover the AI carriers themselves use. Nothing in them asks about the distribution channel. I wouldn't plan on that lasting.

Here's the thing: banning AI in agencies would be the wrong response, and most executives know it. The tools are on every desk already, and the agencies using them well are the ones you most want distributing your products. Treat AI use in the channel the way you already treat E&O coverage — as something you require, verify, and help agencies obtain.

Four requirements cover most of the exposure.

A written acceptable-use policy, as a condition of appointment. One page will do. It names the approved tools, says what data can never be entered into them, and identifies who reviews AI-generated material before a client sees it.

A yearly sign-off. Agencies already send you proof of E&O coverage on a schedule. Ask them to confirm the AI policy is in place on the same cycle, and the mechanism costs you nothing new.

A named owner for every tool in use, meaning a person inside the agency whose name sits on the output. AI belongs on an organization's chart, with someone accountable for it, rather than in the tech stack as one more subscription nobody supervises. That's manageable inside your own walls. Across a few hundred agencies you don't employ, it only happens if you require it.

A template alongside the mandate. Agencies without a written policy aren't resisting governance. Most have never been handed a policy they could adopt in an afternoon, and a carrier or field marketing organization that supplies one will close more of the gap than any contract clause. It's also the kind of help agencies remember when they decide where to place business.

Verification can start well before anyone commissions an audit. Before the next renewal cycle, put one question to your 20 largest agencies: who reads what the AI writes before a client does? The answers will tell you where you actually stand.


Mike Allton

Profile picture for user MikeAllton

Mike Allton

Mike Allton helps teams build a Digital Crew to handle the research, data entry, and admin that humans hate - reclaiming their time for the work only they can do.

As AI Spreads, Orchestration Is Required

AI enables teams to build intelligence locally, but enterprise value depends on coordinating meaning across organizational boundaries.

Insurance AI

AI adoption is spreading faster than enterprise value. McKinsey's 2025 survey found that 88% of organizations use AI in at least one business function, yet nearly two-thirds have not begun scaling it across the enterprise. Only 39% report any enterprise-level impact on earnings.

The gap is usually described as a failure to move pilots into production. That description is accurate but incomplete. A deeper change is underway inside large organizations: AI has altered who can create intelligence, how quickly they can create it and where that intelligence lives.

For most of the software era, development capacity was scarce. New applications waited for funding, platform teams and long delivery cycles. That scarcity concentrated authority. A central group decided what would be built, which data would be used and how the work would be represented.

Generative AI weakens that constraint. A team close to a client, a market or an operational problem can now create an analysis, assistant or small application in days. The people with the problem no longer have to wait as long for the people who build software.

This is a healthy redistribution of capability. It also creates a coordination problem that most AI strategies were not designed to handle.

AI changed what can be local

A local application often succeeds because it sits inside a dense network of shared understanding. Its users know which source to trust, what counts as an exception and whether an answer looks plausible. They can resolve ambiguity in conversation. Much of the application's reliability comes from the team around it.

AI makes that local operating knowledge easier to turn into software. A broker can build a view of carrier appetite. An underwriting team can assemble a submission assistant. A regional operation can create a portfolio view around the definitions it already uses. These tools may overlap, but that does not make them wasteful. They encode knowledge near the point where the work happens.

The difficulty begins when the output has to cross an organizational boundary. Another team may use a different grain, timing convention or source of record. The same term may carry a narrower scope in one specialty than another. A decision that appears self-explanatory locally arrives elsewhere without the assumptions that produced it.

Two property teams can each produce a correct portfolio view while one organizes business by policy and gross written premium and the other by location and net booked premium. The conflict appears only when someone asks for one global answer. The example is small; the organizational pattern is not.

The enterprise has spent years making data portable. AI is now exposing how little of the meaning around that data was designed to travel.

Coordination becomes the binding constraint

When intelligence was scarce, organizations worried about access to skills, models and infrastructure. Those constraints remain, but they are loosening. As more teams can build, the scarce resource shifts from intelligence itself to organizational coherence.

Organizational coherence can accommodate different regional workflows and product structures. Insurance depends on local regulation, market practice, product nuance and professional judgment. Those differences carry real knowledge.

Coherence means that differences are visible when they matter. A definition has a scope. An exception has an owner. A decision has evidence and a rationale. A local variation can be understood by an application or person outside the team that created it.

Coordinating meaning becomes more valuable

This changes the enterprise AI agenda. Model selection, tool access and data quality still matter. They cannot settle which interpretation of premium should govern a global view, who has authority to approve a regional variation or when a past decision stops applying. Those are questions of organizational knowledge and decision rights.

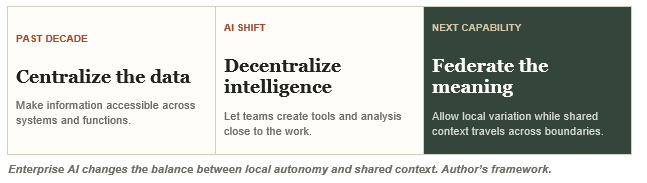
FIGURE 1 · THE NEXT PHASE OF ENTERPRISE AI

Shared meaning is infrastructure

Organizations tend to treat business meaning as documentation. Definitions sit in glossaries, operating procedures, data catalogs and the heads of experienced employees. Applications then rebuild the relevant context through requirements, mappings, prompts and meetings.

AI raises the cost of that arrangement. A person can notice that "written premium" means something different in a particular conversation and ask a follow-up question. An agent operating across several systems may apply the wrong definition consistently and at speed. The more autonomy organizations give AI, the less they can depend on context that remains implicit.

Shared meaning therefore belongs in the same category as identity, security and data lineage: persistent infrastructure that many applications can use. It connects business objects, definitions, sources, decisions and owners. It also records scope and time, because a definition that was valid for one region or period may not apply elsewhere.

The technical expression might be a semantic layer, knowledge graph, metadata system, or combination of approaches. The management idea matters more than the label. Business context must persist outside any one prompt, application or person.

The centralization choice has changed

The traditional response to fragmentation is to centralize applications. One platform, one roadmap, and one set of standards should produce consistency. In practice, full centralization can distance development from the work and turn every local need into an enterprise prioritization decision.

AI makes that trade-off harder to defend. Local teams now have the means to solve some problems faster than a central program can absorb them. Blocking that capacity would preserve consistency by giving up learning and speed.

A federated model separates what can remain local from what must travel. Domains retain authority over their workflows, specialist judgment and legitimate variations. The enterprise establishes identity, interoperability, security and the rules by which shared definitions are published and changed. Accountable owners decide contested meaning; the platform makes those decisions inspectable and reusable.

This is an organizational design choice before it is a technology program. It requires leaders to decide which concepts must remain consistent across boundaries, where variation creates value, and who has authority when definitions conflict.

AI can lower the cost of coherence

Organizations have tried to make knowledge explicit before. Expert systems, rule engines and enterprise ontologies worked in bounded settings, then became expensive to maintain as products, regulations, sources and operating practices changed.

Generative AI changes the maintenance equation. Models can read schemas, documents and conversations; propose relationships and mappings; and flag definitions that appear to conflict. They can help knowledge systems change at a pace closer to the business.

People still decide what disputed terms mean. That boundary is useful. AI can do more of the discovery and drafting while domain owners spend their time on the decisions that require authority and judgment.

This suggests a different measure of AI maturity. The number of pilots says little about whether an organization is learning. A stronger signal is whether each new application leaves behind context that the next application can reuse.

Leaders can test that capability with three questions. Which business meaning must remain consistent when work crosses a boundary? Which differences should remain local because they reflect real market or product knowledge? Who can approve a change and make it available to the rest of the organization?

The answers define the operating model beneath enterprise AI. The test is whether a decision made in one part of the business can be understood, challenged and reused elsewhere without a meeting to reconstruct what everyone meant.

Source: McKinsey, "The State of AI in 2025: Agents, Innovation, and Transformation," Nov. 2025. Survey of 1,993 respondents across 105 countries.

Editorial note: The property example is an illustrative composite. It does not describe a specific company's systems or operating practices.


Shravankumar Chandrasekaran

Profile picture for user ShravankumarChandrasekaran

Shravankumar Chandrasekaran

Shravankumar Chandrasekaran is global product manager at Marsh McLennan. 

He has over 13 years of experience across product management, software development, and insurance. He focuses on leveraging advanced analytics and AI to drive benchmarking solutions globally. 

He received an M.S. in operations research from Columbia University and a B.Tech in electronics and communications engineering from Amrita Vishwa Vidyapeetham in Bangalore, India.

A Hidden AI Risk: Passive Sabotage

Insurance leaders who wait for perfect AI can fall behind competitors already learning to deploy it strategically and responsibly.

Insurance Leaders Must Embrace AI or Fall Behind

Insurance is known as an industry built on caution and calculated decision-making. That isn't going to change, nor should it. But caution becomes a problem when it turns into avoidance.

As AI becomes more embedded across the insurance industry, the greatest risk for many organizations isn't moving too quickly. It is moving too slowly — because some leaders are waiting for the technology to be perfect before they are willing to engage with it at all. That is Passive Sabotage.

Passive Sabotage is the art of dismissing a capability simply because it isn't as good as you think it should be. Does AI code as well as an experienced engineer? Questionable. Does it do it 30 times faster? Yes. Does it know how to tackle new and complex functionality without weeks of meetings, spiking, and exploration? It does. The result is working features in hours or days, not weeks.

Passive Sabotage shows up in small decisions that undermine progress. Abandoning an AI tool after an imperfect result. Delaying a pilot until every problem is solved. Or defaulting to manual processes just because that's what's familiar.

The Real Consequences of Hesitation

This hesitancy comes with real consequences. Organizations that take this approach may miss critical information, move more slowly than competitors, keep experienced employees buried in administrative work, and fail to make full use of the data already available to them. Over time, the gap will widen between companies that are learning how to use AI responsibly and those still debating whether the technology is ready.

Insurance organizations do not need to force AI into every workflow to realize its value. Decisions that carry legal, financial, and human consequences still require consistency, oversight, and experienced judgment. The practical opportunity is to use AI to help teams move faster, reduce manual work, surface information, and test ideas that might otherwise never move beyond discussion.

This distinction matters because much of the skepticism around AI starts with the wrong question. Leaders often ask whether AI can do an entire job as well as a human expert. The better question is whether AI can help a team get to a usable answer, workflow, prototype, or insight faster than they could on their own. In many cases, it can.

For example, AI can summarize claim notes, extract key information from documents, identify missing data, draft communications for review, and help teams prototype new workflow ideas. None of these use cases require handing authority to a fully autonomous system — they require placing intelligence at the right point in an existing process, with the right guardrails, so people are better equipped to make decisions.

Personal Proof

I have tried to demonstrate this through my own work rather than just advocate for it. In the past six months, personally — in between meetings, on planes, nights and weekends — I built:

  • A complete marketplace platform with custom integrations, installation workflows, reporting, and analytics. Historically, I had spent over $150,000 annually on white-labeled embeddable marketplaces for our SaaS products. No more. Built, tested, security-reviewed, and deployed in under four weeks.
  • A centralized enterprise-wide content and knowledge library with a fully integrated newsfeed to deliver personalized updates across the organization — all AI-enabled summaries and agents — replacing a platform that had cost over $180,000 annually.
  • An Outlook add-on built end-to-end in 90 minutes using publicly available API documentation. Another two to three hours of refinement based on testing and feedback.

Were those outputs perfect on the first pass? No. But they were usable — and they were created dramatically faster than they would have been through a traditional process.

Speed changes how organizations learn. Teams can move from idea to prototype in a fraction of the time. They can react to something tangible instead of spending weeks writing requirements for something they have not yet seen. Leaders can test concepts, refine workflows, and make more informed decisions earlier in the process.

This is especially important in insurance, where many organizations are led by experienced executives who did not enter the industry because they were passionate about technology. For many, technology has always been a means to an end. That is understandable, but AI requires leaders to build a new level of familiarity. They do not need to become engineers, but they do need to understand where the technology can create practical value.

Where Organizations Get Stuck

This is where many organizations get stuck. But companies moving ahead are not waiting for AI to become flawless. They are learning where it works, where it needs oversight, and how it can fit into existing processes.

Governance must be part of that process from the beginning. In insurance, requirements can vary by state, business line, client, and use case. Organizations need the ability to decide where AI is used, where it is not, and the option to quickly adapt capabilities if requirements change.

Because of this, modularity is essential. A rigid AI deployment can create risk and limitations, but a configurable approach allows organizations to apply AI where it makes sense, keep human judgment where it is needed, and adapt as the regulatory environment changes. In insurance, where a regulatory change can shift how you apply AI overnight — by state, by client, by risk type — a deployment you can't reconfigure by rule is a liability.

Trust will remain one of the biggest barriers to AI adoption. Many professionals are still getting comfortable with the technology in their everyday work. Technology providers and industry leaders have a shared responsibility to deliver tools that feel useful rather than threatening, and to be honest about where AI needs human oversight and where it does not.

AI does not have to be perfect to be valuable. It does not have to replace expert teams or solve every problem to create a competitive advantage. Insurance leaders who understand that will learn faster and make better use of the information already in front of them.

The companies getting ahead are learning where AI works, where it needs oversight, and how it fits into existing operations — through direct use, not by delegating the evaluation and waiting for a recommendation. If you're a "leader" riding side-car to the opinions of others on this, your days in that role are numbered. It's time to begin using AI yourself.