Download

How AI Search Changes Insurance Marketing

A new decision layer is forming above the traditional sales funnel. Traditional measures of effectiveness no longer matter. 

AI Visibility Decouples from Insurance Market Share

For decades, the math governing property and casualty insurance distribution was straightforward: premium scale translated into market share, and heavy marketing budgets translated into digital reach. A carrier that dominated search results, television, and agent awareness could reliably occupy the top of the customer-acquisition funnel.

A new decision layer is now forming above that funnel. Buyers, agents, brokers, and business owners increasingly ask AI platforms to compare carriers, explain coverage, and recommend providers. Those systems do not return 10 blue links. They assemble a short, synthesized answer.

That distinction matters. A carrier can remain commercially large, rank well in traditional search, and still be absent when an AI system constructs the shortlist. Its legacy presence has not disappeared—but it can be bypassed at the moment of consideration.

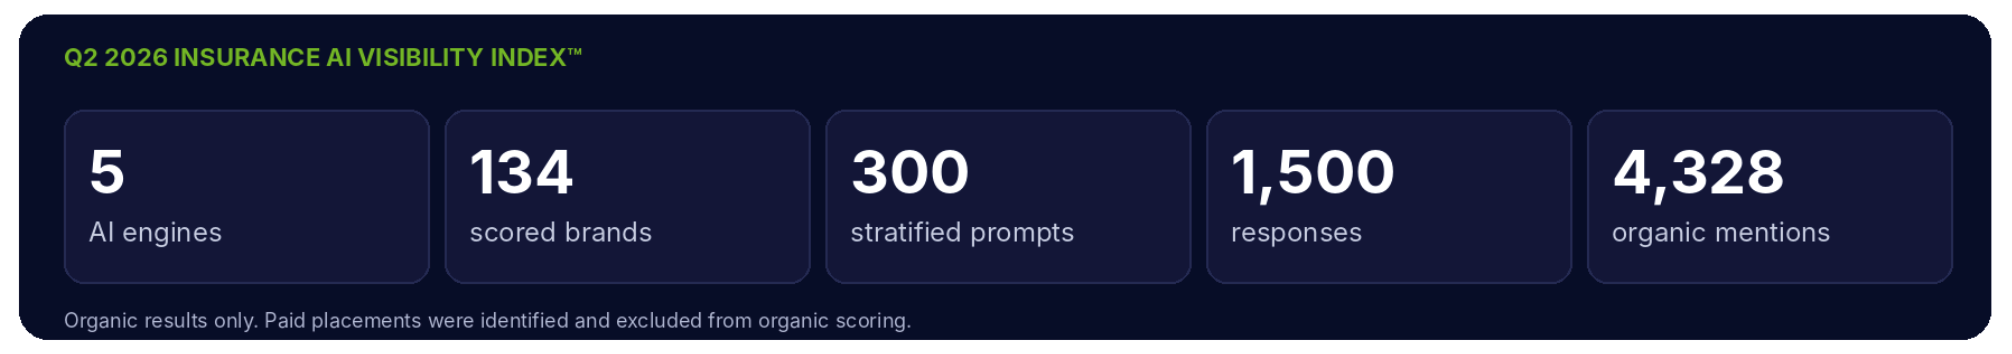
To measure this emerging risk, Brainpan.AI's Q2 2026 Insurance AI Visibility Index™ tracked 137 insurance brands and scored 134 with sufficient measured data. The study tested 300 stratified prompts across ChatGPT, Gemini, Claude, Perplexity, and Copilot, producing 1,500 responses and 4,328 organic brand mentions. The benchmark measures whether brands are retrieved, placed prominently, recommended, and supported with visible evidence; it is not a ranking of carrier quality, financial strength, or customer value.


Q2 2026 Insurance AI Visibility
The Market-Share Illusion

The study's most commercially provocative finding is the decoupling between real-world market share and visibility inside AI-generated answers. Premium share remains an essential measure of commercial scale. It is not, however, a reliable proxy for AI mindshare.

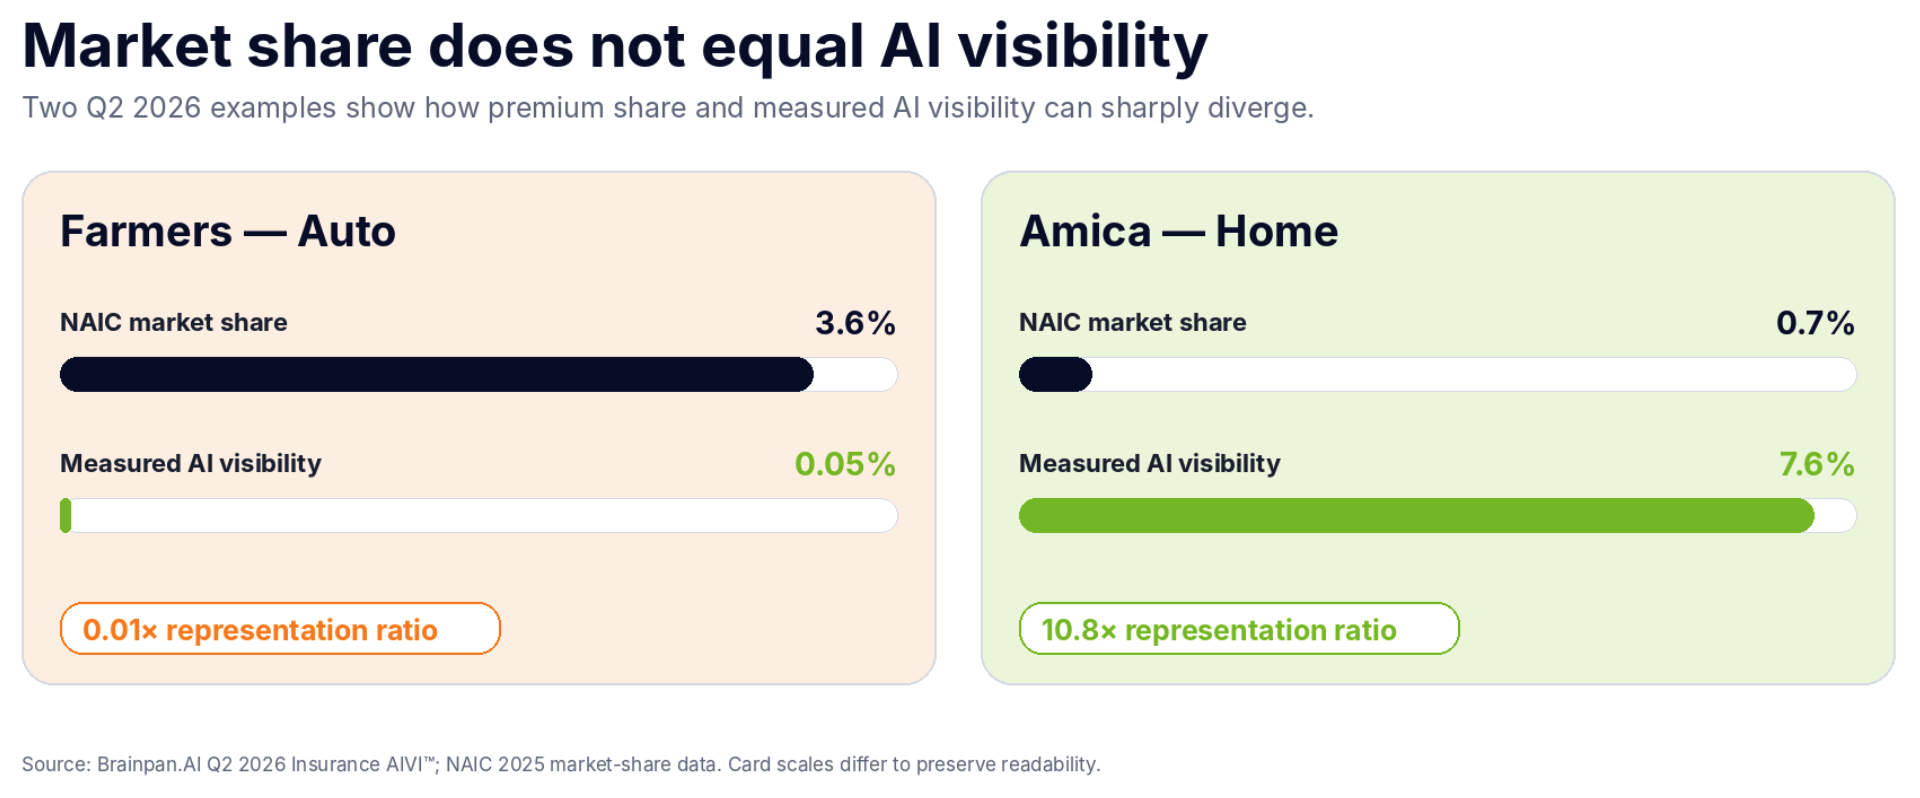
Farmers illustrates the downside. In Auto, the carrier held roughly 3.6% of the real market, according to NAIC data, yet registered approximately 0.05% of measured AI visibility in the study—functionally absent relative to its commercial position. Amica illustrates the opposite pattern. Its Home AI visibility reached 7.6% against approximately 0.7% real market share, an overrepresentation ratio of about 10.8 times.

These examples do not prove that AI visibility causes premium growth or policy conversion. They establish something more immediate: market scale and machine visibility are now separate competitive assets. A carrier may lead one and trail badly in the other.

Market Share

Figure 1. Real-world market share and measured AI visibility can diverge sharply. Farmers is severely underrepresented in Auto, while Amica is substantially overrepresented in Home.

Visibility Is Not One Metric

The benchmark also shows why a single mention count is insufficient. AI visibility has at least three distinct dimensions: reach, recommendation efficiency, and prominence.

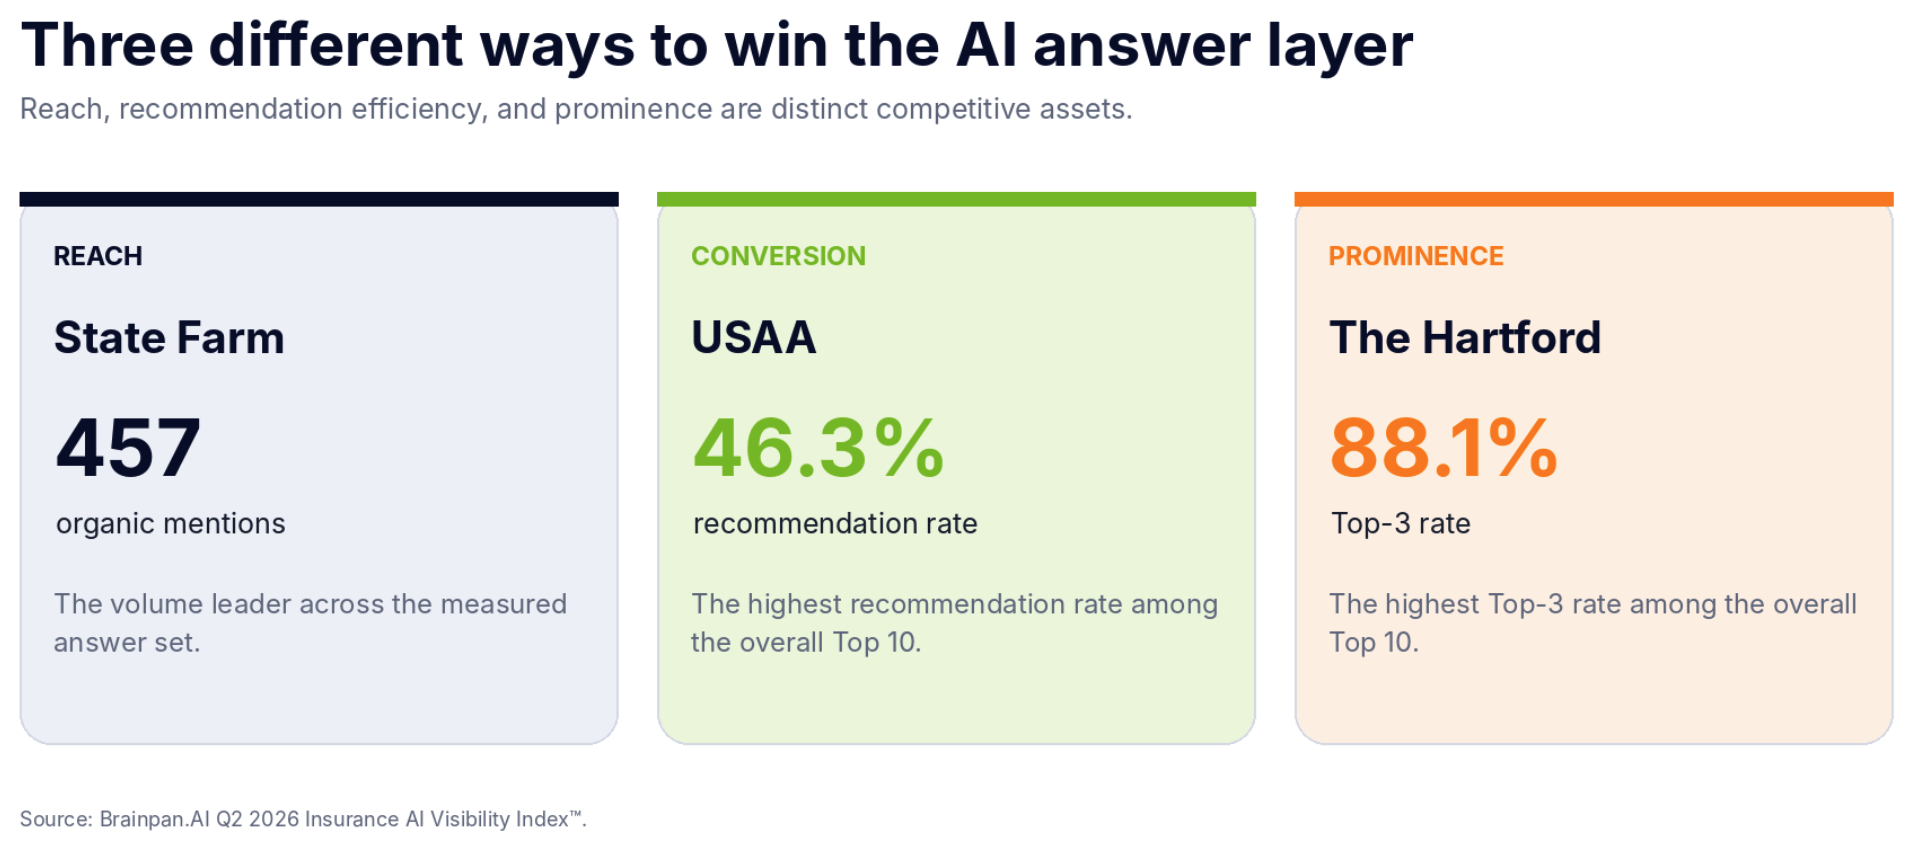
State Farm led the study on reach, with 457 organic mentions. USAA appeared less often, but recorded a 46% recommendation rate—the highest among the overall Top 10 brands. The Hartford was the prominence outlier: although it ranked eighth in total organic mention volume, 88% of its appearances landed in the Top 3, the highest Top-3 rate among the overall Top 10.

These are different advantages. State Farm owns more of the answer layer. USAA converts a larger share of appearances into genuine recommendations. The Hartford is surfaced near the top when it appears. A carrier's reporting should separate all three rather than collapsing them into a single traffic or visibility number.

AI Answer Layer

Figure 2. Reach, recommendation efficiency, and prominence describe different forms of competitive strength inside AI-generated answers.

Two Operational Drivers Leaders Should Examine

The benchmark measures outcomes, not the complete causal chain behind them. It nevertheless points to two operational areas that carriers should examine closely.

1. Machine-readable corporate and distribution information

This is not merely an IT plumbing issue. It is a distribution issue. Product availability, underwriting appetite, geographic eligibility, claims capabilities, and partner information are often fragmented across PDFs, portals, state pages, and loosely connected web content.

When public information is inconsistent or difficult to interpret, an AI system has less reliable material from which to construct an answer. Carriers should therefore audit whether their public-facing product and appetite information is explicit, current, consistently named, and easy for both humans and machines to retrieve.

2. Independent authority—not citation volume alone

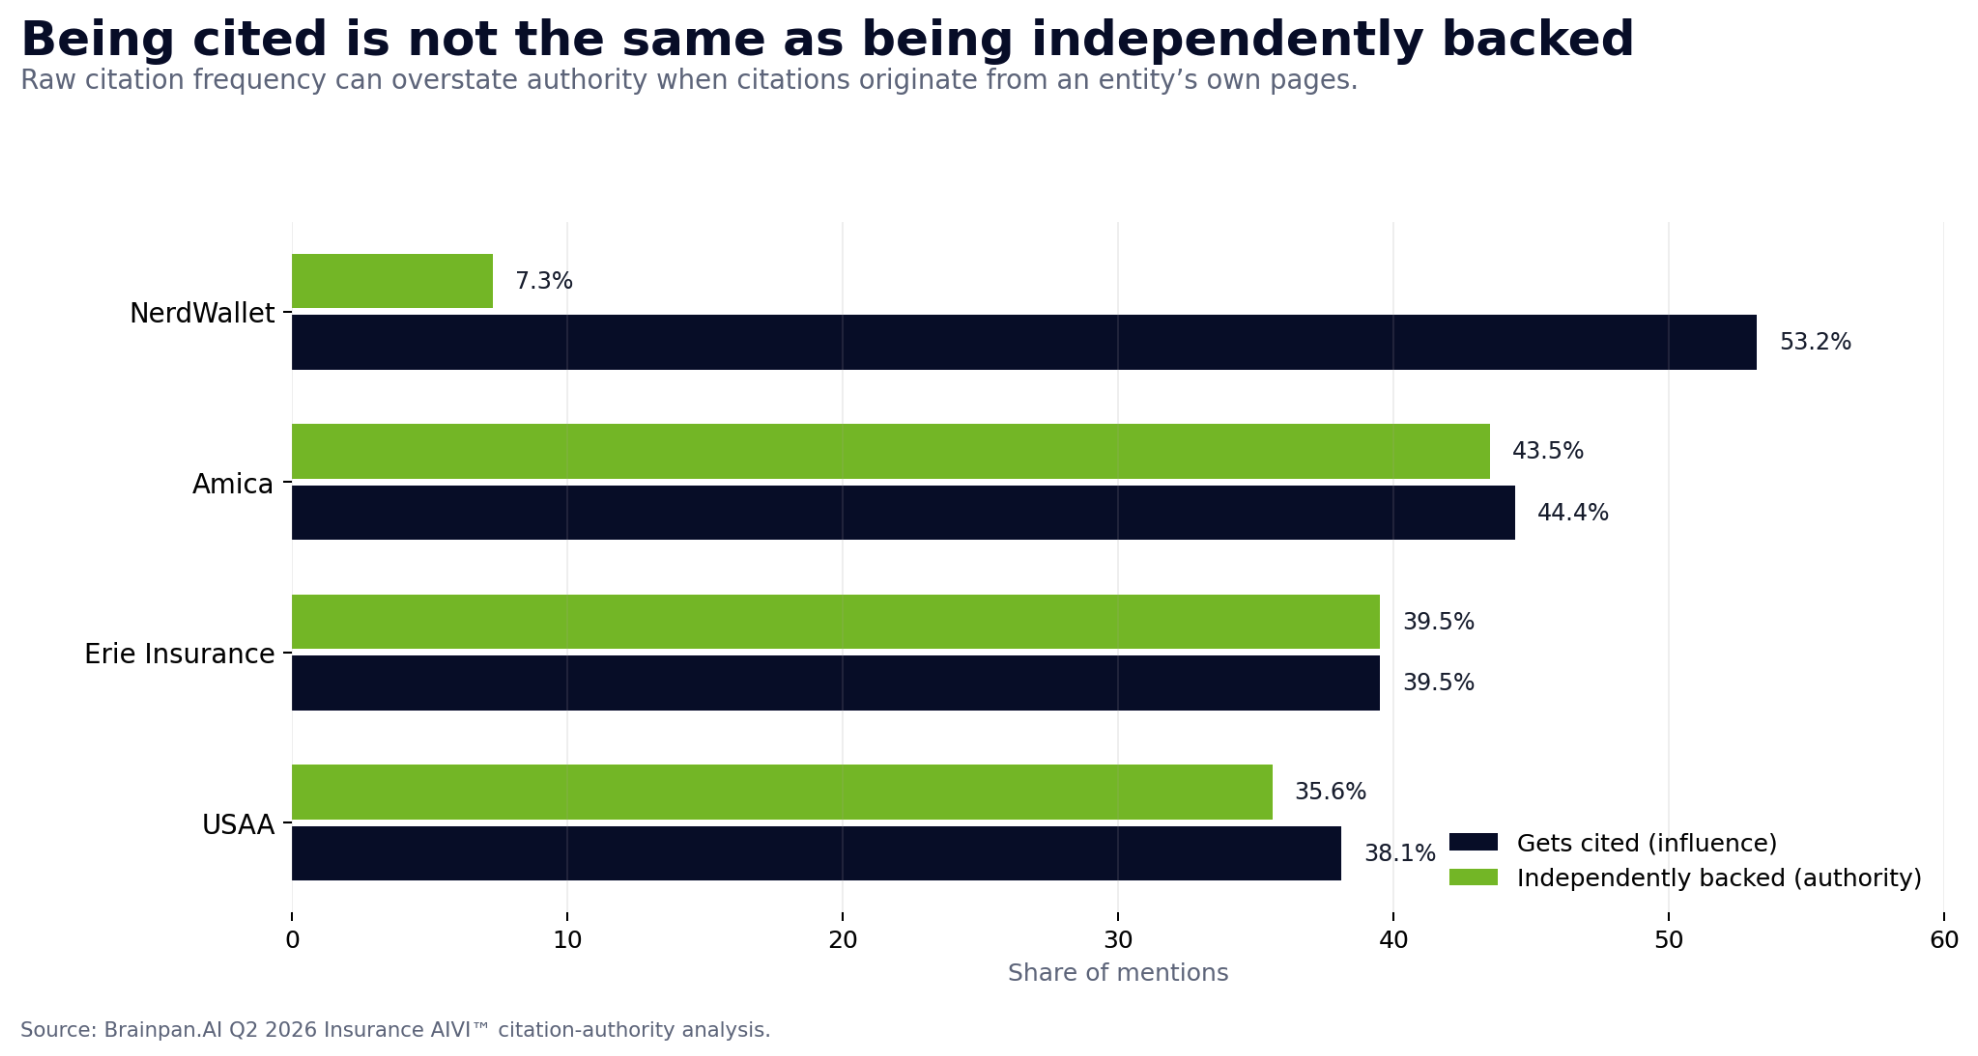
The study also separates citation influence—how often an entity receives a visible citation—from independent authority, or how often that supporting evidence comes from a genuine third party rather than the entity's own domain.

That distinction can materially change the interpretation. NerdWallet received visible citations in 53% of its mentions, but only 7.3% of its mentions were independently backed after self-citation was removed. Several carriers showed the opposite pattern: lower raw citation frequency, but much stronger independent backing when they were cited.

The implication is not that owned content is unimportant. It is that raw citation counts can create false confidence. Carrier PR, regulatory references, independent analysis, authoritative industry media, and consistent third-party descriptions now form part of the evidence environment from which AI systems assemble answers.

Cited

Figure 3. Citation influence and independent authority are not interchangeable. A high citation rate may still be driven largely by self-originated evidence.

The Monday-Morning Executive Checklist

AI visibility should not be delegated solely to the web or SEO team. It sits at the intersection of distribution, brand, product, communications, data governance, and customer acquisition. Three questions can quickly reveal whether a carrier is measuring the new risk:

  • "Are we measuring our Share of Model against core competitors—or still relying only on traffic and click-through metrics?" A conventional dashboard cannot show whether a carrier is retrieved, recommended, or placed near the top of an AI-generated answer. Measurement should separate reach, recommendation, prominence, citation influence, and performance by engine and product line.
  • "Is our public-facing underwriting appetite and product information explicitly formatted for machine consumption?" Making distribution information accessible to human agents is no longer sufficient. Public content should use consistent entities, clear eligibility language, current product definitions, and structured relationships that answer systems can reliably interpret.
  • "What is our strategy for building independent digital authority?" Owned content remains necessary, but it is not enough. Carriers need a deliberate evidence strategy across regulatory sources, respected industry publications, analyst coverage, partner ecosystems, and other credible third-party environments.
A New Competitive Layer

AI answer engines are not replacing every existing channel. They are adding a new layer to insurance discovery and consideration—one that can reshape which carriers enter the shortlist before a prospect visits a website, contacts an agent, or begins a quote.

Scale will remain an asset in property and casualty insurance. But scale must now be translated into machine-legible product information, visible recommendation strength, and independently supported authority. The carriers that win this layer will not simply be the ones with the largest balance sheets. They will be the ones whose expertise, appetite, and credibility are legible to the systems assembling the decision set.

Research note: The Brainpan.AI Insurance AIVI is an organic-only benchmark. Paid placements were identified and excluded from organic scoring. The composite weights Share of Model at 35%, recommendation strength at 25%, position weighting at 20%, citation influence at 15%, and Top-3 rate at 5%. Results represent a controlled Q2 2026 prompt sample and should be interpreted as a visibility benchmark, not as proof of revenue, quote, CAC, or policy impact.

Smart Glasses Transform Insurance Claims, Inspections

Smart glasses are standardizing insurance inspections through real-time documentation and AI-guided workflows that improve transparency and reduce claim processing delays.

Transform Insurance Claims and Inspections

One of the greatest challenges facing insurers is making sure that every claim is documented consistently, regardless of who is performing the inspection or where it takes place. Smart glasses offer a clear path to standardizing this process by relaying information, guidance, and documentation tools directly within the wearer's field of view.

Rather than relying solely on handwritten notes, memory, or photos taken after an inspection, smart glasses enable adjusters and field representatives to capture POV evidence in real time while following predefined inspection workflows. Step-by-step prompts, often oral, help ensure that required photographs, measurements, and observations are collected in the same order and according to the same standards across every inspection.

The result is greater transparency for insurers, policyholders, and auditors alike. Claims files become more complete, inspection procedures become more repeatable, and documentation is captured as events occur rather than reconstructed later. This not only improves confidence in claim decisions but also creates a stronger evidentiary record should questions arise later in the claims process.

As AI capabilities continue to mature, AI smart glasses can also assist by identifying missing documentation, recognizing objects or damage patterns, and helping ensure that inspections meet established company guidelines before they are submitted.

Is it possible that AI-enabled remote assessments can reduce the need for adjusters to travel on-site? If so, could this help lower costs or improve overall response times?

In many situations, yes. While some claims will always require an experienced adjuster to visit a site in person, smart glasses make it increasingly practical to conduct guided remote assessments for a wide range of property, vehicle, and equipment claims.

Using a live video connection, a policyholder, contractor, or local representative wearing smart glasses can share a first-person view with an adjuster located anywhere in the country. The adjuster can observe conditions in real time, ask questions, request additional views, and guide the inspection without the delays associated with scheduling travel.

This approach offers several advantages. It can significantly reduce travel time and associated costs, accelerate response following widespread events such as severe storms or natural disasters, and allow experienced adjusters to assist more customers each day. It also improves access to expertise in secure, remote, or difficult-to-reach locations where specialized personnel may not be immediately available.

Faster assessments often translate into faster claims decisions, helping policyholders begin repairs sooner while enabling insurers to manage resources more efficiently during periods of high claim volume.

Can smart glasses better provide guidance to policyholders when resolving claims or billing issues?

Smart glasses have the potential to transform customer interactions from reactive conversations into guided experiences.

Rather than describing damage over the phone or attempting to follow written instructions, policyholders can receive visual guidance while completing important tasks. AI-generated prompts or remote experts can direct them to photograph specific areas, locate serial numbers, inspect equipment safely, or verify documentation without leaving the inspection process.

This guidance helps reduce misunderstandings while making the experience less stressful for customers who may be navigating an insurance claim for the first time.

The same capabilities can extend beyond claims. Customer service representatives may use smart glasses during virtual support sessions to help policyholders understand equipment, review billing questions, or verify information required to resolve an issue more efficiently. By providing contextual information directly within the user's field of view, smart glasses make complex interactions easier to complete while reducing the need for repeated follow-up calls.

How can smart glasses create a more consistent experience to guide policyholders through the documentation process when building claims?

Incomplete documentation remains one of the most common reasons claims require additional review or follow-up. While wearing smart glasses, users can be guided through a structured documentation process from beginning to end.

Instead of expecting policyholders to determine which photos to take or which details are important, the system can provide step-by-step instructions tailored to the type of claim being filed. Users can be prompted to capture specific rooms, damaged assets, identification numbers, receipts, or supporting evidence before moving to the next step.

Because the guidance is delivered in real time, the likelihood of missing critical information is significantly reduced. AI can also identify gaps in the documentation, recognize whether required images have been captured, and recommend additional photos when necessary.

For insurers, this creates a more standardized claims package regardless of who submits it. For customers, it reduces uncertainty and increases confidence that the necessary information has been provided the first time, helping claims move through the review process more quickly.

What's the hidden benefit of the insurance industry beginning to adopt smart glasses, and why is it happening now?

The most significant benefit may not be the technology itself—it is the ability to capture data and make it available anywhere.

Insurance organizations face continuing challenges associated with workforce transitions, increasing claim complexity, and rising customer expectations. Smart glasses enable experienced adjusters to extend their knowledge beyond physical travel by supporting multiple inspections remotely, mentoring less experienced personnel, and guiding policyholders through complex situations from virtually any location.

At the same time, artificial intelligence is making these systems increasingly valuable. AI can assist with documentation, recognize objects and damage, summarize inspections, retrieve policy information, and provide contextual recommendations without interrupting the inspection process. Together, AI and smart glasses create a powerful platform that augments human expertise rather than replacing it.

For the insurance industry, the opportunity extends beyond operational efficiency. Smart glasses have the potential to improve consistency, strengthen documentation, reduce unnecessary travel, accelerate claims resolution, and deliver a more transparent and supportive experience for policyholders. As insurers continue to seek ways to improve both customer satisfaction and operational performance, AI smart glasses are emerging as a practical technology capable of advancing both objectives simultaneously.

With so many smart glasses flooding the market, which is the right choice for insurers?

Not all smart glasses are designed for the same purpose. While consumer AI glasses like Ray-Ban Stories, Virtue, and Xreal have generated significant attention for features like voice assistants, messaging, and media capture, insurance organizations require a very different set of capabilities. Claims assessments, inspections, and customer interactions demand devices that are built for reliability, security, and extended professional use.

Enterprise smart glasses, such as the Vuzix M400, are specifically engineered for these environments. They offer extended-wear battery life, hands-free operation, high-quality cameras, and displays that remain visible in a wide range of lighting conditions. Just as importantly, they integrate with enterprise software platforms, support secure device management, and can be deployed and updated across large organizations.

For insurance professionals, this means adjusters can access claims information, inspection checklists, policy details, and remote expert assistance without interrupting their workflow or reaching for another device. Enterprise platforms also support compliance requirements through encrypted communications, secure authentication, and centralized IT management—capabilities that are often essential when handling sensitive customer information.

Durability is another important consideration. Field adjusters routinely work in challenging environments, including construction sites, disaster areas, industrial facilities, and severe weather conditions. Enterprise smart glasses are designed to withstand these demanding settings while delivering consistent performance throughout a full workday.

Perhaps the most important distinction is purpose. Consumer smart glasses are primarily designed to enhance everyday personal experiences, while enterprise smart glasses are built to improve business processes. In insurance, success depends on accurate documentation, standardized inspections, secure data handling, and efficient collaboration between policyholders, adjusters, and remote experts. Enterprise smart glasses are purpose-built to support those objectives.

As AI capabilities continue to evolve, the most valuable deployments in insurance will likely combine enterprise-grade hardware with intelligent software that assists users in documenting claims, identifying missing information, guiding inspections, and connecting field personnel with subject matter experts. Choosing a platform designed for professional workflows ensures insurers can take advantage of these innovations while meeting the security, reliability, and scalability requirements of the modern enterprise.


Matt Margolis

Profile picture for user MattMargolis

Matt Margolis

Matt Margolis is VP of business development and strategic relationships at Vuzix. 

Prior to Vuzix, he spent more than 15 years in corporate finance in a variety of roles. 

He holds a bachelor of science degree in business administration from Babson College.

R&W Insurance Deserves a Closer Look

Representations and warranties insurance offers block reinsurance buyers and sellers faster closings, cleaner exits and stronger protection at reasonable cost.

R&W Insurance Gains

In the world of mergers and acquisitions, representations and warranties (R&W) insurance has become a near-standard tool for managing transactional risk. Buyers and sellers across industries routinely use these policies to bridge gaps in negotiation, allocate liability, and move deals to the finish line with greater confidence.

Yet in the reinsurance sector, specifically within large and complex block transactions, R&W insurance has been conspicuously absent from the conversation. As one transactional attorney puts it, a block reinsurance deal is functionally "like an asset deal but in the insurance space."

It's a missed opportunity, leaving significant value on the table for both ceding insurers and reinsurers.

A Tool That Has Been Hiding in Plain Sight

Block reinsurance transactions carry a unique set of risks. Whether the deal involves a loss portfolio transfer, a full novation of policy liabilities or a multibillion-dollar block of long-dated, asset intensive life or annuity liabilities, both the ceding company and the assuming reinsurer must navigate a unique set of representations about the underlying book of business. Such matters can be further complicated if the block reinsurance transaction also provides for a transfer of a policy administration platform to the reinsurer, thus requiring additional representations about the platform. These representations typically cover the accuracy of financial statements, methodology for computing reserves, the validity of policy data, regulatory compliance, and a host of other material facts that inform the economics of the deal.

For a ceding insurer, a fundamental motivation for entering a block deal is to achieve certainty and finality. That goal is undermined when the cedant is saddled with long-tail indemnity obligations post-closing. This is precisely the friction point R&W insurance is designed to solve. It allows the ceding insurer to achieve a 'clean exit' with no significant post-closing obligations with respect to inaccurate R&Ws (outside of fraud) while the assuming reinsurer receives meaningful financial protection.

Despite this complexity, R&W insurance has traditionally not been a feature of block transactions, historically relying instead on traditional risk allocation mechanisms. These alternatives, however, have significant downsides:

  • A cedant indemnity can lead to protracted and contentious negotiations over the drafting of R&Ws and the size and survival period of the indemnity itself. This not only delays closing but can sour the post-closing relationship if a claim arises. Post-closing relationships are particularly important in reinsurance transactions where, even though the economics of the block are being transferred, the parties will remain tied together for the duration of the block of business.
  • Self-insuring the risk leaves the reinsurer holding all the exposure for losses from a breach, an atypical and often undesirable position.

The gap in R&W adoption has been fueled by a perception that reinsurance deals are lower risk or that R&W policies were not designed for their nuances. However, these views overlook the primary benefit: superior deal efficiency and a cleaner allocation of risk for all parties.

Speed, Simplicity and Reasonable Cost

For those involved in block transactions, the practical benefits of R&W insurance are compelling and worth serious consideration.

One of the most attractive features is the speed at which coverage can be bound. Block transactions often operate on tight timelines, particularly when they are driven by regulatory deadlines, fiscal year-end targets, or strategic portfolio management objectives. R&W policies can typically be bound in a matter of weeks, and in some cases even faster, once the underwriting process is underway. This timeline aligns well with the pace at which many deals need to close.

Beyond speed, R&W insurance can simplify the negotiation process between the parties. In any transaction, the allocation of risk around representations and warranties can become one of the most contentious and time-consuming points of discussion. The ceding company wants to limit its post-closing exposure, while the assuming reinsurer wants robust protections in case the underlying information relied upon when entering into the transaction turns out to be different from what was represented.

When an R&W policy is in place, much of that friction is removed. The policy effectively backstops the representations, giving the assuming reinsurer confidence that it has recourse in the event of a breach, while simultaneously allowing the ceding company to reduce or eliminate its indemnity obligations. The result is a cleaner, faster negotiation with fewer sticking points.

While major indemnity claims are infrequent, industry data shows that roughly 20% of R&W policies have claims submitted. This suggests that buyers are more willing or able (e.g., because a broader suite of representations are made) to seek recourse from an insurer than from a counterparty, making the protection more practical. In this context, that means preserving the commercial relationship between the cedant and reinsurer, turning a potential dispute into an unemotional claim against the R&W insurer with minimal adverse impact on the parties' continuing relationship.

Cost is another consideration that often surprises parties who are new to the product. Premiums for R&W insurance in the current market are reasonable and generally in line with what organizations pay for other financial and transactional insurance products. For example, in a block deal with a $500 million ceding commission, a customary 15% policy limit ($75 million) would cost approximately $2.25 million - $3 million in premium (i.e., a 3 - 4% rate-on-line).

There is also an important qualitative benefit that is easy to overlook. The presence of R&W insurance can signal to both parties that the transaction has been conducted with a high degree of diligence and good faith. The underwriting process for an R&W policy involves a thorough review of the deal's representations, the underlying data, and the due diligence that has been performed. This independent layer of scrutiny can increase all parties' confidence in the integrity of the transaction.

Placing the Policy: What to Expect

Mechanically, crafting an R&W policy for a block deal is very similar to a standard M&A transaction. The underwriting process involves the vetting of the reinsurer's due diligence. Although there may be less detailed third-party due diligence reports on reinsurance transactions than on corporate M&A, so long as appropriate levels of due diligence are conducted in light of the scope of the representations and warranties being insured, fulsome coverage will be available.

However, there are unique aspects to consider. For example, certain representations around actuarial data accuracy are notoriously difficult to insure. Insurers are not in the business of guaranteeing reserves. Therefore, the "specified data rep" will be heavily scrutinized and may be knowledge qualified or excluded depending on the specifics of the transaction and supporting diligence information and sufficiency of reserves is likely to be excluded from coverage. An experienced broker and legal advisor can help navigate these nuances to secure the broadest possible coverage.

Looking Ahead

With the uptick in block deals, the demand for tools that reduce transactional risk and accelerate deal timelines will only grow. R&W insurance is well positioned to meet that demand, offering a practical, affordable, and efficient solution that more reinsurance professionals should have in their toolkit. For those considering their next block transaction, exploring how to leverage R&W insurance most effectively could be one of the most valuable conversations to have before the deal gets underway.

12 AI Deployment Myths Debunked

Organizations rushing to deploy AI face a widening gap between pilot success and production value, driven by persistent misconceptions about capability versus application.

Deployment

It doesn't matter how beautiful your theory is, it doesn't matter how smart you are. If it doesn't agree with experiment, it's wrong. - Richard P. Feynman

Myths, Evidence and Truth

The explosive growth of generative and agentic AI has provided unprecedented capability in the hands of businesses. The associated narrative of what could be achieved with that capability has created amplified levels of hype. Driven by a clear fear of missing out, industries are initiating pilots that attempt to reimagine existing business processes through the addition of AI.

AI is increasingly being positioned as a foundational technology, with the potential to usher in a civilizational shift in how individuals think, work, create, consume information, and participate in the economy. Generative and agentic AI are now able to perform tasks that were previously considered uniquely human, including producing content, writing software, analyzing information, supporting decision-making, and acting with a degree of autonomy. The capabilities are, by any measure, both expansive and bewildering, as what was once considered impossible is now a reality.

Companies no longer see AI adoption as an elective. It is increasingly seen as critical to business growth. The focus is now shifting from capability to application, experimentation to deployment, and technical feasibility to economic value. In this transition, organizations are facing a harder challenge in translating available capabilities into sustainable business outcomes. The widening gap between expectation and realized value has begun to unravel a set of myths.

The usage of AI can be classified into two categories: AI for IT and AI for business. The core objective of AI for IT is to apply these technologies to build, enhance, or optimize technical systems. The primary users in this context are those involved in the software development lifecycle, including activities such as defining business requirements, development, quality assurance, production support, and related functions. In contrast, the core objective of AI for business is to improve decision-making, enhance customer service, and drive economic outcomes. The primary users are executives, managers, and people in operations engaged in both front-office and back-office functions across the process value chain.

While AI for IT demonstrates measurable progress, AI for business remains largely restricted to what can be described as pilot purgatory. This pattern is driven by factors such as escalating operational expenses, integration issues, data quality challenges, change management issues, and scalability challenges. Both pilot purgatory and post-deployment disillusionment can be traced back to a shared set of myths that shape how organizations approach AI adoption. While multiple such misconceptions exist, this article focuses specifically on 12 myths associated with the deployment of AI solutions in business contexts.

01. Unstructured text means Generative AI

The basis for this myth is the impressive, demonstrated capability of generative AI to understand, interpret, summarize, and generate content from unstructured text. This has led to a general perception that generative AI is the default solution for tasks involving unstructured information. Such a technology-centric conclusion assumes that input determines the choice of solution. While unstructured text is an important input characteristic, it is not a justifiable technological requirement to use generative AI or a reason to avoid it.

The real solution determinant is always the nature of the task being performed. Each task has different requirements in terms of accuracy, explainability, risk tolerance, and economic viability. For instance, within the insurance claims process, the extraction of claim data from First Notice of Loss documents is an information extraction problem that can be addressed using OCR, entity extraction, and document processing techniques. The classification of claims into loss categories represents a classification problem, for which rules engines or machine learning models are better suited. Coverage determination, on the other hand, is fundamentally a policy interpretation and rule application problem, which is commonly addressed through deterministic rule engines.

02. Select a single model and build systems around it

Many organizations approach generative AI adoption through a model-centric lens, where the sequence begins with selecting a model, followed by training, and then integration into software systems. This approach prioritizes building infrastructure around a single model, rather than focusing on business outcomes. The origin of this view can be traced to traditional machine learning practices, where model development remained the most important task.

In the business landscape, specific success stories of flagship models are often overgeneralized to all use cases. This leads to an assumption that a single model can address a wide range of business needs. In practice, performance varies based on the nature of the task, the characteristics of the data, and the operating context. This results in failures when these conditions change. There is also a tendency to treat model selection as the primary source of risk, whereas actual outcomes are more dependent on data quality, system integration, and alignment with workflow. Even powerful models fail in production environments due to weaknesses in supporting pipelines.

A model-centric approach remains appropriate in research settings or in scenarios involving the development of proprietary models. In enterprise environments, however, it proves less effective, as value realization is more strongly influenced by use case validation, data readiness, economic viability, and integration considerations.

03. Bigger models guarantee superior outcomes

The myth stems from the assumption that enterprise problems require maximal intelligence rather than fit-for-purpose outcomes. The myth is reinforced by visible breakthroughs from large frontier models that demonstrate high levels of reasoning, language fluency, and generality, leading to the extrapolated thinking that increasing model size translates directly into business value.

The assumption begins to break down when outcomes are decomposed into their actual drivers. Many business tasks are repetitive, well-defined, and bounded in scope. In these cases, prediction consistency and low latency matter more than depth of generalized reasoning. In such conditions, smaller models or even rule-based systems can outperform large models by delivering faster response times, lower cost per transaction, and higher predictability. Large models introduce higher computing costs, increased energy consumption, and added operational complexity, often without proportional performance gains even when the task complexity does not require their full capability.

While larger models provide superior performance in open-ended, complex, and unstructured problem settings, smaller or tailored systems often deliver superior outcomes in repetitive, narrow, and latency-sensitive enterprise workflows. The correct approach is to move from capability maximization to outcome optimization by aligning model choice with task characteristics, cost constraints, and operational requirements.

04. All work lies on an automation spectrum

The myth arises from early automation narratives and traditional AI maturity models that frame progress as a linear continuum from manual effort to full automation. With agentic AI, the continuum has extended further into autonomous decision-making. This thinking is convenient because many computational tasks have historically followed this path. As newer agentic AI systems demonstrate the capability to act and decide, organizations assume that moving toward full autonomy represents a natural progression.

The view relies on the notion that reducing or eliminating human involvement improves outcomes. The assumption collapses when work is decomposed by purpose rather than process. Organizations automate for reasons such as optimizing cost, quality, speed, customer outcomes, and risk. Automation and autonomy are mechanisms that influence these variables and often function as proxies rather than end goals. Further, any work can be decomposed into computational work or accountability work, based on purpose. Computational work, such as classification, extraction, prediction, and routing, is performed to transform, process, or analyze information, and becomes suitable for automation as model capability improves. In contrast, accountability work is performed to establish responsibility and ownership for decisions and their consequences and requires human authority irrespective of machine accuracy.

The automation spectrum applies only to computational work and does not extend to decisions where consequences must be owned by a person. Accountability work is governed by the need for responsibility and ownership and does not diminish with improved model performance.

05. Processes are the right unit of analysis for AI deployment decisions

The myth persists due to business operations being historically designed, measured, and optimized at the process level, making it the natural unit for strategic discussion. Even enterprise IT application transformation efforts, consulting frameworks, and governance models reinforce this view by framing change in terms of end-to-end processes, leading to an assumption that AI decisions should operate at the same level of abstraction.

This reflects the belief that processes represent homogeneous units with consistent characteristics and that a single technology approach can be applied uniformly across all steps within a process. Processes are collections of heterogeneous activities that require fundamentally different capabilities such as extraction, prediction, classification, and contextual reasoning. AI suitability must be evaluated at the activity level to determine feasibility and value. Applying a single AI strategy across an entire process either overengineers or misapplies automation in areas with different requirements and risks, and results in overfitting simple tasks and underperforming on more complex ones.

Any single process typically contains fundamentally distinct categories of work such as following rules, detecting patterns, interpreting information, coordinating actions, and exercising judgment. Given the accuracy, latency, compliance, and economic considerations involved, each requires a different approach, spanning rule engines, traditional machine learning, generative models, or human decision-making. While process-level evaluation is useful for scoping, AI decisions must be made at the activity level, and technology selection must align with the specific requirements of each step.

06. More data solves performance problems

The myth is anchored to traditional machine learning thinking, where larger labeled datasets often lead to measurable performance gains. This has created a persistent belief that the scale of data is the primary driver of model effectiveness.

The view is driven by three underlying propositions. One, model performance is primarily constrained by data quantity. Two, additional data always adds signal rather than noise. Three, enterprise failures stem from insufficient data rather than limitations in how knowledge is structured, maintained, and applied. The assumptions begin to break in enterprise settings where failures typically arise from poor knowledge quality rather than data scarcity. Adding more data does not resolve outdated procedures, conflicting policies, undocumented exceptions, or fragmented business rules.

Additional data improves performance only when it is relevant, consistent, and aligned with the task. Further, modern models often require less data to deliver meaningful value. Methods like RAG eliminate the need for large-scale retraining. In many cases, smaller, well-curated datasets or limited fine-tuning outperform large but poorly governed corpora.

07. If a model has sufficient data and knowledge, it can replace human expertise

The myth is rooted in the ability of modern AI models to access, synthesize, and communicate vast amounts of information with high levels of fluency. As models are trained on increasingly large corpora and supplemented with external knowledge sources, organizations tend to equate accumulated knowledge with expertise.

The claim reflects the belief that expertise can be reduced to knowledge retrieval and pattern matching, and that improved model performance directly translates to superior decision-making. The argument fails because expertise is not defined by knowledge alone but by how that knowledge is applied under constraints. Experts prioritize competing objectives, interpret ambiguous situations, and make trade-offs where no clearly correct answer exists. They define boundaries, handle exceptions, and remain accountable for outcomes in ways that models cannot replicate. Even when models achieve high accuracy on routine tasks, they do not assume responsibility for errors or resolve conflicts between competing goals such as risk, customer impact, and regulatory compliance.

In practice, models can replicate parts of expert knowledge and automate routine aspects of expertise, but they do not replace judgment, trade-off resolution, or accountability. The role of experts therefore shifts from execution to policy definition, oversight, boundary-setting, exception management, and failure evaluation. While this makes expertise less visible, it only becomes more critical.

08. Humans are the primary bottleneck in enterprise processes

The basis of the myth is the visible delays, inconsistencies, and perceived subjectivity in human-driven processes. It is reinforced from the success of earlier automation initiatives that reduced cycle time by eliminating manual steps. The emergence of generative and agentic AI further introduces a misplaced belief that intelligent systems can compensate for flawed process design and bypass human inefficiency without the need for structural correction.

The claim is anchored in the biased idea that inefficiency is driven primarily by human limitations rather than process design. It rests on the premise that processes are structurally sound and require only faster execution. The assumption does not hold as enterprise processes can be internally inconsistent, redundant, or poorly defined. AI systems inherit the same structural inefficiencies, amplify inconsistencies across process steps, and introduce additional risks when acting on ambiguous or conflicting inputs.

Humans act as bottlenecks only when processes are well-designed, but execution is the limiting factor. However, when the processes are inherently flawed, intelligent systems do not eliminate inefficiency, they accelerate it instead. Structural correction, such as process redesign, simplification, and clarification of decision boundaries, must precede automation and agentic deployment.

09. Human-in-the-Loop by Default Ensures Safety and Control

The myth is derived from traditional control models such as maker–checker frameworks, where experienced humans validated outputs produced by others. This is further reinforced by early AI governance approaches that successfully positioned human review as the ultimate safety net. Even as AI systems become more capable, the same logic is being extended, with the expectation that placing a human checkpoint will compensate for model limitations and ensure safe outcomes.

The claim propagates the anthropocentric perspective that humans reviewing AI outputs have sufficient context, expertise, attention, and incentives to detect errors made by intelligent systems in a consistent manner. It further extends to the belief that review quality remains stable under scale, and that human judgment can neutralize model errors without being influenced by them. The assumptions collapse under real operating conditions. Human reviewers frequently exhibit automation bias, and excessive reliance on AI outputs due to their fluency or perceived authority. As workload increases, oversight degrades due to cognitive overload, fatigue, and loss of situational awareness. Unlike traditional maker–checker models where expertise is built through experience, AI-era checkers are often required to validate outputs generated by systems whose reasoning they cannot fully understand. This results in superficial checks and rubber-stamping behavior, where the presence of a human does not materially improve correctness.

Human involvement improves safety not by default, but only when it is consciously and carefully designed to account for all failure modes, with sufficient context, tooling, incentives, and controlled workload.

10. The primary source of risk is the model

The myth originates from exaggerated narratives around model failures such as hallucinations and bias. To stay safe, organizations tend to concentrate on model selection and evaluation as the central risk management activities.

The claim reflects the belief that AI system behavior is determined only by the model and that all risks can be materially reduced by improving model quality. It positions other factors such as prompts, workflows, controls, and integrations as secondary drivers of outcomes. The assumption does not hold because most enterprise AI systems are rarely standalone systems. The secondary drivers determine how the model is used and the actions that follow. In real implementations, risk is not concentrated in the model but distributed across the system.

The model is just one component of risk, and improving the model addresses only a subset of risks. Organizations that focus excessively on model evaluation while underinvesting in process design and control mechanisms often experience suboptimal outcomes.

11. Success in pilots or proofs-of-concept predicts production success

The myth is shaped by the fact that pilots consistently show strong performance, which creates the belief that demonstrated capability will translate directly into business impact. The claim focuses only on the specific use case or the problem being tested and treats all other factors as representative of real operational conditions. It is further reinforced by the view that any challenge in production can be addressed once the capability of the model to solve the business problem is established.

This fails in real-world conditions, as pilots deliberately exclude the most challenging parts of enterprise reality. They operate on curated data, controlled and optimized workflows, limited edge cases, and dedicated resources. They operate in test environments that do not require integration with legacy systems or exposure to fragmented data architectures and inconsistent business rules. Production environments introduce constraints that materially affect system behavior. As a result, systems that perform at high accuracy in pilots significantly degrade in production due to systemic factors rather than model performance.

Pilot success demonstrates technical feasibility not operational viability. Real production success depends on operating model, process design, data quality, and governance integration, rather than model capability alone.

12. AI implementation is primarily a technology project

The myth is a consequence of how AI implementation projects are structured and executed. AI is primarily introduced through tools and platforms, making the technology layer more visible. The surrounding organizational work remains implicit, which leads to the belief that implementing AI is comparable to historical IT programs delivered as standalone technology initiatives. The claim is constructed on the premise that existing processes, roles, and workflows are structurally sound, and that AI can be applied without requiring redesign. The people, governance, and operating models are expected to adapt once the system is deployed. It further extends to the belief that any friction can be addressed by improving or fine-tuning the model.

The belief crumbles in enterprise settings, as AI fundamentally changes how work is performed. Most organizational outputs are deterministic, and incorporating probabilistic AI systems requires process redesign. Workflows must adjust to handle exceptions and ambiguity. Business roles shift accordingly from execution to supervision, validation, and policy definition. Failures are often driven by poorly defined processes, unclear ownership, weak governance structures, and fragmented operating models. These issues cannot be resolved merely by increasing model capacity or fine-tuning. Organizations must introduce new governance structures for accountability and risk control. Ownership boundaries need to be redefined to reflect machine involvement in decisions. If these aspects are not put in place, the system either underperforms or leads to the introduction of new risks. In theory, implementing AI may appear similar to a traditional IT program. In practice, however, it is a cross-functional transformation effort rather than an isolated technology deployment.

Looking through the lens of practicality

To navigate these myths and layers of hype, organizations must evaluate AI through the lens of operational conditions. Many deployment failures are driven by equating technological capability with deployment necessity, confusing assistance with accountability, and interpreting pilot success as evidence of production readiness.

Correcting these misconceptions requires shifting the unit of analysis from the process level to the activity level and adopting simplicity as a design principle. As each additional layer of complexity introduces new failure modes, it is important to recognize that human judgment remains essential at every step where accountability, trade-offs, and consequence management are required. Governance must be integrated into system design rather than positioned as an optional control layer within the escalation pathway.

AI systems rarely fail only due to lack of model capability. They fail when organizations misclassify the nature of work, extend automation into domains requiring accountability, and deploy technology without redesigning the surrounding systems.

Key Decisions When Deploying AI Claims Triage

Deploying AI in claims triage requires conservative accuracy thresholds and clear escalation boundaries to avoid regulatory exposure and customer dissatisfaction.

AI Claims Triage

Claims handling is one of the most visible cost lines in insurance. Industry estimates consistently place 70% to 80% of claims handling costs inside routine, repeatable processes: status inquiries, documentation requests, coverage confirmations, first-notice-of-loss intake. These are the categories that make the AI business case straightforward to build and difficult to execute without hurting accuracy.

Most insurer AI triage deployments begin with a proof of concept on controlled test data. What they encounter in production is a different environment, with a different risk profile, and different failure modes. Three design decisions determine whether the transition from pilot to live operation succeeds or stalls.

The Claims Categories Ready for AI Triage (and the Ones That Are Not)

The categories that perform reliably in production share a characteristic: the resolution requires accurate information retrieval and a rule-based decision, not adjuster judgment.

First-notice-of-loss intake for standard peril types (vehicle collision, water damage, property theft) follows a structured data-collection process that maps cleanly to what AI agents do well. The agent gathers required fields, confirms coverage against the policy record, generates a claim reference, and routes to the appropriate handling queue. Intake time drops significantly with AI. Early-stage accuracy is high when the agent has direct, live access to the policy management system.

Policy status and coverage inquiries are a second reliable category. Policyholders and brokers need clear, accurate answers about what is and is not covered under a specific policy. These queries have a deterministic answer that the AI can retrieve from the policy record and communicate without ambiguity. When it does so accurately and immediately, satisfaction scores on this category improve, and the insurer avoids the misquote risk that comes from a rushed human response during peak volume.

Documentation status updates on open claims, whether a repair estimate has been received, whether a payment has been processed, where a claim sits in the workflow are the third reliable category. These interactions are high in volume and low in complexity. They consume significant adjuster time. When the agent handles them with real-time access to the claims management system, adjusters recover that time for interactions that actually require their expertise.

The categories that are not ready are those that require genuine coverage interpretation, multi-party coordination, or circumstances the policy language does not address clearly. Deploying AI on these categories in an early implementation is where most accuracy problems originate.

The Accuracy Threshold That Protects Both CSAT and Regulatory Standing

In most service sectors, a triage system that resolves 70% of queries correctly in the first months of deployment and improves from there is considered a successful pilot. Insurance applies a different standard, for two reasons that are specific to the sector.

First, inaccurate coverage information given to a policyholder at claim time creates both a CSAT problem and a potential errors-and-omissions exposure. A claimant told their loss is covered and later finding it is not does not experience this as a minor service inconvenience. Second, insurance regulators in most markets require that specific communications meet accuracy and disclosure standards that a misconfigured AI agent can fail to meet without the insurer knowing until a complaint surfaces.

The practical consequence is that the confidence threshold below which the AI escalates rather than responds must be set higher in insurance than in most service environments. A system that generates a coverage answer when its confidence score is moderate is operationally acceptable in retail support. It is not acceptable in insurance, because the cost of a wrong answer is asymmetric: a small number of incorrect coverage statements create regulatory and customer relationship problems that far outweigh the efficiency gains across the cases the system handled correctly.

Define the escalation trigger conservatively in the early deployment. A narrower AI scope with a high accuracy rate builds the internal confidence and operational track record needed to expand scope responsibly. A wide scope with a moderate accuracy rate generates precisely the incidents that slow adoption and invite regulatory scrutiny.

What Production Looks Like After the Proof of Concept

Proof-of-concept environments test the happy path. Production environments test the edge, at volume, across the full range of policy types and peril circumstances the carrier actually handles.

Three failure modes appear consistently in live insurance triage deployments.

The first is policy variant coverage. A claimant's policy may carry endorsements, exclusions, or carrier-specific modifications that are not reflected in the standard coverage language the agent was trained on. Without direct access to the full, structured policy record, not a summary, the agent falls back to standard language and produces an answer that is accurate for the base product and wrong for that policyholder's specific terms.

The second is multi-party claims. In a commercial property claim or a liability claim involving multiple parties, the intake process requires collecting different information from parties with different roles and interests. AI agents calibrated for personal lines intake do not handle this correctly without specific configuration, and the errors they generate in multi-party scenarios tend to be the most visible ones.

The third is mid-process handoff quality. When a claim requires escalation from the AI to a human adjuster, what the adjuster receives determines whether the customer experience continues or restarts. A handoff record that captures the full interaction context, what the agent understood, what was collected, and what was confirmed allows the adjuster to continue from where the agent stopped. A handoff that returns the claimant to the beginning of the intake process generates the complaint pattern that regulatory affairs teams track.

Keeping Adjusters in Control of What Matters

The framing that produces both operational results and staff adoption is direct: AI handles information retrieval and routine intake so adjusters spend their time on the interactions that require professional judgment, relationship management, and expertise. Not as a threat to the role. As a description of what the role becomes.

The adjusters who see AI triage succeed in their operation are consistently the ones who were involved in defining where the escalation boundary sits. That line is a professional judgment, not only a technical parameter. Involving the claims team in setting it and giving them a clear override path when the system routes something they believe it should not produce better-calibrated systems and faster adoption than any training program.

The insurers getting durable results from AI claims triage are not the ones that deployed the most capable model. They are the ones that were clearest about where human judgment is irreplaceable and built their system around that boundary from the first day of deployment.


Ralf Klein

Profile picture for user RalfKlein

Ralf Klein

Ralf Klein is the founder of Triad, an operational AI agency that builds and deploys AI agents for organizations handling high volumes of claims, service requests, and maintenance tickets. 

The AI-Informed Homeowner Is Already Here

Homeowners are using AI to research coverage and compare policies before meeting agents, fundamentally reshaping the insurance buying process.

homeowners

A few years ago, a homeowner walking into an insurance conversation was a lot like a patient walking into a doctor's office. They knew something was wrong (or at least expensive), but they mostly deferred to the expert. The agent explained coverage options, translated policy language, and guided the decision. The homeowner nodded along and signed.

That dynamic is breaking down. A growing number of homeowners are doing research with AI before they ever talk to a human agent. According to the 2026 Hippo Housepower Report, 54% of homeowners plan to use AI to check whether they're paying a fair price, 48% to compare providers and policies, and 40% to better understand their policy.

Much like patients who Google their symptoms before showing up at the clinic, homeowners may not have the diagnosis right, but they have the vocabulary. They're arriving with more context, more specific questions, and higher expectations for speed and transparency than they had even two years ago.

The natural question is how far this goes. If consumers are already using AI to research coverage and compare carriers, will AI eventually handle the entire transaction? Some agencies are already building toward that, but the industry isn't ready for a fully autonomous buying experience. The regulatory, financial, and psychological infrastructure to support it doesn't exist yet.

The last mile stays human

Even with all of that AI-assisted research, the final purchasing step will remain a human interaction for a long time. When it comes to big purchases or signing on the dotted line, consumers want to be able to look someone in the eye. They want a person to put an arm around their shoulder and say, "Yes, this is the right policy. You're covered."

Think of it like booking a complex international trip. Most people will spend hours researching flights, hotels, and visa requirements online. But when the itinerary gets complicated, plenty of people still pick up the phone and call a travel agent for that final confirmation. The AI does the legwork, but a human closes the loop.

Beyond that psychological barrier is the legal one. In most states, core insurance functions like binding coverage, providing advice, and serving as the agent of record are non-delegable duties that require a licensed human. AI sophistication won't change that in the near term. 

The National Association of Insurance Commissioners (NAIC) adds a regulatory layer. As of early 2026, 25 jurisdictions have adopted its Model Bulletin on the use of AI systems by insurers, and another four states—California, Colorado, New York, and Texas—have their own insurance-specific regulations. 

On top of that, payment companies are still uneasy about sensitive credit card or EFT information flowing through AI, even with tokenized digital wallets. Carriers also need to modernize the underlying technology stacks, data systems, and APIs that agents already rely on. Layering agentic capabilities onto outdated or unreliable infrastructure will only create more friction and make it harder for agents to trust the technology enough to use it.

Gen Z homeowners are already far more comfortable with AI in their insurance decisions than older cohorts. But for now, the human at the end of the buying process provides reassurance that AI cannot replicate at scale.

Who's liable when the AI agent gets it wrong?

Independent agents are already hiring technology companies to build AI chatbots that handle initial consumer conversations, run quotes, and present coverage options. The technology works. What's unresolved is who's responsible when that bot gets something wrong.

Let's say an agent deploys an AI tool built by a third-party vendor. That tool runs a quote, explains coverage, and presents a recommendation to a consumer. The consumer buys the policy. Six months later they file a claim, and the AI-recommended coverage had a gap.

The mistakes are easy to imagine. AI may draw attention to key coverages, but not that requirements and policy language vary by county, or that some carriers in a region build that coverage into the base policy while others exclude it entirely. It can look up a flood zone but misinterpret whether their property sits on the edge of one, or that the distinction can change based on drainage and slope. And replacement cost—one of the most important numbers in a homeowners policy—depends on regional labor rates, local building codes, and material costs that fluctuate with supply chains. An AI tool pulling from general data is likely to get that number wrong, or differently than an insurance company.

So who owns the gap? The tech company that built the bot? The agency that deployed it? Or is there a disclaimer at the bottom of the screen that says the onus is on the consumer? For human error, the answer is settled. Agents carry errors and omissions insurance for exactly this reason. None of that infrastructure exists yet for AI agents. These questions will get worked out in the courts, slowly, and until they do, anyone deploying consumer-facing AI is carrying a risk that's difficult to quantify and impossible to fully insure against.

The new visibility problem

If you're a carrier and you're not thinking about how AI-assisted shopping will affect your visibility to consumers, think about what happened with search engine optimization. Companies that ignored SEO a decade ago disappeared from Google results. They were invisible to the vast majority of consumers, regardless of the quality of their product. The same dynamic is starting to form with AI.

As more homeowners begin their insurance research with an AI tool, carriers that win will be the ones that are prepared for it, with clearer coverage language, accessible APIs for AI tools, and structured product information. The rest risk being left out of the conversation entirely.

The homeowner sitting across from an independent agent today is more informed and more specific in their questions than they were three years ago. AI is a big part of why. The industry's job is to meet consumers where they are and to be clear about where AI ends and experienced human judgment begins.

What Cyber Underwriting Is Missing

Cyber underwriting has become adept at measuring technology. The missing signal may be the condition of the organization responsible for keeping it secure.

Organizational Deterioration

Since the ransomware crunch of 2020, cyber underwriting has gotten steadily more external and more technical: attack-surface scans at quote, patching cadence wired into the catastrophe models, and third-party telemetry now feeding the major vendor platforms. Global cyber rates have kept falling through early 2026 even as claim frequency rises.

All of cyber underwriting measures the current state of technology. Almost none of it measures whether the organization behind those controls is deteriorating: losing the people who understand its systems, struggling through major organizational change, or cutting the resources needed to sustain operations.

Is that kind of operational strain visible from the outside and distinguishable from the ordinary noise any large company produces? To find out, we traced public signals in the year before three major breaches: TCS, CDK Global and Change Healthcare – plus a peer control study for TCS. In each case, the deterioration left a public, dated record months before the loss.

The signals are public posts: employee reviews on Glassdoor, AmbitionBox, Indeed and Blind, and practitioner and customer threads on Reddit. We ignored general dissatisfaction and looked for dated observations tied to identifiable roles, in four categories: organizational instability, security dysfunction, financial distress, service degradation.

The outsourcer

The connection is most direct at TCS, a services business where the workforce is the product it sells. Through 2025, it held an A on SecurityScorecard, a rating that spans everything from patching cadence to how exposed its people are to being targeted.

Across the 201 signals, the recurring themes were constant reorganization, experienced staff leaving faster than they were replaced, and people put on work they weren't equipped for. Four months before the M&S attack, a TCS consultant described being presented to clients as a cybersecurity analyst despite never having worked in that role. Months earlier, a SOC analyst listed "slow incident response" among his team's problems.

In April 2025, attackers called the IT helpdesk TCS had run for Marks & Spencer since 2018 and talked staff into a reset; M&S put the profit impact near £300 million. Jaguar Land Rover followed months later, at an estimated £1.9 billion cost to the UK economy. TCS ran IT there too, though the public record doesn't establish that its people were the ones socially engineered.

The obvious objection is that every Indian IT major generates this kind of noise. So we ran the same collection on Infosys, Wipro and HCLTech: 501 signals across the three, against TCS's 201. All four show reorganization noise. But security staff are about 8% of TCS's signals against roughly 3% at the nearest peers. While the baseline volume varies by firm, only TCS showed a concentration of security-role complaints describing problems within the security function itself.

The buyout

At CDK, the pressure came through ownership. Brookfield took the company private in 2022 in a deal backed by roughly $5.8 billion of debt, and public posts began documenting the operational consequences.

From June 2023 to the day before the attack, employees across engineering, support, sales and training described the same sequence: repeated layoffs, work shifted to the outsourcing partner Genpact, and the people who understood the systems walking out with each cut. A trainer who left in February 2024 traced it to the top: a 30% margin wasn't enough for the CEO, so he cut across the board to reach 40%. That same month, a director's advice to management consisted of three words: "stabilize the talent drain."

Security leadership also became harder to identify. David Hahn, CDK's first publicly identifiable CISO – a role the company first filled in 2020 – joined Ballistic Ventures as CISO-in-Residence in December 2022. We found no public evidence of a successor before the ransomware attack. Across dealership forums, users described repeated outages, with one writing during a July 2023 incident that the platform was "up for 3 minutes and then down for 30."

In June 2024, BlackSuit ransomware hit and froze nearly 15,000 dealerships, about $1 billion in dealer losses. CDK never disclosed the intrusion vector, so no causal link can be drawn. What the public record does show is that the organization operating those systems had been under visible operational pressure for a year beforehand.

The pattern is structural: across private-equity portfolios, where the incentives are the same, S-RM found 72% of firms had a serious cyber incident in their portfolio within three years. In February this year, Bloomberg reported on Ivanti, which Clearlake Capital had taken private. Cost-cutting there stripped out the engineers who understood the company's VPN code, and Chinese state hackers exploited the resulting flaws to reach US government and corporate networks. Some government and corporate buyers, Bloomberg reported, now factor private-equity ownership into how they assess security products. In the same report, Rob Leahy, former CIO of NASA's Goddard Space Flight Center, said ownership structure should be part of any product risk assessment: "Are they investing in the future or are they not?"

The rollup

Change Healthcare was assembled by serial acquisition and run for margin, where cost-cutting meant deferring integration. Optum, UnitedHealth's health-services arm, absorbed it in October 2022.

Across the 142 signals we collected from Change and its new parent, employees repeatedly described experienced staff leaving and the loss of institutional knowledge. One review summarized the effect as "letting the knowledge walk out the door." Another, posted in November 2023, three months before the breach, described acquired companies as "not integrated into network sometimes ever."

In February 2024, attackers got in through a single internet-facing Citrix portal with no multi-factor authentication (MFA). By the CEO's later congressional testimony, it ran on technology acquired in 2022 that had never been brought under the company's own MFA policy. The breach reached 192.7 million people, at a cost UnitedHealth put at $3.09 billion for 2024 alone, the largest healthcare data breach on record.

Change is one of three Optum acquisitions to have been breached since 2023; Solutran and Episource followed, the last hit twice, in 2023 and in 2025. Two years after the attack, UnitedHealth was still consolidating 18 acquired medical-record systems down to three. Acquisitiveness itself leaves a statistical trace: a 2025 study of 5,072 U.S. firms found the more a company acquires, the more breaches it experiences, the effect growing when acquirer and target come from different businesses.

Organizational deterioration is already familiar to cyber insurers. It appears in breach investigations, claims files and post-loss reviews, where staffing shortages, restructurings and operational strain often help explain how technical failures developed. By then, however, those signals are explanatory rather than predictive. The cases here suggest that some of the same patterns are visible months earlier in public operational data.

Three cases chosen for how they ended cannot establish predictive value on their own; that requires knowing how often the same signals appear at companies that never suffer a loss. The TCS peer comparison is a first attempt at that question.

Cyber underwriting has become increasingly sophisticated at measuring the state of the technology. Whether the organization behind those controls is changing in ways that affect cyber resilience is not yet part of how the risk is priced.

How to Accelerate Recovery From Floods

Bipartisan legislation would use federal mitigation funds to support parametric flood insurance, accelerating disaster recovery in underinsured communities.

flood

Forecasts suggest this year's hurricane season could bring lower than average storm activity. But disaster risk is not measured solely by the number of named storms.

It only takes one major flood to expose the vulnerabilities that persist across the US flood protection system. And increasingly, flood losses are not confined to coastal communities or storm surge alone. Flooding driven by heavy rainfall, overflowing rivers, and flash floods are increasingly affecting communities far beyond traditional flood zones, often in places where insurance take-up is low and financial resilience is limited.

This reality highlights an urgent policy challenge; America's flood protection gap continues to widen at a time when economic exposure is growing.

Flooding can happen almost anywhere, yet millions of American households and businesses remain uninsured or underinsured against flood risk. When disasters strike, the consequences extend well beyond individual property losses, which alone are already devastating. Delayed recovery affects local employers, municipal budgets, infrastructure systems, housing markets, and broader regional economic activity.

Insurance plays a critical role in helping individuals, businesses, and communities recover more quickly and reducing long-term economic disruption. Strong insurance participation supports financial stability after disasters, accelerates rebuilding, and reduces reliance on post-event federal assistance. It's an essential component of economic resilience for all Americans.

That's why Congress should advance the bipartisan Community Flood Resilience Act, introduced by Congressman Andrew Garbarino and Congressman Gregory Meeks.

The legislation reflects a pragmatic recognition that resilience requires both physical mitigation and financial preparedness. By allowing a portion of federal flood mitigation assistance funding to support community-based parametric flood insurance solutions, Congress is advancing a thoughtful public-private sector approach to disaster resilience.

This legislation does not replace the National Flood Insurance Program (NFIP). Instead, it acknowledges that public and private solutions can work together to expand protection, improve awareness, and strengthen recovery capabilities. In today's evolving risk environment, collaboration is essential.

Community-based parametric insurance provides funding when predefined conditions are met, such as measured rainfall levels, river heights, or other objective flood triggers. Because payments are tied to those triggers rather than lengthy loss-adjustment processes, communities can access funds much more quickly after a disaster. Faster access to funding can help local governments stabilize essential services, support small businesses, and assist vulnerable populations during the critical days immediately after flooding occurs.

Speed matters after disasters. Delays in recovery funding often translate into prolonged economic hardship for communities already under strain. Parametric insurance policies can deliver payments within 30 days, or less, when the funds are needed the most.

The legislation also emphasizes education, outreach, and transparency. Participating communities must describe how they promote flood insurance awareness, encourage mitigation efforts, and communicate clearly about how these products function alongside traditional coverage. These provisions recognize that resilience begins with understanding what's at risk.

The insurance industry has long played a foundational role in supporting economic growth and recovery following catastrophic events. As risks evolve, innovation in risk transfer and resilience financing will increasingly become important complements to infrastructure investment, stronger building standards, and disaster mitigation programs.

Public-private collaboration will be critical to narrowing the protection gap. Legislation like the Community Flood Resilience Act demonstrates how policymakers can encourage innovation while strengthening community preparedness and preserving the role of insurance in supporting economic resilience.

Resilience is built before disasters through smarter planning, stronger mitigation, and broader financial protection. Public policy that improves flood insurance participation and accelerates recovery better protects homes and businesses, and promotes the long-term economic stability of communities across the country.

As flood risk expands beyond traditional geographic boundaries, policymakers need tools that strengthen both physical resilience and financial preparedness. The Community Flood Resilience Act is a practical way to do both.


Adrian Hall

Profile picture for user AdrianHall

Adrian Hall

Adrian Hall is CEO US for Swiss Re Corporate Solutions.

He is also a member of the Swiss Re Corporate Solutions global executive committee and a board director for Swiss Re Corporate Solutions America Insurance.

Previously, he was the managing director & head, UK, Ireland, South Africa and EMEA Wholesale, and CEO & Chief, Agent Canada, for Swiss Re Corporate Solutions. An insurance industry veteran with over 30 years of experience, he has lived and worked across five continents.

Hall holds a bachelor of science degree in business from University of Wales, Swansea and a master’s certification in marketing leadership from York University, Schulich Business School, Canada.

Radical Efficiencies in Insurance

Aerial imaging provides near-real-time intelligence that takes cost out of claims, providing a blueprint for efficiency in other parts of the insurance industry. 

Interview

Paul Carroll

The insurance industry has long operated in a paper-driven, inefficient way, with only about 60 cents of every premium dollar going out in claims. Improving operational efficiency could help get more people insured while reducing costs—which is why we delve into the topic every year for ITL Focus. To start us off: How does Eagleview's technology make the claims process for property insurance more efficient than it has been historically?

Patrick Gill

Eagleview has been in existence for more than 25 years.  We started with government use cases such as tax assessment but quickly expanded to other industries such as insurance based on the notion that what works for government tax assessors likely also works for inspectors and appraisers of any type, including insurance claims use cases. We're flying airplanes with proprietary camera technology over the entire U.S. and large parts of Canada on a regular basis. We capture high-resolution imagery both with orthogonal—so, top-down—views, as well as views from each 45-degree angle. This enables us to build 3D models of properties. From that, you can extract measurements, study the roof condition, and analyze other attributes of a property.

One of Eagleview's most significant contributions to the insurance industry has been providing precise, independent, and objective property measurements. One of the big parts of the claim is the reconciliation between what the adjuster thinks needs to be done to repair a property and what the contractor or homeowner thinks. This frequently resulted in unnecessary disputes and inefficiencies—arguing over the size of a roof, for example, with people up there with competing tape measures coming up with different numbers. Eagleview created a standard that both contractors and insurance adjusters could agree on and made that go away.

There are plenty of other things to debate, but suddenly, the measurement portion of building a roof repair or roof replacement estimate went away. To your core thesis here, Eagleview has always been about trying to deliver operational efficiency into the insurance claims process.

How much detail you can have about a property before you have to physically roll out to it creates all kinds of opportunities for efficiency. Our capabilities have expanded well beyond measurements to include a broad range of property intelligence.

Our mantra is: How much better can you operate if you know more before you go? A lot of money is spent on third-party ladder assist companies going up and doing the tall and steep structures, for safety reasons and lots of other things. But if you don't know for sure what property is tall and steep, oftentimes you're sending out your own adjuster. If he gets out there, then realizes that it's tall or steep and then needs to order a third-party ladder assist, that costs time and maybe means another visit to the property—waste that can be eliminated if you can have that information upfront.

That's one example. Where we've been moving is: How much more data can we serve into the claims triage and routing process to make sure they're intelligently managed, with the right resources the first time for the cleanest, fastest, most efficient resolution?

Paul Carroll

I imagine that once a hailstorm hits an area and you fly a plane over it, aerial imagery can help insurers make decisions about the whole area and recovery process, beyond what they can know about individual houses. 

Patrick Gill

Resolution hasn't quite gotten to the point where you can see actual hail hits. We're almost there, but not quite. The long-term vision is straightforward. A huge hailstorm hits Colorado Springs, we quickly get a plane over the area, and then claims can be handled remotely.

But I'll tell you what the first phase in that direction is: There's a lot you can do by starting to integrate several different data sources to get to smarter expectations about the damage from that hailstorm in Colorado Springs.

There's weather data that, on its own, you're not going to make claims decisions on, but it's excellent input. What if you know the age of the roofs on all those properties that were likely hit? What if you knew the roof condition of each of those properties? All of a sudden, you can quickly assess the higher-risk properties, the ones that are most likely going to need to be addressed, versus the ones that may fall outside of scope and may be less likely to be a valid claim.

So you can categorize better what types of claims these are, which then gets back to who are the right people to go do the adjustment. If I know there was a storm with two-inch hail, and I know this group of properties has 20-year-old roofs, it may be more efficient to go ahead and write the roof replacement check right away and not send an expensive, experienced adjuster out there to do an assessment. Maybe send someone to grab some photos and confirm the situation.

We’re in an in-between state, but you can already be much smarter about what has likely happened than you could even three years ago based on the data.

Paul Carroll

The historical data you've accumulated, giving you multiple images of the same property over the years, has to help with claims assessment after a storm, right?

Patrick Gill

That's correct. In places where there's a lot of activity, whether it's hail or a hurricane, we have more looks at what's happened. When I mentioned roof age earlier, that's exactly how you determine it. We look back to find where there's been a significant change in that roof, then count forward to understand the roof's age.

We have a new AI product—I know everybody has a new AI product, but we have an agentic AI solution called Eagleview Horizon that is in early access mode with customers right now. It allows a claims leader to do exactly the type of thing you're asking. Show me all the older roofs in poor condition in the path of that particular storm so I can sort them into the proper workflow.

What would have been a data science project even a year ago—probably hard to fund internally and would have taken weeks to pull all the different data sources together—you can literally do in five to 10 minutes now.

Paul Carroll 

What about drones? Are they something Eagleview would do directly, or are you focused on collaborating with drone operators?

Patrick Gill

We have experimented with drones and operated a network of pilots but have decided not to provide that service ourselves. It's a complicated, messy thing to manage a pilot network.

Our focus is on building the capability to ingest imagery captured from drones and other aerial platforms, then applying our AI and damage detection models consistently across those data sources.

Paul Carroll

Looking ahead two or three years, what features do you hope to add?

Patrick Gill

The most exciting development is the pace at which the underlying technology continues to advance.

Flying over properties on a regular basis, you don’t just see changes in roof condition. You see changes like a new presence of a pool or the evolution of a particular property. These are very interesting to the insurance industry. They're also interesting to our large customer base in local county government—tax assessor's offices, but also 911 emergency services for understanding how you access a location.

On the underwriting side, obviously you could spot a negative change—the degradation in condition—but you could also see an improvement if there's more defensible space for wildfires, there's no more tree overhang. You can actively monitor the state of a property in a way that hasn't been available.

Insurance has dealt in static data. So the notion of change detection at scale is going to be, in my mind, game-changing in terms of how the insurance industry and other industries can understand what's going on in the real world.

Paul Carroll

One of the things I find interesting and exceptionally powerful, having covered information technology for decades, is that when you start wiring the world and collecting all kinds of data you find other uses for it. There's a company called Ting Labs that produces a device that you plug into your wall, and it detects electrical problems that could cause house fires. But they're also finding that they can detect problems in the grid, and they can let utilities know when there's an outage because a whole bunch of homes lose power at the same time. If power goes off in the winter, pipes may freeze, and you may have a flooding issue; they can alert people to that, as well. 

I can imagine all kinds of uses for the kinds of data you're collecting.

Patrick Gill

Today, you literally have to look at side-by-side images of the same property at different times to draw conclusions. The way computing power and AI have evolved, you can now do that without manual review, which means you can do it at scale and then feed that intelligence into other systems where insurance carriers are making decisions, so much more cleanly and easily.

We’re on the cusp of this all being in plain language and queryable. Claims managers will be able to get much, much more sophisticated about how they plan broadly. Carriers will be much, much smarter about what's going on in their book of business or in their preparation for a particular CAT event.

Getting back to your premise around how you drive operational efficiency, there's going to be substantial opportunities to improve efficiency.

Paul Carroll

Here’s hoping. 

This is great. Thanks, Patrick.


About Patrick Gill

Patrick Gill

Patrick Gill is Senior Vice President and General Manager of Insurance & Commercial Solutions at Eagleview where he is focused on expanding customer value and strengthening Eagleview's leadership across property intelligence markets.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

The Ghost in State Farm's Machine

State Farm's sweeping cuts to agent compensation signal how private equity thinking now shapes even mutual insurers' operating models.

Ghost in the Machine

State Farm just told 19,000 captive agents the deal has changed. Deferred compensation? Gone. Health benefits? Reduced. Renewal commissions? Squeezed in favor of new-business production.

State Farm is a policyholder-owned mutual—the largest in the country—not a private equity play. Yet the announcement reads like it came straight out of a KKR, Apollo, or Blackstone operating playbook.

For decades, State Farm's model rested on a simple premise: a book of business is not self-sustaining. It requires labor. Agents weren't just selling policies; they were maintaining them—fielding calls, resolving issues, retaining customers, spotting risks before they became claims. Renewal commissions weren't a bonus. They were the operating system.

But operating systems get deprecated.

Every generation redraws the line between labor and leverage, between what requires a human and what can be systematized. The real question isn't whether people add value. It's whether they add the same value they once did—and whether that value supports the same cost structure.

Seen through that lens, State Farm's move wasn't surprising. It was inevitable.

Three forces have been quietly closing in.

First, competition. Progressive and GEICO operate without an agent-heavy cost base. They built direct models—leaner, faster, less sentimental. As they gained share—Progressive recently passed State Farm as the top writer of auto policies in the US—State Farm was forced to respond.

Second, management migration. Over the past two decades, executives have moved through private equity portfolio companies, internalizing a shared language—almost a mantra—of efficiency, productivity, and return on capital. What was once distinctive to private equity is becoming simply how management thinks.

Third, AI. Service calls, billing questions, renewals, first notice of loss—tasks that once justified large workforces and long-tail commissions—are increasingly handled by software that doesn't sleep, doesn't churn, and declines in marginal cost over time.

This doesn't make human agents obsolete. It makes legacy compensation models obsolete.

Human value doesn't disappear, it concentrates in complex cases, edge scenarios, trust, judgment—the hard stuff. But the routine? The repeatable? The predictable? That's already slipping out of human hands.

The private equity approach asks a relentless question of every line item: if we were building this today, would we pay for it this way? That question is destabilizing inside legacy models, because once you ask it honestly, a lot of "strategic investments" start to look like habits. And habits, over time, get expensive.

So this isn't a story about private equity taking over State Farm. It's something more consequential: the normalization of a worldview private equity helped industrialize. Nothing is sacred—except the spreadsheet. Every cost is conditional. Yesterday's logic expires faster than anyone wants to admit.

Cost cutting is the easy part. Plenty of companies are doing that—and calling it strategy.

The harder move is what comes next: reinvesting those savings to build something better. Better experiences. Stronger capabilities. New forms of growth that justify the disruption.

In the end, the winners won't be those who simply get leaner. They'll be the ones who get smarter about where humans still matter—and ruthlessly disciplined about where they don't.

That's the real ghost in the machine.


Riv Arthur

Profile picture for user RivArthur

Riv Arthur

Riv Arthur is a business leader and technologist working in insurance, healthcare, and private equity.