Download

Advice for Insurers as Ransomware Evolves

Ransomware's evolution from organized supply chains to fragmented chaos is rewriting insurers' assumptions.

Hand Holding a USB Flash Drive with Key Drawn on it

Ransomware has always been a moving target but is now entering a period of volatility unlike anything we've seen before. Tactics are shifting rapidly, tools are becoming more sophisticated and more widely available, and the threat-actor landscape is splintering into a chaotic mix of groups, affiliates and opportunistic newcomers. For insurers, this fragmentation and instability is rewriting assumptions about predictability, frequency and severity.

To understand why ransomware feels more volatile than ever, it's important to start with how organized these operations once were. Historically, major threat groups behaved with a degree of predictability. Their operations had a clear methodology and often resembled a supply chain. One group identified or acquired a zero-day vulnerability; another specialized in gaining credentials and access to victims' networks; a ransomware group purchased that access and deployed their malware; and another entity handled negotiations, payment facilitation and hosting on data-leak sites. While criminal, these actors operated within consistent roles.

Today, that methodology and structure has fractured. Law-enforcement pressure, internal disputes and simple profit incentives have splintered once-dominant ransomware groups. Nowadays there is not just one geography or one group that's doing everything from start to finish. It's now a combination of parties. Coupled with this, their tools, particularly the ransomware variants themselves, have leaked into the wild or been deliberately sold off. As a result, sophisticated malware that was once tightly controlled is now available to operators with minimal skill. Cheaper, less advanced variants such as Dharma and Crysis proliferate broadly, while more refined strains like Akira or LockBit remain selectively distributed, but even those find their way to multiple groups.

This "plug-and-play" ecosystem means that a threat actor with little technical capability can now operate at a level previously reserved for elite cybercriminals. The result is a wave of attacks that are increasingly unpredictable in both frequency and quality. Some are clumsy and quickly detected, while others unfold with alarming precision.

At the same time, attackers have become far more agile once inside an environment. Earlier ransomware operations often unraveled when attackers encountered unexpected security controls. Today, threat actors pivot rapidly. If endpoint detection and response (EDR) tools block one path, adversaries switch tactics, attempt to disable protections or even infiltrate the security tools themselves.

In a recent Akira-related incident, adversaries gained access to a victim's SonicWall EDR environment, used it to disable protections across the entire network and maintained persistent access. A lesser threat actor would have been stopped at the first hurdle. Today's operators adapt with remarkable speed.

This agility is compounded by AI-driven malware development. Threat actors are now capable of generating malware tailored to a victim's specific security gaps. By feeding reconnaissance data into AI coding engines, attackers can produce bespoke code that evades detection. As a result, EDR tools lose some of their efficacy, and traditional antivirus can become entirely ineffective.

AI-generated phishing is also affecting attacker capability. Previously, many phishing attempts were identified by grammar and spelling errors. Today, threat actors can generate credible, fluent communications that mimic native language use, making social engineering exponentially harder to detect. The potential for automated scaling, for example one threat actor deploying hundreds or thousands of simultaneous phishing attempts, also poses a challenge.

While tools and execution are evolving, so too are the extortion tactics, with threat actors now using multifaceted pressure strategies. When improved backups reduced victims' need for decryption keys, threat actors began stealing data and threatening to leak it and cause reputational harm. And when regulators and law enforcement discouraged companies paying for data deletion promises, promises criminals often broke anyway, attackers escalated further.

Recent incidents also show threat actors emailing victims' employees and customers directly, claiming the organization "does not care about your data," or triggering every printer in an organization to output ransom notes - ensuring employees, customers and potentially the media know about the breach. Even more concerning is a trend toward re-attacks, where threat actors revisit a network weeks after an incident to exploit newly discovered gaps and re-encrypt systems, leveraging continuing disruption as a negotiation tool and providing incentives to victims to pay the ransom.

This evolution raises the stakes for incident response and negotiation. Speed, visibility, and technical capability are more critical than ever - and so is insurer preparedness.

For insurance and risk professionals, several priorities stand out in this new environment.

1. Baseline controls are still non-negotiable

Multifactor authentication, managed EDR and reliable offline or immutable backups remain the strongest defenses against ransomware and help to ensure business continuity. These controls buy the time and visibility needed to detect intrusions early and recover without paying a ransom. But they must be properly managed. Too many insureds deploy security tools without the professional oversight required for them to function effectively, just to satisfy an underwriting requirement.

2. Deploy advanced protections

Beyond baseline controls, insureds should also adopt least-privilege models, zero-trust architectures and AI-enhanced security tools that dynamically detect "known good" and "known bad" behavior. Historically, organizations avoided these approaches due to complexity, but modern implementations are increasingly manageable and fill critical gaps left by traditional defenses.

3. Prepare for negotiation scenarios that are more aggressive and less predictable

Extortion is no longer a one-dimensional threat. Insurance companies must partner with response teams experienced in managing multi-vector pressure tactics, from public-facing harassment to second-wave attacks. These partners are capable of advising clients through highly fluid situations.

The ransomware landscape is transforming rapidly, driven by fragmentation, automation and unprecedented agility among threat actors. For insurers and their insureds, adaptability is now a core competence. Those who evolve their incident-response strategies alongside the threat landscape will be far better positioned to protect both their clients and their own business.
Embedded Insurance's Next Leap

Embedded insurance is transforming from a distribution tactic to a customer experience strategy as insurers prioritize seamless, friction-free protection.

A Person Using a Laptop Holding a Credit Card

Residents don't want to search high and low for protection; they expect it to appear where it's most relevant. Insurance has always been about confidence, but during a digital buying journey, confidence depends on timing, relevance, and the ease with which protection blends into the experience itself.

That expectation is reshaping strategy across the industry. The State Of Embedded Insurance 2024 found that 94% of insurers view embedded insurance as a critical part of their future strategy. It's clear that insurers are no longer treating embedded insurance as only a distribution tactic but are treating it as a customer experience (CX) function.

Embedded insurance isn't new. What is new is the maturity of the technology and partnerships behind it. The next step is deepening trust and reducing friction at the emotional peaks of the journey.

TWO MOMENTS THAT MATTER THE MOST

In CX, timing is everything. Embedded insurance delivers its biggest impacts at two places in the customer journey: at checkout and right after purchase.

At checkout, customers are already in decision mode. They're focused and ready to act. When protection is offered right there, without extra steps or redirects, it feels like a natural extension of the transaction, rather than a separate sale. Subtle integration is essential. Research from BCG found that "conversion rates for traditional insurers that have embraced this model are already higher than for separate insurance for the same products," reinforcing the power of being present at the right moment.

The second moment is right after purchase, when the customer starts using what they bought. That's when peace of mind kicks in and becomes tangible. Knowing they're covered from day one reduces post-purchase anxiety and builds trust between buyer and brand. This connection ties into measurable CX gains with higher engagement and improved retention.

These moments also help explain why embedded insurance is expanding so quickly. As smoother, better-timed experiences become the norm, adoption rises. The embedded insurance market is projected to grow from $143.88 billion in 2025 to more than $800 billion by 2032, a CAGR of 28%. This steep trajectory is fueled partly by higher conversion rates and growing customer preferences for protection that appears naturally within the journey.

INSURANCE THAT FEELS LIKE CARE, NOT COMMERCE

For embedded insurance to actually enhance the CX, it has to feel like part of the service. That starts with seamless integration: no pop-ups, no redirects, and no disruption. Protection should appear inside the same interface the customer already trusts.

Clarity matters just as much as placement, so straightforward pricing, quick activation, and simple-language explanations reduce the mental load that often accompanies insurance decisions. The experience also extends beyond the sale. Claims, renewals, and continuing support must feel as intuitive as the initial purchase; otherwise, trust gained in the beginning evaporates quickly.

Four levers determine whether embedded insurance feels like care:

  • Timing: Arriving at the ideal moment in the right emotional window. Too soon and it's irrelevant; too late, and the customer has already mentally moved on. But hit that perfect moment and attention can quickly become willingness.
  • Personalization: This revolves around contextual relevance and offering coverage that fits the user's situation without demographic stereotypes or generic add-ons.
  • Speed: Instant activation reinforces confidence; waiting undermines the very safety insurance is meant to provide.
  • Claims: The ultimate test. A smooth, low-effort claim can turn a customer into a word-of-mouth marketer.

For example, a tenant signs a new lease through a property management portal. They're immediately directed to a co-branded insurance portal to either purchase coverage or upload proof of an existing policy. The transition is simple. If purchasing in the insurance portal, the tenant can then select appropriate limits or choose coverage that protects their personal belongings. And if a pipe bursts after move-in, the tenant can upload a few photos through their digital account and submit a claim within minutes, guided through each step instead of navigating stressful paperwork alone.

These moments define the experience much more than policy language. When embedded insurance removes friction, both emotional and practical, it stops feeling like an upsell and starts feeling like protection. The impact is clear in customer metrics. A 2024 study found a 17-point increase in customer satisfaction with digital insurance claims, driven largely by improvements in the range of services offered on mobile apps and websites, as well as visual appeal. Clearly, showing up with the right design and at the right time can shape customer sentiment at critical moments.

CX LIVES OR DIES IN THE PARTNERSHIP LAYER

No insurer or platform can deliver embedded insurance on its own. And any embedded insurance experience can fall apart if the system behind it isn't prepared and aligned. CX is co-owned: the insurer, the distribution platform, and the underlying technology all shape the moment a customer is offered protection. The strongest partnerships don't feel like transactional business deals; they operate like shared problem-solving.

A BCG report says that "to make the most of their opportunities, insurers will need to support and collaborate extensively with their business partners to become the provider of choice." This means teams jointly determine where insurance should appear in a workflow and how it should feel when it does. Technology, design, and messaging must blend seamlessly with the platform's brand so that customers only see a single experience, not two companies stitched together.

All of this work happens long before the first customer sees an offer. During discovery, both sides typically map the data already available in the platform's journey, such as lease information and account details, to the minimum information an insurer needs to provide a quote. When this is done well, eligibility questions shrink, quoting steps become simpler, and drop-off decreases. Clearer language replaces legal jargon, and forms become shorter and more intuitive. This way, the partnership shapes the ease customers feel long before they think about making a claim.

Customers remember the experiences that remove fear, not the ones that add friction. So the next step for embedded insurance will come from insurers and platforms working in sync and designing for real human moments. The future of insurance hinges on making every step intuitive, predictable, and easy at every touchpoint.

Using Serial Acquisitions to Turbocharge Growth

With organic growth softening, insurance agencies are turning to serial acquisitions to accelerate expansion and build market dominance.

Skyscrapers in City Against Sky

One of the best ways for insurance agencies to grow is through acquiring or consolidating with another agency or book of business, especially since organic growth has softened. And many agency owners are finding that repeating the process – becoming serial acquirers – reaps strong benefits for their businesses if done correctly and effectively. Before heading down that path, it's important to understand the keys to making successful acquisitions and smart financing options.

General benefits of serial acquisitions

Regardless of the industry, serial acquisitions can provide the following advantages for the purchaser:

  • Economies of scale – Serial acquisition allows overhead costs to be spread over progressively larger revenue streams. This advantage grows as the number of acquired firms increases.
  • Instant revenue increases – With each new acquisition comes new revenue. These revenue increases can fund technology upgrades, enhance marketing efforts, and additional acquisitions.
  • Higher company valuations - A Kearney study has shown that serial acquirers create greater shareholder value than companies pursuing fewer acquisitions. In addition, their success leads investors to assign higher values to serial acquirers.
Benefits specific to insurance professionals

In addition to the general advantages, there are several benefits of serial acquisition specific to the insurance industry:

  • Ability to reach higher carrier bonus levels and higher commission levels – Most carriers offer incentives for agencies to meet certain levels of premium. With serial acquisitions, an agency can reach higher levels faster than through organic growth alone.
  • Easier cross-selling and multi-lining – With multiple agencies connected through central ownership, clients can be offered new products and bundles, producing organic growth from inorganic growth.
  • Immediate cash-based revenue – A buying agency takes on the predictable cash flows of the purchased business. With these liquid assets on hand, the buyer has more choices regarding how to continue growth and expansion.
  • Access to talent – The shortage of new talent entering the insurance field is well documented. Serially acquiring other agencies allows a business to continually bring on experienced team members who can produce from day one. However, it's important that they also fit into the overall culture.
  • Access to specialized knowledge and technology – Serial acquisitions are a great way to build up an agency's tech portfolio and expand into new service areas. With a careful eye to each target company's unique strengths, a serial acquirer can assemble a formidable agency with the ability to provide a wider range of services to a growing clientele.

Steve DeLuca, founder and owner of the DeLuca Agency, has successfully acquired more than 10 agencies. He advises agency owners who are just getting started with acquisitions to look at smaller agencies. As his company started to grow, he didn’t want anything “too big that could change the culture of our current business, and something that was not too difficult to roll into our book of business at the time.” Other key factors for good acquisitions, according to DeLuca are low loss ratios, profitability, and book rolls.

Seven keys to successful serial acquisitions

While there are many advantages of acquisitions (serial or individual), it's important to go into the process with one's eyes open. Not every acquisition opportunity is going to be a good fit, so it's wise to keep several points in mind when evaluating a potential acquisition target:

  1. Foster cultural alignment - Adding more agencies to a portfolio is most successful when both have a similar workplace environment and are built on the same principles and goals.
  2. Retain + maintain human capital - As mentioned previously, keeping talented employees on both sides of the acquisition should be a focus - those who can drive success and are flexible in a new environment.
  3. Maintain strategic focus – An acquisition only makes sense if it fits with the agency's overall strategic focus.
  4. Develop expertise – Acquisitions require specialized knowledge. If an agency is planning to pursue serial acquisitions, it's worthwhile to have a dedicated individual or team with the interest and knowledge to take the lead on investigating opportunities and structuring deals. DeLuca says: “You’ve got to have a mentor, someone that you can talk to, someone that can bring you through the process, because it can be very stressful. You’ve got to have a good attorney experienced in mergers and acquisitions. You’ve got to have your purchase agreements and all your forms in place, and you’ve got to have a good banker.”
  5. Be willing to walk away – A deal that sounds great at the start may not look so good as time goes on. An agency owner needs to have the discipline to walk away from a deal that throws up red flags or doesn't prove to match the buyer's objectives.
  6. Plan integration early – An acquisition is only successful if the companies involved integrate well after the sale. Plans for integration need to start early in the negotiations so there are no surprises when the companies come together.
  7. Have a goal – Acquisitions should be part of an overall strategy for growth. Setting a goal for growth – e.g., $1 million in revenue per year – can help a buyer evaluate potential targets. This strategy avoids wasting resources on small fish as well as preventing becoming overwhelmed with targets that are too big to successfully integrate into the current business.
Financing options

Agencies with abundant liquid capital may choose to pay cash outright. However, that approach limits how much can be spent on other areas that drive growth (such as technology investments).

Loans from the Small Business Administration (SBA) are another option. With SBA loans, the borrower's personal assets are often used as collateral, and the paperwork for approval can be daunting. Even so, SBA loans can be a good option for borrowers whose credit is less than ideal.

Financing through specialty lenders who focus on the insurance industry is an appealing choice. These lenders – in contrast to most traditional banks – understand the nature of the insurance industry. They will often use the projected increase in cash flow as collateral for the loan, rather than encumbering other assets.

Summary

“In today's market, it's very hard to grow organically… so if you're going to grow, you've got to get into mergers and acquisitions,” DeLuca said.

In today's market, it's very hard to grow organically… so if you're going to grow, you've got to get into mergers and acquisitions.

Serial acquisitions can be a powerful way to turbocharge an agency's growth. It requires research, focus, and planning, but it can provide a big payoff when well-managed.


Rick Dennen

Profile picture for user RickDennen

Rick Dennen

Rick Dennen is the founder and chief executive officer of Indianapolis-based Oak Street Funding, a First Financial Bank company.

The firm offers customized loan products and services for specialty lines of business, including certified public accountants, registered investment advisors and insurance agents nationwide.

Rate Filing Reimagined

Fragmented rate filing processes constrain P&C insurers, prompting data integration and GenAI solutions.

An artist’s illustration of artificial intelligence

Accelerating P&C product and rate filing is critical to meet dynamic market demands and regulatory requirements. Traditional processes are constrained by manual handoffs, fragmented data, and slow approvals, resulting in delayed product launches and constrained profitability. This article explores how data, GenAI, and Agentic AI can transform rate filing—enabling parallel execution, automated testing, and intelligent workbenches for competitive analysis.

By adopting best practices in architecture, automation, and governance, insurers can compress cycle times, enhance pricing sophistication, and improve compliance. The approach outlined empowers carriers to respond swiftly to market shifts, optimize risk management, and gain a decisive edge.

Problem Statement: What?

Property and casualty (P&C) insurers in the United States face a complex and fragmented regulatory environment when filing new products or rates. The average time to approve rate filings has increased by 40% nationwide (for the period from 2018 to 2024 for homeowners' product). The result is delayed market response, constrained profitability, missed opportunities to reflect a changing risk posture (for example: In California, Proposition 103 limits insurers to base rates on historical losses rather than current and predictive/forward looking models).

While these regulatory complexities add to the delays of rate approvals, insurers also face internal challenges. These are magnified by fragmented data assets affecting rate development/indications, weak/limited integration of policy administration systems and rating engine, manual scenario generation & validations across rating workflows, too many handoffs, and manual state filing preparation.

Understanding Regulatory Complexity in State Filing

The regulatory complexity arises from several related factors:

1. State-Based Regulation and Legal Diversity:

Insurance regulation is primarily state-based, with each state legislature enacting its own rating laws, standards, and filing requirements. These laws may be based on NAIC model laws (e.g., prior approval, file-and-use, use-and-file, flex rating), but significant variation persists in definitions, processes, and compliance expectations across states. Insurers must navigate a patchwork of statutes, administrative rules, and case law, often requiring tailored filings for each jurisdiction.

2. Multiplicity of Filing Types and Entities:

Filings may pertain to rates, rating rules, policy forms, underwriting rules, or combinations thereof. Entities making filings include insurers, advisory organizations, and third-party filers, each subject to different rules and authorities depending on the state and product category.

3. Rigorous Data and Actuarial Standards:

Regulators require extensive supporting data for rate filings, including historical premium and loss data, actuarial analysis, and justification for rating factors. Standards mandate that rates must not be excessive, inadequate, or unfairly discriminatory, but interpretations and required methodologies (e.g., loss ratio vs. pure premium methods, credibility standards, catastrophe modeling) vary by state. Data quality, segregation, and rate adjustment protocols are scrutinized, and regulators may require multi-year data, trend analyses, and loss development triangles.

4. Procedural Complexity and Review Process:

The filing process involves multiple steps and stakeholders: filers must ensure completeness and compliance with state-specific requirements, often using tools like SERFF for electronic submissions. Reviewers conduct detailed checks for statutory and regulatory compliance, issue objection letters for deficiencies, and may require hearings or amendments. The process is iterative, and delays often result from incomplete filings or back-and-forth correspondence.

5. Policy Form Review and Public Policy Considerations:

Beyond rate filings, policy forms are subject to rigorous review for compliance with mandated provisions, prohibited clauses, readability standards, and consistency with pricing memoranda. States may require additional documentation, such as actuarial memoranda or advertising materials, and enforce unique requirements for specific lines of business.

Internal Challenges in Rate Change Management

Rate change management in P&C insurance is challenged by fragmented data sources and limited clarity/disjoint in data/business requirements for rate development & analysis. Insurers must reconcile information from underwriting, claims/loss history, reinsurance, and market trends, which demands extensive data wrangling and preparation. Latency in accessing third-party data and manual handoffs between product, actuarial, and IT teams further slow the process, leading to rework and misalignment.

The absence of integrated platforms for hypothesis development, rate workups, and filing results in inefficiencies and extended cycle times. Compliance steps are repeated for each state, and technical requirements for integration are often relayed indirectly, compounding delays. Manual testing and architectural gaps—such as non-stateless rating engines and scattered product management logic—impede data-driven decision-making and actuarial rigor.

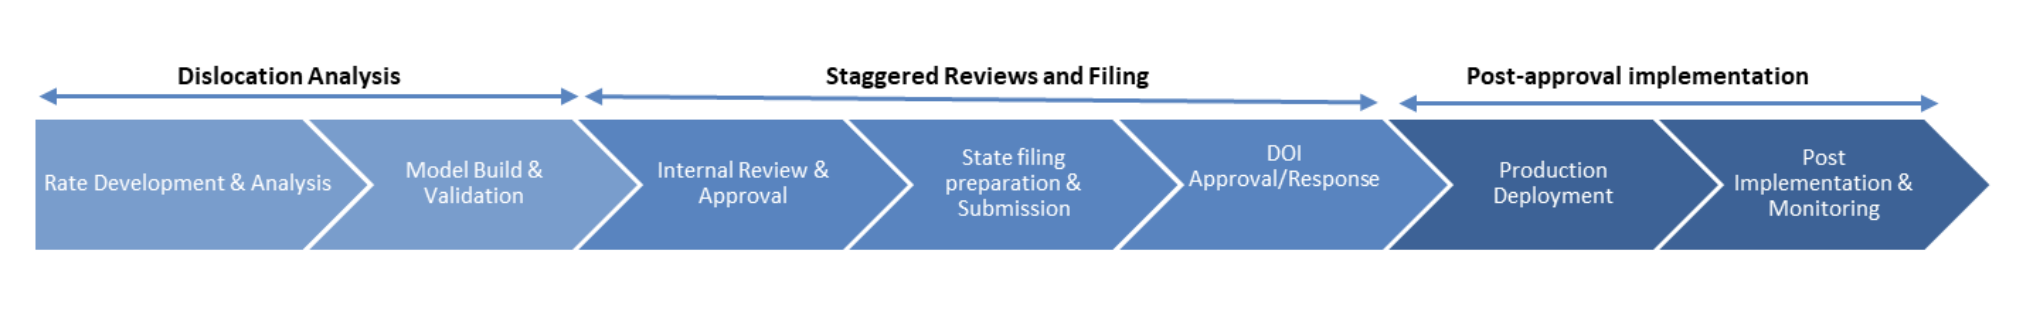
Dislocation analysis, a key actuarial process, is time-consuming due to sequential, repetitive workflows and limited automation. The challenge is to quickly identify segments with disrupted rates and adverse loss ratios, as variable-by-variable reviews are essential but time-consuming. Without robust analytical capabilities, targeted adjustments are delayed, increasing regulatory risk and reducing pricing effectiveness.

Flow Chart
How to bridge the internal challenges?

To accelerate and improve product/rate filing for Personal Auto & Property, insurers must deploy targeted interventions across dimensions such as Planning & Communication, Platform/Architecture, Data Controls & Trust, Validation, and rate filing intelligence—ensuring each stage of the value chain is robust, data-driven, and responsive to market and regulatory demands.

• Planning & Communication: Product / Rate filing has a direct correlation to business or product strategy. Considering its significance and the complex nature of the regulatory, it requires well-architected planning and execution. More often the challenges or delays are due to siloed interactions, lack of integration, gaps in business & IT/data requirements, delayed communication etc. across teams (product management, IT, Data, Actuarial, State filing etc.). Creating a digitized & integrated master rate change plan (by state, LOB, change complexity, filing type, etc.), workflow assignments and tracking ensure timely communication, transparency in timelines, dependencies etc. and enables identifying the choke points to improve execution. For example, Shift left the production IT activities related to configuration and build (i.e., before DOI approval/state filing, pre deploy with future effective dates toggled off until approval). Use emergency change approvals for minor rate updates and enforce strict SLA/OLA for signoffs to cut internal wait times.

• Platform/Architecture: Significant data engineering and configuration effort spent during Dislocation analysis and Post approval implementation. Address duplicate efforts spent in dislocation analysis and implementation (post rate approvals) by choosing appropriate rating engines (e.g.: Akur8, Earnix) with integration accelerators and compatible with modern policy administration systems.

• Data Controls and Trust: Automated data pipeline to ingest information, third-party data from near real time sources (telematics, IoT) on loss characteristics, use of CAT models for rate filings to assess risks like wildfire in California (as part of sustainable insurance strategy) to aid rate factor selection and an Assumptions Data Hub to capture UW assumption, Pricing assumptions, loss data etc., helps to build agility. Similarly, replacing legacy /excel-based models for rate filings with python/modern platforms such as hx Renew for central, version-controlled environment helps to improve collaboration, simplification and drive accurate filings.

• Automated validation: Leverage pricing tools/platforms such as hx Renew to automate scenario analysis (what-if") scenario analysis, automate the assessment of the impact of model changes and changes to assumptions, automated validation rules. Also, pairing provisional rate implementation with automated regression and CI/CD, improves response time via elastic rating engines and enhances rate monitoring, compliance, and traceability.

• Rate filing intelligence – Build & leverage rate filing intelligence powered by insights from SNL insurance product filing datasets (from S&P Global Market Intelligence) to understand market strategies, industry trends, analyze filings/factor changes of peer insurers, insights wrt objections, approval/response timelines of DOI etc. Harnessing these insights provides a feedback loop wrt product strategy, planning & execution adaptation to market conditions and decision-making.

Potential Benefits

Adopting integrated interventions such as master rate change plans and disciplined workflows, modern rating engines and platforms, reducing/eliminating excel based rating models, third-party data integrations, CI/CD and automated regression, market aware rate filing intelligence and effective change management—can significantly increase throughput of rate changes, strengthen rating traceability, reduce refiling/rerating cycles, and leverage richer third-party data for more responsive pricing, improving conversion, loss ratio resilience, and agility to market shifts.

The Way forward

To accelerate rate filing and product launches, insurers should assess their implementation strategy across the dimension such as people, process, technology and data, to evaluate their performance and outcomes. By operationalizing some of the relevant interventions listed above, insurers can compress cycle times, respond swiftly to market shifts, and optimize risk management. Now is the time for industry leaders to champion these changes and drive better outcomes.


Prathap Gokul

Profile picture for user PrathapGokul

Prathap Gokul

Prathap Gokul is head of insurance data and analytics with the data and analytics group in TCS’s banking, financial services and insurance (BFSI) business unit.

He has over 25 years of industry experience in commercial and personal insurance, life and retirement, and corporate functions.

Continuous Underwriting Wants to Scale  

Insurance premiums could fluctuate daily like stock prices, but regulation and reinsurance prevent the scaling of continuous underwriting.

White Clouds on Blue Sky

Ten years ago—has it been that long?—I was working with the largest insurer of churches and religious institutions in the US when we discovered they were incurring an average of $70 million in annual losses from frozen pipes.

It makes sense. Many houses of worship sit empty most of the time, and in the northern half of the country—where most of this carrier's book was concentrated—a power outage or failing furnace leads to frozen pipes, burst lines, and substantial water damage claims.

So we built an IoT service that monitored furnace activity and water pipe temperatures, complete with a call center to alert policyholders before problems escalated. It worked so well that it survives today: insureds receive annual premium discounts for enrolling, and frozen pipe claims have dropped over one-third.

That experience in continuous risk management sparked my fascination with the next frontier: continuous underwriting. In my view, there's no reason insurance premiums shouldn't fluctuate daily—like stock prices or utility bills—as new risk data emerges.

Frustratingly, there are exactly two reasons they don't: regulation and reinsurance.

Tesla Insurance: A Case Study in Market Inertia

Tesla Insurance launched in 2019 in California, leveraging real-time telematics data from connected vehicles to offer up to 30% lower premiums through a Safety Score algorithm that tracks behaviors like hard braking and collision warnings. The system performs real-time scoring—true continuous underwriting—and adjusts premiums monthly.

Today, Tesla Insurance operates in just 12 states. Twelve states in six years represent a glacial pace for a company built on speed, underscoring how state-by-state regulatory approvals and legal roadblocks stifle algorithmic pricing scalability. Elon Musk has joked that SpaceX will reach Mars before Tesla Insurance writes business in all 50 states—a sadly ironic quip, since the technology for continuous underwriting already exists.

Then there's reinsurance. Earlier this year, Tesla accelerated its pivot toward vertical integration by launching full in-house underwriting for California policies, marking a strategic departure from third-party partners like State National Insurance (a Markel subsidiary). This move gives Tesla direct control over risk assessment, pricing, and policy issuance—despite California's Proposition 103 restrictions on dynamic telematics pricing.

This operational autonomy does two critical things: it eliminates reinsurance constraints—such as conservative loss ratio caps that previously stifled Tesla FSD-linked innovations—and positions the company for national expansion, with pilots already running in Texas and Illinois. By year-end, in-house underwriting will cover 40% of Tesla's $1.2 billion premium base.

Cyber Insurance: A Case Study in Market Necessity

Cyber underwriting has traditionally relied on static annual assessments, but accelerating threat velocity—in the first half of '25, incidents grew by 49% YoY—demands a shift to continuous underwriting. Real-time data from AI-driven tools like open-source intelligence (OSINT) scanning and attack surface risk management (ASRM) enables dynamic risk evaluation and premium adjustments.

Cyber insurtechs such as Cowbell are transforming underwriting from a snapshot into a living process. They report a threefold reduction in claims through proactive remediation and adaptive policies tied to evolving security postures.

These cyber insurtechs focus almost exclusively on the SME segment—businesses with less than $1 billion in revenue, fewer than 1,000 employees, and, crucially, simpler IT environments than large enterprises. They're also proactive. Cowbell, for instance, actively monitors and underwrites risk for over 31 million SME entities using continuous external attack-surface scanning (their Cowbell Factors), often before a quote is even requested. This makes them one of the clearest real-world examples of continuous underwriting operating at scale in the small-and-mid-market commercial segment.

Regulation is actually helping here, pressuring carriers to verify real-time adherence to baseline security standards like multi-factor authentication through tools such as Endpoint Detection and Response (EDR) and Managed Detection and Response (MDR).

Reinsurance innovation is providing capacity. Leaders like Munich Re and Swiss Re are investing in advanced modeling and proportional treaties that favor data-rich, quota-share structures—lowering capital needs while supporting AI-enhanced risk portfolios.

Continuous underwriting unlocks growth. Projected global cyber premiums are expected to more than double from $14 billion in 2023 to $29 billion by 2027.

The "Big" Fight to Scale

In this corner, the champ: Big Insurance and Big Legal (has anyone not heard of Morgan & Morgan?). They'll spend upwards of $200 million this year lobbying Washington to preserve the McCarran-Ferguson Act of 1945, keeping arcane insurance regulations frozen in place.

In that corner, the challenger: Big Tech. As continuous underwriting—by definition, fully automated—consumes AI data center capacity, the AI hyperscalers are throwing untold millions into the fray.

The majority of insurance consumers—per recent surveys—are rooting for the challenger.


Riv Arthur

Profile picture for user RivArthur

Riv Arthur

Riv Arthur is a business leader and technologist working in insurance, healthcare, and private equity.

'Inevitablism' in Insurance

Technology slowly replaces insurance professionals' systemic value rather than eliminating their jobs outright.

An artist's illustration of AI

I'm not here to scare anyone by saying, "Tech will replace all insurance professionals." That line is boring now.

What I want to talk about is something else: Tech may not replace your job immediately, but it is slowly replacing your worth in the system.

We are entering a phase where some changes in insurance are no longer a choice. They are inevitable. I call this "inevitablism" in insurance.

What Is Inevitablism?

Inevitablism in insurance refers to the mindset that certain industry shifts — such as automation, AI adoption, data-driven decision-making, and modernization of legacy systems — are not optional but unavoidable.

It's the belief that these changes will happen regardless of current comfort, resistance, or preparedness, and that insurers must adapt rather than delay, because the future will arrive with to without them.

Tech vs Talent: The Usage Gap

There is no shortage of talent in insurance. The real problem is how that talent is being used.

Across the industry, many bright professionals spend their day on low-value tasks:

  • Moving data between systems
  • Updating spreadsheets
  • Chasing documents
  • Sitting in the same recurring meeting.

They are capable of designing better products, rethinking portfolios, and solving complex risk problems. But because technology inside many insurers is underused or outdated, people become the "glue" holding legacy processes together.

And let's be honest — we all know insurance adopts technology at a speed of 0.1× compared with the rest of the world. When the world is moving toward no-code workflows, instant software creation, and autonomous systems, insurers are only now preparing to give GenAI controlled access to production environments.

The gap is not just between tech and customers; it is between tech and talent.

Instead of using technology to free people for higher-value work, we often use people to compensate for the lack of technology. That's where the fear of AI comes from. It's not just, "Will AI replace my work?" It's also, "Have we allowed our roles to become so basic that any decent system could replace them?"

The Age of Innovation

We are already in a world shaped by Web 3.0, emerging platforms and decentralized technologies. Bitcoin's rise is just one signal of how digital value and infrastructure are shifting. On top of this, AI is accelerating innovation at a speed the industry has never seen before.

In this environment, insurers do not have the option to "wait and watch". They will be forced to adopt technology and create products that match how people actually live, work and transact today.

Innovation will not grow linearly; it will grow exponentially with the help of AI.

Automation will not be a luxury; it will be a necessity.

With open-source AI tools, startups can build, iterate and launch at a fraction of the cost and time. This new tech wave can easily create the next 10 major insurance players for the world—born digital, data-native and globally connected from day one.

In the future, most people will have their own AI agent helping them choose the right policies from hundreds of options. Most interactions—advice, onboarding, even parts of claims—could happen through VR or AR environments, especially for complex or high-value risks.

Behind the scenes, risk and portfolio decisions will rely on far more computing power than today, with advanced simulation and optimization. At the same time, connections between insurance and reinsurance will become more streamlined, with better data-sharing, real-time insights, and smarter capital allocation.

Leadership Choices in a Legacy World

Some leaders still believe that sticking to legacy systems and old processes is the safest path. They focus on short-term stability, minimal change and being answerable upwards, rather than looking ahead.

And this creates another silent problem — there is no real plan to make the transition easier for the next generation of leaders. Very few leaders think 10 years ahead. They avoid solving foundational issues like unstructured data, fragmented systems, or outdated architecture. But if today's leaders don't streamline data, modernize infrastructure, and clean the technical debt, how will the next leader build, innovate, or scale?

Without this groundwork, every new initiative becomes a retrofit, every improvement becomes a patch.

On top of that, most organizations don't have a clear plan to upskill employees before introducing new technology. Instead of preparing talent for next-level work, new tools get dropped in suddenly. This creates anxiety, resistance, and the fear of being replaced. A thoughtful, long-term upskilling roadmap not only protects employees — it empowers them to drive the transition and elevate the organization to its next stage.

Others think long term. They understand that the next generation of executives will not just "manage operations" but will be expected to embrace innovation, work with AI and data fluently, and redesign how insurance is delivered.

The organizations that win will be the ones where leaders:

  • Invest in modern platforms instead of patching legacy systems forever
  • Empower teams to experiment, automate and simplify
  • Build long-term upskilling plans so employees grow with the technology
  • Prepare future executives to operate in a world where AI, Web 3.0 and virtual interactions are normal, not experimental

The choice is simple: either leadership shapes the transition, or the transition happens to them.

A Future No One Wants to Miss

If we get this right, the future of insurance is not something to fear—it's a future no one will want to miss.

Insurance will work much more globally than it does today. Risks will not only be priced and held locally; they can be pooled globally, with capital, data and exposure flowing more smoothly across borders.

With the help of Web 3.0 and digital identity, we may see unique decentralized IDs created for individuals, businesses and even digital assets. These IDs can carry verified risk information, claims history, behavior patterns and coverage details in a secure, portable way. That means faster underwriting, smarter risk selection and better pricing for those who manage risk well.

For customers, protection becomes something that quietly works in the background—across countries, platforms and channels—instead of a one-time, paperwork-heavy transaction.

At the same time, insurers may rely on an entire army of AI agents to handle day-to-day tasks: answering queries, comparing products, monitoring exposures, flagging anomalies, and triggering workflows. These agents will effectively act on behalf of both the insurer and the customer.

That raises a new question for the industry: we won't just be insuring people and organizations — we will also need to think about how to insure the agents and the risks created by their decisions, errors, or failures.

As more processes are automated and more intelligence is built into systems, something important happens on the human side: we actually get more time and space to think.

More time to:

  • Discover what risks and needs are emerging
  • Innovate types of coverage and services
  • Design better experiences for both physical and virtual worlds

AI, automation and advanced computing handle the volume and speed. Humans handle the nuance and direction.

Final Thoughts

The future will not argue with any of us.

We can continue to debate whether Al will really reach certain capabilities, whether regulators will permit specific models, or whether customers will fully trust automated decisions. Many of these discussions are valid and necessary.

But some trends do not wait for our full intellectual comfort. They advance quietly through small projects, pilot programs and incremental upgrades.

The future does not require large numbers of people to keep legacy processes alive. It requires fewer people doing higher-value work, supported by smarter tools and more connected systems.


Manjunath Krishna

Profile picture for user ManjunathKrishna

Manjunath Krishna

Manjunath Krishna is a property and casualty underwriting consultant at Accenture.

He has nearly a decade of experience supporting global underwriters and carriers. He holds CPCU, AU, AINS, and AIS designations.

Can Farmers Overcome Insurance Challenges?

Satellite technology transforms agricultural insurance, enabling parametric solutions that protect entire supply chains, not just farmers.

Photo of Green Field Near Mountains

Farmers have been managing the risks to productivity throughout human history, for example by selecting the most appropriate choice of crop to plant according to state of soil moisture at the time. This is efficient, dynamic risk management the old-fashioned way.

From the late 19th century, the traditional way of protecting against the risks of perils, including hail, drought, flood, frost, heatwave and windstorm, has been indemnity insurance.

But just as farming techniques have evolved, farmers today benefit from new sources of data and technology, combined with alternative risk transfer options, to better protect their interests. What's more, these alternative solutions can allow farming supply chain partners, from processors, manufacturers and retailers, to protect their particular interest in the primary inputs into global food and beverage industries.

What obstacles do farmers face with traditional insurance?

Traditional crop insurances rely on accurate measurements taken at field or farm level. However, visiting farms and fields, often in remote locations, can prove time-consuming and may not give farmers the payouts they need to recover from losses when they need them.

Also, if a loss event is widespread, affecting many growers at the same time, there may not be enough experienced individuals to carry out the necessary loss evaluation work fast enough.

That's when alternative insurance arrangements, such as parametric solutions, can benefit both farmers and their supply chain partners.

What benefits do parametric solutions offer farmers?

Parametric solutions differ from more traditional, indemnity-based insurance contracts. They don't rely on on-the-ground loss adjustment because there is no need to prove loss, as in indemnity insurance. Instead, the insurance contract provides a payment based on a threshold being met on a pre-agreed scale or index. Such an index may be quite simple, for example the millimeters of rainfall recorded during the growing season or a critical part of it. Indices can also be temperature based: how many hot (or cold) days at prescribed temperatures are recorded.

Parametric insurance also differs from traditional insurance because payments are made automatically when contract terms have been met, without any need to 'claim' in the conventional sense. While the index will have been calibrated to reflect conditions that are likely to have caused a crop loss, the actual condition of the crop and resulting harvest are not considered when the payment is calculated.

Parametric solutions can be applied in varying forms and to address distinct risks that affect the supply chain, including cropping (both annual and perennial) and also livestock, aquaculture and forestry.

How can satellite technology and parametric insurance protect farming supply chains?

The routine availability of remotely observed data from satellite sources removes the need for insurers to visit the location of the insured assets for either risk or loss assessment. Such data sources let insurers measure vegetation health and evidence of burning remotely.

Such data, when combined with parametric insurance arrangements, enables interested parties up and down the food chain to protect their interests. If your business relies, for example, on the successful harvest of coffee in Brazil but you're not the grower of that coffee crop, you can still protect your interest with an appropriately designed parametric contract.

Traditional contracts of insurance are typically regulated so the policyholder must have an 'insurable interest' and, in the event of a claim against the policy, to show a 'proof of loss.' Parametric contracts can operate outside traditional constraints. This flexibility enables partners across supply chains to achieve a broader range of risk management objectives.

How can farmers take the first step toward parametric insurance?

Parametric insurance may sound complicated and sophisticated, but, in practice, almost the reverse may be true. While it may take the careful input of highly skilled experts to construct such products and to ensure they are fit for purpose, for the end user they should be easy to understand with payments, when due, being swiftly settled.

If you're a farmer or would like to explore protecting an agricultural supply chain partner with parametric insurance, your first step would be to assess your supply chains and their vulnerabilities. Geospatial analytical tools, for example, can help you quantify the likelihood and severity of multiple perils across global supply chains.

Claims Processing Requires Explainable AI

Explainable AI transforms insurance claims processing by making automated decisions transparent, addressing ethics challenges in legacy systems.

An artist's illustration of AI

Several insurance firms rely on legacy claims processing systems that create significant obstacles for maintaining ethical standards and transparency. These outdated systems feature siloed data structures that make it nearly impossible for claims adjusters to deliver fair and transparent outcomes.

Legacy infrastructure prevents effective data sharing between departments. Claims adjusters cannot identify fraud patterns when information remains trapped in separate systems. Manual workflows dominate these environments, with paper-based forms causing extensive delays in claim approvals. This leads to customer dissatisfaction and damaged relationships.

That's why insurance companies should consider modernizing their claims processing approach with solutions that prioritize both efficiency and transparency.

How Explainable AI Enables Responsible Claims Management

Explainable AI insurance claims processing software brings a fresh approach to insurance technology. It makes AI decisions clear and easy to understand. Traditional "black box" claims AI systems keep their decision-making hidden, but explainable AI shows the exact reasoning behind approving or rejecting claims.

This technology bridges the gap between complex algorithms and human understanding. Claims adjusters can check the AI's logic and change decisions when needed. This creates a vital balance between streamlined processes and ethical oversight.

Transparency gives this technology its edge. Traditional AI might simply mark a claim as fraudulent without explanation. Explainable AI reveals the specific factors that raised red flags. This helps adjusters make better decisions instead of blindly trusting machine outputs.

The technical gains offered by explainable AI claims processing software include:

  • Consistent Decision-Making Across Large Volumes - Claims processing system insurance software applies uniform criteria to thousands of claims while maintaining human supervision capabilities. This consistency eliminates the variability that occurs when different adjusters handle similar cases using manual processes.
  • Adaptive Fraud Detection - Unlike rigid rule-based systems, explainable AI insurance claims processing software adapts to new fraud patterns quickly. The technology learns from emerging schemes and adjusts detection mechanisms while providing clear explanations for why claims receive fraud alerts.
  • Faster Processing Times - Automated analysis significantly reduces the time required to evaluate claims. Adjusters spend less time gathering information and more time making decisions based on comprehensive data analysis.
  • Regulatory Compliance Documentation - These systems create detailed audit trails that demonstrate compliance with regulatory requirements. Every decision includes documentation showing the factors considered and the reasoning applied.
  • Enhanced Customer Communication - Clear explanations help adjusters communicate decision factors to customers effectively. Even when claims are denied, customers receive specific reasons rather than generic responses.

Insurance companies can now provide the transparency that customers expect while maintaining operational efficiency.

Improving Processing Transparency and Ethics

Explainable AI has become the lifeline of modern insurance claims processing systems. 

1. Supporting Human-AI Collaboration

A technical survey found that 44% of insurance customers continue to trust the decision-making process of human claim adjusters over AI-based systems. Explainable AI systems create productive partnerships between claims adjusters and automated technology. Rather than replacing human expertise, these solutions highlight relevant policy details and flag potential inconsistencies. The system explains its recommendations using clear language that adjusters can easily understand.

By implementing explainable AI claims systems, adjusters can maintain greater control over the claims decision process. They can assess the intelligent model's reasoning, validate precision, and override automated decisions when claims processing requires human intervention. This collaborative approach produces decisions that balance efficiency with ethical considerations.

For example, when processing a property damage claim, the claims processing system insurance software might highlight specific policy clauses while flagging unusual repair cost estimates. The adjuster receives clear explanations for both observations, enabling informed decision-making rather than blind acceptance of automated outputs.

2. Promoting Ethical Fairness and Bias Reduction

Modern insurance claims management systems do more than process data. They identify and reduce potential bias. These systems make decision-making criteria visible, which allows insurers to check if certain customer groups experience different outcomes. This visibility helps create fairer assessment protocols and gives equitable treatment to all policyholder demographics.

3. Improving Customer Trust Through Transparent Communication

Clear explanations about claim status significantly improve customer satisfaction levels. Explainable AI insurance claims processing software enables adjusters to provide specific reasons for decisions rather than generic form letters. Customers understand the precise factors that influence their claim outcomes.

Even denied claims receive better customer acceptance when explanations are thorough and understandable. Adjusters can point to specific policy language, documentation requirements, or coverage limitations that apply to each situation. This transparency develops trust even during complex conversations.

Insurance agents benefit from extensive claims decision logs that enable them to respond to policyholder queries with greater precision. The result is improved customer experience throughout the entire claims process.

4. Facilitating Continuous Auditing and Model Accountability

Transparent claims management systems for insurance create detailed audit trails that document every decision-making step. Supervisors can review patterns across thousands of claims to spot potential problems before they become systemic. This continuing accountability keeps the system reliable and trustworthy.

5. Strengthening Compliance

Insurance regulations require justifiable decisions and transparent processes. Explainable AI claim processing systems provide documentation that proves compliance with evolving regulatory requirements. This helps insurers avoid penalties while building stronger governance frameworks.

Legacy Claims Processing Challenges

Traditional claim processing systems create several critical challenges that reduce efficiency and ethical operations in the insurance industry. Explainable AI provides targeted solutions to these continuing problems and helps insurers overcome major obstacles.

I. High Error Rates and Inconsistent Claim Outcomes

Legacy claims management systems with manual data entry cause frequent errors and inconsistent decisions. Claims adjusters often make decisions with incomplete information that result in different outcomes for similar cases. Explainable AI claims management systems for insurance solve this through standardized processing protocols, while human oversight remains where needed. This combined approach gives consistent judgments and keeps the flexibility to handle unique claim situations.

II. Ineffective Fraud Detection Mechanisms

Traditional claims processing system insurance solutions use rigid rules that clever fraudsters can easily bypass. These systems are incapable of managing subtle patterns and new fraud techniques. Whereas explainable AI claims software identifies complex connections across data points and highlights potential fraud activities that human reviewers might overlook. They also give clear explanations about flagged claims.

III. Lack of Predictive Insights and Adaptive Intelligence

Older insurance claims management systems react to situations instead of preventing them. They don't know how to predict claim patterns or adapt to changing risk landscapes. Explainable AI platforms learn continuously from new data and improve their accuracy over time. They remain transparent about how they generate predictions.

IV. Poor Customer Experience and Communication Gaps

Legacy systems keep claimants uninformed about their claim status. Policyholders often complain about limited visibility into decision processes. Explainable AI platforms enable clear communication about claim progress and decision factors. This deepens customer trust even when outcomes are negative.

Final Words

Insurance companies are moving away from legacy claims processing systems to explainable AI, and this marks a major change in claims handling. Old opaque processes left customers confused, and adjusters didn't deal well with limited information. But explainable AI fixes this gap naturally.

Trust forms the foundation of claims processing. Policyholders need fair treatment when they file claims during vulnerable moments. Explainable AI keeps this trust intact while making the process more efficient. These systems don't replace human judgment; they boost it by giving adjusters clear reasoning behind every recommendation.

What Brokers Actually Hold Together

Brokers' representation, translation and defense functions risk being simulated by platforms rather than being genuinely performed.

Women and Men Working over Laptop

What brokers actually do, beneath the pitch decks and client presentations, is harder to name than it should be. I've come to see it as three distinct but deeply connected acts: representation, translation, and defense. None of them are transactional. All are structural. And when one breaks down, the entire architecture starts drifting in ways that don't announce themselves until pressure arrives.

Representation

We tell ourselves we represent the client. It's written into the mandate, formalized in the engagement terms. But that's not what I mean when I talk about representation as a function. Real representation is interpretive work. It's absorbing not just what the client articulates in meetings but what they can't fully express or haven't realized matters. The CFO's underlying anxiety about retention levels that never gets voiced directly. The operational reality that contradicts what's written in the business continuity plan. The political tension between local offices and headquarters that shapes every decision but never appears in formal communications.

A good broker doesn't just collect this information and file it away. They inhabit the client's frame of reference well enough to anticipate friction before it surfaces, to shape options in language that resonates with how the organization actually makes decisions under pressure, not how they describe their decision-making in the abstract.

This work resists automation because it operates in the space of what isn't said. The risk manager who mentions supply chain concerns but doesn't mention the board's private anxiety about a key supplier in political turmoil. The CFO who approves the renewal but whose body language signals doubt about whether local subsidiaries will comply. You can't checkbox your way into understanding what keeps someone's leadership team awake at 3 a.m., or what past incidents have shaped their risk appetite in ways they haven't articulated.

When representation fails, it fails quietly at first. The client says yes to a structure they don't fully understand, or worse, that doesn't quite match what they thought they were agreeing to. Six months later, at claim time, that gap becomes visible and consequential. By then it's too late to recover the alignment that should have been built from the beginning.

Translation

Here's where the function becomes more complex and less visible from the outside. Clients don't speak insurance. Markets don't speak business operations. The broker stands between these two worlds, translating in both directions, and this is genuine translation in the transformative sense, not simple transmission.

A client says something like "we're worried about supply chain disruption" and that statement, while meaningful to them, isn't something a market can price or structure coverage around. The broker needs to transform that anxiety into something that can be underwritten: specific exposure scenarios, concentration risk analysis, dependency mapping, contractual arrangements with suppliers, mitigation measures already in place.

Then the market comes back with their response, which might be, "We'll write it, but we need a 72-hour notification clause and a sub-limit on critical suppliers." Now the broker has to translate that back into consequences the client can evaluate in operational terms. What does 72 hours mean in the context of their actual supply chain? If the client's procurement operates on quarterly cycles and their logistics team is in a different time zone with no weekend coverage, that 72-hour clause isn't a technical requirement. It's a structural impossibility that will surface as a coverage gap during a claim. What constitutes a critical supplier in the policy language versus in their business model? What happens when those definitions don't align?

This is knowledge work that creates value precisely by bridging incommensurable ways of understanding the same underlying reality. The broker needs to be fluent in multiple languages simultaneously: the operational language of the client's business, the technical language of insurance contracts, the commercial language of market negotiation, and the legal language of claims defense. More critically, they need to know how to move among these languages without losing essential meaning in the translation.

Platform automation can make failures in this translation work particularly invisible. Information passes smoothly between systems without requiring interpretation, and misalignments get embedded from the start, invisible in the flow of data that appears to be working correctly.

Defense

The first two functions matter enormously, but defense is where they actually get proven. When a claim is contested, when coverage becomes ambiguous under specific circumstances, when a market pushes back hard on their obligations, this is the crucible that tests whether the entire structure holds.

No platform can argue a claim under contested wordings. No template can untangle jurisdictional complexity when a multinational client has an incident that touches three countries with different policy triggers and legal frameworks. No automation can stand between a client and a reluctant market when things get genuinely difficult and relationships are strained.

Major claims regularly hang in suspension because the broker who placed the program has moved on, and no one remaining can explain why certain structural choices were made. The documentation exists, perfectly filed. But the reasoning behind a split trigger structure across jurisdictions, or why specific sub-limits were set at particular thresholds, has left with the person who built it. The market sees ambiguity where there should be clarity, and coverage that seemed solid becomes contested.

Defense is existential work. It's the moment when the broker's function becomes most visible, when all the careful work of representation and translation either compounds into coherence or reveals itself as insufficient.

Defense reveals the quality of representation and translation that preceded it. Good representation creates a foundation of mutual understanding that makes defense easier when pressure arrives. Good translation produces clear documentation that withstands scrutiny and doesn't create new ambiguities under stress. When defense succeeds, it typically does so because representation and translation were performed well from the beginning. When defense fails, you can almost always trace the failure back to a gap in representation or a distortion in translation that went unnoticed during the calm periods. The claim becomes the moment when hidden misalignments become visible and consequential.

Why They Work as a System

These three functions don't operate in sequence. They work as a feedback loop. Every claim you defend teaches you what actually matters in representation. Every translation that fails under scrutiny reveals gaps in your initial understanding of the client's operations. The system learns, but only if the same intelligence holds all three functions.

This is why traditional cross-functional team structures don't work well for broking, despite their popularity in other contexts. Cross-functionality distributes partial competencies across specialists who each own a piece of the process. But effective broking requires holding all three functions simultaneously in integrated view. You need to see how choices made during representation will affect translation work later, and how both create the conditions for eventual defense. When these functions get distributed across different people or teams who can't see the full arc, the feedback loop breaks and the system loses its ability to learn and adapt.

Nobody else in the insurance ecosystem is structurally positioned to hold all three at once. That's what makes the broker's role irreducible to its component parts.

What Happens When It Breaks Down

What concerns me is that as platforms become more sophisticated and persuasive in their interfaces, these three functions risk getting simulated rather than genuinely performed. Representation becomes templated intake forms that capture standard data points. Translation becomes automated data mirroring that passes information between systems without transformation. Defense becomes an escalation protocol that routes problems through predetermined channels.

The organizational structure looks the same on paper. The dashboards show activity and completion metrics. But the system stops thinking in any meaningful sense. It stops adapting to what it learns. It loses the capacity for judgment that accumulates through experience.

This pattern appears when operational metrics look excellent while the capacity for genuine broking work degrades. A sophisticated platform migration maps every data field perfectly, preserves every document template, automates every workflow. Six months later, the team can't explain why a D&O program has separate retentions in different jurisdictions, or why certain sub-limits were structured the way they were. The logic lived in institutional memory. The platform captured the output but not the reasoning. When the people who built the structure move on, the program becomes an artifact no one can interpret.

This pattern appears when operational metrics look excellent while the capacity for genuine broking work degrades. Coverage structures get ported through system migrations, and at each step the program logic gets simplified to fit new data architectures. When claims arrive that test the structure, teams can't explain why certain elements exist or what scenarios they were meant to handle. Fluency in the platform's language replaces fluency in the client's business. The interpretive memory of why structures were built gets lost. The simulation of broking replaces its substance, and the difference only becomes visible when genuine pressure arrives.

What This Means Going Forward

I'm not arguing against platforms or digital transformation. The efficiency gains matter, and clients have come to expect sophisticated digital interfaces as table stakes. But we need much greater clarity about what technology can and cannot do.

Technology can accelerate transactions and make process visible. It cannot interpret complexity or maintain judgment across time. It can structure workflows and standardize inputs. It cannot hold the kind of accumulated understanding that gets better with experience rather than worse with scale. It can simulate the appearance of alignment. It cannot defend that alignment when it comes under genuine stress.

The brokers who will remain relevant aren't the ones who adopt new technology most quickly or enthusiastically. They're the ones who understand precisely which parts of their function can be automated without loss and which parts require human judgment that deepens rather than degrades over time. They're the ones who can articulate the difference between performing these three functions and merely simulating their performance through sophisticated interfaces.

Representation, translation, defense. Three functions that work as an integrated system. Easy enough to describe in the abstract. Much harder to automate without losing what makes them valuable. Essential to preserve if broking is going to remain a strategic function rather than devolving into process management.

The question for every broker is whether they're actually performing all three or whether they've gradually allowed platforms to simulate them while the substance quietly erodes. Your clients won't know the difference until the moment they need you most. By then the damage isn't just a failed claim. It's a program structure no one can defend because no one remembers why it was built that way. The broker who can't explain why becomes the broker who can't argue when. And that's when representation, translation, and defense collapse from professional functions into administrative tasks no platform can rescue.


Arthur Michelino

Profile picture for user ArthurMichelino

Arthur Michelino

Arthur Michelino is head of international coordination at OLEA Insurance Solutions Africa.

Michelino previously worked at Diot-Siaci as an international coordinator for key accounts. He began his career at Willis Towers Watson (formerly Gras Savoye), implementing international programs for the mid-market segment.

Insurance Modernization Is Stalling

Carriers are confronting widening gaps between ambitious digital strategies and operational execution.

White and Blue Building during Daytime

The insurance industry has spent years talking about modernization. Strategies drafted, budgets allocated, and pilot programs launched. But after early progress, momentum is slowing—and for many carriers, stalling altogether. The result is an industry caught between ambition and execution, where the cost of standing still grows with each passing quarter.

Recent data from West Monroe's survey of 300 insurance executives reveals a distinct pattern: while nearly every carrier has modernization plans in motion, few are making meaningful progress. 20% have defined strategies but haven't advanced execution. Another 12% remain in early planning stages. The most jarring: two-thirds of insurers expect it will take another three to seven years just to move core systems to the cloud, with 14% having no timeline at all.

This goes beyond technology. It's a business risk that's compounding with each passing quarter.

The Legacy Tax Is Draining Innovation Capacity

The clearest evidence of stalled momentum shows up in budget allocation. More than half of insurers now spend 51-75% of their IT budgets simply keeping existing systems operational. This "legacy tax" creates a self-reinforcing cycle: aging systems require more maintenance, leaving less capital for transformation, which in turn allows those systems to age further.

The impact is measurable. In the past 12 months alone, 52% of organizations delayed or canceled two to three strategic technology programs due to budget constraints. These programs include data governance improvements, AI capabilities, and customer experience enhancements that would position carriers for future competition.

Many insurers are still running core operations on COBOL, a language older than most of their customers. More than half report between six and 15 mission-critical COBOL modules still in production, revealing how deeply legacy code runs through their systems. This dependency exposes a major contradiction: organizations may have modern customer-facing experiences, yet their back-end processes remain anchored to aging infrastructure that limits scalability, agility, and speed.

Closing that gap requires more than new tools—it takes a clear modernization strategy that balances innovation with operational stability.

Speed Matters, And It's Slipping

The operational consequences of stalled modernization are impossible to ignore. 41% of executives say their critical data is only available when needed, not in real time. That lag translates directly into competitive disadvantage.

Consider the pace of basic operations: 48% report it takes 16 to 30 days to complete a rate indication assessment. Nearly half say it takes nine to 16 weeks to launch even a minor product endorsement. In a market where competitors can respond to emerging risks in days, not months, this kind of delay erodes competitive positioning.

In a market defined by speed, the ability to act in real time is becoming a key differentiator—separating those who capture growth from those still optimizing for stability.

The AI Paradox: Investing in Tools Without Foundations

Perhaps nowhere is the momentum problem more evident than in artificial intelligence adoption. Nearly 60% of insurers report being past the pilot stage with generative AI, yet most deployments remain small-scale and fragmented. Claims leads slightly with 30% actively piloting tools, while underwriting shows 27% still in proof-of-concept.

The stall is structural, not technical. Organizations that haven't invested in platform and data modernization face mounting costs and complexity. Large-scale transformations of policy administration, billing, and claims systems are creating more tech debt, pushing carriers further behind.

When asked about barriers to AI adoption, respondents pointed overwhelmingly to human factors: 24% cited resistance to change, 23% struggled with unclear value propositions, and 20% pointed to poor user experience. Only 13% identified technical issues as the primary obstacle.

This reveals the core challenge: insurers are trying to scale AI on foundations that weren't built for it. Without modern data governance, unified platforms, and streamlined processes, even sophisticated AI tools remain trapped in pilots instead of powering real underwriting and claims improvements.

Business and IT Misalignment Multiplies the Problem

Momentum stalls when priorities diverge. While 40% of organizations report "some alignment" between business and IT, that qualification signals trouble. Critical disconnects remain, and those gaps slow decision-making, blur accountability, and fragment modernization efforts across competing initiatives.

The data shows this misalignment in action. When asked about primary modernization objectives, 36% said improving customer experience, yet when budget allocation was examined, customer digital experience ranked last in funding priority. Meanwhile, 30% are betting on GenAI and advanced analytics, but 28% acknowledge their data layer and governance must mature first.

This represents an execution gap. Without shared ownership between business and IT, modernization risks solving for technology instead of solving for customers. The organizations breaking through are those that have hard-wired collaboration into their operating model, ensuring priorities and budgets move in lockstep.

Breaking the Stall Requires Strategic Focus

Momentum doesn't return through incremental adjustments. It requires strategic recalibration. Carriers gaining ground have stopped treating modernization as a technology initiative and started treating it as a business imperative tied to measurable outcomes.

That means rebalancing spend away from maintenance toward platforms that reduce future technical debt. It means building data governance that enables speed, not just compliance. And it means aligning business and IT not just in planning sessions, but in budget cycles, decision rights, and accountability structures.

Most critically, it requires accepting that modernization timelines measured in half-decades are no longer viable. When asked what would happen if modernization efforts froze for 24 months, 45% predicted significant competitive disadvantage. Yet nearly one in five believed a freeze would have minimal effect, a perception gap that signals how far some organizations still are from connecting technology strategy to business outcomes.

Those Who Move First Will Define What's Next

Momentum can't be restarted by chance—it has to be rebuilt with intent. The carriers regaining speed are the ones tackling legacy debt, modernizing data foundations, and aligning business and IT around a shared vision. With these foundations in place, AI and emerging technologies can do more than pilot—they can accelerate real performance and growth. For insurers, restoring momentum isn't just about catching up; it's about setting the pace for what comes next.


Peter McMurtrie

Profile picture for user PeterMcMurtrie

Peter McMurtrie

Peter McMurtrie is a partner of the insurance practice for West Monroe, a global business and technology consulting firm. 

He joined West Monroe from Nationwide Insurance, where he was president of Property & Casualty Commercial Insurance.