Download

Ukraine Invasion's Potential Impacts

The invasion poses a complex threat to the operations of financial services companies and has enormous consequences for the financial markets in the short term. 

ukraine

On Feb, 24, Russian armed forces attacked Ukraine. The invasion is first and foremost a human tragedy, and Allianz has been clear in its opposition to this unprovoked attack. As a secondary topic after the humanitarian concerns, the invasion poses a complex threat to the operations of financial services companies and has some enormous consequences for the financial markets in the short term. 

Immediately after the invasion, there was a panicked reaction in the capital markets, particularly European banking stocks. Banks from Italy and France are most exposed to Russia, together accounting for more than 40% of the total exposure of foreign banks in Russia at $25.3 billion and $25.2 billion, respectively. However, these numbers only account for very low single-digit percentages of their total foreign claims. Banks with large Eastern European activities also saw stock prices declining materially. 

Stocks of Russian banks saw massive declines, and interest rates on (expected to default) Russian and Ukrainian sovereign debt, as well as the cost for credit default swaps, went through the roof. Europe’s Single Resolution Board took action on Russia’s Sberbank subsidiaries in Croatia and Slovenia to avoid failure.

The macroeconomic impact and increasingly higher inflation expectations are being fueled by elevated commodity prices. In Europe, the risk of stagflation has increased, and markets are closely watching the next steps central banks around the world are taking. Increasing inflation, together with low economic growth, may lead to lower profit generation for banks and hurt the results derived from retail operations.

When it comes to U.S.-based financial institutions, some asset managers and banks do have physical assets exposure to Russia and Ukraine. However, the evidence seems to suggest that such direct assets exposure (whether these are leased airplanes, real estate, equity investments, Russian and Ukrainian debt/bond investments denominated in USD/Russian rubles/Ukrainian hryvnia, etc.) and other related exposure is in low-single-digit percentages. 

Underwriters expect U.S.-based financial institutions to conduct full write-downs of their investments in Russia and Ukraine during fiscal 2022 and possibly later, as the ultimate outcome of the conflict remains uncertain. It is also likely that the U.S. assets in Russia will be nationalized in response to the U.S.-imposed sanctions, ruling out any possibilities of future recoveries.

A number of U.S. asset managers have highlighted that sanctioned Russian nationals are limited partners in their funds and that they are working to buy back their interests in these private funds to cease the affiliation with these limited partners. 

At the same time, certain U.S. hedge funds are buying up Russian and Ukrainian bonds at cents on the dollar, perhaps betting on an early resolution of the conflict. The Ukrainian bonds are currently trading at higher prices given the pledged financial support of Ukraine by the U.S. and the European Union. While doing so is somewhat of a common practice by hedge funds, aiming to profit from the current unprecedented situation in Eastern Europe may be viewed as an environmental, social and governance (ESG) issue by the investment community and the regulators.

See also: Ukraine: How Exposed Are Insurers?

Cyber and ESG issues

Alongside the human toll, the invasion of Ukraine provides a salient reminder of the omnipresent danger of state-sponsored cyber-attacks that aim to disrupt and disable IT systems. Banks and financial institutions are on alert for an escalation in hacking attempts and Russian reprisal cyber-attacks after the imposing of sanctions by Western nations, resulting in a number of the country’s lenders being kicked off the global payments messaging system SWIFT.  

This comes at a time when risk managers have never been more aware of the hazards posed by cyber criminals. Recent high-profile cyber-attacks have shown a worrying trend, where hackers target technology or software supply chains. AGCS analysis of more than 7,500 insurance claims involving financial services companies over the past five years (worth $1 billion-plus) show that cyber incidents are already the top cause of loss. IT outages, service disruptions or cyber-attacks can result in significant business interruption costs and greater operating expenses from a variety of causes, such as customer redress, consultancy costs, loss of income and regulatory fines. Brand reputation and, ultimately, a company’s stock price can also be harmed, while management can also be held responsible for lack of preparedness.

It is unsurprising then that cyber incidents was ranked as the top risk for the financial services sector by 51% of the 872 respondents who participated in the Allianz Risk Barometer 2022. For companies, and their senior management, this ultimately requires them to maintain an active role in steering the information and communications technology (ICT) risk management framework, including assigning clear roles and responsibilities for all functions and appropriate allocation of investments and training. Companies need to operationalize their response to regulation and privacy rights and not just look at cyber security.

At the same time, the broader ESG impact is being felt by asset managers assessing the impact these developments have on the sustainability of their investments post widespread sanctions, on a country that already scored relatively low in terms of governance and social matters. No doubt some asset managers will consider divesting Russian assets based on ESG considerations. Companies’ boards are re-evaluating presence and activities in the country due to concern over reputational damage.


Anton Lavrenko

Profile picture for user AntonLavrenko

Anton Lavrenko

Anton Lavrenko is regional head of financial institutions for North America at Allianz Global Corporate & Specialty.

Originally from Eastern Europe and a fluent Russian speaker, Lavrenko has more than 25 years of international insurance experience in commercial, financial institutions, reinsurance and brokerage segments.

It’s Time to Reimagine Digital Payments

The acceptance and delivery of payments must be in real time, and capabilities must let customers create tailored digital payment experiences that fit their needs best.

digital

What makes a true digital payment experience in insurance? Although the past few years have been characterized by rapid digital payment options, the game-changer has been the focus of market leaders to embrace the transformation of the actual payment experience – both for premium and claim payments.

In SMA’s new research report, "The Race Toward True Digital Payment Experiences: The Digital Transformation of Premium and Claim Payments in 2022 and Beyond," SMA explains the current state of premium (inbound) and claim (outbound) payments. Although there is a strong effort by insurers to provide true digital payment experiences, many continue to operate with outdated processes that don't meet the needs of today's consumers.

New preferences brought on by the pandemic and a more digital-connected world demand that insurers reimagine the payment experience. Within premium payments, this means offering policyholders the ability to manage how they interact with their insurers and control payment management and notifications. The goal should be to expand payment types and access options to give policyholders greater control of their experience.

On the claims side, while it is more challenging to establish a fundamental digital interaction, insurers have a tremendous opportunity to improve operational efficiencies and reduce costs. This includes establishing digital interactions that go beyond payout delivery for claimants, agents, claims adjusters, vendors and other third parties.

See also: Seeing Through Digital Glasses

For both premium and claim payments, speed and convenience are paramount. The acceptance and delivery of payments must be in real time, and capabilities must give customers the power to create tailored digital payment experiences that fit their needs best, from how they want to transact to how they want to communicate with their insurers.


Karen Furtado

Profile picture for user KarenFurtado

Karen Furtado

Karen Furtado, a partner at SMA, is a recognized industry expert in the core systems space. Given her exceptional knowledge of policy administration, rating, billing and claims, insurers seek her unparalleled knowledge in mapping solutions to business requirements and IT needs.

P&C Agencies Are Ready to Break Out

This year and beyond, agencies will fiercely focus on channel expansion and assess their current partnerships. Insurers must stay abreast of new partnership opportunities.

aisle

Retail agencies and brokers are rethinking their channel partner strategies just as carriers and others across the distribution landscape do the same. Although carriers will always remain underwriting partners, more agencies are exploring new channel partners in the distribution ecosystem to ultimately reach customers and connect with carriers. New research from SMA finds that as options for channel relationships continue to expand, distributors across the personal and commercial lines segments are divided on the best approach for their businesses.

In 2022, agencies and brokers are not only turning to traditional partnerships, such as aggregators and banks or financial institutions, but are also exploring up-and-coming channels, such as insurtechs and digital agencies. The recent SMA research report, "Channel Strategies and Plans for P&C Agencies: A View of Commercial and Personal Lines Segments in 2022,” shows that very few agencies expect insurtechs to have a limited impact on their business. It follows that 52% of agents in the small commercial segment and 48% of agencies in personal lines fear the possibility of insurtechs encroaching on their business spaces. Thirty-two percent of agencies in mid/large commercial lines feel similarly. 

While many agencies partner with insurtechs as solution providers, very few are currently planning to use digital agencies as channel partners within the next three years. Rather, most see them as competitors. However, SMA advises that insurtech will increasingly become a force, especially in mid/large commercial lines, as technology advancements make these risks more viable targets while also improving the systems and processes within this segment. This year and beyond, agencies will fiercely focus on channel expansion and assess their current partnerships. At the same time, insurers should also take a step back to review their agency partners and prioritize key relationships by understanding their growth plans and vital industry segments. In today’s quickly changing distribution landscape, insurers must stay abreast of new agency channel partnership opportunities and the benefits they offer.

See also: 2-Speed Strategy: Optimize and Innovate


Heather Turner

Profile picture for user HeatherTurner

Heather Turner

Heather Turner is the lead research analyst at Strategy Meets Action.

Turner supports SMA's advisory and consulting engagements through rich written content, quantitative and qualitative primary research, market and technology trend analysis and the management of SMA IP materials.

Prior to SMA, Turner was managing editor of the NU Property & Casualty Group at ALM, which includes the insurance industry publications PropertyCasualty360.com and NU P&C and claims magazines. She started her career as a journalist reporting on the property and casualty insurance industry at Insurance Business America and its sister publications in Canada and the U.K. 

How Automation Can Streamline Claims

Insurance claims software lets agencies reduce fraud, shorten the claims lifecycle, optimize costs, improve efficiency and a lot more.

software

Insurance agencies across the globe are embracing software solutions that transform the filing and settling of claims into a quick and satisfying experience. In this blog, we will explore the typical lifecycle of a claim and how claims management software can streamline it. 

The Lifecycle of Insurance Claims

The insurance claims process usually involves five key stages, starting from first notice of loss (FNOL) to resolution. 

  • Claims creation or FNOL
  • Validation of the claim
  • Review and evaluation
  • Adjustment
  • Cancellation or payment 

How Claims Software Can Streamline the Lifecycle 

Integrating automation into the claims process benefits all types and sizes of insurance agencies. It allows them to introduce efficiencies and shorten the lifecycle of the process, providing numerous benefits: 

  1. Process Standardization

Manual workflows tend to get complicated, as several employees and partners may be involved. Each has a unique approach, which can lead to inconsistencies. Claims software offers a shortcut to process standardization, meaning more compliance and ensuring that no crucial steps are overlooked.

  1. Efficient Collaboration

Nowadays, the most efficient insurance agencies are the ones that have digitized, streamlining their day-to-day processes and encouraging collaboration among previously siloed departments. Claims management software lets you send updates and notify the concerned departments, teams or individuals on coming tasks and activities. The software reduces the scope for miscommunication and enables claims handlers to coordinate better with customers. 

  1. Higher Efficiency

The automation means users do not have to consistently check whether the process is advancing; the software keeps track for you. Likewise, the software, powered by machine learning and artificial intelligence, recognizes and address mistakes or bottlenecks.  

  1. Regulatory Compliance

Regulations keep changing, making it challenging for agencies to ensure compliance as they strain to improve operations and meet the needs of customers. Failing to meet compliance norms can bring expensive, as well as inconvenient, consequences. 

But claims software helps with compliance. Automating the process means you are continually recording key information, producing a database that comes in handy during audit and compliance reviews. 

  1. Data Security

Paper-based records are vulnerable to theft and can be destroyed in accidents and natural disasters, but digitizing processes and storing the data electronically keeps the information safe and easily accessible. Insurance claims software includes advanced security measures, such as multi-factor authentication. 

See also: How to Resist Sexy Analytics Software

  1. Cost Optimization

Claims management software supports end-to-end processes, from registration to resolution, and accelerates the everyday work of claims handlers, producing efficiencies and saving on costs.

  1. Increased Accuracy

Irrespective of how skilled or prepared the staff is, errors will undoubtedly occur occasionally, but automating the claims processes drastically lowers the probability of slip-ups or redundancies. 

  1. Faster Resolution

Insurance processes can be tedious and lengthy, but customers want quick resolutions and frequent updates -- and automation can shorten the settlement process while helping spot fraud.

Final Words

Insurance claims software lets agencies reduce fraud, shorten the claims lifecycle, optimize costs, improve efficiency and a lot more.

4 Steps to Support Patient Financial Health

Existing strategies addressing medical debt, such as stopping lawsuits or removing it from credit reports, are important but do little to actually prevent debt.

featured
health

Medical debt totals at least $140 billion nationally and is the most common type of past-due bill for which consumers report being contacted by debt collections. The pandemic only increased the debt load for many Americans, despite insurer cost-sharing wavers. And, given that more than three in five adults struggle to pay medical bills even with insurance, it's clear that insurance alone does not provide adequate protection against medical debt.

New solutions and approaches are needed, and insurers have an important role to play. Existing strategies addressing medical debt - such as stopping lawsuits, negotiating repayment terms, removing it from credit reports and even charity buyouts of debt — are important but do little to actually prevent debt.

A new series of reports from the Financial Health Network, the nation's leading authority on financial health, and the Robert Wood Johnson Foundation finds that healthcare system actors, including hospitals, insurers and employers, can all intervene earlier to curb the risk of debilitating medical debt.

Medical Debt is a Social Determinant of Health

Medical debt forces tradeoffs in basic needs, such as choosing between food and paying off debt, disrupts physical and mental health and often leads to litigation, property seizure, wage garnishments, reduced credit scores and even bankruptcy. The financial implications are far-reaching, limiting consumers' ability to buy homes, pay for education, advance careers, build savings and pay off other debts, such as credit cards and student loans. Individuals with medical debt have triple the incidence of mental health conditions such as anxiety, stress and depression. And those with medical debt are more likely to forgo necessary care due to costs, potentially exacerbating health conditions and increasing healthcare costs down the line.

Worse, the burden of medical debt and its adverse implications disproportionately affect those with lower incomes, those who experience chronic illness and disabilities and Black, Latinx and indigenous households. For instance, 28% of Black and 21% of Hispanic households have medical debt, compared with 17% of white households. This creates a spiral wherein those least able to manage debt continue to incur more of it in their pursuit of medical treatment.

See also: Why Financial Wellness Is Elusive

Insurers as the First Line of Defense

Health insurers play an important role in stopping medical debt before it starts. This is especially true among the commercially insured, because the way in which members understand, use and experience their insurance can lead to unexpected medical debt.

Unfortunately, most members do not fully understand insurance terms, and lower health insurance literacy -- the ability to understand, select and use insurance -- is associated with higher medical debt. In fact, more than one in four Americans report forgoing care because they are unsure what is covered by their health plan.

Further, members can be caught in the middle or left with excessive medical bills when providers and insurers do not settle disputed claims quickly. Even worse, more than a quarter of adults in employer-sponsored plans are now considered underinsured.

Not only does acting to prevent medical debt fit under insurers' efforts to address the social drivers of health, but it can help to improve overall health and health equity. Our research found four key actions insurers can take to curb medical debt, improving the health of their members and the larger healthcare ecosystem:

  1. Aid members in plan selection, and ensure members understand key health insurance terms. Insurers need to support members in selecting plans based on their particular health and financial circumstances with decision support tools, and ensure members understand health insurance terms.
  2. Inform members of out-of-pocket expectations and how to navigate lower-cost options through effective price transparency resources. Insurers have a responsibility to support member decision-making by providing user-friendly, accessible and plain-language explanations of out-of-pocket expenses so members can plan for and navigate these costs. Knowing the cost of care in advance allows members to better budget for those payments.
  3. Encourage primary and preventive care services by reducing or eliminating associated out-of-pocket expenses. This can prevent the need for unnecessary or costly care that puts members at risk for medical debt. This is particularly important for members with chronic conditions who tend to require more frequent and sometimes more customized care to manage their conditions. The same may be true for members experiencing long COVID symptoms.
  4. Improve claims adjustment and prior authorization processes. Insurers should coordinate with providers to ensure disputed claims are settled quickly. Insurers should also streamline prior authorization, which can often be burdensome for members and providers and create delays in care.

These actions can lower members' risk of medical debt and should be part of insurers efforts to create more responsive, member-driven care. Doing so can improve member experiences, improve health and health equity, prevent members from catapulting into financial ruin, drive use of higher-value and lower-cost care and even help insurers build a competitive advantage.

You can read the full Insurance-focused report, as well as the other reports in this series on medical debt as a social determinant of health, here.


Uzma Amin

Profile picture for user UzmaAmin

Uzma Amin

Uzma Amin is a manager on the program team and comes to the Financial Health Network with a passion for healthcare. Amin's background is in community-based public health, working with vulnerable populations around social services and substance use. She has used these experiences as a lens and means for advocating for the underserved in her other work in healthcare communications and strategy, human-centered design and social entrepreneurship.

Growing up in a low-income, immigrant family, Amin has experienced the challenges of achieving financial health in the U.S. In graduate school, she developed her interest in inclusive economic development and is interested in exploring the connection between physical health and financial health to create healthy and resilient communities.

Amin holds a master’s of public health focused in healthcare management from Yale University and a B.A. in South and Southeast Asian Studies, with a minor in global poverty, from UC Berkeley.

A Glimpse Into the Future

Every once in a while, we get a glimpse of the future in the here and now. The strategic uses of cameras and digital communication in Ukraine show where insurers are headed. 

Image
a view of a city skyline and a blue sky. There is a darkened portion of the photo that is the outline of a man staring off in the distance.

A favorite line among technophiles is that “the future is here; it’s just not evenly distributed.” Every once in a while, we get a glimpse of the future in the here and now, in a way that can help us prepare for when that technology or way of life will become pervasive.

And I believe that the exceptionally quick, vivid and detailed coverage of the Russian invasion of Ukraine shows us what a truly connected world will look like – a world that all businesses, including insurers, are moving into, whether they like it or not.

We talk a lot about living in a connected world, with the IoT, telematics and so on, but we’re actually still in a pretty primitive state. I’d say the world of business is connected in much the way the world of communication was connected for the coverage of the Gulf War in 1991 – some crackly video, often days after it was shot; audio reports from correspondents while the TV showed a map; reports from military headquarters, etc. But the world of business is moving toward the world of unlimited communication and cameras and sensors everywhere that is giving us almost instant understanding of what’s happening on the front lines in Ukraine. The implications will be profound.

Think back to early this year, as Russia massed troops on the Ukrainian border -- and satellites let everyone see what was happening. While Saddam Hussein had managed to surprise the world with his invasion of Kuwait in 1990, even a cable-TV audience today could watch what Putin was doing. He insisted that he intended no harm, and some commentators bought the line, but then the satellites saw medical units being moved up to the border, including supplies of blood -- a pretty clear sign that he intended to attack.

He did, on Feb. 24, and all sorts of other cameras came into play. While few TV cameras were in Saudi Arabia in 1991, and transmission via satellite was spotty as the U.S. and allies geared up to retake Kuwait and then attacked, cameras are everywhere in Ukraine. Living on the U.S. West Coast, 10 hours behind Kyiv, I could turn my TV on at 9 every night, see the scenes from cities across the country and assure myself that Ukraine still stood.

That sort of coverage helped Ukraine President Volodymyr Zelenskyy rally support from the international community and turn some initial victories into a resounding defeat of the overwhelming Russian forces in the northern part of Ukraine. The availability of cameras and high-bandwidth connections has also let Zelenskyy boost morale by showing himself daily and even to address the U.S. Congress and the E.U. Parliament.

The ubiquitous cameras in people's phones have captured video of Russian atrocities, like a tank veering from its path to run over a car with an old man in it (miraculously, he survived) and like all the bombings of civilian targets, including a maternity hospital. The cameras also broadcast the remarkable courage of the Ukrainians, such as someone popping out from behind a tree to fire a Javelin missile and blow up a Russian tank at the head of the convoy, making the whole convoy a stationary target, or such as the intrepid farmers who hitched up tractors to tanks and hauled them away if they were briefly left behind because of a mechanical problem or because they ran out of gas.

In the Gulf War, you'd get some action footage, but not at this level of intimacy, not this quickly and not from the very front lines. (I have pictures of myself from 1991 standing in a Russian tank whose top had been blown off, but I assure you that no combatants were anywhere in the vicinity.) Russia has banned journalists from entering Mariupol, to hide the hardships that its siege is inflicting on residents, but satellite images let us count just how many desperate people are standing in line outside supermarkets. Today, satellites can see the front lines or even beyond, even when journalists can't get there. 

The adage says that the first casualty of war is truth, but satellites have even pushed back there. When the Russians pulled back from Kyiv over the weekend, they claimed that the hundreds of dead civilians left behind had actually been killed by Ukraine or that the scenes had been staged. But, as this New York Times article documents, satellite images showed that the bodies had been in the streets of Bucha for weeks, while the Russians controlled the area. 

Thomas Friedman of the New York Times refers to the invasion of Ukraine as World War Wired because of all the digital aspects to it. He writes: 

"Anyone with a smartphone and a credit card can aid strangers in Ukraine, through Airbnb, by just reserving a night at their home and not using it. Teenagers anywhere can create apps on Twitter to track Russian oligarchs and their yachts. 

"Meanwhile, Ukraine’s government has been able to tap a whole new source of funding — raising more than $70 million worth of cryptocurrencies from individuals around the world after appealing on social media for donations." 

What happens to insurance when the future becomes more evenly distributed and a Ukraine war-level of connection takes hold broadly? We can already see pieces of that future.

Telematics, while progressing slowly over the past two decades-plus, is nonetheless offering real-time observation of drivers. Cameras on the rearview mirror will increase that monitoring -- then autonomous cars will change the game entirely. 

The ever-present cameras in our phones are already being used to take pictures of car accidents and damage to homes, to speed the filing and processing of claims and to lower costs. Those cameras are also being used increasingly for do-it-yourself home inspections. Drones are being used to inspect rooftops, especially after major storms. All of those trends will continue.

And I think the satellites that are playing such a role in Ukraine will become increasingly important. If you can count people standing outside a supermarket in Mariupol, why can't you routinely check on the homes you insure to warn of risks -- perhaps a problem with a roof or the growing potential for flooding or a mudslide -- or make sure a home is properly insured after the owner installs a pool or a trampoline? At a macro level, satellites will make it increasingly possible to monitor the effects of climate change -- erosion, the effects of increased heat on water supplies, etc.

Cameras will also feed social media. Just as the images out of Ukraine are touching people's hearts, consumers will increasingly use images and videos to document and share their interactions with companies. In my experience, I'm sorry to say, consumers are much more likely to share complaints than to offer praise, so I'd say insurers should be prepared to deal with unhappy customers who tell compelling "stories" on social media using visuals designed to make a company look bad. 

Finally, while the issue doesn't relate to what's happening in Ukraine, I'd say insurers also need to be increasingly prepared for unhappy customers to start producing audio recordings of their interactions with agents and other representatives. Those smartphones don't just contain cameras; they're all recording devices, too. Disputes about guidance may no longer be, he-said, he-said; they may be, he-said-and-he-has-the-recording-to-prove-it.

War drives innovation to the extreme because so many lives are at stake, and it'll take insurance a while to catch up to the cutting-edge uses of technology happening in Ukraine. But we'll get there, and we can start preparing for the implications now.

Cheers,

Paul

Is Insurtech a Superpower?

Only if it's used right. Root is having problems, but Discovery Insure shows how telematics can make a profound difference. 

tech

I've spent the last six years bragging about insurtech's potential in improving the insurance business, for instance in the 2016 article My Four P's of Insurtech and, at the end of 2017, the book All the Insurance Players Will Be Insurtech. One of the insurtech topics I have talked most about has been telematics (usage-based insurance for my U.S. friends), such as in The Past, Present and Future of Telematics and UBI

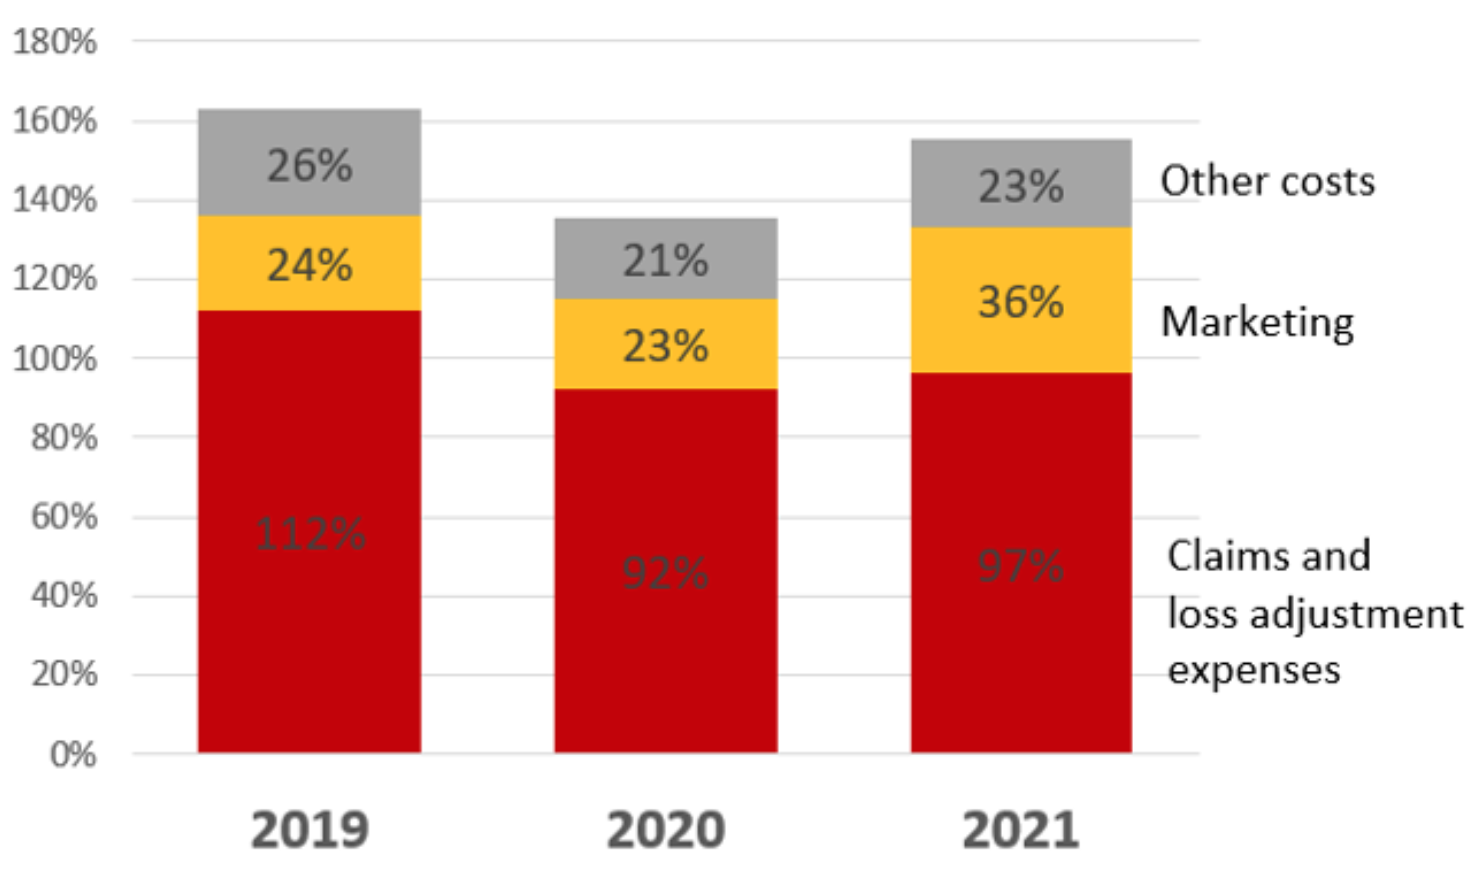
But, since its inception, Root's auto insurance book has not performed well. For each dollar of premium paid by the client, their risk transfer approach has always cost more than $1.35 (Lemonade has done worse.)
chart

So we have an insurer that in 2017 underwrote $4 million in premiums and -- in just four calendar years -- has scaled to more than $700 million. Root obtained a $3.6 billion evaluation at the halfway point of this journey.
headline

As of March 25, that valuation had tumbled to slightly above $500 million. Something has not gone as they expected.

In recent weeks, we've read about Root reducing marketing and other expenses:

However, these cuts don't seem to compensate for the main problem: the amount of claims compared with the premiums.

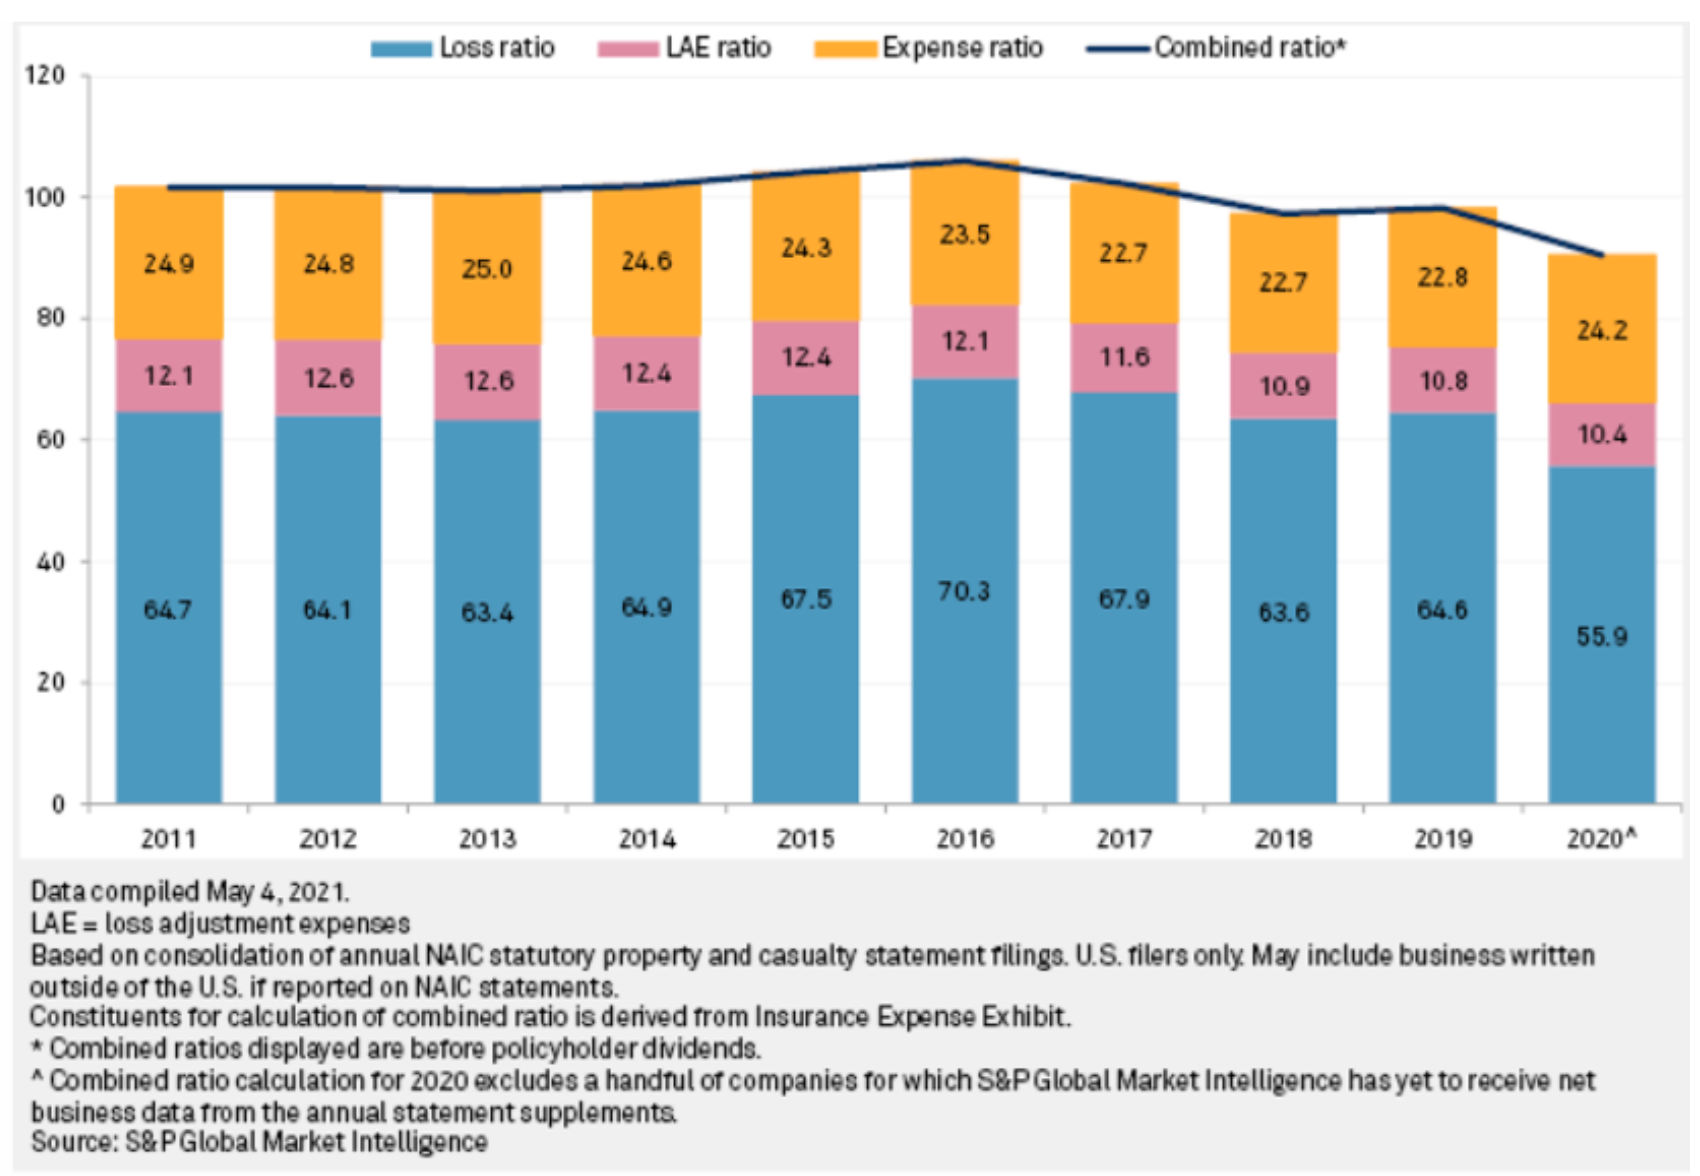
For reference, this is the historical series of U.S. auto insurance key performance indicators (KPIs)...
chart

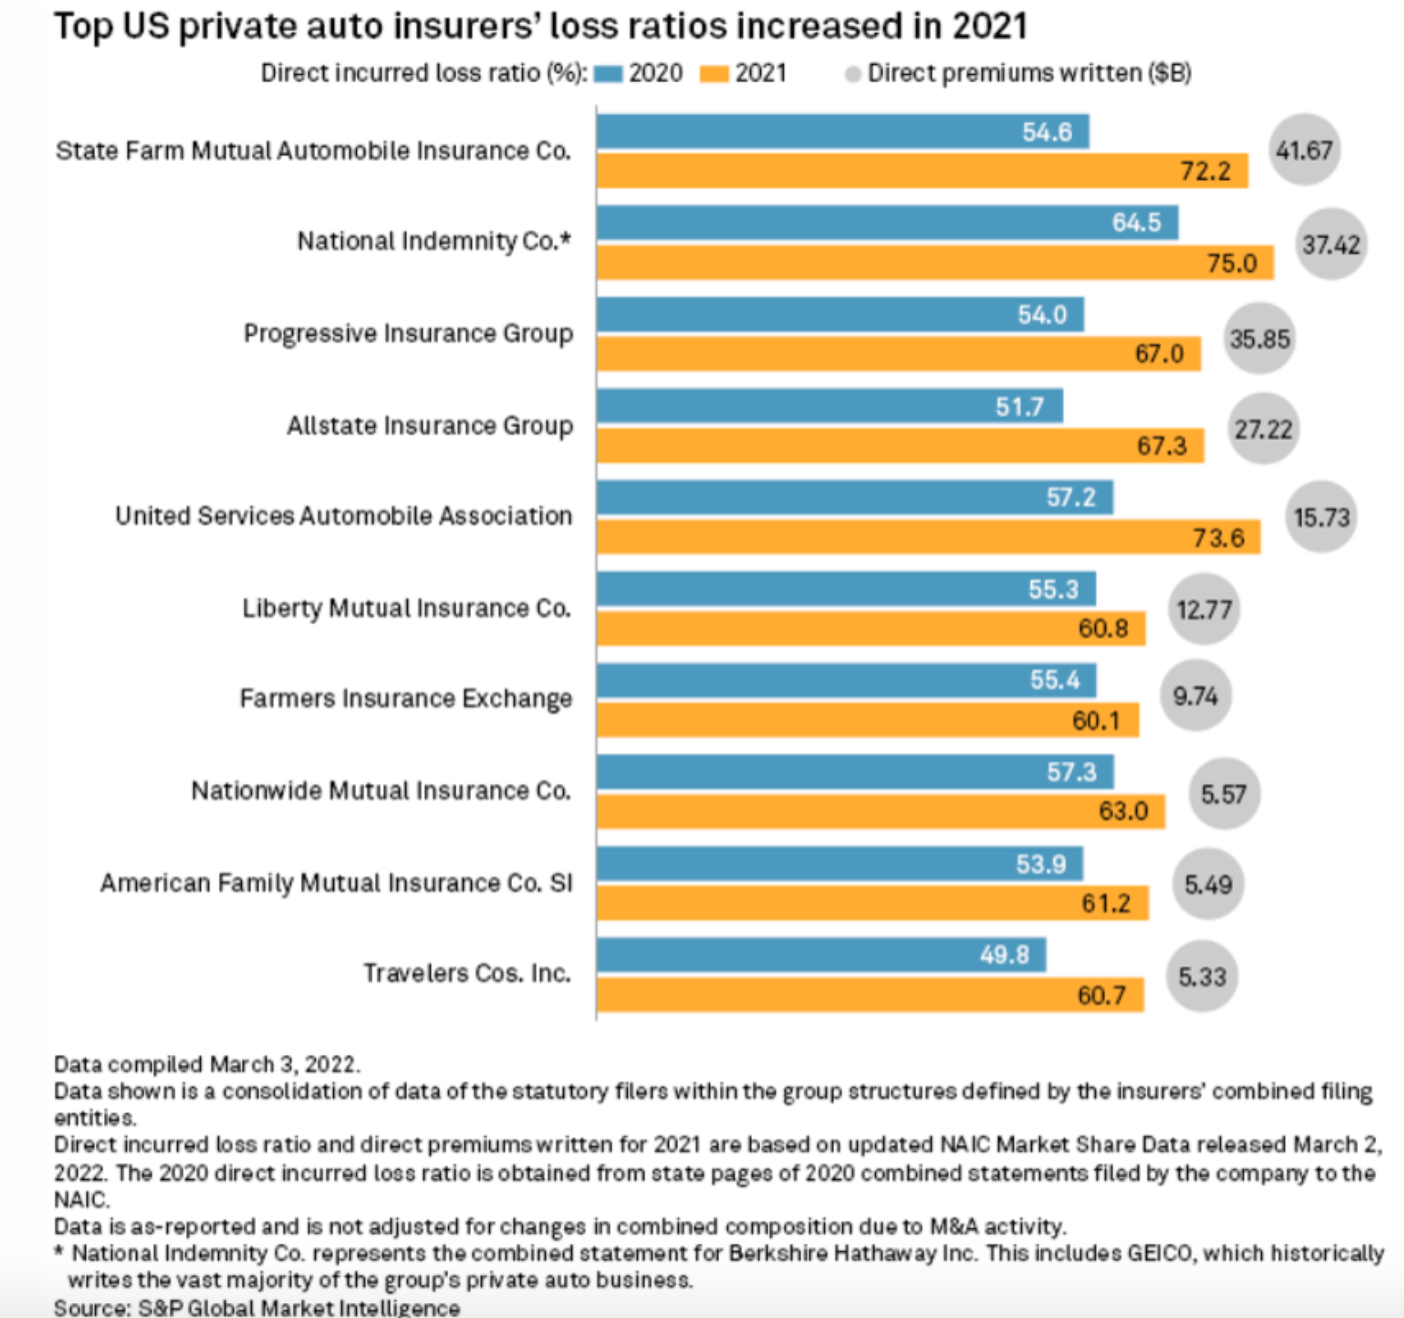
...and the evolution of the loss ratios in 2021:
chart

Here we have the key point: the book of business' (un)profitability and the role of insurtech (usage of telematics data).

How it started

Root started its journey in 2015 and the following year began to transfer risks using telematics:

I like this idea of using telematics data for providing the first quotation. Even Progressive has liked it (this probably is even more indicative that it makes really sense) and introduced Snapshot Road Test in 2020.

See also: 5 Tips to Ensure an Insurtech Fails

How it's going

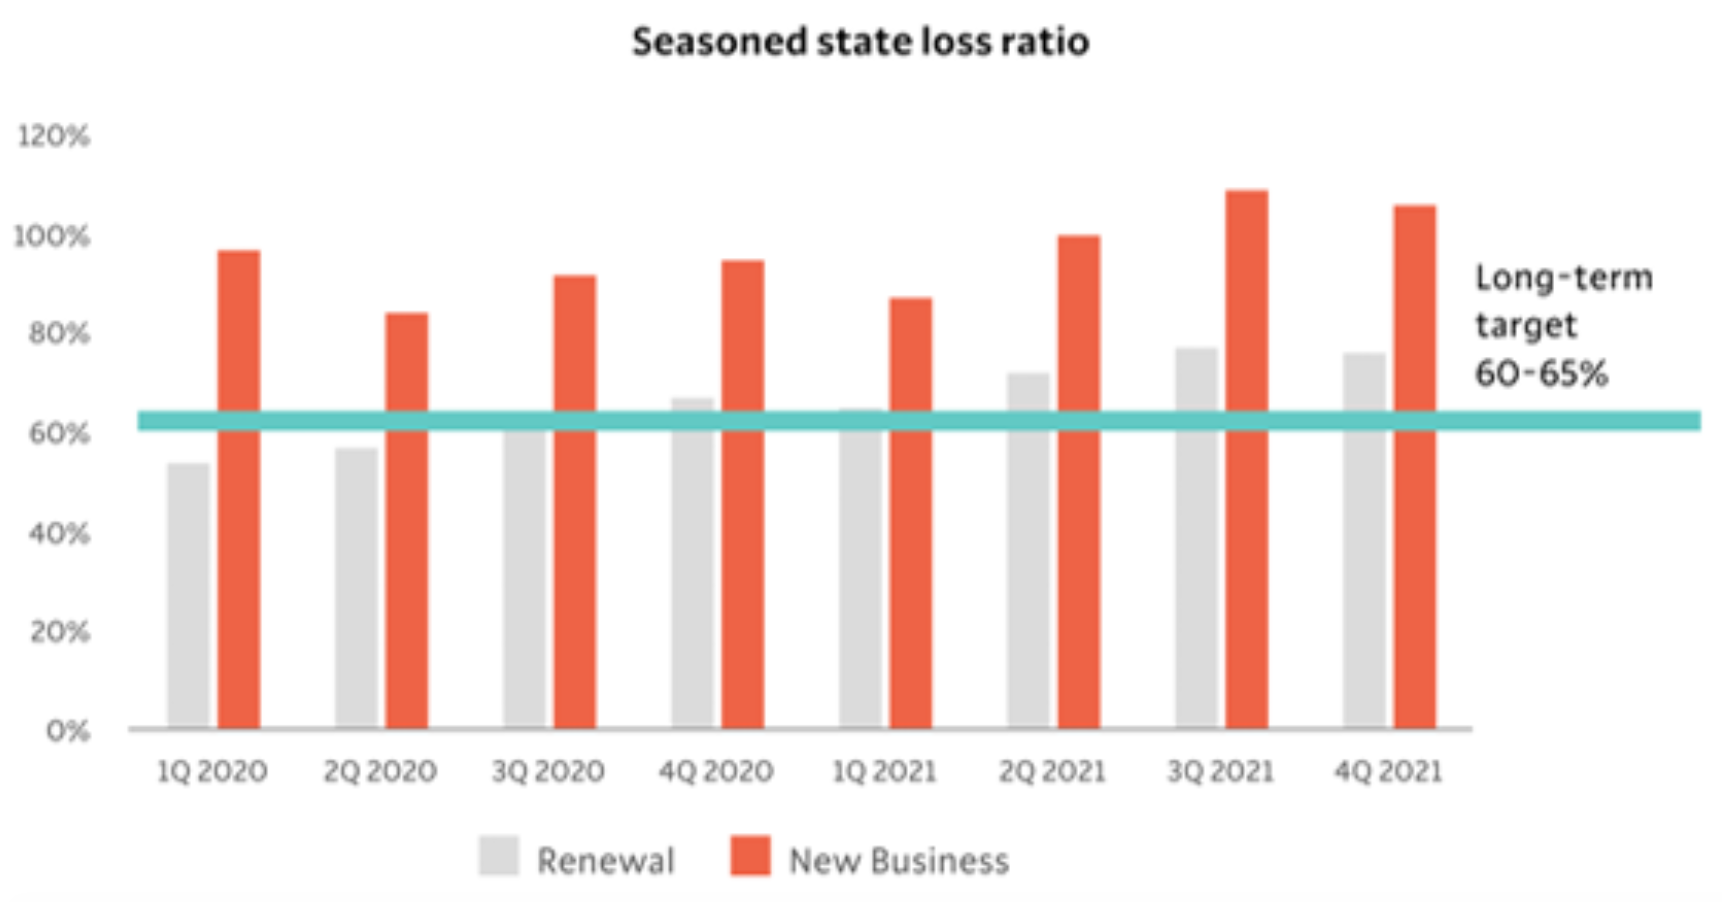
Root's loss ratio has been really, really bad for the new policies, and not too bad for the ones they have renewed.
chart

From Root's Form S-1: "As of June 30, 2020, our term one and term two policy retention rates, excluding policies that do not make it through the underwriting period and company-initiated rescissions, were 84% and 75%, respectively. Over time, retention rates may improve as we build deep relationships with our customers, and already we are seeing an improvement in retention with bundled offerings. Our retention rates include customers that retain through the first day of the subsequent term and exclude policies that do not make it through the underwriting period, as defined by state law, and company-initiated rescissions. Adjusting for these customers reduces one- and two-term policy retention by 33% and 10%, respectively."

From an oversimplified, outside-in perspective, Root's usage of telematics data for insuring only good drivers (eliminating the other drivers) and charging them an adequate price is not performing well at all: the first period of coverage has an awful loss ratio!

The company needs to prune the portfolio at each renewal.
post

Even Lemonade has started to play with telematics data and acquired Metromile (the pay-per-use insurance icon). I recently spoke about this situation in Business Reporter's Future of Insurance, claiming that insurance professionals have chosen the wrong insurtech idols!

Root is not using telematics data well for pricing and risk selection. Moreover, they have even denied the usage of telematics data for claim management and for changing driver behaviors.

But there are many different startups and incumbents’ initiatives out there that are showing great returns on their telematics investment and can be used as inspiration.

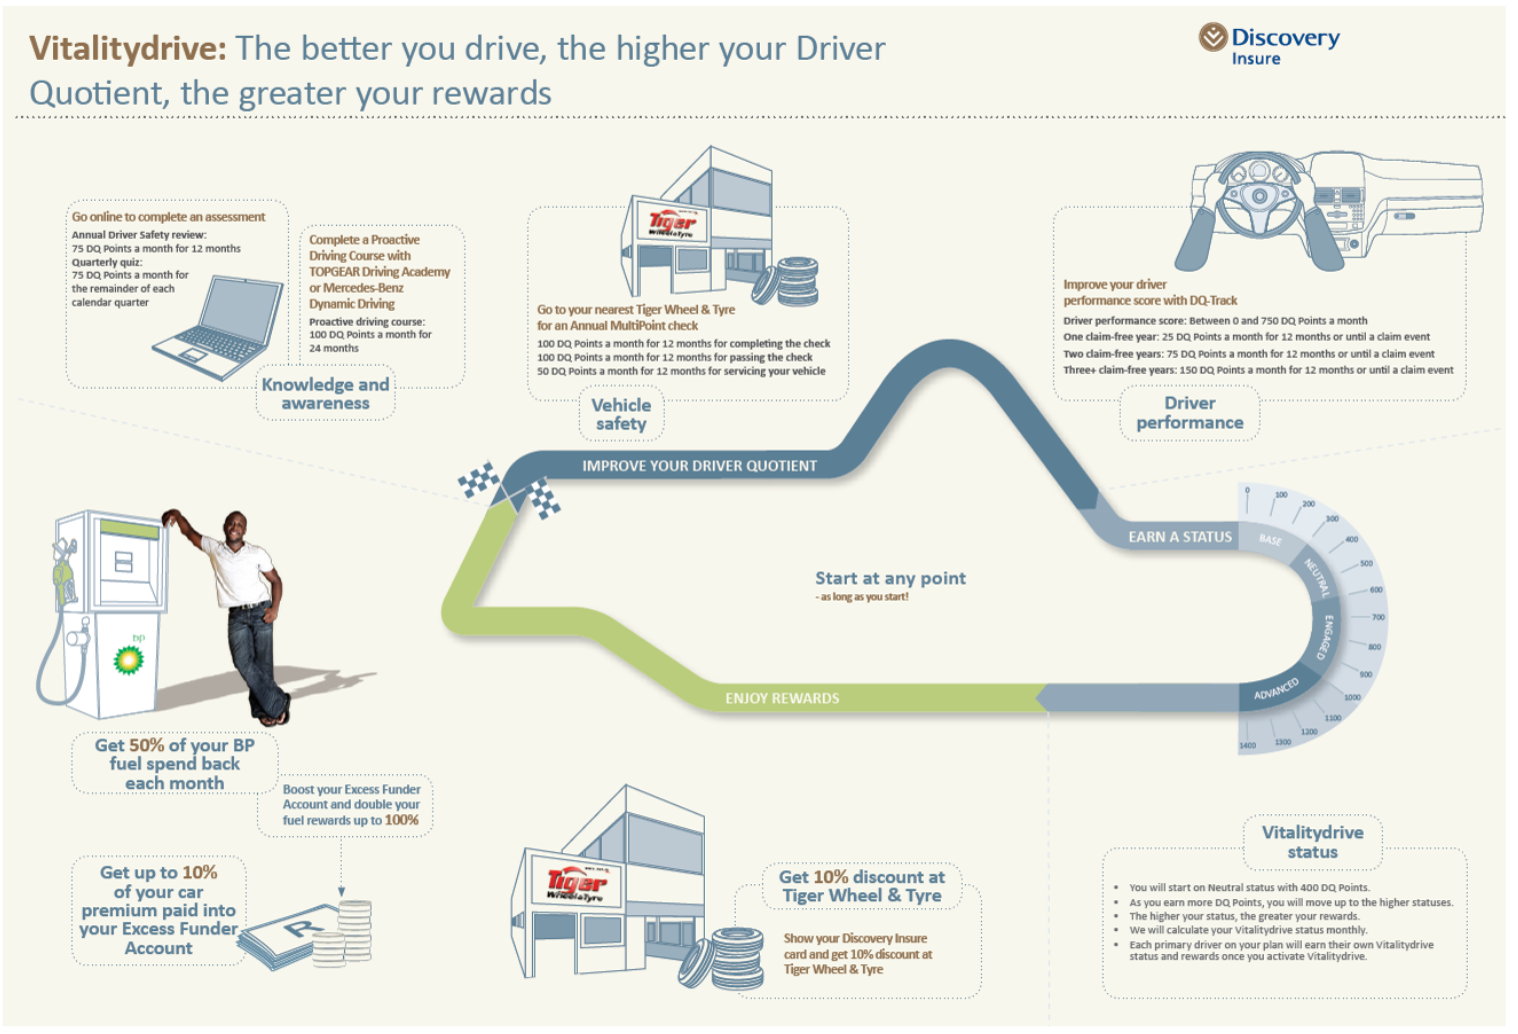
One great example comes from one of the members of my IoT Insurance Observatory: Discovery Insure. I fell in love with this telematics approach in 2013 when I saw their brochure for the first time (below) and I started studying their behavioral change approach. My recent exchange (below) with their CEO Anton Ossip shows the potential of telematics data in the auto insurance business.

This is a great example of Insurtech as the superpower for assessing, managing and transferring risks.
picture

Matteo: We have known each other for almost 10 years, and I have enjoyed discussing with you the sequence of innovation cycles you and the Discovery Insure team have implemented. How has telematics been relevant in this journey?

Anton: Our business began in June 2011. The simple premise was whether we could create a business that encouraged and rewarded people for being better drivers. This was especially relevant in a South African context, where we had the third-highest road deaths per annum in the world. We had the benefit of 20 years of shared-value insurance that Discovery had pioneered globally through the Vitality program that encourages people to live healthier lives. We believed we could leverage off this science and know-how to achieve this. That is how Vitality Drive, our behavioral-based incentive program, came to be. When we first started the business, the use of telematics technology in the insurance industry was not common, but it enabled us to offer a highly differentiated value proposition to an otherwise saturated market. Through vehicle telematics, we are able to accurately measure a client’s driving behavior from how and when they drive to whether they use their cellphones while driving. By doing this, we’ve been able to collect over 14 billion kilometers of driving data, which has allowed us to risk-differentiate and offer more accurate premiums as well as provide exceptional rewards to our clients who drive well. Our telematics technology also allows us to provide unique safety features to our clients, such as Impact Alert, where we can detect if a driver has been in an accident and send emergency assistance without them having to call us.

Vitality Drive has proven to be an extremely successful value proposition, not just for our business but for our clients, who receive significant value. Over the last 11 years, we have grown to be one of the larger insurers in our market, growing at double digits, profitable and demonstrating constantly improving actuarial dynamics. We recently spoke about our journey since inception, which I have linked here.

Matteo: I’ve always admired Discovery’s capability to track the innovation initiative impact. Could you share the main economic benefits achieved through the usage of telematics?

Anton: As a business with lots of actuaries, measuring every aspect of the business is part of who we are. From day 1, we saw the incredible correlation between driving ability as we measure it and claims frequency and severity. In our experience, there is so much value you can get from telematics, but it’s not just the data that achieves this. It is ultimately how it’s used. The Vitality Drive program engages customers throughout their journey with us, and through this we have been able to achieve the goals we set out for ourselves, including:

  • Attracting the best drivers. We found that drivers who joined Vitality Drive were on average more than 27% better drivers than the general population.
  • Improving their driving behavior. On average, clients who install a telematics device have a 15% improvement in driving behavior within 30 days.
  • Improving our loss ratio and passing these savings back on to clients. We found that our best drivers have on average a 54% lower loss ratio than our worst drivers. This allows us to reward these drivers with over 70% of their premium in rewards.
  • Retaining the best drivers by offering them greater rewards. We find that our drivers with a Gold or Diamond Vitality Drive status have an 84% lower lapse rate than drivers with a Blue Vitality Drive status. Over time, this decreases our overall loss ratio and lapse rate.
  • Getting to our clients the fastest and offering valuable safety features. For instance, in the last half of 2021, we reached out to over 36 000 clients when our data detected in real time that they might have been in an accident.

The data we’ve gotten from our telematics devices has also given us the ability to innovate and adapt our model over time so that we are able to offer the most relevant benefits to clients"

Matteo: Is it possible to change policyholder behaviors? This is a question I had to address in many of the workshops with the IoT Insurance Observatory members for the last six years in Europe and North America. Could you share something about the lessons learned and achieved results?

Anton: Yes, through Vitality Drive, we have seen that it is possible to positively change behaviors. We have seen that the Vitality drive program achieves behavior change quickly, where we see an incredible improvement in the driving behavior of our clients as a result of installing a telematics device. On average, drivers have a 15% improvement in driving behavior within the first 30 days.

But we’ve also put the mechanisms in place to sustain this over time. Most drivers know that some of the things they do when driving are not ultimately good for them or those around them. As an example, it’s no surprise that texting while driving is a very dangerous thing to do. This is where the concept of goal setting comes in. Merely educating clients driving well does not encourage behavior change, even though people will often recognize the importance of such behaviors. By setting challenging yet attainable goals and providing explicit rewards for achieving the result, people increase their effort to improve the relevant behavior. Vitality Drive offers weekly rewards for meeting your drive goal, and we’ve seen that people who meet their goals every week improve their driving behavior 15 times more than drivers who only achieve their goal once a month. So, without the correct nudges offered in the right way, most people don’t change their behavior.

See also: Time to 'Flip the Bird' on Insurtech

By combining our telematics data with our claims data, we are able to more accurately predict accident risk. We see that clients who drive better (as indicated by their driving scores) are less likely to get into an accident. Clients who improve their driving behavior score by more than 300 points in one year have a 24% reduction in their motor accident frequency, again showcasing the efficacy of the model.

Matteo: Looking to Discovery Insure’s journey, I have seen a focus on innovating commercial auto over the last few years. Would you like to share any facts and figures about these new offers?

Anton: The transport sector contributes significantly to GDP, with 76% of freight in South Africa being transported by road. Three and a half years ago, we extended this to business customers and now have a growing base of commercial fleet drivers on the Vitality Drive for Business program. Our commercial presence is growing quickly, with the size of book doubling annually over the past two years. Discovery Business Insurance is a natural extension of Discovery Insure and is committed to creating better businesses by sharing value through incentives. Even during this early stage of our Vitality Drive for Business program, we have seen encouraging results from Vitality Drive for Business that show that vehicles driven by better drivers have a lower loss ratio. Our driving data shows that vehicles that have the best drivers have a loss ratio that is 87% lower than those vehicles that are not on the Vitality Drive for Business program.

We have also extended the Vitality Drive program through partnerships with Covea in the U.K. (Vitality Car) and in the Saudi market as (Tawuniya Drive). Both of these businesses show favorable dynamics and provide the opportunity to make a significant impact to drivers in those markets. We expect such partnerships to continue to develop over the next few years. We haven’t stopped at developing a program for personal lines clients.

3 Trends Driving Growth in Parametric Insurance

Clients, brokers, insurers and investors have woken up to the possibilities of simpler, faster catastrophe insurance, and they are already experiencing the benefits.

storm

As FloodFlash CEO, my focus gravitates toward certain news items as they float across my personal ticker. So far this year I’ve been drawn to the events industry re-opening and how we will finally be able to meet the brokers we work with across the U.K. and overseas, and then to the Met Office as the weather forecasts showed the first warnings that ultimately became Storms Dudley, Eunice and Franklin, all of which struck the U.K. in February.

These storms filled my newsfeed as wind, rain and snow pummeled the U.K., eventually leading to widespread floods. FloodFlash claims are almost entirely automated, so having that heads-up two days in advance has little impact. We have removed loss adjustment from the process, so there’s no need to mobilize early or book support functions. Nonetheless, I keep an eye on the events and trends that will affect FloodFlash in the coming hours, months and decades.

A career quantifying the probability of "black swan" events has taught me that the world is full of randomness. I sympathize with the unknowableness espoused by Nassim Taleb rather than the idea of pre-written destiny found in the world of Hollywood (although the latter makes for a better movie). However, trends sit below the randomness. The confluence of these trends has the power to steer products, companies and markets.

One such market, that of catastrophe insurance, plays host to two sets of unstoppable macro trends. Climate change, population growth and urbanization are all driving up annual catastrophe damages. And increasing computer power and the proliferation of IoT networks mean that mass-market parametric insurance is possible for the first time. These trends will shape the catastrophe insurance market for years to come. They are also why Ian and I started FloodFlash.

Those macro trends explain why parametric insurance has started to take hold. In this article, I want to explore three smaller but significant trends that are accelerating parametric growth. Together, they explain why parametric insurance has gone from a conference buzzword to form award-winning coverage used by clients worldwide.

#1: For the first time, all businesses understand what they need to survive a catastrophe

Catastrophes kill businesses. The U.S. Federal Emergency Management Agency (FEMA) says “90% of smaller companies fail within a year unless they can resume operations within five days.” COVID created a world in which every business is alert to the threat of being closed.

The best way to steady a business whose source of income is in crisis is to provide cash fast. This is where the gap between traditional and parametric insurance products begins to emerge.

Traditional claims employ an arduous loss-adjustment processes. Catastrophic flood claims take months to resolve. That’s months in which a business might have no source of income but plenty of debt in the form of mortgages, rent, staff wages or tax liabilities. When protecting a business’s balance sheet, you sacrifice time at the altar of perfect indemnity. Not just time waiting for the final settlement, but staff resource managing and chasing the claim, too. And, as FEMA says, time is the one thing businesses can’t afford to lose.

Parametric insurance uses pre-defined values for claims. That means insurers remove the value of damage from the underwriting equation, and with it the requirement for claim adjustment. Parametric claims happen in hours, not the months it can take traditional catastrophe coverage to pay out. FloodFlash paid a Storm Franklin claim in under six hours. In the wake of COVID, that’s what businesses demand, and need, to survive.

It’s a relief to think that you don’t have to bother with chasing insurance companies. Most businesses with any sort of business interruption spend so much time trying to sort out the claim[…] It does involve the individual running the firm, and usually the top person within the firm. To take away that worry so the people running it can just get on with their business is a hell of a relief -- Clive Steggel, whose business, CRS Consultants, flooded during Storm Christoph in January 2021.

See also: Parametric Insurance: 12 Firms to Know

#2: Hard markets drive insurance innovation

Like any other market, insurance has the dynamics of supply and demand. On one hand, there are people looking to buy insurance coverage for their risks. On the other are those with capital looking for a return by covering that risk. When there is plenty of money in the system, supply of capital is plentiful. That means lower insurance premiums and looser policy wordings: a "soft market."

When money flows out of the insurance market – typically due to paying out claims from one or a series of catastrophe events – the supply of capital tightens. There is less capital to insure the same amount of risk. Premiums rise, and risks are harder to cover. We are experiencing a “hard market” right now.

Insurance prices have risen consistently over the last few years, and COVID-19 has made capital and capacity even harder to come by. According to the Marsh Market Index, global property insurance pricing increased by 17% in Q1 2021, with U.S. prices increasing by 14% in the same period, capping off many months of increases.

One of the first casualties in a hard market is catastrophe coverage. When the supply of capital runs dry, insurers are more reserved about the business they write. Policy wordings tighten, prices increase and exclusions start to creep in. This is where parametric insurance comes into its own.

Parametric insurance is attractive in hard markets for two reasons. The first is the lack of uncertainty: Using pre-defined values for a claim means the insurer is exposed to fewer variables. Insurers pass that benefit on to clients as lower premiums.

The second reason comes down to how parametric covers are structured. If a client sees an unattractive price, they can adjust the parameters of the coverage to suit their budget. They might not get penny-perfect indemnification, but they have coverage in place to protect their cash flow and survive.

The adage that "necessity is the mother of invention" holds true in the insurance market. Previous recessions have hosted the creation of some of the world's most successful technologies. Necessity is now driving the demands for parametric covers. As a specialist parametric broker told me recently: “It has gone crazy since Christmas.”

#3: The word is out

I’m not the only person recognizing these trends. Venture capitalists concerned with what the world looks like in 10 years have also cottoned on. Renowned VC and early Facebook executive Chamath Palihapitiya announced his latest venture at the beginning of last year: OTT Risk, a platform for pricing and trading parametric business interruption coverage. Descartes Underwriting, Parsyl and Arbol have all announced big equity raises from VC funds in recent years. Not to mention the FloodFlash Series A raise announced earlier this year.

Fueled by this interest, new and exciting applications of parametric insurance principles are emerging and growing faster than ever. Clients, brokers, insurers and investors have woken up to the possibilities of simpler, faster catastrophe insurance, and they are already experiencing the benefits. The capital pouring into parametric insurance firms will fuel this growth.

These parametric insurance trends mean movement is accelerating every day. Based on the trends on my news ticker, 2022 is set to be a landmark year. By December, more livelihoods and more businesses in more markets will be protected – and survive – because of parametric insurance.


Adam Rimmer

Profile picture for user AdamRimmer

Adam Rimmer

Adam Rimmer is the chief executive officer at FloodFlash, the first parametric flood insurance available to the mass market.

3 Ways to Cut Defense Counsel Costs

Carriers can begin by simply challenging their outside counsel to deliver more value and then discussing how to get there together.

building

In 2017, a large insurance carrier challenged our law firm to significantly reduce its legal spending and cycle times without any material uptick in indemnity costs or compromise to the quality of legal services. Last year, the carrier publicly reported that the program we jointly developed was responsible for closing 25% of the carrier’s claims litigation annually with an average reduction in legal costs of 49% on closed files, which has led to millions of dollars in cost savings to the carrier.

Over the past five years we have implemented, tested and refined numerous measures to deliver those results. Along the way, we have learned a lot about how a law firm can deliver more value to an insurance carrier and its policyholders. Here are three critical items that any carrier working with outside defense counsel should consider and discuss with counsel.    

1. The Appropriate Staffing Model on Each Case

Typically, outside defense counsel will assign two attorneys—e.g., a partner (or partner-level attorney) and an associate—to each case. In fact, the litigation management guidelines for many carriers state that this is the expected or preferred staffing model. The conventional thinking is that the carrier does not want to pay a partner’s higher hourly rate for work that can be adequately performed by an associate. The problem is that, when two attorneys work on a case, there is invariably some duplication of effort. While the partner generally handles the more complex and strategically important tasks, both attorneys must review the pleadings, motions and discovery to remain informed. Further, the two attorneys must communicate closely. Two attorneys working the case means more overall attorney time, which translates to higher defense costs.

Carriers that employ staff counsel have figured this out. Carriers using a staff counsel model typically assign only one attorney to handle all aspects of each case.

Carriers that employ outside defense counsel would be well-served to consider the complexity of each assigned case and to work with counsel to identify those cases that can be staffed with only one attorney. Yes, that one attorney must be experienced, and, yes, that experienced attorney will handle basic tasks (e.g., direct oversight of drafting and responding to discovery, drafting and arguing simple motions) while billing at the partner rate. But, in our experience, the result is a meaningful reduction in average attorney fees per case. 

See also: Time to Send Employees to Sleep?

2. Methods for Identifying and Pursuing Risk-Transfer Opportunities

What better way to reduce defense (and indemnity) costs and shorten cycle times than to convince another party or its insurer that it is obligated to defend and indemnify a policyholder who has been sued? Outside defense counsel who are truly committed to lowering a carrier’s defense costs should implement measures to systematically identify and aggressively pursue risk-transfer opportunities. “Systematically” is emphasized here for good reason. Counsel’s efforts to transfer risk should be structured and methodical in each case. Here are some steps outside counsel can take:

  • Provide detailed training to all firm litigators on how to identify and pursue risk-transfer opportunities.
  • Create a checklist of information and items to be obtained from the policyholder to facilitate a risk-transfer analysis (e.g., contracts with vendors and management companies, other insurance policies that may provide coverage, etc.). During the very first communication with the policyholder, ask that all such items be immediately gathered and provided, and keep asking until they are received.
  • At the outset of each case, automatically assign the handling attorney the task of conducting a risk-transfer analysis and reporting the results to the carrier.
  • Create robust templates (preferably using automated document assembly software, as described below) for tender demand letters.
  • Develop a calendar with automatic reminders that prompt continual follow-up on tender demands until a response has been received.
  • Keep metrics on the cases resolved through risk transfer and use the metrics for process and performance improvement.

Risk-transfer opportunities are the proverbial “low-hanging fruit.” Carriers should work with their panel counsel to ensure that they are systematically (there’s that word again) harvesting this fruit. 

3. Time- and Cost-Saving Technologies

Software claiming to use AI has become all the rage and, without question, may be beneficial in certain types of cases (e.g., those that are document-intensive). But several more basic technologies can significantly reduce the time required to complete billable tasks on a wide variety of legal matters. Outside defense counsel should consider: 

  • Automated document assembly software: These programs have become very inexpensive to implement and simple to use. Various types of case-specific information—such as the case caption, court, case number, parties and their counsel, claim number, etc.—are typed in once, and thereafter documents are automatically populated. A small library of automated templates can save countless hours of time on each case.
  • Macros and autotext: Some text is used repeatedly in litigation documents. Consider, “Defendant lacks sufficient knowledge and information to form a belief as to the truth of this allegation and on that basis denies it in its entirety.” This language might be used repeatedly in an answer. Likewise, the same objections often appear many times in a discovery response. With macros and autotext, there is no need to type the same language again and again, or to repeatedly scroll to another location in the document, copy the text, scroll back and paste it. The language can be inserted with a simple mouseclick or keystroke. 
  • Quick steps and quick parts: These are similar to macros and autotext, but they are used in MS Outlook, reducing time-on-task for email communications. 
  • Task-based matter management systems: While the facts of each case vary, litigation is largely a series of repeatable events. Many matter management systems permit automated assignment of repetitive tasks and the ability to “program” into the task the relevant instructions and required information for completing it. Potentially billable time to provide such information and instructions (or to research it) can be minimized.
  • Role-based automated task assignment: Carrier litigation management guidelines often prescribe that certain types of work should be performed by qualified paralegals and billed at the paralegal rate. We use a system that automatically assigns such tasks to paralegals, thereby ensuring compliance with guidelines and billing at the appropriate rate. This reduces inadvertent overcharges and cuts down on administrative time (ours and the carrier’s) for invoice review.

See also: The End of the 9-to-5 Workday

You Can Get There From Here

The above are a few of the many measures and strategies our firm has taken to significantly reduce the legal defense costs for a large carrier. The results have been extremely well-received.

While none of the measures are overly complicated or difficult to implement, it does require commitment and discipline to consistently use them. We are all creatures of habit, and we tend to return to the same old ways of doing things until a newer, better behavior or routine becomes ingrained as the new habit.

With that said, any outside defense firm that is willing to commit to and invest in these strategies, and take steps to ensure that they are consistently used firmwide, should be able to meaningfully reduce carriers’ legal spending and cycle times. Carriers that seek such results can begin by simply challenging their outside counsel to deliver more value and then discussing how to get there together.


Christian Dodd

Profile picture for user ChristianDodd

Christian Dodd

Christian Dodd, Esq., is the legal operations partner for Hickey Smith Dodd LLP. He is responsible for the design, implementation and execution of the firm’s unique legal services delivery model.

Prior to joining HSD, Dodd practiced law for 10 years in the large firm environment, litigating complex commercial and business matters and intellectual property disputes. His experience ranges from simple B2B contract disputes to consolidated multi-district class actions and bet-the-company litigation. Dodd draws on his broad experience to devise strategies to improve efficiencies, reduce costs and better evaluate risk in litigation.

2022’s Top Trends for Property/Casualty

Efforts will include using technology to improve the ease of doing business for agents and implementing tools and applications to increase employee productivity. 

trend

New variants of the COVID-19 virus and the “Great Resignation” affected the insurance industry deeply in 2021 and are primed to keep influencing 2022. To enhance the customer experience and improve internal efficiencies, insurers’ focus this year is on digitization. 

These efforts will include using technology to improve the ease of doing business for agents and implementing tools and applications to increase employee productivity. 

Aite-Novarica Group has identified 10 trends that will shape property/casualty insurance around the globe in 2022 and beyond. These include:

  • Insurtech goes mainstream. Even during a global pandemic, investment in insurtech has continued unabated. One curious trend is that traditional core vendors now view themselves as insurtech firms or architects of insurtech adoption, with some acquiring startups in areas like predictive analytics. Speed to market is always a key objective for insurers, resulting in the growing trend of low-code/no-code engines in their core platforms.
  • Increased adoption of purpose-built AI-based solutions will change the game. Despite concerns surrounding data privacy, model bias and regulations like the European Union’s AI Act, insurers are continuing to invest in AI. Insurers are adopting purpose-built AI-based solutions to overcome financial and operational challenges. Core systems vendors are offering insurers access to these solutions through application programming interfaces (APIs) and open-platform architecture. These solutions tend to be cloud-based and can be implemented immediately. 
  • Insurers and distributors will come together to embrace digital. As insurers and distributors implement agent portals and vendor agency management systems, many of these solutions do not meet customer expectations in today’s digital world. The ability to offer capabilities such as real-time quotes and automated underwriting requires digital investments in online and mobile capabilities. Insurers and distributors need to work together to provide more robust digital capabilities and stay competitive.  

See also: Future of P&C Tech Comes Into Focus

While these trends will be important for property/casualty insurers this year and in the future, they are by no means the only areas of focus. Data and analytics, the evolution of cyber risk, claims optimization and more are occupying property/casualty insurers’ time and budgets. 

Customer expectations are at an all-time high, and countless digital technologies are emerging in the insurtech sector. Aite-Novarica Group expects insurers and vendors to continue working together to prioritize the insurance experience for all stakeholders as the year moves on.

To learn more about the trends our team foresees dominating the space in 2022 and into the future, please read our full report, Top 10 Trends in Property and Casualty, 2022.


Stuart Rose

Profile picture for user StuartRose

Stuart Rose

Stuart Rose is a strategic advisor on Aite-Novarica’s P&C insurance practice. He is responsible for market research and delivering strategic advice on applying data, analytics and technology.

Rose began his career as an actuary at a leading global insurer in both its life and property and casualty divisions. Prior to joining Aite-Novarica, he worked for a variety of software vendors, including at SAS for nearly a decade. He has been responsible for go-to-market strategies, product marketing and application development. He has extensive experience working with insurance companies across the globe, including in the U.S., the U.K., continental Europe, Latin America, Asia and South Africa.

Rose graduated from the University of Sheffield with a B.Sc. in mathematical studies. He is a regular contributor to insurance publications, frequently speaks at industry conferences and is co-author of the book Executive Guide to Solvency II.