Download

The End of the 9-to-5 Workday

As managers debate the future of remote work, the model of the 9-to-5 work day needs to adapt, too, and in some cases be eliminated.

Image
a man turned away from the camera, walking towards a white building. The man is in a suit and holding a bike

As corporate offices increasingly reopen, many managers are focused on finding the right mix of work from home and work in the office, and that's certainly important. But another key topic has been flying under the radar and deserves more attention: the fact that the model of the 9-to-5 work day needs to adapt, too, and in some cases be eliminated.

While many jobs don't lend themselves either to remote work or to variable work hours -- think of construction workers, restaurant employees, most doctors and nurses and so on -- many jobs in insurance afford a great deal of flexibility, and we'd do well to take advantage of what we've learned in the two years of working from home during the pandemic. Employers could see a boost in productivity, while employees could live healthier, better-adjusted lives. 

When many of us started working from home, we not only gained the time that our commutes used to eat up but found that we could structure our days however we liked. Sure, we had Zoom calls -- lots and lots of Zoom calls -- and we might be expected to respond fairly quickly to a boss or coworker during the meat of the day. But whatever output we were supposed to produce -- analysis for a claim, underwriting, whatever -- could then be slotted in whenever we wanted. 

Some of us work better in the morning and tackled projects when we were fresh. Others work better in the evening or even late at night (count me in that group) and increasingly pushed the work that demanded the most attention into those times of day when we thought most clearly and, perhaps, had the fewest interruptions.

Many of us learned the value of naps, something that would never have even occurred to me before COVID. In the past, if I felt tired, I'd have kept banging my head against a writing project because I felt locked into a work schedule -- but would have gotten nowhere. Now, I close my eyes for an hour and, when I return to the project, am clear-headed enough to feel some creativity and generate some flow. I'm more productive even if you count the naptime as work time. (I don't, of course.)

There still needs to be some coordination, of course. If a morning person is working with a night person on a project, simple communication could make a project take many days if they just keep passing drafts and questions back and forth, while having them both focused on a project for an hours-long stretch could allow completion in a single day. But, to the extent that individual, remote work is possible, breaking the 9-to-5 paradigm can deliver big productivity gains.

Employees may benefit even more. If they just owe a chunk of hours per week or a certain amount of output to the employer, they can sleep in when they're tired, can make that trip to the gym when they're most motivated, go shopping when there won't be much traffic and so on. Parents with small kids may benefit the most, especially if both work, because they can cover for each other. Work fits into life, rather than the other way around.

The biggest obstacle I see to greater variability in hours is that employers just aren't accustomed to measuring employee performance that flexibly. If an employee is in the office, the employer feels reassured. With remote workers, seeing that green signal of Teams shows that they're at their computer. Surely, some sort of work is going on. 

Employers will have to find new ways to evaluate employee performance, based on some combination of volume of work and quality. And, yes, some employees will game the system once constraints on hours are removed, so HR departments will have to stay on their toes. 

A recent New York Times op-ed on flexible hours says that "a few simple tweaks to work culture would make a big difference.... Scrap all but the most essential meetings. Don’t expect remote workers to be always available or use invasive software to keep them on task. Focus on results and normalize later start times. To foster collaboration among workers who are on different schedules, companies could set limited core hours."

I've actually lived that flexible future for more than 35 years. Even when I showed up at a Wall Street Journal office in suit and tie every day, the life of a reporter lets you do pretty much whatever you want. You show up early, you show up late, you leave early, you leave late, you work in the office, you work at home -- all that matters is what shows up in the paper, and that's there for everybody to see. (Once or twice, when I went a couple of weeks without my name in the paper, my father called and said he just wanted to be sure I was still employed there.)

When I became a partner in a consulting firm, I had to commute to headquarters in Chicago two or three times a month from the Bay Area, which was no fun, especially with little kids, but when I was home, I was home, and had lots of flexibility. If my daughters wanted me to jump in the pool with them in the middle of the afternoon, I could just about always indulge them (and myself). 

And the sorts of writing projects, mostly books, that I've done for the past 20 years, leading up to my work with ITL, have certainly allowed for flexibility, including probably the best decision I made as a parent. My younger daughter was a nationally ranked distance runner in high school, and I felt bad that she would have to head out in the heat in the summer to do a hard 10- or 12-mile run, so I made a standing offer that I'd go with her any time she asked (on a bike, of course; I couldn't possibly have kept up with her on foot). She'd pick a history topic and ask me to tell her about it for the hour or so she'd be breathing hard, which indulged my fondness for telling stories and would let me make some use of all the histories I've read over the years. Those run/rides were some of the best bonding time imaginable -- and she later earned a history degree from Yale, on her way to a law degree and a job in Washington, DC. 

Flexible hours don't work for many jobs, just as remote work doesn't, but, if flexibility is possible, I highly recommend it. And it's possible for a lot of insurance jobs.  

Cheers,

Paul


In Defense of Agents

Agents and Brokers Commentary, March 2022

two hands shaking over a laptop and a contract.

It's not often that someone tells me that something I published made him "physically cringe." In fact, I'm not sure I've ever received that particular form of hate mail. But someone made that claim recently on LinkedIn and tagged me, after I published at www.insurancethoughtleadership.com a piece that I thought was pretty straightforward. It argued simply that insurtechs should work with human agents to provide the human touch even as they improve the technology that connects with customers and insurers. 

The writer argued that "insurtechs can definitely be independent agents themselves and provide the advice and human touch that some customers require. I think this is the model that will be successful for transactional and simple products."

Who needs human agents?

I prepared to wade into the discussion -- and found I really didn't have to, because so many others had already made my points for me.

Matteo Carbone, who I think of as Mr. Insurtech, wrote in defense of the agent's role: "At a global level, only 6% of personal line premiums have been generated without a human touch."

Another wrote that, when insurtech platforms first came out, "Their leaders were implying that they are going to disrupt the existing system. Some belittled the existing system, only to turn to agents when they could not pull off what they initially claimed they would. Many did not have any insurance experience and knew very little about all the issues and moving parts associated with insurance. There just has been so much insincerity and frankly taking advantage of investors.... Is there a marketplace for selling insurance online? Sure, but it's not causing the disruption as some had falsely claimed it would."

Still another: "Look to the travel agent.... Despite popular conceptions, select travel agents are experiencing a golden age. How? They evolved to luxury and niche (complex) excursions for high-net-worth individuals or people with specialized interests (helicopter skiing, exclusive resorts, ecotourism, etc.) The ones who just assumed people would always be intimidated by booking basic holiday packages were devoured by Expedia (which absolutely provides advice and comfort via online chats). There's a salient lesson in there somewhere."

I'm not at all arguing that agents don't need to stay on their toes. As you'll see from this month's interview and from the articles we've highlighted, agents very much need to keep up with the times. And not all comments were so firm in their support of agents. (You can read the full exchange here:. I've highlighted the article below that stirred up the fuss -- "3 Reasons for Insurtechs, Independent Agents to Collaborate.")

But I did find it encouraging that so many rallied around the role of the agent, which I see evolving much as travel agents have.

That, and it's always nice to be read.

Cheers, 

Paul 


Paul Carroll

Profile picture for user PaulCarroll

Paul Carroll

Paul Carroll is the editor-in-chief of Insurance Thought Leadership.

He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.

Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.

Characteristics of an Effective Change Agent

84% of executives agreed that innovation is critical to their growth strategy, but only 6% are satisfied with innovation performance.

agent

According to McKinsey’s Global Innovation Survey, 84% of executives agreed that innovation is critical for their business and is an important component of their growth strategy, but only 6% are satisfied with innovation performance. This gap between strategy and results can be felt across the commercial insurance industry. While commercial lines carriers and brokers have focused intensely on digital transformation initiatives for the past several years, many lines of business, core operational processes and manual workflows have not been modernized in a meaningful way in 30 years.

We all know that digital transformation is a journey, not a destination. Large-scale change doesn't happen overnight, and digital strategies can take years to develop and implement.

“I’ve been in the insurance industry for 20 years, and, as long as I’ve been here, we’ve been transforming,” says Stacey Brown, head of global technology innovation, AXA XL, a division of AXA, and founder at InsurTech Hartford. “And I’m certain that, long after I’ve retired, we will still be transforming. Change is the only constant. There is always resistance to change. Everyone in an organization can know they need to change, but they can’t agree on how.”

We also know that change agents at all levels of the organization play an important role in sustaining the momentum of any innovation initiative.

Change agents are essential to overcome organizational inertia and resistance to change; they help motivate and align people around the “how and why.” But what qualities define an insurance change agent, and how can insurers identify and nurture those qualities? To help answer these questions, we reached out to several insurance industry leaders and subject matter experts who know first-hand what it takes to roll out successful digital strategies and mobilize internal change agents to embrace – and lead – meaningful change.

Change Agents Stand Out

A common theme is that identifying internal change agents isn’t an issue; they’re easy to spot.

“Innovative change agents often think outside the box, leveraging knowledge and experiences from a wide variety of areas – from different jobs, roles and industries to reimagine the possibilities,” says Denise Garth, chief strategy officer at Majesco. “Because of this background, they are often considered rebels or rabble-rousers who too often are discounted but instead should be embraced by leaders.”

Brown agrees: “Change agents are vocal for the most part. They tend to stand out in organizations because they are outspoken about how they see that things could be different. If you want to empower change agents and teams to embrace or lead change, you need to give them a reason. Help them understand why innovation is important and how it fits into the organization’s strategic goals. Find out what motivates them. The intrinsic and extrinsic motivators to embrace change will differ from person to person. Sometimes, ‘your job will suck less’ can be a motivator. Sometimes it’s incentive plans, promotions or opportunities to advance in their career and take on new challenges.”

The real challenge for insurers is how leadership responds to change agents – whether companies encourage challenges to “the way we’ve always done it” or attempt to ignore or suppress them.

“I would argue that one of the greatest roadblocks to digital transformation in commercial insurance is a lack of organizational courage,” says Jason McDermott, president and CEO of Chisel AI. “In an industry composed of professional risk managers, courage to challenge the status quo is not a natural strong suit; it must be purposefully cultivated and nurtured.”

It takes courage to step up and speak about the need to change and improve. “You need to be comfortable with challenging people, with being the only person at the table who thinks one way and who isn't going to get swayed the other way automatically,” says Mark Rieder, senior vice president, head of innovation at NFP, a leading insurance broker and consultant.

Any type of organization can transform its culture, according to Kris Østergaard, author of Transforming Legacy Organizations: Turn Your Established Business Into An Innovation Champion To Win The Future. “But it doesn’t happen by itself, and it is probably also the most difficult endeavor that organizations can set out on – much more difficult than getting to know and apply technology. Culture is the ‘hard problem’ of corporate innovation. It demands that companies transform their entire systems away from misaligned key performance indicators, legacy IT and business models, ineffective work methods, too-high-risk averseness built into strategies and business plans and short-term thinking. It has far more to do with this than it has to do with people’s lack of willingness to change. Of course, there is human resistance to change. It is a real thing. But human beings are actually remarkably adaptable to change – if they have the right conditions to change under.”

See also: Bright Prospects for 2022

Building a Culture of 'Change Resiliency'

“It all comes down to two things,” says Kacie Conroy, director of IT at M3 Insurance, one of the top insurance brokers in the U.S.: “Merge the IT and business worlds together to innovate and to experiment early and often. This means you need to build a culture of experimentation and change resiliency. That also means that the term ‘failure’ needs to be redefined. The only failure is not trying, not experimenting, and not learning. This approach allows you to learn, adapt and ultimately bring more value to your business.

“When cultivating innovation in your organization, locate those ‘intrapreneurs’ who thrive on change, are curious and think creatively to establish a foundation of innovation. Use this newly formed community to participate in pilots of new, innovative technology.

“Technology is the easy part. The focus, and the hard part, is all about HOW you innovate, HOW you implement the change. With seemingly unlimited options, it requires businesses to think more creatively like an artist when it comes to painting the picture of their innovation strategy.”

“What isn’t changing?” asks Amy Radin, author of The Change Maker’s Playbook: How to Seek, Seed and Scale Innovation in Any Company. “Today’s pressures are not defined by any one trend; they are the sum, with compounding effects, of multiple parts of the business model changing simultaneously, unpredictably and at times in conflict with each other.”

comic

“Change agents are people at the top and throughout an organization who provide leadership and direction that motivate, inspire and empower others to execute toward a new future state,” Radin says. Based on Radin’s experience, these leaders:

  • Recognize the inevitability of change and demonstrate urgency to act
  • Visualize a purpose and North Star direction
  • Magnetically attract diverse talent – intellectually curious, continuous learners and collaborators
  • Create a culture where people are empowered to execute, take risks and bring forth new thinking
  • Ensure people have access to required capabilities and resources
  • Establish governance that is fit for the purpose of transformation
  • Are decisive and role models of agility
  • Are customer- and partner-focused, letting market insights drive strategy 

NFP’s Rieder believes that insurance leaders who are effective at leading change and motivating change agents possess the ability to help people “come to a decision on their own and allow them to be the ones bringing the ideas to the table.” Innovation leaders need to “be comfortable with being behind the scenes, pushing people ‘towards the light.’”

Tapping Into an Innovation Ecosystem

While we’ve focused primarily on internal change agents, insurers often look to distribution partners and insurtechs for guidance and solutions to help accelerate change. The emergence and maturation of a robust insurtech ecosystem has generated ideas and innovative solutions that insurers can tap into. Dan Keough, chairman and CEO at Holmes Murphy & Associates and co-CEO at BrokerTech Ventures, stresses that insurance innovation is collaborative, requiring industry-wide cooperation and alignment both within and beyond the insurer’s walls:

“At the highest level, there should be alignment around change, and the solution impacting change to achieve end-results we are working toward, together,” Keough says. “Effective change agents are action-oriented individuals who have a great understanding around the problem we are collectively trying to solve, and those who are relatable to the individuals with the task [change] at hand. Transformative change needs to be supported and led out by senior leadership, and then activated through and by internal entrepreneurs [e.g., labs by BTV & Holmes Murphy].

“As an example, in our first BrokerTech Ventures Cohort, we were able to learn about Broker Buddha – an insurtech company that is addressing the insurance application process, activating technology to create ease and efficiency, demonstrating a smoother process for our service teams, ultimately delivering a greater client experience for our carriers and to the end-client. The success of such change/transactional transformation was predicated around the alignment of stakeholders along the insurance value chain, who all worked together to produce a better outcome for our client.

“Ultimately, alignment around change, and integration throughout the stakeholder value chain, delivers a culture of innovation and one which is open for lasting and transformative change.” 

Bold Is Beautiful

If there’s a common denominator in the perspectives above, it’s that change is constant and inevitable. How insurance organizations manage change is critical.

“Change is always scary, uncomfortable and harder to accept than the status quo,” says Chisel AI’s McDermott, “but it can also be tremendously rewarding. Having spent 30-plus years of my career working with technology startups, I’ve experienced firsthand how it feels to take a leap of faith and stand on the ledge of uncertainty. So, we need change agents with the courage to provoke change, to act as the catalyst for change and to emphatically guide co-workers and peers through the transformation. With technology as the enabler, it takes individuals with grit and determination to thrust innovation forward within their organizations, rally others for the change ahead and reimagine new approaches to drive tangible business outcomes.”

See also: 3 Reasons for Insurtechs, Agents to Collaborate

“Technology moves at such a rapid pace, and the insurance industry is now seeing this firsthand,” says M3 Insurance’s Conroy. “In some ways, insurtech is challenging our risk management roots. We need to get more comfortable with change, specifically the unknown, and stop striving for perfection.”

“I also think we as an industry need to be bolder,” Rieder says. “I see a lot of people get caught in ‘pilot hell,’ where they’re doing 12 technology pilots at once. Well, how’s that impact top-line revenue growth or bottom-line efficiency if you just test a bunch of stuff and never pull the trigger? You need to get into the game. You’ve got to get off the edge of the pool and start swimming.”

Further Reading

Check out this recent article for more perspectives on change management and how to cultivate a culture of innovation in commercial insurance. Industry leaders and change agents -- including Tony Fenton, vice president of commercial lines underwriting and product, Nationwide; Brian Falchuk, author of The Future of Insurance: From Disruption to Evolution; Ryan Collier, chief digital officer, risk placement services; Tina Osen, president, Hub International Canada; Abel Travis, vice president and head of Fundamental Underwriters, a division of AF Group; and Bob Frady, vice president, HazardHub at Guidewire Software -- provide their insights on how insurers can embolden change agents and embed courage into their culture from top to bottom.


Steve McOrmond

Profile picture for user SteveMcormond

Steve McOrmond

Steve McOrmond is senior content marketing manager at Chisel AI and editor of the Writing the Future blog, a commercial insurance forum that focuses on digital transformation, change management and the impact of innovative technologies like artificial intelligence on the insurance industry.

Time to Send Employees to Sleep?

Studies show that the quantity and quality of sleep have declined steadily, and sleep loss can make it more challenging to maintain focus and vigilance.

sleeping

The 18th of March marked this year's World Sleep Day, a day dedicated to raising awareness about the importance of healthy sleeping patterns. It's a celebration of sleep and a call to action on important issues related to sleep, such as how sleep affects job performance and safety. Experts suggest we should get between seven and nine hours of sleep a night, but the average U.K. employee only achieves around six hours. What can businesses and brands do to support and improve workforce wellbeing?

We know from data collected across the world that the quantity and quality of sleep have declined steadily over recent years. Sleep loss can make it more challenging to maintain focus, attention and vigilance in everyday life.

Lack of sleep can also have a profound impact at work, as feeling tired and trying to stay awake takes a lot of mental energy, making it more difficult to stay focused on tasks.

Sleep-deprived employees are also more likely to make errors, either through a lack of attention to detail or a mistake due to slower reaction times. Alertness, vigilance and concentration are diminished by long-term poor sleep, as are problem-solving, creativity and decision-making abilities. In some professions, increased reaction times may mean missing an important task, but in other professions -- such as doctors, first responders and truck drivers -- slow reaction times can be the difference between life and death.

What does your business do to manage the risks associated with employee fatigue? Those working in certain industries, such as logistics, will be familiar with the strict rules surrounding drivers' hours and the implications of getting things wrong. Meanwhile, employers in other sectors might not have such specific legislation. It's important businesses and leaders can reference policies or risk assessments that deal with fatigue. Fatigue risks need to be a factor and inform management decisions.

As with any workplace risk, businesses must consider what might happen and not just wait for issues to reveal themselves. With regard to fatigue, it's possible that some employees might feel reluctant to raise any concerns, and others may not be able to recognize the signs of fatigue.

Solving sleep deprivation at work is hugely important. Here is my advice to businesses on where to start:

Awareness and education

Virtually everyone in the world has had a bad night's sleep and felt the impact the following day. However, feeling tired is just the tip of the iceberg, and many people disregard, or are unaware of, the health issues associated with regular poor sleep.

As you'd expect, organizations are becoming increasingly aware of the impact of sleep deprivation on their financial performance, and more importantly their employees' health and wellbeing. Many businesses have already taken steps to support sleep and recovery in their workplace.

It all starts with providing the right support and information to educate your employees on the basics of getting a good night's sleep.

Everyone at work should be able to identify the signs of fatigue and know what to do about it. Many job-specific risks are covered during employee inductions and training, but few organizations include fatigue. This can be communicated simply, through leaflets, microlearning or short sessions introducing the concept of sleep and the impact on the workforce.

Understanding the physical effects

Understanding the possible health issues that arise from poor sleep helps with iprevention. There is strong evidence to indicate that chronic sleep loss may lead to serious health consequences, such as an increased likelihood of cardiovascular diseases, impaired immune function and early onset of Type II diabetes.

In addition, there is evidence to suggest that chronic sleep loss (such as long-term fatigue) is associated with certain mental health issues, such as schizophrenia and clinical depression.

These health issues are preventable, and employees at all levels should understand the impact of poor sleep.

See also: Construction Workers’ Mental Well-Being

Identify the risks

Every business should identify its key fatigue risks, seek solutions and allocate resources to the risks with the most significant impact.

Business leaders should be looking at who is at risk, then whether their work is physically or mentally demanding and how lack of sleep can affect the business, as well as the employee's engagement, happiness and performance at work.

It's important to consider factors such as a long commute, as this can affect an employee's sleep and performance. Any life events, such as having young children, can also reduce sleep, so businesses should see if they can provide additional support.

Track and monitor

Businesses need to monitor and track performance, and there is a wealth of information and platforms available to employers to identify potential fatigue issues.

Being alert to your staff's behavior patterns will help you identify if any of your team are having issues with sleep, as will listening for workers who are always complaining about being tired. For high-hazard roles, you should conduct regular cognitive testing.

Don't just brush the fatigue issue under the carpet. Employees might be reaching out and will benefit from your support.


Matthew Elson

Profile picture for user MatthewElson

Matthew Elson

Matthew Elson is CEO at Evotix, which harnesses the latest technology to give people intuitive, human tools that address their most pressing EHS and wellbeing challenges. He acquired Evotix (formerly SHE Software) in October 2011. He combines strong commercial and leadership skills with strategic insight developed through a career of varied roles.

Elson began his career as an engineer before spending six years at McKinsey as a management consultant. Since then, he has built extensive executive experience in large and small businesses, including as CEO of ESR Technology, a manufacturer and engineering consultancy, and as managing director of Atkins management consulting division.

3 Ways to Cut Time, Frustration, Cost in Accident Claims

Embracing a digital approach reduces roadblocks to deliver exponential benefits for policyholders and your claims organization.

time

Motorists are involved in an accident every 60 seconds in the U.S., and the damage, injury and stress can complicate an already difficult situation. Insurers face the challenging task of getting accurate information as quickly as possible to manage loss cost and additional expenses, while supporting policyholders in their moment of need. 

However, only half of drivers involved in an accident end up filing a claim. Of those claimants, just 9% to 13% provide first notice of loss (FNOL) from the scene of the accident. Receiving FNOL after the vehicle leaves the accident scene can lead to much higher costs and longer cycle times for insurers. Rather than the insurance company initiating a tow directly to the repair shop, the vehicle will likely spend five to six days captured in tow storage, lengthening the process (and frustrating the policyholder) while also increasing transport and storage fees. 

With the right tools and accident scene management processes in place, insurers can quickly receive notice of an accident along with the information needed to enable earlier loss determination and ensure proper vehicle routing to streamline the claims process and avoid secondary expenses. Let’s explore three ways insurers can save time, frustration and money while handling accident claims. 

Recover more vehicles from the accident scene with crash detection response

Crash detection technology is poised to go mainstream with both insurers and auto manufacturers, and it promises to have major long-term impacts on claims and repair. But with the average age of vehicles on the road today exceeding 12 years, we are likely still more than a decade away from reaching a critical mass of connected cars. Smartphones, on the other hand, are prevalent throughout the world, with 90% of consumers owning one. And there’s a very strong chance these devices will be in the vehicle at the time of an accident. 

These devices contain many sensors that, combined with optimized algorithms available through an appropriate mobile telematics app component, can accurately predict the severity of the crash to determine if there are injuries and identify the likelihood of a vehicle being undrivable. Beyond the obvious – and extremely important – health and welfare benefits of instant accident notification, the technology also significantly improves the overall accident management process. With crash detection technology in place, especially when tied into accident response and insurer claims management systems, first responders and insurance companies receive near-instant notification that an accident has occurred. 

In addition to these notification and claim initiation benefits, crash detection technology allows for more accurate liability determination and automatically connects the driver to their insurer for help immediately following an accident. Current FNOL processes are typically based on rudimentary inputs, often collected orally from the policyholder. Digital telemetry and crash reconstruction data can not only shed light on the collision itself (force of impact, etc.) but also the events leading up to the crash, including whether the driver was talking, texting or using an app on their phone, overall vehicle speed, if the brakes were engaged before the collision, and more.  

See also: 'Digital' Needs a Personal Touch

Enable digital intake and follow-up with an accident management dashboard

Connecting an insurer’s claims system to a mobile app provides the option to submit details of the accident digitally, removing the barrier of a phone call and in turn reducing congestion from the contact center. Not only does this simplify the customer experience, but it also uses contact center resources more efficiently. Location data and details can also be automatically detected, automating the collection and sharing of essential case information.

However, even in cases where a customer reports the accident directly from the scene, incomplete information can require additional follow-up calls that delay vehicle pickup and overall cycle time. With added delays also comes the risk of keeping the vehicle in storage, accumulating storage and rental fees as the missing information is collected. To avoid follow-up calls that further delay cycle time, implementing digital communication tools can help fill in these missing blanks.

An accident management dashboard makes it easy to handle and update cases through an easy-to-use interface. It also helps to expedite follow-up communication when additional action or information is required through a digital communication feature – all while eliminating the need for an outbound phone call. Instead, claims handlers can digitally update final tow destination, approve advanced changes, share updates, and request receipts. Because this is all done digitally, the requested information can be shared much quicker to ensure there are no hiccups that delay cycle time.

Leverage data and experience to alleviate vehicle release complexity

When a vehicle is not recovered from the accident scene, a new challenge arises: dealing with the vehicle release. The vehicle release process can be rather complex due to varying requirements from state to state and even shop to shop. Whether it’s negotiating release fees, cash requirements or processes and paperwork, securing a vehicle release from a storage yard or salvage lot requires a certain level of expertise. Without this experience, release costs can also add up, and cycle time can be extended by an industry average of five to 15 days.

Experience in accident management significantly simplifies the complexities of releasing a vehicle from storage. Look for an accident management partner that has navigated this landscape and can leverage extensive data on historical release charges and regulations to anticipate requirements and negotiate the best release fees. In addition, your partner should have a team of dedicated release coordinators that will manage the entire release process, ensuring your agents can remain focused on your policyholders. Even in cases where on-scene capture was not possible, insurers can still benefit from simplicity, cost reduction and a shorter process for policyholders.

There are many challenges and complexities with managing the accident lifecycle efficiently, but embracing a digital approach and leveraging an experienced partner reduces these roadblocks to deliver exponential benefits for policyholders and your claims organization. While some costs are unavoidable, these three approaches can help insurers reduce cycle time and manage costly, complex and time-consuming claims processes. That’s good news for everyone involved.


Mubbin Rabbani

Profile picture for user MubbinRabbani

Mubbin Rabbani

Mubbin Rabbani is vice president of product at CLARA Analytics.

He has over 15 years of product management experience focusing on commercial insurance claims. Prior to joining CLARA, he served in senior product leadership positions at Liberty Mutual, Agero and Deloitte. At CLARA, he is responsible for delivering innovative solutions that address critical operational and financial levers in the claims value chain.


Is There Such a Thing as 'Positive Friction'?

Application forms that encourage fast thinking can lead to misdisclosure through careless mistakes, approximate answers and intuitive biases. Slowing the buyer down may help. 

driving

One key goal of digitizing the life insurance customer journey is to create speedy and seamless application experiences, which, it is hoped, will increase conversion rates. 

Research, however, has shown that there may be a hidden cost to fast, frictionless digital insurance applications. The prevailing view in psychology, popularized by Nobel Prize-winner Daniel Kahneman’s book Thinking, Fast and Slow, contends that humans have two modes of making judgments. One is very quick and intuitive, but doesn’t gather all available information or take time to consider a response. The other is slower and takes more effort but is logical and considered. 

Insurance companies have been focusing on making the applicant user experience (UX) as fast and frictionless as possible. Although a worthy goal, it also increases the likelihood of intuitive responses to the provided questions without real thought or care, thereby leading to misdisclosures. Could there be value in introducing "positive friction" (i.e., more time for consideration) into the application process? 

Disclosing … fast or slow?

Responding to questions on a life insurance application is a constant and unexpected exercise in thought, judgment and decision-making. Research has shown that often people will have a tendency (or bias) to satisfice, meaning they will provide “good enough” rather than optimal responses, to minimize their efforts. In situations where people are encouraged to respond quickly, “accurate enough” (i.e., approximate or incorrect) responses for metrics such as height, weight or alcohol intake might be provided, instead of putting in the effort to give more precise responses.

A second concern is whether encouragement of fast thinking might lead to greater misdisclosure by spurring applicants to rely more on their intuitions during the application process. This is not to say people are intuitively attempting to gain economic advantage: Indeed, in studies in which participants earned a bigger payment by deceiving a fellow participant, they were found to be honest more often, sacrificing the incentive, when they had to decide on a response quickly. Similarly, people are not necessarily intuitively seeking to secure themselves the best insurance deal. Formulating a lie is actually quite mentally taxing, as is figuring out how to “game” an insurance application. 

When misdisclosure occurs intuitively, it does not necessarily derive from a desire to game the application process. Often, it stems from an applicant’s desire to display their social value. Applicants are more likely to misdisclose details about themselves that are weighted with social stigma, such as recreational drug use or high body mass index (BMI). This is due to susceptibility to the social desirability bias — the natural human impulse to present oneself in the best light. 

RGA research has found that people responding to questions under time pressure are less likely to disclose sensitive details about themselves than those not experiencing time pressure. Hence, encouraging people to respond quickly may make it more likely that they would intuitively aim to present a positive social image, leading to misdisclosure. 

These biases are particularly concerning for life insurance underwriters, as they are natural, affect people in many situations and are easy to self-justify. In a study using real application data, RGA compared self-reported BMIs with those obtained in paramedical exams and found that a full two-thirds of the applicants underestimated their BMIs. The vast majority of underestimations were for less than 10% – a possibly justifiable “white lie” for an applicant, but a material amount to an insurer across a whole portfolio. The implication here is that applicants might have been intuitively managing their self-images by subtly underestimating their weight but not brazenly misreporting a weight to secure more favorable underwriting. 

A Case for Positive Friction

These findings are significant for underwriters. Application forms that encourage fast thinking can lead to misdisclosure through careless mistakes, approximate answers and intuitive biases. How can insurers mitigate misdisclosure risk while improving customer underwriting journeys? 

Designing effective applications means making it psychologically easy for applicants to answer questions honestly. This can be done by providing memory-prompting cues, such as images, or by breaking complex multi-part questions down into much smaller components. These can make applications easier to fill out while still producing honest and accurate disclosures.

Insurers can also leverage the social desirability bias to improve disclosure rates. For example, forms can be written using language that contains subtle reminders that an applicant’s social responsibility is to report their lifestyles honestly, rather than tweaking their numbers in ways that would add luster to their self-images. Additionally, presentation of social norms can be reframed in ways that will encourage people to conform to them in their responses. For example, cues for “normal” levels of drinking, smoking or BMI can be provided via scales that have high (but realistic) limits. 

Third, application designers can acknowledge that friction in a digital process might not always be a negative in user experience. Indeed, positive friction can be used creatively to benefit users and businesses alike. UX designers in other industries are already using it: Bank apps, for example, now have warning screens that will prompt users to stop and check payee details to mitigate risk of fraud, or even to protect vulnerable customers from impulsive late-night purchases. 

See also: A New Boom for Life Insurance?

Final Thoughts 

Could positive friction be a plus in digital life insurance applications? More testing and study will be needed to understand whether slowing user application processes could improve not just disclosures but the entire user experience. Indeed, it is possible that reducing the process’s friction too much may be incompatible with applicants understanding their policies fully, which may risk the sorts of misunderstandings that could lead to early lapses and cancellations and possibly reduce trust in a brand, as well. 

Psychologists have also found that, when people put effort into creating something, they may value it more. This phenomenon, first written about in 2012, is known  as the IKEA effect. What this may mean for insurers is that the need for more effort on a customer’s part, even if it means taking longer to fill out  an application, may not necessarily be negative for conversion in the long run. With more effort, the customer’s investment in the application process may increase throughout the sales journey, potentially building a higher perception of the policy’s value. 

Digital form designers may want to consider whether a side effect of frictionless interfaces might be responses provided with minimal thought, increasing risk of misdisclosure. This could happen in instances where fast responses lead customers to approximate their answers and make careless mistakes. There is also a risk that encouragement of fast responding increases applicant use of their intuitions to provide responses, which increases the effect of biases such as social desirability that harm disclosure rates. 

Finally customer journey designers may also ask whether there may be material sales trade-offs in customers’ experience by slowing applicants down. Slower application processes may offer a higher chance of customers fully considering their purchase, and that greater investment in effort may lead to an increased perception of value and greater trust. The path of least resistance may not lead to the best outcome.


Peter Hovard

Profile picture for user PeterHovard

Peter Hovard

Dr. Peter Hovard is vice president and chief behavioral scientist at RGA.

Hovard has a Ph.D. in experimental psychology from the University of Sussex, has taught university classes across psychology, and has published in peer-reviewed journals on eating behavior, appetite, and atypical perception.

The Power of Intelligent Automation

The roots of intelligent automation remain firmly established in the information technology industry, yet its influence has branched to serve a wide range of businesses.

robotic

The roots of intelligent automation remain firmly established in the information technology industry, yet its influence has branched to serve businesses traditionally considered far removed from IT. As diverse business sectors and organizations recognize the need to help clients and customers more effectively, intelligent automation is being applied to business processes to propel those companies forward.

Look no further than the insurance industry. 

Streamlining processes

As organizations are beset with regulations that vary between states or include federal oversight, insurers must adapt their products and services to these rules while serving customers and attracting prospects. Simultaneously, reams of paperwork processes are grandfathered into workstreams. These are burdens to agile businesses and require solutions that move at the speed of modern technology, consumer demand and regulatory change.

Enter intelligent automation.

Simply automating assignments in the regular workflow hastens the completion of repetitive tasks, freeing employees to use their talents on more important responsibilities. However, any change in the process or how it works can require human intervention. Intelligent automation solves this challenge. Introducing machine learning and natural language processing optimizes speed and precision. More importantly, intelligent automation can iteratively learn and incorporate changes in the automation on the fly. 

Intelligent automation replaces outdated systems that have been implemented over time as insurance businesses and the industry have evolved. 

The impact is profound across the enterprise: in the claims operations, underwriting, financial services, accounting, customer service and lead generation. This transformation optimizes workflow tracking, which is woefully inefficient in paper systems. 

Additionally, there's no more need to adapt to internal or external change with irregular solutions or processes that mesh poorly. Modern digital tools used to bring a business up to the contemporary demands of insurance services are much nimbler in addressing future pressures that will mandate adjustments.

See also: Insurers Turn to Automation

Insurance challenges

In one instance, an insurer managing more than a million policyholders implemented a customized content management solution to eliminate waste, improve efficiencies and enhance customer service. The innovative system was designed to engage enterprise-wide and, as importantly, functioned in synchronization with third-party administrative systems. 

These digital processes, implemented on time and budget, have customer service metrics skyrocketing. First-call resolution rates have reached 95% accuracy, rates of closed inquiries have topped 98% and the automated routing of work and use of intuitive dashboards has improved workflow across the board.

The insurer sought a 20% improvement on underwriting costs, the elimination of paper processes, new functionality in claims, managing annuities and customer service and the flexibility to adjust in the future. It enjoys all this today, along with the freedom to streamline up to a third of its core and support staff, resulting from improved operational efficiency.

Fast-paced pharma 

Pharmaceutical and healthcare businesses likewise show the power of intelligent automation. They need to reduce paper processes while having at-the-ready, real-time access to information, intelligence, documentation and work inventory status. They want to boost customer service effectiveness and efficiency. 

Businesses that manage 340B pharmaceutical reimbursement programs are overseen by federal regulations and live in a world incorporating healthcare providers, drug distribution and pharmacy operations and reimbursement. Thus, their tracking, reporting and compliance obligations are significant, and their functions must integrate with external systems. Like the insurance industry, these businesses can often be plagued by antiquated, inefficient processes.

One such business has adopted and deployed an online, automated intelligence system that's solved inefficiencies and focuses on pharmacy clients. It allows the business to serve those customers by managing high volumes of 340B reimbursements, generating accurate reports and remaining audit-ready and compliant.

Within a short time, the organization used the first phase of a state-of-the-art automated intelligence solution that managed claims processing, inventory fluctuations, order management, inventory replenishment, reporting and more. 

Explicitly designed to function within an agile software development lifecycle, this highly scalable, web-based solution reduced development costs and enabled the company to enter the market quickly, raising its profile as a pharmacy-centric provider. After incorporating an in-house file processing platform, the solution functions today with a client load that regularly creates thousands of claims and processes them within a tighter time frame while meeting the terms of service level agreements.

See also: Future of Claims: Automation, Empathy

Different needs, different solutions

No two transformations are alike. Yet many have similar goals to meet and challenges to overcome. These examples in insurance and healthcare are only two of a countless variety of solutions that automated intelligence can address.

To accomplish cost-effective build-outs of new digital processes like those highlighted above takes in-house expertise for guidance and implementation. Highly skilled digital transformation companies have mastered weaving in digital solutions for rapid end-to-end business process automation. 

Organizations that need to transform should seek a provider with an established framework that can deploy domestic, offshore and hybrid development talent to the necessary tasks if required. This is a highly sought benefit that bolsters on-time and on-budget transformations. It helps ensure the design and delivery of a secure system environment with the highest quality assurance.

The company will reap its adaptation capabilities and continue serving at scale in the future.

When You Have Too Many Good Innovation Ideas

Here’s a four-step plan to initiate a systematic process to uncover, screen and scale the best ideas using an innovation portfolio approach.

innovate

In my past several IIS innovation research articles, I challenged insurers to think big, really big, about how they might innovate with purpose to change the world—and, in doing so, drive tremendous growth. In this article, I address the flipside of that challenge: how to hone too many potentially good ideas into a manageable yet holistic set of innovation investments.

Executives often tell me that their problem is not having too few big ideas, but having too many. Great ideas are purportedly coming at them from every direction. They come from the front lines where the organization interacts with customers and contends with competitors; from technology and marketing wizards keeping a sharp eye on disruptive market trends; from senior executives and board members grappling with issues at the organization’s strategic horizon; and sometimes even from conversations with outside advisers like me.

Peter Drucker offered some of the best advice on how to handle so many potentially great (and possibly awful) ideas:

“Don’t subscribe to romantic theories of innovation that depend on ‘flashes of genius.’ Innovation begins with the analysis of opportunities. The search has to be organized and must be done on a regular, systematic basis.”

In the spirit of Drucker’s advice, here’s a four-step plan insurers can use to initiate a systematic process to uncover, screen, and scale the best ideas using an innovation portfolio approach.

Stimulate and Inventory Opportunities

Start by casting a wide net in the context of your company’s environment, purpose, strategy and capabilities. For example, hold scenario-planning sessions with senior executives and board members to explore continuous and disruptive opportunities and challenges that arise out of key strategic questions. Organize learning workshops to educate and gain insight from the wider organization about potential future scenarios. Engage teams at multiple levels to articulate both desirable and dangerous future histories for the organization. Sponsor innovation contests to uncover both continuous and disruptive ideas.

Continuous innovations offer incremental or faster, better and cheaper-type optimizations, such as shedding costs, reducing cycle times and generating incremental revenue. With sufficient license, numerous continuous innovation ideas can flow out of such discussions. Make sure you capture them.

Disruptive innovations rise to the level of game-changing and world-changing potential. It’s important to create space for these really big ideas. For example, stimulate potential organizational responses to thought questions like these:

  • What are the most pressing protection gaps in the communities your company currently serves?
  • How might those gaps evolve over the next several decades, especially for those who are the most underserved?
  • What evolving technological capabilities might help narrow those gaps, especially as they continue to progress following the Laws of Zero?
  • How might you apply these leading edge tools to better expose, model and mitigate meaningful slices of corresponding risks?
  • What early lessons from innovators and early adopters around the world might be adapted to your community’s evolving challenges?
  • What extreme competitive threats (that is, doomsday scenarios) might new entrants wielding these disruptive solutions pose to your business?

Categorize Opportunities Based on Investment Type and Impact

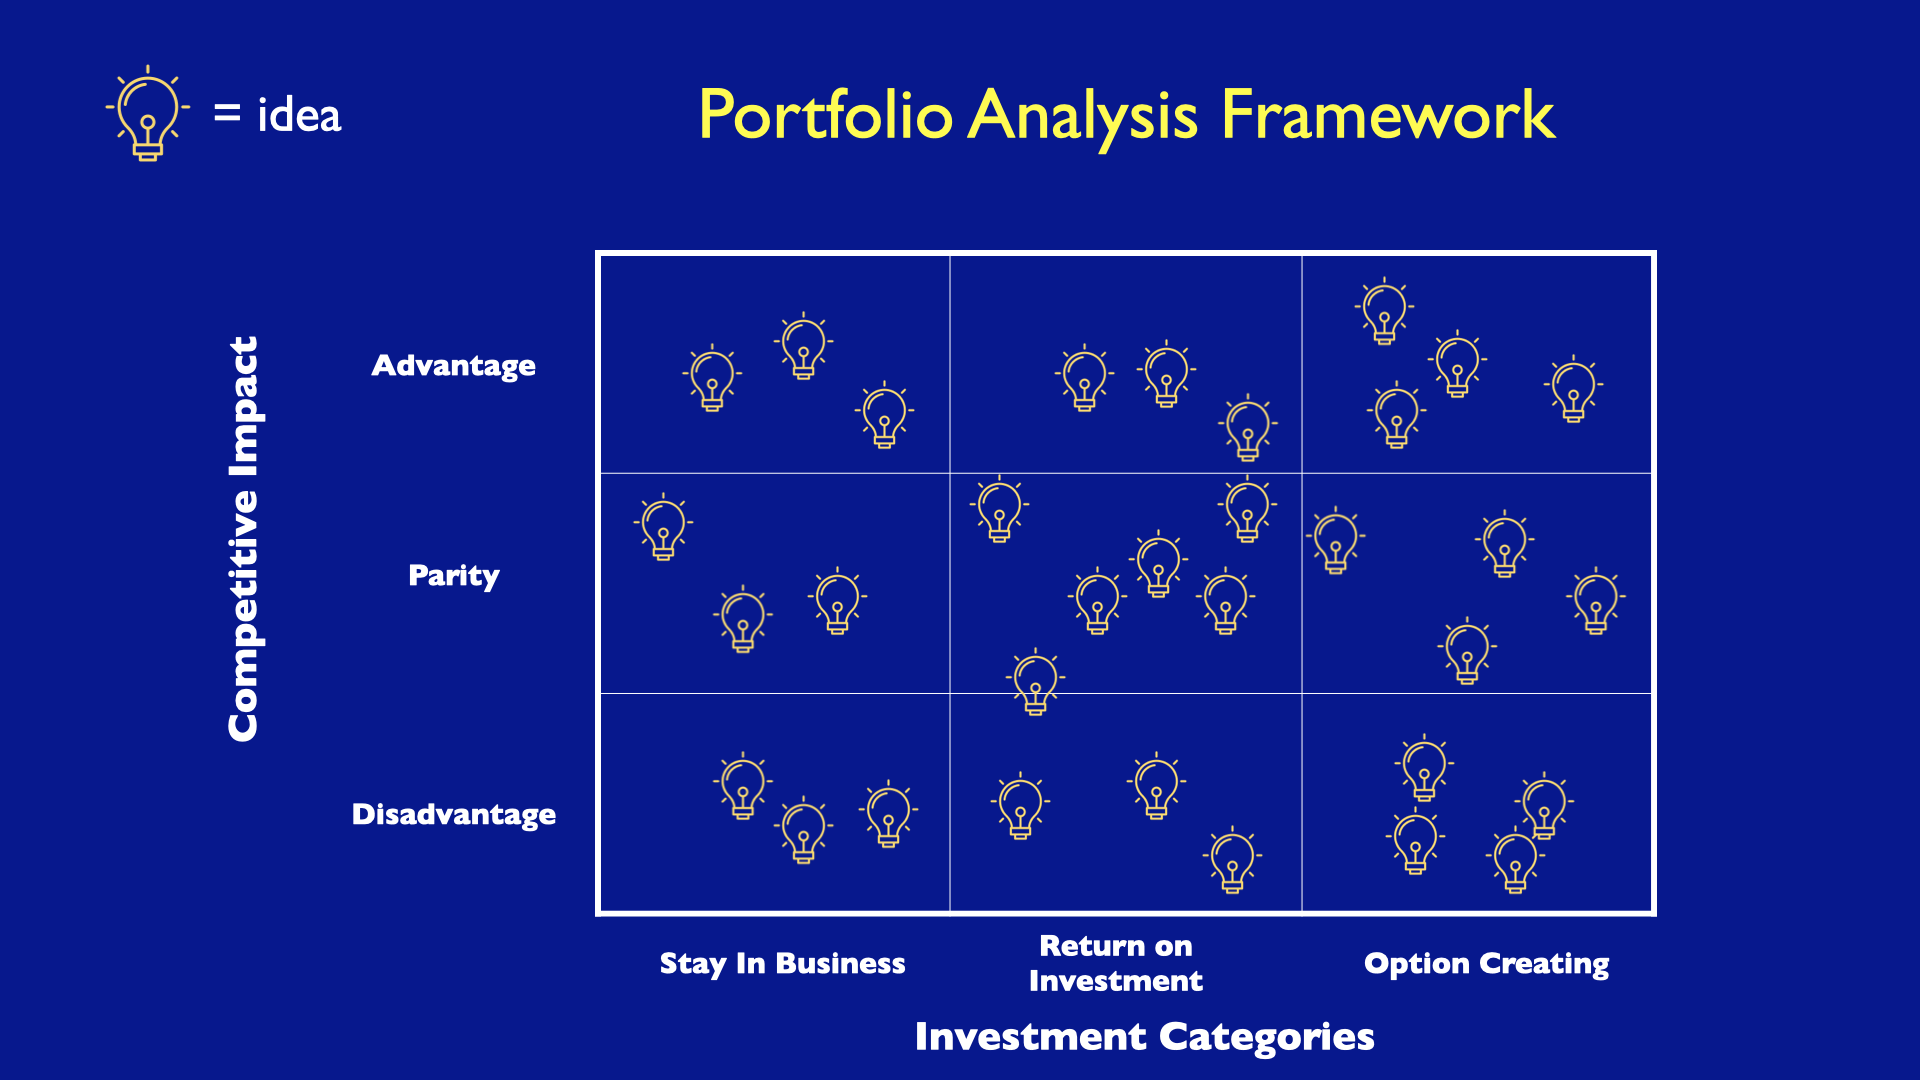
Next, categorize the opportunities according to investment type and a potential competitive impact. This will allow you to array all the ideas in the 3x3 matrix formed by the two categories, as illustrated in Figure 1.

Figure 1: Categorize Ideas Along Two Key Dimensions

image1

Each idea can be categorized as one of three distinct types of investments:

  • Stay in business (SIB) investments
  • Return on investment (ROI) opportunities
  • Option-creating investments (OCIs)

Categorization enables more suitable metrics and better comparative analysis. It also allows for strategic allocation of investment resources across categories based on organizational need.

SIB investments are for basic infrastructure or nondiscretionary requirements. They are common across companies. For example, large investors and regulators are promulgating a range of industry-standard Environmental, Social and Governance (ESG)-related reporting and compliance requirements that most companies will have to follow. The rise in cybersecurity challenges requires significant infrastructure enhancements. COVID-19 has driven significant investments to reconfigure built environments and enable remote work, where possible. SIB investments should be assessed on how adequately they meet regulatory or technical requirements while minimizing risk and cost.

ROI opportunities are company-specific offerings that are pursued for near-term financial returns. Most continuous innovation ideas fall within this category. Standard measures, such as net present value (NPV), return on equity (ROE) or other well-understood metrics are applicable for evaluating ROI opportunities.

OCIs are the earliest stage of innovation initiatives. Companies typically pursue them to explore business opportunities that might yield large returns in the future. They resemble financial options—from which the name is derived—in that they exhibit high risk and offer tremendously high potential returns but do not commit the organization to exercising the option. OCIs do not yield financial returns directly. Instead, they reduce uncertainties and build capabilities and learnings that could be translated into future ROI opportunities, if appropriate. All discontinuous innovation ideas should start as OCIs.

Next, make a high-level assessment of the idea’s future potential competitive impact.

Consider Wayne Gretsky’s adage about skating to where the puck is going, rather than to where it is. This dimension measures differentiation against what competitors will likely have deployed by the time an idea is launched. Once successfully completed, would the innovation have an advantage, be at parity or be at a disadvantage against the competition?

This method addresses two key screening mistakes. The first is evaluating an innovation idea against the organization’s current internal capabilities or product offerings, rather than the alternatives that customers will have in the market. The second mistake is evaluating the idea against current competitive offerings, rather than recognizing that competitors won’t stand still, either.

See also: When Incumbents Downplay Disruption...

Screen the Opportunities

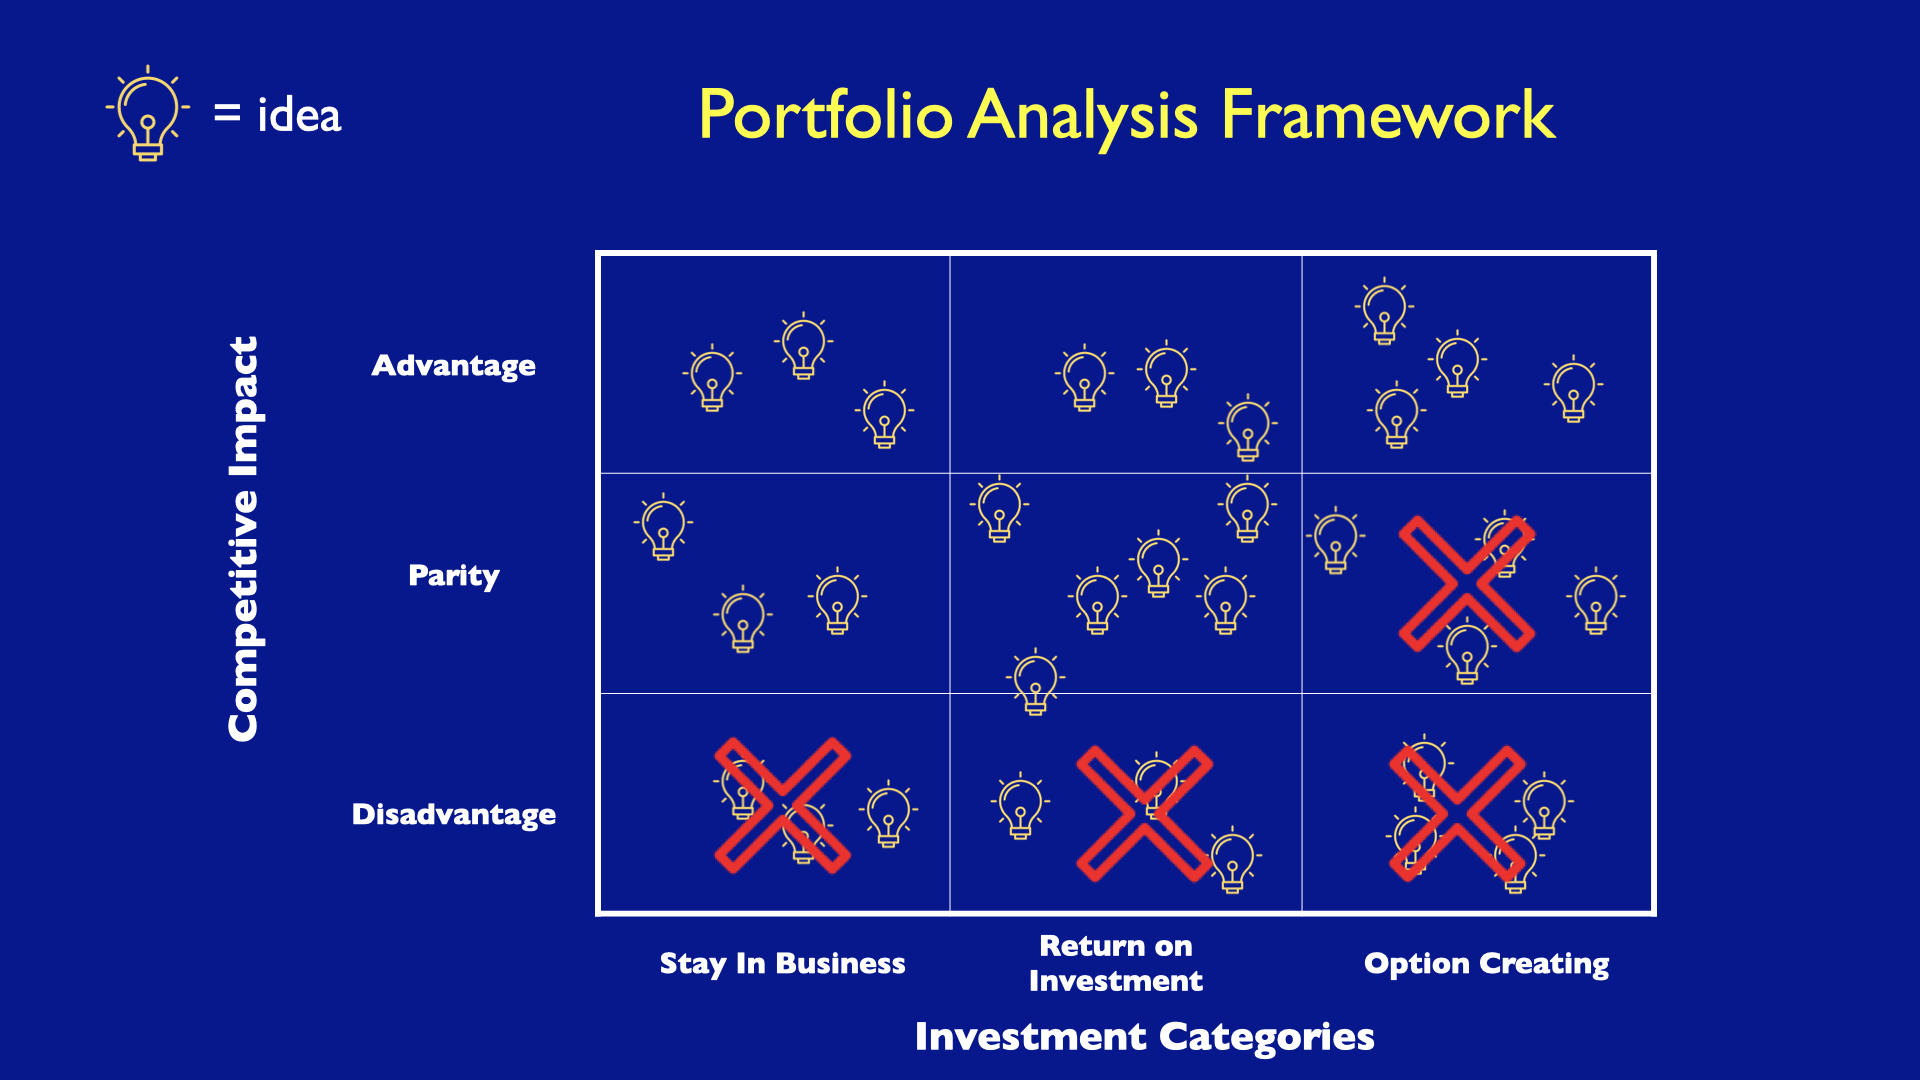
Arraying opportunities in this analysis framework allows for simple heuristics to eliminate seemingly good ideas that fall outside of acceptable boundaries. For example, companies should not pursue opportunities that, once completed, are already at a disadvantage against the competition—no matter how much they improve upon current internal capabilities. There’s no reason to pursue OCIs that, no matter how advanced they are, would deliver only competitive parity, as new parity offerings would be unlikely to dislodge existing offerings or deliver outsized returns. Figure 2 illustrates how the analysis might look at the end of this stage.

Figure 2: Initial Screening

image2

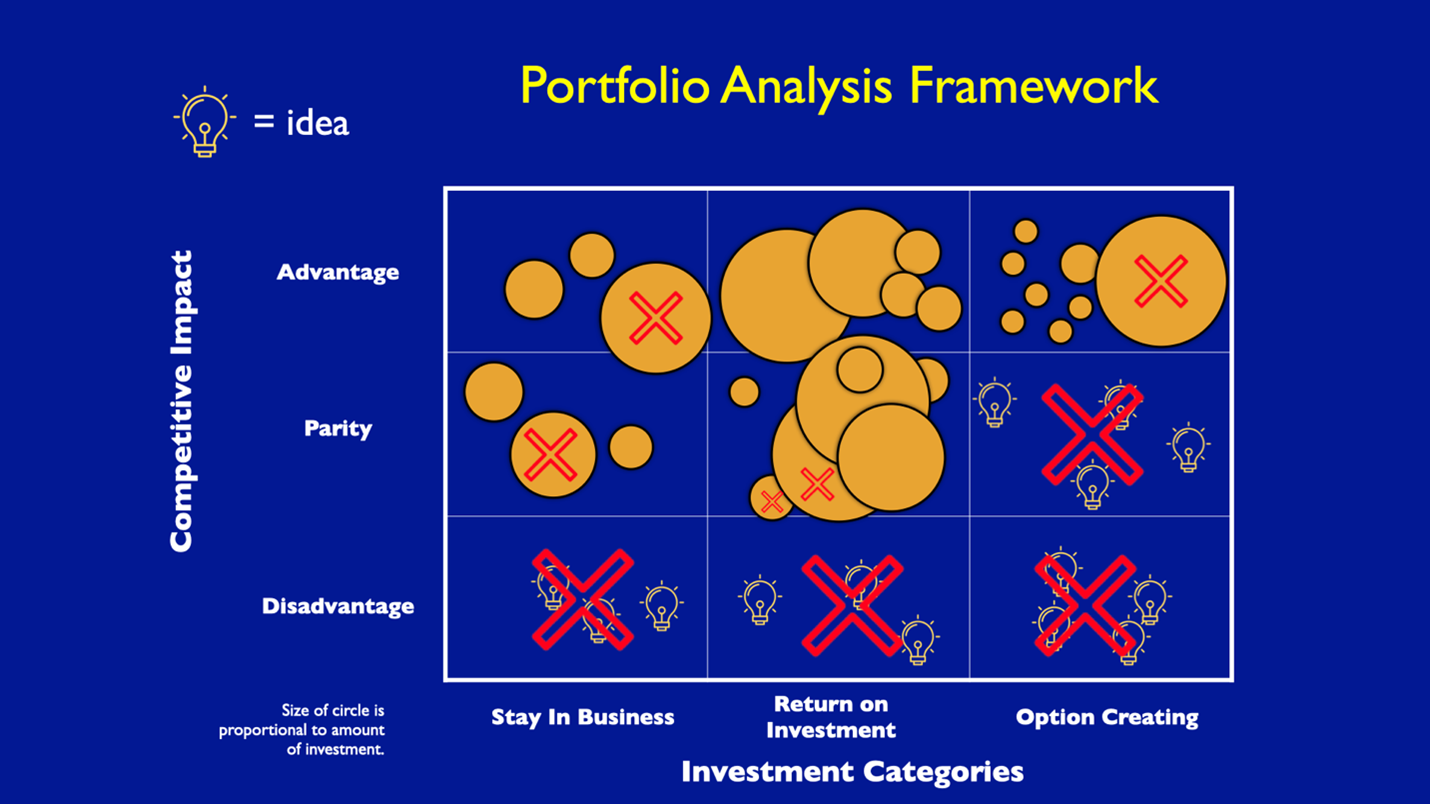
For the remaining opportunities, develop an initial sizing of investment levels and potential benefits according to each investment category. This allows for another level of screening, as shown in Figure 3.

Figure 3: Additional Screening Based on High-Level Sizing

Image3

For example, eliminate ROI opportunities that do not meet standard corporate hurdle rates. Eliminate OCI opportunities that do not exhibit extraordinary option value or require relatively significant upfront investments. Eliminate SIB ideas that do not adequately minimize cost and risk—be very skeptical of SIB opportunities justified by predicted ROI or OCI benefits.

Rebalance the Innovation Portfolio

No new set of innovation initiatives, no matter how potentially great, can be considered in isolation from continuing innovation programs. The final step of the screening process is to evaluate both existing and potential initiatives in the context of the overall innovation portfolio, and to rebalance that portfolio as appropriate.

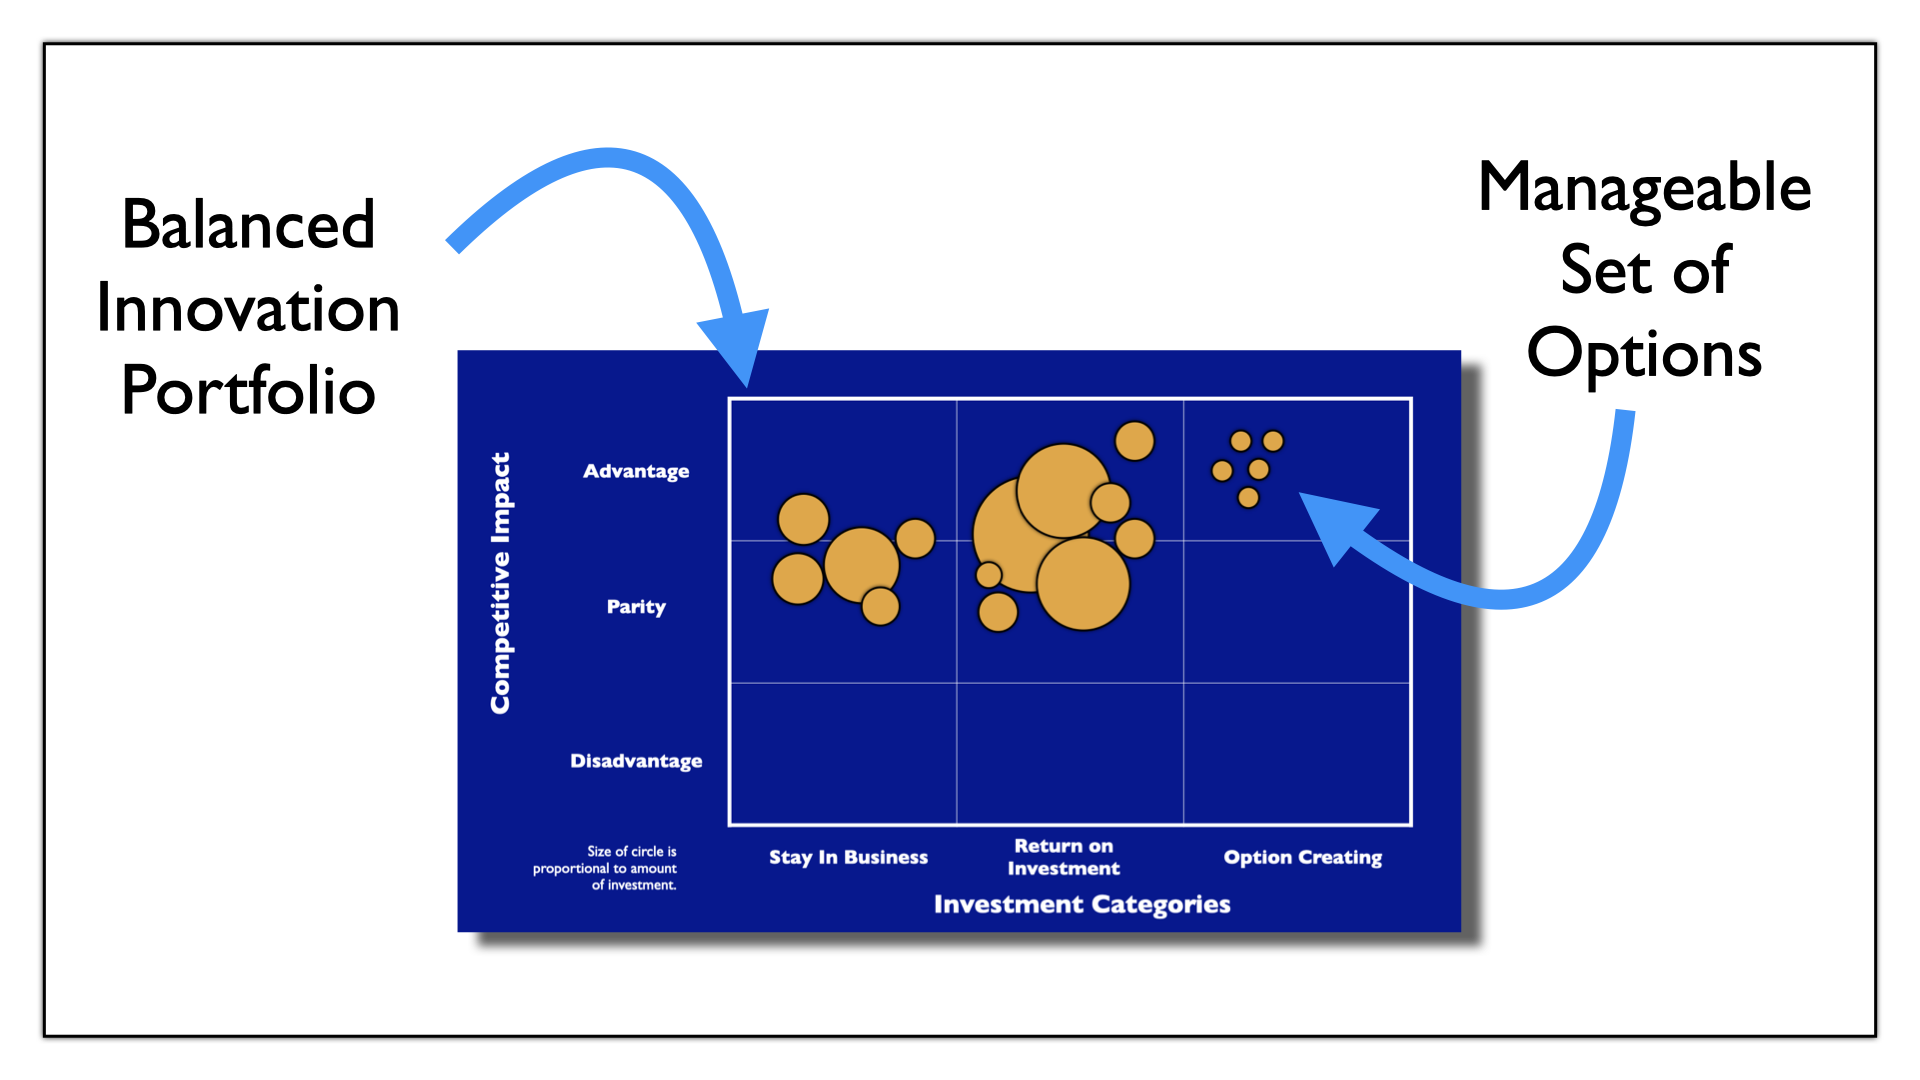
The right prioritization and allocation across the portfolio depends on a company’s investment capabilities, competitive circumstances and strategic aspirations. For example, as shown in Figure 4, a market leader could gear its portfolio toward aggressive growth by enhancing its infrastructure, investing heavily in near-term profitable opportunities and developing a small number of disruptive options for furthering its competitive advantage.

Figure 4: A Market Leader’s Balanced Portfolio

Image4

In my experience, the right number of disruptive options is on the low end of the magic seven, plus or minus two. That’s because the limiting factor is senior executive attention, not investment dollars. Market leaders have a lot of money to invest, but no project with truly disruptive innovation can succeed without significant senior executive attention. At the same time, astute companies will not place “all their eggs in one basket” by having only one or two future-looking disruptive options. Instead, they hedge their bets by having multiple bets in place.

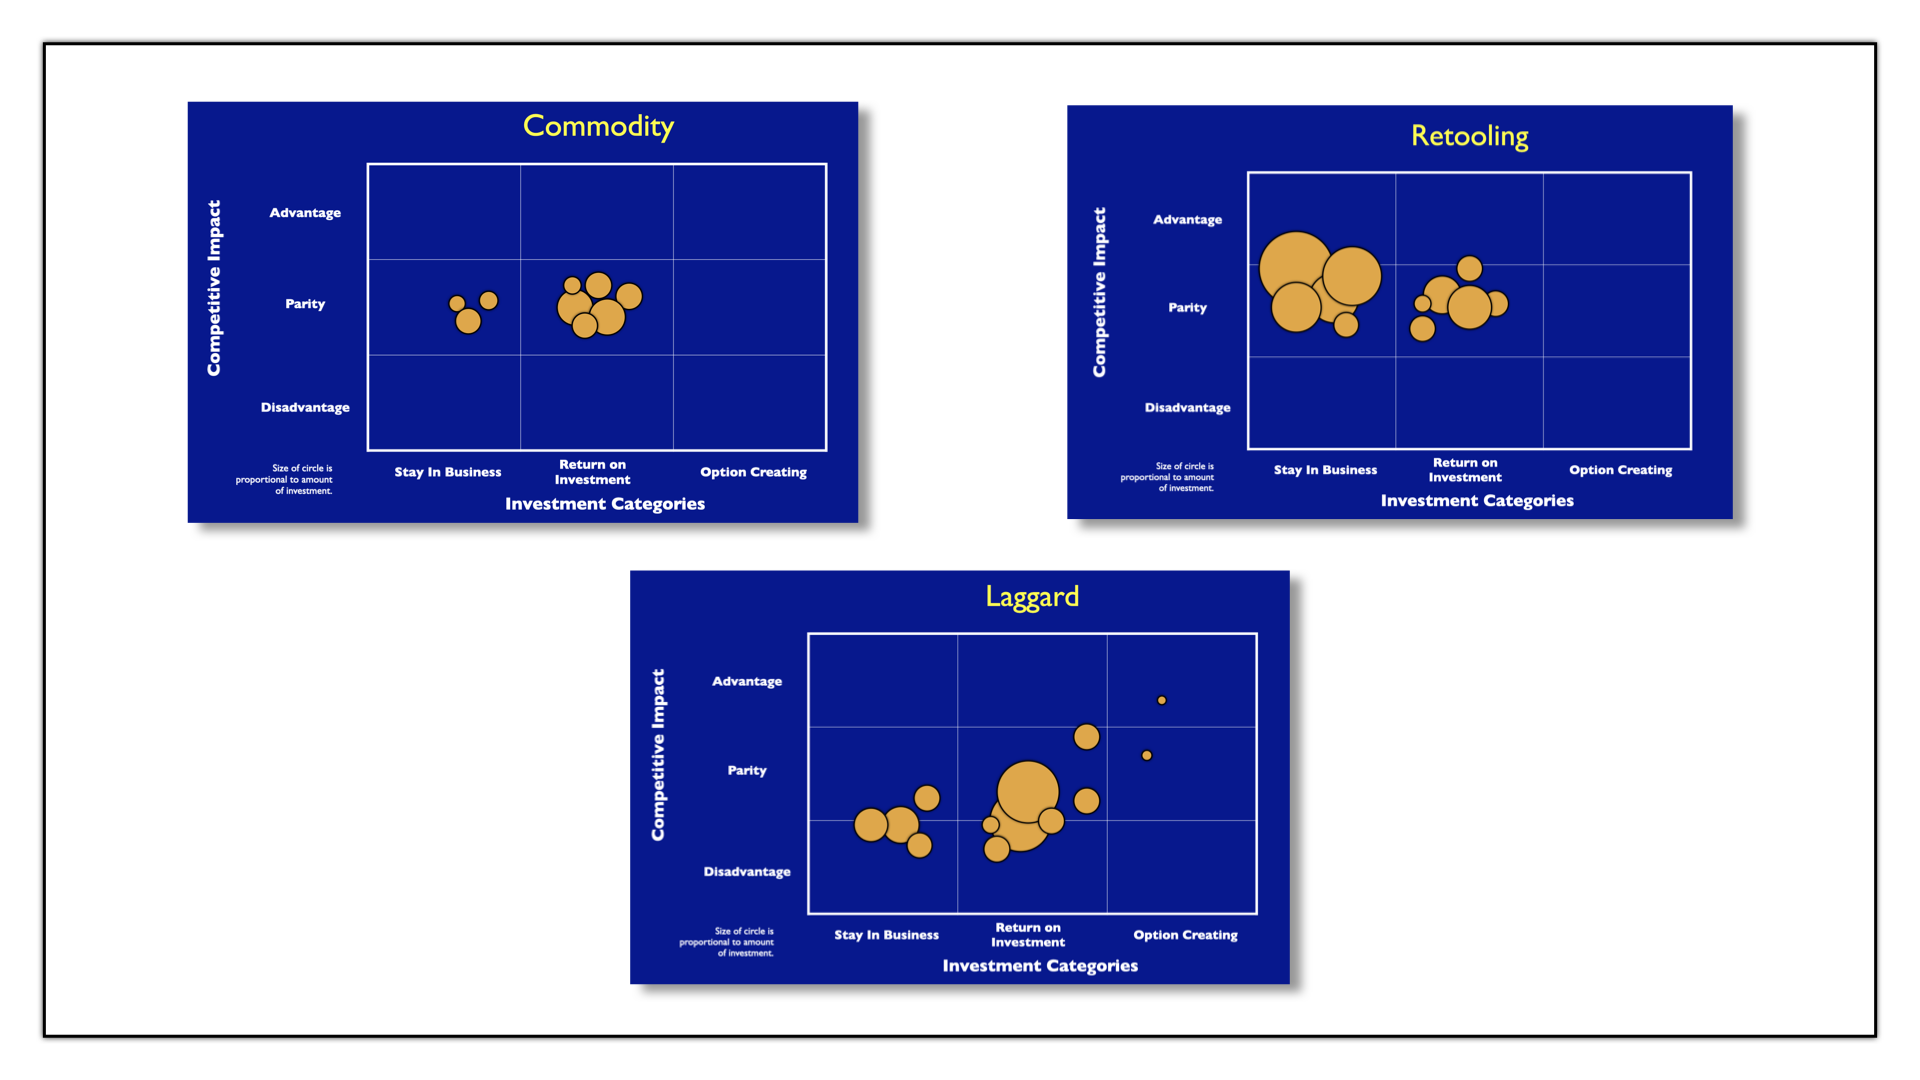
Other illustrative portfolio profiles are shown in Figure 5. Commodity businesses tend to minimize SIB investments and OCIs. Companies that are retooling might emphasize infrastructure and near-term investments and only minimally invest in future options. Underperforming companies tend to invest in programs that barely achieve competitive parity or worse and do little to prepare for the future in any of the three investment categories.

Figure 5: Other Illustrative Portfolio Profiles

Image5

***

At the end of this four-step process, companies should have a prioritized and staged investment plan that represents a coordinated enterprise innovation strategy and follows a think-big, start–small, learn-fast innovation roadmap.

Achieving an adequate understanding of the entire landscape of possibilities facilitates and encourages thinking big. Management of the innovation portfolio provides clear criteria for evaluating other big ideas as they come up. It also demands the discipline of starting small and learning fast in the pursuit of disruptive innovations that will shape the company’s future history.

Stocking Caps and Insurance

How Amazon’s approach to selling the former can help you move more of the latter.

tech

I’m a golf nut. The Tournament Players Championship, the PGA Tour’s flagship event, was held recently in northern Florida. The weather was sunny and warm to start, but then a front blew through, carrying a day’s worth of rain and leaving behind it forty degree temperatures with cold north winds. During the rain delay, Shane Lowry of Ireland, one of golf’s global stars, was asked by a television interviewer how he was spending the downtime. Lowry, scrolling on his phone, said, “I’m on Amazon buying a stocking cap for tomorrow’s round, as I didn’t bring one.” 

Of all the options for stocking caps--tour reps doling out free gear, a massive pro shop at the course, several stores nearby--the winner was Amazon. Lowry, 34 years old, is a Millennial. I’m 58, a Boomer II, and would’ve gone the same route. Raise your hand if you would’ve at least started the hunt on your phone.   

The easier a thing is to use, goes the technology adage, the harder it was to build. “The Everything Store,” as Amazon is known, makes it look so easy we’re prone to take it for granted. But their portfolio of human, physical and especially technology assets is unrivaled. Taken together, the stuff just works, and stocking caps arrive before tomorrow’s frigid tee time. 

Two questions relevant to our work in insurance.

Question #1: When is the last time you talked to a human at Amazon? 

I’ve been a Prime member since 2010, and, aside from thanking delivery drivers whenever I see them, the answer here is never. And I’m a very satisfied customer.  

From the sale of their first book, Amazon designed their business to be as friction-less as possible, defined as people-less, i.e., zero human contact. “If an Amazon customer needs to speak with a person at Amazon,” said founder Jeff Bezos. “We view that as a fail.” 

Contact centers are a hot spot with our insurance customers, as resource costs are rising and manpower availability is shrinking. Smart automation is a winning strategy. Smart elimination of inbound contacts works even better.  

There are two components to contact elimination. The first is process-oriented, around defect reduction and execution. The majority of inbound customer contacts happen when something is wrong. What is your rate of negative customer contacts by event per unit sold? You should know this number, and it should always be trending down.

Disciplined process management can feel like bureaucracy to the inexperienced. But effective process is not bureaucracy; bureaucracy is senseless processing (as I described in an earlier article). 

The second component of contact elimination is informational. Click on Amazon looking for stocking caps, and everything you need is right there in front of you--an array of relevant choices, detailed product information, “customer reviews,” “answered questions” and delivery dates. (The one thing not there is an 800-number.)   

See also: What if Amazon Entered Insurance?

When Amazon introduced “customer reviews” in 1995, many people thought they’d lost their marbles, and book publishers threatened to pull product, believing negative reviews would hurt book sales. Amazon’s philosophy, then as now, is that the company doesn’t make money when it sells things; it makes money when it helps customers make purchasing decisions. So “customer reviews” won out, and more--not fewer--books were sold.  

What do your customers really want from you, and how does your digital presence deliver against those desires? Are your channels providing the information customers truly want and need? The answers have little to do with technology.     

Which brings us to question #2: What’s the name of Amazon’s CIO? 

The answer is, they don’t have one. Neither do Alphabet (Google), Meta, Apple, Netflix or any other digital-native firm you can name. Technology is implemented directly in business units. Though digital natives typically have the functional equivalent of a CTO, the role exists to coordinate platform and tool choices, orchestrating and enabling business success.  

The point is, IT isn’t a department. It’s a way of life. The business owns the customers, and so it owns the technology interacting with those customers. A corporate technology structure operating at one remove from customers is a distance too far. 

A recent study from PEGA reveals 68% of corporate technology executives want to move from “command and control” to more of an enabling, facilitating function. The same study reveals 48% of non-technology executives don’t trust corporate IT. 

Assuming a typical 80/20 technology budget split, we’re seeing more customers allocate the 80% for “lights-on” to corporate IT and the other 20%, the strategic portion, to the business. In this structure, corporate IT operates as a support function, like finance. Think: rapid evolution driven by the business, not the T-word driven by corporate IT.

Until recently, this kind of arrangement was unrealistic in terms of implementation. But new AI and smart orchestration technologies enable fantastic end-to-end customer experiences with legacy as-is, data where-at. 

The “institutional no” regarding new product- and customer-facing initiatives becomes an institutional yes.


Riv Arthur

Profile picture for user RivArthur

Riv Arthur

Riv Arthur is a business leader and technologist working in insurance, healthcare, and private equity.

'No-Code' Goes Mainstream

It's time to take a hard look at no-code--generating computer programs without the need for programmers--which could streamline business processes and slash costs.

Image
no code

If my kids want to figure out whether a band has made it into the mainstream, they ask whether I've heard of it. (Precious few pass the test.) Likewise, I know that an esoteric technology has hit it big when a national, non-technical publication writes a major feature about it -- and "no-code" technology just got its moment in the sun at the New York Times. 

The attention suggests it's time for insurers to take a hard look at the possibilities of no-code -- generating computer programs without the need for programmers -- which could streamline numerous business processes and slash costs.

I think of no-code as sort of the graphical user interface for programming. Back in the 1980s and '90s, we were all lectured about how we needed to become more computer-literate. We were even told that national competitiveness depended on our becoming more computer-literate than other nations. Then the graphical user interface came along, and computers became much easier to use. There are people who delve deeply into the capabilities of their computers and are wildly computer-literate, but the difference between them and the rest of us is far less than it was when those of us among the great unwashed would just stare at the C prompt and wonder what to do next. 

Although coding is far more complicated than just firing up my laptop, the same sort of progression toward simplicity has been going on for decades. Originally, coding was done in assembler -- strings of 1s and 0s that directly controlled the workings of a computer. Then compilers came along, letting programmers write in (still esoteric) languages that were translated into the 1s and 0s that controlled the computer. By the mid-1960s, the most powerful computers could handle operating systems, which made programming even easier. Operating systems migrated to minicomputers and then to personal computers in the 1980s. Object-oriented programming then arrived, meaning that programmers didn't have to write everything themselves for each app -- they could grab a calculator object or a clock object that someone else had written and just incorporate it into the app. Apps are now everywhere.

No-code takes programming to the next level, because it lets even us non-technical types do that sort of grabbing of objects to assemble apps that make computers do what we want them to do -- without having to wait for the IT department to have resources for us and without having to translate our current processes and our desires into some language that they can turn into code.

No-code also allows more fiddling -- and fiddling is crucial. At the moment, once you go through all the effort of producing a program, it's pretty well set in stone. But, with no-code, you're not only more likely to get things right the first time, because you know just how you want to operate, but you can test and reset easily. After all, you're doing this yourself, not via a steering committee of 12 people and a programming staff that may be many time zones away. You can keep fiddling until you get exactly what you need.

We've published a fair amount about no-code over the years -- the topic has intrigued me ever since I wrote about "code generators" for the Wall Street Journal back in the late 1980s -- and I certainly commend our articles to you, among them: Breakthroughs Via Low-Code and No-Code, Things Heating Up in Low-/No-Code and Unlocking the Power of No-Code. 

But I have yet to see in the insurance industry the sorts of easily understandable examples that are in the New York Times article, so I encourage you to read it, too. For instance, the Times writes about a beekeeper who set up a camera outside his hives and trained a no-code AI app to monitor the pictures and warn him if the dreaded Asian murder hornet showed up. An organization that gives small amounts of cash to mothers in Nigeria to encourage them to immunize their children used a no-code system to build an app that lets employees track that data while in the field. A marketer used a no-code system to track which keywords and titles got his clients' blog posts the most visibility in search engines and to predict what would work for future blog posts. He says results improved by a third.

Describing the capabilities of no-code, the Times writes: 

"'I could say something like, ‘Look up all the customer records from the last year,’ and it will go do that for you automatically,' said Charles Lamanna, Microsoft’s corporate vice president of business apps and platforms. He estimates that half of all office work could be automated with AI if there were enough developers to do the work. 'The only way to do this is to empower everybody to be a no-code developer.'

"Eventually the broader public will be able to create A.I.-enabled software in much the same way that teenagers today can create sophisticated video effects that would have required a professional studio a decade or two ago."

Now, none of this will happen especially soon. It's taken us 75 years to get from assembler to where we are today, so it's unrealistic to think we'll all be programmers soon. But, if the technology has caught the attention of an outlet like the New York Times, then I'd say it's worth at least getting acquainted with the technology, and maybe even exploring how it might be deployed in the field, where people are likely to have the sorts of painful but manageable itches that no-code can scratch.

Cheers,

Paul