Download

Data-Driven Transformation

Insurers have always been data-savvy, but they will have to move faster than ever to keep pace with competitors and other industries.

data

Rapid technological advances and changing customer behaviors have accelerated change in many industries. COVID-19 has accentuated the pace of disruption. Insurance companies need to be ready to face these new challenges and take advantage of opportunities.

Insurers have always been data-savvy, but they will have to move faster than ever to keep pace with competitors and other industries. Given the higher volume and velocity, insurers must invest further in their capabilities to store and compute their data assets.

The journey begins with solving for data silos that have been created over decades and that inhibit Insurers. The presence of multiple legacy systems may elongate the transformation, so insurers must use automation to achieve speed to value and reduce costs.

Below are the key business imperatives that a modern-day insurer needs to enable to stay ahead of competitors.
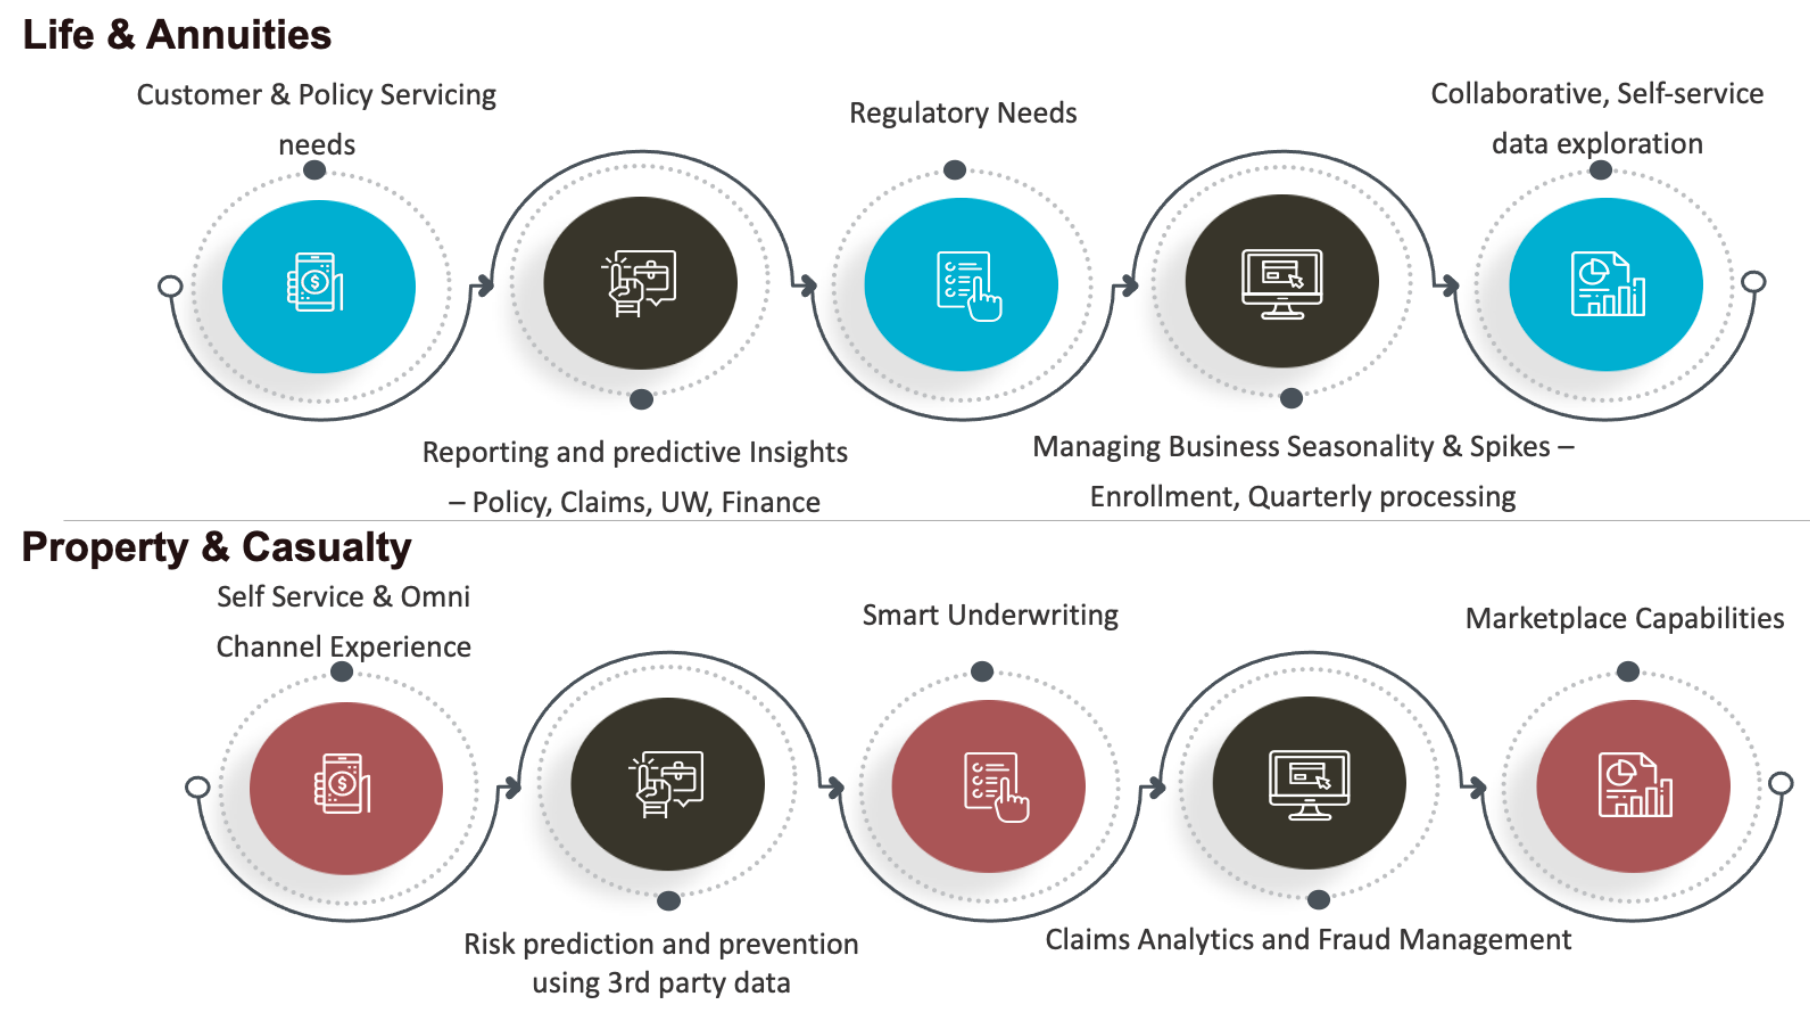
data

The insurance sector of the future will look very different, and this shift has already started to happen across the value chain. Insurers are increasingly re-shaping their roles and value propositions, transforming from purely insuring risks to being data-driven and value-based.

"Data on Cloud" is the driving force behind much of this change and presents a solution for Insurers.

Opportunities for data-driven insurers

For insurers that are weaponizing data, there are tremendous opportunities. Here are key use cases that can be enabled:
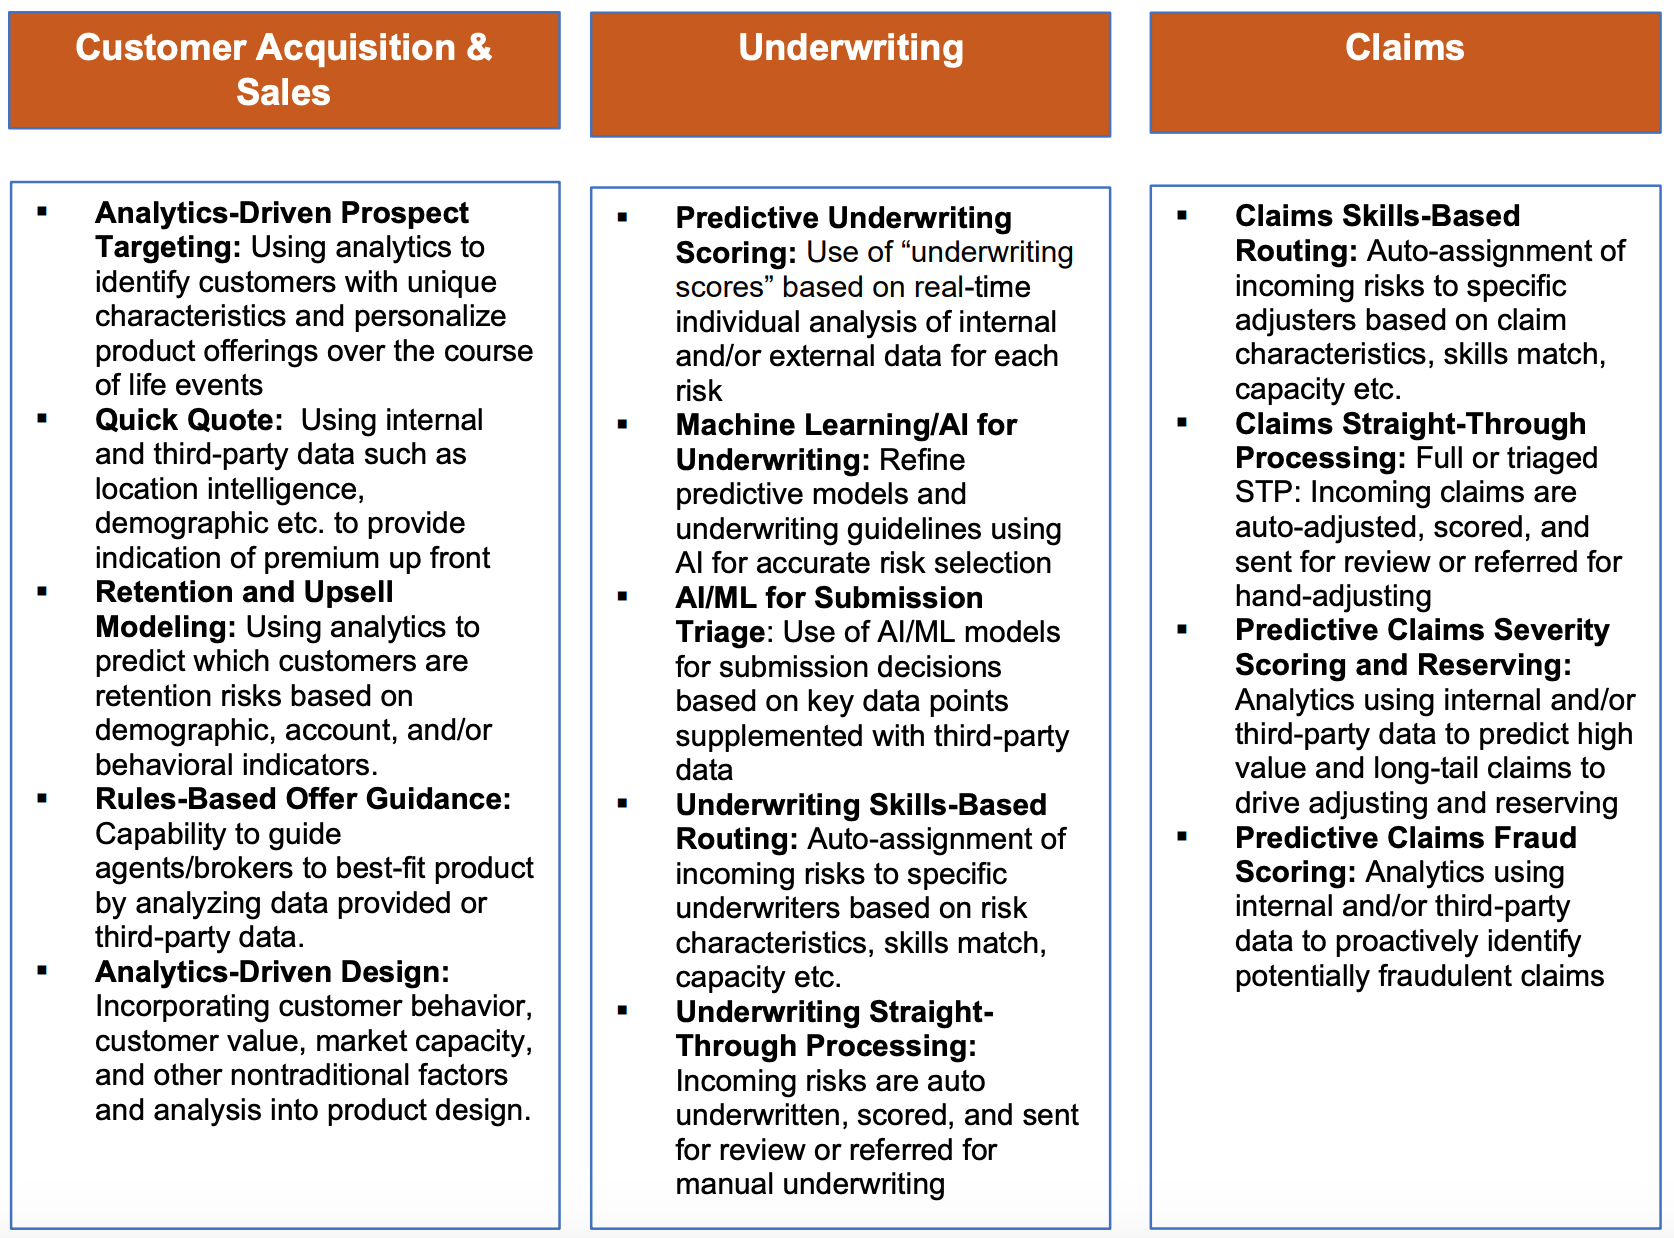
chart

See also: Thinking Big for True Transformation

Key decisions that affect the data cloud strategy

Here is a way to envision those decisions: 
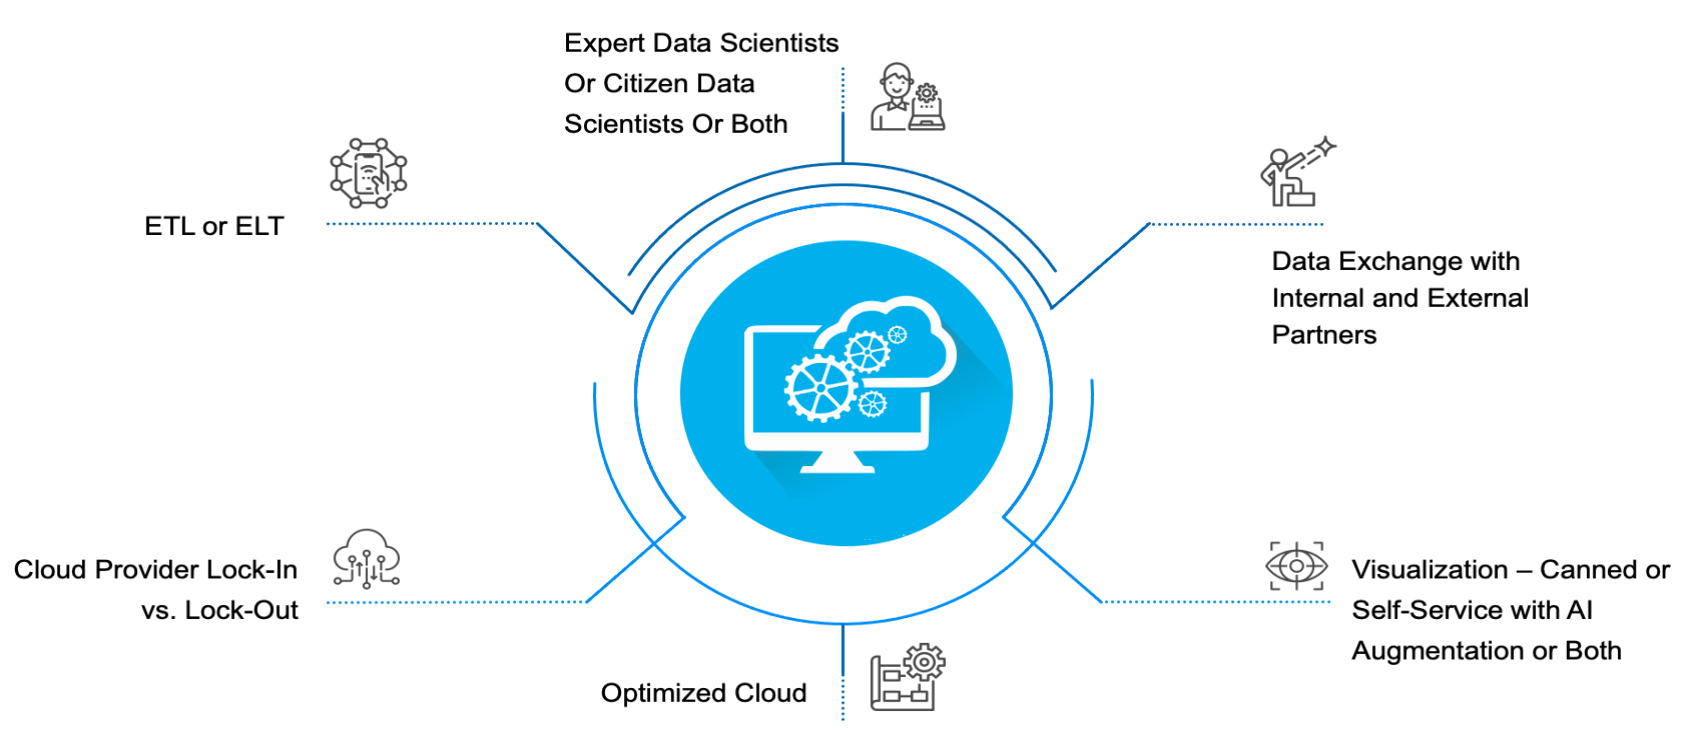
 

chart

Key Decision: Cloud provider lock-in vs. lockout

Recommendation: 

All public cloud providers are continuously enhancing their capabilities to keep up with customer needs. While most key capabilities are common, each cloud provider brings in a few unique capabilities. That’s why it is prudent for Insurance enterprises not to get locked in to one public cloud provider and be flexible.  

Evaluate available options against each architectural building block and pick the best available across the cloud platforms -- perhaps Snowflake for cloud data platform and Azure Synapse or AWS S3 for your data lake needs, especially around unstructured data.

Key Decision: ETL or ELT?

Recommendation: 

ETL – Extract, Transform and Load is used mostly in traditional architectures. As the ETL engine needs to transform a large amount of data, it usually hosts a complex logic and is expensive to run and maintain.  

ELT – Extract, Load and Transform is more suitable for cloud-based data platforms. It is about scaling and processing data in parallel without any impact on performance. A cloud data warehouse such as Snowflake separates storage from computing and allows both to scale as needed. This is especially cost-effective when you consider the amount of resource required to transform data in legacy systems before loading it.

Key Decision: Expert vs. citizen data scientists or both?

Recommendation: Every enterprise has different needs when it comes to AI/ML capabilities, although most  insurance enterprises are looking to enable citizen data scientists’ capabilities in addition to expert data scientists, to achieve the scale and speed that the organization needs. While enabling key features around model building and operationalizing, such as notebook, "API-ification" of a model, model refresh and release to production, the data platform must also be able to support the compute and storage needs for data science use cases. Snowflake's key feature of isolated loads provides separate computing power for each use case, and Auto scales up or down based on data processing volumes.

Key Decision: Data exchange vs. sharing

Recommendation: One of the key needs for building a true data culture is to enable smooth exchange and sharing of data sets. Datasets that are certified by one team can be used by other teams within the enterprise without spending time on the data prep and cleansing work. This facilitates faster insight generation while increasing accuracy. Third-party data plays a critical role in insurance, so, having a streamlined mechanism to procure, certify and publish third-party data is critical. Many insurers are setting up private a data marketplace to facilitate sharing, smooth integration with third-party data and centralized cost monitoring. Although most public cloud providers come with their own marketplace, Snowflake is a step ahead in this capability because of industry-specific data sets  and seamless integration with Insurance core systems using APIs.

Key Decision: Visualization with self-service and AI augmentation

Recommendation: Business intelligence (BI), visualization and analysis ultimately decide how successful your data initiatives are. Technologies such as augmented analytics combine machine learning and AI to assist data preparation, insight generation and explanation to augment how people explore and analyze data in analytics and BI platforms. Adding the power of natural language processing with data for faster and accurate diagnostic, predictive and prescriptive algorithms, we can empower business users to interact with data more effectively.

Key Decision: Optimized cloud

Recommendation: Success of data on a cloud platform does not only depend on building it right but also on how well it is optimized to run post-implementation for cost, performance and security. It is important to have the right governance in place to avoid sticker shock. Most cloud platforms provide some ways of monitoring, but having a solution customized to your organization is critical.

See also: 20 Insurance Issues to Watch in 2022

Why "Data on Cloud"?

Insurers need to think long-term while choosing a data platform, so it is recommended that they choose cloud-agnostic capabilities that are scalable, secure and at the same time very cost-effective. Generally, SaaS-based offerings can go a long way because they provide near-zero maintenance cost while providing enough flexibility to configure, manage and govern the data platform based on the specific needs of each insurer.

In summary, the recommendations are:

  • Separate Computing and Storage — providing the ability to have unlimited computing power for isolated workloads while not worrying about storage costs.
  • Auto Scaling — providing auto scale-up and scale-down based on data workloads, without manual intervention or any process delays.
  • Third Party Data Exchange — providing seamless data integration with third-party data sources, whether through a marketplace or an API-enabled mechanism.
  • Data Sharing — providing the ability to share data with internal and external stakeholders with the right access control mechanisms. 
  • Data Integration — working with various tool sets, including cloud native connectors to integrate data from a variety of sources, such as core insurance products, mainframes, IOT and telematics.
Ravindra Salavi

Profile picture for user RavindraSalavi

Ravindra Salavi

Ravi Salavi is a financial services technology leader with over 20 years of advisory and consulting experience working with major insurance and financial enterprises.

His key expertise is in digital transformation and the role of data analytics and AI for risk insights, profitable underwriting decisions, cost and fraud optimization for claims, etc. He has led strategic initiatives for leading insurers in North America.

Underinsurance: A Call to Action for Agents

We need to start a discussion about underinsurance, especially after natural disasters, to determine if changes need to be made to better estimate replacement costs.

wildfire

Is it time to re-visit the methodology used by agents to determine replacement costs and re-construction costs? How confident are you that the real property replacement values that you develop are sufficient to either replace or rebuild? If a natural catastrophe hit your community, would you have the same confidence in your replacement or rebuild figures? As the increasing frequency and severity of natural disasters occur, one of the first questions in their aftermath concerns underinsurance.

In the aftermath of the Marshall Wildfire in Boulder County, Colo., the Denver press has continually explored these questions from the insured survivor’s perspective, but there has been little discussion from the insurance industry perspective. The purpose of this blog is to start a discussion on the continuing perceptions of underinsurance, especially after natural disasters, to determine if there are changes needed to better estimate the replacement costs on both personal and commercial policies that agents sell to our customers.

Insurance to value (ITV) is a basic concept that many insurance personnel learn at the outset of their careers. Although counseled that we are not appraisers, adjusters, agents and underwriters were provided with training and valuation tools, aka costimators, that seemed to work very well over the years. Conversations with many front-line agent/brokers assisting with their customer’s valuations find that these tools do not change in their basic structure and do not regularly leave customers underinsured. In retrospect, were they just lucky because they did not face many total losses, or did their continual efforts to monitor and adjust the replacement cost values (RCV) help achieve those excellent valuation outcomes.

Bottom line: This methodology and training has worked quite well over the past 50 years to assist customers with valuing RCVs. Many agents have occasionally seen competitor agents/companies use similar tools to undervalue required limits, which permitted them to underbid higher, more correct valuations. While this behavior still exists, it does not occur as frequently as it once did, and, in the new insurance marketplace used to occasional natural catastrophes, it presents another opportunity for the agent to advocate protection over lower prices.

Why does this subject matter to the author? When he was embarking into semi-retirement, he was asked to serve as a volunteer insurance consultant to the Waldo Canyon wildfire recovery team, Colorado Springs Together (CST), because he was not directly contracted with any of the insurers that faced 347 total losses and some additional damaged properties. Starting that volunteer effort, he was initially concerned about the potential for underinsurance based on other insurance catastrophes, rumblings in the local press and chatter in social media. This recovery process was a huge learning experience in many different aspects of how insurance policies deliver in a major natural disaster, but, happily, the issue of underinsurance did not prevent one of the most complete major wildfire recoveries experienced after a large urban fire.

The Waldo survivors, their builders and their companies navigated through the many different coverage “buckets” -- i.e., debris removal, law and ordinance, extended replacement, inflation guard and landscape allowances, which helped to close most rebuild gaps. In fact, the most extreme Coverage A dwelling underinsurance situation that he encountered (approximately 40%), the policy holder was able to close the gap with the above additional coverages and their company’s endorsement, which doubled the extended replacement and law and ordinance limits because the cause was a declared natural disaster.

What were the lessons learned from his CST experience? There are too many stories to recount in this short piece, but the following were most significant:

  • A community-based recovery team that allows for many segments of the local community to participate in the recovery goal is an important attribute to a quick and complete recovery.
  • The recovery team needs a strong leader to keep the team focused on the main task – rebuilding the neighborhood.
  • A community and team focused on minimizing politics, controversy and adversarial relationships among stakeholders is a critical component of a solid recovery.
  • The encouragement of the survivors to better understand their policies and limits as well as the insurance claims process facilitates quicker resolution of any outstanding issues.
  • Local economic conditions can be a positive driver of the recovery. The Waldo recovery occurred during the end of the 2008 recession, so labor and supplies were more readily available to the recovery.

The recovery team had a self-imposed one-year recovery time limit because virtually all the pieces for the Mountain Shadows Neighborhood recovery were in place by the end of the year. Survivors, neighbors, the city and team members were pleasantly surprised that, despite the early alleged obstacles, an amazing outcome was collectively achieved.

See also: Dramatic Shift in Underwriting Ahead

After such a positive recovery experience, he followed many other wildfire recoveries both in Colorado and other areas in the U.S. Interestingly, he is not aware of another public-private recovery team approach that resembled what was done here in Colorado Springs. In most cases, it appears that recoveries are driven by the local governments, which tend to be slower due to the more bureaucratic approach that government must take to conduct all of its business. Why does this matter in a discussion of underinsurance? Slow recoveries exacerbate the effects of underinsurance.

As Boulder County faces its recovery from the Marshall Fire, the topic of underinsurance seems to dominate its early recovery preparations. Certainly, the recovery challenge is more than three times greater than the Waldo recovery, which will certainly further slow the recovery based solely on the scale. Without being embedded in the Marshall recovery team, it is difficult to fully access the extent of the underinsurance at this time, although there are some early warning signs of potential concern:

  • The limited supply of builders needed to rebuild all the destroyed residences may be a driver of higher replacement/reconstruction costs;
  • The unprecedented increases in the local building costs over the past two years may not have yet been incorporated into the costimator valuation processes;
  • Initial indications of added building code requirements needed to rebuild are very concerning and would not have been included in any costimators;
  • Debris removal delays will slow the actual reconstruction;
  • Unusual supply chain challenges are arising;
  • Popular insurance advertising promotes price competition vs. coverage adequacy;
  • Other natural catastrophes compete for resources; i.e., Kentucky wildfires, California wildfires, Louisiana hurricanes, etc;
  • Rebuild permitting processes aren't streamlined; and
  • There is the continual reminder of underinsurance, which encourages survivors to think their recovery will be impossible.

It is critical for the insurance industry to take the lead in starting to diagnose any shortcomings in the procedures and systems for valuing properties, as well as best practices to streamline recoveries. As we know, insurance coverages/limits may differ among the homeowners policies that different insurance companies write. Perhaps, it is also time to realize that there may be different valuation needs for natural disasters. Of course, the biggest hurdle is to overcome the average consumer’s belief that “it can’t happen to me."

What can front-line agents do to start or aid this discussion? Here are some initial steps:

  1. Identify either personal or commercial accounts where you think whatever costimator being used may either under- or over-insure.
  2. Identify any differences within your agency on how real property valuations are done and re-train as necessary so there are consistent processes.
  3. Check with local claim departments and construction businesses to determine what the going rate is to build in your community/region.
  4. Double check a sampling of real property valuations periodically to make sure they are responsive to local building costs and national inflation and supply line conditions.
  5. Refer any valuations that are either over- or under-valued to the insurer and ask them to check to make sure that they agree with your valuation, leading to continual conversations regarding insurance to value.
  6. Start tracking any variations so valuation adjustments can be made as necessary.
  7. Share any variations in values with your local agency associations so the magnitude of any underinsurance can be assessed. This is especially important in locations more frequently visited by natural catastrophes.

Agents can make great differences for both their customers and the industry. In the meantime, if you have examples of under- or over-insurance using the various costimators provided by your companies, please share them with me at jeputnam@aol.com.

This article first appeared on Bill Wilson's blog. 


John Putnam

Profile picture for user JohnPutnam

John Putnam

John E. Putnam has worked 53 years in the insurance business, including time as a claims representative, a systems procedures analyst, a P&C agent and an independent insurance agency owner/officer. Currently, Putnam is an insurance consultant/broker/teacher who serves as an insurance broker/agent for a medium-sized law firm and large school district and provides a wide range of insurance continuing and professional education courses, teaching about the growing insurance impacts of climate change and extreme weather. 

IPutnam is the past president of the Pikes Peak Genealogical Society and serves as their delegate to the Colorado Council of Genealogical Societies. 

Property Insurance Shopping Tumbles

Despite optimism at the outset of Q4 2021, property and auto insurance shopping trended below 2020 levels by year’s end, TransUnion finds. 

property

Despite optimism at the outset of Q4 2021, property and auto insurance shopping trended below 2020 levels by year’s end, according to the results of TransUnion’s latest Personal Lines Insurance Shopping Report.

While the auto insurance market remained suppressed throughout 2021, the housing market had been red-hot until year’s end, when it dropped into negative territory for the first time in more than 18 months. The findings reveal that in Q4 2021 auto insurance shopping was down an average of 13%, while property insurance shopping dropped an average of 3.4%, compared with the same period in 2020.

Several factors cooled off the property market, including the resurgence of COVID-19, as well as rising interest rates and rent prices. Shopping rates had been elevated well above normal levels, and this change may have been more of a correction following a solid year.

Other findings in the study showed that record-breaking prices for both new and used vehicles deterred many consumers from auto shopping. At the same time, insurance premiums have continued to rise in response to increasing severity trends, prompting more consumers to switch carriers, according to a recent report by J.D. Power. 

What does this mean for 2022?

COVID-19’s omicron variant served as a harsh reminder that even near-term events are challenging to forecast. Another factor is the increase in severe weather events in December. The TransUnion report notes that damages inflicted by tornados pushed the U.S. past its predicted $105 billion in weather-related losses. The fallout is likely to include generally higher premiums and lower marketing budgets, which will reduce consumer engagement—a critical element of sales.

Despite this volatility, some projections can be offered. For example, auto lending to non-prime customers will likely grow in 2022, but vehicle inventory may affect overall originations.

See also: Property Claims: It's Time for Innovation

Also, while the housing market cooled, homeowners are still likely to take advantage of their equity gains by selling and downsizing or renting. Millennials will continue to be the most active in migration and home purchases. The report notes that there are more Black and Hispanic households within this group than in older generations, and homeownership among younger Hispanic people is growing especially fast. 

As Millennials mature and have increased earning power, they face unprecedented and unpredictable financial, environmental and social changes. Insurers should take a partnering approach by meeting people where they are in their current financial pictures and by offering flexible solutions.

To learn more, please visit TransUnion’s latest Personal Lines Insurance Shopping Report.

The End of Monolithic IT Systems

Given the need for flexible and agile insurance product lines, the future of insurance lies in the adoption of SaaS systems.

buildings

The U.S. market is ever-changing, with new niches expanding continuously and creating opportunities for insurers. But the IT systems of the past hold back coverage providers from expanding their product offerings.

With the increased use of digital capabilities during the pandemic, ransomware attacks have hit a record. In the U.S., the volume of ransomware attacks surged 185% in the second half of 2021, compared with the first half, while the average cost of recovering from a ransomware attack stayed at a staggering $1.9 million. The global cyber insurance sector is expected to hit $36.85 billion by 2028. Insurers need to be nimble to help clients deal with cyber attacks, including the expected surge in premiums. 

Catastrophic coverages are seeing major changes, too. In the U.S., Hurricane Ida was last year’s costliest natural disaster, with overall insured losses of $36 billion, and scientists expect extreme weather and disasters to continue to increase in 2022. In the past few years, extreme events have outpaced experts’ predictions, turning climate change into one of the top emerging risks. Experts anticipate that the P&C sector will see the highest growth in written premiums in the past 18 years. 54% of Americans say they cannot afford disaster debt, and almost half of businesses are not able to reopen after a natural disaster hits. To tap into this expanding niche, insurers need to think about leveraging flexible and agile systems. Speed, cost and flexibility are needed now more than ever.  

New risks need new systems

But many insurance companies are still leveraging systems that are primarily serving the back office. These monoliths rely on inflexible databases and have become obese systems that are difficult and costly to change. Developers have added custom capabilities and functions for each client, ending up with large code bases built by accident, not design. This has created more work for coverage providers, which now have to deal with heavy technology to develop and launch products. The downside of the monolithic architecture lies in the insurers’ inability to create products that serve expanding niches, such as cyber and climate insurance.

To maintain competitive pricing when entering niche markets, insurers have low-cost digital transformation in mind. Achieving this may seem impossible, because speed to market is key when trying to stay ahead of the competition. Insurers can balance both, by turning their attention to vendors providing platforms for curating insurance products. Software-as-a-Service (SaaS) systems are both speedy and flexible. They allow providers to customize their products without any coding or advanced technical knowledge. Insurers can save both time and money by adopting such systems and focusing their attention toward expanding their coverage umbrella.

It’s time to get personal

Personalized insurance products will be the winners in each niche market. Customer demand for usage-based insurance is on the rise: Consumers expect to have the ability to calculate premiums based on what they are using in real time. SaaS-based systems can facilitate these features 

The user-friendly interface of SaaS systems allows insurers to build products that comply with back-office requirements and fulfill customers’ demand for personalization at the same time. In this way, insurers can keep up with the changing coverage market and offer the targeted services consumers want. 

See also: Does P&C's Future Lie in Datasets?

Progress doesn’t have to be pricey

Having the right systems in place is crucial for entering niche markets with low-cost products. If insurers are not thoughtful and progressive with their innovation practices, they can end up spending millions on IT solutions that include features they do not even use. With SaaS systems in place, insurers only pay for the tools consumed.

Smart insurers will capitalize on the opportunities offered by niche markets, especially in the cyber and climate sectors. To stay ahead of the curve, insurers need to understand the importance of exploring new platforms. Monolithic systems are no longer a viable solution for developing flexible and agile insurance product lines: The future of insurance lies in the adoption of SaaS systems, and the forward-thinking insurer knows that.


Greg Murphy

Profile picture for user GregMurphy

Greg Murphy

Greg Murphy is executive vice president for North America at Instanda. He is an accomplished financial services executive with a passion for transforming the customer experience and improving the reputation of the industry.

Balancing Personalization and Automation

Seemingly impersonal digital transactions underscore the criticality of personalization. The key is to pinpoint the exact moment of need in the insurance buying and filing experience.

balance

The insurtech industry is hot with data gathering, analytics, automation and all-things digital. And for good reason. As more people prefer online experiences and are accustomed to intent marketing practices that “know” your online moves, it’s inevitable that carriers will also know and mine digital movements like purchasing, enrolling and filing claims. Does all this digital transaction insight and big data mean that human touch or consult has gone by the wayside? Not at all. In fact, all these seemingly impersonal digital insurance transactions further underscore the criticality of personalization. The transformative opportunity is to pinpoint the exact moment of need in the insurance buying and filing experience.

With increasing integration connections to sources of customers’ information as well as investing in analytics, carriers are poised to create the perfect blend of automation and personalization. It’s critical that a carrier consistently proves that they understand the customer and can streamline their needs. It all hinges on clearly understanding the customer’s journey. 

Carriers that understand the customer’s motivations for buying insurance and filing claims will reap the benefits of the nexus between automation and personalization. It’s short-sighted to think of the customer as a single-touchpoint transaction, such an enrollee or a claimant for a single product. Rather, they are on a life journey that includes a variety of experiences where insurance can assist. Understanding this balance creates opportunities for customer loyalty to, and engagement with, a carrier. 

The Journey of Employee Benefits

Take employee benefits. This journey begins when the employee enters the workforce and ceases on retirement or their death. Each employee begins with enrolling in benefits, continues the journey through life experiences that cause them to file for claims, such as short-term disability or paid family leave. As the employee’s life and career matures, they may make further investment in benefits. This journey with employee benefits typically ends with accessing retirement plan benefits. Upon death, their beneficiary files for the death benefits from the employee’s life policy. 

Understanding the employee’s journey is the first part. The next is to home in on the employee’s motivations to consider each employee benefit through that journey. Savvy insurance carriers understand this. 

See also: Why Customer Journey Mapping Is Crucial

Enrollment: The Journey’s First Step 

Because an employee is excited to embark on their career, they are less focused on employee benefit enrollment upon hire. Creating an easy, informational enrollment process is key. Carriers can use their decades of data coupled with connected census and policy information to create an automated yet personalized experience. Layering in AI-enabled informational touch points for the typical questions an employee raises during enrollment adds the right level of human intervention. Auto-enrollment in certain benefits such as 401(k) retirement or low-cost life insurance is even better. At this juncture, the carrier has provided an automated but personalized experience. 

Claim Filing: The Journey Continues

When it’s time to file a claim against the employee benefits, typically years after enrollment, the employee likely experienced a dramatic event in their life. This could be exciting like welcoming a new child or enrolling in a graduate program or stressful like an illness or workplace injury. Now, the employee’s motivation is to avail themselves of the benefit quickly so that the benefit assists them with navigating the life experience. But, due to the complexity of the employee’s life change, the employee likely has questions that need answering quickly and easily. At this point in the journey, carriers must provide the human consultation, the empathy and critical thinking necessary to assist the employee through the benefit-filing process. 

At this stage in the journey, automation expedites the filing process, including surfacing the relevant and eligible customer products and employee census information. In the example of the employee giving birth, personalized automation should quickly present short-term disability, paid parental leave or FMLA, or trigger health insurance requirements like adding the baby to the policy. When a carrier delivers a personalized but automated approach to the employee’s life situation, the employee gains a sense of understanding of their specific wage replacement and job-protected benefits, or their out-of-pocket costs.

Industry data is clear that online claim filing is trending, but the majority of claimants still prefer personal communication when filing and questions answered by humans. Optimal insurance experiences are often found when humans and machines work together. Integrating transfer points between technology and carrier staff along with real-time data access is key to creating a balanced approach.

Additional Benefits: Advancing the Journey

Later, as the employee settles into their career and begins to further consider their finances and potential additional benefits, carriers again have an opportunity to leverage the employee’s motivation. This is an opportunity to delight employees by understanding this stage of their journey by automating information, or even enrollment, around retirement benefits, family care leave and life insurance.

Even at this stage, though, carriers must remember that customers often don’t understand the complexities of insurance, such as how the benefits available to them might meet their personal goals, risk adjustment and what goes into quoting and underwriting. Employees are primarily focused on their personal life advancement, not details of their insurance. Therefore, it’s essential that benefits are characterized in a way that is relatable to a customer’s stage in their journey. This includes not only accessing information about the benefit (online versus a consultative broker or HR professional), but actually accessing the benefit itself. Auto-enrolling new hires into a company 401(k) plan was once controversial; now, it’s deemed as a brilliant and helpful way for employers to ensure employees’ financial future. Automation such as auto-enrollment at certain stages of an employee’s journey provides incredible value. Auto-enrollment at certain points in an employee’s journey is well worth considering, especially for long-term disability or paid family leave when an employee reaches a certain tenure or adds a family member to insurance.  

See also: Why Cyber Strategies Need Personalization

Cashing Out: The Final Stage

Finally, filing for retirement or life insurance benefits comes from an obvious different motivation than filing for benefits around an illness or family-related life event. With these end-of-career benefits, carriers can again easily automate to expedite benefit decision and payment. Connecting with fraud detection sources allows further acceleration of benefit processing. 

Chatbots and AI can be a bridge to human interaction as well as provide a 24/7 convenience. When used well, AI can manage high-frequency inquiries in a way that feels natural to users. By now, customers expect the carrier to have information about them readily accessible. As the “conversation” progresses, AI can use workflow to route the claimant to a trained human resource professional.

The Market Is Changing, but Human Basics Remain

This increase in the use and demand for relevant and pinpointed insurance requires that carriers rise to the occasion. By focusing on the customer journey, not the insurance product, insurance carriers have an opportunity for life-long relationships with customers. Carriers can apply automation and ecosystem connection to adapt to rapidly changing market expectations and create positive insurance experiences by leveraging technology-enabled information, as well as human consultation and empathy. This benefits customers and carriers alike. 

In this new era of insurance, carriers can replace siloed, product-focused and human-heavy interactions with state-of-the-art, responsive personalized ones. The result is a contemporary and financially beneficial experience. In doing so, carriers provide easy access to needed benefits and helpful services, thus creating loyal customers for years.


Megan Holstein

Profile picture for user MeganHolstein

Megan Holstein

Megan Holstein is the executive vice president of claims and absence product at global software company FINEOS, Holstein is responsible for the strategic design and marketing of the company's claims, absence and integrated disability and absence management (IDAM) software solution.

She is an expert at the nexus of employee benefits, paid leave and technology. She believes the time has arrived for a modernized, holistic approach to absence benefits and is influencing insurance carriers, third-party administrators (TPAs) and employers to move toward more efficient, comprehensive, easy-to-navigate solutions for employees needing to take time away from work.

Employee Benefits in the Time of COVID

The pandemic has provided the sort of compelling event that is needed to propel employee benefits insurers to a digital transformation. 

digital

Digital transformation is difficult because it is as much a business change management issue as a technical challenge and often requires a truly compelling event to propel such a sweeping project. The COVID-19 pandemic caused such a compelling event in employee benefits.

A recent Zurich Sigma study of life, accident and health insurance (Swiss Re sigma 3/2021 - World insurance: the recovery gains pace) projects an increase in life protection insurance premiums such as disability, hospitalization and critical illness. At the same time, the nature of work is changing based on the global need to quarantine during the height of the pandemic. In a recent Bloomberg article, Prathima Choudhury, a Harvard School professor and expert on remote work, says, “We will probably in 10 years stop calling this ‘remote work.’ We’ll just call it work.” 

Employee benefits insurers seek to enhance their operational processes, provide better customer service across their customer base as well as within their partner ecosystem and quickly bring new products to market. Addressing these goals requires a range of digital capabilities including software-as-a-service (SaaS) platforms that remove constraints around location and physical access; smart process management based on machine learning; better analytics and modeling tools; and user experience options that go beyond the traditional interface.

Making 'Work from Anywhere' Possible 

Spurred by the pandemic, there has been a slow move toward “work from anywhere” models in the workplace, especially in the software world, but for a variety of reasons many companies have been slow to change. The employee benefits business is well-suited to this model due to the virtual nature of the product/service model and the recent advances in knowledge worker tools. However, some critical issues must be addressed.

Most insurers are still struggling with core insurance processing systems that are decades old and, in many cases, built before the internet became an essential element of commerce. Those systems were designed to support one product and aren't capable of enabling service-based products such as government-mandated paid family leave and new business models such as voluntary worksite products. 

Employee benefits carriers have done an admirable job wrapping their homegrown legacy systems with workflow software and robotic process automation (RPA) tools to provide some levels of digital process management and customer service. Nevertheless, the result is usually awkward to use and manage. Also, these hybrid systems are still mostly on-premise, requiring a physical data center or expensive custom hosting. Insurers tend to cling to these older systems because they have decades of insurance process and product expertise layered in.

The good news is that new SaaS systems and a wide variety of new technology from insurtechs and traditional software providers can meet the needs of the next-generation carrier. Here are a few key areas where new technology is helping:

  • Modern SaaS core systems: There are core systems available today that serve the employee benefits market that were either “born in the cloud” or have become “naturalized citizens.” They go beyond basic hosting to leverage the natural advantages and inherent capabilities of the SaaS model. These systems tend to interoperate better with other SaaS-based systems used by brokers, benefit administrators and HR systems. The systems are capable of supporting the new, broader definition of employee benefits products.
  • Machine learning: Employee benefits is one of the most complex insurance segments, with a B2B2C business model that has multiple value chain partners providing services to the employer, the employee and, in some cases, each other. Products have many options and are often heavily configured by the broker and presented in mixed portfolios across multiple insurers. Machine learning, which has been heavily employed in claims fraud and underwriting risk scoring models, is now being deployed in transaction segmentation, automated workflow and advanced user experience support.
  • Rethinking the user experience: The employee benefits ecosystem has a lot of stakeholders, including the insurer, brokers, benefit administrators, consultants, enrollment firms, employers and, of course, the employee. That employee often gets the least attention in the broader user experience discussion. If all goes well for them, they have the least day-to-day interaction with the ecosystem, with the employer acting as the “customer.”

The introduction of voluntary benefits and workplace selling models has changed the dynamic. Employees have more options under their direct control when making plan choices, and some of those options require more understanding of the benefits and their interaction with others. For example, an employee needs to understand what combination of HSA funding and voluntary accident, hospital and critical illness insurance provides the best protection at the best price, all of which goes beyond their major medical insurance and company paid disability plans. 

See also: Thinking Big for True Transformation

Employees need help in making these decisions, but insurance carriers realize that too much information can often be as bad as too little. The goal becomes to create a balanced user experience where employees get the information they need without being forced down a narrow path of a few standard choices. The same approach of balanced user experience applies to the claims process, where employees want as little friction as possible while still getting the full benefit they deserve. Using machine learning, purpose-built core systems and the right digital connections, a user experience could be as simple as a text from the insurance carrier informing the employee that their $10,000 claim payout was just deposited into their account and enabling issue resolution options as simple as a reply text to be connected to a case worker.

Employee benefits insurers have an opportunity to gain real competitive advantage and better serve their customers, and the pandemic has created the compelling event to make it happen.


Chuck Johnston

Profile picture for user ChuckJohnston

Chuck Johnston

Chuck Johnston is responsible for the global marketing team at Fineos, driving the corporate brand, product go-to-market and in-market product management for North America.

Johnston has over 30 years of expertise in insurance and information technology. He is a frequent presenter at industry conferences, including LOMA events, LIMRA, the Insurance & Technology Executive Summit, ACORD, IASA and the International Insurance Society. His background in the carrier, analyst and software vendor communities give him a broad perspective on the insurance market.

Earlier in his career, Johnston helped relaunch the Meta Group insurance industry practice and helped it become the leading insurance advisory services practice of its time. With the merger of META Group and Gartner, Johnston moved to the vendor community, holding leadership roles at Callidus Software, Siebel, Oracle, Celent Research and EIS Group.

A Milestone for Driverless Cars

U.S. regulators essentially took the training wheels off autonomous vehicles last week, clearing the way for AVs to take a major step forward. 

Image
a photo of a driverless car projecting sensors

While progress may seem to have stalled for driverless cars, don't be fooled. U.S. regulators essentially took the training wheels off autonomous vehicles last week, clearing the way for AVs to take a major step forward. 

The U.S. National Highway Transportation Safety Administration ruled that manufacturers can produce cars without controls designed for human drivers. No more need for a steering wheel, a brake pedal, a dashboard or anything else that we traditionally think of as part of the interior of a car. AVs can be optimized for carrying people, for making deliveries or for anything else.

The NHTSA said AVs still have to meet all the safety standards required for cars with human drivers but will no longer specify the sorts of equipment that must be in a vehicle to meet those standards. 

The change will allow for the sort of creative use of space that General Motors' Cruise subsidiary has demonstrated for its driverless vehicles, based on the idea that they will be used to ferry people to work and school in the mornings and take them home in the afternoon or evenings but will be available for grocery deliveries mid-day. Cruise has shown a cargo module with refrigerated lockers that can be put into a vehicle to quickly fit it for deliveries. (Cruise surely hopes that its integration with GM's manufacturing expertise will give it an edge over Waymo, which has led on AV technology but which, as a subsidiary of Google, doesn't have as tight a coupling with an OEM.)

Now, the NHTSA ruling won't change things overnight. AVs will have to continue to improve, especially in city environments, where pedestrians and cars can act unpredictably, and must demonstrate their safety following at least half a dozen fatalities over the past few years. At the moment, despite all the expectations for AVs, Waymo has been operating only a limited number of fully autonomous vehicles (in other words, with no safety driver behind the wheel) in the relatively simple environment of suburban Phoenix, and Cruise has just begun operating a few fully autonomous robo-taxis in San Francisco. 

So, auto insurers won't see their sales to individual drivers dry up any time soon. But no one should think that progress has stalled.

In fact, the move toward electric vehicles (EVs) in recent years -- which will accelerate if gas prices stay so high for an extended stretch because of geopolitical tensions, supply chain disruptions and other factors -- bolsters the move toward AVs. Driverless cars require so much electricity for sensors and computation that all are expected to be EVs. The switch from internal combustion engines to EVs requires a transformation of the entire automotive ecosystem, from suppliers of raw materials and parts up to the OEMs and then out to those who sell, finance, service and insure the vehicles, and the momentum for EVs will prepare the way for the transition to AVs. 

When that transition happens, just don't expect the vehicles to look much of anything like they do today. Cars were initially defined by what they lacked -- they were called horseless carriages. But cars came into their own soon enough in ways that bear little resemblances to the carriages of the late 1800s. AVs are now defined by what they lack -- they are driverless cars. But, following the NHTSA ruling, they can go pretty much anywhere from here.

Cheers,

Paul


3 Reasons for Insurtechs, Agents to Collaborate

Independent agents, in particular, have the human touch, industry knowledge and carrier access needed to build and retain customer relationships.

agent

Last year, insurtechs received $10 billion in investments worldwide. And, as direct-to-consumer (D2C) distribution becomes more and more popular, some analysts have even questioned whether insurtechs will replace the insurance agent altogether. 

But agents deliver value that tech can’t quite replicate. Independent agents, in particular, have the combination of human touch, industry knowledge and carrier access needed to build and retain customer relationships. Instead of sidelining them, D2C insurtechs should partner with agents to increase revenue and maximize customer satisfaction.

Here, we’ll take a deeper dive into three ways that insurtechs and independent agents can benefit from joining forces. 

#1: Independent Agents Build Customer Trust and Loyalty

In the insurance industry, consumer trust and loyalty aren’t just important – they’re essential. 

Customers insure property that’s valuable to them, and they rely on the insurance provider they’re working with to find the best coverage. As part of the process, customers have to disclose personal information. They’re trusting their insurance provider to handle it with care. Trust and loyalty go hand in hand – a breakdown in trust will push customers away. 

Here’s the problem: Consumers don’t exactly trust digital insurance services. When it comes to claims, for instance, Accenture research shows that…

  • 49% highly trust human professionals.
  • 12% find automated services to be similarly trustworthy.
  • 7% trust chatbots at a similar level. 

For digital-first D2C insurtechs, these numbers should be alarming. Even with insurtechs’ explosive growth, low consumer trust spells a future of high customer turnover. 

To avoid this outcome, D2C insurtechs need a way to build personal connections that generate trust. The simplest route? Partnering with independent agents.

From the first consultation, agents and customers establish a rapport that strengthens over time. 

With each personal connection they make, agents also help D2C insurtechs build a more loyal customer base. 

As it stands, all-digital insurtechs give customers little reason to stick around. If pricing or product offerings change, customers won’t hesitate to switch providers. Agents, however, can create that crucial link between customers and insurtechs. When customers feel a connection, they’re more likely to stay loyal to the agent – and the company – they’re working with. 

#2: Independent Agents Deliver Custom Professional Guidance

Insurtechs excel at digital innovation, and the right tech can make for a smooth and convenient user experience. But when customers have questions about their coverage, digital tools can’t offer much beyond general guidance.

For example, think about an insurtech that relies on AI chatbots to answer customer questions. If a homeowner asks, “Do I need flood insurance?”, the chatbot’s ability to respond is limited. In this case, it might be able to provide a general answer. But what happens when the customer doesn’t know enough to ask a question in the first place? Here, the chatbot can’t address the customer’s needs. 

Agents can help D2C insurtechs overcome these shortcomings. 

For example, with flood insurance, the agent might look up whether the customer's home is in a floodplain – and when the floodplain map was last updated.

The best part about this interaction: It points the customer toward information they didn’t know they needed. This both makes for a better-informed customer and builds trust in the agent’s expertise. 

In this model, when pricing or product offerings change, the agent can educate the customer about their options – and the customer trusts the agent to guide them toward the one that makes sense.

See also: Agents Must Become ‘Discussion Partners’

#3: Agents Need the Digital Tools That Insurtechs Can Offer

As insurtechs have matured, the reigning industry narrative has been framed in terms of opposition – a battle between D2C insurtechs and independent agents.

The reality, though, is that these two parties don’t have to compete. Agents can help insurtechs build trust, and insurtechs can help agents streamline and digitize their operations.

Insurtechs can leverage their tech capabilities to address critical agent pain points. The right tech (including the following) can empower agents to deliver a seamless user experience that’s on par with what insurtechs themselves provide:

  • Policy/carrier rating software. 
  • A policy management system.
  • Robust IT infrastructure.
  • Omnichannel distribution tools.
  • Data-driven digital marketing support.

Tech-enabled agents can help more customers find the best available policies. With each customer they serve, agents will build and deepen relationships that make everyone happy – agents, insurtechs and customers. 

High-Powered Partnerships Are the Future of Insurance 

In a rapidly changing industry, neither insurtechs nor independent agents can afford to operate in a silo. Without a more human touch, insurtechs will struggle to build the connections that create lifelong customers. Meanwhile, agents need digital tools to overcome their inefficiencies. 

For both parties, a future of growth will require tech-powered partnerships. Working together can create more efficient paths to stronger customer relationships that keep customers coming back.

The information contained in this page is provided for general informational purposes only and may not be applicable to all situations. PEAK6 makes no guarantees of results from the use of this information.


Deb Franklin

Profile picture for user DebFranklin

Deb Franklin

Deb Franklin is the co-CEO of PEAK6 Insurtech, the insurance operations and technology subsidiary of PEAK6.

The company's first tech-based solution was developed in 1997 to optimize options trading, and, over the past two decades, the same formula has been used across a range of industries, asset classes and business stages. Today, PEAK6 seeks transformational opportunities to provide capital and strategic support to entrepreneurs and forward-thinking businesses, helping to unlock potential and activate what is into what ought to be.
 

10 Tips for Preventing Workplace Suicide

Leaders can take bold and visible positions declaring suicide prevention and mental health promotion critical community concerns.

person

1. Leaders Take a Stand — “Not Another Life to Lose”

Leaders can take bold and visible positions declaring suicide prevention and mental health promotion critical community concerns. This statement can be written or oral and might include some of these talking points:

  • Thank you/We are all in this together:
    • Authentically express gratitude for the community’s service and dedication during stressful times and how their efforts are contributing to the overarching important mission and vision of the community.
    • Offer specific examples of key people or groups demonstrating resilience, caring for one another or serving well to promote well-being.
  • We see you, and we want to hear from you: 
    • Acknowledge that people are facing challenges right now (list examples specific to your community) and that many may be experiencing high levels of stress. 
    • Then say, "I get it. Me, too." 
    • Give a specific example of a challenge you faced – you can describe any specific hardship that you feel comfortable with, and you can go into as much detail as you are willing to share. The point is that you are human. too. If you have received support from others, describe how it was helpful.
    • Offer an open forum where community members can connect, check in and support one another.
  • We care about you: 
    • Say. "While we had no choice but to rise to face the stressors we’ve been challenged with, we have choices about how we take care of each other. Your contribution to this community matters because you matter to us. Your families matter to us. We don’t want you to just survive the coming weeks and months, we want you to thrive because we need you. You are part of our community and part of our family. Today, I want to talk about how we are going to take care of you and each other.”
    • Offer a short list of resources and steps you are taking to help them cope (e.g., community resources, crisis resources, and the resource page you are developing on your website).
    • We have a plan – here is what to expect on how the community will work to prevent suicide and promote and mental health.
    • Offer reassurance: “If you get stuck, I want you to come to me. I’ve got your back. Together, we will find a way through.”

2. Bring Mental Health and Suicide Prevention Resources to Life

In addition to posting social media graphics and posters with the crisis resources numbers and lists of website links, take time to bring these resources to life for people. Effective mental health advocates do their homework. If you want to be a trusted referral source, you need to walk your talk. Get to know your local mental health providers. Visit your local psychiatric hospital or addiction recovery center. Attend a 12-step meeting. Invite local counselors to a “meet and greet” event. Call your local crisis line to get a better sense of how it works. Ask the questions you need to have answered so you can confidentially refer. Your referral will be so much stronger if you can say, “Oh, I know Dr. So-and-so, she’s really approachable and competent. I’ll take you there to meet her, if you’d like.”

  • Conduct a mental health resource audit:
    • Kick the tires of your available resources -- ask them questions about how they work, what to expect, and what their credentials are.
    • Go further -- use the services to see how they work from your personal experience.
    • Create a “what to expect” document of the best resources for your community.
    • Develop a resource promotion plan.
  • Share stories of how resources were helpful:
    • Build credibility by talking about what you and others have learned from your firsthand experiences.
    • Troubleshoot on ways to work through barriers to help.
  • Meet and greet your resource representatives:
    • Bring a representative from a mental health or crisis service to your community to describe the resource and answer questions. Put a face and a name to the contact to help facilitate the future warm hand-offs.

See also: Why Invest in Suicide Prevention?

3. Launch a Well-Being Advisory Council

A true comprehensive and sustained public health approach to prevention will take more than an awareness week or one-time training. To create significant change, a more strategic approach is needed. Start by pulling together a small group of stakeholders – people whose roles in the community reflect some level of relevance to this issue and others who are passionate about suicide prevention because it has touched their lives personally. Their task? To identify culturally relevant areas of strength and vulnerability for suicide within the community and to develop a strategic approach to change. 

4. Implement an Engaging Communication Strategy

Look beyond the awareness week to figure out a broader and deeper, multi-pronged approach.

People who are experiencing suicidal intensity often feel great comfort in knowing they are not alone in their pain. By realizing that trauma, grief and injustice often lead to suicidal thinking, people living through this despair can start to shift their thinking. The trap that some advocates fall into is overemphasizing the prevalence of extreme behaviors as an “epidemic.” This type of messaging can make people feel hopeless about change. Worse, when it comes to suicide, this type of exaggeration might even create a cultural script that inadvertently influences people to engage in suicidal behavior, because it is the "norm" of what people do to cope with pain. Use suicide death data and suicide loss stories judiciously and make sure they are balanced with other data that represents healing and help-giving.

Tell people what you want them to remember:

Sometimes, in our attempt to get attention to our cause, we play up tragic outcomes and overlook important calls to action and messages of hope. We need to tell people what we want them to remember: Treatment works, prevention is possible, and people recover. Let people know what to do if they are struggling or if they are worried about a friend or loved one. Tell people exactly how to get involved in suicide prevention in their communities.

5. Cultivate Powerful Storytellers and Reduce Bias

A main goal of many mental health advocates is to “reduce the stigma of mental illness”; however, the more we talk about stigma, the more we actually reinforce it. Instead, we can fight bias and prejudice about people who live with mental health conditions or suicidal thoughts by sharing stories of hope and recovery. When we can demonstrate how others transform their wounds into sources of power, we create hope. When respected people come forward and say, “I fought through my suffering, I got support, and I got better,” others feel they can get better, too, and the issues become less marginalized. When you do programs that highlight how people have lived through their pain, be sure that they don’t end with despair; share the healing practices and positive outcomes, as well.

6. Honor the Life Lived of Those Who Died By Suicide and Celebrate the Lives of Those Who Have Survived.

Just like we do for people who fight cancer, we can honor the life that was lived with dignity and celebrate the resilience of people who fought to stay. 

7. Offer Screening Tools that Lead to Self-Empowerment

Screening is a great example of a low-cost, high-impact tool for mental health and suicide prevention advocates. Like with other health issues, screening for mental health conditions increases the likelihood that we can identify emerging symptoms and alter their course with early intervention. Screening offers people a way to anonymously self-assess, which is often an attractive first step for those who are ambivalent about seeking help. A screening that just gives participants a label, however, will fall short. Effective screening tools give participants a call to action and link them to additional local and on-line resources. Here are some examples:

8. Make Mental Health Promotion and Suicide Prevention Programs and Trainings Engaging

It’s human nature to turn away from things that are scary, confusing and depressing. The challenge for mental health/suicide prevention advocates is to make programs uplifting, engaging and cool without becoming so superficial they miss the point. 

  • Develop a contest to encourage participation:
  • Provide opportunities for deep learning.

Many mental health promotion efforts seek to promote awareness, but education alone will not move the needle. We call it the “State Trooper Effect.” We pay attention to educational or awareness-raising efforts when they are done well and right in front of us, but, once they are in our rear view mirror, we tend to go back to what we were doing before. Deep learning goes beyond passive input of knowledge. Deep learning engages people in a knowing-being-doing process. Yes, education is part of that equation – a necessary but not sufficient piece. We also need to get people “doing” – physically, emotionally and even spiritually involved in the work, and, to really make it stick, personal reflection on the experience is key.

  • Offer a training to your community.

Consider offering a brief suicide prevention gatekeeper training

See also: Blueprint for Suicide Prevention

9. Create a Symbol of Solidarity

We’ve seen the pink ribbons, the rainbow flags and the Black Lives Matter fists. Symbols of solidarity work, but they need to be unique. When these symbols work well, people can see at a glance the community that is being built. Symbols used to promote suicide prevention can let people find others who have lived through suicidal intensity or find people who might be safe to approach with questions. When the symbol of solidarity starts to spread to large groups of people, it is a powerful testament to a person secretly in despair. Some examples of symbols of solidarity in suicide prevention include:

  • Project Semicolon: https://projectsemicolon.com/ 
  • Honor beads often worn at the American Foundation for Suicide Prevention’s Out of Darkness Walk. Participants choose to wear different colors to symbolize their experience – one color represents “I have lost a loved one to suicide,” another color might mean “I have struggled myself,” while another might mean “I support the cause of suicide prevention.”
  • Stickers worn on construction hard hats showing which workers had received suicide prevention training.

10. Donate to or Volunteer for Local or National Suicide Prevention Organizations

Engaging in community prevention efforts is a great way for people to give back and to get to know the local resources available. Investments in prevention programs and research will help us get ahead of the problem. Get involved!


Sally Spencer-Thomas

Profile picture for user SallySpencerThomas

Sally Spencer-Thomas

Sally Spencer-Thomas is a clinical psychologist, inspirational international speaker and impact entrepreneur. Dr. Spencer-Thomas was moved to work in suicide prevention after her younger brother, a Denver entrepreneur, died of suicide after a battle with bipolar condition.

A New Look at Strategic Initiatives

Personal lines insurers will continue to advance their digital transformation strategies in 2022, albeit with a new lens and several shifts in priorities.

lines

Personal lines insurers are no stranger to widespread digital transformation and innovation, having been at the forefront of these changes for the past decade. When the pandemic hit in 2020, personal lines insurers responded in different ways. Some stayed the course with their existing digital strategies, whereas others began reshaping and even accelerating their plans to meet the shifting needs and expectations of policyholders, agents and employees. As the pandemic wore on into 2021, insurers split increasingly between maintaining or reshaping their current initiatives. Now, according to a new study from SMA, personal lines insurers will continue to advance their digital transformation strategies in 2022, albeit with a new lens and several shifts in priorities.

SMA's recent research report, "2022 Strategic Initiatives: P&C Personal Lines," features market insights from an annual survey of insurance executives about the state of their strategic plans. Despite the numerous and rapid changes resulting from the past two years, the personal lines segment remains committed to digital transformation. One hundred percent of surveyed executives report that digital transformation is a key strategic initiative in 2022. However, compared with 2021, there has been a two-fold increase in those developing strategies over implementing or broadly deploying new initiatives. This reflects a broader industry trend SMA is seeing of insurers opting to reexamine their go-forward strategies in light of lessons learned during the pandemic and to align their transformational and business priorities. What is now clear is that the next wave of transformation is on the horizon.  

Just as digital strategies are shifting, so are the key business drivers of personal lines insurers’ investments. While cost containment was a key driver in 2021, executives did not identify it as a top priority for 2022. Additionally, innovation, which has historically been a critical investment driver, returned to the top-five list in 2022 after declining in importance in 2021. As personal lines insurers become increasingly more confident about the state of the industry and workforce post-pandemic, SMA is seeing a corresponding shift in their business priorities.

See also: Insurtech: A Decade Gone, a Decade Ahead

Insurers entered 2022 with a new perspective and are taking the time to adapt their business roadmaps accordingly – both in terms of digital transformation and workforce strategies. Personal lines insurers have built a strong platform for innovation and digital advancement, having been a leader in these areas for years. By continuing to focus on their key business drivers and adapting to the changing needs and expectations of their key stakeholders, personal lines insurers are well-positioned for success in 2022 and beyond.

For more information on specific strategic initiatives of personal lines insurers, including both traditional and transformational initiatives, read SMA's recently published research report, "2022 Strategic Initiatives: P&C Personal Lines."


Mark Breading

Profile picture for user MarkBreading

Mark Breading

Mark Breading is a partner at Strategy Meets Action, a Resource Pro company that helps insurers develop and validate their IT strategies and plans, better understand how their investments measure up in today's highly competitive environment and gain clarity on solution options and vendor selection.