Download

Auto Claims and Collision Repair: The Great Reset

Barring another “black swan” event like the pandemic, the automotive ecosystem of 2030-2035 will be virtually unrecognizable from today.

building

While technology-enabled disruption of the automotive ecosystem was already well underway prior to 2020, the global pandemic caused even greater disruption, and many of the changes will continue to affect every corner of society and industry well into the future. We have identified deceleration in some areas but acceleration in others. Our intent here is to put as much of this into context as is possible and to offer a view of the “new” future as we see it, following what we are calling “The Great Reset”     

Auto Safety

Early Traffic and Driver Safety

Traffic safety has been a concern since the first U.S. gasoline-powered car was introduced in 1896. In fact, the first seat belt patent was granted in 1858. Massachusetts introduced the nation’s first statewide traffic laws in 1901, limiting speeds to 12 mph in cities and 15 mph on country roads. New York introduced a drunk driving law in 1910. And in 1930 the nation’s first three-way traffic light was introduced.

Before there were lane departure warning systems, blind spot monitoring and rearview cameras, the automotive world saw one of the most important safety technologies to ever be invented—brake lights. The first brake lamps appeared as early as 1905, though the requirements for brake lamps took a bit longer to catch on. For many drivers, hand signals were enough of a warning to other drivers of their intent to stop or turn. This reliance on hand signals made it difficult for many drivers to enjoy their automobiles at night, though, making the brake light a necessity.

By 1928, 11 states in the U.S. had made brake lights a requirement on cars. But the most important brake light of all is the third brake light, introduced in 1974. The third brake light reduced rear-end collisions more than 60%. It quickly became a requirement on all automobiles.

Later in this article, we describe more recent driver safety technologies, introduced in 1950, and collectively referred to today as ADAS (Advanced Driving Assistance Systems).   

Rising Traffic Deaths

In spite of all of the many driver safety technologies and the many impaired and distracted driver laws, U.S. traffic deaths have continued to rise. One of the many unexpected consequences of COVID was the increase in driving speed on much-less-congested roadways, which resulted in higher accident severity, including more fatal crashes. The number of U.S. traffic deaths surged in the first nine months of 2021 to 31,720. The estimated number of people dying in motor vehicle crashes from January to September 2021 was 12% higher than in the same period in 2020. That represents the highest percentage increase over a nine-month period since the U.S. Department of Transportation (DOT) began recording fatal crash data in 1975.

This February, DOT announced an ambitious safety plan with the goal of zero roadway deaths. Calling the status quo “unacceptable,” Secretary of Transportation Pete Buttigieg unveiled a plan that will be implemented over the next three years. He noted that nearly 95% of U.S. transportation deaths occur on streets, roads and highways. Buttigieg cited National Highway Traffic Safety Administration (NHTSA) data that found an estimated 38,680 people died in motor vehicle crashes in 2020 and 20,160 died in the first half of 2021. That’s an 18% increase compared with the first six months of 2020 and is the largest number for January through June since 2006.

Collision Repair Industry Consolidation

For the last 15 years, we have seen the influence of financial institutions, investment banking and private equity targeting industry consolidation through multi-shop pperators (MSOs). Today, small to medium-size MSOs are now partnering with private equity companies to help accelerate their growth. These aggressive consolidators, known as multi-location operators (MLOs), such as Crash Champions, Classic and CollisionRight, are building regional and super-regional platforms to compete with the larger legacy consolidator MSOs like Caliber and Boyd/Gerber.

The collision repair space has long-term, proven economics and insurance-industry-driven demand dynamics that create relatively strong cash flow stability. A very high percentage of the repairable vehicles come from direct repair program (DRP) relationships with top 10 insurance carrier partners with ever-increasing market share. Repairers that provide consistent, high-quality repairs and service can depend on receiving a steady stream of vehicles. The quid pro quo revolves around managed performance metrics and agreed revenue/expense models between the repairer and insurer. The better the performance metrics, the more reliable volume the carrier will continue to influence to the MSO; carriers will rescind flow if performance and customer satisfaction deviates much from agreements.  

Insurers rely on the MSO repair organization to expand to new locations in insurer-targeted markets while the repairer looks to benefit from incremental cash flow through the working relationship and referrals from the insurance partner. This relationship allows the repair organization to leverage its insurer referrals without investing heavily in consumer direct marketing.

There is no evidence of a slowdown, especially for private equity investors, as they continue to see opportunity in consolidating the collision repair industry, even during a worldwide black swan event like the COVID-19 pandemic. Currently, there are 12 MSOs in the U. S. that have a total of 15 private equity or strategic investors or are publicly held.  

See also: Reflections on Insurtech, Pandemic

Caliber and Boyd/Gerber, by far the two largest consolidators, have continued to be consistent, prolific buyers of MLOs throughout the last two years. Service King continues its acquisition hiatus, which now spans almost four years. Two of the largest acquisitions in 2020 were of the U.S. Fix Auto network by Driven Brands and of Pacific Elite by Crash Champions. 

Because of these and many other transactions and despite COVID’s impact, 2020 and 2021 ranked as very active years for MLO transactions, with 676 MLO locations acquired, representing revenue of $1.8 billion. Since 2012, when we initiated coverage of MLO transactions, 2,271 MLO locations have been acquired, reflecting over $6.5 billion of revenue transfer while averaging $2.9 million per location.

The Advent and Future Impact of ADAS

Adoption and Impact on Collision Repairs

ADAS were being used as early as the 1950s with the adoption of the anti-lock braking system (ABS). Early ADAS include electronic stability control (ESC), anti-lock brakes, blind spot information systems, lane departure warning, adaptive cruise control and traction control.

The adoption of ADAS features on newer vehicles is having a growing impact on all aspects of collision repair and paint consumption, along with material changes and consequences within the auto physical damage landscape. Below, we have quantified through the current decade those changes most important to the number of collision repairable vehicles, PBE and paint company refinish revenue and expected changes across related distribution channels.

A new American Automobile Association study on the effectiveness of driver monitoring systems in vehicles equipped with ADAS found that direct systems with driver-facing cameras to detect driver distraction or disengagement are more effective than those that only monitor steering wheel use. On average, the percent of time drivers were engaged was approximately five times greater for direct systems compared with indirect systems.

The U.S. government’s annual safety ratings of cars may soon give them credit for having driver-assistance systems, the latest indication that the once-futuristic technology is becoming mainstream. DOT proposed on Thursday that lane-keeping support, automatic emergency braking, blind spot detection and blind spot intervention be incorporated into its Five-Star Safety Ratings program for new cars.

ADAS Features

While there is not industrywide agreement on the nomenclature and features composing ADAS, there is general agreement that ADAS today may include any or all of the following 16 safety features:

●   Reverse Camera

●   Rear Collision Warning

●   Rear Collision Mitigation

●   Adaptive Cruise Control

●   Automatic Emergency Braking (AEB) or Collision Avoidance

●   Brake Assistance (sensors determine when driver is making emergency stop and applies full    

braking force)

●   Blind Spot Warning

●   Blind Spot Mitigation

●   Lane Departure Warning/Lane Keeping Assistant (LKA)

●   Lane Departure Mitigation

●   Cross Traffic Warning (blind spot alert using long range radar)

●   Forward Collision Warning

●   Forward Collision Mitigation

●   Pedestrian Detection 

●   Adaptive Headlights

●   Driver Monitoring

ADAS Impact on Claims Frequency and Severity

While there is not yet enough data to forecast the long-term impact of ADAS on accident frequency, existing data and opinion indicate that overall accident frequency is likely to decrease as ADAS features proliferate, but the nature of accidents will shift until all vehicles are similarly equipped. (Currently, for instance, there is an increase in the percentage of front-rear collisions as Automatic Emergency Braking and Collision Avoidance technology reacts more quickly than do the drivers of unequipped vehicles). Offsetting this decrease in accident frequency is the sharply increasing severity of accidents due to the higher costs of ADAS technology replacement and the necessary associated repair procedures required.        

By 2030, 75%, or 211 million vehicles, of the 281 million cars registered in the U.S. are anticipated to have some number of ADAS features.

Compared with similar vehicles without any core ADAS features, vehicles with at least one core ADAS feature resulted in:

  • 1% lower Bodily Injury claim severity
  • 1% lower Property Damage claims severity
  • 4% lower Property Damage claim severity

(Source: LexisNexis Risk Solutions, November 2021)

COVID and the Great Reset

COVID Cuts Into Collision Repair Production 

The lack of production based on technician shortage has been real since the beginning of COVID. This is due to not only COVID but is also based on changing cultural work norms and mores reflecting less interest in being a repair technician. Fewer available techs = less production = more time to repair = fewer cars being repaired = less collision repair revenue produced = lower paint sales for suppliers and distributors. 

A half-dozen collision repair companies in different regions of the country that were contacted last week all reported having staff out during the first half of January with COVID-19. A seven-location MSO in the Northeast reported having as many as 15 people home sick at the same time. A shop in the Midwest had 10 of its 16 employees on sick leave.

“This is the worst we’ve seen it since the pandemic began,” a West Coast shop owner said. “Customers and even most insurers have been pretty understanding about the delays, but customers are back to asking a lot more about how we’re cleaning their vehicle before they pick it up – more like they were doing the first few months of the pandemic. One lady paid us to deliver her car and park it in her garage with all the windows open, saying she’d look it over the next day.”

Post-Pandemic: What Stays, What Reverts?

The global pandemic had a broad range of impacts, many of which were expected, a few of which were totally unexpected and some of which continue and are likely to leave the world permanently changed.

Driving Behavior and Deaths 

Initially, pandemic lockdowns and work-from-home (WFH) models took the majority of private passenger vehicles off the roads, almost instantly cutting car accidents and repair volumes, and caused most auto insurers to reduce/refund auto premiums in one way or another. A noticeable uptick in usage-based insurance program adoption quickly followed, reflecting consumers’ interest in more closely matching auto premiums to the new realities of risk. It remains to be seen whether this adoption will continue once the pandemic recedes. 

Touchless Everything

Out of consumer concerns about infection, touchless everything became pervasive, and digital claims solutions, including auto photo accident claim self-service, absolutely spiked. As COVID fears began to recede in late 2021 and into 2022, miles driven returned to almost pre-pandemic levels, as did accident frequency, but the average severity of each accident and repair has increased due to higher speeds on more open roads, which drivers became used to, and the higher cost of onboard technologies. 

Crashes — and deaths — began surging in the summer of 2020, surprising traffic experts, who had hoped that relatively empty roads would cause accidents to decline. Instead, an increase in aggressive driving more than made up for the decline in driving. And crashes continued to increase when people returned to the roads.

Now, the U.S. is enduring its most severe increase in traffic deaths since the 1940s. Deaths from vehicle crashes have generally been falling since the late 1960s, thanks to vehicle improvements, lower speed limits and declines in drunken driving, among other factors. By 2019, the annual death rate from crashes was near its lowest level since cars became a mass item in the 1920s. But then came the COVID-19 pandemic.

And virtual claims inspection continues to gain traction as the preferred method of inspection (MOI) for insurance claims of many kinds, led by personal lines auto, with personal property close behind. There appears to be no going back to historical levels of staff or independent appraisal methods. 

Work From Home and the Great Resignation

Many of us initially assumed that working from home would be temporary and that a return to pre-pandemic working models was only a matter of time. We now know that to be wrong. A majority of the workforce, if given the choice, would now prefer some form of WFH, either hybrid or complete, to a full-time return to the workplace.

A lack of work-life balance and declining job satisfaction are among the greatest factors contributing to mass employee departures, referred to as the Great Resignation. Owing to the trend of working from home, the lines between work and leisure often get blurred, making professionals work beyond their dedicated hours. Working remotely for almost two years has gotten many employees used to the new trend. Some employees will inevitably quit their existing jobs and search for new opportunities if their employers leave them with no option but to work on-premise.

Recent research reveals that: 

  • The recent rise of COVID-19 cases resulted in 71% of respondents’ companies delaying plans to return to the workplace or reverting to remote/hybrid work.
  • 30% were back in the workplace and reverted to remote/hybrid work.
  • 41% rescheduled or canceled plans to return.
  • Nearly half (48%) have not determined a date to return to the physical workplace.

Auto Claims, Current State of Collision Repair and Projections Through 2030

Within the collision repair industry, 2019 was the pinnacle for opportunity and success. Repair facilities were flush with repairable vehicles, and the relevant total addressable market (TAM) reached its historical high of $38.3 billion.  

Then with very little warning, in March 2020, the scourge of the COVID-19 pandemic emerged and persisted through 2020, 2021 and, while the spread of the omicron variant seems to be slowing, through the beginning of 2022. 2020 will forever be seen as a year of significant disruption and structural change with far-reaching economic, social and political implications.

It clearly has not been a short-term experience. Following are some of the 2020-2021 collision repair industry’s confluences of trends and constructs affecting the entire auto physical damage ecosystem. 

  • Consolidation remained well underway and was intensified by the numerous private equity investors and their MSO buyers. M&A activity remained extremely active in 2020 and throughout 2021, continuing within the collision repair segment and throughout the broader auto physical damage landscape, including the many segments within its orbit:  insurance, parts, technology, dealers, glass and paint, body and equipment, etc.
  • We estimate that 2020 repairable claims were down around 22% nationally when compared with 2019. We have seen some recovery in 2021 and estimate the year to end up 10% to 13%, with repairable claims reaching 2019 levels by late 2022 to early 2023, barring some external events like COVID continuation.
  • Technician labor and skill shortages continue to hurt revenue and production opportunities while increasing costs.
  • Increasing parts costs, coupled with sourcing and delivery delays, are adding to the increase in total repair cycle time.  
  • Digital transformation of the repair process, well underway in 2019, was aggressively stepped up in 2020 by the insurance industry and supported by technology and information services companies. The virtual repair process model was becoming ubiquitous through the use of self-service photo estimating, artificial intelligence, AI and human intervention as a way to co-manage estimating vehicle damage. This model morphed into an auto-generated image capture of vehicle damage supported by adjuster exception-based estimating. Video estimating supported by AI, machine learning and computer vision, is inevitable and has already surfaced within many areas of claims processing. 
  • A gap continues to exist between insurers and OEMs regarding the OEM vehicle repair standard and its growing adoption and implementation and how to balance and resolve keeping the repairer out of the middle regarding repair procedures completed and payment for same. Despite the insurer/OEM repair standard gap, forward-thinking repairers took the opportunity to diversify their businesses by leaning into their relationships with OEMs through participating in OEM certification programs.
  • As of November 2021, year-over-year inflation was at 6.1% and growing. Inflation jumped to 7.5% in January 2022. 
  • According to Enterprise Holdings, the average length of rental is now just over 17 days, an increase of 3.9 days from the fourth quarter one year earlier. 
  • Despite improvement in front-end claims repair process reduction, primarily due to a decrease in cycle time at first notice of loss (FNOL) assisted by telematics and AI, the middle to back-end of the repair process has been increasing due to many of the constructs mentioned above.
  • We expect vehicle repair costs to rise moderately, but steadily, in the future due to several factors:
    • A shortage of qualified and dedicated technicians, which is fueling the need for increasingly competitive employee acquisition and retention compensation programs.
    • Increased vehicle repair complexity and embedded ADAS technology.
    • Expense of participating in OEM certification programs, including training, equipment and tools.  
    • Increased use of OEM parts and additional line-item repairs due to OEM certification program participation requirements and growing acceptance of OEM repair standards.
    • Growing long-term risk of existing and proposed country-of-origin tariffs raising the cost of automobiles manufactured outside the U.S.
    • Short to medium-term Inflation. 

Most repairers remained open during the pandemic. With business down 50% to 60% in the early days, repairers cut costs, accepted PPP money from the government and furloughed personnel. In some cases, repairers shuttered their businesses for a time, ultimately reopening with limited work. Many of these locations are single, mom-and-pop-style shops that will struggle to make the types of investments needed as cars become more sophisticated. This scenario means that more and more work will continue to shift to larger, more sophisticated operations with brand-specific training and certifications. 

The disruption caused by the pandemic will accelerate change in ways that make it difficult to find clarity around both near- and long-term effects. The expected and unintended consequences of the pandemic will accelerate what we have profiled previously as the dynamic and interactive confluence of prevailing trends and conditions throughout the broader auto physical damage ecosystem.

We expect to emerge from 2021 with stronger nascent and legacy businesses that were well-capitalized pre-COVID-19 and with emerging disrupters that happen to be at the right place and time with new solutions within the broader aftermarket.

The pandemic caused a dramatic decrease in vehicle repairs and total losses from the 2019 total of 15.7 million to 12.4 million in 2020. 2021 saw a partial return to pre-pandemic levels, with 13.9 million vehicles repaired. However, our projections (see figure below) indicate that the industry is unlikely to ever return to 2019 levels as ADAS features continue to penetrate the population of registered vehicles and significantly reduce collisions. There may be some short-term anomalies in repair volume in early 2022 as the industry works to clear its record backlog as labor and parts shortages ease.  

The average repair severity stood at $3,527 at June 30, 2021, up 6% compared with $3,327 for the prior 12-month period . 

As shown in the chart below, the number of insurance and consumer paid repairable and total loss vehicles dropped precipitously in 2020, partially recovered over 2021 and 2022, but are unlikely to ever return to 2019 levels. The forecasted decrease between the 15.7 million repairs in 2019 and the 14 million repairs in 2030 is 12%.  
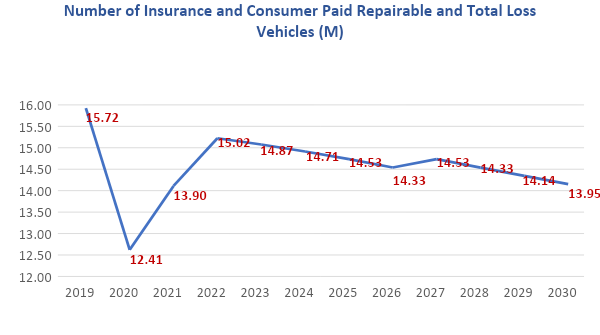
Source: Romans Group and Insurance Solutions Group extensive market research informed by our understanding of the facts and trends related to ADAS adoption and its impact on repairable vehicles

See also: Insurance 2030: Implications for Today

Future View

There is no doubt that EVs (electric vehicles) and AVs (autonomous vehicles) will displace gas-powered cars – that transition has already begun. General Motors and Ford have vowed to phase out internal combustion engine (ICE) vehicles – GM by 2035 and Ford by 2030 — and some states will also ban gas-powered vehicles by 2035. Joint ventures between OEMs will also continue, such as those between BMW and Toyota on the Supra and Subaru and Toyota on an SUV. In fact, Ford just announced that it is splitting into two distinct business segments – Ford Blue managing legacy internal combustion engine (ICE) vehicles and Ford Model E for electric vehicles (EVs).

In addition, there is a related transformation emerging that will transform the future of the auto ecosystem – the new OEM strategy around the connected or software-defined vehicle (SDV), a term that describes a vehicle whose features and functions are primarily enabled through software, a result of the transformation of the automobile from a product that is mainly hardware-based to a software-centric electronic device on wheels. The implications are enormous and far-reaching. Current plans call for OEMs to earn subscription fee revenues in the tens of billions of dollars by 2030 for a wide range of travel, safety and entertainment products and services such as insurance, premium ADAS features and tailored brand and vehicle experiences that include family activities, off-roading adventures and performance-oriented outings.

The questions now are at what rate should we expect these changes and what will they mean to the many players, large and small, across the broad automotive ecosystem?

Let’s start here with five major short-term trends identified by CCC Intelligent Solutions:

  1. The changing work landscape and its continued impact on auto sales, traffic volumes and accident severity
  2. The growth of ADAS and connected-vehicle technologies
  3. Climate change and its emergence as a significant factor in the future of insurance risk and regulations
  4. New customer expectations in our on-demand, need-it-now world
  5. A carry-over from 2021: Increasing complexity given all these factors continuing to disrupt the status quo

Technology and the Future of Collision Repair: EVs, AVs, SDVs and Computer Vision

One major industry that will continue to be heavily affected by the proliferation of EVs, AVs and SDVs is the collision and mechanical repair industry. The EV market share in the U.S. at Dec. 30, 2021, was only 3.5%, but EVs may account for up to 40% of new car sales by 2030. One industry expert predicts that dealer service volume will decline by 35% while tire replacement, glass and visibility services and length of ownership will all increase with EVs. Until autonomous vehicles are widely in use by consumers, there will be many AV fleets, robotaxis, delivery and commercial trucks and trains, especially in and near urban areas. 

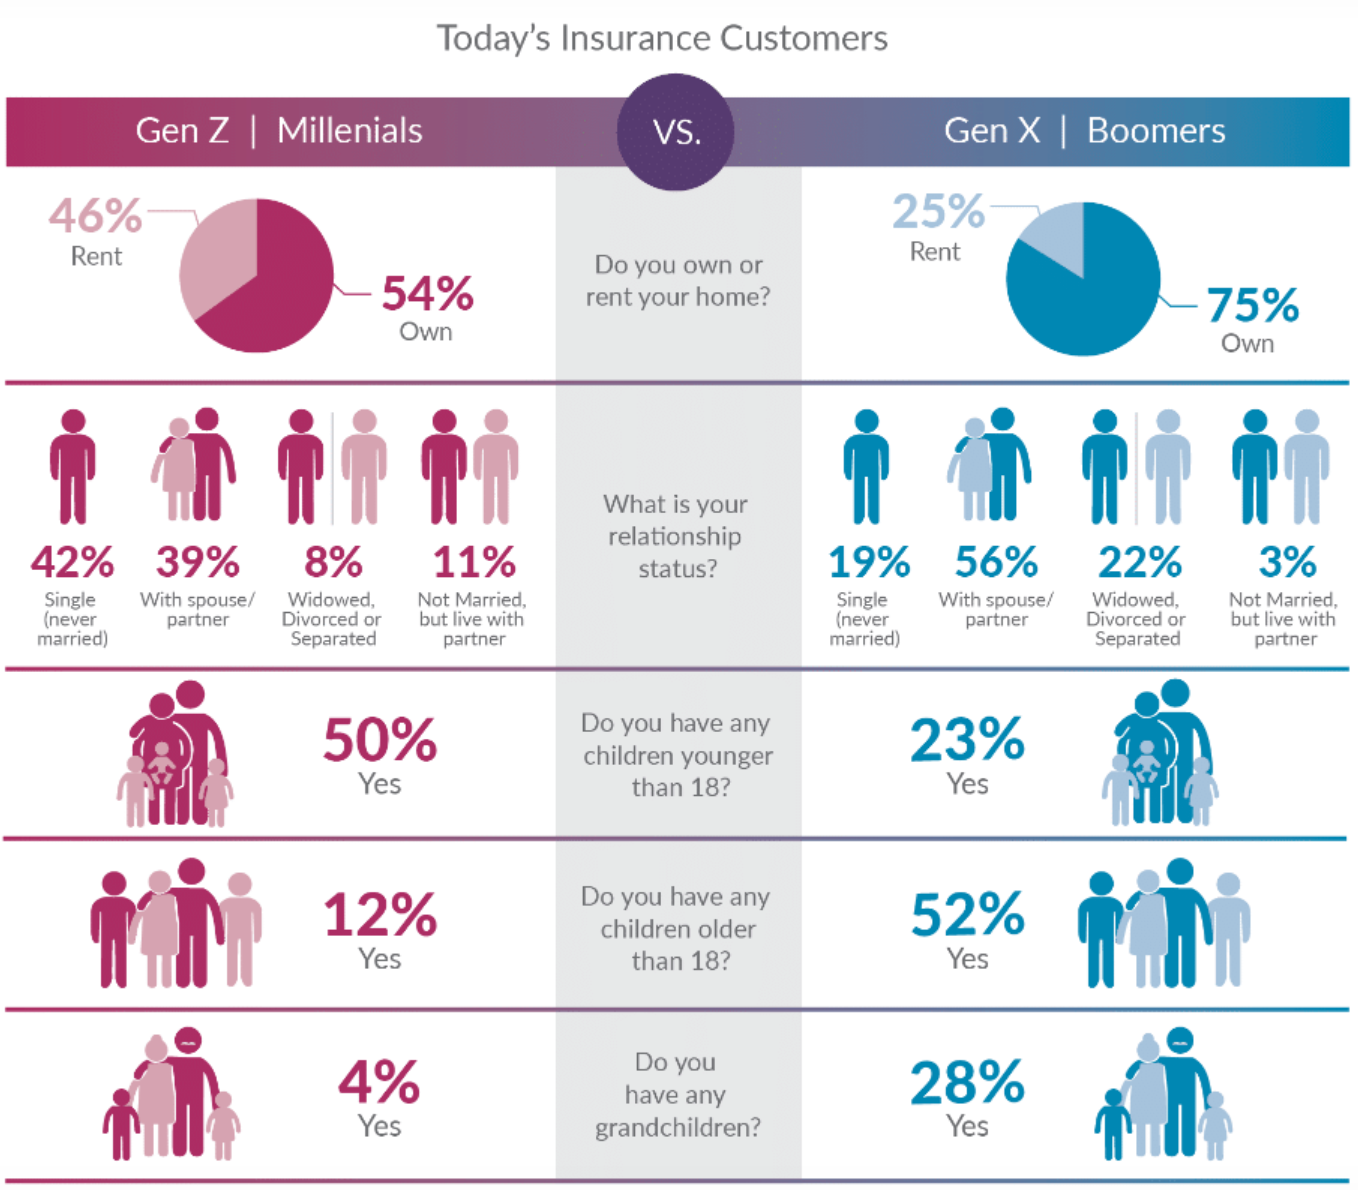
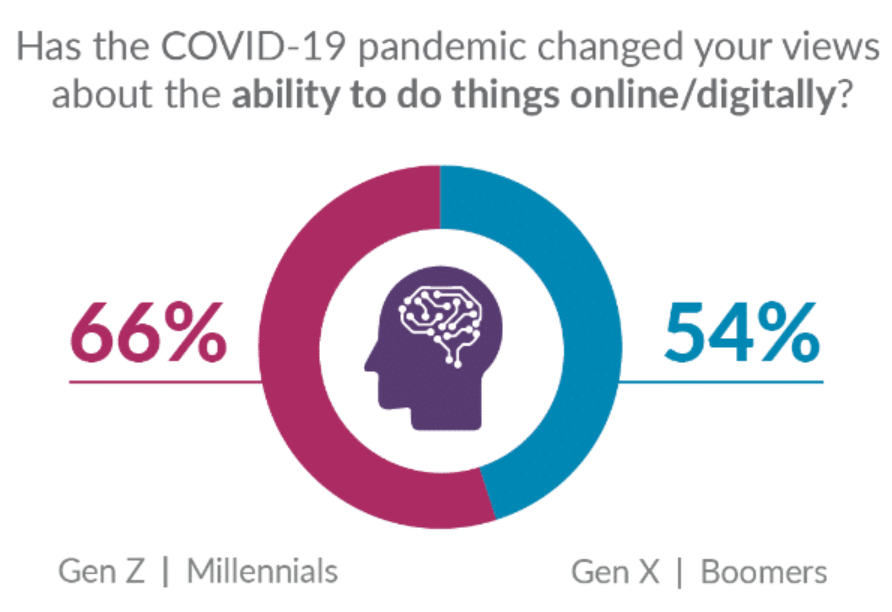
OEMs are catering to Millennial and Gen Z consumers who expect online and app connectivity. And shops need to have an online presence to reach them because both generations look online for everything, including where to take their cars for repairs. OEM-certified repair networks will exert growing influence over repair procedures and referrals. 

Collision repairers will need to pivot from traditional body repair work to become more like computer technicians. New and different skills will be required, and the industry may begin to seem more appealing to young people as compensation rates increase. Specialized training programs will emerge to serve this new profession. Vehicle repair costs could double between now and 2030. One industry expert predicts that in five years the average repair order will be $6,000 to $7,000 due to the increase in parts and technician costs as repair complexity continues. The collision repair industry of the future will need EV charging stations and dedicated work areas or separate locations to repair EVs. 

OEMs and the Connected Vehicle Economy

Self-driving vehicle companies from Tesla to General Motors’ Cruise are racing to start making money with their technology, outrunning efforts by regulators and Congress to write rules of the road for robot-driven vehicles. This month, Cruise said that SoftBank Group will invest another $1.35 billion in anticipation of Cruise launching commercial robotaxi operations. Cruise is opening up its driverless robo taxi service to the public in San Francisco as it creeps toward commercialization.

OEMs will continue to push to certify collision repair shops, which means that the repair work must be done to each OEM’s recommended repair guidelines for shops to be part of these certified networks, receive repair referrals and maintain vehicle warranty provisions. This will likely increase the average cost of repair to auto insurers, putting upward pressure on auto premiums. It will also likely disrupt the multibillion-dollar aftermarket parts and distribution markets as more OEM parts are sold to certified repair shops. More auto insurer-OEM partnerships are likely to emerge out of economic pragmatism, especially as the capability to automatically generate real-time crash notifications and triage accident and repair management improes. Fifth-generation (5G) cellular network will enable this era of more reliable connectivity that facilitates faster data throughput rates and greater network capacities, while ultra-low latency ensures fast response times between senders and receivers.

Telematics will eventually connect everything to the vehicle, the urban infrastructure, homes and other property.

One regulatory movement that could impede or slow these developments is the “right to repair” legislation that is rapidly emerging at federal and state levels. These rights are positioned as giving consumers choice, the right to their vehicle’s data and safeguarding a free and fair repair market. Most notably among these proposals is the “Right to Equitable and Professional Auto Industry Repair Act” introduced by U.S. Rep. Bobby Rush (D-Ill.)      

Summary

If we’ve learned anything from COVID, it’s that the future is not easy to predict or certain to unfold based on existing trends. However, we are confident that barring another “black swan” event in the next decade, the automotive ecosystem of 2030-2035 will be virtually unrecognizable from today. Some legacy market leaders will lose ground and disappear. New market entrants possessing truly transformative technology and business models will rise. New and unprecedented inter-industry partnerships and alliances will emerge. And, above all, evolving consumer preferences and choices will dictate almost all of the change.
Vincent Romans

Profile picture for user VincentRomans

Vincent Romans

Vincent Romans is the founding principal and managing partner of The Romans Group, which was established in 1996 and which leverages four decades of business operator and consulting experience with domestic and global enterprises.

The Romans Group provides business, market, financial and strategic development advisory services to the collision repair, property and casualty auto insurance and the auto physical damage aftermarket ecosystem.

He is a frequent speaker, moderator, panelist and writer on the dynamic and evolving marketplace and industry trends affecting the collision repair, property and casualty auto insurance and numerous other adjacent segments involving the auto physical damage supply chain. 


Stephen Applebaum

Profile picture for user StephenApplebaum

Stephen Applebaum

Stephen Applebaum, managing partner, Insurance Solutions Group, is a subject matter expert and thought leader providing consulting, advisory, research and strategic M&A services to participants across the entire North American property/casualty insurance ecosystem.

The Buzzword of 2022 Is... PDAAS?

The forward-thinking approach in the P&C market is to provide the required property data as a service (PDaaS) to carriers.

words

Despite its status as representing around one third of the insurance industry, with $1.6 trillion in annual premiums, the U.S. property and casualty sector still depends too much on manual intervention to keep up with constantly evolving customer requirements. This high reliance on manual intervention in the form of inspection agents taking charge of property assessments leads to increased personnel costs and high turnaround time. 

Property and casualty insurance companies can now benefit from risk models that analyze huge and diverse data sets. And new data source influencers are emerging in the insurance industry, to provide the most comprehensive and accurate assessment of a property and bring about the end of an era for traditional assessment methods.

Insurers will thrive by partnering with technology companies that have demonstrated expertise in the property attributes and are continuously evolving. Insurers will be better able to identify and add attributes that improve underwriting and claim handling. Insurers will also have access to data solutions that reduce manual tasks and streamline workflow for new business. 

The forward-thinking approach in the P&C market is to provide the required property data as a service (PDaaS) to carriers, removing the burden of gathering property images and extracting all the risk attributes from those images. The accuracy of attributes, determined based on multiple images and a 3D view of the property, is only one highlight of PDaaS’ unique proposition.

See also: Lemonade: No Sign of Disruption Yet

Knowledge is power

Progressive-thinking property insurers across the globe are competing to take advantage of upgrades in camera technology and the surge in imagery captured by drones and satellites. This advancement, combined with cutting-edge research in artificial intelligence algorithms, has opened avenues for property insurers to leverage image analytics to property underwriting and claim handling.

Where PDaaS corners the market

The growing list of customers using PDaaS appreciate that it can handle entire updated datasets every six months or a year. For example, any roof damage in the form of missing shingles or presence of tarp on the roof can be noticed via updates. As PDaaS platforms are continuously evolving, operators are adding attributes not available from other providers of property data.

PDaaS allows carries to integrate the data in mass volume workflows (such as pre-fill forms and fast online quotes). PDaaS provides extensive multi-sourced and AI-driven property data sets, allowing property insurance underwriters and claim handlers to undertake thorough, reliable risk assessments. What’s not to like?


Upendra Belhe

Profile picture for user UpendraBelhe

Upendra Belhe

Dr. Upendra Belhe is president of Belhe Analytics Advisory.

With over 30 years of experience in the P&C insurance sector, Dr. Belhe has held senior leadership roles in global insurance organizations. Dr. Belhe now collaborates with insurers, insurtech firms, and investors to develop and implement analytics strategies.

4 Strategies as Customer Behavior Changes

In dynamic conditions like today's, strengthening existing relationships, elongating the customer lifecycle and focusing on the right prospects are all-important.

waves

Since the start of the pandemic two years ago, consumers' online insurance shopping has become increasingly active and sustained.

Here are a few highlights from Jornaya’s network of thousands of comparison shopping sites that attract millions of consumers every year:

  • Auto insurance comparison shopping increased 49% from 2019 to 2020 and was up 16% from 2020 to 2021
  • Home insurance comparison shopping increased 43% from 2019 to 2020 and shrunk 8% from 2020 to 2021
  • Life insurance comparison shopping grew 45% from 2019 to 2020 and sat almost flat from 2020 to 2021 (-1%)
  • Health insurance comparison shopping sustained consistently healthy growth throughout, with 16% and 11% increases in 2020 and 2021, respectively

However, in recent months, insurance providers have noticed a decrease in online shopping volume across auto, home and life insurance. The year-over-year comparisons, when focused on Q4 2021, paint a very different picture.

Auto insurance comparison shopping in Q4 2021 was up 5% year over year, a stark slowdown from the double-digit percentage growth in prior quarters. Year-over-year shopping growth was flat in January. Carriers' profitability surpluses are shrinking, as claims severity continues to be high, and claims frequency is on the rise as drivers return to the road. Premiums need to catch up to risk.

In late 2021, home insurance shopping levels fell 22% year over year. Home insurance shopping was down 23% in January 2022 from January 2021.

See also: Tips for the Hybrid Work World

Life insurance comparison shopping in Q4 2021 was off more than 31% from the high-water mark the market reached in Q4 2020. Shopping volumes in January were half of what they were a year ago (the most shopping Jornaya witnessed in years). While insurance providers accelerated their digital transformation efforts to meet heightened consumer interest in life insurance, demand may prove fickle over the long term as consumers become more desensitized to the risks posed by COVID-19. Call center shortages and broad staffing woes may have also hindered insurance providers’ ability to capitalize on remaining opportunities, shrinking the need for performance marketers to drive traffic to their life insurance websites.

Health insurance comparison shopping was down 4% from Q4 2020’s volume, though, with this year’s extensions to open enrollment, it may be due more to a spreading of volume over a longer time than an actual decrease. Shopping grew 3% YoY in January.

Across every line of business, the online shopping explosion of the past two years may finally be tapering, exacerbated by a drop in demand for new business leads while carriers increase rates to address profitability concerns and improve loss ratios.

Particularly in auto insurance, gaining new customers has become less profitable, especially with price-sensitive consumers more likely to leave before their first or second renewal period. Given these challenges, carriers must be thoughtful about the types of consumers they want to target. 

How do insurance marketers make the most of the current landscape?

In dynamic conditions like this, where insurers and agents need to pick their spots, strengthening existing relationships, elongating the customer lifecycle and focusing on the right prospects are all important. Here are four strategies to help marketers advance efforts: 

1. Invest in your existing database to learn about the customers you have and the customers you want 

Insurance companies already own or have access to vast amounts of data, but often it’s not well-structured and is siloed within groups or divisions with limited data sharing. 

Insurers can and must break down these barriers to better understand how customers enter, engage with and leave the business. This is critical to being able to identify opportunity and risk at scale.

Capturing, organizing, then deploying this data helps companies offer highly personalized customer interactions built on knowledge, whether through well-timed emails or phone calls to prospects or being alerted when existing customers are in-market. Marketers can anticipate customer needs, all while keeping privacy in mind and respecting consumer boundaries.

2. Implement a strategy that balances profitability and volume 

In the current market, it is vital to build a marketing strategy that considers the right mix of volume and profitability. Be cautious of a strategy that focuses purely on good profitable risks, as this won't generate enough volume to meet sales goals. 

Conversely, a strategy that focuses too much on active shoppers with a “come one, come all” approach will worsen existing profitability problems.

The ideal book of business is made up of both transactional business and good risk that can be written on a long-term basis.

3. Know which households to target; use data to understand customer needs

Data and technology have advanced to the point that insurance marketers no longer need to build customer “personas” or look-alike profiles of ideal customers. Today’s leading companies know, down to the household level, which consumers they want to write and their behavior. Data removes the guesswork. Take time to understand the households you want to write.

Once customer targeting is established, with the organization behind it, data can be used to dictate personalized outreach. In today’s highly competitive online insurance market, it's not enough to simply know who your customers are; marketers should also know what their customers’ needs are, when those needs are most acute and how to address them consistently. Today, marketers can leverage data to know who, what and when – applying their expertise to accomplish the how is where insurance providers can create unique advantages and differentiation from their competition. 

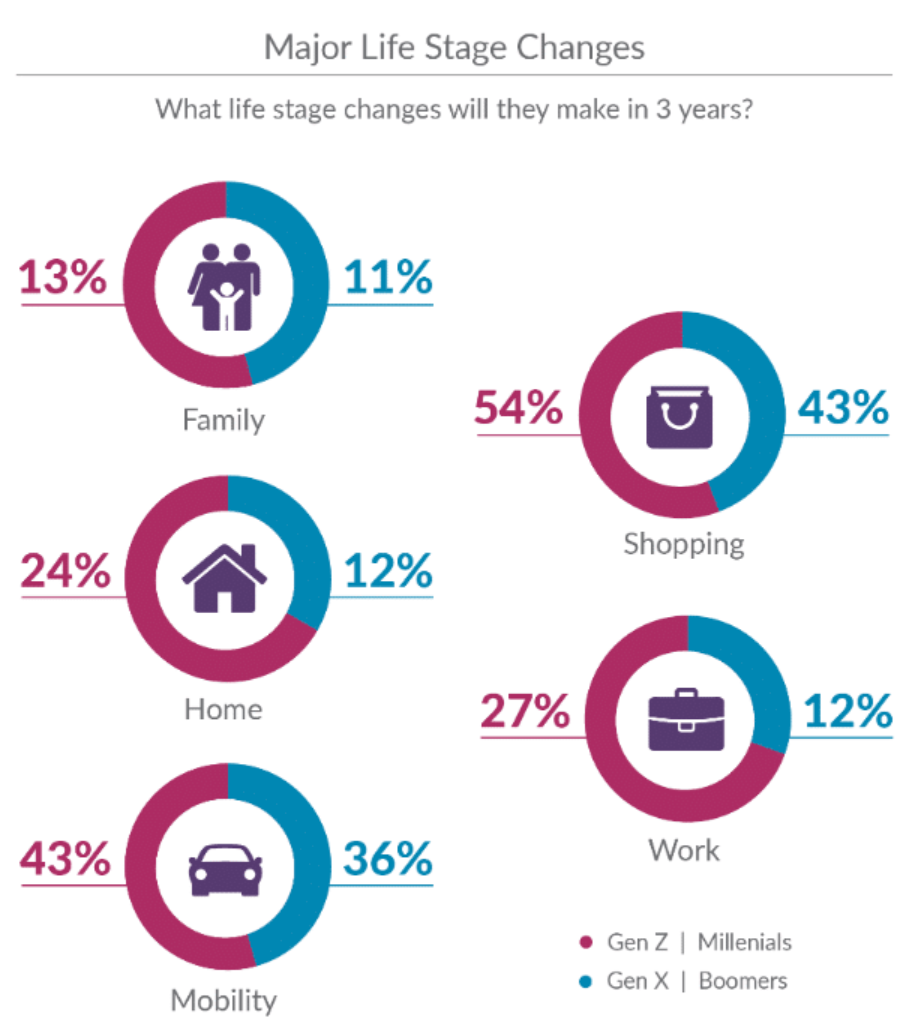
For example, is a new baby coming, has there been a career move, is a family member attending college? Data surrounding these events is widely available to advertisers. Organizing data at the household level then enables insurers to take the next step – knowing what needs are present and when to engage – personalized outreach delivered precisely when customers are in-market and most receptive to an offer. 

4. “Skate where the puck is going to be” — predict future needs 

The best marketers don't just know who they're targeting today — they know what the household may need in 90 days and why, even if the household doesn't know it yet. Robust household data paired with exhibited shopping behaviors can help predict future consumer needs. 

For instance, a consumer who is planning a home purchase may not be thinking about property insurance, but they absolutely will be on a property insurance buying journey soon. A recent Aite-Novarica Group survey found 87% of consumers are interested in receiving personalized recommendations about how to improve their insurance coverage. This type of data-driven head start can be precisely the edge an insurance provider needs to grow the business (or protect it).

While many factors affect the timeline of an insurance shopping journey (and sometimes lead consumers to other purchase journeys), knowing what customers need and being there at the right time to advise is a winning marketing strategy. 

See also: Getting to the Next Level in IT Systems

Bringing it all together

Use data to be choosy about which consumers you interact with, how you engage them and when. There is little benefit in acquiring customers who buy quickly and leave quickly. Conversely, there is risk in spending all of your time and resources on a historically profitable segment of consumer that is becoming increasingly comfortable with shopping and switching their insurance. Despite recent tapering in shopping frequency, comparison shopping is still above 2019 levels.

In today’s market, insurance providers must feel comfortable with the pace of shopping and strike a balance between hunting good risks and seizing the active shoppers to meet sales goals. 

Insurance carriers can capitalize on a changing profitability market by embracing technologies and digital tools that support our industry’s original mission – to help consumers make the best insurance decisions and provide peace of mind.

At Jornaya, a Verisk business, we work with insurance providers who leverage our view into daily comparison shopping behavior to acquire, retain and grow their customer base quickly, safely and confidently. 

Six Things: March 8th, 2022

Red Alert for Cyber Attacks. Plus, OCR plus AI opens new vistas; a low-tech approach to work automation; 4 P&C mega risks in 2022; and more.

six things header


Red Alert for Cyber Attacks

Paul Carroll, Editor-in-Chief of ITL

With Vladimir Putin denied the quick victory he hoped to achieve with his invasion of Ukraine, the Russian military is reevaluating its strategy -- which may now include cyber attacks that could broaden far beyond those that the Russians have been waging against Ukraine for months.

Obviously, no one knows for sure what Putin will do next. But Russia has a history of hacking, even against major powers. According to the Mueller report, Russian government hackers stole emails from the Democratic National Committee in 2016 as part of Putin's effort to help elect Donald Trump president. In 2021, a gang of Russian hackers launched a ransomware attack that shut down the Colonial Pipeline and cut off its supplies of gasoline in the U.S. East and Southeast. And Putin has said that even nuclear weapons are on the table if other countries intervene in his war on Ukraine, while listing 13 countries that have been "unfriendly" to Russia, so it's hard to imagine that cyber warfare isn't somewhere in the cards.

Insurers would do well to prepare themselves and their clients for the possibility of cyber attacks, to the fullest extent possible.

continue reading >

New Majesco Research

Check out Majesco's new research which underscores the need for insurers who seek relevance and growth in the SMB market to provide new risk products, value-added services, and customer experiences...digitally.

Download Now


SIX THINGS


Ukraine: How Exposed Are Insurers?
by Michel Leonard

New political risk insurance losses in Ukraine due to Russia's invasion will likely be material but well within the ability of private carriers to perform on their obligations.

Read More

OCR Plus AI Opens New Vistas
by Michael de Waal

AI-powered optical character recognition lets insurers unlock vast troves of data and streamline all processes.

Read More

How IT Savings Can Fund Innovation

Sponsored by Rimini Street

While IT infrastructure is a business necessity, aging IT systems can inflate expenses and limit the ability to spend on initiatives that will really move the needle for a business. In this webinar, we discuss how insurers can optimize their data centers and generate savings that can fund innovation, while improving security.

Read More


A Low-Tech Approach to Work Automation
by Tom Bobrowski

Work automation is not about technology. It’s about process. A process that is best led by the line of business or function head and not corporate IT.

Read More

Balance of Information Between Insurers, Consumers
by Frank Schmid

Insurers are already familiar with adverse selection. Now, they are getting to grips with the new concept of inverse selection that arises with big data.

Read More

4 P&C Mega Risks in 2022
by Mike Chapman

These risks are moving the insurance market away from transactional coverage and more toward co-management of risk. 

Read More

Tips for the Hybrid Work World
by Kevin Knopf

The following are important ways to reduce corporate risk and support employees in both remote and on-site environments. 

Read More

Use Halo & AI For Claims Processing to Proactively Identify and Mitigate Emerging Fraud

Sponsored by Daisy Intelligence 

Daisy AI solutions recommend step-by-step implementation of Halo Effects into your fraud detection, claims management and underwriting processes, including useful examples that can be put into practice

Read Now


MORE FROM ITL


March Focus: Life and Health

For an industry that has long been considered sleepy, life insurance has a lot going on. 

The efforts getting the most attention have probably been those related to improving the customer experience, largely by speeding underwriting by reducing or doing away with the need for medical exams and the providing of blood and urine samples. 

But other big changes are afoot, too. .

Read More

The Impact of Rising Inflation and Interest Rates on Insurance Profitability 

Sponsored by Insurance Information Institute 

Paul Carroll, ITL's Editor-in-Chief, and Dr. Michel Leonard, vice president, senior economist and head of the Triple-I’s Economics and Analytics Department, continue their series of webinar discussions by looking at the Triple-I's latest projections for inflation and interest rates and talking about how the insurance industry can prepare.

Read Now


Partner with ITL to create expert thought leadership content.

Custom Content
Promoted Content
Display Advertising
Custom Webinars
Monthly Topic Sponsorships
ITL Partner Packages and more


Learn more and get the 2022 Media Kit


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

New Conclusions for P&C Insurers

The customers want to drive. Are insurers prepared to thrive once we’ve handed them the keys?

growth

The impact of business and consumer trends is sometimes seen more clearly when we link them. For example, if you follow the progression below, you might come to some new conclusions about where and how P&C insurers should be targeting their development strategies.

  • In 2019, personal savings in the U.S. were $1.2 trillion.
  • In 2020, personal savings in the U.S. skyrocketed to $2.3 trillion.
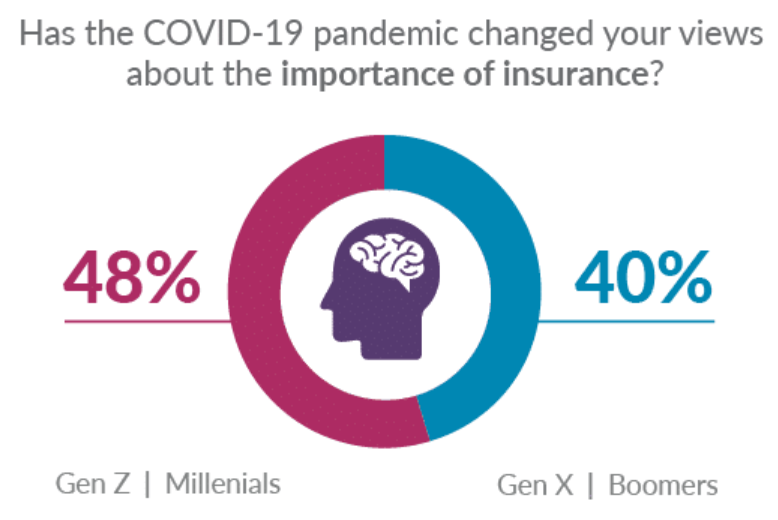
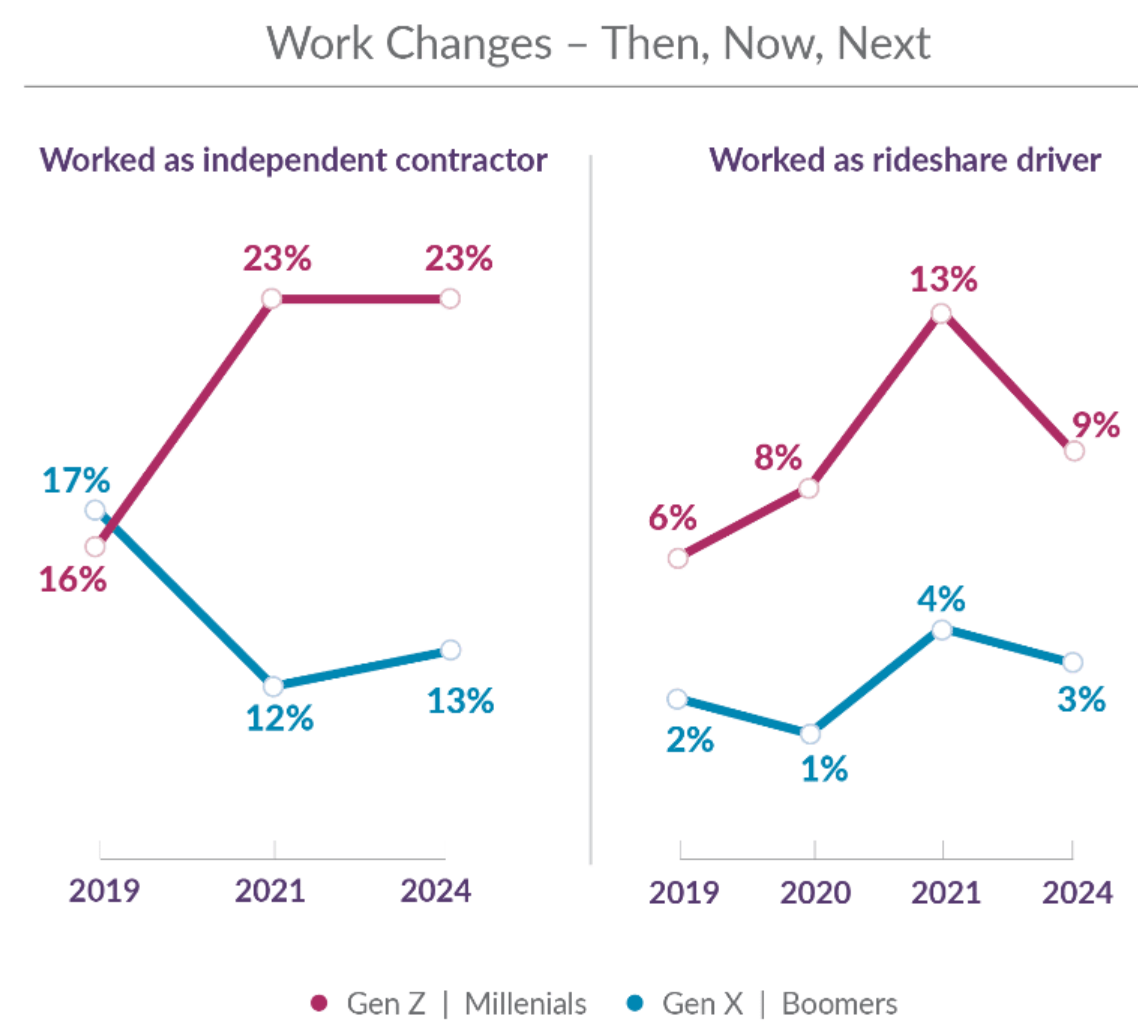
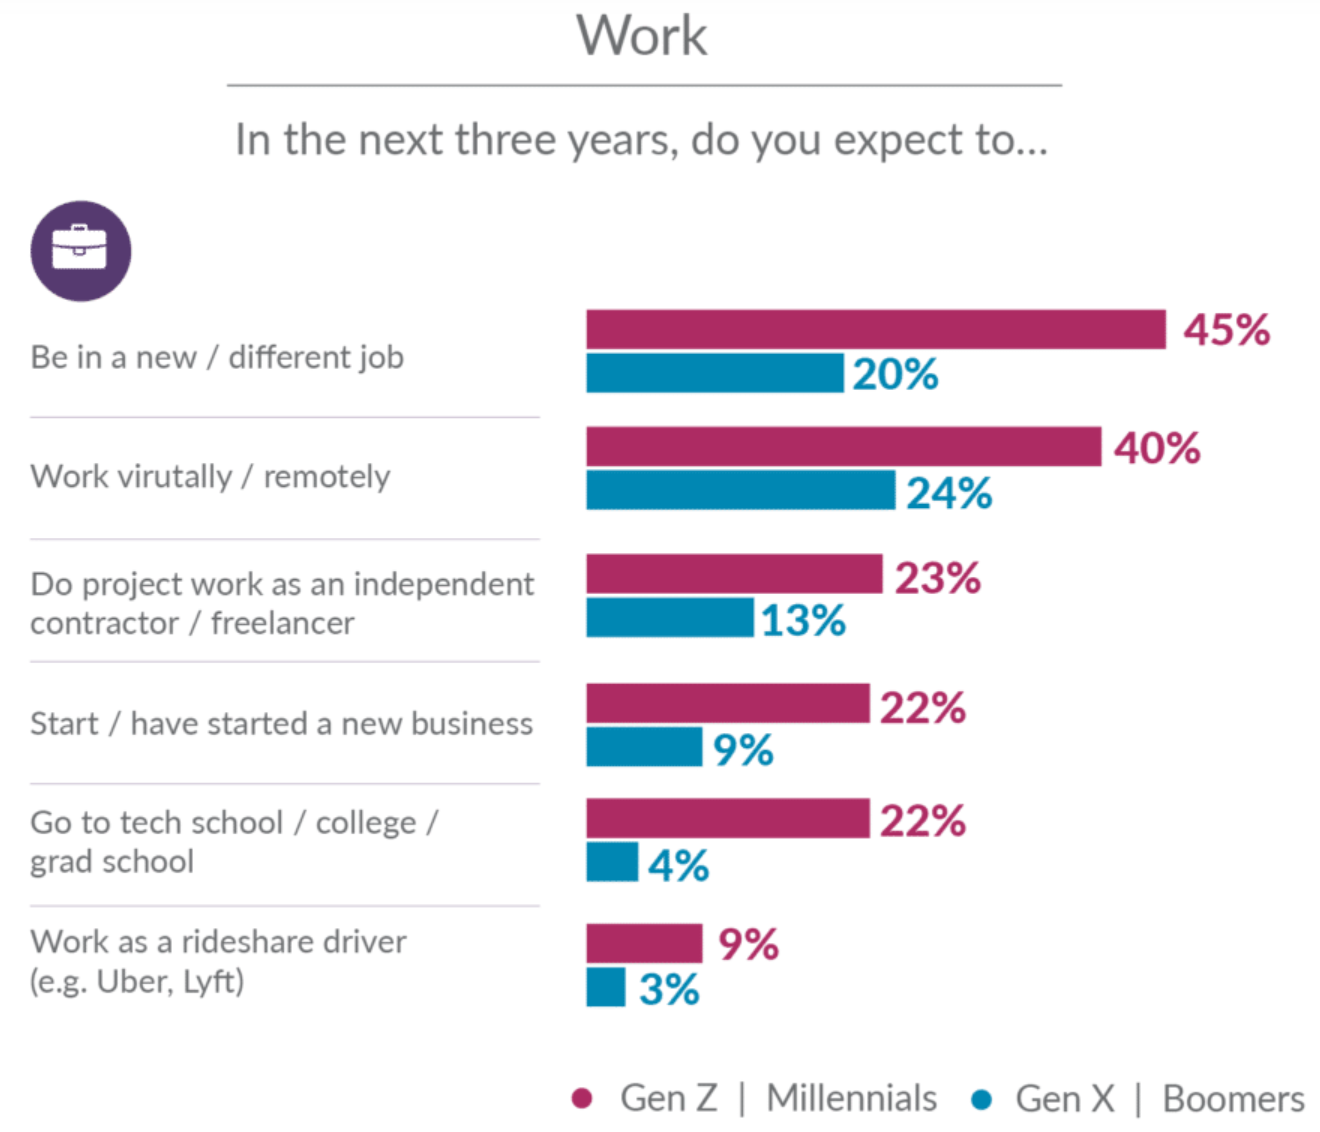
  • Gen Z and Millennials are investing outside of their retirement plans at higher rates than predecessors, but their investment tools of choice are up-and-coming platforms, such as Robinhood.
  • Robinhood holds a 37% market share, over Fidelity (26%) and Acorns (23%).
  • Personal wellness expenditures are on the rise, with individuals looking to improve their health

All of this points to a renewed desire for financial control, self-sufficiency and protection from catastrophic economic impact. At the same time, long-held insurance policies will come under scrutiny by financially conscious customers seeking price and value.

The message is clear. A volatile world has generated scrutiny by individuals and companies. They want to prepare for anything by shielding themselves against loss and doing what it takes to keep the keys to their future in their own hands. The customers want to drive. Are insurers prepared to thrive once we’ve handed them the keys?

Innovating with the customer at the center

Majesco and Capgemini have jointly released a thought-leadership paper, Embracing Innovation and Growth Opportunities in P&C Insurance. We used the paper as the springboard for a discussion on why P&C insurers need to reinvent themselves to fit new market needs. In this blog, we’ll look at how creating an engaging customer experience will invigorate an insurer’s strategy and allow the insurer to capitalize on platform technologies.

Responding to change. Changing to respond.
At a high level, insurers need to accomplish two related goals.

  1. They need to respond to change by shifting from push to pull. They need to transform the insurance product into something that is bought, not sold.
  2. They must improve their speed and agility. They need to transform their operations and technologies to become responsive to market changes and opportunities. The faster they can bring products and channels to market, the more effective they will become at capitalizing on trends.

Shifting from push to pull

In this new insurance era, nearly every process is rapidly becoming frictionless, including buying. If distribution channels are easy to use, with products that are easy to understand, insurers can grow through a friction-free, multi-channel distribution system. According to the World Insurance Report 2021 by Capgemini and Efma, more than 70% of customers expect a seamless multichannel experience for policy research and purchase. The benefit of adapting to these channel dynamics is that we move from needing to sell people on purchasing insurance to introducing insurance that is ready to be bought seamlessly at the point of need, creating a scalable, sustainable business model.

Technology is fueling customer expectations, altering and expanding markets and channels through which insurance is sold, including automotive, transportation businesses and Big Tech. To prompt customers to buy insurance products independently, in addition to identifying customers’ needs and expectations, insurers have to understand and adapt to their behaviors. Customers want to buy where, when, how and from the provider that offers the best fit.

Role rehearsal

Crucial to this is the expansion of partner ecosystems where insurers can assume multiple roles, from the owner of the unifying experience to the orchestrator of the products and services or provider of products and services. This will lead to a transition of the insurance value chain from a monolithic to a modular one, where the industry players will focus on their strengths within a specialized value chain. This can lead to two future scenarios as highlighted by the World InsurTech Report 2021 by Capgemini and Efma – Insurance embedded as a value add within third-party ecosystems or Insurance with added value at the core of the offerings.

What insurers achieve will depend on their ability to enter the market while it is still an uncrowded white space. As early insurers enter these markets, they will be experimenting, succeeding, failing and learning how to best fill their roles in the new insurance landscape. An insurer’s ability to enter now will provide greater long-term value. New revenue streams and access to broader markets will produce a multiplier effect. We are currently seeing this play out in the new affinity and program business models emerging in the market.

Insurers need to rehearse their role by adopting the “cultural persona” of flexibility. Firms with a cultural mindset that insurance must adapt to the customer will overtake competitors that believe policyholders must adapt to insurance.

What insurers will find is their choice of location in the ecosystem, the best pick of available roles and the first crack at innovative products that will change the face of insurance. The future depends on being in the right place at the point of opportunity.

Market moving through speed and agility

Of course, demand for insurance isn’t the only determinant for value. Innovation plays a role. Can insurers anticipate what’s coming and make forward-thinking, market-moving products and services? Can they use customer trends to predict customer needs and voluntarily give customers the keys to buying? It isn’t easy for any organization to gain the momentum it needs for change while the enterprise is in motion.

Industry trendsetters differentiate themselves by first giving up their need for legacy operational traditions that are built into their current business core systems. Instead, trendsetters shift their technological and administrative weight using a two-speed strategy for growth:

  • Speed of operation is for the traditional business model with mature systems and processes needing operational improvements through modernization and optimization using cloud and modern solutions based on application programming interfaces (APIs) that deliver in months vs. years.
  • Speed of innovation is for agile, fast and minimum viable product (MVP) models to explore, test and introduce products – many in 12 weeks or less. This strategy prepares the new business for the future using next-gen native cloud microservices and API-based solutions.

Visionary, inventive leaders see the market, customer segments and technological trends as a gateway to new revenue. Therefore, they are preparing to use new data sources, reach new market segments, offer innovative and appealing products, create exceptional customer experience and leverage new channels.

Leaders execute exceptionally well from Knowing to Planning and then Doing, aligning priorities to strategies and action. When these are not aligned, a Knowing-Doing gap emerges that defines insurers as a Leader, Follower, or Laggard, based on Majesco’s Strategic Priorities research.

Companies that procrastinate put their future at risk. The time for plans, preparation and execution is now – recognizing that the gap is widening and the timeframe to respond is closing. Leaders, as early adopters, are positioned to succeed.

Platforms fit customer-centric engagement and insurer needs for rapid flexibility

Leaders are using an outside-in view with the customers’ needs at the center. This is where platform technology makes a difference. Platforms are underpinning robust business models with network effects that disrupt traditional models, create tremendous customer loyalty and offer significant opportunities for growth. As a result, platforms are fundamentally changing businesses, and insurance is no exception.

The heart of the insurance platform is an orchestration of next-gen technologies, including cloud-native computing, microservices, APIs, new data sources, and artificial intelligence and machine learning, coupled with a vibrant ecosystem of partners that provide innovative or complementary products and services. This unified combination of components enables insurers to shift from owning complex core systems to owning greater technical agility and flexibility, digital fluency, innovation, and the speed to value required to meet today’s pace of change.
Leading firms are partnering to expand reach, adopt new capabilities, access new data and accelerate speed-to market.

  • Collaborating with ecosystem partners and insurtechs enables insurers to cross-sell/upsell and launch innovative products.
  • Carriers that deploy open APIs can reduce service cost, bundle services and strengthen the value proposition.
  • Insurers that collaborate with ecosystem partners keep informed about future product needs.
  • And, they can bolster their digital strategies, adopt new business models and add lucrative revenue streams

The most successful insurance leaders are increasingly adopting leading platform technologies and are innovating at a faster pace. They increasingly see themselves as technology companies providing protection services vs. insurance companies using technology to deliver insurance products.

For a deeper look at the report,  including the six key focus areas that insurance firms can leverage, be sure to download Embracing Innovation and Growth Opportunities in P&C Insurance. And, if you’re curious about all of the benefits you’ll receive through core transformation, you can receive an excellent primer and overview with Majesco’s latest webinar, An Intelligent Core to Transform Your Business.

Seth Rachlin, global insurance industry leader at Capgemini, and Denise Garth, chief strategy officer at Majesco, are co-authors of this article.


Denise Garth

Profile picture for user DeniseGarth

Denise Garth

Denise Garth is senior vice president, strategic marketing, responsible for leading marketing, industry relations and innovation in support of Majesco's client-centric strategy.

Why P&C Must Reinvent Itself Now

While some may consider today's challenges translating to the worst of the times, this is the best of times for innovative-minded P&C companies.

wires

If insurers completely understand the implications of customer trends, competitive pressures and technology leap-frogging, they will be justifiably anxious about their future — unless they prepare.

Drones make an excellent short case for both the threat and the opportunity. If you fly helicopters in Hollywood for filming, or you cover traffic for the evening drive news, or you once flew a fighter in the Air Force, your occupation is in jeopardy due to drone technology. Cinematography isn’t going away. But the method for shooting the video is changing. Drone use for package delivery, powerline examination purposes and even insurance claims research will replace traditional methods with technology-enabled improvements. Those who haven’t adapted will feel threatened. Those who have adapted will feel liberated.

P&C insurers must reinvent themselves. Reinvention begins with an understanding of insurer mindsets. Most insurers still don’t consider themselves to be technology companies. They are risk management companies. But in a hundred different industries, we’re seeing the same shift. Companies that thought they had their niche locked up are finding themselves displaced because of the technology that is linked to their delivery. They need to become tech-flexible, tech-enabled and tech-creative. Technology is still a tool and not the end-game, but it is the thread that makes all insurance scenarios possible and exciting.

Once carriers have awakened to their need for change, most will quickly realize that their efforts are worth it. Every step out of the traditional business model is a step toward organization-enablement and greater profitability. Jump through the hoops, and suddenly the world opens up for rapid innovation and improved competitive positioning. Ask any executive if they would rather have their future dictated to them by technology constraints or if they might prefer instead to write their own success story with creativity as the theme. Innovation will always be “in.”

Recently, Majesco and Capgemini jointly released a thought-leadership paper, Embracing Innovation and Growth Opportunities in P&C Insurance. The paper illustrates the link between industry and market pressure and an insurer’s future ability to fill opportunity gaps. Can insurers capture the right perspective on the forces that are driving them toward change? In this blog, we’ll discuss a few of those pressures in detail, then we’ll touch on strategies that can bridge the distance between knowledge and implementation. 

Pressures, threats and changes — the starting line for insurance innovation and opportunities.

It seems a cliché to say that we are living within a perfect storm of insurance pressure, but the cliché fits. P&C insurance is like a hurricane. The core may look calm, but even it is heading for landfall. The storm is affecting everyone from insurers to reinsurers, brokers and MGAs. Rapidly evolving industry dynamics are offering opportunities for those who can capture the wind. The Majesco/Capgemini report points out five significant areas:

1. Emerging and evolving risk scenarios: Business clients are emerging with new or unknown risks. Existing businesses are moving to digital business models that require updated coverage, such as cyber. Enterprises that use IoT and artificial intelligence need new coverage. Disruptive environmental patterns are intensifying and expanding risks. The pandemic impact on nearly every industry and business is pressuring P&C insurers to rapidly and profitably adapt to new needs, demands and expectations.

2. Increasing competition: Significant growth in managing general agents (MGAs) and program business, and reinsurers that directly bring new products and businesses to market are creating rivalries. Non-traditional players such as automotive, retail and product manufacturers are entering the market. According to the World InsurTech Report 2021 by Capgemini and Efma, more than 50% of customers are willing to purchase coverage from non-traditional players.

3. Expanding customer expectations: Policyholders now seek complete protection, and they conduct independent research to learn what’s available and from which providers. More importantly, they want digital access to their risk products and value-added services on the go and at a faster pace, holistically and conveniently, 24/7. Customers seek peace of mind that their coverage is appropriate, and they are taking preventive measures to protect their assets and avoid claims. Changing customer expectations require P&C insurers to expand and reevaluate old paradigms.

4. New products and business models: Insurtech startups, greenfields launched by existing insurers, reinsurers, MGAs, brokers and other ecosystem players are collaborating and debuting new products and business models that address unmet risk needs, emerging risks such as climate change, new gig and sharing economy risks, new channels with embedded insurance and new product bundles to meet customer needs and expectations.

5. Accelerated technology adoption and landscape showing more opportunities: Explosive growth in new data sources, AI/ML capabilities, cloud platforms with APIs, microservices, ecosystem models and new digital platforms provide unmatched opportunities for insurers to enhance business operations, innovate and redefine their business for the future. While some may consider these challenges translating to the worst of the times, this is the best of times for innovative-minded P&C companies who are ready to embrace opportunities to become the new leaders in the future of insurance. NOW is the time to align business strategy with the new, shifting market needs to execute efficiently.

A strategy to harness the wind

Of course, these pressures are driving everyone. Each organization will make its own decisions on how and when to make the changes that need to be made to stay competitive. Insurers can fight the current, or they can let it push them to recreate themselves. Organizations that wish to lift their sails and let the current and winds carry them on to something new need to understand where this journey is taking them. Even if the organization is planning on using a two-speed approach to their business model, they need to envision how the new model might look. This model will be holistic, encompassing product, services, customer engagement and, of course, processes and technologies that will provide the data and analytics that will assist the insurer and make every moment a learning moment. 

New product strategy

Insurers need to rethink their product strategy and the value proposition by identifying new risk areas and new value-added services and thinking beyond premiums and claims payouts. Insurers should focus on providing comprehensive coverage, coming up with innovative products to cater to new customer segments, exploring new business models such as usage-based insurance and embedded insurance and simplifying their offerings.

For example, Nationwide has launched a comprehensive coverage for customers working from home - providing homeowners or renters insurance, usage-based auto insurance and identification of theft. They saw a need for new insurance package, and they created a hybrid product to fit.

Expanding offerings into value-added services

Insurers must go beyond just the risk product to focus on ensuring a speedier return to normalcy and intervening at the right time for risk prevention and mitigation. Insurers should provide risk advisory and encourage safe behavior, enhancing the customer experience. They can leverage technology to alert customers about loss incidents, thereby preventing losses or reducing their severity. By expanding their role to partner and preventer, insurers can achieve the golden mean between growth, customer-centricity and profitability.

Prevention services are certainly a logical entry point for P&C. International insurance specialist Hiscox partnered with the provider of LeakBot, a smart water leak alarm, to offer policyholders a mobile-app leak detection system. Insurers such as Chubb, Travelers and American Family have partnered with Wildfire Defense Systems for supplemental prevention services for homes and businesses in the case of regional wildfires.

Rethinking customer engagement

An effective customer experience strategy takes an outside-in approach, considering what and how the customer wants to engage – rather than an internal operational view. The customer experience strategy needs data to anticipate possible needs, and insurers must move from transactions to personalized experiences and use a 360° view for the customer whether for buying, servicing, submitting or paying claims and accessing value-added services – making insurance relevant when needed.

New strategies for innovation and new business models to meet the new world of insurance

Next-gen customer experiences that engage and excite customers must take a holistic experience view rather than a transactional view. Significantly changing customer risk management needs and engagement expectations are forcing the insurance industry to move from practices and technologies of the past to new platform-based technologies and business models that will carry them into the future. In our next blog, we’ll discuss that future from the perspective of innovation strategy. What approaches make the most sense in light of financial considerations and traditional businesses that can’t transform overnight?

For a preview of our conversation, be sure to download Embracing Innovation and Growth Opportunities in P&C Insurance and sign up for Majesco’s webinar, An Intelligent Core to Transform Your Business, a conversation focused on property & casualty insurers and their hurdles and needs when looking at new core platforms.

Seth Rachlin, global insurance industry leader at Capgemini, and Denise Garth, chief strategy officer at Majesco, are co-authors of this article.


Denise Garth

Profile picture for user DeniseGarth

Denise Garth

Denise Garth is senior vice president, strategic marketing, responsible for leading marketing, industry relations and innovation in support of Majesco's client-centric strategy.

Distribution Management: A Path to Maturity

Can insurers envision the opportunities clearly enough that they are motivated to switch gears and change something right now, and tomorrow, and the next day?

path

In the 1993 movie Groundhog Day, Bill Murray plays a Pittsburgh broadcaster stuck in a loop, replaying the same day, Feb. 2, over and over. The screenplay, written by Danny Rubin and Harold Ramis, was ingenious in its ability to make us consider what we would change in a day if we had an unlimited number of do-overs. Would we repeat the same mistakes? Would we suffer through irritation at replaying the same scenes again and again? Or would we choose to get better at what we do, adapt to fix the issues around us and maybe even try to improve the lives of others.

Though every day in a distributor’s world is different — different people, different coverages, different issues to solve — current distribution tools and methodologies may look the same way they have looked for years, even when both insurers and distributors know that there is a better way.

Distributors and insurers wake up each day to accomplish their goals within the context of the insurer’s present level of distribution maturity. Every day, both sides see the positives and negatives of processes that could be better. Are they following a path that will take them to real distribution maturity?

It’s an important question because insurers and distributors rely so heavily on one another. What insurers need, in many cases, is an understanding of what will happen tomorrow if they are willing to make some changes today. Can insurers envision the opportunities clearly enough that they are motivated to switch gears and change something right now, and tomorrow, and the next day? What will their efforts mean to courting and keeping the best distributors?

Majesco and PwC recently released a report that examines this very issue; Distribution Management: A Path to Maturity. The report outlines in detail five distinct levels of distribution maturity. What are the inherent characteristics of Level 1? What improves at each level? How does the learning from one level transfer into the business wisdom at the next? Is there a perfect ending?

The end goal is for distribution management transformation to deliver value across three key dimensions:

  • Improve productivity and next-gen distributor experience.
  • Increase operational efficiency and effectiveness.
  • Improve insurer ability to adapt to change.
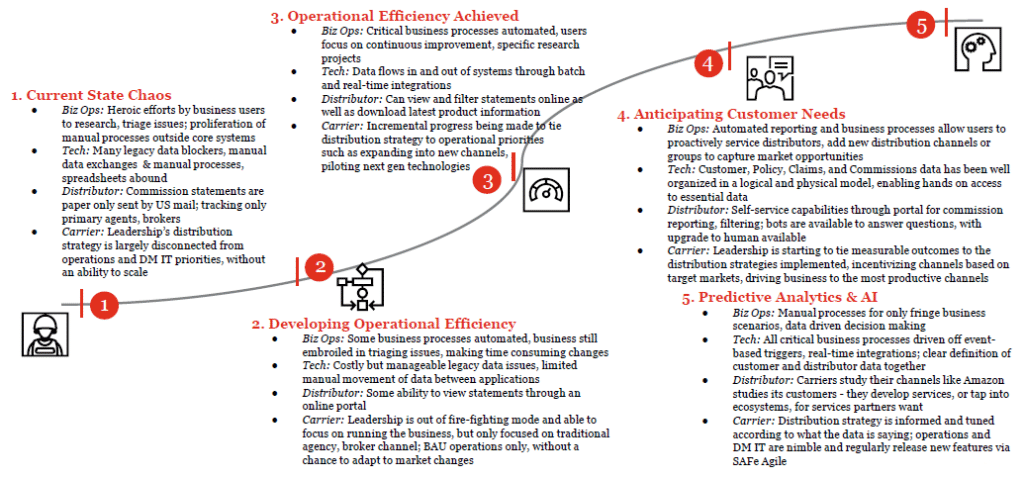
Climbing the Maturity Curve (The 5 Stages of DM Maturity)

curve

Stage 1. Current State Chaos

Stage 2: Developing Operational Efficiency

Stage 3: Operational Efficiency Achieved

Stage 4: Anticipating Customer Needs

Stage 5: Predictive Analytics & AI

A Day in the Life — Challenges, Hurdles and Efficiencies

For each of the stages, we’ve envisioned what it is like to live each day from the insurer and distributor perspectives. Is technology hurting or helping? What hurdles need to be dealt with before moving to the next step? As you read the list below, consider where your organization might be placed along the curve, then keep reading for a glimpse at the capabilities and efficiencies you might gain at the next step.

1. Current State Chaos

The earliest stage of the maturity curve is characterized by an enormous amount of manual effort just to stay a step behind. Fundamental tasks like research or triaging of issues are extensive and time-consuming for business users.

On the technology side, users must have a keen awareness of where different data lies across a multitude of offline documents or tables due to the abundance of siloed spreadsheets. As a result, carriers see centralization of knowledge in a few highly experienced resources. They experience long replacement cycles, inconsistent service quality and data management challenges. There is an inherent risk of this tacit knowledge being held by a small group of employees, many of whom may be quickly approaching retirement age. What happens when they leave and take this knowledge with them? All of this means that the organization must focus on survival rather than thriving.

From a distributor perspective, “ease of doing business” is nonexistent. Changes are time-consuming. Call volume skyrockets due to a lack of transparency and access to information. Lots of time is spent troubleshooting or researching what happened, when and why. Issues can’t be addressed quickly and result in a lot of incorrect transactions. Growth, let alone retention of top distributors, is a challenge, at best. It is hard to get the benefits from any technical investments without integrations to other core systems or the availability of digital information.

2. Developing Operational Efficiency

At the second stage of the maturity curve, carriers start to develop simple, yet fractured automations that break up the monotony of manual heroics. While this is a relatively improved stage, there will still be a high degree of manual effort.

Many carriers reach this phase and get discouraged with the results. Historically, this is an awkward period that should be viewed as a “practice phase” based on early results, rather than the endpoint of a transformation for the organization. Triaging issues remains a complicated and time-consuming process for business users.

On the technical side, legacy data issues are common, and, while they remain costly, the majority of data is starting to be passed from application to application via automated jobs. There will still be some lingering instances of legacy operational data living offline for accepted, fringe business cases only.

Operational efficiencies are still being created at this stage, but a day in the user’s life still starts and ends with operational inefficiencies. Business users will still spend considerable time triaging issues, a process that requires navigating multiple applications to find the most useful data. Distributors might be able to view select statements through a basic online portal at this stage, but little else is available online, and they are often still dealing with the inefficiencies of paper mail. To move from the first to the second stage, it is important carriers start optimizing various processes via automations, as well as implement a basic portal with at least foundational capabilities. Carriers will still need to add automations to adapt in real time.

3. Operational Efficiency Achieved

Once a carrier reaches the third stage of the maturity curve, enough automation has been implemented that the carrier can notice the operational efficiency that has been achieved. At this stage, critical business processes are automated, freeing up the bandwidth of business users. Without having to invest as much time and energy into firefighting, users can prioritize research that drives continuous improvement. Technology efficiencies are driven by batch and real-time integrations, allowing data to flow across applications without manual manipulation.

The introduction of siloed but now digitally enabled self-service tasks is the hallmark of the Stage 3 producer experience, laying a foundation for “ease of doing business” going forward. Many core platforms have made investments to allow for easier deployment of digital experiences. Producer portals allow distributors to view and filter all statements online and download the latest available product information.

One holistic benefit of achieving these operational efficiencies is that carriers will be able to increasingly tie their distribution strategy to operational priorities. Newfound abilities such as expansion into new channels or the piloting of next-gen technologies will offer tangible proof that progress is being made toward a true distribution management transformation.

4. Anticipating Customer Needs

At the fourth stage of the maturity curve, all users at a carrier are increasingly able to select how and where they want to make improvements to the business. Here, automated reporting and business processes allow users to proactively service distributors; all core operations require very little effort from users. Business users can more readily identify new distribution channels or groups, and they are able to capitalize when market opportunities present themselves. Users are further aided by the fact that customer, policy, claims and commissions data has been well-organized in a logical and physical model; it is both efficient and intuitive to get access to essential information.

The producer portal moves beyond siloed transactions to a holistic experience from onboarding, to servicing, commission statements, lead generation and more, redefining “ease of doing business.”

Business users invest little to no effort to access the information they need, and portal capabilities are fully self-servicing with human interaction being almost a luxury upgrade. Leadership at the enterprise level will be able to start tying measurable outcomes to the distribution strategies implemented during the transformation. At the channel level, incentives will be based on target markets, and business will be driven to those channels that are most productive.

5. Predictive Analytics & AI

Very few carriers, if any, have made it to Step 5. It’s the right vision to aim for, though, because it encapsulates what is currently possible.

Once carriers reach this stage, data-driven predictive alerts for business users will enhance the timing, speed and quality of decisions related to managing their distribution channels. Core processes will be conducted via automated data-driven decision making, rather than highly manual intervention by business users. Technology will inform these automations given the presence of event-based triggers and real-time integrations.

Manual effort is limited to fringe exceptions. Distribution capabilities should be mature enough that carriers can have a comprehensive understanding of their customers. They will only develop services or strategies that tap into ecosystems when it clearly makes sense for what their partners want. Distribution strategy will be fully informed and tuned to what their data is saying. Carrier technologies will be nimble enough to consistently and effectively meet the needs of customers.

You Can Get There From Here!

Carriers and distributors can escape that groundhog feeling with incremental improvements and a vision of a transformed experience for everyone. In fact, the vision is a great place to begin. What will a successful transformation look like? What are key metrics to track throughout the journey? Is this something we can do alone, or should we seek a partner?

Every organization is different, but all insurers should be working within a growth strategy that includes next-gen customer and distributor experiences. The capabilities needed will be found in next-gen distribution management technologies.

For an expanded look at transforming distribution management, be sure to download the Majesco/PwC report, Distribution Management: A Path to Maturity. For a closer look at how to achieve the right mix of technology and flexibility in your operating model, tune in the latest Majesco/PwC podcast on Adapting and Growing.


Denise Garth

Profile picture for user DeniseGarth

Denise Garth

Denise Garth is senior vice president, strategic marketing, responsible for leading marketing, industry relations and innovation in support of Majesco's client-centric strategy.

Gen Z and Millennials Make Bold Moves

Consumer trends may cause you to rethink how your organization fits within other ecosystems that customers want and are willing to buy insurance from.

millennial

At one time, life seemed to be compartmentalized. Work was work. Home was home. You commuted to work or business. Your work stayed at work. You slept and ate at home. You might drive back out to a movie or a restaurant on the weekend. With the exception of agricultural jobs, where home and farm were often the same, most of us lived and operated within these compartments. Insurers understood the compartments and insured them appropriately. Insurers and their agent channels knew how to catch us where we would be most likely to sign up for insurance. They were adept at selling.

Convenience and technology, however, kept creeping into the picture. We had our newspapers and mail delivered to our homes but now receive them digitally. We watched movies at the mail but now download or stream them. We had pizza delivered and now can have nearly any restaurant food or groceries delivered. We ordered books online with a click and now can download them to read on tablets.

This trickle of ease and use of technology gave us a taste of how convenience could improve our lives. Aspects of our compartments were seeping into the other compartments. This made selling a more difficult process. All industries had to rethink their products and services from the standpoint of the customer – their desire for convenience and use of technology. If you couldn’t get people to go to their entertainment, you had to bring it directly to their homes. If you couldn’t get people to walk into your bank, you needed to place your bank on their phones.

We are now evolving beyond convenience. Life is no longer compartmentalized. It has gotten complicated.  Customers want simplification and a holistic view to manage their lives across many different areas. And insurers have to pay attention to the changes. What happens when a large portion of the population begins to drive their cars for work instead of to work or many people shift to work at home instead of working “at work”? What if people want value-added services to manage risk – from their homes and autos to their health and more? These are radical shifts that are rewriting the stories of insurance. The nature of home, work, business and family are erasing the conceptual lines that kept insurance “traditional.”

In this blog, we are going to give you a high-level peek at some of the trends we found in our annual consumer survey. Some of them will make you want to press fast-forward on your strategic plans. Others may cause you to rethink how your organization fits within other ecosystems that customers want and are willing to buy insurance from. No matter what you find, you’ll be better-informed as you grapple with important decisions and future plans.

The Gen Z and Millennial Lens

Though Majesco’s report covers all age groups, insurers that are concerned about the near future will be most interested in the shifts and interests among Gen Z and Millennials. They are now the dominant buyers for both life and non-life insurance products, with a focus on five segments: life/health/accident, employee/voluntary benefits, auto, mobility and homeowners/renters insurance.  

Millennial and Gen Z life journeys have not followed the traditional path set by older generations, with high percentages remaining single and not married but with partners. They have made other significant lifestyle shifts from older generations that result in different risk needs that require different insurance needs.

Over the next three years, Gen Z and Millennials plan to accelerate their life journeys through rapid change, outpacing the older generation in all aspects, including twice the average rate of changes in the home, work and mobility aspects of their lives.

These shifts align with a shift in expectations regarding the types of insurance products they need, the necessity for value-added services and the demand for personalized underwriting. This will pressure insurers to accelerate and improve IoT and data strategies.  

The Millennial and Gen Z populations desire a holistic customer experience – where digital offerings bring together other products and services to help customers manage their lives. This necessitates a full view for customers across their insurance products, value-added services and non-insurance products. When insurers can’t deliver that view, a gap arises between customer expectations and what insurers are delivering. This gap opens the door for new competitors to meet that expectation – either directly or through partnerships with insurers. Just consider what companies like Toyota, Sofi, Ford, Petco and Outdoorsy are doing by offering insurance products through embedding or partnering on channel options with various insurers. This year’s research adds clarity to the market areas where insurers are currently missing opportunities.   

CAUTION: Opportunities Ahead

If change brings opportunity, then insurers are right now staring at an ocean of real opportunities. Let’s look at the changes that are most prominent.

Millennials’ life journeys have not followed a traditional path, largely due to the severe economic stress of the 2007-2009 Great Recession as they entered the workforce. Since then, many have achieved a firm foothold in their life journeys, with a growing majority owning their homes and having children. Yet, high percentages of Gen Z and Millennials are single (42%) and not married but with partner (11%), reflecting a significant lifestyle shift from older generations, which likewise reflects different insurance needs as seen in Figure 1.

Figure 1: Life stage characteristics of today's insurance customers

data

Over the next three years, Gen Z and Millennials will outpace Gen X and Boomers in lifestyle changes in all aspects, including twice the average rate in home and work categories, as seen in Figure 2.  Each of these aspects is assessed in detail in the report over the seven-year window.

Figure 2: Expected life stage changes in the next three years

data

Every area that directly affects the need for and use of insurance is prime for growth. The only question is whether insurers are prepared to capitalize on that growth. In many cases, the growth won’t be through traditional methods of selling or even through traditional products. Digital plays a HUGE role in their expectations. And holistic lifestyles and the desire for convenience will push insurers to digitize and innovate their channel and ecosystem partners to place their products at the point of life events and important larger purchases.

COVID-19 Hastens Market Shifts by Making Insurance Top-of-Mind

A connected facet of insurance’s potential growth and change is a new protective mindset. A crucial factor influencing all generations is COVID-19 and customers’ views on insurance. Nearly half of Gen Z and Millennials and 40% of Gen X and Boomers in this year’s research felt that insurance has become more important due to the pandemic. (See Figure 3.)

Figure 3: COVID's impact on the importance of insurance

data

Is “the COVID Effect” a fad? Possibly, but unlikely. Even if COVID were to evaporate overnight, general uncertainty over new weather patterns, social and political unrest and property investments means that insurers need to respond quickly with new or modified products, value-added services and customer experiences that meet rapidly changing customer needs and expectations. The work and home trends that were accelerated by COVID have been around long enough to have made a lasting impression on both the economy and consumer sentiment.

Opportunities in the Widening World of Work

During 2020, 42% of Americans worked from home, nearly double the rate from 2019. Gen Z and Millennials reflected higher rates of gig work as both independent contractors and rideshare drivers in 2021, likely reflecting job losses, resignations from jobs and seeking new job options. (See Figure 4.) This means that geographic distribution of “the workplace” is now wider than ever before. This segment anticipates a steady continuation of independent contractor work but a decrease in rideshare work back to pre- and early-COVID levels as their employment and personal financial situations stabilize.

Figure 4: Gig economy work trends

data

True to this generation, Gen Z & Millennials expect to be in different jobs (45%) and working remotely (40%), continuing the transient aspects of this generation that will put new demands on employee benefits to be flexible and portable. Nearly 25% indicate they will start a business, highlighting an opportunity for insurers to develop relationships with employees directly to keep them as customers as their lifestyle changes.   

These changes reflect growing opportunities for insurers to cover the shifting worker and employer needs. From on-demand benefits for gig/independent contractor work to work-from-home setups – employee and employer needs are dramatically changing. Innovative options like Nationwide’s work-from-home insurance, which bundles home/renters, usage-based auto and identify theft insurance, is an example at the forefront of this change.
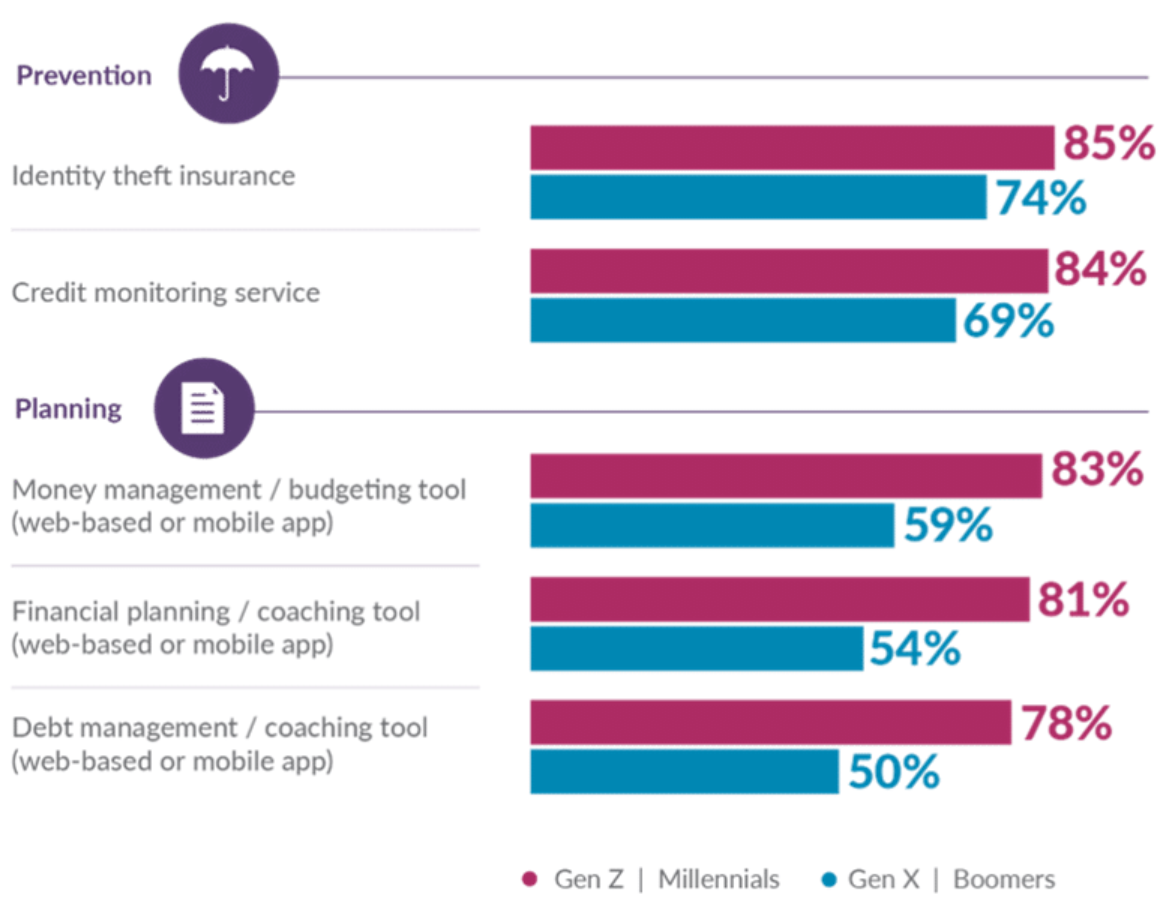
Figure 5: Expected changes in work in the next three years

data

Opportunities in the Financial Sphere

Gen Z and Millennials have consistently trailed the older generation in banking and investing by an average of 10% to 15%. This offers an excellent opportunity to engage them now to address a broader financial well-being approach by developing a partner ecosystem that brings together other financial offerings and value-added services. Insurers can take advantage of Gen Z and Millennials’ high levels of interest for both planning (money management, financial planning, debt management) and financial loss prevention and recovery services (identity theft insurance, credit monitoring) as first areas of focus for partnerships (Figure 6). 

While Gen X and Boomers don’t feel the same need for planning tools or services, they are still interested in financial loss prevention and recovery services to protect their financial assets as they enter or are in retirement.

Figure 6: Interest in financial wellness value-added services

data

Product Placement: An Opportunity for Ecosystem and Partnership Development

For every opportunity, however, insurers will need to ascertain the best route into the market. Majesco’s research into digital shopping trends highlights the need to not just be online but to think innovatively around online positioning with partnerships in areas where people are already shopping.

The last year has accelerated the use of digital and online options across all industries. The level of impact is substantial with 66%, of Gen Z and Millennials and 54% of Gen X and Boomers changing their views of the importance of digital and online capabilities due to COVID as seen in Figure 7. McKinsey research found that online purchases increased 30% since the beginning of COVID and have remained at this level.

Figure 7: COVID's impact on the importance of digital capabilities

data

And expectations continue to rise for digital and online.  Both generational groups expect to do more shopping and buying online, outpacing in-store or in-person shopping by 10%. Once again, positioning is best where life happens. Carvana, for example, offers both gap insurance and mechanical protection "at the point of sale" for any car in its inventory. Are insurers prepared with the technologies and digital connectivity that will help them fill the growing gaps in online placement?
Mining the market

Just as Bitcoin was an industry to be “mined,” consumer and business trends are also filled with value for those who read the research. The viability of the insurance industry is connected to demographic trends, market trends, customer expectations and adoption of new technologies. If we lose touch with our customers, both current and future, we lose business.

Don’t miss out! You can access Majesco’s latest mine of valuable consumer information by downloading our 2021 Consumer Survey Report. And be sure to watch our recent webinar, Your Insurance Customers: A Crystal Ball of Big Changes in a Small Window of Time.


Denise Garth

Profile picture for user DeniseGarth

Denise Garth

Denise Garth is senior vice president, strategic marketing, responsible for leading marketing, industry relations and innovation in support of Majesco's client-centric strategy.

Women in Tech: Leveling the Playing Field

The gender gap is societally based, and change needs to happen at a core level. Not just with how men see women in the industry, but with how women see themselves.

women

The tech industry is growing and evolving at an exponential pace. New opportunities and innovations are appearing every day.  The majority of college degrees earned are in STEM fields. U.S. tech budgets will expand by 6.7% in 2022. And competitive compensation, flexible hours and worldly culture are attracting a young, dynamic workforce. But for all this change and development in the industry, one aspect remains unfortunately static — lack of gender diversity.

Despite the industry being based on the notion of innovation and disruption to the “old ways”, the perception of women’s capabilities and contributions to the industry is unfortunately still rooted in the heavily biased past. Women are underrepresented in technology leadership, presenting fewer role models and possible allies for others entering the industry. 

This often starts at the ground level, where few women choose to be in STEM roles. According to the National Girls Collaborative Project, women received more than half of the bachelor’s degrees awarded in the biological sciences in 2015. However, women received far fewer degrees in the computer sciences (18%) and engineering (20%) that same year. 

This gap is societally based, and change needs to happen at a core level. Not just with how men see women in the industry, but with how women see themselves and their potential for success. There are needs that go beyond formal education. Mentoring programs can be vital first steps to encouraging young women to enter the tech industry. 

When I started this company, I knew I wanted gender diversity to be at the heart of our workforce strategy, and that has enabled us to follow through on the promise. Currently, 50% of the executive roles are filled by women, and 46% of the entire company are women. Gender representation in the tech industry needs to be balanced because diverse thinking is imperative both for innovation and for agile execution. We have made it a core initiative to be more inclusive of women in hiring, promotional and cultural strategies. We founded the Planckademy, an internal training course for inexperienced college graduates, which helps train developers — a field with very low female representation. In the class of 2021-2022, 57% of participants were women. 

Donating to and volunteeing with numerous nonprofits that address this agenda is a beneficial exercise, as well. One organization we like to support is SheCodes, a non-profit organization that offers free training in coding for women (by women). Our executives have refereed hack-a-thons and recruited female developers who have gone on to make amazing contributions to our organization. 

To address gender disparity, organizations of all sizes must first understand why representation of women is beneficial. At a tech company, situations evolve quickly, and there’s not a lot of time available for research and decision-making. A diverse team includes different backgrounds and brings new ideas to the table. Taking in these viewpoints allows you to broaden your perspective as a leader. Being better-equipped to react and adapt leads to a better organization and a healthier bottom line.

The evidence shows overwhelmingly that diverse companies have stronger employee engagement, talent retention and operational success. When an employee feels seen, appreciated and represented, she or he is inspired to deliver better work, contributing to the financial health of the organization. 

Planck also gives higher ranking to investors with female partners and women in key roles. The board of directors manages the CEO, and, thus far, I have selected three female directors. My objective for Planck is to achieve 51% female representation overall, reflecting the makeup of the globe. 

See also: How Women Can Cut Through the Tangles

While this shift in mentality needs to come from the core, change begins at the top. CEOs and founders have the responsibility to choose wisely and consciously. Be mindful of hiring in a balanced fashion. Take a hard look at your own personal biases, acknowledge them and consider them when decisions are made. Make sure that women’s voices are heard in all discussions regarding the work environment and culture; that diversity, equity and inclusion are core components of your employee experience and brand; set the bar higher in the industry by speaking out about gender disparity in tech and contributing to gender equity conversations and initiatives. It can pay dividends to provide internal education opportunities and career paths to create opportunities for women to gain experience and excel.

Organizations must frame diversity as a competitive advantage and build hiring strategies around that goal. You can start making a difference at your company by considering the concerns of women in the workforce. A few standards we follow include:

  • Promote an inclusive, clean and respectful workplace
  • Provide flexible work schedules and fully remote options
  • Perform formal annual salary reviews to maintain a zero gap in gender pay equity
  • Practice role-modeling by promoting women from within and scheduling internal presentations by successful women from the tech industry 

COVID-19 shifted the landscape of business worldwide, and the enduring lessons of the pandemic have the potential to further the role of women in tech. In 2020, millions of women left the workforce due to the caregiver crisis – sacrificing their jobs to take care of children and loved ones. Since that time, extended lockdown measures have completely changed the way the world does business, normalizing the concept of a fully remote workforce. In 2021, according to the U.S. Bureau of Labor Statistics, the tech industry saw a significant increase in resignations over the previous year. In a tight labor market where all employers are competing for talent, tech companies should consider reaching out to talented female candidates with offers of flexible work options and a better employee experience.

Sponsoring women’s communities with meetups and nonprofits, creating a supportive environment for all employees to thrive and building varied routes to success illuminates the pathways for tomorrow’s leaders — men and women — and fosters a stronger tech industry. A vision we all aim to achieve.


Elad Tsur

Profile picture for user EladTsur

Elad Tsur

Elad Tsur is chief AI officer at Applied Systems.

Previously, he was the co-founder and CEO of Planck, where he developed an underwriting workbench enhanced by generative AI;.the lead architect of the Salesforce Einstein platform; and founder of BlueTail (acquired by Salesforce).

The New Age of Insurance

Insurers have at their disposal incredible amounts of data, and powerful analytics can turn it into business intelligence better than traditional tools.

data analytics

The world generates 2.5 quintillion bytes of computer data per day. That’s 25 followed by 16 zeros. What’s more, 90% of today’s data was created in the past two years, meaning that big data’s role is massive and growing.

In the insurance industry, all this data positions companies to provide their clients with unsurpassed coverage and service if they can access the information on-demand in practical formats, making it work for everyone’s benefit.

Applying this intelligence can affect business in multiple ways, to:

  • Target customers more efficiently
  • Improve decision-making
  • Lower exposure
  • Discover and implement ways to add tangible value to operations
  • Reduce costs

What’s necessary is on-demand access to data that provides insight and context to business intelligence, information that should not take an advanced degree in technology or systems analysis to interpret results. Analytics designed to thrive in a user experience environment and empower analysts to conceptualize data will serve data-intensive industries like insurance the best.

Addressing complexity

Insurers have at their disposal incredible amounts of data: Intelligence on their customers; demographics by geography, age and gender; market trends; and historical information are just a few of the numerous categories. Promptly gathering this information in helpful formats for employees with varying levels of responsibility and analytic skills is the challenge that insurers and many other organizations face. Powerful analytics can deliver this business intelligence better than traditional tools.

Users need to understand the data and apply it to their tasks. Staff swiveling in and out of different business intelligence tools to perform their assignments is less efficient than using well-designed analytics that allow them to stay within the workstream when gathering, assessing or reporting information.

For example, some auto customer data can be stored on one platform within a property and casualty insurer while claims history is accessible on different software. Vehicle features and values may be drawn from other databases, while driving records need to be pulled from one or many public safety departments from across the country. Such a puzzle is rich in data but complex in a traditional workflow. Having well-designed analytics built into the system simplifies the process of quoting customers, especially in a 24/7 environment.

See also: 3 Digital Customer Service Strategies for 2022

Engaging applied intelligence

Merely providing intelligence is not all that analytics can do.  

Engaging dashboards, visualizations and other delivery methods create a vibrant workspace for the user, offering context to otherwise jumbled or contradictory information. Users adopt attractive tools more extensively, use them more frequently and instinctively ask more of the instrument and the data it delivers. 

Embedding predictive analytics to intelligence gathering strengthens the usefulness of the data for timely decision-making. All these actions increase productivity. 

Analytics allow professionals to apply their individual business talents to tasks without needing a high degree of technical expertise to gather or interpret the data, serving entry-level professionals through senior executives. 

Inexperienced underwriters can more quickly assess customer applications, rejecting or connecting them to favorable coverage options at an appropriate premium, and claims analysts can identify fraud more effectively. The same analytics tool in the hands of veteran executives can give them other valuable insights such as data that readily demonstrate to regulators that products are appropriately priced and reflect exposure, that they meet acceptable loss ratio and combined ratio norms and that the insurer is a trusted partner in protecting the market.

These are simple examples of well-designed analytics directly affecting business success at multiple levels.

Intuitive self-service

There are valid reasons to compartmentalize intelligence in today's business environment, but the versatility of built-in analytics allows a wide variety of access levels to personas or individuals. Access is based on roles and need-to-know, not how well a person understands code or software. 

As people's business roles, responsibilities and talents change, the tool serves intuitive self-service. Access to intelligence is acquired by applying amassed business acumen, not technological know-how about obsolete software.

Customizing analytic tools allows people to dedicate themselves to productivity rather than repetitive problem-solving and troubleshooting. Actuaries can spend the workday assessing market risks and exposure, creating innovative product offerings or adjusting investment strategy on the book of business instead of figuring out new software updates on old business intelligence platforms.

See also: Improving Customer Experience In 2022

Expect more and deliver

Employees will use the tools at their disposal, whether those tools are adequate or outstanding. However, those that enrich the user experience and directly drive business value get the best adoption rates and results. 

The more comfortable people at an enterprise-wide feel with their tools, the better they’ll perform. Powerful analytics, including predictive analytics, streamline assessment, planning, forecasting and overall decision-making experiences. They allow insurers to effectively connect the benefits of business intelligence to the customer and the organization’s goals.

The sooner insurers adopt analytics to leverage big data, the more quickly they will improve efficiency, reduce costs, meet and exceed customer expectations and boost expectations in an increasingly competitive marketplace.