Download

Is the Email Era Ending?

Email is based on an antiquated physical model (the inbox and outbox), and better ways of communicating -- even collaborating -- with customers are emerging.   

Image
a photo of three sets of hands on a wooden table. Two people are holding smartphones and one is typing on a silver laptop. There are drawings of email symbols above all three sets of hands.

Paradigms die hard, but they can eventually die. The idea of a carriage stuck around long after engines, rather than horses, began to power them, but the horseless carriage became the car over the course of a few decades. TV shows were initially just radio shows or Vaudeville acts done in front of a camera, but "I Love Lucy," "The Honeymooners" and others eventually pioneered a better way, just as cable TV has morphed into its many, many current forms after initially being just broadcast TV carried on a wire. 

Even though email has been around so long that many of us can't remember life without it, it's actually based on an antiquated physical model -- the inbox and outbox -- and the paradigm is showing signs of dying. While it's still not clear just what approaches will supplant email, they could make internal communication more efficient and, even more importantly, provide better ways of communicating -- even collaborating -- with customers.  

The limitations of the inbox/outbox model have been apparent almost since email became widespread. I remember once having breakfast with Steve Ballmer, then the No. 2 executive at Microsoft, and asking him what the next killer app would be for personal computers. Email, he said. Well, that breakfast was in maybe 1991, and, by 1993 or so, email's limitations were so apparent that Lotus Notes had become popular as an alternative that allowed for better group collaboration.

Email: from killer app to serious pain in two years.

Companies have been wrestling with email ever since, if only by encouraging a code of etiquette that limits the number of people copied. (Email has been described as a way for others to add items to your to-do list.) Relatively recent tools, such as Slack and Microsoft's Teams, have facilitated collaboration, and those sorts of apps will become more prevalent as we older types age out of the work force and as more digital natives age in. (If I forward something to my daughters via email... crickets. But if I DM or text them... whammo! They may respond immediately. And just imagine the interactions if I ever start to use Instagram.)

As a New York Times columnist wrote recently in a piece titled, "The Kids Are Right About Email, Too": "For them, email isn’t annoying. It simply doesn’t exist."

I'm sure companies will continue to find ways to use collaboration tools to work more effectively than they have been able to just through email. As I've written previously, especially here, I believe that a lot of the increase in effectiveness won't be through speeding communication but by slowing it down, or, more accurately, letting senders and receives sort communications better so the time-sensitive issues get addressed quickly while others are set aside so they don't upset the flow of the receiver.  

But what has really caught my attention is the potential for better communication with customers. They are moving faster than companies are to a post-email world and, as usual, will get impatient with companies that don't keep up. 

Connie Chan, a general partner at the Andreessen Horowitz venture capital firm, lays out some intriguing possibilities in this blog post. (She uses China as an example, and I realize China is a controversial topic these days, but I figure we have to find examples wherever we can.)

She describes a new form of communication called "private traffic," which she defines as "a customer relationship management (CRM) strategy that emphasizes direct communication between brands and customers" and is better than email marketing "because private traffic enables two-way conversations. Customers expect a real back and forth whenever they communicate with brands, and in some cases interact not only with other brands but also with other customers....

"Here's one example of how private traffic might work: Let’s say you go to a store to buy a barbecue set. The sales rep might make a recommendation for a specific grill and say, 'Hey, after you purchase this, why don’t you add me as a contact? You can message me if you have any questions about installation, or any aspect of using your grill. If I come across cool barbecue recipes, or accessories for your barbecue set, I’m going to send them your way.'

"You agree, allowing the store rep to start a one-on-one chat with you. What’s the impact? You’re more likely to buy the barbecue set because you have the store sales rep’s personal support, and you’re less likely to return it because you now have a direct connection with them. This kind of private, two-way conversation also helps brands understand their customer better, which in turn helps breed deeper customer loyalty."

Chan describes an approach that Ctrip, the biggest travel company in China, began offering a couple of years ago: "If you booked an international flight for a week-long vacation, you’d have the option of joining a group chat with other travelers who booked tickets to the same destination, around the same time. There would also be a customer sales rep in the chat to act as a travel concierge before and during the trip. They’d answer questions about anything from what to do about a lost passport to which type of outlet converter to bring. But the best part is, once your vacation starts, you’re not only asking the customer sales rep questions — often, you’re talking to other group-chat members too. You might ask how long the line at an amusement park is, or see who has sightseeing recommendations, or even invite people to meet up for dinner. Essentially, the group of strangers becomes a community."

It's easy to see how the private traffic idea could translate to at least some situations in the insurance world. After a flood or wildfire, an insurance agent could act as a sort of concierge for a community, not only helping with claims but answering other important questions about how families can get back on their feet and connecting families with each other for counsel and support. Insurers could also act as a sort of insurance-plus concierge for clients with similar businesses -- landscaping firms, pizza parlors, etc. -- advising them while they advise each other. In addition, insurers could plug themselves into private traffic arranged by others -- perhaps the auto dealer who is maintaining a relationship with customers would welcome an expert to answer tricky insurance questions as part of the dealer/customer private traffic. 

It's easy, too, to see how quickly private traffic could get messy. For one thing, it requires a significant time commitment. And what if someone in the community you organize says something bad about you? Or gives inaccurate advice? Who would be liable? What will regulators say?

But the customer is always right. Right? So, we need to find some way to stop just blasting those email surveys to customers or simply sending forms about policy renewals and to engage them in ways that they find meaningful and helpful. 

If we do, we can obtain what some marketers are calling "privileged insights." The idea is that you can get certain basic insights from market research or from customers when they buy the first product from you but can gain deeper insights -- privileged insights -- if you establish a relationship with them and build trust by offering good advice, providing prompt service, treating them and their data with respect, etc. You develop a virtuous cycle. Customers grant you insights that let you improve your product or service, which makes them trust you more and grant deeper access to their thinking, which lets you....

But part of building that trusting relationship with customers will require meeting them where they are, with text, chat, DMs, etc. and less and less with email.

Yes, I realize the incongruity of my sending you an email about the end of email and expecting you to read it. But I think email newsletters, which are currently so successful for so many, can change as your needs and habits do. I certainly hope this one will. 

Cheers,

Paul 
How to Use Social Media Data in Underwriting

Social media data provides insurers with an opportunity to gain insights into a customer's risk exposure in real time. But it comes with many challenges.

phone

With more pressure than ever to offer competitive pricing, insurers are seeking innovative ways to leverage additional data sources in underwriting. Today, there are over 4.62 billion social media users globally, leaving endless amounts of personal data across social media platforms like Facebook, Twitter, Instagram and LinkedIn. 

The need for more data sources to augment and support internal processes is growing, especially with the rise of predictive analytics, AI and new demands to improve the customer experience. 

Social media data provides insurers with an opportunity to gain insights into a customer's risk exposure in real time. But it comes with many challenges. It can be used—but take care!

Some insurers have already jumped on the bandwagon 

One auto insurer created a personality-type assessment based on certain choices and actions of potential clients. These included what athletes the client likes/follows, how concise their writing was and how often they used exclamation marks in social media interactions. The data enabled the insurer to determine if the client was overconfident or reckless, traits associated with many high-risk drivers. 

A life and health insurer in the U.S. tested behavioral data gathered from online retail sites and third-party databases as inputs for predictive modeling to determine the health risks of over 60,000 applicants. Examining user behavior helped the insurer get results similar to traditional medical examinations. Each application cost the insurer only $5, instead of $250 to $1,000 for conventional medical tests, according to a Deloitte report.

AI to the rescue

Scalability is a critical challenge with social media usage in underwriting. Manually collecting vast quantities of social media data is impossible. However, insurers can partner with third-party data vendors that use AI to scrape data from users' profiles. 

AI tools, equipped with machine-learning algorithms, can collect written and visual consumer data and build predictive models faster than human agents. Predictive models let underwriters gain a more detailed assessment of an insured’s level of risk.

Sentiment analysis, equipped with natural language processing (NLP), is a machine-learning technique that analyzes and interprets text. Sentiment analysis can take in written user information at scale and use it to assess a client's behavior. For example, sentiment analysis can read, analyze and collect information from a business's review section, flagging any potential risks that require further investigation.

Machine vision uses software algorithms to assess images based on existing data sets already evaluated by humans. Insurers can leverage machine-vision applications to investigate the photos and videos to discover more about a client's lifestyle, including eating, exercise and smoking habits.

Legal and regulatory pitfalls

Experts say insurers using social media data to fight fraud are on solid legal ground. But, what about underwriting? Regulation is evolving. Proceed with caution. 

Data mining through social media may violate privacy laws, such as the E.U.'s General Data Protection Regulation (GDPR). 

Closer to home, the New York State Department of Financial Services says they're concerned insurers could use their own algorithmic underwriting systems to discriminate against consumers illegally. 

New York’s insurance laws, and similar laws elsewhere, prohibit the use of race, national origin, lawful travel, mental or physical disabilities or traumatic experiences such as domestic abuse in any aspect of insurance underwriting.

Insurers must ensure that the external data sources they use meet their antidiscrimination requirements. Additionally, carriers must be transparent to customers about the content of the external data and its source when being used to increase premiums or deny a customer coverage.

One expert says insurers can test their algorithms for discrimination by examining the algorithm's results. For instance, insurers can test their algorithms by omitting standard customer data and only using information about the client's race. If the algorithm can predict the customer's premium by only using race, the model is too dependent on protected personal attributes. 

See also: Personal Connections Via Social Media

Does using social media data violate trust?

Collecting clients' social media information without consent or transparency can feel like a violation of trust. If not done sensitively, this can severely damage an insurance company's reputation, brand and relationships with policyholders. Always ask prospects and customers for permission to view their social media posts.

Lawyer Tyler Dillard compares the use of social media data to previous decisions arrived at on the issue of genetic testing for insurance. For example, while AI may suggest certain typing habits (e.g., excessive use of exclamation points) are correlated with bad driving, the causal link is dubious and supporting evidence is sketchy, unlike genetic testing. Insurers that use AI for big data analysis of social media should emphasize explainability above all else: Why did our program draw this connection?

From a proportionality perspective, analyzing social media data in such a granular way may only produce marginal benefits at the cost of severe regulatory consequences and offending customers. 

Of course, the accuracy of the source data on social media is suspect. The online personas users construct are not always accurate reflections of reality. Moreover, insureds can seriously undermine the underwriting process by learning what information carriers are looking for and publishing content they believe will help them get a lower premium.   

Personalized policies

Despite its challenges, social media remains a great tool for enhanced customer intelligence and developing more personalized policies.   

Although social media data offers a trove of growth opportunities for insurers, the legal challenges, brand-affinity risks and lack of data verification are causing many to steer clear of this underwriting method. In fact, out of 160 insurers investigated by New York state, only one used social media for underwriting. 

To mitigate risks, insurers should focus on rewarding “good” behavior on social media rather than punishing “bad” behavior. In other words, offer discounts to desirable risks. Many regulatory bodies are slow to respond with clear guidelines on big-data analysis of social media. Err on the side of caution. 

As social media data usage in underwriting is adopted, insurers must be transparent with customers about using and obtaining the data. This step is imperative, as undisclosed use of client social media data can infringe on privacy laws and antidiscrimination laws and leave customers feeling violated. 

Leveraging consumer external data remains critical for insurers today. Insurers that comply with regulatory requirements and emphasize explainability and proportionality can mine magnitudes of external customer data and turn it into actionable information. Of course, they’ll need modern rating and underwriting systems to leverage that information.

AI, Cybersecurity and Insurance Risk

Having multiple reviewers with varied socioeconomic, ethical and individual backgrounds can lower the risks of biases being placed into AI programs.

cyber

Physical assets that we can touch and see make sense to protect. Windows get broken by accident, thefts occur, pipes can burst and anything and everything can happen in between. But what about our assets that we can’t see? What about cybersecurity? The information that we store online can be extremely valuable to those looking to do harm. 

Roughly 2.5 quintillion bytes of data is created every single day, and phishing attacks, ransomware attacks and distributed denial of service attacks are so common that some 23% of small business owners have experienced an attack on their business in the last 12 months, according to a survey by Hiscox. 

Here are examples of how AI can be used to fight against specific types of cyber threats:

Privacy 

Whether it be federal government organizations, local law enforcement or even personal home networks that have unique features within their dataset that are used to train algorithms, the identities within these systems may be compromised. To avoid identities having their integrity compromised as part of the training data and adding risk to privacy, organizations/persons can use unique techniques such as federated learning. What it comes down to is training the separate models locally at the source and federating them on a more global scale, to keep the personal data secured at the site of origin. Finding specific samples of outliers and excluding them from the training is a good practice.

Bias Bounties

With older software, sharing the intricate details of an AI algorithm can become more and more of a liability, because it’s able to provide insights into the model structure and its operation. A good countermeasure, described by Forrester as a trend for 2022 (North American Predictions 2022 Guide), is bias bounties, which help support AI software companies to further improve their algorithm robustness and reliability.   

Bias bounties are becoming the go-to tool when it comes to the defense of having ethical and responsible AI because they can help ensure that the algorithm in place is as unbiased and as functional as possible. There are more sets of eyes and different thought processes involved to help review the data throughout the course of the campaign.  

See also: Quest for Reliable Cyber Security

Data Poisoning

Data poisoning is taking data and then using it for ill intent. Data used as samples in training algorithms are changed to have an output or prediction that is malicious when triggered by specific inputs. 

Data poisoning is done before the model training step occurs. Zelros has an ethical report standard, where they have been collecting a dataset signature on the successive steps of modeling to ensure that data has not been compromised.

Human Behavior

With data or AI manipulation, malicious activity is typically responsible, but personal data that we often willingly share can be used against us 

Cybersecurity's most prominent weakness is our ability to propagate knowledge of our identity and activities in seconds to millions of people across the globe. Artificial Intelligence or even basic tools that can collect data have exacerbated the problem. 

For instance, geolocalization data that is openly shared on social networks can be leveraged by AI systems to place into categories potential customer targets and provide specific outputs or recommendations. The "attention economy” has been built on the personal data that can be fairly easily accessed. Cultural and scientific awareness is going to be one of our best bets for countering the problem (as detailed in the first topic of this article).

A machine learning model may learn much more than what we could have anticipated. For example, when gender has not been identified in customer data, the algorithm can learn to infer about gender through proxy features, in a way that a human could not, at least with the same amount of data, and in such a limited time. For this reason, analyzing and monitoring the ML model is crucial. 

If we are to anticipate algorithm and model behavior, and help prevent discrimination from occurring through proxies, a key element is diversity. Having multiple reviewers who can provide input based on their socioeconomic, ethical and individual backgrounds can lower the risks of biases being placed into AI programs in the first place. Organizations can also request algorithmic audits by third parties if the organizations lack the knowledge and diversity to complete the tasks themselves.


Antoine de Langlois

Profile picture for user AntoineDeLanglois

Antoine de Langlois

Antoine de Langlois is Zelros' data science leader for responsible AI.

De Langlois has built a career in IT governance, data and security and now ethical AI. Prior to Zelros, he held multiple technology roles at Total Energies and Canon Communications. He is a member of Impact AI and HUB France AI.

De Langlois graduated from CentraleSupelec University, France.

Lessons From Travel Insurance

When done correctly, technology is as transparent as it is critical. When implemented poorly, it's like begging your customers to look elsewhere for services.

travel

While watching an old movie, have you ever thought about the fact that there's no computer on the main character's desk? What was it like back then? I imagine sipping coffee, opening my mail, wondering if a check has arrived that I can deposit at my local bank later in the afternoon, hoping the phone will ring and then actually answering it when it does. I might also think about the meeting I'll have that afternoon, penciled into my day planner for 3, while thinking, "I bet Bob will be 10 minutes late. Bob's always late."

Today's world travels at a different speed. I'd say light speed, but I'll spare you the cliché. No one hangs out a shingle and then hopes for customers to notice as they drive by. Customers expect to be wooed, they expect to be wowed and they expect to be impressed by personalized experiences. Your benchmark is no longer your industry -- it's Uber. Customer expectations are no longer based on your competitors -- they're based on Amazon.

There is no single technology that makes this happen. Rather, technology is brought to bear on customer desires. When done correctly, technology is as transparent as it is critical. When implemented poorly, it's like begging your customers to look elsewhere for services.

Here are some lessons that travel insurance has learned that could apply to other parts of the insurance industry:

Mobility

As a travel insurance company, Seven Corners has spent a lot of time transforming the experience of our customers. For example, having an app for both Android and iPhone devices that allows the insured to "carry us with them" wherever they go provides peace of mind for the traveler. Knowing they can pull up their digital ID card or get turn-by-turn directions to a reputable medical facility is a big deal when you're traveling, especially internationally.

Could there be a better sell for getting people to leave location services enabled for your app than travel insurance? People say fear sells insurance, and travel insurance is no exception. Fear of getting sick right before a trip, fear of weather-related issues and now, of course, fear of pandemics has travelers at the height of concern. Why wouldn't they want you to know where they are throughout their trip? It helps provide peace of mind and provides you with an excellent opportunity.

Scalability

Putting data in the cloud has moved from being suspicious to expected over the last 10 years. Having the ability to scale systems to the farthest reaches of the globe with relative ease is critical to providing low-latency access to your products and services for anyone, anytime and anywhere. Imagine being able to set up infrastructure in a new region or country in a matter of days, instead of months or years. Being nimble is a requirement for companies that intend to compete.

Customer Choice

Customers of different backgrounds and generations have different ways they like to purchase and communicate. You can buy a travel insurance policy on our website, of course, but maybe you have questions. Travel insurance is something that most people buy only occasionally, so talking on the phone with someone about where you are going and what you need can be very comforting. After you purchase, you may have benefit questions or need to update information such as trip costs, travel dates or destination country. If you need to file a claim, you might have questions or need clarification on why your claim was paid or denied.

Technology plays a big role in making this easy for customers, meeting them on their terms. For example, allowing customers to interact via WhatsApp or text messaging can provide a real wow factor, letting them use tools they live in all the time to interact with your company. On the back end, the right technology allows customer service representatives to interact with the customer like any other chat. Once the conversation ends, it's stored with their customer record for future reference.

See also: Travel Insurance: An Exemplary Experience

Terminology

While this might not sound like a technology play, it is very common for technology to drive terminology, rather than terminology driving technology. What is a member, or an insured, or a customer? Are they all the same thing? Did you know that most of your customers don't know what a provider is? To them, they visited their doctor or the local urgent care, not a provider. Travel insurance companies are notorious for making their customers learn new terms, rather than engaging with them using the terms they expect.

One way to make sure that technology is driven by customer terminology, rather than the other way around, is to ensure your systems use the terms your customers use. Creating a data dictionary with a glossary of terms, and using this company-wide, will help guarantee that technobabble and industry-specific jargon does not make its way into use on your website, your app and in oral and text communication with customers. Mapping your customer journeys, surveying your customers and simply putting yourself in your customer's shoes will do wonders for making your company seem accessible and available to your target audience.

Speed

In this modern era, new features, functionality, products and services need to be provided at record speeds. Whether you implement R&D, fail forward, set up hackathons or something else, you must have an agile mindset and make sure your technology allows you to deliver new things quickly. If you don't, your competitors will.

To stay competitive in today's fast-moving world and the growing industry of travel insurance, companies must adapt to customers' needs and wants and stay up to date with the latest trends in technology. Transforming the user experience to make things as simple as possible for travel insurance customers will not only make them feel comfortable when planning their trip but will also remain consistent with other technology-friendly user experiences they're already used to. This will only increase the chance that they'll choose to work with your company again in the future.


Ryan Brubaker

Profile picture for user RyanBrubaker

Ryan Brubaker

Ryan Brubaker is chief information officer and executive vice president of operations for Seven Corners. In his role as CIO, he uses technology to drive revenue, reduce costs and lower risk. As head of operations, he works to drive the best possible customer experience by guiding customers through their preferred channel and processing their claims with speed and professionalism.

Brubaker graduated from Purdue University with a degree in management and a minor in information systems and later received an MBA from Indiana University.

Revolution? Not Yet. Evolution? You Bet.

In our fervor to embrace new insurtech companies, we may have missed the opportunity to learn from those incumbents that have seen the ups and downs.

chess

To be an incumbent means you have been around a while. That sounds old-fashioned, out of touch and full of "good old days" stories. As I have been told, “past performance is not an indicator of future performance.” However, this is shortsighted because this disclaimer is usually accompanied by a chart showing why I should invest today because the future is predictable to some degree. Right?

In our fervor to embrace new insurtech companies, we may have missed the opportunity to learn from those that have seen the ups and downs. Those underwriting cycles seem to persist no matter how much data and technology we have today vs. yesterday or how many new Instagram followers I got this week. 

Fundamentally, the challenges we face today: inflation, catastrophes, debt and destabilization, are not new to those incumbents. They are new to the insurtech community. The world is getting more complex by the day, and a solid foundation of the past certainly helps to pave the way through to the future. The trick is how to get rid of the “vs.” and replace it with “and.” 

The airline industry is a great example of the evolution not revolution that can happen. The technology revolution in this vertical enhanced our ability to access travel, not to replace it. Using technology, the industry suddenly brought to life the infinite possibilities of traveling the world. I could now see myself on a beach halfway across the world. That excited travelers around the world and grew the industry from $1.9 billion in 2000 to $4.7 billion in 2019 (pre-pandemic). A fourfold increase. This wasn’t because we reinvented the airplane. We used technology to make traveling on an airplane more accessible and interesting to all. That is powerful. 

The point is that we do not need to reinvent the insurance industry, we need to combine forces with the insurtech space and make it more accessible, understandable and interesting, to grow the market together. For the benefit of all. 

Agent vs. Digital 

So the next "vs." we are confronted with in the industry serves the same lesson. "The end of the agent is upon us" is as realistic as the end of brick and mortar. Oddly, these prognostications occurred about the same time. But within the last week I did business with both agents and brick and mortar, while also doing business digitally. I’m confused. This world is built on absolute statements because they are great headlines, but the truth is there are very few absolutes in this world except the ones your parents told you, death and taxes. Beyond that is pretty murky. 

While our industry toils in absolutes, the real winners and breakthrough companies will figure out how to meld together the agent and digital in a seamless experience. The first step in doing this is in a realization that the agent brings things to the table that digital cannot, and vice versa.

Whoever effectively figures this out will align digital and people assets to create a great customer experience. 

See also: Good, Bad and Ugly of Going Digital

The retail industry is one that we can learn from, as they are years ahead of the ballgame, and you can start to see winners emerge. If you were a company built on stores, you moved to create a seamless online and digital experience that may lead you to a store, but your order could get dropped off at your front door or shipped from a central warehouse. Two-day delivery was cool; how about 20-minute delivery? For the digital native players, they realized at some point they needed local stores to provide personal services, convenient options or perishable goods. All retailers are being rewarded as consumer spending has been on a tear even through the pandemic. The winners make it so easy to spend money and get stuff that the only loser here is my bank account. 

The point is, every time we get rid of the "vs." and insert "and," we grow the marketplace. The insurance industry could benefit greatly by partnering to build an agent and digital ecosystem. 

Wait, did anyone ever ask the customer? 

Funny how we can solve everything with solid academic theories and forget to ask the customer. This is exactly why this is my last section: to punctuate that our evolution as an industry needs to put aside our intellectual arguments and put the customer at the forefront of our decisions. 

If we build our industry to create more value, be more interesting, be more accessible, then the overall spending for our products will increase. How many of us have used this statement, “for the cost of one Starbucks a month, you can cover your family,” and then nothing happens? This needs to change because that protection is more important than a cup of coffee, yet many people still remain without adequate insurance protection. 

We all have work to do. The start of this happens when we replace "vs." with "and." 

We can get back to our most important promise and be financially sound enough that no matter what happens we hold true to our promise to our customers.


Bill Walrath

Profile picture for user BillWalrath

Bill Walrath

Bill Walrath is currently working as an adviser in the insurance space for technology and is building a unique product offering for property owners.

He.has more than 25 years of experience managing markets across the U.S., bringing together agents, product teams and underwriting to drive profitable growth. He has lived and worked with companies in California, Michigan, Illinois, Oregon, Ohio and Texas. Working with thousands of independent agents, he has a track record of growing distribution networks and leading large teams.


The Opportunity of a Lifetime

The insurers that will pave the road to the future will be those that figure out to seamlessly serve customers by matching each product to the right distribution channel.

workers

My family recently purchased me a coffee cup with the slogan, “I’m not always sarcastic, sometimes I’m sleeping.” And I get really sarcastic about the notion that insurers put the customer first.

What do customers want from insurance? 

That is a pretty broad topic, so let’s explore. Each day, we interact with products that are customary, or quite simple. We are familiar with them and therefore can make decisions with the use of minimal information and help. On the other hand, there are products that are unfamiliar and complex and even if we work with them quite frequently are still confusing. Take the purchase of my internet service vs. doing my taxes. Although there are a number of different bundles and options for the internet, I will quickly settle in on the right service for me. When I do my taxes, even though this is an annual occurrence, I still seek the advice of a professional because my circumstances may change and the array of options is confusing. 

Now consider insurance. We have some products like auto insurance that act a bit more like the internet service provider. Once I am comfortable with my limits of coverage, I likely renew each year without fail unless the provider does something that I question, like increasing rates. On the other hand, if I were to purchase commercial insurance, there are more moving parts -- my business may expand, payroll may change, I may add vehicles or I ay enter into a new service or product line. Commercial insurance takes some advice and hand-holding to ensure the coverages are appropriate and aligned with my expectation. 

Customers want delivery that meets their needs. That delivery is what we call distribution. Whether through an agent, directly online or via a call center, distribution must bring order to chaos. 

If we are going to make a breakthrough, where do we start? 

First, we need to step back and evaluate the go-to-market strategy. If you do not have a GTM strategy or it is “do what we have always done,” then now is the best time to review. 

Each product in the insurance industry can be categorized based on two attributes that determine how you should take it to market: 

  • Product complexity 
  • Margin

A product that has high complexity and a high margin can and should be supported by an expert who can answer questions, customize coverages and explain the product choices. Contrast that with a product that has low complexity and low margin. This can and should be digitized. 

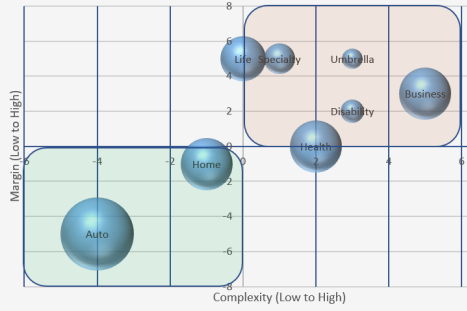
The chart below depicts a simple view of the marketplace in terms of complexity, margin and market size. You could analyze your own offerings based on a qualitative and quantitative approach considering your own portfolio or considering the future growth opportunities facing your organization. 

See also: How to Achieve Customer Ownership

Product Comparison of Margin v. Complexity by Line of Business 

There is a linear path that exists in charting these products, suggesting that all lines of business fundamentally are either low-complexity and low-margin or high-complexity and high-margin. On the lower-left portion of the chart, competition keeps margins low, which means keeping complexity low. On the top right, you see products where competition may be more fragmented and where pricing advantages are not the only determining factor in taking market share. 

How do you put this analysis into action? 

First, plotting your own performance is key. Second, understanding your starting point and determining the important priority for each product will help you invest in the right change for the future. For instance, for a low-margin, low-complexity product like auto insurance, you may want to use agents today, call centers in the intermediate term and digital channels in the future, while high-margin, high-complexity products like commercial insurance would be taken to market by agents, whether now, in the intermediate term or in the future. 

A few important points to consider: 

  • Agents and companies that do not perfect digital selling for low-margin/low-complexity products will suffer in the future. 
  • The idea that agents will disappear is false. 
  • Incumbent companies should evolve their distribution to obtain customers digitally and seamlessly refer these customers to professional agents to upsell and cross-sell. Insurtech companies need to consider this, as well, and the potential to partner with agents in the future. 
  • Companies that have agents need to support their agents in moving to more profitable products, opening new market opportunities and finding ways to compensate for the value they bring to the customer journey. 
  • Finally, decisions about change are guided by alignment with customer expectations first and further supported by financial success. 

The road to the future will be paved by companies that understand that customers want a seamless purchasing experience for all their insurance products and are able to design a strategy that meets them where and how they expect to purchase important coverages.


Bill Walrath

Profile picture for user BillWalrath

Bill Walrath

Bill Walrath is currently working as an adviser in the insurance space for technology and is building a unique product offering for property owners.

He.has more than 25 years of experience managing markets across the U.S., bringing together agents, product teams and underwriting to drive profitable growth. He has lived and worked with companies in California, Michigan, Illinois, Oregon, Ohio and Texas. Working with thousands of independent agents, he has a track record of growing distribution networks and leading large teams.


An Overlooked Target for Modernization

Maintaining compliance requires manual, repetitive and error-prone processes, handled by small armies of well-compensated experts -- but many can be automated. 

tech

While the insurtech movement has taken hold and insurers are rushing to automate core processes, a labor-intensive cost center ripe for modernization is often overlooked: regulatory compliance.

Heavily regulated industries, such as finance and insurance, must grapple with a compliance landscape that is fast-changing and chaotic. Without automation and modernization, compliance change management swallows up resources at an alarming rate. Maintaining compliance in these industries requires many manual, repetitive and error-prone processes that must be handled by small armies of well-compensated experts.

To stay current, compliance officers must keep up with not only regulatory changes from multiple agencies but also the enforcement patterns that illuminate on-the-ground realities in a range of jurisdictions, from local municipalities all the way up to international regulatory bodies. Without automation, finding, reading and interpreting relevant regulatory changes and numerous enforcement actions is a cumbersome, manual, labor-intensive process that shifts the attention of skilled specialists away from higher-value projects. 

Regtech solutions automate many of those core compliance processes, so skilled experts are freed to apply their skills to initiatives that better leverage their expertise to benefit the bottom line. 

How regtech complements insurtech

For organizations already benefiting from insurtech, an obvious next step in their digital transformation journey is to investigate complementary solutions, such as regtech, which rely on similar innovations. 

Insurtech and regtech solutions  have evolved along parallel paths. In fact, some insurtech solutions include basic compliance features and vice versa. 

Regtech leverages many of the same core technologies (SaaS, ML, predictive analytics) as insurtech to deliver operational efficiencies, cost savings and better overall user experiences. As the name implies, regtech also plugs important gaps, such as automating regulatory change management, flagging relevant enforcement actions and delivering actionable insights to various stakeholders throughout the organization in near-real time. 

As with insurtech, regtech solutions are also expanding rapidly. According to ResearchAndMarkets, the global regtech market grew from $6.26 billion in 2020 to $7.9 billion in 2021, a compound annual growth rate (CAGR) of 26%. The market research firm predicts that the sector will continue to expand at a CAGR of 24% for the next few years, reaching $18.89 billion in 2025.

The steep cost of legacy anchors

However, insurtech and regtech are both still early in their adoption cycles. A major reason insurance firms are often slow to adopt new technologies is the need to support legacy software that was designed for a different era, one when cloud computing was not common and software was sold as a product, not a service. Many organizations believe that the change costs are too high to abandon these systems. 

Nothing could be further from the truth.  

Cloud/SaaS-based solutions have given businesses across the economy the opportunity to transform various cost centers in their businesses by optimizing processes, automating tasks that can be handled by new solutions, such as ML and AI, and adopting best-of-breed SaaS solutions that deliver fast ROI, turning capex into opex.

Legacy, pre-cloud systems, in contrast, are usually deployed on on-premises infrastructure that requires high up-front costs, steady maintenance overhead and steep management costs. These systems constantly burden IT teams with a range of labor-intensive, repetitive, error-prone tasks that are better and more affordably handled by technologies such as ML and AI. 

Most regtech solutions, just like insurtech, are built from the ground up as cloud-native, whether public, private or hybrid, and to be consumed as SaaS. With streamlined deployment cycles, intuitive user interfaces, automated workflows and application programming interfaces (APIs) that connect related solutions, regtech software eliminates errors, streamlines the compliance lifecycle and frees compliance officers from time-consuming, error-prone, manual processes.

Why 2022 is the right time to modernize compliance. . . before it’s too late

While regtech can help insurance organizations modernize, optimize and eventually automate many compliance processes and workflows, adopting regtech isn’t a simple bolt-on to insurtech platforms, and insurance companies will need to carefully manage the transition to automation-driven compliance.

A September 2021 study by McKinsey forecast the top 10 technology trends that are poised to disrupt the insurance industry in the near term. Of these, McKinsey zeroed in on five that will have the biggest impact on insurance: AI, distributed infrastructure, future of connectivity, next-level automation and trust architecture. 

All of these next-generation trends are converging with today’s best-of-breed regtech solutions, which are powered by AI and built on distributed cloud infrastructures. Regtech software also connects to related business solutions through open APIs, automates cumbersome tasks like tracking regulatory changes and should easily integrate into zero-trust architectures. 

In contrast, insurance organizations that continue to rely on ad-hoc workflows and outdated compliance software risk lagging behind competitors that are quicker to modernize. Lagging businesses also face higher risks of falling out of compliance and getting penalized for it. 

With regtech adoption on the rise and the regulatory landscape growing increasingly complex, 2022 is the year to get serious about modernizing compliance, so you can transform one of your organization’s cost centers into a competitive advantage. 

How to evaluate regtech providers: seven questions to ask

While insurtech and regtech have much in common, the two emerging technologies also differ in important ways. Here are seven questions to ask providers that will help you evaluate whether their solutions will meet your organization’s goals: 

1. How will your solution integrate with complementary solutions  we have already deployed, such as insurtech? 

Integrating insurtech with regtech will help you mitigate risks. For instance, many insurance companies are eager to leverage insurtech to deliver new products, but what happens if those products run afoul of existing (or pending) regulations? 

Ask regtech providers how data will be shared between the solutions and then throughout the organization, so business decisions do not undermine compliance.

2. Do you have reference customers in our sector of the insurance industry? 

Some regtech providers may offer solutions for your industry that are retrofits of solutions designed for other industries, such as healthcare or financial services. While some features may port easily to insurance, others may not. 

Ask vendors to provide references of customers from your market sector, so you understand any challenges that may be specific to your industry. 

3. What’s a realistic timetable for ROI?

Every SaaS provider promises low total cost of ownership and fast ROI, but don’t mistake this for table stakes. Those claims are often inflated. Ask providers to calculate your ROI. . . and then ask them to show their work. 

4. After the transition, where do our existing compliance experts fit in? 

Many fear that AI and automation could eliminate skilled positions that really shouldn’t disappear. Modernization shouldn’t destroy organizational strengths like institutional knowledge and the kind of nuanced subject matter expertise that AI cannot duplicate. 

Ask regtech vendors for a before-and-after picture. How will adopting regtech affect your existing compliance team, and how will the day-to-day work of compliance experts change?   

5. What happens if we decide to switch to a competing provider in the future? 

One of the biggest drawbacks of the cloud/SaaS era was supposed to be a major strength: data portability. In theory, data should be easy to move from one system to another and from one vendor to another if you decide to change, but proprietary software layers often prevent this. 

Ask providers about data ownership and find out how difficult it is to export your data. 

6. How do you protect data and control access? 

Automated compliance won’t deliver ROI if a data breach hits your organization. Be sure to have your security experts grill providers on their various access control and data protection features. 

7. Does your regtech solution satisfy regulators? 

Regulators will have their own priorities, and regtech solutions should have built-in features to address them. Be sure to ask providers about areas that regulators emphasize, such as transparency and the ability to repeat processes and audit data trails.


Kayvan Alikhani

Profile picture for user KayvanAlikhani

Kayvan Alikhani

Kayvan Alikhani is co-founder and CEO of Compliance.ai, where he leads operations, strategy, sales and marketing.

He is a leader in industry strategy and serves as a representative on various industry alliances and boards, including FIDO ( Fast "IDentity" Online) Alliance. Alikhani is also CEO and co-founder of PassBan (acquired by RSA), a company focused on mobile identity assurance.

He has a strong background in leading strategy and creating security identity for mobile solutions in VOIP-based (voice over internet protocol) networks. In addition to PassBan, Alikhani has several other ventures in his portfolio, including co-founding then serving as CTO at BeNotified, a cloud mobile communication service provider. He also serves as co-founder of AVIRNEX, a cloud-based, enhanced-fixed and mobile communication service provider.

April Focus: Automation and RPA

ITL FOCUS is a monthly initiative featuring topics related to innovation in risk management and insurance.

This month, we're focusing on Automation and RPA

a header graphic reading "ITL FOCUS: Automation and RPA April 2022". It is white text on a blue background next to a photo of a man holding a tablet connecting to machines.


FROM THE EDITOR

Sometimes, innovation takes time. 

Some 30 years ago, I wrote an article for the front page of the second section of the Wall Street Journal that declared a revolution in forms. We were far enough along in the personal computer revolution that software companies were coming out with products that would let users fill out forms on-screen, speeding the process and eliminating the errors that occurred as someone had to interpret people's handwriting. Even more magical, the spread of local area networks meant that information could flow straight from my screen into a corporate database, with no never to ever print the form and have someone re-enter the data.  

Everything I wrote was correct, and forms did take a major step forward, but, here we are three decades later, still drowning in forms. And the insurance industry is Exhibit A.

I realize that, in many ways, the need for clarity and standardization means insurance has to think in forms -- certainly, many regulators do. But there is so much inefficiency tied up in filling out forms, processing them and gathering them for use in underwriting and claims that I've been trying as hard as I can for years to drive people to consider the sort of automation that is the ITL Focus this month. 

As you'll see from this month's interview with Nigel Walsh, a longtime consultant who is now managing director, insurance, at Google, he's pretty much moved beyond automation. His thinking is: Why automate a process when you can do away with it entirely? 

He does acknowledge that automation can deliver loads of incremental gains, and the six articles I've highlighted this month lay out a number of possibilities for you to consider. 

The whole experience with automation reminds of two lines I use often (apologies, if you've heard them before). 

One is a Silicon Valley bromide: Never confuse a clear view with a short distance. That's something I did with forms and do all the time -- even though I know to never confuse a clear view with a short distance.

The other is one I came up with on my own: Let's burn all the fax machines. They, to me, are such a symbol of antiquated technology and of the inefficiency in our industry. Let's automate all of them out of existence, then turn our attention to doing away with all the forms that we use fax machines to send back and forth.

I may have been much too early about expecting forms to go away, but I'll eventually be right. Really, I will.


Cheers,

Paul

INTERVIEW WITH NIGEL WALSH

As part of this month's ITL Focus on automation and RPA, we spoke with Nigel Walsh, managing director, insurance, at Google, about how far automation has progressed -- and about how to think about what comes next. Why automate a form or a process when you can simply eliminate it? 

""I think things have played out quite well. Bit by bit, area by area, division by division, process by process, things have improved. Adoption of automation throughout insurance businesses increased, without question, and there's no end of processes left to go, I would guess.""

-Nigel Walsh
Read the Full Interview
 

READ MORE


Stocking Caps and
Insurance

How Amazon’s approach to selling
the former can help you move
more of the latter.

Read More

Insurers Turn to Automation

When automation is a core
technology, transformation can
occur at speed, meaning faster
return on digital investment.

Read More

What’s Beyond Robotic
Process Automation

RPA is a primitive technology and represents only a small part of
what’s needed to scale and allow
for straight-through processing

Read More

Tipping Point for Claims Automation

While virtual estimating for
auto claims—using photos in place
of a physical inspection—is not
new, the pandemic has made
it the preferred method.

Read More

How to Automate Your Automation

It's crucial to take a top-down a
pproach, to get a bird’s-eye view
of all of processes, to be able to
see which will benefit from RPA.

Read More

How Automation Adds
to Need for Humans

Automation does not mean industry professionals will be left out in
the cold.In fact, the opposite may
be true.

Read More


FEATURED THOUGHT LEADERS


View all ITL FOCUS topics
 
Share Share
Share Share
Tweet Tweet


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

An Interview with Nigel Walsh

As part of this month's ITL Focus on automation and RPA, we spoke with Nigel Walsh, managing director, insurance, at Google, about how far automation has progressed -- and about how to think about what comes next. Why automate a form or a process when you can simply eliminate it? 

A graphic reading "an interview with Nigel Walsh" it is white text on a dark blue background and a image representing automation

ITL:

When I was preparing for this month’s ITL Focus on robotic process automation (RPA) and the broader possibilities of automation, I went back and looked and saw that two of the five most popular articles we’ve ever published on the topic were ones you’d written. I thought, I haven’t talked to Nigel in a while, not since your move to Google, so I decided to give you a try and am delighted to get to chat a bit. 

Maybe we can start here: When you were writing these pieces a few years ago, it seemed that automation had great promise. Now that we’re some years on, how has that promise played out?

Nigel Walsh:

I think things have played out quite well. Division by division, process by process, things have steadily progressed. Adoption of automation within the insurance industry has increased, without question, and there are still plenty of processes left to automate.    

I always talk about evolutionary and revolutionary steps. I think RPA falls categorically into the evolutionary mode. We can make everything better than it was. In the cycling world, people will know this as marginal gains. Break it all down, improve it by 1% and rebuild it all.

ITL:

What would revolution look like? And is that possible?

Walsh:

Revolution would ask, Why are we doing this in the first place? Why do we need it? Can we remove it entirely?

If you're automating a process, you’re grabbing data to fill out a form that was always used. Maybe 20 years ago that was a form on paper for an agent or broker or customer. But why automate that old form? I would challenge us to ask, “Why can't we skip the form and automate the whole process, end to end?”      

Artificial intelligence has helped us understand our workflows. Think about your phone with all the shortcuts. Artificial intelligence (AI) says, actually, Paul, based on your location and the time of day and these three other factors, I know what you want to do, and I’ll get you right to it. Our ability to learn and predict quickly has improved exponentially. 

ITL:

So, you can go straight from whatever is going on to whatever the result ought to be.

Walsh:

The initial achievement of automation was to make the machine go faster and be more efficient. But what if there's a new and better way to do things? I’m not sure we pause enough and ask or challenge this. You can argue that automation is still horizon one thinking when we could be looking at horizon two or three.

ITL:

Do you know the name Mike Hammer? He was an MIT professor who pioneered reengineering in the 1980s and 1990s. He used to caution against paving the cow paths because he lived with the problems that were created in Boston when city officials did just that.  In the 1900s, city officials started just paving roads where cows had created paths over the centuries. He said we have to imagine the new – the superhighways or air travel or whatever – rather than just do a better job of what we’ve always done.

Walsh:

Exactly that. Otherwise, all we've done is make faster horses. As Henry Ford said, if we had asked people what they wanted, that’s what we’d have ended up with.

ITL:

Just the other day, the U.S. National Highway Transportation Safety Administration ruled that a car no longer had to have a steering wheel, gas pedal, brake pedal, etc. to meet safety criteria. So, now, we can have cars that don’t just look like they always did, without someone in the driver’s seat, but can reinvent the interior of cars entirely. 

Do you have an example or two of how the more revolutionary approach might work in insurance, of what could be entirely done away with rather than simply automated?

Walsh:

We’ve been talking for years about how you move from reactive to proactive. I think we are at that point now when we have the tools and the datasets available to make that shift. 

When you think about the whole process of insurance in the first place, it's the collection of data to assess risk, assign a price to it and return the assessment to the customer. But, even with all the information that is available, the orchestration is still being assigned to a human, even if it could be automated. A good example is parametric insurance. If we’re in a commodity world and there is an outage or breakage, you can automatically restore the customer to the pre-loss condition.

You can also change the business model of insurance. Look at folks like Laka, which sells insurance for cyclists. They set a cap on your premiums, but, if there are no claims or lower claims than expected, you pay less.  Why don't more companies do this?

ITL:

In terms of automation of the evolutionary variety, are there particular areas where you've seen successes or have seen failures?

Walsh:

I think you can apply automation to just about any area and see benefits. It’s not hard to take your 10-stage process and automate elements of it. But automation of just the arms and legs is unlikely to give you the benefits or outcomes you really need. 

ITL:

A few years ago now, I helped three senior partners at a big consulting firm write a book on how to innovate on strategy, and one of the major points they made was that operational efficiency can generate strategic advantage, even though it tends to be treated as separate from strategy discussions. They said they thought insurers should be able to take out 50% of their operating costs and rather quickly. Does that sound realistic? And, if so, how far along do you think insurance is on that trip?

Walsh:

Using Google Cloud, Ki Insurance built a Lloyd’s syndicate driven by algorithms. That’s a business traditionally grown by experienced executives, but Ki generated some $400 million in premium in its first year. A lot is possible when technology is an integral part of the business strategy.      

ITL:

Thanks, Nigel. Always great talking with you.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

The Power of Ecosystem Transformation

The ecosystem model empowers technology departments by getting them closer to the end customers, positioning them as supporters of business strategy.

digital

The constraints of insurers' legacy technology have become more obvious in the days of digital transformation. These systems can no longer support customers’ demands for speed of change and omnichannel experiences. 

Enter the era of ecosystem transformation. 

Legacy systems create siloed processes, multi-generational technology landscapes, limited point-to-point external integration and the lack of a comprehensive customer view across various solution offerings. But, within a broader partner ecosystem, technologies such as cloud, software-as-a-service (SaaS) and low-code allow carriers of all sizes to be more efficient, productive and modern and – ultimately – move closer to customers.

When technology and business operations are closely integrated across the entire insurance value chain, carriers can innovate in ways that matter most to their customers.

Connecting Emerging Technologies 

In an increasingly crowded space like insurance, and with the growing speed of digitization changing customer expectations, carriers need to constantly reassess customers’ needs and rethink the value they can bring. 

In the recent past, carriers have begun to diversify their lines of business and to leverage new technologies such as SaaS, artificial intelligence (AI) and machine learning (ML) to streamline the underwriting and claims processes. 

SaaS is reshaping how carriers deliver their services. From infrastructure, to solution offerings, to services and support, SaaS’ real-time nature allows IT teams to work more efficiently, building and testing rapidly and iterating faster than ever before, building a more nimble environment for insurance carriers. As a result, customers can get the latest capabilities and solution updates in a fraction of the time. 

In fact, in our Driving the New Standard of Insurance global benchmark survey conducted last year, over one-third of respondents told us high operating costs are the biggest obstacle to profitable growth for insurance businesses. 

Carriers that take this ecosystem approach will find themselves moving away from needing to upgrade constantly. This helps reduce technical debt and minimize both technology expense and burden. The configurability and malleability of SaaS brings speed, and it streamlines processes and workflows to benefit carriers in the long run. 

Speed, Speed, Speed! – Rewriting the Rules of Insurance Operations

Insurance has always been about data. We now have a lot more of it, placing a premium on analytical capabilities. This has strained technology systems – and, eventually, when the data dictates required changes to product, it can be a struggle to achieve desired product development outcomes with outdated systems. 

To address this challenge, carriers of all shapes and sizes are beginning to make substantial investments in SaaS-enabled ecosystems, enabling operational agility and efficiency in the product development and deployment cycles. 

How could this be done? An insurance ecosystem brings together a close integration of analytics, computing, data, mobile and security from different sources and partners, allowing even small and medium-sized carriers to benefit from the nimble infrastructure and emerging technologies. This gives them a leg up to compete in the fierce insurance marketplace, especially in the lines of personal auto, homeowners and small commercial.

When built into carriers’ core systems, this approach supports carriers’ business strategy with the ability to enter new markets, and deliver new products more effectively and efficiently. This allows insurance CIOs and IT professionals to focus on the overall business operations and concentrate the resources on product innovations to address customers’ evolving needs.

See also: Designing a Digital Insurance Ecosystem

2022 Keywords in Insurance – The Experience Economy and Personalization

Customer expectations have changed drastically in the past two years. An omnichannel experience is a key driver in customers making insurance purchase decisions. Fast-paced insurtechs and startups offer digital customer experiences and convenience that many carriers aspire to.

The delivery of experiences includes multiple layers – from data and technology to partners and ecosystem. Getting this right requires aligning these different layers to determine how they can be optimized for customers.  

When it comes to data and technology, insurance is at a unique position where customer data is readily available through claims history and the underwriting processes. How data is used is arguably the most critical factor in how well a carrier meets customer expectations and improves the overall process. Data management and analytics tools  can help carriers take advantage of new customer touchpoints and make sense of what customer data is telling them.

Partners and ecosystems, on the other hand, help fill the gaps of insurance offerings. By leveraging the innovative products and services from partners and external resources, insurance companies are able to improve claim accuracy and reduce processing time. This helps improve the customer experience.

However, the increased need for digital engagements doesn’t mean that the role of traditional agents is eliminated. Agents, carriers and partners work seamlessly together as a team with each being a critical element of the insurance ecosystem. 

Final Words

The ecosystem model is the way forward for the insurance industry. 

It empowers technology departments by getting them closer to the end customers, positioning them as supporters of business strategy as carriers enter new markets or reach new customers. The model also enables technology departments to play an integral role in the efficient and effective delivery of new products, allowing companies to move with incredible speed and agility in this crowded space.


Nag Vaidyanathan

Profile picture for user NagVaidyanathan

Nag Vaidyanathan

Nag Vaidyanathan is chief technology officer at Duck Creek Technologies.

He is responsible for the execution of Duck Creek Technologies' current and emerging product road maps while ensuring the adoption of proven software development patterns, architecture standards and frameworks.