Download

ML Improves Life Settlements

Advancements in machine learning are changing the landscape of the life insurance industry, making life settlements more accessible to policyholders.

Abstract drawing over a photo of a human head

The life settlement is a legal, regulated process for liquidating life insurance. Unfortunately, the regulations in place don't fully address the culture of mistrust in the industry. That culture is an outcome of the traditional process: Life settlement cases have historically been managed behind the scenes, with each stakeholder having access to only some of the case details. That veiled environment allows providers, agents, advisers, investors, brokers and policyholders to work at cross purposes.

Complicating matters more, the amount of funds available to buy policies has exploded in recent years. As more money circulates in the industry, dishonesty and deception remain key issues that ultimately work against all stakeholders. 

However, advancements in machine learning technology are changing the landscape of the life insurance industry, making life settlements more open and accessible to policyholders than ever before. 

Underlying mistrust and lack of transparency 

The traditional life settlement auction process has pockets of secrecy. Insureds, agents, advisers, life settlement brokers, life settlement providers and life settlement funds rarely have access to the same set of information. Brokers typically act as gatekeepers, with the freedom to share or withhold details as they see fit. That naturally creates a lack of transparency and fosters mistrust. 

Some of that mistrust is warranted. Unethical brokers will award cases based on relationship rather than bid size. That's a clear disservice to the insured, who assumes the broker is working to negotiate the highest selling price possible. In these cases, the broker must intentionally limit the auction information provided back to the insured. The insured certainly won't see the highest bid -- and also may not know how the winning offer was calculated or where it came from.  

Fortunately, these problems are solvable with technology. Life settlement auction platforms create transparency by giving all stakeholders access to the same information. With case details and bids accessible electronically, the auction becomes unbuyable. Whoever submits the highest bid wins the case, period. There is simply no room to make a backdoor deal, which ensures a fair process for everyone involved.

See also: Adding Transparency to Life Settlements

Poor communication

Poor communication, whether intentional or by accident, worsens the lack of transparency in the traditional life settlement process. Layers of hidden fees charged by providers or brokers cut into the insured's proceeds -- often, without the insured's knowledge. 

As an example, a broker might deliver a net offer to the insured, with no breakdown of the gross selling price and the broker's commission. As well, providers may put in offers net of their fee, essentially hiding those fees from funders.

Policy metrics can be another area of confusion. Actuarial firms, responsible for valuation, may be inconsistent on key metrics, such as life expectancy. That misalignment of data works against providers that are trying to put their best offer forward to win the deal. 

Again, technology can solve for missing or inconsistent data. Life settlement auction platforms state valuation metrics upfront so all parties are working from the same set of numbers. They also require families to sign off on commissions for every transaction -- ensuring full transparency into the fees paid out of sale proceeds. 

Reinventing the life settlement market 

Until now, it took months for financial professionals to understand and identify which life insurance policies have value and provide the proper guidance. A primary cause for this is cost of insurance (COI) data being fiercely protected by life insurance companies. COI incorporates several variables, such as when the insured purchased the policy, how old they were when they bought it, their health at the time and the policy type, which determines how much each policy is worth.

Thanks to machine learning technology, the future of the life settlement industry is bright. Financial professionals can now use a life settlement calculator to evaluate their entire book of clients in a matter of minutes and identify which would benefit from a life settlement. Technology makes the life settlement decision process easier than ever so advisers can understand their client's full financial picture and provide the right guidance, especially during times of economic distress. 

The life settlement industry is growing 34% per year on average and is expected to be worth $212 billion by 2028. Each and every American deserves to know the true value of their assets so they can make the best decisions for themselves and their families. With AI-powered technology, life settlement valuations are now a far more accessible, honest process for more policyholders nationwide. 

Lucas Siegel

Profile picture for user LucasSiegel

Lucas Siegel

Lucas Siegel is the founder and CEO of Harbor Life Settlements, a life settlement company that is dedicated to helping seniors and the terminally ill sell their life insurance policies, and Harbor Life Brokerage, a life settlement broker.

A Surprising Opportunity

Agent and Brokers Commentary: September 2022 

digital insurance image

As the momentum for "embedded insurance" has built in recent years, I assumed it would mark yet another attempt to cut agents and brokers out of the sales process. So I was intrigued when, in this month's interview, the director of agency accounts at Clearcover suggested embedded insurance could actually mark an opportunity for agents and brokers.

Clearcover's Kaitlyn Taylor said that the insurtech is working to help agents and brokers remain part of the process even if someone who is, say, buying a car is prompted to purchase auto insurance while at a dealership. The buyer could be presented with a QR code, for instance, that would steer the insurance purchase through an agent, or some other link could be provided. 

Lots of details remain to be worked out, so the customer could both get the convenience of buying insurance while it is top of mind, without having to reenter all sorts of personal and financial information, and get the comfort of dealing with an agent on any questions, both during the sales process and during the relationship that follows. Commissions will, of course, have to be resolved, too, based on who gets credit for initiating the sale and who services the customer and policy from then on. 

So, Taylor cautioned that the work at Clearcover is in its very early stages. Still, I found the notion intriguing.

People keep trying to disintermediate agents and brokers... and keep failing.

Cheers,

Paul


P.S. Here are the six articles I'd like to highlight this month for agents and brokers:


You May Be Lighting Benjamins on Fire

You are passing up maybe $1,000 in commissions per client if you aren't cross-selling instant-issue term life insurance policies that don't require a medical checkup.

Why Brokers Have a Leg Up in Insurtech

While insurtechs are struggling, established brokerages have deep industry knowledge and solid businesses from which to build and evolve technology solutions. 

5 Keys to a Low-Stress Work Environment in 2022

Stressed employees are less engaged and have lower productivity - and some may even left their job. Here is how to promote a low-stress work environment.

Fried Chicken and Customer Loyalty

Customer loyalty, and thus retention and profitability, isn’t driven by cheap prices, AI bots, big data or nifty phone apps.

2 Areas of Focus for Distribution

Distribution partners are focused on two key areas – user experience and ease of doing business – and are looking to work with insurers.

Power of Partner Ecosystems

Insurers seem stuck in traditional channels rather than expanding channel choice and reach, meeting customers where and when they want.


Paul Carroll

Profile picture for user PaulCarroll

Paul Carroll

Paul Carroll is the editor-in-chief of Insurance Thought Leadership.

He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.

Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.

An Interview with Kaitlyn Taylor

In this month's interview, Kaitlyn Taylor, director of agency accounts at Clearcover, talks about helping agents be more confident about their opportunities to take advantage of technology and serve customers.

Kaitlyn Taylor banner

ITL

There was a time, not so long ago, when the mantra of the insurance experts was disintermediation. Agents and brokers? Let's get rid of them. But agents and brokers not only survived; they're thriving, to the extent that a successful insurtech like Clearcover has someone—that would be you—focused on nurturing relations with them. Could you start us off with a bit of perspective on Clearcover's thinking?

Kaitlyn Taylor:

Yes, many thought that agents would be old news pretty soon, and the pandemic probably heightened that belief, but we don't think that's the case. That's why we launched the independent agent channel starting in 2019.

There are some  customers who have strong digital desires but who rely on agents for their insurance needs, and we need to make sure we're paying attention to those people. Agents have such a plethora of knowledge, not only about insurance, obviously, but also about customer expectations. We want to ensure that they can continue doing what they’re doing by embracing technology that we can bring them.

ITL

What does that technology look like?

Taylor:

D2C [direct-to-consumer] companies brag about how quickly you can quote and bind by yourself online, while talking about how you may wait on hold for an agent, or your producer is out of the office and you wind up in a long, drawn-out process. We feel like we have the responsibility to help speed up this process for agents so they're just as competitive as if their customers were going to D2C. And our AI makes decisions in a tenth of a second on whether a customer is a good fit for our products.

There's also the nitty gritty stuff in the agency. It's important that we're integrated with the agency’s CRM [customer relationship management], so information is being transferred from our database to theirs. We also, in general, need to help agencies speed up their processes so they can keep up with customers' expectations.

ITL

How far along do you think you are in the process? And what would be the next step or two that you could take to make the life of an agent easier?

Taylor:

More and more agents are hearing the term "embedded insurance," and we want to help agents make sure they can participate. We want to provide them with the APIs [application programming interfaces] or QR codes so they can tie into referral networks and make it easy for customers to click on a link and get a quote. We're hearing a lot about embedded insurance.

We also need to help agents adapt to new technology. At the end of 2021, we did a survey of agents—they weren't necessarily Clearcover agents—and found that 90% said they had to change their technology practices to keep up during the pandemic. Okay, that's not too surprising. But 67% said they still lacked confidence in their ability to keep up with technology. That was really surprising to me, because they had just gone a year and a half fully living in a techie, probably virtual environment.

When we have one-on-one conversations with agencies, we try to give them confidence, and we talk them through how things work in the background, to remove any concerns. For instance, we push hard to make sure customers download the mobile app, where you can digitally sign your documents. And I think some agents worry: What happens when a customer downloads the Clearcover app? Do I lose some control over the customer’s experience and their insurance journey? So, we assure agents that we’re only going to feed, positively, into the journey.

We also educate agents. My favorite example about the power of a mobile app is a personal one. I just had to update my banking information with another carrier I will not name. They sent me a secure PDF that I could use to provide the information, which they would then put into their system. That made me wildly uncomfortable. And we know from our own research that a big reason that customers want to download the mobile app is just to put in their own banking information.

With a mobile app, documents are sent to the customer’s email. That's one less thing for the agent to worry about. And now we have a permanent digital file of it. The mobile app also means they're already equipped with the ability to submit a claim and with the ability to update certain things about their policy on a Saturday morning when maybe the agency isn't able to.

ITL

Are there other technologies that you think are especially important that you're going to lean into?

Taylor:

We've been using AI since 2020 to help agents find quality long-term prospects by predicting if a customer is a good fit for them and us.

We've also focused a lot on speeding the claims process, so agents can instead direct their attention to generating more business in their agency. Like a lot of carriers, we have a lot of data on claims, so we determine if one is eligible for an expedited payment. We've paid a claim in as little as seven minutes from the time we received it.

ITL

How about digital payments?

Taylor:

Yes. And here's a cool thing: We now offer Uber credits to eligible customers if they don't need a rental car right away. I, myself, am currently in a rental car because of a claim that happened in April, and the parts just now came in. So, I would be a good case: You could give me the Uber credits in April, but I'm not going to use them until August.

ITL

Last question: What would you say most makes Clearcover stand out from your competition?

Taylor:

I think ease-of-use is where we have a leg up, especially if we have an agency that's particularly passionate about us.>

ITL

I'm a big fan of ease-of-use. Good luck, and thanks for taking the time.


Kaitlyn Taylor

Kaitlyn Taylor

Kaitlyn Taylor is the director of agency accounts at Clearcover, the tech-driven car insurance company. She currently oversees the distribution of Clearcover's product through Clearcover's growing independent agency channel.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

Payment Processes Must Be Simplified

Insurance companies pursue digital transformation and customer experience optimization but overlook some of the fundamentals. This is exemplified by payments.

Person holding credit card in front of a laptop

The insurance industry continues to aggressively pursue digital transformation and customer experience optimization but is still overlooking some of the fundamentals. This is exemplified by payments, which remain fragmented and needlessly complicated.

A key goal of digital transformation is to provide customers with streamlined, consistent user experiences. PYMNTS, a data, news and insights firm, reported that 67% of insurance carriers view digitizing payments as an important part of their digital upgrade plans. Yet large brokers and insurance carriers may have upwards of 40 payment providers with potentially hundreds of payment contracts—each with different reporting, pricing, capabilities and accounting interfaces. While this creates a challenging environment, improving this part of the business doesn’t require a significant investment. 

Whether you’re a carrier, broker, MGA or just about any entity in the insurance ecosystem that accepts and makes payments, it’s important to prioritize your payments strategy and create a unified experience to better meet the needs of customers and internal teams. 

Domain Expertise Is Key

Why have payments in insurance become so fragmented and inefficient? There are hundreds of payment providers, but very few have the insurance domain expertise and offer the services to adequately serve a complex, regulatory-heavy B2B2C industry like insurance. Oftentimes, they only provide an application programming interface (API), forcing carriers or brokers to build workflows or other capabilities on their own and take on the responsibility of maintaining highly customized integrations and interfaces. Further, some payment processors enlist third parties to underwrite transactions, which can lead to clunky customer experiences like having to re-enter credit card information and navigate multiple screens. Or, some brokers might rely on multiple payment processors, each offering different ways to accept premium payments.

For these reasons, it’s crucial to work with payment providers that have a deep understanding of insurance management systems and offer core technology and services such as payments underwriting, credit approvals, fraud prevention, administration and policyholder support.

On the operations side, insurance companies using multiple payment providers and workflows invite inconsistent pricing and reporting. For example, agency branches with different payment processors will pay varying fees for the same type of transaction. In other cases, outsourced billing firms have software on the front end but humans performing manual invoicing on the back end, which leads to higher transaction overhead. 

Consolidating payment processing helps standardize the workflow, the reporting and the costs. Of those surveyed in the PYMNTS report, 64% say those upgrade plans are motivated by their desire to be less dependent on paper checks, and 53% are looking to reduce their internal expenses. And the cost savings can be staggering. Bank of America has estimated that paper checks can cost approximately $4 to $20 per check based on the check price and postage, which doesn’t even take into account the labor costs of writing, mailing, collecting and reconciling the check, not to mention the increased exposure to fraud.

See also: Using Payments to Improve the CX

Customer Experience and the Bottom Line

In general, customer experience drives retention, new and expanded business and Net Promoter Scores, but when it comes to payments, the customer experience can also accelerate (or impede) cashflow. For an insurer, money that gets in the door faster will be invested faster. A complex digital payment experience can result in delay or abandonment of the process, as questions get answered or as the policyholder regresses back to sending a paper check. These are outcomes that not only delay the payment but add cost.

Digital insurance payments are a key part of the customer experience and yet often get overlooked. Nothing will change if payments are viewed as “checking off a box” rather than a critical component of the business that demands oversight and strategy. Many insurers and brokers are stuck in the first phase of digital payments, where the market had forced its adoption. Now it’s time to enter the next phase, where insurance organizations become more adept at managing their payments, and, as a result, reduce costs, streamline operations, improve cashflow and provide a seamless experience to customers.


Michele Shepard

Profile picture for user MicheleShepard

Michele Shepard

Michele Shepard is chief commercial officer of Paya.

She focuses on developing and executing forward-thinking customer engagement strategies across sales, marketing and customer success. Shepard's previous experience includes leading high-growth sales and business development teams as well as implementing successful go-to-market strategies at high-growth vertical software companies Insurity and Vertafore. Shepard also served as a senior sales leader at Gartner, focusing on tailoring sales to targeted vertical end markets.

Blueprint to Counter Ransomware Attacks

Insurers have collaborated on a detailed plan for small and midsized businesses, which find themselves in the sweet spot for ransomware attacks. 

Hand typing on a colorful but dark keyboard

In 2021, crypto analysis firm Chainalysis estimated that victims of ransomware paid over $692 million in extortion payments. This marked a 70% increase from the previous worst year on record (2020), and it only tells a small part of the story.

Analysis from cyber insurance claims shows that, as frustrating as it is to pay criminals to restore critical data, the cost to the business is significantly worse. Data from insurance broker AON projected that the business costs from ransomware attacks in 2021 would top $20 billion.

70% of ransomware victims are small to midsized enterprises (SMEs) with fewer than 500 employees. This is a sweet spot for criminals because these organizations – many of which are cities, hospitals and school districts – can’t afford to shut down but also can't afford to compete for expertise, given the 700,000 open cybersecurity positions across the U.S.

At Resilience, we are laser-focused on these middle-market organizations and see firsthand the pain enacted by this menacingly profitable form of cyber crime. The school district that not only struggles to restore teachers’ computers but also worries about criminals leaking student personal data. The manufacturer that missed a critical patch and now wonders how long it can afford to delay orders. The city with thousands of civilians that has to choose between funding more crime fighting or keeping critical services running. Organizations must build resilience in their digital systems that allows them to defend against ransomware attacks and recover in a manner that doesn’t necessitate paying a ransom. 

Our drive to build cyber resilience in our customers led us to join our partners on the Ransomware Task Force to launch a tool specifically focused on supporting SMEs, the Blueprint for Ransomware Defense. 

From the start, we wanted to move past the various vendor-sponsored “top 10 lists” for how one product or another could protect against ransomware attacks. This type of FUD (fear, uncertainty and doubt) marketing promises that a specific product or solution will make a company completely secure against attacks. As cybersecurity and insurance specialists, we know the hard truth: no system is completely safe from a determined adversary, and success relies on an organization’s ability to take a punch and maintain operations. 

Instead, the blueprint begins with data-backed security control recommendations from the non-profit Center for Internet Security. With their assistance, task force members prioritized security measures based on: 

a) what has been proven to be most effective at stopping attacks; and
b) what is reasonable for an SME with minimal staff and funding to accomplish.

As an insurance provider, Resilience was also able to offer insight into which controls had the greatest effect on lowering the damage of successful attacks and helping companies recover without paying a ransom. 

See also: Ransomware Grows More Pernicious

The blueprint prioritizes these controls along seven categories:

  • Environment
  • Secure Configurations
  • Account and Access Management
  • Vulnerability Management Planning
  • Malware Defense
  • Security Awareness and Skill Training
  • Data Recovery and Incident Response

While none of this is earth-shattering to security professionals, we believe that the core value of the blueprint lies in its ease of implantation by the partners that serve this highly targeted group of SMEs, including cloud providers, consultants and managed service providers. As these organizations look to defend their clients from ransomware, we will continue to maintain this list as a prioritized “building code” for what is currently working best to build resilience against attacks.

As noted in the report, the ransomware blueprint also provides two critical elements for the cyber insurance industry’s fight against the rise in criminal ransomware attacks.

First, the blueprint provides a practical, data-driven guide specifically for middle market and small businesses, which often struggle the most with defending their systems. Starting with the CIS Implementation Group 1 control set, the task force selected these security measures as the most critical defenses against ransomware. Underwriting and claims professionals have also reviewed these measures to ensure they match with what is being seen to help lower the likelihood of attacks.

Second, the blueprint helps the insurance industry better understand what signals to look for when underwriting accounts. In other lines of insurance, engineering-based loss data drives underwriting and risk mitigation efforts by carriers and reinsurers. Because of its human adversarial element and highly technical nature, cyber insurance has often relied on data breach litigation data to drive actuarial pricing and determine underwriting guidelines. The rise in ransomware has dramatically shown the need for a greater focus on security controls that can stop attacks and speed recovery so that insureds are not forced to pay extortion to recover their critical systems quickly.

As a newer cyber insurance provider, Resilience believes in sharing insights we’ve gained as security practitioners with the broader insurance community. A unique feature of the insurance industry is that many firms provide capital for insuring a single organization. This process is called building an insurance “tower," meaning that competing insurance providers may share the risk on the same account. We believe that sharing public resources like the blueprint can help less technical underwriters better understand the risks they are underwriting, which benefits the industry.

Some of these best practices from the blueprint that Resilience considers when underwriting against ransomware risk include: 

  • Implementation of strong backups;
  • Security awareness and incident response training;
  • E-mail security deployed across the entire enterprise;
  • Advanced endpoint protection against malware; and
  • Network visibility and security.

Building cyber resilient companies is about more than setting up strong defenses or paying insurance claims. The ambitious nature of ransomware actors has led to consistently evolving tactics that thwart common defensive measures. Focusing solely on prevention is a risky endeavor if an organization has not also thought about how to maintain operations during a disruption. 

Coming back from a successful attack without resorting to extortion payments or a complete overhaul of critical systems is the other half of a cyber resilient mindset. Resilience believes the traditional cyber insurance market has to evolve from simply transferring financial burden of an incident toward using data and knowledge to increase the safety of customers. At Resilience, this virtuous cycle of security and insurance has been shown to reduce claims costs, increase patching cadence and drive executive attention across our customer base. 

We feel bold enough to say the cyber resilience model must be the next insurance market evolution for this product. With the Ransomware Task Force Blueprint launch, we believe this is a concrete first step down that path and encourage you to join us. 

Access the blueprint for yourself at: https://securityandtechnology.org/ransomwaretaskforce/blueprint-for-ransomware-defense/


Davis Hake

Profile picture for user DavisHake

Davis Hake

Davis Hake is the co-founder and vice president of policy at Resilience.

Prior to co-founding Resilience in 2017, Hake managed cybersecurity strategy for Palo Alto Networks, served on the National Security Council and was a lead author of cybersecurity legislation in the U.S. Congress. Hake is an adjunct professor of risk management at the University of California, Berkeley, and is a term member of the Council on Foreign Relations.

He holds a master’s in strategic security studies from the National Defense University and a bachelor’s in international relations and economics from the University of California, Davis.

Expanding Channels for Insurance: A Spectrum from Traditional to Affinity and Embedded

Read the latest report from Majesco to understand the opportunities of creating a diversified distribution ecosystem that expands the footprint of offerings and reaches new markets.

Majesco banner

The insurance purchase process can be complicated and difficult, but many insurers are taking a multi-channel strategy that makes it easier for customers. As organizations work to meet customers where and when they want to purchase, insurers must look at embedded insurance to gain a competitive advantage.

Read Now


Sponsored by ITL Partner: Majesco


ITL Partner: Majesco

Profile picture for user majescopartner

ITL Partner: Majesco

Majesco isn’t just riding the AI wave — we’re leading it across the P&C, L&AH, and Pension & Retirement markets. Born in the cloud and built with an AI-native vision, we’ve reimagined the insurance and pension core as an intelligent platform that enables insurers and retirement providers to move faster, see farther, and operate smarter. As leaders in intelligent SaaS, we embed AI and Agentic AI across our portfolio of core, underwriting, loss control, distribution, digital, and pension & retirement administration solutions — empowering customers with real-time insights, optimized operations, and measurable business outcomes.


Everything we build is designed to strip away complexity so our clients can focus on what matters most: delivering exceptional products, experiences, and long-term financial security for policyholders and plan participants. In a world of constant change, our native-cloud SaaS platform gives insurers, MGAs, and pension & retirement providers the agility to adapt to evolving risk, regulation, and market expectations, modernize operating models, and accelerate innovation at scale. With 1,400+ implementations and more than 375 customers worldwide, Majesco is the AI-native solution trusted to power the future of insurance and pension & retirement. Break free from the past and build what’s next at www.majesco.com


Additional Resources

Modernize or Fall Behind: 2025 Retirement & Pension Top Industry Trends

Read More

Closing the Insurance Customer Protection Gap: How Generational Differences in Risk, Readiness, and Coverage Are Redefining Insurance Value

Read More

Bridging the Customer Protection Gap

Read More

Transforming Specialty Insurance with AI

Read More

Leaders Reinventing Insurance: Strategic Focus on Business Operating Model and Technology Foundation

Read More

What Customers Actually Value

A survey by Hi Marley identifies two problems in the claims process that annoy customers, yet that would be easy to fix via technology and some training. 

Image
What Customers Actually Value

A partner of mine at a management consulting firm introduced me to the idea of "break points" in customer expectations some 25 years ago, and they struck me as a revelation.

I had just thought of, say, faster response to customer calls as a good thing, and assumed that the faster the better. In fact, there were break points. Customers would get royally hacked off if kept on hold for a certain number of minutes -- let's say 10 -- so it was worth the effort to keep response times below that threshold. But -- and this was the revelation -- you didn't get additional credit from customers if you cut response time to nine minutes or eight or seven or.... You didn't get credit until you reached the next break point, perhaps at less than a minute, a response time that would delight customers.

But that didn't necessarily mean you should try to delight customers. The expense might be prohibitive. You might make an economic calculation to merely satisfy them. 

That idea got refined for me a few years later in a conversation with Mike Hammer, the pioneer of business process reengineering and all-around famous professor at MIT. He told me of a large utility that found that the key metric for customer satisfaction when it started service for a customer wasn't what I would have expected: the number of days between the request for service and its initiation. In fact, the key metric was whether the utility lived up to its promise about when service would start. In other words, whether it took one week or two to start service mattered less than whether the technician really showed up between, say, 2 and 4pm on the appointed day.

That's a bit of a long windup, but I wanted to make clear why I was so intrigued by a Hi Marley survey about what really matters to customers in the claims process. While two of the main concerns that surfaced strike me as hard and expensive to resolve, one seems to be really low-hanging fruit ("process explanation and expectation setting"), and another seems within reach ("responsiveness and availability").  

The Hi Marley survey looked at thousands of four-star ratings in their database and identified 1,300 claims in which policyholders relayed issues that, had they been handled differently, would’ve resulted in a five-star rating. Of those, 95% fell into four categories: process explanation and expectation setting (34%), unresolved claim issues (28%), responsiveness and availability (18%) and adjuster attitude, approach and level of knowledge (15%).

You will decide for yourself how hard each of the four issues would be to attack, but it strikes me that process explanation and expectation setting should be relatively easy to improve, especially because of new technology tools.

Think of how package deliveries used to work, vs. how they work now. A decade ago, deliveries were a black box. You placed an order, and it eventually showed up at your doorstep, but you had no visibility about what happened during the days in between. You could call and ask for an update, but the customer service rep often had no more information than you did -- something you'd find out only after working your way through a phone tree and spending time on hold listening to bad music or ads. Now, you can simply check an app and know that the item has shipped, see where it is in the USPS, FedEx or UPS delivery network and get a precise idea of when the item will arrive. More advanced companies, such as Amazon, automatically text you or email you alerts about where your item is in the process, when it will arrive and when it has, in fact, landed on your doormat.

Why couldn't that sort of system work for claims? Yes, it would take work on the back end to automate updates, but then the marginal cost would be almost zero -- and customers would be a lot happier if they knew where their claim stood in the process. Even if they just got a notification every few days letting them know that you were still working on resolving a particular issue, they'd know you hadn't forgotten about them. That sort of notification would be especially valuable these days, given that supply chain issues can mean long waits for parts for a repair. 

Some training and continual communication would also, in my experience, be needed to improve process explanation and expectation setting. An awful lot of experts I've dealt with over the years, whether a plumber or a lawyer, have forgotten that they're experts. They assume I know things that I have never remotely experienced. Those working on claims would likely benefit from training and then frequent communication reminding them that they need to start from zero as they're explaining the process to someone filing a claim, that they should avoid all jargon at all costs and that they need to set realistic expectations (or under-promise and overdeliver). 

Technology can help here, too. The ease of electronic communication can let companies develop standardized materials that can be shared with claimants and explain the process in a thorough but friendly way. (Lemonade makes for a good model.) Electronic communication can also serve as a backstop -- if a claimant says you didn't warn them about something, you'll have a record showing that you did. 

The other point where I think real progress can be made -- responsiveness and availability -- is rather trickier, because that may require additional resources, but technology can take at least some of the load off agents. The sort of digitization of the claims process that would allow for automated updates would also provide for self-service and remove the need for any kind of response from an agent. A claimant doesn't have to place a call and wait for a response from an available agent if the person can just go to a website and look something up or interact with a chatbot and get a question answered at 2am or on a weekend. The responsiveness and availability are instantaneous.

The other two issues identified by Hi Marley -- unresolved claim issues and adjuster attitude, approach and level of knowledge -- are surely worth addressing but seem to require more systemic change. Claim issues involve the whole process, from beginning to end, and attitude, approach and knowledge depend not only on training but on finding the right talent. 

With all four of the issues identified in the survey, Hi Marley suggests that there is a clear benefit just to getting customers to raise your rating. I'm not necessarily convinced. You still have to do the analysis to see if the expense of resolving the issues would matter enough to get past a break point and lead customers to change their behaviors.

But I also don't think that it would take that much effort to improve on process explanation and expectation setting and on responsiveness and availability. 

Cheers,

Paul

How to Address COVID Fatigue

The anti-vaccination movement has resulted in 1 out of 10 American parents delaying or outright refusing necessary childhood vaccinations.

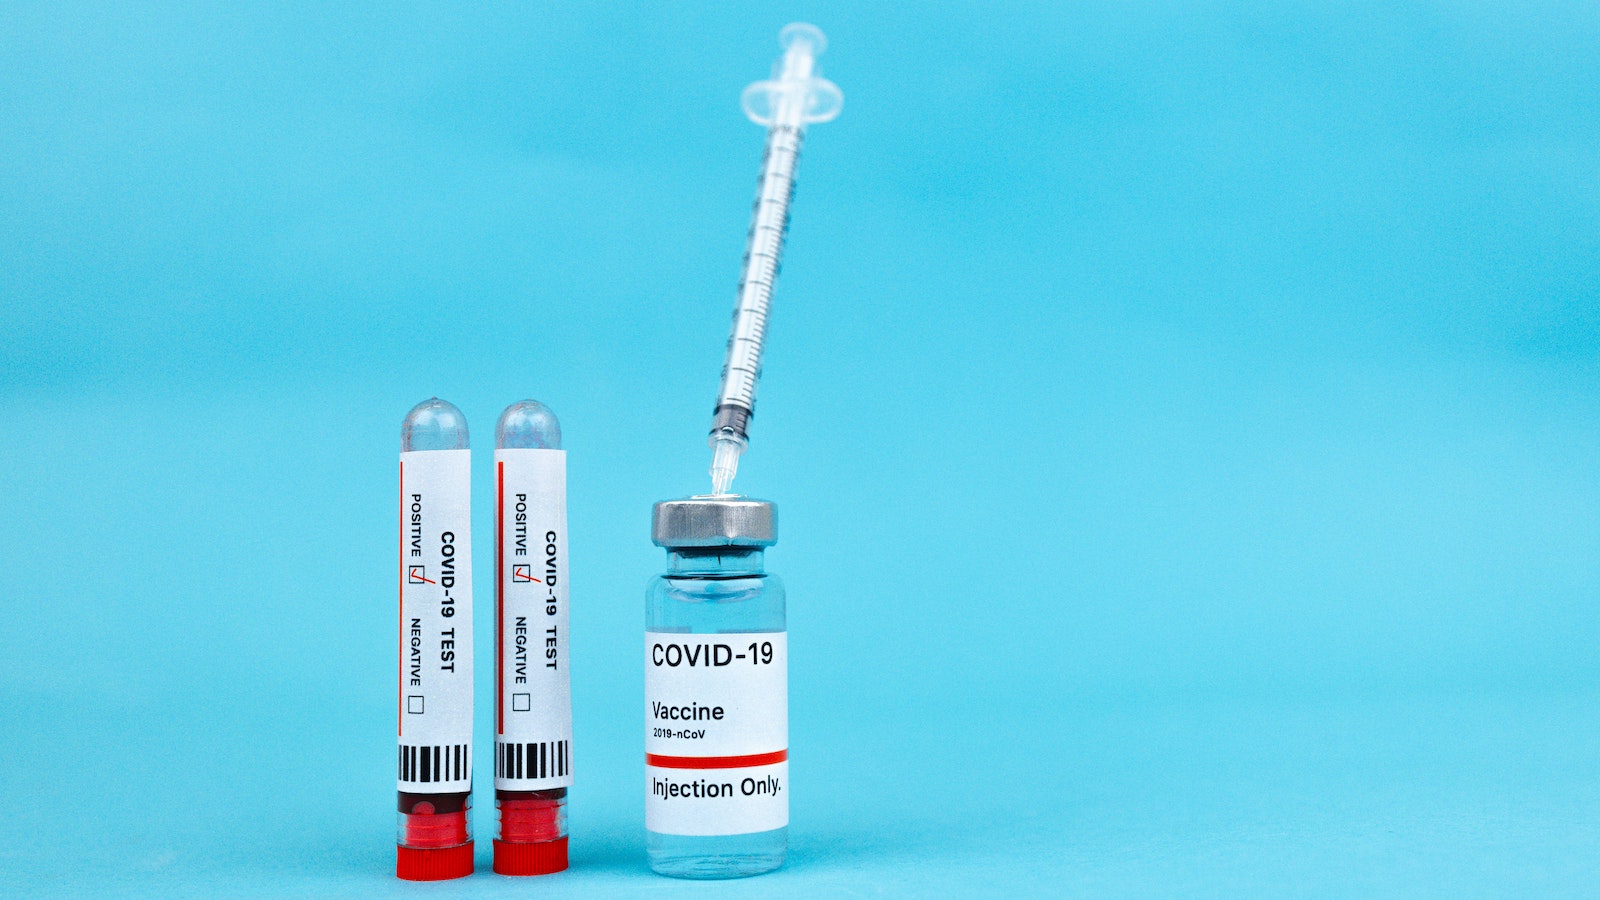
Covid test and vaccine on a blue background

The Centers for Disease Control (CDC) director announced in mid-August that the public health agency required a shake-up or “reset” after its’ admitted failures during the COVID-19 pandemic. Who is to argue? The CDC was too bureaucratic and slow to allow it to collect data and respond quickly at the same time to the evolving health emergency and spread of variant strains. 

I, too, felt completely disillusioned during the peak time of the holiday season last year when, despite being fully vaccinated with the initial booster shot, I learned that the data showed I still could get the new Delta variant and spread it to others.

I had just visited my oldest brother in a rehab hospital, where he was recovering from a COVID outbreak in the facility. My niece in medical school was ill from long-term COVID symptoms, and there was no COVID-19 testing available anywhere. I had no choice but to spend the holidays away from my family because I could not get tested until after New Year’s.

This was 18 months after the start of the outbreak in March 2020, and zero tests were available. I mean zero. The national TV news showed lines of people and cars waiting for COVID tests across the country.

Guess what? The federal funding for three COVID tests just expired due to a funding short fall at the same time public health officials predict a surge in COVID cases this fall and winter.

Although Operation Warp Speed will go down in history as one of the great public health success stories, the federal governments’ role in providing widespread real-time COVID-19 testing and accurate, updated public health information... not so much.

What has made matters worse: The anti-vaccination critics have now seized the situation to continue to spread their political agenda to discredit the field of public health with threats of public hearings and conspiracy theories. 

Like I have said, “do the math.” (See ITL article: On COVID Vaccine: Do the Math 9/8/21) A recent study conducted by the Imperial College of London and published in the Lancet Journal of Infectious Diseases stated that the COVID-19 vaccines saved 20 million lives worldwide in the first year alone. The vaccines reduced deaths by 63%. If the vaccines developed through Operation Warp Speed were not made available, the death rate today would be three times higher in a much more severe catastrophic worldwide pandemic.

See also: Brace Yourself for More Waves of COVID

The anti-vaccination movement has resulted in 1 out of 10 American parents delaying or outright refusing necessary childhood vaccinations. What was just found recently in New York City sewage by public health researchers? Polio!

One of the most dreaded childhood diseases. officially eradicated decades ago. Public health officials announced that polio was also found in wastewater in Rockland County and has now been found in wastewater in neighboring Sullivan County. Nearby Orange County has a childhood vaccination rate of 59% for two-year-olds, who should have received the recommended three polio shots by 18 months. The state health commissioner recently stated, “The polio in New York today is an imminent threat to all adults and children who are not vaccinated.” A documented case now exists in Rockland County for an unvaccinated person -- the first documented case in America in a decade.

In incredibly bad timing in the decades-long world-wide effort to eradicate polio, in rare circumstances the oral vaccine containing a weakened form of the virus, which is cheap and easy to administer and widely used in poor isolated countries, has been found to cause polio in two to four children per two million doses. (The oral vaccine has not been used in the U.S. since 2000; only the inactive polio virus vaccine.) Worldwide health officials are now warned they must use the most recent vaccines in the effort to eradicate polio in poor isolated pockets in the world -- and now apparently in New York.

Although COVID-19 today has moved from a pandemic with over one million deaths in the U.S. to an endemic phase. it still accounts for 400 deaths, 500 hospitalizations and 80,000 new cases a day. The FDA has now cleared through an emergency use authorization (EUA) a brand-new bivalent vaccine booster from both Pfizer and Moderna that targets both the original virus and the now dominant BA.4 and BA.5 omicron variants. 

Again, the new Omicron booster will not provide full immunity to the virus but can reduce serious illness, hospitalizations and deaths. A major concern, due to what I believe is COVID fatigue, mixed messaging and pure hypocrisy, is that there is no current federal funding to provide the new booster shots to Americans who want the booster. In terms of people who refuse to get vaccinated, the FDA commissioner just stated; “It’s painful to see people dying when we have free treatment available to save lives.”

We need to both fund and restructure federal public health agencies like the CDC and FDA to help overcome public mistrust and outright lies and distortions by providing the best updated scientific information without outside political interference about the safety and effectiveness of vaccines.

See also: On COVID Vaccine: Do the Math

There is legitimate debate about the effectiveness of the mandated use of masks and school and business closings during the pandemic. However, a recent study of 33,000 students at Boston University found masked and vaccinated students had virtually no chance of catching COVID-19 in the classroom. The students who had COVID were infected in other places. That is why some universities such as Rutgers will still require masks in indoors classroom settings, libraries and clinical settings and testing for unvaccinated students this fall.

There will be an continuing need for research and studies about the source, treatment and testing of COVID-19 variants, along with studies on the effectiveness and timelines for new boosters similar to the annual flu shot. Right now, there are zero federal dollars until at least October, when the new federal budget comes before Congress. Talk about a reset!

Our public health agencies need to be way ahead of the learning curve on updated medical studies and be prepared for the next mutation or pandemic, which they have admitted they were not this time. 

However, there should be no such debate about the role of public health campaigns and the use of proven safe and effective vaccines that once were thought to have eradicated childhood diseases like polio and the measles, which have now reared their ugly heads again.

The answer to the question, can a person get the new booster and the flu shot at the same time, is yes. Once in each arm.

5 Keys to a Low-Stress Work Environment in 2022

Stressed employees are less engaged and have lower productivity - and some may even left their job. Here is how to promote a low-stress work environment.

Woman grimacing while on her computer

Around 80% of workers feel stress on the job, and in just about every type of job or position. Employees are reporting neck pain, eye pain and lower productivity due to stress. In fact, around one in five people has quit a job due to stress.

Making some simple changes around the office (including remote offices!) can have a large impact on workplace stress and, thus, productivity. Let’s review five simple but effective ways to promote a low-stress work environment.

What’s new in 2022?

A 2021 survey found that 76% of respondents with 500 or more employees said that improving employee mental and emotional health was a top priority. Employees are also beginning to view protection of their mental health as a non-negotiable aspect of their job, and, as a result of the pandemic, many employees found themselves with newfound power as people left their jobs in droves. This “power shift” has led to increased demands for conscientious and flexible management.

See also: Insurance Tips for the Remote Workforce

5 Tips to Create a Relaxed Work Environment

1. Use communication tools

We’ve all heard it before: Communication is one of the best tools to reduce stress. But with so many workers moving to remote work, communication has also become much more difficult. Gone are the days of popping into someone’s office to check in on a project’s status (or a coworker’s wellbeing!). Instead, leaders need to leverage communication technology. 

How, you may ask? Communication software not only helps people stay on track and avoid wasting time emailing back and forth but can help set clear expectations and deadlines and avoid misunderstandings that cause stress. Using communication software can also help build virtual communities that would not otherwise be possible. Finally, communication software can help your team respond faster to potential issues, helping disrupt problems before they become even more stressful.

2. Take time for team building

A strong team is generally a more relaxed team. While team building has garnered a rather unfortunate reputation in recent years (how many more rounds of Two Truths and a Lie can most people take…?), team building actually is a crucial tool for reducing stress. Not only can team building help managers understand employees’ strengths and weaknesses better, but it can provide employees with an opportunity to blow off a little steam – in a healthy way.

Team building doesn’t have to feel like forced fun. Today, there are plenty of options for team building activities that are engaging and fun for everyone. For example, this escape room in Los Angeles advertises the benefits of playing an escape room for corporate team building, such as improved collaboration and the ability to think outside the box. More unusual team building activities that are both fun and effective include scavenger hunts or office trivia. 

No matter your activity of choice, even five minutes of team building can reduce a little stress -- especially if the activity doesn’t feel like a waste of time. Consider incorporating real-world office training into your team building exercise. For example, if your team visits an escape room, consider incorporating the escape room into a larger training on time management.

See also: Bridging Health and Productivity at Work

3. Set boundaries

A healthy work-life balance is absolutely crucial to a stress-free work environment. If employees are overworked and using their downtime to think about work, stress is likely to build up quite quickly. Successful employers encourage employees to set healthy boundaries between life and work so that everyone can take a much-needed mental break every once in a while. Not only will a healthy work-life balance reduce stress, but it can also free up mental space for breakthroughs in the future; without breaks, it’s easy to get stuck in the same thought patterns. 

Employers can lead by example and implement boundaries between home life and work in their own life. This will likely encourage their employees to follow suit!

4. Create healthy variety

Studies have shown that boredom is highly linked to stress; monotony at work can actually, counterintuitively, lead to high levels of stress. It’s important to create variety in your work day to avoid this!

The best way to avoid the boredom trap is to perform a variety of tasks throughout the day. Consider splitting your day into “focus chunks,” in which you pick one task to work on for a specific period. If you’re motivated to finish it, great. If not, and you’re starting to feel boredom creeping in, move to another task if you can. Not only is variety proven to reduce stress, but it’s also shown to increase satisfaction.

5. Allow autonomy

Finally, feeling control over your environment or situation is proven to reduce stress. After all, stress often occurs when things feel out of our control. As an employer, it’s important to allow your employees control over their workflow when possible. For example, consider assigning a goal or outcome and allowing your employees to figure out how best to achieve it. Autonomy may also extend to allowing employees to choose their hours and daily schedule or, as we’ve seen with the pandemic, their workspace.

Conclusion: Where Are We Headed?

As remote and in-person workers alike begin to demand working environments that are healthy and supportive, employers simply cannot afford to ignore stress in the workplace. And an increased employee focus on their own mental health is here to stay, bringing with it increased happiness and productivity. The businesses that work hard to promote a stress-free workplace will likely be the ones to succeed in the long run; after all, much of a company’s success depends on the security of its employees.


David Evans

Profile picture for user DavidEvans

David Evans

David Evans is a freelance writer covering sustainability challenges and solutions. He writes to help companies and consumers understand the environmental and ethical challenges in products and their supply chains so we can find viable solutions for both. See more of his writing at: Plastic.Education.

You May Be Lighting Benjamins on Fire

You are passing up maybe $1,000 in commissions per client if you aren't cross-selling instant-issue term life insurance policies that don't require a medical checkup.

Hundred dollar bill on fire

Wait! You Forgot Your Thousand Bucks!

You just wrapped up this year's renewal  on your client's auto and homeowners coverage. You got the green light to place the umbrella coverage, too. And you got a nice referral to the brother-in-law. Nice work, right? Of course it is. But you probably left about $1,000 in commissions on the table if you didn't log in and hand them a "While-You-Wait" instant-issue term life insurance policy. What's that you say? Read on.... SO much has changed.

It's All About the "E"

Sixty seconds. That is how long it takes to have a term life policy electronically underwritten in real time, approved, issued and spouting forth from your (or your client's) printer. The client puts their E-signature on the online E-application, and the policy is immediately E-delivered via PDF for qualified applicants. Is that enough "Ease" for you (bad pun intended :) ?

What if there was a simple, online system that provided:

  • A step-by-stop questionnaire to fill out your client's E-application in 10 minutes
  • Built-in E-signature
  • Automated underwriting based on "AI" (artificial intelligence)
  • No need for a medical exam
  • Immediate approval for qualified applicants
  • E-policy delivery of the life insurance policy PDF in about 60 seconds?

Cross-Selling Is King

We all want to generate additional revenue for our businesses. Existing clients and policyholders are the best source of new business. The "bridge of trust "already exists with them.

But, in working with huge numbers of property & casualty as well as health insurance agencies and agents over the years, we have heard countless times how they are not asking the client about their life insurance needs. Giant numbers of consumers tell us the reason they don't have life insurance is because "no one has approached me about it."

What need is the most unaddressed financial risk for American consumers? Life insurance.

See also: Selling Where Life Happens

The Old Reasoning for Not Cross-Selling Does Not Fly Anymore

Before high-speed, real-time processing of life insurance sales, the reason for not embracing cross-selling life insurance held water. Clients hated the lengthy forms, the confusion, the waiting and the mysterious nature of getting life insurance coverage. One life insurance industry veteran who comes to mind used to say, "Life Insurance is the only industry where one could swear that we're trying to actually PREVENT the customer from buying our product." Back then, he got that right. But today, the right digital tools are here, are super easy to use and are the key to almost unlimited amounts of additional revenue and profits to your organization.

Recent Advances in Agent-Friendly Technology Create the Golden Opportunity

Non-medically underwritten term life is the key. It satisfies most consumers' needs. This is the basic family-needs market we're talking about. $50,000 to $500,000 of coverage.

Better than old, worn-out "simplified" programs that are too small, are too expensive and are perceived as "flimsy" by consumers, Non-medically underwritten term life uses a thorough but still compact application online. Underwriting decisions are made electronically and, therefore, instantly for the majority of applications. 

This new frontier described here is opening up right in front of us. Now is the time to embrace the new capabilities, which are making the great promise and potential of digital technology a reality for life insurance sales.