Download

How to Choose a Fertility Vendor

97% of employers offering infertility coverage say that it adds little to medical plan costs and that many employees prize it.

A white dandelion in the foreground with green plants in the background

KEY TAKEAWAYS:

--There are multiple considerations when choosing a fertility clinic, such as pricing, success rate and what the percentages are for singletons vs. multiple births.

--Another important consideration is whether a vendor’s performance claims have been vetted by an independent third party, like the Validation Institute. If not, why not?

----------

Does your company’s health plan offer fertility benefits? What’s the case for making these services available, and what issues should you consider in choosing a vendor?

A recent World Health Organization (WHO) report found that one in six people worldwide experiences infertility during their lifetimes and one in eight experiences it at any one time. Infertility is “a disease of the male or female reproductive system defined by the failure to achieve a pregnancy after 12 months or more of regular, unprotected sexual intercourse.” The report clarifies that infertility is a common condition worldwide. Any employees and their partners, both women and men, including singles and those in the LGBTQ+ communities, can need help in forming a family. For employers, workers with infertility issues are likely to have physical and emotional burdens -- e.g., anxiety, depression and financial stress -- that corrode employee engagement and productivity.

Infertility care can be expensive. A single in vitro fertilization (IVF) cycle -- ovarian stimulation, egg retrieval and embryo transfer -- can range from $15,000 to $30,000. Many patients require multiple IVF cycles before getting pregnant or taking a different path.

While 12 states have mandated coverage of fertility services, its cost has led many employer benefits managers and consultants to consider it a “premium” benefit, meaning that they’re most popular with employers in high-margin industries. The result has been limited coverage, with only one in four people getting the treatment they need. 

Even so, 97% of employers offering infertility coverage say that adding it did not significantly increase medical plan costs. They appreciate that these services are prized by many employees and can often be a deciding factor in the competition for top talent. 90% of employees with infertility concerns say they would change jobs for fertility benefits. 61% claim that receiving benefits increased their loyalty. 58% think it is discriminatory not to provide fertility benefits. 

A number of fertility companies have come into the market in recent years, and it can be difficult to compare them. Here are some key issues to consider:

  • What are the recruitment criteria for the fertility companies’ physicians and clinics networks? Do they rely on objective data related to health outcomes and cost?
  • What are their rates of singletons vs. multiple births? Singletons are likely to have a higher gestational age than multiple gestation births, so they typically have lower morbidity and mortality rates, as well, with better health outcomes and lower costs. It’s critical to know what each vendor’s numbers are and what they’ll guarantee.
  • What is their pricing and what is it based on? 
  • Is the employer-paid portion fixed or flexible/discretionary? Does the fertility vendor offer employers a range of subsidy options?
  • Is the vendor backed by private equity or venture capital investments? If so, it’s almost certainly paying a 20% to 30% annual interest rate on those investments that must be built into the vendor’s pricing structure. Organizations that have bootstrapped their operations, with lower-cost capital typically have a competitive pricing advantage.

See also: 20 Issues to Watch in 2023

Another important consideration is whether a vendor’s performance claims -- fertility or other --  have been vetted by an independent third party, like the Validation Institute (VI), and if not, why not. (Disclosure: I serve unpaid on the VI’s Advisory Board.)

The VI stands behind its validation process, offering customers of validated solution providers up to a $25,000 guarantee for claims-based validations and up to $50,000 for program validations. They offer four validation levels, with 4 representing the highest. 

  1. Contractual Integrity, meaning that a vendor “is willing to put part of their fees 'at risk,' as a performance guarantee.”
  2. Metrics, meaning that “credible sources and valid assumptions create a reasonable estimate of the program’s impact.”
  3. Outcomes, meaning that “the product/solution has measurably improved an outcome of importance.”
  4. Savings, meaning that “the vendor can reduce healthcare spending per case/participant or for the plan/purchaser overall.”

As I wrote this article, I pulled up the VI home page, clicked on Validation Reports and searched using the keyword “fertility.” Up popped the names of 11 fertility companies, including Carrot Fertility and ARC Fertility, which had sought validation. Nine others were marked “Not Validated.” The VI’s listing does not include all U.S. fertility vendors.

Carrot achieved a Level 2 validation (Metrics) for their savings calculator. The report reads, “For each component in [Carrot’s] logic model, Validation Institute verified each assumption, data source and calculation. The model gives an evidence-based estimate of the program’s impact.”

ARC Fertility achieved Level 3 (Outcomes) and 4 (Savings) validations on two different performance claims. The Level 3 claim was “ARC Fertility clinics’ patients have a lower rate of multiple births (twins, triplets and higher) than all other U.S. clinics' average. Multiple births impact the health and the medical costs for mothers and babies.” The Level 4 claim was, ”By reducing the frequency of twins and higher multiple births, ARC Fertility reduces employers’ cost for offering fertility benefits.”

In ARC Fertility’s validation report, VI accessed a data repository maintained by The Society for Assisted Reproductive Technology (SART), which 86% of U.S. fertility clinics participate in. Members contribute specified data on each fertility patient's treatment and outcomes. VI used this resource to compare ARC’s health outcomes and savings with the average performance of other fertility firms. Other member firms can perform a similar analysis.

Which is to say that objective information is available to judge the relative performance of fertility services firms, making it straightforward to identify a vendor that is likely to deliver the highest value care.

(I have no financial relationship with any of the companies named in this article.)

Brian Klepper

Profile picture for user BrianKlepper

Brian Klepper

Brian Klepper is principal of Healthcare Performance, principal of Worksite Health Advisors and a nationally prominent healthcare analyst and commentator. He is a former CEO of the National Business Coalition on Health (NBCH), an association representing about 5,000 employers and unions and some 35 million people.

Insurers' Investment Risks for 2023

Insurers planned to increase their risk tolerance, but a volatile economy has them focused on operational issues and the risks they already have. 

low-angle image of a tall glass building under a blue and cloudy sky

KEY TAKEAWAYS:

--There are opportunities within the volatility. For instance, insurers with ample liquidity to meet near-term needs could diversify their holdings into less liquid securities that could generate greater return.

--Many primary carriers are maintaining more insurance risk and paying more for the percentage of their books they do reinsure but should remain open to pursuing new opportunities. 

----------

Insurers in the fall of 2022 were expecting to increase their risk tolerance in the year ahead, according to a Conning survey of insurance industry professionals. However, the start of 2023 has proven to be a far more challenging environment than expected: Layoffs are on the rise in the financial and tech sectors, the banking system and regional lenders in particular are stressed and the U.S. Federal Reserve has continued interest rate increases to fight inflation. With these headwinds, do insurers still have a growing appetite for risk?

Conning’s discussions with clients suggest they are more focused on managing the risks they currently have on their balance sheets and focus on operational pressures. We also believe that insurers should consider opportunities the current market dislocation is generating – including those with greater investment risk – provided the risks fit within their longer-term strategic needs to manage their companies and portfolios.

Opportunities Within the Volatility

The findings of the Conning Risk Assessment Survey of U.S. Insurers, which received responses from 303 insurance industry professionals, suggest that risk management and sustainability will continue growing in importance but that they are also becoming more complex. The survey adds that insurers would not blindly add risk but would judiciously seek to invest in systems to better understand the risks they are pursuing.

Since the tumultuous start of 2023, Conning has been talking with clients and learning more about their tolerance for risk as a result of recent events. The discussions are unique to each insurer, as they must holistically assess their enterprise's financial health, liquidity position and projected operating performance. They must also look at addressing near-term portfolio stress points while not losing sight of long-term objectives. 

In this assessment, Conning often sees some tradeoffs insurers should consider, or at least be ready to consider, that could potentially lead to improvements in their investment position in areas of interest rate risk, credit risk profile and prospective volatility of certain assets within their balance sheet.

As an example, consider liquidity risk. Given the recent banking industry stresses, liquidity is a hot topic. It’s an ever-present concern for an insurer: assessing the ability to fund future expenses and benefit or claim costs is of paramount importance. But upon a careful examination of business expectations over specific timelines and stress-testing liquidity, a number of insurers may find their portfolios have ample liquidity to meet near-term needs and therefore could further diversify a portion of their holdings into less liquid securities that can potentially generate greater yield or return -- esoteric asset-backed securities, private placements and real estate debt and equity, for example. Insurers should still focus on navigating these shorter-term challenges in this period of volatility but also pursue meaningful income gains over the longer term to help improve their business. 

See also: Adding ESG to Investment Practices

Adhering to Learned Lessons

Conning’s discussions with clients also suggest that, even as they navigate the challenges posed by the current volatility, insurers are unlikely to revert to the less diversified portfolios they had even a few years ago.

One of the outcomes of the persistent low-interest-rate environment since the financial crisis of 2008-9 is that many insurers, desperate for greater income, discovered the diversification and yield opportunities in allocating beyond the traditional fixed-income assets – such as treasuries and high-quality corporate debt – upon which they had relied for many years. It’s a lesson many plan to keep following regardless of market conditions.

Operational pressures for many insurers continue to increase with persistent inflation and reduced portfolio flexibility, given the unrealized losses in their bond portfolios as interest rates rise. Inflation has not just affected investment portfolios but continues to increase expenses and claims costs. Many primary carriers are maintaining more insurance risk and paying more for the percentage of their books they do reinsure. However, these firms remain resilient, and Conning suspects they will have the wherewithal to operate in a more volatile environment, similar to 2022, when they learned to manage through higher interest rates. We expect many insurers will remain open to pursuing new opportunities while stress-testing future operations and managing the risks on their balance sheet. 

U.S. insurance companies remain focused on addressing a number of concerns that are driven by market needs and escalating regulatory demands. As they identify the types of strategies that will best help them respond to these challenges, they often need help in identifying the appropriate resources and tools to help them meet their goals. We remind insurers that they may find valuable resources and expertise in asset managers with deep roots in the insurance industry who can help them face the tough questions in an increasingly challenging and unpredictable investment and operating environment.


Matthew Reilly

Profile picture for user MatthewReilly

Matthew Reilly

Matthew Reilly, CFA, is a managing director and head of Conning’s insurance solutions team.

Prior to joining Conning, he worked for New England Asset Management in enterprise capital strategy and client service roles.

Reilly earned a degree in economics from Colby College.


Lauren Forando

Profile picture for user LaurenForando

Lauren Forando

Lauren Forando is an investment analyst on Conning’s insurance solutions team, where she is responsible for asset modeling and supporting the generation of investment strategies and portfolio benchmarking for Conning’s insurance clients.

Forando joined Conning in May 2022. Prior to joining Conning, she worked for Capgemini as a business analyst and salesforce consultant.

She earned a bachelor’s degree in psychology and statistical and data sciences from Smith College.

5 Things the Navy Seals Taught Me

A "light" boot camp provided a small insight into what our servicemen and women go through -- and the importance of teamwork in business.

White navy boat on on the water

KEY TAKEAWAYS:

--It's crucial to establish a common vision and help, encourage and trust your teammates.

--Value diversity. You'll be surprised what a different perspective can do for you.

--Acknowledge members who deliver on core values. Be flexible and keep it fun (and stay warm).

----------

Navy SEALs are the ultimate team. They accomplish almost impossible feats through precision teamwork. While each SEAL is a formidable fighting machine, it's the team that does fantastic things.

While working in the insurance industry isn't hazardous to life and limb, it does require a team endeavor. Success depends on a well-honed team of underwriters, actuaries, agents, marketers, IT experts and others.

No one succeeds without good teammates. This is what we're taught during team-building activities and something I was reminded of at an industry conference a few years ago.

After attending a Blue Cross Blue Shield conference in San Diego, 32 of us attended a Navy SEAL boot camp on Coronado Island. This "light" boot camp was a great experience, giving us a small insight into what our servicemen and -women go through during initiation -- and the importance of teamwork in the military and business.

We were paired into two teams of 16. Teams were then divided into four boat crews of people of similar heights

There was the usual physical training (PT), during which we were told we were too hot (cool off and get into the ocean), then too clean (roll in the sand) and then too dirty (get back into the sea). Then, there were team obstacle races, memory games, log drills, runs, cold ocean work and more, starting at 5:30 a.m.

So why wasn't I in my comfortable hotel bed at that early hour? Because it was fun, and once I started I didn't want to let my team or myself down.

Finishing the boot camp was something I couldn't have done alone, but having teammates didn't give me an automatic pass. I still had to learn to work with those teammates.

Here are five lessons I learned while at the boot camp:

1. Help, encourage and trust your teammates

It was much easier to reach a consensus and align our goals with our four-person boat crew first. Then, while racing and carrying a log overhead, we first tried to assess how we could best help each other carry the weight.

We knew we needed to step in time so we would not trip on each other. Walter, an ex-Marine, would call out the steps from the rear. During the race, another teammate's shoulder became very sore due to a recent operation. I moved forward to take his weight. We stayed positive, encouraged each other and beat the young guys.

2. Communicate and establish a shared vision

It was a little hard at first to communicate, as none of us knew each other, but we knew that the sooner we could communicate, the sooner we'd have an advantage. So, together, we decided what the core mission was and everyone's role so the team could succeed.

This might seem obvious, but it's easy to lose sight of goals when faced with challenges or obstacles. Whether your objective is supporting your team by linking arms and sitting in the ocean while being pounded by waves -- or implementing software or obtaining market share -- a shared vision will keep the team focused and on track.

See also: There Is No 'I' in 'TEAM'

3. Value Diversity

Some teammates had plenty of boot camp experience, and others had very little. However, their opinions were valued equally because they brought different perspectives and ideas. Unfortunately, many businesses can fail to recognize this.

In business, a healthy exercise is to ask someone in a lower-level position, such as an administrative position, what they think about a problem in the company and how they would solve it. Then, mention their solution at the next C-suite executive meeting. You'll be shocked at how valuable listening to your people can be.

4. Acknowledge members who deliver on values

As a company, you need core values and standards that reinforce those values. As leaders, we tend to recognize performance, which is important. But we also need to recognize when team members deliver on those core values with their behavior. That's how we communicate what's important to us.

One way the SEALs acknowledge values is to simply call out individuals to the front of formations and tell everyone how they are doing a great job. In business, let's say one of your core values is supporting one another (a core value at my company). Openly call out the people at your weekly meetings when they meet that standard with their actions.

5. Be flexible, keep it fun and stay warm

You might have a plan, but be ready to make adjustments at any time. When we thought we understood a drill, our instructors would make it a little more interesting. Todd, the teammate with the sore shoulder, got our boat crew singing during our runs. I encouraged our crew to hug to stay warm when many began to shiver from the cold-water drills. Together, as a team, we finished the boot camp.

Some gave up or got hurt. They grabbed a doughnut and a coffee, rang the bell and left. But we hung in there, breaking the boot camp activities down into one task at a time -- and we got through each of those "one tasks" together.

We will inevitably have our own oceans to cross and missions to accomplish. Yet regardless of the landscape, we will require the help of others to reach our destination. Through positive teamwork, we can harness skills beyond our own and achieve success we might not otherwise see.

The Journey to Sustainable Aviation

Airlines are experimenting with a host of sustainable fuels, electric aircraft, hybrid electric/fuel planes and new operating techniques.

Below view of a plane with a trail against a blue sky with wispy clouds

KEY TAKEAWAYS:

--As aviation tries to get to net zero, innovations such as sustainable aviation fuels (SAFs) can reduce emissions by 80%, or even more.

--Insurers can play a key role in helping their clients de-risk the transition, such as by insuring the construction of SAF manufacturing facilities or the installation of SAF refueling infrastructure at airports.

----------

The aviation sector has pledged, like most, to reach net zero by 2050. From the International Air Transport Association (IATA) commitment to "Fly Net Zero" to the declaration from the International Aviation Climate Ambition Coalition at COP 26, the air transport industry is not short of promises to dramatically reduce its carbon footprint.

Compared with some other sectors, aviation is a relatively small contributor to global greenhouse emissions – in 2019, it was estimated to account for around 2.5% of the world’s CO2 emissions. However, it is also one of the fastest-growing, and there is little doubt that every major airline and aerospace manufacturer in the world now has its environmental impact front and center, a topic that is vertiginously ascending the corporate priority ladder. But what does the flight path to a more sustainable future look like for the industry? And how realistic are the lofty goals that have been set?

The first, and most obvious, conclusion is that there is no silver bullet. Potential solutions abound, but there is no answer likely to single-handedly push aviation to net zero. The second is that, pressure groups and activists aside, intermediate decarbonization goals are linked to commercial aims – stating the obvious, the more efficiently an aircraft burns fuel the better for all concerned. Longer term, however, the aviation industry may need assistance from both its insurance and other financial, partners in de-risking the transition, as the costs associated with change are a significant, but not insurmountable, barrier to progress.

Clearing the Runway for Sustainable Aviation Fuels

The sector certainly abounds with initiatives to aid the transition. The first likely to have a tangible effect is sustainable aviation fuels (SAFs), with many airlines looking to increase their usage (10% is a commonly selected target). As part of the "Fit for 55" package, which sets out an initial target of  a reduction in emissions by 55% in 2030 (compared with the level of 1990), the EU will require every flight leaving its airports to carry a minimum amount of SAF (2% in 2025 and 5% by 2030).  Meanwhile, the U.S. wants to increase the production of SAFs to three billion gallons per year by 2030. While these commitments are welcome, the production of these alternative fuels remains small.

SAFs can be split into three buckets – those recycled from waste products (for example, from used cooking oil), those created directly from crops and synthetic fuels (created by processing recovered carbon dioxide with green electricity). With the commercial aviation world requiring approximately 95 billion gallons of traditional kerosene aviation fuel in 2019, according to IATA, the recycled or grown SAFs suffer from a lack of available resources (short of diverting all global agriculture toward the endeavor) while large-scale production of synthetic fuels will require cheap, high-volume green electricity. 

The price of SAFs is double that of fossil fuels price today, so the dramatic ramp up of SAF production will require significant capital expenditure and initially government incentives are likely to be required to offset the price premium. It will be worth the time, cost and effort. SAFs can result in an 80% reduction of lifecycle emissions (as the only true emissions come from processing steps). The technology is proven and certified (having already been used on over 200,000 flights), and no changes are required to existing aircraft – SAFs can be used interchangeably with kerosene. 

There is also a key role for insurers to play in helping their clients de-risk the transition to SAFs – supporting the construction of new infrastructure and the adoption of different fuels. For example, insuring the construction of SAF manufacturing facilities, or the installation of SAF refueling infrastructure at airports. Insurers may even be able to assist their clients with hedging to allow airlines to protect themselves against SAF price fluctuations.

Ready for Take-off? Electric and Hybrid Aircraft

While SAFs will be the short- to medium-term workhorse, perhaps the more exciting future developments are the new air travel technologies that remain nascent but capture the imagination more than a simple fuel switch. The electric aircraft revolution is firmly underway, with more than 200 global companies developing concepts. Several have even completed test flights, and the appeal is obvious: Electric aircraft have no climate impact during operations. They are a thrilling proposition. 

However, the biggest issue remains technological maturity – in particular, battery density and the associated range. Batteries will need to be at least five times denser than current lithium-ion batteries, and it is not currently thought that true electric aircraft will ever have a range greater than 500 to 1,000km – although it is estimated that half of all global flights are shorter than 500 miles. Electric aircraft also remain relatively far off, with 2040 probably a realistic date for entry into service. There will also be an arduous process of certification of such new types of aircraft, with regulators (quite rightly) needing to know that the new technology is safe before allowing consumer usage.

So what for long haul? The answer may rest with hybrid aircraft. A concept familiar with road vehicles, but likely to be a blend of electric technology and hydrogen propulsion rather than involving traditional fossil fuels. This is certainly the approach being taken by Airbus, which hopes to develop the world’s first zero emission aircraft by 2035, with its three ZEROe concepts. The aircraft are powered by hydrogen combustion through modified gas turbine engines. In addition, hydrogen fuel cells create electrical power that complements the gas turbine, resulting in a highly efficient hybrid-electric propulsion system. While not as efficient as pure electric aircraft, hybrid aircraft will be able to provide a range out of reach of electric alone. They will also be able to carry greater number of passengers and offer a realistic alternative to kerosene-powered long-haul routes.

Such hybrid aircraft may seem like the nirvana, but they are not without drawbacks. Hydrogen storage and usage, of course, brings safety concerns. While hydrogen processing has been used for years in oil refineries and the fertilizer industry, aviation represents a new road to travel. Happily for its passengers, the aviation world is safety-obsessed. All parts of the industry (transport, storage, usage, etc.) must pass rigorous safety tests. Current aviation protocol is based on the fossil fuel-powered jet engine – a technology that has been around for decades. There will need to be a wholesale shift from regulators and companies to embrace a new safety environment.

Insurers can, of course, help by providing cover for new and test products and assisting their clients in de-risking the evolution to new technology. This could include insuring electric and hybrid aircraft types through their testing phases and as they move into service, or creating an insurance safety net for a company’s R&D operations. Such a technological leap is not without risk, and companies (both manufacturers and end users) will hugely benefit from the support of their trusted partners as they adapt for the future.

See also: Aviation Risk Trends Post-COVID

Don’t Forget About Marginal Gains and Design Efficiencies

While they are the future, both electric and hybrid technologies will not be available tomorrow, and, along with SAFs, there are shorter-term, more mundane gains to be made from the aviation industry. One of the key areas for such gains is operational efficiency, and there is nothing to stop all aircraft operators looking at this side of their business and making changes now.

A combination of operational levers can drive emission reductions at scale. Examples can include pre-flight via mission tailoring and fuel planning (i.e. ensuring the right aircraft is being used for the right flight); on the ground via traffic management (to reduce the time engines are on in traffic); during approach and descent via better air traffic management (to reduce holding time) and adapting climb and descent procedures (to spend longer at optimal cruise altitude); during cruise via dynamic routing (responding to changing weather patterns); and after flight via preventative maintenance and cleaning.

There are plenty of airlines already embracing these marginal gains. Over 40 airlines have partnered with Sky Breathe – technology that uses artificial intelligence (AI) to analyze billions of data records from all types of sources, including flight data recorders, operational flight plans and Aircraft Communications Addressing and Reporting Systems (ACARS), before combining them with environmental data from actual flight conditions (such as payload, weather conditions, Air Traffic Control (ATC) constraints, etc.). It then identifies the most relevant saving opportunities and provides a series of recommended actions that it claims can reduce total fuel consumption by up to 5%. 

There are also improvements that can be made to existing aircraft design to drive fleet efficiencies. This mostly comes through the incremental introduction of enhancements (for example, wingtip, blended winglets or increased wingspan) and improvements to engine efficiency. None of these improvements will drive the industry to net zero, but they will all play a vital role in reducing emissions intensity of the aircraft and inch aviation further on its journey toward a more environmentally friendly future. 

This is the broader picture in a nutshell. There are many exciting developments, each with a part to play. Some will grab the headlines and appear to be futuristic leaps; others will go unremarked but are just as important. No one development can help the industry singlehandedly. Instead aviation will look at multiple solutions and there is risk and barriers to each.

Given the uncertainty, there has never been a more important time for insurers and other financial partners to support their clients as they take the steps necessary for a net zero future.


Tom Fadden

Profile picture for user TomFadden

Tom Fadden

Tom Fadden is global head of aviation at commercial insurer Allianz Global Corporate & Specialty. Fadden has more than 30 years of aviation insurance experience.

Say Goodbye to Cyber's 'Dating Profile'

It's time to move past vague questions that try to determine companies' resilience to cyber attacks and move to precise, data-based ratings.

person holding a high-tech tablet with a projected screen

KEY TAKEAWAYS:

--Seven factors are highly predictive of vulnerability to a breach.

--They can be measured precisely, using questions that go far deeper than the standard Yes/No questions like, "Do you have a software patching cadence in place?"

--The seven factors can be monitored continuously, providing an up-to-date understanding both to the insurer and to the client.

----------

Cyber insurance policy application forms are the equivalent of a dating profile. You don’t really know if the person’s picture is up to date, or if what they’re saying about how much they drink and what they do for a living is true. And the cyber applicant isn't necessarily even being deceptive. The person who filled out the profile may not have an accurate understanding of themselves, so how could they give you the complete picture? 

For cyber insurance companies to provide optimal quotes and manage their risk exposure, they need a comprehensive and predictive view of risk -- and it needs to be the same view that policyholders have. 

Questionnaires about insureds’ cyber hygiene and honor system-based notice of circumstance declarations are insufficient. Enter security ratings. As attack surfaces grow, as the number of connected devices increases and as breaches become more prevalent, this continuous, external scanning provides an always-updated view of risk—both of an organization and of its third and fourth parties.

By mapping out digital assets, observing events and settings on these assets and correlating them to cyber incidents, SecurityScorecard assigns an A-F rating and a score of 1-100. Ratings are entirely evidence-based, scored on an underlying and transparent observation from scans of the entire IPv4 space. 

Win-win cyber risk management for insurance providers and policyholders

Together, Marsh McLennan Global Cyber Risk Analytics Center and SecurityScorecard studied how cybersecurity ratings can help insurance companies provide quotes and manage their risk exposure while also offering customers the opportunity to improve their security posture.

We found seven factors that are most predictive of a breach. They are:  

  1. Endpoint Security: Looks at the security of an organization’s operating systems, web browsers and related active plugins
  2. Patching Cadence: Analyzes how quickly an organization installs security updates
  3. Ransomware Score: Measures how susceptible the organization is to a ransomware attack
  4. Network Security: Checks public datasets for evidence of high-risk or insecure open ports within the organization’s network
  5. DNS Health: Measures the health and configuration of an organization’s DNS settings. 
  6. IP Reputation: Uses the SecurityScorecard data, open-source malware information and third-party cyber threat intelligence data-sharing partnerships to assess the reputation of an organization’s IP addresses
  7. Cubit Score: Measures a variety of security issues that an organization might have to identify whether it is adhering to best practices

Taking the steps to mitigate risk associated with these factors will significantly strengthen an organization’s security. 

See also: Why Cyber Strategies Need Personalization

How predictive are the seven factors of cyber risk? 

Let’s get nerdy. To discover which factors are statistically significant, we combined incident data from Marsh McLennan with SecurityScorecard’s ratings data, dating back to 2018. We enriched the incident data with firmographic data including North American Industry Classification System (NAICS) industry codes and company revenue. The joint data sets gave us approximately 12,000 unique, globally distributed entities covering a range of revenues and industries. 

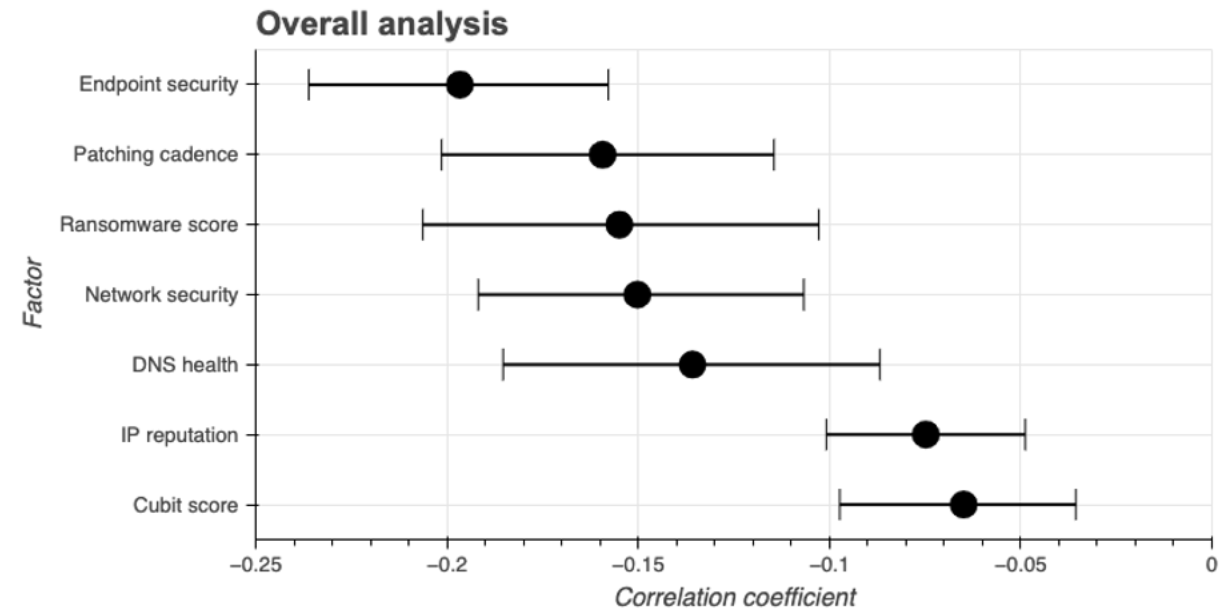
The chart below shows the 95% “confidence interval”—meaning that there’s a 95% probability that the results will fall within these parameters—of the “correlation coefficient,” the statistical relationship between two variables, for all of the entities in the study. 

Overall analysis of endpoint security, IP reputation, DNS health, and ransomware score

Keeping in mind that a correlation of -1 indicates perfect correlation, these results suggest that the seven factors have strong predictive power. 

As you can see, endpoint security is the strongest predictor of a cyber incident overall. [The Cybersecurity Infrastructure and Security Agency (CISA) recognizes the importance of endpoint security, as well. They issued an alert that identified common exploitation vectors and recommendations for mitigation.]

See also: Cybersecurity Trends in 2023

Security ratings boost cyber resilience

The need for cyber insurance is growing, yet only 55% of organizations have policies. And even though enterprises spend a mean of $2.4 million to find and recover from a breach, only 20% have coverage of more than $600,000. 

It behooves both cyber insurers and their policyholders to take the steps necessary to improve cyber resilience. 

In addition to providing a way to quantify and assess risk, security ratings allow providers to stop asking simple questions that require complex answers. Rather than asking a binary "Yes or No" question like, “Do you have a software patching cadence in place,” they’re able to answer complex questions like, “Do you have any high-severity CVEs in your environment, and if so, how long have they remained unpatched?” This is the level of detail required to underwrite cyber risk in the 21st century, and it’s why security ratings are becoming a bigger part of insurers’ profitable growth strategies.

Security ratings and data offer a transparent, two-sided view that reduces information asymmetry so that all interested parties can better understand and measure cyber risk. 

And being aware of the seven factors most predictive of breaches can inform underwriting strategies and help the industry move toward a more sustainable future. A historical view over at least a year is also important, because most cyber policies are written on a claims-made basis. A data breach or other cyber compromise can take many months to come to light, and it’s smart to avoid underwriting an organization in the midst of one. 

Using ratings in underwriting strategies supports insurance companies to more accurately evaluate cyber risk exposure and inform risk selection decisions. Knowing which way to swipe, as it were, drives an efficient risk transfer market with all interested parties on the same page. This helps make all of us—and the world—safer.

The End of Passwords

A Google announcement means we will all soon employ "passkeys" instead of passwords, greatly increasing security -- and ease of use.

Image
Typing on laptop

When brilliant young physicist Richard Feynman ran a group of scientists at the Los Alamos Laboratory that developed the atomic bomb during World War II, he embarrassed security personnel by using a screwdriver to routinely pick the locks on the filing cabinets that contained the facility's most sensitive secrets. He might taunt security by leaving the filing cabinet open or might close the cabinet and just leave a note inside for his colleague saying something like, "Thanks for letting me borrow XYZ document." Security finally got the message and installed locks that each had a million combinations -- and Feynman picked those, too.

For years now, hackers have likewise been exposing the vulnerabilities in the world's attempts at cybersecurity. But an announcement by Google last week means that we are headed toward closing one of the biggest security gaps that hackers exploit: passwords. 

The change won't happen overnight, but it will happen -- accelerated by Google's move into what are called passkeys. The technology requires that we merely have physical possession of our phone or computer and can authenticate ourselves to it through face recognition or other biometric measure. The passkey then handles all sign-ins to our apps and websites, using heavy-duty encryption. 

We users will no longer be required to remember all the different passwords that we're pinged to recreate every six weeks or so, based on the host of different standards that different apps and websites require -- which, in practice, of course means that we're constantly resetting passwords.

Companies will see security increase greatly because employees will no longer use passwords that are trivial for hackers to guess -- the four most common passwords currently are 123456, 123456789, qwerty and password -- and will no longer be vulnerable to phishing attacks that trick them into giving up their passwords.

Insurers will likewise be able to breathe a bit easier -- and adjust premiums accordingly -- as the threat via password theft diminishes. And the industry as a whole will do a better job of protecting all the sensitive information it has about customers, information that hackers try so hard to collect. 

The FIDO Alliance has been rolling out passkeys for a year, and an article in Wired says many companies, including PayPal, Shopify, CVS Health, Kayak and Hyatt, already offer customers the ability to access their accounts via passkeys.

But the article quotes Andrew Shikiar, executive director of the FIDO Alliance, as saying the Google move to passkeys is an inflection point. "A company like Google," he says, "enabling this with so many people actually seeing passkey sign-ins, they’ll be more likely to use them elsewhere. And it will also accelerate other companies’ deployment plans and help them deploy better, because we will learn from this as a body."

The transition from passwords to passkeys will now surely enter the chicken-and-egg phase that just about every new technology faces. Even though the benefits of passkeys are so clear, not a lot of companies will feel the need to offer the option soon, because customers aren't demanding that they do so, and customers won't lean into passkeys right away because not enough companies are offering the option.

Glitches will also slow adoption. For instance, when I try to sign up for a passkey via Google, it prompts me to sign into my gmail account, but I don't use my gmail account. I'm not going to start using gmail as my default just to get access to a passkey, so I'll sit this one out for now.

Once the transition to passkeys builds, insurers will -- or at least should -- encourage it by offering discounts to companies that improve their security by mandating a switch. And when we hit the tipping point in perhaps a couple of years, the transition to passkeys should be so rapid that, as FIDO's Shikiar put it, the World Password Day that was celebrated last week is "going to be like World Horse and Buggy Day."

Cheers,

Paul

P.S. Much of Feynman's picking of the supposedly hyper-secure locks just took advantage of combinations that were the equivalent of a password like 123456. Even at what was supposed to be the world's most secure facility, among some of the world's smartest scientists, one in five never changed the simple, default combination that the factory set and that Feynman knew.

As for the rest of the safes, he found that he only needed to be within two of the correct number in a combination for it to work, so the 100 digits on the dial really only meant he had to try 20 possibilities. With a three-number combination, that still meant trying 8,000 combinations on each safe -- except that he learned that he could see the final two numbers in a combination if he could fiddle with the lock while the cabinet was open. And he was eccentric enough that nobody paid much attention as he played with their lock while in conversation. He'd write down the final two numbers for each safe, then just have to try 20 combinations to open it. 

As much as he frustrated security, he came in handy when a document was needed from a filing cabinet whose owner was off the premises. Whoever needed it would just ask Feynman to pick the lock. Feynman would promise to do so, but only if no one watched. He'd pick the lock within a minute, take out a book and read it for half an hour or so, then open the office door and accept thanks for how hard he'd worked to pick the lock and retrieve the document.

Future Is Here for Fraud Detection

The future of fraud is here, but so is the future of fraud protection. Decision intelligence saves thousands of hours of manually searching through risk anomalies.

Close-up image of a person typing on a keyboard with bright green words on a black screen

KEY TAKEAWAYS:

--Taking the mass amounts of data that customers have and connecting all the dots into a single view is the first thing advanced AI can help insurers to achieve.

--Insurers can then spot industry trends that lead to vulnerability, identify behavioral patterns that point to fraudulent activity and stop wasting time on false leads.

----------

Worldwide inflation is back -- and interest rates are playing catch up. This affects everyone. Businesses. Consumers. Employees. The government. And financial pressure means there is an increased chance that some will partake in illegal activity.

They may look to claim across business lines, making claims that were never needed in the first place. In some instances, some may even make the same claims twice.

Almost more threatening than customers taking advantage is potential for insider involvement. Those who know the ins and outs of the system are much more dangerous. Employees and customers alike may see these crimes as victimless, falsely believing they are taking from faceless corporations. The catch is that insurance fraud depletes funds and forces honest customers to pay higher premiums, creating victims oblivious to the crime.

These crimes often come in the form of digital minds being used to bypass application controls through fast and clever identity switching. Without the technology to interpret these duplicates and paint a single view across all brands and channels, hidden connections will stay hidden and fraud is made possible.

The FBI estimates that fraud costs the average family between $400 and $700 a year in premiums alone. Insurance companies have access to masses of data that is getting harder to protect as fraud crimes advance and their set of challenges increases.

For one, the unfathomable amount of data that businesses have access to allows risk to hide in the reeds. Insurers can no longer rely on rules-based AI models to detect fraudulent behavior, because digital automation has increased, and data is more complex than ever.

According to the Coalition Against Insurance Fraud, fraud costs business and consumers more than $300 billion a year.

Why is the insurance industry so vulnerable? For one, insurance is not homogenous. The industry changes drastically across sectors and has access to data from various parties. Many big insurers have customers in many industries, but also insure personal assets.

See also: How to Balance CX and Fraud Detection

Insurance companies that operate globally have to deal with the intricacies of the industry around the world -- and data from every corner. Companies need to fit into the landscape of each of their globalized markets but fraud looks different everywhere.

There's only one answer to fight fraud in the current climate: Insurers must arm themselves with the right technology. Centralized and contextualized risk management is how insurers can get ahead of fraud against a backdrop of economy instability and crime.

Paint a single view of your customers

Taking the mass amounts of data that customers have and connecting all the dots into a single view is the first thing advanced AI can help insurers to achieve.

One streamlined data foundation will give insurers a contextualized view of the business. It allows them to:

  1. Spot industry trends that lead to fraud vulnerability or security weaknesses -- If insurers can look at their customers as a single entity against the backdrop of their industry, they'll be able to compare notes on competitors and better protect their customer.
  2. Identify behavioral patterns that point to fraudulent activity -- Individual and group behavior is becoming harder to identify as fraud technology advances. Picking out patterns from behaviors across companies will allow for bigger-picture insights.
  3. Clarify the difference between opportunity and risk within these behavioral anomalies -- Bigger-picture insights can actually lead insurers to being more precise. Insurers can stop wasting their time on outliers and start seeing risk more clearly.

Once companies are able to sift through data in this single-view contextualized way, they'll be able to mitigate risk. The most valuable thing that new technology can give insurers is the ability to predict. Being proactive rather than reactive is incredibly important in times like today.

See also: How Blockchain Can Disrupt Insurance

Ease decision making

Given that insurance fraud and the advancements in economic crime changes constantly, it's difficult for individual business leaders to keep up.

The only way to fight advanced fraud and financial crime is by applying more advanced tech. Decision intelligence does just this by allowing insurers to focus on client services and not spend countless hours prying through potential risk anomalies and figuring out how to act. Intelligent platforms are available to make the decisions efficiently and accurately.

Global insurers must rely on intelligent platforms to make the difficult, high-level decisions that come from extortionate amounts of data. Providing humans with the right data and right technology allows them to make the right decisions. AI is not making the decisions, but automating processes to empower humans to make accurate and timely choices.

Insurers will find themselves less and less capable of facing fraudulent activity if it's concealed within a dark cloud of difficult decisions and data -- it needs to be uncovered.

The future of fraud is here, but it brings the future of fraud protection, too. As criminals are using increasing complex and sophisticated techniques and the economic climate continues to worsen, insurance companies must arm themselves with the right technology to win the battle.


Ivan Heard

Profile picture for user IvanHeard

Ivan Heard

Ivan Heard is the global head of fraud for Quantexa, a global big data and analytics software company.

Insurance Is Not a Commodity

But, with carriers running so many ads focused on price, agents need to work hard to get consumers to focus on the differences between policies.

Four people around a desk with laptops open and a bulletin board hanging

KEY TAKEAWAYS:

--To combat the misperception of insurance as a commodity, agents need to start by taking an active role in the buying process and educate customers about the nuances in policies.

--Agents must get customers to focus on the risks they face and the appropriate coverages, not on the price.

--Finally, agents need to individualize their sales approach -- focusing less on serving lots of clients and more on serving each client well.

---------- 

Although insurance was once governed by relationships, product knowledge and market access, it has evolved into an industry driven by price and the simplicity of the service provided. Many consumers now view insurance as a mere commodity. In fact, each policy and carrier is unique in the coverage they provide and in their underwriting and claims processes. But how can insurance agents challenge the perception of insurance as a commodity?

They must educate consumers, emphasizing the differences in policy coverages. Leveraging their product knowledge in tandem with technological developments, insurance agents can solidify the need for an expert-level resource in providing these complex product offerings to consumers. 

Why Is Insurance Viewed as a Commodity? 

Multiple factors have contributed to the perception of insurance as a commodity. For starters, digitization allows consumers to purchase coverage online directly from a carrier. Without a dedicated insurance agent consulting on which coverage is right, consumers naturally focus on price. 

Additionally, the insurance industry itself has been pushing price as the sole distinguishing factor. Consider the advertising campaigns for Geico and Progressive, two industry titans with a combined market share of 25%. Geico’s tagline, “15 minutes can save you 15% or more on car insurance,” has been embedded into our brains through advertising. Progressive’s “name your price” advertising further cements the idea that insurance is a commodity. 

How Can Agents Challenge the Perception of Insurance as a Commodity? 

Having consumers view insurance as a commodity might be good for direct writers, but it doesn’t do much for independent agencies. Here's how agents can reshape the narrative: 

Play an Active Role in the Buying Process 

As an insurance agent, your customers rely on you. While it might be tempting to service as many customers as you can as quickly as possible, it is more beneficial for both your business and the consumer to craft a service approach personalized to each customer.

Your main selling points are your customer service and expertise. Lean into these attributes by guiding your customers through each step of the buying process, showing them why they made the right decision in using an agent rather than purchasing coverage online directly through a carrier. 

Educate Your Customers 

Educating your customers on the differences between policies is crucial. While big carriers have spent millions to convince consumers to focus on price, your job is to help your customers understand the additional factors at play. Your customers might think they know what they need, but a whopping 60% of consumers admit they don’t do any research before obtaining coverage.

What's the best way to provide context and information to your customers? Well, a conversation goes a long way toward understanding their specific needs and creating an opening for offering advice. Creating visual aids and providing easy-to-understand brochures on key policy differences can help. 

See also: Selling Insurance in a Commoditized World

Focus on the Risks 

67% of consumers are willing to purchase insurance from organizations other than insurers. This is a major problem, as consumers who purchase coverage online do not receive the same level of risk analysis as is provided by insurance agents. If an accident occurs, your customer will be grateful their agent spent the time ensuring their needs were met. By focusing on the risks facing your customers, you help them understand that insurance is not about getting the best deal but rather about obtaining the best coverage. 

Individualize Your Sales Approach

21% of consumers say insurance providers do not tailor their customer experiences. Don’t solely rely on sales scripts or rehearsed talking points. Rather, get to know each customer on a personal level. Chances are new customers aren’t well-versed in the different policy coverages available, and you can provide expert advice that no algorithm could ever replicate.

What Does the Future Hold for the Insurance Industry? 

People will always need insurance. It is what allows us to conduct business and engage in many aspects of our daily lives. And, no matter how much money carriers spend to advertise their low prices, one fact will never change; People need agents to help guide them through the intricacies of the insurance industry.

Your job as an insurance agent is very important. You ensure your customers are protected in the event of an accident. You ensure they make it out okay in whatever situation they are facing.

It may at times seem that the industry is trending toward further automation, but by providing expert-level product knowledge and engaging with customers you can leverage technology in a way that enhances the insurance purchasing experience rather than driving it to the lowest common denominator: price.

It's Time to Talk to Homeowners

Incentives for green home improvements create a need for insurers to educate clients on nuances and open up opportunities for conversations.

Overhead view of a neighborhood cul-de-sac

KEY TAKEAWAYS:

--Adding solar panels may increase the value of a home by tens of thousands of dollars, creating a need for more coverage -- but some policies specifically exclude solar panels.

--Another conversation to have about solar panels has to do with where they will be installed — detached structures typically are covered only at a fraction of the main structure’s value.

----------

As homeowners look to take advantage of the new tax credits for green home improvements, insurance professionals should see this as an opportunity to show them what insurance implications those upgrades may hold. 

Solar panels, battery arrays, wind turbines and even LEED certification could all have impacts on a homeowner’s policy, depending on the policy language, and communicating those nuances will be key to maintaining positive customer relationships.

The first basic rule governing insurance to communicate regarding environmental home upgrades should be that they tend to be the same as any upgrade for the home — if it is permanently attached to the home, it should automatically be covered by the homeowner’s policy. But that doesn’t mean installation isn’t a prime opportunity to open a communication channel with the customer. 

One reason is that many homeowners may not realize that their upgrades will increase the value of their homes. A solar array could add tens of thousands of dollars to the home’s value, for example. If the homeowners’ insurance isn’t increased to match, that may mean that in the case of a disaster or loss, they could end up underinsured and without enough coverage to cover the home and the new energy efficient upgrade in a total loss.

Nobody wants to be the agent on the other end of that call explaining why the policy is insufficient to rebuild.  

Another reason to talk to the customer is that some policies specifically exclude solar panels. Some lines are excluding some energy-efficient equipment, whether that is because they could get beat up in a hailstorm or because their raised profile could cause them to peel off in a windstorm. Explaining those limitations to the customers is essential so they know what is covered and, more to the point, what is not. 

Lithium-ion, whole-house batteries are a newer addition many homeowners are choosing. These allow the solar systems to operate even after a power outage, which would render other solar systems inoperable, because in a power outage most solar systems shut themselves down so they don’t back feed electricity onto the grid and potentially endanger line workers trying to restore power. But with batteries, the power can be diverted away from the grid and into the battery. 

Then these batteries can feed that power back to the home at night, serving the role that whole house generators play after a disaster, and also banking energy during normal times. 

See also: Homeowners, Renters Are Overlooking Risks

But with new risks comes unknowns. As batteries become more common, it wouldn’t be surprising to see some policies begin to exclude them as potential risks, as well, at least until more risk profiles and loss data comes back on them, so savvy professionals should keep their ears to the ground to see if these limitations do indeed emerge. 

Another conversation to have about solar panels has to do with where they will be installed. If the customer chooses to install them on a detached structure, such as a shed or a detached garage, they will only be covered by that portion of the homeowner’s policy, rather than the main structure’s coverage, meaning it will be subjected to a lower coverage limit and may not have adequate coverage to replace them in a loss. That is a nuance most policyholders won’t pay attention to — detached structures typically are covered only at a fraction of the main structure’s value. 

And if the solar panels are free-standing, like in a field, they almost certainly won’t be covered by a typical policy, because they aren’t permanently attached to the structure. The same applies to wind turbines, which are almost never attached to the home, so this is a real educational opportunity early in the conversation to prevent confusion. 

Federal tax credits are available for upgrading exterior windows and doors using energy-efficient materials. While the contractor is doing that work, the homeowner might do well to also ask whether there are options that might help with their homeowner’s premium. Things like storm-resistant windows or closable storm shutters aren’t strictly covered by the tax credits, but adding them onto the project might not be a huge cost addition with the contractor already working on the energy-efficiency project. 

Federal tax credits only apply to renovations, but if the client is building new construction, one option is to opt for is a builder who is certified under the Leadership in Energy Efficient Design by the U.S. Green Building Council. LEED-certified homes use far less energy than other homes, and a handful of policies are offering LEED certification discounts — often 5% off the annual premium. 

Both homeowner and business customers can also be steered toward policies with a green coverage rider. These are add-on coverage options that pay an additional amount after a claim to allow for the rebuilding to be done with environmentally friendly components and methods. With this rider, building materials will be recycled rather than landfilled, extra insulation will be used and sustainable materials will be sourced — all for an added premium, of course. 

Congress put some significant money behind green renovations when they passed the Inflation Reduction Act, and savvy insurance professionals can use those incentives as conversation starters to show where energy efficiency overlaps with the insurance world. 

From Startup to Market Leader – The Journey of PURE Insurance

PURE Insurance and OneShield share strategies for future-proofing insurance technology in their eBook resulting from a 17-year partnership. From Startup to Market Leader offers guidance for insurance startups and carriers seeking growth and transformation.

House

The insurance industry is at a turning point; while new startups bring innovation, established carriers struggle with limited resources and skills. PURE Insurance has overcome these challenges by following specific technology guidelines for its trusted partners, allowing them to focus on expansion and innovation. PURE’s CIO and OneShield’s SVP share strategies in their eBook resulting from their 17-year technology partnership. From Startup to Market Leader: Guidelines for Future Proofing Your Technology is a valuable resource for insurance startups and carriers looking to transform their technology and achieve growth. 

Read More


Sponsored by ITL Partner: OneShield


ITL Partner: OneShield

Profile picture for user OneShieldPartner

ITL Partner: OneShield

OneShield provides business solutions for P&C insurers and MGAs of all sizes. 

OneShield's cloud-based and SaaS platforms include enterprise-level policy management, billing, claims, rating, relationship management, product configuration, business intelligence, and smart analytics. 

Designed specifically for personal, commercial, and specialty insurance, our solutions support over 80 lines of business. OneShield's clients, some of the world's leading insurers, benefit from optimized workflows, pre-built content, seamless upgrades, collaborative implementations, and pricing models designed to lower the total cost of ownership. 

Our global footprint includes corporate headquarters in Marlborough, MA, with additional offices throughout India.

For more information, visit www.OneShield.com


Additional Resources


What's Driving Innovation for 2023?

Respondents of our 2022 Insurer Tech Survey, reported that their biggest challenges include keeping up with innovation, having sufficient IT resources and staffing to implement critical strategies, and limitations of infrastructure to address new opportunities. We've just launched our 2023 Insurer Innovation Survey, and it's a great opportunity to share your perspectives and predictions – and gain immediate access to the aggregated responses from your peers as they unfold. Please share your outlook today!

Take Survey Now.

Closing the Gaps: Expanding your technology ecosystem

The right strategic approach to technology ecosystems brings competitive advantages to forward-looking insurers. Learn how to creatively leverage third-party applications to enhance customer and agent experiences, enable automation, predictive risk modeling, and more.

  • The role of the digital platform in creating a unique market advantage
  • How digital leaders integrate ecosystem partners to engage customers, extend distribution and develop new business models
  • How nimble players get to market faster with innovative capabilities and products
  • Mission-critical APIs for success in 2022
  • Security and vetting consideration for potential third-party solutions

Read More.