Download

3 Strategies for P&C Insurers in California

Proposed reforms could lead to brighter days for both insurers and consumers, but firms must adjust their strategies.

Golden gate bridge on a foggy day

The property and casualty business is constantly evolving, with occasional seismic shifts that can transform the market – and require quick adaptation. The proposed insurance reforms in California are a prime example of such a transformative moment.

The proposed reforms could lead to much brighter days ahead for both insurers and California consumers. To navigate these changes and make the most of the opportunities presented, P&C insurers must review and adjust their strategies in the market.

This article explores three actions insurers can take to excel in this shifting landscape.

See also: Growing Number of Uninsurable Risks

Write the Lowest-Risk Properties in "At-Risk" Areas

Many carriers have likely put forward new or revised rate filings compliant with the April 2023 deadline of Regulation 2644.9 – and are awaiting California Department of Insurance (CDI) approval of their filing. Until these approvals are received, some carriers may hesitate to write in “at-risk” areas.

That may be an overly cautious approach. 

The reforms proposed would require admitted carriers to write policies in the wildfire-prone parts of the state – and do so for at least 85% of their statewide market share. For example, if a company provides 10% of policies across California, they would be required to provide 8.5% of the coverage in "at-risk" areas.

We expect smart insurers to race to write policies for the lowest-risk properties in these high-risk areas.

Why is this critical?  According to HazardHub data, approximately 25% of properties in the CDI-defined "at-risk" areas are likely profitable with current rates.

Insurers don't have to wait for their last filings to be approved before acting. Identifying these lower-risk properties in "at-risk" areas can give insurers a competitive edge while demonstrating goodwill through early compliance.

Acquire Advanced Analytics

The second action is understanding the importance of high-resolution analytics compared with the existing low-resolution analytics used by most insurers.

Traditional analytic approaches may no longer suffice as they are often (a) insufficiently granular, (b) rely solely on backward-looking data and (c) consider too few variables to assess and differentiate wildfire risk. They also tend to lump all properties into the same risk level across large census blocks or ZIP code regions.

Insurers that quickly embrace more sophisticated approaches will be able to differentiate risk using considerably more variables – and do so at the specific property parcel level instead of the census or ZIP code level.

Insurers that leap forward with advanced analytics will be able to accurately identify, price and manage risk at a granular level, giving them a significant competitive advantage.

See also: Data-Driven Transformation

Reset Strategy and Refile Rate Plans

The third action revolves around resetting strategy and reevaluating rate plans. This will be necessary to align with the proposed reforms and the changing market dynamics. Some steps insurers may take here include:

·         Assessing Current Market Share in the At-Risk Area: Evaluate existing market presence in California's "at-risk" areas, understanding the proportion of policies held in high-risk regions.

·         Defining Risk Appetite: Reexamine and define their risk appetite, recognizing that insurers will be able to charge premiums commensurate with risk.

·         Realigning Marketing Strategies: Adjust marketing strategies to effectively reach and serve homeowners in the state-defined at-risk wildfire regions.

·         Differentiating Offerings for Competitive Edge: In a market where not every insurer can compete solely on price, explore ways to provide added value, such as speed, ease of service and innovative coverage options. This differentiation will attract customers and help insurers meet their "at-risk" market share target.

As California moves forward with these proposed insurance reforms, it is clear that the market is entering a transformative chapter. Insurers must strategically adapt to the changes to excel in this evolving landscape. It is imperative for them to evaluate their market presence, redefine their risk appetite, revamp marketing strategies and explore avenues for differentiation. Embracing state-of-the-art risk analytics is essential to their success, equipping them with the capabilities needed to precisely identify, evaluate and price risk


Roger Arnemann

Profile picture for user RogerArnemann

Roger Arnemann

Roger Arnemann serves as the general manager and senior vice president of analytics at Guidewire Software.

He has over 20 years of expertise in technology solutions, spanning catastrophe modeling, insurance analytics, cyber risk and fintech.

He holds bachelor of arts, bachelor of science and master of science degrees from Stanford University.

Insurtech/Insurance Index — Q3 2023

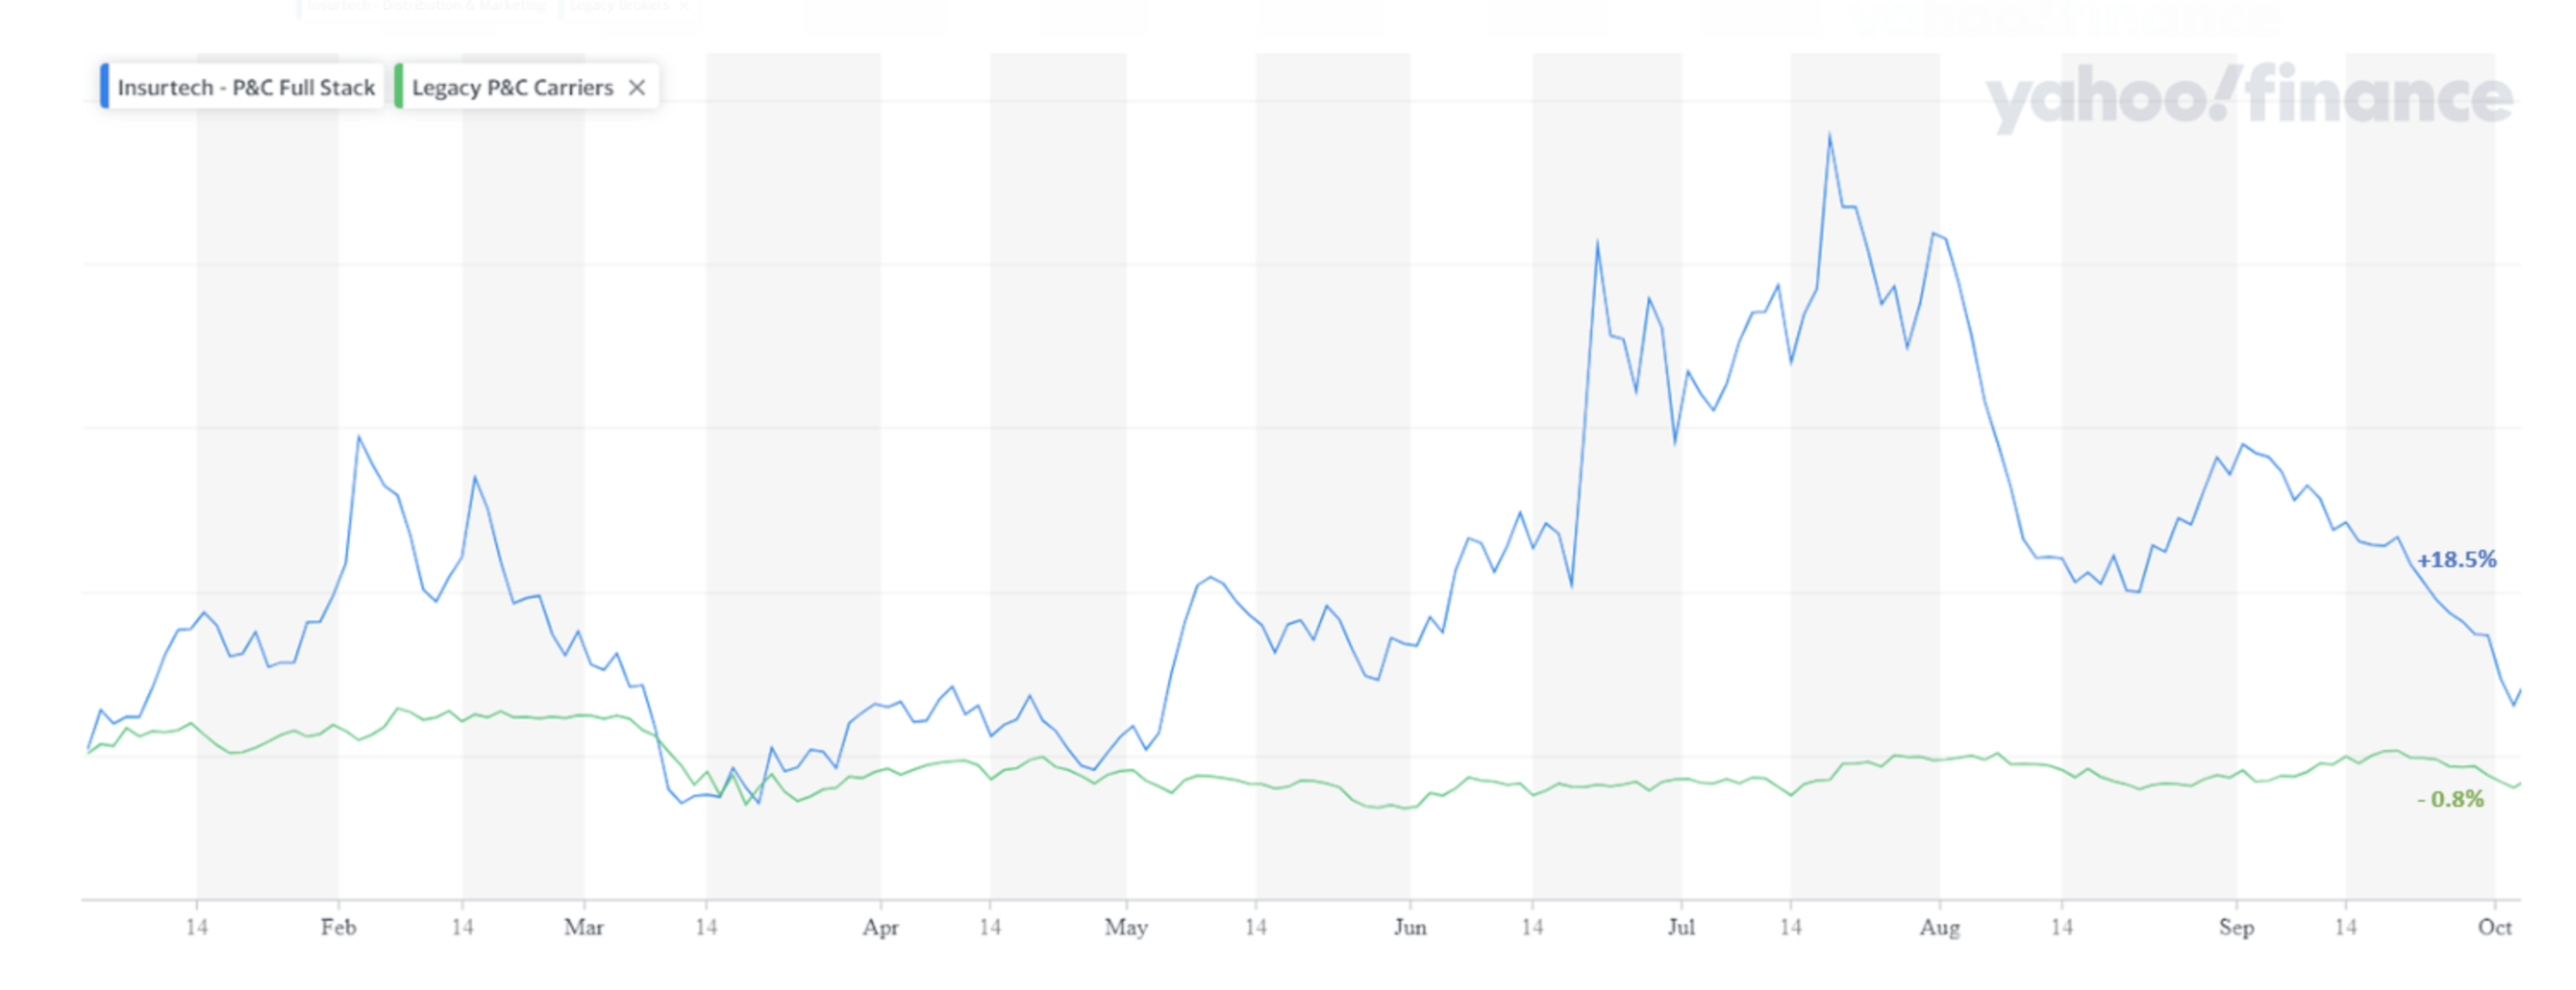
After a Q2 rebound, insurtech carriers reversed sharply over Q3, hit by rising loss ratios and the resulting deceleration in growth.

The Equal Ventures Insurance Index

The Equal Ventures Insurance Index is a quarterly summary of insurance equity performance and trends. We’re back to reflect on the insurance/insurtech ecosystem in Q3, which turned out to be a fairly meaningful quarter in terms of both price action and industry news.

Q3 Headline Summary

  • In Q2, we noted that insurtech carriers rebounded and outperformed; this trend reversed sharply over Q3, as the insurtech carriers in our index were hit by rising loss ratios and the resulting deceleration in growth.
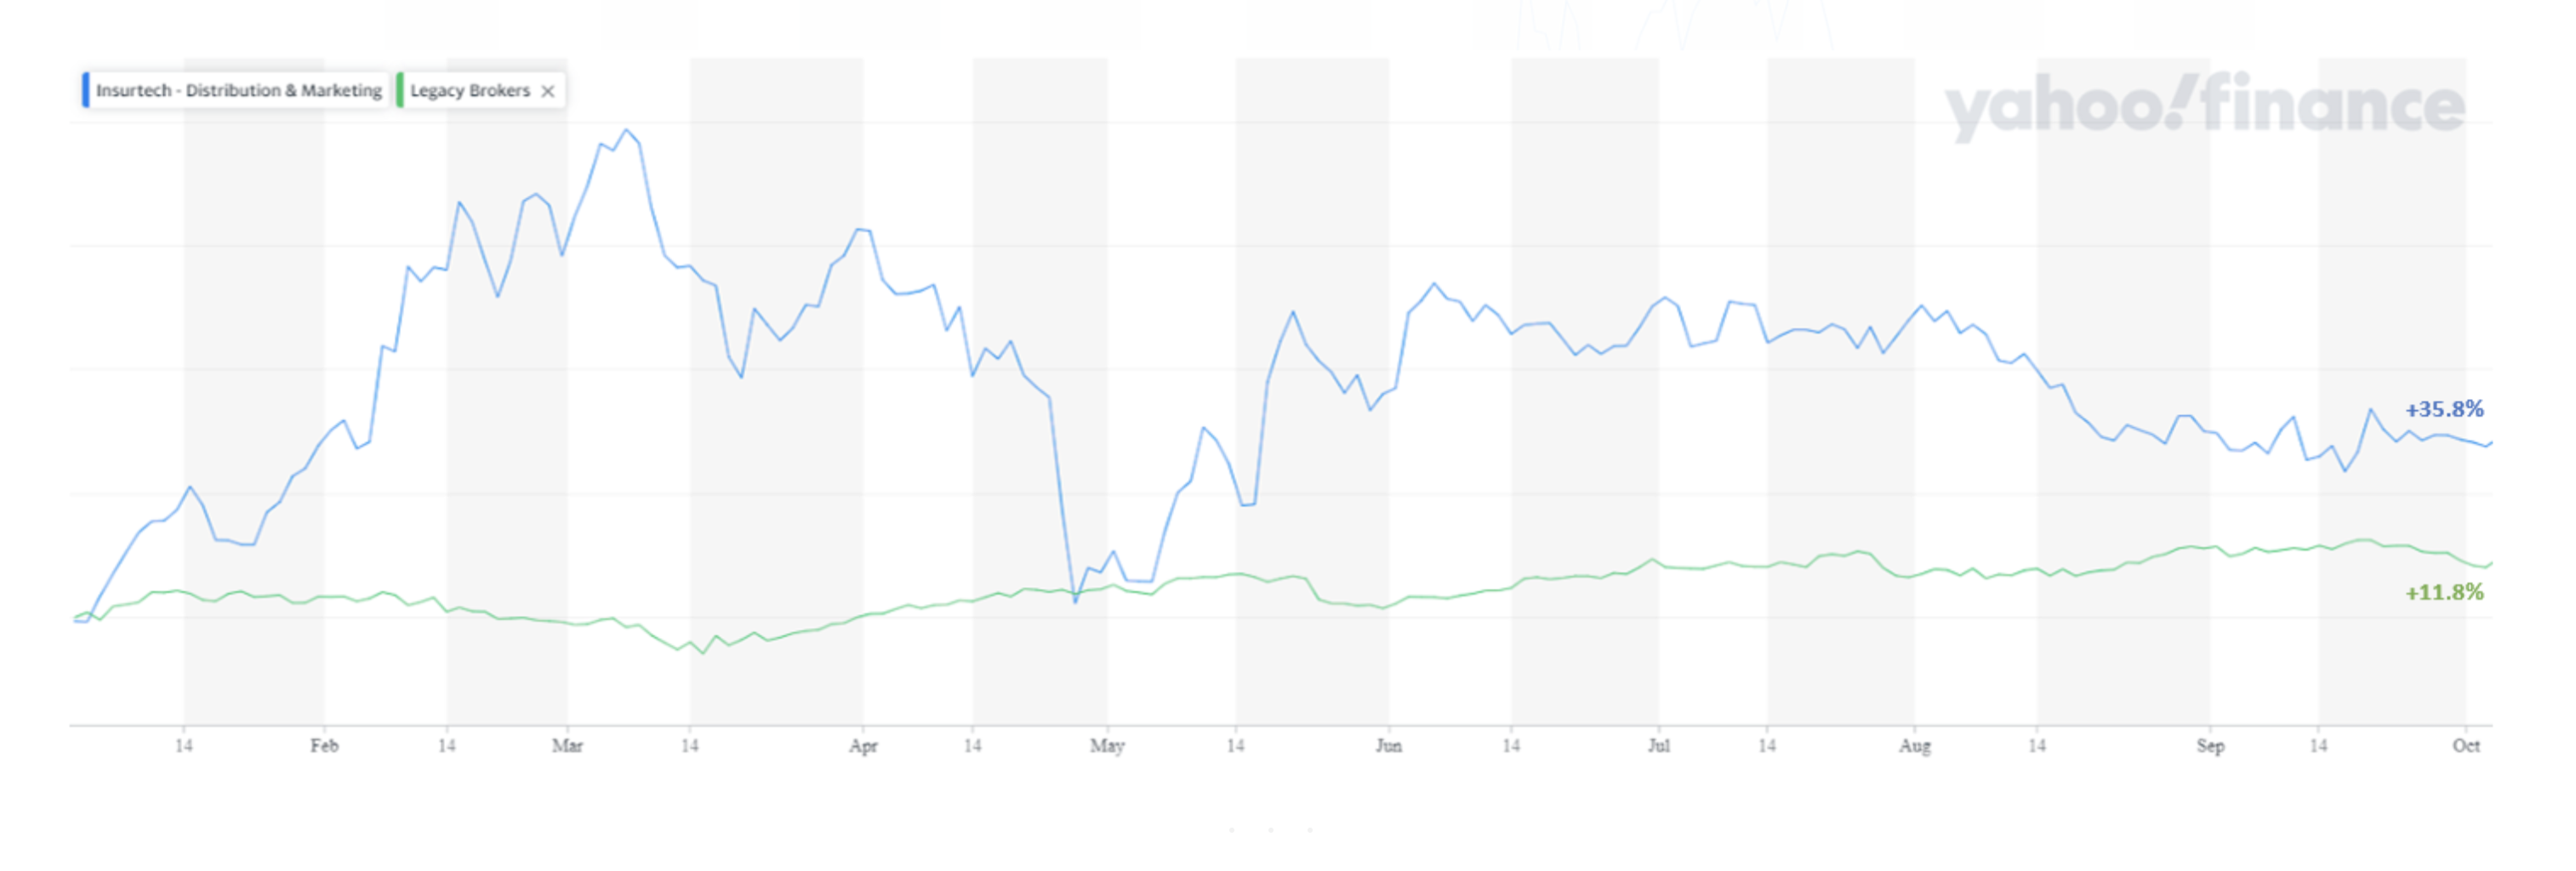
  • Digital brokers once again underperformed their legacy peers, most likely dragged lower as the broader market traded sideways, signaling risk-off for most of small-cap tech.
  • YTD, insurtechs and digital challengers have outpaced their legacy comparables, but the spread in YTD performance narrowed significantly in Q3 (so much for a quick path to valuation recovery…).
  • Legacy brokers and P&C insurers were, on average, flat over the quarter, mirroring the broader market (and also masking larger continuing trends that we discuss in greater detail below).
YTD performance of our index of Legacy P&C Carriers vs. Insurtech challenger carriers; Source: Yahoo Finance as of 9/29/2023
YTD performance of our index of Legacy P&C Carriers vs. Insurtech challenger carriers; Source: Yahoo Finance as of 9/29/2023


YTD performance of our index of Legacy Brokers vs. emerging distribution companies; Source: Yahoo Finance as of 9/29/2023

Takeaways from Q3 Performance

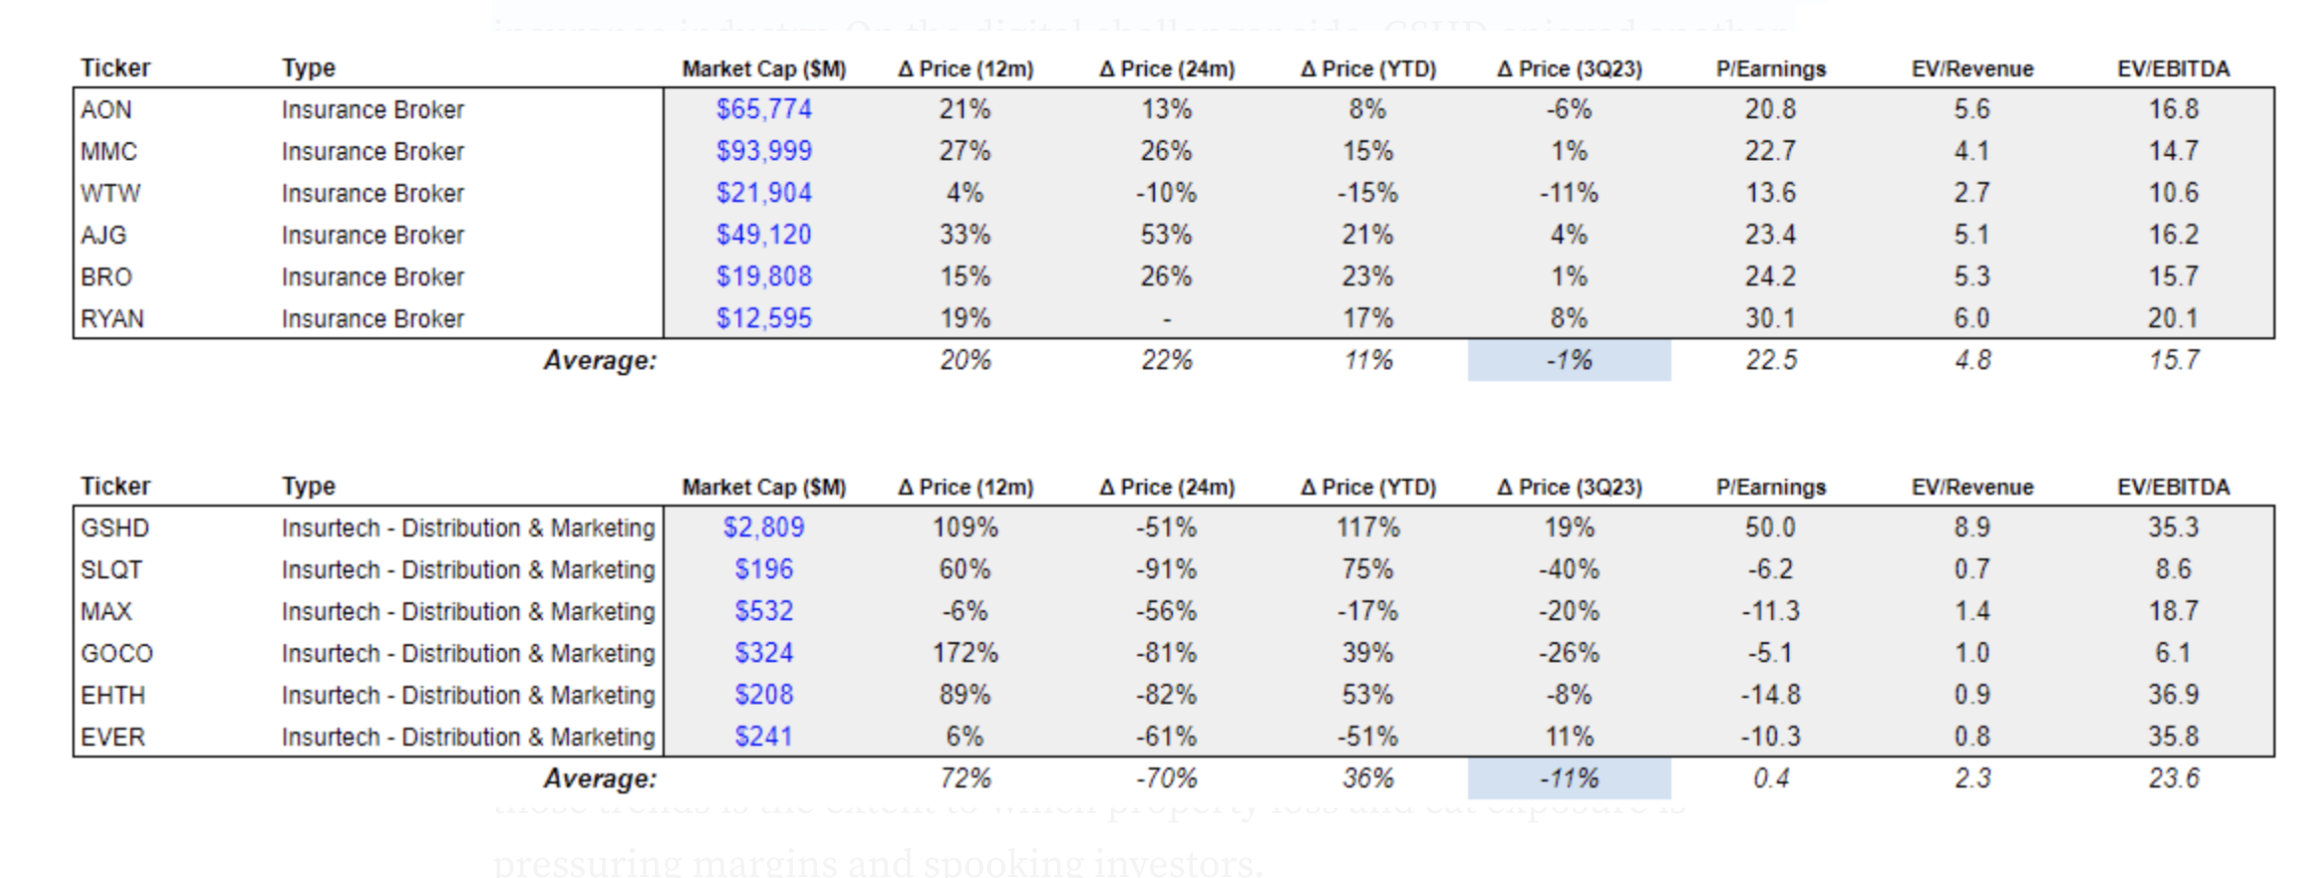
Brokers continue to face a favorable environment as rates trend higher. The legacy names were flat on average in an otherwise choppy market. The index was dragged down by WTW, which reported lower margin and reduced guidance in Q2 earnings in part due to increased investments in talent — pointing to a broader trend in talent management that affects the insurance industry. On the digital challenger side, GSHD enjoyed another quarter of massive outperformance compared with the digital distribution peers we track it against and expanded its already outsized EPS and EBITDA multiples. The lead-gen and digital acquisition companies, on the other front, continued to underperform and for the most part traded sharply lower.

Source: Bloomberg Financial as of 9/29/2023; Earnings, Revenue, and EBITDA are based on forward estimates.
Source: Bloomberg Financial as of 9/29/2023; Earnings, Revenue and EBITDA are based on forward estimates.

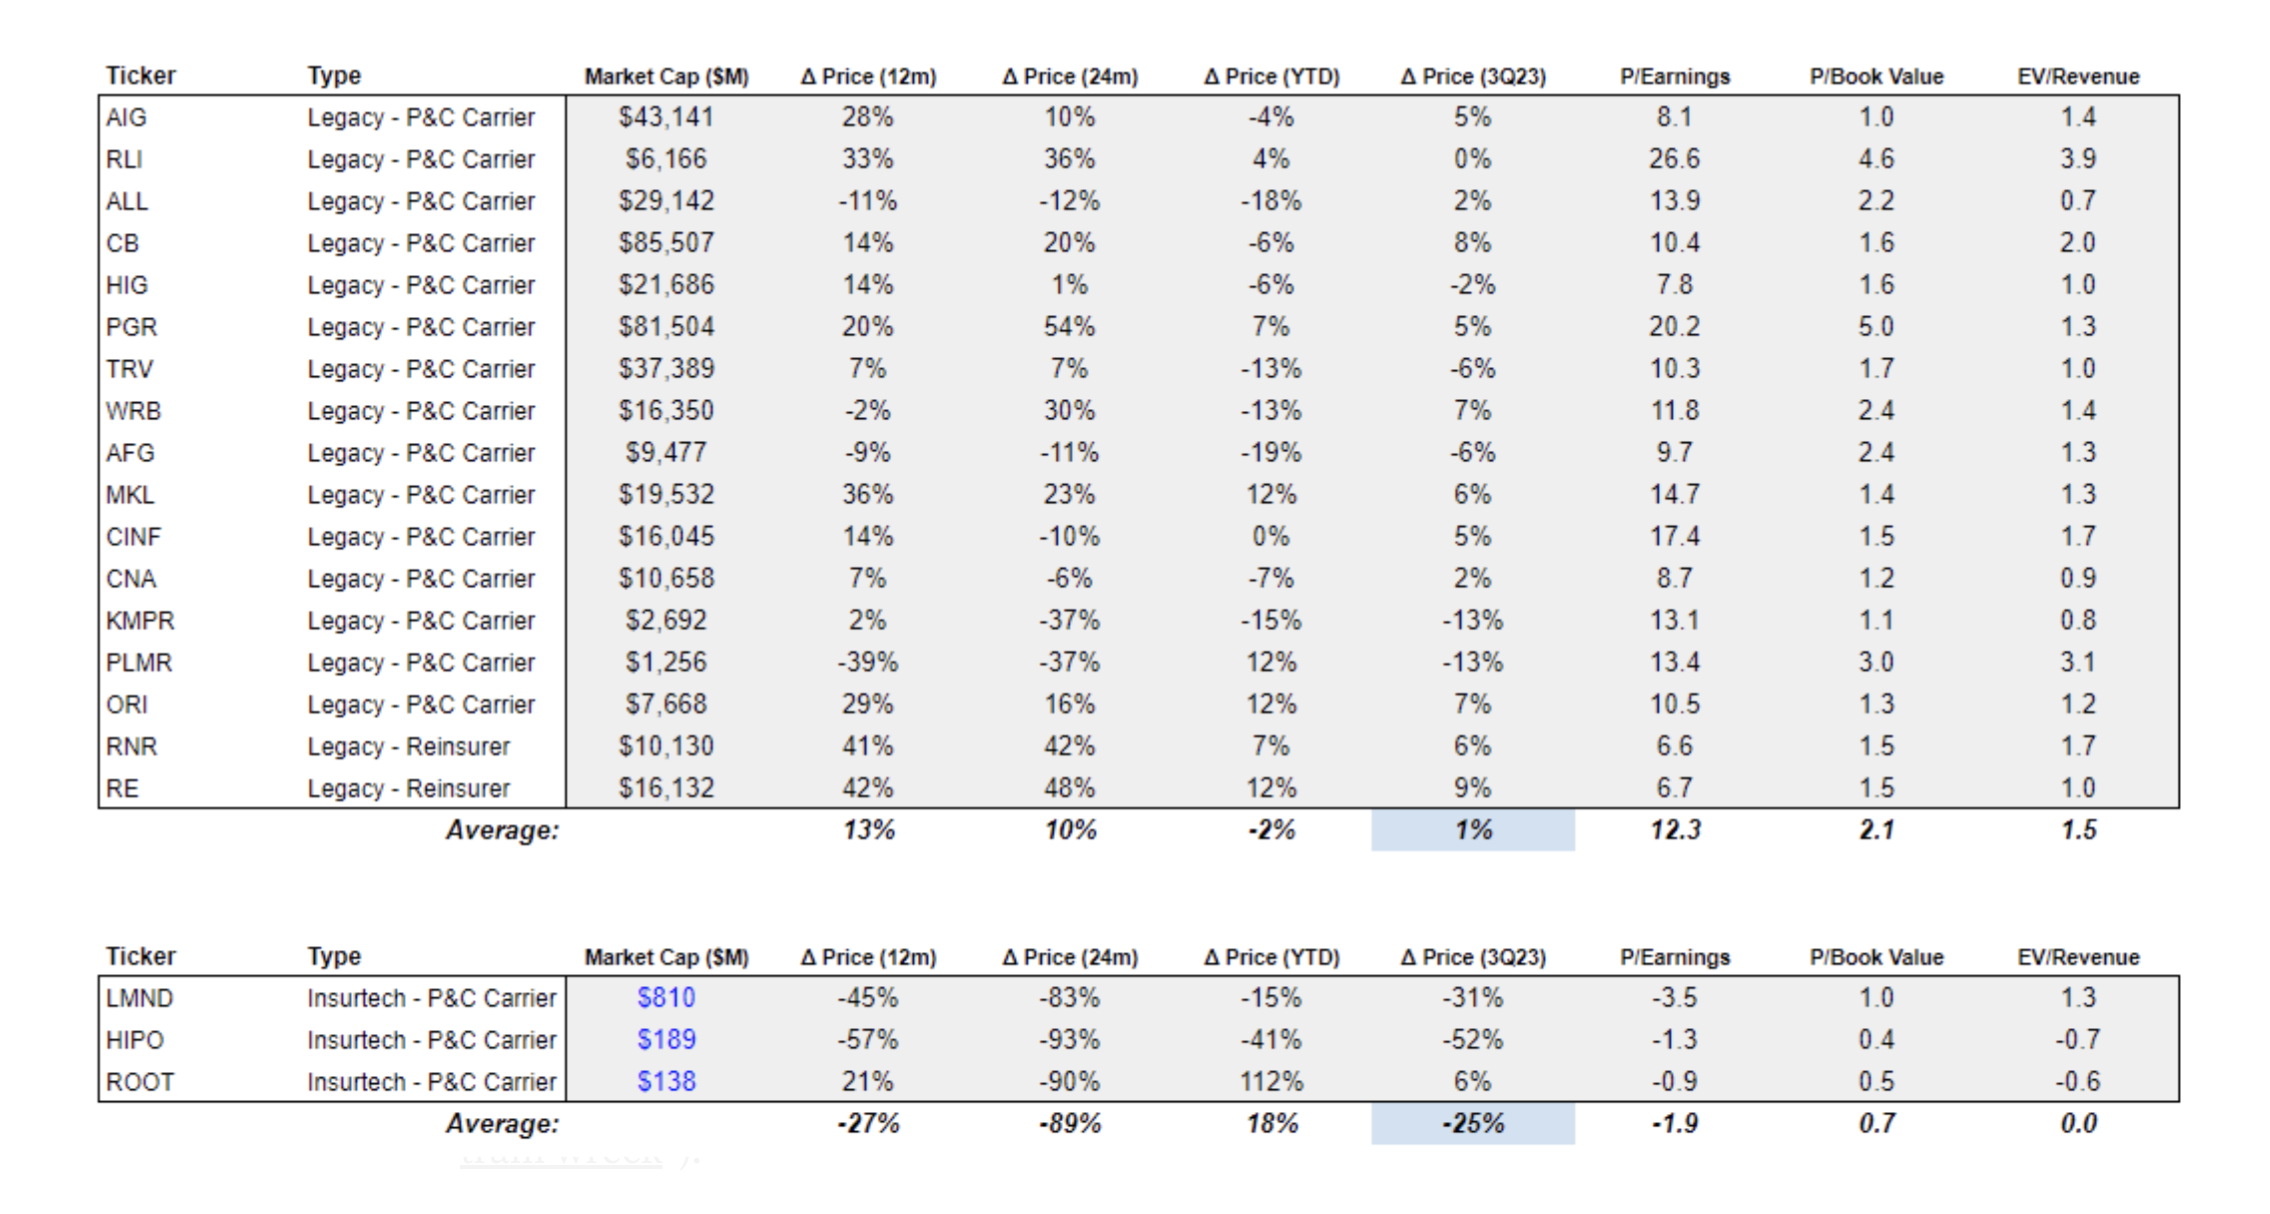
In the P&C carrier segment, observations from Q3 performance highlight a number of powerful and secular trends affecting the industry– chief among those trends is the extent to which property loss and cat exposure is pressuring margins and spooking investors.

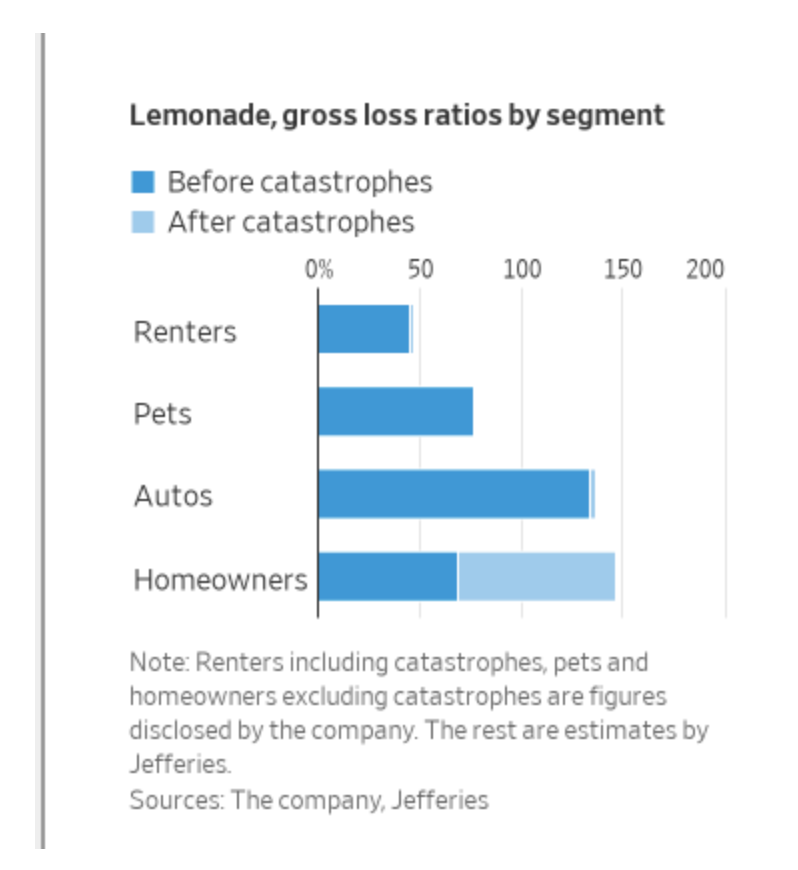
Performance of the volatile insurtech carriers demonstrates this trend. LMND started the quarter strong, after catching a bid from its “synthetic agents” initiative as an opportunity to improve cash efficiency and accelerate growth. But the stock fell off a cliff (and hit all-time lows) after posting higher loss ratios driven by cat exposure in its homeowners segment and announcing reduced reinsurance coverage. As a result, the company announced it would slow growth while waiting out new rate filings/increases. This is likely the responsible thing to do but not at all what investors were looking for. The chart below shows the magnitude of the homeowners losses before/after cat losses.

See also: Lemonade's 'Synthetic Agent' Nonsense

Lemonade, gross loss ratios by segment

HIPO performance tells a similar, if not exaggerated, story about destabilizing cat risks. HIPO reported elevated cat losses attributed to TX hail, and like LMND, made a commitment to slowing growth while rates increase. But shortly after earnings, HIPO abruptly announced an immediate and unprecedented pause of all new business while they “evaluate catastrophic risks, geographic diversification and enhanced underwriting…” Unsurprisingly, their stock fell more than 50% over Q3.

Source: Bloomberg Financial as of 9/29/2023; Earnings and Revenue are based on forward estimates.

Importantly, the trend toward higher property cat losses was not limited to the volatile insurtechs. National carriers continued to exit the CA and FL markets, a trend that started making headlines in Q2. Alarmingly, a greater share of homeowners are forgoing insurance due to cost or accessibility, and there is an increasing reliance on public insurers of last resort (a trend aptly described by a CA insurance industry group last month as a “slow motion train wreck”).

But even outside of these hardest and most disrupted markets, carriers are grappling with increased nat cat event frequency and higher exposure. In the wake of the unstable and disorderly reinsurance renewals market earlier this year, carriers landed with less reinsurance coverage overall (and therefore more exposure to cat risks). At the same time, more conservative reinsurance contracts left carriers with higher retentions and more exclusions to unnamed storms and secondary perils. 2023 turned out to be a particularly active year for severe convective storms — exactly the type of unnamed, moderate-frequency events that carriers are more exposed to due to reinsurance constraints (and exactly the type of non-coastal property losses that HIPO and LMND referenced). Losses from named storms, on the other hand, for which reinsurers bear more risk, have (so far) been relatively subdued. As a result primary carriers faced losses in Q2 as much as 40% above normal, whereas reinsurers effectively enjoyed a windfall from higher rates and below-average loss. This explains both the volatility across P&C carriers in the index, as well as the outperformance of reinsurers.

See also: Insurtech Startups Are Doing It Again!

Beyond property insurance, in a market with reduced access to reinsurance and continuing claims inflation, specialty insurers and brokers continue to take share from the admitted market. Commercial carriers with outsized E&S lines continue to outperform carriers in admitted segments. KNSL, a pure-play E&S carrier (and therefore not part of our index) trades at >2.5x the earnings multiple of our legacy carrier index. As we’ve written about before, it’s up ~60% YTD through Q3 and points to a long-term shift toward specialty risk and niche commercial underwriting expertise. Commercial rates continued to increase in Q3, though the pace of rate growth decelerated sequentially, possibly pointing to more stability for carriers in the quarters ahead.

As a reminder, the purpose of this brief (and oversimplified) analysis is to share high-level trends for insurtech investors, and not to comment definitively on valuations or market expectations. That said, we believe it will be instructive to see how insurance equities fare in Q4, and we note that insurtech carriers appear to be struggling from similar macro trends that are affecting the P&C industry at large. Whatever happens, it is clear that controlling property losses will continue to take on increasing importance for both legacy carriers and digital challengers.

Auto Values Are Out-of-Date

Changes in buyers' behavior mean an insurer using MSRP to set an insurance value is underpricing the vehicle from the start.

Black Suv in Between Purple Flower Fields

Across the last five years, about 40 million used car transactions happened each year (source: Bureau of Transportation Statistics). For most make, model and year combinations, a reasonable and current estimate of the insurance value of a vehicle in operation could be produced from a vehicle identification number (VIN).

This is not your claim adjusters’ Total Loss Value worksheet.  That would have mileage, condition, vehicle history, prior accidents and repairs, and like-for-like comparable vehicles in a local geography.

If you watch "Antiques Road Show" or even "Pawn Stars," you get the idea that everything has a value, that these can fluctuate and that the insurance value to replace something at market is a fungible concept, especially for things mass-produced – like a vehicle.

Before the government-imposed truth in labeling window sticker for vehicles emerged in the late 1950s, there was no ingredient label for what features were on a vehicle nor what a suggested retail price might be. As automotive retail strategies evolve, some manufacturers create many customer options while others produce more of a what-you-see-is-what-you-get menu.  

Before the days of the internet began making a direct-to-consumer order sheet a reality, companies would create their own estimates of what people want, then mass up incentives to clear the lots of anything not selling well. Those practices vastly changed due to the mall front business model of Tesla and the necessities of COVID shopping coupled with supply chain handcuffing.  A neo-epiphany was that you need way less inventory if you can build to order, and the order books were brimming with backlog.

See also: Auto Insurance in an Existential Crisis

The funny thing about the “have it your way” customer experience is that people don’t mind waiting a bit to get what they specifically prefer. The "car ordering" experience is completely different than the "car buying at a local lot" experience. The pressure on salespeople to clear the lot transfers directly to the shopper to “buy today what’s here” instead of buy when you are ready and “buy whatever you want,” where the value engineering of optional equipment and features can ruminate as shoppers sleep and as the showroom test what they can buy online.

This new behavior, coupled with supply chain and inventory constraints, may be a driving force behind recent year up-trimming and option-loading of vehicles entering operation as new inventory sales.  

While the COVID-crazy used car market still swells in lingering value, new sales have witnessed trim up-drift from the traditional production mix of basic, centerline and “premium trims” (source: Cloud Theory, Horizon Platform) to see popular vehicles with high choice configurations delivering many more premium “as built” vehicles today than in the past.

What this means is that if an insurer uses the manufacturer retail suggested price (MSRP) for setting an insurance value, it runs a high risk that the base MSRP will be several to tens of thousands of dollars below the “as built” fully configured total MSRP. And that means the insurer is undervaluing that vehicle from the start.

It gets worse. An object that starts with a higher value generally stays higher-valued than the rest of the production mix. So, if you insure at the base MSRP and then use a declining value forecast, the higher total MSRP vehicles will float above that for a decade. It’s tough to sell insurance for a $65,000 vehicle while charging like it is a $48,000 vehicle.  

While some may argue that at those cost levels any vehicle may only be short $100 a policy period, do remember that when mass produced that figure is multiplied by tens or hundreds of thousands of vehicles in any single model year. As model years accumulate, this undervaluation accumulates, as well. Then, as you factor in the general up-swelling of use vehicle values, a combo effect can kick in, where the accumulation promulgates into a new plateau of actual costs that are uncollected as exposure for the actual cash value of these subjects-at-risk.

See also: Setting Record Straight on Auto Claims Severity

The hangover effect of using an embedded but outdated and under-segmented vehicle valuation predictive model approach from years past is catching up with auto insurers.

Milestones have been passed: window stickers (1958), 17-digit VIN standardization (1981), auto insurance sold on the internet (1997) and ubiquitous sales information for vehicles transparently available for all the inventory on the internet (last 10 years). These created a new way of working with digital data. Perhaps leaving behind static predictions that underperform and using dynamic and continuous data with market savvy valuations is what auto insurance need to do personalized risk-based pricing right.

While there are a lot of reasons that help to explain why vehicle values went up, there are not a lot of good ideas of what will make them go down a lot anytime soon. Adopt and adapt new thinking for the value of the subject at risk for risk-based pricing in auto insurance.

Best practice in data and analytics -- Don’t predict what you can describe.

'When Will Risk Prevention Become Real?'

In this Future of Risk Forecast, Rob Galbraith says the insurance industry is innovating -- but not nearly fast enough. 

Rob Galbraith future of risk forecast


Rob Galbraith Headshot

Rob Galbraith is the founder and CEO of Forestview Insights, an independent consulting, research and training company focused on helping organizations build a culture of innovation. He is the author of the international bestselling book "The End Of Insurance As We Know It" and a popular keynote speaker who has shared his unique insights at numerous events around the globe.

Galbraith has over 25 years of experience in the financial services industry in a variety of leadership positions. He is a recognized thought leader on P&C insurance who is a frequent media contributor and well-known industry influencer.

He holds a master's of science in insurance management from Boston University and a bachelor of arts in economics from Michigan State University. He has earned the CPCU, CLU, and ChFC professional designations.


Insurance Thought Leadership:

It has been almost five years since your book "The End of Insurance as We Know It" was published. What are some of your forecasts that have come true, and are there any that did not come to pass as expected?

Rob Galbraith:

A few months ago, I connected with a startup founder who recently discovered my book, and he exclaimed, “Everything you predicted came true!” I so wish that was the case! My honest assessment would be that the book's core argument remains true – that emerging technologies are coalescing with large amounts of funding and newer, tech-savvy generations to change the insurance industry. I also argued that artificial intelligence would quickly become the most transformational emerging technology, and we see that a lot more clearly today with conversations around generative AI and the ethical applications of AI to remove bias in the industry.

On the flip side, while numerous headlines and a lot of buzz have been generated, the speed and scale of the predicted transformation have been slower to materialize than I anticipated. This has been less due to the challenges of promoting innovation and change with traditional insurance firms – always a big hill to climb - and more due to the relative struggles of outside startups to grab market share against the incumbents and challenge their supremacy. I think there has been more success in specialty and niche segments that were not covered or underserved but less disruption in the core P&C, life and health markets than I originally anticipated. I also foresaw a slower adoption of blockchain, but even with more tempered expectations, I am surprised how little to date blockchain specifically and Web3 more generally have affected the industry. I applaud the steady progress of the RiskStream Collaborative in this area, where many other initiatives have faded.

ITL:

What is an area (or areas) that you believe remains untapped/unfulfilled/overlooked for the promise of innovation in insurance?

Galbraith:

I would categorize investments in innovation based on an insurer’s income statement. Most innovation efforts have focused on increasing revenues through new product offerings and new (digital) sales channels. Another area of significant investment has been reducing expenses and streamlining key processes through systems modernization efforts, automation and low-code/no-code platforms, among others.

What is unique at this moment in time is that companies can simultaneously reduce operational expenses and improve customer experience. Usually, there is a trade-off involved where expenses increase as firms work to improve customer service.

I see a lot of underinvestment in the claims space. Outside of implementing new fraud detection solutions, most firms have shied away from large investments to help better manage loss payouts and reduce loss adjustment expenses. I also think more investment is needed in risk prevention efforts – these tend to have a longer tail to see meaningful benefits in the form of reduced losses, and the ROI is highly uncertain with longer payback periods, so these projects lose out to other efforts with a more concrete return. I also think billing and ancillary functions such as regulatory compliance, premium audit and subrogation haven’t received enough attention.

ITL:

What do you see as the biggest obstacles to insurance innovation, and how would you recommend overcoming them?

Galbraith:

My first takeaway is that innovation is a discipline, not a side show—it should be seen as equal to more established disciplines such as claims, underwriting, actuarial science, IT, HR, etc. The key difference is that it’s a much younger discipline that most firms have focused on for less than two decades, so best practices have yet to be evaluated, well-documented and widely disseminated. Professional designations and continuing education requirements exist for agents, brokers, claims personnel, underwriters, actuaries, IT, HR, etc. These serve as ways to establish a community of practice, and when professionals move from one company to the next, the best practices of that discipline remain in place to guide people. This is not true yet for innovation—each organization approaches the topic quite differently. I help companies assess their innovation efforts and conduct training and workshops to make them more effective based on my past successes and failures.

My second takeaway is that three forces drive innovation: top-down, bottom-up and outside the organization. Top-down efforts, by definition, have senior-level support, but if they aren’t effectively tied to a strategic road map that makes sense, they won’t last beyond the leader who initiates them. Bottom-up efforts are plentiful but must fight hard for attention and resources, are often scattered and incompatible, and usually result in incremental innovation with marginal benefits. Outside forces (technology, the economy, shifts in the market, regulators, etc.) can force companies to respond through innovation, but the resistance to change is high. Reactive innovation efforts struggle to find internal champions and gain enough traction to propel them over the finish line, and the benefits are muted because other competitors have also adapted. Ideally, organizations rely on a blend of “changemakers” incorporating all three forces to have a balanced approach and allow for building a culture of innovation where change is expected and embraced.

ITL:

This year’s launch of Chat GPT has captured the imagination for the potential applications of AI to various businesses, as well as thousands of actual applications. How would you grade insurance efforts to leverage AI?

Galbraith:

On a scale of 1 to 10, I rate insurance efforts at a 4, which may be generous. The challenge isn’t the lack of adoption but rather the speed of adoption. AI is a critical cornerstone technology full of possibilities and challenges, and this year has proven that it continues to evolve rapidly. Traditional insurance organizations generally wait to deploy technologies once they have become stable and proven, but delaying efforts to incorporate AI in a wide range of use cases will create a competitive disadvantage.

Today’s biggest challenge is the hard insurance market, and while there is a confluence of forces that have led to current conditions -- including inflationary pressures, rising interest rates and climate change – clear solutions aren’t as obvious. Raising rates, restricting risk appetites and reducing expenses are insufficient on their own. To achieve profitability, risk selection is paramount – and the only way to improve on current methods is to acquire new, highly granular data. Whether this data comes from IoT-enabled sensors or unstructured sources such as handwritten notes, images or video, artificial intelligence is essential to find meaningful patterns in these rich and previously underused data sets and guide our actions. We have seen the power that AI has in Big Tech and need to accelerate our efforts as an industry to harness its full potential.

ITL:

You recently presented a webinar with The Institutes on insurtech. What are some of the lessons you hope attendees will take away from the course and bring back to their organizations?

Galbraith:

There are three core lessons that I hope attendees leave with. First, we live in an amazing time characterized by rapid technological change. I use an acronym to describe what I call the SCALED emerging technologies of today: Sensors, Cloud, AI, Localized knowledge, Efficiencies and experiences, and Digital distribution and communication. We typically learn about each of these technologies in isolation, but it’s important to see the bigger picture and understand how they support each other, how they interact and the amazing new capabilities and possibilities they unlock.

The second lesson is the importance of seeing innovation as a discipline, as I previously mentioned. Organizations establish and adopt best practices such that when professionals move from one firm to another, the essence of the function is the same, and each has a different “flavor” that makes up its “secret sauce.” By contrast, innovation is an immature discipline that has only been rigorously practiced within insurance organizations for a decade or two. Each firm varies widely in how they approach innovation, yet this discipline is critical for translating the SCALED emerging technologies and applying them in the best contexts for insurance organizations to gain a competitive advantage and better serve customer needs that are being shaped by leaders outside of insurance such as Apple and Amazon.

The third lesson is that innovation isn’t just the domain of a small group of specialists but your entire organization. As the saying goes, “None of us is as smart as all of us.” Innovation is about novel ways of doing business, not merely incorporating a new piece of technology to do business the same way as before. Title and rank matter for access to resources, but there is no monopoly on good ideas. Other necessary ingredients are cognitive diversity to avoid groupthink and psychological safety to speak your mind without fear of repercussion. Failure should not just be accepted but encouraged. Innovation is ultimately about experimentation – learning what works and what doesn’t when there are no clear answers because no one can see the future perfectly. To succeed in the long run, you must build a culture of innovation that goes beyond individual leaders or projects and is ingrained within your organization.

ITL:

The Institutes is leading conversations on Predict & Prevent, the idea of using technology to predict potential losses and prevent them before they can become a claim. What are your thoughts on this shift in how insurance can serve its customers?

Galbraith:

One of the most common questions I receive from industry professionals is, “when is risk prevention going to become a reality?” There was a lot of hype in the mid-2010s about self-driving cars and IoT devices and shifting from a risk recovery to a risk prevention business model for insurance organizations, yet the reality is we have yet to move the needle much. I am optimistic that we can achieve this vision in the long run, and I love that The Institutes is taking a leading role in helping shape this paradigm. It’s a major undertaking, not just from a technological standpoint, but reinventing entire processes and business models that are hard-wired into our industry. In situations like this, I remind myself of the 10/10 Rule: it takes 10 years for emerging technologies to go from conceptual to useful and another 10 years to reach mass adoption.

Think of the social, psychological and economic benefits of loss prevention: it is extremely powerful and a vastly superior alternative to the reactive approach that has characterized insurance since its inception centuries ago. In collaboration with partners, loss prevention is a focus of our industry today in many contexts, such as seat belts, worker safety, building codes, etc. With emerging technologies and innovative approaches, the insurance industry can go far beyond our current capabilities and, ideally, be seen more as true collaborative partners that help people and organizations rather than a source of friction.

ITL:

Thank you, Rob. Are there any other issues or topics that you think we should be paying attention to?

Galbraith:

I’m curious where people assess the state of insurtech in the context of the Gartner “hype cycle” today. With the current hard market challenging profitability across the board for insurance organizations and the challenges that many startups have faced, are innovation efforts moving to the back burner? Are we currently in the “trough of disillusionment” today, and what does the slow adoption and acceptance phase look like? Will a startup competitor like Lemonade or Hippo truly challenge the incumbents and shake up the top 10 in our industry? Some have argued we have not seen this confluence of events – inflation, global instability, high interest rates, large losses – in 40 years or more in the insurance industry. Can innovation lead us back to profitability? Or will market conditions and challenges with availability and affordability persist?


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

Twisted Sister and the Local Agent

Local agents keep being dissed--and keep winning. They'll continue to win, too, in the AI era. Rock on like Twisted Sister!

Two people shaking hands

Since diving into the insurance sector right out of school 36 years ago, I've enjoyed watching the so-called experts predict the demise of the local personal lines property/casualty insurance agent across the years.

There have been several waves of direct-to-consumer (D2C) personal lines P&C insurance provider start-ups throughout that timeframe, and each time we've been left dodging all the subsequent roadkill (or soon-to-be-roadkill among the most recent wave of insurtechs). The next wave will be generated by the "experts" who jump onto the artificial bandwagon.

There are only a couple honest D2C successes over time, and it took a long time for each...and a lot of patience and capital to support the steady growth.

Take Wawanesa. It started in 1975 in San Diego with the support of the Canadian parent, stayed focused regionally and expanded into Oregon around 30 years later. To this day, it only sells policies in California and Oregon. It's an absolute gem of an insurance provider. There's also The General (originally Permanent General) that was launched by Brian Brown in Nashville. And obviously, we have GEICO and Progressive.

GEICO nearly failed in the '70s but was rescued by the Oracle of Omaha, starting in 1976. Per its website, Progressive shifted "focus from being an agent-centric company to building a leading consumer brand" in 1988. With that strategy shift, a legendary leader and a bunch of brilliant, motivated people like Alan Bauer, Progressive thumbed its nose at slow, steady growth and began its meteoric market share grab. (For more on that story, please take 5 minutes to read my all-time favorite article on auto insurance, "Sex. Reefer? And Auto Insurance.")  

But that's about it! Pretty much all others that set out to "crush" the antiquated and bloated local agency model in the last four decades have failed. Fireman's Fund, Great American and Direct Response tried in the '90s, eCoverage in the early 2000s. It even took out a full-page color ad in the Wall Street Journal proclaiming "The Industry is Toast." A year or two later, it shut down and sold its technology to GMAC Insurance for practically nothing.

Oh, and don't forget about Esurance! Did Erin Esurance ever get her loss ratio into the double digits? The insurtech movement burped out "agent killers" like Hippo, Root and Lemonade (to name a few), which all had seriously broken IPOs and, now, rapidly declining market caps.

Now, everyone should get ready (and be very skeptical) of the fat cat consulting firms roaming corporate insurance company hallways who will wave the artificial intelligence flag as the next thing that will no doubt exterminate the local agent. These are the folks who have LinkedIn profiles with "MBA" after their names. because they think it makes them look smarter and more important. like a doctor or professor. (Not in my book....)

The consultants will bash the local agent model and issue recommendations to ditch it and go direct. No consultant can make a living by saying, "You're doing a great job, keep up the great work and don't change a thing!"

Those office water walls and seafood tower dinners aren't going to pay for themselves!

Why does the local agent continue to dominate personal lines auto and home distribution? And why will they become even more important in the artificial intelligence age?

Simple...it's the consumer, stupid! Consumer behavior hasn't changed much when it comes to shopping and buying auto and home insurance. Sure, you have the non-standard consumer who will buy from anyone and the ultra-price-sensitive consumer who will move providers for a couple bucks of savings. But the vast majority of consumers want a local insurance professional who can expertly guide them through the complex buying process to make sure proper coverages are established and be nearby when "the promise" is needed in tough times.

As artificial intelligence continues its rapid rise, I expect consumers will increasingly become skeptical when it comes to insurance, and it will be difficult to trust the machines with protecting their most prized possessions. And forget about trying to have an actual meaningful conversation with a real human being to determine the best coverages for their individual situations.

To you insurance carriers: Don't discount the plus of having boots on the ground to verify reality when needed (this will become increasingly difficult from afar).

The result: Consumers will lean even more into the local agent -- someone they can actually see in person (if they want to) and know is real and nearby. You can't do that with artificial intelligence.

The "experts" will argue that robots residing on corporate servers can do a much better job for consumers than local agents! Please do a focus group before deciding to follow that flawed thinking.

With luck, some carriers will shift gears and begin to invest in agents' compensation, education, development and operations. Those that do will dominate the passing lane on the artificial intelligence superhighway.

To local agents: Sorry, but it's likely you'll all continue to be dissed just as you have been throughout the past. Don't listen, and don't take it.

All of the local insurance professionals I know have tough skin. Rock on like Twisted Sister! "There ain't no way we'll lose it, this is our life, this is our song, we'll fight the powers that be, we're not gonna take it."


Jaimie Pickles

Profile picture for user JaimiePickles

Jaimie Pickles

Jaimie Pickles is co-founder and CEO at First Interpreter.

He was previously general manager, insurance, at Jornaya, which analyzes consumer leads for insurance and other industries.  Before that, he was president and founder of Canal Partner, a digital advertising technology company, and president of InsWeb, an online insurance marketplace.

The Insurance Industry's PR Crisis

Insurance insiders understand why premiums need to climb for autos and homes -- but consumers are angry. 

Image
Insurance Industry

The headline in Business Insider couldn't be starker: "Insurance Companies Have Discovered Devious New Ways to Rip You Off." And I think it should be a call to action.

People in the industry understand the need to sharply raise rates for auto and homeowners insurance. Replacement costs are way up, climbing far faster even than the lofty inflation rates of the past two years. The addition of sophisticated electronics in cars and the transition to electric vehicles increase repair costs, too. Frequency of claims is up, as well, and will likely keep increasing, especially for homeowners, as the warming climate causes more and bigger storms and wildfires. 

As costs rise, premiums have to, too. Insurance is a business, not a hobby.

But consumers aren't in the industry and aren't exactly sympathetic to insurers' problems. They just see rates soaring, and they're angry. They will now generate as much pressure as they can on state regulators -- whom they elect, either directly or indirectly -- and we can expect to see a lot more headlines about "devious" insurers.

What to do?

While nothing will eliminate the problem, I think we can take at least some of the sting out of it by doing three things.

First, we need to communicate, communicate and communicate with customers so they understand why rates have to rise. Then we need to communicate some more.

Most of the burden will fall on agents and brokers, who need to explain, in detail, why costs have soared and, thus, why premiums need to climb, too.

Agents and brokers should also be crystal clear about changes in coverage. Many customers are inclined to scale back to reduce premiums, yet will blame agents and brokers or carriers if they have a loss and find that an exclusion they've forgotten about means it isn't covered. Agents, brokers and carriers all need to get customers to acknowledge what they've decided not to cover and to remind them from time to time. A surprised customer is a furious customer. 

It'd be great if the carriers would lean into educating the public about rising costs, but they seem to view talking about the need for rate increases as an opening for competitors to brag about lower prices. So we'll likely just keep being inundated with geckos, emus and all possible permutations of Flo and Mayhem as the carriers hammer away at improving brand recognition. Our colleagues at the Insurance Information Institute are doing yeoman's work on behalf of the industry, but they can only reach so many people through their comments in the media.

Carriers should, at least, help agents and brokers work with customers on how to reduce premiums -- being as specific as possible for individual customers about how they can diminish, say, wildfire risk or the potential for water damage. If the insurance industry demonstrates good will, customers will be at least a bit more sympathetic about price increases. 

Second, we need to be far more aggressive about lowering costs, as a way of diminishing the need for rate increases. Geico just announced that it is laying off 2,000 employees, or about 5% of its workforce, and Farmers Insurance said in late August that it was laying off 2,400 people, or some 11% of its employees. But there are loads of other ways that insurers can become more efficient, too.

Matthew Grant, CEO of Instech, said in a recent conversation that insurtechs have developed lots of ways that carriers can cut costs, and carriers see clear benefits, but "there wasn't really a burning problem, so are you going to make the effort to bring something into the company?" He said insurtechs' cost-cutting innovations always seemed to be "No. 11 on the list of boards' top 10 priorities."

Cost-cutting should move way up those lists -- and carriers should make sure customers know about it, so, again, they see the insurance industry working on their behalf to minimize price increases as much as humanly possible.

Third, the industry should move as swiftly as possible toward the "Predict & Prevent" model and away from the traditional "repair and replace." We have all this data about where the risks are. On the theory that the best claim is the one that never happens, let's use that data to help customers prevent losses, rather than just help them recover after something goes very wrong.

We've published extensively on the topic at ITL, and I'd encourage you to check out some of the very smart pieces. Here is a smorgasbord, based on a search for "Predict & Prevent" on the ITL site. If you have time for just one, I'd suggest this webinar I hosted with Pete Miller, the CEO of The Institutes; David Harkey, president of the Insurance Institute for Highway Safety; and Roy Wright, president and CEO of the Insurance Institute for Building & Home Safety.

Nobody wants to buy insurance, but everybody wants protection.

With all that said, I think the piece in Business Insider is, well, hardly an example of journalistic excellence. While it's posted on the site as a news article, a note at the end describes it as part of an initiative that provides "thought-provoking perspectives, informed by analysis, reporting and expertise." In other words, opinion. 

The piece was written by a professor at an Australian university who wrote a book a few years ago about how businesses are, to quote the subtitle, "extracting data, controlling our lives and taking over the world." The closest the piece comes to quoting someone as saying something negative is a paraphrase of Dame Inga Beale from a talk she gave, and there's no link to the talk, so I can't see precisely what she said or the context for her words. 

The article makes claims that will strike any student of business as silly. Insurers are dinged for focusing on the lifetime value of customers -- something every sentient business does. The article also sneers at usage-based insurance as somehow unfairly intrusive and at how insurers "might look at your home's roof using drones and automated image analysis, or where you're driving based on data from a smart device in your car."

What's devious about any of that?

Where the article delves into issues that could be legitimate concerns -- using AI for "price optimization," based not on risk but on customers' ability and willingness to pay, and "claims optimization," based not on what should be paid but on how much customers complain if claims are denied -- the writer cites no evidence and quotes no one. He also doesn't try to quantify the extent of these alleged practices. He just asserts that insurance companies are guilty.

So, while Business Insider is generally a legitimate publication, I don't take the complaints at all seriously. 

But my analysis of the article doesn't matter. Neither does yours. What matters is that the article is out there and that a lot more like it may be in the works because consumers are angry about soaring premiums.

We as an industry need to change the narrative as aggressively as we can, or we'll let this public relations crisis define us.

Cheers,

Paul

CBRN Terrorism Insurance: A Risk Too Far?

Helping clients manage chemical, biological, radiological or nuclear (CBRN) risks has to begin with good information. 

Stop sign in front of a large mound

To many, the threat of a chemical, biological, radiological or nuclear (CBRN) attack is informed by Hollywood movies and the occasional news report from Ukraine or Iran. Actual incidents, thankfully, remain few and far between, and in many cases are a result of direct state involvement. For example, the poisoning attempt in Salisbury or the successful assassination of Kim Jong-Un’s half-brother in Kuala Lumpur.

That said, our research shows broad terrorist intent to use CBRN material. And while such plots are infrequent, they do garner press interest because of the very mystery and intrigue they trigger within the general public. Much of the reporting can be unhelpful, with descriptors of a certain quantity of material commonly measured in “teaspoons” or “having the ability to kill X% of a population,” with little nuance on how that might be practically achieved.  

This type of reporting presents a challenge for the insurance industry. How to sensibly communicate CBRN risks and support clients in their risk management solutions?

Access to the facts from credible, well researched sources is the first step.

See also: Growing Number of Uninsurable Risks

CBRN incidents January to June 2023

As malicious risk advisers, the team at CHC Global undertake a six-monthly CBRN Risk Report. The latest edition, covering January to June 2023, identified two late-stage plots that were foiled in Europe and one high-profile death threat reported in the U.S. During this period, CBRN concerns driven by geopolitical maneuvering continued to feature in mainstream media, primarily due to Russian and North Korean activity. But the tangible use of CBRN appeared to be more likely at a sub-state, decentralized level.

This trend is aligned with the broader commentary around terrorism threats in the advanced economies, where risk of detection and interception by intelligence and security forces has very much reduced the possibility of larger groups organizing and initiating attacks. Key terror risks are now really confined to lone actors, many of them self-radicalized, seeking to conduct low-level attacks using whatever means are readily available to them.  

In the same period in Germany, police arrested an Iranian man in the city of Castrop-Rauxel for allegedly plotting an “Islamist-motivated” attack using cyanide and ricin. The man’s brother was also arrested in connection with the plot. It transpired that no poison was discovered at the man’s residence, and reports made no mention of any viable method for producing or acquiring cyanide or ricin. It is unclear how far the alleged plot had developed, but police did seize electronic devices while searching the suspect’s residence. Following this, authorities stated they believed action needed to be taken as soon as possible. Ricin is a highly potent toxin that can be lethal if injected into a person’s bloodstream, inhaled or ingested. According to the U.S. Centers for Disease Control and Prevention (CDC), testing indicates that a dose as small as three milligrams of inhaled ricin can kill an adult.  

Athens police, with assistance from Israeli national intelligence agency Mossad, arrested two Pakistani nationals, reportedly foiling a plot to conduct a mass-casualty attack on Israeli and Jewish targets in the city. Police stated that a planned attack was imminent, and an unnamed Greek official revealed that one target of the plot is believed to have been a chabad house (Jewish community center). Israeli National News reported that the individual who led the planning of the plot, based in Iran, had attempted to source “poison gas” that was intended to flood the target site with noxious fumes and harm as many people as possible.

Insurance considerations and CBRN Risk

Balanced reporting of the facts will support the insurance industry to sensibly communicate CBRN risks to their clients. But how to support clients in their risk management solutions?

The inclusion of CBRN cover in terrorism insurance policies can vary, depending on the insurer and the specific policy wording. In the U.K., terrorism insurance typically covers damage or losses resulting from acts of terrorism as defined in the Terrorism Act 2000. Given that the consequences of a large event could result in the loss of many billions, the majority of cover in the U.K. is reinsured through Pool Re, though CBRN policies are offered outside this state-backed scheme.

While the CBRN perils tend to be grouped for convenience, the specific nature of the materials, their damaging effects and the potential longer-term consequences on people, property and business operations vary significantly. A hazardous chemical gas, such as chlorine, can disperse in a few hours and is unlikely to require any active decontamination. Conversely, a dispersed radionuclide, such as caesium-137, can continue to pose a health hazard for decades, with costs accumulating rapidly – for decontamination, building demolition, hazardous waste removal and rebuilding.

A further complication in these highly technical risk management processes is the impact on both public perception and political leadership. While response to an event will be initially governed by operational scientific and medical advice, progress of the hazard and risk management processes will inevitably be influenced by how the wider public reacts to the reported news – and how political decision makers choose to resolve the situation.  

The consequence is that the ability of an insured party and their underwriters to influence the timings and nature of issue resolution and return to normality is somewhat out of their hands. In spite of a whole range of decontamination activities, one of the commercial properties affected by anthrax after the 2001 "Amerithrax" attack remain unoccupied for years. This was not because of any detected residual hazard but simply that no insurer would offer employee liability cover. And as we saw in the Salisbury Novichok event, some properties were cordoned off for over a year.  

See also: How to Plan for Armed Intruders

Low-probability, high-impact events

The insurance industry must put into context that the likelihood of a CBRN attack might be low, but the impact is high and potentially catastrophic for organizations and people. We only have to look to COVID-19 to see how quickly a biological attack could affect organizations and individuals worldwide. 

In this context, insurers should ensure they have access to credible information sources about the realistic threats a CBRN attack might present. And then highlight to their clients the potential threats and impact these types of attacks could have on operations, employees and claims – so organizations can take the necessary steps to manage their risk.


Jerry Smith

Profile picture for user JerrySmith

Jerry Smith

Jerry Smith is senior partner and head of advisory at CHC Global, advisers on malicious risks.

He works with the insurance industry, blue chip companies, national governments, supra-national organizations and international NGOs. He is recognized globally as one of the leading experts in chemical, biological, radiological, nuclear and explosive materials (CBRNE,) and has been awarded an OBE for services to international arms control and WMD counter-proliferation.


How to Address the Talent Shortage in Insurance

As the talent ages, millennials are maturing, ready to develop into the next leaders of the industry.

Woman on her phone with a coffee mug next to her

When I entered the insurance industry out of college, the recruiting toward millennials was on point. I was courted to feel like I could bring my whole self to work, all of my identities — my Blackness, my quirks, my ambition and my curiosity. But when I arrived in all of those ways, I realized that, in practice, the authenticity-at-work concept was still a work in progress.

An overwhelming amount of data shows that more people, especially millennials and Gen Z, want their labor to affect the world in meaningful ways. As idealistic as it seems, social responsibility is an important aspect of mental wellness. The COVID-19 pandemic showed us how important interpersonal connection is for our well-being.

The insurance and risk management industry has a reputation for being self-serving. Outsiders perceive insurance companies as striving to deny claims or at least pay as little as possible. Whether that’s true or not, there’s another side to insurance. 

As an industry, we need to educate prospective employees about the ways that insurance policies create a safety net for the infrastructure of the economy, real estate, schools, churches — every industry is secured by a compulsory insurance policy, where it’s a liability policy or workers’ compensation. Educating younger generations on both the tangible and abstract ways that insurance supports people, places and things can help connect the dots between the daily work and the broader missions of many insurance organizations (beyond shareholder profit).

Once we’ve convinced millennials and Gen Z that there are good things happening in this industry, retention is paramount. I learned the phrase “big ship, slow to turn” while working for larger insurance carriers. As I navigated career development, I intimately understood what that meant. Research from the financial services industry shows that Black professionals tend to plateau at middle management, as the executive ranks are peppered with disproportionately low numbers of Black leaders.

See also: Solving the Talent Crisis in Insurance

I’ve observed these phenomena in my own career. Looking around my office, I noticed a large proportion of my Black colleagues of various ages in lower-complexity claims positions, while the higher-complexity claims teams lacked the diversity that initially piqued my interest about the company. Scanning the org charts for people who look like me, I found few Blacks in positions with greater authority, responsibility and pay bands. Disheartened with this grim reality, and impatient with what felt like stagnation, I realized that, traditionally, it’s expected that you stay in your role for several years, possibly collecting small merit increases annually, and then look upward toward the next step.

I appreciate that there is value in remaining in the same position for a while, reaching a level of proficiency, then taking on additional responsibilities. Nonetheless, inflation outpaces merit increases, and employees’ desires to make more, faster, especially when excelling in their roles, isn’t unreasonable. 

To address the talent shortage, the insurance and risk management industry should consider looking within. As the talent ages, millennials are maturing, ready to develop into the next leaders of the industry.

The youngest millennials are now 30 years old, and we’ve got families and homes and live real adult lives. It’s time for industries to start appreciating the talent and maturity of a growing generation.


Mi Aniefuna

Profile picture for user MiAniefuna

Mi Aniefuna

Mi Aniefuna is a principal consultant for Risk Nerds, a risk management and insurance consulting firm. After a decade of experience in complex commercial claims, he developed a passion for helping businesses reduce claims costs and protect the people, places, and things that make their businesses thrive. Mi has hands on experience in general liability, toxic tort, construction defect, workers compensation, and auto claims, loss control consulting, training, and data analytics. He applies his multi-sector background to the insurance and risk management industry to find innovative solutions to established and emerging risks like environmental health hazards, cyber liability, and the maturing insurance workforce. When not working on his dissertation at Columbia University, Aniefuna and his wife are chasing around their infant and toddler and writing children's books. 

Does Generative AI Kill Process Outsourcing?

Can generative AI replace the advantages that insurers and brokers sought to achieve by offshoring? It's possible.

Abstract object with many lines extending from a center point

KEY TAKEAWAY:

--The primary value proposition for offshoring – more work at less cost – is declining with digitalization. And AI technologies, when implemented right, can make processes cheaper, better and faster than manual processing and deliver significantly improved customer experience. 

----------

Everyone is talking about artificial intelligence, especially generative AI, the breakthrough technology that brings the capability to learn from experience and to “think” in almost-human terms.

It is certainly true that using AI in the insurance world promises extraordinary benefits. To date, the AI-enabled innovation receiving the most attention is the increase in efficiency by automating mundane tasks.  Other benefits that are becoming part of the AI buzz include its potential for lowering risk, improving compliance, gaining business insights from predictive analytics and achieving higher profitability. 

One area that has not yet been addressed is the fate of process outsourcing, which has become standard practice for insurance firms over the last two decades. Can generative AI replace the advantages that insurers and brokers sought to achieve by offshoring? Will business process outsourcing disappear? Is there a place for it in the automated world of the future?

The State of Process Outsourcing  

Twenty years ago, labor arbitrage was big news. By taking advantage of low wages paid in other parts of the world, American companies discovered that they could save considerable operational costs. Soon, most firms had an office in Ukraine, India, the Philippines or other countries where labor costs were a fraction of those in the U.S. Expenses dropped.

However, over the last two decades, unforeseen developments have clouded this rosy picture.

The initial expense of hiring and training this international workforce was substantial. There was -- and is -- considerable competition for skilled individuals who are fluent in English and who could be rapidly trained to perform the required tasks, quickly and accurately. Over time, labor costs increased as salaries rose to be competitive. The costs of recruiting, training and providing facilities for this overseas workforce have also gone up. Consequently, savings from process outsourcing are less attractive today.

Unanticipated risks and complications associated with process outsourcing can be disruptive. For example, a volatile geopolitical climate can disrupt operations, as has happened in Ukraine, which is the location of many outsourced operations. 

As companies grow and acquire other firms, the process of training, adoption, integrating legacy systems and developing workflow processes must be repeated with the offshore organization. These significant efforts detract from the value the acquisition is supposed to bring to the parent organization and can be very frustrating to the staff involved. Similar adjustments must be made with the introduction of new technologies, and opportunities for insights from predictive analytics were not realized because data was siloed and some vendors declined to share data for analysis.  

Offshoring also had unanticipated downsides for the American workforce. Employees experienced considerable demoralization as people were laid off (including colleagues they had worked with for decades) and jobs disappeared across an ocean. Fear of losing one’s job eroded company loyalty, and workforce reductions thinned the ranks of skilled and experienced people here in the U.S. 

See also: AI: The Future of Group Insurance

In-Country Outsourcing

Not all outsourcing occurred offshore. Some functions were given over to outsourcing centers in the U.S. These arrangements avoid some of the risks of offshoring; however, manual processing still requires resources for staff, takes time and is not scalable. 

Regardless of the location of the outsourcing organization, one reality working against efficiency remained. 

While costs may have been lower, processing times were still an issue. Having tasks performed by humans still took time. Policy reviews and other tasks required people to review the documents, do the analysis, check their work and perform any necessary research to verify accuracy. Customers and U.S.-based staff could still experience significant time lags in getting documents analyzed and returned, no matter the location of the outsourced workforce. 

Comparing Options

A comparison of different options shows the advantages and disadvantages of three approaches: manual in-house processing, manual outsourced processing and processing by artificial intelligence. The task compared below is policy checking and verification.

Manual In-House Processing: Requires approximately 60 minutes of a customer service representative’s (CSR) time. This staff time, especially at the account executive level, could be better spent focused on customer needs. There is no standard output and no future reference on reviews. 

Manual Outsourcing Processing: Approximately 30 minutes of time from a CSR, in addition to the time taken by the offshore team to pick up the job and start processing it. The process is not scalable, there may be quality and data security concerns and there is no comparison of language in the forms by the outsourcing company. As seen during the pandemic, offshore teams were unavailable, thereby delaying E&O checks significantly.

AI Processing: Approximately 10 minutes of time from a CSR. Processing is instant, there is no lag time irrespective of volumes or peaks. AI also delivers instant confirmation of variances, there is a broader risk advisory, differences in language are highlighted and insights are offered in real-time.

See also: Overcoming the Challenges Posed by AI

The Value Proposition of AI

The primary value proposition for offshoring – more work at less cost – is declining with digitalization, which is defined as the process of using digitized data (encoding data by converting it into a digital format, like PDFs for insurance policy documents) to improve workflows by process automation. Intelligent automation has significant advantages over outsourcing to humans in any setting. AI technologies, when implemented right, can make processes cheaper, better and faster than manual processing and deliver significantly improved customer experience.  

Speed. With AI, complicated data can be analyzed and vetted within minutes and hours, not weeks and months. 

Accuracy. The service level standards achieved by AI exceed those offered by outsourcing services, consistently delivering accurate results faster and with fewer errors.

Instant business insight. With insights gleaned from the analytics performed by AI, executives have fast, accurate information to make better business decisions, increase profitability and even capture new sources of revenue. Implementing intelligent automation with AI allows the entire organization to be “flattened,” with few layers, immediate access to information and the ability to share and act on insights right away. 

Savings. The savings achieved from no longer funding outsourced centers or third-party vendors can be redirected to covering operational expenses.

Increased value of American jobs. With the AI revolution, unlike the offshoring migration of 20 years ago, the jobs of American employees are not at risk. In fact, their jobs will be enriched because workers are now armed with accurate data much more quickly than before. Employees have more time to spend on tasks that are client-facing and that deliver high value to customers instead of mundane repetitive task work. As these employees deliver greater value, their own value increases, as well, making them worth more. Automation has historically created specialized positions, which improves the workforce production, earnings and morale.

Will outsourcing disappear with AI? The answer must take into account the role that manual process intake plays with AI. An AI model is only as smart as the data fed into it. This data must be input to a level to educate the model and to continue to allow it to become “smarter” over time. So, manual input will continue to be with us, whether offshored or outsourced in the U.S., but on a much more limited basis once insurance companies adopt AI models. 

Undertaking this shift from offshoring to in-house automation is critical to the success of every company in the insurance sector. Fortunately, this transition does not have to be as disruptive and painful as the rush to offshoring was 20 years ago, if this shift is approached with an understanding of change management. It’s important to undertake this seismic task with an end-to-end plan, versus spot solutions, and to have partners with insurance sector expertise who can develop the customized solutions that an individual company will require. The first step is to understand the ramifications and benefits of this transformation, and that it is inevitable for companies that want to be the market leaders of the future.


Steven Salar

Profile picture for user StevenSalar

Steven Salar

Steven Salar is the president of Exdion Insurance, an insurtech that partners with commercial insurance agencies and brokers to digitize their operations, using AI, machine learning and natural language processing. 

Salar has more than three decades of experience in commercial and personal lines in property and casualty insurance, including experience as a producer, compliance manager, operations executive, technology consultant and risk manager.

Prior to joining Exdion, he worked with QBE North America and the AIG companies and owned the Steven Salar Agency. Among personal lines carriers, he has worked for State Farm, Farmers Insurance and Countrywide Insurance Group

Automating Financial Underwriting in Surety

With automated financial underwriting, the provider can instantly quote and issue bonds that previously took hours or even days. 

Person holding stylus and using a computer mouse

Picture this: Your customer needs a high-risk surety bond with a large bond limit. You submit an application to your traditional surety carrier on your customer’s behalf and receive a response indicating that the bond will not be approved unless your customer provides financials. What ensues is an arduous series of back-and-forths between you, the underwriter and your customer in an attempt to provide the surety company with the required information. The underwriter then manually reviews your customer’s financial information, and, after what feels like an eternity, your customer’s bond is issued. 

This is how financial underwriting works in the surety industry. 

Now picture this: Your customer provides their financial information directly through the bond application, the surety provider’s software automatically reviews the information in seconds and the bond is immediately quoted and ready to be issued. Your customer is amazed at how easy it was to obtain a high-risk bond, which in turn makes you look extremely good. 

See also: How Automation Can Address Today's Growing Underwriting Challenge

What It Is 

Automated financial underwriting allows the surety provider to systematically review financial statements, verify assets and underwrite the risk without human intervention. With automated financial underwriting, the surety provider can instantly quote and issue bonds that previously took hours or even days due to the need to review financial statements. 

Without automated financial underwriting, human underwriters must carefully review each aspect of your customer’s financial statements. This can cause exasperating delays. 

Why It Matters 

President Theodore Roosevelt famously said, “Nothing in this world is worth having or worth doing unless it means effort, pain [and] difficulty…” I would counter that Teddy never tried to obtain a surety bond that was subject to financial underwriting. 

Automated financial underwriting presents a better path forward for agents than the status quo and eliminates one of the primary pain points associated with obtaining larger surety bonds.