Download

What a Successful Pivot Looks Like

Key lesson: Never pull the plug on something that is working to do something new until proving that you can successfully do the new thing. 

Blue Aircraft on Ship

“Pivot” ranks right up there on the Mt. Rushmore of startup jargon – right alongside “bootstrap,” “scale,” and “agile.” 

With AI becoming mainstream over the last year, discussions of pivots have been sent into overdrive. We’ve seen one tech company after another pivot toward AI. Some are genuinely integrating AI into their products; others are using marketing plays to AI-wash their brands.

To be clear, AI is the real deal; it’s why I wrote my thesis on it in business school. It’s not just a wave of enthusiasm – AI is finally delivering on the promise that’s been decades in the making. Everyone wants in, builders and investors alike.

But a pivot, whether it’s toward AI or something else entirely, is never easy. You can’t just will it to success. And while there’s a lot to be excited about, many organizations are sprinting too drunkenly toward AI. Worse, many companies that are doing just fine without AI are making drastic, irreversible changes that could cost them dearly – for the sake of AI.

A good pivot demands a clear strategy and a perfect product market fit. Founders must make decisions based on a deep understanding of market dynamics, not a fear of missing out on the next hot thing. 

Trust me, I have been there.

See also: 7 Things Sailing Taught Me on Leadership

An aircraft carrier-style turn

My company, Sure, began as a direct-to-consumer (D2C) mobile insurance app before becoming a digital insurance infrastructure company, using our existing core technology. In hindsight, the shift was absolutely the right move, but success wasn’t guaranteed, and it wasn’t always clear if it would work.  

They key lesson I learned: Never pull the plug on something that is working to do something new until proving that you can successfully do the new thing. 

Our transformation didn’t happen abruptly, or as a result of one meeting or feedback from our board. It wasn’t a situation where we got up one morning and decided to do something totally new. It was an evolution based on skeptical thinking. 

We didn’t even utter the word “pivot” – we thought of it as an aircraft carrier-style turn. We kept our heads down on the existing business while we started to identify the first customers for our SaaS solution – and it worked. The first partnership that we ever secured as a SaaS infrastructure provider is still going strong to this day. In fact, it’s never been stronger.

Unfortunately, many startups make the fatal mistake of impulsively abandoning what they are currently doing successfully to prematurely pivot toward something new – and, well, they end up failing, oftentimes slowly and painfully.

What not to do

Don’t get me wrong. A pivot can succeed. It just requires careful execution and avoiding certain pitfalls. Here are some pits of sorrow and misery that will make your pivot fail and lead your company toward oblivion:

  • Act impulsively: Jump on any trend, regardless of its long-term viability or relevance to your core strengths.
  • Ignore customer feedback: Avoid engaging with customers or conducting thorough market research. Ignore data, trust feedback from one VC. 
  • Rush the pivot, at all costs: Make abrupt changes without considering the impact on your existing customer base, team, and business partners that joined with the prior strategy.
  • Abandon your strengths: Disregard what your company is currently successful at. Instead, pivot toward unfamiliar areas that you’ve spent a weekend thinking about.
  • Stick to a rigid plan: Refuse to adapt your strategy as challenges arise. Remain stubbornly committed to an initial plan, no matter its flaws and lack of traction.
  • Reinvent the wheel: Forego seeking advice from experienced peers or industry experts. Ignore what you are uniquely good at.
  • Chase short-term gains: Focus solely on immediate results rather than long-term sustainability and growth. Try to hit that next milestone for a capital raise instead of focusing on building for the long-term.
  • Avoid feedback: Neglect to refine your pivot strategy based on customer or market feedback. Don’t be skeptical. Your first idea wasn’t right, so the second one must be right!?
  • Expect smooth sailing: Fail to anticipate and prepare for the inevitable difficulties and setbacks that come with major change or a whole new set of competitors.

See also: Leadership Lessons From Sports

What to do

Pivoting is nothing new in the startup world, especially in recent years. Startups have navigated through periods of rapid growth, abundant capital, and challenging economic climates. Seasoned founders understand that simply having a great product doesn’t guarantee success, and shifting focus can either make or break even the most innovative companies.

While Sure may have had a short lifespan as a D2C mobile app, the strategic hypotheses that we committed to early on helped us to grow into the complete digital insurance technology solution that we are today. That core technology, application programming interfaces (APIs), embedded insurance, and fundamental hypothesis about the market has never been more true than it is today. We chose to stay focused on our core strengths while we explored new markets, and the results speak for themselves. 

Pulling off the pivot isn’t easy, but if done well it can unlock bigger opportunities you never dreamt about at the beginning of your entrepreneurial journey – all while positioning your company for long-term success.

Benefits of Insurance Agency Outsourcing

By offloading non-core tasks to outsourcing companies, agencies can boost productivity and improve overall operations.

Aerial View of Cityscape

Insurance agencies constantly face operational challenges, from managing client renewals to processing claims and updating policies. These tasks can overwhelm internal staff, distracting them from core business responsibilities. With increasing customer demands and the need for faster, more accurate service, insurance agency owners are looking for ways to remain competitive and efficient. 

Many are turning to outsourcing, which can help streamline operations and deliver key benefits to insurance agencies.

See also: Does Generative AI Kill Process Outsourcing?

Operational Challenges in Insurance Agencies

Insurance agencies face challenges daily such as data entry, policy renewals, claims handling, and policy checking that require constant attention and precision. Agencies must also deal with issuing certificates of insurance, sending out renewal notices, and ensuring accurate policy documentation. These tasks often take significant time.

Moreover, the high volume of repetitive tasks can make it difficult for the internal team to focus on more strategic functions, such as client management and improving customer service. By offloading non-core tasks to outsourcing companies, agencies can boost productivity and improve overall operations.

Here are potential key benefits:

Improved Operational Efficiency

By leveraging insurance outsourcing services for administrative functions—such as policy renewals, claims processing, and certificate of insurance services—to specialized teams, insurance agencies can ensure these tasks are handled quickly and accurately. With experts managing back-office tasks, agencies can experience faster turnaround times and greater accuracy in service delivery.

Cost Reduction and Resource Optimization

Hiring and training full-time employees for non-core tasks can be expensive, especially when considering expenses such as salaries, benefits, and continuing training. By outsourcing, insurance agencies get help from experienced people without the long-term financial burden of maintaining in-house staff. This not only lowers operational costs but also optimizes resource allocation, allowing agencies to invest more in the growth of their agency.

See also: Why Hasn't Insurance Automated More?

Access to Skilled Expertise

Outsourcing partners bring industry-related expertise, providing insurance agencies with access to already trained personnel. These people are familiar with processes such as policy checking, claims management, and other critical tasks. 

Flexibility and Scalability

Whether an agency is experiencing a temporary rise in workload during busy seasons or needs to reduce support during slower periods, outsourcing provides the flexibility required to adapt quickly. Outsourcing also offers agencies an excellent way to scale operations without the challenges of hiring in-house staff.

Focus on Core Business Functions

Day-to-day responsibilities like client relationship management, sales, and business development are crucial to long-term success but often take a back seat when administrative responsibilities pile up. Outsourcing frees internal teams to concentrate on essential areas, improving customer satisfaction and driving growth.

Improving Client Satisfaction Through Outsourcing

By offloading time-consuming tasks like policy checking, certificate issuance, and claims processing to outsourcing teams, agencies can respond more quickly to client inquiries and process insurance documents with greater accuracy. 

How to Choose the Right Outsourcing Company

To begin, agencies must clearly define their current back-office needs. It’s important to choose an experienced provider and one that offers a range of services, including ones you might not need at the moment but might want in the future.

Additionally, it's important to evaluate the BPO company security measures and compliance, to safeguard client information.

See also: A Turning Point for Offshore Wind

Conclusion

Outsourcing provides insurance agencies with processes to streamline operations, boost efficiency, and improve client satisfaction. By delegating non-core tasks to an experienced outsourcing company, agencies can focus on their primary business objectives while reducing costs and maintaining exceptional service quality. 

Leveraging Gen AI for Fintech Software

Generative AI enables self-learning models that continuously refine themselves using multimodal data, including text, images, and sensor data.

An artist’s illustration of artificial intelligence

Leveraging generative AI can transform the insurance sector by enabling dynamic risk modeling that evolves with real-time data inputs. 

Generative AI does this by integrating self-learning models that continuously refine themselves using multimodal data, including text, images, and sensor data. Insurance products can evolve alongside emerging risks, allowing for unprecedented precision in underwriting and claims management and fundamentally altering the competitive dynamics within the industry. 

Understanding Generative AI 

Generative AI models such as ChatGPT can produce content in various forms from data in which it has been trained. The content can be audio, image, or text. Generative AI models analyze information, look for patterns in it, and produce original content at a speed that far exceeds that of any human being. Generative AI processes data like the human brain does because it is based on neural networks.

Generative diffusion models are another prominent part of the generative AI industry. These models, such as DALL-E 2, Midjourney, and open-source Stable Diffusion, produce good-quality photos, video, and sound by reversing information loss because of noise intervention. Noise is a mathematically designed addition to an image. It incrementally blurs the data that is required to create a realistic image, and the model is able to generate the needed image without any data. 

Another paradigm of AI is predictive AI. It uses historical data to foretell outcomes accurately. For example, AI-driven risk assessment tools analyze and study historical data and help companies be insightful about future market trends. Predictive AI models are especially beneficial for businesses in the fintech industry, where forecasting and planning are strategic priorities.

See also: 3 Lessons Learned From Leveraging Gen AI

Enhancing Risk Modeling and Underwriting With AI

AI has improved the accuracy of many life insurance risk models and improved the underwriting process. 

Traditionally, life insurance risk models were based on historical data and estimates of mortality rates. The models could not adapt to capture the complex and changing nature of particular risk profiles. However, AI-driven predictive analytics can use a lot of data from various sources to detect subtle relationships that cannot be found by traditional methods.

Machine learning algorithms can learn from historical insurance data, and other sources like medical records and lifestyle information, then make highly accurate and specific risk assessments. Another branch of AI, deep learning, uses artificial neural networks that mimic the human brain's functioning. 

In insurance, deep learning can assess medical images and detect signs of diseases not observable in traditional medical records. When made a part of risk models, this information leads to a detailed assessment of a person's longevity. 

Also, the integration of real-time data from sources like wearable health trackers, fitness apps, and social media platforms presents a complete picture of risk profiles to underwriters. Advanced analytics and AI, such as predictive analytics, explore patterns that forecast future claims. 

The use of this technology also eliminates manual operations, thus lowering operational expenses and errors. A great example is the improved claims management process. AI-powered claims processing tools can quickly evaluate data from several sources. These can be police reports, medical records, and statements of witnesses.  

Thus, insurance firms are able to make well-informed decisions quicker.  

Hyper-Personalisation 

The use of generative AI presents huge opportunities for insurance and fintech domains primarily due to hyper-personalization. Financial products tailored to the needs of customers, such as personalized savings plans, investment strategies, and personalized premiums, enable organizations to provide a highly satisfying customer experience. 

Personalized customer engagement platforms use AI to manage  the questions of claimants and guide them through the entire claims process.

Additionally, generative AI improves an insurance firm's ability to assess credit risk. Thus, it boosts the ability to approve loans quickly. Such platforms use synthetic data to automate the evaluation of the financial historical and current data of the borrower. Thus, potential credit concerns and risks can be examined effectively. 

See also: 5 Ways Generative AI Will Transform Claims

Generative AI Integration With Existing Systems

Generative AI Integration is increasingly effective in data collection and processing. It is beneficial for sectors like fintech. When it is incorporated with existing systems, companies can find behavioral patterns that they cannot otherwise. 

This maximizes operational efficiency and helps pinpoint the activities of fraudsters. Here are key points for integrating GenAI.

  • Identify where you want to integrate generative AI. For example, you may want to integrate it with real-time applications like risk assessment tools. 
  • Set objectives or metrics for this implementation, such as customer engagement or cost reduction.
  • Evaluate different models on the value of their output, scalability, and integration flow.
  • The datasets prepared for training should be of high quality. Also, data governance practices impart greater accuracy.
  • Integrate generative AI with your CRM, ERP, or marketing automation software as it gives the most advantage.
  • Use strong security measures like encryption and access controls in the systems for data privacy, protection and transparency. 

Potential Challenges and Mitigation Strategies

Integrating generative AI in afintech business's ecosystem is not a straightforward process. It poses some challenges, which include the following:

Bias, Transparency, and Explainability in Decision-Making

The opacity of the AI models (also known as black box) and systems often conceal the reasoning behind their decisions. More important is cognitive bias, which introduces discrimination in the training data set. It begins with data generation and continues until the deployment of the AI system. 

Developers should embed fairness and transparency principles when structuring AI algorithms. The models should take into account fairness metrics and be able to give explanations for their decisions. The explanations should be clear to humans. 

This is particularly important in finance because unclear decisions in this high-stakes domain have severe consequences. Explainability can be introduced in many ways. Some major techniques are using interpretable models like decision trees, creating LIME, or Local Interpretable Model-agnostic Explanations, and using set standards. The standards should warrant AI systems to give clear reasons for their decisions. 

Model Interpretability

Interpretability in generative AI models is crucial for transparency. It also makes sure that senior insurance executives understand the outcomes produced by the model and validate the decisions. 

With time, AI implementation is subjected to regulatory standards. It makes interpretability essential for ensuring compliance with the regulations. It also enhances the trust and accountability of advanced technologies, which improves the rate of integration of generative AI across fintech and insurance domains. 

Innovative Approaches to Adaptive Insurance Solutions

AI algorithms that are trained properly analyze the risk profile comprehensively using factors beyond traditional demographics. The models re-evaluate existing customers and emerging risks whenever new information becomes available.

The following techniques and practices will aid in the development of insurance products that adjust to emerging risks. By doing so, they usher in many positive changes in the actuarial practices.

  • Set clear objectives to achieve real-time insights regarding risk.
  • When collecting data, make sure it is high in quality and relevant. 
  • Train generative AI models using historical data so they can determine patterns that point to potential risks.
  • Configure continuous data feed from integrated sources. It will keep your models updated in real time.
  • Techniques like stream processing facilitate continuous ingestion and analysis of data streams from different sources in real time. 
  • Train the model to automatically allocate risk scores to various processes and transactions based on the analyzed data.

However, to fully take advantage of the opportunities of generative AI, you need a thorough assessment of the business ecosystem by professionals who specialize in building and integrating generative AI. 

Well-thought-out investments in generative AI will help in the following ways:

  • Enhanced product offerings
  • Greater market reach 
  • Efficient allocation of spending
  • Operational intelligence 

Case Study

1. Metromile

Metromile, the mileage-based auto insurance company acquired by 2022, has successfully applied AI. It did so by developing ideal insurance products for its core audience to widen its market reach. It considered technologies that would evaluate potential risks, send personalized messages to users, and take on other important tasks. 

Metromile developed an interesting model of insurance whereby policyholders only pay per mile driven. It evaluates how a car is driven and tailors premiums based on this. Therefore, a policyholder who drives less will pay lower premiums. 

Metromile's unique approach and solution were widely praised. It resonated with drivers that had low monthly mileage and those in public transit or the remote workforce.

2. Appian Documentation Tool

Appian, founded in 1999, implemented AI in their Appian Documentation Tool for dynamic risk management. The platform uses AI for classifying documents and extracting important data automatically. This process also validates information.

The tool enables organizations to achieve increased visibility and maintain control over all their risk management activities. Additionally, the software's AI-based data fabric gives a single view of a firm's risk exposure. The risk reports produced by the tool are tailored to the needs of different stakeholders. The reports provide risk analytics in real time and support better decision-making.

Appian Documentation Tool has become a top AI-powered tool used by businesses in the banking sector. It has also been recognized by leading technological research and consulting firms like Gartner. 

3. MillerMo Employe Tool

MillerLabs took advantage of generative AI to enable insurance executives to automate routine tasks and fuel an environment of collaboration and innovation. The MillerMo Employe Tool uses the OpenAI GPT4-32k model and has a variety of functions. It serves as a personal assistant and facilitates proofreading and content production, data set analysis, and software development.

The tool automates administrative tasks for the company's employees so they can focus on the more significant aspects of their roles. 

Conclusion

Data analysis is very important for risk management in the insurance and fintech sectors. However, legacy systems compromise the ability to assess risk in today's ever-changing environment. 

Generative AI technology, which is evolving quickly, provides a great opportunity to enhance data analysis. With more accurate risk assessment, tailored policies, and seamless processes, AI improves customer experience. AI is, therefore, a strategic enabler that insurance and fintech firms have to adopt if they are to retain their competitiveness. 

AI’s Role in Modern Claims Management

Successful insurance companies will leverage AI for operational efficiency while retaining human oversight to address its limitations.

A Woman Explaining a Document to a Couple

Artificial intelligence (AI) has enhanced efficiency, accuracy, and customer satisfaction in claims management while reducing manpower and errors. In fact, AI-driven claim validation has improved accuracy to 99.99% and boosted operational efficiency by 60%.

By 2030, automation could replace over half of current claims activities — an indication that AI is not just a trend but will have a lasting impact in insurance.

However, successful implementation requires forward-thinking insurance leaders to take a balanced approach that recognizes both AI's potential and its limitations.

See also: How to Optimize Insurance Claims Management

How AI is improving claims management 

AI improves operational effectiveness, reduces costs, and improves accuracy and has an especially big impact on workers' compensation. Here’s how AI is reshaping claims in key areas:

  1. Workers’ compensation (WC) claims — AI improves WC claims management by providing predictive insights and reducing costs. A study shows AI integration can reduce legal involvement in lost-time claims by 15%, saving 5% in claim costs, or $3.5 million annually for insurers handling $70 million in claims. For instance, AI can predict the life of a claim, estimate settlement amounts, suggest light-duty jobs, and allocate funds accordingly, reducing the need for consultants and minimizing human errors.
  2. Fraud detection — AI can flag suspicious activities, such as claims reported on Monday mornings or at the end of the construction season, and alert human claims professionals to take a closer look. The AI enhances efficiency and reduces the resources needed for investigations.
  3. Catastrophe (CAT) modeling — AI can predict and respond to natural disasters. Adjusters use AI for heat mapping to identify areas likely to be hit by storms, allowing insurers to prepare and advise clients on precautions to take. For example, AI predicted Hurricane Ida’s path, enabling insurers to effectively allocate resources and promptly support affected clients.
  4. Budgeting — By analyzing past claims to predict future costs, AI can help companies plan for future claims and reduce financial surprises.

AI limitations in claims management

While AI has revolutionized claims management, it is not without its limitations and is not a foolproof method.

For one, AI’s effectiveness is highly dependent on the quality of data input, including claim amounts and quantities. An estimated 83% to 92% of all AI projects fail due to poor data quality. Ensuring the data is accurate and current remains a significant challenge.

AI also may struggle to make the right decisions in intricate situations. For example, claims involving complicated medical procedures, such as back surgeries, still require human oversight. AI might assist in processing but cannot fully replace human judgment. Insurance companies often have AI approvers — humans who review AI-generated decisions for accuracy and legality, particularly for complex claims. This human review is crucial.

Importantly, AI lacks the human empathy necessary for evaluating claims involving pain and suffering. While AI can calculate settlements based on medical expenses and wages, it cannot account for the emotional and psychological impacts of an accident. For instance, when determining compensation for someone who needs a knee replacement, AI won’t consider their co-morbidities, past athletic activities, or current job status. These nuanced considerations require a human touch.

See also: Making the Claims Process More Efficient

A balanced approach 

AI has become crucial in claims management, enhancing efficiency and accuracy. However, it will never fully replace human involvement. The future lies in combining AI’s strengths with human expertise to handle complex claims and provide empathetic service.

Successful insurance companies will leverage AI for operational efficiency while addressing its limitations with human oversight. Partnering with agile, AI-savvy risk management experts will be key to adapting to the evolving landscape.

AI will continue to shape claims management, but a balanced approach will ensure the highest standards and benefits for both insurers and clients.


David Chmiel

Profile picture for user DavidChmiel

David Chmiel

David Chmiel, senior vice president, is the national director of claims for global insurance brokerage Hub International.  

He has nearly 30 years of experience in the risk management space. He is a Worldwide Broker Network regional leader. 

Complications of Alcohol, Marijuana on Claims

Although a life or AD&D claim involving one or both substances could seem straightforward, far too often carriers encounter complications during the process. 

A couple drinks and smokes in the window

The effects of alcohol and marijuana may be well-known, but they present a less understood side effect for the insurance industry. Although a claim involving one or both substances could seem straightforward, far too often carriers encounter complications during the process. The solution tends to veer from black-and-white into gray.

Case in point

Consider this true scenario. A policyholder drowned while kayaking in rough waters and was found three days later. The blood alcohol concentration (BAC) measured 0.12%, well above the national limit of 0.08%. Believing this contributed to the accident, the carrier denied the claim. Yet what seemed like a simple closed case morphed into one far more complex.

The beneficiary argued it was decomposition that led to the heightened BAC level. Indeed, photos of the death scene and the autopsy showed noticeable body decomposition. Research indicates that high blood alcohol levels may develop during decay of organic material and that a level as high as 0.2% does not necessarily indicate alcohol was consumed before death.

Also, blood alcohol levels during an autopsy are valid for up to 48 hours, assuming proper protocols are observed. Because the insured was discovered after 72 hours and the decomposition process was under way, the BAC was found to be inconclusive and the denial was overturned on appeal.

Alcohol vs. marijuana

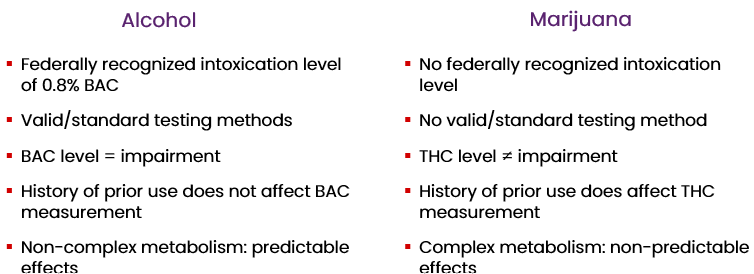
The impact of alcohol on life and accidental death and dismemberment (AD&D) claims is more defined than that of marijuana. Alcohol has been legal in the U.S. since 1933 (post-prohibition), nearly as long as marijuana has been federally illegal (since 1937). This creates some stark differences between the two substances:

  • Alcohol laws are consistent nationwide, as is a federally recognized intoxication level (0.08% BAC). The same does not hold true for marijuana. Regulations vary by state, and there is no standard intoxication level.
  • Alcohol has an established testing protocol to determine impairment – blood alcohol concentration; marijuana does not. The level of tetrahydrocannabinol (THC), the active ingredient in cannabis, does not necessarily equate to impairment.
  • A history of alcohol use does not affect the current BAC; the opposite is true for marijuana, where prior use can affect current THC levels.
  • Alcohol’s metabolic process is understood, and the effects are predictable. In contrast, the metabolism process for marijuana is more complex and its effects are unpredictable. For example, THC can be stored in body fat for up to 28 days.

Regulations for marijuana are still under development, and it could be years before there is national clarity matching what exists for alcohol.

See also: Why Are So Many Dying on U.S. Roads?

Challenges with alcohol and marijuana claims

AD&D benefits tend to be approved when the loss is the direct and sole result of an accident with no contributing causes, such as alcohol or marijuana. Still, the industry faces a few obstacles that complicate the process.

Unclear policy language

Ambiguous policy language creates confusion for claim handling. The absence of clear language can lead to inconsistent decisions, and appeals can go in the claimant’s favor.

Inconsistent practices

Carriers across the industry have varying approaches to risk management. While some insurers strictly adhere to policy language, others may demonstrate flexibility. Even the number of resources used for claims differs by carrier.

Lack of direction

The claim evaluation process can be riddled with ambiguity, making the decision less straightforward. Vague policy language can contribute to uncertain claim direction.

Lack of understanding

Most policyholders and beneficiaries lack a true comprehension of policy provisions and claim processes, especially where exclusions apply.

Different state, different law

Unlike alcohol, no federal standards for marijuana exist. Depending on the state, cannabis can be illegal, legal for medical use, or legal recreationally.

Documentation is key

Obtaining the proper documentation is critical for reaching an accurate decision. Examples of records to consider include:

  • Policy language
  • Death certificate
  • Coroner or medical examiner report
  • Toxicology report
  • Police report

The latter three can help determine policy exclusions for factors such as being under the influence.

Classifying marijuana

Because marijuana has been illegal in the U.S. for nearly 90 years, minimal medical science exists. Merely classifying marijuana presents a challenge. Because THC can cause multiple reactions to the central nervous system – excitement, impairment, depression – it does not fit into one drug category.

The Drug Enforcement Administration (DEA) has proposed reclassifying marijuana from a Schedule I drug – those without an accepted medical use and a high potential for abuse (e.g., heroin, LSD) – to a less regulated Schedule III drug (e.g., ketamine). If the change is made, it could create an avenue for expanded testing and established standards for law enforcement and the insurance industry. The road to reclassification is likely to be lengthy.

See also: Behavioral Science and Life Insurance

The state of marijuana

Because the legality of marijuana varies, claim decisions involving it require familiarity with the laws for the state in which the insured resided at the time of death.

Every state has laws addressing alcohol-impaired driving and drug-impaired driving, but the latter are more complex and difficult to enforce and vary substantially by state. One of two laws tends to apply when considering drug-impaired driving:

  • Zero tolerance: It is illegal to drive with any measurable level of specified drugs in the body.
  • Per se: It is illegal to drive with a level of specified drugs in the body that exceeds certain limits.

Conclusion

Alcohol- and marijuana-related claims exemplify the challenges inherent in claims adjudication. The complexities, especially for marijuana, create a significant challenge for carriers evaluating a claim’s validity.

Solid risk management protocols require a more detailed review of policy language, documentation, and state laws.

The impact of alcohol on claims is largely clear, but marijuana regulations vary by state and will continue to change. Insurers should consider broadening their exclusion language to address the use of marijuana and other drugs.

This is an ever-evolving process. The experts at RGA will continue to monitor its progress and provide future updates on alcohol, marijuana, and their complex impact on life and AD&D claims.


Kari Briscoe

Profile picture for user KariBriscoe

Kari Briscoe

Kari Briscoe is an executive director, claims consulting, at Reinsurance Group of America. 

Prior to joining RGA, shei was an appeals case manager for several years with a group disability insurer. She also has significant experience as a LTD Social Security case manager and was a paralegal for several private law firms.


Jill Underhill

Profile picture for user JillUnderhill

Jill Underhill

Jill Underhill is a director, claims consulting ,at Reinsurance Group of America. 

She is responsible for assisting RGA customers with disability claim management best practices, process improvement, and operational excellence. She has more than 18 years of combined experience working for major insurance companies.

Scaling Intelligent Automation in Insurance

Automating repetitive tasks can streamline workflows and allow for data-driven decisions with greater accuracy and speed.--but getting to scale can be tricky.  

Gray Scale Photo of Gears

Driven by the need to improve operational efficiency, enhance policyholders’ experiences, and reduce cost-to-serve, more insurers are deploying automation. Automating repetitive tasks can streamline workflows and allow for data-driven decisions with greater accuracy and speed. However, many insurers struggle to scale these solutions to full implementation. In this blog, we will explore how to move from pilot projects to organization-wide adoption efficiently. 

See also: Why Hasn't Insurance Automated More?

Create a Vision

Executives need to start by identifying areas where intelligent automation will have the biggest impact and aligning plans with overall company goals. Instead of prioritizing short-term, tactical savings, this usually entails bigger, long-term objectives. For instance, automation in insurance claims processes reduces errors, fast-tracks settlements, and improves customer satisfaction.

Consider factors such as business process complexity, scalability, workforce readiness, stakeholder engagement, and current technology infrastructure to get the real picture. The goal is to make the business more intelligent, flexible, productive, and competitive.

Assemble the Stakeholders

Without obtaining buy-in from key stakeholders, it is nearly impossible to transform an intelligent automation plan into a living program. So, from the outset, involve people such as senior IT personnel, who can help with many essential issues, including security compliance, auditability, and the supporting infrastructure, configuration, and scalability. Their expertise is vital in ensuring that automated processes, such as claims handling or underwriting, are secure and compliant. Working with IT should be a continuous process to mitigate operational consequences.

Develop the Plan

To automate insurance processes, you should collect the right data during the process definition phase. This requires subject experts as well as a walk-through with the appropriate stakeholders to see how the automated processes will differ from their manual counterparts.

Development commences once the relevant business and process design authorities accept the suggested blueprint. Your strategy should ideally include: 

  • Clear Objectives: Determine what success looks like to you, along with the metrics that will guide the implementation.
  • Technology Selection: Select the right tools and technologies for automation. This may include robotic process automation (RPA), artificial intelligence (AI), machine learning (ML), etc. 
  • Change Management: Prepare for the organizational changes that automation will bring. Provide for employee training to minimize resistance to change. 
  • Pilot Testing: Test the waters with pilot projects before committing to a full-scale rollout.
  • Scalability Planning: Make sure the insurance automation solution is flexible and accommodates changing business needs. 
  • Continuous Improvement: Make provisions for regular reviews to assess performance, identify areas for optimization, and adapt to changing business needs or technological advancements.

Execute the Plan

Now that you've developed your strategy, it's time to put it into action. Begin with the pilot project, perhaps automating a specific claims process or policy renewal workflow, and closely track its progress. Collect performance data and obtain user comments. Address any challenges that develop as soon as possible and use this information to improve your strategy.

Once the pilot run is successful, start scaling the automation throughout the organization. This phase includes extending the solution to more processes, such as quote generation, underwriting, and policy management automation, and possibly different departments such as finance or legal. It is critical to maintain communication with all stakeholders, solve any new difficulties, and continuously improve your automation techniques based on feedback and performance statistics.

See also: Why Touchless Claims Is a Must-Have in 2024

Measure and Track

The right key performance indicators (KPIs) provide tangible goals to strive for and clear milestones to track the progress of your initiatives, including aspects like automation in insurance underwriting. The KPIs do more than just measure. They measure what counts. They produce insights that help create a compelling business case for implementing or enhancing automation. KPIs might include metrics like reductions in claims processing time or improvement in customer satisfaction scores. They assist in answering issues such as, "Are we on track to meet our objectives?" and, "Do we need to change course?" With these KPIs, insurance leaders make strategic decisions, drive a culture of automation, and make necessary changes to meet goals. 

Conclusion

Scaling automation projects is no small endeavor. However, by embracing automation, forward-looking insurers position themselves to streamline operations and improve customer experiences. 

Solar Power Comes With New Hazards

Solar power carries risks from fire, natural hazards, and theft and vandalism. It also creates potential liabilities, including from overloaded roofs.

Dry plants on shore of calm reservoir

Investment by the power sector in solar photovoltaic – or solar PV – is expected to exceed $500 billion in 2024, surpassing all other generation technologies combined, and solar PV alone is expected to meet roughly half of the growth in global electricity demand to 2025. 

Global solar yearly installations in 2023 grew by 87% on the previous year, with growth dominated by China, which installed 57% of the world’s solar. There are now 33 countries where solar provides more than 10% of power generation, including Chile (20%), Australia (17%), and the Netherlands (17%), as well as the state of California at 28% -- itself the world’s fifth-largest economy.

We’ve seen many governments around the world announce carbon commitments and set net-zero goals to drive the energy transition, so we know clients face increasing pressures from regulators and stakeholders to revisit their energy strategies and improve their environmental performance. With the climate crisis intensifying a sense of urgency, solar power will be a leading light in the transformation of the power sector.

Opportunities to convert sunshine to electricity can be created on large rooftops on all kinds of buildings, on carports, in open land, and even over bodies of water, such as old quarries, with the development of floating photovoltaics (FPV). FPV technology has the potential to expand the installed capacity of solar power in densely populated regions where land is scarce.  

Solar PV installations offer the chance to reduce energy costs, demonstrate a company’s commitment to sustainability, and create energy independence, but they also present new risks.

As this market grows, installers need to be aware of the hazards such systems can introduce and understand how to mitigate these. The rapid rise of installed systems on rooftops, for example, has created complex challenges for both fire services and the code enforcement community. Several high-profile fires have occurred in commercial buildings with roof-mounted solar PV systems.

See also: Threats From Hurricanes Expand

Hazards, challenges, and loss prevention

Some of the potential hazards posed by solar PV installations include:

1. Fire  

Fire is the key concern with solar PV, as a roof fire can result in a total loss of the building and business interruption, not to mention loss of human life. PV panels introduce an ignition source to a roof and, like all electrical installations, are subject to electrical faults and other system failures that can result in "hot spots," which can ignite combustible material. Incorrectly installed or defective components can also cause fires, as can inadequate ground fault protection. A 2023 report shows the top five rooftop PV safety concerns were grounding issues, damaged modules, cross-mated connectors, poor terminations, and improperly assembled connectors.

Components in PV systems typically include plastics, which increase the combustible loading of a roof. The installation of PV panels on commercial and industrial buildings with combustible roofs, such as those insulated with combustible polystyrene, is discouraged. Green or sedum roofs, which are increasingly popular, can act as a thermal barrier and protect combustible insulation beneath them, but care should be taken with their design and installation, including using only low-growing plants. 

Rooftop PV panels are usually beyond a building’s fixed fire protection and detection systems, which can delay detection and therefore delay firefighting by the fire department. Firefighters can be exposed to the risk of electric shock, exposure to fumes from burning plastic materials, and the danger of falling debris.

2. Natural hazards

The exposed positions of roof-mounted PV systems make them susceptible to natural hazards like hail, wind, snow, and lightning. Around the world, project development is pushing developers to use locations that are highly exposed to natural catastrophe.

Risks from hail and windstorm, in particular, are increasing due to climate change and the trend toward using larger panels with thinner glass. For example, hail is the largest cause of loss for solar projects and facilities – in recent years, the insurance industry has continued to see reports of claims totaling $5 million to $80 million. Although hail claims tend to be low in number compared with other natural catastrophes, the values of them are significant. For example, a summer hailstorm in Texas in 2022 caused more than $300 million in damage to solar fields.

Windstorms can also severely affect PV panels, dislodging parts that become windborne debris, while the trend toward larger panels is altering panels’ wind resistance. The accumulation of snow and rainwater, combined with the weight of a PV system itself, can damage panels and roofs, or even cause roofs to collapse, while flooding can cause erosion that compromises the integrity of ground-mounted modules’ structural supports. 

PV installations are not thought to increase the probability of lightning strike on a building, but solar PV panels can be damaged by lightning. Earthquakes can result in broken glass, damaged electrical components, and increased fire risk. 

3. Overloading the roof

Solar panels, cabling and mounting equipment add between 10kg and 20kg per square meter. Not all roof structures are designed to withstand additional loads. Solar panels also influence how wind forces affect a roof structure, as well as how other loads, including snow, accumulate. Over time, extra load can lead to stress on the roof, potentially causing leaks, sagging, or even collapse. 

See also: Texas Wildfires Illustrate Challenges

4. Theft and vandalism

Theft of and vandalism to PV systems are on the rise globally, resulting in potentially serious financial losses for companies affected. Thieves are increasingly using modern technology such as Google Earth and drones to scope out targets. Sometimes, whole panels are stolen to be resold, or thieves remove the valuable materials they contain, including copper. 

5. Liability risks

Although the installation and operation of solar PV are based on proven technologies, liability risks that need to be considered include product and installation quality, contracting, and third-party assets. The operation of a roof-mounted solar PV system on the asset of a third party can also be a concern, such as when an entity leases their roof or ground area to another party to operate solar PV systems.  

The long-term nature of warranties on solar panels can present a liability risk if panels underperform due to unexpected degradation and the manufacturer’s warranty is no longer valid. Third-party liability risks are also posed by the presence and use in solar panels of PFAS and cadmium telluride, due to their toxicity and potential to pollute the environment. 

6. Floating solar PV

FPV uses conventional PV technologies, but the long-term reliability of FPV structures is not widely documented, as they have not yet been deployed at scale. Known challenges include: the need for divers to install the anchoring system; wear and tear on mooring systems; the accumulation of algae or microorganisms on PV modules (‘biofouling’); high humidity, which can accelerate corrosion; limited tilt angles due to wind considerations; uncertainty over the ownership of the water surface (which could be publicly or privately owned) and third-party rights to use it, such as fishing or shipping rights; and shading on the panels from bird droppings. 

Why Hyper-Accurate Geocoding Is Key

If an insurer is evaluating risk for properties along a Florida coastline, a discrepancy of as little as 50 to 100 feet matters during hurricane season. 

Unrecognizable paraglider flying in sky

You're likely familiar with the adage: “There’s no such thing as selling a bad risk. There’s only selling a badly priced risk.”

In an industry where risk is unavoidable, accurately assessing risk is paramount. The more accurately insurers can assess and factor for exposures, the more likely they can sell profitable policies. However, this is easier said than done. 

Many insurers are forced to gauge risk based on data that’s too imprecise to guarantee accuracy. As street, address, and ZIP codes are tweaked to resolve duplicates and fix errors in USPS data, many rely entirely on the wrong data.

Finding the right balance between risk and profitability is nearly impossible without precise underwriting based on accurate geocoding and risk analysis practices. To keep loss ratios in check, insurers must develop new processes that help them arrive at the most accurate price point possible. 

See also: "Micromorts": A New Way to Talk About Risks

Risk evaluation is a game of accuracy

One of the biggest mistakes an insurer can make is undervaluing or overvaluing the risk on a specific property. But it’s easy to understand how an inaccurate assessment can happen in practice. 

When evaluating a property’s risk, a typical insurer may perform some internal modeling to gauge the losses and wins other insurers have already experienced in that specific area. For example, if an insurer is exploring potential policies for properties along the Miami coastline, they’ll attempt to gauge which properties have a higher risk of storm surge and which are more protected. 

If an insurer overprices a policy (thus overestimating the risk exposure), they’ll struggle to sell that policy, and upon renewal may eventually see that policy churn to other companies that have more accurately identified the risk level. Conversely, if the insurer underprices a policy (thus underestimating the risk exposure), the insurer can sell that policy quickly but at a price that damages loss ratios. These underpriced customers are discouraged from leaving, leading to policy premium leakage.

But how do you factor in these hard-to-pinpoint risks without pricing policies so high that resource-strapped policyholders are edged out? In a time where there’s so much insurers can’t predict, the answer lies in fine-tuning the tools and processes that are in their control.

Accurate and high-speed geocoding, the process of turning a street address into geographic coordinates, offers a solution. Many insurers rely on outdated, on-prem servers and processes to assist their geocoding efforts. These servers are often slower and lack the precision of newer, cloud-based solutions, which in today’s insurance landscape, can make all the difference. For example, if an insurer is evaluating risk for properties along a Florida coastline, a discrepancy of as little as 50 to 100 feet matters during hurricane season. 

By using high-speed geocoding capable of processing tens of millions of records per hour, insurance analysts can efficiently model various scenarios and identify the most profitable pricing strategies.  

So, how can you reach this next level of underwriting, where you can consistently and precisely tie perceived risks back to policy pricing? It starts with hyper-accurate geocoding. 

The next frontier in underwriting

There are four main levels of geocoding precision: ZIP codes, streets, parcels, and rooftops.

Each progressing level offers more precise coordinates, which makes rooftop-accurate geocoding the goal for all insurers. Using high-precision geocoding can improve risk analysis and assist insurers with improving loss ratios. Even minor imperfections in geocoding can lead to millions of dollars of inaccurately priced policies.  

Rooftop geocoding is crucial for success, but equally as important is the ability to have a persistent and unique identifier (PUID) that acts as a single source of truth for a specific property. This is otherwise known as an address key. As street names change, you must maintain access to a stable address key over time. 

By connecting risk data to a PUID, insurers can create and test risk models accurately, faster, and more efficiently. A PUID can also link multiple risk data variables to a single location, even if that location may be associated with different street names and addresses. 

The first step is investing in more accurate geocoding and more consistent address data sources. But to effectively and consistently leverage these insights during underwriting, you must have rooftop-accurate geocodes and a PUID. This is where a cloud-based application programming interface (API) provider can come in handy, providing a customizable geocoding solution that fits neatly into your existing underwriting processes. The right API provider can help you manage and interpret data points from various sources, making it easier to leverage them in your underwriting process.

If you haven’t already done so, it’s time to explore a partnership with a third-party geolocation solution provider — because the most accurate data wins in insurance underwriting. You can have more experience, resources, and employees than the next company, but you won’t be able to maximize profit margins without accurate data.

See also: The Cognitive Biases Hurting Risk Management

Accurate property data is king

It’s time for a more nuanced approach to understanding location risk, one that prioritizes rooftop-accurate geocoding and a persistent, unique identifier for the properties being underwritten. This combination puts you in a better position to accurately gauge the risk for a specific property and, in turn, find the right price for that location.

Ultimately, for insurers, whoever has the most accurate and scalable geocoding will put themselves significantly ahead of their competition. Address and ZIP code data will continue to evolve, but those who prioritize hyper-accurate geocoding today will continue to reap the benefits for years to come.


Berkley Charlton

Profile picture for user BerkleyCharlton

Berkley Charlton

Berkley Charlton is the chief product officer at Smarty, a leader in location data intelligence.

Prior to Smarty, Charlton worked at Pitney Bowes Software as their managing director of product management. Charlton also worked as the VP of strategy and business development at Gadberry Group.

Individual Healthcare Is Creating Opportunity

As America goes freelance, health insurance for independent workers is more important, more accessible, and more affordable.

Silver computer on Brown Table Inside Room

When I left my full-time corporate job to start my own business, one of my first challenges was figuring out how to maintain my healthcare. I nearly fell out of my chair when I saw what it would cost me to continue my corporate plan under COBRA. When I turned to the health insurance marketplace for alternatives, I found myself completely lost in the jargon-heavy Summary of Benefits and Coverage documents, despite being a well-educated professional.

As I began reaching out to friends who’d been independent workers for years, I quickly learned I wasn’t alone. Anecdotally, my peers all agreed that costs and confusion were the greatest barriers to getting insured. The Kaiser Family Foundation’s analysis of uninsured adults found similar results: 64% cited cost as the reason they remained uninsured, while 22% pointed to the complex shopping and sign-up process.

These barriers are holding back the next generation of American entrepreneurs. Surveys suggest that between one in six and one in three American workers remain in corporate jobs to keep their benefits. In other words, they are so intimidated by the individual marketplace that many choose to stay in jobs they merely tolerate or dislike rather than navigate buying their own insurance. In recent years, however, meaningful changes have been made to the individual marketplace, making it far more appealing for independent workers by reducing costs and streamlining the enrollment experience.

See also: AI and Skills-Based Hiring

Developments in the Individual Healthcare Marketplace

In 2024, a record 21.3 million Americans enrolled in individual health insurance, including five million who were new to the individual healthcare marketplace. The Inflation Reduction Act (IRA) and the American Rescue Plan have introduced generous subsidies that bring the cost of healthcare into reach for millions of consumers. In fact, 80% of HealthCare.gov customers paid less than $10 per month for their insurance, after taking subsidies into account.

With these subsidies now available to independent workers, the individual market faces a twofold challenge in the Open Enrollment period: clearly communicating the availability of these subsidies and ensuring they are easy to access. Both the public and private sectors recognize these challenges and are working on complementary solutions to improve consumer education and streamline access.

The federal government recently announced $100 million in grants to provide free enrollment assistance, primarily through in-person support in underserved communities. Meanwhile, private-sector partners like Catch are collaborating with the Centers for Medicare & Medicaid Services (CMS) to develop seamless digital enrollment experiences that meet CMS’s rigorous security standards. These partners bring private-sector agility (and funding) and fresh ideas  to the individual market, reducing consumer friction and attracting new participants.

See also: Digital Self-Service Is Transforming Insurance

Impact on Insurance Industry

The individual insurance market has historically been an unpopular and overlooked niche of the broader healthcare ecosystem. Group brokers were put off by smaller commissions and fragmented distribution, while carriers were skeptical about the profitability and risk calculations involved.

Today, the individual market offers a growing opportunity across the benefits landscape. For carriers, it’s a chance to create products that appeal to the exploding population of independent workers—now 64 million and counting. For group brokers, it’s a chance to drive additional value to clients by serving their 1099 and part-time team members, as well. By partnering with digital enrollment platforms, brokers can support individual clients without the burden of excessive paperwork, enabling them to monetize their existing relationships more effectively.

Through collaboration across the insurance value chain, more individuals can access healthcare through the marketplace, fueling greater  entrepreneurship, investment, and innovation in the space. With this collective effort, the next aspiring entrepreneur leaving her corporate job will be able enroll in an affordable plan that fits her needs—in just minutes.


Alexa Irish

Profile picture for user AlexaIrish

Alexa Irish

Alexa Irish is co-CEO of Catch.

Previously, she served as VP of strategy and innovation at CLEAR. Before CLEAR, Irish was VP, marketing, at Nielsen. 

She graduated from Harvard in 2009.

The Growing Need for Real-Time Data

Historical data offers outdated information. Real-time data keeps you informed of changes to a policyholder’s risk profile, letting you adjust premiums. 

Person Writing on White Paper

Insurance policy structures thrive on data. Traditional models collect information about past events to guide risk assessment procedures.

However, there are instances when historical data does not apply to the current landscape. New intelligence could drastically influence policy structures. Real-time data collection provides a continuous stream of data to keep information current, revolutionizing the world of insurance. 

Traditional data collection methods — such as email questionnaires, oral conservations, and web forms — have been sufficient, especially at providing personal information about customers. However, this same set of tools creates several pain points for insurance companies:

  • Organization: There is a variety of information scattered throughout different collection methods, and collating the files requires a lot of resources. 
  • Viewing data: You may also struggle to access and view that data. Traditional intelligence piles up, requiring you to sort through files. Thus, viewing fresh information would still take time due to the backlog. 
  • Deriving value from data: Only 18% of insurance organizations have the tools and technologies to derive full value from the growing volume of files. Additionally, six in 10 collaborate with insurance technology companies, despite the fact that many insurance data masters view insurtechs as a threat. 

Real-time data collection offers a chance to enhance insurance systems. Introducing it may improve several processes:

  • Speeding up accessibility: Insurance professionals can pick out a recent file in a few clicks rather than sifting through multiple documents and scanning multiple texts. 
  • Verifying data reliability: Automating data collection verifies information to make it as reliable as possible. 
  • Accessing more accurate trends: You can also train predictive models to notice recent customer trends regarding their chosen insurance plans and claims. 
  • Forecasting outcomes: With more accurate data, companies could forecast outcomes and mitigate high-cost cases. They can also speed up adjustments. 
  • Enjoying more confidence: Insurance systems can also feel more confident in their numbers with real-time reporting. They can make more informed decisions and more accurately define patterns and trends. 

See also: The True Cost of Big (Bad) Data

Risk Assessment Accuracy

Historical data offers outdated information, and inaccuracy may result in financial losses. With real-time data, you remain informed of changes to a policyholder’s risk profile and can make adjustments to their premiums. Here are a few examples:

  • Driving and auto insurance: If you have real-time insight into a policyholder’s driving behaviors — such as speed and acceleration — you can adjust your assessments. If you notice any concerning behaviors, you can offer incentives for safe driving behaviors and assess whether they are effective.
  • Weather and homeowners insurance: If a policyholder lives in an area that has experienced an uptick in extreme wildfires, hurricanes, floods, or other weather phenomena, real-time data can determine their present risk and indicate whether it would be beneficial to update coverage. 
  • Theft and homeowners insurance: Real-time data can reveal high-risk areas where higher premiums may be necessary. 
  • Policyholder health and health insurance: Monitoring an individual’s health history, demographic factors, and lifestyle in real time can guide insurance companies to update health insurance premiums. 

Personalized Service

Real-time data collection allows insurance companies to offer personalized services to current and potential policyholders. Predictive models showcase more recent trends to see what people in different segments want in their insurance plans. You can match coverage limits, premiums, deductibles, exclusions, and other terms and conditions to the specific individual. 

Updated information can also speed the claims process. With automation, there’s no need to review paperwork and find the relevant data for a case. Automated systems can compile everything you need so that the recent data is at your fingertips.

With real-time data, you’ll understand how policyholders wish to be contacted and can communicate with them effectively. You also get a better basis for your decisions and inevitably create better insurance policies. 

Dynamic Pricing

Real-time data collection is also ideal for creating more dynamic pricing strategies.

Machine learning models that use historical data to guide pricing only improve profits by 1% or less. Replacing historical data with a continuous stream of information tailored to the individual policyholder can lure away potential policyholders from competitors.

Dynamic pricing allows you to act on real-time market changes and meet customer expectations. 

In addition to gathering market data about competitor pricing and demand, you can offer premiums that reflect the individual policyholder, essentially offering lower premiums for low-risk customers and higher premiums for high-risk customers. 

See also: Unauthorized Use of Auto Claims Data

Advanced Fraud Detection

In the U.S., more than $300 billion is lost to insurance fraud annually. Fraud results in higher premiums for all policyholders and costs each consumer approximately $900 per year.

Real-time data plays a critical role in detecting and preventing fraud. Policyholders may make illegitimate claims, whether deliberately or accidentally. With current information, insurance companies can detect anomalies and discrepancies in documents and evidence.

Whether a policyholder deliberately fakes an accident to fabricate an insurance claim, misrepresents an accident to receive a bigger payout, or accidentally omits important information when making a claim, real-time detection can help.  

Machine learning (ML) models are especially useful because they can calculate large datasets. One study published in 2024 found that effective ML models could drastically reduce health care fraud and minimize the resources needed to investigate probable fraud. 

When integrating real-time data collection and fraud detection technology, a human set of eyes must still assess those activities and make the final decision. Predictive analytics and models are only meant to display information and are still not perfect in their structure. 

Privacy and Compliance Considerations

Insurers must, of course, comply with privacy laws. A significant example is the European Union’s General Data Protection Regulation (GDPR), which extends its protection beyond its borders. 

A U.S. company may only receive personal data from an EU resident in accordance with GDPR guidelines. Insurers that provide services to individuals in the EU must comply with GDPR regulations, regardless of where the insurance company is registered. 

Select U.S. data protection laws also exist and prioritize the protection of policyholders. For instance, the Insurance Information and Privacy Protection Act (IIPPA) covers California residents, while the Health Insurance Portability and Accountability Act (HIPAA) protects an individual’s medical records and personal health information. Another important law is the Gramm-Leach-Bliley Act, which requires companies that offer financial services to explain their information-sharing policies to customers. 

Technological advancements like blockchain can provide data privacy advantages to insurance policymakers and holders. It’s designed to protect confidential and sensitive information by decentralizing control and using encryption to ensure data is inaccessible to unauthorized users.

Blockchain technology maintains the system's integrity and gives users peace of mind that their data is protected. Insurance companies also implement traditional cybersecurity protocols to mitigate cyberattacks.  

Revamped Policy Structures

Effective insurance policies protect policyholders. The best insurance policies are tailored to the individual and take market conditions into account. These policies help foster the relationship between companies and people. However, policies created using outdated information benefit neither party. In fact, they may diminish policyholder trust and lead to adverse financial outcomes. 

Real-time data collection is a key asset for insurance professionals. They can gain more updated information about their current and potential policyholders and resolve some of the issues associated with using historical data. With real-time data, your company can better assess risks and create a better relationship with customers. 


Jack Shaw

Profile picture for user JackShaw

Jack Shaw

Jack Shaw serves as the editor of Modded.

His insights on innovation have been published on Safeopedia, Packaging Digest, Plastics Today and USCCG, among others.