Download

A Strategic Bet on Private Credit

TCW Group's $3.25 billion partnership with Nippon Life signals private credit's evolution as insurers seek higher-yield investments.

Two People in Long-sleeved Shirts Shaking hands

The private credit market is witnessing a wave of strategic partnerships, and one of the most significant developments comes from TCW Group and Nippon Life Insurance. In a major move to anchor TCW's alternative credit business, Nippon Life has committed $3.25 billion in capital — marking another milestone in the convergence of insurance capital and private credit.

This deal not only reflects the growing appetite for private credit but also highlights the increasingly vital role that insurance companies are playing as strategic investors in illiquid assets. For TCW, this partnership solidifies its position as a key player in alternative credit, while Nippon Life gains access to robust returns from one of the fastest-growing asset classes.

Let's break down this deal, its significance for the broader market, and why partnerships like TCW-Nippon Life are shaping the future of private credit.

The Deal: $3.25 Billion in Anchor Capital

At the heart of this partnership lies Nippon Life's $3.25 billion capital commitment to TCW Group. The capital will serve as anchor funding for TCW's alternative credit business, allowing the asset manager to scale its private credit offerings and attract additional investors to its platform.

This isn't Nippon Life's first foray into private credit with TCW. Earlier this year, TCW joined forces with PNC Financial to launch a $2.5 billion private credit platform — a deal in which Nippon Life also participated. Nippon Life's expanded commitment underscores its confidence in TCW's ability to deploy capital effectively and generate strong risk-adjusted returns.

For TCW, Nippon Life's anchor capital provides a springboard for growth, ensuring the firm can compete with other alternative credit managers while leveraging its expertise to capitalize on opportunities in the private credit space.

Why Insurance Companies Are Betting Big on Private Credit

The TCW-Nippon Life deal is part of a broader trend: insurance companies increasingly turning to private credit as a preferred destination for their long-term capital. With traditional fixed-income investments offering diminishing yields, insurers are seeking higher returns without compromising stability. Private credit fits this profile perfectly.

Here's why insurance capital and private credit make for a winning combination:

  1. Attractive Risk-Adjusted Returns: Private credit offers yields that far outstrip traditional bonds, particularly in an environment of rising interest rates. For insurance companies with long investment horizons, these returns are especially appealing.
  2. Illiquidity Premium: Insurance companies are well-positioned to take advantage of illiquid investments, as their liability structures allow for long-term capital commitments. This makes private credit a natural fit.
  3. Diversification Benefits: Private credit provides insurers with exposure to a diverse range of assets and industries, helping them spread risk while enhancing overall portfolio returns.
  4. Strategic Partnerships: Deals like the one between TCW and Nippon Life demonstrate how insurers can partner with established asset managers to gain direct access to private credit opportunities, ensuring their capital is deployed efficiently.

TCW Group: Expanding Its Private Credit Platform

For TCW, Nippon Life's commitment represents more than just capital — it's a validation of TCW's alternative credit strategy and its ability to deliver results. As private credit continues to attract institutional interest, asset managers like TCW are scaling their platforms to meet growing demand.

The partnership with Nippon Life, alongside TCW's earlier collaboration with PNC Financial, reflects a clear strategy: leverage anchor capital to build scale and attract additional investors. By securing significant commitments from trusted partners, TCW is well-positioned to:

  • Expand its deal pipeline: With $3.25 billion in anchor capital, TCW can pursue larger and more complex transactions.
  • Attract additional investors: Anchor commitments provide a foundation that other institutional investors find attractive, helping TCW grow its platform further.
  • Compete with larger players: As competition in the private credit space intensifies, TCW's ability to secure long-term capital commitments gives it an edge.

Private Credit: The Growing Asset Class

The TCW-Nippon Life deal is a testament to the growing importance of private credit as an asset class. What was once a niche market has evolved into a multitrillion-dollar industry, attracting capital from a diverse range of investors, including insurers, pension funds, and endowments.

Several factors are driving this growth:

  • Bank Retrenchment: As traditional banks pull back from middle-market lending, private credit funds have stepped in to fill the gap.
  • Higher Yields: Private credit offers higher yields compared with public fixed-income markets, making it an attractive option for yield-hungry investors.
  • Flexibility and Customization: Unlike syndicated loans, private credit transactions are often tailored to meet the unique needs of borrowers, creating wins for both lenders and companies.
  • Resilient Performance: Even during periods of economic uncertainty, private credit has demonstrated resilience, further solidifying its appeal.

For insurance companies like Nippon Life, this asset class represents a strategic opportunity to deploy capital in a way that aligns with their long-term investment goals while enhancing returns.

What This Means for the Market

The TCW-Nippon Life partnership highlights a broader trend: the deepening relationship between private credit managers and insurance companies. As private credit platforms scale, partnerships with insurers provide a critical source of anchor capital, allowing managers to pursue larger opportunities and compete on a global stage.

For the market, this deal signals two key shifts:

  1. Private Credit's Institutionalization: The involvement of insurance giants like Nippon Life underscores private credit's evolution into a mainstream asset class.
  2. The Power of Partnerships: Strategic collaborations — like TCW's partnerships with Nippon Life and PNC Financial — are becoming a hallmark of success in the private credit industry.

Final Thoughts

TCW Group's $3.25 billion capital commitment from Nippon Life is more than just another deal — it's a sign of where the private credit market is heading. As insurers seek higher returns and private credit managers look to scale, partnerships like this one are setting the stage for the next chapter in alternative credit.

For TCW, Nippon Life's commitment reinforces its growing leadership in the space. For Nippon Life, the deal represents a strategic investment in one of the most attractive asset classes available today. And for the broader market, this partnership highlights the continued evolution of private credit as a key pillar of institutional finance.
Rajiv Bhat

Profile picture for user RajivBhat

Rajiv Bhat

Rajiv Bhat is co-founder and chief executive officer at martini.ai, a leader in AI-driven credit analytics. Rajiv was co-founder at social commerce startup Mertado (Y Combinator W2010) through its acquisition by Groupon. Later, he led data science at ad tech unicorn InMobi. He holds a Ph.D. in theoretical physics from University of Colorado at Boulder and an undergraduate degree from Indian Institute of Technology (IIT) Kanpur. For more information on martini.ai, please visit www.martini.ai, and follow the company on LinkedIn.

International Casualty Outlook for LATAM 2025

Latin America's booming life science sector faces new global risks, and environmental standards are evolving.

A Woman using Microscope

Positive outlook for life science sector

The life science sector in Latin America is experiencing significant growth, particularly in pharmaceuticals and clinical trials. With a projected compound annual growth rate of 10% in the pharmaceutical sector since 2021 and a diverse population with improving healthcare infrastructure, Latin America is a hub for clinical trials for international trial sponsors.

This growth has been driven by an aging population that requires advanced healthcare. The Latin American life science market has expanded due to increased healthcare investment, regulatory improvements, a focus on local production, and advancements in technology that have helped to broaden treatment options.

From a regulatory standpoint, Latin American countries are progressively aligning their practices with international standards, including good clinical practice (GCP) and International Council for Harmonization (ICH) guidelines. This harmonization contributes to more efficient and expedited approval processes for new pharmaceuticals and medical devices, enhancing growth opportunities for their products domestically and internationally.

Despite challenges posed by the current geopolitical environment, strong global demand remains for pharmaceutical products, providing significant opportunities for the Latin American market. As life science companies begin to export outside of Latin America, their liabilities and potential exposures change, making insurance an essential part of risk management. Not having adequate insurance in place for these businesses can mean they could be financially responsible for any injuries or damage caused by their products, which can lead to substantial legal and medical expenses.

With the rising costs of litigation and settlements globally, it's crucial for these businesses to be aware of these exposures when entering the global market. This is why working with specialist life science insurance providers is critical to ensure companies in the sector have adequate protection for their exposures, globally.

The need for environment liability cover

This section was written by Olivia Hogan, senior underwriter – international casualty, at Markel.

The financial implications of an environmental incident can be devastating, and with evolving environmental regulations, stricter laws are being implemented to improve compliance across the board.

One of the immediate impacts of more stringent environmental regulations on businesses is the necessity for compliance and a reinforced commitment to environmental responsibilities. Consequently, insurance companies are prompted to adapt their risk assessment models to address the increased environmental risks associated with these regulations, such as the probability of non-compliance or accidental breaches. The evolving landscape of environmental laws has driven innovation within the insurance sector, where insurers are now creating products designed to cover these risks on behalf of policyholders.

While numerous environmental laws and statutes exist across Latin America, they're governed by the "polluter pays" principle: "Those who produce pollution should pay for the costs associated with damage caused." Brazil, for example, is globally recognized for its vast and rich biodiversity, and protecting these natural resources is at the forefront of the country's environmental policies. The polluter pays principle is embedded in various laws and regulations in Brazil aimed at preventing and mitigating environmental damage.

Companies operating in industries where significant environmental impact could occur (e.g., mining, oil and gas) are required to take out environmental liability insurance in certain countries across the region to mitigate risk associated with their activities.

In Mexico, for example, transporters of hazardous materials are required to have environmental insurance coverage that meets the standards set by the Mexican government. These should specifically cover the costs of cleanup and remediation of environmental contamination resulting from spills or leaks. Transporters must ensure their insurance policies comply with the requirements set, which involves working with insurance providers that are familiar with the specific needs and regulations related to the transport of hazardous materials. Non-compliance with these insurance requirements can result in fines and legal penalties.

Environmental liability insurance will provide financial protection against environmental damage, statutory liability, and onsite first-party clean-up costs, as well as off-site clean-up costs and third-party bodily injury and property damage.

The demand for innovative and comprehensive coverage solutions will continue to grow as regulations tighten on an international level. Therefore, having an insurance partner that can provide comprehensive and adaptive coverage that evolves in line with legislation is paramount, ensuring businesses and individuals are fully protected if an incident occurs.


Olivia Hogan

Profile picture for user OliviaHogan

Olivia Hogan

Olivia Hogan is senior underwriter, environmental liability at Markel. She has 12 years' London Market experience, previously holding positions at Liberty and most recently AIG, leading the U.K. environmental underwriting team.

AI and Long-Term Care: Solving an Age-Old Challenge

AI transforms long-term care planning by offering personalized projections and strategies for an aging population's future needs.

Woman Standing Beside Woman on White Wooden Chair Facing Body of Water

Long-term care (LTC) planning has long been one of the most complex and emotionally charged areas of financial advisory services. As the aging population grows and care costs continue to escalate, advisors and clients alike face a daunting set of challenges. Traditional planning tools often rely on broad averages and generic simulations such as Monte Carlo that fail to capture the nuances of an individual's future needs and don't motivate families to plan for LTC. However, advances in artificial intelligence (AI) are beginning to transform this landscape, offering more precise and personalized approaches to LTC planning.

The Complexity of Long-Term Care Planning

Conventional tools that tend to use national averages and basic models can lead to several recurring issues:

  • Delayed Engagement: Many clients postpone LTC discussions until a crisis occurs, leaving little time to develop a thoughtful strategy.
  • Impersonal Data: Generic statistics and broad-based simulations do little to illustrate the true financial impact of LTC on an individual family.
  • Lost Opportunities: Without a tailored planning tool, advisors often struggle to convert early LTC discussions into concrete strategies, whether that means guiding a family toward an appropriate insurance policy or structuring a comprehensive financial plan.

These challenges highlight why LTC remains one of the few unsolved wildcard scenarios in retirement planning. Advisors and clients must contend with significant uncertainty. 

Yet, it is precisely this uncertainty that offers a last-mile opportunity for advisors to differentiate themselves by providing uniquely tailored, high-value solutions.

The AI Advantage in LTC Planning

Unlike traditional methods, AI-driven platforms can analyze a vast array of data, from regional cost variations and healthcare inflation to individual health status and family dynamics, to generate a personalized projection of a client's LTC journey. New technology solutions such as those we've developed at Waterlily are leveraging AI to personalize LTC planning, starting with streamlined intake processes.

These platforms create a tailored set of predictions to tell an insightful story of a client's future LTC needs. This narrative includes detailed projections on the timing and duration of care, anticipated costs, and even the care hours that will be taken on by family caregivers. Such personalized insights allow advisors to move beyond vague "what if" scenarios, initiating rich conversations that address the specific realities of each client's situation.

Enhancing Advisor-Client Interactions

The precision of AI-generated projections fundamentally changes how advisors engage with clients on the topic of long-term care. With clear, individualized data at hand, advisors are better positioned to:

  • Initiate Rich Conversations: Instead of relying on broad averages, advisors can discuss specific care projections tailored to the client's circumstances. This not only demystifies the planning process but also helps clients understand the real implications of their choices.
  • Accelerate Decision-Making: When clients are presented with a clear plan that outlines expected timelines and costs, this shortens the time from initial inquiry to concrete decisions, such as purchasing an appropriate policy or annuity.
  • Unlock Premium Growth: Personalized planning helps overcome the emotional barriers that often hinder LTC discussions. By converting these conversations into high-value, concrete plans, advisors can capture opportunities that might otherwise be lost.

These capabilities tackle key challenges in traditional LTC planning by promoting early client engagement and fostering stronger, data-driven advisor relationships. Further, LTC planning isn't just about traditional LTC insurance. Innovative options like life with rider policies, hybrid solutions, annuities, and even short-term care are energizing the market and offering clients potentially more competitive choices than ever before. When used effectively, AI makes it easier to build a strategy that educates, motivates, and covers every aspect of a client's long-term care needs and wants.

Balancing Technology With the Human Touch

While AI is undeniably powerful, its greatest strength lies in complementing, not replacing, the human expertise that financial advisors bring to the table. The nuanced and emotionally charged nature of LTC planning demands empathy, active listening, and the ability to navigate complex family dynamics. AI provides the detailed, data-driven insights that can inform these discussions, but it is the advisor who translates this information into a personalized plan that aligns with the client's overall financial goals and emotional needs.

In this evolving landscape, the role of the advisor remains as crucial as ever. By integrating AI-driven insights into their practice, advisors can offer a service that not only anticipates future expenses but also supports clients through one of the most challenging aspects of retirement planning.

The Future of LTC Planning for Advisors

As we move further into the era of digital transformation, the integration of AI into LTC planning is likely to become a standard practice in the insurance brokerage community. The ability to provide detailed, personalized care projections will not only help families prepare more effectively but will also drive opportunities for advisors to convert early, meaningful discussions into robust financial strategies.

At least for our rapidly aging society on the cusp of navigating long-term care with limited funds and family support, the potential impact of AI is significant. With more accurate projections and a personalized approach, advisors can help families navigate the uncertainties of aging with confidence. By combining technological innovation with the irreplaceable human touch, the insurance brokerage community is poised to turn one of the most challenging aspects of financial planning into an engaging and ultimately more secure experience for everyone involved.

In a field where the stakes are incredibly high, leveraging AI to craft clear, personalized LTC plans can be transformative. Advisors have the opportunity to remain enduring pillars in the insurance and financial services landscape by ensuring that families are not only financially secure but also emotionally supported as they navigate the future.


Lily Vittayarukskul

Profile picture for user LilyVittayarukskul

Lily Vittayarukskul

Lily Vittayarukskul is the co-founder and CEO of Waterlily. 

She started college at 14 years old and by 16 was venturing into a career in aerospace engineering as an intern at NASA. She graduated from UC Berkeley with a bachelor's degree in genetics and data science and led product and engineering at multiple startups before founding Waterlily. 

Are Insurtechs Still Considered a Threat?

Insurtech startups show signs of recovery despite past legal troubles, prompting traditional insurers to reconsider their competitive stance.

Assorted-color Opened Umbrella Hangs On Display

Insurtech startups have sprung up like mushrooms since the Great Recession — a period when public confidence in the traditional financial sector hit rock bottom. Full-stack upstarts were seen as existential threats to their established insurance player counterparts struggling to adapt to the digital age.

Nearly a decade after the insurtech rush in the first half of the 2010s, investor interest in these challenger brands has waned. Many of these startups have had their fair share of legal troubles, revealing the cracks in their business models. Given the growth and decline of insurtechs, should they still keep traditional insurance companies up at night?

The Strengths of Traditional Insurers Are the Weaknesses of Unicorns

Rapid innovation is the calling card of insurtech startups. They exist to disrupt the status quo, identify problems and use advanced technologies to solve them.

Technologically agile competitors strike fear into the hearts of decision-makers at established insurance companies. Startups have prompted old-school senior executives to reconsider legacy thinking and move out of their comfort zones.

What insurtechs don't have going for them is operational stability. Their leaders can be serial entrepreneurs with no previous insurance background. Lemonade's Shai Wininger and Hippo's Assaf Wand are excellent examples.

Wininger founded and co-founded several tech ventures — including Trimus, Handsmart Software, Mobideo, Fiverr and Santa — before starting his crusade to revolutionize renters and homeowners insurance. Wand was the head honcho of Foris Telecom and Sabi before developing one of the first smart home insurance products.

These newcomers to the industry excel at innovation. However, they lack expertise in risk management and regulatory compliance. In contrast, incumbents shine in these areas because of their centuries of head start on their tech-driven competition.

The genesis of the American insurance industry dates back to the 18th century, and many of today's largest home insurance companies — such as State Farm, Allstate, Liberty Mutual, USAA and Farmers — are decades older than Lemonade and Hippo. Full-stack insurtech firms haven't been around the block enough times to recognize the fundamental flaws in their business models and iron out the kinks of their operational frameworks.

Poor Stock Performance — Investors Give Insurtech Enterprises a Reality Check

The turn of the 2020s was a watershed moment in the history of insurtech startups. Numerous full-stack unicorns went public between 2020 and 2021 to raise much-needed capital as they targeted profitability. Unfortunately for these newly minted publicly traded entities, the euphoria was short-lived.

Charles River Associates (CRA) compared the stock prices of 13 insurtechs against 18 traditional insurance companies that went public between 2015 and 2024. The consulting firm's two sets of findings were as different as night and day.

Most insurtech enterprises recorded negative returns against the S&P 500 (SPX) and the S&P 500 Insurance Industry Group indices three months and one year after their initial trading date. This trend persisted after examining these enterprises' historical stock prices up to April 30, 2024 — the date on which CRA compiled the data.

On average, insurtech stock prices plummeted 24% three months after their first trading date and 19% one year following their initial public offering (IPO) with or without a special purchase acquisition company (SPAC). The more time passed, the worse the drop was. From going public to April 30, 2024, 61% of the value of insurtech stocks vanished.

This phenomenon doesn't extend to the greater insurance industry. The noninsurtech stocks yielded impressive medium- and long-term returns. Their value jumped 33% one year after their initial trading date and 318% by April 30, 2024.

Many factors come into play when a stock chronically underperforms. However, no factors were as significant as getting involved in high-profile legal scandals.

Hippo Fuels Legal Arguments Against SPACs

Some insurtech unicorns used SPACs to go public for practical reasons. These blank-check companies promise fast execution, upfront price discovery, low marketing costs and quick access to operational expertise.

The problem is that SPAC mergers are subject to less scrutiny. The process requires less due diligence and can result in exaggerated valuations, which is what happened to Hippo after its ticker symbol floated on the New York Stock Exchange.

Hippo’s market capitalization was $5 billion when it went public. By September 2023, its valuation plunged by 96%, reducing its valuation to about $222 million. Mammoth withdrawals by the insurtech's SPAC investors triggered the decline.

Hippo's lackluster stock performance compelled the board to oust Wand as CEO in June 2022. The company’s stock launch also helped galvanize the SEC into imposing additional IPO-by-SPAC procedural and disclosure requirements to strengthen investor protections.

Increased oversight over SPACs should prevent future public companies from suffering the same fate as Hippo. However, the stigma of entering public markets through a SPAC has followed tech-first insurers — including those that chose the traditional IPO route.

Insurtech Firms Are Prone to Securities Class Action Litigation

The insurance industry is no stranger to lawsuits. All players — big and small — get in legal trouble on occasion. However, insurtechs account for a significant portion of securities class action litigation relative to their quantity.

Tech-first insurers are in the minority. There were 1,500 of them in 2024 — a tiny fraction of all regulated insurance companies in the U.S. This figure is only slightly higher than the average number of licensed foreign insurers per state at 1,403, according to the National Association of Insurance Commissioners.

According to CRA's insights, there were 39 Section 10(b) and 12 Section 11 filings in the insurance industry from 2015 to 2024. Nine insurtech firms that went public in the same period found themselves in hot water by getting involved in these cases.

One of them was Clover Health. Investors sued this Jersey City, N.J., insurtech for allegedly hiding the fact that it was under active investigation by the Department of Justice for undisclosed third-party deals, kickbacks and many other issues when it went public.

The company also allegedly misrepresented its revenue streams and overstated its software platform’s capabilities. The allegations ended in a settlement worth $22 million without Clover Health admitting wrongdoing.

Another widely discussed example was GoHealth. The complainant alleged that the Chicago-based health insurance marketplace's IPO registration statement failed to contain crucial information for investors — like the higher risk of customer churn due to its limited carrier base and unique business model.

GoHealth and the plaintiffs settled the case for $29.3 million after more than three years of litigation.

Most of these securities class action lawsuits involved accusations related to the fundamentals of insurance operations. They highlight insurtechs' lack of operational resilience when leveraging technological innovation.

Traditional Insurance Companies Are Not Out of the Woods Yet

After many years of poor stock performance and legal battles, tech-driven startups are once again showing signs of life. They completed 71 deals in 2024’s first half despite reduced funding, crowning the U.S. as the leading insurtech market globally.

Furthermore, insurtechs that went public from 2020 onward rebounded in 2023. Their stocks collectively went up by 22%, and many of them were able to shrink their net losses. Such performance indicates that public market investors are slowly regaining their faith in insurtechs.

It would be premature to describe recent developments as a resurgence of trust in these startups, as many of them are light years away from their original valuations. Still, there's no denying that more investors are giving insurtech stocks a second look. Stock market participants may have had a change of heart because they're now more familiar with how these businesses work.

Understanding the complexities of insurtechs is vital in assessing their value as enterprises. More investors appreciate the innovations they bring to the table — like the use of telematics to collect and analyze fleet vehicle data for risk assessment or the application of AI to empower customers to complete applications and file claim reports independently with chatbots.

Hippo CEO Rick McCathron can attest to this. He said that his organization missed out on adequate analyst coverage because of its SPAC history. McCathron and Co. moved mountains to get analysts to care and are now reaping the fruits of their labor.

Hippo gained momentum in 2023 and carried it into the following year. 2024 was its best year so far; it recorded net income of $44 million in Q4. Only time will tell if Hippo can sustain this upward trajectory and if other insurtechs will report similar net earnings.

Viewing Disruptors as Collaborators Instead of Competitors

Traditional insurers shouldn't feel threatened by the recovery of insurtech stocks. It's normal for legacy-minded professionals to feel insecure about losing market share to more tech-driven players. However, established insurance companies should accept that they're here to stay and use these innovative individuals to modernize their systems, offer personalized services to customers and more.

After all, not all insurtechs are competitors. The others are partners looking for mutually beneficial collaborations to improve the insurance industry.


Jack Shaw

Profile picture for user JackShaw

Jack Shaw

Jack Shaw serves as the editor of Modded.

His insights on innovation have been published on Safeopedia, Packaging Digest, Plastics Today and USCCG, among others.


Strategic Priorities 2025: A Modern Era of Insurance Comes First

Don’t miss Majesco’s latest research report that highlights insurer’s top strategic priorities for 2025 and how they plan to compete in today’s changing market landscape.  

blue prints

2025 has been a wake-up call for insurance. The demand to invest in new technology and deliver next-gen capabilities is placing insurers at a crossroads of rethinking their strategies and priorities in order to stay ahead and compete. Read Majesco’s latest thought leadership report to understand what’s needed to fuel optimization, transformation and innovation.

Majesco - A New Operating Business Foundation for the New Era of Insurance

Read Now

Sponsored by ITL Partner: Majesco


ITL Partner: Majesco

Profile picture for user majescopartner

ITL Partner: Majesco

Majesco isn’t just riding the AI wave — we’re leading it across the P&C, L&AH, and Pension & Retirement markets. Born in the cloud and built with an AI-native vision, we’ve reimagined the insurance and pension core as an intelligent platform that enables insurers and retirement providers to move faster, see farther, and operate smarter. As leaders in intelligent SaaS, we embed AI and Agentic AI across our portfolio of core, underwriting, loss control, distribution, digital, and pension & retirement administration solutions — empowering customers with real-time insights, optimized operations, and measurable business outcomes.


Everything we build is designed to strip away complexity so our clients can focus on what matters most: delivering exceptional products, experiences, and long-term financial security for policyholders and plan participants. In a world of constant change, our native-cloud SaaS platform gives insurers, MGAs, and pension & retirement providers the agility to adapt to evolving risk, regulation, and market expectations, modernize operating models, and accelerate innovation at scale. With 1,400+ implementations and more than 375 customers worldwide, Majesco is the AI-native solution trusted to power the future of insurance and pension & retirement. Break free from the past and build what’s next at www.majesco.com


Additional Resources

Modernize or Fall Behind: 2025 Retirement & Pension Top Industry Trends

Read More

Closing the Insurance Customer Protection Gap: How Generational Differences in Risk, Readiness, and Coverage Are Redefining Insurance Value

Read More

Bridging the Customer Protection Gap

Read More

Transforming Specialty Insurance with AI

Read More

Leaders Reinventing Insurance: Strategic Focus on Business Operating Model and Technology Foundation

Read More

The Insurer’s Guide to Generative AI

Insurance leaders embrace generative AI to transform operations, with 82% seeing greater potential for business impact.

And abstract 3D rendering of green and blue ovals on a white background

Generative AI (gen AI) is transforming how we work and conduct business, and its impact is particularly evident in the insurance industry. From improving customer interactions to driving process efficiency and supporting decision-making, the technology is reshaping the entire value chain.

With gen AI's applications and use cases continuing to expand, our recent C-suite survey reflects a surge in optimism and confidence in the technology among insurers. 82% of insurance decision-makers now see greater potential for business impact from gen AI, based on their experience with the technology over the past year. Furthermore, 84% of leaders expect their organizations to increase their gen AI investment in 2025 as compared with 2024.

For insurers, this is an opportunity to capitalize on the immense potential that will come with scaling this technology to drive long-term growth. However, there are several key requisites that must be addressed to ensure a successful and responsible integration when designing a gen AI strategy:

Lead with value

Although gen AI has the potential to affect the full value chain, we see the greatest potential in underwriting/distribution and claims.

Research shows that 40% of the average underwriter’s time is spent on administrative and other non-core tasks. These demands and the surges in submissions in turn lead to an increase in workload without a proportional increase in revenue. Through automation and task augmentation, gen AI can help underwriters handle more tasks, work more efficiently, reach better decisions faster and win more business. For example, we worked with QBE, a multinational insurance company, to scale industry-leading AI-powered underwriting solutions across multiple regions and lines of business. They are now able to make faster, more accurate business decisions and greatly accelerate market response time. Early results also indicate an increase in both quote-to-bind rate and premium.

Gen AI can significantly enhance claims processing and outcomes, whether for frequency or severity claims. Additionally, using gen AI in claims can also improve rating and pricing activities. As a best practice, carriers can incorporate learnings extracted from unstructured claims data into a feedback loop for underwriting to guide future decisions, guidelines and appetite.

Reinvent talent and ways of working

Job displacement is a common concern when discussing gen AI. However, in the insurance industry, gen AI is more likely to augment, not replace, human activity. Regulation and licensing requirements need licensed professionals to make and communicate decisions. Unless requirements change, these roles cannot be replaced by AI.

In fact, both automation and augmentation with gen AI will create daily benefits for workers. Research shows that 29% of working hours in the insurance industry can be automated by gen AI, relieving workers of many of their more mundane and tedious tasks. What's more, 36% of working hours can be augmented by gen AI, which is crucial as the industry faces staffing shortages due to an aging workforce and competition for talent.

Close the gap on responsible AI

Insurers hold a position of trust when storing and processing sensitive data belonging to customers and partners, and it's important that this trust is maintained as gen AI becomes more integrated into operations.

As gen AI becomes more autonomous, the need for responsible AI practices becomes a necessity. Insurers must implement systematic testing and monitoring across quantitative and qualitative dimensions to manage risk with the highest ethical standards. This includes controls for data privacy, cybersecurity and sustainability, to ensure compliance as regulatory requirements inevitably increase.

Quantifiable measures help demonstrate the insurer's due diligence amid escalating cyber threats. Qualitative controls are equally important, improving transparency, explainability, accuracy, and safety. Insurance products can be hard for many customers to understand, and these issues are harder to navigate in communities where past discriminatory practices have undermined industry trust.

Build an AI-enabled, secure digital core

To fully realize the potential of gen AI, insurers require a strong digital core and a secure cloud. This starts with a simplified cloud infrastructure that integrates with core systems and can support the data and model needs of AI. A continuum control plane can serve as a unified command center, orchestrating infrastructure, applications, data, network, people and processes and simplifying cloud integration across a range of vendors. This not only improves operational resilience but also enhances visibility across the enterprise and can address complexities associated with moving operations to the cloud.

Security is another critical component essential to operational resilience and data protection. As the threat landscape evolves, insurers must implement systems that reduce the risk of breaches and adopt post-quantum encryption methods to protect vital and sensitive information. A modernized data platform, leveraging technologies like vectorDBs and knowledge graphs, can help insurers make the most of their data while ensuring compliance and privacy.

Foundation models can be easily integrated with the primary cloud setup. However, as needs become more complex, it's important to reassess priorities and retrain or build a new model to address specific goals and market realities. A model switchboard allows for dynamic adjustments to models based on the weight assigned to various priorities, such as accuracy, efficiency and cost.

The AI and gen AI capabilities of core insurance platforms are evolving quickly. For example, we’ve embedded AI and gen AI throughout our Accenture Life Insurance and Annuity Platform (ALIP) with cloud-managed services that include an AI-led user experience with conversational AI navigation and intelligent alerts.

Embrace change and continuous reinvention

Many insurers are now seeing material economic gains as they scale their AI and gen AI investments for continuous reinvention. This involves disciplined replication and re-use of gen AI solutions. Multiple lines of business in claims or multiple products in underwriting may be able to use the same user interface (UI) and user experience (UX) for gen AI implementations. Investments in UI/UX, front-end and back-end coding, rule and prompt libraries and data modernization can often be leveraged across the value chain.

Insurers are accelerating their reinvention journey with gen AI. They are building a culture and capability for continuous reinvention by centering every function in the value chain around a modern digital core. As such, the future of insurance will be led by those companies that can seamlessly blend human expertise with this technology, redefining what it means to be a trusted and innovative insurer.

A Radical Possibility for AI's Future

Could AI factories remove the need for insurers to have their own underwriting, policy administration, or claims processing units? 

Black and Gray Computer Motherboard

Insurance customers everywhere, across all lines of business, are clamoring for change. They want more simplicity, transparency and usability and lower rates. In response, regulatory solutions are being proposed in state capitals, and legislative solutions are being discussed and even hotly debated in Washington, D.C.

Meanwhile, Nvidia's annual GTC conference recently wrapped in San Jose, Calif. What started as a niche gathering of hard-core gaming enthusiasts (GTC stands for GPU Technology Conference, and GPU stands for graphics processing unit) has morphed into "The Super Bowl of AI," with a sold-out crowd of over 25,000 people attending in person and thousands more online.

What sets GTC apart from other tech conferences, and why I'm writing about it, is the growing number of non-IT participants. As AI is making English the programming language of the future, the business domain is becoming the language of AI.

This year, we learned that Nvidia's new Blackwell GPU chip is about 40x faster on half the power consumption than their existing Hopper GPU. Nvidia's next-generation GPU releases, Rubin in 2026 and Feynman in 2027, will at least be 40x faster on half the power than their predecessors. Over 90% of AI workloads run on Nvidia GPUs, and that won't change anytime soon.

We learned Nvidia is releasing an open-source operating system, called Dynamo, to orchestrate enterprise-scale GPU workloads. They also announced radical advancements in silicon photonics to accelerate switching in large-scale AI data centers. Add it all up, and Nvidia is moving beyond building AI chips to building "AI factories."

This means the latest language models with a trillion parameters will soon be outpaced by even more powerful systems, with tens of trillions of parameters on the same power consumption at a constant price.

New AI systems won't just be faster, they'll be ever smarter, more adaptable, and capable of handling complex tasks with high precision at massive volumes. This is where insurance comes in.

Imagine a world where the 2,000-odd insurers in the U.S. no longer need their own underwriting, policy administration, or claims processing units. Instead, AI-powered "super processors" handle the heavy lifting, leaving insurers to focus on marketing, finance and investment strategies. Think Visa and Mastercard. Banks once managed their own card networks, but now they outsource everything to these super-processors maintaining only affinity commercial relationships.

On the upside, insurance customers would win with lower premiums thanks to scale efficiencies and reduced overhead. Super-processors would wield unprecedented purchasing power with vendors such as auto body shops and home repair companies, further reducing costs. Litigation would logically be a fraction of what it is today with better information on all sides of a claim, harvesting and processing telematics data at machine speed in real time. Customer satisfaction would improve, perhaps dramatically. Carriers would win with variable, consumption-based pricing.

On the downside, thousands of insurance-processing jobs would disappear. But is that a problem or a solution? We know older insurance workers are retiring in numbers; we also know younger people with choices aren't flocking to the insurance industry. Attracting one talented human to run a digital workforce of 20 bots might be easier than attracting 20 humans to do mundane, bot-like work.

Might the critical path to optimal simplicity, transparency, usability, and lower premiums in insurance be digital black-box agents hosted in insanely complex, massively expensive AI data centers? And might this paradoxical solution be closer than we think?


Riv Arthur

Profile picture for user RivArthur

Riv Arthur

Riv Arthur is a business leader and technologist working in insurance, healthcare, and private equity.

Property Insurance Faces Existential Risk From Climate Change

All players in the property insurance ecosystem must help clients and communities harness property insurance as a tool for climate adaptation - or risk irrelevance.

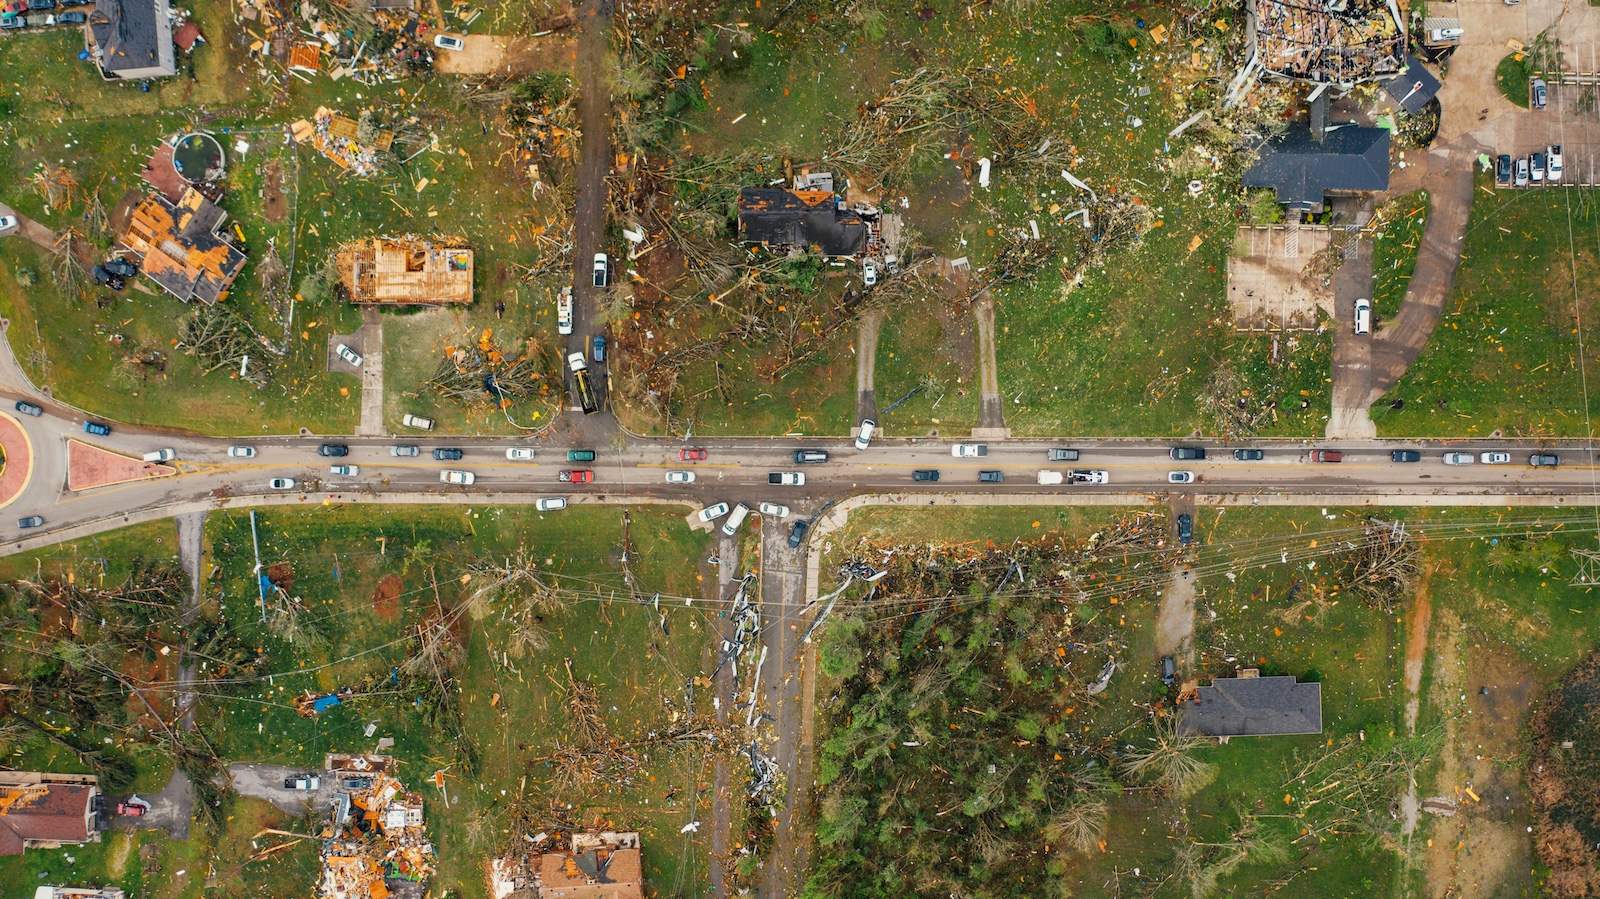
Dramatic aftereffects of thunderstorm on settlement cottages

Amid the daily 8 a.m. to 5 p.m. grind in the Square Mile, it can be easy to forget how much insurance matters. Not just to individuals and businesses, but to entire communities, economies and countries. This is especially true in the face of climate change.

The Los Angeles wildfires are just the latest prominent example of how the ability to recover from disasters depends on insurance, and how a lack of affordable property insurance will have long-lasting implications for individuals, businesses and economies.

It's against this backdrop that we as an industry need to carefully consider our approach to property insurance.

The decisions we make about what's insurable have begun to dictate whether people and companies can harness private property insurance as a tool for adapting to extreme weather and climate change.

Without greater awareness and engagement, we risk private property insurance becoming irrelevant to all but the wealthiest homeowners and most-profitable, best-capitalized companies. And we run the risk that government intervention in property insurance will transform markets in ways we are ill-prepared to cope with – with significant implications for our books of business and profitability.

Government and industry: Who will be responsible for risk?

Local, regional and national governments care deeply about the availability and affordability of property insurance. A lack of affordable insurance can force the need for greater government spending on recovery in the aftermath of disasters. It can also affect where investors decide to invest and lenders decide to lend, and on what terms. It is entwined not only with disaster preparedness and recovery but also with housing affordability and economic development on local, regional and national levels.

Governments also care because property risk is an increasingly political issue. Constituents are complaining as insurers worldwide respond to more frequent and severe extreme weather events by increasing the cost of property insurance or withdrawing from vulnerable geographies entirely. As we've recently seen in California, governments often respond to these kinds of complaints by imposing new regulations, especially around data, ratemaking and pricing. In some cases, quasi-governmental entities step in as (re)insurers themselves: For instance, Canada is setting up a flood insurer of last resort, Italy recently launched a multi-peril reinsurer of last resort, and the U.S. state of Colorado is creating an insurer of last resort for individuals and businesses facing elevated wildfire and hail risk.

At the heart of these efforts is a question of responsibility. As climate change intensifies extreme weather hazards, who will bear the risk? Also, what roles should the insurance industry and government each play in addressing property insurance affordability and risk challenges?

With the answers to these questions being worked out in real time at local, regional and national levels, it would be dangerously short-sighted if we as an industry did not meaningfully engage in these conversations as a partner for the long haul and in good faith.

Resilience and insurability: a two-way street

The insurance industry must urgently work to reduce the emissions that cause climate change, by encouraging and supporting fossil fuel clients in their transition to zero emissions. We are key to bringing lower-emissions energy sources to market, through our investments and by underwriting technologies such as wind, solar and nuclear power.

But climate change isn't just about decarbonization and fossil fuels. It's also about physical risk and helping homeowners, businesses, communities and economies become more resilient to extreme weather and natural hazards.

As an industry, we stand to benefit from reduced losses when homes and businesses have been fortified against floods, wildfires and hurricanes. We need to do more to encourage risk mitigation, through bursaries and other incentives that foster investments in adaptation and resilience. We can push governments to include funding for risk reduction as a priority alongside other regulatory reforms designed to bring down insurance costs. We should also ensure that our models properly account for investments that homeowners, businesses and governments have already made, at both individual and community scales.

Most of all, we need to recognize that resilience and insurability are critically linked. Helping insureds and communities become more resilient will mitigate their risk, increasing the likelihood that we can sensibly continue to underwrite them for years to come. Simultaneously, when we choose to continue underwriting (within reason) places where climate change is intensifying natural hazards, we ensure those communities can continue to attract the investment they need to adapt to climate risk.

Insurance is a for-profit industry, and no one is suggesting that's likely to change anytime soon. But it's illogical to focus solely on short-term financial value when insureds and governments are desperate for assistance protecting multiple different forms of value – embodied in homes, neighborhoods, communities and ecosystems – over multiple time scales.

Property insurance's existential question

For hundreds of years, the insurance industry has been able to make a profit by providing a social good: the funds homeowners and businesses need to recover, rebuild or relocate after disasters. However, climate change and extreme weather, insufficient investment in adaptation and risk reduction, alongside continued development in areas vulnerable to natural hazards, make it unlikely that property insurance as we know it will continue indefinitely.

The balance of responsibility for property risk is shifting, with governments, businesses and individuals each having a new role to play. For the insurance industry, the question is whether we want to be a supportive partner in deciding what the future of property insurance looks like or stand by while others make the choice for us.


Kate Stein

Profile picture for user KateStein

Kate Stein

Kate Stein is carrier relationship manager, WTW and co-founder, Climate-Resilient Insurance Strategy Project (CRISP).

How to Attract the Next Generation of Insurance Talent

Insurers must modernize their workflows and invest in automation. Gen Z will refuse to tolerate systems and processes that make them inefficient.

College Students Waiting on a Staircase

For years, the insurance industry has struggled to attract young professionals. Despite offering stable careers, strong earning potential, and meaningful work, insurance is overlooked by many college graduates in favor of tech-driven industries. 

The challenge? Outdated systems and technology that don't align with what Gen Z expects from their workplace.

If insurers want to build the next generation of talent, they must modernize their workflows and invest in automation. Gen Z will refuse to tolerate poor systems and processes that make them inefficient just because "that's the way we have always done it." Here's how upgrading your systems can make insurance a top career choice for young professionals.

Why Gen Z Prioritizes Technology

Today's college grads have grown up in a digital world. They expect seamless, intuitive technology in their personal and professional lives. According to a Deloitte study, 91% of Gen Z employees say technology influences their job choices. Outdated systems frustrate young employees, leading them to seek careers in industries with modern tools. When I was interviewing for positions on the carrier and broker sides, I would make sure to ask about their systems, and usually the best response they would come up with was along the lines of "You know, every company has its challenges."

By adopting better automation, cloud-based platforms, and AI-driven workflows, insurance companies can create an environment where young talent thrives.

How Better Technology Creates a More Attractive Workplace

1. Efficiency That Matches Expectations

Gen Z is accustomed to speed—whether it's instant communication or real-time data access. If an insurer relies on legacy systems that require manual data entry, slow approvals, and redundant paperwork, young professionals will see it as inefficient and outdated. Modernizing systems with automation tools reduces tedious tasks and lets employees focus on more strategic, engaging work.

2. Collaboration and Remote Work Readiness

The next generation values flexibility. Cloud-based platforms enable remote work, seamless collaboration, and real-time updates—key factors in attracting young professionals who prioritize work-life balance. A McKinsey report found that 87% of Gen Z employees want hybrid or remote options. Companies that embrace this shift will have an advantage in recruiting top talent.

3. AI and Automation for Higher-Value Work

Young professionals don't want to waste time on repetitive tasks. AI-driven automation eliminates manual processes, allowing employees to focus on problem-solving, client engagement, and innovation. When insurance firms adopt smarter workflows, they create a workplace that feels dynamic and forward-thinking—something Gen Z values highly.

The Bottom Line: Modernization Is a Recruitment Strategy

Improving your technology isn't just about efficiency—it's about talent acquisition. While the brand awareness of the insurance industry is based on funny characters advertising personal auto and home coverage, the companies that invest in automation, seamless workflows, and AI-driven processes will not only operate more effectively but also attract the best young talent in the industry.


Darren Bloomfield

Profile picture for user DarrenBloomfield

Darren Bloomfield

Darren Bloomfield partners with carriers and brokers at Feathery to implement automations to attract younger talent. 

He graduated from Butler University with a bachelor's degree in risk management & insurance/ finance. 

3 Ways Carriers Can Win With Independent Agents

Independent agents say carriers can gain a competitive edge and build deeper connections by improving process, communication and technology.

Businessman shaking hand of applicant in office

In 2025, insurance carriers are shifting their focus to drive growth. They're exploring new business opportunities while prioritizing relationships with independent agents.

However, to make their relationships with agents stronger, carriers must first understand what independent agents want and need. Vertafore's recent report, "Independent agents on improving carrier partnerships: Report for insurance carriers," analyzes survey responses from nearly 1,300 independent insurance agents to better understand their daily interactions with carriers and identify the tools needed to strengthen these relationships.

Agents identified three core areas where carriers can gain a competitive edge and build deeper connections with independent agents: process, communication and technology.

1. Refine Carrier Processes to Streamline Agent Workflows

The report found that efficient, streamlined processes are the foundation of a strong agent-carrier relationship. Just as a racecar driver relies on their pit crew, independent agents rely on carriers to navigate the onboarding process quickly and minimize administrative burdens, allowing agents to focus on their core strengths: serving clients and growing their business.

For example, 80% of agency customer service representatives said the ability to view and make changes to policies online should be a top priority for carriers. That number jumps to 83% for policyholder billing status. In a similar fashion, just over a third of respondents said it's important for carriers to invest in better onboarding and licensing tools and processes.

Agents aren't looking for flashy products; these outlined priorities demonstrate the big value that simplified processes bring to the table. From onboarding to claims handling, quick, available, and accurate information from carriers is vital.

2. Prioritize Clear and Responsive Communication

In addition to process efficiencies, the survey revealed that agents want clear, prompt communication when working with carriers, especially for underwriting and policy updates. As shifting market conditions and a complex underwriting environment bring big changes for carriers and agents alike, it's vital for carriers to communicate any changes quickly and clearly to minimize confusion and build trust.

According to the survey, 78% of agents cite ease of communication as key to giving more business to carriers. Producers and account managers also ranked personal relationships with underwriters (60%) and claims service (75%) as top factors that influence how they place new business. Survey respondents said that having a designated underwriter helps them write policies with more confidence, as they're able to rely on that personal relationship.

While technology is essential to facilitate strong communication between carriers and agents, it's not always the complete solution. Chatbots are a good example. While the insurance chatbot market is rapidly growing, and expected to hit nearly $4.5 billion by 2032, the surveyed agents mostly had a negative view of chatbots.

Only 15% of respondents said chatbots are "must-have" technology. Many agents voiced frustration with carrier chatbots and urged their carrier partners to make live assistance from real, seasoned team members more readily available.

Poor communication erodes trust, leaving agents feeling less inclined to place business with a carrier. If automated chatbots can't provide correct or complete answers, their efficiency doesn't compensate. In contrast, carriers that prioritize personal connections and responsiveness set themselves apart as top performers.

3. Adopt Modern Technology to Improve the Agent Experience

The last big takeaway is that technology modernization remains a top priority for agents and carriers. The agents surveyed reported the following capabilities as the most important to their day-to-day work:

  • Personal lines raters: Seven in 10 independent agents said digital personal lines rating and submission is a must-have. And raters for commercial lines are increasing in demand, as well.
  • Digital document and policy delivery: Six in 10 respondents agreed that digital document and policy delivery is critical when engaging with carrier partners.
  • AMS (agency management system) integration: Half of independent agents said it's important for carriers to integrate with their agency management system.

Integrated and easy-to-navigate systems significantly reduce the time agents spend on manual tasks, standardizing their workflows and increasing their capacity to write business. By investing in effective technology, carriers can set the tone for strong agency partnerships and achieve sustainable growth.

Next Steps for Carriers

These survey results make one thing clear: independent agents want efficiency, responsiveness, and modern technology. They expect carriers to invest in tech that streamlines workflows while enhancing, rather than replacing, their personal relationships with clients.

Carriers who refine their processes, improve communication, and invest in the right technology will stand out in a competitive market. By doing so, carriers can get the best out of their agency relationships, setting everyone up for long-term success.