Download

Baby Boomers' Retirement Crisis

Baby Boomers are suffering from a catastrophic shift of pension risks from institutions to individuals, because of a misunderstanding of behavioral steering. 

Elderly Man Holding Flowers While Walking with His Wife

When the facts change, I change my mind. What do you do? – John Maynard Keynes.

The Baby Boomer generation was the first to experiment with "the Great Risk Transfer" (GRT), a trend in which risks were transferred from institutions to individuals. In employee benefits, it manifested as workplace pensions moving away from defined benefit (DB) plans to defined contribution (DC) plans. Behavioral economics played an important role in this workplace pension risk transfer.

The moment of truth to assess the effects of the GRT and behavioral steering experiments is upon us, and the telltale signs are not too exciting. Baby Boomers are facing a retirement crisis, with fewer savings in their pension pots at the point of retirement or facing the prospect of running out of money while in retirement. Given the checkered results of the GRT, governments are embarking on a new wave of systemic pension reforms. The essence of these reforms is not to reverse the original risk transfer and make institutions fully responsible again but to strike a middle ground where they co-own some of the risk. The reforms also limit some of the autonomy individuals previously had but did not use wisely.

This article discusses risk transfer in workplace pensions, how behavioral economics influenced the course of retirement savings and retirement spending, how the original plan unfolded, and the continuing course-correction efforts.

Baby Boomers and the Retirement Crisis

Baby Boomers, currently in their late 50s to 70s, are either entering retirement or have already moved into a retired life. Representing a sizable portion of the population, they are facing a retirement crisis. Those who are at the doorstep of retirement are realizing that they have not saved enough, whereas those who are already retired are sensing the grim prospect of running out of money. They now have limited choices: postpone retirement, "unretire" and return to work to save for a few more years, or rely more heavily on Social Security for their income. Whatever the choice, they face a significantly reduced quality of life compared with what they once envisioned.

The cause of this predicament can be traced to the GRT, for which this generation became a "poster child" (euphemistically speaking) or a "lab rat" (if using a dysphemism). GRT is a term used by the Institute and Faculty of Actuaries (IFoA), UK, to refer to a trend of transferring risks from institutions—such as employers, the state, and financial service providers—to individuals. Prominent examples of the GRT trend include the steady shift from DB to DC pensions, the move from annuities to drawdown, fewer investment products with guarantees, and insurance products that are increasingly priced based on individual risk profiles rather than group-based pricing (Institute and Faculty of Actuaries, 2021).

A review of the retirement saving journey of employees after the GRT came into effect shows mixed results. The Homo Economicus population, or "economic man," representing a small fraction of the population—who is consistently rational, narrowly self-interested, and pursues subjectively defined ends optimally—might have done well by maximizing benefits from DC plans. In contrast, Homo Communis, or the common man representing the vast majority, who is far from rational, has not fared as well.

It is becoming increasingly evident that many retirees are sliding into a retirement crisis, with median savings significantly lower than what is needed to achieve a reasonable standard of living in retirement (Chater & Loewenstein, 2022). By following the principles of libertarian paternalism, these plans allowed individuals to withdraw or liquidate their pension pots when they needed money, leading to substantial retirement fund leakage. Pension experts now ruefully opine that staying with DB plans might have produced better outcomes, as those funds are professionally managed and can cross-subsidize long-lived pensioners with contributions from those who pass away early. Meanwhile, individual participants in DC plans must worry about outliving their funds.

As the experimental generation steps into retirement, another shortcoming is revealing itself. During the long accumulation phase, DC plans focused too much on the means and methods of accumulation, while the importance of decumulation was largely overlooked. The decumulation landscape, which was previously monopolized by the option to annuitize, gained another choice: withdrawing in lump sums or flexible installments. Annuities lost their appeal, and purchasing one came to be seen as a poor financial decision due to low returns on the money invested. The longevity risk of outliving one's savings faded from the personal finance risk radar.

There is now a late realization that while accumulating a pension pot was once considered the biggest challenge, an even greater challenge lies in efficiently accessing that pot to generate a regular stream of income that protects against inflation and rising expenses in retirement.

The Making of the Retirement Crisis

The workplace pension, also known as an occupational pension or employer-sponsored pension, is one of the great welfare success stories. A workplace pension requires an employer to contribute a sum of money to a pool of funds set aside to pay for a worker's future retirement benefits. The money accumulated during an employee's working years is used to pay a guaranteed, predetermined income for life once the individual reaches a certain age and retires. As labor-intensive, manufacturing-driven economic growth swept across the developed world, providing a workplace pension was seen as the perfect way to retain talent and reward employees.

When the Baby Boomers started working, the workplace pensions that existed were DB plans. Employers or institutions shouldered the entire spectrum of responsibilities, including enrollment, contributions, managing investments, and paying a sum of money on a regular basis sufficient for employees to live on for the rest of their lives. The amount of pension paid was linked to employees' wages or salaries, their length of employment, and other factors. These plans remained the most preferred or even the only workplace pension plan until labor-intensive work flourished.

DB plans started facing extreme financial stress due to the changing nature of work, an increasing old-age dependency ratio, rising life expectancy, declining fertility rates, interest rate volatility, and overall economic fragility. As pensions were guaranteed in DB plans, regulatory frameworks mandated that the funds meet their liabilities even in the worst demographic and economic scenarios. This requirement led employers to invest pension funds in assets considered safe, with minimal interest rate and inflation risks, while also producing regular cash flows to match pension payouts.

The advent of globalization and the shift in drivers of economic growth from manufacturing-based to information- and knowledge-based industries changed the course of industries. The number of new employees in traditional companies declined. The concept of employee persistence also changed, as careers no longer followed a linear pathway but were increasingly disrupted as individuals switched from one job to another. The cascading impact was that the equation between the inflow of money from contributions and the potential outflow as future pension payments began to dangerously signal a possible collapse.

This, in turn, triggered a series of reforms to reduce risk for employers and contain pension expenditures. There was a drive to gradually transfer the financial burden of retirement funding and related risks onto the employees, who were the participants and beneficiaries of the plans. What followed was a well-orchestrated shift from DB to DC plans. Institutions started to mitigate their risk by closing DB plans and sponsoring DC plans to avoid liability shortfalls.

In DC plans, both the employer and employee contribute to the employee's retirement account, and the funds are invested across various financial instruments. The employee controls the amount contributed, chooses where it is invested, and bears the investment risk. The pension benefits the participant receives are based on the amount contributed, as well as factors such as market performance, inflation, fees, and taxes. The transfer of financial risk was candy-wrapped and made to appear lucrative through the application of behavioral economics principles, creating the impression that it provided employees with more freedom, control, choice, higher returns, and personalization.

The Effects of the Great Risk Transfer

The risk transfer conveniently shifted the herculean task of managing long-term retirement finances from qualified professionals and institutions to amateurs and unskilled individuals. Workplace pension plans comprise two phases: accumulation, when money is saved during the working life to create a pension pot or nest egg; and decumulation, when the pension pot is accessed, and the nest egg is hatched to generate a structured payment after retirement. 

In DB plans, both phases remain closely integrated. The plan is tightly controlled and inflexible, giving employees no control or decision-making power. Despite appearing authoritarian or overly paternalistic, these plans were well-designed to account for the limitations of individual participants and were inherently more forgiving in nature. They provided equal financial security to employees across a wide spectrum of financial literacy. An employee participating in a DB plan could be unskilled or inexperienced in managing long-term finances, yet the plan ensured a financial safety net for the rest of their life.

In contrast, DC plans follow the principles of libertarian paternalism—an approach that respects individual freedom while aiming to nudge people's choices in a direction that enhances their well-being. The plan offers employees ownership, greater choice, control, and flexibility. The two phases of the plan are unbundled, and the employee must make decisions during both the accumulation and decumulation phases. Though the plan is more accommodating, it is unforgiving if employees make mistakes. Employees must actively enroll in the plan, determine the appropriate savings amount, efficiently manage their investment portfolio for several years, and then make the right decisions on how to access their retirement funds—whether by converting their pension pot into an annuity for regular income, opting for a lump sum, or choosing flexible withdrawals. If they misstep in any of these activities, the consequence is a punishment in the form of an inevitable retirement crisis faded from the personal finance risk radar.

Finding the Fingerprints of Behavioral Steering 

Given the complexities of risk transfer, the application of behavioral economics played a significant role in shifting risk in workplace pensions. While institutions were primarily motivated by reducing their pension liabilities, there was no equally strong incentive for individuals to willingly assume these risks. Therefore, a compelling motive had to be created to ensure the transfer happened seamlessly. To encourage participation in DC plans, they were marketed through advertisements and supported by regulatory guardrails, giving individuals a sense of security that these plans were highly regulated and safe. The relatively strong economic growth, including multiple bull-market runs in the 1980s and 1990s, acted as a macroeconomic catalyst for the expansion of these plans. This created a "steroid effect," reinforcing the belief that taking on risk and participating in DC plans would lead to a better retirement outcome than remaining in DB plans.

Employers, as sponsors of the plans, partnered with private plan providers to hold company-wide meetings introducing DC plans and encouraging participation. The benefit illustrations projected higher returns from stock market investments compared with the lower but stable returns from traditional pensions. Beyond the potential for higher returns, the plans offered employees a compelling value proposition, including tax-deferred benefits, employer-matching contributions, and plan portability. Packed with hard-to-resist benefits, DC plans quickly became the most common employer-sponsored retirement plan.

Despite the risk transfer, employers had a fiduciary responsibility toward their employees that they had to comply with. They still had the responsibility to provide qualified investment choices, guide employees toward making the right decisions, and ensure that funds were invested appropriately and that the plans were administered judiciously. In the early days, when new-age technologies had not emerged, marketing strategies, advertising, and providing in-person advice through certified advisors played an important role.

After new technologies emerged and do-it-yourself interfaces became the default choice for user engagement, any user interface, from organizational websites to mobile apps, became a digital choice architecture designed to nudge individuals. Choice architecture is the background against which an individual makes decisions and has major consequences for both decisions and outcomes. Changes to the user-interface design elements to guide people's behavior in a digital choice environment were much easier to implement. Consequently, digital behavior-steering initiatives were developed to nudge and steer individuals toward making rational choices. Given the vast time period, spanning several decades, and the comprehensive coverage of subject participants representing different demographic, geographic, psychographic, and behavioral segments, retirement savings became a perfect platform for conducting behavioral-steering experiments.

Choice architecture and nudge prompts were created to improve the participation of individuals and the decisions made by automatically enrolling an employee into a DC plan, creating curated default investment options to simplify the investment process, automatically escalating the contribution made, and, when the participant opted out, re-enrolling or re-escalating the contribution rate. These initiatives showed very promising results and gave confidence that behavioral steering could make up for the deficit in financial knowledge or rational boundedness that individuals are known for.

Behavioral Steering in Workplace Pensions: A Mistake or Misdirection?

Though the GRT was implemented due to economic considerations, the flaw was in the conception and execution in workplace pensions. The advocacy of libertarian paternalism and behavioral steering propositions for retirement did not work as well as initially believed (Chater & Loewenstein, 2022). The approaches were supposedly modeled to be a success based on Homo Economicus. On the contrary, the real world is represented by Homo Communis. These individuals are easily influenced by social and emotional factors and are limited by their own cognitive biases.

In addition, the supposed conclusions on the success of behavioral steering were based on limited-period studies, not longitudinal studies that reflect the multi-decadal time periods that a typical retirement saving accumulation spans across. Only a marginal percentage of the participants in DC plans are financially skilled, whereas the vast majority is unskilled and susceptible to making sub-optimal decisions. Even among those who are supposedly skilled in handling financial decisions, many are only skilled in managing immediate, short-term, or medium-term finances. Retirement saving is altogether a different beast to tame, requiring individuals to have the foresight to plan and pursue the planned path for several decades. This is an extremely rare skill and discipline that even an average Homo Economicus might find lacking.

The very hypothesis that, with the right interventions, individuals—irrespective of their financial knowledge and mental acuity—can make the right decisions to solve the retirement challenge and tackle the risks on their own was flawed and did not yield a binary result. While economic man participating in DC plans benefited immensely by judiciously leveraging deferred taxation, employer match, and better investment options, a rationally bounded Homo Communis choked due to the inability to function under the burden of excessive freedom. The decisions made by them were predominantly driven by immediacy bias, influenced by what they were going through at any given moment.

Research shows that nudges successfully influence initial decisions but lose steam over time. Nudges can make choices more likely but not the behavior that follows them (Polman & Maglio, 2024). Although nudges indeed make people more likely to select the targeted option, they use it less often and for less time compared with people who made the choice without a nudge. The lack of conscious effort might lead people to feel disconnected from their choices, potentially reducing their engagement. It is now acknowledged that the previous line of thinking—that many of society's most pressing problems can be addressed cheaply and effectively at the level of the individual, without modifying the system in which the individual operates—was a mistake (Chater & Loewenstein, 2022). Nudges can contribute substantially to fixing a "broken" policy by helping people make better choices. But behavioral economics, more broadly, should, in the longer term, also help shape the formulation and direction of policy (Loewenstein et al., 2016). Heavy-handed policies that remove individual choice seem to produce superior outcomes compared with nudge approaches that stop short of "forbidding any options" and are "easy and cheap to avoid" (Loewenstein et al., 2016).

It was probably not an optimal thought in the first place to believe that, with the right choice architecture, decisions that span several decades concerning retirement savings could be simplified into a one-time activity requiring a spot decision. To explain this in the context of the Behavior Grid designed by B.J. Fogg, it is like converting the retirement challenge into a dot behavioral change (Fogg, 2007). The grid defines three types of behavioral changes: dot, span, and path, which represent changes made respectively once, for a specific period, or for the long term starting now. The behavioral steering approaches attempted to convert retirement savings into a dot-behavior change, which the participant had to do once and then forget about it. While dot-behavior change might work for something like installing solar panels on a house, it has limited appeal for situations like retirement savings and spending, which require regular follow-through for several decades—essentially a path-behavioral change. According to Fogg, behavior change is a product of three factors: motivation, ability, and prompts (Fogg, 2009). The problem with the behavioral steering approaches experimented with in the DC plans was that they leaned heavily on the strength of triggers or prompts for a successful, permanent behavior change, even when motivation and ability remained unclear or weak. Prompting someone toward saving for retirement is not as simple as buying a consumable.

Lessons Learned: Better Late Than Never

It is clearly emerging that, despite the appeal, the GRT and behavioral steering have not worked well, especially in driving the mass of Homo Communis toward a retirement paradise. It is now accepted that merely setting up defaults cannot guarantee retirement security. Unfortunately, this wisdom is dawning after a colossal failure, with a major percentage of Baby Boomers losing their way in the retirement maze. Governments across several countries have embarked on a new wave of pension reforms. Systemic interventions are being introduced, with some responsibilities shared by the governments or employers, and guidance is being provided. Governments are making changes to the approaches toward both accumulation and decumulation phases. 

Educating people and engaging them to make the right financial decisions is gaining strong momentum. Making qualified and impartial advice available to everyone is another idea that is taking shape. For those who are nearing retirement, assistance and guidance in the form of financial consultations, engagement to plan for retirement, advice to make informed decisions about their pensions, and, in the worst cases where individuals have not saved enough, career consultations to prolong working years are provided.

To protect the interests of those in the early years of the accumulation phase, governments are tweaking workplace pension plans to withdraw some autonomy that the employees previously had but did not use wisely, and to impose some restrictive, hard, paternalistic approaches. Some countries have reformed or are in the process of reforming their pension systems by legalizing mandatory participation. To arrest gross leakages from retirement funds in the form of early withdrawals to meet immediate needs, the retirement fund is split into two parts: flexible and inflexible. Early withdrawals are allowed only from flexible funds, and the inflexible fund is insulated from any intermittent withdrawals. The accumulated portion in the inflexible fund can be used only for the payment of a structured pension at the time of retirement.

Another important product innovation that is gaining wide attention is the creation of collective defined contribution (CDC) plans, also known as target benefit or defined ambition plans. These plans work like a hybrid between DB and DC plans. Instead of contributing to individual accounts, the participants pool their retirement contributions into a single fund. These plans spread the investment risk across all the participants. The contributions are invested to provide members with an income during retirement. The plans provide a target pension, which is based on factors such as salary, length of service, and contribution rate. The income from CDC plans is not guaranteed and may vary based on investment performance and other actuarial factors.

Conclusion

The workplace pension risk transfer effected a paradigm shift in the core philosophy of employee benefits, fiduciary responsibility, and retirement protection. Several countries across the world adopted this model, and now reforms to strike a middle path are gaining momentum. The immediate impact of these reforms will be on the residual late-boomer cohort, which is yet to retire. The lessons learned from the experimental generation will immensely help Generation X, which is currently peaking in the accumulation phase, in seeking appropriate advice and making the right accumulation, decumulation, and retirement decisions.

As for Generation Y and Generation Z, who are respectively in the beginning and growing phases of retirement savings, some new macro challenges are emerging. The nature of work is shifting from regularized employment to freelance or gig work. This poses legal challenges in the definition of employment, the employer-employee relationship, and fiduciary responsibilities. To provide retirement savings to these demographic cohorts, carefully designed regulatory frameworks and new pension plans are needed.

With work itself becoming a matter of personal choice and freedom, behavioral economics and digital choice architecture may become even more important. The personal characteristics and traits of each generation, along with their sensitivity to behavioral steering triggers, differ. Hence, providing everyone with templated advice instead of advice personalized to their situation would not resonate with them. To manage this, it is likely that future digital interfaces will be designed to engage individuals on a personal level and provide continuous behavioral steering prompts to enforce path-behavioral change. While designing any new choice architecture for behavioral steering, it must be borne in mind that it is not the thrill of the journey that matters, but the safety of the travel and reaching the right destination.

References

Chater, N., & Loewenstein, G. (2022). The i-Frame and the S-Frame: How focusing on the Individual-Level solutions has led behavioral public policy astray. SSRN Electronic Journal. https://doi.org/10.2139/ssrn.4046264

Fogg, B. (2009). A Behavior Model for Persuasive Design. https://www.demenzemedicinagenerale.net/images/mens-sana/Captology_Fogg_Behavior_Model.pdf

Hanks, A. S., Just, D. R., Smith, L. E., & Wansink, B. (2012). Healthy convenience: nudging students toward healthier choices in the lunchroom. Journal of Public Health, 34(3), 370–376. https://doi.org/10.1093/pubmed/fds003

Institute and Faculty of Actuaries. (2021). Campaign recommendations. In Institute and Faculty of Actuaries. https://actuaries.org.uk/media/31hbykda/campaign-recommendations-april-2021.pdf

Loewenstein, G., Bryce, C., Hagmann, D., & Rajpal, S. (2014). Warning: You are About to Be Nudged. SSRN Electronic Journal. https://doi.org/10.2139/ssrn.2417383

Loewenstein, G., & Chater, N. (2017). Putting nudges in perspective. Behavioural Public Policy, 1(1), 26–53. https://doi.org/10.1017/bpp.2016.7

Maglio, E. P. and S. J. (2024, May 26). The Problem With Behavioral Nudges. WSJ. https://www.wsj.com/economy/consumers/decision-making-research-behavior-2e5060c1

Mertens, S., Herberz, M., Hahnel, U. J. J., & Brosch, T. (2021). The effectiveness of nudging: A meta-analysis of choice architecture interventions across behavioral domains. Proceedings of the National Academy of Sciences, 119(1). https://doi.org/10.1073/pnas.2107346118

Polman, E., & Maglio, S. J. (2024, April 29). Will Your Nudge Have a Lasting Impact? Harvard Business Review. https://hbr.org/2024/04/will-your-nudge-have-a-lasting-impact

Sunstein, C. R. (2013). Nudges.gov: Behavioral Economics and Regulation. SSRN Electronic Journal. https://doi.org/10.2139/ssrn.2220022
 

How Insurers Can Win in an Uncertain Market

Insurance firms face mounting data challenges as transactions soar and become more varied. Legacy systems struggle to keep pace.

Strands of Light dangling down form the top of the frame

Insurance firms are drowning in data. The average insurer processes over 10 million transactions annually—a figure expected to rise by 29% in the next two years. And the challenge isn't just volume, it's variety, too. That's according to a recent industry report that found that two-thirds of insurance firms handle data from an average of 17 different sources in their premium payment process alone.

Data sources are multiplying, too, and outdated systems are struggling to keep up. This increase in data is driven by the rise of digital transactions, third-party data sources, and regulatory changes. Meanwhile, customer expectations for faster payouts and greater transparency are higher than ever. And new tech-driven players (insurtechs) are setting the standard for faster, more accurate and efficient processes.

New Market Pressures

Legacy systems and manual processes weren't built for this level of complexity, and the consequences are evident. Manual processes are time-consuming and error-prone, leading to delayed settlements and making it difficult to consolidate data across platforms, resulting in data silos and fragmentation. Without centralized, automated data flows, insurance firms lack real-time visibility. However, 90% of firms are considering a new reconciliation solution to address these issues and avoid being left behind during a time of competitive change.

Insurance firms that centralize data management and automate reconciliation will save time, reduce human errors, accelerate reporting, and gain deeper strategic insights—turning data complexity into a competitive advantage.

The Need for Speed

Today's customers expect claims to be settled quickly and with minimal friction. In the U.S. alone, 80% of auto insurance customers are planning to or have already left their current insurer due to the lack of speed and accuracy.

With the insurtech market expected to grow more than 50% from 2024 to 2030 in the U.S., a new benchmark has been set for speed and efficiency to keep customers happy. Digital-first platforms are processing claims in minutes, while traditional insurance firms struggle to keep up with the amount of data being processed.

Insurance firms that automate payment processing and improve back-office efficiency will reduce settlement times, strengthen cash flow, and improve customer trust. So, faster payments don't just enhance customer experience, they create financial stability and free up capital for strategic growth.

Battling Regulatory Pressure

Regulatory standards are becoming more stringent across key markets like the U.S. and the U.K. With varying requirements across states, insurance firms are facing growing pressure to demonstrate accuracy, transparency, and financial control under regulations such as the International Finance Reporting Standard (IFRS 17) and the California Consumer Privacy Act (CCPA). Yet many insurance firms still rely on manual processes for regulatory reporting, raising the risk of inaccuracies, missed deadlines, and penalties.

Implementing automation in regulatory reporting and data reconciliation allows U.S. insurance firms to maintain compliance with greater accuracy and reduce manual efforts. Real-time data validation and automated reporting tools reduce the administrative burden, enabling insurance firms to adapt quickly to changing requirements.

The Power of Centralized Control

To stay competitive, insurance firms need more than small fixes—they need smarter, faster operations. Streamlining processes, improving accuracy, and speeding up service are key to meeting rising customer and market demands. Managing data across multiple platforms and sources is messy and slows operations when time is of the essence. Centralizing data into one system and automating key processes like reconciliations can reduce errors and speed reporting. With cleaner, more connected data, insurance firms can make faster, more informed decisions and respond to market changes with confidence.

Slow payouts frustrate customers and strain cash flow. Automating reconciliations and settlement processes reduces delays, lowers costs, and improves accuracy – boosting customer trust and financial strength. At scale, automating manual processes can lead to an average cost savings of up to 30% within five years for payers.

Regulations are complex and costly to get wrong. Automating reporting and data validation simplifies compliance – reducing risk without adding to operational workloads.

Adapt or Risk Being Outpaced by Competitors

The insurance industry is at a crossroads. Spreadsheets are still integral to financial operations in 90% of organizations. Firms that cling to outdated systems will face higher costs, slower growth, and frustrated customers.

Those who embrace automation and smarter data management will operate more efficiently, improve customer satisfaction, and strengthen their market position.


Piers Williams

Profile picture for user PiersWilliams

Piers Williams

Piers Williams leads the insurance sector globally at AutoRek. 

Previously, he worked in insurance brokerages and held various business-to-consumer (B2C) sales positions as well as working for GE Capital's U.K. asset management division. 

He holds a degree in international business (BSc) from Brunel University.

The Power of AI in Insurance Communications

AI technology helps insurance agencies streamline customer communications while maintaining consistency and compliance standards.

Grayscale Photo of a Circuit Board

In today's fast-paced digital world, insurance agencies are constantly looking for ways to improve their customer experience and meet the demand for quick service. Unfortunately, agents are wasting a lot of time on the leg work portion of customer service.

Agents spend 60% of their time each day on tasks related to customer service. That includes finding the right information about their clients' accounts, analyzing that information, communicating it to their clients, and bridging the knowledge gap so the client truly understands what they are receiving. This can equate to around five hours a day! This is a lot of really valuable time that is being lost. Not only does it slow the response time to clients, but it also takes agents away from more valuable interactions with their clients.

Fortunately, technology has played a major role in transforming how accounts are serviced and has evolved to meet customers' ever-changing wants and needs. AI now offers a chance to take this a step further.

There are myriad ways AI can be integrated into marketing and servicing workflows, ultimately freeing agents to focus on what matters most: building relationships and providing personalized advice. As most of us are familiar with AI-augmented chatbots to automate claims management and generative AI to create content, let's take it up a notch and look at how AI can be used in your client communications to ensure consistency and compliance. Using AI to do these things will save your team time while increasing customer satisfaction.

Build Consistency Guardrails

The tone and style of your agency's communications may vary depending on who is sending the emails. Some customer success representatives may take a more formal tone, while others write to their clients like they would their friends. Some may provide many details, while others may believe in keeping email communication brief and to the point. This can be frustrating for your clients. They crave consistency and want to interact with your agency as if the brand is one trusted person.

AI can provide guardrails to your communications, ensuring they remain consistent no matter who sends them. It can detect the tone in an email and suggest changes that will keep it in line with your agency's predetermined brand standards. AI can also help the customer representative properly phrase the information so that it's easier to understand.

Using AI to enforce consistency across client communications will make your customers happy. They will appreciate the steady tone and easily comprehend the information being shared. After all, the information doesn't do your clients any good if they don't understand it! Your team will also be happier because AI will save them time and effort in creating that consistency. Before AI, your team would need to manually review emails for tone and length, but now they can do it with a click of a button. This is a win-win for clients and staff!

Employ Compliance Fact-Checkers

Compliance is crucial for any business dealing with sensitive information. This is especially true for insurance agencies, whose systems house confidential identification and health information. Exposing the information in your agency management system (AMS) would not only upset your clients but could have costly consequences for them. Things like incorrect invoices, stolen bank account information and identity theft will create financial issues and definitely not lead to happy customers. Your agents are human, however, so mistakes can happen. It's easy for numbers to be typed into an email incorrectly or for the wrong customer's information to be included in an email. That's why it's imperative to use technology to safeguard against those mistakes.

Think of AI agents as your compliance fact-checkers. These tools can use the information in your AMS to ensure that you are only sharing the information you want shared. They can even flag information that may belong to another client. Agents no longer need to worry about sharing confidential information with the wrong person. Not only does this save your agency from the consequences of costly E&O issues, but it also saves your team the time of manually double- and triple-checking this information. Most importantly, your clients will be happy knowing their information is safe and secure.

Make AI Your Customer Service Partner

AI offers a wealth of opportunities for insurance agencies looking to elevate their customer service. By strategically implementing AI-augmented tools into the client communication process, agencies can free valuable time for their agents to focus on building stronger customer relationships and providing personalized advice. While it's important to be aware of the potential challenges and frustrations associated with AI, the benefits of increased efficiency, improved customer experiences, and enhanced growth opportunities make AI an invaluable tool for success.


Elad Tsur

Profile picture for user EladTsur

Elad Tsur

Elad Tsur is chief AI officer at Applied Systems.

Previously, he was the co-founder and CEO of Planck, where he developed an underwriting workbench enhanced by generative AI;.the lead architect of the Salesforce Einstein platform; and founder of BlueTail (acquired by Salesforce).

Pragmatic AI Strategy for Insurance Leaders

A strategic approach to multi-cloud AI helps P&C insurers reduce complexity while driving measurable business outcomes.

color image of a brain representing AI set against a dark shaded background

Lately, I've been getting a lot of questions about how to leverage multi-cloud AI capabilities across platforms while minimizing complexity and cost. In my experience working with P&C insurers implementing AI strategies, success depends on strategic clarity rather than the use of the latest technology. The most effective approach balances innovation with pragmatism.

A Business-First Approach

P&C insurers succeed with AI when they start with specific business challenges rather than technology capabilities. Insurers should identify quantifiable business objectives such as claims leakage, underwriting accuracy, customer retention, or operational efficiency. Then link AI initiatives directly to business KPIs aligned on those objectives. This business-first approach will help create a balanced road map of quick wins and strategic capabilities, ensuring investments address actual business needs.

Fit-for-Purpose Strategy

Recently, a client with an M365 E5 subscription was wondering whether implementing Copilot would conflict with their AWS-based analytics platform.

A fit-for-purpose approach would allow insurers to match appropriate AI technologies to specific functions, reducing integration complexity and avoiding the "one-size-fits-all" pitfall that has derailed many AI initiatives.

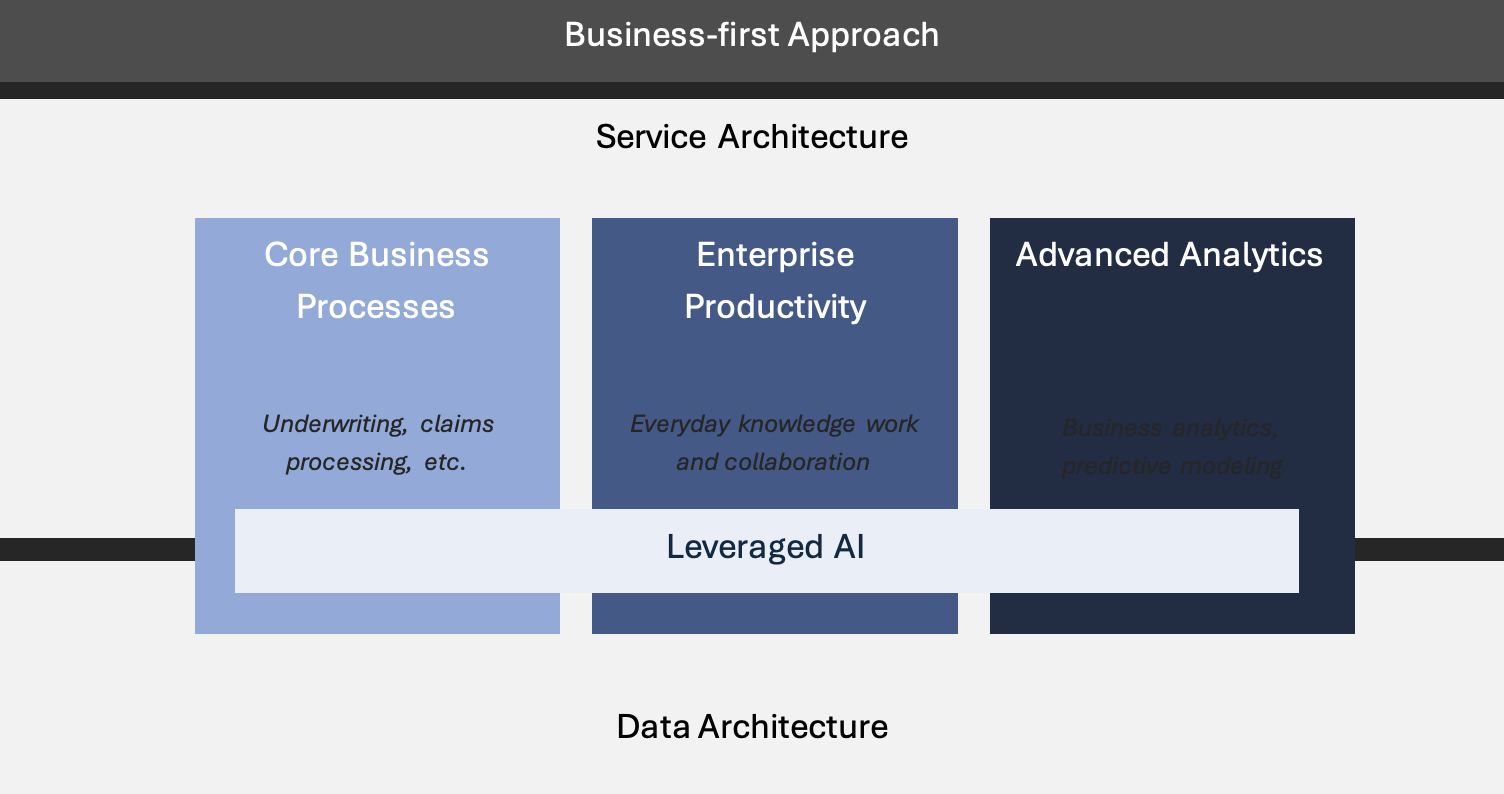
Here's one way to think about the AI landscape based on the purpose it would serve:

  • Core Business Processes: Leverage specialized insurance AI solutions for underwriting, claims processing, and risk assessment through embedded AI in core platforms or third-party integrations. Reserve in-house development for capabilities that create genuine market differentiation or deliver clear ROI.
  • Enterprise Productivity: Use the tool aligned with the enterprise productivity suite for everyday knowledge work and collaboration.
  • Advanced Analytics: Deploy models via the cloud provider's AI suite for specialized use cases, aligning with the enterprise data management platform and technology stack.

When it comes to leveraging any pre-built AI models and services, including GenAI, insurers should start with defining a framework to leverage them either as-is or fine-tuned, through hosted environments or API integrations, depending on the use case, overall cost and security requirements. The focus should be on speed to value rather than development. Then, organizations should implement a cross-cutting approach that integrates leveraged AI into and enhances solutions across functional areas.

Chart Displaying a Business-first Approach

Let's now revisit the question around Copilot and AWS. These platforms serve different purposes in the organization. Microsoft Copilot would integrate with M365 for daily productivity, while AWS would provide the infrastructure for specialized insurance analytics. Microsoft Purview, included with E5, will provide the necessary governance framework to monitor AI usage across the productivity layer. AI infrastructure on AWS will closely align with the organization's broad analytical data architecture.

This approach also helps insurers avoid the common pitfall of implementing GenAI as a technology-first initiative disconnected from real business challenges and outcomes.

Data Architecture

It is critical to prioritize data management, integration, and governance before sophisticated AI implementation. Insurers that approach data as strategic products rather than passive assets gain significant competitive advantages.

I recommend designing a unified data ecosystem connecting structured and unstructured business data into domain-specific data products that mirrors the organization's business architecture. It is also important to implement a data governance framework that ensures consistency, quality, and appropriate controls, and develop robust metadata that gives context and lineage for key data assets. Without this foundation, even the most sophisticated AI strategy will underperform against business expectations, as models will produce unreliable results.

By investing in a strong data architecture first, insurers can establish a reliable foundation for sustainable AI success.

Service Architecture

A robust service architecture enables services to deliver AI, to consume AI, and to be consumed by AI models using standardized protocols. A well-designed architecture helps transform AI from isolated experiments into scalable business capabilities, ensuring investments remain relevant as technologies evolve and new providers emerge.

AI services must be built around core business capabilities rather than technologies, and their effectiveness must be evaluated based on business metrics like loss ratio improvement and adjuster efficiency rather than technical metrics.

Core systems, data infrastructure, and AI capabilities must be connected using standard interfaces, creating an adaptive ecosystem rather than isolated point solutions. This integration serves as the glue between the functional areas mentioned earlier. It's also important to develop test-ready service endpoints and self-service validation interfaces for business users, fostering trust through transparency.

Governance protocols to address data drift, model drift, version control, and compliance-readiness should be baked into this architecture.

Conclusion

Successful P&C insurers understand that the value of AI lies not in specific vendor solutions but in the business capabilities it enables. By prioritizing data architecture and aligning efforts with business outcomes, insurers can navigate the rapidly evolving AI landscape while staying focused on what matters most: reducing complexity, controlling costs, and delivering measurable business impact early and incrementally.

Insurance Crisis Threatens Affordable Housing Development

Rising insurance costs threaten to derail affordable housing initiatives as developers struggle with soaring premiums in the U.S.

Overhead view of a neighborhood showing multiple homes

The U.S. has been facing an affordable housing crisis, with millions of low- and middle-income families struggling to find stable housing.

The National Association of Realtors' Housing Affordability Index (HAI) shows that for most of 2023 and 2024, the typical U.S. family earned less than the required income to qualify for a mortgage on a median-priced single-family home. Although recent data shows easing in both the HAI and the national rent-to-income ratio, affordability challenges persist. A recent Pew Research Center survey found that 69% of Americans said they were "very concerned" about the cost of housing.

While policymakers, community groups and private developers work to expand affordable housing options, an invisible but significant barrier threatens to derail these efforts: the escalating home insurance crisis.

Impacts of Rising Home Insurance Costs

Losses from natural disasters and consequent insurer withdrawals from high-risk markets have driven the sharp increase in property insurance rates. Additional factors, including elevated home prices, inflation, worsening climate issues, and increased rebuilding costs, have contributed to skyrocketing premiums, making securing coverage more difficult and expensive for both individuals and developers.

In states prone to hurricanes, wildfires and flooding, consumers have seen insurance costs surge. Between 2017 and 2022, homeowners insurance premiums rose 40% faster than inflation.

In high-risk states like California, Florida and Texas, gaps in coverage are forcing homeowners to rely on expensive state-backed programs (often with reduced coverage) or to forgo insurance altogether. Regulatory efforts to stabilize the market have struggled to balance affordability with insurer sustainability, leading to further uncertainty.

How the Insurance Crisis Affects Housing Development

For affordable housing developers and providers, challenges in the property insurance market pose multiple barriers.

Higher Development Costs

Rising insurance premiums increase overall construction and operational expenses for affordable housing projects. Developers must secure insurance for both the construction phase and for property management, and with costs surging in high-risk areas, many projects become financially nonviable — especially for affordable housing providers who cannot (or choose not to) pass on the higher costs to tenants. From 2020 to 2023, multifamily insurance rates increased by an average of 13% annually — and some developers struggle to find insurers willing to provide coverage at all, leading to costly delays or project cancellations.

Reduced Investment Appeal

Lenders and investors assess risk when funding housing projects, and skyrocketing insurance costs add another layer of uncertainty. When premiums eat into projected profits, financial institutions may hesitate to approve loans for developments in disaster-prone areas. For developers, lower returns on investments make affordable housing projects less attractive, pushing them toward more profitable, higher-income developments. Even for those prioritizing mission over profits, funding and managing projects at a loss is not sustainable.

Limited Availability for Homeowners and Renters

Higher insurance costs are ultimately passed down to homeowners and renters in most cases. Low-income families may find homeownership unattainable as rising premiums inflate total housing costs. Renters, too, face increasing expenses as landlords adjust rental prices to cover surging insurance rates, further limiting affordable housing options.

In instances where raising rents is not an option, capped or against the developer's mission, many affordable housing providers face difficult choices like offloading properties that will likely become market-rate units, potentially displacing renters and eliminating existing affordable housing.

How Affordable Housing Providers Are Navigating Insurance Challenges

The impact of rising insurance costs on affordable housing is being felt across the country, with projects stalled, canceled or scaled back.

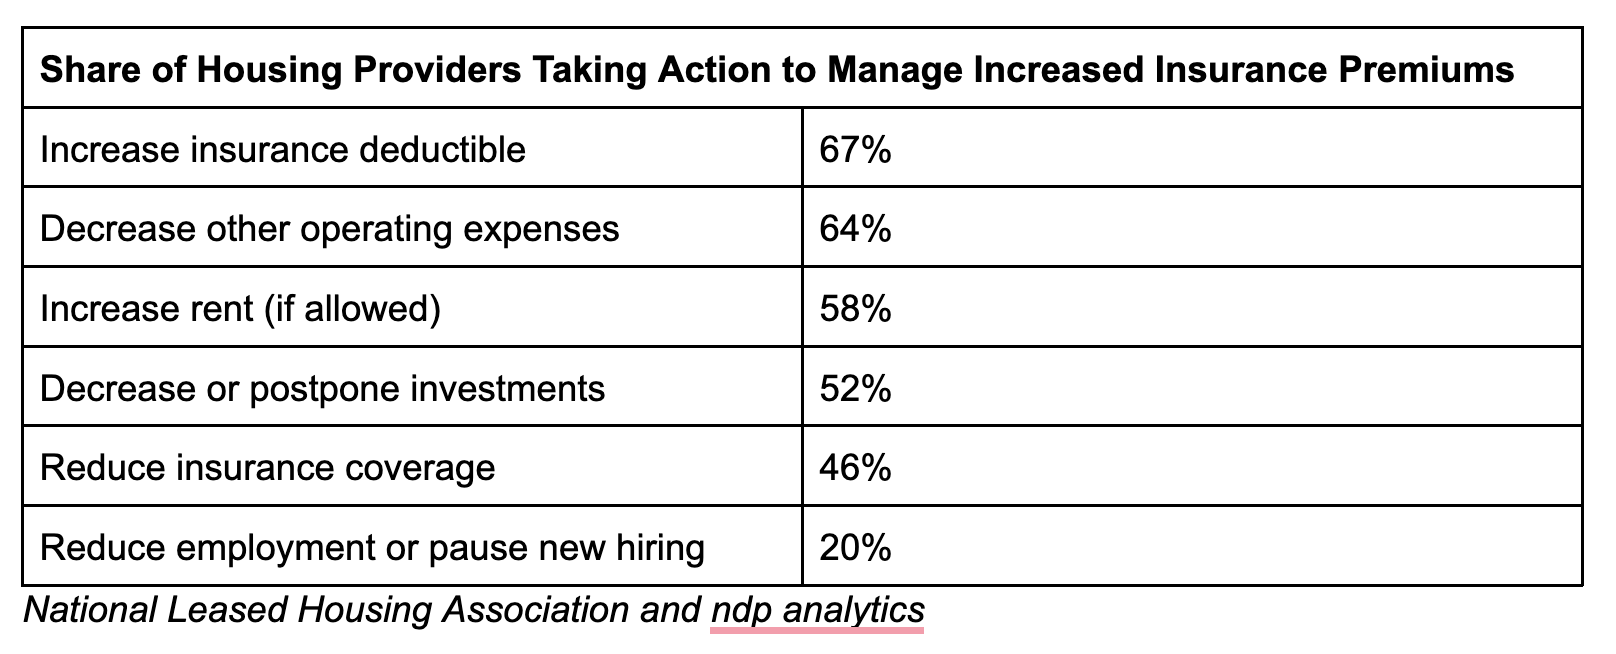
According to a 2023 survey from the National Leased Housing Association, 93% of affordable housing providers indicated they would need to adjust operations to manage increased insurance costs. More than half said they would decrease or delay investments in both existing housing stock and new projects.

Share of Housing Providers Taking Action to Manage Increased Insurance Premiums
Finding Effective Solutions

Developers warn that insurance costs are making affordable housing projects less viable, while insurers argue that increasing climate risks necessitate higher rates. Housing advocates stress the need for policy interventions to ensure that skyrocketing insurance costs do not exacerbate the nation's housing crisis. Consequently, addressing the home insurance crisis requires innovative industry solutions, targeted policy changes, and risk mitigation strategies that meet the needs of all stakeholders.

Some affordable housing providers suggest federal-backed statewide insurance pools, while others promote expanding state-run insurance programs. Others argue that doing so would ultimately drive up rates. Additional solutions include moving to a lower premium, higher deductible model, creating lower-cost policies for properties less vulnerable to extreme weather effects, subsidizing insurance costs, and creating a public reinsurance fund for insurers.

Measures developers could take include embracing resilient building techniques, such as fire-resistant materials and flood-resistant infrastructure, to reduce insurance risks and lower premiums. However, they call for guarantees from insurers that taking such measures would reduce rates; each potential solution naturally carries risk, costs and consequences.

A Complex but Urgent Matter

Policy reform and industry overhaul rarely happen quickly, but time is of the essence. The U.S. housing market is estimated to need up to six million more affordable units; losing more of these units to market-rate housing could intensify the crisis.

Addressing the impacts of elevated home insurance costs on affordable housing is not just about stabilizing the insurance market — it's essential for ensuring long-term housing equity, economic stability, and the ability to meet the nation's growing housing needs.


Divya Sangameshwar

Profile picture for user DivyaSangameshwar

Divya Sangameshwar

Divya Sangameshwar is an insurance expert and spokesperson at ValuePenguin by LendingTree and has been telling stories about insurance since 2014.

Her work has been featured on USA Today, Reuters, CNBC, MarketWatch, MSN, Yahoo, Consumer Reports, Consumer Affairs and several other media outlets around the country. 

Parametric Insurance Key to Climate Disaster Recovery

As climate disasters intensify, insurers must blend parametric and traditional coverage to deliver faster policyholder relief.

A Fireman in Uniform Standing Near the Blazing Fire

Historically, the insurance industry has focused on long-term strategies for climate risk mitigation and recovery planning. But that alone no longer works.

The situation is grim. In 2024, the U.S. experienced 27 weather and climate disasters that incurred over $1 billion in losses each, and economic losses reached nearly $218 billion – an 85% increase compared with 2023. Globally, economic losses totaled $368 billion. Extreme weather is also becoming more frequent. From 2000 to 2019, there were 6,681 climate-related disaster events, while the previous 20 years only recorded 3,656. With losses this devastating and disasters becoming more common, consumers and policyholders cannot wait weeks, or even months, for insurance payouts.

This is a challenge for homeowners and business owners alike. According to FEMA, 43% of small businesses affected by a disaster never reopen, and a further 29% go out of business within two years of the disaster. Consumers may also not be able to pay for the work that needs to be done to repair their properties if an insurance check is being held by a bank or mortgage servicer. Electrical blackouts could also lead to overdrawn accounts, and the stress of rebuilding and returning to normalcy could result in missed bills and ballooning credit card debt.

These challenges clearly illustrate the need to pivot. A comprehensive resilience and recovery plan must reflect the current risk environment and should include a healthy mix of both long- and short-term insurance solutions to effectively support consumers, fill in the insurance protection gap, and create a financial safety net that is broad and inclusive.

Before creating the solutions, we need to acknowledge the issues preventing the industry from resolving key policyholder pain points.

Despite the clear evidence demonstrating how climate perils are related, long-term insurance pricing and solutions don't reflect that correlation. While the wildfires in Los Angeles have been extinguished, Angelenos aren't in the clear yet. Following the fires, they were inundated with rain, causing mudslides and debris flows that shut down one of their major highways and swept cars into the ocean. This was not a coincidence. Extreme heat can serve as a catalyst for wildfire by creating drier conditions, making vegetation more flammable and accelerating the spread of fire. But it can also alter rainfall patterns, often leading to more intense rainstorms following a wildfire.

Extreme heat's ability to act as a driver for both wildfire severity and increased precipitation is a prime example of the ways climate risks are innately connected, illustrating the need for insurance to factor the relationship into modeling and insurance products. While accurately forecasting these related climate risks is difficult, it is possible. Farmers have long paid attention to these longer-term cycles. Insurance should look to do so, as well. The industry must create a solution that supports policyholders and provides proper protection from natural disasters and climate perils.

Long-term insurance policies have been the industry standard for centuries, but too often the claims and payout processes can feel never-ending. It can take four to eight weeks before a standard flood claim is finalized and paid. Without any complications (although there typically are many), home insurance claims could take anywhere from a few weeks to several months to settle. Both situations force policyholders to rely on their savings to rebuild after the devastation.

Just one inch of water in a home can cost up to $25,000 in damages. Meanwhile, the average American family only has $62,410 in liquid savings, and insurance rarely accounts for the other economic damages that can be rendered post-disaster. Policyholders don't just have to replace their physical assets, they also need to allocate funding for short-term accommodations, emergency childcare, and potential medical expenses not covered by health insurance. Rebuilding may also require policyholders to miss work, increasing the financial burden. Others may not even have a workplace to return to if it was destroyed.

Insurance coverage also isn't available in the markets that need it the most. States like California, Louisiana, and Florida have borne the brunt of recent natural catastrophes, while simultaneously experiencing the departure of multiple carriers from their markets. This combination of factors has exposed millions to economic losses and potential financial devastation.

This is where parametric insurance can help.

Incorporating parametric products as a complement to traditional insurance is an effective way to rapidly infuse capital into communities after disasters. This helps to ensure that policyholders' immediate needs are met while providing space for long-term capital to deploy. The two products working in tandem provide a comprehensive resilience solution.

Parametric insurance products have already been successfully deployed in the Pacific, Colombia, and India, among other markets, and in other branches of the insurance industry, such as travel insurance and event delay insurance. However, the U.S. hasn't seen a deep proliferation of the model in catastrophe or property insurance yet. To date, there have only been a handful of pilot programs, as seen in Mississippi and California.

This is partially because insurance is regulated at the state level. If carriers wanted to add parametric coverage to existing insurance products, it would require teams of people to do so and a drawn-out regulatory process. The natural solution, then, is for carriers to turn to managing general agents (MGAs) to help address the market's parametric needs.

MGAs have flexibility that enables carriers to reach new markets and customer bases without having to add additional personnel or execute complicated paperwork. The technology-focused aspect of many MGAs can also help carriers streamline the claims and product creation process, thus constructing insurance products that meet policyholder needs.

A multi-faceted resilience strategy is the key to short- and long-term recovery.

The insurance industry has the technology and models to provide capital faster than traditional catastrophe and property insurance policies. What it hasn't been able to figure out is the human element of decreasing the timeline for claims processing after an event, even for some of the larger policyholders. But parametric insurance helps fix that problem.

The parametric model's ability to pay out a claim as soon as a specific criterion is met helps eliminate some of the embedded bureaucracy that causes frustration for the policyholder and for the carriers themselves. This is especially important during a time when public perception of the insurance industry is at an all-time low.

To provide true resilience and recovery in the face of mounting climate risks and worsening perils, the insurance industry needs to provide both short- and long-term insurance solutions that work in tandem to support consumers after a disaster. Neither strategy will work in isolation.


Nakita Devlin

Profile picture for user NakitaDevlin

Nakita Devlin

Nakita Devlin is CEO and founder of Ric, an insurance tech company dedicated to providing rapid-response parametric insurance solutions to communities and employers affected by climate-related disasters. 

She has an extensive background in risk management and insurance brokerage.

Insurers Must Innovate the Captive Agent Model

Insurance carriers must innovate their captive agent models or risk losing talent to independent distribution channels.

Young woman in a white button down shirt with a black headset on in front of a computer

Historically, insurance carriers have often considered captive or career agents as the backbone of their sales and distribution model. In recent years, however, the market share of insurance sold through independent channels has grown, eroding the strength of the career agency model.

Consider that in 2024, 53% of all life premium, 41% of annuities, and 39% of personal lines P&C premium all were placed through independent channels – continuing a trend seen over the last several years.

But the issue for carriers is not just that increased premium is coming through independent channels – it's that captive agents are leaving carriers for independent distributors. That matters – captive agents have incentives to push both the carrier's brand and products to customers. A reduction or reliance on captive agents would fundamentally change the entire value chain for a carrier (e.g., product pricing, sales and marketing, customer service models).

The Case for Change

Captive agency models have always battled for talent with independent distributors. A perfect storm has formed to force distribution leaders to rethink their overall strategy:

  • Reliance on Third-Party Distribution – The increasing shift in premium sales toward third-party distribution is providing greater leverage to independent channel distributors. This creates stronger negotiation power for advisor commissions and makes carriers much more dependent on those distributors for sales. For instance, while 53% of all life premium came from third-party sales, nearly 90% of indexed universal life (IUL) premium came from independent channels. This reliance puts carriers at potential distribution risk.
  • Advisor Shortage – A recent report estimates that in 10 years, there will be a shortage of approximately 100,000 financial advisors. This means that not only is there a competition for assets and customers, but there will also be increased competition for advisors. For carriers leveraging a captive agency model, the advisor deficit further complicates recruitment and retention challenges.
  • Owning the Customer – An aging advisor field force and concerns surrounding succession planning have placed a premium on carriers developing relationships directly with the end client. As advisors retire, carriers with stronger client relationships will be better positioned to retain those clients, particularly as clients ask advisors to go beyond simple product sales and focus on more holistic solutions. Captive agent models are uniquely positioned to win this, as their agents are often aligned with the overall corporate brand and marketing that help customers associate their advisors with particular products and services.

The combination of these factors paints a clear picture for distribution leaders – there is significant competition for customers and talent. This forces distribution leaders to develop a robust strategy to either innovate their captive agent model or embrace alternative sales channels and the changes that go along with that.

For some carriers, the decision has been or will be to embrace alternative distribution channels. This is not necessarily a bad strategy, particularly for P&C personal lines carriers, leveraging a combination of direct-to-consumer (DTC) efforts with third-party distribution models to de-emphasize captive agents (e.g., Allstate).

Redefine the Captive Agent Model

But not every carrier has the luxury (or desire) to de-emphasize its career agency channel. Career agent models have innovated before to remain competitive against independent models, but part of the challenge will be to rethink the captive agent value proposition. Specifically, carriers need to embrace four opportunities to win the battle for advisor talent:

1. Win the IXP Battle – Inexperienced producers (IXPs) will likely be the future of the advisor field force – retiring experienced advisors and overall deficit in advisor talent force carriers to rethink the recruitment and development pipeline. Winning recruits on college campuses and those changing careers will be critical to captive agent growth. This means comes down to selection, training, and retention. Leveraging AI will be a key tool – AI models may be more effective methods of pushing enterprise recruitment efforts in identifying candidates who are likely to be successful. To do this, carriers need to think about their existing recruitment strategies, advisor outcome data, and how to leverage them to both market and select the right talent.

2. Redefine the Ease of Doing Business – The ease of doing business is consistently ranked as one of the most important factors when an advisor is choosing which carriers to work with. Captive agent models will need to embrace agent experience as a core strategic goal in their long-term efforts to recruit and retain talent, consistently measuring and tracking efforts to improve agent Net Promoter Score (NPS). But carriers should also redefine the ease of doing business as something beyond whether they accept paper applications. Specifically, carriers should evaluate the ease of developing and growing a business. For example, leveraging carrier data to develop improved leads is a good first step, but matching client persona with agent selling personas in the sales process would increase the likelihood of agent success.

3. Leverage Data to Compete With Technology – Carriers have one significant advantage over independent distributors – they tend to have much more complete views of the customer. This includes not only knowing which policies they have in-force, but the ability to leverage multiple interaction points across the customer journey to create more holistic views of the customer. For example, an independent agent knows that a policy was purchased, but the carrier is in the best position to synchronize a customer's interactions with the agent, contact center, and claims process to understand opportunities to improve cross-sell and next-to-purchase opportunities. Carriers that harness this data can convert it into a strong technological advantage – enhanced data science capabilities, greater insights for potential automation, and stronger AI models to differentiate against the market.

4. Understand Your Advisor – Carriers have devoted countless resources to better understanding their customers, and for good reason. But to win the competition for talent, carriers also have to view their captive agents as another customer they must understand. This means first knowing the value proposition for an individual to become an agent with you. Second, it means knowing who is – and is not – the right fit for your field force. Third, carriers must rethink the role of an agent in a shifting distribution operating model. The value for carriers is in owning and servicing the client. This means that not every agent can or should be performing the same function. For example, leading carriers will evaluate incoming agents and determine whether they should focus on selling or servicing, or if they should be customer-facing or working in a contact center model. Redefining who is an agent and what an agent does in your firm is critical to achieving success.

Carriers must embrace these opportunities to transform their career agency models now as a part of how they assess their broader distribution strategy. A failure to do so now will make carriers reactive to the market. A carrier could find itself where it is overly reliant on a distribution strategy that no longer works – over-reliant on the career agency model with no investment to win the talent necessary to continue to compete in the future.


Chris Taylor

Profile picture for user ChrisTaylor

Chris Taylor

Chris Taylor is a director within Alvarez & Marsal’s insurance practice.

He focuses on M&A, performance improvement, and restructuring/turnaround. He brings over a decade of experience in the insurance industry, both as a consultant and in-house with carriers.

How AI Can Detect Fraud and Speed Claims

With the ability to process billions of data points in real time, AI-powered fraud detection and claims systems can do what human analysts cannot.

Person Counting Cash Money

Fraudsters are getting smarter — and faster. With generative AI and deepfake technology at their fingertips, they're flooding insurers with fake claims and exposing cracks in traditional fraud detection methods. Insurers are in a high-stakes race against AI-powered deception, and the cost of falling behind is steep: billions in losses and eroded customer trust.

Outdated systems can't keep up with AI-driven scams. It's no longer a question of if insurers should adopt AI-powered fraud detection but how fast they can do it. The good news is the same technology that fuels fraudulent claims can also be used to fight them.

Generative AI offers insurers a way to not only detect and combat fraud but also streamline case management, accelerating claims processing and improving efficiency.

The Game Changer in Claims Management

Insurance fraud isn't a new problem, but it's never been this sophisticated. Gone are the days when fraudulent claims were limited to exaggerated injuries and staged accidents. Today's fraudsters have access to AI-generated medical records, synthetic identities, and eerily convincing deepfake videos, allowing them to construct entirely fabricated incidents with alarming precision.

Traditional fraud detection methods — document reviews, phone interviews, and outdated rule-based systems — are no match for the scale and speed at which AI-powered fraud is evolving. But with the ability to process billions of data points in real time, AI-powered fraud detection systems can do what human analysts cannot: instantly cross-reference claims against vast datasets, identify inconsistencies, and flag suspicious activity before payouts occur. This technology enables insurers to detect deepfake-generated documents and videos, analyze behavioral patterns that suggest fraudulent intent, and shut down scams before they drain company resources.

Unlike legacy systems that react to fraud only after it has occurred, AI-driven fraud detection is predictive and preventative. By leveraging machine learning models trained on historical fraud cases, insurers can anticipate emerging fraud tactics, staying one step ahead of the criminals. This shift from reactive to proactive fraud prevention is a game-changer, saving insurers billions while safeguarding legitimate policyholders.

How AI Automates and Accelerates Claims Processing

Fraud detection is only half the battle. Insurers are also under pressure to process legitimate claims quickly and accurately. Customers expect seamless, hassle-free settlements, and insurers that fail to deliver risk damaging their reputation. Generative AI not only combats fraud but also revolutionizes claims processing, allowing insurers to operate with unprecedented speed and efficiency.

One of the most significant advantages of AI is automation in the records retrieval process. Traditionally, insurers relied on manual verification processes, which involved requesting medical records, police reports, and other supporting documents. AI-powered claims processing can help limit the need for time-consuming manual labor by instantly verifying, retrieving, and analyzing records from multiple sources.

Natural language processing (NLP) further enhances claims processing by extracting key insights from medical records, adjuster notes, and even policyholder communications. This allows insurers to assess the legitimacy of claims with remarkable accuracy, ensuring that genuine cases are settled swiftly while fraudulent ones are flagged for further investigation. Moreover, AI-generated summaries provide claims adjusters with clear, concise insights, minimizing the need for extensive document review. By scanning vast amounts of structured and unstructured data, including text, images, and videos, AI can quickly identify critical information, reducing claim review times from weeks to mere hours and improving overall efficiency.

Another emerging trend is leveraging agentic AI systems that autonomously analyze, plan, and execute tasks within structured workflows. Unlike traditional automation, which follows fixed, rule-based processes, agentic AI adapts dynamically, makes context-aware decisions, and operates with a level of self-governance. Powered by advanced machine learning, it enhances efficiency, flexibility, and decision-making in complex environments. These systems handle domain-specific tasks like data extraction, fraud detection, anomaly identification, and decision support. Serving as the intelligence layer of the workflow, they enhance efficiency and decision-making through advanced automation.

The result is faster settlements for legitimate claims, reduced administrative costs, and an enhanced customer experience. In an industry where trust is paramount, the ability to process claims quickly without sacrificing accuracy gives insurers a significant competitive advantage.

Overcoming Implementation Challenges

While AI is a powerful tool, it isn't perfect. Despite its transformative potential, implementing AI in fraud detection and claims management comes with challenges. One of the biggest challenges in AI-driven fraud detection is the risk of false positives — legitimate claims being incorrectly flagged as fraudulent. Over-reliance on AI without human oversight can lead to frustrated policyholders, increased dispute resolution costs, and potential reputational damage.

The solution is establishing a hybrid model that blends AI automation with human expertise. AI should act as an intelligent assistant, identifying patterns, flagging anomalies, and presenting data-driven insights. However, final decisions should still involve experienced and trustworthy claims adjusters who can apply contextual judgment and verify AI-generated findings.

A hybrid approach consists of three key elements:

  • AI-driven fraud detection: AI scans claims for anomalies, inconsistencies, and suspicious behavior, flagging high-risk cases for review.
  • Human validation: Trained fraud investigators assess flagged claims, ensuring that legitimate cases are not wrongly denied.
  • Continuous AI training: Machine learning models are regularly updated with new privacy-compliant data, allowing AI to adapt to evolving fraud tactics and reduce false positives over time.

This collaborative human-in-the-loop approach ensures insurers reap the benefits of AI's speed and scalability while maintaining fairness and accuracy in claim resolutions. It's about striking the right balance — using AI to enhance human decision-making rather than replace it entirely.

Data security is also a common concern with increased AI integration. AI-driven systems process vast amounts of sensitive information, from medical records to financial transactions. These systems are vulnerable to cyberattacks and data breaches without stringent security measures. Insurers must adopt robust encryption protocols, strict access controls, and de-identification techniques to protect customer data.

Another challenge is the risk of model drift and bias. AI models must be continuously monitored to ensure they remain accurate and fair. Bias in training data can lead to skewed decision-making, disproportionately flagging certain demographics for fraud investigation. To mitigate this risk, insurers should implement transparency measures, regularly audit AI algorithms, and use diverse datasets to train machine learning models.

Regulatory compliance is another critical consideration. As AI becomes more deeply integrated into claims processing, insurers must navigate a complex legal landscape. Compliance with industry regulations and ethical guidelines is essential to avoid potential lawsuits and maintain consumer trust. A structured AI governance framework — incorporating transparency, accountability, and ethical considerations — ensures AI adoption aligns with regulatory standards.

The Race to Automation: Why Insurers Must Act Now

Fraudsters aren't waiting. Every day, they refine their tactics, using AI to create more convincing fake claims. Insurers must move just as quickly — if not faster. The race to automation is not just about keeping up with fraud; it's about securing a future where AI-powered claims management is the norm, not the exception.

The insurance industry is at a crossroads. Companies that embrace generative AI will lead the way, while those that hesitate will struggle to keep up. The future of fraud detection and claims management isn't coming — it's already here. Insurers must decide whether they want to be proactive innovators or reactive bystanders.

Why Point Solutions Are No Longer Enough

Commercial insurance technology platforms are emerging as the solution to fragmented systems that waste agents' valuable client-facing time.

Flat Lay Photography of Hand Tools

Despite billions poured into insurtech over the past decade, commercial insurance agents and account managers still spend over 50% of their time toggling between fragmented systems instead of serving clients. 

The commercial insurance industry has reached an inflection point. Faced with rising customer expectations, evolving risks, and growing competitive pressures, agents and carriers are increasingly turning to technology for answers. However, the proliferation of single-purpose tools and point solutions has created a new set of challenges, hindering true transformation.

Quote comparison tools, policy review software, appetite search engines – while valuable in isolation, these point solutions have inadvertently reinforced existing data silos and workflow inefficiencies. The result is a disjointed ecosystem where agents toggle between multiple systems, manually reconcile data, and struggle to gain a holistic view of their clients and business. This fragmented ecosystem undermines productivity, causes errors, and frustrates clients seeking seamless interactions.

As the co-founder and CEO of an AI-powered platform for commercial insurance, I've seen how this fragmentation impedes growth. Agents spend countless hours on low-value tasks, carriers miss opportunities to streamline underwriting, and clients experience disjointed interactions. The future of insurance demands a different approach – one that brings together data, workflows, and intelligence into cohesive platforms designed for the industry's unique needs.

The Limitations of Point Solutions

To understand why point solutions ultimately fail commercial insurance, we must recognize the industry's inherent complexity. Insurance data spans structured and unstructured sources, from policy forms and loss runs to emails and PDFs. Workflows are deeply interdependent, with each process relying on data and decisions from multiple upstream and downstream systems.

In this environment, standalone tools create more problems than they solve. Integrations become a constant struggle, with IT teams devoting countless hours to building and maintaining brittle connections between disparate systems. Data definitions vary across solutions, leading to inconsistencies that undermine analytics and decision-making. And with each new tool, users face increased cognitive overload, navigating multiple interfaces to complete routine tasks.

Imagine an agent assessing a client's loss history, forced to toggle between emails, PDFs, and quote engines—wasting valuable hours and missing critical insights. Compounding these challenges are the industry's stringent regulatory requirements. From data privacy to audit trails, insurance demands comprehensive governance that point solutions simply can't provide on their own. This creates an illusion of digitization, masking underlying inefficiencies and compliance risks.

The Power of Platforms

The path forward lies in holistic insurance platforms that unify data, orchestrate workflows, and embed intelligence at every step. Unlike point solutions, platforms take a fundamentally different approach to value creation.

At their core, insurance platforms serve as a unified data layer, bringing together information from across the policy lifecycle into a single source of truth. By standardizing data definitions and providing comprehensive governance, platforms eliminate silos and enable seamless information sharing among brokers, carriers, and clients.

But data connectivity is just the beginning. True platforms also orchestrate workflows end-to-end, guiding users through complex processes while automating repetitive tasks behind the scenes. By embedding best practices and intelligent recommendations directly into workflows, platforms turn data into action, helping teams work smarter and faster.

Perhaps most importantly, insurance platforms leverage this unified data and workflow foundation to deploy advanced analytics and AI at scale. Rather than isolated pockets of intelligence, platforms infuse every decision with contextual insights – from identifying at-risk accounts to optimizing carrier selection. As more data flows through the platform, these insights become sharper, creating a powerful flywheel effect.

The AI Catalyst

The rise of AI simultaneously necessitates and amplifies platform adoption. Powerful generative AI tools have lowered barriers to building specialized capabilities, commoditizing point solutions. Consequently, competitive advantage shifts to platforms that integrate AI comprehensively across the insurance lifecycle.

For instance, AI-powered platforms instantly identify hidden risks by scanning emails, prior policies, and loss runs—tasks that fragmented solutions cannot accomplish efficiently. Insurers must embed AI seamlessly into their operations, leveraging unified data architectures and workflow integrations to unlock AI's full potential while mitigating associated risks.

The Path Forward

Insurance leaders must prioritize platforms over fragmented point solutions. Embracing this shift requires adopting a new mindset—valuing holistic transformation over incremental quick fixes. Brokers, carriers, and managing general agents (MGAs) who embrace a platform-first approach position themselves strategically for success in the evolving, AI-driven marketplace.

This transition requires deliberate actions:

  • Begin with a comprehensive audit of existing systems to identify redundancies.
  • Develop a strategic road map prioritizing early wins and long-term integration.
  • Partner with technology providers experienced in insurance complexities, proven in deploying holistic platforms.
  • Leverage this opportunity to significantly reduce outsourcing expenses—often by 80% or more—by automating processes traditionally handled externally.

Legacy systems must evolve, data models must be standardized, and workflows must be reimagined. Yet the rewards—significant efficiency gains, accelerated growth, and vastly improved customer experiences—will far outweigh the effort.

The insurers that will lead the next decade are those that build their businesses on robust, integrated platforms. By uniting data, workflows, and intelligence, these platforms will become the foundation for innovation and a definitive source of competitive advantage.


Vishal Sankhla

Profile picture for user VishalSankhla

Vishal Sankhla

Vishal Sankhla is the co-founder and CEO of Outmarket AI, an intelligence platform for the commercial insurance industry that enables agents and carriers to automate workflows, enhance decision-making, and drive growth in the age of AI.


The Key to Unlocking ROI From AI

Without observability built into AI initiatives, insurers risk flying blind in their automation transformation efforts.

Numbers on Monitor

Your AI and automation initiatives will fail.

Not because of bad code. Not because your data scientists aren't smart enough. But because you'll lack the one thing that determines whether any AI initiative succeeds: observability.

If you can't see what your automation is doing — how it's affecting business processes, where it's breaking down, and what value it's delivering — you're flying blind. And in high-stakes domains such as distribution, new business underwriting, claims, and retention, that's a recipe for expensive failure.

The insurance industry is doubling down on AI, machine learning, and process automation. But here's the truth most don't want to hear: Implementing AI is the easy part. Proving it works — and improving it over time — is where the real challenge lies.

Automation Without Visibility Is Just Faster Failure

At Neutrinos, we work with insurers that are pushing the boundaries of intelligent automation. And we're seeing, again and again, that after the initial excitement of go-live, leaders are left asking:

  • Is it actually working?
  • Are we saving time, or just doing things faster without better outcomes?
  • Where is human intervention still needed - and why?

These questions aren't technical — they're strategic. And they're impossible to answer without observability baked into the entire automation lifecycle.

This isn't about tracking CPU usage or memory spikes. Observability in the context of AI and process automation means real-time, contextual insight into your business metrics:

  • How is the policy issuance cycle trending post-automation?
  • Are underwriters accepting or overriding AI-generated decisions?
  • Which customer segments are seeing improved experiences—and which aren't?

Without this visibility, AI becomes a black box. And black boxes don't earn trust — or ROI.

The Observability Trinity: Leading, Lagging, and Real-Time Indicators

To extract value from AI initiatives, insurers need to shift from retrospective reporting to proactive insight. That means tracking three types of indicators:

  1. Leading Indicators – Metrics that forecast success or failure early, such as time-to-decision, document intake accuracy, or triage confidence scores.
  2. Real-Time Signals – Operational insights that allow for immediate course correction, like exception frequency, process fallbacks, or system latencies.
  3. Lagging Indicators – Traditional business outcomes like cost reduction, improved persistency rates, or faster policy issuance cycles.

The magic lies in correlating them. If you see triage decisions being overridden frequently (real-time), it could signal that your risk model needs retraining (leading), which if left unaddressed could result in increased underwriting time and reduced efficiency (lagging).

Observability makes this feedback loop visible — and provides automated, actionable insight.

When this visibility is fully embedded into the automation lifecycle — from initial ideation and design to deployment and continuous improvement — insurers can make intelligent, timely adjustments to improve performance by shifting observability left.

Use Case: New Business Underwriting in Life & Annuities

Life & annuities underwriting is ripe for transformation — and risk. The process involves vast amounts of unstructured data, human judgment, and regulatory complexity. That's why insurers are increasingly applying AI to:

  • Automate document extraction and data enrichment
  • Use natural language processing (NLP) to analyze medical records and lifestyle disclosures
  • Triage applications for fast-track vs. full manual review

Sounds great. But after deployment, reality sets in: Are the right cases being fast-tracked? Are policy decisions aligned with actual risk? Are underwriters trusting the AI or working around it?

This is where observability must step in. A well-designed observability framework will monitor metrics like:

  • Fast-track case approval vs. post-issue adjustment rates
  • Frequency of manual intervention by underwriters
  • Average time to underwrite per segment, before and after automation
  • Confidence vs. override correlation for AI-generated recommendations

These aren't just performance metrics — they're trust metrics. And they directly inform whether your AI is doing what it was intended to do.

From Insight to Action: Why Observability Isn't Passive

Observability isn't just about dashboards and data. It's about decisions.

Once you have visibility into how your automation is performing, you can begin to optimize. You might adjust your triage rules. Retrain your NLP models. Refine your underwriting workflows. Or even re-segment your customer cohorts.

The point is: AI isn't static. Your observability layer shouldn't be either.

In fact, the next evolution of observability is prescriptive: platforms that not only show you what's happening but recommend what to do next. This is where proactive optimization begins — not with human guesswork but data-backed decision support.

Why to Build Observability In, Not On

Most platforms treat observability as a bolt-on — something you figure out after launch. At Neutrinos, we believe it should be core to your automation architecture.

So our automation platform includes observability capabilities that track the entire lifecycle of a process:

  • From intake to triage to decision
  • From AI model inference to human review
  • From business rules to real-world outcomes

It's not just visibility for IT — it's insight for business leaders, compliance teams, underwriters, and customer experience (CX) strategists.

Whether it's surfacing drops in the policy journey, highlighting model drift, or comparing AI-generated recommendations to human decisions — effective observability helps insurers optimize not just automation, but outcomes.

Observability: The Real AI Differentiator

In a market where most insurers are deploying similar tools and technologies, the competitive edge won't come from your AI engine. It'll come from how well you can see, understand, and improve what it's doing.

Observability is what separates the pilot projects from the enterprise-grade transformations.

Your AI investments don't have to fail. But if you're not watching the right metrics in the right way, you'll never know if they're working — and you won't know how to fix them if they're not.

Visibility isn't optional. It's strategic. And it's the key to unlocking return on investment (ROI) from your AI initiatives.