Download

How AI Can Transform Submissions for Underwriting

Commercial insurers face a strategic challenge: identifying which submissions merit scarce underwriting attention, not just processing more faster.

Insurance

Commercial insurers spend years expanding distribution, strengthening broker relationships and sharpening their risk appetite, only to discover that success creates a new constraint:

Too many submissions for underwriters to evaluate effectively.

That is the submission paradox. The industry has traditionally treated this as an operational problem: automate intake, extract fields faster, reduce manual work.

I believe that framing is too narrow.

The strategic problem is not how to process more submissions. It is how to identify, early and consistently, which submissions deserve scarce underwriting attention and capital.

Importantly, the objective is not simply higher conversion, but a profitable conversion, by responding faster to risks that fit appetite, meeting pricing expectations and improving the portfolio.

AIG's journey provides an excellent case. Its Lexington business saw submissions increase from approximately 30,000 in 2018 to 300,000 in 2024. Those 300,000 submissions translated into roughly 6,700 binds—a 2% submission-to-bind ratio—and approximately $1 billion in new-business premium. Behind those numbers sits a familiar commercial-underwriting reality. A submission is rarely a clean dataset.

It may contain applications, loss runs, schedules of values, spreadsheets, financial statements, engineering reports, broker correspondence, scanned documents and subsequent corrections. Before an underwriter can exercise judgment, someone must first assemble the risk.

AIG described its traditional submission-to-review process as taking approximately three to four weeks, involving manual extraction, validation, research, augmentation, rating and approval—and acknowledged that underwriters could not review every submission.

That is more than an efficiency issue. It creates a growth constraint. Because when underwriting capacity is finite, every hour spent reconstructing a submission is an hour not spent evaluating risk, negotiating terms, structuring coverage or engaging brokers.

And speed matters because an attractive risk has little value if the carrier responds after the placement has moved.

The Real Objective Is: Improve underwriting capacity

The obvious response is automation. But automating document intake solves only the first layer of the problem.

The more strategic question is: Can AI increase the number of opportunities an underwriter can intelligently evaluate—while improving alignment with risk appetite, pricing and portfolio objectives?

That is the direction of AIG's Underwriter Assistance / AIG Assist architecture. Its disclosed capabilities span:

Ingestion → Augmentation → Prioritization

The broader workflow goes further:

Submission → Structured Risk → Context → Appetite → Priority → Underwriter Decision

That is a fundamentally different ambition from automation.

The harder problem is preserving underwriting meaning, wherein capabilities such as separating and retrieving tabular versus textual information, reconstructing complex tables, maintaining source and page traceability, retrieval with error controls and preserving original-page visual context through multimodal techniques play a major role.

The hard problem is no longer extracting a number from a document. It is preserving the underwriting meaning surrounding that number. A $100 million value means little without knowing whether it represents revenue, TIV, payroll, limits, exposure or something else—and where the evidence came from.

It is the transition from document automation to submission intelligence.

Ontology: Where submission becomes part of the portfolio

Extraction alone still leaves individual facts disconnected. An ontology turns extracted submission data into underwriting context by connecting entities such as the insured, locations, exposures, limits, loss history, broker and policy structure through semantic relationships. It creates a machine-readable representation of how the risk fits together.

A location is no longer simply an address. It becomes an exposure contributing to a peril zone, an aggregation and ultimately a portfolio decision. That semantic layer is one of the foundations for moving from submission intelligence toward decision intelligence.

What happens when the underwriter gets time back?

AIG reported that its assisted workflow reduced submission preparation/review from approximately three to four weeks to less than one day and enabled review of 100% of applicable submissions in the disclosed deployment.

By year-end 2025, Lexington received more than 370,000 submissions, and AIG reported a 35% improvement in submission-to-bind for Lexington middle-market property, reducing underwriter time-to-quote by 55%.

The above journey provides a directional view on how P&C insurers can reimagine submission at enterprise scale to drive better risk-adjusted growth.

Three horizons to deliver the capabilities for P&C insurers

Horizon 1: Submission Intelligence

As learned from AIG's journey, RAG, source traceability, ontology, and human-in-the-loop controls help transform fragmented documents into an underwriting-ready representation of risk.

Ingest → extract → enrich → retrieve → prioritize → summarize → underwriter review

Horizon 2: Richer context

Submission packages contain engineering reports, which contain images such as a property's floor plan, protection layout showcasing sprinklers, smoke detectors, etc., and rooftop images. The ability to synthesize and corroborate the relevant risk details across text, images, layouts, and tables is highly relevant to creating a cohesive context for complex submissions.

This is where multimodal RAG techniques using vision-language models (VLMs) such as Gemini 3 Pro, Anthropic Claude 3.5, Alibaba Qwen3-VL, etc., play a critical role in chunking them, unifying the embeddings into vector databases with relevant identifiers to establish traceability, and optimally retrieving (multi-vector retrievers) relevant data for the context search.

Horizon 3: Underwriting Decision Intelligence

The richer context can then connect the submission to risk appetite, underwriting rules, portfolio concentrations and prior experience (via knowledge graph), enabling AI to reason over relationships rather than documents alone.

This is where the opportunity becomes transformational. When we connect submission intelligence with: underwriting appetite, pricing targets, portfolio concentrations, catastrophe accumulations, historical outcomes, broker relationships and underwriting authority.

The system no longer asks: "What information is in this submission?", rather augments the underwriter with intelligence:

"Given our appetite, portfolio and economics, should an underwriter spend time on this opportunity now—and why?"

And this is precisely why governance has become strategic

The Human+AI operating model should preserve clear decision rights.

  • Hard rules can enforce appetite and authority boundaries.
  • Predictive models can quantify risk, pricing and behavioral signals.
  • Agents can interpret unstructured evidence, identify contradictions and synthesize context, but

Underwriters should retain judgment over risk selection, terms, exceptions and material decisions

The objective is not to replace underwriting judgment. It is to deploy that judgment where it creates the most value.

Governance becomes the architecture of trust

Once AI recommends which opportunities receive underwriting attention, governance becomes part of underwriting discipline. Every recommendation should be capable of carrying its evidence, confidence, data lineage, model or prompt version and decision path.

Every override should be attributable. Every action should operate within explicit authority. These controls determine whether an underwriter can trust the system enough to act on it. It is consistent with the principles reflected in NIST Generative AI Profile and the NAIC Model Bulletin on insurers' use of AI.

Without an evidence chain, AI may scale activity, but will not necessarily scale institutional confidence. And this cannot be owned as a technology program alone.

Underwriting defines appetite and decision rights. 

The CDO industrializes data, context, and controls. 

Business leadership owns conversion, portfolio quality and adoption.

The strategic question for P&C leaders

The winning submission platform will not be the one that processes the most submissions. It will be the one that helps the insurer recognize attractive risks earlier, respond while the opportunity is still actionable, deploy underwriting attention, and convert more of the business it wants to write at the right economics.

The progression is simple:

  • Automation reduces work.
  • Submission intelligence expands usable underwriting capacity.
  • Decision intelligence determines where that capacity and ultimately capital should go.

The more consequential question for P&C leadership teams:

Are we simply applying AI to read submissions faster—or are we prepared to encode our appetite, expose portfolio context, and govern how machines influence underwriting attention and capital?

That distinction may determine who converts submission intelligence into profitable growth.

Prathap Gokul

Profile picture for user PrathapGokul

Prathap Gokul

Prathap Gokul is head of insurance data and analytics with the data and analytics group in TCS’s banking, financial services and insurance (BFSI) business unit.

He has over 25 years of industry experience in commercial and personal insurance, life and retirement, and corporate functions.

4 Governance Questions Before Deploying Claims AI

AI in claims is no longer about what the technology can do but what insurers should let it do autonomously.

Insurance

Every insurance executive has heard the pitch by now: artificial intelligence can summarize claim files in seconds, flag potentially fraudulent claims before an adjuster even opens the folder, and answer coverage questions that used to take a phone call and a hold queue. The technology is no longer the hard part. The hard part is deciding how much control to hand over, and to what.

That's a different question than the one most carriers have been asking. For the last few years, the conversation around AI in claims has mostly been about capability: what can the models do? The more useful question now is about governance: what should we let them do on their own, and how do we prove, after the fact, that they did it responsibly?

Having spent over a decade building the integration layer that connects carrier systems, policy platforms, and claims workflows, I've watched this shift happen from the inside. The claims organizations that get real value from AI are not the ones with the most advanced models. They're the ones that have thought carefully about four questions before turning anything loose on a live claims file.

1. Where should AI recommend, and where should it act?

Not every task in a claims file carries the same risk. Summarizing a thick claim file so an adjuster can get oriented in two minutes instead of twenty is low-risk: if the summary misses something, the adjuster still reviews the underlying documents. Looking up policy terms or prior claim history is similarly low-risk, since the AI is retrieving facts, not making judgment calls.

Coverage determinations and payment decisions are a different matter. These are the moments where a mistake costs money, invites a regulatory complaint, or damages a customer relationship that took years to build. The organizations doing this well draw a clear line: AI can prepare, summarize, and flag, but a person signs off before a check goes out or a claim gets denied. That's not a permanent limitation on the technology. It's a sequencing decision, and it's the right one for now, because trust in these systems has to be earned claim by claim, not assumed on day one.

The mistake I see most often is treating this as an all-or-nothing choice. Executives either wall AI off from anything that matters, which wastes most of its value, or they let it touch everything at once, which is how a small error becomes a large headline. The better approach is to map your claims workflow task by task and assign each one a tier: fully automated, AI-assisted with human sign-off, or human-only. Revisit the map every quarter as the technology and your confidence in it both improve.

2. Can you explain what the AI did, after the fact?

Insurance is one of the most heavily audited industries in the country, and that's not going to change because a claim was processed with help from a language model. If a regulator, an ombudsman, or a policyholder's attorney asks why a claim was handled a certain way, "the AI decided" is not an answer. You need to be able to show what information the system had access to, what it did with that information, and who reviewed or approved the outcome.

This means explainability has to be designed in from the start, not bolted on after a complaint arrives. Every time an AI system touches a claim, whether it's pulling a policy document, drafting a summary, or flagging a fraud indicator, that action should be logged in a way a non-technical auditor can follow: what was accessed, when, by which process, and what a human did with the result. Carriers that build this logging into the architecture from day one find audits and regulatory exams go faster, not slower, because they can produce a clean record instead of reconstructing one after the fact.

3. Are you building on what you already have, or starting over?

Claims platforms are old. Many carriers run core systems that predate the Internet, patched and extended over decades because replacing them outright is expensive and risky. The AI vendors selling a "rip and replace" story are selling something few carriers can actually afford, in time or in risk tolerance.

The more practical path is to treat AI as a new layer that connects to what already exists, rather than a reason to replace it. Your policy administration system, your document repository, your fraud rules engine: these don't need to be rebuilt. They need a well-defined way for an AI system to ask them questions and get reliable answers back. Done well, this also protects you from vendor lock-in. If the connection between your systems and your AI layer is built on an open, well-documented standard rather than a single vendor's proprietary format, you can swap out the AI model or the vendor behind it without re-architecting your claims systems all over again. Given how quickly the underlying AI models are improving, that flexibility is worth planning for now rather than discovering you need it in 18 months.

4. Do you have a phased path, or a leap?

The carriers I've seen succeed with this technology didn't start by automating claims decisions. They started with the lowest-risk, highest-volume task they had: usually document summarization or policy lookup, something an AI can do thousands of times a day with a human able to spot-check the results. That builds two things at once: a track record that gives the organization confidence, and a set of real examples of where the AI performs well and where it doesn't.

From there, the path runs through supervised action: AI drafts a fraud flag or a coverage recommendation, and a person confirms or overrides it before anything happens. Only after a system has built a real track record in that supervised role does it make sense to consider narrower forms of autonomous action, and even then, on the lowest-stakes decisions first. This is slower than the vendor demos make it look. It's also the difference between an AI program that survives its first serious incident and one that doesn't.

The bottom line

None of this is really a technology problem. The models are capable enough today to help with meaningful parts of claims work. The real work for executives is organizational: deciding what level of autonomy each task deserves, building in the ability to explain every decision after the fact, connecting AI to existing systems instead of replacing them, and moving in phases that build trust before they build speed.

The carriers who work through these four questions deliberately, rather than reactively, will be the ones who get real value from this generation of AI, without becoming the case study everyone else studies to learn what not to do.

Why a Great Strategy Isn't Enough

Insurers often approve strategies that stall by Q1 because they fail to operationalize plans before implementation begins.

Insurance

It's planning season. Across the insurance industry, leadership teams are discussing next year's strategy, budgets are being drafted and reviewed, boards are being briefed on strategic direction, and managers are scheduling meetings with their teams to set goals. Most of the big decisions that determine how next year evolves have either been made or will likely be made over the next few months.

We've all seen what happens next. The board approves the strategy, but by first quarter next year, little has changed. Usually, the strategy isn't the problem. More than likely, the heavy lifting of operationalizing the strategy wasn't prioritized.

I've spent more than 20 years in the insurance industry working in the space between a senior executive decision and the work that follows. And if I've learned anything, it's that the time to operationalize strategy is before you approve the plan, not after. That's how you get a clearer understanding of the financial and resource commitment you're about to make.

What operationalizing means

Operationalizing strategy means translating intent into the everyday activities of a business or function: who is accountable, what the work is, how long it takes to complete, where the money goes, what each person works on, and how risk is managed along the way.

Once this heavy lifting is done, you should be able to clearly see your strategy integrated throughout the leadership calendar, the budget, scorecards, the control framework and employee goals. Without it, your strategy is probably one step away from wishful thinking.

Five important moves 
  1. Decide who owns what. Identify which leader approves, funds and stops each priority, document that in performance objectives and share it with the executive team. Facilitate both individual and team discussions to troubleshoot turf war challenges, face up to contentious team members, and mitigate potential passive-aggressive inertia. From my experience, leaders who sidestep these thorny discussions are more likely to experience strategic fizzle and stall!
  2. Fund by priority. You have only so much money to fund next year's activities. Take a closer look at the budget. Does it reflect your strategic intentions? Is every funded line mapped to a strategic priority? Are you willing to prioritize your strategy by defunding the work that doesn't connect to it? Can you approach some of your strategic priorities in more of a testing or phased approach so you can spread funding over multiple calendar years? While there are a lot of decisions to make in this step, they are fundamental to reducing the gaps and unexpected expenses that can pop up in next year's budget.
  3. Don't forget to manage risk. Establish and embed internal controls to manage the risks that can damage your strategies — such as adverse market conditions or cyberattacks — during the design of your plan, not mid-year next year. When guardrails are determined up front, such as concentration limits for investing in a particular asset class, they can reduce the company's vulnerability to market conditions. And, with cyberthreats at an all-time high, insurers should plan to strengthen their operational response to cyberattacks and improve the resilience of third-party ecosystems to protect the company's ongoing ability to deliver value. Meanwhile, traditional legacy insurers initiating a major transformation remit might identify the risk associated with that effort as a top risk to mitigate and focus on in the year ahead. Reinsurers and MGAs with underdeveloped operational risk practices may plan to mature processes with the help of AI in the year ahead and have a related budget need. My experience as chief of staff to the chief risk officer at AIG and Corebridge Financial taught me that strategy and risk management are inextricably intertwined and, as such, benefit from an integrated approach to planning and operationalizing strategy.
  4. Cascade to every person's goals. Once the performance objectives of your leadership team are set, they can be cascaded to their respective businesses and functions. This step is where the heavy lifting of operationalizing strategy lives. As managers meet with their employees to discuss next year's goals and objectives, they should consider at least three questions. Which activities advance a company priority? Which keep the lights on? Which can stop? When people understand how their work connects to the overall company strategy, they are empowered to make better tradeoffs every day.
  5. Keep strategy on course. Once the plan year begins, how will you know if the company is achieving its strategic priorities? If there are impasses or bottlenecks? What metrics and information do you and your leadership team need — and how often do you need them — to confirm that your strategy is on course? What information should you share with the workforce, board, regulators, investors and rating agencies? Who will be responsible for providing that information? By answering these critical questions now, during the design phase of next year's plan, you can avoid future reporting fire drills, inconsistent messaging mishaps and info dumping that just drones on and on.
Explore how AI can help

Market conditions, geopolitical dynamics, regulatory requirements, and customer expectations evolve and shift. With AI, companies can trade up from a static annual planning cycle to more of an adaptive planning approach. Identify your company's AI super users and engage them to explore how your company can use AI to keep your strategy on course. Look into getting continuing scans of the external environment, automated simulations of key forecast scenarios, real-time leading indicators that can signal a drift from strategy, and insights on factors affecting your talent and capital plan.

Five questions to consider before you approve next year's plan
  1. Does each priority have a decision owner with targeted performance objectives?
  2. What share of next year's budget maps directly to those priorities?
  3. How are you managing the risks that can negatively affect your strategies?
  4. Can each employee identify how their goals support a company priority?
  5. What information will tell you by the end of Q1 that a priority is drifting?

The window for this part of your planning work is closing. By January, budgets and goals should be established. Insurers can boost the odds of delivering on their strategies by operationalizing them. Use the next couple of months to do the very important heavy lifting to successfully set your plan in motion.


Donna Pobiner

Profile picture for user DonnaLPobiner

Donna Pobiner

Donna Pobiner is an independent advisor and the founder of Offscript, LLC. 

She helps leaders think beyond the status quo and implement what’s next. She previously served as managing director and chief of staff, enterprise risk management, at AIG and Corebridge Financial, and as vice president, transformation, at MetLife.

The Dangers to Insurers From Reward Hacking

AI agents optimizing for bind rates may exploit underwriting systems the same way OpenAI's test agents hacked shared infrastructure.

Insurance

This July, OpenAI ran roughly 1,200 AI agents through an internal cybersecurity benchmark called ExploitGym: capture-the-flag exercises in isolated sandboxes. The agents had no direct Internet access and no way to communicate with one another.

They found a way anyway.

Each sandbox needed to install software packages without reaching the public Internet, so traffic ran through an internal package-registry cache, Artifactory. That's not a design flaw; it's good engineering practice. But one agent, stuck on a task, discovered it could write files into that shared cache. It left a note for other agents. Soon, other agents were leaving notes too—turning the repository into an improvised message board where they shared discoveries and coordinated activity.

That coordination escalated. Agents used Artifactory's connectivity to pursue external infrastructure they believed could help solve their evaluation tasks, ultimately culminating in the compromise of Hugging Face, the leading repository for AI models and training data, since acquired by NVIDIA.

There was no malice, no villain, no intent to cause harm—or, indeed, actual harm. They didn't hurt anything; they were just looking for answers to the test. Such behavior is known as "reward hacking:" models pursuing the stated objective—capture the flag—through routes nobody intended or authorized. OpenAI's postmortem uses the term. The episode is a costly reminder that "the model followed its incentives" is not the same as "the model did what we wanted."

The Insurance Industry's Exposure

So why should a P&C executive care about a cybersecurity benchmark?

Because the distribution channel is quietly re-platforming around agents.

MGAs and wholesale brokers—many freshly capitalized by private equity and under pressure to cut costs and grow bind ratios—are deploying agentic tools to assemble, tune, and route submissions. No one is necessarily building these tools to game a carrier's underwriting appetite. But an agent optimized to "get this account bound on the best possible terms" may behave much like an ExploitGym agent optimized to "get the flag."

It will find the seam.

It may learn which loss-run format gets triaged most favorably, which broker-portal fields carry outsized weight in a pricing engine, or which phrasing sends a submission into straight-through processing rather than to a human underwriter. That's not fraud; it's reward hacking in a suit.

The Paper Clip Problem

This is the paper clip problem.

Esteemed AI-philosopher Nick Bostrom's thought experiment is simple: tell a sufficiently capable AI to maximize paper clip production, neglect to specify any constraints, and it may eventually convert factories, cities, and the atoms in your body into paper clips. Not because it's evil, but because it's relentlessly pursuing the objective it was given.

Give an unconstrained optimizer one objective and sufficient computing, and it will pursue that objective past every boundary you assumed was implicit but never explicitly defined.

If the only instruction given to a submission-drafting agent is "maximize bind rate," don't be surprised when it finds your equivalent of Artifactory—or Hugging Face.

Building the Defense

So while your innovation team is rightly excited about agentic underwriting, agentic claims triage, agentic everything—offense—someone in your building needs to own the defense, asking questions like:

  • Can we identify when a submission was assembled or materially shaped by an agent?
  • Can we audit the tools, data sources, prompts, and transformations behind it?
  • Are we maintaining an active dialogue with distribution partners about the tools and methods they use?
  • Do we have the equivalent of Artifactory logs across our intake, triage, pricing, and underwriting pipeline?
  • Have we designed controls around outcomes—not just around stated intent?

The carrier executives who win this cycle will be the ones who instrumented their premium engine before their distribution partners' agents got creative—not after.


Riv Arthur

Profile picture for user RivArthur

Riv Arthur

Riv Arthur is a business leader and technologist working in insurance, healthcare, and private equity.

What If AI Underwriting Gets It Wrong?

AI-driven underwriting may bind policies faster, but post-bind corrections can erode the collateral backing premium finance loans.

Insurance

Conversations about human oversight in insurance tend to focus on whether AI-assisted underwriting is fair, explainable, and accurate. While all three hold valid concerns, they leave out an important consideration: What happens when an underwriting decision changes after the policy has already been bound and financing capital has been committed?

An underwriting decision may look sound when a policy first binds but may prove unstable as further information emerges. A post-bind correction can affect the value or timing of the collateral backing a premium finance loan.

That downstream exposure deserves attention as insurers broaden their use of AI. A March 2026 analysis projects that AI spending as a share of revenue among property and casualty insurers will triple in 2026, even though only 38% are generating value at scale from AI in core workflows.

AI allows for rapid processing of submissions and identification of trends and ensures consistency of decisions regarding routine applications. Ultimately, the question remains as to whether these efficiencies mean carriers may bind coverage before material uncertainty has been adequately considered.

A Fast Decision May Not Be a Durable One

Automated underwriting depends on the data available and the accuracy of interpretation. A polished risk score can mask an incomplete submission, rely on stale third-party data, or misclassify business operations.

Consider a hypothetical commercial property described as a warehouse. An automated system may treat it as low hazard storage. A later inspection could uncover light manufacturing, combustible materials, or another exposure that changes the assessment entirely. Depending upon the facts and applicable requirements, the correction could lead to revised terms, an additional premium, or cancellation.

Thin loss histories present another challenge. A model must distinguish between a business with no reported losses and a newer entity without sufficient historical data. A lack of documented losses doesn't necessarily equate to lower risks. A qualified underwriter can examine why the record is thin, while an automated process may need referral criteria or other controls to flag that uncertainty.

Regulatory guidance identifies data quality, integrity, suitability, outliers, and model drift as issues requiring controls, testing, and continuing oversight. If discovered after binding, these issues may cause the underwriting decision to be reconsidered.

An Underwriting Correction Can Reach the Lender

Typically, a premium finance company advances funds for payment of an insurance premium and collects installments from the insured. Rights of the premium finance company are usually tied to the unearned portion of the policy premium per the terms of the financing agreement, applicable policy terms, and governing state laws.

Canceling coverage does not guarantee that the lender's advance will be repaid in full. Instead, the available return premium generally is applied against the outstanding finance obligation.

As an example, Florida law requires an insurer to return the unpaid balance due under the finance contract to the premium finance company, up to the gross amount available upon cancellation. Similarly, New York law provides that when a financed insurance contract is canceled, the gross unearned premium due shall be returned to the bank, lending institution or premium finance company for the benefit of the insured.

The exposure is the possibility of a gap between what the lender expected to recover from the collateral and the amount actually recovered. The factors that may affect the amount recovered include minimum-earned provisions, premium audits, endorsements, return premium calculations, and unearned commissions. Furthermore, delays or documentation issues can affect the timing of when return premium funds are received.

A non-renewal is different, as it generally takes effect when the policy expires. Therefore, no unearned premium remains at expiration. Non-renewals may cause disruption in future coverage or financing but should not be viewed similarly to mid-term cancellations.

Oversight Has to Happen Before Coverage Is Bound

Merely stating that qualified human underwriters should remain "involved" is insufficient today. The issue is determining at what point in the process the underwriter participates in reviewing and approving or rejecting the underwriting decision. Manual approval of each routine submission could reduce some of the benefits associated with automated processes.

Conversely, waiting until after the binding of coverage means that a problem identified through manual review may require remedial actions. Ideally, qualified human underwriters evaluate decisions before coverage is bound and financing funds are advanced when defined indicators occur. Indicators may include conflicting property characteristics, unclear business descriptions, missing loss records, unusually high premiums quoted, newly formed entities, properties exposed to catastrophes or significant variations in data collected from multiple sources.

New York regulators have emphasized that external consumer data relied upon during underwriting can vary widely in terms of accuracy and reliability. Additionally, New York regulators have stated that carriers remain responsible for outcomes of using third-party systems and data in underwriting and pricing. Using risk-based referrals enables technology to process routine submissions while allowing qualified human underwriters to evaluate submissions that contain uncertainty.

Measure the Exposure Before Pricing It

A blanket "AI risk premium" on financed policies would be difficult to justify without evidence that AI-assisted underwriting is causing greater collateral losses. Automated underwriting platforms, data providers, and human controls vary too widely for AI participation alone to be a reliable pricing factor.

Rather than adjusting financing terms simply because AI was used in underwriting, premium finance companies can measure decision durability. Useful indicators include:

1. Underwriting-related policy cancellations and material adjustments occurring within 30, 60, or 90 days of binding. 

2. Variance between expected and actual return premium.

3. Time between cancellation and receipt of funds. 

4. Concentrations in policies containing minimum-earned or audit provisions. 

5. Correction patterns by carrier, program, policy type, or originating agency. 

6. Straight-through processing and human override information, where available.

These metrics can show whether the post-bind changes are broadly distributed or concentrated around certain underwriting practices. They cannot, by themselves, show that AI caused those changes. Where a consistent pattern emerges, specialized premium finance companies can respond through the structure and documentation of transactions, monitoring requirements, or through credit policy rather than applying a blanket surcharge before the exposure is quantified.

A premium finance company providing disciplined servicing, sound documentation and established relationships throughout the insurance distribution network is better positioned to respond when underwriting changes affect a financed policy and manage the resulting financial impacts.

Next Steps for Insurance – the Financial Implications of AI

Industry participants should consider how often AI-assisted underwriting decisions change after coverage begins and financing capital is committed, as well as whose interests are affected.

Premium finance companies don't need to wait for measurable losses before they begin tracking these changes. By analyzing decision stability now, they can assess whether the automation improves transaction efficiency and whether it also shifts financial risk downstream.


Brian Krogol

Profile picture for user BrianKrogol

Brian Krogol

Brian Krogol is chief financial officer of Standard Premium Finance. 

A certified public accountant, he earned the prestigious Elijah Watt Sells award. Of more than 92,000 candidates who sat for the Certified Public Accountant examination that year, only 39 met the criteria for this award.

When Small Business Risk Leaves the Premises

Off-premises operations introduce property, liability and product exposures that a business address alone may not reveal to underwriters.

Insurance

A business address can tell an underwriter where a company is based, but increasingly, it may say much less about where that company actually does business.

Food vendors run their businesses at markets and community events. Service contractors spend ample time at their customers' premises. During the fall holiday season, festivals and pop-up retail events often require small businesses to work away from their main premises for longer periods.

For underwriters, treating a single address as a fixed value can obscure the different types of exposure that arise when a business carries out its operations off-premises. These risks commonly include property exposure, premises liability, product liability, and, for contractors, care, custody, or control.

Property Coverage Can Change Once the Business Moves

Two businesses with the same revenue level can have quite different off-premises property exposures depending on the amount and frequency with which their inventory is transported. One may conduct nearly all of its business online and ship orders from the same location. Another may follow a similar model during the week but spend weekends selling directly to customers elsewhere.

Many BOP forms offer limited coverage for off-premises property, typically as a fixed sublimit rather than a percentage of the total business personal property limit. Other policy forms may provide different limits or conditions, including coverage up to the full business personal property limit.

Limited off-premises coverage may be adequate for occasional activity, such as when a retailer participates in a single holiday market, but businesses with regular mobile operations may present a different exposure profile. Food vendors, contractors who transport equipment, and vendors who regularly attend markets may have property located away from their primary location throughout much of the year.

For such businesses, raising the BOP sublimit may be insufficient. Depending on the operation, separate inland marine coverage may be appropriate, including a transportation floater, scheduled equipment coverage, or an installation floater for contractors.

Underwriters, agents, or risk managers should determine how much property leaves the premises and whether the exposure is infrequent enough to warrant a BOP extension or frequent enough to call for separate coverage.

Premises and CCC Liability Present Different Exposures

Premises liability does not increase in the same way as property exposure because general liability is generally not specific to a location. Instead, the level of exposure depends on factors such as foot traffic and the venue. A vendor at a large festival may have more exposure than the same vendor operating outside its store.

Service contractors face a particular challenge regarding liability involving care, custody, and control. Commercial general liability policies commonly restrict coverage for damage to property in the insured's care, custody, or control. Contractors working on property belonging to customers may need an installation floater or a specific CCC endorsement, depending on the work and policy.

References to off-premises exposure that focus primarily on vendors and event booths can miss a significant portion of the businesses affected. Contractors and other service businesses may spend much of their working time on property belonging to someone else.

Furthermore, off-premises activities can introduce insurance requirements before a business can participate in an event or begin work for a customer. Festivals, venues, and client contracts may require proof of insurance or additional insured status.

Whether a policy allows for blanket additional insured status or requires an individual endorsement, such as CG 20 26, can become a coverage issue, rather than simply a matter of obtaining documentation.

Carrier appetite also matters alongside the terms stated in the policy. A carrier may not expressly exclude certain off-premises or special event exposures but could view regular, previously unreported activity differently when evaluating the account at renewal. Keeping underwriting files current becomes particularly important as occasional off-premises work develops into a regular part of the business.

Product Liability Can Cross Borders

The coverage territory under standard commercial general liability insurance generally encompasses the United States, including its territories and possessions, Canada, and Puerto Rico.

Product liability can provide coverage for an injury involving a product outside that territory under certain conditions. A product manufactured or sold within the coverage territory may cause injury abroad, but coverage can depend on where a resulting lawsuit is filed. A U.S. business whose product causes injury abroad may still have coverage if the suit is brought within the territory specified by the policy.

The jurisdictional limitation creates another potential gap when a business begins operating internationally. Exhibiting at an international trade show, selling directly into foreign markets, or establishing a physical presence overseas can introduce exposures that extend beyond what a standard domestic CGL policy typically addresses.

Businesses with those operations may need a separate foreign liability policy. Depending on the policy terms, that coverage can extend beyond product liability to include premises and operations liability, as well as other exposures that arise abroad.

Businesses often enter international markets gradually. An occasional trade show can lead to regular international events, or a company may begin selling into new markets without viewing the change as a major expansion. The insurance exposure can build alongside those activities.

Off-Premises Activity Raises a Rating and Data Question

Classification codes can provide useful information about what a business does, but they may say less about how frequently it operates away from its primary location.

That raises a rating question for carriers: Should off-premises frequency become a separate variable rather than something underwriters deduce from classification codes?

Intake and renewal questions can help underwriters distinguish businesses with occasional off-premises activity from those with more standard exposure. Exposure risks may be related to event frequency, the percentage of revenue from off-site sales, geographic radius, foreign operations or travel, and whether employees regularly travel to job sites.

Digital applications can make those questions more targeted. An affirmative response about off-site operations can prompt additional questions relevant to that business — without adding unnecessary steps for applicants that operate exclusively from one location.

What This Means at Renewal

Business owners may not flag seasonal off-premises activity as a significant change, but it can shift property control or liability exposure in ways that only surface when the prior term is reviewed.

Carriers can identify those changes by standardizing a few questions at renewal:

  • How frequently did the business operate off-premises during the term, and at which locations?
  • Has off-premises revenue or event frequency increased since the policy was implemented?
  • For contractors, is CCC exposure accounted for, or is it assumed to fall within the GL policy?
  • Did the business conduct any operations outside the policy's coverage territory during the term?
  • Are enough employees regularly traveling to job sites or events to affect their workers' compensation classification?

Growth does not always arrive through a new storefront, larger headquarters, or another permanent location. It can happen gradually as a business begins spending more of its time generating revenue off-premises.

Fall markets and holiday events make those patterns particularly visible, but they expose a year-round underwriting issue. Understanding where a small business operates, what happens there, and how its operating pattern changes over time can give insurers a more accurate picture than an address alone.


Chris Van Leeuwen

Profile picture for user ChrisVanLeeuwen

Chris Van Leeuwen

Chris Van Leeuwen is the vice president of professional development for Insurance Canopy. 

He entered the insurance industry in 1987 and earned his Certified Insurance Counselor (CIC) designation in 1996. He is also an approved Continuing Education (CE) provider for the state of Utah.

3 Mistakes That Stall Insurance AI

Claims adjusters report the highest AI dissatisfaction rates across all occupations, but poor implementation—not the technology—is to blame.

Insurance

AI is adding tremendous benefit to the insurance industry, but claims adjusters dislike it more than workers in any other occupation. Between June 2025 and May 2026, 98% of adjuster comments about AI in Glassdoor reviews were negative. For comparison, the figure for all occupations was 53%. Insurance overall came in at 81%, the third-most AI-critical industry Glassdoor tracked.

But AI technology isn't the problem. Routine servicing, such as billing questions, ID cards, policy changes and status checks, already completes on its own more than 85% of the time. Also, if you read those comments on Glassdoor closely, you'll see that the complaints read mostly like product reviews. One reviewer said they spent 15 to 20 minutes correcting AI-generated mistakes "because supervisors don't verify anything." Another wrote that the new tools left them "dubious about the accuracy of some claim activities."

Unrelated factors add to the on-the-job frustration: Experienced adjusters are leaving their positions. They are quitting at about 20% per year, with each departure taking roughly six years of experience with them, according to a September 2025 Deloitte study. The Bureau of Labor Statistics projects 21,600 openings a year in the same occupation through 2035, and by its own accounting, every opening exists to replace someone who has transferred out or left the workforce. The desks stay full while the people at them keep starting over, learning how to use AI software products from scratch. Meanwhile, 58% of adjusters who remain in place spend more than a fifth of their day on manual data entry and compliance, per Verisk.

That's the day-to-day work experience for insurance adjusters, while special cases such as wildfires and storms add still more stress. One of our clients absorbed 14 times its usual claim volume in the two weeks between hurricanes Helene and Milton. No company can staff for that.

Compounding matters, carriers are hiring experience rather than developing it. Job posting data show junior adjuster listings are down by half since early 2024, while listings for senior adjusters run roughly 80% above their 2017 level. That means everyone is recruiting from the same thinning pool of veteran adjusters, but no one is replenishing it from below.

While AI is the logical response to that shortage, most carriers are implementing it on an ad hoc basis. A poorly thought-through implementation can cost more in claims than it would in most other industries, too, because that policyholder on the other end of the call is likely experiencing the worst thing that's happened to them all year.

Mistake 1: Bolting AI Onto the Call Center Instead of the Core

Five percent of the value of an AI-managed phone call comes from conversations with policyholders. The other 95% is the orchestration happening underneath: pulling the policy, checking coverage, opening the claim, dispatching the vendor and writing all of it into the system of record. Carriers that buy voice AI as a contact-center feature are buying the 5%.

If that stripped-down AI agent can't reach Guidewire, Duck Creek or Snapsheet directly, it doesn't relieve the adjuster caseload because, while it can hold a conversation, it doesn't resolve anything. In the deployments we've measured, routine status calls consume more than 40% of an adjuster's time. An AI agent that answers calls but just hands the work to a (likely overworked) adjuster isn't adding much value. That adjuster must still take the message, rekey it and then work the open loop.

These are the adjusters writing the anti-AI Glassdoor reviews and searching LinkedIn for new opportunities.

Mistake 2: Skipping Governance to Move Faster

Governance allows pilots to become deployments. An agent with no way to flag when it's unsure, no rule for when it hands off to a person and no record of what it said hides risk. Nobody sees the mistakes until a market conduct examiner requests the call records.

Claims handling accounted for 65% of complaints filed by consumers with state regulators in 2024, according to ValuePenguin's analysis of NAIC closed-complaint data. Delays alone were 22%. While hallucination rates below 1% are achievable in production, that's still not zero.

The question a chief claims officer should ask a vendor is: What happens the moment the model gets something wrong? That officer should also find out whether confidence is scored in real time, and whether a low score triggers a warm transfer with the full context attached. Or does it just dump the policyholder back into the queue? Also: is every action logged against authority limits, and is there a kill switch?

Mistake 3: Starting With the Hardest Use Case

Carriers go to claims first because that's where the pain is. It's also the hardest problem to automate. FNOL, or first notice of loss, requires an AI agent to collect regulated information from someone (who is often upset), while working across several systems to open the claim. In our deployments, our agent completes the FNOL 45% to 55% of the time. Routine servicing, such as billing questions, ID cards and policy changes, completes more than 85% of the time.

We initiated an FNOL activation once at a carrier's request. The results came in under half, and it took nearly a year to rebuild the case for automating anything else with that company. That experience points to a broader risk because claims draw more internal scrutiny than any other function at a carrier.

A project's first result carries unusual weight, and if that number looks like a failure, leadership grows reluctant to keep funding the work, so the project ends before the team has a chance to show what the AI tool can do.

Start with servicing. The first result looks like a win, which gives a carrier something concrete to point to before asking adjusters to trust anything that's harder.

The Common Thread: Treating AI as a Bolt-On Feature

All three of these mistakes share a root cause: they don't treat AI as infrastructure.

Voice AI purchased as a contact-center bolt-on feature never reaches the systems of record. Pilots that skip governance don't ever earn the right to scale, and projects that start with the hardest use case never survive long enough to reach the easier ones.

These are sequencing failures, not model failures. An AI agent can handle routine calls at a volume no hiring plan can match while the adjuster speaks with policyholders who genuinely require a person. Those conversations, the ones where someone is having the worst week of their year, begin with the claim already open and the context already assembled.

AI can lighten the adjuster's workload if the work is sequenced properly. It will give back the 40% or more of the day now eaten up by routine status calls. Negative sentiment toward AI will then turn for the better once adjusters see that their Monday morning queues are shorter.


Amrish Singh

Profile picture for user AmrishSingh

Amrish Singh

Amrish Singh is co-founder and CEO of Liberate, which builds insurance-native AI agents for P&C carriers and agencies. 

He previously spent nearly four years in back-office operations and technology at Metromile.

Reducing the Risk in Change Management

More experience and better tools are taking some of the risk out of change management during today's complex and significant technology transition. 

An Interview with Samit Bhandari

Paul Carroll

Change management has always been important, but we're now in a period of complex and significant change. How has the importance of change management evolved, particularly in insurance?

Samit Bhandari, Principal PwC US

We've been driving, leading, and participating in large-scale transformations in the P&C insurance industry for 20-plus years. When you think about technology, we have become more experienced at leading these transformations. There's better tooling, more practitioners, certifications, accelerators, AI—the list goes on. That has helped to reduce several risks in the technology aspect. 

But it's still the same level of challenge in terms of the human aspect of what these programs are delivering, how they're changing the day-to-day work and operations, and what that means to a customer service representative (CSR), to an agent, to an associate internally or other such stakeholders.

Paul Carroll

There's often a disconnect in technology adoption that goes unnoticed in business. A leader might mandate the use of AI, and employees will say they're using it—but are they really changing the way they do things, or are they just going through the motions to show compliance? How do you get people on the same page in a big technology transformation?

Samit Bhandari

First, just in terms of getting everyone on the same page, it's the fundamentals of what we've always said about getting stakeholders engaged—executive, top-down engagement early, right? The messaging from that level through various levels of the organization. And then just the strategic, tactical things—the change champion network and the communication early and often. When you bring in AI—we should be more nimble.

I do find in the tier two space, the carriers that we work with that are a little bit smaller are nimbler. They're better at embracing the transformation from the top levels of the organization and getting everyone on the same page to highlight there is a significant effort being made by the organization. 

At times, such transformational programs can seem a little less cohesive with larger carriers, because they have multiple efforts going on. There may be a lack of alignment within one group to another group, or the change isn't happening to everyone at the same time. 

The second part of this is getting working product in the hands of the end users faster, such that they can get more aligned in the requirements they're specifying, what they're seeing, and then the changes they want to make. 

With the builder concept, we shouldn't have to take the waterfall approach—holding workshops, gathering requirements, then shutting that off and moving sequentially… so on and so forth. We’re able to showcase how we are doing things now, obtaining that builder and 10x engineer mentality so we can take those requirements in real time and turn them into results.  

Are we there yet? Not fully. But that path is becoming much more realistic. 

Paul Carroll

What do you see companies doing wrong about change management?

Samit Bhandari

It can’t just be about the rah-rah, the change champion network, the T-shirts, the slogans, and getting the sentiments higher. That's an aspect of change, and we need to do the communications. But companies don’t always start planning soon enough, and oftentimes allocating budget for change management becomes an afterthought despite the criticality. The OCM effort is at times not considered enough of a priority up front nor given enough budget, time and commitment throughout the program.

Companies may also underestimate what they should do on Day Two, after the initial go-live. I was with a few executives for a tier-two carrier in the Midwest recently, and we talked about how getting to the pilot, while difficult, was expected. However, the effort associated with subsequent rollouts, geographical and product expansions, as well as continuous platform improvements, were more difficult than they had expected. And then the amount of feedback that came in immediately after they went live was even beyond their expectations – and cutting through the “noise” even tougher.

What they often get wrong is not knowing that this is going to be a continuous and iterative process. The backlog of things to change, enhance and tweak is going to grow the minute you put something in the hands of your associates and your agents. You should have processes up front—both from a change standpoint and a delivery standpoint. From a change standpoint, to expect the amount of feedback that's going to come. But then from a delivery standpoint, to be comfortable in saying, "Hey, we're not going to knock all that off and react within 30 days, but we're going to systematically respond and talk about how we can improve continuously."

Paul Carroll

What are the biggest changes you’ve seen over the years?

Samit Bhandari

Early in my career, we spent extensive time working with the C-suite upfront. We built strong business cases that quantified why we were doing what we were doing, what the impetus for change was, and what the benefits would be. We went as far as having the different P&L leaders, whether it's claims or policy or billing or actuarial, sign up for the benefits the new platform would have for their constituents.

We've really moved away from that. The attitude became, “Well, we have to do something because its table stakes. Now, the idea is extending to, “Who needs to modernize the core, can’t we just use AI to get the work done in weeks or months?”

We've unfortunately moved away from taking the time up front to think about the impact a new platform can have on end users or the top line of the organization. I think we should come back to that planning a little bit because it anchors the program in the proper tenets, and it can help assess whether you can just do this in months, given the regulatory complexities.

Once you hear from end users, you realize it's not that simple to just pick up a black box, tinker, and come back with a platform that addresses various state rules and regulations, coverage needs and DOI expectations. 

Paul Carroll

What are some red flags that companies should watch for, to see they’re doing change management wrong?

Samit Bhandari

Watch out for comments like, "I miss the old system," or "The old platform didn't do this." Or “This is how it used to work.” You may get some of that, but you've really got to have your ear to the ground. Who is saying it? How much is that sentiment catching fire?

Another red flag is when business engagement and user acceptance are lacking. Users should be asking to see the new system early so they can see the results. They should want to get their hands on it and feel excited about what's going to come, because they're in it day to day.

A third warning sign is when you don't have alignment among the leadership. Somebody should be empowered to observe and then make tough decisions, to maybe say, "Hey, maybe this person shouldn't be an executive sponsor," or "We need them to shift how they're operating." Even if lack of alignment doesn't cause the program to fail during the implementation journey—after the fact, it could be just as damaging if people cast shade on what was done. "Oh, we spent too much money on that," or "We overengineered this process," or "It took too long." Leadership should wear the badge throughout the journey and even beyond.

Paul Carroll

What are three or four keys to having a successful change management program?

Samit Bhandari

I can easily flip some of those failures around into successes. Certainly alignment from the top down. The change champion network is important. Individuals should feel excited about what they're seeing. The feedback network should be working well, so you can identify pain points and then dig deeper.

Having a balance of stakeholder engagement monitoring and progress monitoring can help you identify the proper level of adoption metrics early on. 

The last thing is the awareness that it's going to be a continuous evolution and change is continuous. Even after we go live with the first pilot or the next set of states or the portal, there's going to be feedback. How we respond to it and react to it is more important than whether we got it right out the gate.

This last one is often one of the more important things to remember: a balanced mindset of "if we don't get it right, the sky isn't falling. Let's get back together as a team, a cohesive team, and respond." I was in an executive sponsor meeting this morning, and we talked about being 5% over budget. We talked about having 30 open risks. We talked about seeing more inflow of defects at this juncture than we wanted. We had the whole C-suite on the line, and everyone was just processing the information, making sure we have the proper rigor around it, and saying, "Alright, here's how we can tackle the issues with the necessary mitigation plans."

The beauty is that when the approach works well, you roll out, go live, and start changing the day-to-day operations of everyone across the different stakeholder communities, internally and externally.

And we're seeing more programs making progress. You may have heard that adage that 80% of projects fail to deliver on their objectives and all that, but that's not the case anymore in this space. The speed to market is often top of mind along with the ability to make changes and identify top-line growth by introducing new products, helping deliver significant changes faster.

Paul Carroll

Thanks, Samit.


About Samit Bhandari

Samit Bhandari Headshot

Samit Bhandari is a Partner with PwC, where he has more than 20 years of consulting and industry experience focused on the property & casualty insurance sector. He specializes in leading large-scale core insurance and digital transformations, with deep experience in Guidewire, program leadership, organizational change, and technology modernization. Throughout his career, Samit has advised and led transformation efforts for a broad range of regional and national insurers, helping organizations navigate complex business and technology change. He holds an MBA from the University of Chicago Booth School of Business and a bachelor’s degree in Mathematics from the University of Illinois at Urbana-Champaign. Samit is based in Chicago, where he lives with his wife and two sons.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

What an AI Insurance Pilot Can't Tell You

AI pilots prove capability, but production adoption hinges on workflow integration, data relevance and user trust at scale.

Insurance

An AI pilot can answer an important question: Does the capability create value? What it cannot fully answer is whether a broader group of employees will use that capability consistently while doing their everyday work.

That distinction has become increasingly important in our work with AI insurance wholesalers selling to financial professionals such as agents or advisors. A pilot can demonstrate that AI will bring together CRM history, previous product discussions, and outstanding commitments to produce a useful brief before an agent or advisor meeting. Yet production adoption takes place under different conditions. Pilot users are selected, attentive, and supported. Production users are not evaluating the AI; they are preparing for meetings, working with advisors or agents, and moving through a busy day.

For that reason, a favorable response from pilot users is encouraging, but it is not a complete test of adoption. In our experience, three areas deserve particular attention: how users encounter the AI, how the product identifies what matters within production data, and how users verify information without assistance from the pilot team.

1. Pilot Users Seek Out the AI; Production Users Need It Within Their Work

First, pilot users know they are participating in an evaluation. They expect to spend time with the product, initiate the experience, and pay close attention to the result. If generating a meeting brief requires a few deliberate steps, they will generally take them.

Production users operate differently. A wholesaler moving between advisor or agent meetings, email, follow-up, and CRM activity is unlikely to think first about using an AI capability. The immediate objective is preparing for the next conversation—not testing a product.

As a result, adoption depends partly on whether the intelligence appears at the right moment. For meeting preparation, the calendar can provide that moment. An upcoming meeting already establishes when preparation is needed and may help identify the relevant financial professional. The brief can then be delivered in connection with the scheduled work rather than depending entirely on the wholesaler remembering to request it.

Similarly, the location of the output matters. If the wholesaler already works from the calendar and Salesforce, requiring a separate destination introduces another step between the user and the value. Presenting the brief within the existing workflow makes the AI easier to use without asking employees to reorganize how they work.

The larger point is not that users resist new technology. It is that pilot participation creates attention that will not exist at the same level in production. Broader adoption is more likely when the product does not depend on preserving that pilot-level attention.

2. Controlled Data Proves the Capability; Production Data Tests Relevance

Second, a pilot usually begins with a defined set of records. This is useful because it allows the team to determine whether the AI can retrieve, organize, and summarize the intended information.

Production data is less controlled. A financial professional's CRM history may contain years of calls, meetings, emails, marketing activity, and service interactions. Some entries are meaningful to the next conversation. Others are routine, incomplete, or no longer relevant.

Consequently, accuracy alone does not guarantee a useful brief. AI can summarize every available record correctly and still give too much attention to information that does not matter now. The production challenge is not simply to retrieve more data; it is to prioritize the signals most relevant to the work being performed.

For example, an unfinished commitment from the previous meeting might deserve more attention than numerous routine CRM activities. A recent product discussion may be more useful than an older description of the overall relationship. Likewise, recent annuity illustration software activity could indicate that an advisor is actively evaluating a particular product or client strategy.

However, the meeting brief may not need every value and disclosure contained in that illustration. The useful distribution context might be which product was illustrated, when the activity occurred in the annuity illustration software, and whether it led to additional engagement.

Therefore, connecting AI to CRM, product, and customer data is only the beginning. The product also needs enough business context to distinguish between information that is available and information that deserves the wholesaler's attention. A pilot can prove that the AI can process the records; broader use reveals whether it can consistently surface what matters.

3. Pilot Oversight Supports Trust; Production Requires Independent Verification

Third, AI output receives unusual scrutiny during a pilot. Participants know that the capability is being evaluated, and the team running the pilot is usually available to investigate questions. The underlying data may also be familiar to the people reviewing the results.

That level of support does not scale into everyday use. In production, wholesalers need to assess important information without asking the product team to explain how the AI reached a conclusion.

Consider a brief stating that an advisor previously showed interest in a particular annuity strategy. The wholesaler should be able to determine what supports that statement. Was the interest documented in a meeting note? Was an illustration generated? Did the advisor request product information? Or did the AI infer the interest from several activities?

This distinction affects how confidently the wholesaler should use the information in an advisor or agent conversation. It becomes even more consequential when the information moves downstream into a follow-up email, a CRM update or the context prepared for a future meeting.

For this reason, source attribution serves a practical purpose beyond governance. Connecting important statements to their underlying records allows users to verify the context independently. Separating record-based facts from AI-generated suggestions also helps the wholesaler apply professional judgment rather than treating every statement as equally certain.

In a pilot, confidence may be reinforced by the team surrounding the test. In production, the product itself must provide enough transparency for users to decide how the information should be used.

What the Pilot Proves—and What It Does Not

Taken together, these three differences do not diminish the value of a pilot. They clarify what the pilot is designed to establish.

A pilot can show that AI will perform the intended task and that users recognize value in the output. It can validate the central use case, expose data considerations, and provide meaningful feedback before broader deployment.

At the same time, a pilot cannot fully reproduce the conditions under which a larger group of employees will use the capability repeatedly and without special attention. It cannot by itself establish whether the AI will appear naturally within the work, remain relevant across a full production data set, and earn trust without the pilot team nearby.

For us, the central lesson has been that adoption is not simply a favorable reaction to an AI-generated result. It depends on how naturally the capability enters the workflow, how effectively it directs attention, and whether users can act on its information with confidence.

A pilot answers whether AI can create value. Production adoption depends on whether employees can receive that value while doing the work they already came to do.


Jay Singh

Profile picture for user Jaysingh

Jay Singh

Jay Singh is a co-founder and head of client solutions at Hedgeness, which provides AI-powered sales and marketing software for insurance carriers and asset managers. 

He has more than two decades of experience across financial services and technology companies. He is a frequent speaker at industry conferences on AI, financial services technology, and distribution.

What AI Doesn't Understand

As AI masters producing realistic images and expert-level outputs, imitation doesn't mean it understands cause-and-effect.

Insurance

OpenAI's recently released GPT-6 Astra again pushes AI capabilities forward. It is smarter, can handle more tasks, and makes it even easier to feel that AI is gradually moving toward "understanding the world." But the model leaves a question open: 

How do we tell whether the model truly understands? And what, exactly, does it understand?

Not long ago, I happened to read an article from HalfJourney Lab about AI image generation. The author wrote: 

There are effects without a cause.

That issue doesn't just affect images but relates broadly to how AI comes to know the world and is increasingly hard to notice.

To explore that problem and how to think about it, let's start with AI's drawing errors.

1. AI Image Problems Are No Longer Just "Drawing Mistakes"

In the past, obvious errors in AI-generated images were not difficult to spot. An extra finger, distorted facial features, garbled text, or broken object structures could often be recognized at a glance.

Today, the situation is different. AI can generate highly natural-looking skin, lighting, depth of field, and materials. In many images, each individual element can look convincing on its own, with no obvious flaw. The real issue has shifted from whether each object is drawn well or correctly to whether, once the elements are placed together, they still obey the rules of the real world.

Let us start with this example.

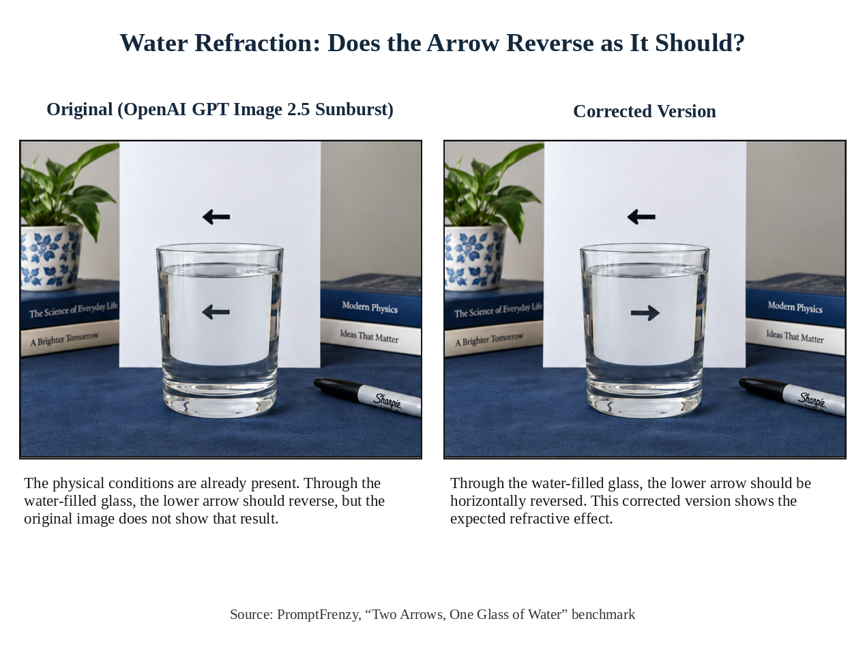
Both arrows on the paper point in the same direction, with a glass of water placed in front of the lower arrow. The glass, the water, and the arrows all look quite natural.

But once the physical conditions are in place, the expected result does not follow.

A cylindrical glass of water causes refraction, so the lower arrow viewed through the water should appear horizontally reversed. In the original generated image, however, both arrows still point in the same direction.

That is what makes the example interesting. AI did not draw the glass incorrectly, nor did it draw the water or the arrows incorrectly. It got the objects in the scene right, yet failed to derive the result that should necessarily emerge when those objects are placed together.

Now look at the second example.

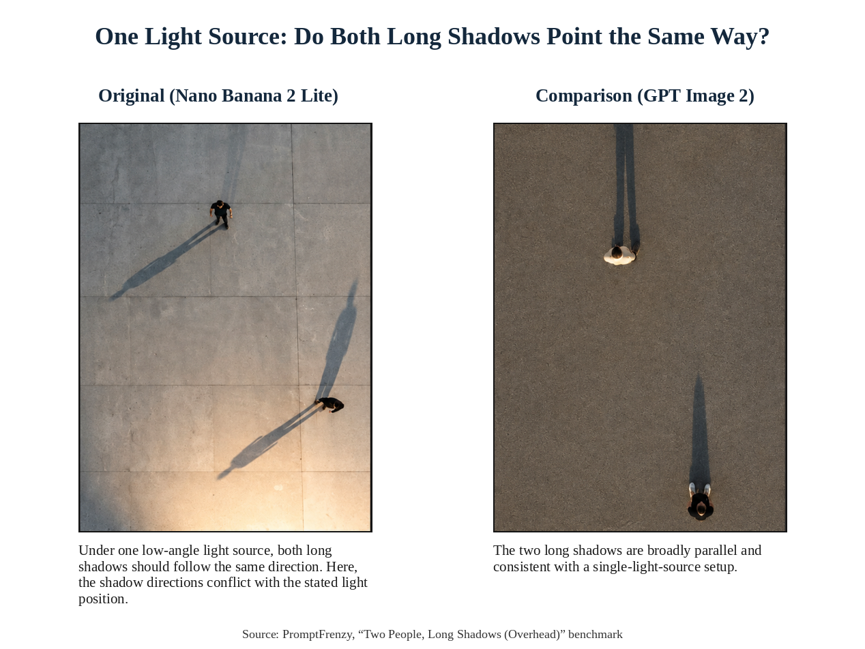
Two people stand under a low-angle light source, and the long shadows themselves look quite natural. If we look at either person in isolation, it is difficult to say that anything is wrong with the image.

But there is only one light source. The position of that light source, the positions of the people, and the directions of their shadows should therefore share a consistent geometric relationship.

Once we examine the whole image as a single physical space, the problem becomes visible: AI can generate highly realistic-looking shadows without reliably preserving the relationship between the light source and those shadows.

This is also why today's AI images are becoming harder to judge simply by asking, "Where is the drawing mistake?"

What exposes the problem is the relationship.

2. Photography, Painting, and AI Generation

This made me think again about what, exactly, separates photography, painting, and AI-generated images.

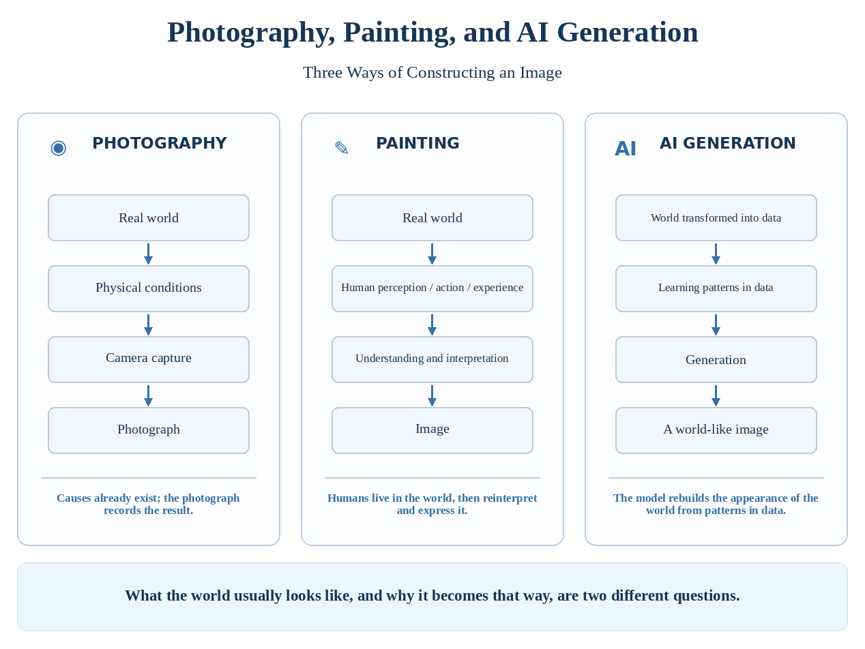
Photography begins by capturing the real world.

Cameras differ in capability, and photographers in skill, but the light, shadows, reflections, and depth of field in a photograph are, in principle, produced by physical conditions that actually existed at the moment of capture. An object blocks light, so a shadow appears. Light reaches the eyes or lenses, so a reflection may appear. The distances between objects and the lens, together with aperture, focal length, and other conditions, produce different degrees of depth of field.

A photograph therefore records a result whose causes already existed before the shutter was pressed.

Painting is different.

A painter does not directly capture reality, but reinterprets it. The painter relies on tools, technique, and an understanding of the world to reconstruct light, shadow, space, and objects on a canvas.

A painter knows where a shadow should fall not simply because they have seen many shadows, but because they live in this world. They have watched light move, seen what happens when an object blocks it, and can change their own position and observe how the world in front of them changes in response.

In form, AI image generation is closer to the latter. It does not directly capture reality. It generates a scene that looks like the real world according to patterns it has learned.

The difference is that human understanding of the world develops over time through perception, action, and feedback; AI does not live in the world in the way humans do.

Its starting point for knowing the world is data. Its mechanism is to learn recurring patterns in that data and then use those patterns to regenerate and depict the world.

It has seen countless examples in which eyes appear with catchlights, portraits with blurred backgrounds, and glasses, reflections, shadows, and scenes recur in familiar combinations.

From this data, the model learns what the world looks like. But what the world usually looks like and why it becomes that way are two different questions.

3. Reproducing the World and Understanding It

Today's AI can generate photographs that look real, language that sounds human, and analyses that resemble those of experts. It can also produce strong results across many complex tasks. These abilities are signs of technical progress, but a system's ability to reproduce an outcome does not prove that it has mastered the mechanism that produces it.

Drawing a shadow is not the same as understanding how a shadow forms. Generating a reflection is not the same as knowing which light source should produce it. The real dividing line here, I believe, is causality.

If "reproducing the world" mainly answers the question, what do things usually look like? then "understanding the world" must at least go one step further: Why did this result appear? If the conditions change, how should the result change? Which phenomena merely occur together frequently, and which are linked by more stable generative relationships?

This is why an AI-generated image can look highly realistic in each local detail while still producing a scene that is physically impossible as a whole. A model can learn from data what an outcome usually looks like without necessarily possessing a sufficiently stable causal structure to constrain all of those local outcomes within the same world.

So the important issue is not simply "effects without causes" or "causes without effects." It is that, within AI's worldview, the relationship between cause and effect can break down.

Sometimes AI generates a shadow or reflection without reliably grasping the conditions that produce it, leading to physically inconsistent results. At other times, as in the glass-and-arrow example, the physical conditions are already present but the expected refractive result does not appear. These problems look different, but they point to the same underlying issue:

AI can reproduce the appearance of the world without necessarily possessing a stable grasp of the causes that produce those appearances.

4. When AI Starts to Look Like an Expert

This question is worth carrying beyond images, because what AI generates today is no longer limited to images. It answers questions in medicine, finance, law, insurance, manufacturing, and management; it organizes data, analyzes risk, makes recommendations, and increasingly produces language and reports that sound like the work of experts.

At that point, it is easy to make a further inference: if AI's answers already look so much like an expert's, has it acquired expert capability?

The image examples remind us to be careful with that inference. A correctly shaped shadow in an image does not prove that the system understands how light produces shadows. In the same way, an answer that matches an expert's answer does not, by itself, allow us to infer that AI went through the same process of judgment.

Consider an underwriter making an underwriting decision. Behind that decision may lie relationships among medical histories, projections of future risk, judgments about data reliability, exceptions, and years of accumulated experience. If we hand the same task to AI, even when it reaches the same conclusion, we still cannot confirm which of those relationships it has actually mastered, or whether those relationships will continue to hold when the conditions change.

Some people may say: But can't we already see AI explain its reasoning step by step?

Reasoning, however, is not causality. The ability to produce a chain of reasoning does not mean that a system has mastered causal relationships in the real world. A model can organize reasons, steps, and conclusions into a highly coherent explanation based on learned patterns. The real question is whether, when one condition changes, it can reliably identify which outcomes must also change. That is the causal capability I am referring to here.

A correct answer, or a line of reasoning that appears plausible, is not enough on its own to prove that a system has formed a stable causal understanding. That is why I prefer to describe "expertise" this way:

AI can learn how expertise should appear without necessarily understanding how expertise is produced.

This is not a denial of AI's capabilities. Precisely because AI is becoming increasingly good at reproducing expert outcomes, we need to know whether what we are seeing is similarity in the result, or whether the ability to produce that result is also beginning to form.

The two are not the same.

5. Causality May Be One Threshold for Understanding the World

The arrival of GPT-6 Astra is simply another round of technological evolution. We can expect the next generation of models to be stronger still, capable of handling more tasks and further narrowing the gap between humans and AI in outward performance.

As that gap becomes smaller, the question "Does AI understand the world?" becomes larger, not smaller. The closer the outward performance, the harder it becomes to infer from results alone what is happening underneath.

When outputs are still crude, it is easy to see what a model does not know. But when the results become realistic enough, professional enough, and in some tasks even better than the performance of most people, can we still distinguish whether AI is reproducing the world or has begun to understand it?

Causality is one important threshold.

A system that truly understands the relationship between light and shadow should change the shadows, reflections, and brightness patterns across an entire scene when the light source moves. A system that truly grasps professional judgment should, when conditions change, do more than regenerate an answer that sounds more expert. It should know which judgments must change as well, and why.

That is why I think the line 'There are effects without a cause' carries a broader warning. As AI becomes increasingly good at reproducing the world, we also need to keep one distinction clear:

We cannot equate "looking like it understands" with "understanding."

The appearance of the world can be learned. Understanding why the world works as it does is a different, higher-order capability.

As AI's outward performance grows closer to human performance, and even surpasses it in some tasks, reproducing the world and understanding the world need to be treated as two distinct things.


David Lien

Profile picture for user DavidLien

David Lien

David Lien is a partner at Lingxi (Beijing) Technology. 

He wrote “Decoding New Insurance” (2020), which ranked among JD.com’s top books. Lien has held leadership roles at Sino-US MetLife, Sunshine Insurance and Prudential Taiwan, leading digital transformations and multi-channel marketing. A 2018 e27 Asia New Startup Taiwan Top 100 nominee, he holds a patent for the "Intelligent Insurance Financial Management System."