Download

Why Are Insurance Jobs Disappearing?

The latest jobs report for the U.S. highlighted a surprising decline in employment in insurance. I have a theory about the reason -- and it's not AI. 

Image
Insurance

The employment report for September in the U.S. showed a loss of 7,000 jobs in financial services. Insurance, alone, has now lost 90,000 jobs since May 2025.

What's going on?

I have a theory, and it's not about artificial intelligence. If I'm right, hiring in insurance will stay in the doldrums for a while.

Let's have a look.

As Insurance Business reports, the industry still employs a massive 2.9 million people in the U.S., but claims jobs are down a hefty 21% over the past year, while life and health is off 4%, P&C down 1.7%, and agents and brokers down 1.1%. The losses are accelerating: The article says, "Insurers lost about 1,900 jobs a month on average in 2025 and roughly 6,900 a month so far in 2026."

A thorough analysis in Barron's mostly attributes the job losses to cost-cutting under pressure. Barron's notes that the surge in rates following the COVID disruption has slowed. In addition, government subsidies for healthcare have been cut even as claims costs keep increasing. In the face of pressure on both premiums and expenses, insurers have had to become more efficient, Barron's says.

It does say AI has played a role by automating tasks but doesn't treat that as a huge issue just yet (and I've been arguing for months that the fears of job losses to AI are overstated).

You could also add the effects of the "silver tsunami" -- the oft-quoted projection by the Bureau of Labor Statistics in 2021 that 400,000 insurance professionals would retire by the end of 2026. Unemployment in insurance remains well below that for the economy writ large -- 3.1%, vs. 4.2% -- so some of the job losses may simply be that companies haven't yet been able to fill the positions left by retirements.

But I think there's an overarching issue that gets short shrift if you spend too much time in the details.

My Theory  

My theory boils down to uncertainty. I think economic and geopolitical uncertainty are holding back the economy, in general, and the insurance industry, in particular. And I don't see the uncertainty subsiding any time soon.

Tariffs have not only raised costs but, because of their on-again, off-again nature, have slowed investment and the sort of adaptation of supply chains that would ordinarily happen if, say, Canadian lumber suddenly became 50% more expensive. Why spend a lot of money and time if prices might return to normal shortly, whether because of a court ruling against tariffs, because Democrats win control of Congress and assert its power, or simply because President Trump changed his mind?

Now add the uncertainty from the war on Iran. Even though oil flows out of the Middle East are improving, Iran retains the capability to attack tankers, to blow up one of the major pipelines being used to skirt the Strait of Hormuz, or to do more damage to the diesel refineries in the region, whose loss has contributed so much to the soaring prices for the crucial fuel. 

While Trump has repeatedly told us that Iran wants to make a deal and that prices for oil will soon plummet, some of us are old enough to remember how the Iranian zealots acted after taking 66 American hostages in 1979. Angry at President Carter, they didn't release the hostages until minutes after Ronald Reagan became president in January 1981. Who's to say the Iranian theocrats won't treat Trump the way their predecessors treated Carter, declining to make a deal until he leaves office?

What is now looking like a blue wave in next month's midterm elections might relieve some of the uncertainty about tariffs, perhaps even leading to serious settlement talks with Iran, but a loss of control by Trump would surely lead to at least a burst of chaos -- perhaps even a sustained stretch. The Democrats are itching to go after him, and he would surely return fire with every one of the many assets at his disposal.

The current uncertainty and the prospects that it will continue will create headwinds for the economy, which insurance, especially P&C, tracks closely. The problem will be even worse than normal, I believe, because the effects will hit personal lines so hard. 

Replacement costs for cars have surged in recent years because of supply chain disruptions, and they will likely stay in flux. Insurers will also have to deal with possibly significant changes in driver behavior if gasoline and diesel prices stay so high -- or go even higher. 

Costs for home repairs have likewise soared, and uncertainty will tend to keep them high. Meanwhile, the general uncertainty about the economy has fueled inflation, leading the Fed to raise rates for the first time in years and to signal that it may raise rates again soon. A result has been 7% mortgages that have pretty much crushed the housing sector. The reduction in construction means fewer homes to insure, and the stagnant resale market limits the opportunities to poach customers as homes change hands.

The result will, I believe, be unrelenting pressure on revenue and costs at a time when customers are exhausted from all the post-COVID rate increases.

I hope I'm wrong, but it's hard to see a lot of hiring in that sort of environment.

Cheers,

Paul

TESTING focus newsletter

some summary here

View this email in your browser | Forward to a colleague
 
ITL FOCUS is a monthly initiative featuring topics related to innovation in risk management and insurance.
This month, we're focusing on IT Ops: Change Management

FROM THE EDITOR

Some two decades into the insurance industry's digital transformation, companies have spent hundreds of billions of dollars on new core systems, cloud migrations, digital portals, and AI tools — but the technology was rarely the hardest part.


The hardest part was the people.


The people part has long been treated as a supporting act in large technology transformations. But as the pace and complexity of transformation accelerates, that approach is showing its limits. Employees nod along, say they're using the new system, and then quietly find workarounds. Leadership mandates adoption from the top while alignment quietly fractures below. Organizations sprint to the go-live date and then discover that the real work hadn't started yet.


Samit Bhandari has watched this pattern play out across the P&C insurance industry for 20 years as a partner at PwC. He's worked with carriers of all sizes through core system replacements, AI rollouts, and full-scale digital transformations — and has seen where these programs succeed and where they quietly go off the rails. He acknowledges there has been improvement—he says the assumption that most large technology programs fail is increasingly out of date. But he says organizations keep making a lot of the same, old mistakes, including the tendency to underinvest in what happens after a go-live, to confuse executive messaging with genuine alignment, and to treat transformation as a one-time event rather than a continuous process.


Read the full interview to find out what red flags signal a change management program in trouble, why smaller carriers are often better at transformation than their larger counterparts, and what Bhandari thinks the industry has stopped doing that it should start doing again.

continue reading >
 

Reducing the Risk in Change Management

Paul Carroll


There's often a disconnect in technology adoption that goes unnoticed in business. A leader might mandate the use of AI, and employees will say they're using it—but are they really changing the way they do things, or are they just going through the motions to show compliance? How do you get people on the same page in a big technology transformation?


Samit Bhandari


First, just in terms of getting everyone on the same page, it's the fundamentals of what we've always said about getting stakeholders engaged—executive, top-down engagement early, right? The messaging from that level through various levels of the organization. And then just the strategic, tactical things—the change champion network and the communication early and often. When you bring in AI—we should be more nimble.


read the full interview >
 

MORE ON CHANGE MANAGEMENT

Change Management Is Changing

by Melissa Palmer

Change management can no longer be viewed as a one-time project discipline. It must become an organizational capability.
 
Read More

How to Put People First in Your AI Rollout

by Tracey Brown

"We made a deliberate decision to treat employee confidence as the primary KPI of our AI transformation."
 
Read More

Insurance Hiring Practices Hamper Transformation (Part 1)

by Amy Radin

Insurance companies hire for sector expertise, but transformation demands cross-boundary judgment that traditional filters miss.
 
Read More

The Answer to Too Much Technology Is More Technology

by Riv Arthur

Claudeforce signals a shift from building tools for humans to use and toward creating infrastructure where machines increasingly do the work.
 
Read More

How to Build Tomorrow's Insurance Workforce

by Afiong Ekong

Insurance's talent crisis demands a shift from hiring for past experience to identifying transferable skills and future potential.
 
Read More

Making Innovation Stick in Insurance Organizations

by Abrianne Harmon

Sustainable innovation in insurance requires organizations to master change adoption through culture building and strategic training design.
 
Read More
View All ITL FOCUS Topics 
 

MORE FROM OUR SPONSOR

NextGen Change

Sponsored by PwC

See how a human-centered approach to change helps your people adopt new ways of working—so transformation sticks.
Read More


ITL 2026 Partnership Opportunities
Partner with ITL to create expert thought leadership content.
Custom Content
Promoted Content
Executive Interviews
Custom Webinars
Monthly Topic Sponsorships
ITL Partner Packages and more
 
Learn More & Get Media Kit 
 
Write for Us
Our authors are what set Insurance Thought Leadership apart.
Get Started

October 2026 ITL FOCUS: Change Management

ITL FOCUS is a monthly initiative featuring topics related to innovation in risk management and insurance.

FROM THE EDITOR

Some two decades into the insurance industry's digital transformation, companies have spent hundreds of billions of dollars on new core systems, cloud migrations, digital portals, and AI tools — but the technology was rarely the hardest part.

The hardest part was the people.

The people part has long been treated as a supporting act in large technology transformations. But as the pace and complexity of transformation accelerate, that approach is showing its limits. Employees nod along, say they're using the new system, and then quietly find workarounds. Leadership mandates adoption from the top while alignment quietly fractures below. Organizations sprint to the go-live date and then discover that the real work hadn't started yet.

continue reading >


Reducing the Risk in Change Management

Paul Carroll

There's often a disconnect in technology adoption that goes unnoticed in business. A leader might mandate the use of AI, and employees will say they're using it—but are they really changing the way they do things, or are they just going through the motions to show compliance? How do you get people on the same page in a big technology transformation?

Samit Bhandari

First, just in terms of getting everyone on the same page, it's the fundamentals of what we've always said about getting stakeholders engaged—executive, top-down engagement early, right? The messaging from that level through various levels of the organization. And then just the strategic, tactical things—the change champion network and the communication early and often. When you bring in AI—we should be more nimble.

read the full interview >


MORE ON CHANGE MANAGEMENT

Change Management Is Changing

by Melissa Palmer

Change management can no longer be viewed as a one-time project discipline. It must become an organizational capability.

Read More

How to Put People First in Your AI Rollout

by Tracey Brown

"We made a deliberate decision to treat employee confidence as the primary KPI of our AI transformation."

Read More

Insurance Hiring Practices Hamper Transformation (Part 1)

by Amy Radin

Insurance companies hire for sector expertise, but transformation demands cross-boundary judgment that traditional filters miss.
 

Read More

The Answer to Too Much Technology Is More Technology

by Riv Arthur

Claudeforce signals a shift from building tools for humans to use and toward creating infrastructure where machines increasingly do the work.
 

Read More

How to Build Tomorrow's Insurance Workforce

by Afiong Ekong

Insurance's talent crisis demands a shift from hiring for past experience to identifying transferable skills and future potential.
 

Read More

Making Innovation Stick in Insurance Organizations

by Abrianne Harmon

Sustainable innovation in insurance requires organizations to master change adoption through culture building and strategic training design.
 

Read More


MORE FROM OUR SPONSOR

NextGen Change

Sponsored by PwC

See how a human-centered approach to change helps your people adopt new ways of working—so transformation sticks.

Read More


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

Fleets, Insurers Struggle With Telematics Data

Fleets and insurers now have access to telematics data but struggle to convert it into actionable insights that reduce risk.

Interior view of a car featuring the GPS navigation system illuminated at night, showcasing technology and modern travel

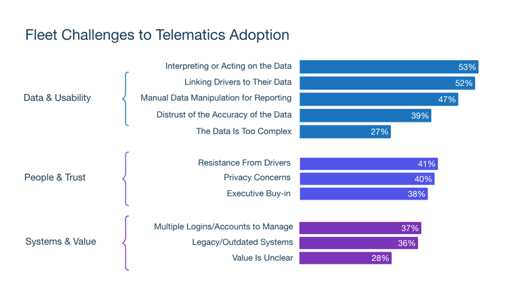
Telematics is no longer a hard sell for fleets. According to new data from SambaSafety, 46% of fleets have been using telematics for at least six years — long enough for the conversation to shift from whether to adopt it to how to act on everything it collects.

SambaSafety's fourth annual telematics report, based on survey responses from 740 fleets, insurers, and brokers, indicates that 53% of fleets struggle to interpret or act on their telematics data. That now ranks ahead of driver resistance and privacy concerns, the two objections the transportation industry has spent years trying to overcome.

On the other side of the table, insurers are experiencing their own successes and challenges. In 2025, data showed that 48% of insurers said convincing large fleets to share their telematics data is a top challenge. In 2026, the concern faded quickly, falling to 24%. With access largely settled, the harder work moved downstream to what insurers do with the data once they have it.

Insurers are working through the same question fleets are, which is how to turn telematics data into something of value, both for their own operations and for the insureds they cover. In SambaSafety's report, that difficulty now ranks as their leading challenge to using telematics in their operations.

Both findings create a clear picture of fleets with data they can't fully use and insurers with access to data that isn't fully leveraged. Neither is behind the telematics adoption curve, but they are short on turning raw data into actionable insight that reduces risk.

Two Sides of the Telematics Data Problem

For commercial auto fleets, leveraging multiple telematics service providers is common. Each provider defines events differently, scores drivers on its own logic, and delivers data in its own format. The result is several partial views of driver risk across separate dashboards, with the work of reconciling them falling to the fleet.

The challenge is exactly what fleets are experiencing, and many are planning to reduce this friction over the next 12 months. Twenty-nine percent of fleet respondents name improving their ability to interpret telematics data as a priority, with 27% focused on improving their ability to act on it.

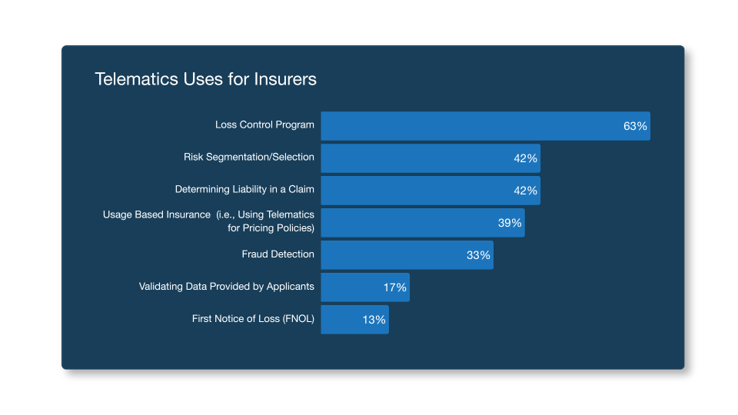
Insurers, as another player in the commercial auto ecosystem, also see the value in telematics data. Loss control is a leading use case for telematics, cited by 63% of insurers, as well as risk segmentation and claims applications. What's missing is the connective tissue between having access to the data and building a program around it for their insureds to use.

"For years, the insurance industry has stayed focused on gaining access to telematics data. That was an important first step, but access alone doesn't improve safety outcomes," said John Barbagallo, strategic advisor at SambaSafety. "The next stage of telematics maturity is helping fleets and insurers act on what the data is telling them. Whether the goal is better loss control or stronger underwriting decisions, value is only created when the data are understood and acted upon."

Insurance companies aren't lacking telematics use cases. On average, they apply telematics data across 2.5 distinct functions, like underwriting or claims processing, making their biggest challenge less about gaining access to telematics data and more about creating value for their insureds.

Applying Telematics to Create Meaningful Value

Insurers and fleets face similar issues from different angles. But the two sides aren't starting from the same place. Insurers possess stronger infrastructure, including loss control programs and expertise in underwriting and claims, while fleets have tremendous amounts of raw data that are difficult to act on.

The opportunity arises when insurers direct this infrastructure to the specific gaps that fleets describe, particularly in interpretation and training to make telematics meaningful for both stakeholders.

Driver training decisions can be a starting point. Telematics events can alert fleet safety leaders to speeding, harsh braking, or distraction alerts, but report insights suggest that only 26% use that information to decide who gets trained and on what. Most fleets deliver training in a broad sense rather than tailoring it to individual drivers who pose a road risk. And the payoff for connecting telematics to training is one that fleets don't shy away from.

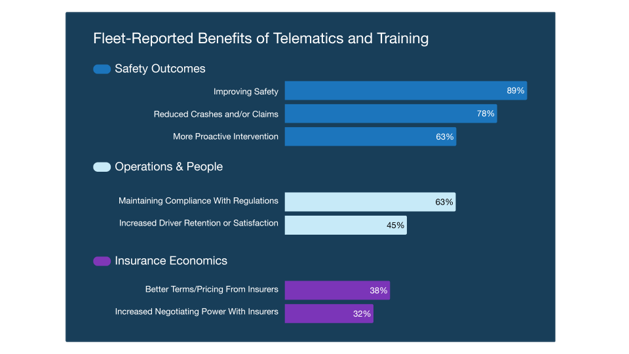
Fleets that pair telematics with structured driver training report fewer crashes or claims 78% of the time, a three-year high, and 89% say their overall safety has improved as a result. For a fix that's specific but straightforward, the report suggests insurers and brokers may be well positioned to help connect the data with loss control or training decisions.

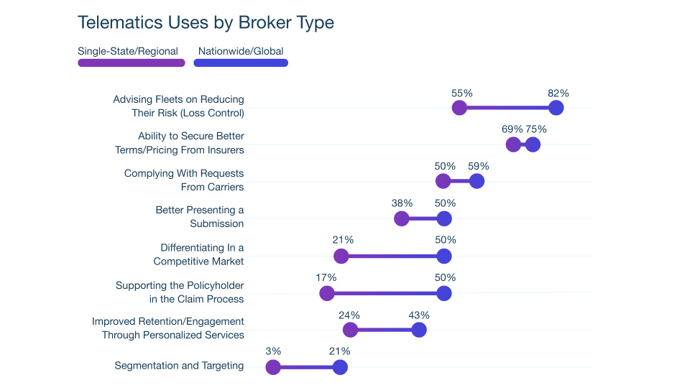
Brokers show how that positioning is still largely unclaimed. Sixty-eight percent of the brokers who use telematics data, according to the report, do so for loss control consulting, up from 45% previously. When taken a level deeper, the use case is more concentrated with national and global brokers, who offer that guidance at 82%, compared to 55% of state and regional brokers.

The difference isn't a lack of access to the same data, but whether that data has been turned into something a client can act on — a shared conversion problem all brokers may experience.

Both insurers and brokers with existing loss control programs can add value to their fleet relationships by using telematics data. Converting telematics events into focused training can provide a measurable ROI that fleets are likely to support, effectively completing the data cycle they currently possess.

The Business Case Beyond Telematics Maturity

When it comes to telematics, the next phase won't depend solely on collecting more information. Instead, insurers and brokers now have a straightforward way to explain the benefits of data and how it informs decisions about training, loss control, underwriting, or risk management.

As telematics adoption reaches maturity across commercial auto, the organizations that create the greatest value may not be the ones collecting the most data. They may be those best able to translate telematics insights into improvements in safety and insurance outcomes.


Arissa Dimond

Profile picture for user ArissaDimond

Arissa Dimond

Arissa Dimond is a lead copywriter of insurance at SambaSafety, a provider of cloud-based risk management solutions for over 15,000 organizations with automotive mobility exposure.

Speed Drives Commercial Insurance Retention

Commercial insurance buyers switch carriers due to slow service and unclear exclusions, not pricing, according to new research.

Insurance

A commercial insurance study published by research agency The AJ Center finds a fundamental disconnect between carrier assumptions and enterprise buyer behavior. While insurance executives frequently attribute client churn to aggressive competitor pricing, empirical data indicates that commercial account defections are overwhelmingly driven by administrative friction, opaque underwriting classifications, and uncommunicated policy exclusions.

The study, titled Mining the Margins: How Enterprise Leaders Optimize Commercial Insurance, analyzed procurement behaviors across business founders, chief financial officers, and operational executives. The findings offer a clear strategic blueprint for carriers, brokerages, and risk advisors seeking to defend high-margin commercial accounts in an increasingly competitive market.

Speed as a Credibility Benchmark

The most striking finding in the report centers on administrative responsiveness. While underwriting teams often spend considerable energy adjusting baseline rates, corporate buyers view operational speed as the primary proxy for provider competence.

According to the data, 73% of commercial account switches are directly triggered by administrative latency—defined as delays exceeding 48 hours for loss-run reports, policy clarifications, or routine Certificates of Insurance (COIs). Pure premium increases accounted for only 27% of carrier switches. Multi-day administrative delays signal an operational breakdown to corporate leaders, creating lingering doubts about how efficiently a carrier will handle a catastrophic claim.

For commercial brokers and agency principals, the takeaway is immediate: standardizing service response times and eradicating administrative delays builds client retention far more effectively than competing on baseline rate cuts.

Exclusion Transparency Outweighs Rate Discounts

In competitive bidding scenarios, sales teams routinely lead with introductory rate discounts. However, enterprise risk managers view unaddressed policy exclusions as far more dangerous to business solvency than higher baseline premiums.

The AJ Center's research demonstrates that corporate decision-makers evaluate policy exclusion clarity and plain language at 4.2 times the weighting ratio of introductory price cuts. When vendors present generic, bloated contracts with hidden carve-outs, experienced buyers systematically disqualify them. A minor savings in annual premium is instantly wiped out if a major operational loss falls into an uncommunicated policy blind spot.

At the same time, traditional underwriting classification frameworks are failing modern businesses. Fully 60% of specialized, hybrid, or tech-enabled companies report receiving inaccurate, bloated policy quotes because legacy underwriters force them into generic North American Industry Classification System (NAICS) risk pools. When carriers fail to adjust pricing logic for modern operational models, high-performing businesses actively seek out specialized brokers who understand their exact risk profiles.

The 10% Rate Hike Trigger and the Evidence Gap

Price adjustments are an inevitability during volatile market cycles, but the manner in which renewal terms are delivered dictates client retention. The report highlights that an unexplained premium increase exceeding 10% creates an 88.2% probability that an enterprise client will shop the open market.

When carriers deliver passive renewal notices 30 days prior to policy expiration without presenting a clear loss-ratio story, corporate buyers conclude that they are subsidizing underperforming risks elsewhere in the carrier's portfolio.

Conversely, proactive providers who engage clients 100 to 180 days in advance achieve dramatically higher retention rates. Extended timelines allow management to audit operational records, resolve open risk items, and present underwriters with pre-packaged, auditable proof.

The study underscores that presenting underwriters with structured operational evidence—such as documented intake protocols, QA checklists, equipment maintenance logs, and safety certifications—yields an 81.2% success rate in avoiding generic market rate hikes. By contrast, companies submitting standard static application forms achieved only a 13% success rate. Handing an underwriter empirical evidence forces them to price the account based on verified risk discipline rather than broad market averages.

Strategic Imperatives for Insurance Service Providers

For commercial carriers, agency principals, and risk advisors, the report's conclusions mark a necessary transition from transactional selling toward operational partnership. High-performing commercial providers are securing long-term account retention by making three immediate operational shifts:

  • Eradicating Service Latency: Treating COI turnaround, loss-run delivery, and policy responses as primary client-retention metrics.
  • Prioritizing Exclusion Clarity: Conducting upfront "exclusion audits" to build immediate trust with risk-averse CFOs rather than relying on price-discount messaging.
  • Packaging Auditable Risk Proof: Partnering with clients three to six months prior to renewal to build structured evidence packages that force underwriters to reward verified risk discipline.

As enterprise decision-makers continue to scrutinize operating overhead, commercial insurance providers who deliver administrative velocity, contractual transparency, and empirical risk packaging will capture and hold the market's most profitable accounts.

The complete 10-point benchmark report, recommendations and full dataset are available on The AJ Center Insights.

How AI Must Change Healthcare Delivery

Healthcare faces a critical choice: responsibly embrace AI to enable proactive, personalized care or risk system collapse under mounting costs and workforce strain.

Insurance

Artificial intelligence (AI) has become one of the most debated technologies in healthcare. Concerns surrounding privacy, cybersecurity, accuracy, bias, transparency, and appropriate oversight are valid and require thoughtful safeguards. However, as healthcare systems face unprecedented challenges, it is equally important to recognize another risk: the risk of failing to responsibly embrace technology that can help transform healthcare delivery.

From Reactive to Proactive Care

The most important role of AI in healthcare is not replacing physicians, clinicians, or human expertise. Its greatest opportunity is to help healthcare professionals work better, not simply work more. By transforming increasingly complex information into meaningful insights, AI can help reduce administrative burden, support clinical decision-making, and allow providers to focus more time and attention on what they do best: caring for patients. More importantly, AI has the potential to help healthcare shift from a reactive model — where care begins after symptoms worsen or disease progresses — toward a proactive model that identifies meaningful changes earlier, supports prevention, and helps individuals maintain better health outcomes.

Rising Costs and Workforce Strain

This distinction is especially important as healthcare systems face growing challenges. Healthcare costs continue to rise, while providers are managing increasing patient demand, workforce shortages, and burnout. According to the Business Group on Health's 2026 Employer Health Care Strategy Survey, employers continue to anticipate significant increases in healthcare costs, creating challenges for organizations attempting to maintain affordable benefits while managing workforce health needs. CMS has also reported continued growth in Medicare spending, including increases in Medicare Part B premiums.

The solution cannot simply be asking healthcare professionals to do more with fewer resources. The future requires tools that enhance the ability of providers to deliver more personalized, efficient, and effective care while helping identify risk earlier and support proactive health management.

A Tool, Not a Replacement

The healthcare workforce is facing a convergence of challenges: an aging population requiring more care, increasing chronic disease burden, rising costs, and provider shortages. A healthcare system built primarily around responding after illness or disability occurs will become increasingly difficult to sustain. AI should not be viewed as a replacement for healthcare professionals, but as a tool that allows clinicians to leverage technology's ability to analyze information while preserving the judgment, experience, and human connection that define quality healthcare.

The future of healthcare requires a fundamental shift: moving from a reactive model, where care begins after disease or disability develops, toward a proactive model focused on maintaining health, identifying risk earlier, and improving quality of life.

The Evolution of Digital Health

Digital health has already demonstrated the potential of this transformation. Telehealth expanded rapidly during the COVID-19 pandemic by reducing barriers to care and allowing more healthcare services to be delivered remotely. However, digital health has evolved far beyond video visits. Today, it includes connected devices, wearable technology, biometric monitoring, artificial intelligence, and data-driven platforms that are changing how healthcare is delivered, managed, and paid for.

The next evolution of digital health is not simply collecting more information. It is understanding what that information means.

AI as an Intelligent Assistant

AI has the potential to interpret complex streams of healthcare data and identify patterns that may not be apparent through traditional assessments. The opportunity is not for AI to independently determine a diagnosis or replace clinical judgment. Rather, AI can serve as an intelligent assistant — helping healthcare professionals recognize meaningful changes earlier, understand individual health trajectories, and make more personalized decisions that move healthcare from reacting to problems toward preventing decline.

Movement as a Health Indicator

This opportunity is particularly important in areas such as musculoskeletal health. Musculoskeletal disorders are among the largest contributors to pain, disability, healthcare usage, and lost productivity in the United States, with annual costs estimated in the hundreds of billions of dollars. These conditions are frequently associated with additional health challenges, including obesity, diabetes, cardiovascular disease, arthritis, frailty, and falls.

Movement is one of the most important indicators of health, independence, and quality of life, yet it remains one of the least continuously measured aspects of healthcare.

Imagine a healthcare system where AI does not simply react when someone develops pain, disability, or functional decline, but helps interpret changes in physiological and movement patterns earlier.

For example, understanding movement requires far more than knowing whether someone is active. It requires understanding how the body functions. How does a muscle activate? Is there altered coordination? Is one muscle compensating for another? Is there reduced range of motion, weakness, spasm, or changes in movement quality?

This is where the combination of AI, biometric data, and wearable technology creates new possibilities.

The Foundation: Quality Data and Oversight

Artificial intelligence is a broad category of technologies designed to perform tasks that traditionally require human intelligence, including recognizing patterns, analyzing information, and generating insights. Machine learning (ML), a subset of AI, enables computer systems to learn from data rather than relying only on explicit programming.

However, the value of AI depends on the quality and relevance of the information used to train these systems. In healthcare, meaningful AI requires carefully selected data, appropriate clinical context, and responsible oversight.

One of the most important approaches within machine learning is supervised learning, where algorithms are trained using structured data to identify patterns and improve performance. In healthcare, this means understanding the biological and functional characteristics that truly matter.

A system designed to understand human movement must account for the complexity of the body itself — including muscle activation, biomechanics, coordination, and individual variability.

A Partnership Between Human and Artificial Intelligence

The future of AI in healthcare should not be defined by replacing human expertise. It should be defined by enhancing it.

For insurers, employers, healthcare systems, and patients, the opportunity is a transition from reactive healthcare risk management toward proactive health intelligence.

The question is no longer whether AI will influence healthcare. It already is.

The question is whether we will use it responsibly — with appropriate safeguards, clinical oversight, and a focus on improving outcomes.

The greatest opportunity may be creating a partnership between human intelligence and artificial intelligence: combining clinical experience, compassion, and judgment with technology's ability to analyze complex information at scale.

Healthcare does not need less human involvement. It needs better tools to help humans deliver better care.

How to Find the Right Agency Niche

Independent agencies are shifting from generalist models to specialized niches, but success requires matching passion with carrier appetite and operational capacity.

Insurance

Here's a question agency owners ask me constantly: Which niches are gaining the most traction? It's one of the hardest questions to answer, because the right fit looks different for each agency.

Consider an agency specializing in commercial property. The opportunity can vary significantly by geography. For agencies in regions where catastrophic weather events occur infrequently, such as Vermont, Maine, or Arizona, the opportunity can be extremely profitable. The opposite can be true in Colorado, Florida, or California, where convective storms or wildfire risks loom large.

Geography, however, is just one of many considerations. Carrier appetite, competition, market size and an agency's ability to service a class of business all influence whether a niche offers true growth opportunities or a costly misstep.

The Rise of Specialty Agencies

The move toward specialization has flipped agency structure on its head. Previously, most independent agents were generalists, with some adding a small niche to their offerings. That meant their market was limited by geography. Agencies traditionally served their immediate neighborhood and sometimes reached into the next town or county.

Today, some independent agents have made specialization the largest part of their business while maintaining a small generalist component. This approach lets agencies focus on specific markets and expand their book of business beyond geographic boundaries, provided the agency can not only meet statutory requirements to write business, but also meet carrier requirements for appointments and be able to appropriately service their client base.

To see how, consider the owner of a crane service business, which is a high-risk, hard-to-write category. That business owner will look online to find an agent who specializes in crane and rigging insurance, regardless of their physical location, so they can secure the most comprehensive coverage. If your agency fits their needs, you stand a decent chance of winning their business.

Weighing the Pros and Cons

Specialization, when done properly, brings numerous benefits. Marketing becomes easier because you're targeting a specific niche. Staff hiring and training are simplified because agency owners know the exact skills and expertise they want to attract. Processes become streamlined, boosting agency profitability.

Owners of niche businesses also form tight relationships. When a restaurant owner finds an insurance agent who delivers value beyond writing a policy, they will recommend them to other restaurateurs.

One risk of specialization is defining the niche too narrowly. For example, an agency may pursue only preferred accounts or rely exclusively on excess and surplus (E&S) placements. Focusing only on preferred risks can mean turning away potentially good, long-term clients because they do not qualify for standard markets today. Conversely, an agency that writes only risks eligible for E&S coverage could lose clients once their risk profiles improve, and carrier appetites change. A sustainable specialty practice should be prepared to serve clients as their risk profiles, and available market options evolve.

Choosing the Right Niche

Differentiating your agency in a specialty line is about servicing your clients, not just writing a policy. Agency owners seeking to break into a niche should consider these four crucial factors.

  1. Select a niche you're passionate about. Do not pick a specialty solely because you think it will make your agency more profitable. Instead, choose based on your personal interests. An agent who tries to break into transportation insurance but knows nothing about trucking or logistics will struggle to convince clients they're an expert in the space. They'll also get burned out fast.
  2. Evaluate your carrier partners. You may be a self-proclaimed foodie, so restaurants might seem like an ideal niche. If your carrier partners aren't interested in writing restaurant risks, however, you will not be able to match clients with the coverage they need. Look instead at niches that your carrier partners want to write.
  3. Review market availability. Broad niches aren't always the best niches. A specialty like cyber insurance is likely shared by multiple agencies, making it harder for your business to stand out. A better approach is to pick a narrower niche with less competition.
  4. Assess your path to prospective clients. Consider whether you already have relationships, referral sources, or a credible presence within the target industry. An existing concentration of relevant clients or local businesses can provide a practical entry point, while a niche with few reachable prospects may require a much greater investment in expertise, marketing, and relationship development.
Avoiding a Common Mistake

A growth-focused mindset is an asset, but it can become a detriment when agency owners choose niches that overwhelm the capabilities of their business.

A one- or two-person agency pursuing clients worth $1 million in premium will need to compete against large national brokers with teams of a dozen or more staffers dedicated to a single account. Smaller agencies with limited human resources must also be realistic about their ability to service high-risk accounts that will require such a galactic amount of work.

Using Technology as a Differentiator

Agencies seeking to break into niche markets should use technology as an enabler. Having a customer relationship management (CRM) platform is critical. So are digital tools that empower staff to ask clients deeper questions so they can obtain the information needed to write business more efficiently. Agencies that can move fast while obtaining higher-quality, detailed information from clients will deliver an enhanced customer experience.

One platform available to SIAA members is AgencyIQ, a tool we built to help make life easier for agency principals and their staff. The platform uses predictive analytics to scan a book of business and identify cross-sell and upsell opportunities to increase premium per client, close coverage gaps and retain more clients. Tools like these give agencies the data they need to grow a niche deliberately.

From extreme sports and cannabis businesses to specialized commercial real estate and inland marine risks, agencies have plenty of niche options to choose from. The key is finding one that matches your personal interests and your agency's capabilities. Do that effectively, and you'll chart a path to sustainable business growth.


James Keane

Profile picture for user JamesKeane

James Keane

James Keane is the vice president of national sales for SIAA – The Agent Alliance.

He serves as the liaison between SIAA and its Strategic Master Agencies’ (SMAs) leadership, helping them maximize recruiting efforts, organic growth programs, agency development and member engagement. 

A Novel Approach to Preventing Water Damage

LeakBot provides a sensor that detects tiny, even hidden leaks so they can be repaired months before they would cause significant damage.

Insurance
Paul Carroll

As part of our push for insurers to increasingly adopt a Predict & Prevent model, I’ve been tracking water sensors for a long time. Leaks cause so much damage to homes. The sensors I’ve tracked have improved a lot, getting ever closer to the point where they make clear economic sense—where the savings from prevention exceed the cost of deployment. You have a different approach that has convinced a lot of insurers that you’ve passed that tipping point. 

To start us off, would you tell us what your approach looks like?

Craig Foster

We work with 28 insurers around the world. All our partners offer the sensor for free. If you say “yes” to an agent or click on the button, the device arrives in the post. The sensor has a clip on the back, and you attach it to your home’s main water pipe, near the shutoff valve. It takes a couple of minutes. 

That unit can detect a leak anywhere on the main water system, and it's sensitive down to about a teaspoon of water per minute—we say five milliliters per minute in the U.K. It's about 100 times more sensitive than an ultrasonic sensor, which is the next best approach without physically cutting the pipe.

If we detect a leak, we'll tell you what to do through the app. If it looks like you've got a hidden problem, we'll send a LeakBot plumber to the house. And there's absolutely no charge for that—it's all paid for by the insurance company.

Paul Carroll

A lot of leak sensors shut off the water automatically when they detect a problem. Why do you take a different approach?

Craig Foster

This is a key point. We're detecting really small leaks before they've had a chance to build up and cause a big problem. 

The first response is often what you've said, Paul: "Wait a minute. Don't you need a shutoff valve to stop the damage?" But the important insight is that plumbing rarely goes from being fine to a sudden high release of water without any problem in between—unless there's some kind of DIY mistake or a pipe freezes and thaws, and there’s a break. 

In those instances, we'll alert the customer and say, "Hey, water's running. Do you know what it is?" But we deliver the ROI for partners by catching leaks much, much earlier—months earlier. Leaks start very small, with drips, then get exponentially worse over time, but you don't know about it as the homeowner because the leaks are hidden. They're in cavity walls. They're in ceilings. They're down the back of cupboards. They're in places where you just don't see them.

Carriers will tell us, "We get a lot of claims on water heaters. They’ll fail and suddenly leak gallons and gallons of water in a basement, and it's a $40,000 claim. You wouldn't be able to shut the water off in time." But we’ll show them that that sort of problem is a really high percentage of what our plumbers fix every day.

We'll get alerted to a leak, go to the home, and find a pinhole leak on the pipe into the water heater—sometimes with just a bit of green calcification and a tiny drip. It could keep getting exponentially worse until there is a faster flow, and then the pipe pops. That would normally be the first time the homeowner knows there’s a problem—but we’ve fixed it. 

In the U.S., it's almost like carriers have been trained that a shutoff valve is the gold standard. They’re expensive, so carriers will sometimes talk to us as they look for a cheaper alternative. But we convince them that we’re not just more cost-effective, we’re a better solution.

Paul Carroll

Once you know a home is leaking a teaspoon of water a minute, how do you find the problem? Homes are big places.

Craig Foster

If we're detecting a small leak, we'll alert the customer and guide them through steps to check common causes. Maybe they’ve been in the garden and haven’t completely turned the hose off. Or they’ve had guests, who’ve used a bathroom they don’t use all the time, and the tap is dripping. 60% of the time, customers solve the problem themselves.

If the customer says, "I can't see what it is. Can you help me?" then we suggest booking one of our plumbers. The genesis for the company was actually as part of a home services group in the U.K. that also has a big business in the U.S. called HomeServe. So we have a heritage in plumbing and brought a lot of expertise with us when we spun out. 

Our plumbers use thermal imaging cameras, and we have patented technology that pressure tests the property. The plumbers will find and fix a problem, then run the test again. Sometimes they fix one thing, sometimes two—I think the record is 11 things, in a big house in Virginia. They'll keep going until the property is leak-free. 

We train our plumbers to think like adjusters. They take pictures of what they fixed, before and after. And let’s say they fix a hidden feed into a tap or a toilet in an upstairs bathroom—they go to the room below and take a wide photograph of that space. All that information goes into partner portals so our insurance partners can review the evidence of the risks we're removing from properties. If you show these reports to anyone in the claims team, they recognize them instantly.

The other day, someone at a carrier partner who used to work in claims looked at a photo of a basement where we fixed a leak and said, "Oh, man, that would have been a $30,000 claim." Why so expensive? He said, "Look at the floor—it's continuous all the way through that finished basement. If that gets damaged, even a small section, we have to replace the whole floor."

Even before we get to the statistical evidence about the ROI we provide, this all feels right to the claims guys. We’re fixing the things that definitely do cause them claims.

Paul Carroll

The economic argument for prevention is always complex. Homeowners save on the deductible and avoid enormous hassle, while the carrier saves money by preventing losses and presumably improves retention by increasing customer satisfaction. But how do you assemble those four, sometimes amorphous benefits into a case that convinces a carrier to distribute leak detection devices for free?

Craig Foster

We have a very simple proposition. Our solution delivers a straight return on investment on the claims saved versus the cost of deployment. And we make that return easy to measure.

We charge a single fee for an active device in an insured home: $60 a year. That fee includes everything. There's no extra hardware fee. There's no shipment fee. There’s no fee for customer support, including us sending a plumber into the home as many times as we need to get that property leak-free. The carrier only pays for the devices that are installed. If you ship 100 to your customers, and 70 get installed, we take the hit on the other 30.

So all you need to know is if you're going to save more than $60 in underwriting costs a year per home.

This is really the nub of our recent white paper. We've proved, time and time again, based on a highly statistically relevant sample, that we can reduce the frequency of leak claims by 60%. In the U.S., on average, that delivers a 40% return on investment, and that’s just based on frequency. There is a severity benefit, too, because we tend to take out the bigger claims. Customer satisfaction is also fantastic. 

Nevertheless, we put all that to the side because the ROI case is clear and easy to measure.

Paul Carroll

I found the analysis in the white paper to be quite sophisticated. For instance, it takes into account the bias that can occur during pilot programs due to self-selection—something many companies conveniently ignore. It also acknowledges that claims actually increase early on as previously unknown problems are discovered and solved, before declining over time. But you’ll keep learning as you continue to scale, so I wonder both where you are now and where you expect to be in the next two or three years.

Craig Foster

We're now up to 360,000 exposure years of data—devices active in homes where we've been consistently sending plumbers and generating thousands and thousands of claims mitigation reports. We ask partners for as much information as they can provide about claims still being experienced by the cohort with LeakBot sensors, and we’re iterating to make the system better. 

The biggest issue, by the way, is with customers who got an alert but didn’t think there was a problem and didn’t call out our plumbing service

Paul Carroll

I imagine you see some interesting patterns.

Craig Foster

We've learned a lot about different cohorts and different countries. For example, pipes in 1970s Denmark are particularly high-risk because of the type of plastic used. Victorian properties in the U.K. are very risky because they've got old copper plumbing and lots of bathrooms. We work with NFU, the National Farmers Union, and we're fixing leaks in these huge farmhouses in the middle of the countryside. They've all got like six bathrooms, and the plumbing is 100 years old, so they're just full of leaks.

Paul Carroll

Have you explored joint marketing opportunities with other companies in adjacent spaces, beyond your existing carrier partnerships?

Craig Foster

Bob Marshall [CEO of Ting Labs, whose device detects electrical problems that can cause fires] and I have met many times and exchanged notes a lot. There are lots of synergies. 

For one, Bob’s success with Ting has changed the mindset of carriers. We're moving past, “Predict & Prevent sounds like it might be a good idea, but will it really work? Let's maybe do a small test." The mindset is now, “Predict & Prevent is the future.” It's now a question of what the real solutions are that actually deliver a return on investment.

Our partners have found that if a customer has already installed a Ting, they don’t even need to ask if the customer would like a LeakBot. They just send one, and we get the same installation rate as through the opt-in process. 

Ting is a great solution, and their success helps us, as well.

Paul Carroll

Any final thoughts?

Craig Foster

The question from U.S. carriers was, “You're a U.K. company. Can you really get this working in the U.S.?”

We're now in 26 states, and we've got the actuarial evidence in the U.S. We're not reliant on the European data, although it's, funnily enough, remarkably consistent.

So we very much see that tipping point, and the U.S. is the key for us in terms of the scale of the opportunity. That's the focus for the business going forward. 

Paul Carroll

Thanks, Craig. 

--

Download the 2026 Leakbot White Paper

Sponsored by LeakBot


LeakBot

Profile picture for user LeakBot

LeakBot

LeakBot is the only end-to-end IoT solution protecting homes from water damage—one that begins with leak detection and can end with a free repair. Backed by more than 10 years in business and 29 patents, a single self-installed device clips onto the home's main water supply line, monitoring water usage and detecting micro-leaks as small as one teaspoon per minute. When a leak is detected, the homeowner can book an appointment for LeakBot's trained employee plumbers to visit, locate, and repair it using specialty equipment — at no additional cost to carrier or homeowner. Homeowners consistently recognize LeakBot's value, reflected in a Net Promoter Score of 82/100 and Customer Satisfaction Rating of 4.9/5. That impact is especially powerful when a hidden micro-leak is found and fixed before it becomes a claim—or a costly plumber bill. That's #PredictAndPrevent in action.

Please connect with us: 


A Scary Stat for Insurance Brands

As AI search reshapes buying behaviors, Flo, Mayhem, and other big insurance brands likely will lose some of their sway.

Image
Insurance

If you watched anything close to as much football over the weekend as I did, your brain is swimming with images of Jake from State Farm, the GEICO gecko, and so many more insurance mascots. Sing after me, "Liberty, Liberty, Liberty... Li-ber-ty."

But a stat and some analysis from an article last week suggests strongly that their heyday may be, if not ending, then at least diminishing. Brands not backed by hundreds of millions of dollars of advertising may suffer even more in the age of AI search.

Companies need to rethink how they market online.

Let's have a look.  

The stat that caught my eye relates to retail. BrandRank.AI tracked 4.3 million AI recommendations across the major AI models from January to July  and found that the share captured by major brands fell from 97% to 94.3%, while private label, retailer own-brand programs, and generic ingredients gained those 2.7 percentage points of the share of recommendations. 

But I think the finding also relates to insurance. So does the founder of BrandRank, who, as it happens, I interviewed about insurance marketing a year a half ago. The founder, Pete Blackshaw, told me:

"AI is becoming the new purchase funnel.... Everyone is going to AI for everything now - what product to buy, how to use products. This has massive implications for businesses. 

"Search 1.0 is a $250 billion industry, and Gartner predicts that by the end of 2028, half of it will shift into what I call the answer economy, based on AI-based search. Even if only 10% shifts, that's a massive change.

"For brands, it's critical to understand what shows up when you type in your name and why. Who's getting exposure? What are the consequences? 

"It's very tricky, because companies spent 25 years trying to figure out how to become one of 10 blue links in Google searches. If you didn't like the results, you could buy an advertisement. Now search provides one blended response.... Either you're in the response the AI prepared or you're not, and most of the time, you're not."

This June, Riv Arthur wrote for us about AI search's impact on marketing and, in his distinctive way, said:

"The question is whether your business is legible to the machines that will increasingly decide who gets recommended, who gets trusted, and who gets the transaction.

"Most businesses, if they're honest, are not legible.

They're running on claims systems from 2009, CRM platforms that don't talk to each other, PDFs that contain institutional memory no one has ever indexed, and tribal knowledge sitting in the heads of people who are 18 months from retirement....

"An AI agent deciding which carrier to recommend, which doctor to surface, or which vendor to integrate is going to favor organizations whose operations are coherent, structured, and machine-readable. It has no patience for ambiguity. It won't retry. It won't call customer service. It will simply move on to the competitor whose data makes sense.

"Which means a structured operational model isn't just an IT project anymore. It's the difference between being findable and being invisible in a world where the searcher is a machine with no tolerance for mess.

His analysis doesn't leave much room for marketing through building a brand through cute advertising, does it?

Earlier this month, Kevin Walsh provided us some research from his firm, Brainpan AI, that shows that, in his words, "a new decision layer is forming" above the traditional sales funnel. He wrote:

"Buyers, agents, brokers, and business owners increasingly ask AI platforms to compare carriers, explain coverage, and recommend providers.... A carrier can remain commercially large, rank well in traditional search, and still be absent when an AI system constructs the shortlist. Its legacy presence has not disappeared—but it can be bypassed at the moment of consideration....

"Farmers illustrates the downside. In Auto, the carrier held roughly 3.6% of the real market, according to NAIC data, yet registered approximately 0.05% of measured AI visibility in [Brainpan's] study—functionally absent relative to its commercial position. Amica illustrates the opposite pattern. Its Home AI visibility reached 7.6% against approximately 0.7% real market share, an overrepresentation ratio of about 10.8 times."

The AI engines are just making recommendations, not doing the actual purchasing — at least for now — so there's still room for those ear worms from TV ads to influence buying, but the online marketing competition is clearly changing.

If my Steelers lose to the Brownies on Thursday night, I'll probably boycott football next weekend, but even if I subject myself to another onslaught of insurance ads, the cute branding bits will keep making less of an impact on me and everyone else in the age of AI search.

Cheers,

Paul


To Deploy AI or Not to Deploy AI

Companies rushing to deploy generative AI must assess 12 critical factors across suitability, risk, operations and transformation before implementation.

Insurance

The enterprise conversation on generative and agentic artificial intelligence (AI) is shifting from exploration to execution. Discussions are no longer focused on possible use cases, pilot success, output accuracy, or potential benefits. Instead, attention is turning to questions such as: What is the optimal deployment approach? How much autonomy should be granted? What are the quantified benefits and risks? How can human oversight prevent those risks? How can organizations comply with the regulations? What is the expected return on investment? What is the break-even period?

However, the deployment decision, contrary to conventional thinking, is neither linear nor binary. The reason is simple: all business processes comprise a sequence of heterogeneous activities performed using a combination of traditional software code, rule engine, machine learning, and human judgment. Not all activities benefit equally from generative AI or present the same level of risk. Companies are beginning to realize that the deployment of generative AI is not merely a technology implementation, but also a significant organizational transformation involving people and processes.

This article presents a decision framework built around four lenses and 12 evaluation axes to help companies determine whether to deploy generative AI in a business process. While companies may already be conducting this analysis, the framework provides a methodical approach to the decision.

Where to begin?

The journey from pilot to production begins with the key questions: where and how to begin. While companies may currently be exploring some aspects of AI in simple, low-risk use cases, they know that, in due course, they must expand across a wide spectrum of capabilities and processes. The lingering dilemma is whether they should begin with an enterprise-wide IT capability-building exercise or focus on specific business outcomes.

IT-led capability-building prioritizes creating centralized infrastructure, foundational model access layers, and unified data pipelines before business applications are deployed. This approach suits companies with a long-term capability-building strategy; however, they are currently bogged down by low AI and data maturity and high technical debt. It requires significant upfront investment and can delay time-to-market for business units. The benefit is that a scalable AI foundation reduces the cost and effort of future deployments.

A business outcome-based approach, on the other hand, identifies high-value business challenges and deploys targeted solutions. This path is typically chosen by companies facing competitive pressure and the risk of falling behind in AI adoption. The advantage is that it attempts to deliver rapid validation of business value. However, when a company lacks a baseline level of AI and data maturity, this band-aid approach can deliver less-than-optimal benefits and increase technical debt.

Given that the current AI wave, despite being just over three years old, took companies by surprise with its rapid emergence and exponential growth, many were left unprepared, with technology environments that were not ready for AI. As a result, they continue to carry a significant legacy footprint, fall short on AI and data maturity, and face pressure to accelerate AI adoption. Consequently, despite its limitations, the more commonly adopted approach is often short-sighted and business-outcome-driven.

To Deploy or Not?

Regardless of the approach, the central question companies face is whether AI should be deployed in a specific process or activity. As this is neither a linear nor a binary decision, answering the question requires an assessment of both business and technological viability. The assessment can be structured through a framework (see Figure 1) comprising four lenses (suitability, risk, operations, and transformation) and 12 axes. While each lens defines the dimension being assessed, each axis represents a specific aspect that influences the deployment choice.
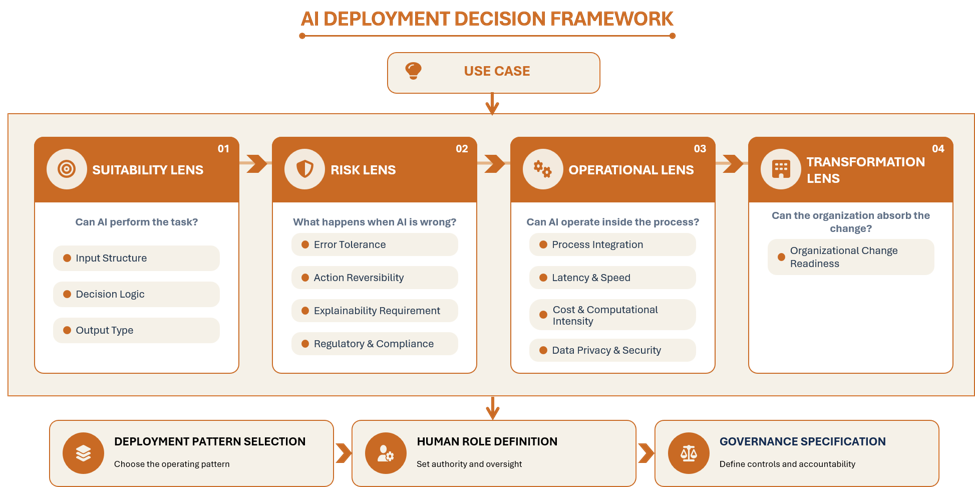
Figure 1: AI Deployment Decision Framework

Suitability Lens

The focus of the suitability lens is to analyze a task and determine whether AI can perform the task technically. This lens examines three aspects of the task, namely input structure, decision logic, and output type. It begins by ascertaining whether the task is a rule, a prediction, judgment, or generation problem. This classification helps identify the most appropriate approach to be deployed, such as software code, rule engine, machine learning, human judgment, or generative AI.

Input structure.

This axis measures the degree to which the inputs to process steps are predictable, standardized, and machine-readable. If the input is fully structured, it favors code or ML, and generative AI is probably unnecessary. If it is unstructured, generative AI becomes the primary candidate for interpretation and extraction and is worth evaluating, subject to the other axes.

Decision logic.

This axis deals with the style of reasoning or rules needed to process inputs into outputs. The implementation approach depends on the type of decision required. For example, deterministic decisions are best handled through code and rules, pattern-based decisions through ML, and creative tasks through generative AI with human review. Decisions that require judgment should remain human-led, with generative AI playing a supportive role. The ground rule is to never substitute a probabilistic system for a deterministic requirement.

Output type.

The structure of the output type is an important parameter in deciding the approach used to produce it. Binary outputs (accept or decline, approve or deny) are best suited to code or traditional ML. Numerical risk scores or rankings (risk score, fraud probability, severity estimate) are naturally suited to traditional ML with code-applied thresholds. Structured data outputs (extraction, form population, data transformation) can be handled with code, ML, or generative AI. Unstructured outputs (free-text narratives, summaries, correspondence) are best suited to generative AI.

Risk lens

The focus of the risk lens is to assess the capability of the organization to safely tolerate AI in a specific task. This lens examines four aspects of the task, namely error tolerance, action reversibility, explainability requirements, and regulatory and compliance exposure. It begins by answering the question, "What happens when AI is wrong?" to determine the consequences of AI failure. This helps identify whether autonomous execution is prohibited or permitted and, if permitted, the necessary controls to mitigate risk and maintain compliance.

Error tolerance.

Error tolerance defines the level of error an organization can accept for a task before the consequences become unacceptable. Steps with zero error tolerance, such as regulatory violations, safety controls, and financial calculations, must always be correct. These tasks are unsuitable for probabilistic systems as final decision-makers, making deterministic controls, code-based execution, and human oversight the preferred approach. Tasks with moderate error tolerance can accommodate errors if they are detectable and corrected before causing material impact. These tasks are suitable candidates for generative AI when supported by human review and exception-handling workflows. Tasks with high error tolerance have limited consequences and can be corrected easily, allowing generative AI to operate with greater autonomy while risk is managed through periodic human monitoring.

Action reversibility.

Action reversibility assesses whether the consequences of an AI error can be undone once a task has been executed. Before approving any AI design for a process step, assess whether the actions triggered at that step are reversible and the impact that irreversibility would cause. Irreversible actions in high-risk or high-impact tasks require near-zero error tolerance from the AI system and human approval. In these cases, human approval must not be treated as an optional escalation path but must be built as a mandatory step in the workflow before the action is taken.

Explainability requirement.

Explainability is the ability to reconstruct, interpret, and defend a decision after it has been made. In many business contexts, this requirement is not merely technical but also a legal, regulatory, or ethical obligation. For probabilistic systems, explaining intermediate reasoning requires significant technical design effort, which can result in slower processes. System design therefore involves a trade-off between speed and explainability. Based on the business context, a system can be designed to provide explainability at the overall action level rather than the step level. If every element of a process must be fully traceable, it generally favors code, constrained ML, and human review. Where the requirement for explainability is partial or low, and only a rationale rather than full reconstruction is required, generative AI is appropriate.

Regulatory and compliance exposure.

Regulatory and compliance exposure assesses the extent to which a process step is subject to legal, regulatory, or compliance obligations. These obligations must be mapped before designing the technical architecture. Some process steps carry direct regulatory exposure, produce outputs subject to adverse action disclosure, or create systemic regulatory risk. An error at these steps does not simply cost money or compromise customer experience. It creates legal liability, triggers regulatory examination findings, and may require remediation. This axis must be evaluated independently of explainability and error tolerance because its consequences are qualitatively different. If the step has no direct regulatory exposure, it offers broader latitude for AI. However, when there is direct regulatory exposure, AI may assist; however, deterministic audit trails, human accountability, and regulator-ready documentation are mandatory.

Operational Lens

The focus of the operational viability lens is to assess whether AI can operate efficiently within a specific task or process. This lens examines four aspects of the task, namely process integration, latency and speed, cost and computational intensity, and data privacy and security. It determines the practicality of deploying AI in a production environment. This helps identify if the solution is limited to a pilot, production-ready, scalable at the enterprise level, or economically infeasible.

Process integration.

Process integration measures how closely a task is connected to other workflows, systems, and external actors. An isolated task has different requirements from one that is part of a larger process, where it may need to trigger downstream actions, interact with multiple systems, or coordinate with actors outside its own boundary. Unlike the other axes, process integration does not distinguish between code, traditional ML, and generative AI. In all three cases, the workflow path is predefined, including the systems involved, the sequence of steps, and the decision rules.

This axis becomes more important with agentic processes, where the path is dynamic and determined at runtime. Instead of following a fixed sequence, the process must choose the next step and may require coordination across multiple systems, APIs, approvals, and handoffs based on intermediate results. Such workflows require an orchestration layer that determines the execution path before any individual step is performed.

Latency and speed.

Latency and speed requirements assess the time sensitivity of a task and the speed at which an output is required. Regardless of how well a task scores on other axes, tasks that require real-time or sub-second execution are generally better suited to traditional code or machine learning. Generative AI may be unsuitable for such tasks unless the deployment is specifically engineered for sub-second response times and the model is heavily constrained. In production environments, token-by-token inference, multi-step reasoning, and tool calls introduce latency. When tasks can be executed synchronously within acceptable response times or asynchronously, generative AI and agentic AI become more practical options.

Cost and computational intensity.

Cost and computational intensity assess the economic viability of AI deployment by evaluating the cost per transaction and the overall budget impact of operating the solution. A technically effective approach that is uneconomical at the required scale is not a viable option. The cost assessment should also cover governance, verification, exception handling, and the continuing operational overhead of maintaining the system. It should also account for common platform investments that are incurred upfront and can be shared across multiple use cases. As a rule of thumb, high-volume tasks with already low transaction costs often make generative AI economically unattractive, even when it is functionally suitable, because token-based processing and multi-step reasoning can increase operating costs beyond the value delivered.

Data privacy and security.

Data privacy and security assess the sensitivity of the data involved in a task and the level of privacy, security, and compliance controls required for its use. This axis influences which AI infrastructure is appropriate, not whether AI should be deployed. The nature of the data should be classified before selecting the deployment architecture. Public or non-sensitive data provide the broadest latitude for AI approaches and hosting models. The use of internal intellectual property, highly regulated data, or personal data does not automatically preclude AI adoption. Instead, it constrains the choice of infrastructure and controls. While public or weakly governed AI environments are generally unsuitable, such use cases require enterprise-controlled or private deployments that adhere to private-by-default architectures, deterministic controls, data-masking pipelines, and human accountability.

Transformation Lens

The focus of the transformation lens is to assess the organization's ability to adopt, operate, and sustain an AI solution. This lens examines the factors that determine the level of organizational, process, and capability change required to support the solution. It begins by answering the question, "Can the organization operate the solution after deployment?" and assesses the level of organizational change required. This helps identify whether the solution fits the existing operating model, requires targeted process and capability changes, requires enterprise-wide transformation, or is not viable because of organizational constraints.

Organization change readiness.

Organization change readiness assesses the extent to which an organization is prepared to adopt and operate an AI solution. It is based on the premise that technical suitability alone does not guarantee success. To score highly on readiness, an organization must have executive sponsorship, a well-defined AI strategy, clean data, skilled practitioners, governance infrastructure, process maturity, and the change management capacity to absorb a new operating model. Regardless of the other lenses, organizations that score low on readiness may be unable to deploy AI successfully. It is suggested that organizations scoring low on change readiness address foundational gaps before pursuing major AI initiatives.

The Decision Path

Applying the four lenses and 12 axes without a clear decision sequence can create analysis paralysis. The journey starts by selecting a priority process for which the organization is actively considering AI investment and mapping each step in granular detail. The override axes, namely latency and speed, action reversibility, regulatory and compliance exposure, and data privacy and security, should be assessed first because failure on any of these aspects can eliminate an otherwise attractive option regardless of how well it performs on the remaining axes. If a step passes assessment against the override axes, the remaining axes should be evaluated individually. After documenting the axis profile and recommendation, the human role should be defined, ranging from no human involvement to a human acting as the sole decision-maker. Finally, governance specifications should be established for every step where AI is deployed.

The enterprise narrative around AI has assumed that technological capability creates an obligation to automate. This assumption is now demonstrably incorrect. As a ground rule, the principle of correct design is to apply the simplicity principle by choosing the simplest approach that can meet the business requirement for each step. Escalation from traditional code to ML to generative AI to agentic AI should be made only when the simpler approach genuinely cannot do the job and the step genuinely requires the additional capability. Solution complexity is a cost, not a benefit. Every additional layer of technical complexity in a process design adds cost, introduces failure modes, increases governance burden, and makes the system harder to understand, maintain, and improve.

The 12-axis framework guides AI enthusiasm and forces organizations to ask, at every stage of decision-making, "What does this step need?" It forces the answer to be specific, not aspirational. It then directs that answer toward the simplest and most efficient approach, rather than the most fashionable one.