Download

What the Metaverse Debacle Should Teach Insurers

Even if new technology is great — and the Metaverse is far from great technology — it has to fit into workers' and customers' existing routines

Image
purple city in the metaverse

Four years ago, days after Mark Zuckerberg debuted the Metaverse, I wrote a Six Things commentary that began: "The vision of a metaverse laid out by Mark Zuckerberg last week is bonkers. Nutso on steroids. It won't be realized in my lifetime, yours or his, even if some of the wildest claims about longevity come true and we all live to be 150."

Since then, the Metaverse group within the company Zuckerberg renamed after what I referred to in that commentary as "a fever dream for gamers" has racked up $70 billion in losses, and Bloomberg and the New York Times reported last week that he is planning to cut staff by between 10% and 30%, possibly in January.

So, in retrospect, I'm just sorry I pulled my punches. :)

Trashing the Metaverse on Day One was not a remotely hard call, because it violated one of the cardinal rules of innovation: As much as possible, an innovation has to fit within the existing work environment or lifestyle of the prospective user. Yet the Metaverse required radical changes in how individuals interact — with, as far as I could discern, no appreciable benefits.

It's worth taking a minute to look at where Meta went wrong, because the mistake is awfully tempting for all of us. 

The Metaverse assumes that people want to live online a huge percentage of the time. You have to produce an avatar to act as you and learn all sorts of new behaviors to interact with other avatars and with everything else that populates the online world. (I tried this a couple of years into the Metaverse experiment, courtesy of a consulting firm that was enthusiastic about its prospects, and it was still quite hard just to maneuver, let alone to talk with others' avatars or to conduct a transaction.) 

The rule of thumb in Silicon Valley is that an innovation has to be 10 times better than anything it is intended to replace, yet the Metaverse was far less useful than the Zoom calls and other technologies we already used, while requiring huge changes in people's routines. 

Apple made a similar mistake with its Vision Pro virtual reality device — and yes, I trashed that, too, right after it was announced at the beginning of last year. I wrote: "There's simply no reason to strap a 1 1/2-pound device to your face (nearly the weight of a quart of milk) and put a three-quarter-pound battery in your back pocket so you can type with your two index fingers in mid-air while strangers or officemates gawk at you. Not when some combination of today's laptops, tablets and phones will do just fine."

The Vision Pro has been a dud for precisely the same reasons the Metaverse has flopped. 

By contrast, Metaverse has a budding hit with the AI it has built into Ray-Ban "smart display" sunglasses. The capabilities are still pretty limited but are enough to get started: You can use voice commands to snap photos, record videos, send messages, make calls, and ask questions of Meta's AI. And Meta isn't asking customers to do anything out of the ordinary. Just about everybody wears sunglasses. Besides, Ray-Bans look cool.

When you look at the history of major technology innovations, they almost all replace something similar. Smartphones replaced iPods, which replaced the Walkman, which replaced transistor radios. Smartphones also replaced early cellular phones, which replaced hardwired phones in homes. There was almost no need for changes in behavior; everything just became easier and better.

Note that once you get a new device into people's lives, like a smartphone, you can start to get them to change behaviors that have nothing to do with the original purpose — when I first saw a smartphone demo, some 25 years ago, I had no idea I'd be doing my banking and shopping on a phone, or listening to podcasts on it and having it monitor my driving.

The insurance industry seems to mostly get this principle, that innovation has to fit into existing behaviors. That's why we're seeing so many dashboards that incorporate the advances in generative AI, gathering information and making evaluations in the background and presenting them to underwriters, claims professionals or agents and brokers as part of their normal workflow. I think chatbots were initially seen too much as a standalone technology but are now being integrated much better into the customer experience.  Whisker Labs' Ting device has taken off because a customer simply has to plug it into a wall socket to have it monitor for electrical issues and prevent home fires. Roost built another Predict & Prevent business by offering batteries that can be plugged into existing smoke detectors and ping a customer's cellphone when an alarm sounds, in case they aren't at home to hear it.

Still, the principle is worth keeping in mind, because the temptation — which I've witnessed across industries in my decades of writing about innovation — is to think that what you're doing is so useful that people will adapt to you, freeing you from worrying about how to adapt to them. 

If Meta and Apple can make that mistake, you can, too.

Cheers, 

Paul

P.S. While I've patted myself on the back for dumping on the Metaverse and Vision Pro right out of the gate, I need to acknowledge that I've made mistakes, too. While I can't recall a time when I savaged an idea or product and been wrong, I've certainly been too optimistic about how quickly change would happen. I try to live by the Silicon Valley dictum that "you should never confuse a clear view for a short distance," yet, well, I sometimes do.

For instance, I wrote an article in 1991 or 1992 that said paper forms no longer had a reason to live, given that we could all input information into personal computers connected to whomever or whatever needed the data. That was more than three decades ago, and, hmmmm....

But at least the article only ran on the front page of the second section of the Wall Street Journal, so only a few people read it, right? 
 

The Dawn of the 'Connected' Insurance Agency

System fragmentation threatens agencies as 2026 digital investment surges and informed consumers verify information in real time.

Close Up Photography of Yellow Green Red and Brown Plastic Cones on White Lined Surface

The insurance industry is entering 2026 with pressure mounting from every direction. Regulations are tightening, consumers are walking in more informed than ever, and agencies are still battling the same silent threat that slows them every day. Their systems can't talk to one another. Data shows up late or contradicts itself. And the very people tasked with guiding buyers through complex decisions often lack the real-time information they need to do it.

This is why 2026 is shaping up to be the year of the connected agency. Agencies that reduce fragmentation, unify their data, and adopt technology with intention will be positioned to capture the full value of the industry's next wave of digital investment. Those who cling to disconnected processes will fall behind consumers who now validate information as fast as it is shared.

Clarity Drives Connection

A connected agency is not defined by how many tools it owns. It is defined by how seamlessly those tools work together. The goal is a low-touch, high-accuracy workflow where agents have immediate access to reliable carrier data, leaders see what drives performance, and consumers receive information they can trust without hesitation.

This shift is happening fast. By 2026, digital investment in insurance is expected to climb more than 25%, driven by demand for automated workflows, integrated data systems, and more personalized consumer experiences. Technology is no longer a support function. It is shaping marketing, underwriting, distribution, and customer engagement.

Still, investment alone does not guarantee improvement. Agencies cannot unlock the value of new tools if their data foundation is fragmented.

Fragmentation Holds Agencies Back

Ask agency leaders about their greatest operational challenges and you hear the same themes. Carrier data arrives in inconsistent formats. Product details get updated in one system but not the others. Teams rely on manual workarounds to resolve discrepancies. Compliance reviews become more difficult as regulations change and competitors accelerate their digital capabilities.

This fragmentation is more than a workflow issue. It affects credibility. Consumers have changed the buying dynamic in a way the industry has never seen before. ACA marketplace enrollment reached more than 21 million people, and combined marketplace and Medicaid expansion enrollment climbed past 44 million last year. That scale reflects a buyer base that is more informed, more comfortable with independent research, and more likely to challenge any detail that feels out of sync.

It is now common for a consumer to verify a quote during a live sales call. When the information they find online contradicts what an agent is sharing, trust erodes instantly. The agency that loses trust loses the sale.

The First Step Toward Modernization

Most leaders understand they need to modernize. What they do not always know is where to start. The instinct is to focus on new platforms, upgraded CRMs, or advanced analytics dashboards. But the most effective starting point is much simpler. Agencies need a clear understanding of their historical data.

Knowing who you serve, which products perform, where gaps exist, and how your book of business has evolved gives you the context to make smarter decisions about every step that follows. It also gives you a realistic baseline to measure improvement.

This approach aligns with broader industry research. Deloitte's digital insurance analysis shows that organizations with unified, trusted data foundations see higher returns on modernization efforts because they can automate more workflows and personalize the consumer experience more effectively.

Once the data foundation is clear, the next decision is choosing the right partners. Smaller and mid-sized agencies do not need to build their own technology. They do not need to hire internal engineering teams or maintain complex systems. They need partners that can bring accurate data, integrated workflows, and automated decision support to the table. That is how they modernize without stretching budgets or shifting attention away from their core work.

The Truth About AI's Role

AI is dominating insurance headlines, and there is real potential in the technology. But agencies should approach it with clear eyes. AI can guide consumer decision-making, support call center staff, and help identify needs based on anonymized data inputs. It can also expand access to personalized insights that would be impossible to generate manually.

But AI only works when the underlying data is clean and accurate. If an agency's data is fragmented or outdated, AI amplifies those problems instead of fixing them. Advanced analytics and AI can drive meaningful value, but only with strong governance and reliable data inputs. Without those elements, AI introduces more oversight responsibility and more operational risk.

For most agencies, the path forward is not to become AI experts. It is to build the foundation that allows AI and automation to work safely and effectively when they are ready to adopt them.

Why Connected Agencies Win

Agencies that embrace a connected model see improvements across several dimensions. Efficiency rises because teams spend less time reconciling data. Institutional knowledge becomes easier to preserve as workflows are documented and digitized. Compliance risk decreases because processes are structured and repeatable. And growth accelerates because agents can spend more time selling and less time troubleshooting systems.

Connected agencies also protect themselves from external volatility. Whether regulations change or carriers update products, a unified system makes it easier to adjust without disruption.

How to Evaluate Technology Partners

As agencies evaluate their options heading into 2026, selecting the right partners matters as much as choosing the right tools. Reputation still carries weight, but agencies should look deeper. The strongest partners offer capabilities that feel like table stakes for a modern agency, not add-ons that require extensive customization or additional cost.

The right partner should reduce friction, expand visibility, and help an agency operate with confidence even when the market changes. They should support a clean data foundation, integrated workflows, and the level of accuracy required to serve a consumer base that double-checks details in real time.

What It Takes to Win in 2026

Success in 2026 is not about size or budget. It is about clarity. Agencies that know their data, streamline their workflows, and align with partners that fill technical gaps will thrive. Those who continue working in fragmented systems will find it harder to grow, harder to stay compliant, and harder to keep pace with a consumer base that expects precision.

The industry is evolving quickly, but the path forward is clear. The connected agency is not a trend or a buzzword. It is an achievable and necessary model for every organization that wants to stay competitive in the years ahead.


Travis Conley

Profile picture for user TravisConley

Travis Conley

Travis Conley is the chief technology officer of Heathos.. 

He has more than 20 years of experience in IT leadership, with a focus on the insurance sector’s regulatory and customer challenges.

Insurers Face Cyber Talent Shortage

Cyber talent shortage leaves insurers vulnerable to the same threats they underwrite for clients.

A Woman Using Computer While Sitting on the Floor of a Dark Room

In an era when cyberattacks are escalating in frequency, sophistication, and financial impact, the insurance industry finds itself in a peculiar moment—not only underwriting cyber risks for clients but also struggling to protect itself from those very threats. The rising tide of digitalization has created an urgent need for cyber resilience within insurers' own operations. However, the industry is facing a growing challenge: a critical shortage of cyber talent.

As we move into 2026, insurers are increasingly asking a difficult question—can they insure themselves against cyber threats when they are struggling to hire and retain the very talent needed to defend their own systems?

The Double-Edged Sword of Cyber Risk

The insurance industry is uniquely positioned in the cybersecurity conversation. On one hand, insurers are developing and pricing cyber risk products for clients—especially businesses vulnerable to ransomware, data breaches, and phishing scams. On the other, their own systems hold vast amounts of sensitive personal and commercial data, making them lucrative targets for hackers.

Cyber insurance is one of the fastest-growing lines of business in property & casualty (P&C). According to industry projections, the global cyber insurance market is expected to exceed $30 billion in premium volume by 2027. Yet this growth is tempered by mounting internal threats and limited in-house cybersecurity capacity.

Internal Vulnerabilities on the Rise

Recent incidents have made clear that insurance firms are not immune to breaches. In fact, attackers see insurers as high-value targets due to their access to confidential policyholder data, claims histories, and financial information.

Despite increased investments in firewalls, intrusion detection systems, and endpoint protection, many insurers lack the personnel to monitor and respond to cyber incidents around the clock. The result? Gaps in defense, delayed response times, and higher exposure to reputational damage and regulatory fines.

The Cybersecurity Talent Shortage

At the heart of this vulnerability lies a growing talent crisis. Cybersecurity roles—such as threat analysts, security architects, and SOC (security operations center) analysts—are among the hardest to fill in the insurance sector. According to (ISC)², the global shortage of cybersecurity professionals stood at over 3 million in 2024, and the demand has only surged since.

Insurance firms are particularly affected because they must compete with tech giants, fintech startups, and government agencies that often offer more dynamic roles, faster career progression, and higher compensation. Many young professionals perceive the insurance industry as slow-moving or less innovative, further compounding hiring difficulties.

Legacy Systems and Innovation Drag

One of the key barriers to attracting cyber talent is the industry's continued reliance on legacy systems and outdated IT infrastructure. For cybersecurity professionals trained in modern cloud architectures, DevSecOps, and zero-trust frameworks, legacy environments are often perceived as stagnant or restrictive.

While some carriers have accelerated their digital transformation journeys, many are still in transition, which creates both technical and cultural obstacles for cybersecurity hires. This gap between modern cybersecurity demands and legacy environments makes onboarding and retention all the more difficult.

What Can Insurers Do?

To address the cyber talent crunch, insurers must rethink both their talent strategy and their organizational culture. Here are a few steps leading carriers are taking:

1. Rebrand Insurance as a Tech-Forward Industry

Firms need to reposition themselves as digital leaders. Highlighting innovation in AI-driven underwriting, blockchain-based claims processing, and cloud-native architectures can attract a new generation of tech talent who want purpose-driven and cutting-edge roles.

2. Invest in Internal Talent Pipelines

Rather than exclusively hunting externally, insurers can build internal training programs to upskill existing IT staff in cybersecurity. Partnerships with universities, bootcamps, and certification bodies like CompTIA, (ISC)², and SANS can help develop talent in-house.

3. Strengthen CISO Leadership

Chief information security officers (CISOs) must be empowered with a direct line to the board, strategic autonomy, and a clear mandate to drive transformation. Elevating the visibility and authority of cybersecurity leadership can improve team morale and signal seriousness to prospective hires.

4. Leverage Managed Services and AI Tools

Until talent gaps are fully addressed, insurers can turn to managed security services providers (MSSPs) and AI-based threat detection tools to bolster their defenses. Automation can't replace humans, but it can reduce the burden on limited teams.

5. Create Mission-Oriented Cyber Roles

Younger professionals are increasingly motivated by purpose and impact. Insurers can emphasize the role their cybersecurity staff play in protecting policyholders, critical financial infrastructure, and even disaster response systems.

A Call to Action for 2026 and Beyond

The cyber threat landscape isn't going to ease anytime soon. As quantum computing, generative AI, and decentralized finance (DeFi) introduce new vectors of attack, insurance firms must urgently fortify their digital perimeters.

But technology alone isn't the answer. The human layer—those who configure, monitor, and manage these systems—remains the most vital and vulnerable link. Closing the cyber talent gap is no longer a back-office IT issue; it is a business-critical challenge that could determine the long-term viability of an insurer.

The industry must act boldly. This includes building more inclusive pipelines, embracing flexible work models, offering competitive compensation, and nurturing a mission-driven, security-first culture.

Because in 2026, it's no longer just about insuring others. It's about ensuring the insurer can protect itself.

Reimagining Workers’ Compensation in the Age of Generative AI

Exploring how Generative AI could transform workers’ compensation — from smarter claims management and cost control to worker-centric care models and next-gen risk oversight.

gold ai

Workers’ compensation insurers are turning to generative AI to improve injured worker outcomes, strengthen performance, and build safer workplaces—here’s how:

Read Now


Sponsored by ITL Partner: PwC


ITL Partner: PwC

Profile picture for user PwC

ITL Partner: PwC

At PwC, we help clients build trust and reinvent so they can turn complexity into competitive advantage. We’re a tech-forward, people-empowered network with more than 364,000 people in 136 countries and 137 territories. Across audit and assurance, tax and legal, deals and consulting, we help clients build, accelerate, and sustain momentum.

New technologies, emerging competitors, and evolving customer expectations are reshaping insurance. 

Staying ahead means making the right moves at the right time — and we know what it takes. Our 14,000+ insurance-focused specialists worldwide, including 5,000+ in the US, work with life, P&C, specialty insurers and reinsurers to tackle the industry’s toughest challenges with practical, forward-looking insight.

We’ll work with you to tackle whatever comes your way, just as we have with 70% of Fortune 1000 insurers and hundreds of smaller and specialty carriers. Find out more at www.pwc.com.

__________________________________________________________________________________________________

Additional Resources

Case Study: Guidewire Cloud modernization at Columbia Insurance

Read More

Case Study: Encova Insurance: Accelerating speed and confidence with Guidewire Cloud

Read More

Explore PwC Insurance

Learn More

Explore the PwC and Guidewire alliance

Learn More


SURVEY: INSURTECH AND TRUST

How much do you trust insurtech right now? Take 5 minutes and find out.

man on phone shocked

From ROI and productivity gains to AI adoption and new market entrants, every signal influences how much trust you place in insurtech today.

Share your perspective in this anonymous survey about the insurtech your company relies on. Have a say in determining where trust is built and where it breaks.

Take the 5-minute survey


Sponsored by Benevolent Marketing


Benevolent Marketing

Profile picture for user BenevolentMarketing

Benevolent Marketing

Benevolent Marketing was founded in 2022 by Steve Pieroway, a former VP Marketing and executive team member at Policy Works (a Canadian insurtech). Why the name ‘Benevolent’? It is a key component of trust. Experts lean hard on expertise. Customers want to know they aren’t getting taken advantage of. That’s where benevolence comes in.

Transparent Health Reinsurance to the Rescue

The government shutdown crisis spotlights transparent health reinsurance as an emerging, nonpartisan solution aligning corporate and consumer interests.

A Person Wearing Blue Medical Gloves

Transparent health reinsurance may now emerge as one crucial and in all probability uncontemplated reform of the government shutdown crisis. The shutdown drew attention to a perfect storm: legislators, impotent to distribute patronage to donors and sponsors dependent on a malfunctioning health care system animated by the best of intentions as Congresswoman Nancy Pelosi (D-Calif.) pointed out in the House recently yet now so overburdened with special interest profit taking that it fails too many participants.

Transparent health reinsurance fills a missing link achieving health freedom and presents nonpartisan solutions addressing Democratic leadership challenges to Republican Senate and House majorities to bring forward workable healthcare policy.

Traditional reinsurance affords risk transfer, often with defined risk exposure parameters, percentages, and ratios for certain lines of risk (treaty reinsurance), facilitates specified claim reimbursements, and frees insurer capital, otherwise set aside for catastrophic claims, for investment. And, it accommodates negotiated deal making for specific policies an insurer may seek to reinsure (facultative reinsurance). It typically mitigates insurer exposure for large scale natural disasters and sustains reinsurer solvency during incidents impelling insurer reimbursements for exceptionally catastrophic claims.

Transparent health reinsurance, by contrast, assures, constitutes, and advances marketplace solutions to "managing risk in connection with healthcare costs," absorbing applicants, and legislating and implementing public policy in synch with technology and the times. The approach is equally ideal for health freedom as it is for remediating current, partisan, patronage system shortfalls.

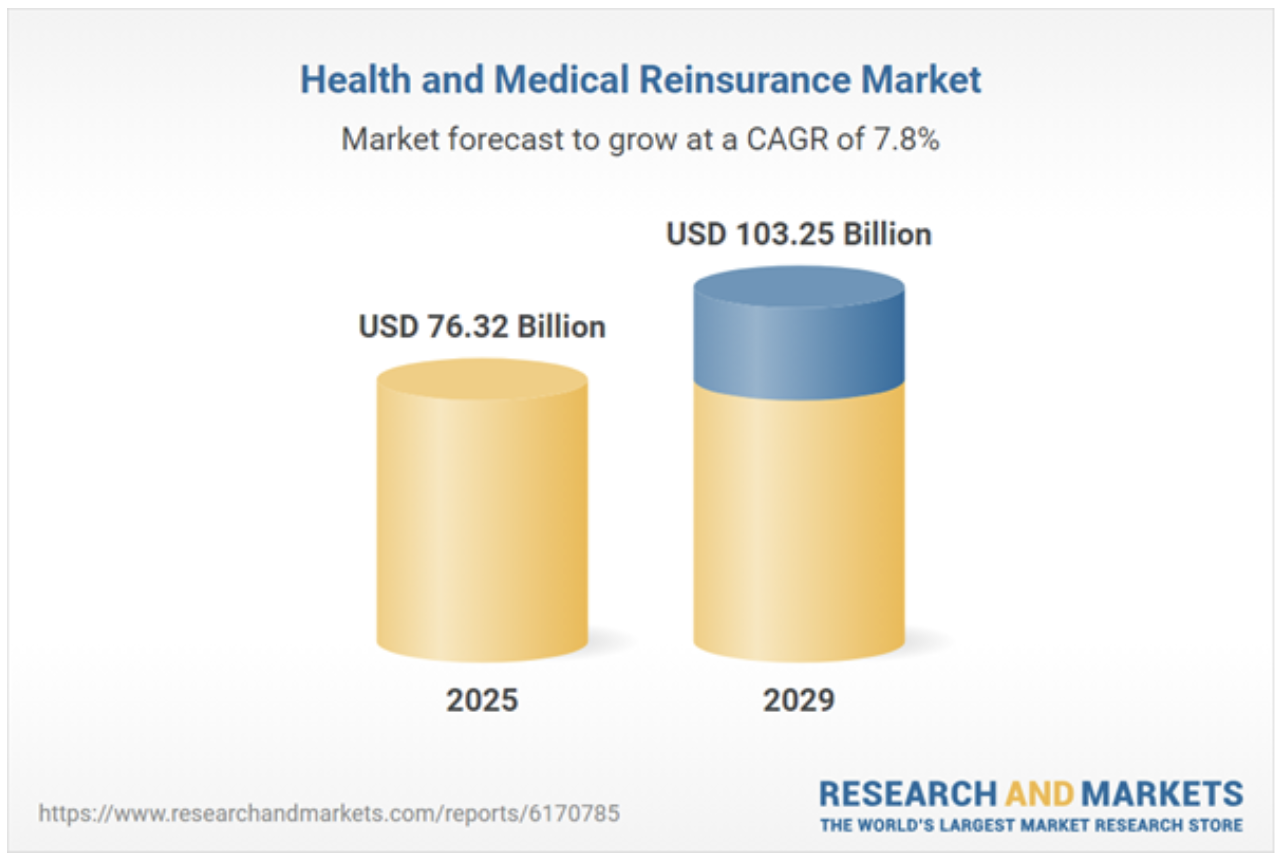
Timing could not be more propitious. Health and Reinsurance Market Report 2025, a Research and Markets expert report, forecasts that "health and medical reinsurance market size… will grow to $103.25 billion in 2029 at a compound annual growth rate (CAGR) of 7.8%. In the forecast period, growth is expected to be supported by the expanding adoption of digital health platforms, increasing demand for customized reinsurance models, greater participation by self-insured employers, a stronger focus on financial risk mitigation, and rising awareness of reinsurance benefits among smaller insurers. Key trends anticipated include innovations in underwriting models, the development of AI-powered risk assessment tools, increased investment in data analytics and automation, and advancements in health claim management systems."

Health and Medical Reinsurance Market

Transparent health reinsurance, in consequence, now embodies an instance in which corporate and public interests align for consumer welfare.

Health reinsurance innovators enjoy appreciable investment opportunities. "At Qatar Investment Authority [Qatar's sovereign wealth fund], we believe healthcare investments should aim to solve big problems for societies – and the businesses that are doing this are the ones that should thrive and survive…. QIA…can provide patient capital…This long-term approach to growth works best for our partners and aligns with our mandate," Dr. Mohamad Ghanem, QIA healthcare head, observes.

Market liberalization through transparent health reinsurance would also achieve President Trump's vision of empowering citizens to become entrepreneurs with their health care. Transparency animates voluminous data markets, which would enable all market participants to monetize the value of their information. These liberalizations should generate new revenues for all participants.

"Affordability" characterizes contemporaneous sensibilities, and transparent health reinsurance expedites and decongests easy passes to reasonable costs, rational profits, competitive prices, and high quality.

For instance, transparent health reinsurance could compensate outcomes. So doing would provide incentives for physicians to treat and cure patients.

Instead, contemporaneous health insurance compensates services. Just about everything palliates symptoms and protracts illness while patients struggle to get and be well.

As importantly, transparent health reinsurance can initiate systemic reforms by creating and rationalizing markets to address cost and price, key Trump Administration goals and concerns. So doing would liberate and empower all participants to loosen and break the shackles of current health insurance by vastly increasing market reach, size, and variety.

Like the old saw that doing good is doing well, transparent health reinsurance creates wide varieties of new products for the insurance and reinsurance industries 1) rewarding physician, health care provider, institution and hospital supply, and 2) responding to health care consumer demand.

For instance, transparent health reinsurance could broaden insurance coverage for homeopath physicians, whose remedies are often as, if not more, effective than allopathic pharmaceuticals at a fraction of those costs achieving timely cures rather than dependencies on recurrent symptomatic treatments.

There would, of course, be some heavy lifting. Homeopathy is all constitutional while allopathy focuses on addressing and, ideally, curing symptoms afflicting specific systems in one's body. So, pricing and coding integrating homeopathy would have to be conceptualized and tested, and it would have to achieve practitioner, insurance industry and patient consensus and adoption.

National Institutes of Health Director Jay Bhattacharya is especially insightful on systemic health reform in a wide ranging conversation.

The current state of health insurance is vastly more expensive than the original 2010 legislation. Key Obamacare risk coverage, notably risk corridors, went by the wayside. Premiums, point of service costs, and taxes are all higher. Legislator and regulator are each distinctly prey to industry capture. And, going forward, ever ballooning taxpayer contributions and higher health care insurance prices loom.

Unless we do something. 

3 Ways AI Agents Are Changing Claims

As insurance faces a worker shortage, AI agents handle repetitive claims tasks while humans retain control.

Person Facing Numbers

The insurance industry is facing a critical challenge driven by significant staffing shortages and rising turnover rates. Data from the U.S. Bureau of Labor Statistics suggests the industry is expected to lose nearly 400,000 workers through attrition. This trend highlights the urgent need to backfill an aging workforce and bridge the worker gap, especially as retaining employees for tedious back office work becomes increasingly difficult amid shifting regulatory and customer requirements.

While there has been plenty of hype surrounding artificial intelligence (AI), the real opportunity today lies in using AI agents to strategically fill this impending claims management workforce shortage. By focusing on practical, proven use cases, carriers can determine what tasks can be automated, what will remain a human function, and how AI agents can interact to maximize the benefits for the workforce and overall back-office throughput. The goal is to incorporate the human-in-the-loop so that AI is safe and actually used. Let AI agents do the boring, repetitive tasks so adjusters can focus on judgment, negotiation, and empathy. Humans will be kept in command via review queues and escalation rules.

Here are three ways AI is actually changing claims management and where humans still matter most:

1. AI Handles the Clerical, So People Handle the Critical

The biggest gains in efficiency come from removing friction so that claims professionals can spend more time on strategy, empathy, and problem solving. AI is currently adding real value in focused, repetitive areas and big data applications. Success can be measured by metrics such as intake resolution rate (% calls/emails fully handled by agent), AHT (average handle time) delta (minutes saved per claim) and error rate on field extraction (when extracting knowledge from data).

Key practical and proven use cases where AI is delivering value today include:

  • Omnichannel claim intake across email, SMS, and telephony, with entity capture (name, policy, plate/ID) and automatic case creation.
  • Knowledge-mining and data processing over large document sets per claim/patient; agents extract tasks and schedule nudges for upcoming visits or missing paperwork.
  • Risk signals and fraud triage by comparing millions of claims to spot outliers for SIU review.
  • Subrogation and recovery automation: detect subrogation opportunities from facts, generate demand letters, track recoveries.

These applications highlight the concrete ways AI can address the rising difficulty of retaining employees for back-office work.

2. Keeping AI Safe and Trusted Through Human-in-the-Loop Design

As AI systems handle more aspects of the claims process, it is paramount that organizations design systems where humans stay in control, ensuring both safety and trust. This approach is known as human-in-the-loop design, where the AI assists but the human remains in control.

To keep AI safe and trusted, organizations must prioritize the following design principles:

  • Confidence Thresholds and Guardrails: These are necessary to decide when AI acts independently versus when it escalates the task to a human. (For example: LLM as a judge "license-plate number ≥0.95, name ≥0.90"→ auto-apply vs queue)
  • Designing the Handoff: Claims leaders must focus on designing the precise interaction and transition between the human and the AI, rather than just the underlying model. An incremental adoption example of this is seen in IVR systems with forwarded calls serving as human escalations.
  • Trust as a Feature: Transparency, explainability, and auditability must be prioritized at every step. This means showing the sources for information, not just providing answers.
3. Driving Adoption – Because Tools Only Matter If They're Used

AI tools can only deliver strategic advantage and address the workforce gap if they are actually incorporated into daily workflows. Focusing on adoption over mere availability is crucial. Successful incorporation depends on leveraging behavioral and cultural levers.

Agents should join like a new teammate: they sit in channels, see only the data they're allowed to see, and can @mention humans when confidence is low. Companies that route people to a separate 'AI dashboard' will lose adoption; companies that embed agents into existing flows win.

The drivers of real adoption can be broken down into three areas:

  • Ability: AI solutions must meet users in their existing workflows; employees should not be asked to change tools. For example, AI functionality should be integrated within claims management systems or email platforms like Outlook.
  • Motivation: Organizations must identify champions within the workforce and highlight peer success stories to drive internal motivation.
  • Prompts: Adoption can be encouraged through in-workflow nudges, such as prompting a claims adjuster when creating a plan of action note. Other effective reminders include in-system messages, like "You saved 2.5 hours using AI drafting this week," or social/peer prompts sharing success stories.

By focusing on these three foundational approaches, the insurance industry can strategically leverage AI to address its critical staffing shortage and elevate the remaining workforce to focus on high-value, strategic functions.

A Note about Privacy, Security, and Governance

AI in claims is cultural, not just technical: every claimant is a human with an inviolable right to privacy. Agents should be designed to honor that first, then apply industry controls.

  • Privacy principles: Data minimization by default; purpose-bound processing; least-privilege access; explicit consent for recordings; subject access and deletion flows.
  • Security controls: Encryption in transit and at rest; envelope key management with regular rotation; short, business-justified retention windows; immutable audit trails; per-tenant isolation and row-level security; tamper-evident logs for model/tool outputs.
  • Governance: Data Processing Agreements and BAAs where required; vendor due diligence; model/version change logs; approved "never-autonomy" actions; periodic access reviews.
  • Regulatory alignment: Designed to align with HIPAA principles for PHI, GDPR for EU data rights, and SOC 2 control families for security and availability.
  • Human accountability: High-impact actions require human approval; overrides and escalations are attributed to specific users; exceptions are reviewed in weekly ops.

Leander Peter

Profile picture for user LeanderPeter

Leander Peter

Leander Peter is a co-founder of Avallon, which builds AI agents that automate repetitive tasks in insurance claims operations. 

Before starting the company, he built core operational technology for FINN’s fleet operations in Germany and the U.S.

2025 Reflections & 2026 Outlook for Insurance

Insurers are entering 2026 with one clear mandate: Strengthen the core to unlock scalable, AI-enabled growth. 

An artist's illustration of AI

For insurers, 2025 marked a reset in core systems strategy. After a decade spent patching legacy and modern-legacy platforms, layering point solutions, and stitching together data across disconnected architectures, insurers are now shifting toward rebuilding the core operational backbone required for resilience, agility, and sustainable growth. This is not a cosmetic upgrade; it's a structural re-architecture. The industry signal is now evident: competitive advantage will hinge on the agility, intelligence, and adaptability of an insurer's core platform.

This shift reflects a clear market reality: after years of incremental fixes and deferred modernization, insurers are being forced back to fundamentals. Achieving long-term, risk-adjusted profitability in a volatile environment while meeting rising customer expectations now depends on strengthening the foundations — systems, data, and operating structures — before meaningful innovation can take hold.

Insurers are entering 2026 with one clear mandate: Strengthen the core to unlock scalable, AI-enabled growth. GenAI and agentic AI have transformed expectations across underwriting, claims, and service, but legacy architectures cannot support the data fluidity, governance, and orchestration required. Modernization is no longer a technology upgrade; it is a business model reset.

Below are the key trends and imperatives that I believe will define the insurance sector in 2026:

1. Legacy Systems

Across all lines of business, insurers recognized that 'legacy' and 'modern-legacy' systems — platforms and systems built in the last 10–15 years, but architected on monolithic design principles — are already outdated and have become a structural barrier to progress.

As volatility increased across climate, capital, and customer expectations, the constraints of modern legacy systems became harder to work around and impossible to ignore. These platforms were never designed for API-first distribution, dynamic product configuration, governed AI, continuous delivery, cloud elasticity, or complex ecosystem integration. The result is the same across markets: slow product development, limited data flow, high integration cost, and constrained customer experience innovation.

Imperative for insurers: Seeking efficiency improvement alone is no longer enough, nor should it be the goal. Insurers must shift from a traditional, technology-centric ('inside-out') process automation approach to a more customer-centric ('outside-in') operating model redesign that is squarely anchored on customer journeys, contextual intelligence, and connected data. This requires replacing rigid, policy-centric architectures with data-fluid, AI-ready core platforms that evolve at market speed.

2. The Legacy–AI barrier 

It is real, and insurers are prioritizing platforms that remove it. AI advanced at extraordinary pace in 2025, but insurers discovered a hard truth: AI cannot deliver value if the core platform cannot provide clean, contextual, real-time data. Siloed, batch-based architectures choke AI's ability to reason across the customer lifecycle, perform real-time risk adjustment, orchestrate multi-step workflows, and meet regulatory explainability standards.

Imperative for insurers: The market trend is clear: 2026 is the year AI becomes operational, moving out of innovation labs and into the core workflows of underwriting, claims, billing, service, and distribution. However, AI is only as powerful as the governance and data lineage behind it. To ensure confidence in execution and enable the system to operate at its full intelligent potential, the next generation of cores must embed intelligence at the platform layer, ensure end-to-end traceability, support natural-language workflows, orchestrate AI agents safely, and provide explainable models by design. Systems that can't meet these requirements will be replaced, not augmented.

3. Continuous underwriting

Prioritizing continuous underwriting and real-time risk intelligence will be key in 2026. Static pricing models tied to annual cycles can no longer keep pace with market volatility. 2025 exposed a fundamental shift in how data works inside an insurer: the archive-and-retrieval model of the past is no longer viable in a market that demands real-time intelligence. Data has moved beyond being a historical record that's stored and is now a live, strategic asset that powers real-time decisions, customer engagement, and regulated AI at scale.

Imperative for insurers: Insurers need platforms that treat data as live, structured intelligence rather than historical policy snapshots. That requires event-driven cores capable of ingesting continuous signals, recalculating exposure dynamically, and orchestrating rules and AI-driven decisioning in real time. Only with this architecture can insurers shift from reactive loss absorption to proactive risk mitigation, precision pricing, and real-time portfolio steering embedded directly into operational workflows.

4. Trust, transparency, and governance 

They are now hard requirements, not optional values. In 2025, trust became a measurable business KPI. Regulators, and increasingly customers, are demanding clarity on how insurers handle data, automate decisions, and deploy AI. From the EU AI Act to new North American standards, scrutiny now requires model accountability, explainability, auditability, bias monitoring, and transparent decision trails.

Imperative for insurers: Trust will become the defining currency of the insurance industry and it will hinge on core system governance, not just goodwill. Trust must be engineered, not declared. Core systems will increasingly differentiate on their ability to provide full data lineage, governed workflows, explainable AI, audit-ready logic. This governance layer is becoming a top-three buying criterion for CIOs, CTOs, and CDOs.

5. Climate volatility 

It is forcing a radical re-engineering of property risk assessment. The convergence of climate shocks, fraud complexity, and operational pressure is accelerating demand for unified data orchestration, embedded fraud detection, advanced claims automation, and predictive resilience modeling.

Imperative for insurers: The static, inflexible policy-centric architectures of legacy systems must give way to intelligent, adaptive platforms. Insurers need cores that can merge climate data, IoT telemetry, satellite imagery, fraud analytics, operational AI, and human oversight into governed, auditable workflows. Modern platforms must support real-time risk signals, predictive resilience modeling and event-driven orchestration, enabling insurers to manage volatility, prevent loss and maintain trust at scale. Efficiency, accuracy and resilience must now co-exist in the same system.

6. Group benefits

They are evolving into intelligent, portable well-being ecosystems. Employers and employees alike are demanding personalized, adaptive propositions. Traditional product-centric systems cannot support the flexibility needed for next-generation benefits design.

Imperative for insurers: Success depends on cores that can orchestrate outcomes, not just administer products. This means platforms that support continuous personalization, governed data flows, multi-party ecosystems, and contextual well-being journeys. These platforms must enable outcomes such as benefits that adjust automatically to life events, proactive well-being support, and seamless portability as people move between roles or working patterns. In this model, value comes not from the product but from the continuous, connected experiences that surround it.

7. Pet insurance 

It is rapidly becoming a proving ground for ecosystem-driven, customer-centric transformation. Rising vet costs, increased pet humanization, and demand for digitally enabled care are accelerating the shift from transactional reimbursement models to proactive well-being ecosystems. As pet insurance evolves, insurers are beginning to confront foundational complexities, especially the lack of standardized coding and wide cost variability across veterinary services, which makes product design, underwriting, and pricing more difficult than in human health. These challenges are precisely what next-generation platforms must address.

Imperative for insurers: Pet insurers must operate on platforms capable of turning real-time data into proactive care. This means ingesting real-time pet health telemetry (e.g., wearables, vet diagnostics), integrating across vet, nutrition, and behavioral care networks, orchestrating digital ecosystem partners, and dynamically adjusting coverage and pricing based on evolving health and lifestyle data.

Competing in this new model requires a modern core platform that turns real-time health and lifestyle data into personalized care at scale. Leaders will use intelligent, AI-ready core systems to bring order to this fragmented landscape, enabling data ingestion from wearables and vet systems, dynamic pricing based on real behavior, personalized wellness plans, and preventive care journeys tailored across a pet's life.

The future of pet insurance isn't in replicating traditional health coverage, but in creating connected well-being ecosystems that anticipate needs, deliver real-time value, and position insurers as trusted care partners, not just payers of last resort.

Can We Please Tone Down All the 'Inflection Point' Talk?

I believe in creating a sense of urgency as much as the next guy, but it's just not right to say every part of the insurance industry is forever at a crossroads.

Image
group in business meeting

With all the copy I read through every week as I decide which pieces to publish here at ITL, I'm noticing an odd trend. 

For the past couple of years, tons of the articles submitted to me gloried in the insurance industry's "transformation" and "disruption." In recent months, though, lots warn that insurance is at a "crossroads" or an "inflection point" — often dressed up with ominous adjectives so the situation becomes a "major" crossroads or a "crucial" inflection point.  

Why the doom and gloom? And is it justified?

The one issue that could potentially merit the inflection point talk for the whole industry is generative AI. In the three years since ChatGPT announced itself to the world, it has already created numerous opportunities for efficiency, and AI agents hold the prospect of far more profound change. If you can get to the point where you say to your AI, "Gather all the information I need for this claim by contacting all the relevant parties," you would, in fact, have a crossroads. Those who figured out how to take advantage of that sort of AI agent would go one way, toward paradise, while everyone else would head in the wrong direction.

But we aren't there yet, and I think it'll take time for us to get there. The Silicon Valley ethos may be to "move fast and break things," but insurance companies don't get to do that.  We're not allowed to break things. Too many people get hurt if we do. 

The insurance industry faces plenty of other big issues, too: the increased number and intensity of natural disasters, uncertainty and rising prices because of the on-again, off-again Trump tariffs, federal policy that is reducing aid to states following natural disasters and may mean the elimination of the Federal Emergency Management Agency (FEMA), and so on. 

But does that mean we're at an inflection point? I don't think so. I think those issues just show that insurance is a complex, dynamic world, of the sort we've been dealing with, mostly effectively, for a long time. The supply chain disruptions because of COVID certainly caused a crisis, for instance, but insurers have already recovered enough that I recently published an article with the title, "Are Auto Insurers Now TOO Profitable?"

Besides, most of the claims of impending crisis I see are about far less comprehensive issues than GenAI. They're about the need to update legacy systems, to clean data, to adopt some more efficient approach to underwriting or handling claims, and so on. 

I agree with all the points those thought leaders are making. I also understand the need for innovators to create what is often referred to as "a burning platform." At the Wall Street Journal, I covered IBM in the '80s and '90s, a period during which the very smart executive leaders knew they needed to change to keep up with the increasing pace of innovation in the industry but couldn't quite bring themselves to do anything radical, because IBM had been the most profitable company in the world for so long. Only once the company started taking multibillion-dollar writeoffs and laying off tens of thousands of people — having prided itself on never laying off a single person in its 80-year history — did the company have the burning platform that Lou Gerstner used so effectively to change the culture.

I even accept that some parts of the industry are at inflection points. For instance, I recently published a piece by Stephen Applebaum and Alan Demers, "Embedded Insurance Nears Tipping Point" — because they're right; embedded insurance has been percolating as a possibility for years now and may be about to have its breakout moment, especially in auto insurance. I even published a piece in September with the headline, "Insurance at an Inflection Point." That was before I started seeing the term so often that I became allergic to it, and I wouldn't use it in a headline today, but the article makes a smart point about a potential new business model for insurers. 

But we have to maintain our credibility, and we can't be deluding ourselves. We likely aren't doing that if every fifth piece or so that I read claims the industry is at a crossroads/inflection point. (I recently opened a proposed article whose first sentence was, "The insurance industry is at an inflection point," and the next article began, "The insurance industry is at a critical inflection point.") 

There is loads of important change happening in the insurance industry, and GenAI will surely get us to an inflection point. But let's not oversell what's happening now. 

Not every problem is a make-or-break moment. Not every bit of progress is a game-changer.

Cheers,

Paul

P.S. I seem to need to cleanse my soul every six to 12 months with a piece like this. Here are some of my favorite previous rants, which I think hold up just fine: "Let's Stop With the Gibberish," "May I Rant for a Moment?" and "Two Words We Must Stop Using." 

I get riled up just rereading them. Please share with any colleague you think could use a nudge — or maybe a chuckle. 

Cyber Insurance Exclusions to Expect in 2026

Emerging cyber threats are driving insurers to expand policy exclusions, challenging traditional risk management.

Abstract red and blue blurs

Cyber insurance remains a cornerstone for managing digital risk, yet the market is evolving in ways that may surprise many organizations. By 2026, policies are expected to provide less certainty than policyholders have come to assume. Insurers are introducing new exclusions, enforcing stricter underwriting standards and responding to the rapid emergence of complex threats such as AI-driven vulnerabilities, zero-day exploits and connected Internet of Things exposures. 

For risk managers and insurance brokers, anticipating these exclusions and developing strategies to address coverage gaps is essential. Misalignment between perceived protection and actual policy coverage can expose organizations to significant operational disruption and financial loss. 

The next section examines why insurers are introducing these new exclusions and what drives their focus on high-uncertainty, potentially catastrophic exposures.

Why Exclusions are Escalating

Claims metrics in 2025 show relative stability, with reports indicating that both the number and average severity of large cyber claims have remained largely unchanged compared with prior years. On the surface, this might suggest that insurers are not under pressure. However, the surge in exclusions is driven less by historical claims and more by emerging, high-uncertainty risks that could produce catastrophic losses. 

Insurers are increasingly concerned about exposures without established actuarial history, including AI-driven attacks, zero-day vulnerabilities, connected IoT systems and state-sponsored cyber operations, according to a 2025 report by Allianz. 

Even isolated events, such as the 2024 CrowdStrike outage affecting multiple Fortune 500 companies, illustrate the accumulation risk insurers now face—where a single incident can affect numerous policyholders simultaneously. 

This combination of unquantified risk, potential for systemic loss and regulatory uncertainty has prompted insurers to tighten coverage and add exclusions to protect against scenarios that could produce outsized financial consequences.

Emerging Exclusions to Expect in 2026

Risk managers should anticipate new categories of exclusions that will redefine what traditional cyber insurance covers. Understanding the rationale behind each exclusion and its potential impact is critical for preparing organizations.

Artificial Intelligence Risks

Artificial intelligence is becoming ubiquitous, yet insurers are increasingly excluding claims linked to its use. Policies may deny coverage for errors or omissions in AI systems, misleading outputs or regulatory violations tied to AI implementation. 

A notable concern is the breadth of some exclusions, which may apply not only to a company's own AI systems but also to third-party platforms used in business operations. This expansive scope creates uncertainty about whether claims will be honored when AI played even a minor role. Risk managers must scrutinize AI-related language in policies and assess whether existing coverage aligns with emerging liabilities, according to an article in the Harvard Law School Forum on Corporate Governance and Financial Regulation.

State-Sponsored Cyberattacks

Following global geopolitical developments, insurers are expanding war or cyberwar exclusions to cover state-backed attacks, according to Mitigata. The impact can be profound, as even incidents occurring in peacetime may fall within the exclusion if a government is implicated. This is particularly significant for organizations operating in critical infrastructure sectors or with extensive international digital networks. Awareness of the scope and triggers of these exclusions is essential for preparing mitigation strategies and considering supplementary coverage.

Catastrophic and Widespread Events

Insurers are increasingly defining "widespread events" or "catastrophes" in ways that limit aggregate exposure from systemic incidents, according to an article by Chubb. These exclusions may restrict coverage when multiple policyholders are affected simultaneously, such as through a coordinated ransomware attack targeting a popular cloud provider. For organizations, this can mean delayed payouts or denied claims when the event's scale triggers a policy exclusion. Clear understanding of these terms is necessary to plan alternative risk strategies.

Web Tracking and Regulatory Liabilities

Policies are tightening language around website tracking, data privacy and compliance with evolving regulatory regimes. Failure to satisfy underwriter inquiries regarding tracking technologies can lead to broad exclusions. Similarly, coverage for fines, penalties and reputational harm is often limited. Organizations must ensure that their security posture, privacy practices and compliance measures are fully documented to avoid coverage gaps.

Enforcement of Existing Exclusions

Even long-standing exclusions are being applied more rigorously, the 2025 Allianz report found. Insurers are denying claims for failure to meet minimum security requirements, including missing multi-factor authentication, unpatched vulnerabilities or outdated incident response protocols. Insider threats, third-party vendor risks, contractual liabilities and regulatory fines are also increasingly scrutinized. For risk managers, this means that maintaining robust, documented controls is not optional but a condition for coverage.

Managing Exclusions

To navigate this tightening environment, organizations should align coverage with actual risk. Key actions include:

  • Implementing and documenting robust controls, including multi-factor authentication, endpoint detection and response systems and formal incident response readiness.
  • Being transparent during underwriting by accurately representing security posture and addressing known vulnerabilities.
  • Conducting regular risk assessments to ensure IT infrastructure aligns with coverage requirements.
  • Reviewing policy language closely, with attention to definitions for catastrophes, state-sponsored attacks and minimum security requirements.
  • Collaborating with specialized brokers who understand the nuances of cyber policies and can advocate for coverage clarity.

These measures help reduce the likelihood of denied claims and ensure policies reflect actual organizational risk. Insurance remains necessary, but it must be coupled with proactive risk management to be effective.

Filling Gaps with Alternative Risk Transfer

When traditional policies leave high-severity, low-frequency risks uncovered, alternative risk transfer solutions can provide supplementary protection.

Captive Insurance

A captive is a subsidiary insurance company established to underwrite risks for its parent organization. Captives allow coverage of exclusions such as state-backed cyberattacks, AI liabilities, or reputational loss. This approach enables customized protection, keeps premiums and underwriting profits within the organization and provides certainty where commercial markets may be constrained.

Parametric Insurance

Parametric policies pay out based on predefined triggers rather than measured losses. For example, a payout may be tied to a specific number of exposed records or a defined system downtime period. Parametric insurance ensures rapid access to capital for business interruption costs, even if the primary cyber policy contains restrictive exclusions.

Capital Market Solutions

Cyber risks can also be transferred to capital markets through insurance-linked securities such as catastrophe bonds. These instruments attract external capital to cover peak risks, including systemic cyber events, and can expand overall capacity for insuring niche exposures that traditional policies exclude.

Conclusion

Cyber insurance exclusions are expanding in response to evolving threats and increasing claims severity. By 2026, risk managers and brokers must recognize that traditional policies alone may not provide full coverage, particularly for AI-related liabilities, state-sponsored attacks and catastrophic events. Proactive strategies, including robust documentation, controls, regular risk assessments and complementary alternative risk transfer solutions, are essential to bridge coverage gaps. Aligning insurance with operational realities ensures that organizations maintain resilience, protect enterprise value, and respond effectively when cyber incidents occur.


Randy Sadler

Profile picture for user RandySadler

Randy Sadler

Randy Sadler is a  principal with CIC Services, which manages more than 100 captives.

He started his career in risk management as an officer in the U.S. Army, where he was responsible for the training and safety of hundreds of soldiers and over 150 wheeled and tracked vehicles. He graduated from the U.S. Military Academy at West Point with a B.S. degree in international and strategic history, with a focus on U.S.–China relations in the 20th century.