Download

Watchwords for Insurance in 2026

After years of rapid change, insurers prioritize strategic consolidation and efficiency in 2026, with health insurance leading growth.

A person sitting at a desk in a green top with a lop and papers on the desk showing charts and graphs

While the past few years have been marked by rapid digital acceleration and shifting customer expectations, 2026 will be defined by a more measured, strategic approach. It will be a time of consolidation, recalibration, and targeted investment—especially in health insurance and technology.

Health Insurance: The Growth Engine of 2026

Among all insurance segments, health insurance stands out as the most dynamic. Across the globe, public healthcare systems are under increasing strain, and private insurers are stepping in to bridge the gap. This trend is not only a response to demographic pressures and rising healthcare costs but also a reflection of changing consumer expectations. In 2026, I anticipate health insurance to be the fastest-growing segment, driven by demand for better access, personalized care, and digital health services.

In contrast, P&C insurance will likely remain stable. Economic uncertainty and subdued global growth are limiting expansion in this area. Corporate insurance may see modest gains, while personal lines are expected to plateau. Specialty lines—those tailored, niche products—will continue to grow, offering insurers opportunities to differentiate and innovate. Life insurance will remain steady, with annuities maintaining their appeal due to favorable tax treatment and predictable returns.

Consolidation: A Global Phenomenon

We are witnessing a wave of consolidation across key markets. In Europe, Australia, and Canada, insurers are merging to achieve scale and operational efficiency. Japan's market is already highly concentrated, with three players controlling 80% of the market. Australia follows closely, with over 60% of the market in the hands of just three insurers. In Europe, motor insurance remains fiercely competitive, prompting further consolidation. The UK has seen major moves, such as Aviva acquiring Direct Line and Ageas purchasing Saga. Similar dynamics are unfolding in Germany, France, and the Nordics. In the United States, however, fragmentation persists.

The U.S. insurance sector faces a more difficult phase in 2026. Tariffs are expected to have a moderately negative effect on claims inflation in motor insurance and increase pressure on cost structures. Premiums for commercial insurance are likely to remain unchanged or decline slightly, while premium growth in the private customer business will continue but at a slower pace.

The Strategic Imperative: Efficiency and Scale

In 2026, insurers will prioritize efficiency and scale – particularly in property insurance for private individuals. Cost control will be the key to competitiveness. This means investing in automation, simplified standard architectures, modern rating systems and intelligent risk selection. Insurers will need to focus on retaining profitable customers while steering clear of unattractive risks.

In commercial insurance, the emphasis will be on speed and collaboration. Brokers will play a central role, and underwriters will need to respond faster and more flexibly. However, this shift toward a more sales-oriented underwriting approach must be balanced carefully to avoid compromising underwriting discipline.

Health insurance, meanwhile, will demand the most investment. Insurers are increasingly building proprietary medical networks or forming strategic partnerships to enhance service delivery and control costs. This segment will be the most capital-intensive, but also the most promising.

Technology: The Engine of Transformation

The digital transformation of the insurance industry is in full motion, but it is far from complete. The modernization of core systems remains the largest area of investment in countries such as Japan, Germany and France. Commercial lines are adopting underwriting workbenches and automation tools, while retail insurers are focusing on self-service and process automation to reduce call center costs.

Cloud adoption is progressing at varying speeds. Markets like Australia, New Zealand, and the UK are moving quickly, while Japan and continental Europe remain more cautious. Cloud infrastructure offers flexibility and security, but many insurers are still learning how to unlock its full economic potential.

The insurance industry in the United States and Canada will focus heavily on artificial intelligence. Insurers in both markets are currently expanding their AI capabilities with a strong focus on claims management. However, underwriting is likely to receive more attention in connection with AI. Underwriting technology has become a key issue in insurance IT, and in 2026 more insurers will implement digital solutions in this critical area of the insurance value chain.

The cloud has become an essential enabler of innovative insurance technology, and there is no other market where the demand for cloud skills is stronger than in North America. The cloud will play a central role in the expansion of AI use by insurers. Cybersecurity remains an important issue, especially after last year's three major cyber-attacks, which prompted insurers to strengthen their defense and response capabilities.

Broker consolidation is another area with significant potential. Seamless integration between insurer and broker platforms is becoming essential. This trend is already well established in the UK, Canada, and the U.S., and is now gaining traction in continental Europe.

Final Thoughts

The insurance industry in 2026 will not be defined by dramatic upheaval, but by strategic evolution. The winners will be those who embrace scale, prioritize efficiency, and invest wisely in technology.
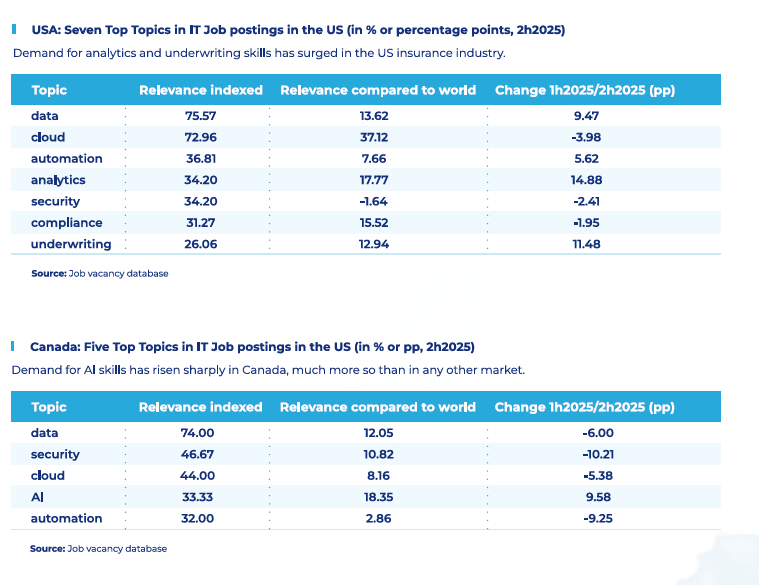
Job Vacancy Data in US and Canada

Insurance Embraces Elastic Staffing Model

Talent shortages and demand volatility are making elastic staffing a defining operating model for insurance organizations navigating uncertainty.

People Sitting Down on Chairs at the Conference Room

You can't scan a business headline, listen to an earnings call, or sit in a leadership meeting today without hearing the term: "elastic staffing."

Once considered a niche workforce strategy, elastic staffing has quickly become a defining operating model for organizations navigating sustained uncertainty. At its core, the concept is straightforward: maintain a strong internal team, then flex capacity up or down by tapping pre-qualified external talent as business needs change.

What's driving its rise isn't novelty—it's pressure. Persistent talent shortages, accelerating retirements, cost volatility, rapid digital transformation, and unpredictable demand have exposed the limitations of rigid, fixed-headcount staffing models across nearly every industry. Nowhere is this shift more apparent than in insurance.

Why Traditional Staffing No Longer Fits Insurance

The insurance workforce model was built for a very different era—one defined by predictable workloads, long employee tenures, and incremental change. For decades, insurance organizations could rely on steady volumes and institutional knowledge accumulated over entire careers. That reality no longer exists.

Today's carriers, MGAs, MGUs, and brokerages are operating in an environment marked by volatile claims activity, rapid technology adoption, tightening margins, heightened regulatory scrutiny, and shrinking talent pipelines. Demand now comes in peaks and valleys rather than steady, forecastable patterns. At the same time, the industry is grappling with a wave of retirements that is steadily draining deep institutional expertise.

Fixed staffing forces leadership into a constant balancing act. Overstaff to prepare for demand surges and organizations absorb unnecessary cost when volumes normalize. Understaff and they risk backlogs, service breakdowns, compliance exposure, and employee burnout when activity spikes. Neither option is sustainable, and both create long-term organizational drag.

As Carrier Management has observed, insurers need workforce models that can "expand, contract, reorganize and modernize quickly without compromising culture or compliance, or creating a disjointed customer experience." That requirement alone challenges the viability of traditional, static staffing approaches.

Elastic staffing addresses this gap by turning labor into a variable resource rather than a fixed constraint. It allows organizations to scale specialized expertise—claims, underwriting, accounting, compliance, account management—without committing to permanent headcount that may not align with future demand. Just as importantly, it provides a practical way to adapt as automation and AI reshape roles, without relying on layoffs as the primary lever.

But flexibility alone is not the answer.

Why Elastic Staffing Can Fail in Practice

Many insurance organizations struggle with elastic staffing because they approach it as a short-term fix or a substitute for temporary labor. When elasticity is treated as a transactional solution, it often becomes reactive rather than strategic—and can introduce new forms of risk.

To succeed at scale, elastic staffing must rest on three critical foundations:

  • Access to experienced, insurance-specific talent
  • Operational consistency and accountability
  • Alignment with how insurance work is actually performed

Without these, organizations may gain short-term capacity but sacrifice quality, continuity, and control.

Insurance is not an industry where generalist labor can be dropped in without consequence. Regulatory requirements, system complexity, and client expectations demand professionals who understand the nuances of the work. Elastic staffing models that overlook this reality often struggle with long ramp-up times, rework, and execution errors.

The Role of Specialized Workforce Models

Elastic staffing works best when it is built around talent pools that are purpose-built for insurance, rather than broad labor marketplaces.

The most effective models share several defining characteristics.
  • Immediate access to experienced professionals: Elastic staffing only delivers value if talent can contribute quickly. In insurance, experience is not optional—particularly in high-stakes functions such as underwriting, claims, finance, compliance, and client service. Deep domain knowledge shortens ramp-up time, reduces errors, and minimizes operational risk.
  • Flexibility without constant turnover: Elastic does not have to mean short-lived engagements. In fact, longer-term, embedded professionals often deliver the greatest value. This approach allows organizations to flex capacity for peak workloads, remediation efforts, or transformation initiatives while maintaining continuity, institutional knowledge, and service quality.
  • Reduced execution risk: Moving from a fixed headcount model to an elastic one introduces new challenges around onboarding, security, performance management, and accountability. Workforce models that already address these operational realities allow organizations to adopt flexibility without redesigning internal processes or overburdening HR and operations teams.
  • Smarter cost control: Elastic staffing converts labor from a fixed expense into a variable one while preserving access to senior-level expertise. When recruiting costs, benefits, turnover, and downtime are considered, this approach often proves more cost-effective than traditional hiring—particularly for roles tied to fluctuating demand or specialized projects.
  • Support for long-term workforce resilience: As retirements accelerate and talent pipelines thin, insurance organizations need solutions that balance immediate capacity needs with long-term continuity. Elastic staffing provides that balance, stabilizing operations today while creating space to rethink workforce design for the future.
Elasticity as a Strategic Operating Model

Organizations that succeed with elastic staffing do not treat it as a stopgap. They treat it as an operating model.

That means planning for flexibility, building repeatable processes, and aligning workforce strategy with business volatility and technological change. It also means recognizing that elasticity is not about replacing internal teams, but about augmenting them in ways that preserve culture, compliance, and customer experience.

In an industry where regulatory exposure and trust are always at stake, execution matters as much as intent. When implemented thoughtfully, elastic staffing enhances resilience. It enables organizations to absorb demand shocks, manage transformation initiatives, and adapt to AI-driven change without destabilizing their workforce or compromising service quality.

The industry is already moving in this direction. As uncertainty becomes the norm rather than the exception, workforce agility is no longer a competitive advantage—it is a requirement.

The elastic wave is here. How insurance organizations ride it will determine who keeps pace—and who falls behind.


Sharon Emek

Profile picture for user SharonEmek

Sharon Emek

Sharon Emek, Ph.D., CIC, is chairman and CEO at WAHVE, a talent agency addressing the approaching Baby Boomer retirement and growing need for experienced talent in the insurance industry. 

She is a frequent speaker on the challenges that employers and “vintage” professionals are facing today by enabling insurers to engage highly experienced, work-from-home professionals on long-term contracts. 


Rick Morgan

Profile picture for user RickMorgan

Rick Morgan

Rick Morgan is senior vice president of marketing at WAHVE.

His background spans underwriting, agency ownership, publishing, and senior executive roles across insurance, technology, and industry organizations. 

Insurance Shifts to Modular AI Deployment

End-to-end AI promises disappointed in 2025, prompting insurers to shift toward focused, modular deployment strategies.

An artist's illustration of AI

For many in the insurance industry, 2025 was the year of the "AI Reality Check." After a whirlwind of excitement surrounding generative models, many carriers found themselves navigating a landscape cluttered with broken promises and stalled pilots. As we look toward meaningful innovation in 2026, the path forward requires us to address the "key myth" of AI: the seductive, yet ultimately destructive, belief in the end-to-end magic pill.

Believing that AI can or should replace human judgment at scale is disconnected from the reality of what the technology is. It's far more nuanced and, ultimately, more valuable. AI excels at specific, well-defined tasks: parsing documents, extracting structured data, identifying patterns in large datasets. Humans excel at everything else: understanding context, applying judgment, managing relationships, and making decisions that balance competing priorities.

AI in insurance isn't about doing it all at once. It's about deploying AI module by module, connecting thoughtfully, and staying grounded in what the technology can and cannot do today. That's how AI moves from hype to durable business value.

This distinction matters enormously, especially in insurance, an industry that has been swept up in the promise of AI-powered transformation. Over the past few years, insurance companies have invested heavily in "end-to-end AI systems," ambitious platforms that promise to automate entire workflows, from document intake through underwriting decisions to claims processing. The pitch is compelling: let AI handle the complexity so your teams can focus on strategy. The reality, however, tells a very different story.

The Gap Between Hype and Production

The most significant barrier to durable business value has been the industry's obsession with "end-to-end" solutions. We have seen insurers attempt to buy "AI underwriters" with the expectation that the model will handle everything from initial intake and actuarial analysis to final premium pricing.

There's significant noise around concepts like "AGI" (artificial general intelligence) which creates unrealistic expectations about what AI can accomplish today. This prevailing narrative obscures a critical truth: we're nowhere near the kind of AI that can independently manage the nuanced, multifaceted work that insurance professionals do every day.

An AI cannot replicate 20 years of an underwriter's experience or possess the nuanced context of a specific account. When these "do-it-all" systems attempt to underwrite a complex entity like a national car rental fleet, they often produce inaccurate results because they lack the human context to understand the specific distribution of vehicle types or local risk factors.

When these end-to-end systems fail to deliver, adoption plummets, and frustrated teams retreat to their old manual ways of doing things. This is a failure of strategy, not technology. The myth that AI can do it all has led many to overlook the "hidden costs of delay"—the thousands of touchpoints where humans are forced to review the same long documents and messy email threads over and over again.
This observation cuts to the heart of the key myth that has driven billions in insurance AI spending: the belief that you can build a single system to handle everything.

The Human Touch

Another critical truth? People want to know there is a human hand guiding the decision-making, particularly in an industry as important as insurance. Insurity's 2025 AI in Insurance Report revealed that just 20% of Americans say it's a good idea for P&C insurers to leverage AI, and 44% of consumers are less likely to purchase a policy from an insurer that publicly uses AI. In a 2025 Guidewire survey, 40% of respondents said they would feel more confident in insurers' AI if decisions could always be referred to a human when challenged. Finally, a 2025 survey conducted by J.D. Power showed that insurance customers are most comfortable with AI when it is used to automate routine aspects such as sending claim status updates (24%), managing their billing (23%), and answering basic customer service questions (21%).

So what insight can we gain from these numbers? People are more wary of the insurance industry's use of AI when there isn't a human available to speak with or in control of ultimate decision-making. It seems that customers are far more comfortable with insurers using AI in their workflows when it is deployed for automatic, manual processes embedded with human oversight.

The Failure of End-to-End Automation

Many insurers bought AI underwriting or claims products with high expectations. These systems promised to intake documents, evaluate risk, and generate underwriting decisions and pricing. It seemed the entire underwriting process would be fully automated. What happened next was instructive.

In one recent example, a large insurer deployed an "end-to-end" AI system to handle renewal underwriting for a major account. The AI evaluated the client's profile and recommended a specific premium. But when the human underwriter, who had managed that account for years, reviewed the recommendation, the flaws became obvious. The AI had missed critical nuances about the client's composition and risk profile. The underwriter knew from years of professional experience that this contextual information fundamentally changed the risk calculation. The AI system had the same information as the human underwriter, but the AI's recommendation was simply wrong.

The outcome was predictable: the insurer stopped using the system and went back to manual underwriting. With one major near-miss, "people just go back to the old way of doing things," the expert said.

This represents a profound failure in the AI industry. After this experience, the underwriter noted "It's better to do it manually than to use an AI. Something seriously has gone wrong here."

The Real Innovation: Modular AI

If end-to-end systems fail, what actually works? The answer lies in a fundamentally different approach: "modular AI deployment." Rather than trying to automate entire processes, successful organizations break complex workflows into smaller, well-defined components and apply AI where it genuinely adds value.

Instead of attempting to automate every aspect of a human's job, AI initiatives should focus on eliminating one extremely tedious and time-consuming task.

This philosophy is particularly powerful in document-heavy operations like insurance. Rather than developing an AI that promises to fully contextualize an underwriting submission and make complex recommendations, a more effective strategy is to concentrate on a single, crucial pain point such as accurately extracting and classifying documents. This is a genuinely difficult challenge. Insurance submissions often contain mixed document types, irrelevant supplemental data, and complex tables that general-purpose AI models frequently fail to process correctly because they are not designed to do so.

This is precisely where focused AI adds clear, measurable value. Once documents are properly classified and key data is converted into structured formats, human underwriters operate with far greater efficiency. Their time is spent reviewing pre-processed data and applying their judgment, experience, and understanding of company-specific risk appetite, not manually hunting through dozens of PDFs for critical information.

Building Digital Transformation Through Integration

The path to meaningful AI advancement in insurance isn't about finding the perfect all-knowing system. It's about thoughtful integration of specialized components to increase efficiency and letting professionals get back to the real work at hand. Organizations should consider which capabilities to buy (like document extraction), which to build internally (like risk models specific to your business), and how to orchestrate them effectively.

This is building AI one small piece at a time. You might deploy document classification as a module. Then add information extraction. Then integrate those outputs into your downstream systems. Each step is validated, each component is understood, and each addition genuinely improves the workflow for the humans who ultimately make the decisions. No "end-to-end" black box AI.

Admittedly, this approach requires discipline and is less exciting than the promise of end-to-end automation. But it actually works and leads to full adoption, rather than initial experimentation and inevitable abandonment when reality fails to match the pitch.


Galina Fendikevich

Profile picture for user GalinaFendikevich

Galina Fendikevich

Galina Fendikevich is the U.S. go-to-market lead at Upstage.

She drives the adoption of AI solutions across highly regulated industries. Previously, she worked on Wall Street managing credit risk systems, co-founded a blockchain and augmented reality team acquired by Niantic, and consulted on AI strategy for consumer brands.

Persistent Adverse Reserve Development

Commercial casualty reserves continue falling short as social inflation and extended litigation challenge backward-looking actuarial assumptions.

Blurred Silhouettes of Commuters Indoors

Since 2019, several casualty lines of business have shown a consistent pattern of adverse development through year-end 2024. Preliminary third-quarter 2025 disclosures signal that this trend is not yet reversing. The underlying experience, however, differs significantly by line and by carrier. This article focuses on where and why reserve shortfalls are occurring. We also provide some high-level suggestions to adjust actuarial methods for more adequate reserves.

Using Annual Statement data from S&P Global Market Intelligence, we examined:

  • Commercial auto liability (industrywide), and
  • Other liability—occurrence experience for 20 writers concentrating on excess or umbrella coverage.

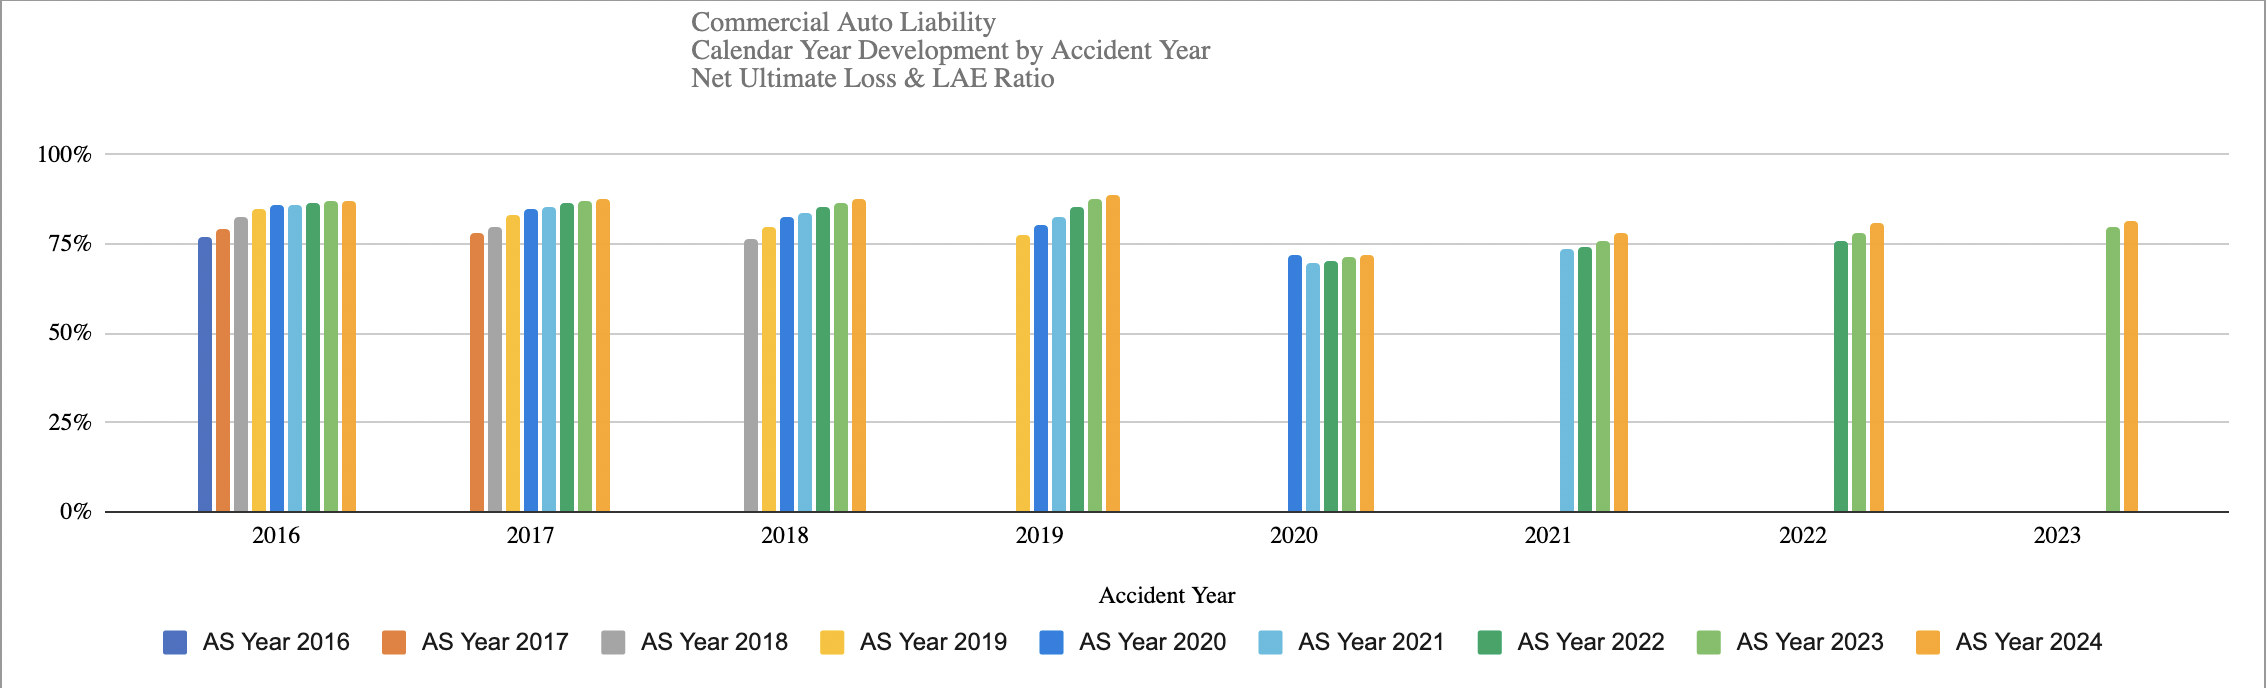
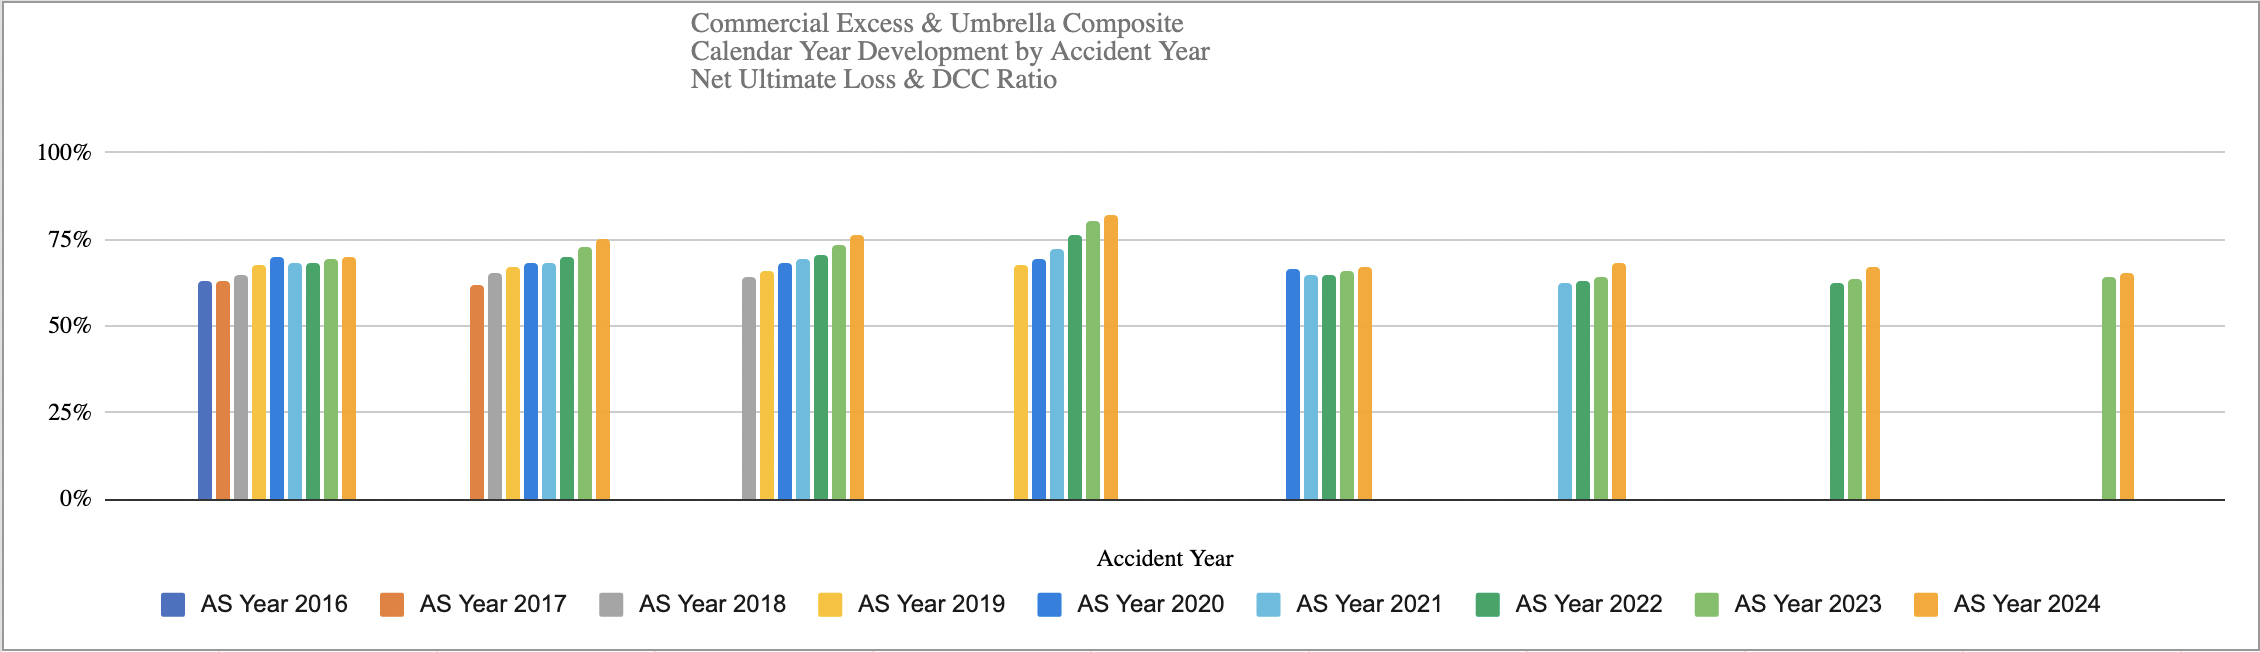
Across accident years 2016–2024, published ultimate loss ratios have increased almost every calendar year. With the benefit of hindsight, initial and subsequent reserves were inadequate.

From Annual Statement data via S&P Global Market Intelligence Industry Commercial Auto Liability

From Annual Statement data via S&P Global Market Intelligence Industry Commercial Auto Liability

From Annual Statement data via S&P Global Market Intelligence based on Other Liability Occurrence results from 20 companies that predominately write excess and umbrella business.

From Annual Statement data via S&P Global Market Intelligence based on Other Liability Occurrence results from 20 companies that predominately write excess and umbrella business.

What is driving this pattern of inadequate reserves? We believe that the following factors are the most significant:

1) Extended Litigation: The expansion of third-party litigation funding and the improved capitalization of certain plaintiff firms mean more lawsuits proceed to trial. This causes challenges with traditional actuarial methods. Actuaries often use the past patterns to predict future patterns; however, if the environment changes significantly the methods become less reliable. With an increasing percentage of claims being litigated, historical loss emergence patterns are less reliably predictive of the future patterns. The industry has observed both longer cycle times (from claim report to claim settlement) due to more litigation and increased settlement costs as jury outcomes increasingly favor plaintiffs.

2) Backward-looking benchmarks: Actuaries often use older years' loss ratios to estimate loss ratio results for more recent years (after adjusting for premium changes and loss trends). However, if the older years' loss ratios consistently increase, the initial assumptions for the newer years start too low.

3) Under-estimated trend in a rising-cost environment: In an environment of increasing costs, it is difficult to estimate trend factors. For example, if average claim costs are increasing, some companies may believe that case reserves are more adequate and therefore not reflect the higher trends in the projections.

4) Management optimism. After the large rate increases and underwriting tightening during 2019-2022, some management teams find it hard to believe that loss ratios are not dramatically improving. This belief can delay the recognition of continuing adverse development.

The published industry results for the last few years clearly indicated adverse industry development as illustrated in the graphs above. Preliminary data published through the third quarter of 2025 indicates adverse development is continuing for some companies.

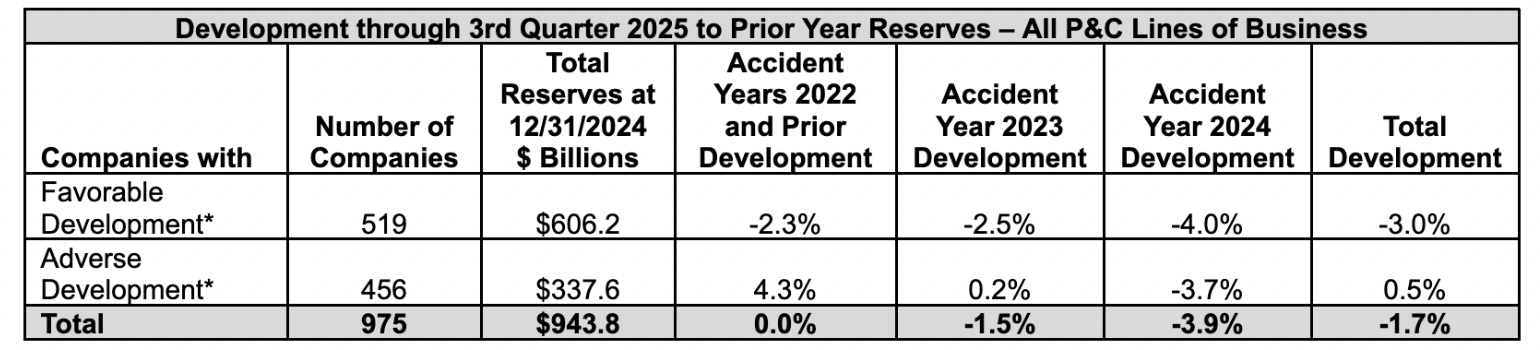
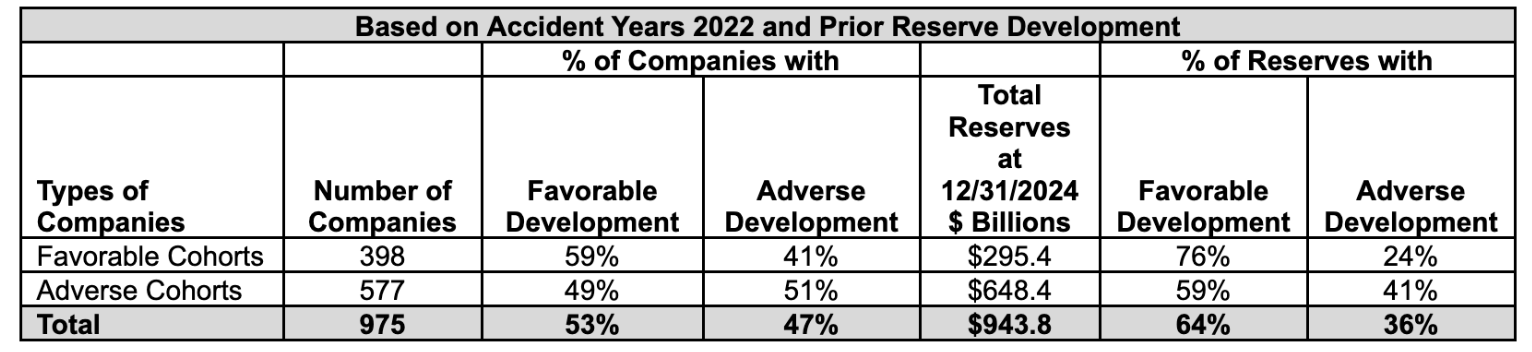
The table below displays development through the third quarter for all lines of business, separated by companies that indicated favorable development for accident years 2022 and prior and those that indicated adverse development.

Based on Accident Years 2022 and Prior  From Annual and Quarterly Statement data via S&P Global Market Intelligence

*Based on Accident Years 2022 and Prior

From Annual and Quarterly Statement data via S&P Global Market Intelligence

For the companies we have summarized that reported third-quarter data, this industry composite displayed little change in prior year reserves for accident years 2022 and prior, with favorable reserve development for accident years 2023 and 2024. 53% of the companies indicated favorable development and 47% of the companies indicated adverse development for accident years 2022 and prior. We note that reserve development differs by company in the amount and magnitude due to the lines of business written.

The quarterly data reported to the NAIC is not presented in the same level of detail as the year-end data, as Quarterly Statements display development for all lines of business combined. Therefore, we segregated the companies into different groupings based on our assessment of the type of business the companies write. Additionally, the quarterly development is only available for accident years 2022 and prior, 2023 and 2024.

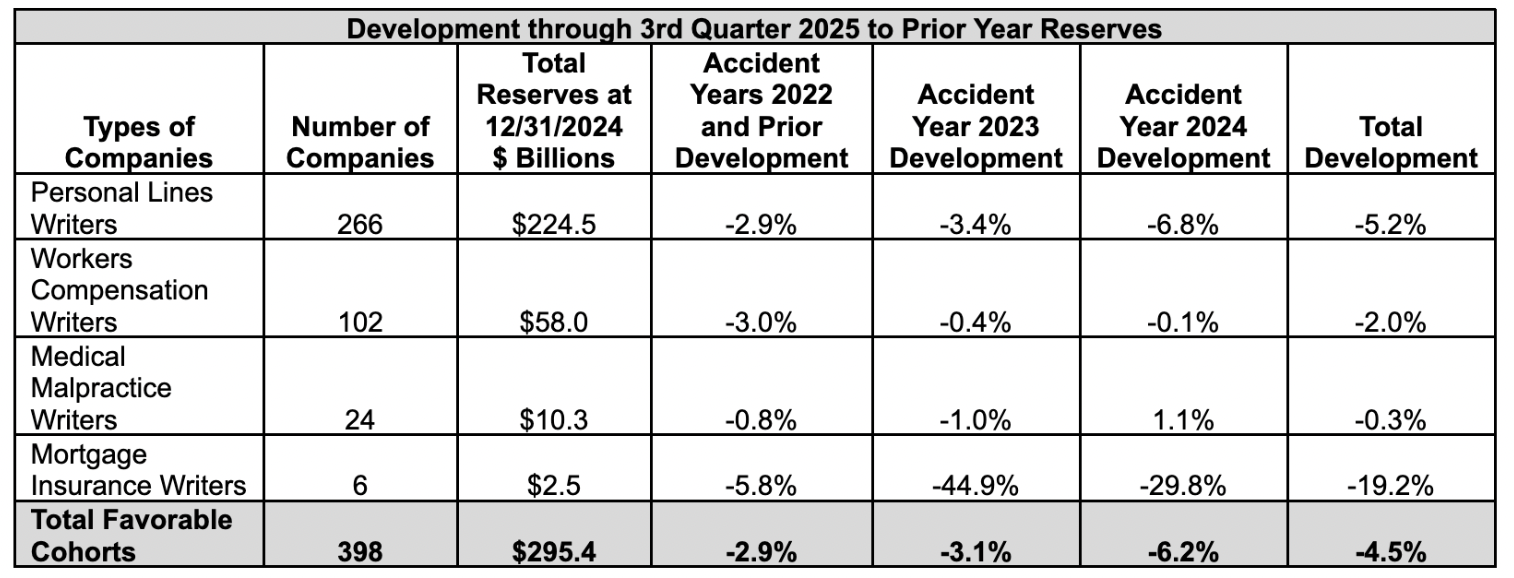
The cohorts of companies that primarily write personal lines business, workers compensation business, medical malpractice business and mortgage insurance displayed favorable reserve development for accident years 2022 and prior, and also for accident years 2023 and 2024. Personal lines business as well as workers compensation business are lines generally less affected by social inflation. For accident years 2022 and prior, the total combined reserves for these cohorts of companies developed favorably by approximately 3%.

Development through 3rd Quarter

From Annual and Quarterly Statement data via S&P Global Market Intelligence

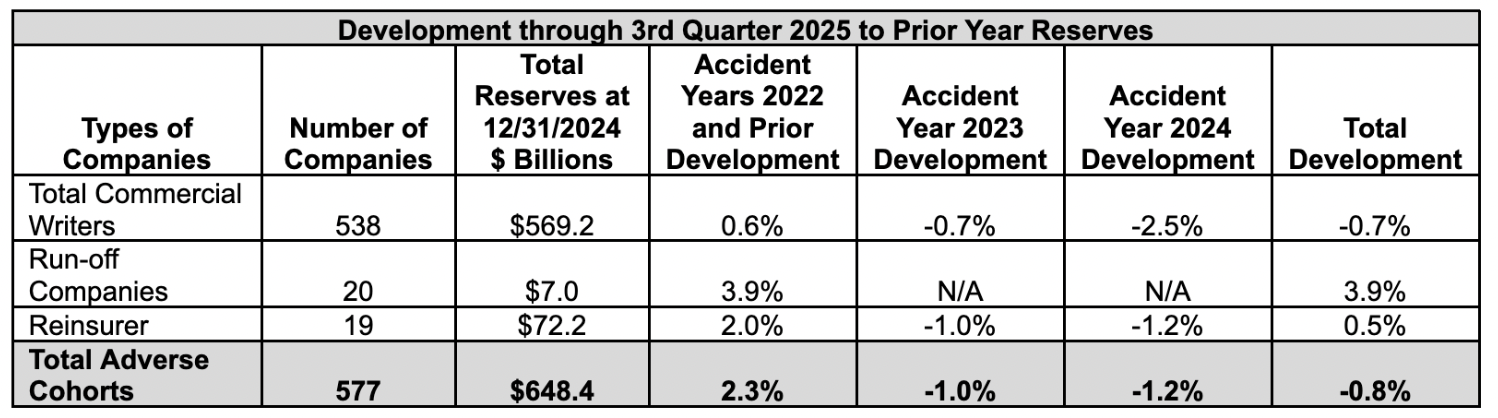
However, the cohort of companies that write primarily commercial insurance, companies in run-off, and reinsurance companies displayed adverse development for accident years 2022 and prior.

Development through 3rd Quarter

From Annual Statement data via S&P Global Market Intelligence

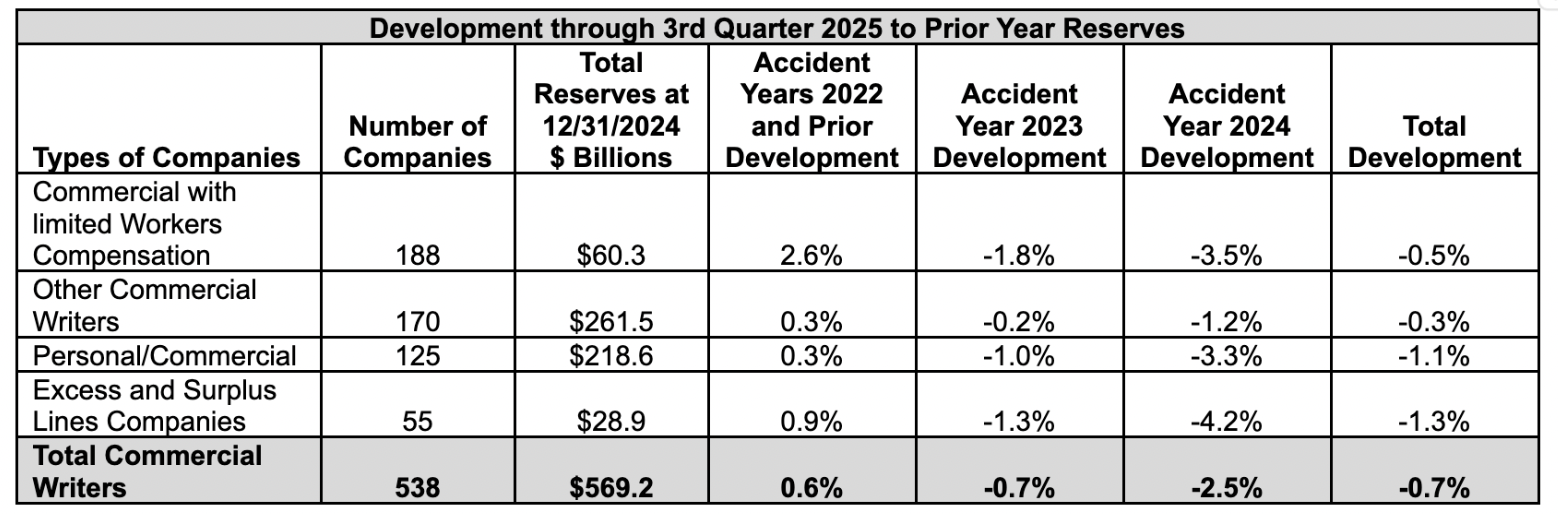
Drilling down within the commercial lines writers provides additional insights. The following table displays the reserve development for commercial lines writers that:

  • write limited amounts of workers compensation;
  • write both commercial and personal lines;
  • are excess and surplus lines companies; and
  • are writers of other commercial lines of business including workers compensation (i.e., "other commercial writers").
Development through 3rd Quarter

The cohort of companies that primarily write commercial lines with limited workers compensation business displayed higher adverse development (2.6% of adverse development for accident years 2022 and prior) compared to their more diversified peers that also wrote either workers compensation or personal lines (these cohorts displayed 0.3% of adverse development for accident years 2022 and prior). It is reasonable to assume that commercial lines carriers that are more diversified (e.g., write workers compensation or personal lines business) are benefiting from the favorable development on these lines which mitigates the development they may be experiencing in their commercial business.

The cohort of commercial companies with limited workers compensation business also write commercial automobile liability. The companies that primarily write commercial auto liability are displaying higher adverse development. We did not separately segregate these companies as the reserve base is limited and the development is driven by a few companies. Commercial auto liability is a line of business more affected by social inflation that has had significant rate increases and re-underwriting over the past few years, which increases the uncertainty in the reserve estimation process.

We note there is variability within the various cohorts and for certain cohorts of companies, a few large carriers had a significant effect. Within the "favorable" cohorts, 41% of companies posted adverse development for accident years 2022 and prior. Conversely, 49% of insurers in "adverse" cohorts reported favorable development for those same accident years. For the lines of business affected by social inflation, prior years' development hinges on how effectively each insurer has captured social inflation effects in past analyses and how aggressively they are recognizing those pressures today.

Based on Accident Years 2022 and Prior

Favorable cohorts: Companies writing personal lines, workers compensation, medical malpractice and mortgage insurance

Adverse cohorts: Companies writing commercial business, companies in run-off and reinsurers

Given the factors outlined, we expect unfavorable reserve development to persist for certain lines of business and companies. However, favorable and adverse development will affect insurance carriers differently depending on the lines of business they write and their prior recognition of social inflation in the actuarial methods.

Although accident years 2023 and 2024 are generally indicating a favorable run-off, we have a concern that adverse development will occur in these accident years as the historical adverse development may not be fully reflected in the actuarial assumptions.

To reflect social inflation in actuarial methods, we recommend companies:

  • Reevaluate the expected loss ratios that are used in actuarial methods to not only reflect historical adverse development but also current claim activity; and
  • Separate lines of business into more granular groupings which segregate those segments more affected by social inflation and those less affected by social inflation (e.g., litigated versus non-litigated claims).

After year-end 2025 data is released, we will publish a companion article that presents updated results with more details by line of business, along with greater discussion on how to adjust actuarial methods.


Brian Brown

Profile picture for user BrianBrown

Brian Brown

Brian Brown is a principal and consulting actuary for Milliman.

His areas of expertise are property and casualty insurance, especially ratemaking, loss reserve analysis and actuarial appraisals for mergers and acquisitions. Brown’s clients include many of the largest insurers/reinsurers in the world.

He is a past CAS president and was Milliman’s global casualty practice director.

Life Insurance Plummets Among Gen Z

Insurers must redesign products, emphasizing relevance, simplicity, affordability and flexibility to attract younger policyholders.

Two young people sitting in a cafe with windows drinking espresso

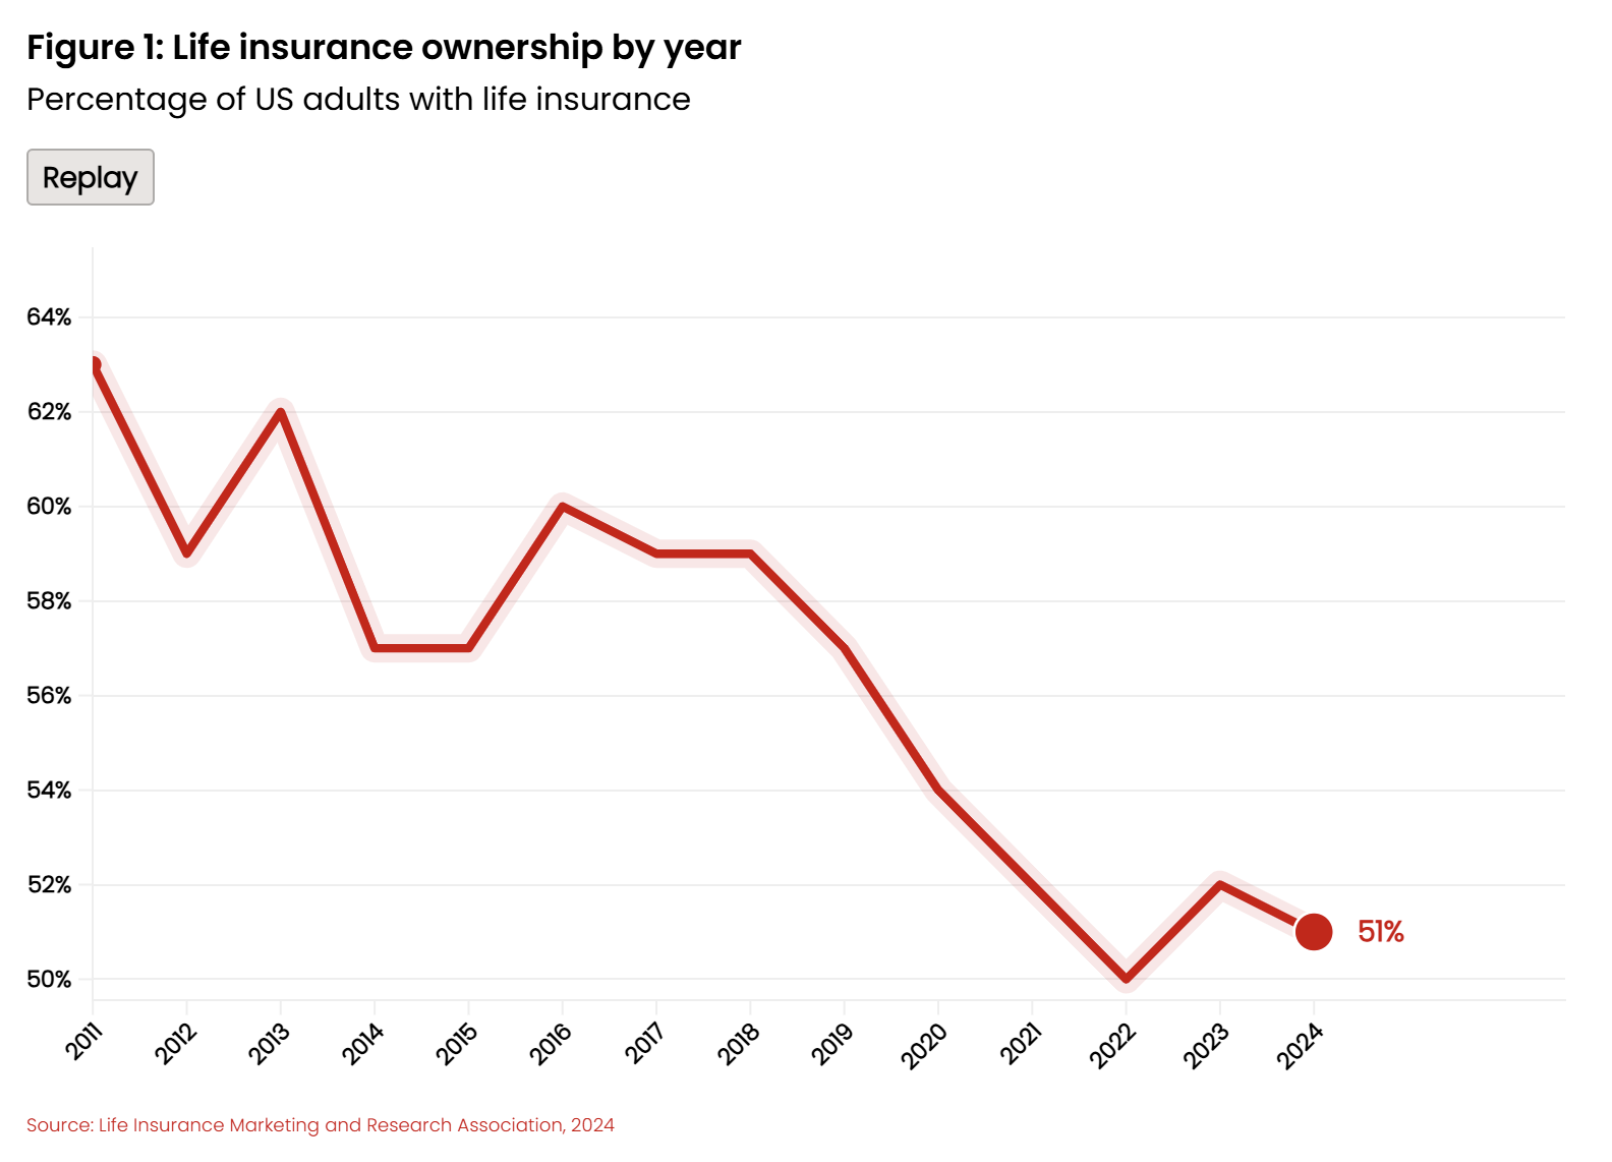
Today's 25-year-olds are far less likely to have life insurance than the 25-year-olds from the late 20th century. In 1989, for example, 65% of adults aged 20 to 39 owned some form of life insurance; by 2025, that total dropped to as low as 36% of Gen Z members.

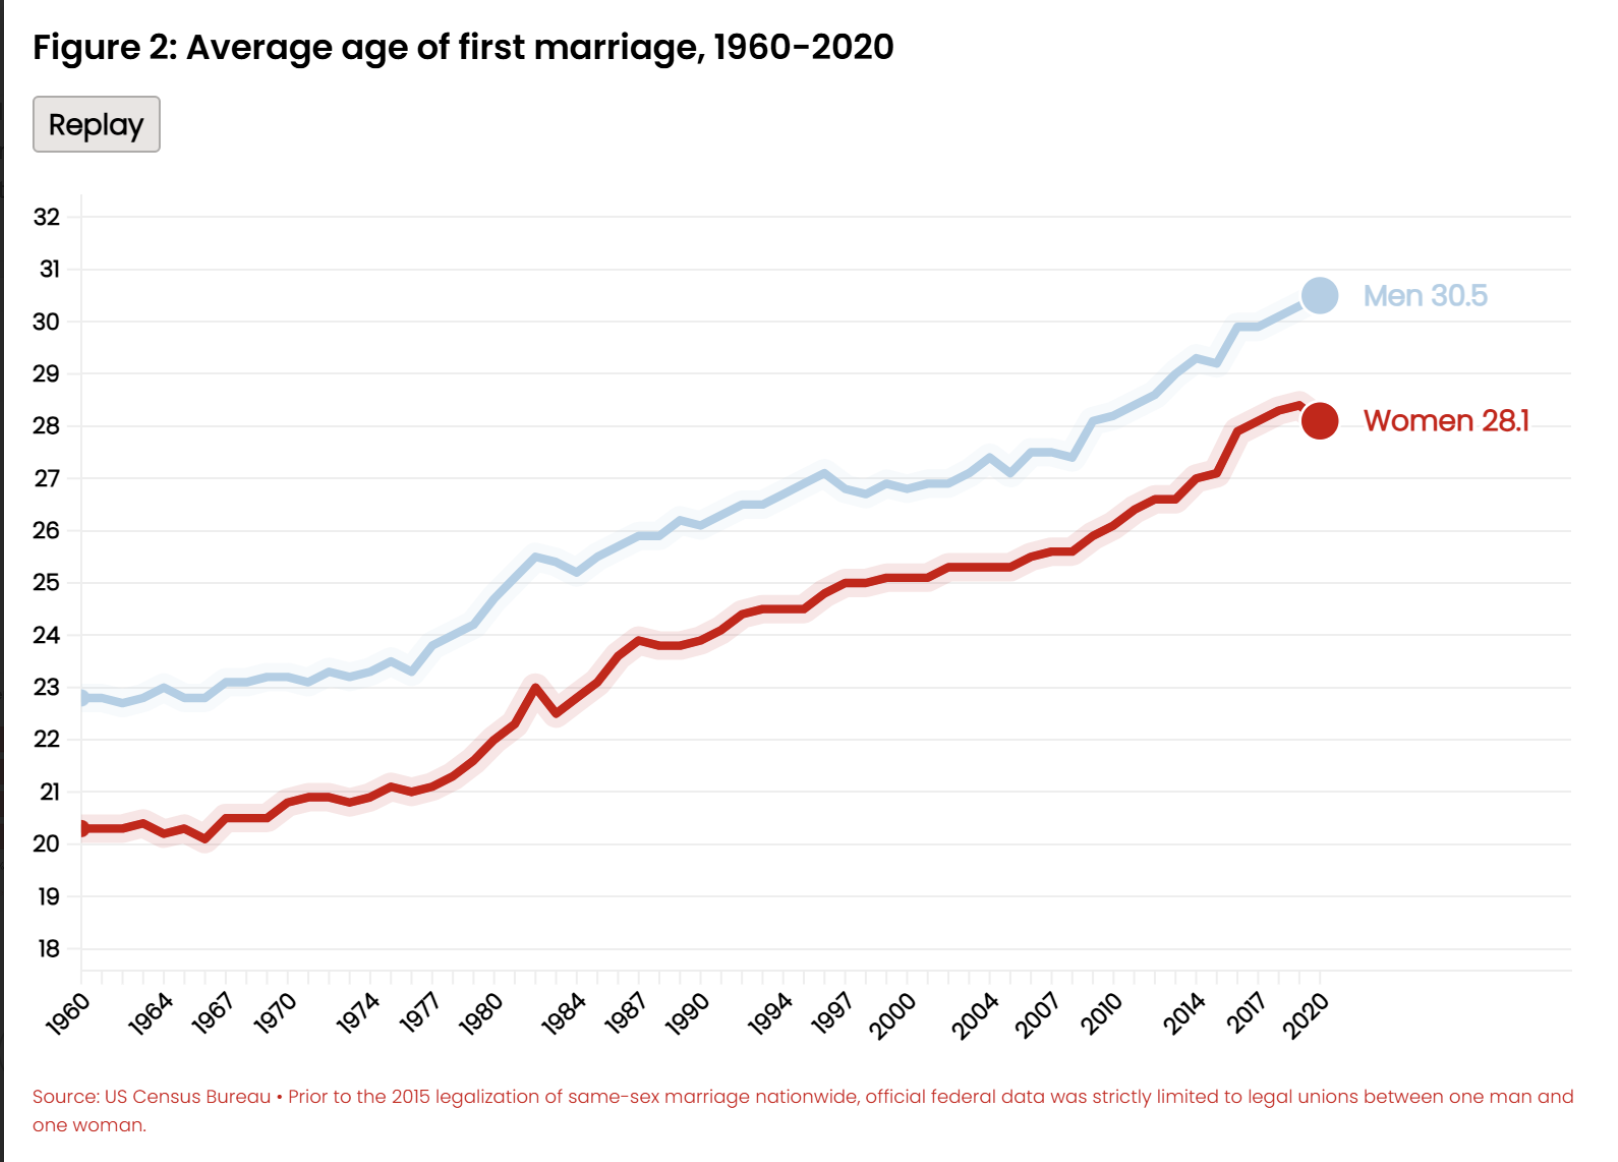
Though part of a general trend toward less life insurance ownership today (Figure 1), the reasons behind the decline among younger consumers are distinct, according to LIMRA and Capgemini's recent World Life Insurance Report 2026. Among them: Historical triggers such as marriage and parenthood aren't happening as soon for today's under-40 consumer – if they happen at all.

This is just the latest data point that spotlights the challenge of selling insurance to the next generation.

For insurers seeking to attract and turn young customers into long-term policyholders, it is essential to develop tailored solutions that address their needs and perceived challenges. RGA's research and experience reveal four key design considerations – relevance, simplicity, affordability, and flexibility. By incorporating these four factors into product development, insurers are starting to find success in attracting younger generations.

Why are young consumers not buying life insurance?

Delays in life milestones that historically prompted insurance purchases present a challenge for the industry. The average age at which a man and a woman marry today has increased approximately eight years since 1960, from 22.8 to 30.5 for men and 20.3 to 28.1 for women.

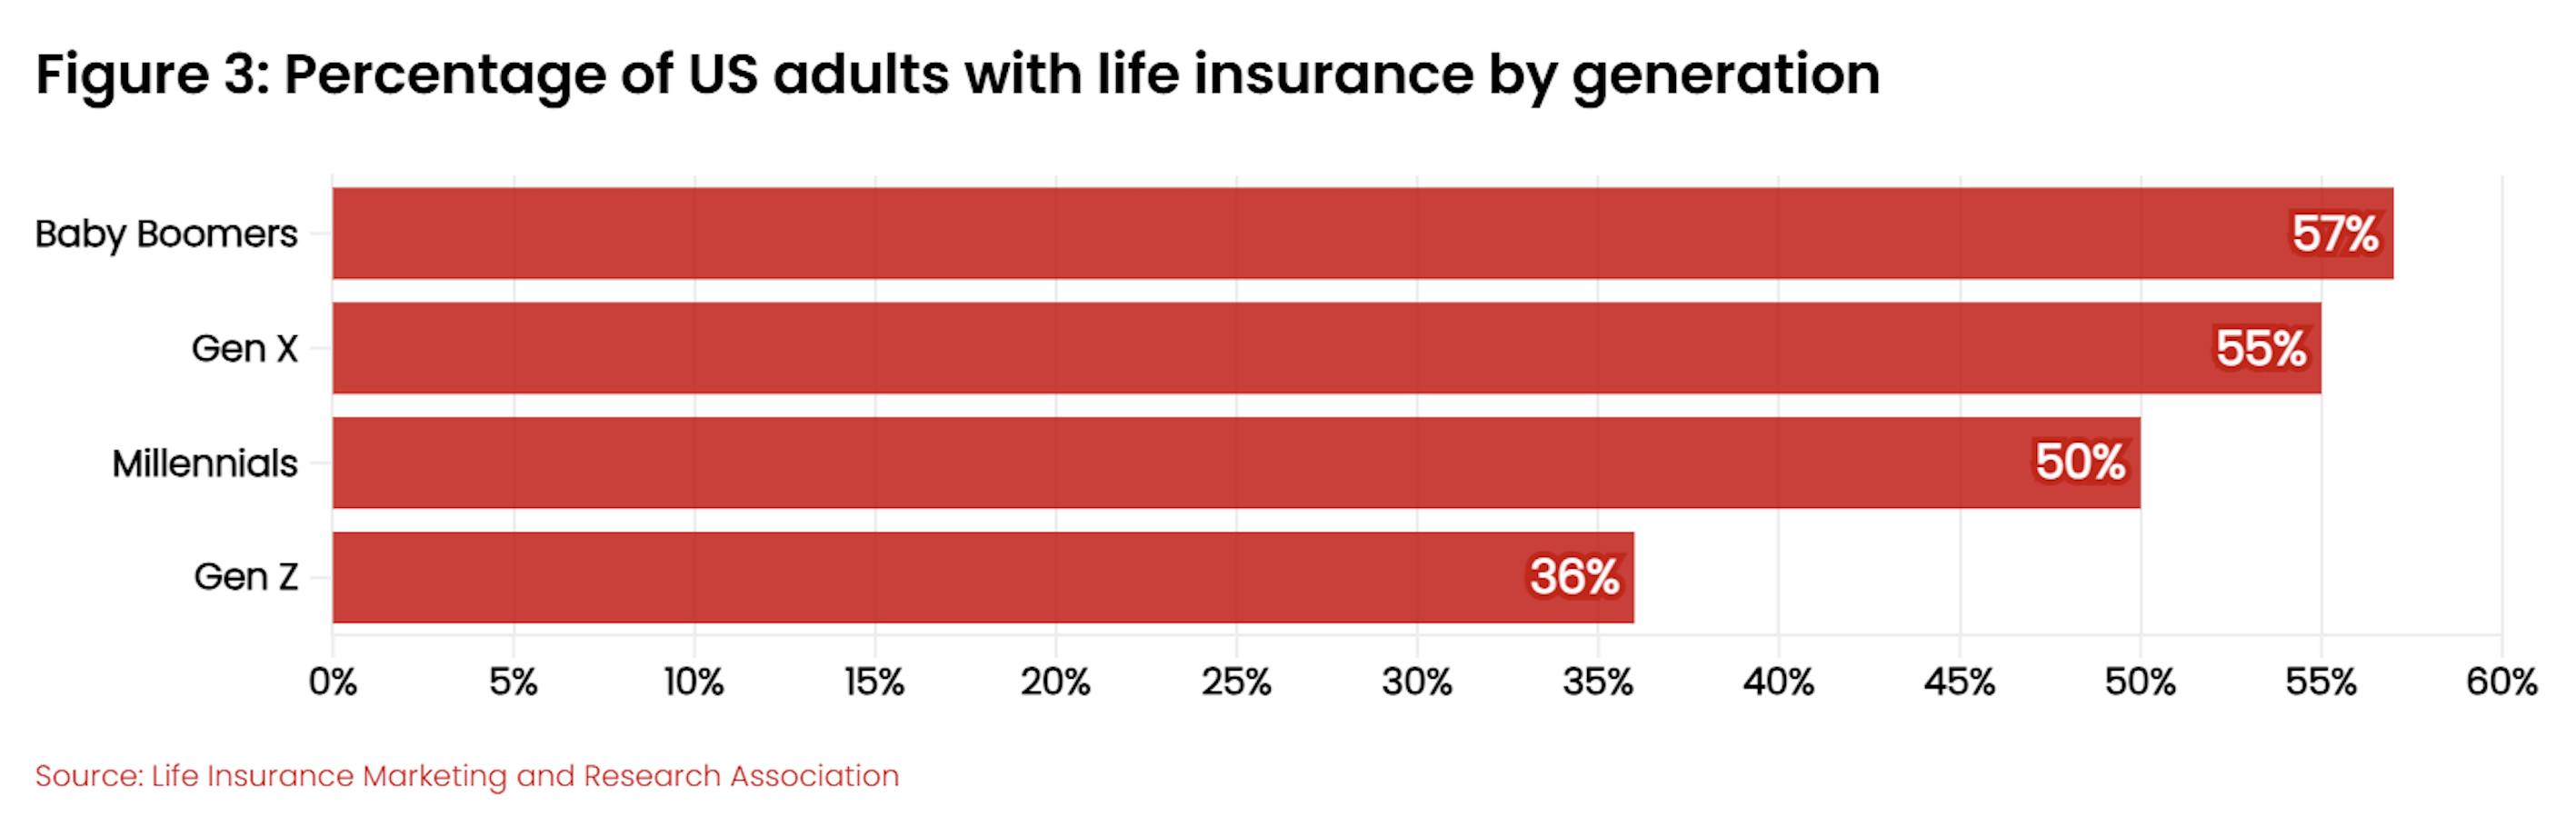
The LIMRA survey also revealed that 63% of consumers under the age of 40 have no immediate marriage plans, and 84% of both single and married under-40 adults have no immediate plans to have a child. This could be a contributing factor behind data showing Gen Z life insurance ownership is more than 20 percentage points lower than it is for Baby Boomers, and 14 percentage points lower than their own next-closest generation, Millennials (Figure 3).

This decline is not due to lack of intent. More than a third (39%) of consumers said in a 2023 U.S. survey they intend to purchase life insurance in the coming year, with higher numbers for Gen Z (44%). Yet those intentions are not turning into actual purchases in sufficient numbers to halt or reverse declining sales.

The reasons younger consumers give for failing to purchase the coverage they know they need suggest opportunities for insurers to develop new solutions addressing those challenges, which include:

  • Concerns around affordability, real or perceived
  • Uncertainty about protection needs and what products to purchase, indicating potential product complexity or lack of relevance from existing offerings
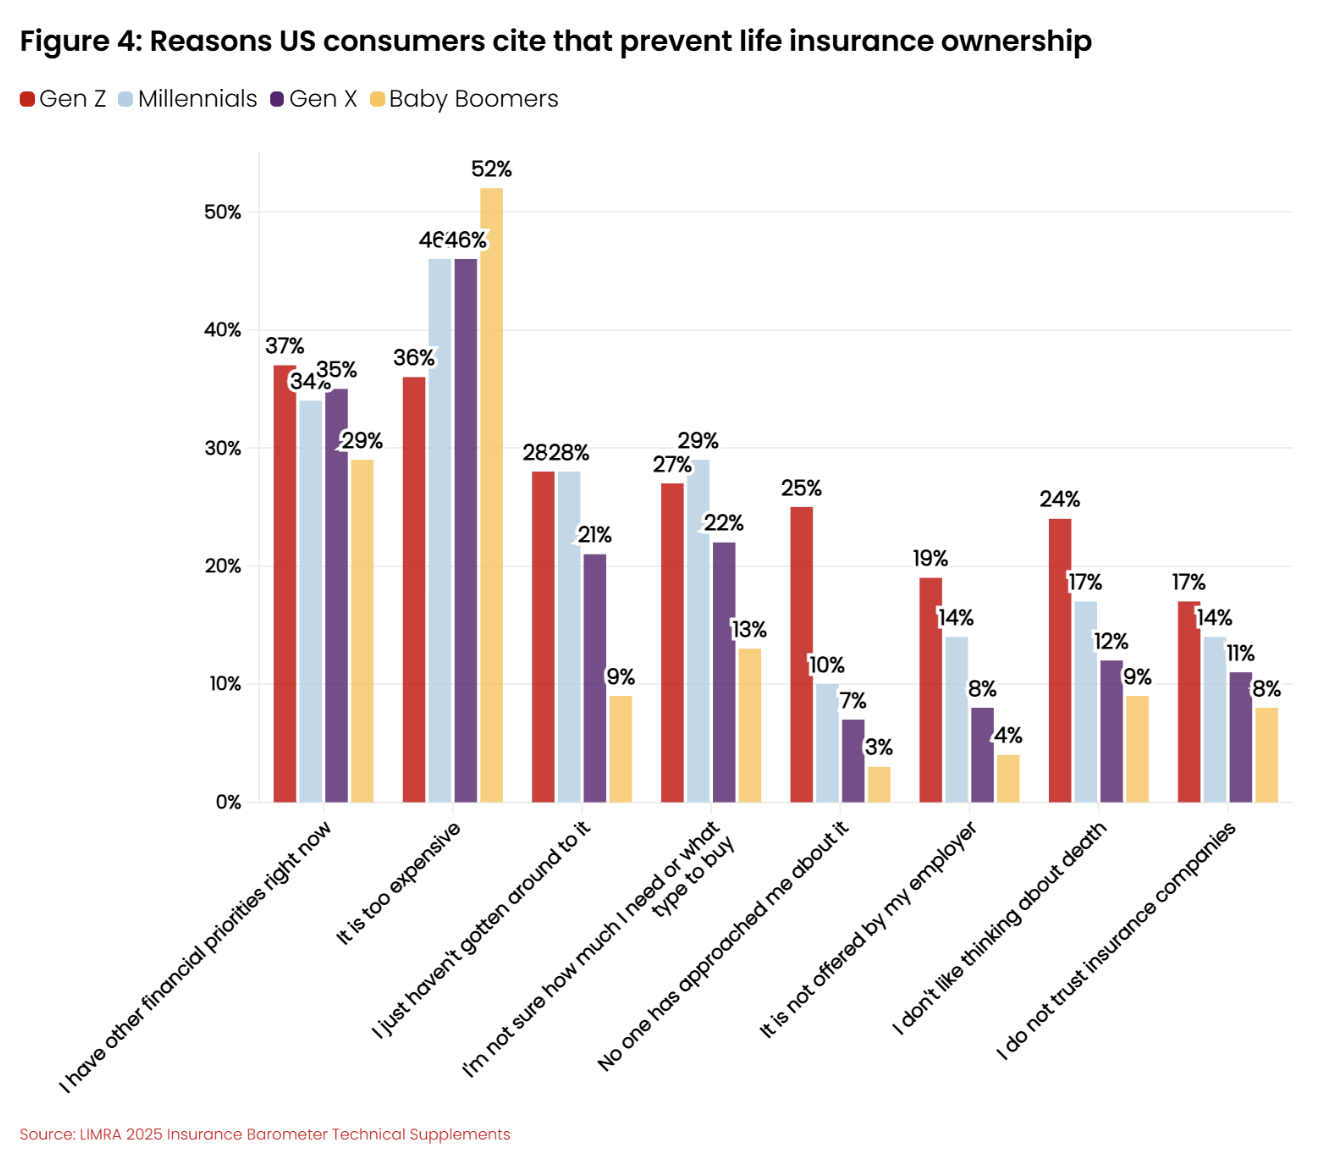
  • Lack of access, pointing to the limitations of traditional life insurance distribution models for reaching that demographic, as evidenced by the larger share of Gen Z and Millennials saying that no one has approached them about life insurance, or that it is not offered by their employer, relative to survey respondents from older generations

Designing life insurance solutions for younger consumers

Insurers have an opportunity to design life insurance propositions that are tailored to the needs of younger customers and that address the concerns they have identified. In doing so, the following design principles should be considered:

  • Relevance of the offering, including the core insurance benefits, value-added services or perks, and the distribution approach
  • Simplicity, including easy-to-understand insurance benefits and terms, authentic language, and streamlined processes
  • Affordability of the overall proposition, both real and perceived
  • Flexibility of the coverage and payment options
Relevance

Young consumers are not a monolithic group. They range in stage of life from those just graduating high school through those who could be considered mid-career professionals.

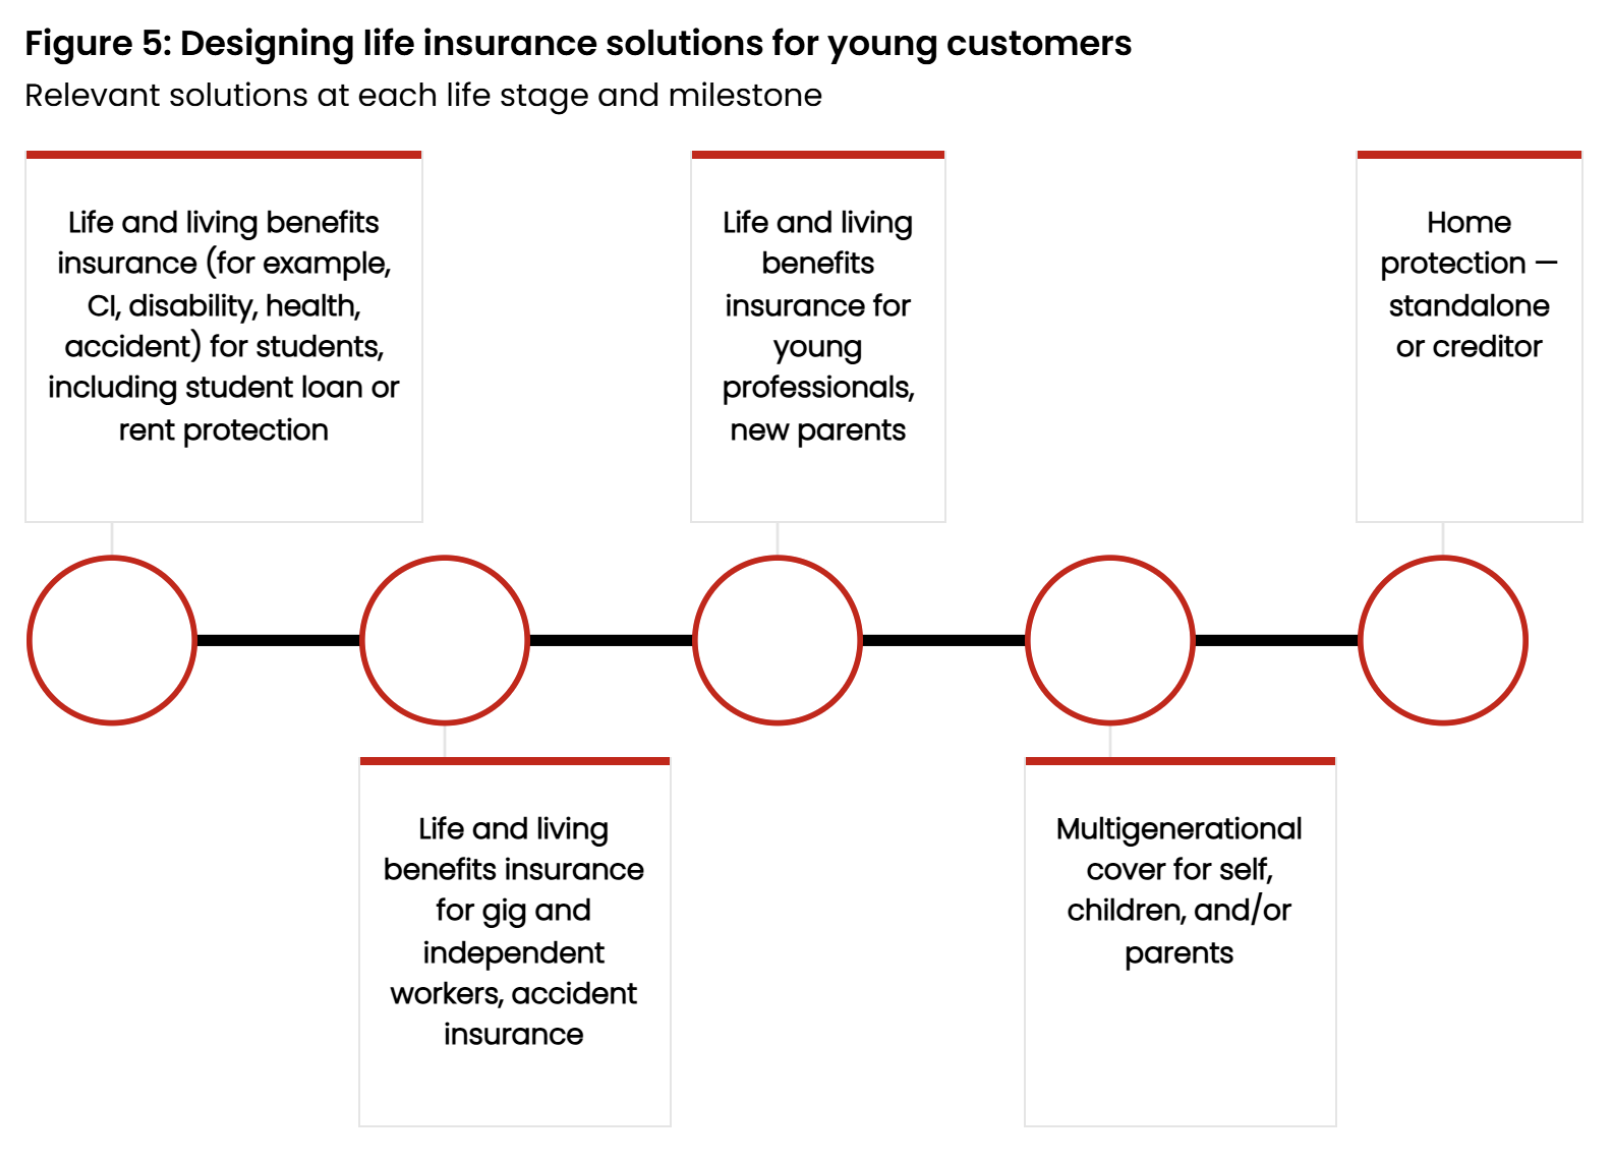
Insurers can design and offer more relevant insurance products that align with key milestones and associated protection needs across this timeline, including life insurance products that offer value-added services relevant to younger consumers. Distribution approaches may also need to be adapted to different life stages, to help mitigate the concerns mentioned by younger customers about lack of access. This may involve considering alternative distribution approaches through partnerships with companies that already have a relationship with younger customers, rather than relying exclusively on traditional distribution models.

For example, home prices in India have increased 1,500% in the past three decades, according to one estimate. That has led more people to delay home purchases and rent instead. One digital real estate marketplace in India partnered with an embedded insurance startup to offer a rent protection plan that can be purchased with a click of a button when consumers submit their online rental payments. Premiums are embedded into the monthly rent payment workflow. Benefits include critical illness coverage from 15 conditions, a personal accident payment, and medical expenses in case of accidental hospitalization.

Increased relevance can lead to growth in the younger-consumer market. Once this younger generation is familiar with a relevant, affordable form of coverage, they can grow into other products as new life events occur and protection needs emerge – from home purchases to marriage to children.

Simplicity

Young consumers have indicated their uncertainty about how much coverage they need and which product to buy (Figure 4). This is likely in part due to the perceived complexity of existing insurance products, and of the language used to describe policy benefits and conditions. Insurers have an opportunity to design simple and easy-to-understand products that young consumers may be more comfortable purchasing, particularly in cases where they have limited access to advisors.

There is also an opportunity to leverage behavioral science techniques to increase comprehension. RGA's research shows that making key policy details more salient, such as by using FAQs or visuals, and improving the relevance of the information presented, for example by leveraging tools and calculators, as well as using video content, can significantly improve comprehension and engagement in digital life insurance customer journeys. These strategies should be particularly relevant for younger demographics accustomed to consuming visual content on social media platforms.

Furthermore, real-world case studies show that improved comprehension through behavioral science techniques can lead to a 48% increase in policy renewal rates and a 32% reduction in policy cancellation rates.

Insurers also need to continue streamlining the life insurance purchase journey they offer to match younger consumers' expectations based on the experiences they're accustomed to from the apps they use daily. As an example, a digital life insurance distributor partnered with RGA and insurers in Canada to offer easy-to-purchase term life and critical illness insurance products, which have achieved success in the market, particularly with younger customers. They offer a streamlined digital customer journey, which allows users to complete a jargon-free fully underwritten application in as little as 20 minutes and receive an instant decision if eligible.

Affordability

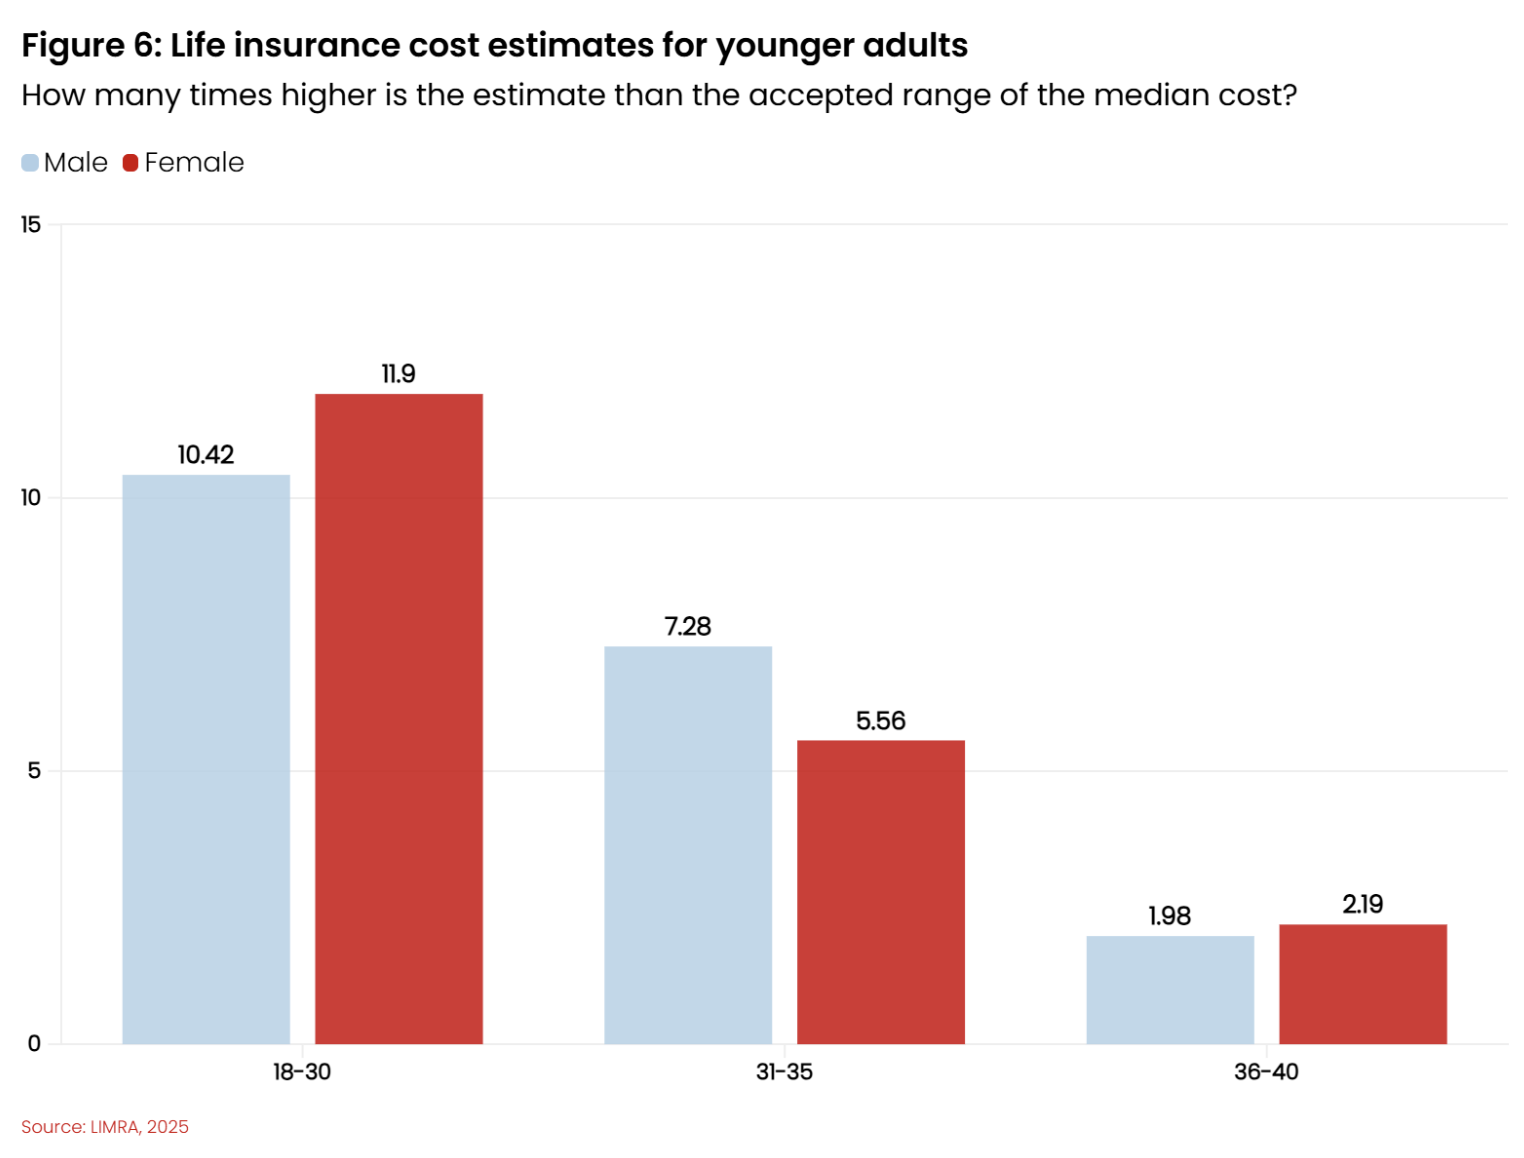
The insurance industry is battling a perception problem. One of the most frequently cited reasons for not having life insurance is that it is too expensive. But when asked for a cost estimate, younger consumers are far more likely to give a price far above the median than older consumers.

Innovations attached to low-cost products offer a direct way to change the narrative.

For example, an RGA-supported effort with a bancassurance product uses banking data to assess the risk of applicants and offer discounts to those who prove to be better risks. This tends to favor younger consumers, who generally are also healthier. Discounts range up to approximately 20% for the lowest risk segments.

Insurers can also address affordability concerns by offering benefits that young consumers appreciate and are able to use today, enhancing the overall value proposition of life insurance. For example, a life product sold through one of the largest retailers in Spain incorporates a wellness rewards program that provides incentives for physical activity. The product includes a mobile app that tracks daily steps and syncs with popular activity trackers. Clients can earn maximum rewards by averaging 10,000 or more steps per day. The program rewards users for maintaining an active lifestyle by converting their daily steps into monetary rewards, which can be accumulated and redeemed as gift cards.

The offering is tied to a popular shopping destination, and is the first insurance product in Spain rewarding customers for wellness activity. It attracts younger people by offering a relevant, simple, and affordable living benefit that encourages healthier living through flexible rewards.

Some items insurers must consider in balancing costs and customer cover include:

  • Full underwriting vs. simplified (or even guaranteed) issue
  • Level vs. YRT premiums, including any premium guarantees
  • Basic life cover vs. accidental cover vs. comprehensive covers, including critical illness and disability

This leads directly to the final consideration.

Flexibility

People tend to procrastinate until they see a solution that matches their unique needs. Young people need to see insurance products relevant to them. Each customer has specific needs that must be balanced in coverage type and levels, premium structures, and underwriting.

For example, offering low and affordable covers initially that can flex as life events occur – such as home purchases, marriages, parenthood – or have the option to renew or convert into further insurance covers can be seen by younger consumers as relevant to their lives right now and, thus, individually tailored.

Similarly, while full medical underwriting traditionally leads to the lowest premium for healthy applicants, it can be too complex, and a barrier to entry, for younger consumers used to quick purchases. Offering flexible options that accommodate different trade-offs between price and customer experience can help address the wide range of needs expressed by younger consumers, from the most cost-sensitive, to those prioritizing the smoothest customer journey.

Conclusion: Gaining customers for life

The insurance industry is seeing a change in life triggers, not an evaporation. Marriage and children might be happening later, but other milestones exist for insurers to offer relevant, simple, affordable, and flexible protection products.

Younger consumers may be harder to convert than in past generations, but product innovations can create a rewarding win-win proposition for both the young policy holder and the insurer.


John Rutherford

Profile picture for user JohnRutherford

John Rutherford

John Rutherford is senior vice president – head of global health and chief of staff – continental Europe, at RGA.

He leads RGA’s global, multidisciplinary team of health specialists as well as the technical teams (actuarial pricing, underwriting, claims and treaties) supporting RGA’s Continental European business.

He began his career in the U.K. direct insurance market before shifting to reinsurance in 1997. He was among the founding members of RGA’s U.K. office and held senior roles at the RGA South Africa office, including serving as chief actuary of the international health business.

Rutherford is a qualified actuary with the Institute of Actuaries in the United Kingdom.

How AI Can Significantly Improve Legal Work

New evidence that AI-assisted lawyers outperform peers puts cautious law firms at a growing competitive disadvantage.

A white background with a colorful swirl

As of early 2026, artificial intelligence (AI) has made only a modest dent in the daily practice of law. Adoption is rising, but cautiously. Many lawyers still avoid AI altogether; others limit its use to narrow, low-risk applications. This restraint sits uneasily alongside the predictions that have circulated since early 2023, when evidence emerged that ChatGPT could earn passing grades on law school exams—and even on the bar exam.

The gap between promise and practice has fed a familiar narrative: if AI were truly transformative, law firms would already look different. Because they largely do not, skeptics argue that AI's disruptive potential has been oversold.

That conclusion gets the timing wrong — and misunderstands what disruption in law actually looks like.

From the beginning, strong performance on exams was a poor proxy for real-world impact. Legal practice is governed by ethical obligations, professional judgment, and client risk—not multiple-choice questions. Lawyers must closely review AI-generated output, especially given well-documented risks of hallucinations and subtle errors. In many contexts, reviewing and correcting AI-assisted work has been slower than producing it directly, or has resulted in lower-quality outcomes than human-only work—particularly when the lawyers involved are highly skilled or when precision matters more than cost savings.

The problem, in short, was not overhype. It was the wrong benchmark.

The question that actually matters is not whether AI can perform legal tasks on its own, but whether lawyers using AI outperform comparable lawyers who do not. Until recently, the answer to that question was unclear at best. Now, emerging evidence suggests it is beginning to turn decisively in AI's favor.

In a recent study, my colleagues and I reported the first randomized controlled trial evaluating two AI innovations with direct implications for legal work. The first is Retrieval-Augmented Generation (RAG), which grounds AI outputs in authoritative legal sources rather than free-form text. The second is the rise of AI reasoning models that structure complex analysis before generating responses.

In the study, upper-level law students were randomly assigned to complete realistic legal tasks using either a RAG-enabled legal AI system, an AI reasoning model, or no AI assistance at all. The results mark a clear break from earlier studies focused on prior generations of large language models. Across multiple tasks, participants using modern AI tools produced meaningfully higher-quality legal work. They also worked much faster. In five of six tasks, productivity increased by between 50% and 130%.

This evidence reframes the AI debate in law. The story is no longer about machines replacing lawyers—or about AI's ability to ace exams. It is about augmentation that finally works: tools that allow lawyers to do better work, in less time, without sacrificing professional standards.

That shift carries real consequences for legal institutions.

Firms that continue to treat AI as an experimental add-on or a compliance risk may soon find themselves at a competitive disadvantage. If AI-enabled lawyers can reliably produce higher-quality work more efficiently, then billing models, staffing decisions, training pipelines, and even partner expectations will come under pressure. Early adopters will not simply save time; they will set new baselines for quality and speed that others will be forced to match.

The implication is clear. The window for cautious observation is closing. In 2026, the strategic question for law firms is no longer whether AI will meaningfully affect legal practice, but how quickly—and whether they will shape that transition or be shaped by it.


Daniel Schwarcz

Profile picture for user DanielSchwarcz

Daniel Schwarcz

Daniel Schwarcz is a profressor at the University of Minnesota law school.  

The author of a leading casebook, he specializes in insurance law, regulation, and the impact of artificial intelligence on law.

He earned his A.B., magna cum laude, from Amherst College and his J.D., magna cum laude, from Harvard Law School.

The Insurance Functions AI Chatbots Can't Replace

AI chatbots streamline routine insurance tasks, but judgment calls, emotional nuance, and complex claims still demand human oversight.

Drawing of robot and human facing each other with laptops and speech bubbles

AI chatbots have become a regular part of how insurance services operate. Customers turn to them to review policies, follow claim updates, or get quick answers without sitting on hold. For insurers, they help handle high volumes of requests while keeping support costs in check.

As these tools become more visible, expectations sometimes drift. Not every task in insurance should be automated, and not every interaction benefits from a chatbot. Understanding where AI chatbots should step back is key to using them well.

This article looks at the functions that still require people, even as insurance chatbots and broader AI insurance services continue to evolve.

Where AI chatbots make sense

There's no question that AI chatbots add value in the right places. Tasks that follow clear rules and don't depend on interpretation are a good fit. Simple policy questions, coverage summaries, payment reminders, and claim status updates are all examples where automation works reliably.

That's why many insurers treat chatbots as the first point of contact. They take on routine requests, ease pressure on call centers, and keep basic information accessible at any time. In that role, chatbots help guide users and filter requests, rather than make final decisions.

Issues usually arise when the same tools are pushed into areas that require judgment, risk assessment, or clear accountability.

Why judgment-based decisions still need people

Many insurance decisions live in gray areas. Coverage disputes, claim denials, and policy exceptions are rarely decided by one clear rule. They usually depend on context, intent, and how similar situations were handled before.

A chatbot can help surface the explanation or point to relevant policy language, but it shouldn't be the authority behind the decision. Once financial impact or legal exposure is involved, a person has to be responsible for the outcome. This boundary matters not just for compliance, but for trust.

AI chatbots in the insurance industry and emotional context

Insurance conversations don't always happen at calm moments. Accidents, property damage, and unexpected losses bring stress with them. Customers often need reassurance as much as information.

AI chatbots in the insurance industry can respond politely and quickly, but they don't genuinely understand emotional nuance. They can't sense frustration building or know when a conversation needs to slow down.

In these situations, escalation to a human agent isn't a failure of automation. It's a necessary part of good service design.

Claims handling beyond the simple cases

Some claims are simple and move quickly. Others take time, context, and careful review.

For low-risk cases with clear documentation, chatbots can play a useful role. Once a claim includes conflicting information, unclear responsibility, or a higher financial impact, automation starts to fall short.

At that point, human adjusters are essential. They review evidence, interpret policy wording, and make decisions that may need to be held up later under review or dispute. Chatbots can assist by organizing information, but they shouldn't own the outcome end-to-end.

Why AI fraud detection still needs people

AI fraud detection is often presented as one of the strongest areas for automation, and in many ways it is. Systems can scan large volumes of data and surface unusual patterns far faster than any manual process.

What these systems struggle with is intent. In real-world use, AI works best as an early filter, pointing investigators toward cases that deserve a closer look and leaving the final judgment to people.

Insurance chatbot use cases that need a handoff

Many insurance chatbot use cases work best when they are set up as shared workflows rather than fully automated paths. The chatbot handles the first interaction, gathers the required information, and then routes the case forward.

Policy changes, renewals, endorsements, and compliance-related questions often fall into this group. Rules can vary depending on region, policy type, or specific circumstances, which means final guidance usually needs confirmation from a person.

In these situations, a smooth handoff isn't a limitation. It's what keeps the process accurate, compliant, and trustworthy.

Negotiation is another clear boundary. Settlement discussions, premium adjustments, and special terms require flexibility and judgment that chatbots don't have.

Conclusion. Why knowing the limits matters

It's easy to judge progress by what AI chatbots can handle. In insurance, setting limits often matters more than expanding capabilities. Chatbots work well for simple interactions, but customers expect human involvement when the stakes rise.

Insurers that design around this reality tend to see stronger outcomes from automation. They gain efficiency without giving up control, and they improve service without undermining trust.

Lessons From LA Wildfires, One Year On

Past wildfire burn areas no longer predict future risk, forcing insurers to embrace climate-aware analytics after Los Angeles's $40 billion loss.

Close-up Photo of Orange Fire

A year after the devastating Los Angeles wildfires of January 2025, the insurance and reinsurance industry is still absorbing the scale of their impact, as well as the lessons learned for future risk assessment. What is now clear is that these fires were not an anomaly but a warning signal for how wildfire risk is evolving in a changing climate.

The financial consequences of the LA wildfires were significant. To date, insurers have paid out approximately $22.4 billion, with total insured losses reaching around $40 billion overall. These figures place this firmly among the most costly natural catastrophe events in recent US history, reinforcing wildfire's status as a primary driver of loss rather than a secondary peril.

The sparks behind the blaze

In the year since, investigators have been able to piece together a clearer picture of how the fires began and why they escalated so rapidly. The initial blaze, the Palisades Fire, was started by human activity. Emergency services believed the fire had been successfully extinguished, but a combination of Santa Ana winds and exceptionally dry conditions caused it to re-ignite, with devastating consequences.

The second major event, the Eaton Fire, was ignited by a nearby power line. While these two fires inflicted the most severe damage, they were only two of 14 separate wildfires that occurred across the region during January 2025.

Climate change also played a central role in amplifying their severity. Heavy rainfall during 2022 and 2023 drove extensive vegetation growth across California. This period of abundance was followed by a prolonged drought, which dried out that vegetation and transformed it into highly combustible fuel. In effect, climate volatility, not just warming, created ideal conditions for wildfire spread.

A global shift in wildfire behavior

The human cost of these events has also been profound. While 31 deaths were attributed directly to the fires, a medical study published in JAMA (The Journal of the American Medical Association) estimates that up to 400 additional deaths may have been caused indirectly, driven by poor air quality and reduced access to healthcare during and after the events. Further, more than 100,000 homes were evacuated, disrupting communities and livelihoods on a massive scale.

Taken together, these impacts underscore a sobering reality: wildfire risk is no longer confined to historically defined burn areas or traditional seasonal expectations. The LA fires echoed patterns seen elsewhere, including the Australian bushfires of the same year, where successive wet years followed by extreme heat produced similarly combustible landscapes.

The diversity of ignition sources - human activity, infrastructure failure, weather-driven re-ignition, and climate change - highlights a critical challenge for risk modelling: wildfire cannot be understood through a single causal lens and the parallels seen across hemispheres point to a global shift in wildfire behavior.

What this means for our industry

For underwriters, the key takeaway is clear and urgent: past bushfire and wildfire burn areas are no longer a reliable predictor of future fires. Historical loss data, while still of value, cannot on its own capture the rapidly changing interactions between climate, vegetation, weather extremes, and ignition sources.

These distinctions matter. The latest wildfire models, such as BirdsEyeView's, for instance, explicitly focus on different ignition mechanisms, recognizing that the probability, timing, and severity of fires vary materially depending on how they start and how environmental conditions evolve around them. Treating wildfire as a homogeneous peril obscures these dynamics and increases underwriting blind spots.

This has significant implications for pricing, accumulation management, and capital allocation. Wildfire has firmly shifted from a 'secondary' peril into a core driver of portfolio performance. Models calibrated on assumptions of climate stationarity risk lagging reality at precisely the moment when precision matters most.

Progress lies in prediction

Looking ahead, the industry's ability to adapt will depend on its willingness to embrace climate-aware, data-driven analytics. Advances in satellite observation and machine learning now allow us to monitor fuel load, vegetation stress, and environmental conditions in near real time, enabling earlier detection of emerging risk patterns and more responsive underwriting decisions.

The lessons from the LA wildfires, one year on, are therefore not only about loss – they are about learning. If reinsurers and insurers can move beyond retrospective modelling and adopt adaptive intelligence, they will be far better positioned to navigate the growing volatility of wildfire risk.

In a world where climate dynamics are rewriting the rules, resilience will belong to those who can see risk forming before it ignites.


James Rendell

Profile picture for user JamesRendell

James Rendell

James Rendell is the founder and CEO of BirdsEyeView. 

The company delivers deliver natural catastrophe risk and exposure management software to (re)insurers, MGAs, and brokers. 

Rendell previously held reinsurance brokerage roles at JLT Re and Guy Carpenter.

OK, 1 More Innovation Lesson From the NFL

I usually limit myself to one commentary a year drawing on doings in the NFL, but the mass firings of head coaches this year merit another quick observation.

Image
hands snapping a football

When the Buffalo Bills fired head coach Sean McDermott on Monday, that brought the number of top jobs vacated this season to 10. That struck me as a huge number, out of just 32 such positions. I'm accustomed to six or seven, maybe even eight. 

It turns out that the 10 departures this year are the most since... the end of the 2022 season. And eight of the 10 hires from three seasons ago have already been fired. 

I realize I have the luxury of surveying the frenzied hiring and firing as a lifelong fan of the Steelers, who have had precisely three head coaches since 1969. (There have been six popes in that same stretch.) The first two of those Steeler coaches are in the Hall of Fame, and Mike Tomlin, who resigned last week after 19 seasons, will surely join them when he becomes eligible. 

It's obviously not helpful to tell teams that they, too, should hire Hall of Fame coaches, but I do think lots of teams are getting one thing very wrong — and anyone leading an innovation effort, including at an insurance company, may be tempted to make the same mistake. 

Basically, too many teams don't have a long-term vision. They think they do, but they don't. So they lose patience too quickly. They get twitchy when the results aren't there immediately and move on to the next coach or general manager or both, only to pull the plug on them too quickly, too. As I wrote two weeks ago — in what I thought would be my one NFL reference for the year — the impatience is partly because owners get focused on the outcomes of their choices, rather than on whether they made a good bet. 

Owners ask: Did we win the Super Bowl this year? They don't ask: Did we put ourselves in a good position to have a chance to win? They don't ask: Are we putting together the pieces for the next several years? They ask: Did we win this year?

That sort of thinking is how you become the Cleveland Browns. Since the 1999 season, when the team was reconstituted after the original franchise moved to Baltimore and became the Ravens, the Browns have had 12 head coaches and are about to hire their 13th. In those 27 seasons, they've won 33% of their games and zero titles in the four-team AFC North. They've played in all of four playoff games, winning one.

Yet the Bills have decided to follow suit. They fired McDermott even though he took the Bills to the playoffs in the last seven seasons and in eight of his nine seasons as head coach. They made it to the conference championship twice, losing both times to the formidable Chiefs. The Bills hadn't been to the playoffs in the 17 years before McDermott arrived. Who do they think they'll get who'll be better? 

Firing Pete Carroll as the head coach of the Las Vegas Raiders after one season? Sure, the Raiders were an awful 3-14 this season, but that's only one game worse than their record for the 2024 season, and they'd had losing records in 2022 and 2023, as well. You're telling me they didn't know what they were getting in a 74-year-old coach who, among many other things, had just coached for 14 seasons in Seattle? I have no idea whether he was the right fit in Las Vegas, but either Raiders ownership was too quick to commit to him as the turnaround guy a year ago or was too quick to bail after this season. In either case, the Raiders showed they're dysfunctional.

By contrast, when the Steelers hired Chuck Noll in 1969, he was a 37-year-old with no track record as a head coach and went 1-13 in his first season. He had losing records in his second and third seasons, too. But he was putting the pieces together, the Rooney family stuck with him, and the magic started happening in season four.

When the Cowboys hired Jimmy Johnson as head coach in 1989, he went 1-15 his first season. But he and owner Jerry Jones had a long-term vision largely based on the eight draft picks, including three first-rounders, they got for trading Herschel Walker to the Vikings. By season four, Dallas was winning the first of the three Super Bowls it took in four years.

The Cowboys actually demonstrate both patience and impatience. After Johnson led the team to two Super Bowls, Jones felt Johnson was getting too much credit. So — in what I believe is the dumbest decision ever by the owner of a sports franchise — Jones fired Johnson and brought in another college coach who had won national championships to try to show that just about anyone could win with the juggernaut Jones, the self-proclaimed genius, had put together. The Cowboys did, in fact, win one more Super Bowl, but then got twitchy as Jones took more control and have never recovered. The Cowboys have won five playoff games in the last 30 seasons and have never even made it back to a conference championship game. 

What Should Insurers Do?

Insurance companies have a luxury that NFL franchises don't: They don't have to deal with hundreds of podcasts by rabid fans who want to fire everybody any time someone fumbles a football. 

Still, insurance companies have to answer to shareholders, and they do have to succeed. That means innovation efforts, especially related to generative AI, need to fit into a long-term vision. They can't be one-offs, because those are too easy to kill. And the efforts can't be judged based just on whether they succeeded or on any other short-term indicators. 

The right questions are: Were they good bets? Did we learn something important? What do we do next to build on what we just learned?

Early on, it was at least okay to do broad experiments with Gen AI. People needed to get comfortable with the concept, and the applicability was somewhat nebulous. But we're more than three years into the Gen AI revolution now, so it's time to do more long-term planning about how Gen AI can both make your organization more efficient and about how it might even let you make more radical changes to your business model. 

Once you've laid out that vision, you have to stick with it. None of this firing the coach or heading off in a new direction the first time something unexpected happens. And the commitment has to be communicated from the top of the organization, repeatedly, so people know this isn't just a phase that they can assume will pass them by if they just keep their heads down. 

I can't guarantee success. Even my Steelers haven't won a playoff game since 2017, and there's no guarantee we won't pick a dud as head coach this time. Dan Rooney played a major role in hiring all three of our coaches since 1969, and he died in 2017. But I can guarantee that taking a stable, long-term approach means you won't be the Cleveland Browns. 

Cheers,

Paul

P.S. How committed have the Steelers been to their head coaches for the long term? My father once told me an illustrative story that was passed on to him by a friend who was the PR guy for the Steelers in the 1970s and 1980s. 

Now, my father was a hail-fellow-well-met, Irish storyteller type, but his stories always started out based on something that actually happened, and I choose to believe this took place just as my father described: 

The PR guy said he was sitting in Noll's office at the end of a workday, when Dan Rooney stuck his nose in. 

Rooney said, "Chuck, I put your contract in your in-box. I left the numbers blank because it's your turn to put them in this year." 

Noll responded, "No, no, it's your turn. I put the numbers in last year."

Rooney said, "I checked. I did the numbers last year. Just put the contract in my in-box when you're done, and I'll sign it in the morning. Have a good night."

Cyber and AI Top 2026 Business Risks

AI surges to second-biggest business risk from tenth place as cyber incidents retain top ranking for the fifth consecutive year.

Code Text on Tilt Shift Lens

Cyber incidents created many headlines in 2025 and are still the biggest worry for companies globally in 2026, according to the just released Allianz Risk Barometer. The past year has also been a significant one for accelerated adoption of artificial intelligence (AI), which is reflected in its ranking as the biggest riser in the annual survey at #2. Close to half of survey respondents believe AI is bringing more benefits to their industry than risks. However, a fifth say the opposite.

The Allianz Risk Barometer is an annual business risk ranking compiled by Allianz Group's corporate insurer Allianz Commercial together with other Allianz entities. Now in its 15th year, the Risk Barometer incorporates the views of 3,338 risk management experts from almost 100 countries and territories and identifies the main perils risk management practitioners are expecting in 2026.

Cyber risks by far the biggest concern for companies

In 2026, cyber incidents are the top global risk for the fifth year in a row, with its highest-ever score (42% of responses), and by a higher margin than ever before (+10%). It ranks as the main corporate concern in every region (Americas, Asia Pacific, Europe, and Africa and Middle East).

The continued presence of cyber at the top of the Allianz Risk Barometer reflects a deepening reliance on digital technology at a time when the cyber threat landscape, and geopolitical and regulatory environments, are fast evolving. Recent high-profile cyber-attacks underline the continuous threat for businesses of all sizes. Smaller and mid-sized enterprises are increasingly targeted and under pressure due to a lack of cyber security resources.

AI creates emerging risks as well as new business opportunities

AI has surged into the top tier of global business concerns, rising to #2 (32%) in 2026 from #10 in 2025 – the biggest jump in this year's ranking. It is a big mover in all regions – ranked #2 in the Americas, Asia Pacific, and Africa and the Middle East, and #3 in Europe – and is a growing risk for companies of all sizes too, moving into the top three for large, mid-sized and smaller firms.

As AI adoption accelerates and becomes more deeply embedded in core business operations, respondents expect AI-related risks to intensify, especially when it comes to liability concerns. The rapid spread of generative and agentic AI systems, paired with their growing real-world use, has raised awareness of just how exposed organizations have become.

Business interruption strongly connected to geopolitical risks

2025 marked a shift towards protectionist trade policies and tariff wars that brought uncertainty to the world economy. It was also a year of regional conflicts in the Middle East and Russia/Ukraine, as well as border disputes between India/Pakistan and Thailand/Cambodia and civil wars in Africa – a trend which continues in 2026 with the U.S. intervention in Venezuela.

Geopolitical risks are putting supply chains under increasing pressure, but as risks rise, just 3% of Allianz Risk Barometer respondents view their supply chains as "very resilient". In the past year alone, trade restrictions have tripled to affect an estimated U.S.$2.7 trillion of merchandise – nearly 20% of global imports according to Allianz Trade – fueling companies exploring trends such as friendshoring and regionalization. These developments lead to a high-risk perception – 29% of respondents rank business interruption as a top peril, placing it at #3, although it drops a position year-on-year.

Unsurprisingly, political risks and violence climbs two places to #7, its highest-ever ranking. The closely linked risk of changes in legislation and regulation – which includes trade tariffs – ranks #4 globally, unchanged year-on-year but with an increase in respondents, driven by concerns over growing protectionism. In fact, global supply chain paralysis due to a geopolitical conflict ranks as the most plausible "black swan" scenario likely to materialize in the next five years, according to 51% of the respondents.

The full report is available at: 2026 Allianz Risk Barometer.