Download

Tech Giants Aim to Eliminate Insurance Costs

Technology companies view insurance as a cost to eliminate, not a business opportunity to pursue.

Low angle view of a tall office building with glass windows against a blue sky

My recent article on continuous underwriting drew some pushback from peers regarding the Tesla Insurance case study. Their argument: Progressive, State Farm, and Allstate have offered usage-based insurance for more than a decade—and they write far more of it. So, what makes Tesla Insurance special?

The difference is that Tesla sells cars, not insurance. Auto insurance is a variable in the car's total cost of ownership (TCO)—and Tesla Insurance exists to drive that number toward zero, or as close to zero as possible. Insurance isn't their business; it's their anti-business.

Tesla brings world-class engineering, its own AI infrastructure, and relentless drive to overcome barriers—including regulatory ones. With a $1.5 trillion market cap (as of this writing)—the equivalent of 11 Progressives, 24 Travelers, 28 Allstates, or 40 Hartfords—it packs serious financial firepower.

Embedded Insurance

It's hard to discuss continuous underwriting without considering embedded insurance. When Tesla bundles coverage with vehicle purchases, when Apple offers device protection, or when DoorDash automatically includes delivery insurance—these feel like features, not insurance products. The insurance almost disappears into the broader service relationship.

Tesla Insurance captures customers at the point of sale, when they're most inclined to bundle. Its customer acquisition cost is nearly zero (versus the industry average of $200-$800), it writes policies 20–30% below standard rates for good drivers while maintaining acceptable loss ratios, and its Net Promoter Scores exceed the industry average by more than 40 points.

This kind of experience turns insurance from a grudge purchase into an invisible part of something people actually enjoy. That perceptual shift creates space for continuous underwriting innovations to take root gradually, without friction.

The Convergence Thesis

Here's where this gets strategically fascinating: Multiple trillion-dollar technology companies—Tesla, Amazon, Apple, Google, Microsoft—all have business models where minimizing insurance costs creates competitive advantage in their primary markets. They possess:

  • Superior data: continuous behavioral and environmental monitoring through devices and services
  • Direct customer relationships: eliminating distribution costs that constitute 15-25% of premiums
  • Technology infrastructure: claims automation, fraud detection, and risk modeling capabilities
  • Brand trust: customers already trust them with payments, personal data, and critical services

Traditional insurers face a daunting scenario: the companies best positioned to innovate in insurance have no interest in sustaining the industry as currently structured. They want insurance to become a nearly free utility that enables their actual businesses.

The Timeline Question
  • Will this disruption happen quickly or slowly? The answer varies by line:
  • Auto insurance: 10-15 years as autonomous vehicles scale
  • Cyber insurance: 5-10 years as security tools improve and become commoditized
  • Property insurance: 15-20 years as smart home technology reaches critical mass
  • Health/life insurance: 20+ years due to regulatory complexity and medical cost inflation

But the direction is clear. We are moving toward a world where insurance exists primarily as:

  • Embedded features bundled free or nearly free with other products
  • Regulatory compliance where coverage is legally mandated
  • Catastrophic protection for truly unpredictable tail risks

The companies building this future aren't insurers trying to sell more policies. They are automakers, technology platforms, security vendors, and device makers for whom insurance is an obstacle to be minimized or eliminated.

Traditional insurers are defending a $1.3 trillion U.S. market. But they're facing adversaries who would gladly destroy 70% of that market if it means selling more of their own products.

The Transition—The Cybersecurity Vendors

Cyber is a textbook case of the elimination incentive. Cybersecurity firms like CrowdStrike, Palo Alto Networks, SentinelOne, and Microsoft profit from prevention, not protection—making cyber insurance their natural competitor.

Some see opportunity in cooperation. CrowdStrike partners with insurers, sharing data to improve underwriting and prove its users suffer fewer breaches. That helps customers pay less for coverage while quietly shrinking the cyber insurance market itself.

Microsoft's position is even more intricate. As both a top security vendor and the source of many exploited vulnerabilities, it has every reason to make breaches rarer. Its visibility into corporate systems through Azure, Office 365, and Windows gives it the data to underwrite risk directly—or eliminate it by making insurance nearly irrelevant.

The endgame isn't selling policies; it's securing systems so completely that the need for insurance disappears.

The Transition—The Hybrids

Out on the edge where technological possibility meets regulatory reality, a new wave of tech‑enabled MGAs and MGUs is emerging. They blend niche specialization—restaurants, beauty, wellness—with continuous underwriting, real‑time risk visibility, behavior‑based credits, and agent‑first digital distribution and economics.

In simple terms, they aim to be the best "program carrier + software layer" for independent agents in specific verticals, not broad, direct‑to‑consumer threats to the long-standing agency model.

With digital sophistication rivaling top cyber vendors, these companies work comfortably within existing regulations and sell through independent agencies using a human‑first model—spending most of their day actually talking to people.

If Tesla Insurance is a glimpse of what auto coverage will look like in 10 years, startups like Rainbow, Next, Coterie, Relm, and Thimble show the incremental progress toward that future happening right now.

In the end, healthy tension between innovators pushing for better experiences and regulators safeguarding financial markets keeps our industry moving—slowly, but in the right direction.

Riv Arthur

Profile picture for user RivArthur

Riv Arthur

Riv Arthur is a business leader and technologist working in insurance, healthcare, and private equity.

Why Zillow Chickened Out

Zillow pulled its climate risk ratings from its home listings even though its model is widely validated. That's a bad sign for the movement to improve resilience.

Image
Orange Sky and Powerlines

Based on the notion that sunlight is the best disinfectant, I've long advocated that homeowners insurance companies give clients as much information as possible about the risks they face. Don't just quote me a premium. Tell me that, perhaps, I'm at more risk of flood or wildfire than old government maps show--and help me understand what I can do to reduce those risks.

Zillow just took a step in the opposite direction. 

It had announced 15 months ago that it would feature detailed climate risk information for flood, wildfire, wind, heat and air quality, but the company quietly dropped that information last month. 

The reason is obvious: pressure from sellers who didn't want the risks to their properties spelled out.

The implications are disheartening. 

What Zillow was attempting was always going to be tough, because we humans aren't wired to think rationally about probabilities. If some political poll says a candidate has only a one-in-10 chance of winning, and they win, we leap to the conclusion that the poll was wrong and the pollster incompetent. Maybe. But maybe not. 

The only way to test is to look over a body of work and over time. Did those predicted to have a one-in-two chance win about half the time? Did the one-in-fours win a quarter of the time? Did those one-in-10s win a tenth of the time?

But models like the one from First Street that Zillow used haven't been around long enough for us to have much evidence about whether they're right when they say there's a one-in-50 chance of a wildfire affecting a home each year. 

A spokesman for First Street said, "During the Los Angeles wildfires, our maps identified over 90 percent of the homes that ultimately burned as being at severe or extreme risk — our highest risk rating — and 100 percent as having some level of risk, significantly outperforming CalFire’s official state hazard maps.”

But we humans are still wired to think, "Zillow said I was at severe risk of flooding, and I didn't have a flood this year, so those bozos were wrong." In the context of the risk ratings provided by Zillow, someone with a house to sell would surely also think, "And their error is costing me money."

While that sort of thinking led to enough pressure on realtors, a key constituency of Zillow's, that Zillow pulled the ratings, there's still some hope for the long run. Even Zillow still provides a link to First Street so those curious enough can find information about risks to properties they might buy. And good models like First Street's will not only get better but will be more accepted over time, as they build up a track record.

It'll just take longer than I had hoped, perhaps much longer.

Sorry, I don't make the rules. I sure wish I did....

Cheers,

Paul

P.S. So I don't end on a total downer, I'll share two links that contain a healthy dose of encouragement. First is a webinar I did recently with Francis Bouchard, a managing director at Marsh McLennan who has focused on resilience for years, and Nancy Watkins, a principal at Milliman who has developed a Data Commons to help mitigate wildfire risks in the wildland-urban interface. Second is the ITL Focus from September on resilience and sustainability, featuring an interview with Francis and parts of an interview with Nancy. 

Both describe the sort of conversation that insurers need to have--and are starting to have-- with architects, builders, city planners and others so that, as a group, we can build resilience into properties from the outset and can at least offer advice to homeowners and communities on how to reduce risks related to severe weather. 

Insurance's Silver Tsunami Knowledge Crisis

P&C carriers face knowledge drain from retiring boomers. AI, used well, can provide systematic processes to capture expertise.

Aerial View of Ocean Waves

The P&C insurance industry is about to lose nearly half of its workforce to retirement in the next five years, driven by the baby boomer exodus from the workforce. Much of that loss is deep expertise about underwriting, decades-honed claims handling skill, and the undocumented tribal knowledge that carry the day for carriers.

This "Great Retirement," also called "The Silver Tsunami," is fast approaching. According to a recent survey by APQC (American Productivity and Quality Center), 93% of insurance CxOs are genuinely concerned ("mission-critical", "strong", or "moderate" concern) about this knowledge hemorrhage. Coincidentally and paradoxically, the same percentage of carriers are not capturing knowledge consistently from departing employees before they walk out the door.

The result of this concern-complacency disconnect? A perfect storm of knowledge drain, compliance exposure, operational disruption, and customer experience degradation—unless insurers leap out of the "boiling frog" syndrome.

Methods Create Barriers

According to the survey, 83% of respondents capture knowledge using manual methods such as people-to-people transfer and time-consuming documentation, a Sisyphean approach that is neither scalable nor sustainable. No wonder time (mentioned by 62% of respondents) and resources (mentioned by 41% of respondents) topped the list of barriers to knowledge capture and management in the survey.

While interest in AI remains high, a stunning 87% of carriers surveyed have yet to operationalize it to automate knowledge capture and management. AI adoption has been slowed down by concerns about compliance (cited by 59%) and correctness of answers (cited by 38%). AI initiatives have been stymied by "garbage in, garbage out" where some carriers tried to slap AI onto enterprise knowledge silos of dubious consistency, accuracy, and compliance. No wonder a recent MIT survey found that only 5% of AI deployments have created any business value!

Trusted Knowledge Foundational to AI Success

The precious few AI-savvy carriers succeed in AI with a trusted knowledge infrastructure, which addresses adoption barriers such as correctness of answers and compliance head-on. At the same time, these organizations use AI to automate the knowledge capture, management, and optimization process:

  • Capture questions that are the highest in volume, value, and complexity, and mine gold-standard answers for them from customer interactions with high-performance agents and intra-enterprise conversation stores among SMEs
  • Capture procedures from flowcharts into in-band guidance for customer conversations
  • Create drafts of knowledge articles that are aligned with the brand voice for human experts in the loop to review and approve
  • Curate content to make it findable and AI-ready
  • Analyze and optimize to identify gaps and improve knowledge performance
Winning best practices

Leading carriers treat knowledge as a strategic asset rather than a collection of documents and unstructured content. Their best practices include:

  • Using AI to continuously capture expertise from daily work, not just end-of-career interviews
  • Embedding trusted knowledge in claims, underwriting, and customer service systems
  • Including compliance checks in knowledge workflows to ensure that answers are correct and aligned with regulatory requirements
  • Training employees to use AI tools as assistants and not adversaries

A 10X acceleration in creation and curation of knowledge and a 3X acceleration in time-to-value is possible when companies use AI well.

The Bottom Line

With AI-powered knowledge capture and management, forward-thinking carriers capture, preserve, and activate institutional knowledge at scale—so every employee—from new adjusters to seasoned underwriters—can access trusted answers and the best thinking the organization has to offer exactly when they need it. Others are well advised to follow suit lest the Silver Tsunami sweep them away!


Anand Subramaniam

Profile picture for user AnandSubramaniam

Anand Subramaniam

Anand Subramaniam is SVP global marketing for eGain. Prior to eGain, Subramaniam served in executive and marketing management roles in a range of organizations from SaaS startups to companies such as Oracle, Autodesk, and Intel. He holds an MBA from the University of California at Berkeley and an MSME from the University of Rhode Island.

Insurers Must Rebuild Trust in 2026

As premiums surge and AI transforms operations, insurers must prioritize transparent communication to rebuild eroding customer trust.

Close Up Shot of Handshake from Above

As we approach 2026, it's clear that the insurance industry needs to focus on something more foundational than product innovation or operational efficiency: rebuilding and strengthening trust. Whether in property & casualty (P&C) or life & annuity (L&A), trust is emerging as an important differentiator, yet it is the hardest to maintain in an environment defined by climate volatility, rising costs, demographic shifts, and accelerating automation.

Right now, insurers face a dual challenge. They must navigate economic and regulatory pressures while also meeting customer expectations shaped by real-time digital experiences in every other part of consumers' lives. That means the industry can no longer view communication as a compliance requirement or an operational task. Communication is the customer experience, and ultimately the foundation of trust.

The 2026 Challenge for P&C

For P&C insurers especially, 2026 is shaping up to be another turbulent year. Rising premiums – driven by higher reinsurance costs, climate-related catastrophe losses, supply-chain volatility, and inflation – are straining affordability. And when coverage feels more expensive while service feels inconsistent or complex, customer trust erodes.

So the question becomes: How do insurers maintain trust at a moment when customers are being asked to pay more?

Across industry studies and customer research, three actions matter most:

1. Explain the "why."

Transparency around rate drivers is strongly correlated with retention. While weather trends, rebuilding costs, inflation, and fraud patterns are all out of insurers' control, and premium increases are something that will never make a customer happy, these factors make sense to policyholders when communicated proactively and clearly.

This is an area where insurers can create real differentiation. A renewal communication that simply states "your premium is increasing" feels one-sided. A renewal that explains why the price changed, how the customer's risk profile evolved, and what the insurer is doing to help reduce costs over time feels partnership-oriented.

2. Increase transparency throughout the journey.

Claims remain the emotional center of insurance. Forrester's 2026 outlook underscores that even when claim outcomes are favorable, perceptions of fairness and trustworthiness are shaped most by transparency through real-time status updates, clear next steps, consistent messaging across channels, and expectations set early and often.

This is also where operational gaps tend to show. If one message comes from the portal, another from the adjuster, and a third from email or SMS – each with a different tone – customers sense misalignment. Consistency and transparency across every channel signals competence, care, and honesty.

3. Make every interaction worth the premium.

People trust organizations that demonstrate reliability, humanity, and capability in real time – not just in marketing.

In other words: customers judge the value of insurance not just at the point of loss, but through every touchpoint, whether for billing, servicing, onboarding, updates, coverage changes, or support. Transparent, consistent, multi-channel communications will be essential to demonstrating that value in a world where premiums continue to rise.

The L&A Perspective: The Trust Gap with Younger Buyers

L&A insurers face a different challenge, one shaped by demographic shifts and a stark contrast in purchasing motivation.

On one hand, the aging population is creating unprecedented momentum: 4.2 million Americans will turn 65 this year, and the wave of retirees has contributed to a dramatic rise in annuity sales, reaching $432.4 billion in 2024, up 12% year over year. For older buyers, the value of retirement income solutions is clear and immediate.

But beyond annuities, L&A products are struggling to capture interest, especially among younger or less financially secure consumers. According to a LIMRA study, younger buyers look, compare, and browse – but do not purchase. Why?

  • They are unsure whether the products are worth the cost.
  • They often feel the industry does not communicate in ways that are relevant to their financial realities.
  • They question whether insurers have their best interests at heart.

Building relevance for younger generations means meeting them where they are: with clarity around value, real-world scenarios that make protection feel tangible, and messaging that explains benefits in everyday language. It also means demonstrating affordability and flexibility – not just in price, but in how insurers communicate, educate, and guide.

The organizations gaining traction with younger customers are leaning heavily into personalized digital journeys, plain-language education, and transparent explanations of how products fit into broader financial wellness and not solely on risk mitigation.

The Trust Imperative for AI in Insurance

Overlaying all of this is the accelerating adoption of AI across underwriting, claims, service, and customer engagement. According to a McKinsey report on the future of AI, insurers see AI as a path to efficiency and accuracy, while customers see risk – particularly around data privacy, bias, and fairness. Public awareness has grown significantly, and regulators are moving quickly.

So the question shifts again: How can insurers build and maintain trust while deploying more AI across the value chain?

A trustworthy AI strategy looks like this:

Be transparent.

Publish clear, accessible notices that describe where and how AI is used, whether for underwriting insights, claims triage, personalization, or fraud detection.

Be accountable.

Explain the safeguards in place to prevent bias or incorrect outcomes and commit to human oversight for material decisions. Make it clear that customers can opt out where appropriate.

Give customers a voice.

Provide simple methods for policyholders to query, appeal, or request review of any AI-driven decision. That two-way transparency is foundational to maintaining trust. AI doesn't erode trust – opaque AI does. When insurers use AI to improve clarity, reduce friction, and increase fairness, customer trust grows rather than diminishes.

The Bottom Line: Trust Is Built Through Communication

As 2026 approaches, one theme cuts across all insurance segments: trust is earned in moments, and communication shapes those moments more than any other factor.

Whether explaining a premium change, guiding a customer through a claim, educating a first-time life insurance shopper, or deploying AI responsibly, insurers must treat communication as a strategic capability, not a back-office task.

The organizations that will lead the market are those that communicate clearly, consistently, and proactively; meet customers across channels with a single, unified voice; make interactions personalized and empathetic; explain the "why" behind every major decision; and demonstrate responsibility and transparency in their use of emerging technologies.

Insurance is, at its core, a promise. And a promise is only as strong as the trust behind it. The industry has a rare opportunity to strengthen the partnership between insurers and policyholders – through transparency, communication, and a commitment to treating every interaction as a moment that matters.


Eileen Potter

Profile picture for user EileenPotter

Eileen Potter

Eileen Potter is vice president of marketing for insurance at Smart Communications. 

She has more than 25 years of insurance experience with both P&C and life. She has worked in independent agencies and MGA operations in various roles, including commercial marketing and underwriting. Her software background includes work with organizations such as ABBYY, Appian, One and Duck Creek Technologies.

D&O Claims Rise Amid Escalating Global Risks

Cyber risks and geopolitical uncertainties fuel surging D&O claims as global bankruptcy rates hit record highs.

Gray Concrete Building under Blue Sky

Around the world, political, economic, and social uncertainties are on the rise. They can affect every aspect of a company's operations, as well as lead to significant changes in financial, regulatory, and legal environments. Failure to anticipate and adapt can expose companies to operational failings, financial loss and reputational harm with consequences for the companies' directors and officers.

According to Allianz Commercial's latest Directors and Officers (D&O) Insurance Insights report, D&Os can be held accountable for misjudging the impact of geopolitical developments on their company's operations or for failing to adequately adapt to the legal or regulatory requirements in different countries. Liability for D&Os may arise from shareholder lawsuits or regulatory penalties directed both against the entity and individual decision-makers.

At the same time, cyber liability risks for directors and officers have risen sharply in recent years with higher expectations for board level oversight of cyber security and a trend toward more litigation and regulatory actions. Exposures for D&Os typically arise from their duty to oversee the organization's cyber security posture.

Claims against directors have been triggered by a wide range of events, including data breaches, ransomware attacks, and even technical failures. Ransomware accounted for around 60% of the value of large cyber insurance claims (>€1mn) seen by Allianz Commercial during the first six months of 2025, according to its annual Cyber Security Resilience Outlook. Should a cyber incident result in financial loss, directors could face legal claims from shareholders, customers or suppliers if the board is seen to have failed to implement adequate risk controls or business continuity planning.

Insolvencies drive D&O claims globally

Bankruptcy and regulatory enforcement actions are among the top sources of private D&O claims, although claims can also arise from allegations for breach of fiduciary duty, such as misleading or inadequate disclosure, or negligence. According to Allianz Trade, global business insolvencies are expected to rise by 6% in 2025 and 5% in 2026. Next year will mark five consecutive years of increases to reach a record high number of bankruptcies, 24% above the pre-pandemic average. Insolvency risks are particularly concentrated in the automotive, construction, retail, and consumer goods sectors.

There has also recently been a notable rise in "mega bankruptcies" in the U.S. – those filed by companies with over US$1bn in reported assets. The first half of 2025 saw 17 such bankruptcies, the highest number since the Covid-19 pandemic, with 32 in the past 12 months, well above the historical average. The current challenging business environment – marked by factors such as tariffs, weak demand, rising costs, technological transformation, growing competition, and regulatory changes – is heightening the risk of bankruptcy and also claims against directors.

Claims activity is increasing in the highly dynamic D&O market

Over the past three years, there has been a continual increase in the frequency of new claims against directors and officers, now approaching or exceeding pre-pandemic rates in most regions of the world. Claims severity continues to be an issue in North America. For D&O insurers, the U.S. especially is a highly complex market due to its high frequency of securities class action claims and surging average settlement costs, which rose by 27% in the first six months of 2025 to US$56mn. Meanwhile, shifting governmental policy in the U.S. and parts of Europe regarding DEI (diversity, equity, inclusion), ESG (environmental, social, governance), and artificial intelligence (AI) have introduced new complexities for boards to navigate.

To read the full Allianz Commercial D&O Insurance Insights report, please visit: Report | Directors and officers (D&O) insurance insights 2026

Strong Growth for Life-Annuity Forecast Through 2027

Strong earnings forecast through 2027 gives life-annuity insurers opportunity to adapt strategy, not just enjoy conditions.

Overhead Shot of a Person Riding a Bike Near People

There's nothing like starting the year off with some good news. Conning's Year-End Life-Annuity forecast for 2025-2027 certainly has a lot of that. For life-annuity industry executives, statutory net operating results, after tax and dividends, are forecast to increase from $27 billion in 2025 to $30 billion in 2027.

Those strong results start with premiums, of course. Due to an increasing number of individuals saving for retirement and pension risk transfers, annuity premiums are projected to increase 16% from 2025 to 2027. Meanwhile, life insurance remains a key financial need for younger generations starting or building their families. As a result, life insurance premiums are forecast to increase 8% from 2025 to 2027.

While premium headlines grab attention, life-annuity insurance executives know profitability depends on successfully managing investment returns, reserves and capital. At the same time, both life and annuity insurers need to begin grappling with the potential impact of GLP-1 drugs on claims and pricing.

Investment performance drives sales and profitability

Life-annuity sales and profitability are sensitive to General Account investment performance. That performance depends on two broad factors: the external rate environment and asset allocation strategy. As we look out to 2027, we see the continuation of a favorable external interest rate environment. We also expect insurers to continue diversifying their asset strategies to achieve higher portfolio yields.

Portfolio yields forecast to increase through 2030

Even if the Federal Reserve cuts rates over the forecast period, we project life-annuity insurers will benefit from higher portfolio yield. Higher portfolio yields support fixed annuity and universal life interest-crediting rates, which are favorable for more sales over our forecast period.

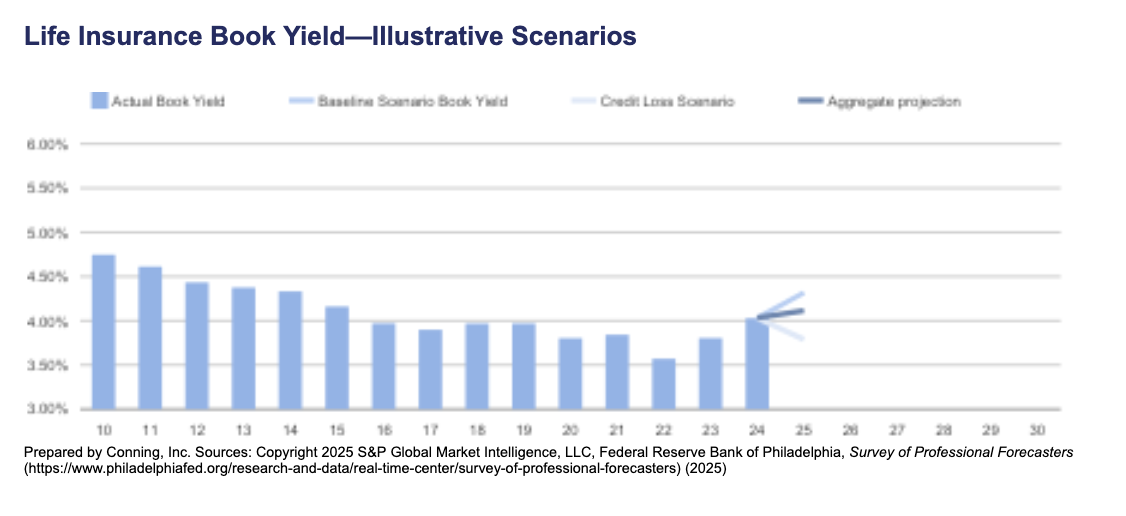
Our portfolio projection uses the moving average ten-year Treasury rate and models three scenarios. The first is based on the third quarter of 2025 Philadelphia Federal Reserve's Survey of Professional Forecasters. The second assumes credit losses reduce the spread over Treasuries achieved in insurer portfolios. The third is an aggregate blend of one and two. By 2027, our aggregate projection is for the portfolio yield to reach 4.22%, up from 4.03% in 2024.

Life Insurance Book Yield--Illustrative Scenarios
Continued asset diversification supports higher portfolio yields

During the longer-for-lower interest rate period of 2015 through 2021, life and annuity insurers began diversifying their assets to generate higher General Account portfolio yields. They decreased allocations to bonds and redistributed to mortgages and Schedule BA assets (alternative assets such as joint ventures, hedge funds, and private equity investments) to gain yield. In addition, there has been a marked shift within the bond portfolio towards private credit.

Even with the recovery of interest rates, we anticipate that diversification efforts will continue through our forecast period.

Reinsurance Continues to Support Growth

Whether onshore or offshore, reinsurance remains a key reserve and capital management tool for life annuity insurers. For example, in 2024, 21% of direct and assumed premiums were ceded. In 2025 and through 2027, we expect that key role will continue. What will be noticed, however, is the growing use of sidecars to support life-annuity reinsurance transactions.

Since 2019, over 15 new sidecars have formed. Looking ahead, we believe sidecars will continue to bring more capital to support life and annuity reinsurance growth. This is a strong positive for the life and annuity industry's forecast capital strength and profitability through 2027.

GLP-1s Affect Claims and Pricing

When we think about claims through 2027, the good news is that excess mortality has receded from the COVID-19 pandemic peak. At the same time, an increasing number of retirees use annuities to generate retirement income and increase annuity benefits. However, the impact of GLP-1 drugs on mortality, morbidity, and longevity is a new factor we and insurers need to consider. These drugs hold the potential to affect life insurance underwriting as well as life insurance and annuity pricing.

There is a concern that applicants may be using the drugs when underwritten for new policies, but then later stop using the drugs, leading to a return of weight and/or other health conditions the drugs treat. On the annuity side, longevity improvements due to GLP-1 change longevity expectations and strain original annuity pricing assumptions. The current impact of GLP-1 on life-annuity profitability may not be large. That said, these drugs may have a long-term effect on claims and pricing beyond 2027.

A Forecast for Strategic Adaptation

How should life-annuity executives respond to the good news in this forecast? The next three years give insurers a rare alignment of strong earnings, improving yields, new sources of third-party capital, and a return to more normal mortality. The companies that use this period to adapt and realign strategy, instead of simply enjoying favorable conditions, will be the ones that lead the industry in the decade ahead.

To position for continued growth and success, life-annuity insurers should accelerate product innovation. Developing flexible products that can adapt to shifting longevity and morbidity trends will help address emerging customer needs and market dynamics.

At the same time, enhancing the investment strategy remains essential. Continued diversification of the General Account portfolio, with a focus on private credit, mortgages, and alternative assets, will help optimize yields. Partnering with key asset management partners will be crucial to executing successful diversification strategies.

Leveraging reinsurance and third-party capital is another strategic priority. Expanding the use of reinsurance, including innovative structures like sidecars, can help manage capital efficiently and support growth objectives.

Driving operational excellence is crucial for sustainable growth. Investing in technology and analytics can improve underwriting, claims management, and customer engagement, while streamlining operations will enhance efficiency and scalability.

Finally, strengthening regulatory and capital management practices will help companies stay ahead of evolving requirements, maintain robust capital buffers, and support business expansion in a volatile market environment.

By executing on these strategic priorities, life-annuity insurers can capitalize on favorable market conditions, manage emerging risks, and position themselves for sustainable growth through 2027 and beyond.


Scott Hawkins

Profile picture for user ScottHawkins

Scott Hawkins

Scott Hawkins is a managing director and head of insurance research at Conning, responsible for producing research and strategic studies related to the insurance industry.

Previously, he was senior research fellow for Networks Financial Institute at Indiana State University. He spent 16 years at Skandia Insurance Group in the U.S. and Sweden as an analyst and senior researcher.

He studied history at Yale, has a certificate in information management systems from Columbia University and was a board member of the J. M. Huber Institute for Learning in Organizations at Teacher’s College.

Independent Agencies Need Real-Time Analytics

Real-time analytics help independent agencies shift from reactive problem-solving to proactive performance management and growth.

Person Writing on Notebook

Elite athletes don't wait for an injury to start strengthening their bodies. They invest in preventative rehab or 'prehab'—the stretching, conditioning, mobility work, and small adjustments that keep them performing at their peak. It's a disciplined commitment to staying strong and ready for what's next.

Independent agencies can approach the year ahead the same way.

Too often, agency leaders slip into rehab mode, discovering a producer's lagging numbers months too late, noticing revenue leakage only after renewals drop, or realizing that their commercial lines pipeline is weak just as growth goals loom. These issues could have been spotted much earlier if the right visibility had been in place.

The agencies that consistently grow and retain clients are the ones that operate with a continuous prehab mindset. They use real-time reporting and analytics to keep a close watch on their business, ensuring everything stays on track and healthy.

As the new year approaches, this kind of clarity becomes one of the most valuable assets an independent agency can have. Here's how analytics can help keep your agency in peak shape for the year ahead:

Daily Performance Visibility Prevents Costly Surprises

Small imbalances like tightness, fatigue, or weakness tend to appear long before a real injury occurs. Athletes rely on these early warning signs to adjust their training to prevent setbacks before they affect performance.

Tracking your agency's key metrics works the same way. Minor shifts like a slipping close ratio or an underperforming line of business can signal larger issues if left unnoticed. By catching them early, you can take corrective action before they seriously affect your agency.

The key is having an agency management system that not only collects and tracks your performance data but also presents it in an intuitive way. Tracking your agency's metrics provides access to dashboards and reports that give a centralized view of its performance, making it easy to act on insights.

Agency analytics tools can help agents track:

  • Policies per term, customer, and transaction type
  • Revenue per client
  • Retention and renewal performance
  • Close ratios per producer and line of business
  • Book mix, risk concentration, and line diversification

When these numbers become part of your daily routine, presented through dashboards that highlight trends, risks, and opportunities, you gain a truly proactive view of your business. You can easily identify top-performing areas, pinpoint where improvements are needed and ensure team members stay aligned with your agency's goals.

Leverage Your Book of Business to Uncover Growth Opportunities

Just as monitoring agency metrics helps you identify where your agency is excelling and where improvement is needed, it also helps you uncover new opportunities for growth. With consistent metric tracking, your agency management system can help identify cross-sell and upsell opportunities within your existing book of business, such as clients with monoline policies who could benefit from bundled coverage or accounts with underinsured risks that may need additional protection or policy enhancements.

Instead of relying on producers to manually hunt for upsell opportunities, agency management systems can surface prioritized lists of prospects ready for outreach. This empowers your team to act quickly and efficiently, maximizing the value already sitting in your book.

By using the data you already have, the right agency management technology can turn everyday servicing into meaningful growth that strengthens client relationships and boosts revenue and retention.

Shared Insights Align Your Team Around What Matters Most

Athletes perform best when they know the game plan and understand how their role affects the team's success. Similarly, agencies thrive when insights are shared across the entire team.

The key is having a system that lets you build reports once and schedule them to run automatically. You can use these reports in meetings, share summaries with producers, or provide leadership with KPIs.

Agency management systems often allow customization, letting you filter, group, and visualize the metrics that matter most—whether it's top producers, policy types, or conversion rates—without extra steps or manual reformatting. Having this clarity gives your team the insight to adjust tactics in real time, keeping your agency in top shape.

Turning Insights into Everyday Action

Setting your agency up for success next year goes beyond quarterly check-ins. It's about building daily habits that keep your business strong. By taking advantage of real-time insights and analytics technology, your agency can spot opportunities early, avoid surprises, and stay ahead all year long. Because when you know more, you can do more.


Rob Bourne

Profile picture for user RobBourne

Rob Bourne

Rob Bourne is the senior vice president and general manager of EZLynx. 

He previously served as SVP at Applied Systems, overseeing inside sales, account management, business development, and alliance partnerships. Before that, he held senior roles at Athelas and Podium. 

He has an MBA from Cornell University.

Attracting Next-Generation Talent to Insurance

Insurance faces a projected 400,000-worker shortage, demanding evolved leadership models and diverse career development strategies.

Man in Black Coat Standing Beside Woman in White Long Sleeve Shirt

KEY TAKEAWAYS:

  • The top-down leadership model is losing relevance as future insurance leaders seek collaboration and dynamic career growth
  • Emphasizing the industry's purpose-driven mission and community impact helps attract professionals seeking meaningful work
  • Affinity insurance, mentorship, and emerging tech roles offer diverse career paths that foster growth and customer engagement in insurance

With the U.S. Bureau of Labor Statistics projecting the loss of nearly 400,000 workers by 2026, the insurance industry is entering a period of significant change. This potential workforce decline underscores the urgent need for insurers to invest in people, culture, and modern career paths that appeal to today's professionals. To attract and retain future insurance leaders, insurers must rethink how they engage talent and structure career development.

Though often seen as traditional and slow to adapt, the industry is actually changing fast. Technology, evolving consumer expectations, and a workforce that values purpose and flexibility are driving this transformation. To bridge the gap between perception and reality, insurance leaders must embrace modern approaches to leadership, career development, and company culture.

To help our industry overcome today's talent challenges, I believe there are four key areas leaders in the industry should focus on.

1. Evolve Leadership Models

The traditional top-down leadership model, where decisions flow from the top, is losing its effectiveness in today's fast-paced environment that emphasizes collaboration and adaptability. Once common, this hierarchical approach no longer aligns with the expectations of younger professionals. According to PwC's 2024 Workforce Radar, this group is seeking environments where their voices are heard, their ideas influence outcomes, and their career paths feel dynamic rather than rigid. They want to be contributors, not just implementers.

Similar research shows that employees who see a bright future at their company are 1.7 times more likely to stay, 2.3 times more engaged, and 2.4 times more likely to recommend their employer. Yet, more than half of Gen Z and Millennial workers hold a negative or neutral view of our industry, often perceiving it as complex and rigid. This growing desire for dynamic workplaces, combined with the industry's negative perception, creates a major challenge in attracting and keeping new talent.

By shifting to collaborative, team-based leadership, we can bring a wider range of perspectives into decision-making, which is crucial for understanding the diversity of today's consumers. Diverse perspectives foster environments where fresh voices enhance market understanding, strengthen decisions, and build greater customer engagement in insurance. This shift also serves as a powerful signal to younger talent that their contributions are not only valued but also essential to our success and future. Collaborative cultures will help forward-thinking insurance leaders appeal to the next generation of talent.

2. Play Up Our Strengths: The Purpose-Driven Core

At its heart, insurance is an industry built on trust and human connection. Our fundamental mission is to help people navigate some of the worst moments of their lives by providing support and financial security. This core mission is a powerful differentiator for attracting talent who seek meaningful, purpose-driven careers.

For many younger professionals, a job is an opportunity to make a tangible, positive impact. Findings from Deloitte suggest that this generation is motivated by a desire to contribute to something bigger than themselves. By highlighting the security and peace of mind we provide for individuals, families, and communities, we show that a career in insurance is deeply meaningful. When corporate culture and leadership embody the industry's thoughtful, service-oriented values, they resonate with employees who want their work to matter and inspire them to bring their best every day.

Emphasizing this core purpose helps attract emerging talent, demonstrating to them that a career in insurance offers meaningful, lasting impact.

3. Highlight Diverse and Emerging Career Paths

While traditional insurance roles like underwriting, claims, and sales remain vital, they're only part of the story. The industry has untapped potential to showcase exciting paths that attract talent seeking innovation, impact, and growth.

Advanced technology, analytics, and digital platforms are redefining the insurance experience from the ground up. New opportunities in AI, cybersecurity, data science, and user experience design open the door to talent that may have once overlooked the industry as a viable career path. By showcasing how these modern disciplines are transforming our industry, we can attract professionals who may have otherwise gravitated toward the tech sector.

Beyond technology, we can highlight unique career paths like those in affinity insurance programs, where professionals work with organizations that reflect their personal interests, such as a university or a professional association. These positions allow individuals to combine their professional skills with their passions, creating highly engaging and fulfilling careers.

Mentorship programs also play a critical role in both recruitment and retention. Mentees gain exposure to cross-functional experiences and broaden their understanding of career possibilities, while mentors gain fresh perspectives on the priorities and aspirations of the next generation. This mutual learning builds stronger connections and encourages long-term engagement.

When insurance leaders effectively highlight diverse career paths and foster mentorship and engagement, emerging talent is more likely to see the industry as a place where they can grow, innovate, and build meaningful careers.

4. Create Genuine Connections

Building and maintaining strong ties with young professionals is essential for long-term success because when employees feel part of a community, they stay engaged and motivated. In addition to nurturing internal relationships, cultivating external networks and partnerships helps new professionals feel welcome, included, and connected to the broader industry community.

Leveraging professional membership organizations is a powerful way to facilitate meaningful connections between young professionals and experienced leaders. These groups provide a vital link between young professionals and experienced leaders, creating opportunities for collaboration and learning. By participating in these networks, new employees can attend special interest groups, join committees, and form relationships that will shape their careers for years to come.

A strong sense of community helps ease the feeling of being an outsider in a new and complex industry. Membership organizations also provide valuable resources and support, especially as we navigate new technologies and evolving market dynamics. In an era defined by change, having a trusted network for shared knowledge and support is more important than ever.

These connections strengthen the industry as a whole. While young professionals gain guidance and insight, established leaders gain access to fresh perspectives and promising talent. Together, these relationships strengthen the industry's future and foster a culture of shared growth and innovation that will help attract, develop, and retain the next generation of insurance leaders.

Shaping the Future of Insurance Careers

The talent gap in the insurance industry is both a challenge and an opportunity shaped by technology, talent trends, and culture. Companies that invest in meaningful connections, diverse career paths, and inclusive environments will not only retain top performers but also build a more engaged workforce. Supporting mentorship and embracing new technologies helps organizations innovate while staying grounded in core industry values. By doing so, they create environments that draw emerging professionals and strengthen the industry for years to come.

What’s Holding AI Back in Insurance

Insurers adopt AI at breakneck speed, yet legacy technology barriers prevent most from achieving meaningful ROI. A platform-based approach is needed.

Line with Arrow and Abstract Shapes

How quickly have enterprises across industries embraced AI? The answer depends on your view of its origins. Some people believe AI dates back to Alan Turing's early theories of machine intelligence. Others see the Dartmouth Summer Research Project on AI in 1956 as its birth.

What is unarguable, however, is that AI has moved at breakneck speed since the launch of ChatGPT three years ago. A recent McKinsey survey revealed that 88% of organizations now use AI regularly. Yet there is a downside. Only one-third of respondents have scaled AI enterprise-wide, and fewer than half can tie any significant earnings before interest and taxes (EBIT) to their efforts.

What will it take for insurers to see real ROI from their AI investments? And how can carriers prepare for an agentic AI future? A look at past tech trends can show us quite a bit about what is to come.

Why Every Tech Revolution Stalls Before It Scales

All significant technological breakthroughs of the past 20 to 30 years have followed a distinct progression. First comes the hype, where inflated expectations generate massive excitement and speculation. Next comes normalization, where practical use cases emerge. Lastly, there is substantive change, where technology becomes embedded in core operations, driving genuine business value.

Within each cycle, however, key barriers exist that block progress once the initial hype fades. In the late 1990s, high-speed connectivity was going to reshape business overnight, but ROI did not come until broadband access expanded. Apple's first iPhone launched in 2007 but did not achieve widespread use until its app store and developer ecosystem matured. Cloud computing brought huge promise in the mid-2000s but did not mature fully until operating models shifted toward DevOps, APIs and microservices.

Even insurtech itself went through a metamorphosis. Early disruptors that set out to overturn insurance incumbents about a decade ago have either been acquired or failed to prosper. Those that focused on partnering with incumbents to modernize core parts of the insurance value chain, however, have grown stronger and manifested an industry that drives innovation in insurance forward.

What's Holding AI Back?

There clearly is no shortage of excitement or action when it comes to implementing AI in insurance. Seventy-six percent of insurers already use generative AI in at least one core business function, making insurance the second-fastest industry to AI adoption, trailing only tech, according to BCG research.

Yet true transformation value remains rather elusive. Despite the breakneck speed of adoption, the results of AI pilots are uneven, and progress is patchy. Only 6% of respondents to McKinsey's survey are classified as high performers. That means they set targets beyond efficiency, embedding AI in existing operating models and new products to capture more revenue and expand cross-selling opportunities.

These high performers have already moved beyond generative AI and toward agentic AI, which involves using AI-powered agents to plan and execute multi-step work. Sixty-two percent of McKinsey respondents are already experimenting with agentic AI, and 23% are scaling agents somewhere in the enterprise. Here again, however, penetration is narrow, with agentic deployments living in one or two functions.

So, what's holding insurers back from ROI with generative and agentic AI? One common thread is deployments that are saddled by the limitations of legacy and mainframe systems. Put simply, insurers cannot reach an AI-enabled future if their workflows are dependent upon decades-old technology that is inflexible and impossible to integrate.

Breaking Through the Barrier

To deliver meaningful returns from their AI bets, carriers must rethink the foundations supporting their technology ecosystems. Many of today's challenges stem from years of product-centric digital transformation that delivered incremental wins but left insurers with a patchwork of disconnected systems. These solutions were never designed for the real-time data or observability that AI and agentic AI require.

A platform-centric approach offers a practical path forward. Unlike point solutions that focus on single steps in the value chain, modern platforms provide the connective tissue that allows data, workflows, models and controls to operate together. Platforms succeed because they allow insurers to redesign workflows holistically; something point solutions were never built to support.

The most effective platforms in the coming three to five years will share several attributes.

  • Flexible, API-driven architectures that allow carriers to integrate new technologies into existing systems without a costly rip-and-replace.
  • A broad ecosystem of partners and integrations, giving carriers access to specialized tools, such as distribution and fraud detection, without adding further fragmentation.
  • AI-enablement at the foundation, meaning agents and models can operate safely and consistently across underwriting, claims, servicing, finance and product development.
  • Built-in governance and human-in-the-loop patterns that build transparency and trust as insurers ask AI to take on more complex work.
  • Outcome dashboards that provide clear metrics, including cycle time, loss adjustment expense, bind ratio, Net Promoter Score, and revenue uplift per use case.

With a platform-centric mindset, insurers can begin building momentum with their existing AI investments and gradually move toward an agentic future. A smart approach is to embed AI agents into crucial workflows where it can consolidate data, reason about actions, and hand off smoothly to humans, such as quote triage in commercial lines or claims final notice of loss (FNOL) to settlement recommendations. Start small, measure the impact, and then implement AI agents into other projects to make adoption stick.

Navigating the Road Ahead

From the dot-com boom to the rise of AI, history shows us reinvention in insurance happens over time, not overnight. AI is moving faster than any wave before it, but the core principles for insurtech companies and carriers alike remain the same: build and implement platforms that solve real business problems and engender trust with customers along the way. This type of measured approach will propel the next generation of AI-powered insurtech platforms and help accelerate the AI adoption cycle.

How Carriers Must Be Strategic on AI

Despite $10 billion in AI investment, only 7% of carriers achieve scale. It's time to decide if you must take the stairs, can find an escalator or, in the best case, can catch an elevator. 

An artists illustration of AI

Every carrier is in a scramble to achieve gains through AI. 2025 investment in AI for insurance was estimated to be over $10 billion, primarily driven by carriers. Yet only 7% have managed to exit the pilot phase. AI investment is usually limited or fragmented and not designed for scale.

Carriers know they need to invest in AI, but their investment thesis must change. Executives must be strategic, but what framework can carriers use to prioritize AI investment?

Carriers should ask themselves two key questions:

  1. Should investment be focused on bolstering strengths or addressing weaknesses?
  2. Does the investment require you to take the stairs or allow you to ride the escalator or elevator?
Strengths vs. Weaknesses

Over the years, there has been an evolution in how insurance carriers have viewed managing the value chain. Carriers shifted from owning the end-to-end insurance value chain, to outsourcing the non-core capabilities, to outsourcing their weaknesses and focusing on their strengths.

AI provides insurance leaders the opportunity to rethink this position. For example, claims administration, which may have been outsourced to TPAs in the past, could potentially be brought back in house, due to both cost and operational capability considerations. But the investment from carriers is limited and must be prioritized.

Leveraging AI to address weaknesses can be appealing, particularly if the weaknesses were driven by human capital considerations. Improved spans of control, greater capacity, and overall process efficiency are all benefits of AI. But consider where AI success is most likely:

  • Quality data
  • Platforms and technology that can integrate with AI
  • Employees with the right skills and talent
  • Strong processes
  • Culture that is open to change

Those are more likely to be strengths for carriers, not weaknesses. For that reason, it is generally better in the short term for insurance carriers to invest their capital into their own strengths and gain even stronger competitive advantages in the market. These AI use cases will likely have greater success, and that success will compel the organization to further invest in the business.

There is another reason that carriers may seek to focus on their strengths. AI is not unique to any particular carrier – TPAs, recordkeepers, and other insurance stakeholders are also making AI investments into their capabilities. If a carrier is outsourcing key functions, then the answer may be to re-evaluate the initial vendor selection to determine who is the best provider in the age of AI. For example, a TPA may have been the right solution five years ago for claims administration, but TPA capabilities have evolved to the point where a carrier may find different leaders and select a different vendor.

While focusing investment on existing strengths may be the preferred strategy in the short term, not every carrier will have the luxury to ignore weaknesses. For longer-term investments, how should carriers think about AI investment?

Stairs, Escalators, and Elevators

Every carrier will find themselves in one of three circumstances:

  1. The carrier does a lot of things well but is not a leader in any particular area or capability
  2. The carrier has a critical weakness that must be addressed (e.g., underwriting/suitability KPIs and metrics)
  3. The carrier identifies a trend that all carriers must address in the future (e.g., hyper-personalization of products)

If AI is being used to address any of the above, then insurance carriers will need to consider the investment required to address these trends, both now and in the future. That investment comes in both cost and time.

To address each of these areas, leaders should consider whether they need to take the stairs, if they can ride an escalator, or if they can take an elevator to where they want to be.

  • Taking The Stairs: Some AI investments will require significant upfront work to maximize the potential return and achieve scale. For example, attempting to leverage AI at scale to improve underwriting requires data, clear processes, and the right workforce for the most complex cases. In these situations, there are no shortcuts – carriers have to make the investment.
  • Riding The Escalator: Some carriers may be able to identify opportunities where outside vendors can provide an accelerant – you will still move faster if you make the investment, but you can see improvement even with small action. One example is next-best-action tools in the sales and distribution space. Vendor tools can still provide significant cross-sale and upsell potential, even without carrier data, but leaders in the space combine their unique data points with the vendor's tools to achieve best-in-class outcomes.
  • Ride The Elevator: In rare cases, there may be AI tools that allow carriers to go from wherever they are today to industry par or even leading capabilities. One possible example is AI tools leveraged for call deflection in call center environments – leveraging these tools can be done with minimal existing capabilities for significant impact. True elevators can be helpful, but eventually, they become table stakes and no longer a differentiator.
The Path Forward

This framework gives carriers a way of reimagining their AI investment – instead of AI committees that simply approve or deny use cases, carriers should be formulating strategies that chart a path on where they want to be and the requirements to get there, then aggressively drive scalable solutions. To do that, carriers have three key considerations.

  1. Identify Your Competitive Advantages – AI investment should begin with assessing value chain strengths. For simplicity, there are five key potential areas: product development, sales/distribution, underwriting/suitability, customer service, and claims. Carriers should identify the areas where they are strongest and determine how AI investment can strengthen their foothold. For example, a carrier that has strong product pricing and development capabilities may want to leverage AI to bolster their capabilities in the market. Buttressing existing capabilities, particularly if leading in the space requires carriers to take the stairs, may cement industry leaders.
  2. Determine The Market Requirements – After investing in their strengths, carriers should determine what it takes to win the market. This will be heavily product-specific, but there are broader trends that are applicable across the industry. For example, carriers should continuously benchmark key cycle times, volumes, and processes against the industry. Wherever they are behind, carriers should leverage AI to focus on achieving industry parity. Carriers need to be mindful – AI is useful, but only when it is placed on optimal processes. This means that carriers need to ensure that they have taken the stairs where necessary, and that may mean investment in areas that do not have the same appeal as direct AI investment.
  3. Develop A Perspective On The Future – After addressing strengths and winning in the market, carriers should focus on longer-term trends and how they develop capabilities to meet the emerging trends. For example, hyper-personalization of products is a growing area of focus. Consumer demand for products that are targeted at their cost point and needs is not going anywhere. From an AI investment perspective, carriers will need to determine how AI helps them address this trend – is it more dynamic product pricing based on consumer needs? AI being leveraged to process increased sensory data to provide more dynamic premium pricing? Or behavioral suggestions to reduce costs or provide additional coverage based on consumer actions? Carriers' bets on directionality will influence what investment is necessary, and when.

Carriers can use this framework in 2026 and beyond to structure their AI investment in ways that will be most immediately significant. But maximizing that investment means understanding where to place their bets and determining what opportunities exist to leverage accelerants and vendor solutions to achieve those results, while also recognizing where carriers are unable to avoid the foundational work to support AI solutions at scale.


Chris Taylor

Profile picture for user ChrisTaylor

Chris Taylor

Chris Taylor is a director within Alvarez & Marsal’s insurance practice.

He focuses on M&A, performance improvement, and restructuring/turnaround. He brings over a decade of experience in the insurance industry, both as a consultant and in-house with carriers.