Download

Agency Buyers Are Pickier, Not Gone

Buyers have not stopped buying. They have stopped buying everything. Here is what that means for owners planning to sell in the next two to five years.

Insurance

Every few months, an owner tells me the window has closed. Deals are slower, the big buyers have gone quiet, and the best time to sell was a few years ago.

I understand why it feels that way. I just do not think it is true.

The market is not done. It is getting picky. And for owners who prepare, picky buyers are good news.

What the run-up looked like

For most of the last decade, buying agencies and distribution businesses was a volume game. Capital was cheap and plentiful. Buyers had growth targets to hit, and the fastest way to hit them was to add revenue by the book.

So they bought nearly everything. Large agencies and small ones. Clean books and messy ones. Owners who planned to stay and owners who wanted out by Friday. Diligence was fast because speed was the strategy. If a deal had a few problems, the thinking went, the platform would fix them after closing.

That era taught a lot of owners the wrong lesson. It taught them that a book of business sells itself. For a while, it did.

What changed

Two things happened. Money got more expensive, and buyers started living with what they bought.

The first part is simple. When capital costs more, every deal has to earn its place. A buyer who once could afford to be wrong on a few acquisitions now has to be right on most of them.

The second part matters more. After years of fast buying, many acquirers spent time integrating the agencies they already owned. They learned which deals delivered and which ones turned into projects. They saw books that shrank after the founder left. They saw producers who walked. They saw systems that lived in one person's head and nowhere else.

That experience changed how they buy. Not whether they buy. How.

What "more strategic" actually means

I have been involved in more than 25 acquisitions and completed two exits of my own. I have sat on both sides of the table. From the buyer's chair, "more strategic" comes down to one question: will this business still work a year after the owner steps back?

Buyers now look hard at a few things.

They look at retention. A book that holds its clients year after year tells a buyer the relationships belong to the agency, not to one person. Retention is the floor. Growth is what earns attention.

They look at dependence on the owner. If every key client calls the owner's cell phone, the buyer is not buying a business. They are buying a job that comes with a resignation letter attached. To the owner, being the center of everything feels like strength. To a buyer, it is a single point of failure.

They look at systems. Documented processes, a clean agency management system, clear compensation and a team that knows how things run without asking. Boring is safe to buy.

They look at fit. Buyers are no longer adding agencies just to add revenue. They want businesses that fill a gap in their footprint, their product mix or their talent. The same agency can be a priority for one buyer and a pass for another.

And they look at the people. A strong number two, producers who plan to stay and a culture that will survive a change in ownership all reduce risk. Buyers pay for predictability, not potential.

What gets passed over

The flip side is just as clear. The businesses that sit on the market now are usually not bad businesses. They are businesses that are hard to transfer.

An agency where the owner is the top producer, the operations manager and the only person with carrier relationships. A book with strong revenue but no clean data behind it. A business that grew fast but cannot explain why clients leave. An owner who has not decided whether they want to stay, go or something in between.

In the run-up, many of those deals closed anyway. Today, they get a polite pass, or they get an offer with so much structure attached that the owner carries most of the risk.

What to do if you plan to sell in 2 to 5 years

The good news is that two to five years is enough time to become the business buyers want. It is not enough time if you wait until year four to start.

Start by making yourself less necessary. Move client relationships to your team. Introduce your key accounts to the people who will serve them after you. Every relationship that lives only in your head is a discount waiting to happen.

Next, get your house in order. Clean up your data. Write down how the business actually runs. Know your retention, your revenue by carrier and line, and your margins without having to dig for them. When a buyer asks a question, the answer should take minutes, not weeks.

Then decide what you want. Do you want a full exit, a partial sale or a role going forward? Do you want a partner who will grow the business or a clean handoff? Buyers are more strategic now. Owners should be too. The right buyer for you depends on what you want your next chapter to look like, and that is a partnership question, not just a transaction.

Finally, build the business as if you will sell it, even if you are not sure you will. The things that make an agency attractive to a buyer are the same things that make it easier to own. Fewer fires. Better people. More time.

Where the market is heading

I expect the market to keep moving, just with more discipline. Buyers will spend more time on fewer deals. They will pay attention to quality, fit, and the strength of the team. Well-run agencies will keep drawing real interest, and the gap between a business that is ready and one that is not will keep getting wider.

That is not a closed window. It is a higher bar.

The real question is not whether buyers are still buying. They are. The real question is whether your business will be the one they choose.

The run-up rewarded owners who were in the market. The next era will reward owners who were ready.


Mike Mathweg

Profile picture for user MikeMathweg

Mike Mathweg

Mike Mathweg is CEO of We Know Medicare, a partner at Gyde and chairman of Relentless Group. 

He has been involved in more than 25 acquisitions in the Medicare space, has completed two agency exits, and advises business owners on growth, acquisitions and succession.

A Key to Growth for Life Insurers

Life and annuities carriers can unlock growth by leveraging AI and data connectivity to streamline operations and strengthen distribution relationships.

Insurance

The life and annuities (L&A) industry is navigating a complex operating environment. Recent research reveals that the net income in L&A remained relatively flat in the first half of 2026, with total income falling 8.1%, driven in part by declines in premiums and annuity considerations. In a more challenging growth environment, every opportunity counts, making it imperative for carriers to maximize business opportunities already within reach.

As we approach year-end and plan for the new year, carriers should revisit efficiencies, identify areas for improvement, and find ways to capture more business from existing demand as well as generate new demand.

Unlocking this potential means addressing current operational inefficiencies. Often, we see carriers relying on legacy systems that don't connect easily, splitting customer and policy information across siloed systems. Additionally, manual processes can slow transactions and increase error risk, while differing compliance and reporting requirements further complicate an already complex process.

Reducing friction starts with better use of what carriers already have: valuable data. Connecting the dots between data is key to streamlining operations, improving services, and capturing more of the market's potential. With enhanced connectivity across underwriting processes, carriers can reduce administrative burdens and overall improve visibility. For advisors, this can be a game-changer, as better access to product information, application requirements, and case statuses means more time supporting clients. For carriers, delivering this experience can strengthen relationships with distribution partners. A win-win overall.

The opportunity here is clear: make existing operations more efficient while creating more capacity to serve customers and place business.

Fast-tracking policy issuance

Every additional manual step in application, underwriting, or case management can add time and costs to getting a policy issued and placed. That inefficiency grows even more when information moves between multiple people, systems, and organizations.

McKinsey's analysis of AI-enabled insurance transformation found that insurance organizations implementing AI-enabled transformations were seeing 20% to 40% reductions in customer onboarding costs and 10% to 20% improvements in agent productivity. For life insurers, the potential is particularly relevant given how much information must move across applicants, advisors, carriers, underwriting teams, and external data sources. Every handoff creates room for errors and can add delays and extra work.

Modern tools, like AI, can help cut manual overload by gathering and summarizing information, identifying missing information, routing work, surfacing relevant documentation, and supporting underwriting workflows. As carriers gain access to more structured data and can analyze it more quickly, they may also be able to make risk decisions with fewer manual steps while maintaining appropriate controls.

The Society of Actuaries' 2026 research on AI and life underwriting highlights the importance of data quality, workflow integration, and governance in determining whether AI delivers value in underwriting. Faster cycle times can ultimately mean less labor devoted to each case, lower costs associated with moving business through the organization and supporting it over time, and fewer opportunities for prospects to drop out.

But faster policy issuance is only one part of the opportunity. Advisors also need the capacity to focus on customers and move more business toward placement.

Customer-forward state of mind

Advisors often spend substantial time finding information, navigating multiple systems, managing applications, and following up on case requirements, limiting the time they are able to spend with customers.

AI can act as a force multiplier by summarizing product and case information, surfacing relevant documentation, guiding advisors through workflows, and helping answer questions based on approved information. The benefits extend to customers. When technology reduces administrative work, advisors can spend more time understanding customers' financial needs and ensure they are recommending suitable coverage as those needs evolve.

This focus on AI is becoming increasingly important as the industry considers the future of distribution. LIMRA's 2026 research points to AI, integrated workflows and automation as part of the technology changes reshaping advisor roles, while the industry continues to face advisor growth and succession pressures.

However, none of this works reliably if the underlying data is fragmented. Carriers need consistent definitions, joined sources, and clear permissions, so AI can surface useful information without creating new compliance or security risks.

Modernizing the experience means strengthening distribution relationships

The people and relationships that support distribution also matter for sustaining carrier growth. A carrier can invest heavily in attracting new business, but fragmented systems, slow processes, and administrative burdens can make it harder for advisors to serve their clients. As a result, inefficiencies can weaken distribution relationships and affect the customer experience.

This should become a focus as new generations of workers enter the market. Younger workers increasingly expect a modern and seamless technology experience. The traditional process of moving between separate systems for applications, illustrations, underwriting information, and case status creates a pain point. A modern workflow can bring relevant information into one place and provide contextual assistance rather than requiring advisors to know which system contains each piece of information.

Carriers should focus on creating more connected experiences that bring relevant information and workflows together. In doing so, it creates a competitive differentiator and helps strengthen the distribution relationship, building the pillars for long-term growth.

Looking ahead

For the L&A sector, growth doesn't always mean finding entirely new sources; in fact, meaningful opportunity already exists in the current business moving through the organization.

The key is using modernization to address the operational barriers that limit growth. Those who get the most from connectivity and modern technology like AI will not necessarily be the ones deploying the most tools. They will be the ones using AI deliberately to address specific business challenges and create measurable value. For L&A carriers, the mandate is clear — leverage technology and AI to improve existing operations so more of the business already within reach can move forward, and long-term relationships can be built.


Katie Kahl

Profile picture for user KatieKahl

Katie Kahl

Katie Kahl is chief product officer of iPipeline. 

Kahl joined iPipeline from Applied Systems, where she was most recently senior vice president of product management. She began her career in product management at Ceridian Dayforce.

She earned a bachelor’s degree from the University of Minnesota.

Can Frontier AI Outdo the Top MBAs?

Frontier AI models score 88% on MBA-level business cases, but that measures match against known answers, not judgment on open decisions.

Insurance

Three of the country's top business schools just tested frontier AI on the analytical work MBAs are trained to do, and the models scored in the high eighties. If you run a company, that number is coming for you soon, probably in a deck that recommends cutting a layer of analysts. So, it is worth being exact about what it measures, because the exact answer is both more useful and more limited than the headline.

The paper is BusinessCaseBench, from researchers at Wharton, Carnegie Mellon, and Harvard Business School. They drew 615 questions from real business school cases across 18 disciplines, from strategy and finance to leadership and ethics. Each model read a case cold and wrote its analysis. A separate grader then compared that analysis against the reference solution the instructor had written, item by item. The models never saw the reference. From the model's perspective, it faced an open business question with no answer attached and answered it well. Under the main metric, Claude Sonnet 4.6 covered about 88% of what the instructor's solution contained, and GPT-5.4 about 87%.

The answer key did not help the model. It could not see the rubric, did not use it, and produced its analysis based solely on the case, as a consultant would from a brief. From the model's perspective, these were genuinely open questions. So it is fair to expect that a model that writes strong analyses on 615 unseen cases will write a strong analysis on the 616th, your real case.

The problem is that "the model will write a similar analysis" and "you will get a similar result" are distinct claims, and only the first is what the benchmark tested.

A Score Is a Comparison

"The model scored 88%" is not a fact about the model's answer by itself. It is a fact about that answer measured against a standard. Two things had to exist for the score to exist – the analysis the model wrote and the instructor's solution it was checked against. The score is the relationship between them.

Now move that setup to your company. The model can still write the analysis, but the standard it's checked against doesn't exist. The 88% was a measure of how well the answer matched a known good answer.

This is not a word game. It is the difference between "the model is competent" and "you can trust the output." The first concerns the answer. The second concerns checking the answer, which requires a standard. The benchmark supplied the standard. Your hardest decisions do not.

Knowable-But-Hidden Is Not the Same as Unknowable

The tempting reply is that the real world is just the benchmark, with the answer hidden. The model handled hidden answers well; a real decision is just another hidden answer.

But the benchmark's answers were not hidden. They were knowable from the start. The professor had already worked the case. A correct answer existed; the model simply was not shown it. That is a different situation from the one you face when deciding whether to enter a market or restructure a division. There, no correct answer exists yet. No one has written it because the outcome that would settle it is years away, the criteria for "good" are contested by the people in the room, and there is no counterfactual to check the decision against, even after the fact.

A graded case has a knowable answer the model didn't see. A live strategic decision has an unknowable answer that doesn't exist to be seen. A student who scores 88% on a past exam she took blind will likely score about 88% on the next exam. But it does not follow that she will make good venture bets, even though both feel like hard, open-ended judgment, because a venture bet has no marking scheme, then or later. The model is the student. The benchmark is the past exam. Your boardroom is the venture bet.

The benchmark is strong evidence for a real claim: Frontier models are good at producing structured business analysis and are improving quickly. It is not evidence for the claim that the score predicts a good outcome for decisions whose standard must be invented rather than looked up. Inventing that standard and deciding what a good answer to your actual question would even need to contain is the judgment.

That argument stands even if the models are excellent.

The Model Is Fully Right About Half the Time

The researchers scored the answers in two ways. The headline 88% reflects partial credit – how much of the instructor's checklist each answer covered. Then they ran a stricter count. They counted how many questions the answer satisfied the entire checklist, every item, with no gaps. That fell to roughly half.

In cases where a correct answer was knowable, the leading model produced a complete answer about once in two cases. The authors put the point in their own title: These are drafts, not verdicts.

Now extrapolate honestly. If you carry this model into the wild and expect "similar performance," you are also carrying its incompleteness. The typical output is strong yet missing something. In the study, a human holding the instructor's solution caught the missing half. In your firm, if you removed the person who could catch it, the missing half would still be missing, and nothing would catch it.

Grader Didn't Check for What Shouldn't Be There

The grader verifies whether each expected point is present. By construction, it does not scan the answer for confident, invented, or incorrect material that falls outside the checklist. A response can meet the expected points and assert three plausible fabrications and still score well, because the method does not look for fabrications.

In the study, the blind spot is harmless because a grader with the solution ignores the extra material. In your company, it is the whole risk. The fabricated line rides along inside a well-organized analysis, unflagged, and the reader of the study who could catch it is the domain expert, whose strong score seemed to make it optional.

Why 'Drafts, Not Verdicts' Is the Expensive Finding

A draft that is 88% right sounds like a bargain, and sometimes it is. But it moves the work rather than removing it. Obvious things that are garbage you would catch. Verified truth is something you could trust. The strong, incomplete, possibly embellished draft is the expensive case, because it earns your trust on the parts you can see and hides its gaps in the parts you would already know the answer to. Catching what it left out requires someone who knows what a complete answer contains, which is exactly the expertise the draft would look to retire.

So, the generation got cheaper, and the checking did not, and for this kind of work the checking cannot be sampled down. You cannot review only the flawed answers, because the flawed ones are the ones that look fine. You review all of them, or you review none and call it oversight. An organization that reads the 88% as a license to remove the reviewers has not automated the analysis. It has removed its own ability to tell when the analysis is wrong.

What It Means If You Run Something

Read correctly, the benchmark is good news. Frontier models are genuinely strong at producing structured business analysis, and that is real leverage you should use. The error is interpreting a score against a known standard as readiness to deploy without a standard.

Two questions to ask of any AI you are about to trust with judgment tasks.

First, does this task have a knowable answer, or is defining the answer the actual job? Where a defensible right answer exists, with a standard you could write down, let the model run and expect it to perform in the wild about as it did on the bench. That extrapolation is fair and worth taking. Where the standard itself must be invented and argued, the model can draft, but a person still owns the decision.

And second, who checks the drafts, and do they know enough to catch what a confident draft leaves out? If the answer is nobody, or nobody who could tell, the high score measures something you will not actually get.

The models are good at the framed question. Your hardest problems arrive unframed. The competitive advantage was never in answering the case. It was in knowing which case you were actually in.


Madhu Shashanka

Profile picture for user MadhuShashanka

Madhu Shashanka

Dr. Madhu Shashanka is CTO, chief scientist and co-founder of Concentric AI.  

He earned his PhD in computational neuroscience studying how the brain coordinates vast numbers of independent units into coherent behavior, then spent two decades applying that lens to organizations, building and deploying enterprise AI across manufacturing, financial services, social media, and cybersecurity. His book "Coherence: The Competitive Advantage AI Can't Buy" explores what the science of coordinated systems reveals about competing in the age of abundant intelligence.

Why the Surge in Business Interruption Claims?

Business interruption claims now average 70% more than property damage losses as concentrated production and fragile supply chains amplify risk.

Insurance

Companies are increasingly at risk from surging business interruption losses due to concentrated production, fragile supply chains, geopolitical tensions, inflation, and growing technology dependencies. New claims analysis from Allianz Commercial shows that the average total value of a business interruption claim now exceeds €850,000. This is around 70% higher than the corresponding average property damage claim of close to €500,000, demonstrating that the financial consequences of being unable to operate can substantially exceed the cost of repairing the damage that caused the disruption.

Allianz's report analyzes 7,888 business interruption insurance industry claims with a total value of approximately €6.74bn, or US$7.82bn, from Jan. 1, 2021, to Dec. 31, 2025. Although claims frequency has remained relatively stable, the average value of claims increased by over 30% annually during the past two years.

Fire is the dominant cause of loss

Fire and explosion is the costliest cause of business interruption claims, accounting for more than 40% of the total value analyzed, equivalent to approximately €2.9bn, or US$3.3bn. Fire was responsible for nine of the 10 costliest man-made business interruption events in the dataset and was the most expensive cause of loss in markets including Germany, Singapore, the UK and the US. One case illustrates how losses can escalate beyond the original incident: a fire at a small manufacturing unit caused relatively limited physical damage but severely disrupted downstream operations, ultimately resulting in a nine-figure group-wide business interruption loss.

Natural catastrophes are the second-costliest cause, representing 34% of the value of claims analyzed, and the most frequent, accounting for 26% of claims. Together, fire and explosion and natural catastrophe events generated more than 75% of total claim value.

However, non-natural catastrophe events – such as fires, water damage and machinery breakdown – remain the principal overall business interruption loss driver, accounting for 74% of claims and 66% of their total value.

Recovery is taking longer and costing more

Some natural catastrophe claims are developing over increasingly long periods. Almost two years after Hurricane Helene in September 2024, many associated business interruption claims remain unresolved, not due to coverage issues, but because some businesses have taken that long to recover. Supply chain delays, labor shortages, and volatile material costs can extend both recovery and settlement.

Concentrated production is also amplifying losses. Industries can depend on a limited number of specialist sites, suppliers, or regions for critical materials and components, allowing a fire, cyber incident, or extreme weather event at one location to cascade through global supply chains. The two costliest non-natural catastrophe events in the analysis involved fires at semiconductor factories.

Cyber disruption broadens the risk landscape

While ransomware remains the leading cyber-related cause of disruption, a growing share of loss activity is also being driven by cloud outages, software failures and incidents at third-party technology providers. More than 48,000 outages were tracked across hundreds of cloud and software services in 2025 alone, according to outage tracker IncidentHub, highlighting businesses' rising dependence on digital supply chains.

High-profile incidents, including attacks on software providers and logistics platforms, demonstrated how a single cyber event can disrupt thousands of organizations simultaneously – one attack on a US automotive software provider caused a weeks-long outage for around 15,000 car dealerships. As companies become more reliant on cloud services, AI and third-party technology providers, cyber-related business interruption is becoming a more significant and complex source of loss.

Loss prevention and preparedness: the way forward

In today's connected environment, the severity of a business interruption loss is not always determined by the extent of physical damage. This underlines the need for robust business continuity planning, including the identification of critical production units, key dependencies and contingency arrangements to limit the impact of a localized disruption. More companies are now requesting risk surveys of key third-party suppliers – a practice well established in the automotive sector but increasingly adopted elsewhere.

In my work with clients, the gap I see most often is not awareness but follow-through. Many organizations have mapped their key suppliers, yet far fewer have quantified how long each critical site, supplier, system or technology provider would take to restore – or tested their business continuity plan against that scenario. The claims experience in the report bears this out: outcomes are materially better where business continuity plans are realistic and tested, and where business interruption values are reviewed regularly so that inflation does not quietly erode cover.

For cyber-related business interruption, early detection and rapid response are the most effective loss reduction levers. Companies that detected and isolated cyber incidents early, prioritized revenue-critical systems and accepted temporary operating modes were able to shorten their effective business interruption period by days or even weeks. Tabletop exercises – essentially "fire drills" for cyber incidents – have also proven highly effective.

However, the report cautions that while many companies have invested in supply chain transparency and dual sourcing since the Covid-19 pandemic, tangible risk improvements – such as enhanced fire protection or increased inventory buffers – have been limited and not consistently applied across companies, sectors and countries. The report emphasizes that even modest investments in fire protection and natural catastrophe prevention for critical assets can significantly reduce business interruption exposure.

To read the full report, please visit: Business interruption claims | Allianz 

Gen Z Drives Insurance Claims Transformation

Gen Z's demand for instant digital experiences is forcing insurers to modernize claims payments or risk losing policyholders.

Insurance

As digital natives who've grown up tethered to smartphones and social media, the Gen Z population's effect on today's consumer trends is well documented. Young shoppers' demands for instant gratification in consumer transactions have ushered in an era of in-app shopping, next-day shipping, and fast, friction-free digital payment options.

Gen Z's influence is extending to the insurance claims process, as well. More and more, Gen Z's preferences are pushing the industry to uplevel its claims experience – to make it faster, more convenient, more tied to mobile, and more transparent to the policyholder. InvoiceCloud's 2026 Claims Experience survey of 1,000 U.S. policyholders shows Gen Z is nearly twice as likely as the overall population to prefer a digital wallet for claims payments (13% versus 7%).

Recent research shines a light on policyholders' discontent with what they identify as their biggest deal breaker: an unacceptably slow process for paying claims.

The InvoiceCloud survey found that only 9% of policyholders received their claims payment within two days. Meanwhile, a quarter of respondents say it took more than a week to receive their claims payout, while an unfortunate 13% waited "several weeks" to get these urgent funds.

This could cause ripple effects. In a 2022 report, "Transforming claims and underwriting with AI", Accenture estimated that poor claims experiences could put up to $170 billion in global insurance premiums at risk through 2027. The InvoiceCloud survey shows how these risks could materialize. At least 75% of policyholders surveyed say they would consider switching carriers after a single negative claims experience. That's a high percentage in any field, but it's particularly high in personal-lines P&C, where switching providers is often easier than it is in commercial, E&S, or other specialty markets.

Improving the claims process

How do insurance carriers improve the claims process? Our research found that speed and transparency matter most of all to policyholders. When asked directly, 30% named a faster claims payment after approval as the single change they want most, more than any other option, while 22% preferred clearer status communication. Gen Z echoes that second point: 24% named clearer, more consistent communication about payment status as the one change they would make, on par with the 21% who named faster payment.

Another issue: Many carriers have modernized inbound premium payments, but outbound disbursements still rely on paper checks and manual processing. Paper checks create fraud risk, delivery problems, and extra work for commissions and return premiums.

The next generation of policyholders is demanding two changes to this payment structure. They prefer a shift to digital, and they want choices.

Digital disbursement platforms can support a wide variety of options including ACH/direct deposit, debit cards, virtual cards, and digital wallets. Direct deposit to a bank account is policyholders' favorite payout, preferred by 52% of respondents, more than all other options combined. Printed checks still account for 19%, likely reflecting legacy carrier processes rather than genuine preference. The gap between generations is wide: 32% of Baby Boomers prefer a printed check, compared with just 9% of Gen Z.

If slow payouts can lead to defections, digital insurance payments can operate as a retention tool.

Insurance carriers can do this by ensuring this critical touchpoint becomes an easy experience end-to-end, from allowing policyholders to self-serve through digital premium payments, paperless billing, and automatic payments, to instant disbursements delivered however policyholders prefer to receive funds.

Real-time digital disbursements are funds sent electronically and received quickly, without a paper check in the middle. For insurance carriers, this means agent commissions and return premiums move through digital payment processing solutions rather than the mail. More importantly, it means getting funds into policyholders' hands fast, when it matters the most.

Raising expectations

As younger policyholders account for a larger share of the insurance market, experiences they've grown accustomed to in other walks of life will increasingly become expectations for insurance as well.

For many, this translates to being able to complete more transactions on smartphones. Digital payments enable customers to choose a payment method from their phone, receive payment notifications, track payment status, access transaction details, and receive funds directly into an eligible account or wallet. That matters most to the youngest policyholders. When asked for the easiest way to access funds in an emergency, 19% of Gen Z chose a mobile wallet, compared with 5% of Baby Boomers, while only 9% would withdraw cash at a bank, compared with 34% of Baby Boomers.

Gen Z's imprint on insurance claims is becoming more pronounced. Today's policyholders want to have insurance claims processed and paid out faster. But they want more. They want the entire journey – culminating in how and when they get paid – to feel as immediate and seamless as any other digital financial transaction.


Ray Walsh

Profile picture for user RayWalsh

Ray Walsh

Ray Walsh leads InvoiceCloud's insurance vertical, helping property and casualty carriers modernize the way they bill, collect, and disburse payments to policyholders. 

He previously served as vice president of enterprise sales at Brightcove and senior vice president of global sales at TransAct Technologies.

Walsh sits on the board of Greater Springfield Habitat for Humanity, where he currently serves as board president. He studied business management at Albertus Magnus College.

How to Use Social Media Intelligence in Claims

Social media intelligence in claims now hinges on authenticated documentation and defensible collection methods, not just finding damaging posts.

Insurance

Most carriers, SIU teams, and adjuster groups built social media research into their claims workflows years ago. The first question, whether to use it, is settled. The second is harder: what to expect from it, how it should be collected, and what to require from whoever does the work.

The cases that get attention are the dramatic ones: a claimant on long-term disability filmed doing something the reported injury should not allow. Those cases are real, but the everyday value of social media intelligence is rarely one damning post. It is a steady, documented record of a claimant's public online presence, gathered carefully and delivered in a form a claims professional can actually use, both when the decision is made and later, if that decision is challenged.

What Actually Changes in a Claim

Fraud detection is the most common reason carriers commission this research, and the value there is well established. Public posts can contradict a reported injury, suggest undisclosed employment, expose a staged event, or connect participants in a claim that does not add up.

But the same work can support a legitimate claim. A claimant's own posts may corroborate the timeline of an accident or document the severity of an injury. Findings like these move a file forward faster and reduce the friction of additional verification.

The research also produces context an adjuster cannot easily develop alone. It starts with finding the accounts beyond the obvious one: profiles under a nickname, maiden name, or handle that does not match the claimant's legal name, and activity on platforms an adjuster would not think to check. From there, it adds confirmation that each account belongs to the subject and not a similarly named person, patterns of behavior across platforms over time, connections between individuals relevant to a fraud ring inquiry, geographic details that corroborate or contradict where a subject claims to live or work, and third parties who posted publicly about the incident. Each of these moves a claim toward resolution, whichever way the facts point.

A $75,000 Gap Between the Story and the Record

Consider a recent bodily injury claim arising from an auto accident. The claimant alleged an injury that limited daily function and mobility, and the commercial transportation carrier handling the file had valued the claim at $300,000. Before finalizing its settlement position, the carrier commissioned a scoped search of the claimant's public social media and online presence, focused on physical activity, mobility, recreation, travel, and any direct statements about the injury.

Photos posted by the claimant showed a race finish and workouts at a gym. Other posts placed the claimant in outdoor recreation requiring balance, core strength, and endurance. A public listing offered the claimant's handyman services for hire. Public court and traffic records, unrelated to the accident, were documented as additional context for the file.

Each finding was documented with its capture date, source code, and an analyst's summary, so the record could be authenticated if the claim was contested. The carrier revised its valuation from $300,000 to $225,000, a $75,000 reduction supported by evidence the claimant had made public.

The lesson is not that social media catches fraud. It is that claimed injuries are described in narrative terms, while public activity is built from dates, images, and firsthand posts. When the two diverge, the gap becomes material to claim value, and the carrier needs a record it can stand behind.

Why the Collection Method Decides Whether It Holds Up

A meaningful share of claims do not end at the adjuster's desk. They move into litigation, often months or years after the investigation closed. When the collection method was built for litigation from the start, that transition is straightforward. When it was not, the carrier is left with content that may be accurate but cannot be defended the way an authenticated finding can. And by the time anyone tries to reconstruct the record, the original posts may have been altered or deleted and are no longer recoverable.

Consider how that plays out. An adjuster finds a post that appears to undercut a claimed injury, takes a screenshot, and notes it in the file. The claim is denied, and eighteen months later it is in litigation. Defense counsel wants to introduce the post. Opposing counsel asks who captured it, when, from what account, and how anyone knows it was not edited. The screenshot has no capture date, no link, no metadata, and no source code to answer those questions. Counsel goes back to the platform, and the post is gone, whether deleted by the claimant or removed with the account. What looked like a smoking gun is now a cropped image with no provenance, and the court may never see it.

What to Require, Whoever Does the Work

Whether the research is done in-house or by an outside provider, the same standards apply:

  • Public sources only. Lawful collection relies on publicly available information, gathered without deceptive friending, impersonation, or any attempt to defeat a platform's privacy settings. Evidence collected outside that line is rarely usable and can expose the carrier to risk of its own.
  • Scope defined at intake. The subject, platforms, time period, known identifiers, and type of content sought should be documented before the search begins, so the work can be explained later.
  • Identity confirmed. The most useful accounts are often not under the claimant's legal name. Every finding should be tied to the subject through distinct personal identifiers, such as photographs, locations, employers, vehicles, family connections, or content cross-posted from a confirmed account, so there is no question who the account owner or originator is.
  • Each finding is preserved for authentication. An image of the content as captured, a link, the capture date, metadata, and source code. This is what lets a finding be authenticated later without rebuilding the record.
  • A repeatable, analyst-led process. Trained people following a consistent methodology, supported by tools where useful, never running on automation alone.
  • The complete record, not just the highlights. Including findings that support the claimant.

Those last two points matter because automation has a role, scanning volume and flagging patterns quickly, but it cannot interpret context. A water-skiing photo that seems to contradict a back injury may have been posted years earlier and resurfaced through a friend's memory share. A gym check-in may be a physical therapy session. Human judgment is what separates a misleading flag from a usable finding.

When opposing counsel asks what was searched, where, and why, there should be a record to answer the question.

The Bar Has Moved

Social media intelligence has matured to the point where the question is no longer whether someone can find something. It is what they find, how they document it, and whether the record holds up across the full life of a claim.

Carriers settled the first question years ago. The ones that will get burned are those still treating it as the only question, running a search, saving a screenshot, and calling the file complete. The second question, whether what was found can be defended when it matters, is the one that now separates a useful finding from an expensive one. Scope the work, confirm the identity, preserve the record, and keep the whole of it. Then the answer to opposing counsel is already in the file.

AI Voice Agents Transform Lead Calling

AI can contact leads much faster than a human workforce can, boosting sales, but a small error rate in managing the AI can lead to serious problems.

Insurance

Insurers and agencies pay to generate leads, then let many of them go cold before a licensed agent calls. AI voice agents can now place that first call within seconds, at whatever volume the lead flow demands. That solves one of the oldest problems in insurance distribution. 

But it does not move the risk. Every AI call goes out on behalf of your company, and the rules treat it that way.

The speed problem is real

A 2011 Harvard Business Review study of 1.3 million sales leads found that firms that tried to contact potential customers within an hour were "nearly seven times as likely to qualify the lead" as those that tried an hour later and "more than 60 times as likely" as those that waited 24 hours or longer. Few agencies can staff to call every lead within minutes and at peak volume. An AI voice agent can call the moment a lead arrives, confirm that the person asked to be contacted, ask a few eligibility questions, and hand the live call to a licensed agent.

Draw the line at the license

The design that holds up best keeps the AI on one side of a clear line. It confirms interest, checks a handful of facts, and connects. Advice, quoting, and selling stay with licensed people. The line also clarifies the economics: 

Measure the AI on qualified conversations handed over and the agent on policies written. In the systems we build at VoiceOI, the transfer carries AI-written call notes, so the agent picks up where the AI left off instead of repeating its questions. When the roles blur, both the compliance review and the return-on-investment math get harder.

The risk stays with you

In February 2024, the Federal Communications Commission confirmed that the Telephone Consumer Protection Act's restrictions on "artificial or prerecorded voice" encompass "current AI technologies that generate human voices." Those calls need the called party's prior express consent. Hiring a vendor does not change who answers for them. The FCC ruled in 2013 that a seller "may be held vicariously liable under federal common law principles of agency" for violations committed by third-party telemarketers. The statute lets consumers recover $500 per violation, and a court can triple that for willful or knowing violations. At the volumes AI makes possible, a small error rate is not a small number.

Much insurance lead flow comes from comparison sites and lead partners. For telemarketing calls, FCC rules define prior express written consent as a signed agreement that "clearly authorizes the seller" to call using an artificial or prerecorded voice. The consent behind a purchased lead has to clearly authorize your company, and you need to be able to retrieve it for any call.

Opt-outs are part of the product

Two rules deserve attention at the executive level. First, artificial or prerecorded voice messages must, "at the beginning of the message, state clearly the identity of the business" responsible for the call. Second, a residential subscriber's do-not-call request must be honored within a reasonable time that "may not exceed ten (10) business days." The same rule says that when someone else keeps the list, "the person or entity on whose behalf the call is made will be liable for any failures to honor the do-not-call request."

A well-built AI agent can recognize "stop calling me" and end the call. The hard part is making sure that request reaches every system, lead partner, and vendor that might call the same person again.

Your phone numbers are a shared asset

Carriers and call-analytics firms judge numbers by how they behave. One voice provider's guidance warns that campaigns "with low answer rates and a high share of very short calls look like untargeted cold calling to carriers and analytics providers." AI agents can produce exactly that pattern at scale, and a spam label on a number follows every call made from it. Keep outbound lead campaigns off the numbers your service and claims teams rely on, and watch answer rates and complaints as closely as conversions.

Start where consent is clearest

The safest first deployment is the one with the cleanest consent trail: people who filled in your own quote form today and asked to be called. Run the AI on that flow beside your current process for a few weeks and compare contact rate, qualified transfers, and complaints against the human baseline. Expand to aged leads or partner-sourced leads only once the consent records for those sources hold up to the same scrutiny.

Five questions before you sign off
  • Consent: Who collected it, for which company, and can we produce the record
  • Disclosure: Does the call say at the start who is calling?
  • Opt-outs: Does a do-not-call request reach every system and vendor within 10 business days?
  • Handoff: What triggers a transfer to a licensed agent, and what does the agent see when the call arrives?
  • Measurement: Are we tracking contact rate, qualified transfers, cost per qualified transfer, and complaints?

AI makes the first call cheap. That is exactly why the decisions around it — whom to call, what to say, and when to stop — now belong with leadership rather than with the call floor.

Turning Volatility Into Value

Amid today's heightened uncertainty, Dawn Miller, chief commercial officer at Lloyd's, explores how insurers can innovate their way to value both for themselves and for their clients. 

Insurance

Paul Carroll

We’re in an exceptionally volatile period, with major geopolitical and economic risks on top of climate-driven catastrophes, nuclear verdicts, and more. The International Insurance Society’s annual Global Insurance Forum in November, which you’re sponsoring and hosting at Lloyd’s, has as its theme this year: "Turning Volatility Into Value." How do we do that?

Dawn Miller

I'm just coming off some time at CIAB [Council of Insurance Agents and Brokers] in Colorado, and the topic that is on everyone's mind, in addition to market conditions, is how multiple perils are intersecting with global trends to create an increasingly varied and complex risk landscape, with some risks well modeled and others less so. 

In the past, our market would focus on certain CAT risks, certain natural perils happening in one place at one time. Now we're seeing multiple risks interact at the same time, from natural catastrophes and supply-chain disruption to inflation, geopolitical uncertainty and demographic risks. And those are just to name a few. It’s the interaction among these different risks that is adding new layers of complexity.

We have innovations that allow us to model with more transparency, and we can bring in supplementary models to assess risk. That's a good thing. But it takes an enormous amount of creativity to predict the layers of complexity around us today.

Paul Carroll

Yes, some people who’ve written for us refer to a “polycrisis.” You mention modeling. Is that the main way insurers make sense of all these complicated connections, or is it improvements in scenario planning, or something else?

Dawn Miller

I believe it's multiple things. We're seeing innovations in modeling—additional data transparency being plugged into some of those core models that we've always used to look at some known perils. The perils aren't changing, but our ability to understand them is getting better, sometimes dramatically. 

There's also an opportunity for geopolitical assessments, economic assessments, and social demographic assessments to all play a role. The modeling itself is a bit of a Rubik's Cube with multiple facets to it.

Paul Carroll

Wall Street talks a lot about alpha and embraces volatility because it creates opportunities. Historically, insurers have not liked volatility. How do you change that thinking?

Dawn Miller

Given that Lloyd’s is guiding a marketplace, we're creating the conditions for success for the world's best risk takers to attach the risks they want to underwrite with capital. We see a mix in our marketplace. We do see investors coming in looking for some of that volatility. That’s what they like, and it fits as a diversifier into their portfolios. We see others wanting the longer-tail risk. This may not be as volatile, but they want it for their own investment reasons.

Our role is to create the environment for all those different profiles to exist and to all benefit from the diversification of our marketplace. It's not an either-or—the alpha seekers or the beta seekers. It's having both in an environment where they can coexist.

Paul Carroll

Volatility requires agility not just for those transacting in your marketplace but for you, too. How is Lloyd's getting faster at identifying opportunities and scaling the winners as quickly as possible?

Dawn Miller

In March, we launched our new five-year strategy, Advance and protect. It is designed to sharpen Lloyd’s financial edge and maximize our unique capital advantage, including by creating a more efficient and flexible marketplace by making the platform more investable, clear, transparent and agile.

Right now, there's some additional reporting, different ways of working, maybe some duplicated oversight here and there—things that have grown up over time for all the right intentions, but maybe as we evolve are not as pragmatic any more. All of those cause a little bit of extra cost, whether it's in time or resources, because time is money at the end of the day.

So we're making things much clearer, making it much more cost-efficient, making sure we are an engine for driving new talent into the marketplace, attracting the best talent and then recycling them back out as advocates and having the marketplace stronger for their being with us. You're creating an ecosystem that is the center of attracting the world's best risk takers, the best capital together with the best brokers, best clients, the best risk.

What that gives us is the ability to innovate. When we think about Lloyd's and the underpinnings of our strategy, our superpower is our capital diversification benefits. Our other superpowers are around our license structure, the framework we have for innovation, the ability to syndicate risk rapidly, our very strong financial strength ratings.

Innovation, whether it is the birth of a new product, or the birth of a new structure, or how we deal with some of the extreme large-scale infrastructure, energy, supply chain, and transportation issues that we see around the world—that is going to take more than one mind to solve. And we are the marketplace for that sort of solution creation.

Paul Carroll

At ITL, in our little way, our mantra is: Nobody is as smart as everybody.

Dawn Miller

That's exactly right. Our role is to convene a marketplace, creating those conditions for success. It happened 338 years ago when people came together over a cup of coffee and said, Let's share this risk so we can get these ships across the globe. Today, the same principle of combining expertise and capital continues across the underwriting room, Lloyd’s Lab and Lloyd’s Academy. 

Paul Carroll

I’m glad you mentioned the lab and the academy, because, as an old hand on innovation efforts, I wanted to ask how they fit into your broader innovation ecosystem.

Dawn Miller

Absolutely. As you know, Lloyd's Lab launched in 2018 to make sure we had a place to accelerate—not necessarily incubate, and I want to make that distinction—new risk-taking ideas or risk-servicing ideas. Over time, we've grown to have about 160 alumni.

This past cohort, Cohort 17, just went through a selection process. We received 280 applications from 31 countries. Fifteen companies were invited to pitch to the market, and 10 were selected for the 10-week Accelerator program. The market plays a central role in that selection process because the Lab is designed to respond to real market needs. 

The focus of Cohort 17 has been in areas where the Lloyd’s market is actively seeking solutions that improve how the market operates day to day to strengthen its ability to respond to the complexity of today’s risk landscape and this can be seen through the themes: operational efficiency, new products and experimental innovation. 

What does that mean? They come in at all different stages of businesses and ideas. They have mentors from the marketplace. They hone, shift, and massage their product and their service. Then they exit the other end, generally about 80 to 85% of them, with either capacity for a proof of concept or a service contract or service proof of concept into the marketplace. That ranges from new products—cloud downtime, wildfire, data analytics—to a whole variety of services.

They work their way through the market, with an accelerated cover holder process. Some of them, like Parsyl, started in the Lloyd’s Lab. Parsyl began by using data and technology to tackle risks in global health supply chains, then became a Syndicate-in-a-Box and now has in-principle approval to become a full syndicate. That’s the process of taking innovation, testing and proving it in the market, and ultimately giving it the opportunity to scale.

They're a part of our ecosystem once they come out as alumni, and they stay within our ecosystem around the world. We continue to help by giving them opportunities to be exposed to end clients, to regulators, to investors, etc.

Paul Carroll

How do you expect these topics—including innovation, geopolitical risk, and emerging technologies—to be developed at the Global Insurance Forum?

Dawn Miller

I always look forward to the Global Insurance Forum; it's a place where market leaders and market practitioners are coming together to exchange on an equal level. We’re reflecting the trends of the times, whether that’s private credit, scaling innovation or how we move beyond the tactical. This year’s theme, “Turning volatility into value,” really captures that. It’s about moving beyond reacting to uncertainty and using better insight, specialist expertise and flexible capital to anticipate changing needs, build solutions and give customers the confidence to invest and grow. 

The companies that come together are from all around the world. Everybody's lens is going to have a slightly different take on how they deal with geopolitical risk or how they're dealing with supply chain or how they're dealing with credit risk or what they're facing at that exact moment. Bringing all of that together allows us to create a narrative that firmly implants how our industry is driving resilience forward.

Our industry provides the oxygen for the economies around us. And I believe we allow our industry to represent itself or be represented by others in a way other than that. I wish we talked more about the outcome our industry enables: resilience. We need to explain insurance through communities, businesses and economies it enables to recover and thrive and persist. 

The forum also creates a great opportunity to bring some of our young leaders to the table. Their perspectives are varied and rich, and we need that diversity of thought. 

Paul Carroll

As someone who’s covered technology innovations for decades, I confess that it was only about 15 years ago that I realized that none of that happens without insurance. Every major innovation—the personal computer, the internet, the smartphone, social media, search engines, GPS, the driverless car—comes with risks, and nobody can take those risks without some sort of protection. 

Dawn Miller

Right. Isn't it funny? We all sort of take it for granted. 

If we could just reframe the conversation and talk more clearly about how insurance creates resilient communities, helping them thrive, we would give people a much better understanding of the value our industry provides. At Lloyd’s, we don’t just seek to understand risk, we take it on, bringing together expertise, capital and risk appetite to help businesses move forward.

The issue couldn't be more important than it is right now, with the multiple layers of risks that surround us.

Paul Carroll

Thanks, Dawn. It’s always great talking with you. 

Dawn Miller

Thank you for having me, Paul; always a pleasure.

If you’re interested in attending the Global Insurance Forum, you can register here.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

Car Thefts Are Plunging. Why?

Car thefts in the U.S. tumbled to their lowest levels in decades in 2025, and are down a further 21% this year. The trend is likely to continue, too.

Image
Insurance

The recent report that auto thefts fell 21% in the U.S. in the first half of the year reminds me of a friend's carjacking some 30 years ago — surely the shortest in history. 

My overeducated friend, with degrees from Brown and the Sorbonne, had just added a certification as an auto mechanic and liked cars that required constant tinkering. While driving near his home in Washington, DC, one afternoon, he stopped at a stop sign, and a pedestrian motioned to him that he had a question. Tim rolled down his window, and the man shoved a gun in his face, ordering him out of the car.

The man got in, engaged the clutch and drove... two feet. He tried again, but the car stalled after two more feet. He tried a third time. A fourth. He hadn't even made it halfway into the intersection before he jumped out, threw the keys at Tim's chest and ran off. 

I'd never thought of having a diseased clutch as an anti-theft device but have watched with interest over the years as actual devices have continually improved. They've now gotten to the point that, combined with other factors, thefts fell 17% in 2024, tumbled 23% last year, to the lowest levels in decades, and are way down again this year. The good news for insurers is likely to continue, too.

Let's have a look. 

Some of my optimism stems simply from the steady modernization of the car fleet. Even though soaring prices for cars have encouraged people to hold on to cars longer than in the past, older, more vulnerable cars are steadily being retired, and that trend will continue. 

In the face of public pressure, companies whose cars were most likely to be stolen have also issued software patches and other updates — as a result, the percentage of car thefts of Kias and Hyundais fell to 14% of the total last year, from 16% in 2024 and 21% in 2023, even as the total of thefts dropped precipitously. 

Meanwhile, the supply chain has sorted itself out post-COVID, so thieves can't rack up the sorts of profits they did from stealing scarce parts in recent years. The U.S. war on Iran may unsettle the supply chain again, including by pushing sales of electric vehicles during a time of high gasoline prices, but the effects have been muted so far, and I suspect they'll remain so.

Law enforcement has stepped up efforts to prevent all sorts of crimes, and car thefts are a visible target at just about all levels of policing. I'm not sure how much more severe enforcement can become, but, especially in a fraught political environment, I don't see that anyone will relax.

Potentially the most important — but fraught — factor that will determine how much car thefts keep falling relates to surveillance technology. Flock has built a massive business by installing cameras on roads nationwide that take pictures of license plates and respond to, among other things, alerts from police departments about stolen vehicles. There are lots of efforts to also figure out how to knit together all the images being gathered by dashcams, which are currently in about one in 10 vehicles in the U.S. and which are being adopted quickly. 

Combining all those feeds could provide real-time intelligence for police departments, making it far easier to catch thieves and creating a massive disincentive for them to steal cars in the first place.  

But....

We've also seen how surveillance can be abused, as I wrote in August. Flock faces a scandal because dozens of police officers used its technology to stalk current and former romantic partners, and the temptation to use surveillance illicitly will only increase as the technology becomes more powerful.

My gut tells me that it will take time, perhaps years, to sort through all the tensions between law enforcement and privacy but that we'll eventually get to the point where some severely circumscribed uses of license plate readers will take another cut out of auto thefts. The privacy issue is one we've mostly navigated with Ring cameras and surveillance cameras on building, so there's a blueprint for progress

The bad guys are always innovating, just as the good guys are, but I think the favorable glide path for car thefts should continue.

Cheers,

Paul

P.S. My other bizarro car theft story, this one involving a nephew and an odd situation for the adjuster:

While my nephew was visiting DC last year, his Hyundai was stolen off the street by four kids — who drove the car right past him as he was talking with the police officer who responded to his report of the crime. They took the car on joy rides for a few days — as evidenced by the thousands of dollars of traffic violations they ran up in DC and Maryland — then used it in a drug deal that went bad. 

The car wound up full of bullet holes, and a friend of the kids was shot. Panicking, the kids put the badly wounded girl in the trunk of the car and dumped her in front of her high school. These young geniuses then abandoned the car and tried to run off but were promptly apprehended by school security. (The girl healed fine.)

The insurance issue was that the adjuster couldn't look at the car because it was in police custody as a crime scene. So my nephew's insurer kept him in a rental car for weeks until it finally satisfied itself that the car was a total loss and wrote him a check for a new one.

My nephew spent weeks unwinding the traffic tickets. He actually had to drive to Baltimore from Philadelphia to appear in court and provide evidence that he couldn't have been at the wheel for the moving violations because he wasn't in Maryland when they occurred. 


AI Shapes Customer Demand While Measuring It

AI systems now shape customer choices through recommendations and interactions, making causal identification essential to distinguish genuine needs from system-influenced demand.

Insurance

When companies talk about understanding customer needs, they often assume a simple path:

Underlying Need → Observed Demand

A customer has an underlying need, even if they cannot fully articulate it. Through questions, data, and observed behavior, companies try to work backward from what the customer says or chooses, to understand what that person actually needs.

Demand discovery has therefore traditionally been treated as a process of finding something that already exists.

In a previous article, I argued that reproducing an outcome is not the same as understanding the causal mechanism that produced it. The same distinction applies to customer demand: observing what customers choose is not the same as understanding why that choice emerged.

What deserves more attention is the arrow in the middle.

The path from underlying need to observed demand is never empty. What customers see, how they are questioned, what recommendations they receive, and how they interact with a system can all shape the demand that eventually becomes visible.

AI makes this issue more important.

When systems begin deciding what to present, how to rank options, what question to ask next, what to recommend, or what action to take based on a prediction, the observed demand that companies ultimately see may already contain the influence of the system itself.

How much of the demand we observe reflects what the customer already needed, and how much emerged through the interaction itself?
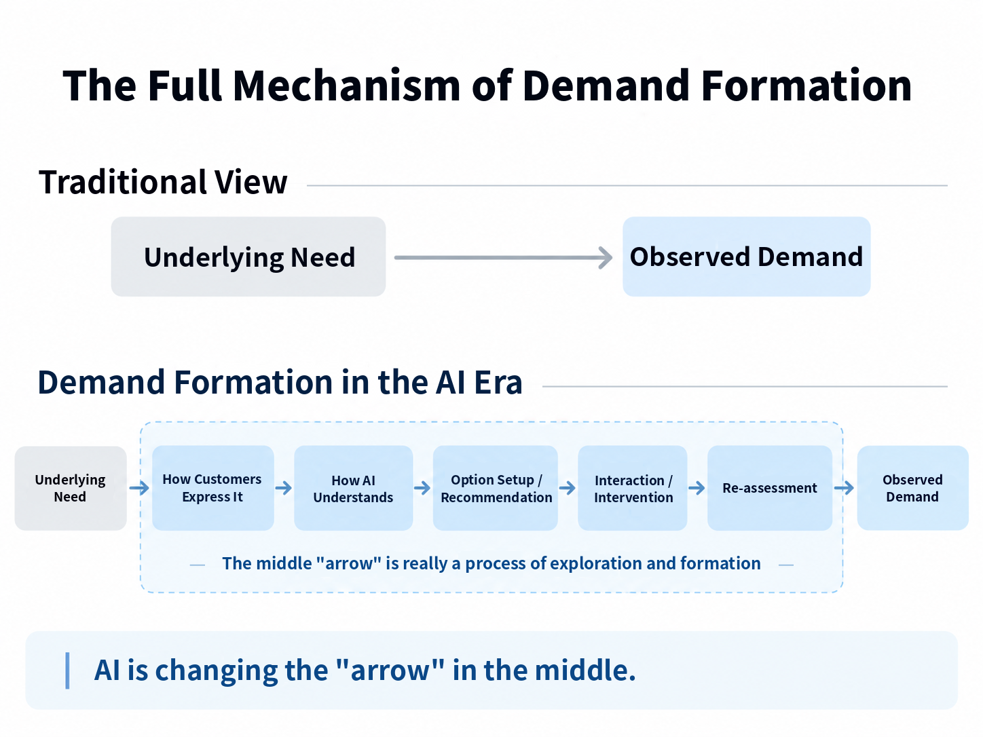
Figure 1. The full mechanism of demand formation.

1. We Have Treated the "Arrow" as Too Simple

Suppose a customer chooses Product A from three options. The intuitive conclusion is straightforward:

The customer chose A, so A must best reflect their preference.

But before making that inference, there is another question:

Why did this customer see these three options in the first place?

In the age of recommendation systems, different customers are rarely shown identical choices. A system may use previous behavior, income, browsing history, search activity, and other signals to determine which products are most relevant to present. The real process may therefore look more like this:

The system evaluates the customer → determines which options the customer sees → the customer chooses from those options.

In 2021, researchers from Cornell and Stanford described this problem in a paper titled "Choice Set Confounding in Discrete Choice." Many preference models infer what people prefer from the choices they ultimately make. But the choice set itself may already depend on the chooser's characteristics and existing preferences. Recommendation systems are a classic example.

If that mechanism is ignored, two different things can easily become mixed together:

What the customer already preferred, and what the system chose to place in front of them.

The hotel-booking example in the study makes this easy to understand.

Suppose a recommendation system has already filtered hotels based on a user's preferences, and the user consistently chooses the cheapest hotel among those presented. A model might conclude that price is the dominant factor in that person's preference.

But that conclusion may overstate the importance of price. Location, star rating, or other attributes may already have been filtered earlier in the recommendation process. Once researchers accounted for this confounding, price became less dominant, and other factors became more important.

Preference is not the same as underlying need. But choices and expressed preferences are important behavioral signals companies use to infer what customers need. 

That means demand discovery cannot focus only on what the customer ultimately chose. It must also consider the choice environment in which that decision was made.

2. AI Does Not Just Influence What We See. It Can Change What We Choose.

Choice set confounding tells us that a final choice cannot be understood independently of the options that preceded it. But there is an even more direct question:

Can AI recommendations themselves change what people choose?

A 2026 Pension Portfolio Experiment posted on arXiv provides a clear example. Researchers recruited 400 South Korean employees who were actually enrolled in workplace defined-contribution pension plans. In a simulation, participants first allocated a hypothetical pension balance across 11 investment products. They were then randomly assigned one of two AI-generated recommendations: one relatively aggressive and concentrated, the other relatively conservative and diversified.

Participants could then revise their original portfolios. Three findings stand out:

  • 81% changed their portfolios after receiving the AI recommendation.
  • Among those who revised, 95% moved in the direction suggested by the AI.
  • The difference between the two AI recommendations was partially transmitted into the final portfolios: the resulting difference between the two participant groups was about 37% as large as the original difference between the recommendations.

In other words, people did not simply follow the AI wholesale. But different AI recommendations still produced different final decisions.

The effects went beyond superficial portfolio changes. Participants who received the more aggressive recommendation ended up with higher expected returns and volatility, less exposure to low-risk products, and more exposure to high-risk products. The study did not find a significant improvement in risk-adjusted performance, but AI clearly changed the risk structure participants ultimately accepted.

The important point is the causal relationship:

Different AI recommendations produced different final choices.

Participants still retained much of their original judgment. The final decision was therefore neither purely human nor purely AI-generated. It emerged from the interaction between the two.

Now consider what happens next. If a company later observes those revised portfolios and records them as new evidence of "customer preference," that data already contains some of the influence created by the AI itself.

At that point, saying "The customer chose A, therefore the customer prefers A" is no longer a sufficient inference.

3. When a Model Begins to Influence the World It Will Later Observe

This leads to another important idea: Performative Prediction.

In 2020, researchers at UC Berkeley used this term to describe situations in which a prediction, once used to support a decision, changes the very outcome being predicted.

Consider a simple credit example. A bank predicts that a borrower has a high probability of default and therefore charges a higher interest rate. But the higher interest rate increases the borrower's repayment burden, which may itself increase the probability of default. The sequence becomes:

Prediction of high default risk

↓

Higher interest rate

↓

Actual default risk changes

The model appears to describe the world, but once deployed, it also begins to influence the world it is describing. Similar dynamics can occur in traffic prediction, policing, recommendation systems, and financial markets. Applied to demand discovery, the mechanism might look like this:

The model predicts that a customer may need A

↓

A is shown more prominently

↓

A is recommended

↓

The interaction increasingly centers on A

↓

The customer ultimately chooses A

At this point, the first layer of influence has already occurred: AI has affected the customer's choice.

The pension experiment shows that this can happen in practice. But there is a second layer. If the company then uses that choice as training data for the next generation of its model:

The customer chooses A

↓

The system records "customers like this prefer A"

↓

Similar customers are more likely to be shown A in the future

The company is no longer merely observing demand. It is beginning to participate in the formation of the demand it will later observe. This does not mean the model is necessarily wrong. The problem arises when companies forget that their own ranking, recommendation, and interaction mechanisms have already entered the causal process. They may then treat outcomes partly produced by the system as if they were pure evidence of the customer's original preferences.

4. The Path From Underlying Need to Observed Demand Is a Formation Process

The apparently simple relationship:

Underlying Need → Observed Demand

can therefore be expanded into something closer to this:

Underlying Need

↓

Customer Expression

↓

AI Interpretation

↓

Option Configuration / Recommendation

↓

Interaction / Intervention

↓

Customer Reassessment

↓

Observed Demand

Several mechanisms operate inside this process.

  • Choice architecture: determines what the customer sees and how alternatives are arranged.
  • Interaction: determines how the system asks, responds, and continues the conversation.
  • Recommendation: introduces new information and direction into the customer's judgment.
  • Intervention: occurs when the company acts on the model's judgment in ways that affect subsequent responses or decisions.

None of these mechanisms is entirely new. What AI changes is its scale, personalization, speed, and ability to operate continuously. There is also an important distinction to make. The fact that demand is shaped through interaction does not necessarily mean it is being distorted.

In many real situations, customers themselves may not fully understand what they need at the beginning. A well-designed discovery process can use questions, comparisons, and different scenarios to help customers clarify what they actually value.

The interaction therefore has two simultaneous functions. On one hand, it generates new signals and reduces uncertainty about the underlying need. On the other hand, the way questions are asked, options are presented, and recommendations are made can also influence how customers think and respond.

In the past, demand discovery was easier to think of primarily as a form of measurement. With AI, measurement and intervention increasingly occur at the same time.

The challenge is therefore not to eliminate intervention altogether. It is to distinguish between signals that reflect a relatively stable underlying need and signals that were caused by a particular question, choice set, or recommendation.

5. From Collecting Answers to Identifying Causes

If a company relies mainly on correlation, the logic is straightforward:

The customer chose A → therefore the customer needs A.

But once the system itself has participated in presenting, recommending, and explaining A, that inference becomes less reliable.

The more important question becomes: If the conditions were different, would the same need still appear?

  • Would the customer still choose A if A had not been recommended first?
  • If the price changed, would the customer still value the same type of protection?
  • If the customer saw a different set of alternatives, would the expressed preference remain?
  • If family responsibilities changed, would the need for protection change as well?

These are fundamentally counterfactual questions: If a particular condition had been different, would the outcome also have been different?

The contrast can be summarized as a shift from a traditional approach based on observed behavior and correlation to a causal approach that varies conditions and interventions to test demand hypotheses.

By introducing different conditions and interventions, companies can test competing demand hypotheses. Some changes should theoretically have little effect on a genuine underlying need. Other causal factors, when changed, should produce corresponding changes in demand. When customer responses behave consistently with these causal hypotheses, companies have stronger grounds for believing they are identifying the underlying need rather than merely predicting an observed response.

The choice set confounding research points in the same direction. When companies understand the variables used to assign choice sets and the mechanism by which those choice sets were generated, causal methods such as inverse probability weighting and regression controls can help reduce confounding and recover preferences more accurately.

AI therefore does not make genuine customer needs impossible to understand. But it changes what understanding requires. Companies cannot simply accumulate more behavioral data and expect the truth to emerge automatically. They need to understand the conditions under which each signal was generated, and whether the signal still holds when those conditions change.

A more mature AI demand-discovery process therefore cannot stop at:

Ask questions → collect answers → predict demand

It also needs to:

Form a demand hypothesis

↓

Design appropriate questions and scenarios

↓

Observe responses under different conditions

↓

Control for possible confounding

↓

Continuously revise the judgment of the underlying need

For example, a customer may ultimately choose Product A for very different reasons:

  • The customer genuinely needed A from the beginning.
  • The system placed A in front of the customer first.
  • The system repeatedly recommended A.
  • The way the questions were framed directed the customer's attention toward A.
  • Other relevant alternatives were never presented.

The observed choice may look identical in every case, but the mechanism that produced it is not.

Interaction is therefore no longer just a way to collect more data. Every interaction can also become a test of a demand hypothesis. The goal is therefore not simply to improve the predictive accuracy of observed demand. It is to improve the company's causal ability to identify underlying need.

Conclusion: Put the Company Back Into the Causal Chain

Traditionally, the challenge of demand discovery has been to look beyond surface-level statements and choices to understand what customers actually need. AI adds a layer. Once a system begins participating in option design, recommendation, questioning, and decision-making, the observed demand that a company sees may already contain the influence of its own AI.

Companies can therefore no longer ask only: How do we infer underlying need from observed demand?

They must also ask: Through what mechanism was this observed demand produced?

And once measurement and intervention can no longer be cleanly separated, companies need more than stronger predictive models. They need causal methods that can continuously improve their ability to identify underlying needs while interacting with and influencing customers.

A mature AI demand-discovery system should incorporate intervention into its design so that every question, option, and interaction helps distinguish among three things:

what the customer already needed, what the system itself helped cause, and what became clearer through the interaction.

If companies want to understand demand in the AI era, they must begin by putting themselves back into the causal chain.


David Lien

Profile picture for user DavidLien

David Lien

David Lien is a partner at Lingxi (Beijing) Technology. 

He wrote “Decoding New Insurance” (2020), which ranked among JD.com’s top books. Lien has held leadership roles at Sino-US MetLife, Sunshine Insurance and Prudential Taiwan, leading digital transformations and multi-channel marketing. A 2018 e27 Asia New Startup Taiwan Top 100 nominee, he holds a patent for the "Intelligent Insurance Financial Management System."