Download

Insurance Distributors Should Buy Carriers

Large insurance distributors are poised to acquire carriers as AI and private equity remove traditional barriers.

Photo of Men Working in a Warehouse

Independent agents continue to drive premium growth for carriers, with 60% of life insurance sales and increasing annuity sales (46% through IA/IMO/Independent BD) coming from third-party distribution (TPD), according to LIMRA.

The implication is clear: The future of insurance will be driven by independent distribution. So far, the focus has been on how carriers can control expenses related to third-party sales and get better selecting strategic partnerships. While that is important, there is a secondary implication that may be more important than the carrier focus:

How can distributors develop better partnerships with carriers?

The solution? Distributors should seek to acquire carriers and develop fit-for-purpose products and capabilities. We have seen this already occur in the P&C/specialty space, where MGAs/MGUs have acquired carrier shells. For example, At-Bay, a cyber insurance MGA, acquired an excess & surplus insurer to issue its own cyber and tech E&O insurance. Controlling the full value chain allowed the distributor the ability to accelerate product development and strengthen its commitment to its distribution channels. Life and annuity carriers could follow a similar model.

Why hasn't this worked before?

In the past, distributor-driven acquisitions of carriers have not been a match, for several reasons:

  • Capital and regulatory intensity – Independent distributors like IMOs are known for being light on capital and are built explicitly for sales and overrides. Carriers are built completely differently – RBC requirements and capital reserves are not only necessary, but encouraged to develop stronger ratings from credit agencies.
  • Scale threshold – Because of the capital and investment required, small to mid-size distributors have no chance to successfully acquire a carrier and leverage it for a fit-for-purpose distribution model. High fixed costs mean that in a highly fragmented distribution landscape, only the largest platforms could attempt this strategy.
  • Execution risk & operational complexity – Even if an independent distributor has the capital and scale, carriers bring capabilities that are non-native to independent distributors – claims, actuarial, and investment capabilities all require net new talent and systems to support.
  • Optionality and flexibility – Independent distributors pride themselves on having access to a wide-range of products in their toolkit. This "best-in-breed" approach is part of why independent channels have taken market share from captive channels. Owning an insurer potentially jeopardizes that optionality.
  • Risk mismatch – Distribution is a very different business than being an insurance carrier. Distributors are built for sales volume – overrides, commissions, and fees are all geared toward "more is better". Carriers are built on loss ratios, investments, and product profitability.
Why this is the time to act

All of these reasons have historically provided plausible rationale for why distributors have focused more on consolidation than achieving a "full stack" solution. But significant shifts in the market make this a time for the right distributor to break the mold.

  1. AI leveraged for neo-insurers – AI has made certain processes more scalable than ever before. The next frontier of AI development through agentic AI will be developing AI-native op models that move capabilities from human-centric to AI-centric. For distributors seeking to become full-stack, this means that the typical FTE-heavy carrier model no longer applies. Indeed, distributors can drive the AI-native carrier onslaught by leveraging AI to provide carrier capabilities within a distributor-centric operating model. Underwriting, claims, servicing, wholesaling functions and many others can now be designed around the distributor's goals and tech platform.
  2. Customer preference for holistic financial solutions – The share of US investors seeking holistic financial solutions (insurance & investment products) has grown from 29% in 2018 to 52% in 2023 (McKinsey). An Orion 2025 Investor Survey highlights that 78% of investors whose advisor does not currently offer holistic financial planning say they want it. Only 23% of advisors even offer insurance, suggesting a significant awareness gap and opportunity for distributors
  3. Heavy PE investment in the insurance market – Capital and investment requirements are significantly less of a concern for private equity investors, who have significant dry powder. This has caused several to go after distributors and/or carriers. These same investors can address a significant hurdle for distributors while diversifying their returns from both distribution and the carrier.
  4. Moat development – In an increasingly competitive market, where large distributors are consistently seeking to grow through inorganic acquisition/consolidation, there are fewer ways to differentiate. One way that some firms have sought to do this is through carrier/distributor partnerships to create products for specific distributors. Distribution-owned carriers take this to its logical conclusion – owning products becomes a key differentiator versus other large distributors.
  5. Innovation and speed-to-market – One of the complaints from distributors is how slowly carriers bring products and capabilities to market. Carriers owned by distributors avoid this – instead of long-feedback loops, distributors can leverage their insights to quickly meet the market where it is. Riders that might take 12-18 months from idea to rollout can be done much more quickly.
The way forward for distributors

Distributors that want to move forward have concrete steps to take on their journey to acquiring a carrier.

  • First, distributors have to make sure that they can successfully acquire and run a carrier. That includes:
  • Having sufficient scale as a distributor
  • Having capital or access to capital necessary to support a carrier
  • The ability to execute and successfully integrate a carrier into the distributor's platform

None of this can be overstated – the difference in creating an oddly formed captive model and a forward thinking distribution-led carrier will come down to execution and integration capabilities. This limits the possible audience to large distributors or those backed by significant capital.

If a distributor has both the means and the willingness to accept the risk, there are three concrete next steps.

1. Understand how the distributor wants to do business

The key emphasis for product fit-for-distribution is that distribution drives capabilities and decision-making. That means starting with how the distributor wants to leverage the carrier to better enable their sales and growth. For example, does the distributor want to accurately price the risk (e.g., leverage APS and medical exams) or do they favor speed of decisioning (e.g., leveraging simplified or accelerated underwriting) to lower cycle time?

There will be trade-offs for sure, but making these types of strategic decisions will directly influence how the carrier delivers key capabilities in support of the distributor (i.e., the operating model).

One additional consideration: what will the product development strategy be? Distributors could choose anything from niche products missing in the market to a full product suite and make them distributor-exclusive or allow others to sell them. Distributors should initially focus on addressing gaps in the market with exclusive products, but keep an eye on when they may have a product that makes sense to sell to others,

2. Develop an operating model that is fit for purpose

Once distributors have made key strategic decisions, it is time to convert that strategy from a what to a how. There are three key levers distributors should consider: AI, outsourcing, internal personnel.

Any distributor developing a carrier should do so in an AI 3.0 mindset – assume that the processes and capabilities should be built with AI at the forefront and human interaction only inserted where AI is incapable of performing the task today. This provides a lean organization that positions itself well in the future: as AI continues to develop this will position the carrier (and the distributor) the next stage of AI-driven operating models.

With AI and automation at the forefront of how the carrier operates, distributors can continue to develop capabilities by outsourcing and internal hiring. There are several considerations, but distributors should consider what talent should be in-house. For example, claims may not be a critical experience to the distributor and could be outsourced to a TPA, while product development may be a capability to retain.

3. Integrate and iterate to continue to improve

In a distribution-centric model, there should be a focus on establishing a proprietary data loop to drive sales.

Full ownership provides clean, first-party data on distribution behavior and claims, which can feed back into product/actuarial/pricing decisions faster than any carrier partnership allow.

To enable that, distributors need to integrate all carrier technology with the distributors existing platform – this will ensure that insights are seen end-to-end that improve the distributors ability to sell.

What comes next?

As distributors develop strategy over the next 5-10 years, they should expect to see independent distribution as a primary value driver, increased competition for advisor talent within independent channels, and an increased focus on customer centricity. The combination of those things suggest that distributor who innovate and can best serve the customer will be winners in the market.

The way to do that is simple, but not easy – leverage carrier capabilities to provide a true, distribution-led product development process. Large distributors and their investors must take immediate steps to leverage their scale to be a first in the market. Fast action will provide them with a first-mover advantage, and position them well as the market transitions. The first scaled distributor or PE-backed platform to execute this strategy will own the next decade of independent distribution.
Chris Taylor

Profile picture for user ChrisTaylor

Chris Taylor

Chris Taylor is a director within Alvarez & Marsal’s insurance practice.

He focuses on M&A, performance improvement, and restructuring/turnaround. He brings over a decade of experience in the insurance industry, both as a consultant and in-house with carriers.

AI as a Tool or AI as a Product?

The gap between $20 ChatGPT and six-figure AI vendors lies in integration, repeatability and operational complexity personal tools can't address.

An artist's illustration of AI

Someone on your team just demoed how ChatGPT or Copilot can extract data from a medical report in seconds. Now leadership wants to know why you're paying a vendor six figures for document processing when the same AI is available for $20 a month.

It's a reasonable question. Personal AI tools and operational AI systems solve fundamentally different problems, even when the underlying technology looks identical.

When an adjuster pastes a claim's medical records into ChatGPT to prep for a call, that's a one-time task. They provide context, review outputs, fix what needs fixing. The AI just makes them faster at work they were already doing.

When AI processes hundreds of documents a day as part of an operational workflow, a person isn't shepherding each one through. The AI becomes one component inside a larger system that needs to work reliably at scale.

The problem is these two use cases get treated as interchangeable. Organizations sometimes spend months building infrastructure for tasks an employee could handle with ChatGPT. Other times, someone proposes using ChatGPT for a process that actually requires serious engineering. Both mistakes come from not recognizing when a task requires a product. The telltale signs are integration, operational complexity, and repeatability.

Integration

ChatGPT works with whatever you paste into it. It can't reach into your claims system, query your policy database, or update a file on its own. In production, the AI sits in the middle of a pipeline. Data has to get in, and data has to get out

On the input side, documents arrive through fax servers, email integrations, and carrier portals. On the output side, extracted data has to be written to the system of record and validated against what's already in the claim file, and exceptions need to be flagged and routed. Without the integration work on either side of the AI, the system can't function in production.

Operational Complexity

When someone uses ChatGPT to extract data from a document, they're the orchestration layer. They decide what to paste in, what to ask for, what order to work through it. If something looks wrong, they adjust and try again. That works when you're processing one document at a time.

At scale, software has to do that job instead. Documents need to be normalized into a usable format. Illegible or corrupted files need to be handled. Outputs need to be validated, exceptions routed, and results connected to downstream systems. When something fails halfway through, the system needs to know where it stopped, what succeeded, and how to recover.

There's also the question of proof. When a claim gets litigated or an auditor asks how a decision was made, "the AI said so" isn't an answer. You need to show exactly where in the document a value came from and why it was interpreted that way. Personal AI tools are black boxes. Enterprise systems build in traceability because insurance requires it.

Finally there is the file size. A single claim file can run 10,000 pages. You can't paste that into ChatGPT. Personal AI tools have input limits that make documents like these impossible to process in a single pass. At that point, you're not using a tool. You need a product.

Repeatability

Personal AI tools are inherently variable. Ask ChatGPT the same question twice and you'll get different answers. When drafting a strategy document, this can actually help. Running the same prompt multiple times gives you different angles to choose from.

At operational scale, variability becomes a liability. A diagnosis code extracted one way in the morning might come out differently in the afternoon. Tags get applied inconsistently. Provider names normalize differently across batches. A claim that gets flagged high-priority on Monday might score as routine on Tuesday. These inconsistencies create problems throughout downstream processes.

When outputs are unreliable, users lose trust. They start checking everything manually, which defeats the purpose. Enterprise implementations address this through standardization: controlled prompts, validated extraction logic, versioned models, systematic testing. When something changes, you know what changed and why. When something breaks, you can trace it back. This infrastructure is what makes production systems require real investment, but it's also what makes them suitable for production.

When You Don't Need a Product

But the opposite mistake is also common. Not everything needs a product. If the task is infrequent and doesn't need to connect to anything, a person with ChatGPT can be the right answer.

A couple of times a year, a supervisor prepares for a mediation on a complex claim. They need to review the medical records, understand the treatment history, and build their argument. Someone sees that and thinks: we should build a tool for this. However, ChatGPT can help them work through it directly, surface key details, summarize sections. That's a tool making someone better at their job, not a workflow that needs to be automated.

The same applies outside of claims. Quarterly management presentations. Strategy preparation for a renewal. Evaluating a vendor. One-off policy research. These happen a few times a year, the output goes into a document or slide deck, and nobody needs the data anywhere else. Building automation around them solves a problem that doesn't exist.

The person doing the work already has what they need. They have the data, they understand the context, they'll review and edit whatever the AI produces. The value of personal AI tools is that they require no infrastructure. Let people use the tools directly, get useful output, and move on. Trying to systematize that just adds overhead without adding value.

Different Problems, Different Approaches

Personal productivity works because a human handles everything around the AI. They provide context, review outputs, catch errors, make decisions. For these use cases, give people access to AI tools and get out of their way.

Operational automation requires software to do what the human does in the personal productivity scenario. Integration with existing systems. Repeatable outputs. An application layer that makes the AI's work usable by others. That's a product.

The underlying AI might be identical in both cases. The difference is what surrounds it. If the task requires integration with other systems, that's a product problem. If it requires orchestration across large or complex inputs, that's a product problem. If it requires consistent, auditable outputs, that's a product problem. The more of these that apply, the further you are from something a person with ChatGPT can handle. If none of them apply, you probably don't need a product at all. Give someone the tool and let them work.

Document ingestion is one example. However, the same pattern holds for triage, fraud detection, subrogation, anywhere AI moves from assisting one person to running inside a workflow. The question isn't whether AI can do the task. It's whether you need a tool or a product. Get that wrong and you'll spend six months discovering why the vendor charges what they do, or build a system for something that just needed a person with ChatGPT.

How to Put People First in Your AI Rollout

"We made a deliberate decision to treat employee confidence as the primary KPI of our AI transformation."

A Woman Presenting in Front of a Room of Employees

When it comes to AI in the insurance industry, 2026 is shaping up to be a defining year. Adoption is accelerating, investment is increasing, and nearly two-thirds of independent agents say they're optimistic that AI can support their work.

But putting generative AI to work inside an independent agency, MGA, or carrier doesn't happen with the flip of a switch. Successful AI implementation takes an operational shift through disciplined execution, clear governance, and a defined path to measurable benefits. Most importantly, it requires investment in your most valuable resource: your people.

That was our guiding principle when we implemented enterprise AI tools at Vertafore. In 2025, we set out to equip ourselves and our teams to use AI in the best way possible. Our goal was to learn how to make ourselves, teams, and products better for the end customer.

To accomplish that, we committed to pausing business as usual for a full week as a company to give our global team time to immerse themselves in AI confidently, responsibly, and creatively. We made a deliberate decision to treat employee confidence as the primary KPI of our AI transformation, and we measured it before and after implementation.

Before expanding access, we concentrated on three priorities: mindset, training, and governance. Here's what happened and takeaways for businesses that want to find success with AI.

Employee confidence sets the foundation

Understandably, some employees fear that companies want to use AI to replace their human workforce. That may be the case in some organizations, but many businesses—including Vertafore—see AI as a tool to help make work more manageable, improve efficiency, and create space for higher-value thinking and better customer service.

The key to managing employee fears is transparency and communication. We addressed employee concerns early and reinforced our intent to use AI to support our human teams, not replace them. That's especially true in a relationship-driven industry like insurance, where judgment and accountability cannot be outsourced to a model.

We reinforced that human oversight remains central, established clear security guardrails, and created structured opportunities for employees to ask hard questions and understand expectations. This included a simple framework: asking "Should I?" instead of "Can I?" Employees were encouraged to consider who benefits, who could be harmed, and whether AI was truly the best fit for a given scenario. The framework reinforced that AI supports professional judgment rather than replacing it.

To measure the impact, we surveyed employees before and after our immersion week. We didn't focus only on productivity metrics or efficiency gains. We measured employee confidence. We positioned AI as a productivity multiplier and asked one core question: How do I make myself, my team, and our products better for the end customer?

The results speak for themselves: confidence rose 13% and those that were "not confident" dropped 11%. Employees who saw AI as a "go-to collaborator" doubled and expected daily or near-daily use rose 27%. Among people managers, confidence using AI rose 23%, with 80% saying they're confident with helping their teams use AI responsibly.

Create space to learn

To help employees build real skills, we made a deliberate choice to set aside dedicated time for learning.

Instead of squeezing experimentation between daily responsibilities, teams were given bandwidth to explore AI. Leaders set up time for employees to test ideas, collaborate across teams, and explore ways to apply AI to their specific roles. And as an organization, we created full-company sessions to dive into AI questions and hear from experts on their lessons learned from putting this technology to work.

Prioritizing learning in this way accelerated adoption. Our teams spent time getting to know the AI tools in the best way possible: by seeking solutions to the challenges and opportunities they encounter every day. Not every idea and trial made it out of the gate. And that's okay. But many of our teams built the foundation for real AI applications.

Internally, our learning and development team created a custom GPT to help employees and managers build individual development plans that support career growth. The tool guides users through identifying where to start, developing skills within their current role, or preparing for a move into another internal role. By following prompts and exploring development ideas, employees can create clear, actionable plans while discovering recommended resources such as LinkedIn Learning and other company tools.

How to measure what matters

If employee confidence with AI increases, it stands to reason that successful adoption will follow. With that in mind, we treated the mindset shift as the first KPI. From there, we narrowed our focus.

Rather than attempting to transform the entire organization at once, we identified one to two areas where return on investment (ROI) could be clearly measured within a defined timeframe. Functions such as customer support often provide the clearest early signals because call times and quality improvements are easier to quantify.

For each use case, we established a clear hypothesis to answer:

  • Where will AI create value?
  • What outcomes should we see within the first 90 days?

Within customer support, for example, we used AI to refine knowledge base articles so representatives can quickly access the most up-to-date product information during calls. Measurable outcomes include reduced time spent searching for information, faster turnaround between calls, and higher customer satisfaction.

Another area we tracked was product development, with defined objectives around output volume and delivery timelines. We've established targets to measure progress and ensure consistent improvement over time. Peer experts also led office hours that created a safe space to test ideas, ask questions, and build confidence.

By focusing on a specific department, establishing clear goals, and tracking quantifiable metrics, such as time saved, communication volume, and call response time, you can better determine the next steps for scaling AI across your teams.

Lessons learned

Our early efforts drove real engagement, but they also exposed some opportunities. Not every team benefited in the same way, and not every employee felt ready to apply what they'd learned. That tension helped clarify what actually drives progress. Here are the lessons we took forward:

  1. AI adoption isn't one-size-fits-all. Teams across the organization have very different AI use cases and skill levels. All-company sessions, such as discussions with external business leaders, offered useful perspectives but did not give employees the role-specific guidance they needed to apply AI in their daily work.
  2. Progress doesn't happen at the same pace. Some individuals jumped in quickly, while others needed more context and support. Moving forward required patience, targeted enablement, and learning experiences tailored to where people actually were rather than where we expected them to be.
  3. AI success starts with mindset, not mandates. Tools alone don't drive transformation. Confidence does. When employees understand the "why" and feel equipped to experiment, adoption follows. That's where change management becomes a true advantage. Organizations that invest in building understanding and trust are best positioned to turn AI from a tool into a differentiator.
A clear path forward

AI transformation begins with people. We learned that dedicating focused time for learning helps employees step away from daily work and fully engage in building new skills.

Pairing that time with privacy and security training ensured employees explored AI tools while understanding the company's protocols for responsible use. When employees understand the purpose, feel supported as they learn, and trust the guardrails in place, AI stops being an abstract initiative and becomes part of how the business operates. In insurance, where judgment and relationships matter, that human foundation is everything.

Invest in your people first. The technology will follow.

AI Transforms Actuarial Reporting

Insurers are achieving 30% efficiency gains as AI shifts actuarial work from production tasks to interpretation and governance.

Red and Green Candlestick Chart

Life and health insurers today face a complex balancing act. Product portfolios continue to grow in sophistication, regulations intensify, and financial reporting teams are under unprecedented pressure to produce fast, accurate, and explainable results. At the same time, operational costs and talent pressures remain stubbornly high.

Against this backdrop, artificial intelligence has rapidly moved from a talking point to a transformational force. AI is often described as "a fast, confident, tireless, occasionally wrong junior analyst" -- and while that may raise a smile, it also reflects a reality: AI is powerful, imperfect, and increasingly expected to transform all workflows.

So, what is AI actually doing in actuarial and financial reporting today? And what might its emergence mean for the people and processes behind the numbers?

How AI is helping to drive efficiency

Over the past decade, AI technologies have evolved from simple statistical models to advanced foundation models, reasoning engines and now AI "agents". This progression is no longer theoretical; insurers are already applying standard tools to accelerate routine work and reduce operational burden, boosting team efficiency by about 30%. The AI agents are increasingly contributing to human efficiency, leveraging advanced software capabilities or functioning as actuarial accelerators to execute specific tasks as needed.

One area where this is particularly visible is model documentation and code translation. For example, tools have been developed that convert actuarial code into clear, natural language documentation, saving around 75% of the effort on much-hated essential activities. Similarly, AI tools that translate open-source code and Excel spreadsheets, as well as building from specifications, can reduce the overall implementation costs by a similar proportion.

We see insurers similarly deploying AI to support data validation and cleansing; bulk document parsing; trend and variance analysis; narrative drafting and financial report preparation workflows; in addition to the more prevalent customer service triage.

Individually, these use cases offer incremental gains. But when stitched together -- and especially when used within agentic architectures -- the effect compounds quickly. Many insurers now see 20–30% efficiency improvements in reporting cycles where AI has been embedded purposefully.

AI vs humans: Augment or replace?

Fears that AI will replace actuarial or financial reporting talent are understandable but, for now, overstated. Judgment, accountability, regulatory interpretation and interpersonal communication remain fundamentally human responsibilities.

However, the nature of early career and mid career work is changing. Traditionally, analysts built expertise through repeated exposure to data preparation and production tasks. As AI increasingly replaces this work, entry level roles will shift rapidly toward interpretation, scenario analysis and communication of results.

This transition brings three major consequences:

Organizational design will change: Continuing the trend seen with automation in recent years, teams built around large production functions will shrink. Fewer people will be needed to generate numbers; more will be needed to challenge, interpret, narrate and govern them.

Skills portfolios must expand: AI literacy will become as fundamental as spreadsheet literacy once was. Those who thrive will be those who can use AI as a collaborator rather than a novelty tool.

Recruitment patterns will shift: Graduate hiring pipelines may narrow in the short term as automation removes the need for large analyst cohorts. Yet regulators retain their requirements for responsibility, with a strong onus on senior management for validation of AI assisted outputs. This will drive a new generation of graduates who learn their trade through challenging rather than doing.

Crucially, the greatest barrier for most teams today is not technology, it is thinking too small. Asking AI simply to fix known errors in a dataset misses the opportunity to validate the data for unexpected issues or even to redesign the end to end process. Creativity and vision will differentiate the winners from the followers.

Human oversight still matters in AI

Even though actuarial work rarely involves personal data with its associated bias and confidentiality risks, financial reporting sits within one of the most tightly regulated environments in the corporate world. Model governance frameworks, audit trails and sign off processes leave little room for opaque or unexplained AI behavior.

Therefore, AI outputs must be reviewed by accountable humans; controls must evolve to include prompt governance, explanation frameworks, and AI specific testing; and corporate governance teams should be partners, not gatekeepers.

Modern AI systems can already perform coding tasks, run high level checks, generate draft commentary and review processes for operational weaknesses. But they must operate under human supervision, much like training and checking the work of a new colleague.

The rise of agentic AI

The next leap in capability comes from agentic AI - systems that can plan tasks, execute multi step workflows, interact with IT systems and use tools semi-autonomously.

For financial reporting teams, this is achieved through a combination of flexible AI questions combined with robust models and reporting processes. Together it could mean real time answers to "what if?" questions; dashboards that update themselves when the market moves; automated change testing and reconciliation workflows; and reduced delays from specialist technical teams

However, these gains bring governance challenges. Today's AI often looks "magical," which can undermine trust. One promising mitigation is neurosymbolic AI, combining machine learning-based pattern recognition with explicit rules - making outputs more explainable and auditable.

AI is moving from passive assistant to active coworker. It has the potential to add huge value in complementing humans. The question for insurers is no longer if this technology will transform reporting, but how quickly they can adapt.


Mark Brown

Profile picture for user MarkBrown

Mark Brown

Mark Brown is global proposition lead of life financial modeling for insurance consulting and technology with WTW.

What the Insurtech Wave Missed

Fragmented producer data threatens to collapse AI ambitions unless the insurance industry addresses foundational infrastructure issues now.

An artist’s illustration of artificial intelligence (AI).

The first wave of the insurtech revolution has crested, and we are getting a clearer picture of the hits and misses. In the last decade or so, the industry has seen massive strides in digital distribution, API connectivity, embedded insurance, and agency management system modernization.

What did we miss? A lot. And our misses are piling atop one another, slowly creating a precarious house of cards. 

The Insurtech Problem

Specifically, producer data quality, ownership, integration, and digitization have been largely ignored as companies race to integrate the latest and greatest tech. We've modernized quoting, underwriting, and customer-facing tools, but the producer data layer that powers distribution has yet to be addressed.

Currently, there is no single "source of truth" for producer identity, hierarchy, or compliance. Fragmented data lies scattered across carriers, MGAs, state records, and compliance systems. The reality of this information chaos is outdated records, manual input processes, duplicate and incomplete records, and severe compliance risk.

Why the First Wave of Insurtech Didn't Fix It

You may ask how a multibillion-dollar industry that the entire country relies on seemingly overlooked these critical issues. The answer lies in the complexity of the insurance industry.

The initial capital injection the industry saw followed revenue, not corporate infrastructure. We know from watching elections play out that infrastructure isn't an exciting topic, and it doesn't make for an enticing pitch to the electorate or the C-suite. Furthermore, organizations already suffered from decades of operational disorganization with highly complex layers. Remember, this isn't a sleek front-end problem, but a back office foundational issue.

Perhaps most importantly, the industry has failed to establish any clarity of data ownership. There is no standardization of which pieces are owned by carriers vs. agencies vs. MGAs. The results have led to fragmented chaos.

Understanding the Business Impact

Many organizations are loath to admit these issues have resulted in hits to revenue from multiple angles. Profit loss occurs from producers not being in compliance with state laws, commission errors, slow onboarding of new producers, data bottlenecks, and distribution channel conflicts.

The industry as a whole is exposed to compliance and regulatory risk. Companies spend large amounts of money trying to mitigate inconsistent licensing verification while navigating the minute compliance laws of 50 different states. Even with a seasoned compliance team, companies of all sizes are opening themselves up to grueling audits and costly fines.

The industry as a whole suffers from distribution inefficiency manifesting itself through slow carrier onboarding and appointment, manual credentialing processes, repetitive manual data entry across multiple systems, and cumbersome systems that either don't interact with each other or do so very poorly.

These issues are ultimately compounded through analytic errors. Across the board, we see inaccurate production reporting resulting in organizations that are unable to properly measure producer performance. In many cases, leadership is operating off of incorrect or skewed information, potentially leaving millions, or billions, on the table.

AI is Poised to Exacerbate the Issue

Every industry conference and corporate event is abuzz with AI adoption. How can it be harnessed? How will your company use it? Who will be the AI winners? The truth is we are all set up to lose.

AI models are only as good as the information that feeds it. Distribution analytics rely on accurate producer hierarchies, meaning that automated commission systems will surely crack under inconsistent data. AI promising fraud detection and compliance screening is doomed to fail without consistent accurate data. Under these circumstances AI will most likely present hallucinations and bad outputs placing companies at greater risk.

The Answer Exists, But Adoption is Needed

There is good news. We know what the industry must do to reduce risk and prevent AI collapse. Organizations need a standardized producer identity layer to ensure successful AI adoption. Defined accountability in the industry would go a long way, and it is something we need to address, but for now companies must implement their own systems.

These solutions exist and many in the industry are confronting the issue head on. But it would be foolish to chase after the AI boom without shoring up your foundations.


Ido Deutsch

Profile picture for user IdoDeutsch

Ido Deutsch

Ido Deutsch is chief revenue officer at Producerflow, which modernizes and streamlines producer onboarding and licensing.

While studying for his MBA at UC-Berkeley, he teamed up with Luis Pino to build Agentero and led go-to-market functions. Deutsch built Producerflow from within Agentero, and it became its own startup in 2025.


AI Transforms Workers Comp for Brokers

AI enables overwhelmed workers' comp brokers to shift from transactional quoting to strategic risk advisory relationships that employers increasingly demand.

Construction Site at Sunset with Workers on Scaffolding

For employers, one of the main concerns with a workplace injury is claims costs running out of control. For insurance brokers, the primary risk of a workers' comp claim not being managed correctly is losing a policyholder. While many brokers can quote workers' comp, few offer the strategy and insights that actually help employers rein in costs and reduce risk.

That has to change, and it can because of AI.

BROKERS AS STRATEGIC PARTNERS

Workers' compensation brokers are experiencing a dynamic shift away from the simplicity and speed of merely "quoting and bidding" to win and keep business. Policyholder expectations of their relationships with brokers have shifted. To stay competitive, successful brokers must differentiate themselves and connect with employers as true risk advisors.

It used to be that brokers only needed to check in with policyholders at renewal time. Employers used to make policy purchasing decisions based solely on rates, but that's no longer the case. Today, employers expect their brokers to serve as true partners, communicating transparently while adding experience, strategy, and insights. To retain customers, brokers must help them improve workplace safety, manage escalating workers' comp claim costs, and reduce overall premiums.

As stated in the Brown & Brown 2026 Employer Health and Benefits Strategy Survey: "Employers want brokers who don't just find a lower premium, but who audit pharmacy management, evaluate stop-loss designs, and flag high-cost claims before they escalate." The 2025 ZyWave Broker Survey reveals that 69% of employers are now prioritizing a more strategic, advisory-based relationship with their insurance broker over a transactional relationship.

However, that's a tall order when brokers are struggling to keep pace with the sheer volume of workers' comp claims they must help their clients navigate. According to the 2025-2026 Workers' Compensation Industry Insights Survey, 56% of claims professionals admitted they have "too many claims" to manage effectively—a 15-point increase over the previous year's survey.

AI: A FORCE MULTIPLIER FOR OVERWHELMED BROKERS

This is where artificial intelligence (AI), in the form of predictive analytics and insurance workflow automation, can provide vital support for brokers, helping them be more efficient and deliver the level of strategic service employers demand.

AI can be a force multiplier for brokers by automating processes and streamlining insurance workflows. With AI accelerating processes and flagging risks, workers' comp brokers can focus on better claims outcomes. The days of brokers existing as quoting and bidding machines are over. Brokers who do not adapt to using analytics and risk mitigation strategies will eventually melt away.

Here are five ways that AI has transformed workers' comp:

  1. Underwriting. Using AI-driven predictive models can help identify the best fit with specific workers' comp programs based on industry, company size, claims history, and other factors. Predictive analytics match each insured with the most impactful services—such as wearable tech, return-to-work programs, or early claims resolution—based on their loss history and risk profile. This tech-enabled approach ensures that operational resources are aligned with account-level risk, directly supporting both retention and loss ratio improvement.
  2. Injury prevention. AI can analyze real-time data to detect patterns faster than humans. AI quickly analyzes real-time safety data (from wearables, IoT devices, computer vision) and loss run reports (three years is a good benchmark) to identify injury frequency and severity. This helps brokers guide clients to focus on common injuries like slips, strains, and sprains that heavily affect their experience modification rate and premiums. These patterns inform a customized prevention strategy that moves the broker-client relationship beyond generic checklists to address specific workplace risks.
  3. Automated claims workflows. The faster claims close, the less they cost. AI significantly reduces the time and cost of workers' compensation claims by automating workflows from First Notice of Loss (FNOL) to closure. By instantly collecting and entering data, AI cuts processing time from weeks to minutes. It integrates daily data, such as adjuster notes, and provides "next best action" guidance, ensuring employers are informed and costs are controlled. This proactive approach allows brokers to deliver personalized, exceptional client service.
  4. Return-to-work. Most employers' return-to-work (RTW) programs are static documents that rarely get used. Brokers can use AI to provide dynamic, tech-enabled RTW playbooks that add real value. AI continuously monitors data (e.g., doctor updates) that previously got lost, leading to unnecessarily prolonged claim payments for workers who could have returned sooner. This efficiency differentiates brokers, allowing them to confidently state that their workers' comp program is superior. AI-guided RTW streamlines the workflow, enabling adjusters to better manage cases and expedite employees' returns to a temporary light-duty role.
  5. Fraud detection. While most workers' comp claims are legitimate, 1-2% involve fraud. Late reporting and manual processes make it easier for dishonest claims to slip through the cracks by allowing injuries to be exaggerated or falsified. Time-sensitive reporting guided by automation helps preserve evidence and ensures accurate witness statements while details are fresh.

The integration of AI is fundamentally transforming workers' compensation claims management. By enhancing everything from underwriting and injury prevention to claims processing, return-to-work programs, and fraud detection, AI provides brokers with a powerful toolkit to reduce client costs, improve operational efficiency, and deliver a truly differentiated, value-driven service experience.

THE HUMAN ELEMENT

Ultimately, while AI offers powerful tools to recognize patterns and automate quantitative tasks in workers' compensation, the most successful brokers will strategically leverage this technology to free up time for vital human interaction. The core of effective claims management remains the human element: the ability to offer empathy, operate with honesty and transparency, and prioritize the client's best interests—intangible skills that technology can support but never replace. The future of workers' comp hinges on a successful partnership between AI efficiency and human consultation.


Adam Price

Profile picture for user AdamPrice

Adam Price

Adam Price is chief executive officer of Kinetic, a tech-first MGA focused on workers’ compensation insurance for safety-critical industries.

Fragmented Systems Plague Insurance CX

The call center isn't a cost center. It's the moment of truth. And, despite investing billions in technology, insurers still fail customers when it matters most.

Concrete Wall with Peeled Off Paper and Paint

A policyholder calls after a flood. She has three feet of water in her kitchen, two kids on the couch, and nowhere to go until she understands what her coverage actually means right now. She has been on hold for 11 minutes. She has already provided her policy number twice. When she finally reaches an agent, she has to start from scratch and do it a third time.

This is the moment the industry exists for. And it's where too many insurers are still failing—it's costing them billions, according to Accenture.

Not because insurers lack technology. Most have more technology than they can connect—voice, messaging, claims systems, and decades of customer data. The problem is that none of the systems know about the rest. Data is fragmented. Context gets lost. And when that happens, the experience feels like nobody cares.

Insurers Solved the Easy Problems. The Hard Ones Are Still There.

There's no shortage of success stories of transformation in this industry. Quotes that once took days now take seconds. Documents arrive instantly. Policies are issued, updated, and managed entirely online. These were hard problems that took real investment to solve.

But they were also easy problems, in one important sense: they could be solved by adding technology. New system, new process, done. What remained unsolved—and what most digital transformation narratives quietly skip—is what happens when a customer actually needs help. When the claim is complex, the situation is urgent, and the stakes are high enough that the experience leaves a mark.

These customer experience (CX) moments don't operate on quiet days. They cluster. A major storm, a regional crisis, a sudden surge in claims, and the entire engagement infrastructure gets tested simultaneously. That's when the gaps between disconnected systems stop being an annoyance and become a liability. KPMG sees fragmentation as one of the biggest challenges to modernization.

The Insurers Moving Fastest on Cloud Aren't Talking About Cost

When insurers talk about cloud migration, the framing is almost always about cost. Total cost of ownership. License consolidation. Infrastructure savings. These are legitimate conversations. They're also the wrong ones to lead with.

On-premise environments were designed for predictability and control. They were never built for real-time, multi-channel engagement at scale, and they can't be retrofitted to handle it. When volumes surge or conditions change, legacy environments don't flex. They fracture.

The insurers making the most meaningful progress aren't asking "can we afford to modernize?" They're asking, "can we afford what happens when we can't scale?" and finding that the math looks very different from that angle.

The insurance industry is spending heavily on AI right now. The ambition is real. So is the disappointment when the demos don't survive contact with actual operations. According to the Boston Consulting Group, only 7% of insurance companies have successfully brought their AI systems to scale.

The reason is almost always the same: AI has been layered on top of fragmented systems and asked to compensate for what those systems lack. When data is inconsistent across platforms, when context doesn't travel with the customer, when the same information lives in four different places. AI doesn't resolve any of that; it amplifies it. The inconsistencies become more visible, not less.

AI performs well in a specific role: removing friction from routine interactions, capturing and routing information early, and surfacing the right context at the right moment so agents can focus on judgment rather than administration. In a connected, well-structured environment, that's genuinely transformative. In a fragmented one, there's more noise on top of existing noise.

How Integrated Communications Changes the Customer Experience

Here's a diagnostic test that reveals a lot about the state of an insurer's communications infrastructure: ask what happens when a customer starts a conversation on the website, moves to chat, and then calls.

In most cases, the answer is: they start over. Three times. No context carries. No continuity exists. Just repetition and the implicit message that the insurer's systems matter more than the customer's time.

When communications infrastructure is genuinely integrated, this changes. Interactions route based on intent rather than just inputs. Context moves with the customer from channel to channel. Conversations pick up where they left off. The difference in resolution speed, first-contact rates, and customer perception is significant, but the more important outcome is harder to quantify: customers feel like the insurer actually knew who they were.

It can also be profitable. McKinsey found that during 2017-2022, insurers with superior CX posted higher total shareholder returns—by between 20 and 65 percentage points.

What It Actually Takes to Modernize Insurance Communications

Modernizing insurance communications is not about adding more technology. Most organizations already have enough. The work is simpler and harder than that: connect what already exists.

When that happens, the contact center stops managing problems and starts anticipating them. Agents stop reacting and start advising. The experience stops being a test of the customer's patience and starts being evidence that the insurer takes seriously the one thing they actually promised: to be there when it matters.

Customers don't remember your technology stack. They remember the call that went well when everything else was going wrong. That's the product.

Telematics and Trust: The UBI Revolution

Adoption of auto telematics has increased 28% a year in the U.S. since 2018. Usage-based insurance is no longer a niche. It is a mainstream strategy. 

Person driving a car with a dark interior

What if your car insurance reflected how you actually drive, not just who you are? That question is no longer hypothetical. In 2024, more than 21 million U.S. policyholders shared telematics data with their insurer, according to IoT Insurance Observatory research. That reflects a 28% compound annual growth rate since 2018. Usage-based insurance (UBI) is no longer a niche; it’s a mainstream strategy reshaping our industry.  

For years, competitive pricing drove adoption. But today, something deeper is at play: Trust and perceived value are fueling the next wave of growth. This isn’t just about saving money; it’s about believing the insurer will use sensitive driving data responsibly and deliver tangible benefits in return. 

Bar chart showing three columns with telematics over time

Source: IoT Insurance Observatory field customer surveys

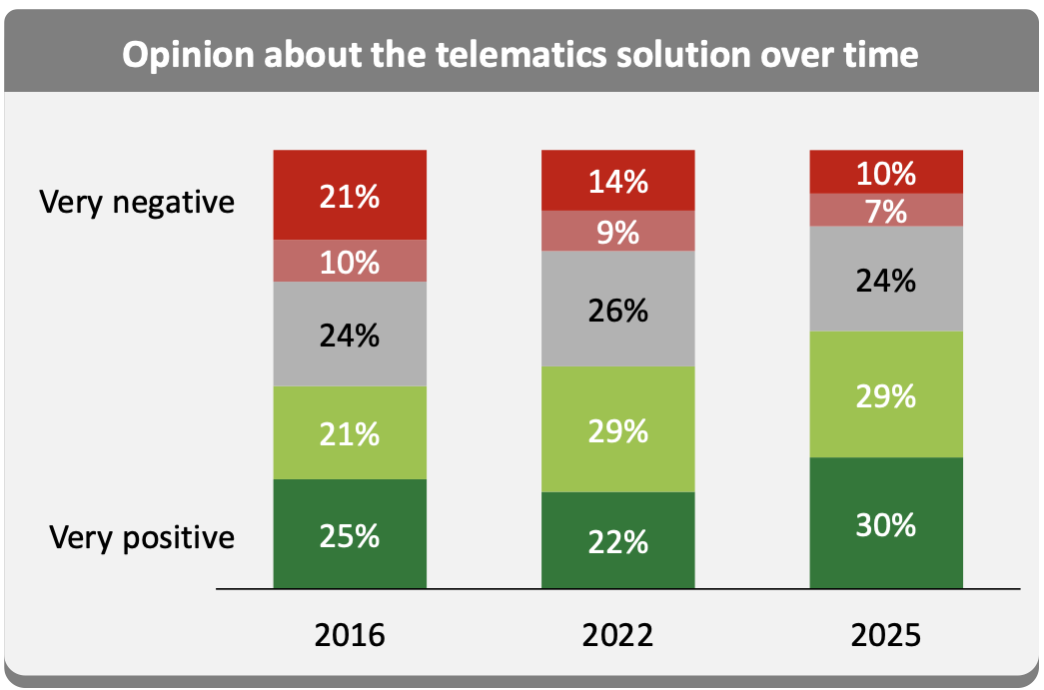
According to a recent consumer survey by Arity and the IoT Insurance Observatory - sampling 2,059 personal auto policyholders representative of the U.S. market - 82% of policyholders would recommend a telematics app that rewards safe driving, offers feedback, provides crash assistance, and delivers other valued services. Among drivers under the age of 53, that number exceeds 90%. Positive sentiment toward telematics has steadily increased over the past decade, as shown in the chart above.

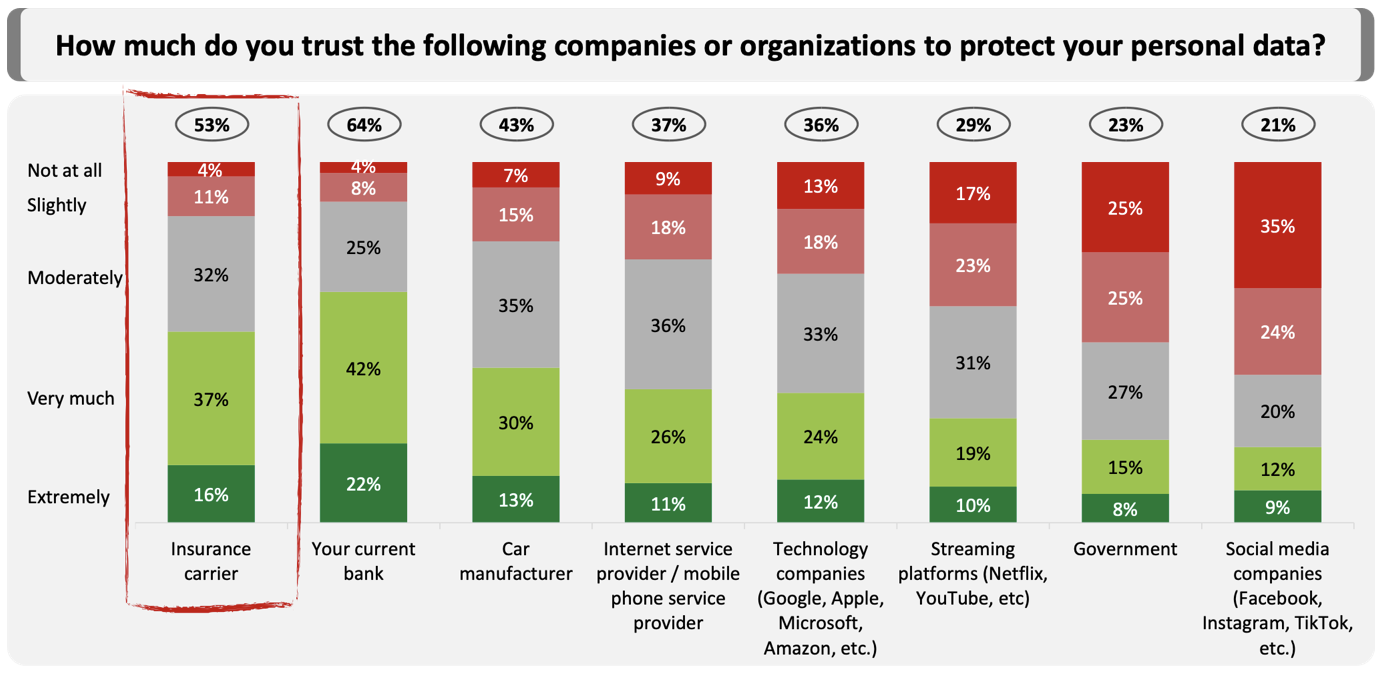
Trust isn’t a buzzword here, it’s the foundation of adoption. Consumers share data only when they believe insurers will protect it and use it to create real value. In fact, 53% of respondents expressed high trust in insurers’ handling of personal data, ranking insurers second only to banks. That trust translates into action: willingness to switch plans, share driving scores, and pay for connected services. 

Bar graphs with eight columns showing company trust

The willingness to adopt UBI is strong: 60% of policyholders are open to switching, rising to 72% among younger drivers. This level is consistent with the evidence from recent TransUnion surveys showing that 60% of people reported being offered telematics opted-in.

When consumers see clear benefits, privacy concerns fade. They want pricing that reflects lifestyle, rewards for safe driving, and features like automatic crash assistance. Three-fourths are open to sharing their driving score for a personalized quote. More than half of those willing to switch prefer pricing models that offer bigger potential savings, even if it means some risk a surcharge. 

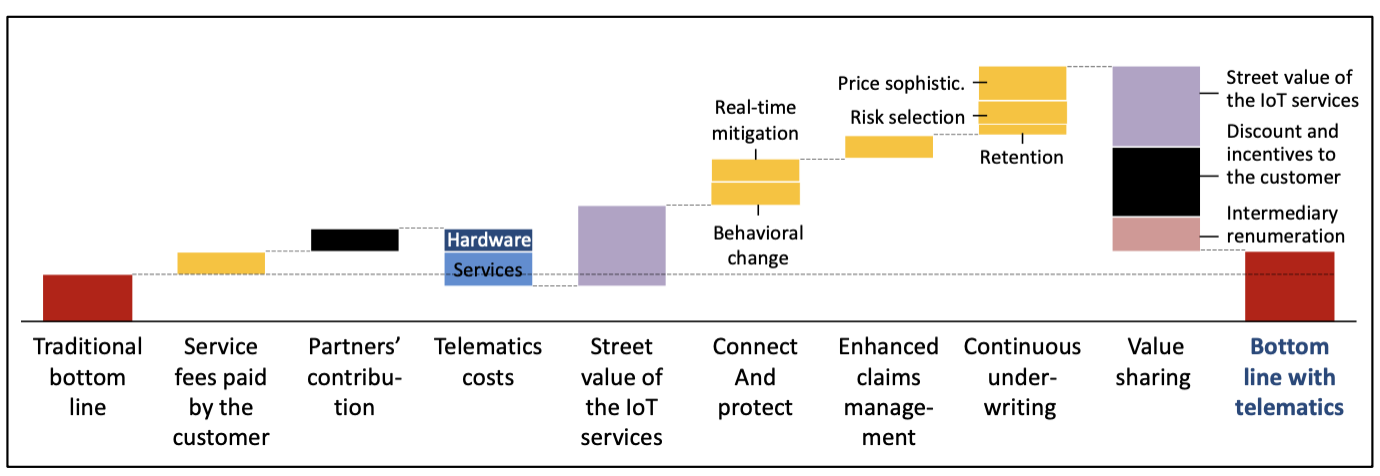
This is where telematics shines. Insurers can deliver compelling offers because telematics unlocks incremental economic value by sensing events, transmitting data in real time, and applying AI-driven analytics to understand, decide, and act. This enables smarter underwriting, faster claims processing, and more proactive risk management. By sharing part of this value with policyholders, insurers create a win-win scenario that makes UBI not just viable - but mainstream.

Bar chart

Source: IoT Insurance Observatory

Over the past decade, insurers have proven the power of telematics data to transform core functions: 

  • Continuous Underwriting: Telematics data enables more accurate risk assessments and selection, allowing insurers to better match rates to actual risks. This leads to more sophisticated pricing, improved retention and effective acquisition of good risks, and reduced premium leakage from riskier drivers. Insurers can also use telematics-based data to make portfolio-level decisions regarding risk appetite and reinsurance.
  • Enhanced Claims Management: Real time crash detection is a game-changer for claims management. Insurers can trigger proactive responses, notify emergency services, and initiate the claims process. Insights about crash events support timely claim handling and help minimize potential fraudulent or inflated requests.
  • Connect and Protect: International telematics-based experiences demonstrate effectiveness in mitigating risks by identifying risky situations in real time and intervening before accidents occur.  Behavioral change programs promote safer driving, leading to fewer accidents and lower loss ratios. 

Policyholders are willing to reconsider their insurer when pricing reflects how they actually drive and live: More than half of policyholders would switch for a product with the premium defined by telematics data. 

Consumers aren’t just looking for lower premiums; they want features that matter. Rewards for safe driving and automatic emergency assistance in severe crashes rank among the top preferences across all generations - from Gen Z to Traditionalists. And the appetite for innovation doesn’t stop there: More than half of policyholders would pay $4.99 per month for a connected dashcam service that offers emergency assistance, video recording for protection against unfair complaints, and real-time safety feedback.

The impact goes beyond individual policies. When the usage of telematics data is holistically adopted across the entire insurance organization, this improves pricing accuracy, reduces losses, and makes insurance more affordable, all while promoting safer roads. Fewer accidents mean fewer injuries and lives saved. That’s why telematics is more than a business strategy, it’s a social good.

The time to invest in telematics mastery is now. Insurers that fully embrace the connected paradigm in all their core processes and responsibly use data with customer consent can unlock greater value—delivering fairer pricing, personalized experiences, and safer roads. This broader usage of data enables higher value creation and sharing, benefiting policyholders and society as a whole.


Henry Kowal

Profile picture for user HenryKowal

Henry Kowal

Henry Kowal is director, outbound product management, insurance solutions, at Arity, an Allstate subsidiary that tackles underwriting uncertainty with data, data and more data about driving behavior gathered via telematics.

AI: Insurance Fraud Wake-Up Call

“Those who seek to commit fraud are often skilled innovators – frequently one step ahead of those tasked with stopping them."

Three people in a row sitting at computers looking concerned

Fraud is hardly a new problem, but it is a serious issue, and recent fundamental changes in societal norms are exacerbating fraudulent conduct and making detection and deterrence less of a priority than warranted. The scope and scale of fraud are truly shocking, especially among government-funded medical and social programs currently under scrutiny, where enormous costs are somehow tolerated.

Fraud not only creates significant economic loss but also undermines confidence in its public and financial institutions, including insurance. Yet preventing and combatting fraud is seemingly episodic and random. 

All of this serves to bring renewed attention to the long-standing concerns about ever-expanding fraud in general – and specifically insurance fraud. Insurers need to heed the wake-up call.

COST OF INSURANCE FRAUD

Quantifying insurance fraud's impact is difficult and spans from premium fraud to claims fraud, whether opportunistic or through deliberate scheme. According to the Coalition Against Insurance Fraud (CAIF), insurance fraud costs American consumers more than $300 billion a year. This amounts to an individual policyholder $900 annual “tax,” as insurer costs are passed on in form of premiums. Claims fraud is said to occur in about 10% of property-casualty insurance losses. Medicare fraud alone is estimated to cost $60 billion every year.

There are also several limitations when it comes to detecting fraud. According to the National Association of Insurance Commissioners (NAIC), there are key differences between “hard” and “soft” types. Soft forms of fraud are widespread and can be a common exaggeration of a legitimate claim. Hard types are described as intentional acts to create or fabricate “damages” and claims. Still, these general headers fall short of telling the whole story. 

Claim fraud can be perpetrated by an individual or involve others including organized crime rings recognizing there are entire ecosystems designed to inflate, embellish and even fake an accident. Billing for unperformed medical procedures pales in comparison to fake “victims” being paid to undergo surgery. A single case in New York uncovered a $31 million scheme between a doctor and lawyer in trip-and-fall “accidents,” paying "victims" to endure surgery, simply to initiate a claim, justify damages or both. So-called runners are paid finder-fees to produce participants.

Further, many frauds go undetected for long periods or are missed altogether because there is much reliance on the “honor system,” whether at point of sale in which premiums are based or when making a claim. Although any healthy system checks and verifies, it is impractical, unnecessary and risky to deeply investigate a large percentages of cases. Insurers balance customer service, state regulatory requirements involving timeliness and potential complaints that can escalate to lawsuits. 

Meanwhile, internal special investigative units (SIUs) likewise have finite resources and bandwidth, only concentrating on the most actionable cases. Law enforcement agencies have similar constraints, and insurance fraud is a lesser priority than other crimes. Altogether, this dilutes the efficacy of combatting fraud, leading to uncaptured and under-reported figures.

Instead, anecdotal case examples tend to do the best job of illustrating the magnitude of fraud. Phony medical clinics, staged auto accidents, even faked deaths demonstrate the amounts at stake and the lengths fraudsters will go. More frustrating is how obvious some of the schemes are, revealed as in the infamous empty day care center stories. 

But what happens when technology pushes the boundaries beyond such traditional fraud methods?

The Yin and Yang of AI and Insurance

The rapid emergence of artificial intelligence has brought greater business risks, and the financial services industries are among the largest victims of related fraud. Ironically, business is quickly learning to harness the power of AI to fight fraud more effectively – but so are the fraudsters. 

The potential of AI in claims fraud detection is among the most powerful applications, and particularly so in life & health and accident, according to a February 2026 report from Gallagher Re and CB insights: "Global InsurTech Report."

AI has many benefits. It can improve efficiency, help make better decisions, and encourage innovation across different industries. But these advantages also come with serious risks – especially the potential for misuse in fraud or deception.

Like any powerful technology, AI can be used for both helpful and harmful purposes. This makes strong and thoughtful governance essential to maximize its benefits and protect against misuse.

Hackers and other criminals can easily commandeer computers operating open-source large language models (LLMs) outside the guardrails and constraints of the major artificial-intelligence platforms, creating security risks and vulnerabilities, researchers said.

Hackers could target the computers running the LLMs and direct them to carry out spam operations, phishing content creation or disinformation campaigns, evading platform security protocols, the researchers said. Roberto Copia, director at IVASS Inspectorate Service, spoke about this issue at the 4th National Congress of the CODICI Association in 2025. He pointed out a growing concern: While AI can improve the efficiency of the insurance industry, it can also give fraudsters more advanced tools to commit fraud.

AI and Insurance: An inseparable alliance

AI is cautiously becoming an indispensable tool in the insurance sector. Its applications range from risk assessment to customer services, claims processing and fraud detection. Predictive algorithms, neural networks, and machine learning models allow the processing of vast datasets, improving underwriting accuracy, accelerating claim settlements and strengthening insurers' anti-fraud capabilities.

But these very tools – powerful, scalable and increasingly accessible – are also being weaponized by fraudsters. “Those who seek to commit fraud are often skilled innovators – frequently one step ahead of those tasked with stopping them,” Copia has said.   

A quantum leap in criminal sophistication

Insurance fraud has always been a structural problem in the sector. Yet today, it’s undergoing a qualitative shift. We’re no longer dealing solely with fraudulent damage to property or fictitious claims. Modern fraud is digital, automated and highly sophisticated. AI has become a powerful enabler for those seeking to manipulate data and images, forge documents or create false digital identities.

A March 2026 report, Verisk State of Insurance Fraud Study, finds, based on surveys of 1,000 U.S. consumers and 300 insurance claims professionals:

  • 55% of Gen Z say they would consider editing a claim photo or document
  • 98% of insurers say AI editing tools are fueling digital fraud
  • Only 32% of insurers feel very confident about detecting deepfakes
  • 69% of consumers believe fraud will raise premiums for all policyholders

A paradigmatic example is the Ghost Broker scam: insurance websites that appear legitimate, often employing advanced social engineering techniques, real logos, and data stolen from unwitting intermediaries. AI allows these fraudulent portals to appear increasingly credible, complete with chatbots simulating customer service, AI-driven profiling of potential victims, and the delivery of highly personalized fake offers. The result is a seemingly flawless customer journey. But the buyer is left uninsured and unknowingly defrauded until subsequent inspection reveals the deception.

Another example involves "synthetic" identity fraud, in which fraudsters create an identity with a mix of fabricated credentials. According to Lexis Nexis, fraudsters may create synthetic identities using potentially valid Social Security Numbers (SSNs), with accompanying false personally identifiable information (PII). This newer challenge raises the bar for insurers to validate identity at point of sale and other policy lifecycle stages.

THE FRAUD FIGHTING IMPERATIVE

We believe that insurers have an obligation to prioritize fraud detection and avoidance in this growing, too-big-to-ignore dynamic. This obligation is moral, economic and legal. An insurer’s duty to its policyholders includes protecting their investment while managing fair and accurate premiums alike.


Alan Demers

Profile picture for user AlanDemers

Alan Demers

Alan Demers is founder of InsurTech Consulting, with 30 years of P&C insurance claims experience, providing consultative services focused on innovating claims.


Stephen Applebaum

Profile picture for user StephenApplebaum

Stephen Applebaum

Stephen Applebaum, managing partner, Insurance Solutions Group, is a subject matter expert and thought leader providing consulting, advisory, research and strategic M&A services to participants across the entire North American property/casualty insurance ecosystem.

GenAI Takes Underwriting Into a New Phase

AI isn't just allowing for efficiencies in underwriting, it's letting carriers make much faster, smarter decisions on how to manage their whole portfolio. 

itl focus interview

Paul Carroll 

With AI transforming underwriting, some say the function is entering a new phase. Do you agree? 

Katie Klutts Wysor 

When you look at what property and casualty carriers are saying and what brokers are starting to say, there’s broad recognition that generative AI could reshape risk assessment and underwriting in meaningful ways. It’s becoming an enabler. It can help underwriters make better decisions and work more effectively. 

Carriers are focusing on underwriting as a function and investing heavily in it. They’re talking about that focus in investor days and earnings calls, and they’re doing significant work internally to organize data and update processes—improving speed, increasing automation, accelerating turnaround times and supporting more informed decisions with better data. 

What’s even more significant than the process improvements is what AI could do more broadly. Think of the underwriter as managing capital and trying to direct it to the ideal place. How can AI help define the parameters around what the carrier wants to write so it can deploy capital where it is targeting stronger returns? From there, you can align appetite and business mix with the underwriting process. 

For example, if I’m a regional workers’ comp player and I want to expand into other lines of business or other states, how can I use AI to support that portfolio management decision and direct capital more effectively? Then, how do I identify the necessary distribution partners to find the business I want? How do I create the proper incentives for distribution partners to bring forward that business, so I have a submission to underwrite? And then, how do I make sure the underwriting process, and decision-making aligns with my appetite? 

I think that’s where a great deal of value could be created from an underwriting perspective, looking at how AI can help inform research on the front end, and how you then use something like a GenAI-enabled underwriting platform to begin systematically embedding strategic capital decisions into appetite, process and guidelines at scale, so underwriters evaluating risks are working from more relevant information. 

Then you can use AI to respond to new business decisions more quickly, respond to renewal decisions more effectively, and potentially take certain actions during a policy’s term to support risk mitigation conversations. 

If you can start mastering that link—how you’re deploying capital and setting appetite, all the way down to those micro process decisions—that represents a new level of maturity. 

Paul Carroll 

Speed has become a significant competitive factor in insurance underwriting. If you’re slow to quote, even with a slightly better price, you may lose the business. What’s happening in terms of speed in the underwriting process, and how do processes need to change—not just the technology—to take advantage of the speed AI can offer? 

Katie Klutts Wysor 

Speed to quote and bind means something very different across varying lines of business. In auto insurance, you need to be able to deliver a quote in seconds. So, you see many personal lines players focusing on quote simplification. In auto, it is close to a mature problem, and many carriers are following established market patterns to stay competitive. 

But the speed question gets harder as you move into more specialized or complex lines in personal insurance and small commercial, middle market and large commercial. 

What we’re seeing there is impressive. Capabilities are now emerging to triage submission intake. From a technology perspective, carriers increasingly can take a submission no matter how it comes in—via email, a platform or another channel—and combine it with what they already know about that risk, along with relevant third-party data. 

At that point, it becomes an execution challenge. How can you more systematically get to a quick yes, no, or maybe on appetite, and then move effectively  toward a quote? 

How fast that can happen depends on the line of business. But that point is right: Carriers should move as quickly as their competitors. If you’re slow, distribution may not be willing to wait. 

And the benchmark will continue to move. 

Paul Carroll 

How far along is the insurance industry in using technology to allocate capital more intelligently, and what needs to happen to reach the next level? 

Katie Klutts Wysor 

It’s less a technology challenge and more a business decision-making challenge. Some players in the market are especially strong at this, and you can see that by looking at underwriting returns over time. Those companies have consistently used technology and data to manage their portfolios and allocate capital with greater precision, and they will likely continue to adopt new approaches as the tech capability improves. The timeline for broader adoption of newer technology, including generative AI, is harder to predict because it comes back to how quickly "the pack" of carriers can  evolve how they manage the profit and loss across the portfolios. 

Paul Carroll 

What is an example of how insurers can improve their capital allocation? 

Katie Klutts Wysor 

The fundamental approach is to look at your underwriting returns against the capital you’re deploying to the business, map that out, compare outcomes, and decide where you want to grow and where you may need to pull back. Improvements in technology may allow carriers to do that analysis more frequently. Instead of doing it once a year as part of strategic planning, you could be looking at a refreshed view every month using more current data. 

Many carriers may be able to move from annual reviews toward monthly or weekly review cycles, depending on how they make decisions. They may also be able to do the analysis in a more automated way and make decisions more intentionally on micro-segments of the business (by geography, class, line, etc.) that would have been too time-consuming to identify and react to previously. 

Maybe a competitor enters the restaurant space aggressively and undercuts on price. You may decide not to follow them down that path because you believe the pricing is unattractive, so you slow growth in restaurants. 

Or take the opposite scenario: A trend affects restaurants and causes the market to become more cautious. You may conclude that the market reaction has gone too far and decide if this is the right time to pursue restaurant business. 

Today's leadership reviews may only look at class code-level data monthly or quarterly, and at frequency and severity trends in a backward-looking way. But if you can automate how, you assess that information at a portfolio level, then you can decide whether to lean in or lean out of a class like restaurants more quickly.  

Paul Carroll 

What about the execution side of this—how do insurers actually act on these faster insights once they’ve identified an opportunity? 

Katie Klutts Wysor 

The second half of the equation is exactly that. Say you’ve been able to automate and generate more timely underwriting data, so you can make portfolio decisions weekly or monthly instead of quarterly or annually. That’s a meaningful shift. The next step is execution. 

Say you decided to lean into restaurants. You want the market to know. You want your agents and distribution partners to know you’re interested in that business, particularly if another carrier has started to pull back or take rates. That’s the business you want to enter the pipeline. 

Then you want to set up your underwriting process so you can pivot quickly. Maybe you were not prioritizing that business to get it to an underwriter’s desk and streamline escalation paths to support faster turnaround. 

Of course, once submissions are flowing in, and the process is in place to evaluate and price the business you want competitively, you also need the proper governance and controls, so you don’t end up writing risks that fall outside appetite. 

The big difference this year versus a year ago is the ability to put agentic AI workflows in place and that support faster transaction-level decisions. Humans are still in the loop, but they are not necessarily slowing down the process in the same way they did when carriers relied more heavily on manual referral and escalation processes to respond to market changes. The next frontier I expect to see in the coming year is using agentic AI workflows to help improve portfolio-level decisions.

Paul Carroll 

Would you talk a bit about some of the process efficiencies from generative AI as underwriters make their decisions? While those efficiencies aren’t as strategic as the portfolio-level decisions you’ve described, they still seem substantial.  

Katie Klutts Wysor 

Underwriters face a series of yes, no, and maybe decisions, and much of the friction sits in the maybes. You can automate obvious yes-or-no decisions. The maybes are the gray area where you bring in a person. 

Over time, we may be able to bring in a person less often because of agentic AI and other decision-support tools, while maintaining appropriate human oversight. 

Some maybes exist simply because a piece of information is missing. A file gets routed to an underwriter to obtain one additional data point. Once that data point is available, a rule can be applied, and the case can become a yes or a no. In many cases, that is increasingly solvable today.  

You should identify those cases in your portfolio, then use AI to obtain the data point and apply the rule. 

There are also maybes that are more judgment-based, where you’ve created a manual review because you want someone to look at it who has seen this kind of case many times before. Maybe they’ve seen a six-figure loss in a similar situation, so you ask, “Would you write this again knowing what you know now?” 

Agentic AI workflows can help by bringing more context to the situation and supporting more informed underwriting judgment.  

Paul Carroll 

Based on what you’re seeing, how much are underwriters working with brokers and clients to provide guidance on risk reduction—essentially telling them, “you’re getting dinged for this, why don’t you fix it to reduce your risk?” 

Katie Klutts Wysor 

Right now, it’s predominantly brokers and distribution partners that are providing that first line of risk management advice. But there’s also a meaningful role for underwriters and carriers. 

The concept is there, the question is how consistently it can be translated into actionable guidance. 

Paul Carroll 

What final advice would you offer to readers? 

Katie Klutts Wysor 

What my clients care about is taking some of the bigger ideas and translating them into what to do right now and how to respond in practical terms. So, what I’d leave readers with is this: Keep thinking about the art of the possible but also focus on what you can implement now to strengthen performance this year, and start bringing those two together. 

Understand what technology, data, and AI capabilities are available to you. But more importantly, identify which ones you can deploy quickly while you continue building toward the more complex architecture and data challenges you should address over time. 

Paul Carroll 

So you can create a cycle: make targeted investments that create near-term efficiencies, then use those gains to support the next wave of investment. 

Katie Klutts Wysor 

Exactly. Don’t spend three years trying to build the perfect solution. There’s a lot you can do right now. Deploy something practical that can create value, then use those gains to support larger investments over time. 

Paul Carroll 

Thanks, Katie. 


About Katie Klutts Wysor

headshotKatie Klutts Wysor is a Principal with PwC who advises insurance leaders on strategy, growth, and transformation. She focuses on analyzing evolving market dynamics to shape perspectives on the future of insurance and translating those insights into practical, outcome-driven growth strategies and transformation programs for carriers and brokers/distributors.

Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.