Download

Insurtech Drives Policyholders' Expectations

Insurtech innovations are driving policyholder demands for digital convenience, personalized coverage and faster claims processing across the industry.

Insurtech

The insurance industry has traditionally been known for lengthy paperwork, slow claims processing, and limited customer interaction. However, the rapid rise of insurtech is fundamentally changing how customers engage with insurance providers. Today's policyholders expect faster services, digital convenience, personalized coverage, and seamless experiences similar to those offered by banking, e-commerce, and technology companies.

Insurtech—a combination of insurance and technology—is reshaping customer expectations by introducing digital platforms, AI-driven services, automation, mobile-first experiences, and real-time engagement. Whether purchasing policies online, receiving instant claims updates, or accessing personalized recommendations, customers now expect insurance experiences to be faster, smarter, and more transparent.

As digital transformation accelerates, insurers that fail to meet these evolving expectations risk losing customers to more agile and technology-driven competitors.

1. The Shift Toward Digital-First Insurance Experiences

Modern consumers increasingly expect convenience and instant access across all industries, and insurance is no exception. Traditional insurance models that rely heavily on in-person interactions, paperwork, and delayed approvals are gradually being replaced by digital-first experiences.

Insurtech companies and digitally mature insurers are introducing self-service platforms that allow customers to:

  • Purchase policies online
  • Compare insurance plans instantly
  • Update policy information digitally
  • File and track claims through mobile apps
  • Access policy documents anytime

This shift has significantly altered customer expectations. Today's policyholders want insurance to be simple, accessible, and available whenever they need it.

For younger generations, particularly Millennials and Gen Z, digital convenience is often a deciding factor when selecting an insurance provider. A slow or outdated customer experience can quickly result in dissatisfaction and churn.

As a result, insurers are increasingly investing in mobile applications, customer portals, and seamless omnichannel experiences to remain competitive.

2. Personalization Is Becoming a Customer Expectation

One of the biggest ways insurtech is transforming insurance is through personalization.

Traditional insurance products often relied on broad customer segmentation and standardized pricing models. However, modern customers now expect tailored coverage options that align with their unique needs and lifestyles.

Insurtech innovations such as artificial intelligence (AI), predictive analytics, telematics, and IoT are helping insurers provide more personalized experiences.

Examples include:

Usage-Based Insurance

Auto insurers can offer customized premiums based on driving behavior rather than generic demographic assumptions.

Personalized Risk Assessments

Home insurance providers can use smart home technology and location-based risk data to adjust pricing more accurately.

Customized Policy Recommendations

AI-powered systems can analyze customer profiles and recommend coverage based on life stage, risk preferences, and historical patterns.

Customers increasingly value personalized policies because they perceive them as fairer, more relevant, and cost-effective.

In today's insurance landscape, personalization is no longer viewed as a premium feature—it is becoming an expectation.

3. Faster Claims Processing Is Redefining Customer Satisfaction

Claims handling has always been one of the most critical moments in the insurance customer journey. Historically, claims processing could take days or even weeks, often leading to frustration and dissatisfaction.

Insurtech is dramatically improving this experience through automation, AI, and digital claims systems.

Modern claims capabilities include:

AI-Powered Claims Assessment

Insurers can use image recognition and machine learning to assess vehicle or property damage quickly.

Digital Claims Submission

Customers can submit claims through mobile apps, upload photos, and track claim status in real time.

Automated Claims Updates

Chatbots and automated notifications keep customers informed throughout the claims journey.

Fraud Detection Technologies

AI helps insurers identify suspicious activities while minimizing delays for genuine claims.

Customers now expect fast, transparent, and hassle-free claims experiences. Delays, lack of communication, or complex processes can negatively affect customer trust and brand loyalty.

For insurers, improving claims efficiency has become essential to maintaining customer satisfaction and retention.

4. Transparency and Instant Communication Matter More Than Ever

In the digital age, customers expect transparency and immediate access to information.

Traditional insurance communication often involved waiting for agent callbacks, email exchanges, or physical documentation. Insurtech is changing this dynamic by enabling real-time engagement and proactive communication.

Modern insurance customers expect:

  • Instant premium quotes
  • Real-time policy information
  • Transparent pricing structures
  • Immediate claims updates
  • 24/7 customer support

AI-powered chatbots and virtual assistants are helping insurers respond faster to customer inquiries, improving responsiveness and convenience.

Transparency has also become a major expectation. Customers want clear explanations of policy terms, exclusions, claim decisions, and premium calculations.

Insurers that communicate clearly and consistently are more likely to build long-term trust and stronger customer relationships.

5. The Future of Customer Expectations in Insurance

Customer expectations in insurance will continue evolving as technology advances.

Several trends are expected to shape the future of insurance experiences:

Hyper-Personalization

AI and behavioral analytics will allow insurers to create highly customized insurance products.

Embedded Insurance Experiences

Customers may increasingly purchase insurance seamlessly during transactions such as booking travel, buying vehicles, or purchasing electronics.

Predictive and Preventive Services

Rather than only paying claims after losses occur, insurers may proactively help customers reduce risks through smart devices and predictive alerts.

Fully Digital Insurance Journeys

From policy purchase to claims settlement, customers will increasingly expect frictionless digital experiences without manual intervention.

Human + Digital Hybrid Support

While automation will grow, customers may still expect human guidance for complex claims or policy decisions.

Insurance companies that embrace innovation while maintaining trust and customer-centricity will be best positioned for long-term success.

Conclusion

Insurtech is transforming customer expectations across the insurance industry by making experiences faster, smarter, more personalized, and more transparent. Today's policyholders expect digital-first services, instant communication, personalized coverage, and seamless claims experiences.

As customer demands continue evolving, insurers can no longer rely solely on traditional operating models. Success in the modern insurance landscape will depend on an insurer's ability to combine technology, convenience, trust, and personalization.

The future of insurance is increasingly customer-driven, and organizations that adapt to changing expectations will be better equipped to build loyalty, improve retention, and stay competitive in an increasingly digital marketplace.
Embedded Insurance Is the Next Big Opportunity

Embedded insurance integrates P&C coverage directly into purchase journeys, creating seamless customer experiences and unlocking new distribution channels for insurers.

Embedded Insurance

The property and casualty (P&C) insurance industry is rapidly evolving as customer expectations shift toward seamless digital experiences. Today's consumers expect convenience, speed, and personalization in every interaction—including insurance. This changing landscape has fueled the rise of embedded insurance, a fast-growing model that integrates insurance products directly into customer purchase journeys.

Instead of buying insurance separately through traditional agents or standalone channels, customers can now purchase protection at the exact moment they buy a product or service. Whether adding auto coverage while purchasing a vehicle, travel insurance during flight booking, or device protection at checkout, embedded insurance simplifies the customer experience while opening new growth opportunities for insurers.

As digital ecosystems continue expanding, embedded insurance is emerging as one of the most promising growth drivers in P&C insurance. But why is it gaining so much momentum, and what should insurers know about its future potential?

1. What is Embedded Insurance in P&C?

Embedded insurance refers to the integration of insurance coverage directly into the purchase process of products or services. Instead of customers searching separately for policies, insurance becomes a built-in or optional part of a transaction.

In P&C insurance, embedded insurance can appear in several ways:

Auto Insurance

Customers purchasing vehicles through dealerships or online automotive platforms can receive insurance offers instantly during checkout.

Travel Insurance

Travel booking websites often provide trip cancellation, baggage protection, or accident coverage at the time of booking.

Home and Renters Insurance

Mortgage lenders, real estate platforms, and rental marketplaces can integrate insurance recommendations into their customer journey.

Consumer Electronics Protection

Retailers can offer device protection plans when customers buy smartphones, laptops, or appliances.

The goal is to make insurance more convenient, contextual, and frictionless by offering relevant coverage at the exact point of need.

For customers, this reduces complexity. For insurers, it creates access to entirely new distribution channels.

2. Why Embedded Insurance Is Becoming a Major Opportunity

Embedded insurance is growing rapidly because it aligns perfectly with changing customer behavior and digital purchasing habits.

Customers Want Convenience

Modern consumers increasingly prefer integrated experiences over fragmented purchasing journeys. Rather than shopping separately for insurance, customers value instant coverage options during existing transactions.

This convenience improves customer engagement and increases policy adoption rates.

Access to New Customer Segments

Embedded insurance allows insurers to reach customers who may not actively seek traditional policies.

For example, younger digital-first consumers may purchase travel or rental insurance when offered contextually, even if they would not independently research insurance products.

Increased Revenue Opportunities

Embedded insurance opens new premium generation channels by integrating insurance into high-volume digital transactions.

Instead of relying solely on brokers, agents, or direct sales, insurers can partner with:

  • E-commerce platforms
  • Automotive marketplaces
  • Travel companies
  • Fintech providers
  • Property technology platforms
  • Mobility service providers

These partnerships can significantly expand market reach.

Better Customer Retention

Offering insurance at the right moment creates stronger customer relationships and improves long-term engagement opportunities.

Embedded experiences also reduce friction, which may increase customer satisfaction and loyalty.

For insurers seeking scalable growth, embedded insurance represents a major opportunity to diversify distribution models.

3. How Technology Is Driving Embedded Insurance in P&C

The growth of embedded insurance would not be possible without advances in insurtech and digital infrastructure.

Several technologies are enabling insurers to scale embedded models more efficiently.

API-Driven Insurance Platforms

Application Programming Interfaces (APIs) allow insurers to connect seamlessly with external platforms.

This enables businesses to integrate insurance offers directly into checkout flows without disrupting the customer experience.

Artificial Intelligence (AI)

AI helps insurers personalize embedded insurance recommendations based on customer behavior, purchase history, and risk profiles.

For example, AI can recommend suitable protection plans depending on product type or customer location.

Real-Time Underwriting

Traditional underwriting processes often involve delays. Embedded insurance requires instant decision-making.

Advanced underwriting technologies now enable insurers to assess risks and issue policies within seconds.

Data Analytics

Embedded insurance ecosystems rely heavily on customer and transaction data to optimize pricing, predict risks, and improve targeting.

These technologies are making embedded insurance more scalable, intelligent, and customer-centric than traditional insurance distribution models.

4. Challenges Insurers Must Overcome

Despite its growth potential, embedded insurance comes with several operational and regulatory challenges.

Regulatory Compliance

Insurance regulations vary by geography and product type. Insurers must ensure compliance while integrating coverage into third-party ecosystems.

Customer Awareness and Transparency

Some customers may not fully understand embedded insurance products.

Insurers must clearly communicate policy terms, exclusions, and coverage details to avoid trust issues.

Integration Complexity

Successfully embedding insurance requires seamless integration between insurers and partner platforms.

Technical challenges around APIs, data exchange, and system interoperability can slow adoption.

Pricing and Profitability

Embedded insurance often relies on smaller premium sizes and high transaction volumes.

Insurers must balance competitive pricing with profitability and risk management.

Data Privacy Concerns

As embedded insurance relies on customer data, insurers must maintain strong cybersecurity and privacy protections.

Addressing these challenges will be critical to scaling embedded insurance successfully.

5. The Future of Embedded Insurance in P&C

The future of embedded insurance in P&C insurance looks highly promising.

As digital ecosystems mature, insurance will increasingly become an invisible yet essential part of everyday purchases.

Emerging trends expected to shape embedded insurance include:

Hyper-Personalized Coverage

AI and predictive analytics will enable insurers to offer highly tailored policies based on customer context and behavior.

Expansion Beyond Traditional Channels

Embedded insurance opportunities will continue growing across industries such as mobility, smart homes, logistics, e-commerce, and subscription services.

Real-Time Risk Prevention

Connected devices and IoT systems may help insurers proactively reduce risks rather than simply covering losses.

Seamless Digital Claims Experiences

Claims processing for embedded products is expected to become faster and more automated.

Ecosystem Partnerships

Insurers will increasingly collaborate with digital platforms, retailers, and technology providers to create integrated customer experiences.

Organizations that embrace embedded insurance early may gain a significant competitive advantage as customer purchasing behavior continues shifting toward digital-first experiences.

Conclusion

Embedded insurance is quickly emerging as one of the biggest growth opportunities in P&C insurance. By integrating protection directly into customer purchase journeys, insurers can deliver seamless experiences, improve accessibility, and unlock entirely new distribution channels.

As customer expectations evolve, convenience and personalization are becoming essential drivers of insurance adoption. However, success in embedded insurance will depend on technology readiness, strategic partnerships, regulatory compliance, and customer trust.

For P&C insurers willing to innovate, embedded insurance offers a powerful opportunity to drive growth, expand market reach, and redefine how insurance is purchased in an increasingly connected world.

How MGAs Can Scale Faster

MGAs are leveraging AI, automation, and cloud platforms to overcome manual bottlenecks and scale operations more efficiently.

MGA

Managing general agents (MGAs) play an increasingly important role in the property and casualty (P&C) insurance ecosystem by offering specialized expertise, niche underwriting capabilities, and faster market responsiveness. However, as competition intensifies and customer expectations evolve, MGAs face growing pressure to scale operations efficiently while maintaining underwriting accuracy, compliance, and profitability.

Traditional growth strategies that rely heavily on manual workflows, fragmented systems, and operational overhead are no longer sustainable in today's digital-first insurance environment. This is where insurtech and digital transformation are creating opportunities for MGAs to scale faster, improve efficiency, and strengthen customer experiences.

By leveraging technologies such as artificial intelligence (AI), automation, cloud platforms, data analytics, and digital ecosystems, MGAs can modernize operations, accelerate underwriting, optimize claims management, and expand distribution channels. But what does successful digital transformation look like for MGAs, and how can they scale sustainably?

1. Why Traditional Growth Models Are Challenging for MGAs

Historically, many MGAs have relied on manual processes, spreadsheets, legacy systems, and human-intensive operations to manage underwriting, policy administration, and claims.

While this approach may work at smaller scales, growth often introduces several operational challenges:

Manual Underwriting Bottlenecks

As policy volumes increase, underwriting teams may struggle to process submissions quickly, leading to delays and missed opportunities.

Limited Operational Scalability

Traditional systems often require additional staffing to support growth, increasing operational costs.

Fragmented Technology Ecosystems

Disconnected systems can create inefficiencies in policy administration, claims handling, compliance, and reporting.

Customer Experience Gaps

Today's policyholders expect digital-first experiences, self-service capabilities, and faster communication—something many traditional MGA models struggle to deliver.

Without modernization, rapid growth can sometimes create operational strain instead of long-term success.

This is why many MGAs are turning toward digital transformation to scale more efficiently.

2. How Insurtech Is Helping MGAs Scale Faster

Insurtech solutions are enabling MGAs to improve operational efficiency, accelerate decision-making, and reduce manual workloads.

AI-Powered Underwriting

Artificial intelligence can analyze risk data faster than traditional underwriting methods, helping MGAs make quicker and more accurate decisions.

AI-driven underwriting can support:

  • Faster submission reviews
  • Smarter risk scoring
  • Improved pricing accuracy
  • Fraud prevention

This allows underwriters to focus on complex or high-value risks while automation handles routine assessments.

Workflow Automation

Automation tools help MGAs streamline repetitive administrative tasks such as:

  • Policy issuance
  • Renewals processing
  • Claims documentation
  • Regulatory reporting
  • Customer communication

Reducing manual intervention improves speed and operational efficiency.

Digital Claims Management

Claims handling is often one of the most resource-intensive areas for MGAs.

Digital claims platforms help improve:

  • Claims submission speed
  • Customer communication
  • Fraud detection
  • Settlement turnaround times

Faster claims experiences can significantly improve customer retention and satisfaction.

Data-Driven Decision Making

Advanced analytics provide MGAs with deeper insights into risk trends, profitability, customer behavior, and market opportunities.

This enables more informed strategic decisions and better portfolio management.

Insurtech is helping MGAs transition from reactive operations to predictive and scalable business models.

3. The Role of Digital Transformation in MGA Growth

Digital transformation goes beyond adopting individual technologies—it involves rethinking how MGAs operate across the entire insurance lifecycle.

Cloud-Based Insurance Platforms

Cloud technology helps MGAs improve scalability, flexibility, and system accessibility.

Benefits include:

  • Faster product launches
  • Reduced infrastructure costs
  • Improved system performance
  • Better remote collaboration

Cloud-native platforms also enable easier integrations with carriers and third-party partners.

API-Driven Ecosystems

APIs allow MGAs to connect with brokers, insurers, claims vendors, and digital marketplaces seamlessly.

This supports faster data sharing and more efficient operations.

Customer Self-Service Portals

Modern customers increasingly prefer self-service capabilities.

Digital portals allow customers to:

  • Access policy information
  • Submit claims
  • Upload documents
  • Track claim progress
  • Receive instant support

Improved digital experiences can become a key competitive advantage for MGAs.

Embedded Insurance Opportunities

Some MGAs are expanding through embedded insurance partnerships, integrating coverage directly into digital transactions across industries.

This creates new revenue streams and customer acquisition channels.

Digital transformation enables MGAs to grow without proportionally increasing operational complexity.

4. Common Challenges MGAs Face During Digital Transformation

Although digital transformation offers significant opportunities, many MGAs face implementation challenges.

Legacy System Limitations

Older policy administration systems may not support modern digital capabilities or integrations.

Data Silos

Disconnected systems can make it difficult to create a unified customer and risk view.

Regulatory Compliance

Insurance compliance remains complex, especially when introducing AI-driven workflows and automation.

Change Management

Employees may require training to adapt to new technologies and workflows.

Cybersecurity Risks

As MGAs digitize operations, protecting customer and policyholder data becomes increasingly important.

Successful transformation requires strategic planning, technology alignment, and operational readiness.

MGAs that approach transformation incrementally often experience stronger long-term outcomes than organizations attempting large-scale disruption too quickly.

5. Future Trends: What's Next for Digitally Enabled MGAs?

The future of MGAs will likely be increasingly technology-driven.

Several emerging trends are expected to shape MGA growth over the next few years:

AI-Augmented Underwriting

AI will continue supporting underwriters with predictive insights and automated recommendations.

Hyper-Specialization

Technology will help MGAs build highly specialized niche products with faster go-to-market capabilities.

Embedded Distribution Models

More MGAs may partner with digital ecosystems to distribute insurance seamlessly.

Predictive Risk Management

Analytics and IoT data may help MGAs proactively identify risks before claims occur.

Digital-First Customer Experiences

Customers will increasingly expect instant quotes, seamless onboarding, and faster claims support.

MGAs that embrace technology strategically will likely gain a competitive advantage in speed, efficiency, and customer engagement.

Organizations modernizing insurance operations through advanced technology, streamlined workflows, cloud platforms, and strong quality assurance frameworks will be better positioned to scale sustainably in an increasingly competitive insurance market.

Conclusion

Insurtech and digital transformation are creating unprecedented growth opportunities for MGAs in the P&C insurance industry. By leveraging AI, automation, cloud platforms, advanced analytics, and digital customer experiences, MGAs can scale operations faster while improving underwriting efficiency, claims management, and profitability.

However, successful scaling requires more than simply adopting new technology. MGAs must align digital initiatives with business goals, customer expectations, compliance requirements, and operational readiness.

The future of MGA growth is increasingly digital, and organizations that invest in transformation today will be better prepared to compete, innovate, and thrive in tomorrow's evolving insurance ecosystem.

Why End-to-End QA Testing Is Essential

As P&C insurers adopt complex digital platforms, comprehensive QA testing prevents costly failures and ensures seamless customer experiences.

Testing

In the highly regulated and customer-driven property and casualty (P&C) insurance industry, system reliability, performance, and accuracy are critical for operational success. From policy administration and underwriting to claims processing and billing, insurers rely heavily on digital platforms to manage core business operations. Even a minor system failure, inaccurate calculation, or integration issue can lead to compliance risks, financial losses, poor customer experiences, and reputational damage.

This is why end-to-end quality assurance (QA) testing has become essential for modern P&C insurers. As insurance companies increasingly adopt digital platforms, cloud technologies, and core systems such as Guidewire, comprehensive QA testing helps ensure business continuity, seamless customer experiences, and operational excellence.

Rather than testing isolated functions, end-to-end QA validates the entire insurance lifecycle—from policy issuance to claims settlement—helping insurers identify defects before they affect customers and business operations.

1. What is End-to-End QA Testing in P&C Insurance?

End-to-end QA testing refers to the process of validating the complete functionality, performance, integrations, and workflows of insurance systems across the entire business ecosystem.

Unlike basic functional testing, end-to-end testing ensures that every system component works together as intended.

For P&C insurers, this often includes testing:

Policy Administration Systems

Ensuring accurate policy creation, endorsements, renewals, cancellations, and premium calculations.

Claims Management Systems

Testing claims registration, approvals, fraud detection workflows, and settlement processing.

Billing and Payment Systems

Verifying invoicing, payment processing, refunds, and reconciliation accuracy.

Third-Party Integrations

Testing integrations with vendors, payment gateways, regulatory systems, CRMs, and external APIs.

Customer Experience Channels

Validating web portals, mobile apps, self-service systems, and customer communication flows.

In complex insurance ecosystems, a defect in one area can affect multiple downstream processes. End-to-end testing helps prevent such failures before production deployment.

2. Why QA Testing is Critical for P&C Insurance Success

Insurance systems handle large volumes of sensitive customer data and business-critical operations. A single defect can disrupt claims payments, affect policyholder trust, or lead to compliance violations.

Preventing Costly System Failures

Errors in underwriting, policy administration, or claims systems can result in incorrect pricing, delayed settlements, or claim disputes.

Comprehensive QA testing helps insurers detect defects early and reduce expensive post-production fixes.

Improving Customer Experience

Today's customers expect seamless digital experiences and faster claims resolutions.

Poor-performing systems, broken portals, or inaccurate policy information can quickly damage customer trust.

QA testing helps ensure:

  • Smooth digital interactions
  • Faster processing times
  • Accurate policy information
  • Reliable claims experiences

Supporting Regulatory Compliance

P&C insurance operates in highly regulated environments where system errors may create compliance risks.

End-to-end testing helps insurers validate regulatory workflows, reporting accuracy, and policy calculations to reduce audit concerns.

Ensuring Business Continuity

Insurance operations cannot afford system downtime.

Performance and reliability testing help ensure systems remain stable during peak claims seasons, catastrophic events, or high-volume transactions.

For insurers, QA is no longer just a technical requirement—it is a business necessity.

3. The Growing Complexity of Insurance Technology

The insurance technology landscape has become increasingly complex.

Many P&C insurers now operate with:

  • Core insurance platforms
  • Cloud-based systems
  • Third-party integrations
  • APIs and digital ecosystems
  • Customer portals and mobile applications
  • AI-driven automation tools

This complexity increases the risk of defects and integration failures.

For example, a change in underwriting rules could unintentionally affect claims workflows or premium calculations if systems are not tested properly.

Similarly, digital transformation projects and cloud migrations often introduce hidden risks if testing is insufficient.

This is especially relevant for insurers implementing or upgrading Guidewire platforms. Specialized testing approaches such as automated regression testing, integration testing, performance validation, and user acceptance testing become critical during implementation or migration initiatives.

Many insurers increasingly invest in specialized Guidewire testing services to ensure seamless system performance, reduce implementation risks, and improve software quality during insurance platform modernization.

4. Key Types of QA Testing Every P&C Insurer Needs

To ensure reliable insurance operations, insurers should adopt a comprehensive QA strategy covering multiple testing approaches.

Functional Testing

Validates whether insurance workflows function correctly, including policy issuance, endorsements, claims processing, and billing.

Integration Testing

Ensures seamless communication between insurance systems, external vendors, APIs, and third-party services.

Regression Testing

Helps insurers verify that new system updates do not break existing functionalities.

Performance Testing

Tests system speed, scalability, and stability under high transaction volumes.

This becomes especially important during catastrophic claim events when system demand spikes.

Security Testing

Insurance systems manage sensitive personal and financial information.

Security testing helps identify vulnerabilities and strengthen data protection.

A strong QA framework reduces operational risks while improving platform reliability and customer confidence.

5. The Future of QA Testing in P&C Insurance

As digital transformation accelerates, QA testing in insurance is evolving rapidly.

Several emerging trends are shaping the future:

AI-Powered Test Automation

Artificial intelligence is helping insurers automate repetitive testing tasks and identify defects faster.

Continuous Testing in DevOps

Insurers adopting agile delivery models increasingly rely on continuous testing to speed up releases without sacrificing quality.

Cloud Testing

As insurers migrate systems to cloud environments, testing strategies are evolving to validate cloud performance, security, and scalability.

Predictive Quality Analytics

Advanced analytics may soon help insurers predict potential failures before they occur.

Customer Experience Testing

Insurers are placing greater emphasis on testing digital experiences across websites, mobile apps, and customer portals.

The future of QA in P&C insurance will be increasingly proactive, automated, and business-focused.

Conclusion

End-to-end QA testing has become a critical success factor for P&C insurers navigating digital transformation, system modernization, and growing customer expectations.

By validating complete insurance workflows, reducing operational risks, ensuring compliance, and improving customer experiences, QA testing helps insurers build reliable and resilient technology ecosystems.

As insurance platforms become more connected and complex, insurers can no longer rely on fragmented or limited testing approaches. A comprehensive end-to-end QA strategy is essential to maintaining system stability, operational efficiency, and long-term business success in an increasingly digital insurance landscape.

AI Won’t Fix the Agency. Re-architecting It Will

The insurance agencies capturing disproportionate value from using AI are restructuring their workflows. Here are some ways that leading agencies operate differently by leveraging AI.

AI for Agencies Graphic

For years, insurance agents and brokerages have pursued growth using a familiar model: Add producers, expand carrier relationships, and absorb the operational load through incremental hiring or outsourced support. When pressure builds, they introduce technology to accelerate individual tasks.

That model is now breaking under the burden of the way agencies actually operate.

Across the industry, agencies are losing significant capacity to operational drag. Anywhere from 30%-40% of their time per week is lost to manual, repetitive work such as rekeying data or manually executing analyses – time that should be allocated to revenue-generating activity.

At the same time, such core processes as policy checking, endorsements and data entry can consume more than 20 hours per week per employee, much of it non-differentiated work. The result: Growth is constrained not by demand, but by how the agency runs.

Industry has moved to AI — but not far enough

Insurance is no longer lagging in AI adoption, it is leading. AI adoption in insurance is outpacing most industries and accelerating rapidly. According to market research firm Zipdo, more than 61% of insurers have embedded AI into workflows or are actively piloting it. Additional research from global consulting firm Deloitte notes that 76% are using AI in some form across their operations.

The impact on the insurance industry of using AI is clear. When AI is applied correctly, insurance organizations have found the following results:

For fast-moving insurance organizations, quoting is where service quality and operational efficiency either scale together or break apart. By implement AI technology, agencies have attained up to 55% faster quoting and 50% faster renewals, improving client satisfaction.

Despite widespread adoption, only a small minority of insurers have scaled AI across their full operating model with most deployments remaining siloed or tactical.

Structural problem: Fragmentation

The majority of agencies have not redesigned workflows. Instead, they have layered AI onto disconnected agency management systems. They continue to use siloed workflows across new business, renewals and servicing. In addition, agencies maintain inconsistent data structures and use manual handoffs from department to department. 

The outcome is predictable: Automation improves isolated tasks, but not end-to-end throughput. Agencies find that they have key data somewhere in their system, but the data is missing context across a policy’s lifecycle. Producers find they continue to be constrained by service dependencies, and the agency’s leadership finds it lacks any visibility into real-time operations.

This is why many agencies experience a paradox: more technology, more automation, and yet limited improvement in growth capacity.

What leading agencies do differently

The agencies capturing disproportionate value are not only adopting AI. They are restructuring the way their agency operates. They are building operating models where:

  • Data flows seamlessly across the policy lifecycle,
  • Work moves across functions with shared context, and
  • AI is embedded into workflows, not added on top. 

This shift is where performance begins to compound. By using AI-driven information, producers can find cross-sell and renewal insights that can increase revenue by 20%-30%. Agencies have found that error rates in operations can drop by up to 90% with integrated validation and data workflows. Most importantly, customer engagement and service response times improve materially, driving retention and growth.  

At an industry level, the upside is significant. According to the well-known consulting firm Bain & Company, AI-enabled transformation represents about $100 billion in value for the insurance industry, driven by productivity, growth, and improvements in operational efficiency. 

The Cogneesol perspective: Extending the agency system

This is the shift Cogneesol is focused on enabling.

The agency management system remains the system of record, but it was never designed to coordinate the full intricacy of modern agency operations.

Cogneesol provides an intelligent operational layer that:

  • Connects data across systems, workflows, and stakeholders,
  • Standardizes and coordinates how work moves across new business, renewals, and servicing,
  • Embeds AI at the points of highest operational leverage, and
  • Creates a unified, real-time view of agency performance.

This is not incremental optimization. It is structural alignment. When agencies move from fragmented operations to a coordinated system many benefits accrue:

  • Producers gain capacity without adding headcount.
  • Service teams operate with greater consistency and scale.
  • Renewal cycles become more predictable and analytics based.
  • Leadership gains actionable visibility across the book. 

Most importantly, the agency transitions from absorbing growth to enabling it.

The bottom line?

The industry has already proven that AI works by reducing costs, accelerating workflows and improving productivity. But those gains plateau quickly when applied to a fragmented operating model.

The next phase of competitive advantage in insurance distribution will not come from deploying more AI tools. It will come from changing the way the agency operates so that intelligence can move across the entire business. That is the difference between simply automating tasks and building an agency that continually improves the way it performs. 

AI is a multiplier, but only if the operating model it sits on is designed to scale it.

About the author

Soumojit Ghosh is Head of Technology Services at Cogneesol.


For more thought leadership from the Cogneesol team, please visit our blog at Cogneesol Blog – For an Ecosystem of Digital Transformation


Sponsored by Cogneesol


Cogneesol

Profile picture for user Cogneesol

Cogneesol

Cogneesol's mission is to help client organizations re-imagine and re-invent every aspect of their business processes.  We seek to achieve this through exceptional, ethical, transparent, and sustainable business services and practices. 

Is the 53-Year Oil Crisis Over?

Even as negotiations on Iran remain muddled, the war shows the world has become resilient to oil shocks. The implications could be profound.

Image
Oil

While oil prices crested at a bit over $110 a barrel In April, some 65% higher than when President Trump began his second term in January 2025, they came nowhere close to economists' forecasts when it became clear that Iran would close the Strait of Hormuz. They expected prices of $150 to $200 a barrel. Some economists feared we might hit $250. 

That oil prices didn't cause a global economic crisis shows that the world has become more resilient in the face of oil shocks. I remember, as a kid, seeing lines around the corner at gas stations after OPEC imposed an oil embargo in 1973, but we came nowhere close to that this time.

The world will now move to become even more resilient, especially to possible events in the Middle East, given that we've seen that supplies can be curtailed just with some mines, speedboats and drones in the world's major oil thoroughfare. The shift toward a global economy no longer dominated by oil considerations will take many years to play out and won't be complete for decades, if ever, but the change will put the world on a new trajectory with profound changes for every industry, including insurance. 

So it's a good idea to start shifting to a new mindset as soon as possible.

My thinking about a post-oil world traces back to 2010, when I was part of a sort of SWAT team at the Department of Energy distributing tens of billions of dollars to drive innovation and help stimulate the economy as part of the Recovery Act following the Great Recession of 2008-9. The leader of the project, Matt Rogers, was the leader of the oil and gas practice at McKinsey, and he had developed a thesis that was radical, especially for the time. While the conversation among economists was about "peak oil" (when global oil supplies would max out and start to diminish), he calculated that the issue was peak demand (when demand, not supply, would crest).

Matt and Stefan Heck, also a senior partner at McKinsey, developed the peak demand idea much more broadly in their 2013 book "Resource Revolution," which I helped them write. So I was intrigued when a columnist in the Washington Post declared yesterday that: "The 53-year-long oil crisis is now over, leaving the world in a better place.... The black, sticky stuff just doesn’t matter as much as it used to."

The soaring output from fracking in the U.S. over the past two decades did a lot to cushion the oil shock this time around. So did impressive flexibility by China, which reduced its imports by some 4 million barrels a day, to less than 8 million, while barely tapping its oil reserves. In coming years, Venezuela may become a major oil exporter again, and the growth of power from renewable sources will keep surging. The Post column notes: "Renewables account for 47 percent of electricity generation across the European Union and 26 percent in the U.S. The share in America is rising fast, with solar last month overtaking coal in power generation."

The columnist says the end of the oil crisis will have three major consequences, and I think he's mostly right:

"First, the Middle East won’t matter so much anymore.... Next, inflation will be subdued. Oil was a crucial enough input in a wide range of products that it helped determine their prices. The U.S. should now expect a decade or more of the cost of living barely changing from one year to the next. Finally, and most significantly, the global economy will be far more stable. Over the last half-century, soaring oil prices accompanied five major recessions or stock market slumps (1973, 1979, 1990, 2008 and 2022).... Chaos was always just around the corner."

I'm not quite as sanguine as the Washington Post writer is, mostly because I've seen too many long-term assurances get derailed. Remember Francis Fukuyama's 1992 book, "The End of History and the Last Man," which assured us that liberal democracy and free market capitalism represented the final stage of human evolution? Look around today and tell me how that worked out.

I can also see plenty of short-term hurdles. The Trump administration is actually paying companies NOT to develop renewable energy, compensating companies for canceling off-shore wind projects. This administration has also recently announced some $700 million to support coal-burning plants, even though coal is on the way out as a source of electricity. In addition, the Trump White House is trying to halt or even reverse the transition to electric vehicles, even though the shift in strategy has caused U.S. car companies to take tens of billions of dollars in write-offs and will help Chinese companies widen their already considerable global lead on the cars of the future.

But I'm still convinced that the half-century-long oil crisis is, in fact, dissipating. 

The geopolitical implications will extend well beyond the Middle East. Other major oil producers, including Russia, Norway, Mexico and, perhaps, Venezuela. will lose huge amounts of revenue and, thus, influence. The world's largest producer, the U.S., won't be immune. Industries, such as chemicals, that rely on cheap energy prices in the U.S. will also lose out. 

Meanwhile, China should gain influence because of its dominance in the rare earth metals that are needed for batteries, in solar panels and in electric vehicles.

The changes should, in fact, reduce global tensions in some areas, though that doesn't mean that peace is at hand. China's increasing influence could, for instance, embolden it to try to retake Taiwan, which could touch off a geopolitical crisis. 

Insurers will have to tack continually as the geopolitical winds shift, and will have to guide clients wisely as they assess their risks. Insurers will likewise have to adapt as industries evolve — probably including shorter, more local supply lines at least for now, in reaction to the Iran war, and to the rise of isolationist politics, including America First. 

Again, there will be lots of twists and turns. Look at how fast Trump reversed U.S. policy in support of electric vehicles. But I think the move toward a post-oil world — at least one far less vulnerable to oil shocks — is accelerating because of the Iran war, and it's never too early to start reshaping our brains to prepare for such a profound change.

Cheers,

Paul

World Cup's First Star — and a Pointer for Insurers

While soccer fans are in a frenzy about the early results from the World Cup, the off-field action offers a suggestion for all businesses, including in the insurance industry. 

Image
Soccer

The World Cup always produces breakout stars. Think of 2018, when the teenaged Kylian Mbappe announced himself to the world by scoring four goals as his French team won the title. So far this year, you might lean toward Folarin Balogun as the possible breakout; he scored twice for the U.S. and looked brilliant as it dominated Paraguay in the opening round. For a team? Perhaps you're partial to Cabo Verde, a country of 500,000 that I confess I did not know existed but that tied mighty Spain, 0-0, on Monday.

For me, the clear breakout star is Freddy. 

The young German has taken social media by storm, growing his follower count on Twitter to 635,000 from the 11,000 he had when he arrived in the U.S. with some friends in early June for a six-week road trip to experience the World Cup. His earnest observations about the U.S. have made him so popular that when he posted that the group was headed to Houston, he arrived to find that former Houston Texas J.J. Watt had paid for a huge room for the group at a posh hotel, and that local businesses had stocked the room with gifts. When Freddy expressed admiration for the music of country music star Ella Langley, she invited the group to meet her backstage after a concert in Oklahoma City. A resort offered to send its plane to pick the group up in Oklahoma City and fly them to Las Vegas for a watch party for a game involving the U.S. men's team. 

There's a reason Freddy has become a sensation, and it suggests something that all businesses, including those in insurance, should do periodically.

An adage attributed to Marshall McLuhan (though with earlier roots) says, "We don't know who discovered water, but it wasn't a fish" — the notion being that anyone immersed in an environment can't understand it the way someone outside that environment can. And Freddy (@FreddyLA7 on Twitter/X) is an outsider providing an unvarnished, unbiased view of America to those of us immersed in it.  

He has shared video of his drive through Alabama and Mississippi and marveled at how beautiful the landscape is — something I certainly missed when I drove through the states on my way from Georgia to Louisiana. Freddy posted a picture of a pile of food at a Taco Bell and called it "the holy land." He wrote: "We were about to walk an hour to the stadium in the rain to save on an Uber, and the receptionist at the hotel we were parked in front of decided to drive us there." Freddy discovered that a Bass Pro Shop had a shooting range inside.

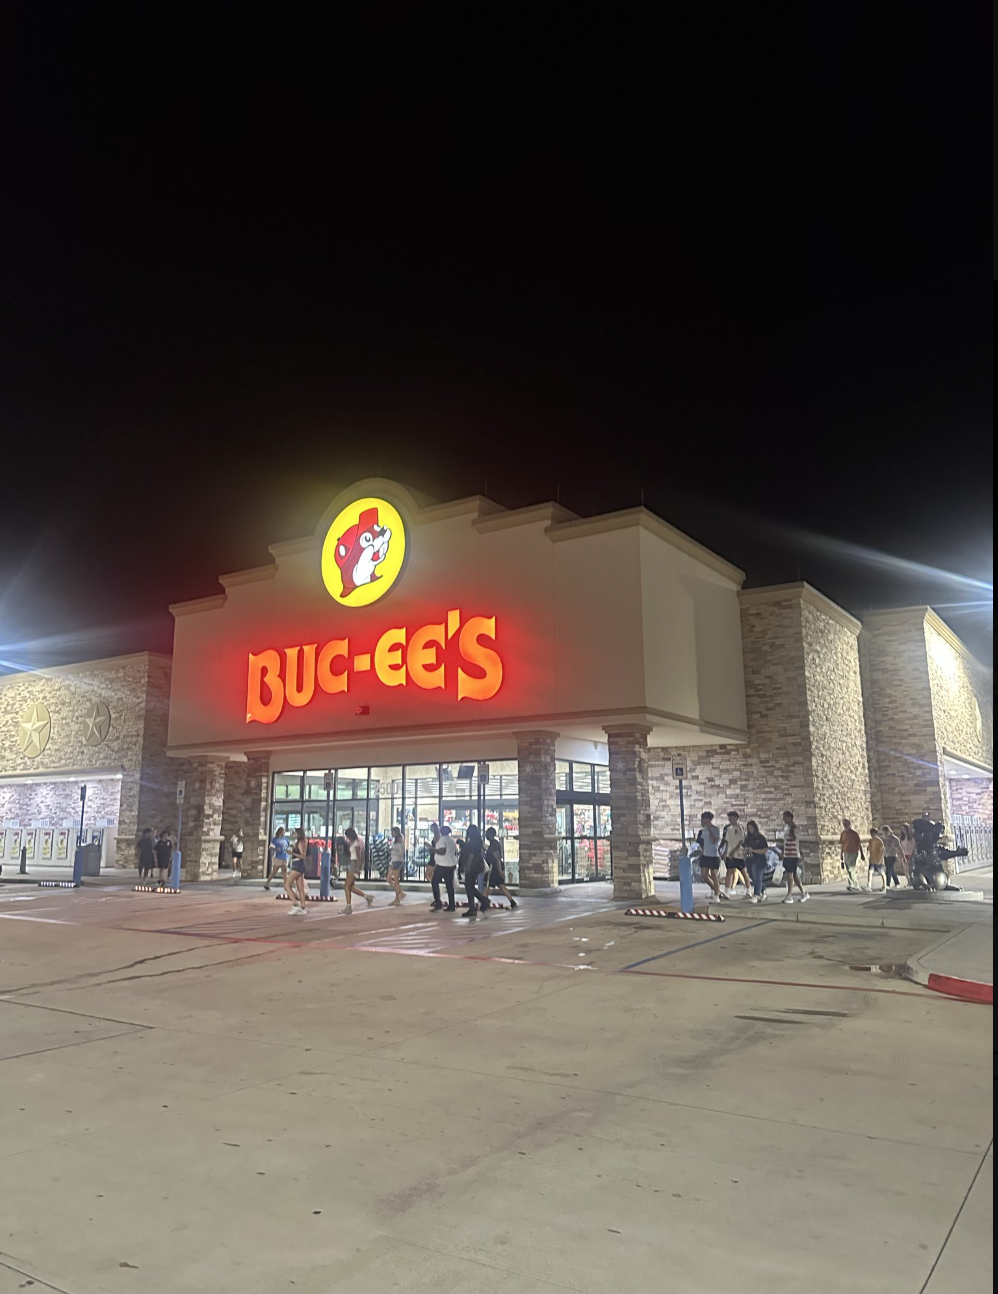
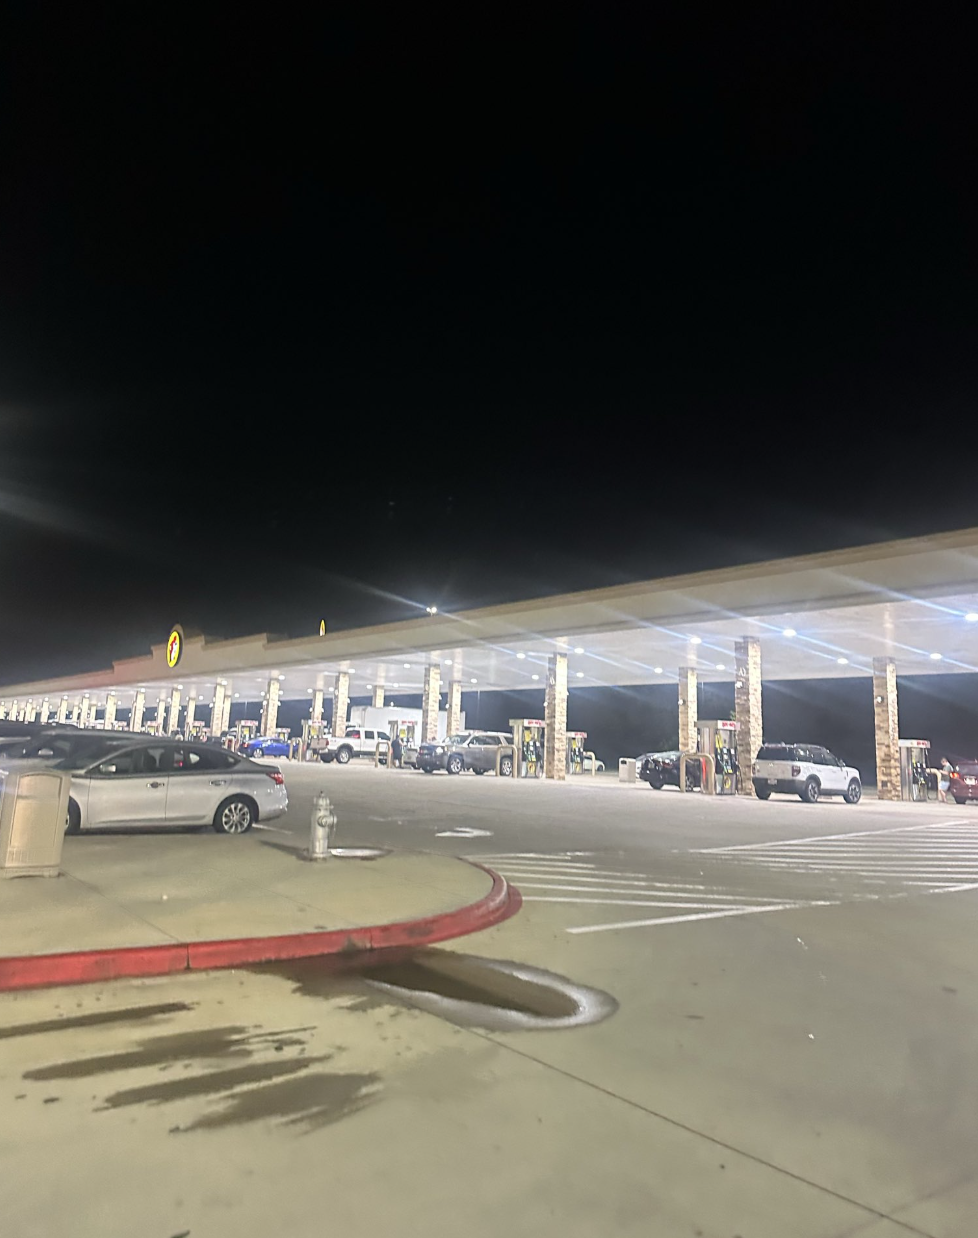
My favorite is a post with two pictures. On the left is a building so big and lit it up it looks like it could be the entrance to an amusement park. On the right is a line of gas pumps stretching way out into the distance. Freddy wrote: "DUDE LMAO THIS IS A GAS STATION." (Someone else said there are 120 pumps and wondered if the travel stop was designed to refuel the U.S. Air Force.)

.           

Freddy then added a photo of the mountain of barbeque he bought inside the Buc-ee's in Texas.

He has surely resonated partly because he's so positive about what he's experiencing in the U.S. Everybody likes to be told they're great. But he still demonstrates the power of outside, objective observation, which is something every company and every individual should solicit as a regular exercise. 

A BCG study I've cited before and will surely cite again found in the early 2000s that 80% of senior executives thought their product was superior to competitors' — and that 8% of customers agreed. Businesses unintentionally erect filters that distort what insiders see, so they have to try extra hard to either remove those filters for themselves or solicit feedback from Freddies who never faced those filters to begin with.

I once interviewed Colin Powell, between his time as the chairman of the Joint Chiefs of Staff and his term as Secretary of State, and he described what I thought was an insightful way to get around the filters. He set up half a dozen phones in his office and gave the number of each phone to a single person whom he trusted to provide a smart, non-DC perspective and reliable, unfiltered information. He told his assistant to never answer any of those phones, to hide the identity of the callers. (I note that the interview was before his time as Secretary of State under President George W. Bush because, after initially resisting the plan to attack Iraq, Powell let himself be sold a bill of goods and made a speech at the United Nations that relied on distorted intelligence to sell the world on the disastrous invasion.)

As I've written before, I think the best way to get unfiltered insight is to experience your company without identifying yourself or to sit with randomly chosen customers as they interact with your company. Make up a persona and call your call center or text it, so you can see what your chatbot actually does. Sit with a relative as they try to decipher the language in the policy you've issued them, without helping. Call people after they've had a claim processed to see just how smoothly your theoretically seamless handoffs from call center and app to adjuster to collision repair shops and rental car companies actually went. And so on.

You surely won't get the sort of joyful feedback Freddy is giving to the U.S., but you'll be able to improve faster than the companies you're up against — and business, like soccer, is a harsh competition.

Cheers, 

Paul

P.S. For those of you who, like me, have been immersed in America so long that the environment feels completely natural, here are a few other observations from visitors for the World Cup:

To start with the negatives, Americans are loud, the U.S. is expensive, and the distances are inconvenient. Traffic is awful. The culture of tipping is baffling. And why are so many items, such as toiletries, locked up in stores?

That said, Ranch dressing seems to be quite a hit. One woman marveled at being able to order a chicken waffle with Ranch dressing and ice cream in an iHOP. Another wrote: "Ranch dressing should be a human right." He added: "The portion sizes are hilarious."

Our grocery store culture has struck a chord, too — the enormity of Walmarts and Costcos, the extraordinary variety of foods offered, and the quality in some of the upscale stores. A Frenchman posted a hilarious screed about how he arrived in the U.S. intending to be a snob but has to admit that the bathrooms in Buc-ee's are nicer than in his apartment. He says, "You could eat the brisket off the floor. It's cleaner than a hospital."

One woman wrote: "I can’t lie… the food in America is ridiculous. Everyone talks about portion sizes, but nobody talks enough about how GOOD everything tastes. Even the ‘quick’ food feels elite compared to what I’m used to in the U.K."

Portion size does come up a lot. One man wrote: "Nobody warned me that American portion sizes are actually a threat to your health. I ordered a medium coffee and received what my country would classify as a bucket."

My favorite, non-Freddy post is a lengthy, almost poetic, one from a Japanese tourist about the biscuits and gravy that a waitress recommended to him at a breakfast counter:

"When the plate arrived, I thought something had gone wrong in the kitchen. I say this with shame. The dish looked like a construction site after rain. Pale mounds. Gray ladle-fall. Speckles I could not identify. In my land, the eye eats first. A meal is arranged like a garden. This meal was arranged like weather.

"I must now formally apologize to the biscuits, the gravy, the waitress, the kitchen and the entire breakfast tradition of the American South. 

"It was magnificent. Warm. Peppered. The biscuit drank the gravy the way a field drinks rain — THAT is why it is shaped like that, you fool — and every mound I had insulted was a soft fold of comfort that my homeland, in 800 years, never once thought to invent."

I'll never look at biscuits and gravy the same way again.

Insurance's $7 Trillion Question

AI-driven data center growth is creating complex insurance challenges that extend far beyond traditional property coverage.

Data Center

Surging demand for artificial intelligence is reshaping the data center landscape at a remarkable pace. McKinsey projects that companies will invest nearly $7 trillion in data center infrastructure globally by 2030, with more than 40% of that spending concentrated in the U.S.

Much of the near-term opportunity is on the development side, with new construction ranging from ground-up hyperscale builds to core-and-shell projects that will eventually be converted into data centers. Beyond new construction, market activity is also being driven by owners and operators of existing facilities, ranging from colocation providers to large enterprises managing their own infrastructure.

As a class, data centers present property insurance exposures that differ significantly from other commercial risks. Understanding the full scope of exposures and the coverage required to address them is critical to building an insurance program that responds as expected when a loss occurs.

TOP EXPOSURES AND RISKS

While data centers are designed for resiliency, meaningful exposure still exists across every stage — from construction and commissioning to continuing operations — and extends beyond the physical asset itself.

Business interruption and downtime are the primary concerns. These facilities are built for continuous uptime that developers and owners depend on, meaning even a brief outage can generate a significant claim. Location compounds that exposure. Data centers are increasingly being built in areas where severe weather is common, considerably raising the risk for catastrophic losses. Even if a major weather event takes a facility offline temporarily, it can produce revenue losses that far exceed the physical damage. As such, carriers are focusing attention on loss control, engineering standards, business continuity and disaster recovery planning. They want confidence that construction can resume at a development site or that a facility can return to operations quickly after a disruption.

Secondary exposures also complicate the risk picture. These include:

  • Power and grid reliability. Power disruptions stemming from grid instability, utility constraints, or insufficient local infrastructure are increasingly common. When operational disruptions occur that don't involve physical damage to the facility, a standard property policy may not respond to losses.
  • Community opposition and project approval risk. Public pushback has become a defining obstacle to data center development. Last year saw 25 project cancellations — more than quadruple from 2024 — largely driven by intensifying community opposition across the country. Access to the power grid and water supply are among the most common sticking points, with the potential for municipal resistance to derail projects persisting well into the development process.
  • Equipment procurement delays. Waitlists are already common for critical, high-value components that are in short supply. If equipment is damaged, stolen or lost in transit, sourcing replacements can further extend a project.
SPECIALIZED COVERAGE TYPES TO CONSIDER

A standard property policy covering physical damage and business interruption is foundational, but data centers frequently require additional layers to address the range of exposures that fall outside traditional coverage triggers.

Builder's risk coverage addresses the construction phase — a critical window of exposure for data center projects. With contractors, lenders, and third-party operators all at the table, each with their own coverage requirements, structuring a program that satisfies every stakeholder is critical.

Parametric and alternative risk transfer products are increasingly relevant for data centers, particularly when the cause of a financial loss doesn't stem from physical damage. Parametric coverage, captive structures, and self-insurance components can be structured to fill gaps where a standard policy doesn't respond. They can also serve as deductible buy-downs on programs with large retentions as well as supplemental capacity where needed.

Transit, cargo, or stock throughput policies are essential given the value of equipment moving through the supply chain. Millions of dollars in power equipment, servers and GPUs may be in transit, held in interim storage, or staged on-site before a facility is operational. If something goes wrong at any point in that chain, both replacement costs and project delays can escalate quickly.

Environmental insurance is worth considering for new construction, given the scope of ground-up development activity and its potential effect on the surrounding site and community. Contamination, pollution, and construction-related environmental liability are exposures that a standard property policy won't address.

Political risk insurance is particularly relevant for international projects. Geopolitical instability, strikes, riots, and government actions can affect data center operations in ways that generate both physical and financial loss.

WHAT THE CURRENT INSURANCE MARKET MEANS FOR OWNERS AND OPERATORS

The property insurance market is in a soft cycle, with data centers largely seen as a desirable class of business. Some insurers are deploying staggering single-line limits on data center risks, which translates to more options and more competitive terms for owners and operators. This is a welcome stance as many lenders and other sources of capital currently require full value limits of insurance vs. limits set by modeled losses based on probabilities and site attributes.

But questions remain as to whether that dynamic will last. Data centers remain a relatively untested class, and how the market responds when significant losses arrive is still an open question. Owners and operators who use the current environment to structure comprehensive, well-designed programs will be better positioned as conditions evolve.


Blake Giannisis

Profile picture for user BlakeGiannisis

Blake Giannisis

Blake Giannisis is executive vice president and the North American property practice leader at global insurance brokerage Hub International. 

He has more than 25 years of property broking experience in various property broking and senior management positions. He spent a decade at Aon, worked at Wells Fargo Insurance Services and also spent a decade at Marsh & McLennan. 

He earned his undergraduate degree from Colgate University and his master’s degree in business administration from NYU Stern School of Business. He has achieved the credential of Associate in Risk Management (ARM).

A Cautious Economic Outlook for P&C

Triple-I Chief Economist Michel Léonard says he remains an optimist but notes a number of risks facing the P&C insurance industry. 

An Interview with Michel Léonard

Paul Carroll

We not only had strong job numbers in the U.S. for May, which would reduce the need for the Fed to cut interest rates, but also had 4.2% annual inflation in the latest report, which would tend to encourage the Fed to keep rates flat or even to raise them. Has your outlook on inflation and economic risks evolved since we last spoke, particularly given what's happening in Iran?

Michel Léonard

You're entirely right. Since we last spoke, I've grown more cautious. 

When the conflict started, nobody expected it to go into a third or fourth month. As a result, we didn't expect the conflict would last long enough for increases in oil and gas disruption to be  transmitted into the price of gas and petrochemicals and as sunk costs throughout the economy. We made the same assessment about the conflict being unlikely to last long enough to significantly alter our P/C replacement forecasts. 

But that transmission is taking place and driving up the price of products key to our replacement costs: construction plastics, PVC, rubber; construction materials; not to mention increases in the cost of transporting all these goods and more. 

That said, I would to share some caution. The price increases we’re already seeing are not solely due to actual price transmission; they're also about the anticipation of transmission. Some companies are pricing up before the higher costs hit them. We saw that during and since COVID. We can’t deny that there is price gouging: Why wait until your margins get compressed? Especially when the wider price narrative in the press and elsewhere is increasing consumer willingness to accept price increases. 

Paul Carroll

What does this mean for P&C insurers next year in terms of replacement costs relative to inflation in the broader economy?

Michel Léonard

Because of the anticipation, I think the trajectory—the pace of increase in inflation, including P/C replacement costs—is above what the underlying supply disruption would warrant. That’s partly because some people have been expecting a bigger disruption than has happened and partly because of gouging by some, who say, "Okay, we can charge a bit more." Right now, the regular CPI and the CPI-core (without energy and food) are increasing in lockstep. What it means is that we should expect P/C replacement costs to increase at the same pace as CPI-core (without energy), at a faster pace than they should given transmission alone, before gouging. 

Paul Carroll

Given the strong jobs report and high inflation, what is your outlook for Fed policy?

Michel Léonard

The Fed has put rates on hold but, in my opinion, still within the wider framework of an easing cycle. The unemployment rate is improving, and though one quarter is not a trend, it’s likely telegraphing to the markets that it the Fed is going from holding rates within an easing cycle, to holding rates between easing and tightening. I would be very surprised if the Fed went directly to telegraphing tightening.

There are a few things to consider here, especially for P/C insurance. Let's put this in context:

The Fed continuing to delay on interest rate cuts, or telegraphing a shift to tightening interest rates, would likely once again reduce homeowners and commercial property insurance’s underlying growth. 

Concerns about inflation, especially if the Fed gets fully on board with shifting to tightening rates, will further accelerate increases in P/C replacement costs – by signaling to producers that they can raise costs ahead of actual price increases. This is before we see more actual transmission from oil prices in to the wider economy.

This is bad news for P/C’s combined ratios – and it could not come at a less opportune time. 

We had COVID inflation and post-COVID inflation that led to carriers working with regulators to implement, in some cases, double-digit or high-single-digit year-over-year increases in premium rates. That's where we came from.

We had finally reached an equilibrium that would justify premium rate increases returning closer to historical averages—low single digits, around 2% to 4% year over year. Now that equilibrium is being challenged.

Now we’re faced with renewed inflation – but instead of doing so in a hard market, we’re doing it as we’re heading into a soft market. Depending on how fast we get there, the impact on combined ratios may be significant.  

Paul Carroll 

What's your assessment of the state of the U.S. economy, given all the stresses?

Michel Léonard

I’m still an optimist and think the U.S. economy remains resilient. Looking at the core drivers of monetary policy and how economists assess the economy —employment, inflation, and growth—let's start with employment. There have been a few months of improvement. If we look at nominal growth, it's healthy. But if we take out inflation from nominal growth, we see the problem. Real GDP is struggling. And inflation is getting worse.

Two out of the three, growth and inflation, are facing headwinds, which I read as the “balance of risks” is still tilting toward the downside. At best, we’re at an equilibrium. I would be wary if the Fed started to talk about raising rates – that would likely worsen the unemployment rate again, accelerate inflation, and bring growth to a halt. In my assessment, such talk would be a significant miscalculation. 

Paul Carroll

Given the enormous amount of geopolitical risk—from the situation in Iran to the Ukraine-Russia conflict to concerns about China and Taiwan—would you point to that risk as a major source of uncertainty that maybe hasn’t been priced into expectations about the economy?

Michel Léonard

Geopolitical risks keep piling up, and, at least for the time being, I would suggest that they aren’t being fully priced across unemployment, growth, and inflation. I did geopolitical risk stress tests 20 years ago about Iran, Taiwan, and war in the Middle East – they all resulted in equity and interest rate corrections much more significant than we are seeing now. Consequently, the tests showed economic performance deteriorating much further than it has now – not to argue that we’re in a good place at this time.  

You asked about what kind of other geopolitical risks are out there that may not have been priced in economic forecasts? A few truly raise alarms for me and not just as an economist: Putin attacking Finland or the Baltic states; China deploying cyber warfare against the U.S. and shutting down transportation, electric cars, or power grids; a new pandemic such as Ebola ,with few of the institutional capabilities we had during COVID; the looming threat of Jan. 6 on the coming midterms in the U.S. 

Paul Carroll

Where do tariffs figure in all this? I certainly have no idea what the tariff regime will look like in six months.

Michel Léonard

Thanks for bringing that back up. The tariff issue hasn’t gone away. There's an economics principle about risk tolerance. For example, folks winning at a casino become more risk-averse and prudent. Folks losing become more risk tolerant and bid more aggressively. With all that's going on in our world right now, folks are actually getting more risk-tolerant, and that's always the problem. 

Paul Carroll

What final words of wisdom would you leave us with?

Michel Léonard

I don't know if it's wisdom. But I would say that, regardless of everything, I remain optimistic. The U.S. consumer is resilient, U.S. companies are resilient. There's a lot of strength there.

For the P/C industry, we’re coming from a good place, even if we’re heading into a soft market. We’ve seen a lot of improvement in the last two years on replacement costs, and more recently we’re seeing better trends for combined ratios. Both provide some protection against the risks ahead of us.

Paul Carroll

Thanks, Michel. I always feel smarter after we talk.


Insurance Thought Leadership

Profile picture for user Insurance Thought Leadership

Insurance Thought Leadership

Insurance Thought Leadership (ITL) delivers engaging, informative articles from our global network of thought leaders and decision makers. Their insights are transforming the insurance and risk management marketplace through knowledge sharing, big ideas on a wide variety of topics, and lessons learned through real-life applications of innovative technology.

We also connect our network of authors and readers in ways that help them uncover opportunities and that lead to innovation and strategic advantage.

The Case for a Personal Digital Bodyguard

As cybercrime hits $21 billion, personal cyber insurance must pivot from reactive coverage to proactive protection.

Cyber Insurance

The FBI’s Internet Crime Complaint Center (IC3) just gave the world a $21 billion wake-up call. According to its 2025 report, cybercrime costs reached a record $20.8 billion in losses last year, sounding the alarm bells on the critical need for personal cyber insurance policies that offer proactive risk management.

The FBI IC3’s annual report states that business email compromise (BEC) and financial fraud are the two leading methods of cybercrime. Long considered a corporate network issue, BEC is now the primary way cybercriminals infiltrate enterprises by targeting the personal vulnerabilities of key leaders. At the same time, high-net-worth individuals (HNWIs) are increasingly victims of cyber-enabled fraud, with AI playing a central role in enabling cybercriminals to create deepfake impersonations and realistic phishing emails and texts, thereby lowering the barrier to entry for malicious hackers.

As the adage goes, “an ounce of prevention is worth a pound of cure.” For cyber insurance underwriters and brokers, offering a policy that only covers remuneration for damages after an event is no longer enough. To manage risk effectively for HNWIs and business leaders, insurance must pivot toward a preventive cybersecurity model that stops incidents – and the long-lasting financial and reputational consequences that follow – before they can happen.

Modern Executives and the Expanding Attack Surface

The FBI IC3’s 2025 report findings highlight growing dangers and underscore the rapid expansion of the personal attack surface, fueled in large part by the rise of AI:

  • Business email compromise: Scams that compromise business and individual email accounts to conduct unauthorized transfer of funds accounted for 15% of all 2025 losses, totaling slightly more than $3 billion.
  • Cyber-enabled fraud: 85% of all losses reported in 2025 were due to cyber-enabled fraudulent activities, including theft of money, data, or identity, or the creation of counterfeit goods or services, totaling $17.7 billion in losses.
  • Tech/customer support fraud: In 2025, nearly 48,000 complaints were filed by individuals about cybercriminals posing as technical or customer support/service representatives, resulting in losses totaling $2.1 billion.
  • AI-fueled threats: For the first time, the report includes a section on AI-enabled cybercrime and scams, reporting that IC3 received 22,364 complaints in this category, which accounted for over $893 million in losses.

High-profile enterprise executives and high-net-worth individuals are caught in the crosshairs of these attacks. Because they have broad digital footprints, typically own multiple homes with numerous smart devices, and maintain significant public profiles, they are now prime targets of cybercrime. Additionally, it’s a tremendous challenge to maintain privacy in the digital era, with social media and the instant, broad dissemination of information. Events we prefer to keep private can instantly become public knowledge, creating a risk profile that corporate cybersecurity policies typically fail to address.

Personal cyber insurance brokers are ideally suited to help their clients consider how a single personal indiscretion or data leak can have long-term career and reputational impacts. Beyond that, however, they have a professional and ethical responsibility to protect their clients – not just provide reactive cyber coverage.

Making the Case for a Digital Bodyguard

In the modern cyber landscape, fraught with potential exposures and points of vulnerability at every turn, highly vulnerable individuals can benefit from personal cybersecurity protection that fills the gaps left unaddressed by enterprise cybersecurity. By shifting from a reactive cyber policy to a proactive, preventive risk-management offering, insurance brokers and underwriters can provide clients with a “digital bodyguard” to protect them while safeguarding their bottom line. I’m not talking about security software; I’m talking about a preventive capability that protects people and stops incidents from ever causing harm.

The core elements of comprehensive, proactive protection include:

  • Minimizing digital footprints: Actively reducing an individual’s "attackable" surface area by minimizing how much information they share online.
  • Data broker removal: Scrubbing personal info from the sites that feed cybercriminals.
  • Hardening accounts and devices: Moving beyond basic passwords to elite-level security to ensure personal accounts and devices are not vulnerable to malicious access.
  • Home network scanning: Continuous monitoring of home networks – the "soft underbelly" of executive security – to detect suspicious activity before it causes harm.
  • Training & hygiene: Empowering individuals and their families on appropriate online behaviors, how to spot scams and threats, and continuing ways to minimize their attack surface.
  • Incident response: Around-the-clock expert support to respond rapidly when a significant threat is detected.

The reasons for offering this type of personal cybersecurity protection and risk mitigation to corporate and individual clients are a no-brainer: insurance brokers can foster greater trust, improve client retention, and safeguard their clients’ financial posture. Preventing a $1 million breach and the resulting reputational and financial repercussions is far more advantageous than paying out on a claim.

Demand for this type of specialized protection is rapidly growing, as organizations and individuals gain a better understanding of what’s at stake. Insurance underwriters and brokers have a window of opportunity to capitalize on this growth before other trusted advisors step in and bolster their own service offerings.

Don Poster, vice president and senior director - national family office leader of Aon Private Risk Management, states: "Our clients rely on us to preserve both their legacy and their lifestyle. In 2026, you simply cannot protect a client’s wealth, assets, family, and privacy without also protecting their digital identity. We view digital executive protection not as a tech add on, but as a fundamental component of holistic risk protection.”

Diane Delaney, executive director of the Private Risk Management Association (PRMA), agrees. “The PRMA recognizes that the most successful brokers are those who offer more than just an insurance policy safety net. By taking proactive risk management approaches such as integrating digital executive protection, brokers can provide a holistic layer of protection that helps mitigate the reputational and financial fallout that traditional cyber insurance policies are meant to cover,” she said.

Locking Down the Future

Traditional insurance reacts to and repairs damage – in simple terms, it’s like getting a broken arm treated at the hospital. Proactive personal protection prevents the break from happening in the first place. In the modern digital realm, AI-powered threats targeting high-profile, high-net-worth individuals are rampant, and the personal attack surface continues to expand. The unfortunate reality is that corporate defenses often fall short of protecting individuals.

The solution is a proactive "digital bodyguard" approach – the best and most sustainable way to manage and mitigate executive risk, and protect people and corporations from significant, costly attacks and breaches. It’s time for insurance brokers and underwriters to stop viewing personal cyber as a standalone policy and begin offering a comprehensive service to lock down an individual’s digital footprint and safeguard their future.