Download

Insurers' Readiness Gap on AI

The problem is not that insurance organizations' data is bad. The problem is that it was shaped for humans, not AI.

Actuarial Numbers

An April 2026 AM Best survey of more than 150 rated insurers and MGAs found that 45% still cite data readiness as the top barrier to AI deployment, even among analytically mature organizations.

Insurance carriers have invested years building trusted analytics platforms. Data warehouses and governed metrics now deliver consistent loss ratios, premium trends and claims data that actuaries, underwriters and executives rely on. Yet when these same carriers launch AI initiatives, results often disappoint. Underwriting assistants hallucinate risk scores, fraud models produce unexplainable flags and catastrophe projections miss critical context buried in broker narratives and loss-run documents.

Your Analytics Layer Works - For What It Was Designed For

Analytics-ready data serves human decision-makers asking backward-looking questions. Actuaries calculating reserves, underwriters reviewing portfolios, compliance teams preparing filings and executives setting strategy all need consistent, summarized and explainable information. The central question is always the same: what happened?

The semantic layer defines business metrics, dimensions and access rules. It creates a single governed version of the truth so an actuary in New York and an underwriting director in London both get the same answer to "What was our Q3 combined ratio?" This layer excels at aggregation and stability. It compresses complex reality into clear, auditable numbers that humans interpret using their own judgment and domain knowledge.

AI Systems Are a Different Consumer Entirely

Large language models, reasoning engines and autonomous agents do not aggregate and summarize. They traverse, reason and act. They consume tokens, embeddings and context windows. They need properties that analytics infrastructure was never designed to provide:

  • Full context and completeness behind every number.
  • Provenance and trust: every fact carries its source, confidence level and resolution history for audit and regulatory defense.
  • Semantic richness: named, typed relationships between policies, claims, insureds and risk factors so agents can reason without custom code.
  • Conflict handling: the system preserves multiple sources, flags discrepancies and tracks resolutions rather than forcing a single version of the truth.

The enabling structure is an ontology - a knowledge layer that makes the domain understandable and navigable for machines.

Key Structural Differences

Analytics-ready data answers "what happened" by compressing thousands of transactions into governed numbers. AI-ready data answers "what should happen next" by preserving the full evidence trail behind every fact. A semantic layer translates business questions into consistent reports. An ontology maps the domain so machines can traverse it, weigh evidence and explain conclusions. Both are necessary. They serve different audiences through different infrastructure over the same foundational data.

The Right Architecture: Parallel Layers, Shared Foundation

Leading insurers build both capabilities over the same foundational event data (policies, claims, submissions). The semantic layer powers governed dashboards and regulatory reporting. The ontology gives AI agents the structure to reason, track provenance and produce explainable decisions.

The layers reinforce each other. Unified governance (lineage, confidence scoring, conflict rules and human review) serves both without compromise.

Why the Stakes Are Higher in Our Industry

Regulators demand explanations that dashboards cannot provide. The NAIC AI Model Bulletin and Colorado SB21-169 require clear, contemporaneous provenance for AI-influenced decisions. Most underwriting intelligence lives in unstructured documents that analytics systems were never designed to handle. Renewal workflows are change-detection exercises that benefit enormously when both layers work together.

Where to Start

Insurers with mature analytics platforms do not need to start over, but they must:

  1. Capture foundational events at the atomic level before aggregation.
  2. Protect your existing analytics layer. It works for actuaries and regulators.
  3. Build the ontology around one high-value use case, such as underwriting submission intake.
  4. Apply governance that serves both layers.
  5. Measure success separately: analytics by dashboard trust and reporting accuracy; AI by reduced hallucinations, explainability and business impact.
The Bilingual Insurer

The carriers that will lead the next decade are fluent in both data languages: one that helps humans trust and explain the past, the other that enables machines to reason about the future with transparency and confidence.

Your current analytics investment remains essential. It is also insufficient for AI. Building a parallel ontology capability is one of the highest-leverage moves you can make today. Closing the gap will unlock better risk selection, stronger regulatory resilience, lower fraud losses and genuinely intelligent operations.
Insurance Industry Faces Critical Talent Shortage

As 400,000 insurance professionals retire and Gen Z stays away, workforce gaps are becoming critical operational risks.

New Hire Shaking Hands

The insurance industry is one built on history and resilience, but it's also one where the future is facing immense uncertainty.

By the end of 2026, an estimated 400,000 insurance professionals will have retired in the U.S. since the beginning of 2021, according to the Bureau of Labor Statistics. At the same time, nearly one-third of the current global population is Gen Z. And yet, 79% say they've never considered working in insurance due to perceptions of the industry being "boring" or too corporate. Right now, the industry is facing a major workforce shortage that could have the same consequences for our stability as any underwriting cycle or catastrophe trend.

This disconnect is a structural risk to the industry's ability to operate, innovate and respond to crises in the years ahead.

The perception problem is now a workforce problem

For decades, insurance has struggled with an image issue. Despite the passing of the so-called "Great Resignation," the insurance industry continues to face significant workforce challenges.

In an industry survey, Gen Z was asked to identify business sectors that they found the most appealing to work in, and insurance came in last.

Not to mention that this generation is bringing a new meaning to work. One of those is finding a greater purpose in the work itself. However, Gen Z doesn't associate the insurance industry as one that could provide that purpose. Not to mention they want to work in a fun, social environment ... and the perception of the industry is the opposite for most.

It's fair to say that these perceptions are working against the industry.

In reality, insurance is one of the most human industries that exists. It shows up at the most critical moments in people's lives. Most people don't picture it in this way, but insurance is the industry that helps families rebuild after disasters, enables small businesses to survive disruptions and plays a major role in addressing systemic risks like climate change. Yet we continue to present it externally as a series of processes rather than outcomes.

At the same time, there's also an expectation that work environments are dynamic and technology-forward. When those expectations collide with outdated perceptions of insurance, the result is simple. The talent looks elsewhere.

Why talent gaps are becoming operational risks

What makes this moment different is not just the scale of retirements but the nature of the skills leaving the industry.

Insurance has always been a knowledge-driven business. Institutional expertise is the foundation of underwriting decisions, claims handling and client relationships. Still, as experienced professionals exit the workforce, much of that knowledge is at risk of being completely lost or only partially transferred.

The industry is also being asked to evolve faster than ever. Volatility just keeps happening. For example, climate-driven events are increasing in frequency and severity, not to mention cyber risk, supply chain disruption and emerging technologies are introducing new categories of exposure. Meanwhile, customers are expecting faster and more transparent service in real-time.

This is where the talent gap becomes a direct threat to performance.

Without a steady pipeline of new talent, insurers are facing three immediate challenges. First, claims handling capacity becomes strained during surge events, leading to slower response times and diminished customer trust. Second, the adoption of technologies like AI and advanced analytics slows, not because the tools are unavailable, but because the workforce lacks the capacity or skills to implement them effectively. Third, innovation stalls, as fewer cross-disciplinary thinkers enter the industry to challenge legacy approaches.

Because of this, workforce shortages are no longer an HR issue. They become core drivers of operational risk.

Reframing insurance careers for a new generation

If the problem is misalignment between perception and reality, then the solution starts with how we present the industry and how we design the actual employee experience behind that message.

The first shift is reframing the purpose of the work. Insurance organizations need to move beyond describing roles in terms of tasks and instead clearly articulate the impact. Processing a claim is not an administrative function; it's helping someone recover from loss. Underwriting isn't just risk selection; it's enabling economic activity and resilience. If we can't clearly communicate why the work matters, we shouldn't expect younger generations to see its value.

The second shift is making the modern reality of the work visible. Inside many organizations, workflows are already evolving. Automation reduces manual processes. AI is supporting decision-making. Data is becoming central to operations. Yet externally, candidates picture fax machines and cubicles. Bridging this gap requires intentional storytelling and transparency about how the work is actually being done today.

The third is creating clearer and faster paths for growth. Gen Z isn't interested in climbing the ladder and waiting more than 10 years to "become important." They want to understand how they can develop skills and take on new responsibilities within the first one to two years. This requires developing more structured progression frameworks, exposure to different parts of the business and earlier involvement in meaningful decision-making.

Finally, the industry needs to address its reputation directly. There's skepticism from younger generations around complexity, transparency and claims outcomes. Ignoring it will only reinforce distrust. Organizations that acknowledge these concerns and demonstrate how they're improving will be the ones that win over talent, and even customers.

At the end of the day, this all boils down to an alignment problem, not marketing. If your employer brand says "innovative, flexible, purpose-driven," but the actual experience feels slow and transactional, Gen Z will spot that immediately and opt out.

Workforce planning is risk management

All of this leads to a broader point that the industry has not fully embraced. Workforce planning should be treated as a risk management priority.

In insurance, we are disciplined about identifying and managing exposures. We model catastrophe risk. We monitor market volatility. We stress-test portfolios. Yet we've historically approached workforce planning as a functional responsibility rather than a strategic one.

This approach no longer works and cannot continue.

Everything in insurance (i.e., growth targets, service commitments, etc.) ultimately depends on having the right people with the right skills. When that foundation weakens, the impact is immediate. Service levels decline. Innovation slows. Risk exposure increases.

Forward-looking organizations are beginning to recognize this and are integrating workforce considerations into broader risk frameworks. They're mapping critical roles against future business needs. They're identifying where skills gaps are likely to emerge and invest ahead of them. They're rethinking talent models, including how and where work gets done, to ensure resilience at scale.

The bigger picture is ensuring the business can operate reliably under pressure.

The path forward

The insurance industry doesn't have any issues being relevant. What it does have an issue with its perception.

The opportunity in front of us is significant. We have a chance to redefine how a new generation sees this industry and, more importantly, how it experiences working within it. Doing so will not only address current workforce challenges but also position insurers to be more adaptive, innovative and resilient in the face of future risks.

The organizations that move first will have a distinct advantage. They will attract the talent that others struggle to reach. They will build the teams capable of navigating increasing complexity. And they will be better equipped to deliver on the fundamental promise of insurance: stability in an uncertain world.

In 2026, changing the narrative around insurance jobs is not optional. It is a prerequisite for the industry's long-term growth and stability.


Norm Hudson

Profile picture for user NormHudson

Norm Hudson

Norm Hudson is co-founder and CEO of Staff Boom.

Previously, he was principal owner and CEO of Inszone Insurance Services. He was also COO of Confie Seguros and president/CEO of Cost U Less Insurance.

Insurers, Plaintiff Bar Wage AI Arms Race

Insurance carriers and the plaintiff bar are waging an AI arms race reshaping litigation economics.

Abstract 3D render visualizing artificial intelligence and neural networks in digital form

The conversation around legal AI usually follows a predictable script about BigLaw billable hours, the democratization of small firms, or whether an LLM can pass the bar. These debates focus on the visible front lines—the lawyers and the courtrooms. But focusing there means you're watching the wrong game. The real transformation is happening deeper within the economic engine of civil litigation, driven by the insurance carriers. And on the other side, the plaintiff bar is arming up just as fast.

McKinsey estimates generative AI could unlock $50–70 billion in insurance industry revenue. Bain found that 78% of P&C insurers are already using generative AI—though only 4% have scaled it meaningfully. The arms race is underway. Most litigators just haven't noticed the battlefield has moved.

From Colossus to LLMs

Carriers have used algorithmic case valuation for 30 years. The best-known tool, Colossus, is a rules-based system with over 10,000 decision rules, relying on structured inputs, including ICD codes, CPT codes, and severity ratings. If something wasn't in a form field, the algorithm was blind to it. What many practitioners don't realize is that Colossus is reportedly still used by over 70% of insurers. If you've negotiated a bodily injury claim in the last decade, your demand was likely run through it or a similar tool on the other side of the table.

Colossus generated over $293 million in class action settlements and sustained NAIC scrutiny over the "black box" problem of algorithmic valuation. That history matters, because the next generation of these tools is far more powerful and far less transparent.

LLMs are the leap. They don't need structured fields. They ingest the entire case file, medical records, deposition transcripts, and police reports, and spot nuance a rules engine never could. The gap between what a carrier knows about a case and what a plaintiff's attorney knows has always been a matter of leverage. That gap is narrowing fast. Vendors such as Shift Technology, CLARA Analytics, DigitalOwl, and Wisedocs are deploying LLM-driven analysis at scale across the carrier ecosystem. Meanwhile, carriers from Allstate to Chubb are building proprietary tools internally.

The Data Moat Is Eroding

The carrier's deepest advantage isn't computing, it's context. Carriers sit on millions of closed claims, private settlements, and internal outcomes that never see a public docket. A carrier AI doesn't just know what a jury in Cook County did last week; it knows what the carrier paid to settle 10,000 similar cases over the last decade without a trial. That training data is unique.

But the moat is narrowing. CLARA Analytics operates a contributory database trained on millions of closed claims across its carrier clients. On the plaintiff side, EvenUp, now valued at over $2 billion, has crowdsourced actual settlement data from over 2,000 plaintiff firms processing roughly 10,000 cases per week. The information asymmetry that defined carrier leverage for decades is real, but both sides are now building proprietary data assets. The gap is closing.

When Models Argue With Models

This isn't hypothetical any more. In January 2026, a startup called Mighty launched a platform that acts as an AI agent negotiating personal injury settlements against carrier AI on behalf of consumers. Its CEO stated plainly: the company gives consumers AI to negotiate with the insurance company's AI. This builds on decades of automated dispute resolution. Cybersettle alone has facilitated roughly 200,000 claims totaling $1.4 billion using algorithmic double-blind settlement since the late 1990s.

Now imagine the next step. A plaintiff firm's AI evaluates a case at $850,000 based on crowdsourced settlement data. The carrier's AI, trained on 40 years of internal claims history, pegs it at $320,000. Does a shared analytical baseline strip away posturing and accelerate resolution? Or does it entrench positions because each side treats its own model as truth? We risk moving from a world of legal judgment to a world of model drift, where outcomes depend less on case facts and more on whose training data runs deeper.

Regulators Are Already on the Case

When a carrier's AI determines a claim is worth zero, how does a plaintiff challenge that logic? Regulators have been working on this since at least 2021. As of early 2026, at least 25 states plus D.C. have adopted the NAIC's Model Bulletin on AI, requiring written governance programs, consumer notice when AI affects decisions, and bias testing. Colorado has gone further, SB 21-169 requires quantitative bias testing for AI used in claims handling, with enforcement tools including civil penalties and license revocation. The black box problem is real, but it's an active regulatory battleground, not an open question. Practitioners who don't understand the compliance landscape their opponents operate under are leaving leverage on the table.

Nuisance Value

If carrier AI gets better at early case triage, the economics of "nuisance value" - paying $5,000 to make a weak claim go away rather than litigating - could shift. Claims that used to settle for small sums may face an automated "no." But let's be honest: there is no published empirical evidence that AI triage is currently eroding nuisance settlement patterns. This is a plausible hypothesis, not an observed trend. And the counter-argument has merit, if AI reduces per-claim evaluation costs, carriers might become more willing to pay small amounts quickly, not less. Conversely, if a model flags a case as high-exposure early, carriers have every incentive to settle fast rather than lowball a claim they're likely to lose at trial.

A New Equilibrium?

Law is an adversarial system. When one side upgrades, the other responds. Carriers are deploying AI across claims processing, litigation prediction, and settlement valuation. The plaintiff bar is responding in kind. Contributory databases are eroding data monopolies. Regulators are imposing transparency requirements that may force carriers to show their work in ways they never have before.

The question for litigators isn't whether AI will change how cases are valued. It already is. The question is whether you understand what's in the black box on the other side of the table—and whether you have your own.


Daniel Ivtsan

Profile picture for user DanielIvtsan

Daniel Ivtsan

Daniel Ivtsan is the senior director of AI products for Steno. 

Steno focuses on providing attorneys with innovative tools and options that overcome the technological and financial hurdles that arise when proving a case. 

Early Diagnosis Challenges Health Insurance Models

Continuous monitoring and early screening are exposing insurers to costs before traditional coverage activates.

A stethoscope and pen resting on a medical report in a healthcare setting.

In recent years, a discontinuity has been emerging in health insurance related to when the need for healthcare becomes observable and manageable.

The evolution of clinical practice—across early diagnosis, continuous monitoring, and risk management—is shifting the point at which the insured enters the care pathway, introducing an intermediate phase between a state of health and a manifest clinical event.

This shift transforms need from a discrete event into a process distributed over time, characterized by progressive signals and increasingly frequent follow-up activities.

Impact on the Insurance Model

The health insurance model remains built around formal triggers and codified benefits. It works when need translates into clearly identifiable actions—procedures, hospitalizations, therapies—but is less structured in the phase where need is still forming. This creates a misalignment: medicine generates demand for care earlier and continuously, while coverage activates when that demand takes on a defined and reimbursable form.

The anticipation of need emergence is not neutral for the portfolio. The increase in screening and monitoring translates into higher frequency of services in early stages: more visits, tests, and follow-ups. The critical issue is not only the increase in frequency, but its nature: it is more difficult to model, as it is linked to distributed behaviors rather than discrete events. The phenomenon is already observable in recurring signals within portfolio data: increased outpatient frequency, longer claims sequences, and greater dispersion between frequency and severity. In this context, leakage phenomena also emerge; services that are in fact preventive are formally classified, through prescription, as reimbursable visits or diagnostic tests. This is not fraud, but a dynamic that shifts volumes into covered areas, making frequency more difficult to interpret.

Diagnostics and Predictive Models

Diagnostic and therapeutic innovations are reducing the informational value of point-in-time measurements used at underwriting (such as BMI, blood glucose, and cholesterol), which on their own are no longer sufficient to represent risk. With the introduction of new therapies, the risk profile assessed at policy inception can change significantly over time: it may decrease rapidly in some cases, or increase, especially in the presence of treatment discontinuation.

Diagnostics and predictive models increase information asymmetry: insured individuals have better knowledge of their own risk than the insurer. Direct-to-consumer tests, such as genomic testing, may lead higher-risk individuals to insure themselves more (anti-selection) and at the same time make premiums less sustainable for these segments.

This is compounded by growing economic pressure: some innovative therapies have costs so high that they challenge the ability of traditional insurance models to absorb them.

Consistency Between Offering Model and Portfolio Impact

Finally, this shift introduces an issue of consistency between the offering model and technical sustainability, which already emerges at the level of portfolio analysis. If an increasing share of activity takes place in this intermediate phase and becomes reimbursable through formal classification as covered services, the risk is that part of the cost is already reflected in the loss ratio without being explicitly recognized as such. This can contribute to a gradual erosion of technical balance and make pricing more complex. For the insurer, the issue is not only whether to extend coverage, but whether the portfolio is already exposed to these dynamics without having been designed and governed accordingly.

This misalignment translates into a gap between the moment when need emerges and the activation of coverage: a space in which need is already clinically relevant but not yet insurable.

In this context, prevention takes on a different role. From an ancillary lever, it can become a point of activation of the insurance relationship along the healthcare pathway, intercepting needs that are not yet formalized. Its integration, however, introduces technical complexities. In particular:

  • the different time horizon between prevention and policy: economic benefits are distributed over multi-year periods and often exceed the contractual duration.
  • variability of engagement: effectiveness depends on the insured's adherence, often heterogeneous.
  • dispersion of economic return: ROI varies by condition, target population, and intensity.

In this context, the design of health coverage cannot ignore the point at which need emerges along the care trajectory, because it is in that phase that a growing share of costs is generated, often already present in the numbers but not explicitly recognized. The issue is not whether to intercept these needs, but whether the portfolio is already exposed to such dynamics without having been designed and governed accordingly. From this perspective, prevention services are not an extension of the offering, but a potential lever to manage frequency and usage dynamics that are already underway.


Paolo Meciani

Profile picture for user PaoloMeciani

Paolo Meciani

Paolo Meciani is a senior advisor in health insurance and digital health. 

He advises insurers, reinsurers, financial institutions, and health tech companies-from startups to scale-ups-as well as corporate players, on strategy, innovation, and the development of new health insurance models. He collaborates with academic institutions and government agencies and is involved in the insurtech ecosystem through industry associations and international networks. His work focuses on prevention, healthcare ecosystems, and the evolving role of insurance in health. He has over 25 years of experience across insurance, banking, and pharmaceutical sectors.

The End of Consulting as We Know It

AI is forcing consulting firms to guarantee outcomes instead of selling advice, a shift that could ultimately displace their clients.

Consulting

Let's be honest: Consulting—my trade for over two decades—has historically been a business of selling inputs while clients absorb the risk. Expertise, frameworks, transformation road maps, all cleanly packaged. Outcomes? Implied, not guaranteed.

AI is changing that, and fast. Insights are suddenly cheap, free even. Sophisticated technology skills are becoming commoditized.

Enterprise buyers are, understandably, thrilled. For the first time, they have the leverage to demand what they always wanted: not recommendations, not capability decks, but results. Measurable, contracted, financially enforced results. No more change theater. Actual change.

More control. Less risk. Pay for outcomes, not effort. What's not to like?

Here's what: The moment you demand outcomes, you force the people selling them to build machines that produce those outcomes, reliably, repeatedly, and at scale. And those machines don't just outperform bad consulting. Eventually, they may outperform you.

If we're being honest about consulting, let's be equally honest about enterprise inertia. Organizational drag, legacy processes, fragmented systems, incentives that reward preservation over performance. In some corners of the enterprise, inertia isn't a problem to solve; it's an asset to protect. Entire roles and hierarchies exist to navigate systems that no one has true incentives to fix.

Demanding guaranteed outcomes implicitly invites someone else to build a better version of your operation. Cleaner, faster, more instrumented, continuously improving, and unencumbered by your history.

Consulting firms that embrace this shift won't look like consultants for long. They'll look like operators running increasingly sophisticated, domain-specific machines, systems that improve with every client, every dataset, every cycle.

And when that machine exists, when it can process claims faster, manage revenue cycles more accurately, underwrite risk more profitably, the boardroom conversation changes. Not "should we take their advice?" but "why are we still doing this ourselves?"

Boardroom decisions will shift from sourcing to sovereignty as the definition of "core" narrows and operational borders shrink.

The consulting business has always been episodic, project to project, relationship to relationship. Promise to promise, you could say. But the model that let a thousand PowerPoint decks bloom while accountability stayed conveniently offshore is getting a reckoning. What's emerging is the opposite, and it has real teeth: firms that own problems, scale solutions, and compound returns with every engagement.

Selling recommendations is out, and delivering results is in. "Trusted advisor" either earns its keep or gets exposed as a title on a lanyard. The firms that win won't just be smarter. They'll be true operators, builders, partners with skin in the game, working alongside clients to eliminate the bureaucratic friction that everyone always knew was there and nobody had the incentive to touch.


Riv Arthur

Profile picture for user RivArthur

Riv Arthur

Riv Arthur is a business leader and technologist working in insurance, healthcare, and private equity.

Will AI Replace Insurance Brokers?

AI accelerates insurance workflows, but brokers remain essential as the translation layer between messy reality and carrier underwriting.

Brokers

The insurance industry keeps asking whether artificial intelligence will replace brokers. I think that is the wrong question. The better question is why does the market still need brokers in the first place?

I work with brokers every day across submissions, renewals, and placements. One thing becomes obvious very quickly: two similar risks rarely look identical to an underwriter.

Same operations. Similar exposures. Comparable loss history.

Yet one submission moves. The other stalls.

That difference is not always the risk itself.

It is how the risk is represented.

THE ROLE WE DON'T TALK ABOUT

The industry often describes brokers as intermediaries—connecting agent/clients to carriers, negotiating terms, and moving submissions through the process.

That description is not wrong. It is simply incomplete.

Brokers are the risk-representation layer of the insurance market.

They take something messy and real operations, exposures, controls, loss history, client explanations, incomplete documentation — and turn it into something a carrier can evaluate, price, and act on.

Carriers do not underwrite reality directly.

They underwrite representations of reality.

WHAT THIS LOOKS LIKE IN PRACTICE

We see it in everyday submission work. One account arrives clear, structured, and coherent. The exposure story is easy to follow. The loss history makes sense. If there were prior issues, they are explained with context: what happened, what changed, and why the account should now be viewed differently.

Another account may involve a very similar risk, but the submission feels fragmented. Details are missing. Insurable values do not fully line up. Losses are listed, but not explained. The story is not necessarily wrong, but it is not complete enough for the market to fully trust.

Both accounts go to market. They do not get treated the same.

Not because the underlying risk is always different, but because the representation of the risk is different.

And someone must bridge that gap. That someone is the broker.

WHY THIS LAYER EXISTS

If risk could be captured once, structured consistently, and reused across carriers and renewals, this layer would shrink. But that is not how the market works.

The same risk is re-described again and again. Information is re-entered, reformatted, and reinterpreted. Loss narratives shift depending on who prepares them. Each carrier may see a slightly different version of the same account.

Every submission becomes a reconstruction.

Brokers absorb that complexity. They align the client's reality with what each carrier needs to see. They fill gaps, reconcile inconsistencies, and shape the narrative so it is credible and complete.

That is not just intermediation. It is translation.

WHY AI HAS NOT REPLACED THIS

AI is already helping the industry move faster. It can extract data from documents, pre-fill applications, flag inconsistencies, summarize files, and support communication.

But speed is not the same as understanding.

If the underlying risk representation is incomplete, inconsistent, or poorly structured, AI simply processes that weakness faster. It may move the submission along, but it does not necessarily make the risk clearer, more credible, or more accurately understood.

That is the layer many technology conversations miss.

The problem is not only that insurance work is manual. The deeper problem is that risk information is often reconstructed from fragments every time it moves through the market.

"AI can improve the workflow around that problem, but it does not solve the problem itself"

THE REAL DIVIDE HAPPENING NOW

What is changing is not whether brokers matter, but which brokers matter.

Some brokers operate transactionally. They move documents, chase quotes, and respond to carrier requests as they come.

Others are much more deliberate about how risk is presented. Their submissions are structured. Their narratives are consistent across cycles. They understand how underwriters interpret information, and they build credibility through clarity, accuracy, and context.

The difference shows up quickly. As underwriting becomes more data-driven, the quality of what enters the system matters more, not less.

THE HIDDEN ASSET

The strongest agencies are not just relationship driven. They are consistent in how they present risk. When a well-prepared submission comes in, you can feel it. It is easier to understand, easier to trust, and easier to price. That does not happen by accident. It is built over time through disciplined data collection, clear documentation, and repeatable submission quality.

You could call this risk representation capital — the accumulated ability to present risk in a way the market can reliably interpret.

That kind of capital is becoming more important.

Not because brokers need to resist technology, but because technology makes weak representation more visible.

WHAT THIS MEANS

The future of brokerage will not be decided only by who adopts AI first. It will be decided by who controls the quality of risk representation.

Because that is what determines how risk is understood, how quickly it moves, and how confidently it is priced.

Until the insurance market has a stable, trusted way to represent risk across time, carriers, and renewals, brokers will remain essential.

"The broker of the future will not simply place risk. They will shape how the market understands it."

What Commercial Clients Ask Agents About AI

Commercial insurance clients now expect agents to articulate how AI strengthens account management, moving expectations beyond traditional placement.

City Scape

Commercial clients are starting to ask different questions. Not just about pricing, coverage, or market conditions—but about something newer: "How are you using AI on our account?"

Sometimes the question is direct. Other times, it shows up in a different way:

  • "Are we approaching this renewal differently?"
  • "Is there a better way to market this?"
  • "Are we using everything available to reduce our cost?"
WHERE THIS IS SHOWING UP

This shift is most visible in commercial accounts. When you're working on multimillion-dollar portfolios, builder's risk placements, construction liability programs, or cyber and professional liability coverage, clients expect more than just placement. They expect strategy.

They are not just buying insurance.

They are evaluating how their risk is being managed—and whether anything in that process is improving.

Behind the scenes, most commercial insurance work still follows a familiar path. Submissions are built through ACORD forms and supplemental applications. Exposure data is pulled from multiple sources—loss runs, schedules, prior policies, and internal systems. Builder's risk and construction accounts require detailed breakdowns of project values, timelines, and subcontractor exposure. Cyber and professional liability placements depend heavily on how controls, processes, and operations are described.

This work is complex and critical. But from the client's perspective, it often looks the same every year. The submission goes out. Quotes come back. The renewal is negotiated.

That's where the question about AI begins to surface.

WHAT CLIENTS ARE REALLY ASKING

Most clients are not asking for a technical explanation of AI. They are asking a simpler question: "Are we doing this in the best possible way?"

When a client managing a large commercial portfolio brings up AI, they are not asking about specific tools. They are asking whether:

  • their account is being marketed effectively
  • the data being presented is strong and complete
  • there is a better way to position their risk
  • anything is being left on the table

AI has become the language for that expectation. For many agents operating in traditional models, this is a difficult conversation—because the honest answer is still evolving.

Many agencies are beginning to use tools that improve parts of the workflow—extracting data from applications, organizing submission materials, tracking marketing activity, or improving internal coordination. But those improvements are not always visible to the client and they don't always translate into a clear explanation of how outcomes are changing.

So when the question comes—"How are you using AI?"—the answer can feel incomplete, even when meaningful work is happening behind the scenes.

WHAT THIS MEANS FOR COMMERCIAL AGENTS

Commercial agents don't need to have a perfect AI strategy to respond. But they do need to be ready for the conversation.

That means being able to explain, in practical terms:

  • how submissions are being strengthened
  • how data is being organized and presented
  • how the account is being marketed differently
  • and where experience still matters in interpreting risk

The agents who can do this clearly will stand out not because they are using the most advanced technology, but because they can connect what they are doing to real client value.

LOOKING AHEAD

This question is not going away. As commercial accounts become more complex and clients become more informed, expectations will continue to rise—not necessarily for more technology, but for better outcomes—and that changes the role of the agent.

The conversation is no longer just about coverage. It's about how the work itself is evolving.

The agents who can explain that—clearly and confidently—will define what comes next.

New Approach to Healthcare Cost Containment

Pre-payment claim evaluation led by human experts is redefining risk management as healthcare complexity and costs escalate.

Doctor Equipment

Risk management in healthcare is no longer defined after a claim is paid. The most important decisions are now made at the point of evaluation, before payment is issued. For years, cost containment has been treated as a back-end function focused on adjusting pricing after submission. That approach is no longer sufficient in a system where claim size and complexity continue to grow.

Today, financial performance is directly tied to how accurately a claim is evaluated upfront. Moving that decision earlier improves both the outcome and the level of control organizations have over cost. As claim costs and volumes continue to rise, this shift represents a fundamental change in how risk is managed, moving from reactive correction to proactive decision-making.

High Cost Claims Carry Greater Consequences

Healthcare spending continues to represent a growing share of the economy, and a large portion of that spending is concentrated in high-cost claims. These cases are not just larger in dollar value. They are more complex and difficult to interpret.

A single episode of care may involve multiple providers, different sites of service and separate billing practices. Each component may be coded and documented independently. When combined into one claim, the result can appear complete while still lacking internal consistency.

In these situations, even small discrepancies can have a significant financial impact. The margin for error becomes much smaller. As a result, these claims now represent a disproportionate share of financial risk for payers and self-insured organizations.

Understanding How Claims Are Built

To evaluate a high-cost claim correctly, it is not enough to look at the total charge. The structure of the claim must be understood. This includes how services were coded, how billing was organized across providers and whether the documentation supports what was submitted.

This level of review requires more than surface validation. It requires connecting the clinical story to the financial representation of that care. When those elements do not align, the risk of inaccuracy increases. Without this understanding, decisions are often based on incomplete information. That is where cost containment efforts begin to lose effectiveness.

Limitations Of Traditional Approaches

Traditional cost containment models focus on pricing adjustments after a claim has been submitted for payment. While this can reduce payment amounts in certain cases, it does not address how the claim was constructed.

Differences in coding, billing structure and service grouping can materially change the value of a claim. If those elements are not evaluated in context, the opportunity to correct inaccuracies is missed.

As claim complexity increases, relying solely on post payment adjustments introduces unnecessary risk and limits the ability to produce consistent financial outcomes. It also creates a cycle where errors are addressed after financial exposure has already occurred, rather than prevented.

Risk Emerges When Evaluation Is Incomplete

When claims are not fully evaluated before payment, organizations expose themselves to avoidable challenges. Disputes, appeals and compliance issues often stem from decisions that are not supported by a complete review of documentation and coding.

As claim values increase, the consequences of those decisions also escalate. Accuracy becomes essential and payment decisions must be defensible from both a clinical and financial perspective.

A reactive model makes that difficult to achieve. In contrast, a proactive model enables earlier intervention and stronger control over outcomes.

Moving Evaluation Earlier in the Process

The most effective way to improve outcomes is to evaluate claims before payment is made. Early review allows for a full assessment of how a claim was built and whether it accurately reflects the care delivered.

This includes validating coding, aligning billing across providers and confirming that documentation supports the charges. Addressing these factors before payment reduces uncertainty and strengthens the integrity of the decision.

In this model, cost containment becomes a process of determining accuracy rather than correcting errors after the fact. In practice, this shifts cost containment from a transactional activity to a strategic function within broader risk management.

The Role of Human Expertise

Technology plays an important role in modern claims management but it is not sufficient on its own. Automated tools can identify patterns and flag potential issues but they do not interpret clinical nuance or reconcile complex relationships within a claim.

That level of evaluation requires human expertise. Professionals with clinical, coding and financial knowledge and experience bring the judgment needed to assess claims in context. They understand how services should be documented, how codes should be applied and how different components of care connect.

This perspective is critical in high-cost cases where the details matter. It is this human-led interpretation that ultimately determines whether a claim is accurate, appropriate and financially sound.

Stronger Financial Outcomes Through Better Evaluation

When claims are evaluated early and with the right expertise, financial results improve measurably. Overpayments are reduced because inaccuracies are identified before payment. Savings become more consistent because they are based upon validated discrepancies rather than broad adjustments.

Equally important, outcomes become more predictable. Decisions are grounded in documentation and supported by a clear rationale. This reduces variability and strengthens confidence in the process.

Cost containment, in this context, becomes a driver of performance rather than a corrective measure. It also supports more sustainable financial outcomes by reducing volatility and improving long-term cost predictability. At scale, this level of consistency contributes to more stable plan performance and reduced overall risk exposure.

A More Effective Model for Risk Management

Risk management is evolving to meet the demands of a more complex healthcare environment. A proactive approach that combines early evaluation, human expertise and targeted use of technology provides a more reliable framework.

Automation supports efficiency and scale. Human review ensures accuracy and context. Together, they create a balanced model that addresses both cost and risk.

Organizations that adopt this approach are better positioned to manage large and complex claims while maintaining financial discipline. This model reflects a broader shift toward more accountable, transparent and outcome-driven risk management strategies.

Healthcare claims will continue to increase in size and complexity. Managing that reality requires more than adjusting payments after submission. It requires getting the evaluation right from the start. A proactive, human-led approach to cost containment shifts the focus to accuracy before payment. In doing so, it strengthens financial outcomes and redefines how risk is managed in today's healthcare landscape.

For insurers, TPAs and self-insured employers, this approach offers a clearer path to controlling costs while improving the integrity of the claims process. It also provides a more effective framework for managing financial risk in an increasingly complex and high-cost healthcare environment.


Bruce Roffé

Profile picture for user BruceRoffé

Bruce Roffé

Bruce D. Roffé, P.D., M.S., H.I.A., is the president and CEO of H.H.C Group, a healthcare consulting firm he founded in 1995. He has over 40 years of experience in healthcare cost management and pharmacy, 

DEMO: Clearspeed

Clearspeed analyzes voice in a unique way to deliver a better customer experience while streamlining costs and reducing fraud.

Clearspeed Logo


 Watch Our Demo: 

Learn More

Are you interested in learning more about Clearspeed and about this product?  Please visit these sites to learn more:

Why We Are the Right Solution For Your Needs

Insurance runs on trust, but most systems still treat every decision like it needs the same level of rigor. That slows down policyholders, adds drag to the process, and spreads teams thin across situations that were never going to be a problem. Clearspeed changes that with a real-time risk indicator that helps insurers move faster, improve the customer experience, and protect the book.

Three Main Benefits of the Product: 
  • The genuine majority clears faster at any point in the lifecycle, with less friction and a process that feels fair.
  • Your operation keeps moving, whatever the volume.
  • Every policyholder gets the same automated questionnaire, assessed the same way, regardless of claim size.
What Part(s) of the Insurance Industry Can Benefit From Our Product: 
  • Claims
  • Underwriting
  • Life & Health
  • Worker's Comp

Clearspeed

Profile picture for user Clearspeed

Clearspeed

 Clearspeed is the global leader in voice-based risk assessment. Its proprietary voice analytics technology detects the level of risk in a person’s voice based on vocal characteristics universal to all humans—enabling faster, more confident decisions in high-stakes environments. Initially developed for the U.S. Department of Defense, Clearspeed quickly exposes indicators of risk for government and military agencies. Commercially, it helps insurers, financial institutions, and other enterprises assess risks like fraud and insider threats, unlock operational savings, and elevate the customer experience. 

Headquartered in San Diego, Clearspeed is used in 37 countries and supports over 60 languages. More at www.clearspeed.com.

First, AI Slop. Now, 'AI Beige.'

AI slop is just weird. "AI beige" is more insidious because it can deceive you into thinking you're smart when you're just being bland. 

Image
wavy lines

Ever since the word "content" began to be used as a generic description of all the video, audio and writing that people like me do, I've not-so-quietly seethed about the leveling that word connotes. Nobody sets out to write the Great American Content. Authors aspire to write the Great American Novel. I don't write Six Things so I can email some "content" to you. I try to provide some perspective, some useful insight. 

"Content" springs to mind because generative AI sure is producing a lot of it, and much of it is as bad as the word suggests. To this point, the concern has mostly been about AI slop--slapdash writing and oddly formed images. But there's another, more insidious type of material that AI is producing: what I think of as "AI beige." 

It's not as clearly off as those pictures where a stray bit of an arm is floating in midair or a hand has six fingers. The problem is that you can easily convince yourself that your AI is generating smart visuals and writing, when it's actually producing a forgettable beige that leaves you at a competitive disadvantage.

I'll explain.

My realization about the danger of AI beige began when my older daughter wrote an article for Quartz about what AI claimed it could do for online dating. She wrote:

"Generative everything — bios, prompts, openers — risks pushing profiles toward a smooth, samey median, making it harder to tell whether you like someone or just their autocomplete. Profile refiners can make dating apps worse by sanding off the idiosyncrasies that signal real, human compatibility....

"What happens when two people send each other messages with a chatbot?

"Do the chatbots fall in love?"

More recently, EY produced a report that explained what it called "the sameness trap." EY wrote about conducting an exercise hundreds of times across the globe, in which people used AI to develop a brand image. Everybody seemed to find the exercise fun and inspiring, and "each team believed it had created something novel, [but].collectively they had created the same thing."

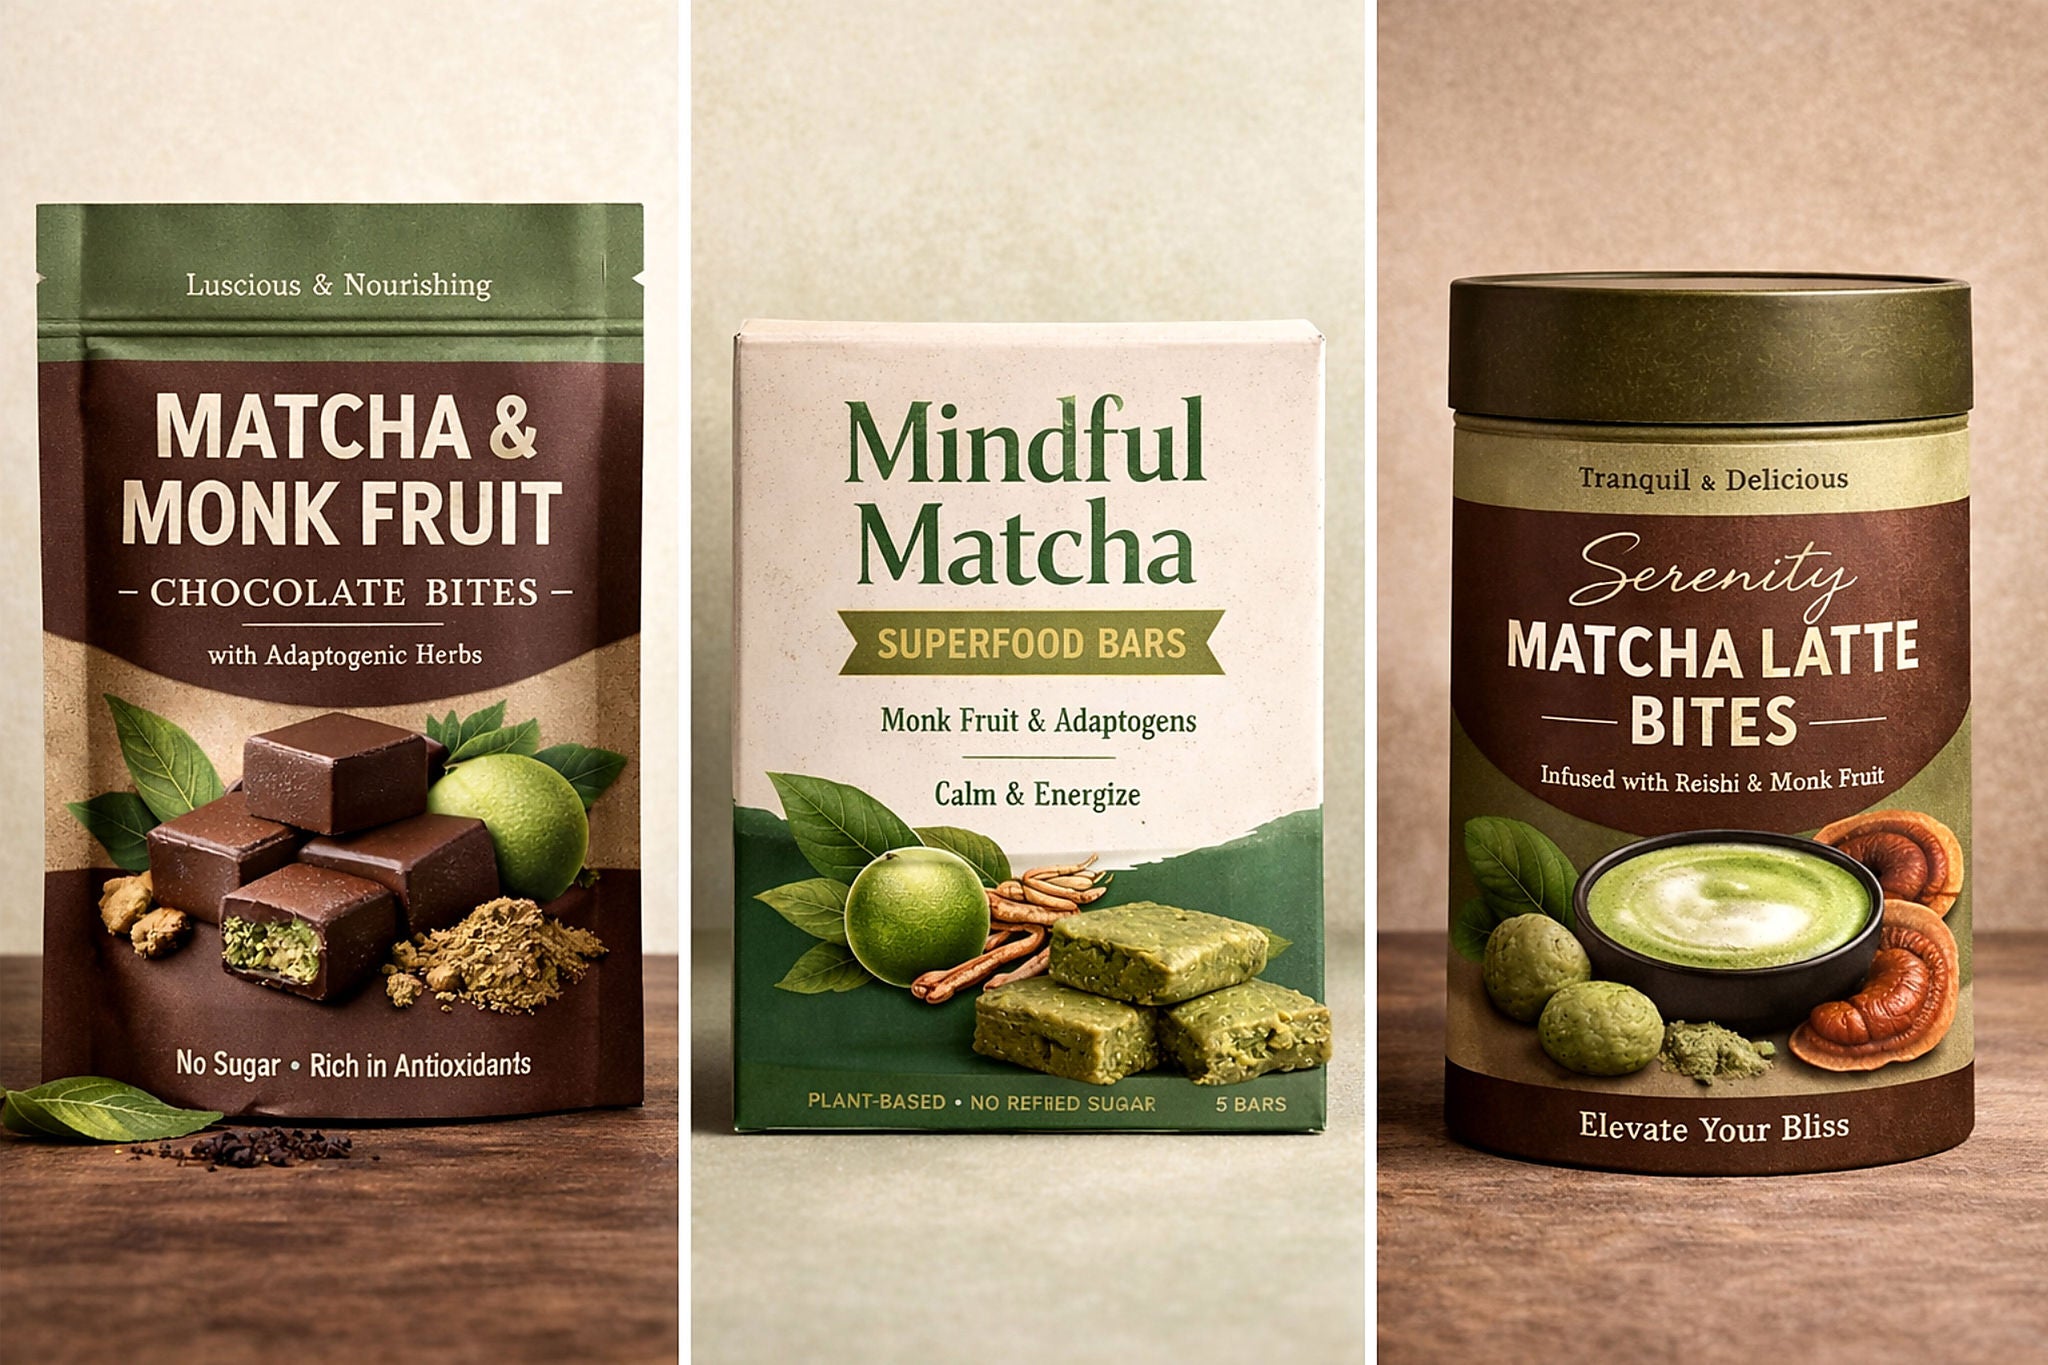
Assorted matcha snack packages including chocolate bites, bars, and matcha latte bites.

Imagine doing all the work to go to market with one of those brands and finding the other two on the shelf right next to you. Differentiation is out the window.

AI will often produce results like that, because the models work in the same way, drawing on the same data (having all basically Hoovered up everything on the internet) and trying to develop the same best practices. 

AI can still be plenty useful and help with creativity, but you have to use it right. You won't get a Think Different or Just Do It slogan if you ask an AI to narrow in on a recommendation, but you might get something that starts you toward a very different, innovative sort of brand if you ask the AI to get a bit wild, or even very wild. You'd have to brainstorm from there and have the humans take over, but the AI can help broaden the range of ideas you consider.

EY suggests putting AI at the end of the process. Don't let the AI "speak" first on a topic, because it carries a high-tech cachet that makes it come across as the smartest in the room, and people become reluctant to voice ideas once the oracle has spoken. EY says to frame AI in an adversarial position:

"AI brings the patterns and the data of what has already happened. The human takes that intelligence and forms a position. Then we ask AI to challenge it. Tell us what we’re missing. Generate the counterfactual. The argument we haven’t considered. What would someone who disagreed with us say that isn’t in here?"

In either case —at the front end or the back end — you want to be aware that your competitors are using AI, too, and are probably being steered in the same direction you are. 

It's common for businesses to pay too little attention to what others are doing. Long before AI became a factor, every computer company started telling me in the 1980s that "We don't sell boxes; we sell solutions." In the 1990s, every startup began its presentation to me by showing a PowerPoint slide that read, "We have the best people." And so on.

In some parts of the business, insurers don't need to worry about having their AIs produce differentiated results. With communications with customers, for instance, if you come across as concerned and professional, the customer isn't going to call up your email and figure out how it compares with a competitor's on the same topic. So having an AI guide you toward best practices is fine, however beige they might be.

But when it comes to branding, sales pitches and strategy, you need to be sure to Think Different.

Just Do It.

Cheers,

Paul