Download

FOMO Is Becoming Insurance's Biggest AI Risk

Insurers are rushing to adopt generative AI without clear strategies, turning competitive pressure into costly pilots that rarely reach production.

AI FOMO Drives Insurance Industry Strategy Problem

The insurance sector is, understandably, quite risk-averse. Insurance companies don't endure and thrive by taking unnecessary risks in an environment defined by stringent regulation and nuanced decision-making. This is why it is so concerning to see companies within the sector taking unnecessary risks as they face up to the mounting pressure of demonstrating progress with generative AI.

It's easy enough to understand the urgency behind the industry-wide scramble to leverage new tools like autonomous agents and AI-powered applications. AI isn't new to the insurance business — use cases revolving around risk modeling and data forecasting were becoming commonplace in the sector before the deep learning and LLM boom in 2023. However, those technologies took years to find a place in insurers' technology stacks. They were heavily tested with strong, clear use cases. The race to adopt generative AI tools is not the same.

EIOPA's 2024 Digitalisation report found that 50% of non-life insurers and 24% of life insurers were already using AI in various areas of the insurance value chain, with applications including pricing and underwriting, fraud detection, and claims management. When it works, it really works. Research from McKinsey found that the insurance sector's AI leaders have created 6.1 times the total shareholder return compared with AI laggards. That figure doesn't just make the case for adopting AI. It makes the case that, if generative tools can be successfully integrated with insurers' tech stacks, the results are outstanding. McKinsey's report found that, in other sectors, AI leaders were generating at most two to three times the shareholder return.

Across the insurance space, there is an increasingly common fear that everyone else is somehow ahead. Companies see their competitors announce new AI pilots and products, vendors make new promises of transformative AI tools, and employees are already experimenting with agents and chatbots. No one wants to be caught standing still while the rest of the market races ahead.

The result is a growing wave of AI FOMO. Insurers are launching pilots, funding multimillion-dollar integration plans, and generally jamming AI into any perceived gap in their workflows. The problem is, many are doing this before interrogating and identifying where AI will actually create any meaningful impact for their business.

The dangers of putting AI before the business case

Last year, a study from MIT found that 95% of AI pilot projects "failed to deliver any discernible financial savings or uplift in profits," the data from which supports an earlier report released by Capgemini in 2023 that found 88% of AI pilots never reached production.

A more recent report from Simplifai found that, while 99% of insurers now have some form of generative AI in place and 83% of carriers are spending more than £3.75 million every year on tokens, subscriptions, and infrastructure, just 42% of insurers had taken the next step towards actually deploying AI into active business functions.

There is an undeniable appetite in the insurance sector for AI, but not a great deal of understanding when it comes to what the technology can do, or where it fits within existing business systems (not to mention the tech stack, which for an insurer is more likely to be some form of legacy system). This issue presents symptomatically as an abundance of AI pilot programmes that never mature into real world business solutions. Insurers know they need to act on AI, but they don't have a clear idea of where to start, which processes to prioritise, or how to evidence the value it creates.

How insurers can distinguish AI opportunity from AI hype

This raises an important question for insurers: what will it take to shift AI from isolated innovation projects to something with tangible business applications?

Scaling AI effectively can lead to substantial business value — the data supports it — but for insurers mired in expensive pilot programmes that never seem to translate into finished products, or who feel as though they're in danger of being left behind, it's essential to approach AI from a business perspective, not a technological one.

Successful AI adoption in insurance might just mean embracing more of the risk averse, methodical behavior for which the sector is sometimes criticized. It means making informed decisions regarding where AI can create real, sustainable impact. Success depends on identifying the use cases with the strongest commercial and productivity outcomes, rather than increasing the volume of AI initiatives in hope of reaching a magical, unspecified tipping point.

Insurance industry-specific AI tools are accessible across the market, doing away with any competitive advantage gained by adopting a particular platform or model. As access to the technology becomes more uniform, competitive differentiation will depend upon how organisations apply it. Successful approaches start with workflows, operating models, and business outcomes. They deploy AI across complete business processes instead of isolated point solutions and establish governance from the outset so that risk, compliance, and accountability are embedded throughout implementation.

The insurance industry doesn't have an AI problem. It has a strategy problem. FOMO is pushing insurers into suboptimal decisions, when the real challenge lies in executing a coherent transformation strategy. The next phase of insurance AI adoption won't be about buying and using more AI. It will be about making better decisions about where AI belongs.

World Cup Shows Insurers How to Avoid a Red Card

Amid a hugely successful World Cup tournament, Argentina demonstrated how actions by a few bad actors can chase away millions of fans (or customers).

Image
WC

A World Cup soccer tournament wouldn't be a World Cup without controversies, and the just-concluded event had its share. 

Then Argentina said, Hold my Fernet con Cola. 

Following the team's 1-0 loss in the finals to a clearly superior Spanish team, an Argentine player picked a fight on the field that included grabbing a Spanish player by the throat and throwing him to the ground, and Argentine teammates backed him up. Just about the whole Argentine team then acted churlish during the awards ceremony, even turning their backs as the Spanish players were awarded their gold medals and the team trophy. 

Within minutes, reporters and fans were revisiting every untoward thing Argentina had done during the tournament, then during prior tournaments, then on the team bus, then.... 

Argentina provides a great example of how actions taken even by a few in the heat of the moment can sour masses of people on a group or a brand. It's a lesson that I think insurers, in particular, should take to heart, given that our most consequential actions tend to come when dealing with people in situations where their emotions are running hot. 

Let's have a look. 

Argentina had been a possible feel-good story coming into the tournament this year. It had finally won the World Cup in 2022 for its captain, all-time great Lionel Messi. If Argentina had repeated as champion, it would have been the first to do so since Brazil in 1962. Messi, who had won the Golden Ball award in 2022, given to the best player in the tournament, was in the running for the award again. Going into the final, he also had a shot at the Golden Boot, given to the top scorer in the World Cup. At 39 years old, a beloved player was putting in a remarkable performance.

Now, Argentina is known for being chippy, even dirty, and it played to form throughout the tournament, including by having a player sent off in the final after a violent tackle. Spain, while hardly free of fouls, played a classic style that contrasted sharply with Argentina and led any number of people to post at the conclusion of the game some variant of, "Football won today." 

The history of writeups about the Argentine team suggests that would have been about the extent of the complaints about Argentina's tactics. 

Then the Argentine players started knocking around some of the Spaniards after the final whistle, and all bets were off. 

Someone quickly shared a clip of the Argentine player instigating the post-game brawl. Then people started going back through the whole game, pointing out everything even borderline that Argentine players did — here is one-such 13-minute clip. But why stop there? Here is a 5 1/2-minute clip of transgressions by Argentina that weren't penalized in the semifinal against England. Of course, there was group play, too — here is nine minutes of uncalled fouls against Switzerland. 

Earlier incidents became fair game, as well. A video surfaced in 2024 of Enzo Gonzalez, the Argentine player who drew a red card in the final, and teammates chanting racist slurs on the team bus, as posts such as this one quickly noted over the weekend. Gonzalez had apologized profusely, including personally to Black players on his club team, and surely thought the incident was behind him. No longer. Many on social media also noted that the Spanish goalkeeper had been classy in accepting the Golden Glove award, for the best at his position in this year's tournament, while the Argentine keeper had used the award to make an obscene gesture when he won in 2022.

Analysts were universally brutal about Argentina after the final. The New York Times ran a story under the headline, "Argentina disgraced themselves, and the World Cup final, with their charmless petulance." In case that wasn't enough, the NYT ran another story, full of images, under the headline, "How Argentina turned the World Cup final dirty with shoves, skulduggery and squealing."

My point being: Once sentiment turns against you, even based on an incident by one person or a small group, things can go downhill fast — and keep going.  

This surely isn't news to insurance companies, which understand that claims are the moment of truth. Everyone and everything has to line up just right when you're dealing with longstanding, loyal customers in their moment of need. They've earned compassionate, professional excellence — and they'll react in horror if they don't get it. 

But I still think object lessons like those provided by Argentina are worth noting and spreading, because it only takes a few people, or even a single person, to undercut what so many other people are doing to earn loyalty. Social media can broadcast bad actions incredibly fast these days and seems to relish doing so, especially if there is compelling video. 

And narratives are hard to shake once they take hold. The Argentine team is being cooked especially hard because it was already known as a dirty team. In insurance, if you're not known for great customer service, complaints will find an especially alert audience — I'm sure State Farm, for instance, is being incredibly careful these days, given the controversy over its handling of claims from last year's wildfires in California.

I won't suggest buying the jersey of Leandro Paredes, the Argentine player who ran up on a Spanish player from behind after the game and knocked him over, because some of the money would find its way back to him. But maybe he can be an anti-hero for anyone dealing with insurance customers. Whatever you do, people, don't earn us a reputation like that guy....

Cheers,

Paul

P.S. When I think back on the World Cup, I'll prefer to think about the positive surprises. Who knew that Costco and ranch dressing would be such delights for those visiting the U.S.? Erling Haaland? I've spent years hating on him in a Man City kit but found him impossibly charming both in a Norway jersey and in his experience with U.S. culture. Then there was Spanish star Lamine Yamal's three-year-old brother, Keyne, who stole every scene he was in throughout the tournament. 

And I'll especially cherish a moment that Jude Bellingham and Bukayo Saka and their English team had in their third-place game against the French. 

When England earned a penalty kick, Bellingham prepared to take it. He had emerged as a full-on star for England and had already scored six goals; seven would be unworldly. But he knew that Saka had scored twice against France, knew that concerns about injury had (unwisely, in my view) kept Saka out of the semifinal that England lost against Argentina, and may have been thinking about how Saka and two Black teammates had missed penalty kicks in a tournament in 2021 and had endured wildly racist criticism. 

Bellingham told Saka, "Go on and get your hat trick," and handed him the ball. Saka converted with a kick that the keeper wouldn't have touched even if he had guessed right, rather than diving in the opposite direction. Saka's goal turned out to be the winner. 

Bellingham, by the way, got his seventh goal a few minutes later with an extraordinary display of technical virtuosity. So nice guys finish.... first?

Becoming a Frontier Insurer

Explore how Frontier Insurers use AI, GenAI, and Agentic AI to lead on competitiveness, cost structure, and growth in the intelligent era.

Frontier Insurer

AI has moved past the hype stage—it's reshaping cost structures, competitiveness, and growth across insurance. Carriers who hesitate are locking in cost and risk profiles that only get harder to unwind. Drawing on original research with insurance executives, this report shows how AI, GenAI, and Agentic AI are separating Leaders from Followers and Laggards—and why 2026 is the point of no return.

AI is now a boardroom priority, tied to insurers' top 2026 goals: cutting costs, streamlining operations, and improving customer experience. Across underwriting, claims, servicing, billing, distribution, and loss control, carriers are moving from talk to active pilots, targeting friction in paperwork-heavy areas like claims and service. But appetite is outpacing the data foundation needed to support it, raising scalability and reliability risks without stronger governance.

The center of gravity is shifting from "AI as a data tool" to "AI as a workforce multiplier," powered by the Frontier Firm—companies built on on-demand intelligence and human-agent teams, where staff act as "agent bosses." Leaders are already scaling GenAI and Agentic AI with mature data capabilities behind them; laggards risk losing ground on performance and cost.

Download this report to explore:

  • Why modernized data and an Intelligent Core are essential for scalable, responsible AI
  • How to bring the Frontier Firm and Agent Boss models into your organization
  • How AI is reshaping cost, competitiveness, and growth across the insurance value chain


Get Started>>


Sponsored by Majesco


ITL Partner: Majesco

Profile picture for user majescopartner

ITL Partner: Majesco

Majesco isn’t just riding the AI wave — we’re leading it across the P&C, L&AH, and Pension & Retirement markets. Born in the cloud and built with an AI-native vision, we’ve reimagined the insurance and pension core as an intelligent platform that enables insurers and retirement providers to move faster, see farther, and operate smarter. As leaders in intelligent SaaS, we embed AI and Agentic AI across our portfolio of core, underwriting, loss control, distribution, digital, and pension & retirement administration solutions — empowering customers with real-time insights, optimized operations, and measurable business outcomes.


Everything we build is designed to strip away complexity so our clients can focus on what matters most: delivering exceptional products, experiences, and long-term financial security for policyholders and plan participants. In a world of constant change, our native-cloud SaaS platform gives insurers, MGAs, and pension & retirement providers the agility to adapt to evolving risk, regulation, and market expectations, modernize operating models, and accelerate innovation at scale. With 1,400+ implementations and more than 375 customers worldwide, Majesco is the AI-native solution trusted to power the future of insurance and pension & retirement. Break free from the past and build what’s next at www.majesco.com


Additional Resources

The Second Half of Agentic AI

Read More

The Insurance Alignment Gap: Where Insurer Priorities and Customer Protection Needs Converge…and Diverge

Read More

Operational Value and Impact of GenAI and Agentic AI

Read More

Reimagining Insurance for a More Resilient Future

Read More

State of Core Solutions Transition: Which Tech Priorities Are Being Carried Out?

Read More

Making AI Work in Commercial Submission Intake

Insurers need a practical blueprint for where to apply AI first, how to move beyond pilots, and how to scale the technology responsibly.

Making AI Work in Commercial Submission Intake

The industry no longer doubts whether AI benefits submission intake in commercial property and casualty (P&C) lines. Recent AI rollouts by Zurich, AIG, Markel, and other market leaders show impressive gains come very quickly: intake timelines for complex submissions compress from hours to minutes, straight-through processing (STP) rates increase from 10% to 95%, underwriter productivity grows by 100%+, and submit-to-bind ratios improve by 35%.

Yet many P&C carriers are still figuring out how to make AI work for their business. Which parts of their submission intake workflow can realistically be automated? Where to start so that we can move out of pilots fast? How can we explain, audit, monitor, and defend what the AI did? And what AI solution design should we actually pursue to scale well?

These are the questions I hear most often in ScienceSoft's engagements with commercial P&C clients. In this article, I'll share my perspective on where AI works best in submission intake today, why many initiatives never move beyond pilots, and what insurers should focus on if they want to launch submission intake AI over the next six to 12 months.

Where AI Delivers the Fastest Value in Submission Intake

From my experience, the quickest wins come from automating the parts of insurance submission intake that are high-volume, repetitive, document-intensive, and largely governed by business rules. Strong starting points in commercial P&C include:

  • Capturing and classifying submissions.
  • Extracting data from ACORD forms, loss runs, schedules of values, and other submission documents.
  • Checking submissions for completeness and identifying missing information.
  • Summarizing and triaging risks for underwriters.
  • Prefilling policy administration and underwriting systems.
  • Drafting underwriting files and follow-up questions for brokers.

These activities create a large operational workload but require little underwriting judgment, which makes them ideal candidates for AI automation. Modern AI systems can handle these connected intake operations almost entirely, only involving humans in complex cases. In this first half of the intake pipeline, STP rates of 90–95% are a realistic target.

They are also the safest processes to automate from both a business and regulatory perspective. In each case, AI prepares data and doesn't touch high-impact decision-making.

AI Benefits Submission Intake

Anything involving decision-making is a different story. Commercial P&C underwriting is rarely standardized. It often requires negotiation, exceptions, and collaborative expert judgment, with every submission carrying its own nuances. Most of the cases are just too complex for reliable straight-through AI decision-making.

That doesn't mean AI has no role here. It can absolutely assist in eligibility assessment, pricing, and coverage decisions — for example, by highlighting relevant risk factors, surfacing similar cases, or recommending next steps — but I'd keep it away from making those decisions autonomously. Human experts should continue to own the final judgment.

Moreover, even when AI acts only as an assistant, the governance bar remains high. You need mature controls, explainability, and human oversight to defend AI suggestions to brokers, policyholders, auditors, and regulators. That's why I usually recommend that clients avoid complex assistive use cases during early AI deployments. A safer path is to first confirm AI accuracy, auditability, and workflow impact across lower-risk data intake tasks, then gradually scale into underwriting decision-support areas.

Overall, I don't think anything close to fully autonomous underwriting should be the near-term objective for commercial P&C insurers. The "AI assists, humans decide" approach, where AI prepares files and experienced underwriters make the final decisions, has proven the most practical operating model. It lets insurers preserve human accountability where it matters most while still delivering huge business returns. I recently came across a case study where deploying AI for submission intake routines alone brought a 646% ROI for a large property carrier through faster, more accurate, and more efficient data processing.

Data Foundations for AI-Powered Submission Intake

First of all, you can effectively start with whatever data you have. That's an important point because I've seen many insurers unnecessarily delay AI initiatives out of fear that their existing data is too scarce or too low-quality for AI processing.

The first necessary data foundation you need in commercial submission intake is a clear document taxonomy. However strong AI may be at data tasks, it still struggles with unstructured, consequential data containing insurance-specific terminology and context. One classic example is loss runs: they vary by provider. Claim descriptions often contain abbreviations. Severity indicators may be buried in narrative text. The AI may read the document correctly but fail to determine what's material from an underwriting perspective.

A clear taxonomy creates enough structure around the data so AI can distinguish between document types and apply the right extraction logic, validation rules, and review requirements to each. It also helps determine which documents AI should treat as authoritative when data conflicts across sources.

What Might Keep AI Stuck in Pilot Mode, And How You Avoid It

By far the biggest blocker is AI integration into existing submission intake workflows.

Most commercial P&C insurers operate heavily fragmented environments. Documents sit in one place, policy data in another, rating logic somewhere else, and underwriting notes in spreadsheets or workbenches. People have built manual workarounds over the years because their legacy core systems do not support the connected workflow.

Making AI work with these core systems doesn't mean you need to modernize or replace all of them. But you do need a practical integration pattern to avoid building numerous point connections. Off-the-shelf AI architectures often hit a wall at this point: most mass-market tools, by design, introduce AI as another isolated interface sitting alongside the existing process. AI product vendors can't possibly account for every system or data format their clients may still be using to build a product that integrates well with legacy stacks.

Another blocker is what I call "pilot thinking." During pilots, people often focus too much on proving that the AI model can accurately classify, extract, summarize, and answer questions. That's necessary, but it's only one part of the equation. Moving to production requires proving that the AI can operate reliably inside a real insurance workflow: integrate with existing systems, handle exceptions, support human review, produce audit evidence, and scale across thousands of submissions. That's where many otherwise successful pilots stall.

The goal of a pilot should be validating not just AI accuracy but rather the operating model around the AI. Can the workflow route low-confidence cases for review? Can underwriters easily verify and override AI outputs? Can the solution recover from missing or conflicting information? Can it integrate with core systems without creating manual workarounds? Those capabilities determine whether the AI can become part of daily operations.

The third blocker is poor ownership models. Someone has to review AI performance, define business rules, validate compliance, and measure outcomes. When ownership is unclear, issues randomly fall between teams. The technology may work, but if nobody takes responsibility for adoption, governance, and continuing improvement, your promising AI initiative may quickly lose momentum after the pilot stage.

You'll need a board of AI governance owners from underwriting, IT, data or AI engineering, and compliance or risk before moving beyond the pilot. The board should regularly review AI performance, override rates, exceptions, user feedback, and regulatory risks, and decide when the solution is mature enough to expand into new workflows or business lines.

Addressing AI Risks That Insurers Often Underestimate

A lot of insurers immediately think about AI hallucinations, and that's a real risk.

To address that risk, the AI reasoning should be grounded in source documents, and the system must show where each important field or summary statement came from. Adding deterministic validation of AI outputs after each processing iteration also helps prevent error creep. These are rule-based checks that verify required fields are present, figures are consistent, references match the source documents, and the output complies with predefined business rules before the workflow continues.

Yet, in commercial P&C submission intake, I think one of the most overlooked risks is silent workflow bias.

By that, I mean AI may not be making the final underwriting decision, but it may still influence which submissions move faster, which are routed to senior underwriters, which are treated as gapped, and which receive follow-up. Those workflow decisions can create different outcomes over time, even if the model never explicitly uses protected-class data.

Another risk is silent portfolio drift. The process gets faster, productivity looks better, and everyone is happy. But over time, the mix of business may change. Maybe more borderline risks get through because the process feels smoother. Maybe underwriters stop asking certain follow-up questions because the AI-produced summary looks complete. None of this looks like a major failure on day one, but it shows up later as leakage, adverse selection, and portfolio quality issues.

The way to manage this is through continuing outcome monitoring. During pre-launch tests, compare AI-assisted cases versus manually processed ones to establish execution benchmarks. After rollout, monitor trends in quote-to-bind rates, referral rates, missing-data rates, post-bind corrections, override rates, and downstream loss performance. Also regularly sample fast-tracked cases for expert review and ask underwriters: would we have handled the submission the same way without AI? The goal is to detect when AI begins influencing portfolio quality in unintended ways.

Regulatory compliance is a known source of risk, and it requires governance from the start. In the US, regulators increasingly look beyond underwriting outcomes and examine whether AI affected submission routing, triaging, eligibility assessment, and broker interactions. The NAIC Model Bulletin on AI, adopted by 24 states and the District of Columbia, calls for controls against AI discrimination. New York, California, and Connecticut have issued their own AI guidance for insurers. You need explainable AI logic, audit trails, mandatory human reviews for high-impact decisions, and evidence that you regularly monitor for bias and drift to withstand regulatory scrutiny.

An Actual AI Solution for Commercial P&C Submission Intake

In an end-to-end commercial submission intake scenario, we would be looking at a multi-agent system coordinated by an orchestrator. We need specialized AI agents to perform different tasks: one classifies incoming documents, another extracts and validates data, the third drafts broker follow-up requests, and so on.

ScienceSoft prefers this pattern because submission processing involves many distinct activities with different accuracy requirements, permissions, and risk profiles. An input classification agent doesn't need access to the same data as a risk file preparation agent. An agent responsible for drafting emails shouldn't be reasoning on eligibility. Separating responsibilities reduces the blast radius of errors and makes governance much simpler.

And then, the orchestrator acts as a control layer of the agentic workflow. Unlike narrow agents, it doesn't perform submission-intake tasks itself. Its only job is to coordinate how work moves between AI agents, business rules, systems, and people. It decides which agent should act next, applies predefined routing rules, manages confidence thresholds, sends exceptions to human reviewers, and maintains an audit trail across the entire process. Think of orchestration as an AI traffic controller. Without it, you have just a set of AI capabilities.

Must-Haves of a Production-Ready AI Architecture

Three engineering principles separate a production-ready agentic AI system from a one-off pilot: decoupling AI from core insurance systems, implementing a multi-level AI authorization model, and building agents in a modular way.

Avoiding tight coupling between the AI workflow and the insurer's existing systems is essential for interoperability. Otherwise, adding AI would require rework across existing systems, and even small changes to those systems would trigger changes to AI-supported operations. In an ideal setup, the orchestrator and AI agents act as a back-end operational layer between your current systems without replacing them or requiring expansion. A layered architecture with a dedicated agentic layer and an integration layer sitting between the AI workflow and other insurance systems works well for that.

Layered Architecture for P&C

Consider applying event-driven integration patterns, where business events (think submission arrival or document upload) automatically trigger the next AI task. This keeps workflows synchronized across multiple systems without creating tightly coupled point-to-point integrations and allows AI to react immediately as an event occurs, making submission intake faster. Another major advantage is easier integration with legacy systems. Older apps that don't support APIs can often participate in the workflow by sending or receiving event messages, removing the need for custom integrations.

One more practical move is to expose the integration layer through a single gateway. This way, you don't need to integrate every AI agent separately with your existing systems and get a single place to capture audit logs. This approach simplifies integration across fragmented environments and supports a consistent audit trail required for compliance. It also minimizes integration maintenance overhead: if you later change your core platforms, the AI integration contracts remain stable.

The second principle is multi-level AI authorization. This approach aims to limit AI autonomy where business and regulatory risks are high while maximizing overall automation. We typically use three authorization levels. The first level allows fully automated actions for low-risk tasks like document classification or completeness checks, provided the AI outputs pass predefined deterministic checks. The second allows AI recommendations but requires human approval before execution, for example, when drafting broker follow-ups or preparing underwriting summaries. The third covers decisions that may affect eligibility, pricing, or other material underwriting outcomes. Here, AI prepares the supporting analysis and data, but humans remain the decision-makers.

You also need the system to log every action, including inputs, outputs, agent actions, source references, validations, and underwriter overrides. With this complete log, you can explain how decisions were reached, trace outputs back to evidence, review AI behavior long after a submission pack is processed, and prove regulatory-aligned controls during audits.

The third principle is modular agent design. With a modular architecture, each agent is built as an independent component. Such a design lets you add, improve, and replace task-specific agents without redesigning the whole system. This means you can first deploy agents for only a few processing tasks, one product, or one submission channel, prove accuracy and adoption, and then expand. That ability to scale gradually lets you start your AI journey with moderate upfront investment and with minimal implementation risk. If you're ready for a broader rollout from the outset, the modular architecture still makes the solution easier to maintain and evolve as business needs change.

The same modularity also allows you to use the best-performing and cheapest technology for each agent. For example, agents that assess eligibility and summarize risks benefit from the reasoning capabilities of large language models (LLMs). Implementing them with tailored retrieval-augmented generation (RAG) pipelines ensures outputs are grounded in actual submission documents. For document classification and entity extraction agents, fine-tuned encoder models trained on a fixed set of documents typically deliver very high accuracy at a fraction of the cost of LLMs. Plus, these models do not generate anything, so there's no hallucination risk at early intake steps.

Contributing to this article were: Vadim Belski, head of AI, principal architect, ScienceSoft, and Stacy Dubovik, financial technology & AI researcher, ScienceSoft.

How AI Search Changes Insurance Marketing

A new decision layer is forming above the traditional sales funnel. Traditional measures of effectiveness no longer matter. 

AI Visibility Decouples from Insurance Market Share

For decades, the math governing property and casualty insurance distribution was straightforward: premium scale translated into market share, and heavy marketing budgets translated into digital reach. A carrier that dominated search results, television, and agent awareness could reliably occupy the top of the customer-acquisition funnel.

A new decision layer is now forming above that funnel. Buyers, agents, brokers, and business owners increasingly ask AI platforms to compare carriers, explain coverage, and recommend providers. Those systems do not return 10 blue links. They assemble a short, synthesized answer.

That distinction matters. A carrier can remain commercially large, rank well in traditional search, and still be absent when an AI system constructs the shortlist. Its legacy presence has not disappeared—but it can be bypassed at the moment of consideration.

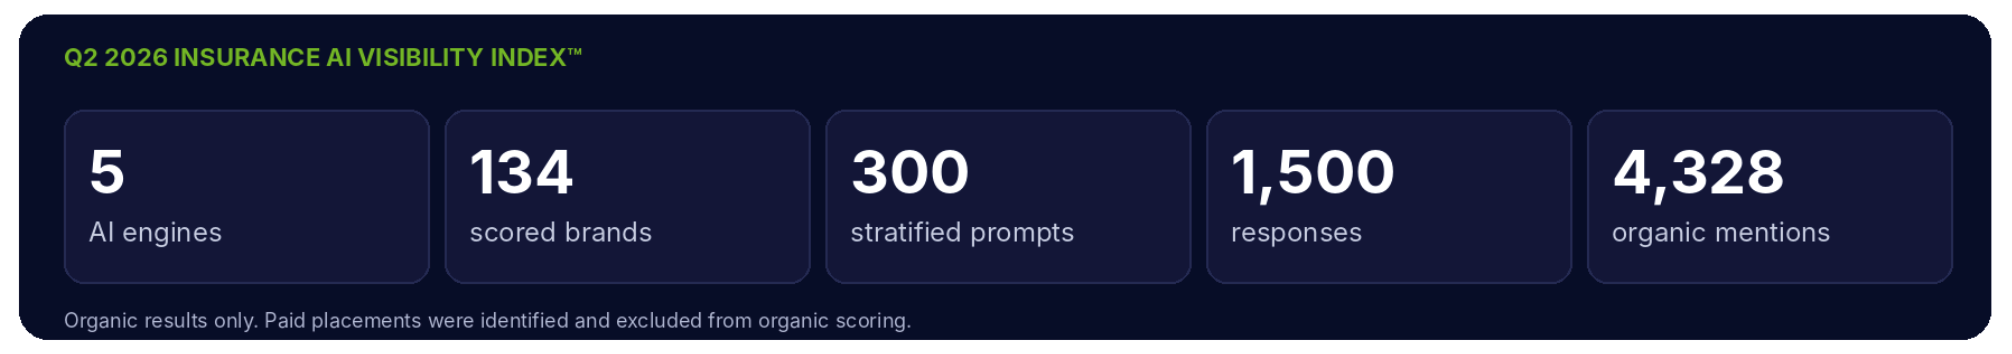
To measure this emerging risk, Brainpan.AI's Q2 2026 Insurance AI Visibility Index™ tracked 137 insurance brands and scored 134 with sufficient measured data. The study tested 300 stratified prompts across ChatGPT, Gemini, Claude, Perplexity, and Copilot, producing 1,500 responses and 4,328 organic brand mentions. The benchmark measures whether brands are retrieved, placed prominently, recommended, and supported with visible evidence; it is not a ranking of carrier quality, financial strength, or customer value.


Q2 2026 Insurance AI Visibility
The Market-Share Illusion

The study's most commercially provocative finding is the decoupling between real-world market share and visibility inside AI-generated answers. Premium share remains an essential measure of commercial scale. It is not, however, a reliable proxy for AI mindshare.

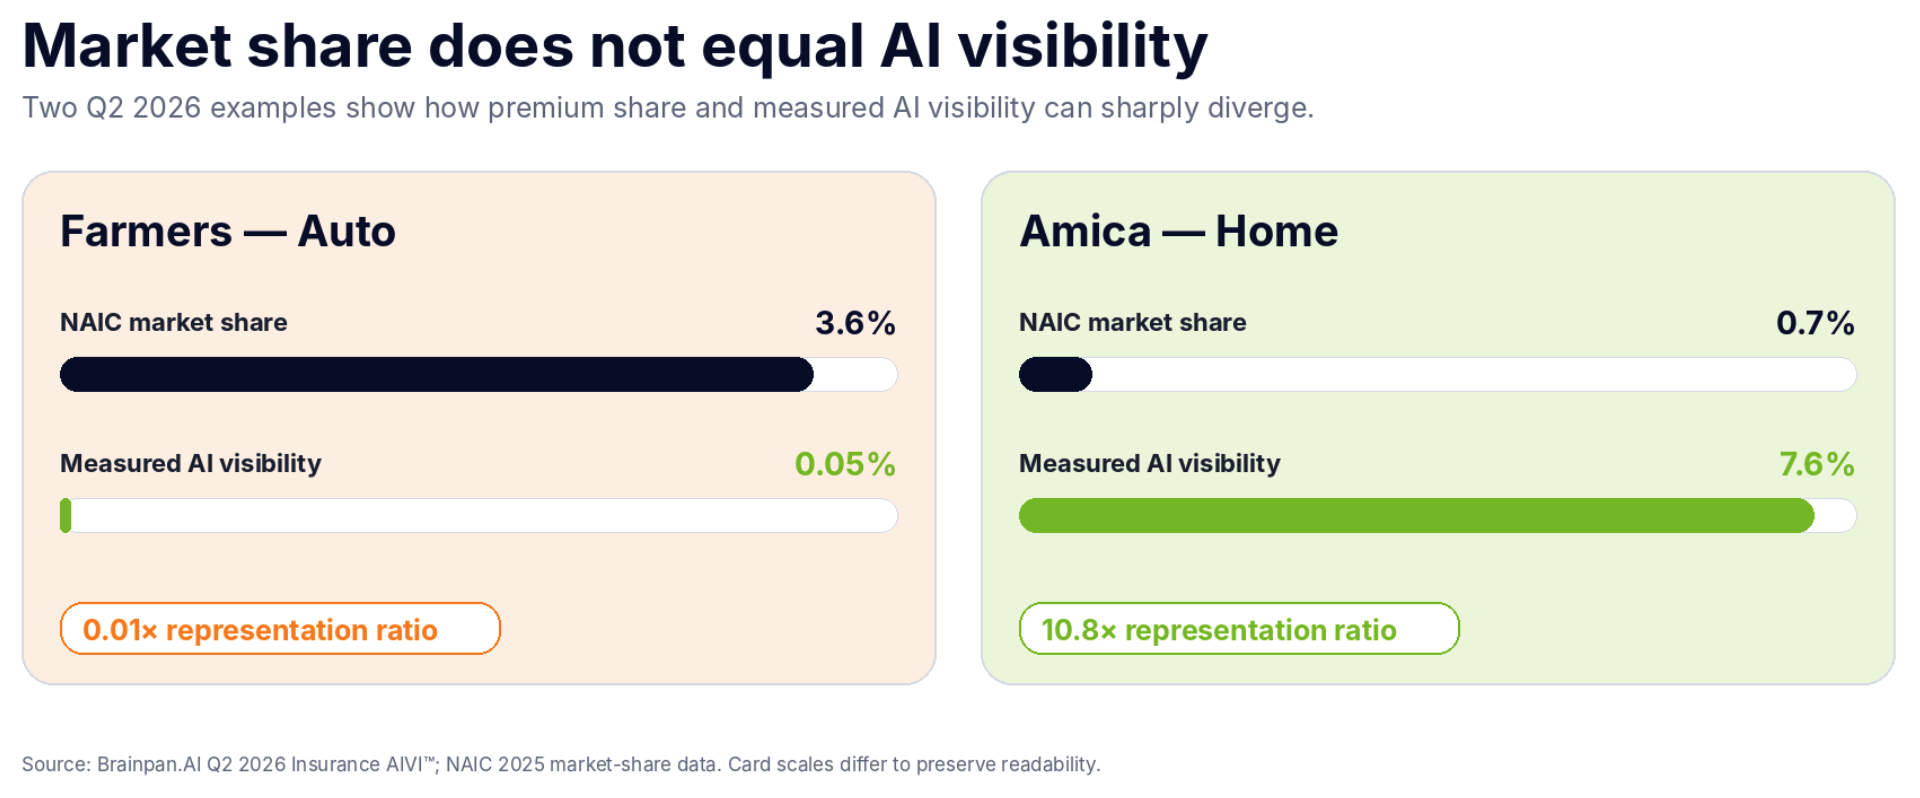
Farmers illustrates the downside. In Auto, the carrier held roughly 3.6% of the real market, according to NAIC data, yet registered approximately 0.05% of measured AI visibility in the study—functionally absent relative to its commercial position. Amica illustrates the opposite pattern. Its Home AI visibility reached 7.6% against approximately 0.7% real market share, an overrepresentation ratio of about 10.8 times.

These examples do not prove that AI visibility causes premium growth or policy conversion. They establish something more immediate: market scale and machine visibility are now separate competitive assets. A carrier may lead one and trail badly in the other.

Market Share

Figure 1. Real-world market share and measured AI visibility can diverge sharply. Farmers is severely underrepresented in Auto, while Amica is substantially overrepresented in Home.

Visibility Is Not One Metric

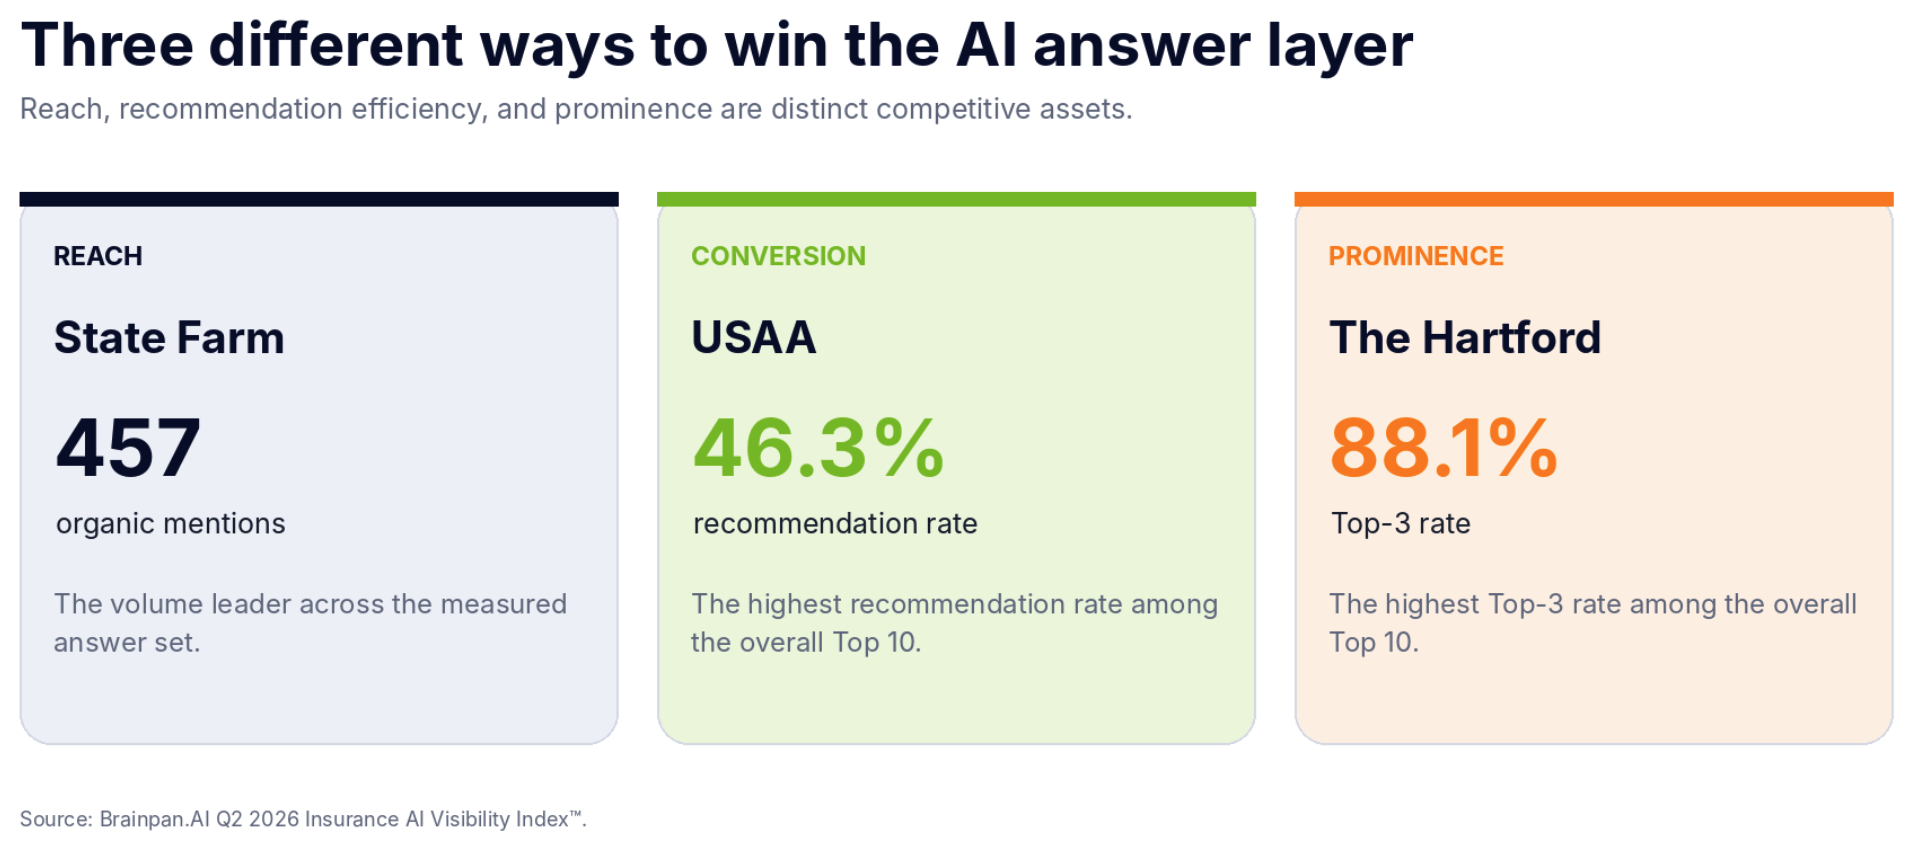
The benchmark also shows why a single mention count is insufficient. AI visibility has at least three distinct dimensions: reach, recommendation efficiency, and prominence.

State Farm led the study on reach, with 457 organic mentions. USAA appeared less often, but recorded a 46% recommendation rate—the highest among the overall Top 10 brands. The Hartford was the prominence outlier: although it ranked eighth in total organic mention volume, 88% of its appearances landed in the Top 3, the highest Top-3 rate among the overall Top 10.

These are different advantages. State Farm owns more of the answer layer. USAA converts a larger share of appearances into genuine recommendations. The Hartford is surfaced near the top when it appears. A carrier's reporting should separate all three rather than collapsing them into a single traffic or visibility number.

AI Answer Layer

Figure 2. Reach, recommendation efficiency, and prominence describe different forms of competitive strength inside AI-generated answers.

Two Operational Drivers Leaders Should Examine

The benchmark measures outcomes, not the complete causal chain behind them. It nevertheless points to two operational areas that carriers should examine closely.

1. Machine-readable corporate and distribution information

This is not merely an IT plumbing issue. It is a distribution issue. Product availability, underwriting appetite, geographic eligibility, claims capabilities, and partner information are often fragmented across PDFs, portals, state pages, and loosely connected web content.

When public information is inconsistent or difficult to interpret, an AI system has less reliable material from which to construct an answer. Carriers should therefore audit whether their public-facing product and appetite information is explicit, current, consistently named, and easy for both humans and machines to retrieve.

2. Independent authority—not citation volume alone

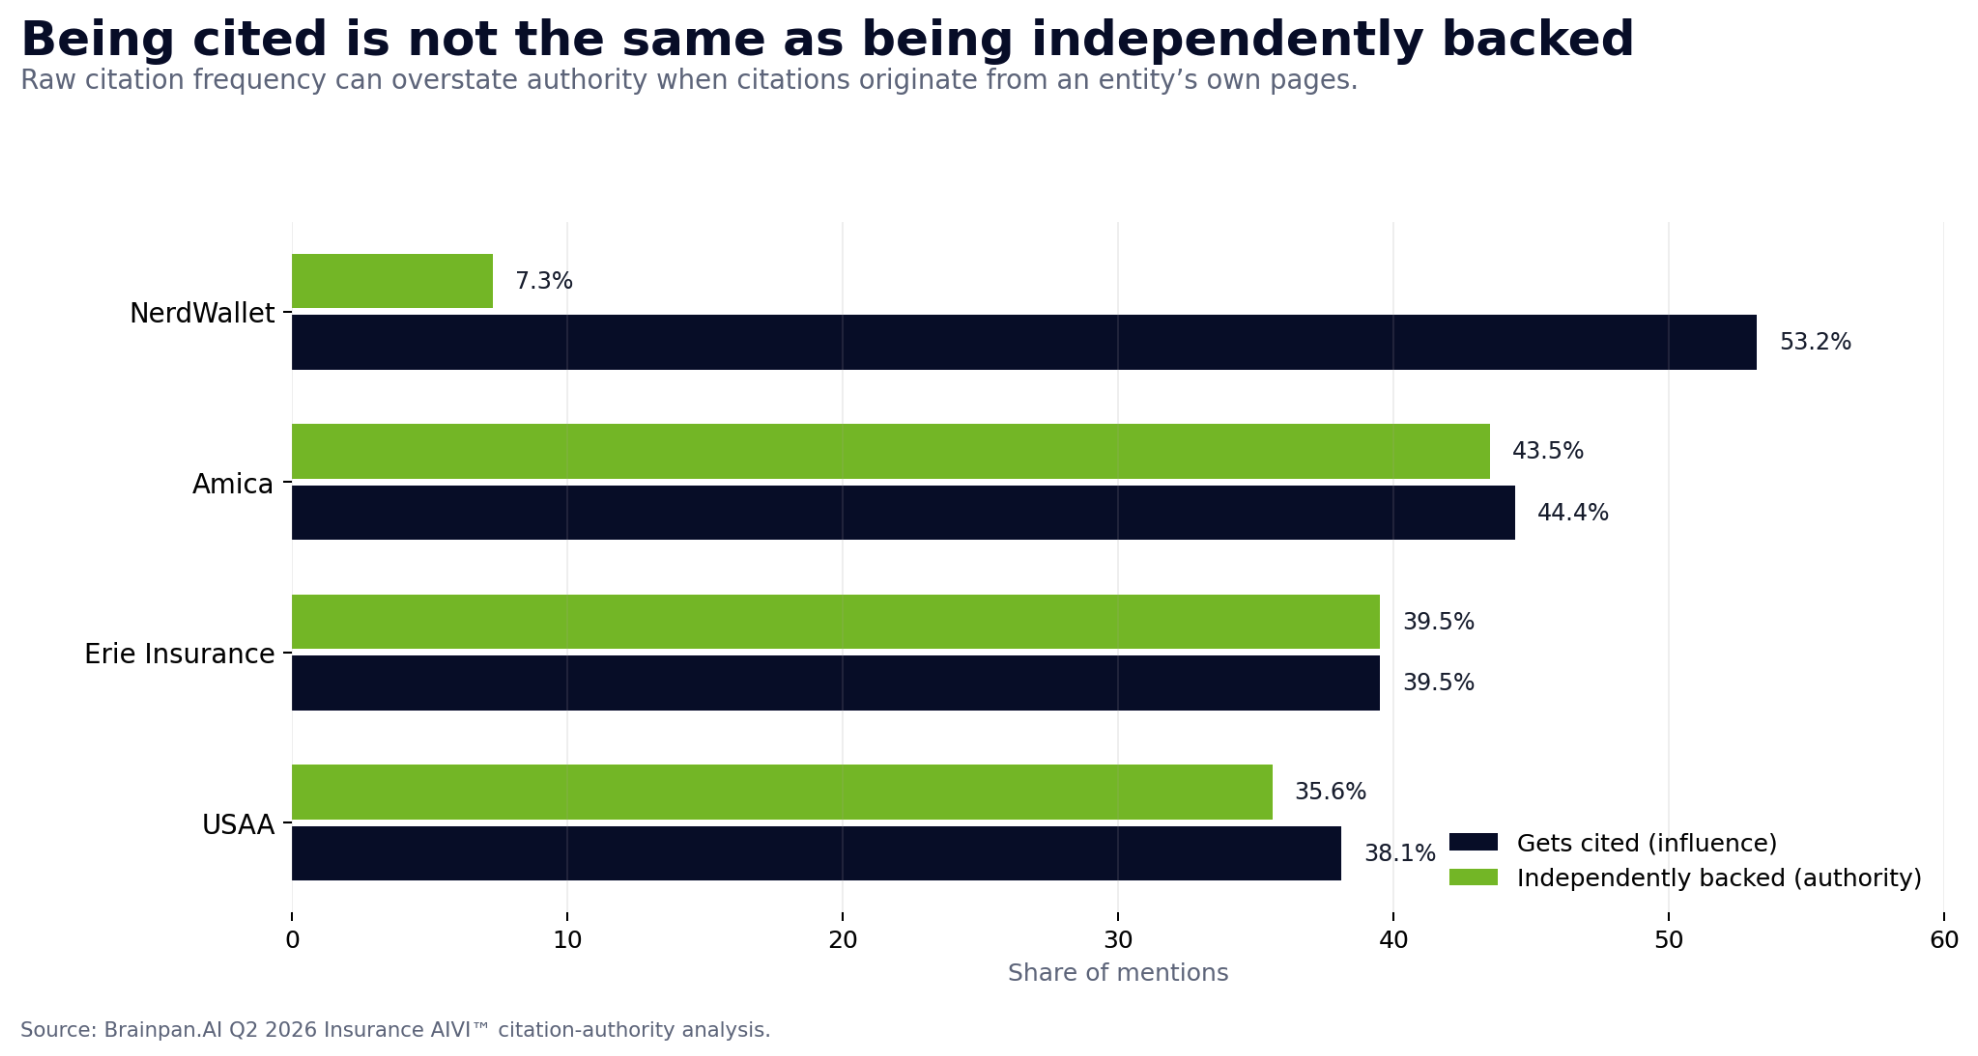
The study also separates citation influence—how often an entity receives a visible citation—from independent authority, or how often that supporting evidence comes from a genuine third party rather than the entity's own domain.

That distinction can materially change the interpretation. NerdWallet received visible citations in 53% of its mentions, but only 7.3% of its mentions were independently backed after self-citation was removed. Several carriers showed the opposite pattern: lower raw citation frequency, but much stronger independent backing when they were cited.

The implication is not that owned content is unimportant. It is that raw citation counts can create false confidence. Carrier PR, regulatory references, independent analysis, authoritative industry media, and consistent third-party descriptions now form part of the evidence environment from which AI systems assemble answers.

Cited

Figure 3. Citation influence and independent authority are not interchangeable. A high citation rate may still be driven largely by self-originated evidence.

The Monday-Morning Executive Checklist

AI visibility should not be delegated solely to the web or SEO team. It sits at the intersection of distribution, brand, product, communications, data governance, and customer acquisition. Three questions can quickly reveal whether a carrier is measuring the new risk:

  • "Are we measuring our Share of Model against core competitors—or still relying only on traffic and click-through metrics?" A conventional dashboard cannot show whether a carrier is retrieved, recommended, or placed near the top of an AI-generated answer. Measurement should separate reach, recommendation, prominence, citation influence, and performance by engine and product line.
  • "Is our public-facing underwriting appetite and product information explicitly formatted for machine consumption?" Making distribution information accessible to human agents is no longer sufficient. Public content should use consistent entities, clear eligibility language, current product definitions, and structured relationships that answer systems can reliably interpret.
  • "What is our strategy for building independent digital authority?" Owned content remains necessary, but it is not enough. Carriers need a deliberate evidence strategy across regulatory sources, respected industry publications, analyst coverage, partner ecosystems, and other credible third-party environments.
A New Competitive Layer

AI answer engines are not replacing every existing channel. They are adding a new layer to insurance discovery and consideration—one that can reshape which carriers enter the shortlist before a prospect visits a website, contacts an agent, or begins a quote.

Scale will remain an asset in property and casualty insurance. But scale must now be translated into machine-legible product information, visible recommendation strength, and independently supported authority. The carriers that win this layer will not simply be the ones with the largest balance sheets. They will be the ones whose expertise, appetite, and credibility are legible to the systems assembling the decision set.

Research note: The Brainpan.AI Insurance AIVI is an organic-only benchmark. Paid placements were identified and excluded from organic scoring. The composite weights Share of Model at 35%, recommendation strength at 25%, position weighting at 20%, citation influence at 15%, and Top-3 rate at 5%. Results represent a controlled Q2 2026 prompt sample and should be interpreted as a visibility benchmark, not as proof of revenue, quote, CAC, or policy impact.

Smart Glasses Transform Insurance Claims, Inspections

Smart glasses are standardizing insurance inspections through real-time documentation and AI-guided workflows that improve transparency and reduce claim processing delays.

Transform Insurance Claims and Inspections

One of the greatest challenges facing insurers is making sure that every claim is documented consistently, regardless of who is performing the inspection or where it takes place. Smart glasses offer a clear path to standardizing this process by relaying information, guidance, and documentation tools directly within the wearer's field of view.

Rather than relying solely on handwritten notes, memory, or photos taken after an inspection, smart glasses enable adjusters and field representatives to capture POV evidence in real time while following predefined inspection workflows. Step-by-step prompts, often oral, help ensure that required photographs, measurements, and observations are collected in the same order and according to the same standards across every inspection.

The result is greater transparency for insurers, policyholders, and auditors alike. Claims files become more complete, inspection procedures become more repeatable, and documentation is captured as events occur rather than reconstructed later. This not only improves confidence in claim decisions but also creates a stronger evidentiary record should questions arise later in the claims process.

As AI capabilities continue to mature, AI smart glasses can also assist by identifying missing documentation, recognizing objects or damage patterns, and helping ensure that inspections meet established company guidelines before they are submitted.

Is it possible that AI-enabled remote assessments can reduce the need for adjusters to travel on-site? If so, could this help lower costs or improve overall response times?

In many situations, yes. While some claims will always require an experienced adjuster to visit a site in person, smart glasses make it increasingly practical to conduct guided remote assessments for a wide range of property, vehicle, and equipment claims.

Using a live video connection, a policyholder, contractor, or local representative wearing smart glasses can share a first-person view with an adjuster located anywhere in the country. The adjuster can observe conditions in real time, ask questions, request additional views, and guide the inspection without the delays associated with scheduling travel.

This approach offers several advantages. It can significantly reduce travel time and associated costs, accelerate response following widespread events such as severe storms or natural disasters, and allow experienced adjusters to assist more customers each day. It also improves access to expertise in secure, remote, or difficult-to-reach locations where specialized personnel may not be immediately available.

Faster assessments often translate into faster claims decisions, helping policyholders begin repairs sooner while enabling insurers to manage resources more efficiently during periods of high claim volume.

Can smart glasses better provide guidance to policyholders when resolving claims or billing issues?

Smart glasses have the potential to transform customer interactions from reactive conversations into guided experiences.

Rather than describing damage over the phone or attempting to follow written instructions, policyholders can receive visual guidance while completing important tasks. AI-generated prompts or remote experts can direct them to photograph specific areas, locate serial numbers, inspect equipment safely, or verify documentation without leaving the inspection process.

This guidance helps reduce misunderstandings while making the experience less stressful for customers who may be navigating an insurance claim for the first time.

The same capabilities can extend beyond claims. Customer service representatives may use smart glasses during virtual support sessions to help policyholders understand equipment, review billing questions, or verify information required to resolve an issue more efficiently. By providing contextual information directly within the user's field of view, smart glasses make complex interactions easier to complete while reducing the need for repeated follow-up calls.

How can smart glasses create a more consistent experience to guide policyholders through the documentation process when building claims?

Incomplete documentation remains one of the most common reasons claims require additional review or follow-up. While wearing smart glasses, users can be guided through a structured documentation process from beginning to end.

Instead of expecting policyholders to determine which photos to take or which details are important, the system can provide step-by-step instructions tailored to the type of claim being filed. Users can be prompted to capture specific rooms, damaged assets, identification numbers, receipts, or supporting evidence before moving to the next step.

Because the guidance is delivered in real time, the likelihood of missing critical information is significantly reduced. AI can also identify gaps in the documentation, recognize whether required images have been captured, and recommend additional photos when necessary.

For insurers, this creates a more standardized claims package regardless of who submits it. For customers, it reduces uncertainty and increases confidence that the necessary information has been provided the first time, helping claims move through the review process more quickly.

What's the hidden benefit of the insurance industry beginning to adopt smart glasses, and why is it happening now?

The most significant benefit may not be the technology itself—it is the ability to capture data and make it available anywhere.

Insurance organizations face continuing challenges associated with workforce transitions, increasing claim complexity, and rising customer expectations. Smart glasses enable experienced adjusters to extend their knowledge beyond physical travel by supporting multiple inspections remotely, mentoring less experienced personnel, and guiding policyholders through complex situations from virtually any location.

At the same time, artificial intelligence is making these systems increasingly valuable. AI can assist with documentation, recognize objects and damage, summarize inspections, retrieve policy information, and provide contextual recommendations without interrupting the inspection process. Together, AI and smart glasses create a powerful platform that augments human expertise rather than replacing it.

For the insurance industry, the opportunity extends beyond operational efficiency. Smart glasses have the potential to improve consistency, strengthen documentation, reduce unnecessary travel, accelerate claims resolution, and deliver a more transparent and supportive experience for policyholders. As insurers continue to seek ways to improve both customer satisfaction and operational performance, AI smart glasses are emerging as a practical technology capable of advancing both objectives simultaneously.

With so many smart glasses flooding the market, which is the right choice for insurers?

Not all smart glasses are designed for the same purpose. While consumer AI glasses like Ray-Ban Stories, Virtue, and Xreal have generated significant attention for features like voice assistants, messaging, and media capture, insurance organizations require a very different set of capabilities. Claims assessments, inspections, and customer interactions demand devices that are built for reliability, security, and extended professional use.

Enterprise smart glasses, such as the Vuzix M400, are specifically engineered for these environments. They offer extended-wear battery life, hands-free operation, high-quality cameras, and displays that remain visible in a wide range of lighting conditions. Just as importantly, they integrate with enterprise software platforms, support secure device management, and can be deployed and updated across large organizations.

For insurance professionals, this means adjusters can access claims information, inspection checklists, policy details, and remote expert assistance without interrupting their workflow or reaching for another device. Enterprise platforms also support compliance requirements through encrypted communications, secure authentication, and centralized IT management—capabilities that are often essential when handling sensitive customer information.

Durability is another important consideration. Field adjusters routinely work in challenging environments, including construction sites, disaster areas, industrial facilities, and severe weather conditions. Enterprise smart glasses are designed to withstand these demanding settings while delivering consistent performance throughout a full workday.

Perhaps the most important distinction is purpose. Consumer smart glasses are primarily designed to enhance everyday personal experiences, while enterprise smart glasses are built to improve business processes. In insurance, success depends on accurate documentation, standardized inspections, secure data handling, and efficient collaboration between policyholders, adjusters, and remote experts. Enterprise smart glasses are purpose-built to support those objectives.

As AI capabilities continue to evolve, the most valuable deployments in insurance will likely combine enterprise-grade hardware with intelligent software that assists users in documenting claims, identifying missing information, guiding inspections, and connecting field personnel with subject matter experts. Choosing a platform designed for professional workflows ensures insurers can take advantage of these innovations while meeting the security, reliability, and scalability requirements of the modern enterprise.


Matt Margolis

Profile picture for user MattMargolis

Matt Margolis

Matt Margolis is VP of business development and strategic relationships at Vuzix. 

Prior to Vuzix, he spent more than 15 years in corporate finance in a variety of roles. 

He holds a bachelor of science degree in business administration from Babson College.

R&W Insurance Deserves a Closer Look

Representations and warranties insurance offers block reinsurance buyers and sellers faster closings, cleaner exits and stronger protection at reasonable cost.

R&W Insurance Gains

In the world of mergers and acquisitions, representations and warranties (R&W) insurance has become a near-standard tool for managing transactional risk. Buyers and sellers across industries routinely use these policies to bridge gaps in negotiation, allocate liability, and move deals to the finish line with greater confidence.

Yet in the reinsurance sector, specifically within large and complex block transactions, R&W insurance has been conspicuously absent from the conversation. As one transactional attorney puts it, a block reinsurance deal is functionally "like an asset deal but in the insurance space."

It's a missed opportunity, leaving significant value on the table for both ceding insurers and reinsurers.

A Tool That Has Been Hiding in Plain Sight

Block reinsurance transactions carry a unique set of risks. Whether the deal involves a loss portfolio transfer, a full novation of policy liabilities or a multibillion-dollar block of long-dated, asset intensive life or annuity liabilities, both the ceding company and the assuming reinsurer must navigate a unique set of representations about the underlying book of business. Such matters can be further complicated if the block reinsurance transaction also provides for a transfer of a policy administration platform to the reinsurer, thus requiring additional representations about the platform. These representations typically cover the accuracy of financial statements, methodology for computing reserves, the validity of policy data, regulatory compliance, and a host of other material facts that inform the economics of the deal.

For a ceding insurer, a fundamental motivation for entering a block deal is to achieve certainty and finality. That goal is undermined when the cedant is saddled with long-tail indemnity obligations post-closing. This is precisely the friction point R&W insurance is designed to solve. It allows the ceding insurer to achieve a 'clean exit' with no significant post-closing obligations with respect to inaccurate R&Ws (outside of fraud) while the assuming reinsurer receives meaningful financial protection.

Despite this complexity, R&W insurance has traditionally not been a feature of block transactions, historically relying instead on traditional risk allocation mechanisms. These alternatives, however, have significant downsides:

  • A cedant indemnity can lead to protracted and contentious negotiations over the drafting of R&Ws and the size and survival period of the indemnity itself. This not only delays closing but can sour the post-closing relationship if a claim arises. Post-closing relationships are particularly important in reinsurance transactions where, even though the economics of the block are being transferred, the parties will remain tied together for the duration of the block of business.
  • Self-insuring the risk leaves the reinsurer holding all the exposure for losses from a breach, an atypical and often undesirable position.

The gap in R&W adoption has been fueled by a perception that reinsurance deals are lower risk or that R&W policies were not designed for their nuances. However, these views overlook the primary benefit: superior deal efficiency and a cleaner allocation of risk for all parties.

Speed, Simplicity and Reasonable Cost

For those involved in block transactions, the practical benefits of R&W insurance are compelling and worth serious consideration.

One of the most attractive features is the speed at which coverage can be bound. Block transactions often operate on tight timelines, particularly when they are driven by regulatory deadlines, fiscal year-end targets, or strategic portfolio management objectives. R&W policies can typically be bound in a matter of weeks, and in some cases even faster, once the underwriting process is underway. This timeline aligns well with the pace at which many deals need to close.

Beyond speed, R&W insurance can simplify the negotiation process between the parties. In any transaction, the allocation of risk around representations and warranties can become one of the most contentious and time-consuming points of discussion. The ceding company wants to limit its post-closing exposure, while the assuming reinsurer wants robust protections in case the underlying information relied upon when entering into the transaction turns out to be different from what was represented.

When an R&W policy is in place, much of that friction is removed. The policy effectively backstops the representations, giving the assuming reinsurer confidence that it has recourse in the event of a breach, while simultaneously allowing the ceding company to reduce or eliminate its indemnity obligations. The result is a cleaner, faster negotiation with fewer sticking points.

While major indemnity claims are infrequent, industry data shows that roughly 20% of R&W policies have claims submitted. This suggests that buyers are more willing or able (e.g., because a broader suite of representations are made) to seek recourse from an insurer than from a counterparty, making the protection more practical. In this context, that means preserving the commercial relationship between the cedant and reinsurer, turning a potential dispute into an unemotional claim against the R&W insurer with minimal adverse impact on the parties' continuing relationship.

Cost is another consideration that often surprises parties who are new to the product. Premiums for R&W insurance in the current market are reasonable and generally in line with what organizations pay for other financial and transactional insurance products. For example, in a block deal with a $500 million ceding commission, a customary 15% policy limit ($75 million) would cost approximately $2.25 million - $3 million in premium (i.e., a 3 - 4% rate-on-line).

There is also an important qualitative benefit that is easy to overlook. The presence of R&W insurance can signal to both parties that the transaction has been conducted with a high degree of diligence and good faith. The underwriting process for an R&W policy involves a thorough review of the deal's representations, the underlying data, and the due diligence that has been performed. This independent layer of scrutiny can increase all parties' confidence in the integrity of the transaction.

Placing the Policy: What to Expect

Mechanically, crafting an R&W policy for a block deal is very similar to a standard M&A transaction. The underwriting process involves the vetting of the reinsurer's due diligence. Although there may be less detailed third-party due diligence reports on reinsurance transactions than on corporate M&A, so long as appropriate levels of due diligence are conducted in light of the scope of the representations and warranties being insured, fulsome coverage will be available.

However, there are unique aspects to consider. For example, certain representations around actuarial data accuracy are notoriously difficult to insure. Insurers are not in the business of guaranteeing reserves. Therefore, the "specified data rep" will be heavily scrutinized and may be knowledge qualified or excluded depending on the specifics of the transaction and supporting diligence information and sufficiency of reserves is likely to be excluded from coverage. An experienced broker and legal advisor can help navigate these nuances to secure the broadest possible coverage.

Looking Ahead

With the uptick in block deals, the demand for tools that reduce transactional risk and accelerate deal timelines will only grow. R&W insurance is well positioned to meet that demand, offering a practical, affordable, and efficient solution that more reinsurance professionals should have in their toolkit. For those considering their next block transaction, exploring how to leverage R&W insurance most effectively could be one of the most valuable conversations to have before the deal gets underway.

12 AI Deployment Myths Debunked

Organizations rushing to deploy AI face a widening gap between pilot success and production value, driven by persistent misconceptions about capability versus application.

Deployment

It doesn't matter how beautiful your theory is, it doesn't matter how smart you are. If it doesn't agree with experiment, it's wrong. - Richard P. Feynman

Myths, Evidence and Truth

The explosive growth of generative and agentic AI has provided unprecedented capability in the hands of businesses. The associated narrative of what could be achieved with that capability has created amplified levels of hype. Driven by a clear fear of missing out, industries are initiating pilots that attempt to reimagine existing business processes through the addition of AI.

AI is increasingly being positioned as a foundational technology, with the potential to usher in a civilizational shift in how individuals think, work, create, consume information, and participate in the economy. Generative and agentic AI are now able to perform tasks that were previously considered uniquely human, including producing content, writing software, analyzing information, supporting decision-making, and acting with a degree of autonomy. The capabilities are, by any measure, both expansive and bewildering, as what was once considered impossible is now a reality.

Companies no longer see AI adoption as an elective. It is increasingly seen as critical to business growth. The focus is now shifting from capability to application, experimentation to deployment, and technical feasibility to economic value. In this transition, organizations are facing a harder challenge in translating available capabilities into sustainable business outcomes. The widening gap between expectation and realized value has begun to unravel a set of myths.

The usage of AI can be classified into two categories: AI for IT and AI for business. The core objective of AI for IT is to apply these technologies to build, enhance, or optimize technical systems. The primary users in this context are those involved in the software development lifecycle, including activities such as defining business requirements, development, quality assurance, production support, and related functions. In contrast, the core objective of AI for business is to improve decision-making, enhance customer service, and drive economic outcomes. The primary users are executives, managers, and people in operations engaged in both front-office and back-office functions across the process value chain.

While AI for IT demonstrates measurable progress, AI for business remains largely restricted to what can be described as pilot purgatory. This pattern is driven by factors such as escalating operational expenses, integration issues, data quality challenges, change management issues, and scalability challenges. Both pilot purgatory and post-deployment disillusionment can be traced back to a shared set of myths that shape how organizations approach AI adoption. While multiple such misconceptions exist, this article focuses specifically on 12 myths associated with the deployment of AI solutions in business contexts.

01. Unstructured text means Generative AI

The basis for this myth is the impressive, demonstrated capability of generative AI to understand, interpret, summarize, and generate content from unstructured text. This has led to a general perception that generative AI is the default solution for tasks involving unstructured information. Such a technology-centric conclusion assumes that input determines the choice of solution. While unstructured text is an important input characteristic, it is not a justifiable technological requirement to use generative AI or a reason to avoid it.

The real solution determinant is always the nature of the task being performed. Each task has different requirements in terms of accuracy, explainability, risk tolerance, and economic viability. For instance, within the insurance claims process, the extraction of claim data from First Notice of Loss documents is an information extraction problem that can be addressed using OCR, entity extraction, and document processing techniques. The classification of claims into loss categories represents a classification problem, for which rules engines or machine learning models are better suited. Coverage determination, on the other hand, is fundamentally a policy interpretation and rule application problem, which is commonly addressed through deterministic rule engines.

02. Select a single model and build systems around it

Many organizations approach generative AI adoption through a model-centric lens, where the sequence begins with selecting a model, followed by training, and then integration into software systems. This approach prioritizes building infrastructure around a single model, rather than focusing on business outcomes. The origin of this view can be traced to traditional machine learning practices, where model development remained the most important task.

In the business landscape, specific success stories of flagship models are often overgeneralized to all use cases. This leads to an assumption that a single model can address a wide range of business needs. In practice, performance varies based on the nature of the task, the characteristics of the data, and the operating context. This results in failures when these conditions change. There is also a tendency to treat model selection as the primary source of risk, whereas actual outcomes are more dependent on data quality, system integration, and alignment with workflow. Even powerful models fail in production environments due to weaknesses in supporting pipelines.

A model-centric approach remains appropriate in research settings or in scenarios involving the development of proprietary models. In enterprise environments, however, it proves less effective, as value realization is more strongly influenced by use case validation, data readiness, economic viability, and integration considerations.

03. Bigger models guarantee superior outcomes

The myth stems from the assumption that enterprise problems require maximal intelligence rather than fit-for-purpose outcomes. The myth is reinforced by visible breakthroughs from large frontier models that demonstrate high levels of reasoning, language fluency, and generality, leading to the extrapolated thinking that increasing model size translates directly into business value.

The assumption begins to break down when outcomes are decomposed into their actual drivers. Many business tasks are repetitive, well-defined, and bounded in scope. In these cases, prediction consistency and low latency matter more than depth of generalized reasoning. In such conditions, smaller models or even rule-based systems can outperform large models by delivering faster response times, lower cost per transaction, and higher predictability. Large models introduce higher computing costs, increased energy consumption, and added operational complexity, often without proportional performance gains even when the task complexity does not require their full capability.

While larger models provide superior performance in open-ended, complex, and unstructured problem settings, smaller or tailored systems often deliver superior outcomes in repetitive, narrow, and latency-sensitive enterprise workflows. The correct approach is to move from capability maximization to outcome optimization by aligning model choice with task characteristics, cost constraints, and operational requirements.

04. All work lies on an automation spectrum

The myth arises from early automation narratives and traditional AI maturity models that frame progress as a linear continuum from manual effort to full automation. With agentic AI, the continuum has extended further into autonomous decision-making. This thinking is convenient because many computational tasks have historically followed this path. As newer agentic AI systems demonstrate the capability to act and decide, organizations assume that moving toward full autonomy represents a natural progression.

The view relies on the notion that reducing or eliminating human involvement improves outcomes. The assumption collapses when work is decomposed by purpose rather than process. Organizations automate for reasons such as optimizing cost, quality, speed, customer outcomes, and risk. Automation and autonomy are mechanisms that influence these variables and often function as proxies rather than end goals. Further, any work can be decomposed into computational work or accountability work, based on purpose. Computational work, such as classification, extraction, prediction, and routing, is performed to transform, process, or analyze information, and becomes suitable for automation as model capability improves. In contrast, accountability work is performed to establish responsibility and ownership for decisions and their consequences and requires human authority irrespective of machine accuracy.

The automation spectrum applies only to computational work and does not extend to decisions where consequences must be owned by a person. Accountability work is governed by the need for responsibility and ownership and does not diminish with improved model performance.

05. Processes are the right unit of analysis for AI deployment decisions

The myth persists due to business operations being historically designed, measured, and optimized at the process level, making it the natural unit for strategic discussion. Even enterprise IT application transformation efforts, consulting frameworks, and governance models reinforce this view by framing change in terms of end-to-end processes, leading to an assumption that AI decisions should operate at the same level of abstraction.

This reflects the belief that processes represent homogeneous units with consistent characteristics and that a single technology approach can be applied uniformly across all steps within a process. Processes are collections of heterogeneous activities that require fundamentally different capabilities such as extraction, prediction, classification, and contextual reasoning. AI suitability must be evaluated at the activity level to determine feasibility and value. Applying a single AI strategy across an entire process either overengineers or misapplies automation in areas with different requirements and risks, and results in overfitting simple tasks and underperforming on more complex ones.

Any single process typically contains fundamentally distinct categories of work such as following rules, detecting patterns, interpreting information, coordinating actions, and exercising judgment. Given the accuracy, latency, compliance, and economic considerations involved, each requires a different approach, spanning rule engines, traditional machine learning, generative models, or human decision-making. While process-level evaluation is useful for scoping, AI decisions must be made at the activity level, and technology selection must align with the specific requirements of each step.

06. More data solves performance problems

The myth is anchored to traditional machine learning thinking, where larger labeled datasets often lead to measurable performance gains. This has created a persistent belief that the scale of data is the primary driver of model effectiveness.

The view is driven by three underlying propositions. One, model performance is primarily constrained by data quantity. Two, additional data always adds signal rather than noise. Three, enterprise failures stem from insufficient data rather than limitations in how knowledge is structured, maintained, and applied. The assumptions begin to break in enterprise settings where failures typically arise from poor knowledge quality rather than data scarcity. Adding more data does not resolve outdated procedures, conflicting policies, undocumented exceptions, or fragmented business rules.

Additional data improves performance only when it is relevant, consistent, and aligned with the task. Further, modern models often require less data to deliver meaningful value. Methods like RAG eliminate the need for large-scale retraining. In many cases, smaller, well-curated datasets or limited fine-tuning outperform large but poorly governed corpora.

07. If a model has sufficient data and knowledge, it can replace human expertise

The myth is rooted in the ability of modern AI models to access, synthesize, and communicate vast amounts of information with high levels of fluency. As models are trained on increasingly large corpora and supplemented with external knowledge sources, organizations tend to equate accumulated knowledge with expertise.

The claim reflects the belief that expertise can be reduced to knowledge retrieval and pattern matching, and that improved model performance directly translates to superior decision-making. The argument fails because expertise is not defined by knowledge alone but by how that knowledge is applied under constraints. Experts prioritize competing objectives, interpret ambiguous situations, and make trade-offs where no clearly correct answer exists. They define boundaries, handle exceptions, and remain accountable for outcomes in ways that models cannot replicate. Even when models achieve high accuracy on routine tasks, they do not assume responsibility for errors or resolve conflicts between competing goals such as risk, customer impact, and regulatory compliance.

In practice, models can replicate parts of expert knowledge and automate routine aspects of expertise, but they do not replace judgment, trade-off resolution, or accountability. The role of experts therefore shifts from execution to policy definition, oversight, boundary-setting, exception management, and failure evaluation. While this makes expertise less visible, it only becomes more critical.

08. Humans are the primary bottleneck in enterprise processes

The basis of the myth is the visible delays, inconsistencies, and perceived subjectivity in human-driven processes. It is reinforced from the success of earlier automation initiatives that reduced cycle time by eliminating manual steps. The emergence of generative and agentic AI further introduces a misplaced belief that intelligent systems can compensate for flawed process design and bypass human inefficiency without the need for structural correction.

The claim is anchored in the biased idea that inefficiency is driven primarily by human limitations rather than process design. It rests on the premise that processes are structurally sound and require only faster execution. The assumption does not hold as enterprise processes can be internally inconsistent, redundant, or poorly defined. AI systems inherit the same structural inefficiencies, amplify inconsistencies across process steps, and introduce additional risks when acting on ambiguous or conflicting inputs.

Humans act as bottlenecks only when processes are well-designed, but execution is the limiting factor. However, when the processes are inherently flawed, intelligent systems do not eliminate inefficiency, they accelerate it instead. Structural correction, such as process redesign, simplification, and clarification of decision boundaries, must precede automation and agentic deployment.

09. Human-in-the-Loop by Default Ensures Safety and Control

The myth is derived from traditional control models such as maker–checker frameworks, where experienced humans validated outputs produced by others. This is further reinforced by early AI governance approaches that successfully positioned human review as the ultimate safety net. Even as AI systems become more capable, the same logic is being extended, with the expectation that placing a human checkpoint will compensate for model limitations and ensure safe outcomes.

The claim propagates the anthropocentric perspective that humans reviewing AI outputs have sufficient context, expertise, attention, and incentives to detect errors made by intelligent systems in a consistent manner. It further extends to the belief that review quality remains stable under scale, and that human judgment can neutralize model errors without being influenced by them. The assumptions collapse under real operating conditions. Human reviewers frequently exhibit automation bias, and excessive reliance on AI outputs due to their fluency or perceived authority. As workload increases, oversight degrades due to cognitive overload, fatigue, and loss of situational awareness. Unlike traditional maker–checker models where expertise is built through experience, AI-era checkers are often required to validate outputs generated by systems whose reasoning they cannot fully understand. This results in superficial checks and rubber-stamping behavior, where the presence of a human does not materially improve correctness.

Human involvement improves safety not by default, but only when it is consciously and carefully designed to account for all failure modes, with sufficient context, tooling, incentives, and controlled workload.

10. The primary source of risk is the model

The myth originates from exaggerated narratives around model failures such as hallucinations and bias. To stay safe, organizations tend to concentrate on model selection and evaluation as the central risk management activities.

The claim reflects the belief that AI system behavior is determined only by the model and that all risks can be materially reduced by improving model quality. It positions other factors such as prompts, workflows, controls, and integrations as secondary drivers of outcomes. The assumption does not hold because most enterprise AI systems are rarely standalone systems. The secondary drivers determine how the model is used and the actions that follow. In real implementations, risk is not concentrated in the model but distributed across the system.

The model is just one component of risk, and improving the model addresses only a subset of risks. Organizations that focus excessively on model evaluation while underinvesting in process design and control mechanisms often experience suboptimal outcomes.

11. Success in pilots or proofs-of-concept predicts production success

The myth is shaped by the fact that pilots consistently show strong performance, which creates the belief that demonstrated capability will translate directly into business impact. The claim focuses only on the specific use case or the problem being tested and treats all other factors as representative of real operational conditions. It is further reinforced by the view that any challenge in production can be addressed once the capability of the model to solve the business problem is established.

This fails in real-world conditions, as pilots deliberately exclude the most challenging parts of enterprise reality. They operate on curated data, controlled and optimized workflows, limited edge cases, and dedicated resources. They operate in test environments that do not require integration with legacy systems or exposure to fragmented data architectures and inconsistent business rules. Production environments introduce constraints that materially affect system behavior. As a result, systems that perform at high accuracy in pilots significantly degrade in production due to systemic factors rather than model performance.

Pilot success demonstrates technical feasibility not operational viability. Real production success depends on operating model, process design, data quality, and governance integration, rather than model capability alone.

12. AI implementation is primarily a technology project

The myth is a consequence of how AI implementation projects are structured and executed. AI is primarily introduced through tools and platforms, making the technology layer more visible. The surrounding organizational work remains implicit, which leads to the belief that implementing AI is comparable to historical IT programs delivered as standalone technology initiatives. The claim is constructed on the premise that existing processes, roles, and workflows are structurally sound, and that AI can be applied without requiring redesign. The people, governance, and operating models are expected to adapt once the system is deployed. It further extends to the belief that any friction can be addressed by improving or fine-tuning the model.

The belief crumbles in enterprise settings, as AI fundamentally changes how work is performed. Most organizational outputs are deterministic, and incorporating probabilistic AI systems requires process redesign. Workflows must adjust to handle exceptions and ambiguity. Business roles shift accordingly from execution to supervision, validation, and policy definition. Failures are often driven by poorly defined processes, unclear ownership, weak governance structures, and fragmented operating models. These issues cannot be resolved merely by increasing model capacity or fine-tuning. Organizations must introduce new governance structures for accountability and risk control. Ownership boundaries need to be redefined to reflect machine involvement in decisions. If these aspects are not put in place, the system either underperforms or leads to the introduction of new risks. In theory, implementing AI may appear similar to a traditional IT program. In practice, however, it is a cross-functional transformation effort rather than an isolated technology deployment.

Looking through the lens of practicality

To navigate these myths and layers of hype, organizations must evaluate AI through the lens of operational conditions. Many deployment failures are driven by equating technological capability with deployment necessity, confusing assistance with accountability, and interpreting pilot success as evidence of production readiness.

Correcting these misconceptions requires shifting the unit of analysis from the process level to the activity level and adopting simplicity as a design principle. As each additional layer of complexity introduces new failure modes, it is important to recognize that human judgment remains essential at every step where accountability, trade-offs, and consequence management are required. Governance must be integrated into system design rather than positioned as an optional control layer within the escalation pathway.

AI systems rarely fail only due to lack of model capability. They fail when organizations misclassify the nature of work, extend automation into domains requiring accountability, and deploy technology without redesigning the surrounding systems.


Key Decisions When Deploying AI Claims Triage

Deploying AI in claims triage requires conservative accuracy thresholds and clear escalation boundaries to avoid regulatory exposure and customer dissatisfaction.

AI Claims Triage

Claims handling is one of the most visible cost lines in insurance. Industry estimates consistently place 70% to 80% of claims handling costs inside routine, repeatable processes: status inquiries, documentation requests, coverage confirmations, first-notice-of-loss intake. These are the categories that make the AI business case straightforward to build and difficult to execute without hurting accuracy.

Most insurer AI triage deployments begin with a proof of concept on controlled test data. What they encounter in production is a different environment, with a different risk profile, and different failure modes. Three design decisions determine whether the transition from pilot to live operation succeeds or stalls.

The Claims Categories Ready for AI Triage (and the Ones That Are Not)

The categories that perform reliably in production share a characteristic: the resolution requires accurate information retrieval and a rule-based decision, not adjuster judgment.

First-notice-of-loss intake for standard peril types (vehicle collision, water damage, property theft) follows a structured data-collection process that maps cleanly to what AI agents do well. The agent gathers required fields, confirms coverage against the policy record, generates a claim reference, and routes to the appropriate handling queue. Intake time drops significantly with AI. Early-stage accuracy is high when the agent has direct, live access to the policy management system.

Policy status and coverage inquiries are a second reliable category. Policyholders and brokers need clear, accurate answers about what is and is not covered under a specific policy. These queries have a deterministic answer that the AI can retrieve from the policy record and communicate without ambiguity. When it does so accurately and immediately, satisfaction scores on this category improve, and the insurer avoids the misquote risk that comes from a rushed human response during peak volume.

Documentation status updates on open claims, whether a repair estimate has been received, whether a payment has been processed, where a claim sits in the workflow are the third reliable category. These interactions are high in volume and low in complexity. They consume significant adjuster time. When the agent handles them with real-time access to the claims management system, adjusters recover that time for interactions that actually require their expertise.

The categories that are not ready are those that require genuine coverage interpretation, multi-party coordination, or circumstances the policy language does not address clearly. Deploying AI on these categories in an early implementation is where most accuracy problems originate.

The Accuracy Threshold That Protects Both CSAT and Regulatory Standing

In most service sectors, a triage system that resolves 70% of queries correctly in the first months of deployment and improves from there is considered a successful pilot. Insurance applies a different standard, for two reasons that are specific to the sector.

First, inaccurate coverage information given to a policyholder at claim time creates both a CSAT problem and a potential errors-and-omissions exposure. A claimant told their loss is covered and later finding it is not does not experience this as a minor service inconvenience. Second, insurance regulators in most markets require that specific communications meet accuracy and disclosure standards that a misconfigured AI agent can fail to meet without the insurer knowing until a complaint surfaces.

The practical consequence is that the confidence threshold below which the AI escalates rather than responds must be set higher in insurance than in most service environments. A system that generates a coverage answer when its confidence score is moderate is operationally acceptable in retail support. It is not acceptable in insurance, because the cost of a wrong answer is asymmetric: a small number of incorrect coverage statements create regulatory and customer relationship problems that far outweigh the efficiency gains across the cases the system handled correctly.

Define the escalation trigger conservatively in the early deployment. A narrower AI scope with a high accuracy rate builds the internal confidence and operational track record needed to expand scope responsibly. A wide scope with a moderate accuracy rate generates precisely the incidents that slow adoption and invite regulatory scrutiny.

What Production Looks Like After the Proof of Concept

Proof-of-concept environments test the happy path. Production environments test the edge, at volume, across the full range of policy types and peril circumstances the carrier actually handles.

Three failure modes appear consistently in live insurance triage deployments.

The first is policy variant coverage. A claimant's policy may carry endorsements, exclusions, or carrier-specific modifications that are not reflected in the standard coverage language the agent was trained on. Without direct access to the full, structured policy record, not a summary, the agent falls back to standard language and produces an answer that is accurate for the base product and wrong for that policyholder's specific terms.

The second is multi-party claims. In a commercial property claim or a liability claim involving multiple parties, the intake process requires collecting different information from parties with different roles and interests. AI agents calibrated for personal lines intake do not handle this correctly without specific configuration, and the errors they generate in multi-party scenarios tend to be the most visible ones.

The third is mid-process handoff quality. When a claim requires escalation from the AI to a human adjuster, what the adjuster receives determines whether the customer experience continues or restarts. A handoff record that captures the full interaction context, what the agent understood, what was collected, and what was confirmed allows the adjuster to continue from where the agent stopped. A handoff that returns the claimant to the beginning of the intake process generates the complaint pattern that regulatory affairs teams track.

Keeping Adjusters in Control of What Matters

The framing that produces both operational results and staff adoption is direct: AI handles information retrieval and routine intake so adjusters spend their time on the interactions that require professional judgment, relationship management, and expertise. Not as a threat to the role. As a description of what the role becomes.

The adjusters who see AI triage succeed in their operation are consistently the ones who were involved in defining where the escalation boundary sits. That line is a professional judgment, not only a technical parameter. Involving the claims team in setting it and giving them a clear override path when the system routes something they believe it should not produce better-calibrated systems and faster adoption than any training program.

The insurers getting durable results from AI claims triage are not the ones that deployed the most capable model. They are the ones that were clearest about where human judgment is irreplaceable and built their system around that boundary from the first day of deployment.


Ralf Klein

Profile picture for user RalfKlein

Ralf Klein

Ralf Klein is the founder of Triad, an operational AI agency that builds and deploys AI agents for organizations handling high volumes of claims, service requests, and maintenance tickets. 

The AI-Informed Homeowner Is Already Here

Homeowners are using AI to research coverage and compare policies before meeting agents, fundamentally reshaping the insurance buying process.

homeowners

A few years ago, a homeowner walking into an insurance conversation was a lot like a patient walking into a doctor's office. They knew something was wrong (or at least expensive), but they mostly deferred to the expert. The agent explained coverage options, translated policy language, and guided the decision. The homeowner nodded along and signed.

That dynamic is breaking down. A growing number of homeowners are doing research with AI before they ever talk to a human agent. According to the 2026 Hippo Housepower Report, 54% of homeowners plan to use AI to check whether they're paying a fair price, 48% to compare providers and policies, and 40% to better understand their policy.

Much like patients who Google their symptoms before showing up at the clinic, homeowners may not have the diagnosis right, but they have the vocabulary. They're arriving with more context, more specific questions, and higher expectations for speed and transparency than they had even two years ago.

The natural question is how far this goes. If consumers are already using AI to research coverage and compare carriers, will AI eventually handle the entire transaction? Some agencies are already building toward that, but the industry isn't ready for a fully autonomous buying experience. The regulatory, financial, and psychological infrastructure to support it doesn't exist yet.

The last mile stays human

Even with all of that AI-assisted research, the final purchasing step will remain a human interaction for a long time. When it comes to big purchases or signing on the dotted line, consumers want to be able to look someone in the eye. They want a person to put an arm around their shoulder and say, "Yes, this is the right policy. You're covered."

Think of it like booking a complex international trip. Most people will spend hours researching flights, hotels, and visa requirements online. But when the itinerary gets complicated, plenty of people still pick up the phone and call a travel agent for that final confirmation. The AI does the legwork, but a human closes the loop.

Beyond that psychological barrier is the legal one. In most states, core insurance functions like binding coverage, providing advice, and serving as the agent of record are non-delegable duties that require a licensed human. AI sophistication won't change that in the near term. 

The National Association of Insurance Commissioners (NAIC) adds a regulatory layer. As of early 2026, 25 jurisdictions have adopted its Model Bulletin on the use of AI systems by insurers, and another four states—California, Colorado, New York, and Texas—have their own insurance-specific regulations. 

On top of that, payment companies are still uneasy about sensitive credit card or EFT information flowing through AI, even with tokenized digital wallets. Carriers also need to modernize the underlying technology stacks, data systems, and APIs that agents already rely on. Layering agentic capabilities onto outdated or unreliable infrastructure will only create more friction and make it harder for agents to trust the technology enough to use it.

Gen Z homeowners are already far more comfortable with AI in their insurance decisions than older cohorts. But for now, the human at the end of the buying process provides reassurance that AI cannot replicate at scale.

Who's liable when the AI agent gets it wrong?

Independent agents are already hiring technology companies to build AI chatbots that handle initial consumer conversations, run quotes, and present coverage options. The technology works. What's unresolved is who's responsible when that bot gets something wrong.

Let's say an agent deploys an AI tool built by a third-party vendor. That tool runs a quote, explains coverage, and presents a recommendation to a consumer. The consumer buys the policy. Six months later they file a claim, and the AI-recommended coverage had a gap.

The mistakes are easy to imagine. AI may draw attention to key coverages, but not that requirements and policy language vary by county, or that some carriers in a region build that coverage into the base policy while others exclude it entirely. It can look up a flood zone but misinterpret whether their property sits on the edge of one, or that the distinction can change based on drainage and slope. And replacement cost—one of the most important numbers in a homeowners policy—depends on regional labor rates, local building codes, and material costs that fluctuate with supply chains. An AI tool pulling from general data is likely to get that number wrong, or differently than an insurance company.

So who owns the gap? The tech company that built the bot? The agency that deployed it? Or is there a disclaimer at the bottom of the screen that says the onus is on the consumer? For human error, the answer is settled. Agents carry errors and omissions insurance for exactly this reason. None of that infrastructure exists yet for AI agents. These questions will get worked out in the courts, slowly, and until they do, anyone deploying consumer-facing AI is carrying a risk that's difficult to quantify and impossible to fully insure against.

The new visibility problem

If you're a carrier and you're not thinking about how AI-assisted shopping will affect your visibility to consumers, think about what happened with search engine optimization. Companies that ignored SEO a decade ago disappeared from Google results. They were invisible to the vast majority of consumers, regardless of the quality of their product. The same dynamic is starting to form with AI.

As more homeowners begin their insurance research with an AI tool, carriers that win will be the ones that are prepared for it, with clearer coverage language, accessible APIs for AI tools, and structured product information. The rest risk being left out of the conversation entirely.

The homeowner sitting across from an independent agent today is more informed and more specific in their questions than they were three years ago. AI is a big part of why. The industry's job is to meet consumers where they are and to be clear about where AI ends and experienced human judgment begins.