Download

Protecting Our Legacy

Watch four black top executives discuss their history and their experiences in the industry as they look towards the future.

Woman working on laptop

The purpose of the webinar will be to discuss how far Black people have come in history, the industry, and what it will look like in the foreseeable future. 

Watch Now


Diversity at The Institutes

Profile picture for user DEIInstitutes

Diversity at The Institutes

The Institutes are committed to cultivating and preserving a culture of inclusion for all who work in and are served by the risk management and insurance community. As a knowledge partner, we build and foster learning opportunities that are accessible to everyone to encourage learning, development, and advancement. We believe each person is valuable; and therefore, a diverse, equitable, and inclusive workplace is essential to our ability to live our values: do the right thing, put our customer first, do what we say, work together, and be innovative. We encourage all to be their authentic selves at work and beyond.

Neurodiversity

This webinar is targeted at anyone interested in learning more about neurodiversity, whether HR professionals, educators, advocates and recruiters.

Puzzle Piece Ribbon Wrapped Around Globe

Neurodiversity refers to the diversity of human brains, and considers differences of how our brains are "wired" as simply another natural variation in humans. It is often used to specifically cover autism, ADHD, dyslexia and dyspraxia, amongst others. Rather than thinking there is something wrong or problematic when some people don't operate similarly to others, neurodiversity embraces the differences in brain function and behavioral traits as a natural element of how diverse the human population is. During this 45 min session, the panelists will give an introduction to neurodiversity and explain how we can we access its amazing contribution to diversity of thought and remove the obstacles to successful neuroinclusion. This webinar is targeted at anyone interested in learning more about neurodiversity, whether HR professionals, educators, advocates and recruiters.

Watch Now


Diversity at The Institutes

Profile picture for user DEIInstitutes

Diversity at The Institutes

The Institutes are committed to cultivating and preserving a culture of inclusion for all who work in and are served by the risk management and insurance community. As a knowledge partner, we build and foster learning opportunities that are accessible to everyone to encourage learning, development, and advancement. We believe each person is valuable; and therefore, a diverse, equitable, and inclusive workplace is essential to our ability to live our values: do the right thing, put our customer first, do what we say, work together, and be innovative. We encourage all to be their authentic selves at work and beyond.

Being your authentic self: A conversation with Dame Inga Beale

This webinar will also explore ways to promote visibility and encourage inclusivity beyond Pride Month in order to impact meaningful change within the industry and to develop deeper advocacy.

Pride

June is Pride Month, an important time to celebrate and a reminder to continue to advocate for the human rights and full equality of the LGBTQIA+ community. Join us as we talk with business woman and former CEO of Lloyd’s of London Dame Inga Beale, who will share her journey in showing up as her authentic self, challenges faced throughout her career and the role of allies in celebrating and affirming the identity of those within their companies. The conversation will also explore ways to promote visibility and encourage inclusivity beyond Pride Month in order to impact meaningful change within the industry and to develop deeper advocacy.

Watch Now


Diversity at The Institutes

Profile picture for user DEIInstitutes

Diversity at The Institutes

The Institutes are committed to cultivating and preserving a culture of inclusion for all who work in and are served by the risk management and insurance community. As a knowledge partner, we build and foster learning opportunities that are accessible to everyone to encourage learning, development, and advancement. We believe each person is valuable; and therefore, a diverse, equitable, and inclusive workplace is essential to our ability to live our values: do the right thing, put our customer first, do what we say, work together, and be innovative. We encourage all to be their authentic selves at work and beyond.

DIVERSITY IN INSURANCE: Attracting, recruiting, and retaining a diverse workforce

Join this webinar sponsored by Origami Risk moderated by Patrick O’Neill, President, and Founder, Redhand Advisors to learn about the benefits of risk and safety professionals collaborating, how technology can facilitate that collaboration, and real world risk and safety technology examples from professionals at Cheesecake Factory and Corewell Health.

Two Woman Talking

Risk management and safety management are often independent disciplines among most organizations. Although both seek similar goals and outcomes towards reduced losses and more efficient financing of these losses, these departments may not necessarily work together. These commonalities often lead to duplicate and overlapping efforts that may be inefficient and expensive. Risk managers often lack visibility into safety programs, which can impact workers’ compensation claims and insurance premiums. And safety leaders frequently don’t have visibility into the financial impact of their programs, meaning they may struggle with organization buy-in on safety initiatives. But what if risk and safety teams were able to work more effectively together?

Join this webinar sponsored by Origami Risk moderated by Patrick O’Neill, President, and Founder, Redhand Advisors to learn about:

  • The benefits of risk and safety professionals collaborating
  • How technology can facilitate that collaboration
  • Real world risk and safety technology examples from professionals at Cheesecake Factory and Corewell Health

Watch Now


Diversity at The Institutes

Profile picture for user DEIInstitutes

Diversity at The Institutes

The Institutes are committed to cultivating and preserving a culture of inclusion for all who work in and are served by the risk management and insurance community. As a knowledge partner, we build and foster learning opportunities that are accessible to everyone to encourage learning, development, and advancement. We believe each person is valuable; and therefore, a diverse, equitable, and inclusive workplace is essential to our ability to live our values: do the right thing, put our customer first, do what we say, work together, and be innovative. We encourage all to be their authentic selves at work and beyond.

Hispanic Heritage Month-Unidos: Inclusivity for a Stronger Nation

During this panel discussion, the speakers will discuss the challenges that they have faced as well as the work that the industry can do to increase representation, belonging and accessibility of the industry to Hispanic and Latina/Latino communities.

Woman speaking into a microphone

Join us as we host a special webinar in honor of Hispanic Heritage Month featuring three Hispanic insurance industry leaders and experts. From September 15 to October 15, we celebrate National Hispanic Heritage Month, which was first observed as Hispanic Heritage Week in 1968 under President Lyndon Johnson. In 1988, President Ronald Reagan expanded it to a 30-day celebration. With nearly a quarter of the U.S. population identifying as Hispanic or Latina/Latino, Hispanic Heritage Month is an important time to recognize the achievements and reflect upon the many ways Hispanic and Latina/Latino American cultures have influenced and contributed to the insurance industry. During this panel discussion, the speakers will discuss the challenges that they have faced as well as the work that the industry can do to increase representation, belonging and accessibility of the industry to Hispanic and Latina/Latino communities.


Watch Now


Diversity at The Institutes

Profile picture for user DEIInstitutes

Diversity at The Institutes

The Institutes are committed to cultivating and preserving a culture of inclusion for all who work in and are served by the risk management and insurance community. As a knowledge partner, we build and foster learning opportunities that are accessible to everyone to encourage learning, development, and advancement. We believe each person is valuable; and therefore, a diverse, equitable, and inclusive workplace is essential to our ability to live our values: do the right thing, put our customer first, do what we say, work together, and be innovative. We encourage all to be their authentic selves at work and beyond.

Veterans Day: The Value of Military Veterans

During this panel discussion, the speakers will discuss the successes and challenges that they have endured, as well as the work that the industry can do to increase representation, belonging and accessibility of the industry to the military veteran community.

American Flags in a Row

Join us as we host a special webinar in honor of Veterans Day featuring three military veteran insurance industry leaders and experts. Every year on November 11th, we celebrate Veterans Day; a time for us to pay our respects to those who have served. With nearly 19 million of the U.S. population identifying as a military veteran, Veterans Day is an important time to acknowledge the achievements and reflect upon the many ways military veterans have influenced and contributed to the insurance industry. We also recognize and honor the skills and diversity that veterans bring to the industry. Leadership, problem-solving skills, and integrity are just some of the skills that military veterans possess, and these skills are needed for a successful career in the insurance industry. With many insurance executives being veterans themselves, the industry is showing that they see the value that veterans bring. During this panel discussion, the speakers will discuss the successes and challenges that they have endured, as well as the work that the industry can do to increase representation, belonging and accessibility of the industry to the military veteran community.

Watch Now


Diversity at The Institutes

Profile picture for user DEIInstitutes

Diversity at The Institutes

The Institutes are committed to cultivating and preserving a culture of inclusion for all who work in and are served by the risk management and insurance community. As a knowledge partner, we build and foster learning opportunities that are accessible to everyone to encourage learning, development, and advancement. We believe each person is valuable; and therefore, a diverse, equitable, and inclusive workplace is essential to our ability to live our values: do the right thing, put our customer first, do what we say, work together, and be innovative. We encourage all to be their authentic selves at work and beyond.

Risk Management, Insurance and Entrepreneurship: Minority Owned Businesses

In this webinar, minority-owned business owners will have an honest conversation about their personal journeys into entrepreneurship, challenges faced, identity, access, leadership, and how they have set themselves apart as minority business owners in risk management and insurance.

Group looking at laptop

Small businesses and entrepreneurs have been longtime generational wealth builders. According to the Federal Reserve Bank of Cleveland, “In 2016, the average wealth of households with a head identifying as black was $140,000, while for white-headed households was $901,000, nearly 6.5 times greater.” Minority-owned businesses have the capacity to reduce this gap and its negative effects on their communities and supporting minority-owned businesses have proved to have a positive impact on communities of color. Minority business owners do face challenges. Roughly 18.7% of U.S. businesses are minority-owned and access to capital still is one of the biggest challenges today. The challenge is even greater for Black women-owned small businesses. In this webinar, minority-owned business owners will have an honest conversation about their personal journeys into entrepreneurship, challenges faced, identity, access, leadership, and how they have set themselves apart as minority business owners in risk management and insurance.

Watch Now


Diversity at The Institutes

Profile picture for user DEIInstitutes

Diversity at The Institutes

The Institutes are committed to cultivating and preserving a culture of inclusion for all who work in and are served by the risk management and insurance community. As a knowledge partner, we build and foster learning opportunities that are accessible to everyone to encourage learning, development, and advancement. We believe each person is valuable; and therefore, a diverse, equitable, and inclusive workplace is essential to our ability to live our values: do the right thing, put our customer first, do what we say, work together, and be innovative. We encourage all to be their authentic selves at work and beyond.

Beyond Moneyball

Observational process intelligence helps insurers find new ways to win.

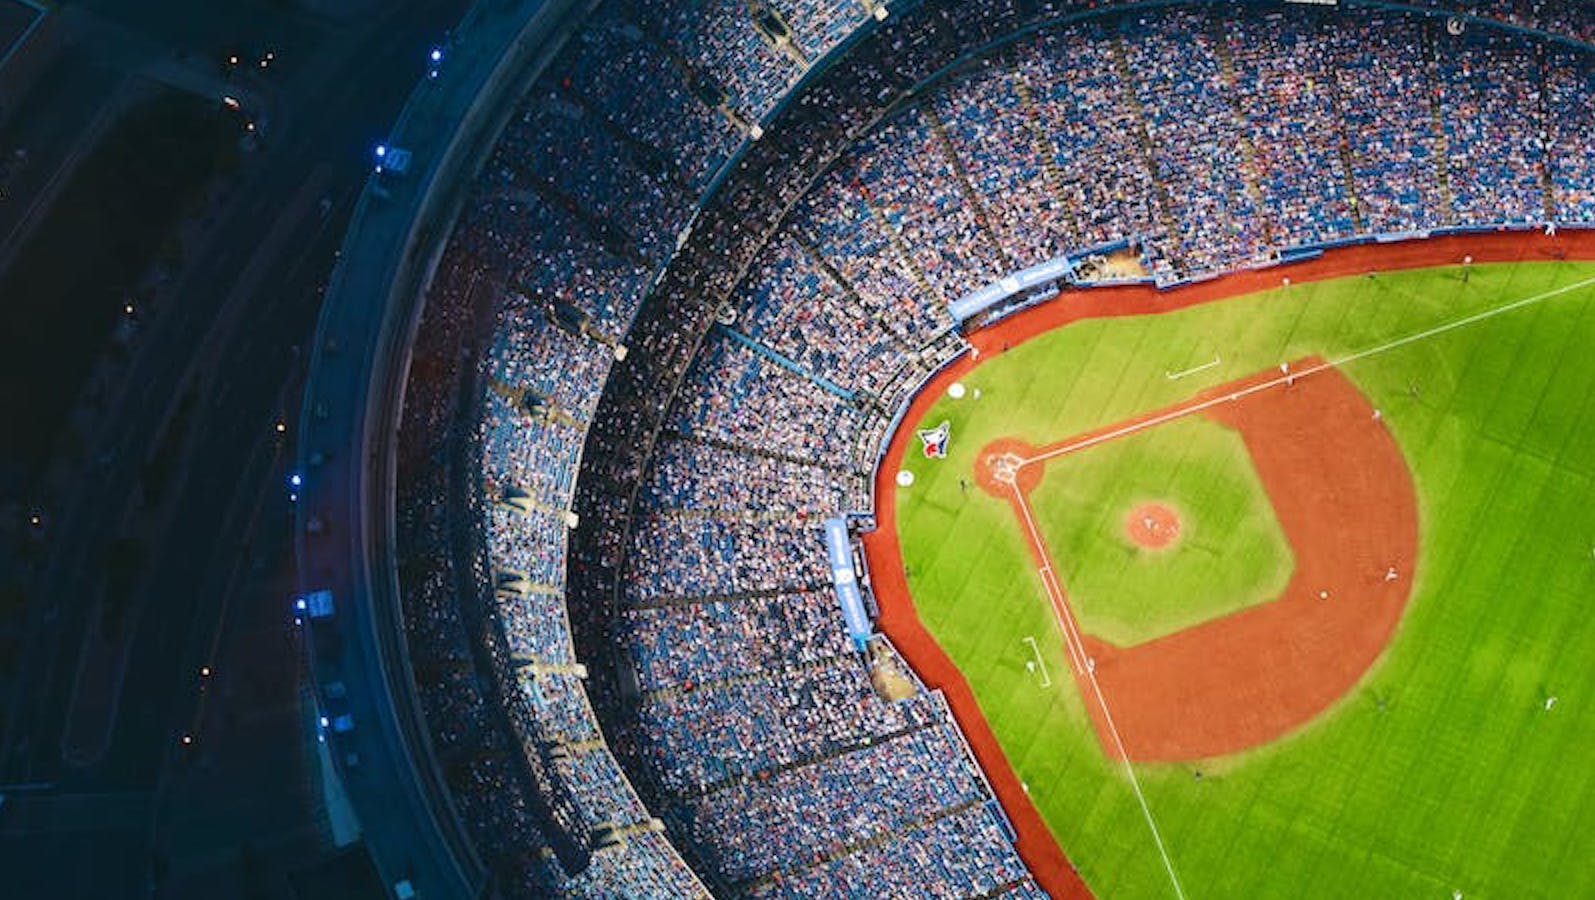
Overhead view of a baseball stadium at night with lights on

Baseball season has arrived.  

"Moneyball," by Michael Lewis, it’s hard to believe, was published almost 20 years ago in 2004. For the unfamiliar, "Moneyball" tells the story of how Billy Beane, general manager of the Oakland A’s, used advanced analytics to identify high-value, low-budget players and win with payroll a fraction of major-market teams like the Yankees and Dodgers.    

Moneyball-type analytics, based on static player and team outputs, have since become table stakes. 

Last year’s World Series champion, the Houston Astros, won despite letting a billion dollars in free agents walk. Their opening day payroll of $180 million ranked eighth in the league. The Astros also won the World Series in 2017 with a payroll of $124 million, ranked 17th. Over the last six seasons, among legitimately contending teams, the Astros rank a clear first in payroll-cost-per-win. 

The Houston Astros were the first team in the league to go beyond Moneyball, investing in observational process intelligence, measuring player and team inputs, not just outputs. Installing computer vision devices and Doppler radar for bullpen and batting practice sessions as well as live games (this year a league-wide standard), the Astros created a class of kinetic data on players in motion to help them improve. An example of observational process intelligence from a different sport is Trackman in golf.   

Observational process intelligence has arrived in our favorite sport--insurance—helping leaders evaluate core marketing, distribution, underwriting, claims and customer service operations in motion. Our company, Skan.AI, combines computer vision with AI to observe humans and the tools they use as they’re using them, in real time, generating kinetic data for continuous improvement. 

See also: Automation 2.0: What's After RPA

Live analytics include: 

  • Process maps and process variability: Dynamic process mapping with variation in how work really gets done
  • Workforce utilization: quantified utilization at the operator, business unit and geography level
  • Workforce productivity: quantified productivity metrics at the case and operator level
  • Technology utilization: quantified application usage across operators and time, with available replays of actions as they occurred
  • Activity-based costing: quantified unit costs at the case level filterable by any vector--customer, geography, product, etc. 
  • Automation discovery: identification and ranking of automation opportunities quantified with estimated cost savings per opportunity 

Everything rolls up to an ops dashboard with hourly or daily reporting to address issues and opportunities as they arise, in or near real time.  

Observational process intelligence helps insurers find new ways to win, selling more policies, drawing new customers and minimizing cost-per-victory.


Riv Arthur

Profile picture for user RivArthur

Riv Arthur

Riv Arthur is a business leader and technologist working in insurance, healthcare, and private equity.

Latest Data on Fatal Occupational Injuries

The fatal work injury rate increased to 3.6 per 100,000 full-time equivalent workers for 2021 in the U.S., the highest annual rate since 2016.

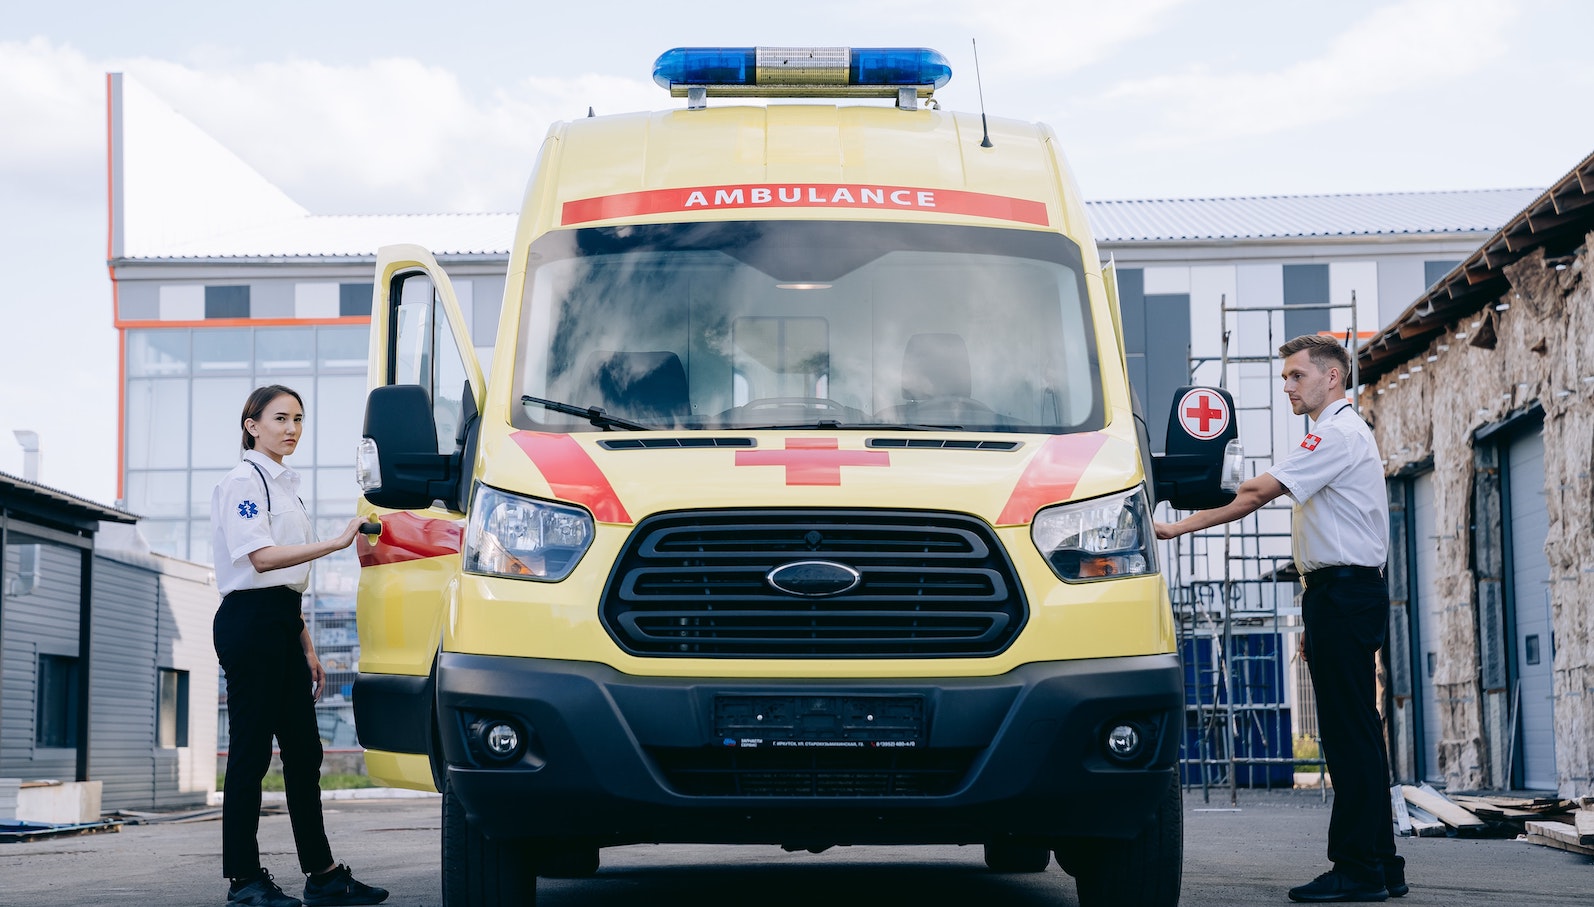
Man and woman standing on either side of a yellow and red ambulance outdoors

According to the latest report from the Bureau of Labor Statistics (BLS), there were 5,190 fatal occupational injuries recorded in the U.S. in 2021, an 8.9% increase from 2020. In 2019, the fatal work injury rate before the COVID-19 pandemic was 3.5 fatalities per 100,000 full-time equivalent workers. This number increased to 3.6 for 2021, which represents the highest annual rate since 2016.

“Even if your particular industry is not high on this list, the exposures that led to the workplace fatalities exist in almost every industry, and employers should certainly be able to find relatable events or exposures,” said Matt McDonough, assistant vice president of risk services at Safety National. “This report shows companies the types of events and exposures that led to workplace fatalities. If they do not have controls in place for some of these exposures, they should certainly start building those programs out now.”

Hardest Hit Industries

Four industries ranked highest for total number of fatalities:

  1. Transportation and Material Moving: This industry reached a series high in 2021. BLS states that there was a 16% increase in deaths for driver/sales workers and truck drivers from 2020 to 2021.
  2. Construction and Extraction: These types of occupations ranked second in number of fatal worker injuries despite experiencing a 2.6% decrease in fatalities from 2020.
  3. Protective Service: Firefighters, law enforcement officers, transit police and others in this field saw a 32% increase in fatalities in 2021. More than 45% of these were due to homicides (116) and suicides (21).
  4. Installation, Maintenance and Repair: This industry saw 475 fatalities in 2021, an increase of 21% from 2020.

The most hazardous working conditions are often related to labor-intensive occupations. The current labor shortage is only exacerbating on-the-job fatalities and injuries. More workers are being asked to take on more dangerous tasks, resulting in a higher risk of injury. There is also a lack of training and a shortage of experienced workers. Finally, employers are trying to manage their business with fewer resources, which can lead to a reduction in safety measures.

Surprises in the Report

Exposure to harmful substances was the third leading cause of fatalities throughout the U.S. in the workplace, just falling behind transportation incidents and falls, slips and trips. These were fatalities attributed to unintentional overdoses, which means nonmedical use of drugs and alcohol.

According to the BLS, exposure to harmful substances or environments led to 798 worker fatalities in 2021, the highest figure since the series began in 2011. This major event category experienced the largest increase in fatalities in 2021, increasing by 19% from 2020. Unintentional overdose from nonmedical use of drugs or alcohol accounted for 58% of these fatalities (464 deaths).

The transportation sector continues to be the most affected industry for workplace fatalities in the U.S. While this may not be considered a surprise, the sheer number of fatalities within this industry is shocking. The increased number of delivery drivers on the road, the increasing number of distracted drivers and insufficient safety protocols to protect workers all contribute to the large number in this industry, which continuously ranks number one in the BLS report.

See also: Unprecedented Severity of WC Claims

Tips on Managing Risks

In light of the information provided in this report, the following are some strategies that companies can implement to help reduce workplace fatalities:

  1. Implement Safety Protocols: Employers should implement clear safety protocols and procedures, including important information on how to safely perform certain tasks and what to do in emergencies.
  2. Develop Training Programs: Develop safety training programs to help workers stay aware of potential hazards and know how to safely perform their jobs.
  3. Promote Safety: Promote a culture of safety in the workplace by emphasizing the importance of following safety protocols and the consequences of not doing so.
  4. Upgrade Equipment: Regularly check and upgrade equipment and replace anything that is damaged or worn out.
  5. Provide Personal Protective Equipment (PPE): Provide PPE to workers who may be exposed to hazardous environments or situations.
  6. Conduct Safety Audits: Regularly conduct safety audits and take corrective action as needed.

Companies should also encourage workers to report any potential hazards they may notice, post signs to remind workers of safety protocols and to help them recognize potential hazards and hold regular safety meetings to ensure that workers understand all safety protocols.

Could Insurance Become Irrelevant?

Worldwide GDP is growing faster than insurance premiums, suggesting insurers aren't keeping up with customer needs. Three areas stand out.

Image
Window

McKinsey has been raising the alarm for some time about how insurers are in danger of losing relevance. The key indicator that we should be concerned is that global GDP is growing faster than insurance premiums, suggesting that insurers aren't keeping up with clients' needs. 

Three areas stand out as ones where insurers seem to be backing away from the risks: natural catastrophes, climate risk and cyber. With natural catastrophes, damages are increasing so fast that they are outstripping coverage. With climate change, the issue is more that attempts to address it rely on new technology, so there is little or no historical data to use for pricing. With cyber, attacks are proliferating so rapidly and changing shape so quickly that many insurers are being cautious.

Now, nobody is saying that insurers should just step in front of these massive risks so they can stay relevant. That would be a good way to get walloped. But McKinsey argues that there are ways to increasingly lean into all of these risks, through a combination of mitigation and pricing, that will grow the industry while preserving its traditional, protective role in society.

In its Global Insurance Report 2023, titled, "Expanding Commercial P&C's Market Relevance," McKinsey says: "While premiums for commercial lines have been growing over the past three years at approximately 7% per year, rate hardening has driven most of this growth. After adjusting for rate growth, global premiums lagged significantly behind real global GDP growth during this same period, indicating a decline in the relevance of commercial lines."

With natural catastrophes (NatCats), the basic problem is just that there have been so many. "Since 2017," the report says, "the U.S. has experienced an average of 15 NatCats per year with damages exceeding $1 billion—up from fewer than 10 per year in the previous decade and fewer than six in the decade prior to 2007." 

With climate risk, the report talks more about opportunities as the world tackles the problems. It says "the transition to a net-zero economy could account for more than $800 billion in annual global capital expenditures in renewable energies and decarbonization technologies by 2030. These new technologies will create new forms of risk requiring protection, and the resulting insurance value pool could be worth up to $15 billion, concentrated in property as well as energy and construction specialty lines." The report says insurers haven't found the renewable energy line of business to be especially profitable, so they have backed away, but says they can do better as they learn more and can develop risk-engineering services "to accompany clients on their way to net-zero emissions."

With cyber, the report talks about a massive problem... representing a massive opportunity:

"As widespread technological shifts have permeated nearly every aspect of work, especially with the rise of remote work environments, cyber risk has become ubiquitous.... Already, cyber economic losses in 2020 totaled $945 billion—more than one hundred times the total premium market ($9 billion in 2021)—indicating a massive protection gap. Even if only a fraction of these losses is insurable, it could translate to a more than $100 billion growth opportunity for the global commercial-insurance industry."

McKinsey says there are four ways to tackle the protection gaps in NatCats, climate risk and cyber: innovating on products and services, adjusting pricing to reflect the true cost of the risk, investing in risk prevention and mitigation services and educating stakeholders to raise awareness of the risks. 

But I've already gone on long enough, so I'll leave you to read about those four options here, in the full report, if you're interested.

While I don't see insurance ever becoming irrelevant, I do think McKinsey has a point: We shouldn't back away even from wildly complex problems like NatCats, climate risk and cyber. We obviously need to price the risk appropriately, but we should lean into our societal role and use all our data and expertise to help the world tackle those issues. We'll stay relevant, earn a lot of goodwill -- and generate a ton of business. 

Cheers,

Paul

P.S. Often, I see items that I think are worth noting, even though I won't go on at length about them, so I'm going to start appending some here. I hope you find these nuggets useful.

--CEOs still don't seem to be seeing that long-predicted recession. A Fortune survey that drew responses from 149 CEOs of major companies around the world found that 45% expect their firm’s growth to be strong (32%) or very strong (13%) over the coming 12 months. Another 44% said modest, while 12% said either weak (10%) or very weak (2%).

--A PwC survey found that 84% of executives thought consumers "highly trusted" their business. 27% of consumers agreed. Hmm. That result took me back to a survey Chunka Mui and I cited in our 2008 book, "Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years." The survey found that 80% of executives thought their product was the best in the market -- and that only 8% of their customers agreed. We really have to stop kidding ourselves.

At least executives seemed to have a better handle on employees' thinking. PwC found that 79% of executives thought they were highly trusted by employees, and 65% of employees agreed. 

--The Insurance Information Institute, a sister organization of ours at The Institutes, released its latest economic outlook. The key takeaways are:

  • Property/casualty (P/C) insurance saw its cyclical underlying growth rebound fail to materialize in 2022’s second half as interest rate tightening depressed housing starts, corporate spending, and vehicle expenditures.
  • Increases in P/C replacement costs (e.g., vehicle parts, housing construction materials) slowed over 2022’s last two quarters but are up 40% since 2019.
  • U.S. gross domestic product (GDP) growth is likely to remain depressed for at least the next two quarters after the Federal Reserve shifted away from its hawkish stand on interest rates; the Fed’s three-year consumer price index (CPI) expectations remain overly optimistic, Triple-I believes.