Download

3 Steps to Demystify Artificial Intelligence

Yes, AI will change everything. But that doesn't mean the technology need be daunting, or that insurers lack the skills to tackle the challenge.

|
Artificial intelligence is the new electricity. We hear it will fundamentally shift the balance of power between labor and capital, mostly by rendering labor obsolete. It will enable and empower transformative technologies that will rearrange the sociopolitical landscape and may lead to humanity’s transcendence (or extinction) within our lifetimes. As it changes the world, it will necessarily rewrite the rules of insurance. That’s the myth, and the nature of the headlines. Interestingly, insurance is heavy on intellectual property (think of proprietary underwriting models), technology and data. And AI is hungry; hungry for data, of course, but also hungry for systems that can be automated and for proprietary classification problems that can be improved. That places insurance right in the appetite of artificial intelligence and its promise of transformation. If we want to act on artificial intelligence’s transformational potential,  we need to understand what it actually is, separate the technologies from the hype and develop a practical understanding of what is required to implement AI-powered solutions in the insurance sector. This article will highlight these three steps and offers a realistic approach for carriers to take advantage of the opportunities. Defining Artificial Intelligence Unfortunately, our first step is also our hardest, as a working definition of artificial intelligence is difficult. The scope of the term AI is broad, and it requires careful consideration to avoid becoming hopelessly confounded with its own hype. It is also challenging to come to a clear definition of natural intelligence, which leaves us struggling for a definition of artificial intelligence because the latter is so often compared to the former. AI tends to be discussed in two flavors. The first is general artificial intelligence (also, artificial general intelligence and strong AI). GAI is machinery capable of human-level cognition, including a general problem-solving capability that is potentially self-directed and broadly applicable to many kinds of problems. GAI references are accessible through fictional works, such as C-3PO in Star Wars or Disney’s eponymous WALL-E. The most important feature of GAI is that it does not currently exist, and there is deep debate about its potential to ever exist. The second is usually referred to as narrow AI. Narrow AI is task-specific and non-generalizable. Examples include facial recognition on Apple’s iPhone X and speech-to-text transliteration by Amazon’s Alexa. Narrow  AI looks and feels a lot like software or, perhaps, predictive models. Narrow AI can be described as a class of modeling techniques that fall under the category of machine learning. See also: Seriously? Artificial Intelligence?   What is machine learning? Imagine a set of input data; this data has one or more potential features of interest. Machine learning is a technique for mapping the features of input data to a useful output. It is characterized by statistical inference, as advanced techniques often underlie machine learning predictive models. Through statistical modeling, software can infer a likely output given a set of input features. The predictive accuracy of machine learning methods increase as their training data sets increase in size. As the machine ingests more data, it is said to learn from that data. Hence, machine learning. Perhaps most important of all, machine learning (as an implementation of narrow AI) is real and here today; for the remainder of our discussion when we say "AI," we mean narrow AI or machine learning. Beyond the Hype The hype around AI and its potential is extensive. Silicon Valley billionaires opine on the potential implications of the technology, including comparing its power to nuclear weapons. Articles endlessly debate if and how quickly AI will structurally unemploy vast swaths of white collar workers. MIT’s Technology Review provides a nice summary of the literature, stating that up to half of all jobs worldwide could be eliminated in the next few decades. AI may well have this kind of impact. And the social, political and economic implications of that impact, especially around questions of potential large-scale unemployment, deserve careful long-term consideration. However, executives and business owners need to evaluate technology investments today to improve their current competitive position. From that perspective, we find it more practical to focus on examining which existing tasks could be automated by AI today. Enter Pigeons In 2012, researchers trained pigeons to recognize people based only on their faces as part of a study on cognition. Suppose you had millions of face-recognizing pigeons; this force of labor could be deployed in a comprehensive facial recognition system -- a system remarkably similar in function to the facial recognition AI of devices like modern smart phones. It turns out pigeons have also been trained to recognize voices, spot cancers on X-rays and count, among a host of other tasks related to headline-grabbing AI achievements. The metaphor is admittedly silly. Instead of pigeons, imagine an army of virtual robots capable of classifying information from the real world to produce a machine-readable data set. In machine learning language, these robots take unstructured data and make it structured. Said robots resemble the automation machinery of a factory; like spot welders tirelessly joining steel members to form automobile frames, our virtual robots tirelessly recognize if a face is featured in a photograph. In contemplating the question, what could be automated with AI, a useful starting place is the army of robots (or pigeons!). For example:
  • What existing analyses could be improved or optimized? Could pricing or underwriting be improved using better classifiers or non-linear modeling approaches?
  • What data currently exist at the firm that could be made available for new types of analysis? Claims adjusters’ notes can be processed by natural language algorithms and cross-referenced with photos of physical damage or prior inspections.
  • What data would you analyze if it could be made available? What if you could listen to all the policyholder calls received by your customer service department and annotate which questions stumped the customer service representatives? Or which responses lead to irritation in the policyholders’ voices?
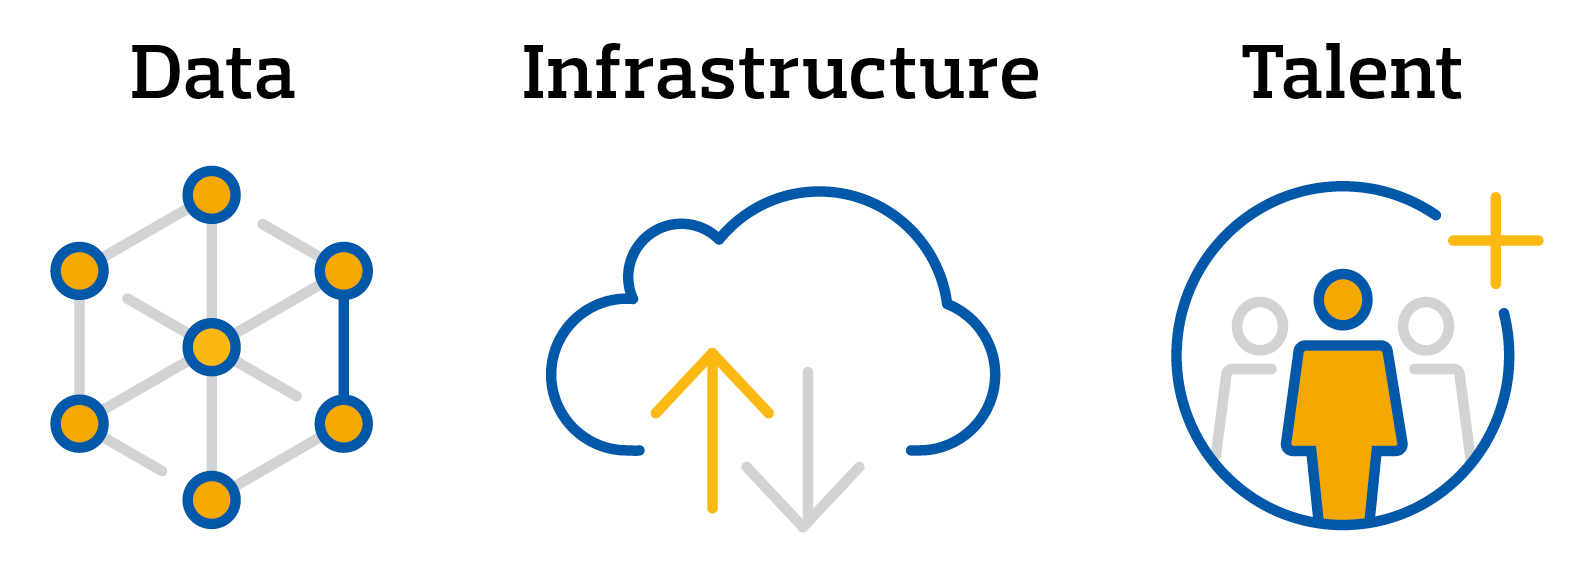
Bringing AI to Insurance What is an insurer to do? Start by not fretting. We propose two considerations to facilitate a sleep-at-night perspective. First, insurers are already good at AI or its precursor technologies. The applicability of AI in the present and near future is entirely based on narrow AI technologies. For example, natural language processing and image recognition are both machine learning implementations with working business applications right now. Both use predictive models to achieve results. The software may be artificial neural networks trained on vast data sets, but they are nonetheless conceptually compatible with things insurance carriers have used for years, like actuarial pricing models. The point is that the application of AI is an incremental step forward in the types of models and data already applied in the business. Second, sorting through the hype requires a staple of good business decision making: the risk-cost-benefit analysis. Determining which technologies are worth investment is within scope for decision makers that otherwise know how to make selective investments in growing the capabilities of their firm. The problems faced by a carrier are much bigger than sorting out AI if management lacks the basic skillset for making business investments. Providing an inventory of every application of AI is beyond the scope of this article. DeepIndex provides a list of 405 at deepindex.org, from playing the Atari 2600 to spotting forged artworks. Instead, suppose that AI, like electricity, will be broadly applicable across industries and functions, including the components of the insurance value chain from distribution to pricing and underwriting to claims. The goal is to identify and implement the AI-empowered solutions that will further a competitive advantage. Our view is that carriers’ success with AI requires three key ingredients: data, infrastructure and talent. Data: AI might be considered the key that unlocks the door of big data. Many of the modeling techniques that fall under the AI umbrella are classification algorithms that are data hungry. Unlocking the power of these methods requires sufficient volume of training data. Data takes several forms. First, there are third party data sources that are considered external to the insurance industry. Aerial imagery (and the processing thereof) to determine building characteristics or estimate post-catastrophe claims potential are easy examples. Same with the vast quantities of behavioral data built on the interactions of users with digital platforms like social media and web search. Closer to home, insurance has long been an industry of data, and carriers are presumed to have meaningful datasets in claims, applications and marketing, among others. Infrastructure: Accessing the data to feed the AI requires a working infrastructure. How successfully can you ingest external data sources? How disparate and unstructured can those sources be? Cloud computing is not necessarily a prerequisite to successful AI, but access to vast, scalable infrastructure is enabling. Are your information systems equipped, including security vetting, to do modeling in the cloud? Can you extract your internal data into forms that are ready to be processed using advanced modeling techniques? Or are you running siloed legacy systems that prevent using your proprietary data in novel ways? Talent: Add data science to the list of AI-related buzzwords. We claimed earlier that many of the advancements attributed to narrow AI are predictive models conceptually like modeling techniques already used in the insurance industry. However, the fact that your pricing actuary conceptually appreciates an artificial neural net built for fraud detection using behavioral data does not mean you have the in-house expertise to build such a model. Investments in recruiting, training and retaining the right talent will provide two clear benefits. The first benefit is being better equipped to do the risk-cost-benefit analysis of which data and methods to explore. The second is having the ability to test and, ultimately, implement. See also: 4 Ways Connectivity Is Revolutionary   In Aon’s 2017 Global Insurance Market Outlook we explored the idea of the third wave of innovation as propounded by Steve Case, founder of AOL, in his book, “The Third Wave: An Entrepreneur’s Vision of the Future.” The upshot of the third wave for insurers was that partnership with technology innovators, rather than disruption by them, would be the norm. This approach applies now more than ever as technological innovators continue to unlock the potential of AI. If you don’t have the data, or the infrastructure, or the talent to bring the newest technologies to bear, you can partner with someone that does. Artificial intelligence is real. While the definitions are somewhat vague - is it software, predictive models, neural nets or machine learning - and the hype can be difficult to look past, the impacts are already being felt in the form of chatbots, image processing and behavioral prediction algorithms, among many others. The carriers that can best take advantage of the opportunities will be those that have a pragmatic ability to evaluate tangible AI solutions that are incremental to existing parts of their value chain. “If you don’t have an AI strategy, you are going to die in the world that’s coming.” Devin Wenig CEO, eBay Maybe true, but that does not make it daunting. The core of insurance is this: Hire the right people, give them the infrastructure they need to evaluate risk better than the competition and curate the necessary data to feed the classification models they build. AI hasn’t, and won’t, change that.
Insurtech's Act 2: About to Start

A “Spotify moment” will see products simplified to their core coverages and then embedded frictionlessly into a digital ecosystem.

|
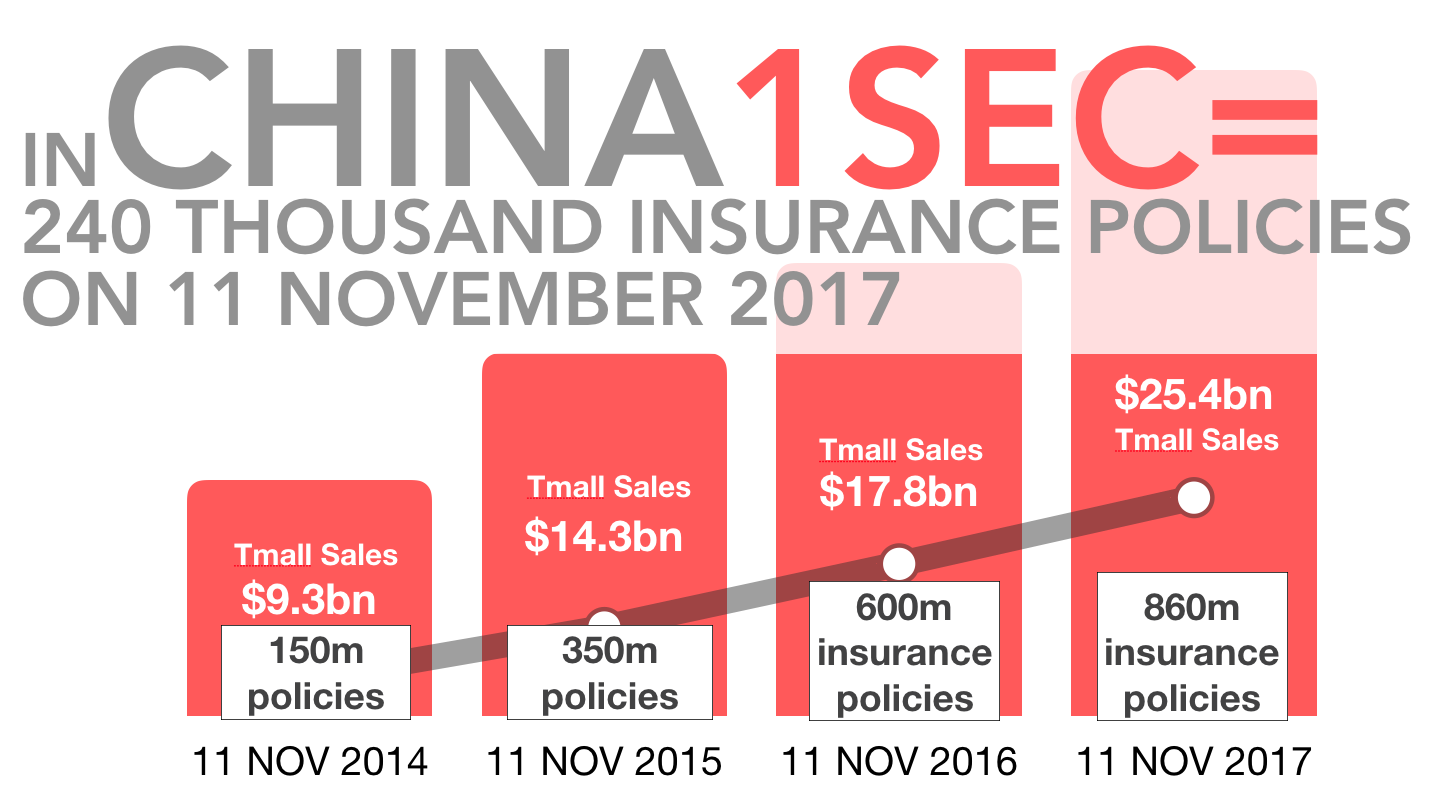
How long did it take to sell 240,000 insurance policies online in 2017? Most insurance leaders across Asia guess “at least a few weeks.” The reality is that, in the age of digital, it only took one second. The record was set on Alibaba's Tmall.com website on Nov. 11, 2017, by Zhong An, Chinese digital-first insurer and the most successful global insurtech so far. The total for that day was a staggering 860 million insurance policies sold online. The pace of Zhong An's growth has given the much-needed wake-up call for the insurance industry. Opening Act of Insurtech Insurtech had emerged in 2012, and over the last six years the insurance industry has started to embrace it. While there’s been a lot of excitement about insurtech, most of the digital efforts so far have been largely incremental—insurance products are becoming slightly cheaper, their distribution becoming a little bit more digitally enabled and the back-office becoming marginally more efficient. The “opening act” focused on the low hanging opportunities that kickstarted the insurtech wave globally. Now as opportunities susceptible to incremental tech solutions quickly dry up, many insurance managers are concluding that insurtech might have run its course, and, going forward, it will be back to business as usual for insurance. They will be in for a surprise! The perfect analogy for the current stage of the insurance industry is a record label in the age before digital music. Record labels erroneously believed they were in the business of CDs, which drove them to focus on pushing pre-packaged products with a single feature that consumers wanted, delivered to customers via expensive and inefficient distribution music store networks. See also: Digital Insurance 2.0: Benefits   The valuable lesson being that the full force of disruption did not come when records started selling CDs online but when Napster hacked through the oligopoly of record labels and force-unbundled their products. While Napster ultimately didn’t survive, it disrupted the status quo by pushing record labels to finally unbundle their products and make them available to digital-music distribution platforms such as iTunes and Spotify. The latest trends coming out of China are pointing to an early shift in insurance fundamentals. So the current slowdown in insurtech is not an end, but the beginning of the ecosystem transition toward the "Spotify moment” for the insurance industry. Main Act of Insurtech The “Spotify moment” happens when a discretionary spending item, like music, gets transformed from an occasional luxury into a utility that millions of customers rely on as their trusted daily tool. The key trigger for a “Spotify moment” is a combination of frictionless customer experience, mass-customization that closely matches consumer’s needs, perceived value for money and access to wide variety of choices. The “Spotify moment” will see insurance products simplified down to their core coverages and then embedded frictionlessly into digital ecosystem. This moment is now fast approaching, and it will bring with it the “main act” of insurtech. In the main act, insurance will move closer to becoming a risk transfer utility and a seamless part of consumers’ day to day digital service consumption. Digital businesses will start to dynamically pick the coverages that are relevant to the specific “worry profile” of their users and allow users to add those alongside their core services. Insurers have a narrowing window of opportunity to prepare or risk being sidelined into niche segments. Key strategic activities should include the following: Product Sprints. Cross-functional teams will need to start executing rapid product unbundling and creation of digital-oriented stand-alone coverages. Currently, it takes insurers on average six to 12 months to launch a consumer insurance product. In the future, product design will need to happen in five-day sprints and become iterative, to identify best product-market fits within the digital ecosystem. See also: Stretching the Bounds of Digital Insurance   Opportunity Management. Evaluating digital opportunities by the same metrics as legacy business is a sure way to destroy any sign of innovation. Digital requires a strategic “VC” approach to opportunity selection and management. Placing many strategic bets will let organization learn and iterate quickly from both mistakes and successes. Dedicating investment pool and digital P&L will keep accountability and ownership clear. Lastly, providing the best support for digital opportunities will maximize the probability of success. After all, would you rather lose your best resources to your self-disrupting digital team or to Amazon? Startup Collaboration. Working with startups and approaching them as high-potential partners will give the organization the right cultural compass and position it well for the dynamic digital insurance ecosystem. The future of insurance is digital; resistance is futile!

George Kesselman

Profile picture for user GeorgeKesselman

George Kesselman

George Kesselman is a highly experienced global financial services executive with a strong transformational leadership track record across Asia. In his relentless passion and pursuit to transform insurance, Kessleman founded InsurTechAsia, an industry-wide insurance innovation ecosystem in Singapore.

How New Medicare Cards Deter ID Theft

Finally, after years of requests, CMS is issuing cards that do not have a Social Security number as the Medicare identifier.

There are big changes Medicare has planned in 2018 that will help protect the identity of seniors and continue proper health benefits. The biggest and best change will be the new Medicare ID cards. When Medicare recipients receive their Medicare card, they are typically shocked to see that their Medicare Identification number is the same as their Social Security number. Medicare beneficiaries run the risk of identity theft when they have their Medicare card in their wallet or purse; it would be comparable to walking around with their Social Security card in their possession. Identity theft is a major issue; when someone has the Social Security number of another person the thief can apply for loans, open bank accounts and possibly gain employment. When someone has your Social Security number, the person has the key to your credit and identity. The Social Security administration and the Federal Trade Commission have been urging the Centers for Medicare and Medicaid Services to change the Medicare Identifier for years. Finally, after years of requesting that changes be made, CMS has made the decision to move to updated cards that do not have a Social Security number as the Medicare identifier. These updated cards were sent via mail in the beginning of April 2018. CMS anticipates all Medicare beneficiaries will have a new, updated card by April 2019. What to Expect from the New Medicare Cards The updated Medicare cards will feature a new Medicare Beneficiary Identifier (MBI) number. The card will display a randomly assigned number for all Medicare recipients. Healthcare providers and Medicare beneficiaries will be able to securely access tools that will allow them to look up MBIs as needed. During the 21-month transition period, it will be possible for providers to use a patient’s Social Security number or the new MBI number. The transition period was put in place to help things run smoothly for providers and patients across the nation. The issuance of a new card will not affect Medicare benefits. The new MBI number will have 11 characters, with a combination of numbers and uppercase letters. These new numbers will have no special meaning, making it safe to keep in your wallet or purse. The new cards will be mailed to you based on your geographical location; however, it is possible that you and your neighbor will get a new card at different times. See also: Identity Theft Can Be Double Whammy The Transition Period CMS is trying to make the transition smooth for caregivers, patients and others who need accurate Medicare information. The transition period will allow beneficiaries and providers to exchange Medicare information with CMS using MBI or a Health Insurance Claim Number; this period is scheduled from April 1, 2018, until Dec. 31, 2019. On Jan. 1, 2020, beneficiaries and caregivers will be required to use an MBI for most situations. It is suggested that beneficiaries keep an eye out for their updated Medicare card, and when it comes they should get into the habit of using their new MBI early. Obtaining an Updated Card Beneficiaries should destroy their old cards immediately after receiving their updated Medicare card. Once the new card is in possession, you can start using it at once. It is important that you keep your new MBI number confidential and watch the mail carefully so that you are aware when the new card is delivered. The new cards are going to be made of paper, making it easier for providers to use and copy. If you are enrolled in a Medicare Advantage Plan, the Plan ID card is the main card you show to your providers, although a healthcare provider may ask to see your MBI card, so keep it with you. How to Protect Your Identity Now Identity thieves have noticed seniors as ideal victims for identity fraud. Seniors typically have more money in their checking and savings accounts, and they have paid off their major financial obligations. Because seniors usually receive Medicare benefits, the door for identity theft in the medical industry is wide open. Because most seniors are not purchasing a new home or taking out a large loan, they have no reason to stay informed and therefore check their credit score less often. How to Keep Important Documents Safe:
  • Make copies of your insurance cards
    • Make a copy of your insurance card and remove the last four digits of your Social Security number.
    • Leave the original at home.
    • If you do need to take an original, remove the card from your wallet after the appointment and store it in a safe place.
  • Keep important documents safe:
    • A home safe can allow you to store important documents; if you have highly important documents, you might want to consider a bank safety deposit box for documents you do not need often.
    • Never carry around extra bank cards, credit cards you don’t frequently use, any health insurance card or your Social Security card.
  • Protect computer and internet access:
    • Be sure you use anti-virus, anti-spyware and firewall software to combat hacking programs that are designed to steal personal information.
    • Be creative with passwords and never use the same passcode for multiple accounts. Changing passwords regularly can ensure privacy.
    • Never send personal or financial information through an email, no matter the situation or company.
    • Be sure to have your Wi-Fi network password protected and secure. Your internet installation service rep can help make sure your wireless network is protected.
  • Check your credit frequently: Per the Fair Credit Reporting Act (FCRA), every 12 months a free credit report can be provided for you from each of the nationwide credit reporting agencies.
  • Destroy old documents:
    • Some documents need to be stored safely; others can be destroyed.
    • You should be destroying credit card statements, receipts, bank statements, tax documents, canceled checks and old driver’s licenses.
The Reason Behind a New Medicare Number The current Medicare number for many beneficiaries is their Social Security number. The U.S. Railroad Retirement Board, state Medicaid agencies, Social Security, healthcare providers and health plans all use this number. There are great dangers that can occur when a Social Security number is in the hands of a criminal. The Medicare Access and CHIP Reauthorizations ACT of 2015 is requiring CMS to replace the old numbers with a new updated Medicare Beneficiary Identifier. These cards are being released for one primary reason, to better prevent seniors from being the victim of identity theft. See also: 8 Questions on Medicare Set Aside Be Aware of Scams The reason for new Medicare ID cards was to prevent seniors from being the victims of identity fraud. Unfortunately, the change has inspired criminals to take a new approach. There have been attempts to mislead Medicare recipients, and more attempts are likely to be made through the transition. It is important that beneficiaries be aware of possible scams. The new Medicare ID does not cost beneficiaries money. The new card has the same benefits as the current card. Do not give the new card to anyone other than a healthcare provider. Many identity thefts are committed by friends and family. Medicare will not ask you to give personal information to obtain your new number and card. Nobody should contact you about the new Medicare card, your new number or any personal information. Medicare does not make uninvited calls to beneficiaries. If you think you are a victim of medical identity theft, contact the Federal Trade Commission about what to do next. Advantages of Change Because the new cards will not have a Social Security number, scammers will find it more difficult to commit fraud. Beneficiaries need to keep MBI numbers confidential and treat the numbers like personal identifiable information. If a beneficiary forgets the new card at home, healthcare staff can search the new Medicare ID number on a secure site. All existing Medicare information will continue to be available to your doctor. More than 57 million Americans will be provided with greater identity protection from the new Medicare ID cards. CMS intends a successful transition to the MBI for all people with Medicare and for their doctors.

Jagger Esch

Profile picture for user JaggerEsch

Jagger Esch

Jagger Esch is the president and CEO of Elite Insurance Partners and MedicareFAQ, a senior healthcare learning resource center.

What GDPR Means for Insurtech

Data security and privacy had seemed to be key concerns that would hold back insurtech, but GDPR allays those worries.

After Solvency II, the European Union is ready for its next big and comprehensive regulation, called GDPR (General Data Protection Regulation). GDPR was approved by the EU Parliament in April 2016 and after a two-year grace period took effect in May 2018! The new regulation will replace the current Data Protection Directive 95/46/EC. Regulatory Landscape and Breaches The first key point of the new regulation is protecting all E.U. citizens’ data privacy with an extended regulatory landscape. New data privacy rules should be applied to all personal data of data subjects residing in the European Union, regardless of companies’ locations. With GPPR, fines for possible breaches were increased sharply, up to 4% of annual global revenue or 20 million euro (whichever is greater). Another radical change is that regulations apply to not just controllers, but also processors. So, cloud processors are also covered. Under GDPR, the data owner must give consent through a document that is understandable, simple and easily accessible. Withdrawal of consent for data usage must also be easy. With GDPR, breach notification will become mandatory and should be performed within 72 hours after the breach is spotted. Notifications must be to all affected data owners. The Key Point for Insurtech These changes are key for insurtech. Data security and privacy had seemed to be key concerns that would hold back insurtech, because of the dangers created by the increased use of connected IoT devices, real-time data collection and high profile cyberattacks. But customers will be much more comfortable with insurtech because GDPR will alleviate concerns about data privacy, without regard to a company’s scale. With GDPR, drivers of insurtech like IoT, machine learning and much more won’t be considered as possible tools for data breaches. GDPR will be a spontaneous trigger of insurtech!

Zeynep Stefan

Profile picture for user ZeynepStefan

Zeynep Stefan

Zeynep Stefan is a post-graduate student in Munich studying financial deepening and mentoring startup companies in insurtech, while writing for insurance publications in Turkey.

The Future of Mobility Takes a Surprise Turn

sixthings

While so many of us have focused on the transformative possibilities of driverless vehicles, a much simpler technology has popped up and begun to reshape transportation in cities, with lots of potential implications for insurance. The technology is what the experts are calling "micromobility" and what the rest of us know simply as scooters.

The technology isn't totally under the radar, of course. When a scooter-sharing startup like Bird raises capital at a valuation of $2 billion, people notice. But I'm not sure that the threats and opportunities of scooters are being understood just yet. There certainly seemed to be a lot of surprise when the Washington Post last week published   an article about the number of people who are ending up in the emergency room following scooter accidents.

They would seem to come with the territory. You have people buzzing down sidewalks at 15mph (and Bird is, unwisely, in my opinion, lobbying against laws that would require helmets) or venturing into streets, where they have to engage with vehicles with a lot more mass and steel protection than the scooters provide. But, so far, people seem to be focusing on the novelty, not the implications.

In the short term, we need to figure out what insurance, if any, covers those in these accidents and whether there are opportunities to sell new forms, as some are doing for Uber/Lyft/Didi drivers and Airbnb hosts. We also need to help find ways to reduce risk. (Hint to Bird: helmets.)

The longer term gets even more interesting if you believe, as I do, that transportation in cities can be rethought from the ground up over the next 10 to 15 years. We accept these days that cars rule the road, but that's only been true for about a century. Through the 1910s, at least, horses, people and carts all shared city streets and only gradually gave way to these loud, smelly, metal contraptions that carried people around. We could well return to a mixed-used environment, with an overlay of information technology that optimizes for speed, convenience, cost, energy use, pollution and many other factors. That environment would be so different that the risks would change considerably, and the insurance and risk management would need to, too.

My working hypothesis is that cities will become bigger and more vibrant, with many more people choosing to live in them. Space will be freed up because driverless cars will so greatly reduce the need for parking, including on streets, and cities can be thoughtful about how to redeploy public thoroughfares among driverless vehicles, mass transit, pedestrians, bikes and scooters, using all sorts of sensors and cameras to manage flow and safety digitally. Today, the first-mile problem (how to get people and goods to mass transit) and the last-mile problem (how to get them to their final destination) are complex, but the problems should yield to a bunch of smart thinking over time both for city dwellers and for those who choose to live in suburbs or even more remote areas.

That's just a hypothesis, of course. As always, I recommend you Think Big, Start Small and Learn Fast so you can find out what the future will actually hold. The time to engage on the mobility transformation is now, but you can do so by testing big ideas in limited, inexpensive ways and only invest real money when an opportunity is clear.

Let us know if we can help with your innovation efforts. In the meantime, you might want to join our discussion in the group, "Inventing the Future of Risk Management and Insurance," on our Innovator's Edge platform. If you haven't already registered on the platform, just   click here. (Registering is free and quick.) Once you're registered,   click here  to join the robust discussion on mobility and a host of other topics.

Have a great week. 

Paul Carroll
Editor-in-Chief


Paul Carroll

Profile picture for user PaulCarroll

Paul Carroll

Paul Carroll is the editor-in-chief of Insurance Thought Leadership.

He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.

Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.

How to Understand Valuation Reports

Just arriving at a reasonable number is inadequate if the report parameters are missing. It is kind of like buying the wrong insurance policy.

Most owners of small businesses, many executives/owners of medium businesses and even quite a few executives/shareholders of large businesses think the most important aspect of a business appraisal is the final number. The business is worth X dollars. Obviously, the dollar amount is important. Getting the right dollar amount is even more important (I make this distinction because, in my experience, some business owners/executives and even quite a few bankers do not understand or sometimes even care about the difference between A Number and the Right Number). However, the number is arguably, especially if contested, only half of the requirement. Depending on the reason for the business being appraised, the actual valuation report MUST meet specific parameters. If the report does not meet these parameters, the value arrived upon by the appraiser may be found meaningless or an opportunity to litigate by tax authorities or plaintiff attorneys. Just arriving at a reasonable number is completely inadequate if the report parameters are missing. It is kind of like buying the wrong insurance policy. The coverage amount might be right, but coverage may not exist because the policy is wrong. Matching the correct report with the need is vital. Not knowing or understanding the difference makes business owners vulnerable to con jobs. And many business owners are conned each and every year. How to Avoid Being Conned First, I advise hiring an accredited business appraiser. All accredited business appraisers must sign a code of ethics, and most believe in their code. Some, though, do not quite believe in ethics as much as others. Some run the same con, but with accreditation. To be fair, I think some complete their reports mistakenly because they do not know any better. They are like insurance people with credentials who can barely spell insurance, much less business income coverage. The better path is to understand the three basic types of Fair Market Value reports and to also understand the huge difference between Fair Market Value (FMV) and Fair Value (FV). FMV and FV are not synonymous. I have seen agency owners, and even accountants and attorneys treat these critical terms as if their meaning was the same. However, many courts treat the values calculated using these two terms quite differently. See also: 3 Myths That Inhibit Innovation (Part 3)   Relative to the three types of valuation reports (there are other types that are generally less applicable to most agency owners that I won't address here), generally there is (exact terms vary depending on the professional association standards to which the appraiser is credentialed or belongs and sometimes depending upon the court, if being litigated):
  1. Summary reports, which are often referred to as letter reports (the entire valuation is in the form of a letter) or short-form reports. These reports contain little detail.
  1. Informal or Calculation Reports. The report writing standard, the analysis, the degree of confidence that applies to these reports are all relatively low. The margin of error is relatively high. The cost of these reports should therefore be relatively low. These reports rarely discuss the applicability of different valuation methods.
  1. Detailed, Written Reports. As the name implies, these are highly detailed reports usually combined with considerable analysis and a thorough discussion of the applicable valuation standards. These should cost the most, all else being equal.
Do not confuse a low price with high quality. Some appraisers charge a stiff penny for lower-quality reports because the customer does not understand the relatively low quality. Customers tend to think the appraiser just charges less. They think they are getting a Cadillac for the price of a Chevy. They are really just getting a Chevy that might not even be new. The con occurs when appraisers fail to offer clients options, especially the most rigorous option, and clients do not know they are comparing apples with oranges when one proposal is for a lightweight appraisal and the other proposal is for a high-quality, heavy weight appraisal. One cannot always tell by the price, either, because the con is to charge as if the lightweight appraisal will be of high quality but just enough less money to get the job. Courts have recognized this problem to some extent. For specific purposes, especially estate taxes, the courts can actually penalize the appraiser. For most purposes, though, once the valuation contract is signed, the damages will fall on the client and not the appraiser. I am not suggesting all reports need to meet the highest standard, because they do not. When someone truly needs a decent, back-of-the-envelope valuation that has a large margin of error that is acceptable to all parties, a low-standard report should suffice. If litigation, a sale, taxes or compensation are directly tied to the value, then usually the best option is to spend the money and obtain a high-quality valuation right from the get go. Having a low-quality report in the hopes that everyone will agree can only complicate the situation if a high-quality report is eventually required. Then one may find it necessary to explain all the factors the low-quality appraisal inadequately addressed. My key point, though, is that it pays to understand some basic valuation differences. It pays to understand that a low-quality report has severely limited acceptable uses, including that one cannot easily dispute the resulting value because the margin of error is so acceptably high. If the calculated value is $1,000,000 plus or minus 50%, then any value between $500,000 and $1,500,000 is okay. See also: 5 Ways Data Allows for Value-Based Care   These are not easy differences for the uninitiated to understand, either. My short summary is a summary of thousands of pages of textbook differentiation. Sometimes, especially when the attorneys and accountants involved do not understand the differences, I think clients should consider hiring someone to just explain their valuation report options. The complexity goes far beyond getting a home appraised, and choosing the wrong standards rarely is beneficial to any party other than the attorneys involved. You can find the article originally published here.

3 Insurtech Firms Take a Star Turn

Smart insurtech firms, such as Habit Analytics, Open Data Nation and StrongArm Tech, are likely to play a key role in helping incumbents.

Three smart insurtech firms were among a select group of startups showcasing their innovations to financial services executives, investors and journalists in New York.

I’m an executive sponsor at the lab, which was founded by Accenture together with the Partnership Fund for New York City. Since the facility opened in 2010, the surge in the number of technology startups looking to break into the financial services industry has been staggering. Nearly 50 startups have received backing from the FinTech Innovation Lab. They were chosen from hundreds of applicants. The funding these innovators have secured from the lab’s partners totals around $655 million. The FinTech concept has proved so successful that we’ve opened similar innovation labs in Hong Kong, Dublin and London. The insurance industry is attracting the attention of a growing number of the startups approaching the innovation labs for support. This year we introduced a dedicated “insurtech track” at the lab to encourage and develop startups that are working on solutions for the insurance industry. It’s been a great success. Three of the 11 startups showing their innovations at this year’s Demo Day were insurtech firms. The Demo Day is the culmination of a 12-week accelerator program that provides selected startups with intensive mentoring, technology and business assessments and extensive networking opportunities. At the Demo Day, the startups showcase their projects to executives from the financial services industry as well as investors and journalists. See also: Can Insurtech Rescue Insurance?   These are the promising insurtech firms that presented their innovations:
  • Habit Analytics. This firm uses real-time consumer data, sourced from smartphones and connected devices in homes, to create behavioral profiles that enable insurance companies to improve their risk models and enhance their products and services. Using information provided by Habit, insurers can, for example, monitor changes in a home’s risk, check the presence and performance of connected alarms and tailor services to suit the specific needs of customers.
  • Open Data Nation. By aggregating and analyzing information from around 2.5 billion public records from major US cities, this startup provides insurers with valuable insights to help them better evaluate risk. The company uses predictive analytics and machine learning to create proprietary risk scores for commercial enterprises in these cities. By accessing these scores, insurers can select and prioritize the risks they wish to underwrite, and thereby improve their efficiency and reduce claims.
  • StrongArm Tech. This insurtech firm aims to improve the wellbeing of industrial workers and help employers and their insurers reduce costs and enhance risk management. The company uses sensors worn by industrial workers to gather real-time data about the activities performed by these employees as well as the environments in which they’re working. Using a cloud-based artificial intelligence solution, StrongArm Tech analyzes this data and advises employers and insurers how they can reduce the risk of injury, and enhance the wellbeing, of workers. The company is also able to send real-time alerts to workers should they be in danger of harming themselves.
See also: 10 Trends at Heart of Insurtech Revolution   All three of these insurtech firms are looking to help insurers better manage risk. They’re aiming to help insurance companies perform better rather than trying to muscle in on their traditional markets. This desire for collaboration is a sign of the growing maturity of the insurtech sector. Smart insurtech firms, such as Habit Analytics, Open Data Nation and StrongArm Tech, are likely to play a key role in helping insurers capitalize on the many opportunities emerging from advances in digital technology. Click here for more information about the FinTech Innovation Labs.

John Cusano

Profile picture for user JohnCusano

John Cusano

John Cusano is Accenture’s senior managing director of global insurance. He is responsible for setting the industry group's overall vision, strategy, investment priorities and client relationships. Cusano joined Accenture in 1988 and has held a number of leadership roles in Accenture’s insurance industry practice.

11 Ways to Use Tech Better With Clients

Too little tech, and you’ll seem out of touch; too much, and you’ll lose the personal touch that keeps customers loyal and engaged.

Technology can enhance a strong, trust-based relationship with your clients, but it’s no substitution for face-to-face time. Here are 11 tips that will help you use high-tech tools in a smart and meaningful way. Technology does a lot, but it can’t do everything. Sometimes, we forget that. We can get so dependent on email and social media that we lose sight of what people really need from us—especially in business. Yes, clients expect to connect with us in various high-tech ways, but they also crave the deep and meaningful connections that can only come from face-to-face (or at least voice-to-voice) connections. It can be tricky to walk the line. Too little tech, and you’ll seem out of touch; too much, and you’ll lose the personal touch that keeps customers loyal and engaged. As you’re trying to find the right balance, just remember this: Your client relationships are built on emotions and trust, so use technology in a way that maintains and enhances relationships and propels them to the next level. I attribute my career journey to my ability to build strong personal relationships. Following early success in the clothing industry, I experienced a devastating bankruptcy that forced me to rebuild my life from scratch. I went on to join Northwestern Mutual Life Insurance Co., where I created an impressive financial portfolio and won multiple “Top Agent” awards. Human needs don’t change. Relationships mattered in the days of pencil, paper and snail mail, and they still matter in the days of Facebook and Skype. Ideally, you would meet with all of your clients in person, but of course that’s not always practical. Still, you should invest in at least one face-to-face meeting with your top clients. Then, use a carefully balanced mix of technology to maintain the relationship. Here are a few tips for using tech the right way. Don’t let “faceless” and “voiceless” technology become your primary communication tool. Nothing can replace the effectiveness of a face-to-face encounter (even if it’s by Skype), especially in the early phases of your client relationship. And meaningful phone conversations can be great, too. It’s fine to use less powerful tech solutions like email, texting and e-blasts to stay in close contact with your clients. These can enhance and strengthen a well-established relationship. But they should only be supplemental. Skype important meetings if you can’t be there in person. Ideally, “in person” interactions are best for relationship building—especially with your top clients—but, of course, they can’t always happen. Video conferencing is second-best. Make sure you’re using this tech tool often. It’s a great way to read body language and facial expressions—crucial for building trust and establishing positive and productive relationships. Pick up the phone regularly. Many people dislike the phone. Conversations can be long and meandering, and we’re all busy. But you must overcome your phone phobia. In terms of relationship building (not to mention problem solving), there is no substitute for the give and take that happens voice-to-voice. Schedule actual phone conversations with clients to catch up and find out how they are doing. Keep that human connection alive! See also: How Technology Drives a ‘New Normal’   Pay attention to how the client communicates. If a client seems to prefer phone, text or in-person communication, note it and honor the preferred style while maintaining your own dedication to person-to-person contact. This shows clients you care about and respect their preferences. Find a happy balance between the client’s style, yours and the demands of the day. Match the medium to the message. If you want to distinguish yourself and have something very important to say, write a letter! If you are trying to book an appointment with a busy person, figure out something complex or discuss a potentially sensitive issue, pick up the phone. If you only want confirmation of a small piece of information and you’ve recently spoken with a client, feel free to use email. Let your instinct be your guide. Be thoughtful and deliberate with social media. Your competition is taking advantage of these platforms, and so should you. But make sure your online presence is well-planned and -executed. Your Facebook or LinkedIn posts should meaningfully connect back to your brand and mission and provide value to clients and other readers. Don’t bombard your followers with inane content. This negates your credibility. Post less, and make sure your content is good. Keep your website young and agile. Is your website in alignment with your business image and your mission? Make sure it’s as professional and sleek as your own personal appearance when meeting a client for the first time. Successful companies have streamlined, up-to-date websites with modern fonts, colors and layouts. If it’s been a while since you’ve changed your design, your website is due for a tune-up and a facelift. Use email to send links to articles you think your client might enjoy. Trusting relationships thrive on frequent contact. To solidify your connection to clients (especially when you haven’t talked in a while), send them little links and articles you know they will enjoy. This gesture shows you are thinking about them and know where their interests lie. Just keep these communications in balance. Bombarding clients with superficial links and articles may actually weaken the value of your contact with them and undermine your relationship. Send e-newsletters to all your clients. This a good way to engage regularly with clients and stay on their minds. Create compelling content that connects with the various lines of services you are currently offering and craft interesting articles for your clients around related topics. Personalize your high-tech communication. Sometimes e-blasts make sense, but, whenever possible, include a small personal note at the top that lets clients see they matter to you. See also: 5 Ways to Enhance Client Engagement   Allow clients to log in and access their information. Whenever possible, empower clients by putting information at their fingertips. This not only saves time for your clients when they need to get a small piece of information, but also goes a long way toward building mutual trust. If you harness the power of technology correctly, it can do wonderful things for your business. But remember that it is only one tool in your toolbox. Use technology to enhance business, but don’t let it overshadow your mission to keep trust-based client relationships at the center of everything you do.

A Contrarian Looks 'Back to the Future'

Shouldn't we begin redesigning our own operations and industry and future before a competitive innovator does it for us?

A recent week started with reading a page by Paul Carroll from his Innovator’s Edge platform. The title question was: "Will Apple enter insurance? Google? Microsoft? Amazon?" His opening statement was, “Apple’s market value crested $1 trillion last week, and its big tech brethren Google, Microsoft and Amazon aren’t far behind, all are valued north of $800 billion…” I wasn’t shocked until he said, “All have extensive data about customers. And all have the size to tackle mind-bending problems that insurance faces – by contrast you’d have to combine AIG, Prudential and Allstate just to surpass $100 billion in market value…” A day later, someone sent me Reagan Consulting’s "The Golden Age of Insurance Brokerage." As I read through this short update, I could almost hear, “Happy days are here again” playing in the background for the brokers. The following captures the essence of this document: “We are living in the Golden Age of insurance brokerage. There are so many good things happening, it is hard to keep track of them all.” This was followed by six bullet points providing evidence of why the brokers are so happy. (No mention was made of insurance buyers, who may not be as HAPPY!) A friend then sent me a link to "The Death of the Old School Agency," by Michael Jans. This is a more in-depth view (30-plus pages) of the world as it may or will be. From the executive summary, we learn that today’s agent faces a new world of:
  • Rapid changes in consumer behavior and expectations
  • Emerging, existing and well-funded competitive channels
  • A rising millennial generation with different expectations, both as consumers and workers
  • A pace of change unlike anything they’ve ever seen before.
Depending upon who, what and where you are, this report will bring good news or bad news, but nonetheless – it is news that (I believe) every agent needs to hear, consider, ponder and then decide on. Agencies tomorrow are not “your daddy’s Oldsmobile.” Ask someone older than 40 to explain the phrase. This was the beginning of the end of a legendary line of General Motors automobiles and probably a foreshadowing of the collapse of General Motors. I encourage you to study all three of these documents – they are well-written by very successful folks. Their ideas should be carefully considered, and, if properly adapted to your circumstances, all can improve your results. That is – as long as the world goes as “we the people” in this industry think it should. What follows is my contrarian view – less “raining on your parade” and more clearing the air as you look to the horizon in tomorrow’s consumer-driven economy. We are not in charge. We today are wagering on our individual and industry’s future. Place your bets. The market will pick the winners. See also: 3 Myths That Inhibit Innovation (Part 3)   This contrarian will offer his ideas by looking “back to the future.” There will remain great opportunities in our future, but these will require transformational change. From today’s selling in an industry that is product-defined and product-driven, to a new client-defined and client-driven marketplace where we will facilitate our client’s buying - solving their problems and meeting their needs. In the competitive nature of tomorrow’s world – we’ll have to use artificial intelligence (AI) to anticipate these needs and deliver solutions before our clients “go shopping.” Some of the people, gifts, expertise, disciplines, skills, etc. we’ll need will be much different than the mechanical process we use today. We will need communicators (verbal and nonverbal), empathizers, artists, inventors, designers, storytellers, caregivers, consolers, big picture thinkers, storytellers, caregivers and “techies.” This is not an all-inclusive list. (Consider reading "A Whole New Mind," by Daniel Pink.) Warren Bennis offered the following wisdom decades ago: “The factory of the future will have only two employees, a man and a dog. The man will be there to feed the dog. The dog will be there to keep the man from touching the equipment.” Consider the following – brief observations from one man’s experience:
  • In 1978, Fireman’s Fund/Famex Agents offered a GM-endorsed insurance program for dealers. I was the SW Louisiana agent. In those days, the No. 1 concern of GM and its dealers was that GM would reach 65% market share and the federal government would break GM up into separate companies, Chevrolet, Pontiac, Buick, etc. GM’s arrogance, the dealers’ complacency, foreign competition, a poor product and a marketplace wanting change reshaped their world. GM never made it to 65% market share. I believe the insurance industry is ripe for a similar transformational experience.
  • In 1994, I was speaking to a bank in St. James Parish (Louisiana) about change. I said, “Today, GM, Sears and IBM are the kings of their respective jungles. I believe, in my lifetime, one of these companies will fail.” I was laughed off the stage. Fourteen years later, I was vindicated with the bankruptcy filing by GM. I personally believe that I’ll also prove right on Sears.
  • In June 2008, I was an instructor for attendees in a risk and insurance class at the KPMG Advisory University in Chicago. This was a continuing education week for KPMG consultants. A rookie consultant asked, “How does an insurance company fail?” I explained with the Champion Insurance story.
Then he asked for an example of a “rock solid” insurance company. I said, “AIG.” The KPMG senior partners in the room nodded in agreement. Less than 100 days later, AIG was functionally bankrupt, requiring a $182 billion bailout by the government. None of us saw that coming. (I’ll bet you were surprised, as well.) As I wrap up this article, hoping I've stimulated a much more important discussion about the future, consider the following:
  1. Companies valued at $100 billion are “big” until measured against trillion-dollar operations in a world in transformation – especially if the giants have better technology and data!
  2. Apple, Google, Microsoft and Amazon (AGMA) are kings of their respective jungles. Yet these companies are not even as old as the majority of readers of this column (with the possible exception of Microsoft and Apple, founded in the mid-1970s). Why would we think that our “old and stoic” industry is “safe” and “promising” for tomorrow? Are we celebrating our past when we should be planning our future?
  3. Do you think that any of your clients who have recently received a rate increase will be as enthusiastic about the profitability of our industry and the future of the world of brokers as stated in the article offered by Reagan? I’ve rarely (if ever) heard a client celebrate the profitability of our industry when it is an expense to theirs…
  4. Generational changes, social media and our societal rethinking of issues of race, gender, ethnicity, family, values, economic models (socialism / capitalism), etc. may result in our going in directions that we, 10 years ago, would have never considered possible.
  5. Has our industry let the government get its nose into our tent/economic system. NFIP has been in this industry as long as I have. The private sector didn’t want to address the flood risk. Now, these nearly 50 years later, the flood program is a government program and not sustainable. Unfortunately, the government may be ready to have the camel stand up in the tent? Medicare for everyone is no longer a crazy idea. It may not work, but....
  6. If the insurance industry was being designed today to do what it does, do you really believe it would be what we have? If you answered yes, please reread the question!
See also: What Is Really Disrupting Insurance?   Bookstores, travel agencies, video stores, etc. were important in our communities of yesterday – UNTIL THEY WEREN’T. Should we begin redesigning our own operations and industry and future before a competitive innovator does it for us?

Mike Manes

Profile picture for user mikemanes

Mike Manes

Mike Manes was branded by Jack Burke as a “Cajun Philosopher.” He self-defines as a storyteller – “a guy with some brain tissue and much more scar tissue.” His organizational and life mantra is Carpe Mañana.

'Wild West' of Suits Coming for Wellness

There is panic over the sunsetting of the safe harbor for incentives/penalties for health risk assessments and biometric screenings.

|||
A group of screening vendors and their trade associations have drafted a letter to senators in which they reveal their hitherto unpublished level of panic over the December 2018 sunsetting of the EEOC’s safe harbor for incentives and penalties for health risk assessments and biometric screenings. Their specific words are: "Without clear guidance from the EEOC, we fear a Wild West of litigation could re-emerge as it did prior to the EEOC guidelines... jeopardizing programs that are improving the health of America's workforce." [Note: They offer no support for the assertion that their programs "are improving the health of America’s workforce,” and their own outcomes indicate the reverse.] Their “ask” in this letter is for the Senate to confirm the pending EEOC appointees, including the chairperson, so that rules can be published by January. Unfortunately, that isn’t going to happen, for three reasons. First, the EEOC has already announced that it doesn’t plan to issue rules in January to replace the rules vacated in December. Second, the wellness industry doesn’t understand the way the rule-making process works. It’s a multistep process, laid out by statute, that in the least contentious of circumstances takes many months. Third, the existence of vacancies on the commission has created a backlog of issues needing resolution. The only way wellness rises to the top of that list is if there is indeed a “Wild West of Litigation” in early 2019—which is actually quite likely. We at Quizzify are already aware of one aggrieved group of plaintiffs planning a class action. So what should you do to hold yourselves harmless once the rules sunset? There are two concerns: --Employee lawsuits in your own company. These will be common—especially in outcomes-based programs, owing to their unpopularity. (See page 15 of this report.) Specifically, the Net Promoter Score for wellness is -52, whereas the lowest major industry, cable TV and internet services, scores +2. --Employee lawsuits in other companies. A federal judge’s decision might well affect the landscape—either an entire circuit or the country as a whole. You could be required to give the 2019 premium differential back to employees if your program fits the category of non-voluntary. Vulnerability may be based on 2019 differentials even if the program itself is undertaken in 2018. As Jonathan Zimmerman of Morgan, Lewis and Bockius put it: “Absent guidance from EEOC (which itself would not be binding on the courts), it’s not knowable whether 2019 premium differentials caused by refusal to be screened in 2018 could survive employee legal challenge. Therefore, it is important to create a path for employees this year that allows them to achieve their full ‘points’ total without medical exams or inquiries.” Quizzify indemnifies customers against EEOC lawsuits, thus solving the first problem. For the second, Quizzify offers a simply money-back guarantee that no judicial decision anywhere else will affect their premium differential.replace the EEOC’s sunsetting safe harbor. Instituting this program in 2018 will create a safe harbor and a money-back guarantee for 2019. To learn more, join us for a webinar at 10am CDT on Wednesday, Sept. 19. Contact us at hello@quizzify.com to get the promo code to sign up for free.