Download

Future of Insurance Looks Very Different

The insurance company of the future won’t be an insurance company at all (or at least not just an insurance company).

A few years ago, the satire site, Cracked, launched a series of fake commercials called “Honest Ads” satirizing various industries. One of their fake commercials was an “honest ad” for a fake insurance company selling car insurance. The commercial features a familiar-looking, aging insurance agent in a suit (and a cape, cuz insurance sales people are also superheroes) explaining in a friendly voice what you really get when you buy car insurance. According to this guy, you’ll pay a lot of money every month for a product that:
  • you probably don’t actually want, but will buy anyway, because you have to -– or else you’ll be a criminal;
  • doesn’t offer you any actual protection (even though you could use protection), just a small portion of the money that you pay into it back, but only if something bad happens;
  • you may actually never use, even though you pay a lot of money for it;
  • if you need it, you’ll have to fight your insurance company to be able to use it, even though, again, you pay a lot of money for it; and
  • if you are able to use it, you’ll be punished, by either being charged a lot more money or being kicked off of your policy
Sign me up … ? The effect is a poignant commentary on why people hate insurance and insurance companies and why, even as insurance products may be improving, at the end of the day no one really wants to buy insurance. That’s why we think that the insurance company of the future won’t be an insurance company at all (or at least not just an insurance company). Sure, people will still need insurance, and someone is going to sell it to them, but to win in the future,you'll need to give them more than just insurance, or something else entirely. With this in mind, here are a few ways insurance companies and startups can move beyond insurance to start offering true value to their customers and repair a relationship that has been tarnished by too many years of arcane business practices: 1. Protect your customer. As the Cracked commercial made clear, a lot of insurance companies message themselves as protectors of the home, the family, the car etc., but most do little to protect their customers beyond offering them money when things go wrong – property is still damaged, cars are still stolen, loved ones are still lost. But what if instead of just compensation, insurance companies gave their customers actual protection? The smart home security company Ring, recently acquired by Amazon, was founded with a mission to make people’s homes and neighborhoods safer. In a talk at last year’s InsureTech Connect, Ring CEO Jamie Siminoff explained that “our KPI is around how much crime we reduce, not how much revenue we produce.” Imagine an insurance company that tracked its success in this way. Because Ring invested and tracked against a KPI not just around revenue, but around customer safety, it has been able to prove that homes where Ring is installed are safer homes, which also make for safer neighborhoods -- a fact that has resulted in more revenue and more business opportunities for Ring. Not only was it acquired by Amazon this past spring, but long before that it was able to form partnerships with insurance companies like American Family, which provides customers a discount on a Ring doorbell and a 5% discount on their homeowners or renters insurance. See also: Smart Home = Smart Insurer!   Like Ring, insurance companies should be thinking more about how to protect their customer and less about how to protect themselves from their customer. People don’t generally want to crash their cars, flood their basements, have their homes broken into. Helping customers better protect themselves from the risks that require insurance delivers value to the customer and to the company, and ultimately provides a way for insurance companies to develop trust with their customers. 2. Entertain your customer. When Amazon first made waves as an online bookstore, few would have predicted that Amazon would one day become a major movie studio and video streaming platform. Amazon’s foray into the movie business, announced in 2010, was never about making money in box office sales or online streaming (although Amazon does both). It was about getting more people to sign up for Prime subscriptions and spend more time and money shopping on the site. And Amazon understood that investing in quality entertainment that could be included in a Prime membership was a promising approach. Not that insurance companies need to become entertainment or media companies, too, but investing in high-quality content that people want (and like) to consume can also be a means of selling insurance. The U.K. insurance comparison website, Compare the Market understood that, while people may not like insurance, they definitely like meerkats. Hopping on the meerkat meme bandwagon, the company launched the website comparethemeerkat.com (a play on market, if you didn’t catch that), where consumers can go online and compare sets of meerkats in the way they might compare auto insurance policies or a credit cards. Beyond comparing meerkats on the website, you can also watch short videos (which are also commercials) about the lives of your favorite meerkat characters, like Sergei, head of IT, who joins the circus to escape the stress of his job at comparethemeerkat.com. Although meerkats may have nothing to do with markets, they definitely make the idea of comparing insurance policies and credit cards a lot more fun. And whether I’m in the market for insurance, I’m always in the market for another meerkat meme … and when it comes time to look for new insurance, I know where I’ll go looking. 3. Educate your customer. Fiverr is a freelancer marketplace that provides a platform for freelancers to sell their services, connecting entrepreneurs and workers with the companies and individuals who want to hire them. Just last month, it launched Fiverr Elevate, a platform where Fiverr freelancers can go to take online courses to help them better run their businesses. As Fiverr Freelancers, they earn credits that they can put toward courses. Educating freelancers and small business owners is not what Fiverr is all about, but education is something that benefits customers and would-be customers and allows the company to build a relationship that’s based on value-added, not necessity. Like entertainment, education is sticky and builds trust with customers outside of the core products and services sold, which in insurance is important, considering that the primary interaction a person has outside of binding or renewing a policy is filing a claim in a moment of crisis, after something bad has happened. 4. Solve problems for your customer. While researching and observing workers in the gig economy for an insurance prototype we designed, we heard more than once from gig workers that they probably won't buy additional insurance, even when exposed to additional risk through their work that their existing policies do not cover.. For example, one Uber driver we spoke with used to work at an insurance company and knew that if she got in an accident while driving for Uber she wouldn’t be covered. Yet because Uber didn’t make her buy additional coverage, she decided not to (a lot of people buy insurance because they have to, not because they want to). Another Uber driver we spoke with described the insurance our prototype was offering as “third tier,” meaning that it would be coverage if his personal insurance and Uber didn’t cover him. Like the other driver, he didn’t think he would buy this kind of insurance. He’d rather take the risk. Offering more than just insurance is particularly pertinent for insurance that isn’t mandatory. Insurance needs to solve other problems for customers that aren’t being solved elsewhere. Our gig economy prototype, for example, allowed gig workers to connect all of their apps to our platform, and provided them with a dashboard that would allow them to track all their gig work in one place, analyzing hours and peak earning times, and offering insights that would allow gig workers to optimize their schedules and their earnings. While at the end of the day our prototype was selling insurance, the users we talked to ultimately wanted to buy it not because it was insurance, but because it was more than insurance – and it was solving an important problem they were experiencing as gig workers. Jetty, the renters insurance startup, is doing something similar. Beyond selling renters insurance, it is also helping solve a critical problem for millennials living in cities. Jetty Passport helps people get into apartments more easily by paying security deposits and acting as guarantors. For a fraction of the price of the security deposit and for an additional 5-10% of the rent, customers don’t have to worry about either. For those using Jetty Passport, Jetty renters insurance, starting at $5 a month, is a no-brainer. See also: Startups Take a Seat at the Table   5. Follow your customer. While it may be true that most people don’t like buying insurance, there are a lot of other things these same people do like buying. Airplane tickets, clothing and apparel, stuff for their house. Finding out what else your customers are doing and buying (and where), and selling them insurance through these channels can help insurance companies align themselves with companies their customers actually do like and trust, while also lowering the cost of customer acquisition so you can offer more competitive pricing. In March, AIG Travel announced that it is partnering with Expedia to sell travel insurance on Expedia sites, including Expedia.com, CheapTickets, Orbitz, and Travelocity, giving Expedia customers booking flights, hotels and other travel arrangements the option to insure their bookings for a small fee. AIG also announced a partnership with United Airlines to do the same earlier in the year. Slice insurance, the homeshare insurance startup, has done something similar, partnering with AirBnB to sell hosts on-demand insurance when renting out their homes. These types of partnerships are a win-win for customers, insurance companies and the platform partners. Platforms get to expand their offering to their customer; insurance companies get to build a direct relationship with customers through a channel they like and trust' and they get access to more customer data to better understand purchasing behaviors outside of insurance. Customers get easy access to insurance coverage that will benefit them without having to go out of their way to make an additional transaction. — It’s no secret that insurance companies have an image problem, one that has been created over more than a century of legacy business practices that make transforming, innovating and developing more customer-centric products easier said than done. But as insurance companies do the heavy lifting to make their businesses more agile and responsive to the market, finding ways to go beyond insurance –through education, entertainment, creative problem solving and thoughtful partnerships– will help them build more trusting relationships with customers and not only maintain current customers but expand into new markets. You can find the article originally published here on Cake & Arrow.

Emily Smith Cardineau

Profile picture for user EmilySmith

Emily Smith Cardineau

Emily Smith Cardineau is the Director of Content & Insights at Cake & Arrow, a customer experience agency providing end-to-end digital products and services that help insurance companies redefine customer experience.

Facebook, WhatsApp Are Dangerous

If these companies were cars, Facebook would be the one without safety belts — and WhatsApp the one without brakes.

Facebook’s woes are spreading globally, first from the U.S. to Europe and now in Asia. A landmark study by researchers at the University of Warwick in the U.K. has established that Facebook has been fanning the flames of hatred in Germany. The study found that the rich and the poor, the educated and the uneducated, and those living in large cities and those in small towns were alike susceptible to online hate speech on refugees and its incitement to violence, with incidence of hate crimes relating directly to per-capita Facebook use. And during Germany-wide Facebook outages, which resulted from programming or server problems at Facebook, anti-refugee hate crimes practically vanished — within weeks. As the New York Times explains, Facebook’s  algorithms reshape a user’s reality: “These are built around a core mission: promote content that will maximize user engagement. Posts that tap into negative, primal emotions like anger or fear, studies have found, perform best and so proliferate.” Facebook started out as a benign open social-media platform to bring friends and family together. Increasingly obsessed with making money, and unhindered by regulation or control, it began selling to anybody who would pay for its advertising access to its users. It focused on gathering all of the data it could about them and keeping them hooked to its platform. More sensational Facebook posts attracted more views, a win-win for Facebook and its hatemongers. See also: Too Much Tech Is Ruining Lives  
India
In countries such as India, WhatsApp is the dominant form of communication. And sadly, it is causing even greater carnage than Facebook is in Germany; there have already been dozens of deaths. WhatsApp was created to send text messages between mobile phones. Voice calling, group chat and end-to-end encryption were features that were bolted on to its platform much later. Facebook acquired WhatsApp in 2014 and started making it as addictive as its web platform — and capturing data from it. The problem is that WhatsApp was never designed to be a social-media platform. It doesn’t allow even the most basic independent monitoring. For this reason, it has become an uncontrolled platform for spreading fake news and hate speech. It also poses serious privacy concerns due to its roots as a text-messaging tool: Users’ primary identification being a mobile number, people are susceptible everywhere and at all times to anonymous harassment by other chat-group members. On Facebook, when you see a posting, you can, with a click, learn about the person who posted it and judge whether the source is credible. With no more than a phone number and possibly a name, there is no way to know the source or intent of a message. Moreover, anyone can contact users and use special tools to track them. Imagine the dangers to children who happen to post messages in WhatsApp groups, where it isn’t apparent who the other members are; or the risks to people being targeted by hate groups. Facebook faced a severe backlash when it was revealed that it was seeking banking information to boost user engagement in the U.S. In India, it is taking a different tack, adding mobile-payment features to WhatsApp. This will dramatically increase the dangers. All those with whom a user has ever transacted can harass them, because they have their mobile number. People will be tracked in new ways. Facebook is a flawed product, but its flaws pale in comparison with WhatsApp’s. If these were cars, Facebook would be the one without safety belts — and WhatsApp the one without brakes. That is why India’s technology minister, Ravi Shankar Prasad, was right to demand that WhatsApp “find solutions to these challenges which are downright criminal and violation of Indian laws.” The demands he made, however, don’t go far enough. Prasad asked WhatsApp to operate in India under an Indian corporate entity; to store Indian data in India; to appoint a grievance officer; and to trace the origins of fake messages. The problems with WhatsApp, though, are more fundamental. You can’t have public meeting spaces without any safety and security measures for unsuspecting citizens. WhatsApp’s group-chat feature needs to be disabled until it is completely redesigned with safety and security in mind. This on its own could halt the carnage that is happening across the country.
Lesson from Germany
India — and the rest of the world — also need to take a page from Germany, which last year approved a law against online hate speech, with fines of of as much as 50 million euros for platforms such as Facebook that fail to delete “criminal” content. The E.U. is considering taking this one step further and requiring content flagged by law enforcement to be removed within an hour. The issue of where data are being stored may be a red herring. The problem with Facebook isn’t the location of its data storage; it is, rather, the uses the company makes of the data. Facebook requires its users to grant it “a non-exclusive, transferable, sub-licensable, royalty-free, worldwide license to use any IP content” they post to the site. It assumes the right to use family photos and videos — and financial transactions — for marketing purposes and to resell them to anybody. See also: The World Doesn’t Need Silicon Valley   Every country needs to have laws that explicitly grant their citizens ownership of their own data. Then, if a company wants to use their data, it must tell them what is being collected and how it is being used, and seek permission to use it in exchange for a licensing fee. The problems arising through faceless corporate pillage are soluble only through enforcement of respect for individual rights and legal answerability.

Vivek Wadhwa

Profile picture for user VivekWadhwa

Vivek Wadhwa

Vivek Wadhwa is a fellow at Arthur and Toni Rembe Rock Center for Corporate Governance, Stanford University; director of research at the Center for Entrepreneurship and Research Commercialization at the Pratt School of Engineering, Duke University; and distinguished fellow at Singularity University.

Important Perspective for Insurance Agents

New legislation says that only "natural" persons must carry a license -- so, AIs can do whatever they and their creators want.

By pure chance, at a completely non-insurance event, I found myself seated next to a deputy commissioner of insurance for a prominent state. This deputy commissioner, when he learned through the pleasantries of exchanging minor personal information around the table that I consulted for insurance agencies, let me know in no uncertain terms that he thought agents were mostly scumbags. It was a wonderful way to embark on a two-hour dinner with strangers. His perspective was that he saw so many cases of agents selling the wrong coverages, purposely selling inadequate coverage and leading clients to believe they had far more coverage than they had. Honestly, through all the E&O work I do, I cannot disagree. It happens every single day. I do not know that I agree agents do so from an unethical basis as much as an incompetency basis, based on my E&O audits, but the issue is real. And I understand from a department's perspective that only sees the problems and never hears about the good outcomes (how many insureds call their department of insurance to exclaim how great their agents are?) that their perspective would be highly biased. I get that. The examples are plentiful. An industry newsletter that often lists new E&O cases recently included cases for a multimillion-dollar coverage shortfall, failure to disclose a major exclusion, an agent arguably not providing realistic client expectations and an agent advising a client they didn't need more than $x liability limits. A separate recent list of E&O claims followed a natural catastrophe, and, while the data I reviewed was limited, it suggested strongly that most of the situations were caused by agents not selling the right coverages or coverage limits. Some of the situations were truly massive incompetency on the part of the agent. An example might be something like advising someone flood was not necessary when the house was on the water or that the client had coverage for a business in the home when the policy specifically excludes such coverage unless the endorsement was purchased. I am not suggesting these are the claims, but these are the types of claims. See also: Agents, Brokers Are Dead? Not So Fast!   I can understand the insurance department thinking agents are scumbags, although I truly prefer thinking these agents are just incompetent. Idiocy feels better to me than the connotations of a scumbag. Insurance departments have a role in this because, as one Michigan judge ruled not long ago, the licensing requirements for an agent are less than that of a beautician. Insurance departments could always raise the licensing standards. Insurance associations and their members are at fault, too. I have heard for decades how agents want to lower the standards of care, so they are less likely to be sued and, if sued, more likely to win. I have heard E&O attorneys and instructors pound into agents' heads to not increase their standards of care. This is truly the epitome of cutting off one's nose to spite their face. If agents want licensing standards far less stringent than someone who paints nails (I am not saying painting nails is not a difficult profession that requires considerable training to avoid injuring a client's fingers or toes) and if agents and their associations want standards of care so low the agent is basically not responsible for much of anything, then in reality who needs a licensed insurance agent? My conclusion is: Absolutely no one. Which brings me to two new legal developments. The first is legislation whereby only "natural" persons will be required to carry a license but non-natural persons, i.e., artificial intelligence computers selling insurance, will not be required to carry a license. This is real and likely to pass. Think about this just for a moment or more. The computer will have no standard of care because it won’t be licensed, and, with no offense, though it may be offensive, an incompetent but licensed human cannot compete with an unlicensed supercomputer that actually probably is fairly competent. Another development is a recently passed law that requires insureds to "understand" their insurance. How any reasonable person could vote for a law that requires a consumer to "understand" their insurance is beyond me. That is an impossible standard, but it negates a standard of care for agents and companies. In fact, it makes agents mostly irrelevant because companies can then sell whatever to consumers, and the consumer loses the middleman agent, the good ones of which are fantastic protectors of clients from insurance companies and incompetent and scumbag agents. That law might be applauded by agents who want no responsibility for selling clients the coverages they truly need. It probably is being applauded by certain companies, especially those that like to cut corners. (As an aside, I wanted to ask the deputy commissioner about his department's efforts to prohibit some companies' filings of policies that actually provide almost no coverage, but that seemed pointless.) I hate it that insurance commissioners and others think of agents as scumbags. These perspectives make it so hard to create trust for those who do their job well and with pride. Someone else at the table asked me if all agents are scumbags, and I explained that in my interactions with thousands of agents over 30 years a large percentage of agents are absolutely the best. They take to heart their clients' coverage needs. They are extremely well-educated in the coverages clients need. They work hard to protect clients from companies, especially when a company is not interpreting coverage correctly after a claim. These are good, hard-working, ethical people who make a positive difference in people's lives. See also: Use Insurtech to Help, not Replace, Agents The high road is always the hardest road. By definition, the high road means climbing, working against gravity and working hard. The low road goes downhill. You know what rolls downhill. With the new laws being passed and promulgated, with many companies working to push aside agents, with the "scumbag" perspective many important people have of agents and the industry, with how insurtech and AI are working to replace agents in some venues, understand all these forces are aimed at eliminating incompetent agents. Incompetent agencies are paid too much, and their extinction creates a cost savings. The low road leads nowhere good. The high road is the ethical, positive legacy and financially beneficial road. If you want to learn more about the high road and if you do not already know where that road is and how to counter all the negatives, let me know. I have created a special path for those wanting to develop a high road that makes their clients' lives better and ultimately rewards them financially and in their hearts.

Medicare Set Asides: You Are Overpaying

Submitting an MSA to CMS for review and approval builds in unrealistic costs that can double the expenses for the workers' comp payer.

Medicare Set Asides (MSAs) have become a standard feature in settling workers’ compensation claims over the past 15 years. This year, MSA proposals for 26,000 workers’ compensation claims might be submitted to the federal government. We present new evidence that strongly suggests that this voluntary process of submission predictably and excessively inflates the cost of claims. For claims payers who are concerned about the burdens of set asides, this problem and its solution are top news. Workers’ compensation claims payers far over-spend on Medicare set-asides (MSAs), paying as much as double what they need to. The conventional practice of submitting a MSA report to CMS for review and approval, which is entirely voluntary, predictably inflates costs and overburdens claims payers. Claims payers simply need to change their gameplan. This year alone, for some 26,000 claims and at an average of about $93,000, claims payers will set aside funds to reimburse Medicare for any medical care Medicare delivers to injured workers to treat their work injuries. I became involved in this massive, cumbersome process of financial resolution in 2000. I participated and watched as most claims payers selected to follow a certain game plan. They’ve stuck to it. In a nutshell, here is what happens, at an annual outlay of more than $2 billion. At the time of a claims settlement, claims payers want to cap their future financial exposure to Medicare. They know that if they submit to Medicare a report for funding (“set aside”) a fixed, irrevocable amount of money for treatment under Medicare, and Medicare approves the report, they can wash their hands of the claim. This method of resolution spawned a small industry of firms that help claims payers prepare these reports and negotiate an amount. Problem solved – but at a very high cost. First, the process is extremely convoluted and time-consuming. Our company’s survey of three dozen claims payers, which we undertook in 2016, revealed a very low level of trust in the process. Due to the involvement of Medicare, it is inherently bureaucratic. Second, these irrevocable set-aside plans (“MSA reports”) tend to be extremely costly. They greatly inflate the projected treatment costs over actual treatment costs. See also: 8 Questions on Medicare Set Aside   Our company recently analyzed several hundred approved reports. We compared the forecasted spending on medical care (surgeries , medication, etc.) with actual spending on behalf of the injured worker for the first five years post approval of the MSA report. We found that in the fifth year, the pace of medication spending was 64% of the forecast and for all other medical care 55%. In other words, close to half of the funds locked up in the MSA reports were not being used! Another study confirms how medical spending declines for many claimants over time. We analyzed a huge database of eight million non-settled workers’ compensation claims, noting medical spending for as much as 11 years after injury. We focused on opioid treatment patterns, as opioids are both expensive and create patient safety risks. The data showed a rapid early decline, as we expected. But it strikingly showed that the decline in use never ceased. For instance, for every 100 claimants who were actively using opioids in the fourth year post injury, only 50% were using opioids in the seventh year and 25% were using opioids in the tenth year. Why don’t MSA reports anticipate that medical spending will go down? The reason is due to mandatory rules that Medicare imposes. If you elect voluntarily to submit an MSA report, you must follow these rules, three of which are worth noting: First, Medicare requires that medications (which compose about half of all set-aside budgets combined) be priced unrealistically high, at Redbook “average wholesale price,” or AWP. I cannot imagine a claims payer paying for drugs at that price. Pharmacy benefit managers arrange for prices that are as much as 30% lower. Second, Medicare unrealistically requires that all medications be budgeted unaltered for the projected life of the injured worker. The average life expectancy for an MSA is 24 years. There is no scientific assurance whatsoever that opioids are effective in providing long-term relief from pain, much less being safe to use for 24 years. Third, Medicare requires that any treatment the worker is receiving or has planned at the time of settlement will continue. In reality, treatment evolves as patients adapt. Rather than submit an MSA report, which locks the claims payer in to an inflated and unalterable fixed amount, the claims payer can prepare a MSA plan for the large majority of claims using realistic forecasts, fund it and enjoy a cap on its financial liability without submitting a report. CMS has always recognized a non-submitted, funded plan as sufficient to satisfy its secondary payer rights so long as certain compliance steps are taken, and in fact states that the submission process is a voluntary one. See also: Medicare Set Asides: 10 Mistakes to Avoid   There is a way to realistically predict the medical spending: refer to a huge database of actual spending. Care Bridge’s analytic-powered MSA generates a Medicare Set Aside plan in minutes, based on machine learning algorithms of more than a billion medical claim transactions. It forecasts future medical care and costs at a zip code level. The variables of a claim can be matched against a large data set of similar claims to forecast care, which offers a more objective and accurate projection compared with current methods. Our clients are able to fund Medicare protection at the most probable cost, rather than an inflated cost, and settle claims  six to eight months faster. This  offers  a defensible way to protect Medicare and manage risk at a more realistic cost. An authoritative white paper, “Medicare Set-Asides: What Is the True Cost of Future Medical Care?” is available here.

Deborah Watkins

Profile picture for user DeborahWatkins

Deborah Watkins

Deborah Watkins is the former CEO of Gould & Lamb, the global leader in full-service Medicare Secondary Payer Compliance. She has worked closely with the Centers for Medicare and Medicaid Services (CMS) and congressional staff advocating for improvements in the Medicare Secondary Payer program.

Does Amazon Threaten Home Insurers?

With an insurtech revolution already starting, how long will it be before the likes of Amazon and Google enter the home market in a serious way?

Amazon has made no secret of its intent to disrupt virtually every industry on the planet, most recently announcing a partnership with JPMorgan Chase and Berkshire Hathaway to create an independent healthcare company. Reportedly, the retail giant has also begun to explore the idea of setting up an insurance price comparison site in the U.K.

The formula is now clear. Amazon and other consumer-first digital disruptors like Google set their sights on a conventional industry with aging distribution and marketing channels, then things start to change rapidly. With an insurtech revolution already starting to brew in the home insurance marketplace, how long will it be before the likes of Amazon and Google enter the market in a serious way? And, if they do, will customers welcome them?

While industry incumbents like State Farm, Allstate and Progressive have begun to speculate on potential scenarios for this kind of digital disruption, J.D. Power’s P&C insurance industry practice went right to the source – the consumer – to ask how real home insurance customers would feel about the presence of tech companies in this space.

Following were the key findings from the J.D. Power Pulse Survey:

20% of Consumers Would Use Amazon or Google for Home Insurance The data revealed that 20% of consumers would use an Amazon or Google for their home insurance. Millennials showed even higher interest at 33% for Amazon and 23% for Google. Of those who indicated that they would be willing to switch, 80% currently have insurance with a large national carrier.

See also: What if Amazon Entered Insurance? 

75% of Consumers Interested in Home Telematics While most of the media’s attention has focused on the future of automation technology in automobiles, the disruption to your home experience – and by extension your home insurance – through smart home technologies is likely to have an equal or greater impact. Smart home technologies are revolutionizing many areas of the home, from simple comfort features that can now turn lights on and off or access in-home entertainment by control of your phone to home security and emergency support with automatic shutoffs and alerts.

The insurance industry wants in on the action. Insurers see smart home technologies as an opportunity to deepen their relationships with customers, while improving home coverage options and underwriting. While leading home insurance carriers have begun to venture into these areas, not much research has been done to understand the consumer’s demand as these features become available.

Based on the J.D. Power Pulse Survey, following are insights into the current consumer appetite for this type of technology:

  • Top areas for insurtech disruption: Among consumers polled, following are the top area of their relationship with their home insurance provider that needs the greatest improvement:
    • Product Options/Coverages – 20%
    • Underwriting Sophistication – 15%
    • Claims – 14%
  • Top insurtech technologies: Among consumers polled, following are the top technologies consumers are most excited about coming to the insurance industry:
    • Cybersecurity – 36%
    • Blockchain – 25%
    • Internet of Things (IoT) – 24%
  • 75% of consumers are interested in home telematics. While the bulk of talk on telematics has been focused in the automotive space, home insurance customers are overwhelmingly interested in getting discounts on their homeowners insurance for proper home maintenance and security.
  • 46% of consumers would be willing to allow their home insurance company access to smart home sensor technology in appliances, such as refrigerators and air conditioners to help prevent loss and malfunction (smart tech loss prevention). 56% of consumers who currently have “smart” tech in their home would allow access

See also: 5 Misunderstandings on Home Insurance  

  • 34% of consumers would likely switch to a home insurance company that offered smart home technology loss and protection options:
    • 57% of millennials would likely switch
    • 40% of consumers who currently have “smart” tech in their home would be likely to switch (64% of consumers reported having some sort of smart tech in their home, such as a smart thermostat, doorbell, etc.)

Keys to Migrating Policy Data

Policy data migration can deliver mature books of business to new policy handling systems and decommissioning of legacy systems.

|
Insurance policy data migration, namely the process by which insurance policies are transferred from one or more source systems to one or more target systems, can be of strategic importance to insurers undergoing core policy system transformation for a number of reasons:
  1. When a legacy policy system is replaced with a net new policy platform, the new platform may deliver additional functionality, but it is the policy data migration that has the potential to deliver mature, profitable books of business to the new platform. As such, in many cases, the underlying business case for a core policy system replacement relies heavily on successful policy data migration.
  2. Legacy policy system decommissioning relies on successful data migration; it is not possible to decommission a policy system until all significant books of business have been migrated off it. As a consequence, building a strong data migration capability able to quickly migrate books of business off legacy policy systems cuits the cost of running the IT estate, freeing funds and resources for other value add activities.
  3. Unsuccessful data migration carries significant downside: poor data quality of migrated policies, lost-in-translation policies that are extracted from the source system but that never land in the target system and data breaches related to migrated records. It is in the interest of insurers to invest in data migration upfront to get it right the first time around.
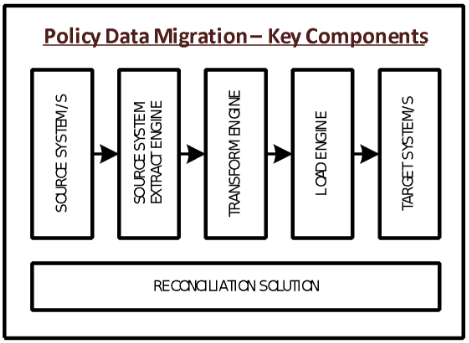
See also: 4 Steps to Ease Data Migration   Although each policy data migration has its own characteristics, most share the following architectural components:
  • Source System/s: the source system/s from which policies are being migrated.
  • Source System Extract Engine: component extracting policies from the source system/s.
  • Transform Engine: component transforming the policies extracted from the source system into a format that can be accepted by the target system/s.
  • Target System/s: the target system/s into which policies are being migrated.
  • Load Engine: component committing the output of the Transform Engine into the target system/s.
  • Reconciliation Solution: component counting migrated records at key steps in the policy data migration flow, to ensure that all extracted policies ultimately land in the target system/s.
Below are some points to consider when designing insurance policy data migration, paired with some experience-based points of view. 1. Target system/s and architecture should be built so that policy data migration can be effective:
  • When designing the target policy system, and all the systems around it, the impact of solution decisions on data migration should be considered. For example, a decision to introduce a net new solution to handle party-centricity may have a limited impact on new business flows, but a significant impact on data migration. If the data migration impact is disregarded, then the project may find further down the line that data migration is prohibitively complex to perform because of the party-centricity solution.
2. Policy data migration should be considered at a company level, rather than at a divisional level:
  • Within insurance companies, in many cases books of business residing on source systems relate to multiple divisions. For example, source systems X, Y and Z may each have books of business from retail, commercial and specialty. When this is the case, it is important to ensure that data migration is considered at a company level, to ensure that books of business are migrated in such a way that decommissioning is feasible. Otherwise, the risk is that policy data migration programs driven by a single division may fail to capture the value derived from decommissioning source systems, as on each source system there may be books of business other than those that the specific division is migrating.
3. The pipeline of policy data migrations should be developed in parallel to the timelines for core policy system replacement:
  • A common error related to policy data migration planning is to delay it until after the detailed planning for the core policy system replacement program is complete. The risk is that only too late will it become apparent that the rate at which books of policies can be migrated is insufficient to complete the data migration within the program timelines. In some cases, the rate may be so slow, for example no more than two books of business per calendar year, that it is not even possible to migrate all books from source to target before the target itself becomes legacy and is replaced.
4. Migration reconciliation should be catered for with either an automated or manual solution:
  • Reconciliation with regard to policy data migration entails two elements: firstly, counting that all the records that are extracted are transformed, and that all the records that are transformed are then loaded into the target architecture, and secondly, determining what has happened to dropped records. For example, if during a data migration cycle 100.000 records should be extracted, transformed and loaded, but only 99,980 are extracted, 99,960 are transformed and 99,940 are loaded, it is the reconciliation solution that should highlight that 20 records have been dropped at each step, and that should indicate what has happened to each of the 60 records.
5. There is significant benefit in defining the goals of each policy data migration in a single sentence:
  • Not everyone is familiar with data migration, so defining what data migration is looking to achieve in a concise manner provides a clear platform to engage non data migration stakeholders. Below is a template sentence using letters to highlight key data migration elements:
    • The data migration for book of business X needs to migrate Y records from source system M into target system Z at a load success percent of T at a rate of R records per second.
6. The decision on whether to migrate policies as quotes or as live policies should be made early in the solution process:
  • When performing policy data migration, the options are to migrate policies into the target system/s as live policies, or as quotes that then convert into live policies a number of days before their renewal date. The advice is that unless there are strong reasons to migrate records as live policies, it is best to migrate as quotes that then convert into policies, as loading as live policies introduces complexity around the live elements of the policies, such as billing accounts.
7. Policy data migration performance implications should be considered upfront:
  • Where the data migration components use transactions that are either shared with new business, or particularly complex and performance-heavy, it is important to ensure that performance implications are considered. For example, a transaction that is used 10 times per minute in new business may be used 1,000 times per minute in data migration, which may cause contention issues. Consequently, both the target architecture and the data migration solution should be designed to avoid performance bottlenecks.
See also: The Rise of Big (Bad) Data   Key takeaways:
  • Policy data migration in insurance has the potential to drive significant business value in that it can deliver mature books of business to net new policy handling systems, and it may allow decommissioning of legacy systems.
  • Most policy data migrations share common components, namely Source System/s, Source System/s Extract Engine, Transform Engine, Target System/s, Load Engine and Reconciliation Solution.
  • Designing a policy data migration is not simple; leveraging insights from previous data migrations may be the difference between success and failure.

How Tech Is Eating the Insurance World

It would be foolish to think that Amazon, et al. will enter the industry to play nice and simply serve as brokers or lead generators.

Amazons and Apples and Googles. Oh my… What do these companies have in common? Devout brand loyalty from the modern consumer coupled with world-leading technology. This poses a massive threat to insurance companies that value ownership of the customer above all else and are seriously lagging on tech. In a post-financial crisis world where financial brands are reflexively distrusted by modern consumers that have incredibly high digital UX standards, technology brands and emerging insurtech startups have a considerable advantage in winning future insurance business. Amazon, Apple, Google and other tech giants don’t do anything small. It would be foolish for insurers to think that these disruptors will enter the industry to play nice and simply serve as their brokers or lead generators. They have capital in spades, massive captive audiences, piles of valuable data and are perfectly comfortable navigating complicated regulatory landscapes. Insurers like to hide behind this regulatory complexity as a reason to dismiss new market entrants, but this is simply a speed bump for those who want to make insurance a point of focus – not an insurmountable barrier to entry. The Google Experience Google dipped its toe in the industry in 2015 with Google Compare and then quickly withdrew in 2016. Insurers like to point to this as the shining example of how technology companies “don’t understand insurance” or how they “underestimate the complexity of the industry.” What they forget (or simply don’t mention) is Google’s core business model – advertising. What is the sixth most expensive word on Google AdWords? Insurance ($48.41 per CLICK!). Who buys that word and drives significant revenue to Google? Insurers. Google's exit was not the result of execution failure or naivete; it was a consequence of rocking the boat with some of their highest-value advertising customers. The rest of the companies listed above, among countless other tech giants and well-funded startups, do not have that same conflict. Insurers are not immune to disruption from them. Shifting Consumer Behavior The modern consumer is a digital native and does not want to speak to people on the phone or fill out piles of paperwork. Consumers want to be offered insurance when it’s top of mind – how they want it, when they want it, from brands they trust, instantly. One of the biggest problems we see with tech-insurance partnerships is insurers’ insistence on controlling the underwriting and sales process, which creates massive friction with technology companies that offer far superior digital experiences. Consumers don’t want to leave Amazon to start a separate purchasing process on an insurer’s website, and Amazon doesn’t want them to leave its site, either. This is something that is easily solved through API-driven technology systems and programmatic underwriting – words that often give insurers heart palpitations. See also: What if Amazon Entered Insurance?   Consumers don’t want to shop around for insurance on quote comparison sites. They don’t want to engage with insurance companies more than necessary or share troves of personal data through an insurance app. They want to purchase insurance when they need it, pay for what they use and never think about it again. Insurance incumbents have responded by building their own apps, offering discounts for more shared data and doubling down on advertisement spending. Insurance in the Background Insurance is an important feature, but not always the star product. It’s sold well to the modern consumer either purely digitally or as part of a broader offering – typically at the point of purchase for a non-insurance product or service. That’s an unpleasant thought for insurers that take a tremendous amount of pride in their history, processes and brands. However, letting pride and status quo dictate your business strategy is a good way to get your business killed. Why not offer homeowners insurance in 15 seconds (not minutes) through fully digital workflow like Kin does? Why not combine cyber protection software and cyber insurance like Paladin Cyber does, so risk is reduced even further in the event of a cyber incident? Why not offer white-labeled SMB insurance to the millions of third-party retailers currently selling on Amazon? Or episodic renter’s coverage directly through Airbnb at the point of booking? Here are a few reasons why insurers aren't being more innovative:
  • insurers’ technology simply can’t support seamless distribution through digital platforms
  • insurers/agents/brokers insist on owning the customer
  • insurers don’t want to alienate their traditional distribution network of brokers and agents
  • insurers want full underwriting control through traditional, and often analog, methods
  • insurers don’t want to share data with tech companies but expect tech companies to open their proprietary analytics models to insurers.
This simply will not work. The Everything Store Apple already disrupted the warranty space by owning the whole AppleCare stack for themselves. Google has the conflicts discussed earlier. Facebook has the same. As a result, I believe Amazon is the most likely tech giant to make a big splash in the insurance industry as they continue to build their “Everything Store.” We already see what they’re doing in healthcare, their investment in Acko in India, and rumors about an imminent play in banking. They recently acquired Ring, which has obvious insurance applications, for a reported $1 billion. The writing is on the wall. While I’m not entirely convinced that consumers will search Amazon.com for auto or home insurance, having millions of third-party seller merchants, adding 300,000 in the U.S. in 2017 alone, is a good starting point as far as addressable commercial insurance markets are concerned. See also: 11 Ways Amazon Could Transform Care   I am a huge admirer of what Jeff Bezos has built at Amazon, and I’m modeling Boost after what they did in the data storage and hosting space with AWS. It would be foolish for anyone to underestimate the impact a company like Amazon can have on any industry – no matter how old, established or huge the insurance incumbents’ businesses may be. Just ask Barnes & Noble, Walmart, media companies or any grocery store right now.

When the Silicon Valley Model No Longer Works

sixthings

Ever since the early 1980s, I've been hearing about how Silicon Valley was passé, soon to be duplicated in other parts of the world and ultimately supplanted. So I've become more than a little jaded as the years have passed and the valley has not only thrived but has spread south toward San Jose and positively taken over San Francisco. The valley has even spread across the Bay Bridge and is heading east. I have a daughter trying to find an apartment in Oakland, and...yikes, it's expensive.

But Silicon Valley has planted the seeds of its own irrelevance, and it's time to start planning for what comes next. Certainly, incumbents like those in insurance need to move past the Silicon Valley model.

I'm not saying that another location—Chicago's Silicon Prairie or New York's Silicon Alley—will take its place, but the sorts of communication tools developed in the valley make it a lot easier to communicate with investors, so startups don't need to cluster around Sand Hill Road any more. The cloud, another gift from the valley (and its northern outpost, Seattle), means computing power is plentiful and cheap. Money is everywhere. The success of the valley's venture capitalists has made sure of that, and hot startups have seeded certain areas—Doubleclick multimillionaires in New York, Groupon multimillionaires in Chicago, Baidu and Alibaba multimillionaires throughout China. Expertise and the entrepreneurial spirit have spread, too. Stanford and Cal no longer have a lock.

The expense of the valley will also tend to drive people away. If you don't absolutely have to be in the valley, why not set up shop in places your people can afford: like Ohio, as Silicon Valley star Mark Kvamme did, or Washington, DC, as AOL's Steve Case did? The bar at the Rosewood Hotel in Menlo Park is quite the scene on Friday night, but you can get your Clase Azul tequila for a lot less elsewhere.

Even more important from the standpoint of insurers, the Silicon Valley model doesn't fit that well. For one thing, most of what we think of it is myths (which Vivek Wadhwa does a nice job of debunking here). For another, insurance can't be transformed just by a bunch of computer scientists, no matter how smart. Industry knowledge is required more than in perhaps any field this side of medicine—as Zenefits learned the hard way. The Silicon Valley ethos of "move fast and break things" (as memorably summarized by Facebook) doesn't work in insurance, either. Regulators won't let you break things, nor should they when we're talking about something like a person's health insurance or life insurance. Finally, the valley's alpha approach has led to rampant issues with sexism, as summarized in the recent book "Brotopia."

Why, then, is there still so much "innovation tourism" to Silicon Valley as insurers look there for answers to their innovation questions?

A different model is needed. It must draw on the audacity of Silicon Valley and its ability to take out a clean sheet of paper and reimagine almost anything. But the model must also fit within the regulatory environment of insurance, within the structure of incumbents and their insurtech partners and within insurance's peculiar constraint: that you often can't know your cost of goods until years or even decades after you sell a policy.

Helping define that model is what keeps us excited about ITL and about our Innovator's Edge platform. We hope you're excited, too.

Have a great week.

Paul Carroll
Editor-in-Chief


Paul Carroll

Profile picture for user PaulCarroll

Paul Carroll

Paul Carroll is the editor-in-chief of Insurance Thought Leadership.

He is also co-author of A Brief History of a Perfect Future: Inventing the Future We Can Proudly Leave Our Kids by 2050 and Billion Dollar Lessons: What You Can Learn From the Most Inexcusable Business Failures of the Last 25 Years and the author of a best-seller on IBM, published in 1993.

Carroll spent 17 years at the Wall Street Journal as an editor and reporter; he was nominated twice for the Pulitzer Prize. He later was a finalist for a National Magazine Award.

Suddenly, Driverless Cars Hit Bumps

Recent tests cast doubt on the efficacy of driver-assist technologies and thus on how soon full autonomy is likely to affect auto insurance premium.

|
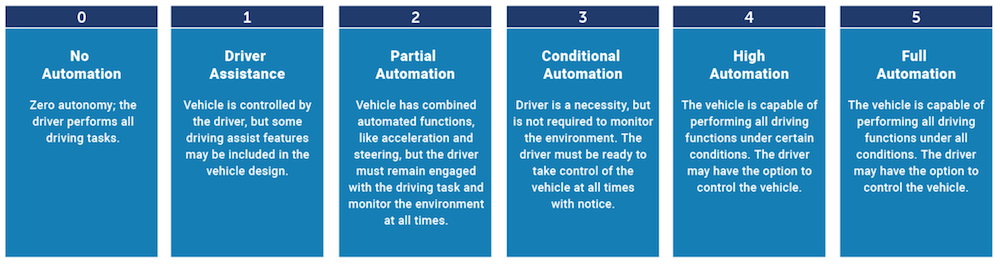
Recent tests by The Insurance Institute for Highway Safety on two key ADAS capabilities cast doubt on the efficacy of these technologies and thus on how soon full autonomy is likely to affect auto insurance premium. Anyone insuring automobiles is paying a lot of attention to the development of ADAS (advanced driver assistance systems) and of fully autonomous vehicles. Many of the underlying technolgies used in ADAS (e.g. cameras, radar, lidar, AI) will also be used in fully autonomous vehicles. However, the demands that a fully autonomous vehicle places on these technologies are quite different than the demands of an ADAS-equipped vehicle. ADAS-equipped vehicles will pass control to and from human drivers (or send warnings to human drivers) in various circumstances. Fully autonomous vehicles will have no hand-offs and no warnings because there are no human drivers to receive them. The Insurance Institute for Highway Safety (IIHS) recently ran a series of tests of two key ADAS capabilities: adaptive cruise control (ACC) and active lane keeping. ACC maintains a set speed and a specified distance from a car in front of the car with ACC. Active lane keeping automatically maintains the car within its current lane. See also: Autonomous Vehicles: Truly Imminent?   Vehicles with ACC and active lane keeping are at Level 2 on the SAE International scale. This is a widely recognized framework demarcating degrees of autonomy — ranging from Level 0 (no automation) to Level 5 (fully autonomous). [caption id="attachment_32988" align="alignnone" width="570"] Source: NHTSA https://www.nhtsa.gov/technology-innovation/automated-vehicles-safety[/caption]

Notice that Level 2 is a long way from Level 5.

The IIHS tested five well-regarded vehicles:
  • A 2017 BMW 5-series with “Driving Assistant Plus”
  • A 2017 Mercedes-Benz E Class with “Drive Pilot”
  • A 2018 Tesla Model 3 and a 2016 Model S with “Autopilot” (software versions 8.1 and 7.1, respectively)
  • A 2018 Volvo S90 with “Pilot Assist.”
The results of these tests were reported in IIHS and HLDI publication, Status Report (Aug. 7, 2018). The results were not pretty.
  • In one test on a public roadway, the Mercedes was aware of a stationary vehicle in front of it but continued without reducing speed, until the human driver applied the brakes.
  • In a 180-mile test drive, the Tesla Model 3 slowed without an appropriate cause 12 times (including seven instances of tree shadows on the road).
  • In testing active lane keeping on curves; the BMW, the Mercedes and the Volvo were unable to stay in their lane without the driver providing steering assistance.
  • The vehicles’ active lane keeping capability was also tested when they reached the top of hills. At the top, some cars’ technologies essentially lost sight of the lane markings on the road. The BMW failed to stay in its proper lane (without driver intervention) in all 14 tests. The Volvo stayed in the lane in nine of 16 tests. The Tesla Model S swerved right and left as it attempted to locate the appropriate lane. Sometimes it also entered an adjacent lane or drove onto the shoulder.
There is evidence that ADAS technologies do reduce accidents and insured losses—here and here. See also: Autonomous Vehicles: ‘The Trolley Problem’   However, the real world test results of Level 2 technology in these five highly regarded models were certainly disappointing. Level 2 autonomy requires the driver to remain engaged and constantly monitor the environment. The key words are “remain engaged.” People, while driving, often do many things other than remaining engaged. Conclusion The shared responsibility between less-than-perfect humans and less-than-perfect technologies of Level 2 implies that either the technologies have to become intrinsically better — or they must find ways to compensate for imperfect humans. As mentioned, you cannot make a straight-line projection of elapsed time from the current state of Level 2 ADAS technology to the arrival of ready-for-prime-time Level 5 fully autonomous technology.

Donald Light

Profile picture for user DonaldLight

Donald Light

Donald Light is a director in Celent’s North America property/casualty insurance practice. His coverage areas include: technology and business strategy, transformative technologies, core systems and insurance technology M&A due diligence.

Logos: Insurance Against Boredom

If insurers use the same words and wield the same pallet of primary colors, they will be too generic to be memorable and too guarded to make a sale.

If the insurance industry connotes feelings of safety, if people feel safe enough to feel bored talking about insurance, if it is better for insurers to be staid than sensational, too much safety can also be a bad thing. That is, boredom is not a brand-building device. It is an effect of safety, not its cause. It is a luxury, because most people who have no insurance—including the poor—cannot afford to feel bored when all they feel is hungry or scared. What does this mean to insurers, whose principal aim is to sell policies, while their initial priority is (or should be) to increase their visibility among the very people who will buy insurance? If names and logos blur, and clarity succumbs to confusion, if insurers use the same words and wield the same pallet of primary colors, they will be too generic to be memorable and too guarded to make a sale. See also: Awareness: The Best Insurance Policy   The best way to solve this problem is for an insurer to be creative without compromising its reputation for caution. A great logo is the answer to this challenge. It is less expensive than increasing awareness through advertising or repeating catchphrases—with more advertising—only to discover a phrase neither catches the attention of consumers nor enters the vernacular of our fractured culture. I am certain about these things, not because science substantiates my feelings, but because it takes time to develop a logo that elicits feelings that scientists can record but not induce among human beings. We are too unpredictable for scientists to devise a formula that yields consistent results. Leave the science of insurance to actuaries and let artists actualize the appeal of individual insurers. According to students and professors at the Parsons School of Design, as well as graphic designers at DesignMantic, great logos are icons. They represent values and ideals. They symbolize virtues worth attaining and prove their worth in the real world. The positive feelings people have about these logos require reinforcement. Put another way, it can take years to build a brand—and the best brands know they cannot rush what they cannot control, which is time itself—but it takes only one misstep to ruin a brand’s relationship with consumers. See also: Lessons From 3 Undisrupted Brands   The logo is a lodestar. It is recognizable, outshining a constellation of competitors. If it looks the brightest, and makes people feel warm and safe, it is because of the work an insurer does and the service its agents provide. Designers give the logo its form, but an insurer is responsible for its functionality. What is missing, today, is not quality service, but a serviceable logo. Serviceable is no substitute for excellence, but I would rather have a logo that works, albeit infrequently, than one that is a disservice to the hard work insurance agents do. Now is the time for insurers to embrace success. Now is the time for them to look successful. Now is the time for them to have logos that succeed.